Daily Stock Market Report (Friday 30th Jan 2026) - PEEL, TRT, PINE, CHRT

Good morning!
All done for today, have a great weekend!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£209bn | SR70) | New strategic collaboration agreement with CSPC Pharmaceuticals to advance the development of multiple next-generation therapies for obesity and type 2 diabetes across eight programmes. CSPC will receive an upfront payment of $1.2 billion from AstraZeneca. CSPC is also eligible to receive development and regulatory milestones of up to $3.5 billion across all programmes. | ||
Experian (LON:EXPN) (£24.7bn | SR52) | US$1bn share repurchase programme. “We continue to trade strongly underpinned by our strategic execution and we expect to end this financial year in a favourable leverage position.” Buyback will reduce shares in issue and also fund employee share-based payments of c. $200m. | ||
Airtel Africa (LON:AAF) (£12.5m | SR87) | Total customer base increased by 10% to 179.4 million. 9-month period: revenues of $4,667m (+24.6% in constant currency). EBITDA +35.9% in reported currency to $2,283m. Profit after tax of $586m improved from $248m year-on-year. | ||
Drax (LON:DRX) (£3.1bn | SR98) | Tolling agreement with West Burton C Limited, a company owned by Fidra Energy (an independent Battery Energy Storage Systems developer), for 250MW (500MWh) of new BESS capacity. | ||
Yellow Cake (LON:YCA) (£1.69bn | SR59) | Value of Yellow Cake's uranium holdings decreased by 0.5% over the Quarter from US$1,778.0 million to US$1,768.2 million as at 31 December 2025, as a result of the corresponding decrease in the uranium spot price. NAV per share £6.06. | ||
Chrysalis Investments (LON:CHRY) (£555m | SR87) | NAV 165.36p (share price: 112p). NAV down 3.7% since 30th September 2025. | ||
Cohort (LON:CHRT) (£553m | SR20) | SP -3% Marlborough Communications Ltd has been awarded a contract with a total value of £14.0m, by a UK government customer for immediate delivery of uncrewed air systems, together with in-service support for two years. Plus another £3.9m order for a UK customer. | AMBER = (Graham) [no section below] £18m of total contract wins did not strike me as a very meaningful news from a business generating annual revenues of c. £300m, and the 3% fall in the share price seems to confirm that. There is reassurance that "sufficient orders have now been secured to underpin fully the Group's 2025/26 financial year consensus forecast revenue", and that is worth something, but the financial year ends in April and so it would have been more worrying if orders to meet FY26 forecasts had not yet been secured. | |
Avon Technologies (LON:AVON) (£541m | SR44) | Avon Protection: record start to the year, healthy order book and sales pipeline. Team Wendy: strong order book but slower first quarter. Assuming no further extended US government shutdowns, the impacts are to be temporary. At Group level, full year guidance unchanged. | ||
Stelrad (LON:SRAD) (£175m | SR80) | 2025: another year of adjusted operating profit growth (+c.3% to c. £32.5m), in line with market expectations. Volumes declined 4%. Outlook: “although there remains a level of uncertainty around the timing of the wider market recovery”, the company has “a robust platform for further progress during 2026.” | ||
Peel Hunt (LON:PEEL) (£131m | SR82) | Continued to trade well in H2. Full year revenues and profits ahead of current market expectations. | GREEN = (Graham) The news that we'll have “full year revenues and profits ahead of current market expectations” doesn’t really tell us all that much, unless Peel Hunt would like to confirm for us what these market expectations are? It would be much easier to invest if all companies provided that information in their RNS announcements, of course. | |
Shield Therapeutics (LON:STX) (£117m | SR35) | Partner in China expects to submit the file for marketing authorisation to the China National Medical Products Administration for the approval for ACCRUFeR® in China in Q1 2026. | ||
Centaur Media (LON:CAU) (£67m | SR62) | Return of up to £64m by way of a Tender Offer at 48p. | ||
Kr1 (LON:KR1) (£35m | SR29) | Aggregate income from staking activities on a range of proof-of-stake networks: £169,615. Net asset value £50.2m, 28.25p per share. | ||
Transense Technologies (LON:TRT) (£17m | SR63) | Pace of growth is below market expectations, primarily due to delays in customer on-boarding. FY26 revenue not less than £5.2m. Revenues from the two operating businesses are expected to grow by not less than 30%. Lower levels of revenue than previously anticipated mean that profitability for FY26 is expected to be materially below current market expectations. | AMBER/RED ↓ (Graham) Marking this down one notch from the neutral stance I took on this last year. This is a major profit warning that puts back financial progress by about a year, in my view. While the business as a whole may be undervalued at this level, market caps of this level are particularly risky in my experience (e.g. delisting risk), so I would tread carefully. | |
RC Fornax (LON:RCFX) (£14m | SR32) | Non-Exec Chair to resign. NED becomes Independent Non-Exec Chair. MD/Head of Engineering joins the Board as Exec Director. FY August 2025 results to be published in mid-Feb, anticipated to be in line with what has been previously communicated. | ||
Rua Life Sciences (LON:RUA) (£10m | SR51) | Revenues for 18 months £6.7m (12 months to March 2024: £2.2m). Loss before tax reduced 85% to £0.2m (2024: £2.0m). Cash £3.25m. “Activity levels achieved during period have continued into current year with encouraging new business pipelines.” |
Backlog (last night)
Pinewood Technologies (LON:PINE)
Up 24% to 476.2p (£548m) - Response to Press Speculation - Graham - PINK
This provider of software for car dealerships put out some pleasant news last night:
The Board of Pinewood.AI notes the recent press speculation regarding Pinewood.AI and confirms that it has entered into discussions with Apax Partners LLP ("Apax") regarding a possible cash offer of 500 pence per share for the entire issued and to be issued share capital of Pinewood.AI (the "Possible Offer") by Apax. As an alternative to receiving cash, the Possible Offer will include an unlisted partial share alternative.
Apax is a global but London-headquartered private equity firm. So I’d view this as a local bid for Pinewood, not a foreign bid.
Importantly, the Board of Pinewood “would be minded to recommend” the offer at 500p, if it materialises.
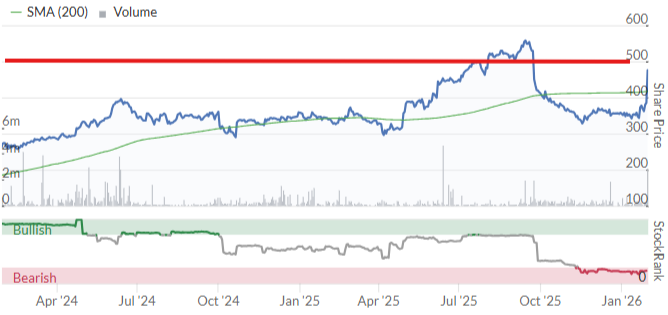
The share price was 385.5p last night, having already risen from 351.5p two weeks ago.
Therefore, against last night’s price, the 500p possible offer is an almost 30% premium.
Against the price two weeks ago, it’s a 42% premium.
That’s the level of premium which is often enough to get deals over the line.
Although I note that PINE shares did reach 500p at one point in the autumn:
Graham’s view
I was AMBER/GREEN on this in June, observing a punchy valuation but with promising growth prospects. US ambitions marked it out as a potentially interesting growth story.
EPS is forecast to grow strongly over the next few years, e.g. in September Zeus published forecast EPS of 12.1p (FY26) rising to 20.2p (FY27). So Apax might be about to pay 25x next year’s earnings.
That might sound a little rich, but there is at least a net cash position (£30m as of June 2025), and that cash position is also forecast to grow strongly. For a successful, growing software business, doing well in the United States, I don't think that 500p is an outlandish price to pay.
So Apax can perhaps do well out of this acquisition, but PINE shareholders may also be perfectly happy to exit and to crystallise their gains. So I guess everyone’s a winner. Let’s hope that the possible offer turns into a real offer soon.
Graham's Section
Peel Hunt (LON:PEEL)
Up 4% to 113p (£139m) - Trading ahead of expectations - Graham - GREEN =
It’s a terse update but a positive one.
Fewer than 100 words:
Reflecting the strength of our corporate client base and both our Investment Banking and Execution Services franchises, Peel Hunt has continued to trade well in the second half of the financial year, and we have supported clients on a range of M&A and equity capital markets transactions. As a result, the Group now expects to deliver full year revenues and profits ahead of current market expectations.
Graham’s view
As I’ve speculated already, the London market is set to be more active in 2026 than it has in previous years.
After all, the FTSE-100 has been carried 18% higher over the past year, and 33% over two years. Not what you might expect if you only focused on the weak flows into London-based active funds:
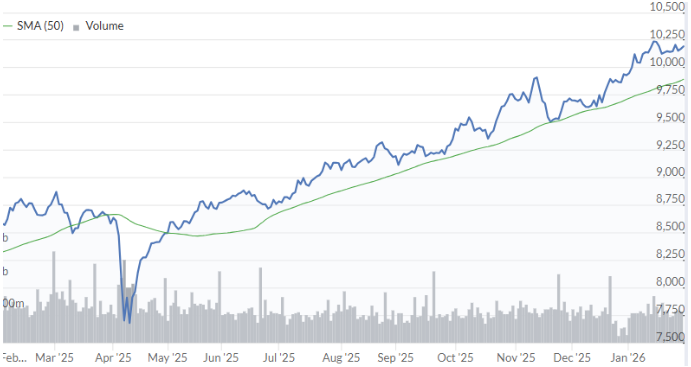
The soaring UK index has created a welcoming environment for forthcoming large-cap IPOs. Two in particular stand out: RAC which is “close to selecting banks” for its IPO (Bloomberg), and also the Norwegian software business Visma.
Other banks are rumoured to be on track to get the RAC deal, and I’m not sure if Peel Hunt will have any involvement with Visma. But these deals point to the “mini-revival” that is expected in London this year.
When it comes to Peel Hunt, I’ve noted that the forecasts available for its revenues and profits this year make little sense, when compared to its interim results. Peel Hunt already made 60% of forecast full-year revenue in H1, and more than 100% of forecast PBT, based on what I can find.
Indeed, from what I can gather, there is only one analyst covering Peel Hunt - the one at Keefe, Bruyette & Woods, Peel Hunt’s broker. And their estimates do not look to me as if they are updated very regularly, at least not in terms of what is released to the public.
Therefore, the news that we'll have “full year revenues and profits ahead of current market expectations” doesn’t really tell us all that much, unless Peel Hunt would like to confirm for us what these market expectations are? It would be much easier to invest if all companies provided that information in their RNS announcements, of course.
But I’m not going to complain too loudly: this is a company I’ve considered to be undervalued, and that I left on my annual watchlist for 2026. So I’m not upset that it’s beating market expectations. It's just that the market expectations themselves are something of a mystery. The numbers on the StockReport are definitely very stale, in my view - this is unfortunately what happens sometimes with stocks that receive limited coverage. The consolation is that this creates opportunities for those who are willing to dig a little deeper!
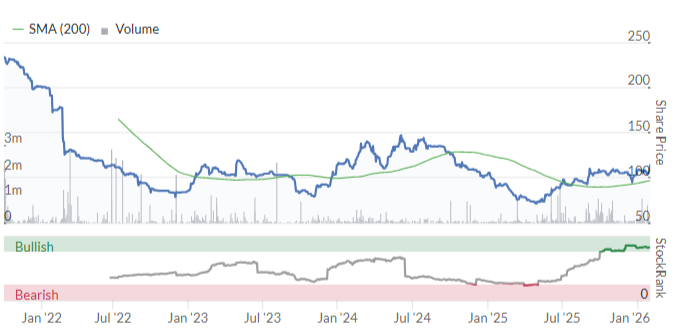
Peel Hunt shares still trade at only 50% of the price at which they IPO’d in 2021 (113p today vs. 228p IPO price):
Update: I contacted Peel Hunt's PR firm, who informed me that prior to this update, market expectations were for PBT of £12m. This doesn't line up with what I can gather from any other source, but it must be true. H1 PBT was £11.5m, suggesting that market expectations were for PBT of £0.5m in H2. At least we can rest assured that the efficient market hypothesis isn't going to be true any time soon!
Transense Technologies (LON:TRT)
Down 36% to 72.05p (£11m) - Trading Update and Notice of Interim Results - Graham - AMBER/RED ↓
Commiserations to anyone who was holding this overnight:
Transense Technologies Plc (AIM: TRT), the provider of specialist sensing solutions and measurement systems, announces a trading update for the six months ended 31 December 2025 and updates on the outlook for the full financial year ending 30 June 2026 ("FY26").
We don’t cover this one regularly, with the last time being February 2025.
It has two divisions, SAWsense (industrial sensors) and Translogik (tyre inspection tools).
H1 has not gone as planned:
Whilst both core trading divisions, SAWsense and Translogik continue to demonstrate increasing revenues, the pace of growth is below market expectations, primarily due to delays in customer on-boarding from their respective pipelines of new business. In addition, expected royalty income from Bridgestone iTrack is now considered likely to be approximately 10% lower than previously expected.
“Delays in customer on-boarding” is a tricky reason, as it requires further elucidation: are customers dragging their feet, or are enthusiastic customers being slowed down by technical problems?
We do get a bit more on this topic, a little further down.
SAWSense: revenue growth +70% in H1, and…
On-boarding of new customers is generally progressing well, however this process can be time consuming in agreement of technical scope, commercial terms and allocating financial budgets. There is currently elevated reluctance to make new commitments, often due to prevailing volatile geopolitical and economic considerations.
This sounds like a “bit of both”: technical obstacles, and some customer reluctance.
Translogik: revenue growth +13% in H1, “despite subdued demand from major tyre producers”.
Guidance:
…the Company now expects that Group revenue for FY26 will be not less than £5.2m, including approximately £2.0m of royalty income. Revenues from the two operating businesses are expected to show composite growth of not less 30% for FY26. Whilst gross margins have been maintained, the impact of these lower levels of revenue than previously anticipated mean that profitability for FY26 is expected to be materially below current market expectations.
Net cash was £0.9m as of Dec 2025.
Estimates: with thanks to Cavendish, the new forecasts are as follows.
FY June 2026 revenue £5.2m (previously £6.5m), adj. EBIT £0.3m (previously £1.3m).
FY June 2027 revenue £6.4m (previously £7.7m), adj. EBIT £1.5m (previously £2.3m).
Graham’s view.
I interpret the new estimates as putting back the company’s progress by about a year. The new FY27 revenue forecast is similar to the old FY26 forecast. And the new FY27 EBIT forecast is similar to the old FY26 forecast. So in simple terms, the timeline of financial progress has been pushed back by a year.
And it’s curious that all revenue streams are marked lower. Not just the operating divisions, but even the royalty stream from Bridgestone iTrack has been reduced, due to lower volumes and negative FX movements.
It is curious that a business earning £2m+ of royalty income per annum is only worth £11m - the operating divisions must be adding almost nothing to the valuation at this stage?
On that basis, I do think there could be value arguments for the stock at this level. Against that, I’m wondering if the group as a whole is perhaps just fundamentally too small to justify a stock market listing? Adjusted EBIT of £1.5m in FY27, even if it’s achieved, wouldn’t change that.
Given the major profit warning, I am going to mark this AMBER/RED today, down from my previous neutral stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
The Peel Hunt share price chart was wrong (it was the FTSE chart, replicated) - I have now fixed it. Apologies.
Re: Precious metals prices slipping today.
Most likely traders/brokers taking profits as it's the last trading day of the month........especially as this has fallen on a Friday.
Hey Ho back to work on Monday!
Pistol
I thinks its profit taking. I don’t blame the traders. I have taken a couple of small cooper and silver positions in January. I am taken aback of the increase in SP over this very small period since purchase. Makes me feel very cautious however if these positions were more matured I would take profits too. Have a great weekend all.
Given that Peel Hunt specialise in promoting the investment credentials of their clients, you would have expected a somewhat more informative trading update. Still a positive update and think they are very well placed to benefit from a pick-up in IPOs - UK equity markets have been surprisingly strong over the last year and there seems to be a growing pipeline of companies looking to list so I can see this gathering momentum.
Airtel Africa (LON:AAF) any reason for share price drop. seems like decent results
Is it to do with the prospect of a stronger $ because new Fed chief Warsh who will not cut rates
I think Warsh will do precisely what the Trump regime tells him to do. That is why he got the job (subject, of course to the "confirmation" of the Senate ... but does anyone doubt the Senate will bend over and do what Trump commands?).
100% with you James here's the bit on the family connection my prediction Kevin will bend the knee in record time.
https://www.theguardian.com/us...
Hi subdoc. I posted a very quick review of the figures for Airtel Africa (LON:AAF) here:
(1) Airtel Africa PLC - Alastair Kendall
I will try and find the time to do a deep dive in the next few weeks ... a favourite way to play African demographics.
Thank you James a very well written review
Bad day for any investments in precious metal mining - has the bubble burst? Gold down 8.5%, Silver 13.7%, Platinum 16.4%.
Or profit taking after very strong runs - they're all still up for the month (13%, 31% and 2% respectively) and up A LOT for 3 months (22%, 92% and 36%).
True and I have taken some profit on BlackRock World Mining Trust (LON:BRWM) first thing this morning - now down 7%+. Still have some exposure so will see if the bullish trend re-establishes it self. In the meantime I suspect as you say there is a lot of profit taking with VanEck Gold Miners UCITS ETF USD A (LON:GDGB) down 8.0%, Wisdomtree Metal Securities (LON:PHGP) down 4.3%, Wisdomtree Metal Securities (LON:PHPT) down 14% and a few of the shares which feature in Stockopedia posts: Serabi Gold (LON:SRB) down 10%, Sylvania Platinum (LON:SLP) down 11% and Endeavour Mining (LON:EDV) down 6.0%. I hold some of these but not all so it will be interesting to see if this is just a blip in the bullish trend or a major setback to the precious metals play.
Personal view I think its just a pull back, whats been driving it is three main factors, an erratic US president, out of control US debt and distrust in the dollar I don't see any of that changing in Trumps term or possibly ever again.
As an aside people say AI will destroy us and I think its already happening at a low level but not in the way most people think, I don;t think it's any accident that countries like the UK and US have become so divided since social media took off.
Just to keep things in perspective, prices are roughly back to where they were a week a ago. When you get these almost vertical moves there will inevitably be violent pullbacks as short-term traders take their profits.
Nothing has changed in my view. There was a major liquidation event in the gold market which knocked US$500 off the price at one point (on COMEX). It could have been driven by a desperate need for liquidity due to options trades on Microsoft ... pure speculation and that is my point. We don't know.
Cathie Wood is calling the gold top. But this is from a woman whose fund is down minus 40% in 5 years during a time of record returns pretty much everywhere else. Sadly, in the days of the internet, we don't have magazines to look at the front cover for our contrarian signal, but Cathie Wood's musings will suffice.
Meanwhile, whilst Cathy Wood is generously sharing her precious metals expertise, physical continued to diverge from paper at unprecedented levels, Shanghai silver market is trading at US$149 whilst COMEX crashed to US$106.
Nobody is arbitraging this profit away because there is no physical silver available to do so.
Some genius shorted COMEX and has reportedly been closed out for a US$5.46 million loss. Who shorts a market where there is a positive and growing differential between physical and paper silver?
As bellicose as the the Americans are, they could not fight a war of the intensity likely in a conflict with China over Taiwan for more than 4 months on account of China controlling the supply chain for the REM, silver and electronics in American missiles. China won the “war” 10 years ago, when the Americans were still thinking it was strategic to sell click bait, memes, and cat stories on their toxic social media platforms to the Europeans. The point is silver is now a strategic metal alongside the Actinides and Lanthanides.
So far as gold goes, the US$ debasement trade is alive and well but now has the polish of official policy. The Japanese are even lending a helping hand.
Trump’s Masterplan For The Dollar Needs A Patsy At The Fed - Search News
Meanwhile, the IMF is preparing for a run on the USD:
IMF prepares for global run on US dollar | Euractiv
As they say nothing goes up in a straight line, but everything falls down in a straight line. I think this is just a liquidity event and I no longer believe COMEX has much relevance. If you cannot deliver the atoms you are irrelevant in this new World.
I agree with all that you say Alastair, although I do wonder whether Kevin Warsh will be the patsy referred to in that Yahoo article. He was a hawk in the past but only time will tell how this unfolds.
I must admit to getting the patsy wrong. I thought it would be Rick Reider, who is currently CIO of fixed income at Blackrock. Maybe Trump did not think Mr Reider would be sufficiently patsy?
Alastair
He's married to one of the daughters of the fella who owns Estee Lauder, and the billionaire father in law is one of the biggest voices whispering in Trumps ear he must have Greenland so my guess is Kevin will fall in line in short order.
I did not know that ... interesting info. Nobel economist Krugman is saying he is not who the market thinks he is as well.
Hi Alastair
Interesting as always.
I have a question around what would happen to physical silver ETCs in the event of a COMEX market break. As I understand it the ETCs track the spot price not the real price - hence why they crashed yesterday when the actual silver price hardly moved. But if COMEX stopped trading I believe the ETCs can (or perhaps are forced to) liquidate at the (fake) spot price at the time and cash me out at whatever that price is.
Do you know if that correct? Because if it is the only advantage of a physical ETC that I can see if that we would get some money back, as opposed to none for the derivative based versions.
timarr
I am sorry this is so long Timarr. I know it barely needs saying, but I am not qualified to advise anyone and neither do I have any knowledge of your personal financial affairs. The following is my understanding of the situation you outline having read through several prospectuses:
The mechanics of ETCs vs. the underlying physical market become brutally important in a disorderly market or exchange failure scenario. Physical silver ETCs do not give you the “real” physical price. Even the fully allocated, vaulted, LBMA‑good‑delivery ETCs (e.g., WisdomTree, iShares, Invesco) are priced off either the LBMA Silver Price or the COMEX front month futures. (There is another can of worms about what the bullions banks do with 3rd party vaulted silver in terms of lending it out).
These benchmarks are all paper market constructs. They are not the Shanghai physical price which is, in my view, the only “real” silver price, because it is a physical market.
So when COMEX pukes, the ETC pukes, even if the physical market barely moves. If COMEX breaks, the ETC must use its benchmark price. If the benchmark becomes unavailable (e.g., COMEX halts), the prospectus normally allows the use of the last available price, or the use of a “fair value” determined by the trustee, or allows the trustees to temporary suspend the creation and redemption of new "shares", or even to liquidate using the last reliable benchmark.
The key issue is that ETCs are not allowed to invent a new price based on “real physical.” They must use the benchmark defined in the prospectus.
If that benchmark is COMEX‑derived, then yes, you get cashed out at whatever that benchmark says, even if the physical market is at a wildly different level. It is even possible for a physical ETC to be forced to liquidate at a broken paper price . Most ETC prospectuses include language like:
“If the benchmark price becomes unavailable or the market becomes disorderly, the trustee may liquidate the fund using the last available benchmark price.”
This is designed to protect the issuer, not the holder.
So your understanding is broadly correct:
A COMEX failure could force a physical ETC to liquidate at a distorted, non‑physical price. You would get something, but not necessarily anything close to the true physical value.
You’re also correct that a physical ETC at least has metal in a vault. A synthetic ETC has only swaps or futures exposure with multiple counter-party risk.
In a catastrophic paper market failure, a synthetic ETC could go to zero if counterparties fail. A physical ETC would liquidate the metal, but at the benchmark price, not the Shanghai or wholesale physical price.
So the physical ETC gives you downside protection against counterparty failure, but not protection against benchmark failure.
There is only one structure, in my view that protects you from a COMEX break and that is direct allocated physical ownership in your name, held outside the financial system in a vault. I do hold some gold in the Royal Mint ETC (LSE: RMAP) where at least the gold is allocated and held in the Royal Mints vaults in Cardiff, rather than in a bullion bank vault, but I much prefer physical. All our strategic multi-generational gold is held as physical (not at home!!).
Hi Alastair
Thank you - no advice expected! Very helpful.
timarr
You are welcome. Questions always help clarify my own understanding!
So if COMEX crashes in March, as many pundits predict, we're better off holding silver miners (who presumably sell real silver at real silver prices?) or stashing silver coins/bars in a vault somewhere?
So if COMEX crashes in March, as many pundits predict, we're better off holding silver miners (who presumably sell real silver at real silver prices?) or stashing silver coins/bars in a vault somewhere?
I'm not an expert (by a long way) but I believe most miners are selling at the spot price. The real price - the retail price - is after all of the processing that's done on the raw product.
Happy to be corrected but I don't think miners expose investors to the price of the physical product. You really only get that by buying physical. In the latter case, of course, you're paying a lot more in the first place.
timarr
So maybe precious metal streaming companies are the way to go!
My strategic holdings are Wheaton Precious Metals (TSE:WPM) , Triple Flag Precious Metals (TSE:TFPM) and gold bullion. Silver and the miners are une infatuation temporaire du cœur and one day, will pass.
Most silver miners are selling on the basis of wall street analysts doing DCFs at US$40 / oz. Even after the crash last week, silver on COMEX is nearly double that. I am working through some figures just now and will publish them. I am thinking of selling my Wisdom Tree silver and buying more Pan American Silver (TSE:PAAS) . Rick Rule has basically done this with 25% into gold bullion, 25% onto O&G and 50% into Pan American Silver (TSE:PAAS) , Wheaton Precious Metals (TSE:WPM) and I think he has bought a couple of junior developers ... Vizsla Silver (TSE:VZLA) being one I remember.
His reasoning was exactly the above ... the silver miners are cheap and priced on old silver spot prices of US$40, so even if silver does not rebound, the miners will as this feeds through into cash flow and EPS upgrades.
To this I would add my concerns about how Wisdom Tree will price its physical silver in a disorderly market. I already own Pan American Silver (TSE:PAAS) and Wheaton Precious Metals (TSE:WPM) and will add to Pan American Silver (TSE:PAAS) as I have gained a deeper understanding of the company and gained confidence in the thesis. I already have a large position on Wheaton Precious Metals (TSE:WPM).
Hi Alastair
His reasoning was exactly the above ... the silver miners are cheap and priced on old silver spot prices of US$40
I get the silver miner thesis - but does the same argument apply to streamers which, on a historical basis, look expensive?
I've come to the conclusion that the physical metal trackers are too risky, am now wondering whether there's a similar concern around the likes of Global X Silver Miners UCITS ETF USD Acc (LON:SILG), although as far as I can see it actually invests in the underlying miners.I've always found commodites challenging to invest in, and the more I dig, the more I agree with myself ...
timarr
I agree. Every time I think I'm getting a handle on things, someone chucks another curve ball.
Hi Timarr
The jollybiologist asked me a similar question on substack, so I will just cut and post my reply here:
ETFs and ETCs
An ETF is a regulated fund holding a diversified basket of assets, usually shares. An ETC is a debt style exchange traded product giving exposure to a single commodity, like silver, and has carrying issuer risk (on account of it being structured as a debt product).
There are loads of rules which distinguish the two. I will try and summarise:
ETF
* Regulated in Europe and the UK under the UCITS rules
* Assets are segregated and protected if the issuer (e.g. Wisdom Tree or iShares) enters insolvency
* Must meet UCITS diversification rules
* Unable, under UCITS riles, to hold a single commodity like silver
ETC
* Usually structured as a debt security
* Investor capital is not a protected fund asset and investors face issuer counterparty risk
* Can hold individual commodities like silver
* Can be real allocated silver or synthetic silver held through swap agreements
I hold some ETFs and ETCs. I am thinking of selling my Wisdom Tree silver ETC (LSE: PHSP) and investing the proceeds in TSX: PAAS and a couple of juniors. I am trying to write an article on this and hope to publish later today, but I am slower than I used to be! The family trust owns the same silver miners ETF as you do (Global X Silver Miners UCITS ETF USD Acc (LON:SILG) ), and we have no intention of selling, despite the recent volatility.
I also hold COPX for copper miners, but I am thinking of selling and placing the proceeds in First Quantum Minerals, increase my position in Hudbay Minerals and also buy a new position in Ivanhoe Mines. Again I will write an article as to why. Of course, these are very personal decisions.
So, to summarise ETC and ETF are not interchangeable terms in the legal sense and my apologies if my language was insufficiently clear.
Streamers and Royalty Companies
They have always looked expensive on a PE basis but this is not the way to value them. I have held Wheaton Precious Metals (TSE:WPM) for over 12 years and also own Triple Flag Precious Metals (TSE:TFPM) . I think Franco-Nevada (TSE:FNV) looks a screaming buy, but do not yet own it.
I wrote some articles on the streamers and royalty companies on my substack here:
Why the Gold and Silver Streaming Model Is One of the Smartest Structures in the Mining Industry
Wheaton Precious Metals: Investment Briefing & Strategic Outlook (2025–2030)
Triple Flag Precious Metals: Investment Briefing & Strategic Outlook (2025–2030): Part I
Triple Flag Precious Metals: Investment Briefing & Strategic Outlook (2025–2030): Part II Finance
Rick Rule thinks the large streaming companies and best of the best miners like Agnico Eagle have never been cheaper, despite the recent share price increases. I did some quick DCFs and agree. If I had ready cash I would be buying more. In my view - and this is obviously a personal opinion , I regard the quality streamers and royalty companies, as the safest way to hold precious metals other than storing coins and bars in your study (but that comes with its own security challenges).
Hope this helps Timarr.
Best wishes
Alastair
Hi Alastair
Thank you for your reply. It gives me somewhere to start.
For what little it's worth I'm also ditching my ETCs, retaining Global X Silver Miners UCITS ETF USD Acc (LON:SILG) and swapping into a diversified group of miners and streamers. Picked up Fresnillo (LON:FRES) yesterday as part of this move.
Love the substack, BTW.
timarr
Thank you so much timarr.
Hi Timarr. I've done almost exactly the same. I'm also buying Pan American Silver to go with my Fresnillo. It's a steep learning curve but a really interesting and enjoyable (and hopefully profitable) one. I did think about getting some coins/bars but turns out you pay VAT on bullion you take delivery of... I agree about Alastair's substack.
This 100%
Precious metal prices
Dropped 10% over two days. Up 30% over this month.
Make what you like but for me the trajectory is clear, marching towards $10,000.
I'm trying to make sense of it like this: Looking at the gold price chart, it's normal for traders and investors to sell into exhaustion extensions like the one we've just seen. The recent spike up looks similar to what happened around 17th October on the chart. So something similar may happen again afterwards, if the price is to build a new continuation base (consolidation), which would align with the bullish fundamentals some are pointing out here and maybe lead to a higher exhaustion extension later. But exhaustion extensions can also mark the beginning of reversal (or topping) consolidations , leading to lower prices.
How big are your golden balls.
I actually margined long on this, after a good week, now all gone and underwater. Easy come quicker to go.
Who knows what Monday brings - Khomeini moves to? Answers on a postcard. Odds on WC1 (sorry slipped
I am very sorry to hear that Harry.
Back in October 1987, I was at Wintrust Securities doing an audit. They still used a manual hand written ledger ... seriously. They had just acquired a TOPIC screen and the CEO was super chuffed as he showed me this piece of modernity in his office. I just watched the screen turn red and realised all those options positions I had written were going to wipe me out. They did and I never told a soul as a I had a feeling, which I did not wish to test, that the audit partners would take a dim view of my entrepreneurial instincts.
It took me 2 years to pay if off and I lived, not for the first time, like a pauper. I was 22 years old and am now 62. In the intervening 40 years, I have never done one leveraged trade. Best to learn one's lessons young.
Agreed as a friend of mine said on friday "if your going to have a mistress do it when your young, then if the wife divorces you she will be doing it whilst your young, skint and pre-kids".
Prices have dropped a lot, this was an overdue correction. But demand is still much larger than supply for all three precious metals. Pointing to higher prices in the future.
The miners have seriously lagged the price of the metals, probably because the market felt that the metals were due a price correction. This means that the miners are still a very strong buy based on the metals prices today.
A 3-Day Event.
agree, i think a lot of forecasts are based on somewhat lower prices still
Sheer volatility, buy some more gold today.
not surprising there is a pullback, after the recent run...
dont see much changing medium term, the demand for metals /precious metals etc is only going one way
If you look at the price of gold during the 1970s there were several pullbacks were the price of gold dropped 30%. During 1975 the price of gold dropped nearly 50% from around $200/oz down to around $100/oz. Those who sold out at $100/oz lost out because gold then rebounded to over $600/oz by the end of the 1970s.
As epitychia has pointed out, this is an overdue correction.
David.
Commiserations to any holders of Transense Technologies (LON:TRT). The brutal sp drop reflects Cavendish reducing eps forecast to 6/26 from 7.8 to 1.3p and to 6/27 from 13.7 to 8.7p and target price from 349 to 251p.
Peel Hunt (LON:PEEL) . With AIM picking up and FY profits already in the bag (from H1) they look cheap to me. Discuss.
Should benefit Cavendish (LON:CAV) too.
PEG ratio 0.5 is decent
Pinewood Technologies (LON:PINE) Pinewood Technologies might be one for the box. RNS overnight recommending a cash offer from APAX. Offer of 500p. Closed at 385p yesterday.