Daily Stock Market Report (Mon 12 May 2025) - US-China Agreement, SNX, IGG, VLG, CWK, VCT, OPT, LIKE, TAND

Good morning!
Welcome back to another week. Today's Agenda is complete.
2pm: let's wrap it up there, thank you!
US-China Trade Talks & Agreement
When I wrote The Week Ahead last week, I mentioned that there would be "ice-breaker" talks between the United States and China in Switzerland over the weekend.
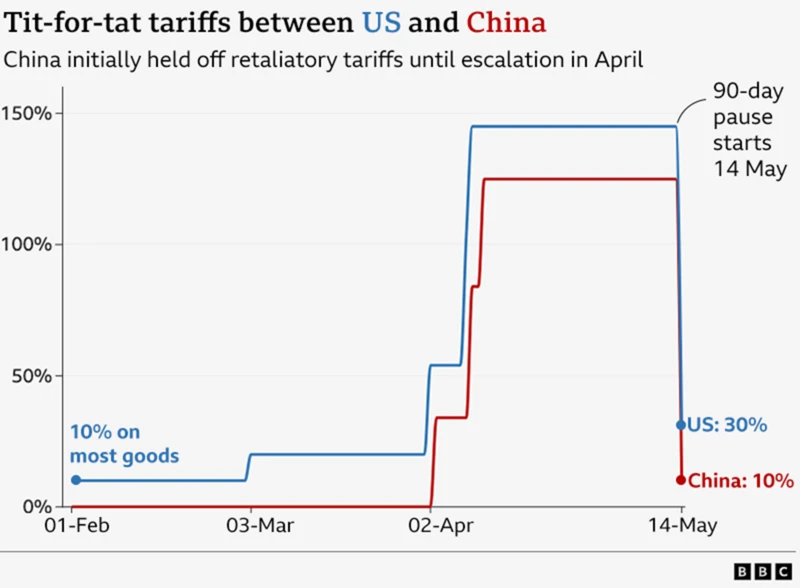
I did not expect - and I don't think anybody else anticipated it - that the two countries would almost immediately agree to reduce their tariffs by anything like this:
Source: BBC
For 90 days, starting on Wednesday, the US tariff on China is reduced to 30%, and the Chinese tariff on the United States is reduced to 10%.
These are still much higher than they were a few months ago. But I would expect the majority of trade to resume at these rates.
The two countries "will establish a mechanism to continue discussions about economic and trade relations". Perhaps this may lead to further progress and a normalisation of tariffs back to where they were before this episode began?
As I've been saying from the start, I think Trump's main objective is to be able to point to concessions he achieves from other countries. If he gets that, I think he's quite happy to drop tariffs.
The FTSE hasn't moved much today (+0.4%) but the S&P is set to open up nearly 3%.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| Rio Tinto (LON:RIO) (£73bn) | Definitive Agreement for Winu Project joint venture | Press Release, not an RNS. Sumitomo Metal Mining will pay up to $430m for 30% JV equity share. | |
IG group (LON:IGG) (£3.8bn) | Ahead. FY25 revenue & adj PBT now expected to “meet or slightly exceed” top end of consensus. | GREEN (Graham holds) With accounting changes, a larger credit facility and a bond issuance, IG are going to have a great deal of flexibility when it comes to M&A, investment in their existing business and share buybacks. I remain a happy shareholder but will monitor their next moves carefully. | |
| Cranswick (LON:CWK) (£2.9bn) | Daily Mail abuse claims | SP down 8% Daily Mail article claims “horrific abuse” at one of Cranswick’s farms. | RED (Megan) I’d be inclined to steer clear of this one until it is clear that all of the rest of Cranswick’s farms are operating free of suspicion. |
Victrex (LON:VCT) (£788m) | Volume +16%, adj PBT -17% to £23.2m. Various headwinds. FY profit: “range of outcomes” | AMBER (Roland) A recovery in volumes has been driven by low-margin sales, with additional pressure from problems ramping up the group’s new China factory. The impact of tariffs remains uncertain and I can’t help feeling today’s outlook is potentially a slight cut to guidance. On balance, I’ve decided to moderate my view and turn neutral until clarity improves. | |
Frp Advisory (LON:FRP) (£336m) | Financial reporting advisory firm. £5.6m for business (5.1x EBITDA) plus £2.5m for net assets. | ||
Capita (LON:CPI) (£235m) | Support services for NHS England primary care practitioners. First 18 months worth £82.5m. | ||
Caledonia Mining (LON:CMCL) (£202m) | Revenue +46% to $56.2m, net profit +493% to $8.9m. Prod +9.3%. FY outlook unchanged. | ||
Tristel (LON:TSTL) (£188m) | Ophthalmic disinfectant foam approved. Positive signs of early adoption. | ||
Optima Health (LON:OPT) (£173m) | FY March 25 revenue down 4.5% to £105m, with H2 growth of 7%. There were two large contract reductions in late 2023. EBITDA to be in line with expectations. A note from Panmure Liberum today forecasts £17.6m of adj. EBITDA (consensus: £17.4m). | AMBER (Graham) [no section below] We checked in on this occupational health and wellbeing company for the first time in April - the stock has only been listed since last year, when it demerged from Marlowe. At 10x adj. EBITDA it doesn’t strike me as a bargain but I’m happy to keep an open mind for the time being. Earnings estimates have been stable/rising. It will be worth seeing how successful they are with bolting on a number of small acquisitions made in recent months, and I'm also keen to see how much adj. EBITDA converts to real profits and cash. The StockRanks seem to agree with my neutral stance (55/100), although they also categorise it as a "Momentum Trap". | |
Batm Advanced Communications (LON:BVC) (£69m) | $1.5m order from longstanding customer. Expects to apply this tech to its commercial products. | ||
Synectics (LON:SNX) (£58m) | Contract with Stagecoach to pilot a new “On-Board Hub” solution for vehicle tracking and safety/surveillance. | AMBER/GREEN (Roland holds) [no section below] | |
Venture Life (LON:VLG) (£58m) | Cash sale of contract development and manufacturing operations to a P/E-backed Italian company. Company now aims to be a pure-play branded consumer healthcare business. | AMBER (Roland) This disposal looks fairly priced and will allow VLG to deleverage and invest in future growth. However, near-term earnings could fall by a third and shareholders will receive no immediate benefit. So the acid test of this will be whether management can deliver on their aim of becoming a higher-margin, capital-light consumer brand business. Given the poor track record of shareholder value creation, I’m staying neutral for now. | |
Likewise (LON:LIKE) (47m) | FY December 2024: sales +7.4% (£149.8m). Adj. PBT £2m (LY: £2.3m). Confidence to achieve current mkt forecasts for FY25. Adj. PBT is forecast to increase to £4m this year and then £5.2m in 2026 (Zeus). Balance sheet strength: the company owns freehold properties worth £23.5m. Today’s balance sheet also shows total tangible net assets of £30m. | AMBER (Graham) [no section below] We’ve been AMBER on this one (e.g. see coverage by Roland in Feb). The growth prospects of this upstart company (rivalling Headlam) are interesting under CEO and 11% shareholder Tony Brewer, but from a sector point of value the valuation at a forward PER of 17.5x is off-putting. However, as the company executives on its plans, we should start to see positive operational leverage. So it does have the clear potential to grow into this valuation. | |
Iofina (LON:IOF) (£43m) | Rev +9% ($54.5m). PBT $4.8m (2023: $8.3m). Net cash $2.9m. “Investment for growth continues.” | ||
MTI Wireless Edge (LON:MWE) (£42m) | €1m contract from long-term customer in Italy to be delivered within 2025. | ||
Cyanconnode Holdings (LON:CYAN) (£29m) | Confirmation of award from Government of Goa’s Electricity Department (worth c. £70m). | ||
Cordel (LON:CRDL) (£14m) | Design & engineering group for rail transport buys Cordel’s LiDAR/AI tech. No financial figures given. | ||
Tan Delta Systems (LON:TAND) (£14m) | “A leading provider of intelligent monitoring and maintenance systems for commercial and industrial equipment.” Revenue down 16% (£1.2m). Loss before tax £1.17m. Cash £3.1m. Pipeline £35m (?!) | RED (Graham) [no section below] | |
Mycelx Technologies (LON:MYX) (£5.6m) | Rev halves to $4.9m due to sale of Saudi ops. Loss $2.6m. Cash $1.3m & $1.25 Saudi earn-out. | ||
Malvern International (LON:MLVN) (£4.8m) | Underlying revenue +38% to £14.7m. Underlying loss £0.1m (2023: profit £0.15m). |
Graham's Section
IG group (LON:IGG)
Up 1% to £10.98 (£3.9bn) - Update on trading and balance sheet management - Graham - GREEN
At the time of publication, Graham has a long position in IGG.
The last update from IG Group in March stated that the company was “confident of meeting FY25 consensus”.
That was before the tariff earthquake hit the financial markets, sending volatility to levels not seen for five years:

One of the attractions of financial trading platforms for me is their counter-cyclical nature: when markets move down suddenly, this spurs trading activity which is good for platforms like IG.
This brings us to today’s update. Note that their year-end is May, so Q4 is from March to May:
The business has performed strongly in Q4 FY25 as elevated volatility across a range of asset classes, particularly in April, has resulted in higher levels of client trading activity than expected in typical market conditions. As a result of the strong performance, the Group currently expects FY25 total revenue and adjusted profit before tax to meet or slightly exceed the upper end of the current range of consensus of £1,051.0 million and £516.3 million respectively.
The market correctly anticipated that IG would trade well in this environment: its shares are up 15% since the end of March.

I think the shares continue to trade at a P/E ratio of about 10x after this update.
Balance sheet management
The second half of today’s update is about the company’s plans for its surplus cash.
There is an ongoing £200m share buyback programme.
The company is now working on increasing its “distributable reserves by reducing its share premium account and merger reserve, with a corresponding increase in retained earnings”.
Let me explain what this means for anyone who might need clarity on it:
Every company’s balance sheet equity is divided into different categories, depending on where it comes from. Only the equity generated by the company’s profits is categorised as “retained earnings”.
When a company wants to declare dividends or buy back its own shares, it is supposed to do this using its retained earnings, not any of the other categories.
But when companies have more surplus cash than the notional value sitting in “retained earnings”, this can create a difficulty for them, as they can’t send all of this surplus cash back to their shareholders..
The solution (if they are legally allowed to do so) is to adjust their balance sheet, so that more of their equity is categorised as retained earnings.
Note that there are no real-world effects of this adjustment. It’s purely a change in the company’s financial statements. But once the adjustment is made, the company can legally send more cash to its shareholders.
The November 2024 balance sheet for IG had over £700m of equity classified within “share capital and share premium” and “merger reserve”:

Nearly all of this could potentially be freed up for shareholders, in addition to the company’s “retained earnings” of £1bn. That’s £1.7bn that in theory could be returned to shareholders.
However, that isn’t going to happen any time soon.
Firstly, the company doesn’t have £1.7bn sitting in cash. Own funds as of Nov 2024 were £1.05bn.
Secondly, there is a regulatory capital requirement of £300m+, and it’s prudent to keep significantly more than that on hand.
So I’m not expecting a £1.7bn windfall for IG’s shareholders any time soon. But it does sound like we could get some more aggressive dividends or buybacks. The existing yield on the StockReport is given as 4.6%.
In addition to the accounting change described above, the company might borrow to increase cash resources:
It has refinanced its credit facility from £400m to £600m.
It intends to issue “a senior unsecured bond to provide long-term financing”.
They conclude:
These actions provide IG with additional liquidity to continue investing in accretive growth opportunities and evaluate returning capital through share buybacks, all while safeguarding the Group's strong financial position.
IG has a well embedded capital allocation framework which has served the Group well. As previously announced, the Group is evaluating if the framework can be further refined and an update will be provided with the full year results on 24 July 2025.
Graham’s view
This is an important shareholding for me - my third largest holding - and my first priority is that they remain extremely safe from a balance sheet point of view. So I’ll be watching their next actions with great interest. I do agree that they can probably afford to boost shareholder returns, at least in the short-term or on a one-off basis.
The shares are at all-time highs but I still consider them to offer some value at a PER of 10x, given its status as a market leader, with a high-quality client base and a trusted brand name. So I don't have any major objection to share buybacks at this level.

The current CEO was previously COO of Paddy Power and CEO of Betfair, and was involved in the merger of those two companies. I think it’s a strong background to bring to IG.
In summary: I’m very much a happy shareholder, but I intend to keep a close eye on what they are about to do with their balance sheet, to make sure that I remain comfortable!
Megan's Section
Cranswick (LON:CWK)
Down 8% to 4960p (£2.7) - Allegations of abuse by Mail on Sunday - Megan - RED
The report from the Mail on Sunday following an undercover investigation at one of Cranswick’s farms in Lincolnshire makes for harrowing reading. The animal abuse which has been caught on camera by an undercover investigator for the animal rights organisation Animal Justice Project (AJP) is horrific and seems to have been carried out by multiple members of staff and the farm’s manager.
Major supermarkets have suspended supplies from the farm pending an investigation. While the AJP has filed a formal complaint to trading standards and is seeking prosecution of members of staff at Cranswick. The group’s founder told the Mail on Sunday: “This marks the start of a national, sustained campaign to expose the violent realities of pig farming in Britain. We will not be pulling any punches.”
This isn’t the first blow for Cranswick. Last month the company had plans for a mega-farm in Norfolk rejected after locals raised concerns about the conditions animals including pigs and chickens were being forced to live in.
The company is the biggest producer and supplier of pork in the UK, ‘finishing’ more than 34,000 pigs every week from its many thousands of farming locations across the country. This year marks Cranswick’s 50th anniversary and executives had been making plans to step up investment in genetics to continue improving the quality and efficiency of pork production. But an investigation into animal welfare even at one of the company’s farming locations is likely to throw a spanner in the celebrations.
Megan’s view:
From a purely moral perspective, this weekend’s revelation at Cranswisk is a major red flag. I have no interest in a company which cannot hold all members of staff accountable to basic levels of humanity.
From a financial point of view, the allegations also aren’t great. Suspension of trading from one farm isn’t a big deal, but supermarkets will be quick to sever ties with any farm where there is just a whiff of animal cruelty. And it’s likely that all of the company’s farms will now be subject to more intense scrutiny.
It doesn’t make for great optics when the company’s four executive directors paid themselves just shy of £10m (including £3.3m for the CEO) last year and have been profiting handsomely from recent share price gains.
I’d be inclined to steer clear of this one until it is clear that all of the rest of Cranswick’s farms are operating free of suspicion. RED
Roland's Section
Venture Life (LON:VLG)
Up 18% to 53p (£68m) - Cash sale of CDMO operations - Roland - AMBER
Sale of contract development and manufacturing operations and certain non-core products for €62m in cash on a cash free, debt free basis
Consumer healthcare group Venture Life is a big mover today after announcing the sale of its operations for a cash payment of €62m (c.£53m) – equivalent to over 90% of its £57m market cap prior to today’s open.

The assets being sold are Venture Life’s contract manufacturing and manufacturing operations and some non-core products.
The buyer is Italian firm BioDue, a contract development and manufacturing operation. BioDue is owned by private equity group Riverside.
Financial impact: based on the financial details provided today, the assets being sold contributed around 40% of Venture Life’s revenue last year and a similar proportion of its profits. The key figures for the disposal are:
Net carrying value: £28.9m
2024 revenue: £20.5m
2024 adjusted EBITDA: £4.9m
2024 pre-tax profit: £0.3m
On these figures, today’s deal values the assets at 10.8x EBITDA or 2.6x sales, which seems like a reasonably good result to me.
The majority of proceeds from this deal will be used to repay the drawn balance on Venture Life’s credit facility, which stood at £20.6m on 30 April 2025. Remaining cash will be used to invest in its existing brands and potentially pursue further acquisitions.
Strategic rationale: these disposals will leave Venture Life as a capital-light business that’s focused on its core, owned consumer healthcare brands. These are said to be higher margin and with superior growth potential.
The company seems to be following the recent playbook of consumer giants Unilever (I hold) and Reckitt by focusing on a group of “Power Brands”. For Venture Life, these are Balance Activ, Health & Her, Lift, Earol, Pomi T, Gelclair.
Venture Life will continue to employ the manufacturing services of the divested business to produce its products and has signed a 10-year deal with BioDue for “development and manufacturing services”.
Outlook & Estimates: broker Cavendish has kindly provided an updated note today with revised forecasts reflecting today’s news.
Cavendish’s analysts expect to see a significant drop-off in revenue and earnings this year before a return to growth, but are projecting improved operating profit margins from continuing operations:
FY25 new: revenue £43m / EPS 4.2p (previously: £66m/6.3p)
FY26 new: revenue £47.1m / EPS 5.8p (previously: £71.6m/7.7p)
These estimates price the stock on around 12.5x FY25E earnings following this morning’s gains.
Roland’s view
Today’s disposals appear to have been made at a fairly attractive price and will substantially strengthen Venture Life’s finances.
However, as a result of this disposal, near-term earnings could fall by a third and the need to repay debt means that shareholders will not receive any kind of direct return to compensate them for this loss of earnings.
In my view, the success of this deal (for shareholders) will depend on whether Venture Life can now transform itself into a more profitable business.
At a statutory level, Venture Life’s profitability has been extremely poor in recent years:

Without further research, I’m not sure if this reflects weak pricing power, lack of scale, or simply poor management, but it’s not been a good outcome for shareholders.
A business that generates such low returns will struggle to create any long-term value for its shareholders.
Compare the two charts below showing Venture Life’s revenue growth and its share price performance over the last 10 years – revenue has gone up, but the shares have gone down. Shareholders have also suffered significant dilution:


I can see some positives from today’s deal, but I’d like to know more about the performance of the group’s continuing operations before taking a positive stance. Can this leopard really change its spots?

At this point, I’m going to echo the StockRanks and remain neutral.
Victrex (LON:VCT)
Down 4% to 870p (£757m) - Interim Results - Roland - AMBER
Victrex plc is an innovative world leader in high performance polymers, delivering sustainable products which enable environmental and societal benefit. This announcement covers interim results (unaudited) for the 6 months ended 31 March 2025.
Today’s half-year results from Victrex are a little weaker than I was hoping to see following December’s full-year results, which I covered here. The market also seems a little disappointed, as the shares are down despite a general rise for industrial stocks reflecting hopes for a US-China deal.

Following December’s results, I was hopeful that signs of improved volumes would translate into a recovery to profits.
Today’s half-year results do report a further improvement in volumes, but there’s no evidence yet of this translating into a recovery in profitability. Instead, various headwinds appear to be holding back profitability.
Half-year results summary: I’ve pasted in the financial highlights table below to show the different moving parts at work here.

I think it’s worth noting how the lower average selling price means gross profit is lower, despite the increase in volume and revenue. This highlights the relatively commoditised nature of Vixtrex’s core PEEK business. While the company is trying to move away from this by selling more added-value finished products, this transition clearly remains a work-in-progress.
Management say there were a number of reasons for the lower gross margin and fall in underlying pre-tax profit:
Adverse currency rates (-£5m on revenue);
Changes to sales mix (see below);
Slower-than-expected ramp up of new China factory, which is now only expected to sell 50 tonnes this year, versus 100t-200t previously.
Looking at the divisional breakdown, my feeling is that the main reason for the fall in average selling prices and gross margin was the unfavourable selling mix:

VARs are value-added resellers. These are customers who buy PEEK from Victrex as a raw material at lower average selling prices than industrial customers buying finished parts. VARs then process the PEEK into products for further resale.
Victrex wants a bigger share of this business and has product development ‘Mega Programmes’ underway in various key segments. But as the table above shows, the group is still dependent on commoditised sales to VARs for more than 40% of its volumes, a situation that worsened in H1.
In fairness, performance across most other customer segments was respectable during H1. The only real weak spot was the automotive sector, which offset gains in aerospace. That seems unsurprising, given the broader backdrop for car manufacturers at the moment.
Balance sheet/dividend: net debt was £40.7m at the end of March, up from £21.1m at the end of September 2024. This looks manageable enough to me and cash generation remains good, with my sums suggesting more than 100% of net profit for the period was converted into free cash flow.
On this basis, I suspect the dividend will remain sustainable despite the slender level of earnings cover:

Outlook: management expects profitability to improve during the second half of the year:
We are targeting a substantial improvement in H2 PBT compared to H1. This is supported by the typical second-half weighting of profits, as well as the current volume momentum driven by Sustainable Solutions.
However, they also warn that the headwinds seen in H1, particularly the ramp up of the new China factory, will continue to affect profitability in H2. Victrex then provides full-year guidance that in my view, is unnecessarily confusing:
These factors, and other previously guided headwinds, including FX, will constrain PBT growth for H2, compared to H2 2024, though we expect these to ease into the next financial year. Given macro-uncertainty, together with the effects noted, we have a range of outcomes for full year profit. For H2, our target is to deliver PBT similar to H2 2024, driving some PBT growth in constant currency on a full year basis.
I think this is an interesting contrast with February’s AGM update, when Victrex made a clear statement that “full-year expectations are unchanged”.
Expectations are not mentioned in today’s results. I don’t have access to broker notes for Victrex, so I can’t be sure. But my feeling is that today’s results could prompt a slight downgrade to earnings expectations for the full year.
Prior to today, consensus forecasts suggested earnings would rise by 18% to 61.1p per share this year.
Roland’s view
In situations like this, identifying whether the problems are transient external issues or more structural problems can provide useful insight on valuation.
In this case, I think there’s a mix of issues. Problems with the ramp-up of the new China factory will presumably ease over time. FX movements also tend to balance out over long periods.
However, the company admits to some uncertainty over the impact of tariffs. At this stage, it’s probably difficult to be sure how this will play out. I wonder if there’s a risk that the economics of the new China plant could end up being less favourable than originally expected.
Similarly, while the company is making progress with its higher-margin industry-specific programmes, it’s the lower-value VAR segment that’s driven most of the recent recovery in volumes.
I’m still optimistic that Victrex can expand its higher-value offerings over time, but I think it faces more competition than – say – a decade ago. I suspect it may struggle to regain some of the profitability that’s been lost over the last five years:

I’m also not sure whether today’s outlook guidance was a slight profit warning in disguise.
The 6%+ dividend yield is still tempting for me. But Victrex’s subdued profitability and increased net debt position are less appealing. With the shares still trading on c.14x FY25 earnings, I don’t think Victrex is necessarily cheap based on near-term expectations.
On balance, I’m going to take a slightly more cautious view than I did in December, moving my view down to neutral (AMBER).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Two issues for Cranswick. Seemingly horrendous farming practices and directors who seem more interested in their remuneration than the company. A sobering reminder of what american factory farming would look like.
Pay peanuts and you get monkeys, here and now, in the UK.
The FTSE 100 hasn't moved much as it's a rotation out of the more defensive names including gold as risk is firmly back on - mid caps and small caps have continued to move north: AIM closed above its 200 day moving average on Friday - first time in almost 7 months
meanwhile almost half of the names rallying today have short interest - shorts have continued to rise even as UK indices staged a V shaped recovery . Does suggest hedgies may be offside and highlights how hated this rally is - also worth noting that some of the best performers over the past few week have been some of the most hated names and sectors. Also a bullish sign . I post this kind of stuff on X - here
UK Total Shorts Keep on Rising - Total Daily FCA Disclosure since may 2024
Shameless plug - If you are interested in technical analysis and research using visualisation of market data - I will soon be doing a weekly newsletter with access to the data reports on my website runprofits.com - sign-up here.
Purpose is insightful data for DYOR so heavy on information, light on narrative/opinions with access to interactive data reports and tools
Good evening DScollard, you newsletter sounds interesting. Can I ask what’s your background with regards to trading / investing?
Warehouse Reit (LON:WHR) significant drop (10%) on valuation issues raised by Blackstone in PUSU extension of offer to 30 May
Rather unnsual and makes you wonder if they uncovered some things in due diligence and now want out - tempted to buy some on the dip but will probably watch on sidelines for moment.
"Previously, Blackstone, acting on behalf of its affiliated investment funds, had proposed a final indicative, non-binding offer of 115 pence per share for Warehouse REIT, adjusted for the interim dividend already paid. However, after due diligence, Blackstone raised concerns about the valuation of a key development asset, which has led to ongoing discussions between the parties.
Warehouse REIT, which had initially indicated its willingness to recommend Blackstone’s offer to its shareholders, is now working with its financial advisers and an independent valuer to address the valuation issues raised by Blackstone."
Classic last minute chipping the price situation sounds like. Probably they'll still agree a deal on a slightly lower valuation.
Given the price is no longer the price as it were, I will not be taking a position again. Who knows what they'll end up agreeing, or whether they'll fall out altogether. Could sink a lot further if they pull out of the deal (in which case personally I would be happy to take up a long term position again at that point).
Worth noting that Warehouse Reit (LON:WHR) is now trading at 95 pence versus a 130 pence NAV... now a lot cheaper than many other listed REIT's not in a takeover situation... Good risk reward, IMO
A NAV that is now under question to the point that a 115pence offer was no longer considered realistic by an acquirer for whom it should be a no brainer to buy and sell it in parts if the NAV is actually even close to fair though...
But maybe you're right, if you are happy to buy and hold for the (potentially) long term its still a good risk/reward
Re Tariffs.
US exports to China are mainly Soy bean and pork. Items China can get elsewhere and probably will get elsewhere given that they have a 10% tariff if they come from the US.
China exports to US mainly electronics, toys, manufactured items, clothes. Items fairly difficult to get cheaply elsewhere. The extra 10% added to the existing 20% tariff will probably be swallowed with little reduction in demand.
US trade deficit with China therefore likely to get worse. Impact on US is mainly the imposition of the 10% tariff on imports from China and other countries around the world. A substantially additional tax burden on consumers which will slow the economy.
Next is opposing a call from major investors at its annual meeting this week to reveal how many of its 40,000 staff are paid below the real living wage of £12.60 a hour.
Such a shame to see a very profitable company not sharing its success with their employees
Don't rely on the Card Factory (CARD) information shown. It is incorrect, showing results under the wrong year and not having been updated for the latest results. It has been reported.
Horrific abuse at Cranswick reported by undercover reporter. SP down 7% with major customer pulling out. As someone who has been involved with agriculture for 40 years, I find this disgusting and unacceptable. I owned Cranswick (LON:CWK) and sold this morning. For me it is a moral issue.
Factory farm supplying Tesco, Sainsbury's and Asda where helpless piglets are beaten to death: Horrific abuse carried out by sadistic workers is laid bare as supermarket giants cut ties with meat supplier | Daily Mail Online
We've covered that in the report, James, thank you for raising it.
As far as I can tell it is only the specific breeding facility that has been suspended - given Sainsburys signed a 10 year supply deal with Cranswick (LON:CWK) only a couple of months ago I doubt the supermarkets could suddenly turn off all Cranswick sourced supplies without the shelves emptying in certain product areas.
I don't like what I am seeing but will await the promised "investigation".
Sadly this is nothing new - another Red Tractor approved farm supplying Tesco faced similar allegations only last year and you have to wonder if the entire industry is suspect:
https://www.grocerygazette.co....
Is this one bad apple, is poor practice company-wide, or is abuse more likely given how labour is sourced in the industry? My suspicion is that consumers will need to pay a higher price for their meat if a higher level of animal welfare is to be consistently achieved. You probably need to CCTV every animal facility, and even then workers will just learn to evade the cameras.
Looking through the reporting it is clear company policy isn't being followed, and things like tail docking would be evident at an inspection, however much advance warning the local employees get of an HQ inspection. Was North Moor Farm an acquired facility? Cranswick are quite acquisitive, and they are also involved in pig-rearing JVs e.g. White Rose Farms after the 2020 acquisition of the Buckle family farming interests. Is Cranswick sufficiently hands-on with acquired & JV operations?
You have to assume the executive team are either unaware, or incredibly short-sighted. Stuff like this hitting the media when you are in multiple planning battles to establish new facilities is a very effective way to shoot yourself in the foot.
Monty Carlo - Thats a really well balanced response, thank you
Card Factory (LON:CARD)
Pre tax profit margins of 14% pre Pandemic, more recently closer to 12%, Peel Hunt now guiding mid-high single digits (6%-8%?)...ie. a company selling a commoditised product suffering from margin erosion.
I read and heard a lot of bemusement about why Card Factory sold off on the results, perhaps this is the reason? Just thought I would mention it as I only ever hear the bull case for Card Factory (LON:CARD) from Paul Scott & Richard Crow to name but a few...
On the one hand you can say the highstreet is doomed, NI increases = shrinking margins, competition from other high street brands etc
The bull case is they just pass along extra costs to customers and employees, make efficiency savings, diversify online, and are best placed to handle headwinds by being fully vertically integrated.
I believe in Card Factory (LON:CARD)'s case they've said the cost pressures will be cancelled out by efficiency savings, and beyond that passing along costs as needed. After that you either trust the management team or you do not - I lean towards trusting them, but only enough to buy in at a very low price - I hold a large position brought at an average of 83p or something, which I viewed as cheap.
Personally I think given the sector (not just retail, but selling cards which has a patchy history with Clintons etc) it should trade at a decent discount in perpetuity but not as heavy a discount as we have been seeing, but given they also have nice divis it is overall a happy holding for me.
Card Factory (LON:CARD)
Pre tax profit margins of 14% pre Pandemic, more recently closer to 12%, Peel Hunt now guiding mid-high single digits (6%-8%?)...ie. a company selling a commoditised product suffering from margin erosion.I read and heard a lot of bemusement about why Card Factory sold off on the results, perhaps this is the reason?
strewth you have to have been pretty blind if you have looked at card factory and not looked at the trend in bottom line margins - and its pretty obvious the recent hike in minimum wage and business rates and corporation tax has not helped ! - imho there is nothing surprising here simply confirming known facts that are no surprise.
Note card have recenly acquired a wholesaler too - so moving away from their core retail only model will also skew the margins made somewhat.
i would agree that part of the reason there is a lowly rating here is that the core retail model deffo faces moare headwinss than tailwinds - not sure this has ever been hushed up - pretty sure suggestions it has are pure nonsense . I would agree lower % of sales flowing through to bottom line is good rather than bad normally .
Just thought I would mention it as I only ever hear the bull case for Card Factory (LON:CARD) from Paul Scott & Richard Crow to name but a few
Huh thats just pure nonsense - for example that last commentary i can see from Paul Scott downgraded rating last October and mentioned the margin issues explicitly and was probably the reason for the downgrades. You can have your own verion of reality but that doesnt make it anything other than nonsense in the whole.
Per Ps October 2024
“HY25 Adjusted PBT was down £7.6 million to £14.5 million, reflecting substantial increases in National Living Wage, plus freight inflation and phasing of strategic investments. As previously guided, the benefit of our strategic investments and robust programme of productivity measures and efficiency savings in FY25 are weighted to the second half of the year and we have already seen these positively impact the cost base.”
Outlook comments - start off with this rather ambiguous point -
“Trading since the period end has been in line with the first half…”
Is that good or bad? The commentary talks as if H1 was good, but it wasn’t - profit was sharply down.
Cost pressures sound like they’re still an issue -
“Whilst macro-inflationary pressures have started to ease in the second half, we continue to manage specific retail impacts.”
I was green twice earlier this year, at 100p and 107p. We’re now at 122p, and H1 results have underwhelmed, putting more pressure on the H2 upturn to be particularly strong. Therefore I think risk:reward is not as good as it was when Teleios selling was suppressing the price (since gone).
Rmillaree,
I don't think that's fair to say I'm speaking nonsense, I would instead refer you to Paul's last commentary on CARD which was in his small caps podcast with Paul Hill 4 days ago. You will hear his ebullience towards the company and his bewilderment and confusion as to why it is not higher rated. That is all I have attempted to address.
For the record I think Paul is absolutely great, i'm a huge fan so please don't interpret my post as an attack, i'm just throwing out an alternative view to a highly popular, highly promoted small cap that everyone seems to think is undervalued.
Card Factory (LON:CARD)
It’s completely overvalued with a business model that will eventually fail.
Sorry to spoil the party.
All the best
Haha! I was trying to be subtler than that but thank you Yiannos!
Now then more importantly, did you buy any Synthomer (LON:SYNT) ? Definitely a bit of interest there the last couple of days.....
Synthomer (LON:SYNT)
Yes I have
Can you tell -:)
All the best
Card Factory (LON:CARD)
I don't think that's fair to say I'm speaking nonsense
happy to disagree with yourself - i quoted linked text here that confirmed Paul S had downgraded Card Factory per the last update he formally did here last year - how on earth does him downgrading the stock and flagging up uncertainty tally with your comment below
Just thought I would mention it as I only ever hear the bull case for Card Factory (LON:CARD) from Paul Scott
imho facts are your comments are at best misplaced/misleading - or worse than that malicious nonsense. Hopefully others can see that when Paul has commented he has commented on pluses and minuses ref this copmpany - whether he is positive or not.
i'm just throwing out an alternative view to a highly popular, highly promoted small cap that everyone seems to think is undervalued.
We all respect alternate viewpoints - your post is useful and valid commentary ref margins other than the assertion Paul has not flagged up bear point issues ref this company previously when he mostly certainly has done so - thats all i am trying to correct here - your text quoted above leaves little to the imagination in that regard and imho is plain outright wrong factuially speakaing imho.
ref podcast thing i havent seen it or been provided link - so i cant comment on that text - but prior commentary imho speaks for itself
There was nothing malicious , misplaced or misleading in Burnt Onions’ post above, just reporting facts, which clearly you don’t like.
Burnt Onions correctly pointed out that in the small caps podcast with Paul Hill last week, Paul Scott was once again saying that Card is undervalued and couldn’t understand why it’s so cheap, especially after the recent results. Maybe the cost pressures has left investors a little wary?
PS was very positive about it to say the least and his valuation was minimum £1.50. He owns but top-sliced before the results.There was a similar positive comment the previous week as well.
I personally don’t hold, good dividend, but the margins and sector, it’s not my thing.
There was nothing malicious , misplaced or misleading in Burnt Onions’ post above, just reporting facts, which clearly you don’t like
Happy too disagree with you too
the use of the phrase "only ever" has clear meaning - pretty much without exception the way i lok at it - i posted an example of when Paul was flagging up things not going so well.
If you go back to September 2022 here are Pauls comments on card
Card Factory (LON:CARD) - I review its interim results, and can see both bull and bear arguments. Overall though, the weak balance sheet, and total reliance on hefty bank facilities, doesn't give me enough confidence to want to invest as we enter a recession.
- this shows the lies that "he has only ever been positive" - i he aint always been positive and in all articles he has posted here formally he has posted plus and minus points very clearly.
Perhaps my annoyance is slightly over the top - but i dont take kindly to people saying black is white - clearly Paul has been positive and negative on this share in the past,
Thats my point nothing more nothing less - its easy to sling mud at well know people but its nicer if its done with facts rather than distoring or exaggerating facts. Its easy to throw mud in kind subtle factual way without going ott - in that regard i feel Burtn Onions was over the top and owes Paul a minro apology - there ya go.
That was nearly 3 years, think he was talking about more recently.
September 2002! That’s a lifetime away in the stock market.
As I mentioned previously PS in the last 2 small cap podcasts, has really been banging the drum about Card. It might even be more than that as it’s one of his stocks of the year “I love it”. Maybe you should clam down and listen to the podcasts before you burst a blood vessel, you’re embarrassing yourself. An apology! now that is laughable
each to their own i have said my piece - you are obviously igoring the principlem involved here of what was said - no biggie to me i am certainly not bursting a blood vessel here - and the fact i think apology was owed doesnt mean didly squat really.
Product mix - they're now a 'celebrations' co and sell more of those products (balloons, gifts etc) than cards, hence lower margins.
Temu. Moonpig. Tesco for that matter and Nisa/Coop. A dry moat.
Gamma Communications (LON:GAMA) in reverse despite moving to the main market
Gamma Communications (LON:GAMA) Blackrock selling some more?
The chart would suggest some profit taking here. I still feel this is all part of a long term bottom inverse H&S but I did sell early today. I may buy back in if inverse H&S starts to materialise.
Worth a mention on the productive trade discussions over the weekend between China and the US. Announcement expected today with details but it's already driving some major pre market gains. Imagine it would lift wider market.
100%, I can't believe there hasn't been wider discussion of this, the papers are implying it's a done deal.
100%, I can't believe there hasn't been wider discussion of this, the papers are implying it's a done deal.
Depends on your definition of "done": 90 day "de-escalation" with tariffs cut by 115% on both sides.
Sadly all those Trump induced bargains have now melted away, just like his tariffs.
timarr
To be fair trump did tell everyone to buy stocks last Thursday.
Perfect a US President providing inside information! The only thing a sound investor needs to understand is he tells fibs to suit his own agenda. So the drive for risk today is absurd. You cannot invest in risk if you can't have some confidence on the outcome. Less sophisticated societies understood you don't build your house on sand and a leaders character is more important than his policies (because they might not be his policies.)
He also sells Tesla's if your interested in buying one, and overvalued worthless meme coins
Just sold mine.
Absolutely right! Trump is manipulating the market. Caused it to crash with his 'Liberation Day' and probably bought a huge amount of stock (or his lackeys did) knowing full well that when he backed down on tariffs the markets would rocket and he would make a fortune. This will no doubt be discovered one day and the 'leader of the free world' will be found out for the insider trading he has surely been orchestrating.
i highly doubt it, who's going to police him? He's broken more laws that my deceased grandmother and managed to wriggle out of every situation
Agree that there’s no chance of proving Trump manipulates the markets, though it was obvious that was also his game when he was last President.
And the Supreme Court have said that he cannot be held liable for any crime he commits whilst the President. Genius.
Hi Graham - Rio Tinto (LON:RIO) have announced a JV with Sumitomo Metal Mining on the RNS this morning. Share price is up 5%. Worth adding to your agenda table just to highlight it. Cheers
Will do, Gung Ho!
Venture Life (LON:VLG) Sale of CDMO capabilities to generate one-off profit of £24.1m. Quite significant given the market value of Venture Life (I hold).
Can anyone explain what IG group (LON:IGG) changes to reserve management means? Will this release meaningful funds for further buy backs or dividends?
’as announced on 13 March 2025, the Group plans to increase its distributable reserves by reducing its share premium account and merger reserve, with a corresponding increase in retained earnings. Regulatory approval was received on 26 March 2025 and the Group has scheduled a General Meeting for 29 May 2025 to request shareholder approval, with a circular due to be published imminently.’
IG group (LON:IGG) - Neil, it sounds like they are running out of distributable reserves, so this is just a technical change to convert some of their undistributable reserves into distributable reserves to enable them to continue dividends and buy-backs. You need both cash and distributable reserves to pay dividends and buy-backs.
Good morning Neil, I have attempted to explain this in my section on IG today! Hope that helps. G
That’s really helpful thank you!
Nice trading announcement from IG group (LON:IGG) . Read across to CMC Markets (LON:CMCX) ?
CMC Markets (LON:CMCX) currently down over 3%.
Another contract win for Synectics (LON:SNX. Just £1.1m, but the interesting part for the longer term holders is "The pilot is expected to be completed within twelve months, with the expectation that it is deployed more widely upon successful completion."
I had a funny feeling news would be out this morning after the spike up on Friday from lunch time onwards. Hate it when news is leaked and I have seen it before with Synectics, but it is what it is.