Daily Stock Market Report (Mon 13th July 2026) - MEGP, BBSN/SYS1, CNC, PAGE, EGT, PLUS, ONT

There has been little change over the weekend in terms of the Iran situation: more tit-for-tat attacks with the US, and disagreements over whether or not the Strait of Hormuz is currently open.
Oil continues to creep higher and is now over $79, having fallen towards $70 when optimism over the ceasefire and the peace negotiations was highest.
In sport, Wednesday evening will see England vs. Argentina, with England taking on Lionel Messi for the first time. That match is at the respectable time of 8pm (as is the World Cup final on Sunday night).
Overnight market movements:
The FTSE is down 0.2% at 10,470
S&P 500 is down 0.6% at 7,530
Brent crude (September) is unchanged at $79.35/bbl
Gold is down 1.7% at $4,050/oz
Bitcoin is down 2.1% at $62,850
Wrapping it up there for today, thanks all. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£79bn | SR87) | Clinically significant rate of participants showing no detectable signs of cancer one year or more after treatment. Results support the potential for dostarlimab to eliminate the need for chemotherapy, radiation and surgery in some patients. | ||
Plus500 (LON:PLUS) (£3.4bn | SR86) | H1 revenue +12% to $462.9m, EBITDA +1% to $187.5m. FY26 revenue and EBITDA expectations unchanged. | AMBER/GREEN ↓ [BLACK (profit warning) against H1 expectations, but full-year expectations are unchanged] (Graham) | |
Derwent London (LON:DLN) (£2.24bn | SR73) | The new RCF has a five-year term with two one-year extension options and a £50m accordion option. Margin and covenants are in line with existing bank facilities. | ||
Grafton (LON:GFTU) (£1.66bn | SR93) | H1 revenue +6.7%, including contributions from acquisitions HSS Hire Ireland, Cygnum and Mercaluz. Average daily LFL revenue +0.6%. Great Britain remains weakest market, with daily LFL revenue -5.2%. FY guidance for adj op profit of £190-£200m is unchanged. | ||
Oxford Nanopore Technologies (LON:ONT) (£1.17bn | SR30) | SP -8% H1 revenue up c.10% to c.£116.5m. H1 trading below management expectations, due to China (-16%) and the Middle East (-14%). Timing of new orders and contract wins also impacted H1 performance. FY26 guidance: revenue growth unchanged: up 21-25% at constant currency. Excluding some one-off items in H2, revenue is expected to be up 16-20%. Gross margin guidance remains c.62%. | BLACK (AMBER/RED) (Graham) [no section below] I haven't studied this one in detail but I'll go AMBER/RED on it considering the StockRank of only 30, the consistently loss-making track record, and the H1 profit warning today. Full-year revenue guidance is unchanged at 21-25% but this includes some new non-recurring items. Excluding these items, it sounds like we are heading for a revenue miss of about 5%, with underlying growth of 16-20%. The shortfall in the Middle East is readily explained, but the shortfall in China is attributed to "enhanced export control restrictions and changes to commercial operations in the region". These don't sound like problems that can be expected to go away very very quickly? The company has reiterated guidance for EBITDA breakeven in FY27. As I'm generally very cautious when it comes to companies that are not yet at EBITDA breakeven, it's natural for me to take a moderately negative stance here. | |
Rank (LON:RNK) (£439m | SR56) | Harris has served as interim CEO since January 2026, so is already in place. He was previously Rank’s CFO (since 2022). | ||
Pagegroup (LON:PAGE) (£422m | SR51) | SP +13% Q2 gross profit -0.2% to £197.6m. “Improvement and signs of normalisation” in a number of markets. FY26 expectations unchanged for operating profit of c.£20m. | AMBER/RED = (Roland) [no section below] My thanks to Tortoise Investor in the comments for sharing his first-hand experience of Page Group. Such scuttlebutt provides useful detail to contrast against top-level financial updates. In today’s Q2 update, Page says that 50% of its markets have now returned to growth. That’s true, although when measured by gross profit rather than region, only 37% of the business showed growth in H1. The recruiter’s largest region, EMEA (52% of gross profit) saw GP fall by 6.9% on a constant currency basis in H1. The UK (11% of GP) was even weaker, down 8.2%. We already know things are bad for recruiters, though. The question is whether the market has already discounted all the bad news necessary to see through the current weakness. Today’s share price gain suggests that perhaps we have now seen the bottom. However, I share Graham’s concern that there’s a risk that technology has brought a permanent structural change to the recruitment business that may be reflected in lower structural profitability going forward. With “a high degree of uncertainty” cited in the CEO’s outlook comment, I’m going to leave our cautious view unchanged for a little longer. | |
ME International (LON:MEGP) (£387m | SR71) | Revenue flat at £154m with pre-tax profit down 4% to £32.7m. Net cash of £7.5m (H1 25: £27.6m). FY26 outlook: has seen a return to more normal trading patterns in H2. Remains on track to meet revised FY26 expectations for PBT of £69-74m. | AMBER/GREEN ↑ (Roland) With slight trepidation I’m upgrading our view by one notch today to reflect the apparent value on offer – this remains a high-margin, cash-generative business with a credible growth plan (in my view). The caveat is that ME warned on profits in June and has included a geopolitical caveat with today’s unchanged full-year guidance. With the stock down 50% over the last year and profits largely unchanged, I think the risk is probably in the price. | |
Gulf Keystone Petroleum (LON:GKP) (£372m | SR79) | Following the recent restart of production and exports on 24 June, gross volumes have now reached “over 43,000 bopd”. Activities are underway to bring additional production online. Discussions continue regarding export sales. | ||
Puretech Health (LON:PRTC) (£292m | SR21) | The first patient has been dosed in the global Phase 3 SURPASS-IPF trial evaluating the superiority of deupirfenidone 825 mg three times daily (TID) vs. pirfenidone 801 mg TID for the treatment of idiopathic pulmonary fibrosis (IPF). | ||
Concurrent Technologies (LON:CNC) (£217m | SR45) | Expect H1 revenue +9.5% to £23.1m with pre-tax profit +22% to £3.3m. H1 order intake +110% to £46.9m vs prior year, including a c.£17m multi-year order. FY26 results expected to be “at least” in line with current expectations (consensus: pre-tax profit of £8m) | AMBER = (Roland) A solid update from this defence-focused business confirming that last year’s double-digit revenue and profit growth is expected to be repeated in 2026. However, despite the potential for an upgrade later this year, there’s no change to expectations. With Concurrent stock trading on a rolling forward P/E of 30, I think the share price is up with events. I’m leaving our previous neutral view unchanged today. | |
Brave Bison (LON:BBSN) (£105m | SR34) | Terms of possible offer: 68 pence in cash and 2.7553 new BBSN shares. Equates to 327p using 20-day VWAP for BBSN. GN note: equates to 317p using Friday’s close for BBSN. Friday’s close for SYS1: 301.2p. | TAKEOVER (AMBER/GREEN = on BBSN and SYS1) (Graham) | |
Avation (LON:AVAP) (£82m | SR44) | Following recently announced leases, the fleet is now 100% utilised with a weighted average remaining lease term of 4.1 years. Currently has 13 ATR 72-600 on firm order for delivery through to 2029. Trading remains in line with expectations. | ||
Ondine Biomedical (LON:OBI) (£81m | SR18) | The Company has updated the expected timeline for release of topline results from the LANTERN Phase 3 study. Results are now expected within approximately six weeks (previously 1-2 weeks) reflecting new guidance on the time required to complete data management activities. | ||
Poolbeg Pharma (LON:POLB) (£49m | SR28) | The trial is investigating POLB 001 as a potential preventative therapy for Cytokine Release Syndrome ("CRS") in patients with relapsed/refractory multiple myeloma receiving the approved bispecific antibody, teclistamab. University College London Hospital (UCLH) has now also been activated as a clinical trial site. | ||
Cobra Resources (LON:COBR) (£45m | SR9) | Bornite-rich zone associated with porphyry intrusion adds scale to shallow high-grade intersections. Cobra has exercised its option to acquire Manna Hill | ||
80 Mile (LON:80M) (£44m | SR13) | The drill rigs have been securely cemented at the first drill locations at Disko, with pressure testing successfully completed. Drilling is now underway towards the top of the target zones. | ||
Zenith Energy (LON:ZEN) (£28m | SR24) | Acquires an additional 4.5 MWp ground-mounted photovoltaic development project in Rome (“located within the Metropolitan City of Rome in the Lazio region of Italy”!). | ||
European Green Transition (LON:EGT) (£24m | SR16) | Following its acquisition, EGT’s Wind Energy Services business delivered strong momentum through Q2. Expanding order book. | AMBER/RED (Roland) [no section below] EGT appears to be transitioning from a mining explorer into a wind energy services business. Of the two, I would certainly prefer to own the latter as I know that repowering and otherwise upgrading existing wind turbines (usually onshore) is a growing business in the UK and Western Europe. The company’s presence in Wind services has been expanded through a recent acquisition and today’s update reports a significant increase to the repowering orderbook, including an increase in projects completed. My difficulty is that there are no forecasts in the market for EGT and the business appears to have zero historical revenue. Without doing some in-depth research, forming a view on valuation is difficult. Given the company’s seemingly recent change of focus and the historic lack of income, I’m going to opt for a cautious view today. But an H1 update is due soon and if the Wind business starts generating meaningful financial activity, then I’d be open to taking a closer look at this business. | |
Genedrive (LON:GDR) (£21m | SR17) | Expects to report total income of c. £1.4m for FY26 (FY25: c. £1m), in line with expectations. “The commercial and operational progress achieved during FY26 reinforces the Board's confidence in the long-term opportunity for both products.” | ||
IXICO (LON:IXI) (£20m | SR17) | Since the half year, two existing Huntington's disease supported by IXICO have been discontinued by their sponsors, reducing the Company's contracted order book by approximately £1.5m over next two financial years. FY26 and FY27 revenue guidance remain unchanged. Programme descoping is reflected in the Company’s forecasting. | ||
Potter & Moore (LON:PAM) (£17m | SR76) | Revenue down 0.4%. PBT down 19.3% (£2.8m). Net cash £3.2m. Changed its name from Creightons and moved from Main Market to AIM. “The Group will continue to face challenges during FY2027, again largely due to factors outside the Group's control…” | ||
Aptamer (LON:APTA) (£16m | SE10) | FY June 2026 revenue c. £1.5m (up 25%). Cash runway into “at least 2028”. | (GN note: no mention of performance vs. expectations or profit/loss.) | |
Pennant International (LON:PEN) (£13m | SR34) | H1 revenues +31% (c. £5.9m). Adj. EBITDA £0.5m (H1 last year: loss £1m). Adjusted loss before tax £0.3m. H2 to be stronger than H1. On track to achieve full year 2026 market expectations. | ||
Alien Metals (LON:UFO) (£11m | SR31) | Independent geochemical review of the Munni Munni PGE-Cu-Ni Project provides “a new and compelling framework for understanding the broader untested potential of the Munni Munni intrusive complex.” Identifies “discrete high-priority exploration targets around the base of the intrusion”. |
Graham's Section
System1 (LON:SYS1)
Up 0.4% at 306.2p (£39m) - Graham - TAKEOVER (AMBER/GREEN =)
RNS from Brave Bison (LON:BBSN): Possible Offer for System1 Group Plc
RNS from System1 (LON:SYS1): Response to announcement by Brave Bison Group plc
In my call with the CEO and CFO of System1 last week, I mentioned the interesting situation with Brave Bison to them, while acknowledging that they wouldn’t be able to tell me anything that wasn’t already in the public domain. And they didn’t tell me anything - but now we learn that there was indeed a lot going on behind the scenes!
On Saturday, The Times scooped that Brave Bison was preparing a bid for System1 (the 72% of it that they don’t already own).
Brave Bison confirms that “collaborative discussions have been underway between the boards of Brave Bison and System1 Group plc… regarding a potential combination.”
System1 rejected the initial approach, with an important “but”:
Whilst the board of System1 rejected Brave Bison's original proposal on grounds of value, it has acknowledged in discussions that a combination of the two businesses has a strong underlying industrial logic.
This is a widely-held view: that it would make sense to strip out some of System1’s overhead by combining it with another group. At its current scale, it has struggled to generate the attractive profit margins of which it should be capable.
The Combination would create AIM's challenger marketing data and technology company with pro-forma net revenues of £79 million and Adjusted EBITDA of £14 million on a pro-forma basis. This pro-forma does not include cost savings derived from duplicate board, plc, property and IT costs which have the potential to increase profitability further.
Details of the offer
There was an all-share approach which valued System1 at 297p.
This has been revised to: 68p in cash and 2.7553 new BBSN shares.
To come up with an estimate of total value for this, Brave Bison uses the 20-day VWAP (volume-weighted average) of their share price, which is 94p. This gives a total value of 327p.
However, their closing share price last week was a little lower than this, at 90.5p. If we use that instead, the total value is 317.35p.
At 327p, the premium against SYS1’s share price last week is 7%. At 317.35p, the premium is only 4%.
This is an unimpressive premium, no matter which way you cut it. Which leads us to System1’s response.
They tell us that the initial proposal was received over a month ago, on 8th June, and “represented no premium to the System1 share price at that time”. But they nevertheless engaged with their largest shareholder:
…acknowledging Brave Bison's position as a major shareholder of System1, the Board has engaged constructively and shared certain information with Brave Bison. This has led to a period of dialogue with the intent to help Brave Bison materially improve the terms of its Initial Proposal.
On Friday, System1 learned of the new bid (the “Revised Proposal”), including cash and shares:
[The Board] has considered the Revised Proposal with its advisers and believes it materially undervalues System1. The Board unanimously and unequivocally rejects the Revised Proposal.
The Revised Proposal does not include any notable premium for control of System1.
They note that the premium being offered now is indeed 4%, using Friday’s share prices for the two companies..
Graham’s view
There are a few interesting features around this M&A situation.
Brave Bison, being System1’s largest shareholder, has to be treated respectfully by the System1 board.
On the other hand, making a zero premium takeover offer, or even a 4% premium, isn’t very respectful.
Brave Bison must think that System1 shareholders are really desperate for a takeover, for this to even be entertained. And they may be right to some extent - plenty of System1 shareholders probably do want a takeover to happen. But I’d find it strange if they were willing to accept a negligible premium to their existing share price.
The only case when a zero premium makes sense to me is when you get an all-share merger of equals. In that case, two companies between one and each shareholder group are left with about 50% ownership of the total.
But that’s not the case here. Brave Bison is worth over £100m, while System 1 is worth less than half that. Even if it was an all-share deal (which System1 doesn’t want), System1 shareholders would be left in the minority. Under the revised proposal, System1 would own 19% of the combined group. And so it’s reasonable for them to expect to receive a control premium.
Having said all of this, the industrial logic makes total sense to me. In the words of Brave Bison:
The enlarged group would have a highly desirable revenue mix, with approximately 58% of net revenue derived from high-margin, low marginal cost, scalable platform solutions. Furthermore, revenue would be diversified across UK, EU and US, with over 700 customers, and limited customer concentration risk.
The marketing technology landscape is undergoing rapid and fundamental change, and AI-native capabilities are fast becoming the price of entry in modern markets. Well-resourced competitors are moving quickly, and the businesses best placed to lead are those with the financial firepower, talent platform, and technical infrastructure to invest decisively and at pace.
This takeover should happen - it’s just a question now of whether the two sides can find an acceptable compromise. My feeling is that Brave Bison should be the first to budge.
Plus500 (LON:PLUS)
Down 16% at £41.50 (£2.88bn) - Half Year 2026 Trading Update - Graham - AMBER/GREEN ↓ [BLACK (profit warning) against H1 expectations, but full-year expectations are unchanged]
Plus500, a global multi-asset fintech group operating proprietary technology-based trading platforms, today announces its trading update for the six-month period ended 30 June 2026.
The market doesn’t like this update, even though it emphasises that FY 2026 revenue and EBITDA guidance is reconfirmed.
Key points:
H1 revenue +12% (Q2 revenue +5%)
H1 EBITDA +1% (Q2 EBITDA +1%)
CEO comment: highlights recent launches in the US and Canada.
"H1 2026 delivered the strongest Customer Income in five years and the highest revenue in three years, reflecting the quality of our customer base, the power of our proprietary technology, and the growing breadth of our global platforms…
…The Board expects FY 2026 revenue and EBITDA to be in-line with current market expectations, following several upgrades this year."
US: “Plus500 has established itself at the centre of the US prediction markets industry… In February 2026, the Group launched its B2C prediction markets offering and, in June 2026, launched its next-generation offering with CFTC-regulated sports event-based contracts, representing the highest-engagement category in prediction markets.” (website can be found here).
Canada/Japan: Canada gets a new localised OTC platform, while Japan gets an “enhanced multi-asset product offering, tailored for the local market”.
Outlook:
Plus500 enters H2 2026 with strong operational momentum and with a broader, deeper and more competitively differentiated strategic roadmap across both its OTC and non-OTC businesses…
Supported by a robust, debt-free balance sheet, proven best-in-class proprietary technology and a growing pipeline of B2B and B2C opportunities, the Company's Board of Directors is confident in the Group's prospects and expects FY 2026 revenue and EBITDA to be in-line with current market expectations, following multiple upgrades this year.
Estimates: the RNS hopefully provides market expectations for FY 2026: Revenue of $811.5m and EBITDA of $368.1m.
Peel Hunt are quoted on Proactive Investors saying the following (emphasis added):
"Revenue was a 4% beat versus consensus, while EBITDA was 3% below consensus, as Plus500 increased investment in customer acquisition, contributing to 17% growth in new customers, but no change in the FY26 expectations in current consensus."
It’s important to note that it’s perfectly possible for the company to miss H1 expectations while still maintaining full-year forecasts.
Cavendish have said something similar in a note published today: that Plus500’s Q2 revenue beat their expectations, but that EBITDA was below expectations, with higher than expected churn. They say “...we believe that the lack of upgrades given the macro environment and share price performance YTD might be perceived as slightly disappointing.”
Graham’s view
With H1 EBITDA of £187.5m, they’ve already secured 50.9% of the full-year forecast. And bear in mind that the market was expecting a slightly higher number than this: it seems to me that the market was expecting about 52.5% of full-year EBITDA in H1.
The revenue picture is even more interesting. The company has already achieved 57% of full-year revenue expectations.
Given the level of product development and the launches that occurred in H1, and the revenue that was achieved, I do think it’s reasonable to be surprised that there is no upgrade.
However, the company has rebuffed that notion, effectively telling us that we’ve had enough upgrades for now.
The conclusion? That H2 might be very quiet, compared to H1.
That does make some sense, considering the extraordinary drama in H1 as Trump’s war on Iran helped to spike the volatility punch bowl:
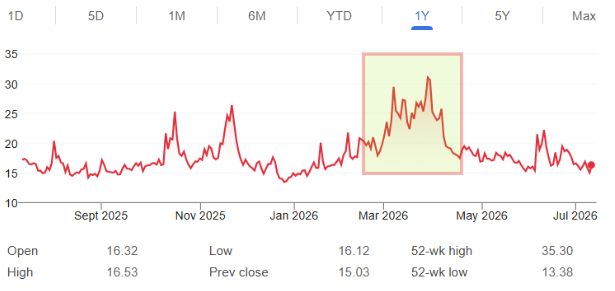
Vix Volatility Index. Source: Google.
With Vix now at the lower end of the range, it’s logical that Plus500 might expect a quieter H2.
But it’s also the case that customer acquisition has been a little more expensive than expected, as the company spent big to replace customers who fell away. Revenue grew 12% but EBITDA didn’t, due to this marketing spend:
EBITDA increased by 1% YoY to $187.5m (H1 2025: $185.1m), equating to an EBITDA margin of 41%, reflecting the flexibility of the Group's operating cost base and its ability to invest in growth while maintaining strong profitability. During H1 2026, the Group deliberately increased investment in customer acquisition, driving a 17% increase in New Customers…
There’s nothing wrong with an EBITDA margin of 41%, but it was 45% in H1 last year (and 46% the year before that).
Overall, then, we have a picture of deteriorating (albeit still very high) profitability, and a big drop-off expected in H2.
I’ve been GREEN on this stock for a long time, and I don’t think today’s announcement changes the big picture.
There’s a little disappointment on customer churn and marketing spend, but the company did successfully replace its outgoing customers and achieve very high revenues - and should be easily on track for full-year expectations.
I’m going to put us on AMBER/GREEN today, with my downgrade respecting the market’s disappointment, the lower profit margin, the miss against H1 EBITDA expectations, and the higher customer churn. We also had an unusually high (for PLUS) P/E multiple, going into today’s update:
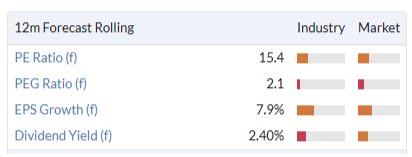
Long-term, I’m still a believer in this company. So I’ll be keen to get us GREEN on it again at the next reassuring update.
Roland's Section
ME International (LON:MEGP)
Up 11% at 115p (£432m) - 2026 Interim Results - Roland - AMBER/GREEN ↑
Trading during the first five months of the 2026 financial year was broadly in line with the Board's expectations, although in April the Group experienced a slowdown in vending revenue, principally driven by a significant reduction in photobooth activity in a small number of countries.
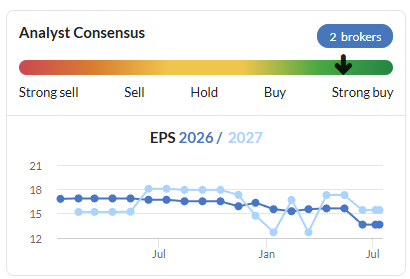
Today’s half-year numbers follow a profit warning in June from this instant-service equipment group, which I covered here. Brokers cut earnings forecasts by 12.8% following June’s update:
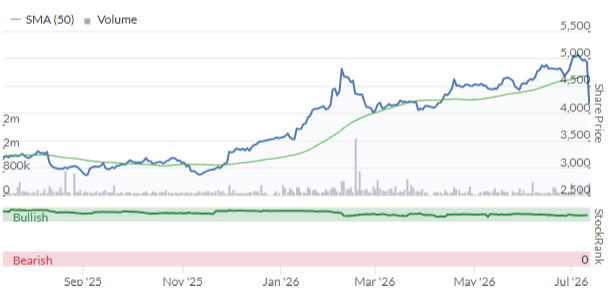
Markets were evidently fearing further bad news today as ME shares have responded positively to today’s unchanged full-year guidance:
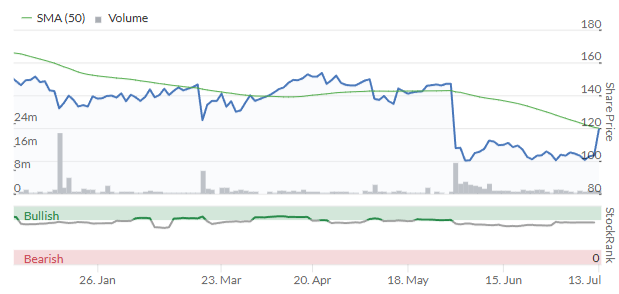
Let’s take a look at today’s results
Half-year results: key points
ME Group’s headline figures for the six months to 30 April 2026 show (real) profits dipping slightly on flat revenue:
Revenue: £154.3m (H1 25: £153.8m)
EBITDA up 7.1% to £57.0m
Pre-tax profit down 3.8% to £32.7m (down by 6.2% at constant currency)
H1 earnings down 3.9% to 6.48p per share
Interim dividend down 6.5% to 3.6p per share
Net cash down 73% to £7.5m
April sales slump: June’s profit warning was triggered by a sales slump in France affecting both laundry and photobooth demand:
[...] the Group's overall H1 performance was impacted by trading in France in April, which the Board believes was largely attributable to a shift in consumer spending patterns and lower consumer confidence due to the Middle East conflict.
France is described as “the group’s largest and most profitable market” but ME doesn’t provide a country-level breakdown of revenue, so we can’t see how significant the impact really was.
German passport photos: last year’s regulatory changes in Germany also continued to place a drag on photobooth revenue in H1. Changes to photo ID regulations last year “require passport photos to be taken in the citizens’ office or by certified photographers”.
ME says it’s developing new machines incorporating “liveness detection and anti-spoofing technologies, designed to meet the new requirements”. Deployment is expected to start in H2 2026, so revenue could recover over the coming years.
WASH.ME is cleaning up: one of ME Group’s self-service laundry units has recently appeared in the car park of the Co-Op supermarket in my local town. According to the company, it’s one of 499 net machines installed during the first half of the year, with a further c.800 installations planned for H2.
A recent deal with Asda seems likely to accelerate UK growth – the company is targeting up to 700 machines across ASDA sites “in the longer term”. This is said to be the largest partnership in the company’s history.
For the first time, WASH.ME contributed more than half the group’s profit in H1.
Segmental results: the majority of revenue and profit comes from the photobooth and laundry businesses, so I’ll restrict this overview to these two key units:
PHOTO.ME
Revenue down 6.4% to £79.0m
EBITDA down 8.1% to £27.3m (47.7% of group EBITDA)
EBITDA margin: 34.4% (H1 25: 35.1%)
Number of units in operation down 0.7% to 30,356
Capex rose to £8.2m in H1 (H1 25: £5.7m) as the company continued to roll out its next-generation photobooths, mainly in France. These are said to be “multi-functional” and should require less maintenance while generating higher revenue.
The rollout still has a long way to go though – 4,362 next-generation machines had been installed at the end of April, less than 15% of total number in operation.
WASH.ME
Revenue up 15.6% to £60.0m
EBITDA up 20.9% to £30.7m (53.9% ot GROUP EBITDA)
EBITDA margin: 51.2% (H1 25: 48.9%)
Number of units in operation up 16.1% to 8,106
The company is continuing to roll-out new products and features. These include 200 dog washing machines “following successful trial”. I think these are being installed alongside laundry units so that pet owners can wash their dogs out of home.
Capex rose in this business too, up 3.5% to £14.9m.
Profitability & Balance Sheet: under pressure?
ME Group’s quality metrics are generally very strong and the group has historically maintained a net cash position on the balance sheet.
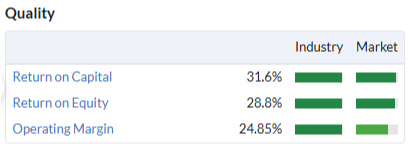
H1 margins were below last year’s full-year result, but were consistent with H1 in the prior year:
H1 operating margin: 21.7% (H1 25: 21.5%)
Trailing 12-month return on capital employed: 32.0%
Last year’s profits were weighted to the second half of the year, as is the norm for this business. A similar H2 weighting is expected for FY26.
Net cash: £7.5m (H1 25: £27.6m)
The decline in net cash is pretty significant, but I don’t think it’s necessarily a concern. Checking the balance sheet and cash flow statement shows an £8m increase in inventories and some working capital outflows. Capital expenditure over the period also rose, with purchase of PP&E rising to £32.2m (H1 25: £27.6m).
All of this fits the profile of a business that’s investing in expansion – assuming this continued investment drives a recovery in revenue and profit growth, then I don’t think it should be a concern.
Outlook: H2 weighting, but no change to guidance
The H1 slowdown in France is being billed as a temporary blip from which the company is already recovering:
In H2 2026 to date, the Group has seen a return to more normal trading patterns, with total vending revenue for May 2026 11.1% higher than May 2025. Wash.ME and Photo.ME vending revenues increased 25.9% and 1.8%, respectively. The positive revenue trend continued in June.
June’s revised full-year guidance is unchanged today, with the caveat that “geopolitical factors [...] may lead to a softening of trading patterns”:
ME Group remains on track to meet revised full year expectations and for FY 2026 profit before tax to be in the range of £69 million to £74 million.
We don’t have access to broker coverage for this business.
Using Stockopedia consensus figures, this morning’s share price rise leaves ME stock trading on a forward P/E of 8.3 with a possible 7%+ dividend yield.
Roland’s view
Zooming out on the chart reminds us that this business has had periodic ups and downs before:
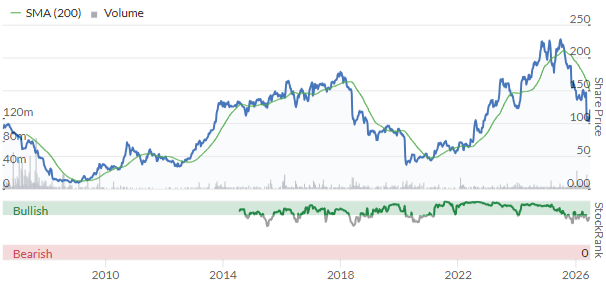
Our research has found that companies often underperform for an extended period of time after an initial profit warning. In my opinion, today’s outlook commentary is deliberately worded to leave some wiggle room if macro conditions do worsen again during the remainder of the year.
On the other hand, sometimes one-off factors do affect performance without signifying an underlying issue. That could be true here.
The StockRanks style this as a Contrarian share, with strong quality and value but (very) low momentum:
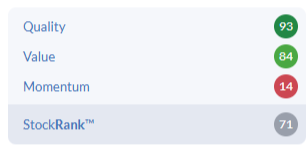
Today’s results don’t appear to highlight any serious issues. On this basis, I think ME shares are likely to be attractively valued at current levels on a medium-term view, given the group’s historical profitability and cash generation.
I can’t rule out the risk of further disappointment later this year, though. I’d also note this business has a slightly unfortunate record of accounting problems (see June).
On balance I feel I should upgrade our view to AMBER/GREEN today to reflect the value on offer. While such cheapness implies a certain risk, I think there’s a good chance this is reflected in the current valuation – the stock has fallen by c.50% over the last year.
Concurrent Technologies (LON:CNC)
Up 2% at 255p (£222m) - Trading Update - Roland - AMBER =
There is nothing to dislike about today’s update from defence-focused computer group Concurrent Technologies, but at the same time I can see why the shares haven’t really moved.
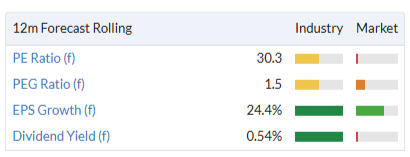
Sprinkling the word record liberally through management commentary doesn’t change the fact that this update is in line with expectations, with a strong (albeit expected) H2 profit weighting required to meet guidance. Given the valuation metrics, a measured response from investors seems fair to me:
Key points - continuing momentum
Here are the key points from this morning’s half-year update, which covers the six months to 31 June:
Revenue expected to be up 9.5% to £23.1m
Pre-tax profit to be up 22% to £3.3m
H1 order intake up 110% to £46.9m
Excluding a recent c.£17m win, H1 order intake was still ahead of “any prior half-year period”
More broadly, Concurrent appears to be making progress in both its core Product division and the nascent Systems business. The company is also on track to expand its manufacturing capacity:
Design wins: Concurrent secured further design wins in both Product and Systems “with a projected lifetime value of approximately £129m”.
Product: “more modest order intake in the first quarter, followed by an improvement in the second quarter, providing greater revenue visibility in the second half”.
Systems: secured orders totalling $8m in H1 “and delivered a profitable first half”. The Systems business is expected to become “increasingly material” to group performance over the medium term.
Colchester factory: expansion is going to plan, with manufacturing capacity expected to “approximately double from Q3 2026”.
Memory shortages are a big issue in the computer industry currently, due to demand from deep-pocketed AI buyers. However, Concurrent says it has been able to manage these issues so far, “securing supplier commitments for forecast DRAM requirements through 2026 and into 2027”.
Outlook
The Company has entered H2 FY26 with good momentum, demonstrated by the $9.4m contract win announced post period end. Combined with a healthy backlog and pipeline and the expected conversion of design wins into production in H2, the Board believes that the Company is well positioned to at least deliver full year results for 2026 in line with current market expectations*.
The term “at least” suggests the risk is to the upside here, perhaps with the potential for an upgrade to guidance later in the year.
For now, expectations are unchanged. Details of current consensus expectations are helpfully included in the RNS:
FY26E revenue: £53m (+15.5% vs FY25)
FY26E pre-tax profit: £8m (+23% vs FY25)
The growth rates implied by these forecasts are very similar to those of 14% and 25%, respectively, achieved in 2025.
This is a good update that suggests Concurrent is maintaining the strong momentum of the last couple of years. Although these forecasts imply a 60/40 weighting to profits, we’ve got used to seeing H2-weighted results from this fast-growing business. I don’t see this as a particular concern.
Roland’s view
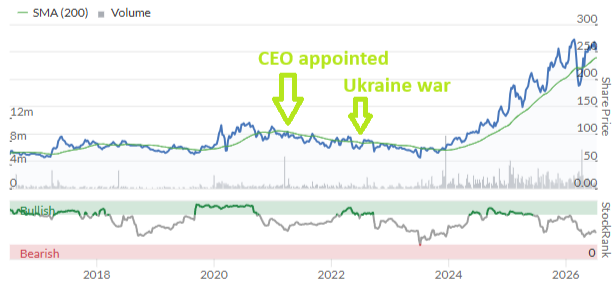
Since taking charge in June 2021, CEO Miles Adcock has rejuvenated a previously somewhat stodgy business.
Without wanting to take anything away from this achievement, I would argue that Adcock has also benefited from one of the greatest gifts that a new CEO can receive – wonderful timing.
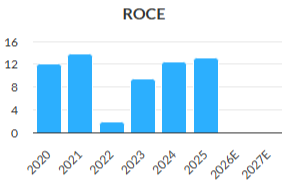
Profitability has not particularly improved, to date:
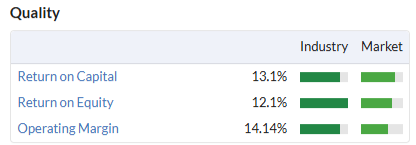
And while Concurrent’s quality metrics are respectable, they are not exceptional:
The StockRanks also have a somewhat mixed view, perhaps reflecting the stock’s High Flyer status:
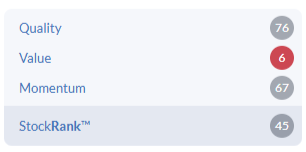
With Concurrent Technologies now trading on a forward P/E of 30, I would want to see a material upgrade to guidance or improved profitability to justify taking a positive view. I don’t see that today, so I’m going to leave our previous neutral view unchanged.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Space Exploration Technologies (NSQ:SPCX) almost back to its IPO price it seems. Wild IPO so far. If it goes far below IPO price I assume this would effectively kill the 2 other big IPOs for the near term?
I saw this interesting headline in my newsfeed today: "Fed could bail out Wall Street after market crash, says ING chief."
As if it wasn't enough of a casino already.
Funding Circle Holdings (LON:FCH) time to take profit ? reporting this wek
Elixirr International (LON:ELIX) daily grind lower, should be an update this week. Nervous times
I hold Elixirr International (LON:ELIX) too, and have for some time. Quality business, with great numbers, but doesn't seem to get much recognition from the market. Low ish PE, decent yield and growing. Guess the potential AI impact on consulting is holding the share price back?
For anyone who is interested in investing in the nuts and bolts of technology ie semiconductors, memory, processors, the equipment for manufacturing same, optronics, photovoltaics, led lighting and displays, and who would like to update their understanding of the science behind them as we move down the nano scale of manufacture to the world of quantum physics which makes it all work: a Youtube presentation which I found fascinating and made it understandable. The world of quantum computing is on the horizon with its promise of cracking on-line encryption and commerce, but also benefits to improving the manufacture of many things which depend initially on time consuming computer trials. Science has changed from using models of what happens such as Newton's and Faraday's laws over the last century to the likes of Einstein's Special Relativity which predicted the need for correcting minute time differences in GPS satellites caused by their movement, and without such synchronisation accurate navigation and even 5G phone links aren't feasible . These once obscure subjects are coming more and more into play as the future world is invented.
I also recommend the lecture by Dr Simon Benjamin on a little trumpeted UK National Quantum Computer Technologies Programme a testing hub for several approaches to Quantum computing.
He is a founder of Quantum Motion which has built a machine that incorporate classic computer chip manufacture techniques to facilitate a rapid scale up of Quantum based process.
See a YouTube video below if interested
I helped Simon and John Morton spin out Quantum motion when I worked at Oxford Innovation. Fascinating IP. If it works it will be game changing in the quantum space but a long way to go. Some serious money being invested at high valuations.
MelloMonday is back tonight and we are joined for a keynote by Andrew Hollingworth, Portfolio Manager and founder: VT Holland Advisors Equity fund for a talk on ‘’An AI investing roadmap. The Capital cycle repeating itself “
Full agenda and more details here as we will also have three company presentations, two educational sessions and an insights session from popular private investor, Mark Simpson: https://www.melloevents.com/mm130726
Use code MMSTOCKO50 for 50% off. Shareholders of our presenting companies are eligible for a complimentary ticket with code SHMM26.
If you cannot make this but would like to register, the recording is shared with all registrants within 48 hours of the webinar ending.
British American Tobacco P.l.c (LON:BATS) . A rather worrying article in the Times (paywall) stating that legal proceedings are being started against BATS for failing to inform the market properly about their operations in N Korea.
https://www.thetimes.com/busin...
Ultimately if you invest in tobacco there is always the constant threat of adverse regulations, taxes or legal measures - that's the reason I never invest in the sector. On top of that you have a prodcut which is inevitably in long term decline. Would require an extremely low valuation to even think about it and then probably only as a trade.
Graham please do a detailed review on plus 500 share drop 15%
re: PLUS. Covered that, subdoc! if you get a chance, let me know if you agree/disagree.... G
Thanks Graham . that is reassuring as I was surprised by the extent of the drop. very helpful . hopefully it is a minor blip and and shares will trend upwards. i think you are bang on the PE which was high based on market expectations as Plus 500 has been a strong performer and the drop today reflects that.
Thanks, Graham, for revealing the kick-off time of the football match. I was wondering about that. Also, nice to see you introducing a sports section. That's what I like about Stocko; you get so much more than boring old stuff about company results.
Pointless comment
I like that instead of just scrolling past what we don't like we get to have a go at the staff with sarky comments. Makes me feel all big and clever.
The New Religion is kicking off.
I for one like to see a little bit of personality and fun in my daily reads. Nothing offensive has been said, it is a couple of brief lines about football. Football is a huge thing in this country and huge amounts of businesses are interlinked directly or indirectly with it.
As an aside, it was also the Wimbledon final this weekend, and it was interesting to hear that since Covid, tennis balls have dropped off markedly in quality, which was accepted as a short term problem at the time, they started to make them with low quality, cheaper materials while rising prices on them. Although Covid has long since ended, the balls are more expensive than ever but still the same terrible quality as the Covid era balls, which has meaningfully changed the way pros are playing tennis, at least according to Roger Federer and many others. Makes me wonder how many businesses are currently huge beneficiaries of seizing opportunities in Covid to do bad things and then just never undoing them.
If you don't want to read about any of this, you are of course welcome to skip my comment, as you can skip the lines in Graham's article.
I second your view - pretty much everything comes out in financial markets one way or another (England's failure to retain the World Cup in 1970 is sometimes given as a reason for Harold Wilson's Labour government losing the general election 2 days later!).
Perhaps one answer is to have a button at the side of a message/thread enabling it (and all responses) to be hidden.
The strategy of Brave Bison (LON:BBSN) to "takeunder" System1 (LON:SYS1) is coming to light. The price is way too low, but Brave Bison (LON:BBSN) hold a 28% blocking stake in SYS1, so that means others unlikely to bid.
A really insulting "improved" offer of c317p from Brave Bison (LON:BBSN) - considering that just recently System1 (LON:SYS1) has been above 330p.
As you say, tricky one as BBSN now have a poison pill stake for anyone else looking to bid. Unless its such a high offer, it gives BBSN a nice massive profit.
Organically, I think they are on the right track for growth given their last trading update. Don't forget last year they had a cliff drop of consulting revenues, because advertisers in April onwards pulled back on new big marketing campaigns, given the Tariff uncertainties in UK, USA, Europe. No new campaigns, no need for SYS1 consulting services. So SYS1 only made the base TYA platform fee revenues. So expect to see a strong recovery in consulting services this H1 of the new financial year.
Personally, I won't be looking to sell below 450p, and think there's a good chance of 550p+ based on recovery back to sustained growth in the next 12 months.
I'm puzzled why BBSN think lowballing works? They also tried that with M&C Saatchi (LON:SAA) for a division. Got nowhere either.
(I hold in the Boon Fund)
Are the Pagegroup (LON:PAGE) trading update today, and the Hays (LON:HAS) update last week, signs of a turnaround for general recruiters? Pagegroup (LON:PAGE) in particular looks a lot better today. Without wishing to promote a "competitor", there was a good recent IC podcast about recruiters which did give me food for thought on whether there is or isn't a structural decline going on.
I do have recent personal experience of Pagegroup (LON:PAGE) in my professional field of PR/communications which I thought I would share. I was recruiting for about 10 roles in my team and we just wouldn't have been able to cope with the likely workload - in my experience I get c.100-150 applications per role and the number of applications has become even higher now a lot of applicants use AI. I therefore went out for tender and asked Page and a more specialist recruiter pitched.
Page actually had the best package of the two - offering a dedicated microsite and a bit more proactive searching of the passive market (people who aren't actively looking for roles). However, in the end I went with the specialist recruiter because Page's team just made constant errors - e.g. typos, forgetting which roles were included, errors in the pricing. I also attended a roundtable discussion they put on which was very badly organised; chaired by an inexperienced member of staff despite Director level attendees. It did give me the impression that Page has junior employees handling a lot of responsibility without sufficient senior oversight. At the specialist recruiter I was dealing with a smaller but much more experienced and organised team. That might be to the benefit of Page's employee costs and profitability, and perhaps my experience is isolated (and only relevant to their main London office), but the risk is they lose business through lack of senior oversight.
I hope that insight is helpful.
Having said all that I did buy Pagegroup (LON:PAGE) shares this morning as a trading opportunity given the current bounceback for recruiters!! Everything has a price...
Interesting comments, useful scuttlebutt.
But surely AI is going to make recruiters a disaster zone. Employers will freeze recruitment this year and presumably start sacking people next year.
The 58% share price fall this year in Pagegroup (LON:PAGE) is probably not unadjacent to this.
As an aside i have found Claude.ai to be very good and in fact better than Chat GPT.
I think the effect of AI is more complex than private investors initially imagine. Positively for recruiters:
But negatively, AI obviously raises the threshold at which people might use a recruiter so we might see a resetting of "normal" revenues - particularly 'generalist' white collar recruiters like Pagegroup (LON:PAGE) and Hays (LON:HAS).
Perhaps the above is also why some specialist recruiters seem to have been doing better than the generalist ones.
On AI, my nephew who works in the field is sceptical. He gave an example of a company that used AI to code its staff systems. It worked brilliantly - but some time later, when the company wanted to scale up, the AI systems began making errors. In the end, they called in a team of coders to get to the root cause. They found that the AI had built code on top of code as issues arose, resulting in millions of lines of codes. The human team simplified these to a few thousand...
And if the AI had been asked to review and optimise the code?
Or if the code had been run through another AI?
I think we should be cautious about judging the pros and cons of AI based on what it can('t) do currently. The tech is fast developing - just look at how much image creation has improved in an extremely short space of time!
Great context thank you. Agreed on companies being overwhelmed with AI CVs. Recruiters are still being used to fill roles.
Be great if you have a chance to update on ME International (LON:MEGP) team , things seem to have steadied but equally doesn't look like a return to previous form is waiting in the future.
With a market cap £380 mil and expected profits between £60-£70 mil would you see this as cheap or a value trap the big drop in net cash seems a worry although appreciate they have been doing buy backs.
What's happening in their AsiaPacific business - mostly Japan - doesn't get much attention towards the start of the RNS but later on they say:
'Photo.ME vending revenue was £19.0 million (H1 2025: £22.3 million), a decline of 14.8% compared to H1 2025 (-7.2% at constant currency1). This was mainly due to changes by the Japanese government for new passport applications.'
About half the fall is due to the weaking of the Yen. But it looks like the Japanese government last year allowed citizens to make a new passport application online including the ability to upload digital photos - previously only renewals were allowed digitally. https://services.digital.go.jp/mynaportal/news/20250321-01/ (You will need to use a translate function).
I imagine this will continue to weigh on H2. In any case this share is about how fast higher margin laundry machines can outpace the fall in photobooth revenues and profits. The photobooth decline seems to becoming more real although I have wondered whether the risks associated with AI altered digital photos might work in their favour.
According to ChatGPT (so usual qualifications apply) you still have to get a driving licence or resident card offline for the most part in Japan - which could obviously change.
Perhaps management's Japanese acquisitons of Fujifilm's photobooths and Photo Plaza Co. Ltd weren't well timed.
I hold.
Thanks Tortoise interesting re the yen.
I sold out of this after the recent, unscheduled TU. Also, I noticed that Speed Queen and Certa now have multiple locations in Ireland. Certa seem to have removed a shop from their forecourts and replaced with self-service Speed Queen laundry. I don't know if this is a recent thing but noticing it was enough to put me off ME Group.
Just to add more positively, given that H1 is often about 40% of earnings - some years a bit more, some less - I think 15p EPS might be possible which would be a beat on lowered market expectations. It feels right for the company to now guide conservatively given the recent track record. This puts the company on around 7.5x p/e this morning. It's had a higher p/e in the past but I'm personally nervous about paying more than 8-10x here given some of the corporate governance issues we've recently had and the risk the photobooth business declines rapidly across geographies that are hard for private investors to keep track of.
This made my Monday morning :) Dog wash machines from ME International (LON:MEGP) !
The rest of the results, not so much.
Puzzled as to:
But overall, despite the wobbles, profitability seems really strong. The external risk of the Photo.ME business is known. But for Wash.ME, it seems like they also have some big external risk that caused a big drop in demand, but one they have not explained well what causes this risk.
They did an excellent presentation (meetinvestor) with a good question/answer session
Thank you! Didn't realise they did one, have added to my list to watch.
Something of a minnow, but a good update from European Green Transition (LON:EGT) EGT this morning. I hold (in small quantity).
The share price has done well this year - congratulations. What's your rationale for holding and what kind of near term revenues and profits do you expect it to make?
Briefly...I have not bought in for what the Stocko profile says it is. I have bought in as a wind energy services play - one of my very few ‘punts/gambles’ in the renewable energy sector. Very much a starter position. The company considers significant growth, a medium term target of £50M group revenue and double digit EBITDA are conservative aims. They have stated intention to look at a dividend and that its ‘services’ nature means EBITDA should be quite close to net cash generation. I like the deal they have taken with Anemos, but confess to not knowing how capable the application is - it’s deployed, in use and they say it pays for itself rapidly. It gives a recurring income. It operates in a very large, but fragmented sector is my reading in terms of what they do. The exec chair, Cathal Friel is to me a conviction, pragmatic and ambitious individual.
They are talking at Mello online tonight! so quiz them there?