Daily Stock Market Report (Mon 17 Mar 2025) - QQ, SAG/RCDO, BKS, MWE, SRC, BAKK/GNC, HEIT/FSG

Good morning and welcome back!
Megan published The Week Ahead, the preview for this week's set of announcements, on Friday. Here's the link.
Today's Agenda is complete (we think!).
12.55pm: all done for today's report, thanks!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Phoenix group (LON:PHNX) (£5.3bn) | Full Year Results | Op cash generation +22% to £1.4bn, in line with targets. CSM +14% to £3.3bn. Div +2.5% to 54p. | |
Qinetiq (LON:QQ.) (£2.9bn) | TU | Delays in UK/US contract awards. FY25 rev exp +2% at 10% margin, vs 11% prev. FY26 downgraded. | BLACK (PW) / RED (Roland) |
Sigmaroc (LON:SRC) (£1.1bn) | Full Year Results | Adj EPS +2.8% to 8.35p, “modestly ahead of consensus”. Outlook: 2025 “started positively”. | AMBER (Graham) [no section below] |
| Bakkavor (LON:BAKK) (£1.0bn) (14 Mar pm) | Possible offer | SP +17% on Friday Greencore (LON:GNC) made two offers for Bakkavor that were both rejected. Second offer: 85p in cash plus 0.523 Greencore shares plus final dividend, total value 189p, 25% premium. Bakkavor shareholders would own 40% of the combined group. | PINK (Graham) [no section below] A 25% premium can sometimes be enough but in reality it might be the bare minimum to get the attention of a company board. And that's when we're talking about all-cash offers. Where it's a mix of cash and shares, it's reasonable to expect more. In the case of Bakkavor, the two founders still own nearly 50% of the company. Perhaps they might be tempted at a better price? I can see the rationale to combine two giants in convenience food and create an entity with even more powerful economies of scale. However, I note that Greencore does not have a net cash position, and neither does Bakkavor. So the cash element of any deal would have to be borrowed. |
Marshalls (LON:MSLH) (£616m) | Full Year Results | Rev -8%, adj PBT -2% to £52m. Net debt reduced. Outlook: market recovery expected later in 2025. | |
Science (LON:SAG) (£188m) | Response to Ricardo | Science Group criticises Ricardo’s board and provides further detail on its analysis/proposed changes. | AMBER/GREEN (Graham) |
Beeks Financial Cloud (LON:BKS) (£171m) | Interim Results | Rev +22% to £15.8m. Adj. EBITDA +25% to £5.7m. Outlook: “within the range” of market exps. | AMBER (Roland) A solid set of H1 results are marred slightly by news of a one-off increase in customer churn and a shift to a new revenue-sharing model for EC contracts. Beeks will no longer receive payment for hardware on handover, but will retain ownership and be paid a higher monthly fee. Forecasts for FY26 have been trimmed. I can’t get higher than neutral on a P/E of >20. |
Harmony Energy Income Trust (LON:HEIT) (£148m) | Possible cash offer by Foresight | SP +20% to 78p | PINK (Graham) [no section below] HEIT invests in energy storage and renewable energy generation. It was already seeking to sell its entire portfolio to a third party. Since it's in wind-down it makes sense that it would be willing to accept a discount. NAV at Jan 2025 was 92.4p per share. This could be a great bit of business for Foresight's funds to get a collection of assets at a discount, and for HEIT to accelerate their wind-down |
Eagle Eye Solutions (LON:EYE) (£107m) | Half Year Results | Rev, adj. EBITDA flat. Confident FY2025 will be in line and confident in med-term milestones. | |
Batm Advanced Communications (LON:BVC) (£64m) | Full Year Results | Trading in the new year is in line. Momentum in Networking division. Diagnostics & Cyber to grow. | |
MTI Wireless Edge (LON:MWE) (£59m) | Final Results | SP -10% | AMBER (Graham) [no section below] These results are a miss against existing 2024 forecasts from broker Shore Capital, e.g. revenue misses by 5%. The RNS does not acknowledge any miss, only observing “extremely difficult conditions in Israel”. The Antennas division is providing all the growth right now and the stock could be considered a winner in the defence theme. However, I am going to downgrade this to AMBER as I have lost some faith in the reliability of forecasts after today’s RNS and share price reaction. It also doesn’t strike me as cheap with a PER in the neighbourhood of 20x. |
Hercules Site Services (LON:HERC) (£40m) | AGM Statement | Successful start to FY25. Expect strong growth to continue. | |
RC Fornax (LON:RCFX) (£11m) | Half Year Trading Update | Revenue +30% to £3.8m, in line. Outlook: confident on track to meet market expectations. |
Graham's Section
Science (LON:SAG)
Unch. at 420.2p (£188m) - Response to Ricardo plc - Graham - AMBER/GREEN
We’ve had a little back-and-forth between these two companies now, after Science started buying up Ricardo shares in a hostile manner. See our coverage on Friday.
On Friday afternoon, after 3pm, Ricardo went public with a written proposal it had previously received from Science group. Unsurprisingly, given what Science has been saying about the alleged failures of Ricardo’s directors, the proposal involved a variety of board changes:
The Chairman to be replaced by an Exec Chairman nominated by Science
Chair of Audit Committee to be replaced by a Science NED
Resignation of another unspecified NED
Ricardo aren’t too impressed by the actions of Science Group. But then, people don’t respond well to public criticism:
Science Group has acquired its shareholding in Ricardo over the last four weeks at a time when the share price has been at around a 15 year low. The Board believes that Science Group is opportunistically seeking to take advantage of the Company's currently low valuation and that its demands to replace identified Board directors is an attempt to gain control of the Company without paying a takeover premium.
They go on to defend their existing work on the transformation of Ricardo into a simplified environmental/energy consultancy, saying that the intervention by Science “will inevitably provide an unnecessary distraction from their efforts”.
They point out some possible issues with Ricardo’s proposal when it comes to the UK Corporate Governance Code and the requirement for independent directors (directors nominated by Ricardo would not be independent).
Finally, they note previous activity by Science:
The Board also notes that Science Group adopted similarly aggressive tactics in connection with its takeover of TP Group plc which completed in 2023. In that case, Science Group built an initial stake in the target company's shares, requisitioned a hostile general meeting to replace two directors and, having taken control, then oversaw a collapse in the company's share price prior to pursuing a takeover at a price which was approximately 40% lower than the prevailing share price had been when Science Group announced the acquisition of its initial stake. In 2019, Science Group also employed similar tactics at Frontier Smart Technologies Group Limited when it replaced a number of board directors with its own nominees prior to its subsequent takeover of the company.
In the archives, you’ll see that I was writing about Science Group’s acquisition of TP Group back in 2022. My impression of this deal is that it worked out reasonably well for Science. So in spite of Ricardo’s attempt to paint it in a bad light, I’m not sure if Science did anything terribly wrong in this case.
Today's RNS
Anyway, the war of words has now begun in earnest with Science publishing a response first thing this morning.
The Ricardo Board continues to seek to deflect from the fundamental issue, namely the poor performance of the company and the ineffective governance of the Ricardo Board which have resulted in the destruction of shareholder value.
I won’t go through all of the points raised by Science today. Suffice to say that they think the Ricardo board aren’t up to it, and they consider their demands for change to be reasonable.
There is an important point re: the Corporate Governance Code (one which I had already thought of!), which is relevant to this story and is important to bear in mind generally. The point is that it’s not mandatory for listed companies to follow all provisions of the code. What they are required to do is to explain themselves when they don’t follow the code.
So for example, it is possible to have a non-independent Chair. The company just needs to explain why it thinks the appointment is in the interests of all shareholders.
Science describes in detail the likely failure of Ricardo to achieve its 5 year objectives that were set out in 2022, concluding that the position of Ricardo’s current Chair is “untenable”.
They note that Ricardo’s board of directors collectively own 0.2% of their company, vs. Science’s directors owning 21% of their company (nearly all of this being owned by Science’s chair, Martyn Ratcliffe).
Graham’s view
A requisition for a general meeting seems inevitable with Science lobbying their fellow shareholders to shake up the board at Ricardo.
These shareholders include Gresham House (the biggest), Aberforth Partners and Royal London.
I welcome today’s RNS as we now know where everyone stands.
We know Science’s main arguments for change, and what they want to see happen at Ricardo. We also know Ricardo's position since Friday.
I’m inclined to leave my AMBER/GREEN stance on Science unchanged today, having downgraded it from GREEN last week.
I’m still a little concerned that attempting to control and improve Ricardo - a £150m market company - might be a very difficult and time-consuming task. For context, Science’s own market cap is comparable to Ricardo’s at £190m, and as I said last week, Science must have spent a very large portion of their last-reported net funds on this “strategic investment”.
Fixing bad or underperforming companies is a strategy that Science might be very good at, but this is different to what they’ve done before.
Their takeover of TP Group in 2022 valued that company’s equity at only £17.5m. So they could afford to buy it up and have total control.
With Ricardo, it’s hard to see how they can achieve anything like that level of control. They will need buy-in from other large Ricardo shareholders to achieve their goals - this is why I wondered aloud last week if they had been in touch with the other shareholders already.
Without the support of other shareholders, they will have about as much influence on Ricardo’s board as you or I would.
This is why I’m staying AMBER/GREEN on Science, rather than going straight back to GREEN: the outcome of this episode strikes me as highly uncertain, and it is already very expensive in terms of the cash spent on Ricardo shares..
Whatever happens, I think we can count on this war of words to continue for at least a little while longer yet.
Science’s shares continue to trade at above-average earnings multiples for companies in the professional services sector:
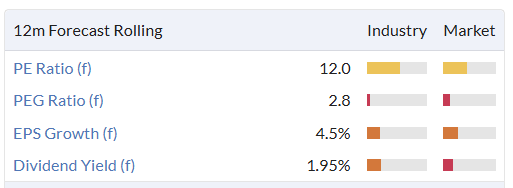
I also maintain the AMBER/RED on Ricardo.
Roland's Section
Qinetiq (LON:QQ.)
Down 17% to 436p (£2.4bn) - Trading Update - Roland - BLACK (RED)
QinetiQ Group plc ("QinetiQ" or the "Group") today issues a trading update covering the fourth quarter, updated year end expectations and an extension to our share buyback programme of up to £200m over the next two years.
QinetiQ has been a general beneficiary from the bull market in defence shares, but unfortunately that has not prevented this FTSE 250 firm from issuing a profit warning this morning:
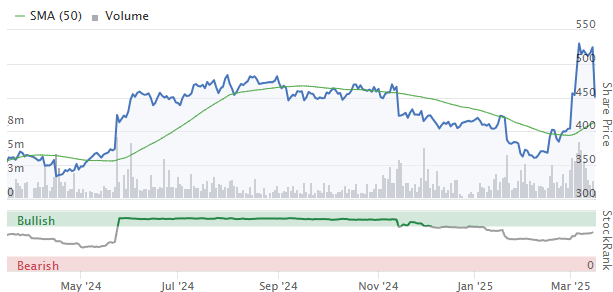
What’s gone wrong? When I covered QinetiQ in January I noted the company reporting a weak order intake, albeit full-year guidance was left unchanged.
It looks the board was keeping its collective fingers crossed for a recovery ahead of the 31 March year end. Today’s update suggests this failed to materialise:
However, tough near-term trading conditions that we referred to in our third quarter trading update have persisted.
The company highlights weakness in areas where order book visibility is limited. These parts of the business each represent c.25% of group revenue, or c.50% in total:
This has affected short cycle work in our UK Intelligence and US Sectors resulting in further delays to a number of contract awards.
Management also makes an interesting comment about US demand:
In addition, recent geopolitical uncertainty has impacted our usual fourth quarter weighting to higher margin product sales from the US.
I’m not completely sure how to interpret this. With many to choose from, which geopolitical factors is QinetiQ referring to?
One possible interpretation I can see is that UK defence contractors relying heavily on US revenues could be finding it tougher to secure contracts from the new administration in Washington. I think this could be an area to watch.
More positively, the company says its FY25 book-to-bill ratio is expected to be “more than 1”, suggesting its order book should be similar to or higher than last year. Net debt is also expected to be in line with last year’s figure of £151m, which looks like it should be manageable to me.
Share buyback: QinetiQ’s management have also announced an extension of up to £200m to its current buyback programme, to be delivered from June ‘25 to June ‘27.
Management says this “will maintain leverage at around the current level over the next two years”.
Updated guidance: we don’t have access to broker notes for QinetiQ, so I’ve done my best to estimate the potential impact on profits using today’s updated guidance.
Organic revenue growth for FY25 to be c.2% at an underlying margin of c.10%, including c.£25-30m of one-off in year charges;
Checking back to January’s third-quarter update, the company was still maintaining its guidance for “high single digit organic revenue growth at stable underlying margin”.
I’m assuming the stable underlying margin referred to is the 11.3% margin achieved in H1 25.
Here are my before and after estimates, using FY24 results and Stockopedia’s consensus estimates:
Previously: FY25 revenue of £2,040m, underlying op profit £230m
New guidance: FY25 revenue of £1,950m, underlying op profit £195m
If I’m in the right ballpark, this suggests operating profit for the year ending on 31 March could be c.15% lower than previously expected. That’s in line with this morning’s share price fall, too.
In addition, the company highlights a number of one-off charges that will be added to this year’s (non-underlying) results:
£140m goodwill impairment relating to US operations
“Exceptional, largely non-cash charges” of £35-40m, mainly relating to “inventory and cost recovery” in legacy US operations
FY26 guidance also appears to have been cut:
FY26 revenue growth to be c.3-5% at margins of 11-12%
Previous consensus estimates appear to have been for FY26 revenue growth of 7%, although I think this margin guidance is broadly in line with previous expectations.
Roland’s view
The company says its long-term outlook remains positive and I probably wouldn’t argue with this:
Longer term, the underlying strength of the Group coupled with the relevance of our mission critical capabilities to the national security needs of our customers in the UK, US and Australia as well as NATO allies, positions us well for long term future growth.
However, I don’t have a great feeling about today’s update or QinetiQ’s near-term prospects.
Reading between the lines, I wonder if QinetiQ’s US business might be suffering from problems that are only just starting to become clear.
I also fail to see the logic in a company with net debt spending cash on buybacks at the same time as profits it’s cutting earnings forecasts. I am not sure QinetiQ’s shares are cheap enough to justify this, from a ROI perspective.
I estimate that the stock could still be trading on a low-teens P/E multiple after today’s drop. Given that our research has shown that a company’s first profit warning often marks the start of a period of underperformance, I don’t see any need to jump in just yet.
The StockRanks showed a high Quality score prior to today, but weak value and average momentum. I’d expect the momentum score to drop when today’s profit warning is reflected in updated consensus forecasts.
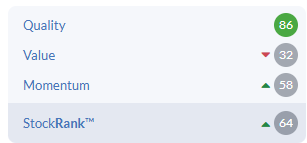
I was neutral in January, but am going to go RED after today’s update, pending clarification on trading and outlook when the company’s full-year accounts are published in May.
Beeks Financial Cloud (LON:BKS)
Down 18% to 202p (£138m) - Interim Results & First Cryptocurrency Exchange Win - Roland - AMBER
Today’s half-year results from this “cloud computing and connectivity provider for financial markets” have been overshadowed by news of higher churn in H1, and the company’s decision to shift to a revenue-sharing model for some of its Exchange Cloud contracts.
As a result of these factors, broker Canaccord Genuity has cut its FY26 earnings forecasts by 4% to 9.1p per share.
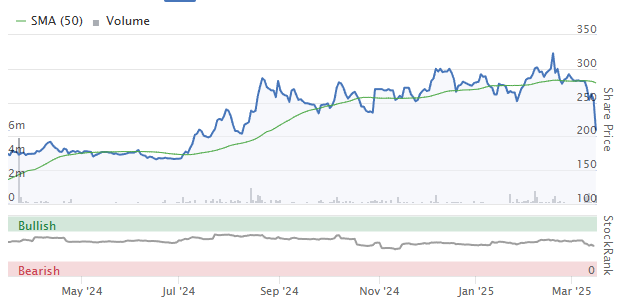
Let’s take a closer look at today’s results.
H1 results summary: today’s numbers cover the six months to 31 December ‘24 and show continued progress at this AIM-listed business:
Revenue up 22% to £15.8m
Annualised Committed Monthly Recurring Revenue (ACMRR) up 7% to £28.5m
Underlying pre-tax profit up 37% to £1.9m
Underlying PBT margin: 12.0% (H1 24: 10.6%)
Reported pre-tax profit up 188% to £0.5m
Underlying EPS up 47% to 2.6p
Net cash of £6.6m (30 June 24: £6.6m)
Trading commentary is mostly positive:
Approval and launch of “the multi-year contract with one of the largest exchanges globally” (presumably this is the NASDAQ contract), with first customers now on-boarded and progressing to plan.
Post-period win with Grupo Bolsa Mexicana de Valores, the second-largest exchange in Latin America
Expansion with existing customers including the JSE
ACMRR “further increased to £29.2m as at the end of February 2025”
However, one item sounds less positive to me, although the company says it should be a one off:
during the period we had some higher than historic customer virtual private server churn following the transition of our server licence estate from VMWare to OpenNebula, as clients cleared out some legacy infrastructure. These reductions have now stabilised and are not expected to recur.
There’s also news that Beeks is venturing into the crypto space with well-respected crypto exchange Kraken:
First Exchange Cloud win in crypto space under new revenue share model, further increasing the TAM for Exchange Cloud as we enter new asset classes. Kracken [sic] is one of the longest-standing, most liquid and secure cryptocurrency exchanges
I have no idea what the potential addressable market value of crypto exchanges could be relative to conventional financial exchanges.
However, this deal also highlights a more mixed item of news from today’s results:
Transition to a revenue-sharing model for Exchange Cloud contracts to enhance profitability and drive long-term value
Frustratingly, the company does not provide any detail on this new revenue-sharing model in today’s results. This means investors without access to broker notes are left in the dark on its potential implications.
According to today’s Canaccord note, the implications could be quite significant:
Existing Exchange Cloud (EC) customers pay 40-50% of the total contract value upfront when hardware is handed over to the exchange
Under the new arrangement, Beeks will retain hardware ownership and receive (higher) monthly recurring fees
This is expected to result in an increase of “>30%” in total contract values and better long-term visibility
However, it creates “a temporary headwind in FY26” with a return to double-digit growth “highly likely in FY27”
This kind of pricing is common in Software as a Service scenarios, where the incremental cost of adding new customers is low.
However, Beeks’ model includes expensive hardware which will presumably now take longer to earn back its cost. I would imagine we could see the company’s working capital requirements expand, at least temporarily. Fortunately, Beeks has a net cash position at present, but this is something I’d watch over the next year.
The scale of the impact of this changed pricing mode is likely to depend on the rate and type of new customer wins (not all are Exchange Cloud).
Outlook: CEO Gordon McArthur’s guidance for the second half of the year appears to be in line:
Outlook for FY25 remains positive and within the range of market expectations
Canaccord has upgraded FY25 forecasts marginally today, but as I mentioned earlier, FY26 estimates have been cut.
Here’s a summary of the latest numbers from Canaccord Genuity, with thanks for making this coverage available:
FY25 EPS 7.8p (previously 7.7p)
FY26 EPS 9.1p (previously 9.5p)
Roland’s view
I understand that Beeks can potentially address a large market with its services and may still have a long runway for growth. But I’ve always been a little worried about the extent of the upfront investment that’s required before any meaningful profits are earned.
Quality metrics have improved somewhat in recent years, but remain below the level I’d see as attractive:
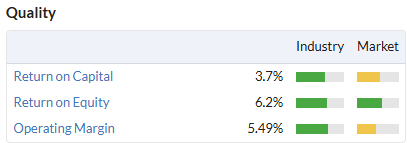
Today’s shift to a revenue-sharing model for EC contracts could potentially make this problem worse, in my view, at least in the short term. I wonder if it also signifies competitive pressures.
My feeling is that Beeks’ previously high MomentumRank and its High Flyer styling could come under pressure following today’s updated forecasts:
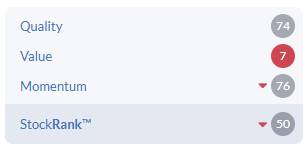
With the stock still trading on a FY26 P/E of 22 and some uncertainty about the outlook for the next 18 months, I think it makes sense to take a neutral view at this point. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Beeks Financial Cloud (LON:BKS)
Not one I know well - but there are a few things that have kept me on the sidelines to date:
1. The share based payments are high, or perhaps in the context of being almost the same as the profit, even very high..and they conveniently remove them for their "underlying" PBT....
2. I don't quite understand the revenue recognition, in that the trade & other receivables are higher in the non-current assets than they are in the current assets. How are they accounting for multi-year contracts? The notes in the interims didn't explain much. If you go back the last set of Finals you find in Note 13:
Contract assets primarily relate to our rights to consideration for goods or
services delivered but not invoiced at the reporting date. The
associated performance will either be the delivery of the bundled
appliance for proximity/exchange cloud contracts or the delivery of the
licence key for software contracts. The contract assets are transferred
to receivables when invoiced.
So these non-current receivables are over a year away and they haven't invoiced for them yet? Have I got that right??
3. The capitalisation of development costs - not that this is unusual in IT/software, but more because if they expensed them that would be the profit largely gone.
Then if you start adding some bigger depreciation numbers on all that hardware in the new revenue model that isn't going help. Are they in effect "vendor financing" by providing the hardware, and what does that do their return on capital? Are they now bearing the risk of installed servers sitting there waiting for customer demand to catch up?
Hmmm. More digging required.
All good points, I think I got caught up in the hype of this one. The new model seems to carry a lot more risk, underutilisation, maintenance etc...
I have to ask again, if it was such a good business model why have the sneaked through this major change that seemed to have been leaked to the market judging by last weeks share price movement, do we have another pump and dump/ lifestyle company special on our hands
I haven't seen Gordon McArthur in one interview today, que surprise
Re the Beeks Financial Cloud (LON:BKS) contract assets, I think it’s because they generally have 3 to 5 year contracts and they’re trying to match the costs with the revenues as per IFRS. So on those contracts, as most of the costs are upfront, they’re taking 40-50% of the revenues upfront and then invoicing for them annually or monthly over the term of the contract. They won’t do that with the revenue sharing exchange cloud model so it should become a lower proportion of revenues over time.
Pershing Square Holdings (LON:PSH) - in Berkshire Hathaway style the annual report is released over the weekend, signed Friday. I still like Bill Ackman and his approach. Very large discount. He now wants to build Howard Hughes into a Berkshire Hathaway vehicle, acquiring controllin stakes in private businesses, but again the deal is not guaranteed. He's had a few aborted deals over recent years.
QQ "UK's Qinetiq slides 16% on grim trading update" Oo. "The company's stock is set to record its worst day since its debut in 2006" Ah.
"The company forecast organic revenue growth of just about 2% for the year ending March 31" Given the ongoing geopolitical upheavals at the moment, that's a bit wan. The problem seems to be with DOGE.
It's interesting to note that about a year ago, QQ was on a PE of 12, whilst BA was on a PE of 18. The market seemed to "know" that BA was the better bet. Over 1 year BAB is up 46%, BA up 27% and QQ up 14%. Both BAB and QQ outperformed BA over 1 year, except that the stumble today meant that QQ fell behind.
Yes, there is just something about Qinetiq (LON:QQ.) that the market doesn't like. To be fair, the company has a track record of mishaps - particularly in the US. I have previously held the stock, but today's update has reminded me why I sold and why I am not tempted to jump back in.
Well adopting the ‘sell on a profit warning’ I exited at a profit c. 35% over original cost - purchased 3 years ago. Guess not a total disaster but you can bet that despite the profit warning and the recommendations of Ken Mitchell (sorry Ken!) to sell on the first sign of bad news the share price will recover from the c. £4.14 I sold at. In fact it is already up 6p from my exit price!
ACounsell
Assuming you’re posting about Qinetiq (LON:QQ.) I would have sold on the first signs of bad news ahead in January. It’s one of the few examples where my tactic didn’t work as QQ. joined in the big rally for defence shares and soared around 80% before tumbling today. It’s not a share I’ve followed but with a red rating along with the commentary from Roland today, I’m not tempted to look further.
Hope the big dividend paying shares we both hold do well for you. Sometimes there is good upside as well if using the tactic of buying the big dips. e.g I’m up over 50% on both Aviva (LON:AV.) and Legal & General (LON:LGEN) where the dividend at my 155p buy price is 13% and with small annual increases. Aberdeen (LON:ABDN) is the lowest quality one, and the only one not increasing the dividend, but looks oversold and might tempt a bidder.
Yes should have included Qinetiq (LON:QQ.) in posting!
Sigmaroc (LON:SRC)
Results read more or less as expected. I like the company and management and think that the medium term looks bright, after all quarries are not overly plentiful. Still unable to grasp what has caused the recent rise in the share price from 75p to 95p in the last few weeks, when the information in the market is reflected in today's results.
I hold but top sliced recently around 90p to add to other positions. Would be interested on a view from Graham, Roland, Megan etc.
Edmund Shing (BNP Paribas Wealth Management) did a 5 min podcast last week discussing the US market correction. Grist to the mill, well worth a listen....
https://wealthmanagement.bnpparibas/en/insights/video-podcast-hubs/podcasts-hub/market-corrections-are-the-cost-of-investing-for-long-term-gains.html
Thanks, useful
Looks like Science (LON:SAG) is almost becoming an activist investor? I guess you can say its gong well until it doesn't. In illiquid AIM or relatively small businesses these are quite expensive distractions. I have memories of a previous AIM based hostile attempts at a takeover which didn't work out.
One to watch, I guess.
Recent sell-off in Tesco (LON:TSCO) and Marks and Spencer (LON:MKS) appears to have been driven by a profit warning from Asda last week, in particular indications that they are planning to cut prices to win market share. I think Asda has its own issues and has been struggling for years - from my own experience, it's the one supermarket I always avoid as the quality is so poor, so I really wouldn't read too much into this. Even if there is a price war, I doubt there would be any impact on M&S at all given the very different demographics and price points. Took the opportunity to by some M&S just now, and may also consider some Tesco if that keeps falling.
If Asda lose the equal pay dispute, which looks likely, this could affect Tesco (LON:TSCO) and some other supermarkets. One estimate is £1.2bn payout at Asda.
Very good point Rusty, so we now have retail headwinds of:
In food retail these challenges are coming up against price competition meaning margin pressure.
There's some inflationary/ potential stagflationary pressure. On the flip side interest rates are coming down.
We do have some very good retailers though!
Interest rates not coming down much, the longer term ones have gone up recently, you can get 4.5% on fixed rate 5 year quite easily.
lf the war in Ukraine does end, gas prices should come down, which will help some food suppliers and retailers.
Yep, and who'll foot the increased cost bill? Of course, the public through increases in prices......
Scuttlebutt can be useful.
I go into Marks and Spencer (LON:MKS) with cash in hand ready to buy and then leave with nothing. A lot of the trousers are 40 inch waist or 28inch. The occasional one which is my size waist (34 inches) have a 36 inch leg. Ridiculous.
Out of about 100 jeans on the shelves NONE are my size. By the way i am an exactly average size for a UK male.
So i dont buy M&S shares for this reason. Couldn't organise a *** in a brewery.
I think you will find that standard M&S jeans leg length options are 29", 31" or 33"
I remember a poster giving a similar reply to yours Epitchyia as the reason they wouldn’t buy, when Marks and Spencer (LON:MKS) share price was 90p! I agree with the negatives you posted but despite that, by the end of 2023 Marks and Spencer (LON:MKS) regained its crown of being the UK’s biggest seller of women’s clothes.
https://www.retailgazette.co.u...
fwiw though using anecdotal evidence like yours and by checking out how busy their stores are when deciding whether or not to buy, I place FAR more importance on the facts and figures in their trading and Results updates. And there’s little doubt that Marks and Spencer (LON:MKS) has got back to top form at long last. But the share price is now nearly 4 times higher than when that poster gave me a similar answer to yours when I was posting the buy case under £1. So unfortunately for anyone tempted to buy now Marks and Spencer (LON:MKS) is no longer at an extreme bargain price. The easy gains have been had.
And I still don’t overly rate their clothes and still don’t own any MKS shares
Yes it was you Penny, but you have done even better with Rolls-Royce Holdings (LON:RR.) where I guess the share has gone up 8 times or so from your buy price. Hope you’re ok and it’s good to see a post from you.
I think that M&S food compares favourably with the competition - which is where the conversation started, discussing the recent change of ASDAs strategy and its possible impact on Tesco etc.
You are quite correct about the men's clothes, but the amount of clothes men buy in caparison to women is quite small so it might not be that important to overall trading.
If they mess up on the women's clothing ( as they once did) then I would suggest that is the time to sell - and quickly.
I agree.
My point is that if they are unable to stock average sized clothes what other things are they missing?
I visited a large M&S last week looking for some women’s trousers and encountered the same problem as reported with the men’s. I would have had a great choice if I was a size 8 or 20 or 22, but as I am a size 10 or 12 my choice was very limited.
Agree men's clothing is pretty dire, but I'd say only small part of business - majority of clothing is women's and children, and of course food is now main part of business.
Bought a good value feathercoat, and a couple of linen jackets from M&S, so not all so bad. Yes trousers everywhere seem to favour the Large and extra large. One of the mysteries of trouserland!
I’m a 34” waist, 31” leg and I’ve never had a problem sourcing M & S jeans, they always seem to have plenty of all sizes. Which stores did you visit? I use Castlepoint in Bournemouth
They are excellent in range, size and and quality and can be ordered on line. Also my youngest son is now a firm M&S fan.
You can just order online, then pick up from the shop, that is what l do, then no wasted journeys. I don't buy M&S jeans though.
I have a lot of M&S clothes because last so long, some are 30 years old, l still wear. Many other brands the collars, get worn after a few years and then the cuffs. I don't know about the newer stuff yet, but will probably outlast me.
Asdas rollback scheme bound to impact Tesco profit margins as they will need to respond. Rather bizarrely a holland and baratt shop has opened within my local Tesco superstore. No idea who buys from h&b but the prices are extortionate - strange partnership
its probably like the giraffe tie up a few years back - if they have something that they can get some income for (rent?) and that brings punters in the the "locale" that should benefit. I think any store in isolation can have issues that passing trade is harder to get year on year (more net sales) - if they are competing against a place where someone can go and visit multiple shop types at once. Ok in thoery they could probably do their own brand stuff - but to me it doesnt not make sense to have the tesco desination being for as many different purposes as possible even if thats not all their direct sales - of that might result in extra trade for them they might not get otherwise or bring in higher overall trade.
Also worries about the increased minimum wage and extra employer NI contributions about to kick in in April. Possibly also fear of what Rachel might announce next week in her spring budget statement.
I have never seen the womens range to be so good in M&S as it is now. It has become one of my go to shops and I would rate it up with Next for quality and stock. Can't comment on the mens clothes. The food is always top quality.
I’ve held Phoenix group (LON:PHNX) for several years, and the share price performance has been very disappointing. That’s despite a huge dividend of over 10% at the closing price on Friday and a progressive dividend policy where today they again kept to their policy of annual dividend increases. At last today the Results have given the share price a lift.
Shares like Phoenix group (LON:PHNX) Legal & General (LON:LGEN) Aberdeen (LON:ABDN) and M&G (LON:MNG) (I hold all of them) are all paying similar big dividends. Aviva (LON:AV.) which I’ve also held for years is the exception and has seen decent share price gain. And they are all (except Aberdeen (LON:ABDN) ) increasing their annual dividends.
That such sustainable yields on such high quality shares are available surely reflects on just how ludicrously cheap these shares are? Why don’t more UK Pension Funds take advantage of that incredible value and buy them?
To save time here’s a paste of commentary on Phoenix group (LON:PHNX) Results today which shows why the share price has at last gone up today:-
“Shares of British insurer Phoenix Group PHNX.L rise as much as 6.43% to 560p, highest since October 2
** Top gainer on FTSE 100 .FTSE
** Co raises 2026 adj. operating profit guidance to 1.1 billion pounds from 900 million pounds ($1.42 billion to $1.16 billion)
** PHNX raises total cash generation guidance to 5.1 billion pounds from 4.4 billion pounds in three years to 2026
** 2024 adj operating PBT of 825 million pounds vs analysts forecast of 734 million pounds, according to a company-compiled consensus
** "Group continues to generate strong capital generation, and management points out today there are no pinch points on paying the progressive dividend policy, which is now yielding 10.6%" - Panmure Liberum analysts
** Up to Friday's close, stock gained 7.94% YTD.”
PHNX
ABDN holds 10% from my memory. Probably the most promising among those you mentioned as it own ii which is very popular among the subscriber here!
I was looking at ii, l know someone who uses it, but l don't like the monthly fees and their forex fees are high.
But they don’t have a % based fee as so many do. £9.99 pm is peanuts and if you don’t deal in particular month, that is your only fee. If you do trade, it’s £3.99 per trade, regardless of size, which also seems perfectly cheap to me. Which company do you use that you feel is significantly better value?
% based fee? What do you mean?
It is £11.99 pm, if you go over £50,000.
I use IG group (LON:IGG) £3 a trade and free on US apart from 0.5% forex fee. No monthly fees.
The person l know is in dispute over their fees, not at all happy. Misleading information.
Ah, you don’t nurse them for a SIPP then, otherwise you would pay IG £210 a year.
No, l don't use them for a SIPP. I'm talking ISAs.
Or ii's FX fees are very, very low - depending on how you look at it.
ii permit you to hold foreign currency in their accounts (except in ISAs where HMRC rules stipulate £ base currency).
This means at ii you can sell a US$ stock and then reinvest the proceeds into another US$ share without incurring any FX fee whatsoever (nor any stamp duty either - pls take note, Rachel).
So yes, 1.5% on initial currency conversion is high (for sub £25k trades), but then it is 0% on sale & reinvesting in same currency.
Compare this to AJ Bell, where you are charged 0.75% on any US$ deal (London listings apart, which are worth looking into for US majors). So lower fee initially, but watch a further 2 x 0.75% = 1.5% head out the door in FX fees if you sell and re-invest the proceeds in same currency. AJ Bell also charge an FX fee on every dividend receipt, which ii don't.
If you want to reinvest US$ dividends back in to US$ shares outside an ISA then ii is the clear winner.
Summary is that ii works out much cheaper in the long run if you have a large overseas portfolio outside an ISA, but AJ Bell suitable for long term buy & hold or if you are mostly £ (and especially if you stick to shares/ETFs and avoid funds).
Another difference is that your GIA (General Investing Account, or Dealing Account) comes for free with an ii ISA, whereas AJ Bell will charge another set of fees to run your GIA. If you have significant investments outside your ISA, especially foreign shares, ii begins to look the better option.
I should add I have SIPPs, ISAs, GIAS and JISAs spread across both platforms (as much a result of consolidation as choice - bye bye Selftrade, TD direct et al) and can measure my total fee costs over a decade & longer.
Once you get to a certain size what really matters is if they cap the admin fee or not. Both AJ Bell and ii are fixed/capped so cost above that is down to your dealing frequency (and on balance I am an investor with multi-year holding horizons, not a day trader).
The less obvious factors matter more to me than outright price - whether you can buy Japanese stocks, buy gilts, buy corporate bonds, what they charge if you can't deal online, bed & ISA etc.
And the ability to link Family accounts in AJ Bell so you can deal from one log-in is an immense timesaver that ii should replicate, but haven't.
It's not quite as user friendly but Interactive Brokers are cheap for trading, allow multi-currency cash, and cheap for FX anyway.
Yes - Interactive Brokers are interesting.
However, no direct SIPP at present, and their monthly inactivity fee of £3 on an ISA means they are not that much cheaper than AJ Bell for buy & hold.
Ken,
Can definitely agree with you on this. Hold all the shares you mention (except. Aberdeen (LON:ABDN) for the rock solid dividend yields. Capital growth may be limited but for income they are difficult to beat. However obviously not exciting enough for investors (traders!) who want to catch that multibagger.
Can't help with your question, Ken, just share that I too have held for around 4 years, and was thinking, in spite of quite a large position, of buying a few more on Friday. Ah well. I did get in on most of the results presentation and like the look of the new COO. They're not going to shoot the lights out, but they look pretty powerfully set up for continued modest growth now, with div sort of inline with inflation. They certainly look good for my target of 640p.
A couple of AIM IPOs this morning, including MHA (part of the accounting firm Baker Tilly).
Hi Topvest, yes I saw the MHA one (hadn't seen the other one). I'm interested because Cavendish (LON:CAV) is the broker on both of them, and on the MHA one (which is the much bigger of the two) it is nominated adviser, bookrunner and broker, with a placing and retail offer.
Given it seems to be the IPO market that makes these brokers most of their money, maybe this will mark the turning point in their financial performance. I have a small holding and want to buy more, but (call me picky) I want to see the share price momentum stop going downwards first.
Cheers
Chris
P.S. (edited this) they also did the RC Fornax (LON:RCFX) IPO at the beginning of Feb this year, which was only another small one (£6m raise) but every little helps those poor investment bankers.
Thungela Resources (LON:TGA) annual results out today.
Would love to hear your thoughts on this one if possible please Graham.
It seems like profit is down (mainly due to the fall in coal prices/demand in the 'mild winter'), but revenue and production output have risen...
Hey Snooze you lose, I appreciate the request but the company description is:
"a global pure-play producer and exporter of high-quality, low-cost thermal coal, with operations in South Africa and Australia."
I'm afraid I can't cover this sector - perhaps Mark will cover it later in the week. I'll take a note to ask him. Sorry about that.
F&C Investment Trust (LON:FCIT) - the oldest investment trust announced results this morning. A 21% NAV total return beating the difficult to beat benchmark in 2024. Very impressive indeed!
Beeks Financial Cloud (LON:BKS) Cannacord Genuity reduces sales (2025/ 26), EPS (2026) and PBT (2025/ 26) forecasts, on change of business model from up front payment for exchange contracts to one where BKS own hardware and revenue is shared with the exchange - so a hit short term as revenue is delayed on new exchange wins. Today's new crypto exchange win is on the new model. Also seems to be some higher churn on historic business. [Edited]
Sounds like the stock will be battered this morning.
Putting 2 and 2 together and hopefully getting the right answer, last weeks downward share price movement was probably associated with the change to Beeks Financial Cloud (LON:BKS) revenue share model rather than the FT article relating to Nasdaq non advertised high speed fibre cancellations. Unfortunately the share price is taking a hammering but the revenue is not lost it's just delayed.
Down 18% now…
Why change a business model that was working, apparently working anyway.
Beeks Financial Cloud (LON:BKS) will visualise greater upside through long term (and less lumpy?) revenue streams. I'm not sure it makes them more 'sticky' as suggested because the exchange won't own the kit. I'm only guessing but a lesser upfront payment perhaps makes it an easier sell to win new business and the revenue share keeps Beeks management focused on service. [For transparency, I do not hold]
A drop of this size for a minor change in forecast earnings for a company with significantly more growth potential seems excessive (I hold). P/E is high but not surprising for a tech stock. The market is a mess at the moment and volatility like this is not going to attract investors. I’m considering selling 50% of small cap shares where I’m happy with the return and buying back in after each announcement which only promotes downward movement these days. The governments move on Aim is going to be unbelievably damaging, they’ll lose all the benefits they were hoping to get, I can see it folding.
Beeks Financial Cloud (LON:BKS) was an highly valued company and so expectations were high. I have been in it since sub 100 and top sliced about 40% of my holding at 300 at the expectation that results would dissapoint (as they so often have.) MIght start re-adding a bit more once the bottom as been found as they still we get taken out later at a significant premium, well least I hope :-)
Well done with the top slice it’s a strategy I’ve rarely pursued but will start to consider this more. Agree on the expectations.