Daily Stock Market Report (Mon 2 Dec 2024) - MERC, GAMA, SUP, SRT, TPT

Good morning! It seems that we have a quiet Monday for company news.
12.45pm: this report is done now. Thanks for dropping by!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
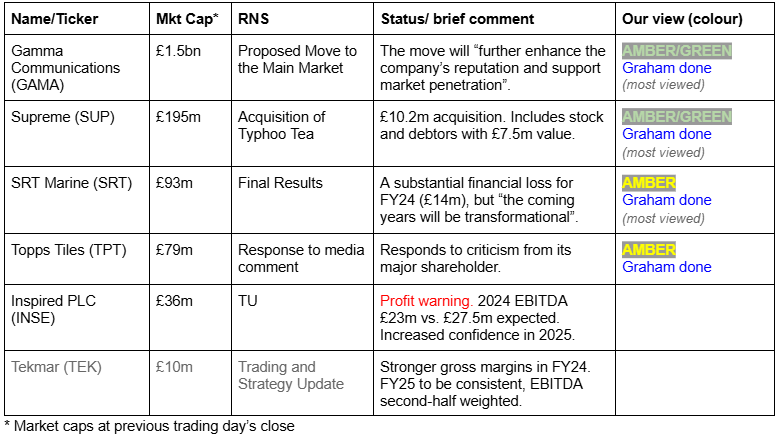
Companies Reporting
Short Sections
Mercia Asset Management (LON:MERC)
31p (£133m) - Interim Results - Graham - GREEN
Last Thursday we had results from regional fund manager Mercia.
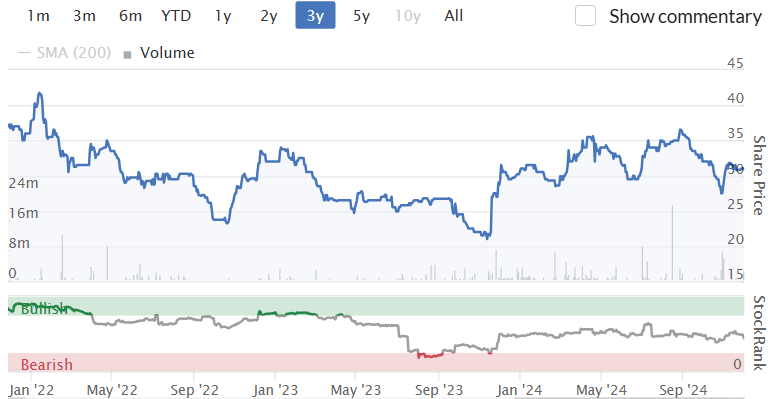
I’ve been positive on this one (e.g. in July at 33p) due to what I perceive as deep value and an interesting growth story, but the market has not agreed with me yet:
In recent times, the company has focused more on investing 3rd-party funds rather than investing its own funds. These 3rd party funds grew only marginally during H1, from £1.63 billion to £1.65 billion. The year-on-year growth rate is far more impressive: up 31%.
Year-on-year FUM growth translated to 19% year-on-year revenue growth (to nearly £18m), and this allowed for a 34% increase in EBITDA (to £3.7m).
Year-on-year comparisons using EBITDA make some sense to me here, in order to exclude something that I believe would distort a year-on-year comparison: interest received by MERC on loans to investees.
See that the company benefited from investee loans in H1 last year, but not in H1 this year:
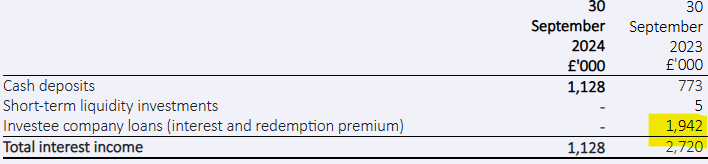
If we are studying this primarily as a manager of 3rd-party funds, then I think the EBITDA number is more relevant.
If all you care about is the bottom line, the company did generate pre-tax profit of £2.4m in H1, up from £1.4m in H1 last year.
Net assets were almost unchanged during the six-month period, finishing at £187m. Strip out intangibles and we still have £152m, which is 15% above the market cap.
Direct investment portfolio: c. £4m (net) was invested in the portfolio during H1. I place more emphasis on the performance of the 3rd-party fund management business now.
Flows: there were gross fund inflows of £57m during H1, all in the “Private Venture” category, which is effectively Venture Capital (it includes VCTs and EIS).
Cash was unchanged at £46m, with no borrowings.
Outlook doesn’t give too much away numbers-wise, but is very confident on strategy, e.g.:
Mercia, with its investment discipline, debt-free cash position and sustainable, long-term private capital deployment business model, has a stable AuM position and a clear strategy through which to continue its growth trajectory. As institutional funds look to impactful, domestic and regional allocations, I remain confident that Mercia is well placed to benefit from this capital transition.
Graham’s view
I continue to believe that there is a lot of business available at this price, when we consider that there is a discount to tangible NAV and a growing fund management business.
However, I acknowledge that this is a complicated picture with both a direct investment portfolio and a 3rd-party fund management business (that includes multiple asset classes) to be analysed. There is no one valuation method that we can rely on, as it’s clearly a situation where both the balance sheet and the income statement have to be included.
Gamma Communications (LON:GAMA)
Up 1% to £15.92 (£1.5bn) - Proposed Move to the Main Market - Graham - AMBER/GREEN
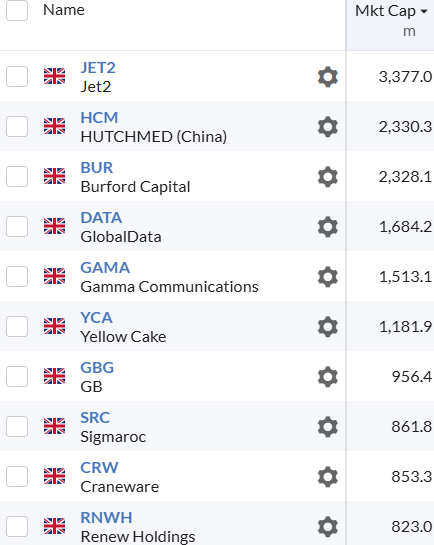
This B2B communications company has been one of the largest AIM companies for some time.
It is currently #5:
In my view, when a company is large enough that it would be able to consistently stay within the mainstream FTSE-350 Index, it should strongly consider going to the Main Market.
In the FTSE-350, you are guaranteed support from the likes of the iShares 350 UK Equity Index Fund and will pop up on the screens of more fund managers and international investors.
You’ll have to leave the light-touch, self-regulatory AIM regime, but companies at this scale should not have any difficulty in doing this.
The cut-off at the bottom of the FTSE-350 in terms of market cap is only around £400m, so all of AIM’s top 10 would have a chance to qualify, if they moved across.
I applaud Gama’s decision:
The Company is in the process of appointing advisers and, subject to FCA approval, expects to move to the Main Market in mid-2025. The Company will provide further updates as specific timeframes are confirmed. The Board believes that a move to the Main Market will serve to further enhance the Company's reputation and support market penetration as Gamma continues to grow in different jurisdictions.
Graham’s view: I’ve not studied the fundamentals of this company today, but I just wanted to point out that the move from AIM to the Main Market could be something to watch out for, especially when it comes to the largest companies.
For these companies, in a context where AIM has been shrinking for years, perhaps light-touch regulation and (reduced) inheritance tax relief might no longer be seen as sufficient perks to keep them around? Especially when there is another world of fresh investment potentially available on the other side of the LSE divide.
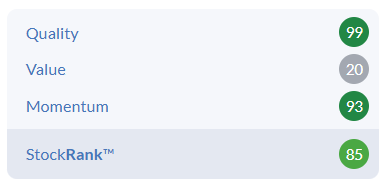
As for the merits of GAMA itself, I note that it passes 7 long screens and has a StockRank of 85 - and so I’ll leave our prior AMBER/GREEN stance undisturbed.
It published interim results in September which showed good continued growth and said that full-year adjusted EPS would be “at the top of the range of market expectations”.
Supreme (LON:SUP)
Up 5% to 176p (£195m) - Acquisition of Typhoo Tea - Graham - AMBER/GREEN
Roland already covered the interim results from Supreme last week, but they are back again with news of an acquisition.
The headline is:
Strategic acquisition of leading consumer brand further diversifies Supreme
I’m not a tea-drinker and have never tried Typhoo Tea, perhaps informed readers can let us know what the USP is?
The details around the transaction remind me why I like it when my companies acquire businesses out of administration: the buyers often achieve excellent value.
Cash price £10.2m
Includes stock and trade debtors with value £7.5m
"We are not taking on any liabilities" - CEO Sandy Chadha speaking with Paul Hill (link).
The company description is impressive given the small deal size:
Established in 1903, Typhoo Tea was the first pre-packaged tea brand in the UK and has since expanded its product offering from traditional black and decaffeinated black teas to now include white and lemon instant flavours, herbal and fruit tea infusions, and a selection of coffees across a portfolio of brands including the iconic Typhoo brand but also QT, Lift, and Heath & Heather. Today, Typhoo Tea supplies all the major UK supermarkets and discounters as well as health food store, Holland & Barrett.
Typhoo’s revenues in FY 2024 were £20m, but it made a loss of £4.6m. Within SUP, it will use “a capital light, outsourced manufacturing model, which the Board believes can generate a gross profit margin of around 30%, with a much reduced overhead base”.
Graham’s view
This strikes me as very good news from SUP.
The main point is that it helps to diversify away from vape into a much safer product category. Vape contributes 55% of revenues and an even larger majority of SUP’s profits currently.
Secondly, cross-selling opportunities are mentioned in today’s announcement. It can’t hurt for SUP to have its foot in the door with more retailers.
Thirdly, the CEO interview with Paul Hill mentions licensing opportunities; it's not possible to quantify the upside here but it sounds like another nice opportunity for SUP and its shareholders.
In terms of financing the deal, SUP reported net cash of £2.3m at last week’s half-year results, putting it in a good position to use its bank facilities for this deal.
And remember that working capital of £7.5m is included in this deal. It looks like SUP are receiving great value as their reward for moving quickly. Typhoo only went into administration on Wednesday.
In summary: this deal gets two thumbs up from me. I leave Roland’s AMBER/GREEN unchanged.
SRT Marine Systems (LON:SRT)
Down 4% to 40p (£89m) - Final Results - Graham - AMBER
Earlier this month I looked at SRT’s fundraising plans as shareholders were being lined up for yet another round of dilution.
I’ve always been sceptical of this one. However, my stance in recent times has been neutral as we wait to see the financial impact of a $200m+ contract in Kuwait, along with some other contracts including a large one in Indonesia.
That impact is not yet visible in today’s full-year results for the 15-month period ended June 2024.
(The fact that it’s a 15-month accounting period is arguably a red flag in itself, as the company has explained that its financial ratios over 12 months would not have been good enough to let it bid for a contract it was seeking.)
For the 15 months to June 2024, SRT has reported revenues down by more than 50% to £15m, and a pre-tax loss of £14.4m.
But the future is said to be brighter than ever: £320m of system projects are expected over the next two years, along with “a further pipeline worth up to £1.2bn”.
Graham’s view
I think that SRT’s “pipeline” number can safely be ignored, as usual. What I can’t ignore are signed contracts.
Meaningful revenues should be about to drop over the next two years:
As of the publication of this report, we have commenced work on our recently announced $213m contract with the Kuwait Ministry of Interior and are pleased to advise that the final administrative processes on the other contracts are nearly complete and thus expect work to commence at the beginning of the second half of the new financial year. Whilst the combination of increased overheads and delayed revenues has resulted in a significant loss for the period, these extensive preparations have placed us in a good position to successfully implement these multiple system projects within the expected two year time frame.
The broker Cavendish has still not dared to publish any specific financial forecasts for FY June 2025. This seems sensible to me as the profitability associated with SRT’s system contracts is entirely unclear.
My strong tendency is to be RED or AMBER/RED on SRT but for now I can only wait and see what happens with the new set of contracts.
Topps Tiles (LON:TPT)
Unch. at 39.9 (£78m) - Response to Media Comment - Graham - AMBER
A little bit of controversy here this morning after TPT’s 30% shareholder decided to go public with strong criticism in a letter dated 28th Nov (link here - PDF), and the contents of this letter made their way into the media.
The shareholder, MS Galleon, is a Vienna-based holding company, and it is concerned about “strategic missteps and operational failures undertaking [sic] by TPT’s senior leadership team”.
These include the “disastrous” acquisition of a competitor by TPT in August this year - and I must say that the criticism from MS Galleon appears valid at first glance, at least in terms of the numbers presented.
They also criticise “long term margin erosion”, “falling organic growth”, “a complete failure to adapt to an evolving retail landscape”, and “poor financial performance versus peers”.
TPT management have hit back today with a response briefly covering the points raised. On the acquisition, they say that it was "strategically compelling”. On overall performance, they say they have flat organic revenue since 2019 vs. a UK tile market down by 20%.
Graham’s view: it can be tricky to disagree with a 30% shareholder, especially in public, but the response from TPT reads well to me. Hopefully the two parties can have a constructive relationship where they learn from each other’s views - even if that is less entertaining than a bust-up.
TPT seemed fairly valued to me the last time I reviewed it, and that remains the case today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Supreme (LON:SUP) - Acquisition of Typhoo Tea for £10.2m - new note accessible here: https://www.equitydevelopment....
Supreme PLC has acquired the trade and selected assets of Typhoo Tea out of administration for a total cash consideration of £10.2m, including Typhoo’s stock and trade debtors with a book value of £7.5m.
For the year to 30th September 2024 Typhoo generated revenue of c.£20.0m, and a pre-tax loss of c.£4.6m. Supreme estimates that the acquisition will boost the annualised contribution from non-vape revenue to c.50% of total, and with full integration into Supreme’s cap-ex-light out-sourced manufacturing and distribution model, should contribute a 30% gross margin, which is in line with the Group’s recent Interim 29.6% margin. In August 2023 Typhoo had suffered from what it called “a group of organised trespassers” at its Merseyside factory which caused extensive damage and loss of stock resulting in £24.1m of exceptional costs. Typhoo entered administration on 28th November; Supreme has acted quickly to assess and act upon the opportunity created for its operations.
Supreme recently reported H1 25 results (ED report, ‘H1 25: margin improvement and FY25 outlook raised’) with revenue +8%YoY and a 22%YoY increase in (adj.) EBITDA reflecting cost control and gross margin improvement. As further details of the acquisition of Typhoo Tea emerge we will update our earnings outlook accordingly.
Great to hear both Supreme (LON:SUP) and Games Workshop (LON:GAW) (I hold both) mentioned in the BBC Radio 4, 6.00-6.30 news slot this evening (Monday 2nd December) for the purchase of Typhoo and the story of being on the brink of joining the FTSE100, respectively. A rare and positive mention of UK companies on mainstream news, especially when so many UK listed companies are currently being bought up, the indices shrinking, and few IPOs to replace them. I have benefited from a number of acquisitions this year including most recently TI Fluid Systems (LON:TIFS), but am much happier to see both Supreme (LON:SUP) and Games Workshop (LON:GAW) continue to grow as UK listed companies as well as see that being reported too.
Avingtrans (LON:AVG) updated the market at its AGM, although it was easy to miss. A single sentence at the end of the statement regarding the outcome of the AGM of 21 November.
“The company is pleased to report that its current performance aligns with market expectations and remains strong.” Nicely understated.
Looking at the consensus FYMay25 14.5 eps followed by 25.9 eps for FYMay26. Advanced Engineering Services is performing strongly and the expectation is for divestment of Hayward Tyler or Booths Industries in the near term, at a substantial premium to their acquisition costs.
The view of Chris Mills and other more adroit small cap fund managers such as Stephen English and Judith McKenzie is that the engineering division is worth north of £5. Who am I to argue with such erudite investors. If the very capable management team (the two Steves) are able to commercialise Adaptix or Magnetica the share price will take off. For the time being I am happy to settle for £5 plus that puts no value on the medical division.
Anyway I have added a few more on the basis of the AGM update at a little under £4. My blended purchase price over the last 4/5 years is 270p.
Re Topps Tiles (LON:TPT) it’s worth noting how well some of their unquoted peers are doing…Tile Mountain seems notably successful & considerably cheaper in my experience…also Victorian Plumbing (LON:VIC) have entered the online tile market
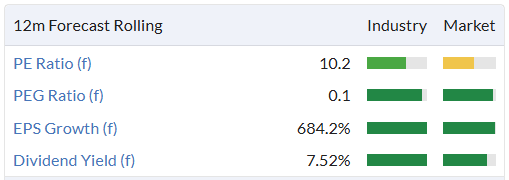
There's a lot to like about Gamma Communications (LON:GAMA), in my view. Consistent revenue growth, high ROCE, growing dividend, strong balance sheet, etc. P/E ratio is 17 using the 2025 EPS forecast so we have a classic 'GARP' stock. Barclays' price target is 2,150p – about 36% higher than the current share price. (disclosure: I own the stock).
Gamma Communications (LON:GAMA) curious to know why the share price fell 60% from peak in August, 2021? Profits look pretty steady.
The stock got a bit ahead of itself during the tech bubble of 2020/2021 when work-from-home stocks were ripping. It then got crushed when interest rates rose in 2022!
Supreme (LON:SUP) - thanks for the video clip Paul. Early days, but this could be a fantastic deal. Opportunistic. There is no reason why they couldn't double sales to £40m over 5 years. It will take time, but buying a heritage global asset for this price is smart!
Mercia Asset Management (LON:MERC) - it's always been on my long watch list. I have always been put-off by the quality of their investment portfolio. When I have researched the biggest names on it, they seemed to be highly-loss making technology companies. They seem to sell them on profitability, and have a good record though. I'm in two minds about them really, but will watch the recent video.
Hey Graham, I know you are a long term sufferer with Evoke (LON:EVOK) but just in case you hadn't noticed the price is perking up a little on decent volumes.....Artemis have recently doubled their stake and a number of brokers have upgraded. Unfortunately I can't get my hands on any of these notes but something has shifted of late...
Thanks burnt onions (your name reminds me of EVOK shares), I see what you mean but I'm not getting excited yet... at 80p I'll sit up and take notice! G
Hi Graham, I believe that in a recent post you said you generally hold on to shares despite adverse price moves. I would love to hear more on this aspect of your investing habits.
Hi Spender, thanks for the comment. There's a lot to unpack in terms of why I don't sell things but I hate paying spreads and commissions, I hate being uninvested, and I hate missing out on share price gains on companies where I've done the work and previously owned it. Besides, timing a sale is extremely difficult. I think life's easier if I don't attempt it. But there is lots more that could be said on this. G
Supreme (LON:SUP)
Sandy Chadha CEO has done some good deals with companies in administration before and this looks like another one.
Graham - you may want to watch this morning's interview with him before you write up on it:
Thanks for sharing! I've mentioned and linked to this in the report. G
Gamma Communications (LON:GAMA) leaving the Aim, this will have an adverse effect on the index. It is currently the 5th largest stock. On the Aim100, it will be replaced by a stock 10% of the size. This is will make the Aim performance look worse?
Rusty, they won't let that cause negative performance, it will not be as if GAMA has fallen 90% in value. They can rebase it. G
OK, thanks, Graham, l was not sure how it works. What happens if a company goes bankrupt?
In that case it has fallen 100% in value (probably) and the index goes down! G
Inspired (LON:INSE)
All 3 optimisation contracts kicking in and benefitiing H1 2025 onwards.
"Looking ahead, Inspired expects strong performance in 2025, with a pipeline of optimisation projects valued at £165 million."
Mkt has pushed up the price early doors.
https://www.investegate.co.uk/...
Inspired (LON:INSE)
Think this is potentially worth investors taking a look at. This was trading at a FY25 P/E of 2.5 before today's share price rise per updated analyst data.
There are some helpful piworld videos available and the company looks to be growing at a decent rate, adding customers and x-selling to existing ones decently.
I think it over-extended itself debt-wise and recent share price falls have been on the back of risk that it would breach covenants due to contracts slipping. Today it looks to face a far better chance of avoiding this, which puts the core business back centre of attention.
Takeover bid for Condor Gold (LON:CNR). Been up for sale for a while so should commute. Of note Sky News picked up on Sunday afternoon. Inclined to sell rather than hold for better offers.
The market hasn’t taken too kindly to Metals Exploration (LON:MTL) today, thoughts from anyone? Looking at the quick maths it seems like it will be good in the run
*long run. However could take some to see the returns. Still holding here!
I thought it would be a big miner with cash to bring its asset into production and has some Nicaraguan experience. Maybe will bring out some bigger sharks.
Good morning Graham, might Supreme (LON:SUP) who confirmed their purchase of Typhoo this morning be worthy of inclusion in your 'Companies Reporting' table?
?si=Bgc5b6o70BlJ5sUNok, TEIN, it's going in! Thanks. G
How nostalgic, love that post Tein, very clever...
Supreme and the Supreme's, you couldn't make it up Burnt Onions.
Carl Jung talked about synchronicity but it was first mentioned in the I Ching 3,000 years ago.
Supreme and Typhoo is an example of synchronicity.
If I remember correctly Typhoo put the T in BriTain. I like clever adds. A lot seem aimed at the hard of thinking these days but as they say "love 'em or hate 'em but don't ignore them.
Your memory serves you correctly Samsgrandad:
https://youtu.be/cKUu-H5Cu6E?s...Supreme (LON:SUP)
the only immediate downside i can think of was that i saw a boat loads of comments on tick tock and they were pretty unanimous that the taste of typhoo pre failure was damn awful compared to all the other brand names one would recognise. So first thing they need to do is ensure that the tea they are selling is fit for purpose with regard to their customers. Obviously group of people posting on ticktock isnt a scientific survey but i would have not expeceted they would all go out their way to call out the poor quality of the offering.
quick look of the webcast cofforms they get £8 mill of positive assets as part of the £10 mill deal - so to me it looks ultra low risk long term even if it doesnt regain any of its former glories. If they can improve the taste if prior mangement were useless well that would be a bonus.
Certainly sounds like it should pretty much be closer to money maker from day 1 ?
K3 Business Technology (LON:KBT) clearly needs to be in the comments today as it sells a large part of its business(but not all) for 150% of its closing market cap. Immediate price rise this morning to 99p. Sale appears account for about 35% of its annual revenue but the remaining revenue/profit needs to be reworked. A “substantial” part of the £36mm proceeds will be returned to shareholders.
Gamma Communications (LON:GAMA) - Not a share that I have followed but intrigued by announcement mentioned above that they intend transferring from AIM to main Mkt. They already have an excellent group of solid institutional shareholders and despite the recent budget I wonder how many individuals are attracted by 20% IHT which will now be lost and if other coys will follow.
With a valuation of 1.5 Billion that moves them straight into FTSE 250 territory, could be a factor? And IHT benefits diminished and potentially further diminished in the next 4 years, seems a safer long term pool of extra liquidity.
I've had a first glance at Mercia, having been jogged a few times by positive comments from Graham.
I must confess that I'm struggling to arrive at fair value.
There seem to be around £166m of assets, in the form of cash and investments. So the market value is fully backed by assets owned by the company - excellent news as long as those assets are saleable at those valuations. But there are big quoted private equity vehicles such as HVPE trading at 40% discounts to NAV. So maybe not so outstanding versus better known equivalents such as Harbourvest Global Private Equity (LON:HVPE) RIT Capital Partners (LON:RCP) Caledonia Investments (LON:CLDN) .
At a P&L level, it looks like the PBT understates the true profits being generated, by some margin, due to things like amortisation. Am I right in thinking that a more normalised P&L could be as high as £7m PBT in a full year?
But £133m market cap versus £7m PBT (if it is anything like that big) - that's high for an asset manager, isn't it.
I'm scratching my head......can't decide if it's good value or not. Just like last time I looked....
Mercia Asset Management (LON:MERC) you need to value the balance sheet investments and fund management business as separate components. I suspect most of the value is in its balance sheet investments, which I'd value with reference to NAV. There are plenty of private equity and venture funds on c40% discounts, but with much more established track records - so I would want at least a 40% discount for MERC. Then add whatever you think the fund management side is worth - doesn't generate a lot of profit, so I wouldn't value this particularly highly. Personally think there are much better opportunities in the PE/venture fund space - Harbourvest Global Private Equity (LON:HVPE) Caledonia Investments (LON:CLDN) Molten Ventures (LON:GROW) and Chrysalis Investments (LON:CHRY) to name just a few.
Incisive reply thanks.
Card Factory (LON:CARD) gets a mention by HL's Senior Equity Analyst:
Card Factory specialises in greeting cards and gifts, with around 1,000 stores across the UK and Republic of Ireland.
The second half of the financial year, which includes Christmas, usually accounts for the majority of its annual profit. This year, it's even more significant.
A quick look at recent performance shows a fall in profit at the half-year mark, and the valuation took a hit. But weaker performance was already expected, as management had guided towards more weight in the second half, even before the results.
The important thing is that there's been no change in their full-year guidance, which signals confidence from management, and we think some positives have been overlooked.
https://www.hl.co.uk/news/chri...
Whatever happened to the news about the USA tie up which was promised for November ? Has it fallen through, or was it hyped to deflect from the awful NIC / Living wage costs that will impact CARD in the next year ?
Thank you very much for your comments on Mercia Asset Management Graham, we are long term holders and added after the results. I'm pleased it's still green but as you say, so far the market doesn't see the potential which makes me only cautiously optimistic.
Equity Development gives a sum of the parts valuation of Mercia Asset Management (LON:MERC) as 52p. Standing at a discount of over 40% I suppose the question is whether there are more attractive investments at larger discounts. If there are please let me know so I can switch!
Quite a few actually, as Grey Investor mentions above. They are also longer established with more proven success. Venture capital funds usually do trade at considerable discounts for the very good reason that we are taking the asset value on trust rather than being able to calculate from current share prices. Mercia Asset Management (LON:MERC) looks interesting but hardly outstanding bargain to me.