Daily Stock Market Report (Mon 22nd September 2025) - VANL, BKS, CFX, MFX, WIL, ELIX

Good morning!
08:17 - Agenda is complete
14:03- Report is complete
Spreadsheet accompanying this report: link (last updated to: 5th September).
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) | |
AstraZeneca (LON:AZN) (£175bn) | Phase III trial results showing Tezspire reduced nasal polyp severity and nasal congestion, nearly eliminated the need for surgery and significantly reduced systemic corticosteroid use vs. placebo | |||
ITM Power (LON:ITM) (£431m) | RWE reserves 30 units for call-off by 2027. | |||
Elixirr International (LON:ELIX) (£401m) | Acquisition of TRC Advisory, LLC | H1 Revenue +35% to £71.4m (17% organic), Adj. EBITDA +42% to £21.5m, EPS +35% to 29.0p. Net debt £6.8m (24H1: Net cash £22.1m). Confident in delivering organic FY 25 trading results in line with market expectations. | AMBER/GREEN (Mark)
Although there are some of my usual concerns about people businesess and acquisition costs, the rating here looks modest compared to organic growth rates. With acquisitions on top, and with a pattern of EPS upgrades, this continues to look good value. | |
Wilmington (LON:WIL) (£299m) | Ongoing revenue +11% to £99.5m, Adj. PBT +18% to £28.4m, Adj. EPS +20% to 23.7p. Net cash excl. lease liabilities £42.2m (FY24: £67.8m). “We have had a good start to the current financial year, with revenues and profits in line with expectations and look forward to Conversia joining the Group later this year.” |
| ||
Riverstone Energy (LON:RSE) (£226m) | All shares in Solid Power Inc, a Louisville, Colorado based producer of all solid-state batteries for electric vehicles, sold for $25.9m. | |||
Beeks Financial Cloud (LON:BKS) | TMX Datalinx, the information services division of TMX Group, which operates primarily Canadian markets, such as the TSE, to offer Beeks' Exchange Cloud® platform to its clients. Revenue share deal to help meet FY26 expectations. | AMBER (Mark) [no section below] This is another deal with a well-known exchange continuing the trend for positive newsflow. It is a revenue share deal, and while no figures are given, my assumption would be that Beeks will fund the capex involved. The typical 30-something per cent gross margins of this business suggest it is either one of the worst software businesses in the UK or one of the best equipment lessors, depending on your view. While it is always likely to be a capital-intensive business, it has shown the ability to grow rapidly when it has the capital, which the interim results suggest it has plenty of to fund deals such as this. This agreement is said to help it meet current FY26 expectations, which at around 26x forward earnings already price in significant growth. The StockRank of just 28 also suggests some caution is warranted, so I am in no rush to change our neutral view on this one. | ||
Rainbow Rare Earths (LON:RBW) | Successful optimisation of the feed stream to the final separation circuit via the incorporation of a Ce depletion step benefitting quality and operating costs. | |||
Ilika (LON:IKA) (£65.1m) | Commencement of its PRIMED programme, a step towards commercialising Ilika's innovative solid-state battery technology. | |||
Colefax (LON:CFX) (£50.3m) | Fabric Division sales for 19w to 12 Sep +7.8% (+10.3% CCY). Cautious about prospects due to the end of the pause in additional US import tariffs on 1 Aug and the additional 50% import duty applicable to Indian origin goods from 27 Aug. “Allowing for these factors and budgeted increases in operating costs we are expecting the current year performance to be in line with expectations.” | AMBER/GREEN (Mark - I hold) [no section below] The revenue growth rates in their key Fabric Division are quite impressive at 10% constant-currency, given the current consumer market sentiment. Interestingly, all regions are growing, even the UK (off a low base)! However, they expressed significant caution around the tariff situation in the US in their FY results that were released at the end of July; they felt that demand had been pulled forward to avoid tariffs. That caution remains in this trading statement despite the positive revenue growth so far continuing into this financial year. Today they also quantify how much extra they will need to charge US customers in future to maintan margins at $6m in total. This is likely to reduce demand in this core market. All of this means that they are unlikely to repeat the 108p of EPS that they delivered in FY25. Instead, they guide in line with forecasts for 76.7p EPS, which puts them on a forward P/E of 11. This doesn’t look particularly cheap, until you realise around half the current market cap is in cash. They have a rather strange way of returning capital periodically, and are quite illiquid. However, their bullet-proof balance sheet, long-term focus and outperformance in difficult market conditions will no doubt appeal to certain investors. Hence, I think it makes sense to have a broadly positive view (and a small holding). | ||
Creo Medical (LON:CREO) (£50m) | Revenue +40% to £2.2m, u/l Loss £9.1m (24H1: £12.8m loss), Cash £20.5m (31 Dec: £8.7m) after sale of 51% of Creo Medical Europe for £24.9m. Continued implementation of operational efficiencies and cost reductions. Management reiterates 40% to 60% full year revenue growth, in-line with guidance. | |||
Fiinu (LON:BANK) (£49.4m) | £2m loan from Manx Financial at a 10% interest rate + convertible at 10p per Fiinu share. | |||
Aoti (LON:AOTI) (£47.9m) | H1 Revenue +21% to $31.8m, Adh EBITDA -10% to $3.07m, Net debt $5.4m (24H1: Net cash $5.5m). “As indicated in the July trading statement, revenue growth for FY 2025 is expected to be in the mid-teens and adjusted EBITDA margin is expected to be low double digit. Trading post period in July and August has been consistent with this revenue growth guidance.” | |||
Ondo InsurTech (LON:ONDO) (£45m) | Continued to achieve meaningful progress, particularly in the US, with US customers of 185k (30% of customers & 50% of recurring revenue). | |||
Manx Financial (LON:MFX) (£43.2m) |
& £2m CLN | H1 net interest income flat at £17.7m, PBT +16% to £4.1m, loan book +5% to £392.6m. CET1 12.2% (31 Dec: 12.5%). £2m loan made to Fiinu at a 10% interest rate + convertible at 10p per Fiinu share. | AMBER (Mark) [no section below] The CLN here seems to be a good deal for Manx, as they negotiated it when Fiinu was trading below the conversion price. They get a 10% annual coupon and are already £350k into the money on the convert. However, things may not be as good as they seem, as Fiinu itself only has a StockRank of 19, and its only positive characteristic is Momentum. A lot is riding on the future success of their Plugin Overdraft® product, and the shares may well be below the convert price by the time they can be converted. If I were Manx, I’d be looking to hedge that position as soon as possible, which may put pressure on the Fiinu share price. The results themselves look ok, but as a non-bank analyst I have little insight apart from that I’m not sure I’d pay 2xTBV for a small bank with a 12% CET1 ratio, when something probably safer and more diversified, such as Barclays, still trades below TBV. However, I don’t have enough conviction either way to change Graham’s previously neutral view. | |
Van Elle Holdings (LON:VANL) (£39.6m) | “…full year trading and profitability is expected to be materially below market expectations, and below the prior year.” Medium-term outlook positive due to strong Jul 31st order book of £47.3m (30 Apr: £41.5m) SP -10% Zeus cut FY26/27/28 EPS by 50%/30%/17% |
BLACK/AMBER/RED (Mark) They say that profits warnings come in threes, so this downgrade should perhaps not be a surprise. However, the scale of the miss is significant, with broker, Zeus, cutting FY26 EPS in half. The company's claim of a positive medium-term outlook doesn’t stop Zeus also making significant cuts to future years and the dividend forecast. This suggests that there is no easy fix here, and while the discount to TBV highlights that there may be value here eventually, there is no sign of all of these assets being made productive anytime soon. As such, I reluctantly reduce our view one notch further, until there are signs that current downward trends are actually reversing. | ||
OPG Power Ventures (LON:OPG) (£28.9m) | Tax rate on coal in India will be increased from 5% to 18%. Expects £2.5m cost increase due to these GST changes. | BLACK | ||
Helium One Global (LON:HE1) (£23.8m) | Electrical Submersible Pump (ESP) purchased. On track to commence ESP operations at ITW-1 in Q4 2025 | |||
B90 Holdings (LON:B90) (£16.3m) | Revenue +75% to €2.41m, EBITDA +65% to €303k, Net loss €39k (24H1: €322k loss), Net Cash €401k (24H1:302k). “With market expectations reaffirmed in our July 2025 trading update, we remain confident in delivering a strong full-year result at both revenue and EBITDA level.” | |||
Rockfire Resources (LON:ROCK) (£15.7m) | H1 LBT £536k (24H1: LBT £888k), Cash £140k (24H1: £515k). £2m gross raised in July post period end. | |||
Oriole Resources (LON:ORR) (£15.4m) | 59 mineralised intersections, including 13.7m at 1.36g/t from 116.9m. | |||
EMV Capital (LON:EMVC) (£11.7m) | Novel, ultra-rapid mechanism that reduces the chance of bacteria becoming resistance to its action and has advantages over traditional antibiotics acquired for £2.475m from Destiny Pharma. | |||
New Frontier Minerals (LON:NFM) (£10.7m) | FY LBT $2.5m (FY24: LBT $15m), Cash $1.8m (FY24: $1.1m) |
* Market caps at previous trading day’s close
Mark’s Section:
Van Elle Holdings (LON:VANL)
Down 8% at 34p - Trading Update - Mark - AMBER/RED
This is now the third clear profits warning. This is the recent history:
In March 2025, their broker Zeus took 6% out of revenue for FY25 and reduced PBT by 33% when the company said that they no longer expected a recovery in 25H2 due to delays in their Canadian business.
There was a small positive in May as they received a cash injection from outsourcing heavy haulage operations to specialist company, transferring their assets.
In early June, we got a further profits warning with Zeus reducing EPS by a further 14% to 2.4p for FY25. The company’s narrative suggested that this was a delay of work from FY25 to FY26, but given, that Zeus took similar amounts out of FY26 and FY27 PBT forecasts, this didn’t hold a lot of water, in my opinion, and I downgraded our view to AMBER (it would have been lower apart from the discount to TBV, and presence of an activist shareholder on the register.)
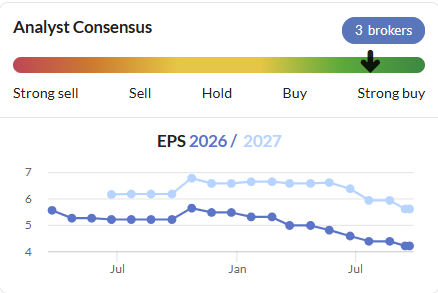
The consensus trend shows a deterioration in outlook that goes even further back:
Today’s further warning is based on a continuation of previously given trends:
As commented on in its results announcement on 23 July 2025, challenging trading conditions experienced throughout FY2025 continued into the new financial year. The expected improvement across the Group's core sectors is yet to materialise, attributable to spending constraints and delays to contract starts across all sectors, particularly related to Building Safety Act ('BSA') approvals for high-rise residential buildings.
Which has led to:
Due to these factors, year to date revenues have not increased as anticipated and consequently, full year trading and profitability is expected to be materially below market expectations, and below the prior year.
This looks to have caught their broker on the hop as there was no updated coverage first thing, but I can now see the Zeus’s updated note in Research Tree, which quantifies the miss:
With FY26 results expected to be significantly below market expectations and below the prior year, we reduce FY26 forecast underlying PBT by c. 50% to £3.0m, primarily driven by a 6.3% reduction in our revenue estimate to £140.0m.
This is a huge downgrade for FY26. However, the company remain positive about the medium term, saying:
The medium-term outlook remains very positive, with significant opportunities in the growing energy and water sectors, where good early progress is being made. The Group continues to maintain a strong order book of £47.3m at 31 July 2025 (30 April 2025: £41.5m).
However, Zeus throw shade on that view by saying:
Zeus FY27 and FY28 revenue forecasts are reduced by 6.4% and 6.5%, respectively, and underlying PBT forecasts are reduced by 31.7% to £5.5m in FY27 and by 16.7% to £7.5m in FY28. The profit downgrade in FY26 reduces our net cash (ex. IFRS 16 leases) forecast from £5.8m to £3.1m, with the Group’s banking facility remaining undrawn.
So again, far from being a short-term shift of demand into the future, this seems to be a permanent downgrade of prospects for the business.
These figures are presumably on a continuing basis as well. In the FY25 results, the company classified their Canadian Rail Operations as discontinued as they expect to sell or close this subsidiary. However, as far as we know this is still operating and the company will still be funding the ongoing losses here. Given that these totalled £1.3m last year, they are material to the reported PBT, which will be lower than the headline figures, at least for FY26.
Valuation:
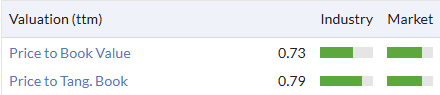
The original bull case here was that a strong cyclical recovery in trading would put this company on a very cheap multiple. This was backed up by the discount to TBV:
If these assets can be made productive again, then the company should be re-rated. Much larger ground-work contractor, Keller, trades on 2xTBV. However, there is little sign that Van Elle's assets can be made productive in the near-term. Indeed, we now need to go out to Zeus’s FY28 forecasts of 5.1p EPS to make this look good value. The company does trade on a low EV/EBITDA of less than 4, but this is not the sort of business where we can ignore depreciation as a cost. Zeus point out that such metrics are merely in line with peers.
Zeus prefer to utilise a DCF as their valuation methodology and the changes to forecasts today, reduce their valuation from 53p to 44p. This still represents some 30% upside from today’s buy price. However, I really struggle to place much confidence in the forecasts. As such, investors may want to demand a higher discount rate that the 11.5% that Zeus use.
The company highlights their balance sheet strength, and the asset-backing and net cash does give them time to wait for a recovery. However, I also not that Zeus have cut their dividend expectations in line with EPS. The company has been paying 1.2p out each year for the last few years, but are only forecast to pay 0.7p in FY26. There are cyclical companies on the UK market that pay a much better yield while investors wait for a recovery in trading.
Mark’s view
I am torn on this one, and it seems the market often is as well. Despite repeated profit warnings, the share price always seems to bounce from current levels as investors get over the initial disappointment, and focus again on the discount to TBV and chance of a medium-term recovery.
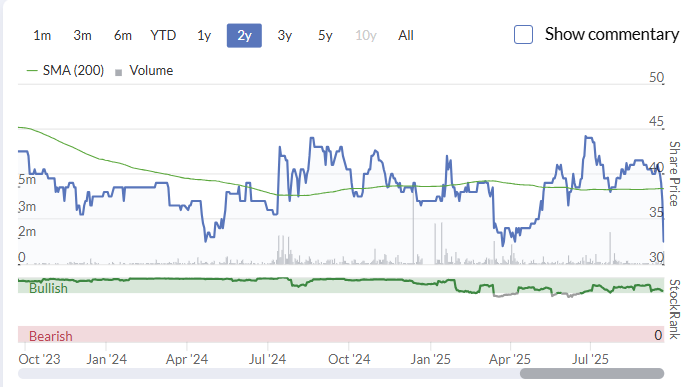
A sale or closure of their loss-making Canadian subsidiary may help remove management distraction even if the losses here are now excluded from these figures. Equally, further intervention by Harwood in forcing a turnaround or other corporate action may give a positive catalyst. The increasing order book suggests that momentum may now be swinging the other way after the third warning.
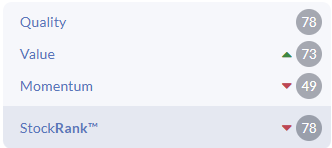
However, I don’t tend to invest on such possibilities, and the only metric the company is really cheap on is now the discount to TBV. One could argue it looks good value on 2028 EPS estimates, but given that forward earnings keep being cut by the brokers I don’t put much weight on this. The StockRank has been declining, and I expect the FY26 results, when they arrive next year, will see further deterioration in most of these metrics:
Everytime the company has warned in the past, and the share price has dropped to these levels, I’ve been tempted to buy, expecting a medium-term recovery. However, the scale of today’s downgrades, including cuts to the dividend payout, and that these forecasts now exclude the large losses from Canada, means that that temptation has disappeared this morning. Hence it is a further reluctant downgrade of my view to AMBER/RED.
Wilmington (LON:WIL)
Unch. 336p - Financial results for the year ended 30 June 2025 - Mark - AMBER
Wilmington describe themselves as a “provider of data, information, education and training services in the global Governance, Risk and Compliance (GRC) markets”. You’d expect this to be a growth area in the market, and the headline figures read well here, with double-digit revenue growth, and operational gearing leading to a 20% rise in EPS:
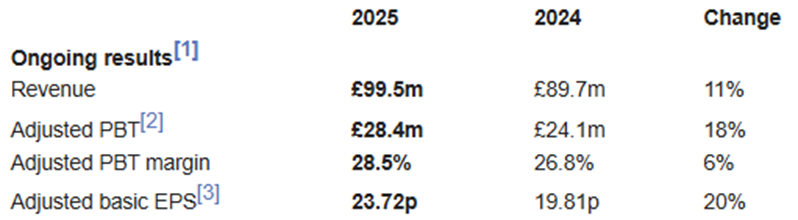
However, you quickly realise that there are three factors to untangle which add to the complexity: Acquisitions, disposals and adjustments. Let’s take these one at a time:
Acquisitions:
They acquired Phoenix Health and Safety in Oct 2024 and this appears to be responsible for all of the revenue growth:
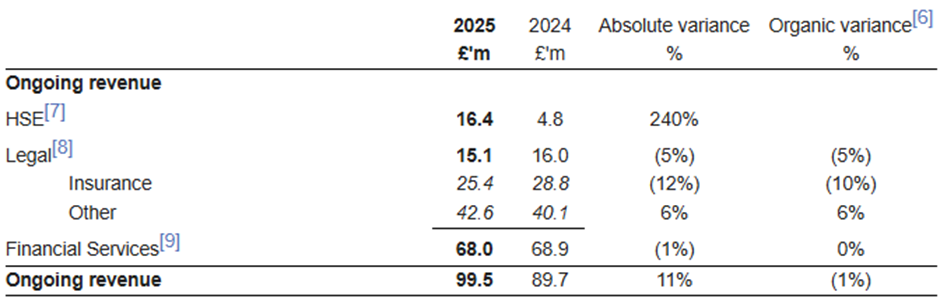
It is largely this acquisition that means that net cash has declined by £25.5m to £42.2m.
They are proposing to buy Spanish business Conversia for £105m for 13xEBITDA, and their debt leverage ratio will go to 2x. While there are strategic reasons for this acquisition, this is not a cheap price (3.3x sales) and adds to the risk here.
Disposals:
They sold Compliance Week in Feb 2025, and are marketing their US events business, FRA. The £662k loss from sold and closed businesses is excluded, although it seems they have yet to classify FRA amongst this.
Adjustments
While adjusted EPS has grown, statutory results are down, mainly due to a big increase in adjusting items:
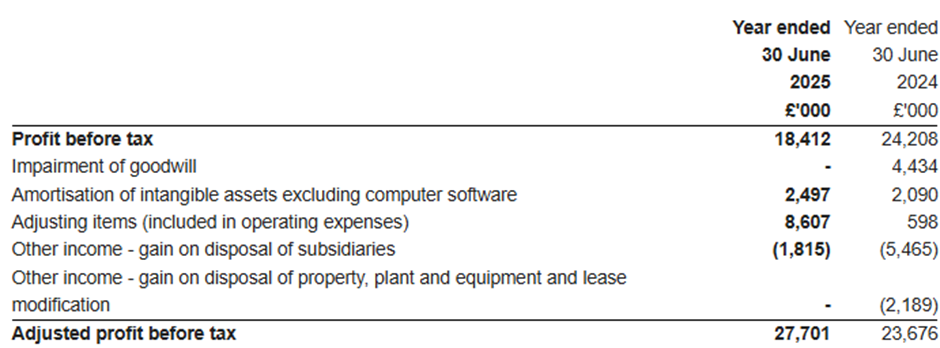
They say:
Strategic activities represent acquisition costs comprising earnouts in relation to the acquisitions of Astutis and Phoenix of £5.9m (2024: £nil) and strategic transaction costs relating to acquisitions and disposals of £2.7m (2024: 0.6m).
So this is another company that wants shareholders to give them the benefit of the acquisitions and disposals they make, but not count the costs against them. For wilmington, such costs seems to be an ongoing expense, as they say:
Alongside streamlining the Group since 2020 by selling or closing eight of the 15 businesses, we have consistently delivered notable profit growth over the five-year period.
Outlook:
They say that in the current quarter revenues and profits are in line with expectations. Presumably, current forecasts don’t include any impact of the Conversia acquisition, but even then the high multiple paid isn’t going to have an immediate material positive impact on earnings.
This means that the current forecasts, while not bonkers, don’t look appealing compared to single-digit percentage growth in revenues and profits:
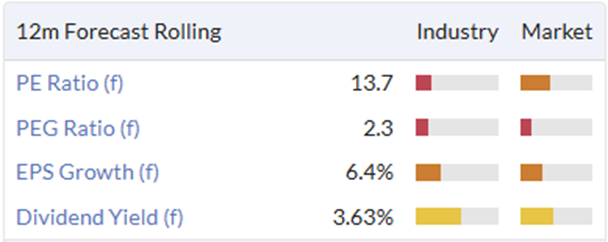
Given the continued sale and purchase on businesses, you can almost guarantee that these figures will include significant adjusting items.
Mark’s view
When Graham looked at this in February, he said:
At 15x earnings it’s not particularly cheap, and that is likely to be before the adjustments are accounted for. Actual reported earnings per share were only 2.88p in H1. I may need to downgrade this further to AMBER, the next time I look at it.
It is a little bit cheaper today, but the risk looks to be ramping up with a strategic, but expensive-looking global acquisition, and no end in sight for the type of adjustments that do impact the company’s cash flow. I am going to cement my reputation as the cynical one and complete Graham’s potential reduction in view to AMBER.
Elixirr International (LON:ELIX)
Unch. at 830p - Interim Results & Acquisition of TRC Advisory, LLC - Mark - AMBER/GREEN
Decent growth in revenue here. Although around half of it comes from acquisitions and hence there isn’t any obvious operational gearing:
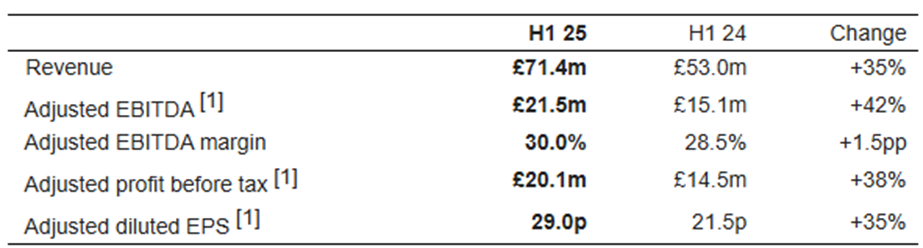
29p doesn’t leave much to do to hit the original FY forecast of 49.6p, although there was a seasonal bias to H1 last year. Having upgraded forecasts recently, their broker, Cavendish make further upgrades today, saying:
We have upgraded FY25E EPS by +12% (+8% organic, +4% from TRC), FY26E EPS by +18% (+2% organic, +16% from TRC) and our target price from 1100p to 1240p.
Helpfully, they have split out the impact of trading and from today’s acquisition. The acquisition itself seems reasonable, but not amazing value for a people business on an EV/EBITDA of 4.2x-7.8x dependent on contingent consideration earned during the top-up and earnout period. The initial payment is met by debt facilities and issuing shares:
The headline initial consideration payable under the Acquisition is US$57 million …The cash component of the initial consideration of US$41 million will be funded through the Company's increased revolving credit facility with National Westminster Bank PLCof £65 million and a US$20.25 million term loan with NatWest. The balance of the initial consideration of US$16 million will be satisfied by the allotment and issue of 1,428,526 new Ordinary Shares to the TRC Seller.
The size of the contingent consideration is significant, and adds to the leverage, if we consider this similar to debt, or dilution if they issue shares for this:
Deferred consideration of up to US$68 million, comprised of:
o A post-Completion contingent top-up payment, capped at US$32 million, to be determined by 30 April 2026 and based on the achievement of agreed FY 25 Adjusted EBITDA performance targets for TRC, will, if earned, be payable up to US$24 million in cash and up to US$8 million to be satisfied by the allotment and issue of further new Ordinary Shares (the "Deferred Elixirr Shares") to the TRC Seller.
o A further deferred performance-based payment of up to US$36 million, payable over three years (2026, 2027 and 2028) in three instalments, at the Company's discretion, either in cash or through the allotment and issue of further new Ordinary Shares (the "Performance Elixirr Shares" and together with the initial Consideration Shares and the Deferred Elixirr Shares, the "Transaction Shares") to the TRC Seller.
Back to the results, there are some large adjustments:
SBP is always a debate, and the size of these suggests we should definitely be using fully diluted share count in any valuation, as a minimum. Costs associated with their move from AIM to the main market should be one-off, but given that they have already announced another acquisition today, M&A maybe should be treated as recurring.
Valuation:
Today’s upgrades by Cavendish mean that the valuation metrics look a bit better than we have in the StockReport:
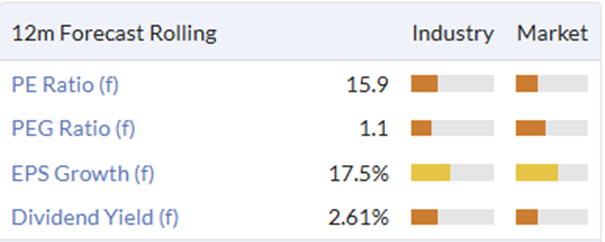
Now we have 14.9x FY25 EPS and 13.1x FY26. Seems reasonable value given the organic revenue growth rates, although some caution is probably required as this is largely a people business, which adds to the risk that the bulk of the returns go to staff not shareholders in the long term. Plus they now have modest net debt forecast, whereas they previously had net cash.
Mark’s view
The organic growth rates in today’s results are probably sufficient to justify the current valuation. When you add in the growth from acquisitions and history of upgrades, this may well be good value, even if one is more conservative than the company about what are really one-off costs. Roland had this is AMBER/GREEN following the H1 trading update and with a further acquisition and EPS upgrades, I am happy to take the same view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
Beeks Financial Cloud (LON:BKS) "it is either one of the worst software businesses in the UK or one of the best equipment lessors, depending on your view."
A really bizarre way of framing it (maybe driven by its high valuation, which I would say is more of a reflection of its sticky, recurring revenue model vs it being considered a software company?) Either way, I'd describe it as an infrastructure as a service business which enables connectivity, monitoring and analytics associated with the financial markets. I think they're developing more offerings which are software-based which integrates with their tech e.g. the analytics and monitoring, perhaps some of the cloud-based elements... but curious how and why they could be considered one of the worst software businesses in the UK given how much loss-making junk must be out there?
Has anyone here heard any news ahead of Spectra Systems (LON:SPSY) interims in a week's time?
The VR, MR and SR have been increasing and the SP steadily falling. The latest trading by an insider was in June when someone exercised some options and took net shares not cash, which seems mildly positive.
Has anyone analysed the trades this year and gained insights?
I hold as one of my largest positions
No great insights. The lack of announced contract wins is perhaps why the market has been climbing a wall of worry here. I hold and am not really worried about the short-term given that the sensor contract will likely see them deliver strong results, it is more the outlook that may be weak if they just aren't getting decisions from key Central Banks. The big prize is still polymer printing contracts and if they actually deliver something here, then they will become the third global player with the equivalent uplift in rating (or be bought out by one of the other players.)
Thanks Mark and Millaree. That's helpful
+1, I agree with Mark and rmillaree here.
No big contracts announced recently, and time is running out to boost FY26 numbers, as work with central banks take a long time from contract announcement to flow of revenues.
Plus, they have nothing yet to show for their efforts in polymer banknote; they had indicated getting on a preferred supplier list for a Middle East bank they were expecting in H1, but clearly that has come and gone. No new "trials" announced either, so the upper funnel pipeline here seems to have gone dry too.
Hoping the recent weakness isn't any news leaked out about issues/delays to the manufacturing and supply of the big sensor contract. Always a risk, with a manufacturing delivery of a contract.
I sold out in July at 220p. Felt that the lack of contracts, plus a very light-weight FD appointment (that can be push around?) was worrying. They've churned through many FDs in recent years, plus their auditor is a tiny outfit; the potential ingredients for cooking the books. Not that I have any evidence from reading the accounts - but coupled with opaque customer list and potentially very complex contracts and less than arms length relationships, I felt a bit antsy and decided to crystallise my gains here and move on.
Breaking into polymer banknotes would be transformational; but again, any "trial" announcement to "tendering" to "selection" to "design" and finally "production" is probably on a 5 year or more horizon, before revenues start to flow in?
Spectra Systems (LON:SPSY)
Heard nowt.
I hold and am not particularly worried - the thing here that goes against the company right now is that next years earnings are trending materially down from the curent year. Thats never the easiest sell if you are saying "yeah company is doing great" - and the future is slapping one if the face suggesting otherwise. To be fair to the company they have been open and transparent in tis regard from the get go - so its notn as if they have over delivered - it was simply that this year is bumper year.
The market doesnt like uncertainty
There is the obvious risk that small holders can be the last to find out that poor trading has taken place - so the danger for anyone adding pre results is that the company are simply being tardy ref delivering some bad news - eg if it ends up the same as £W7L. I get the impression that this share is pretty niche anway though - so random drift is no surprise but if there is bad news us small shareholders are at the end of the info line.
As a holder i would love to know if there are any expectations for 2027 - i suspect it may take initial guidance ref 2027 above 2026 for the dial to move. If the buisness is still growing profits "lumpy contract 2025 aside" it would be nice to have that confirmed - i suspect that wont happen till next year though unless they give us a teaser with super confident outlook.
I struggle to get bank notes out of my head. Believe Spectra Systems (LON:SPSY) has other tech up their sleeve.
We are going digital whether like it or not so governments have control. The only place I use cash anyway is in a street market or barber shop.
Has potential irons in the fire which could be highly game changing in unrealised ways, but don't have time to do a thesis on it. Appreciate if someone has the time. Anything open to making a buck or two, today and tomorrow.
Ah just had a thought - if they had serious tech moat then the US would have hoovered it up. Do hope I'm wrong for hodlers.
Kromek stock rank has moved from 25 to 98 - and is now a super stock. A company that has been a disaster for over a decade and has never shown a meaningful profit. Super stock looks a bit of a stretch, and some would assume the stock rank looks like a system glitch. Does there recent improvements justify such a bullish stock rank, never thought I would see the day that Kromek was rated at 98, and would've assumed they were forecasting much better numbers for this to make sense. Opinions welcome.
I could write a whole thesis on Kromek! I have been a holder since 2020. In fact, after repeated buy ratings in the investors chronicle and multiple top up's during their vertical downward share price it is what inspired me to look at tools like Stockopedia! I will try and give a small snapshot of my view (for the record, I have driven up to AGM's (I live in Bristol and their office is in Durham - so it was a very long day trip!), spoken to their CEO via LinkedIn and done countless hour of research - so hopefully this is qualified to the best of my ability. So here goes.....
For what it is worth I took the following conclusion when I went to the lab for the AGM last December.
It sounds paradoxical considering my experience with the stock but this is my highest conviction (I hold cicra 15-20 stocks). I am hoping its the old adage of time in the market and not timing the market that will yield the long awaited return for me. Kromek has very little goodwill so if this leopard has changed it spots........it will be a multibagger!!! My time horizon is still to hold this for 2-3 years.......I am not looking for a quick one. I was very surprised to see it reach a ranking of 98 and super stock!!!!! I have known for months it would rerate from the low 20s it has been hovering around as the TTM didnt factor in the Siemans deal and this was massive. The one risk is that this deal is a one off......and Kromek revert to mean. If its not a one off this organisation is materially different to being a microcap.
I hope this helpful. As always, views are my own, and there is probably optimising bias in here!
and for anyone interested, there's an IMC presentation at 5pm today.
Hi I wonder how their scanners compare on price/performance with scanner being developed by Avingtrans?
Beeks Financial Cloud (LON:BKS) is a funny one. Announced a raft of new deals this year and seem to have the door open at a lot of new customers and yet the share price is down 29% in the last year. I think they have over promised in the past and the market wants to now see the results improve before they give them the credit but clearly the announcements coming in mean this is going to be significantly bigger than it is today in the next few years. (I hold)
Beeks Financial Cloud (LON:BKS)
and yet the share price is down 29% in the last year. I think they have over promised in the past and the market wants to now see the results improve before they give them the credit but clearly the announcements coming in mean this is going to be significantly bigger than it is today in the next few years. (I hold)
Yes but before dropping 29% the shareprice had tripled in the prior 12 monthly - so the price is still waaaaay ahead of where it was at the start of 2024.
so imho i dont think its funny - just natural that when shares go on a roar they often overshoot at the top the stabalise at level below the peak for extended period of time - thats imply pretty normal.
Ref trading its remarkable how static the stocky numbers have stayed ref eps - for companies going places its nice to get some upgrades to expectations over period of say 12-18 months. In that regard the contract wins are not matched by better than previously expected bottom line.
Note we are in an infromation void at present on stocky - imho stuff like that doestnt help.
Ie we are nearly 3 months into new year and the next year figures (ye 30/6/2027) are yet to be flagged up. Does anyone know what ye 30/6/2027 expected eps is at present if it exists -one would like to think the long hard slog would start to show material fruits in that year.
Note at present even the 2026 numbers are just meeeeh better than 2025 based on the rating.
Add in the fact the company will probably have very heavy "capitalised costs" at present - imho its still got to prove to some (me included) that they will be a cashflow profits machine. I understand why thats not the case short term - but as some stage the prior investment should pay dividends ref cashflow.
Ingenta (LON:ING)
Mark,
I think a few people must have read your positive report on Ingenta over the weekend because they are absolutely impossible to buy today, no signs of an overhang, just a very illiquid, squeezy undervalued share. Best of luck holders, it looks good to me....IMC this week.
I am hoping that this is a rational repsonse to a valuation anomoloy that seems to have occurred due to the persistent selling of a microcap fund over this year. Obviously, this is an illiquid stock and everyone should do their own research, join the IMC presentation on Wednesday and ask lots of challenging questions, rather than relying on my opinion that is undoubtedly biased as an owner of the stock and AGM attendee.
In terms of trades, I looked at the ones last week, and unless there were periods where investors could sell at the ask, then there were about 75k more shares bought than sold. In my opinion, there is no way that market makers would sell short what works out to be 0.5% of the company, so they must have a seller in the background.
If you can't buy today on a rising price, it might mean that the seller is finally cleared, although I'd like to see some larger trades published before coming to that conclusion myself.
Bought into Ingenta (LON:ING) just over a month ago on some of the fundamentals that you have called out. One of my smaller positions but clearly nice to see some positive movement here.
I do hate to be a wet blanket, but when I have messed in these micro caps previously they just haven't worked. I have come to the conclusion that their performance relies on the macro stage. Then they can really deliver but noone wants to get caught in a dropping market with no liquidity. The current macro picture is not clear enough for that level of risk.......in my opinion.
Agree and would never put more than a small position in any of these. I generally invest if I feel they are unloved/undervalued but have a clear exit price built in. First sign of anything bad and I sell regardless of the price.
I'm sure that's wise. We all have to make decisions based on our own assessments and risk tolerances. I am probably more tolerant of illiqidity than many investors as I tend to be naturally contrarian; providing liquidity when the market looks to be selling at any price, and providing liquidity when everyone gets excited and multiples get stretched.
With the continuing troubles at JagLandRover - which British coys are likely to suffer - Volex (LON:VLX) among them..?
I would be interested to hear what our Stocko commentators think of the Wilmington (LON:WIL) results. I used to hold but got spooked as they started to expensively churn their portfolio of businesses. Perhaps early days to assess the success of this strategy, especially as a large acquisition won't complete for another month. However, it looks like a lot of activity to go nowhere so far.
Mark advised caution on VANL on June 5th, he was right, this is the third PW. We hold, is it take our medicine time, or add a few on order book strength? Observations appreciated.
Morning JASVFS, I'll definitely be taking a look at this one.
Hi Jas, Im afraid the correct coarse of action is to sell up VANL . Its failed to live up to expectations and needs to go. Not nice but in the long term for your overall portfolio its a good strategy. Invest it back in with a high stock ranking stock. I sold out on 5th May 2025 and took a loss on it.
Yes its got a good order book but if it cant price its orders so it makes good profit on them then whats the point. Also these captail intense companies are ones to be wary off as they are always having to buy loads of equipment. Thats a barrier to entry but only so much.
GLA
Good morning Mark & Graham,
As Trustpilot (LON:TRST) is frequently discussed here, this short seller report may be of interest. It was mentioned on the Bear Cave newsletter this week. I am not familiar with the blog, but there have long been rumours that there is not much trust in Trustpilot.
Protection racket brought up to date aledgedly?
Morning! just me this morning I'm afraid, Graham will be back tomorrow.
Thanks for the heads up on that report. I've not read it in detail, but I largely agree with the thrust of it from the summary. It has always appeared to me (in my personal opinion, from a non-scientific sample) that there is a wide disparity between the truspilot ratings of well-regarded businesses that are not trustpilot customers and those who are.
The problem with basing a short thesis on these concerns is that they have been around since the days that PurpleBricks was a stockmarket darling (and big user of trustpilot), and they haven't harmed the trustpilot share price yet.
Given the name recognition, at this point it would probably have to be government regulation that could negatively impact the business model, and that a) probably isn't a priority b) could have negative impacts on consumers via regulatory over-reach.
So, while I personally would not invetst in Trustpilot at any price, given my personal concerns with the business model, I also don't see it as a great short.
Thanks Mark. I agree, it's not one to short, just avoid. No stars.
Trustpilot
About time they got their come uppance.
Pure and simple extortion and has no place in our society .
Hooefully the beginning of the end for this disgusting company
Ive been on the receiving end of the tactics and it is just a disgrace .
Thats my two penneth . As chris eubank junior would put it “scumbags”
Morning. I think the wrong ticker has been used for Beeks BKS in the summary table above. Not BKS Bank AG.
updated, thanks
Morning All,
Elixirr International (LON:ELIX) excellent interims, plus an immediate earnings enhancing acquisition!