Daily Stock Market Report (Mon 29th December 2025) - IPF, IES, EMAN, CNS

Good morning! I hope you've been enjoying the festive season. It's wonderful to see how active the forum has been over the past week.
Let's see what today's RNS has for us... these end of year reports can be quite fun, as they often turn into a policing exercise, i.e. studying companies who have tried to sneak out bad results when few are watching, or simply to avoid suspension!
I don't see anything else where I can make a sensible comment today, so I'll leave it there. If I don't speak to you again before 2026, then I hope you enjoy the New Year's Celebrations - unless you are one of those people who goes to bed early on New Year's Eve, in which case I wish you a good night's sleep!
Spreadsheet accompanying this report: link (updated to 24/11).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
International Personal Finance (LON:IPF) (£484m | SR97) | Offer at 235p plus 9p dividend (as previously suggested). The Acquisition is expected to complete during Q3 2026. | PINK (Graham holds) | |
Invinity Energy Systems (LON:IES) (£105m | SR10) | A 3.5 MWh Endurium Enterprise system will be deployed at Charles Murgat, an aquaculture business in France. Delivery of the batteries expected during H2 2026. | AMBER/RED ↑ (Graham) [no section below] I do not claim to understand battery technology but staying somewhat cautious on this seems to be prudent. We haven’t looked at IES since September 2024 (when I was RED) and results have not been pretty since then, with a £23m loss last year and a similar loss pencilled in for the current year. More positively, revenues are set to quadruple from £5m (2024) to £20m+ (2025): Longspur Research forecast turnover of £20.7m for 2025 and then £51.3m for 2026, although the company is not expected to reach breakeven until 2027. And when it comes to balance sheet safety, I note that the company is forecast to have net cash of £33m at the end of this year, thanks to a large fundraise that occurred in September. On balance, therefore, I’m inclined to give this a small upgrade, while staying cautious. It’s undoubtedly a blue-sky share but the combination of soaring revenues and a cash-rich balance sheet provides hope that it can succeed. | |
Batm Advanced Communications (LON:BVC) (£73m | SR65) | Recently appointed NED becomes Chairman. Former Chairman (for the past ten years) will step down from the Board on New Year’s Day. | ||
Panthera Resources (LON:PAT) (£59m | SR33) | H1 net loss $1.4m, “reflecting continued arbitration activities and investment in exploration activities”. Arbitration proceedings advanced, including a damages claim for $1.58 billion. Cash balance $1.9m as of Sep 2025, and has since raised $1.2m. | ||
Corero Network Security (LON:CNS) (£49m | SR12) | SP +5% A short letter to shareholders. “We enter 2026 with a stronger platform, and a strategy sharpened by the realities of the past year.” | RED = (Graham) [no section below] This stock sold off badly in July on a profit warning. The price has been firm since then, and the interim results (published in September) maintained full-year guidance at revenues of $24-25.5m (previous year: $24.6m) and EBITDA of between a $1.5m loss and breakeven. One rule that has served me well is to take a strict line on companies that are loss-making at the EBITDA level: that measure tends to be highly adjusted and very forgiving, so it's right to be sceptical of companies that can't make a profit by that measure. In the case of CNS, given that it's unprofitable at the EBITDA level and it has failed to grow much in 2025, I'm inclined to leave our RED stance unchanged. Today's letter provides a nice overview of the industry and of the evolution of CNS's product, but it doesn't change the overall picture. | |
Everyman Media (LON:EMAN) (£25m | SR37) | CEO steps down with immediate effect. He is thanked. | RED = (Graham) This isn't a share where I'd be tempted to bottom-fish. Net debt of £24m looks like a significant burden, given its generally poor performance and economic vulnerability. | |
Metals One (LON:MET1) (£21m | SR6) | MET1 owns 19% of a mining finance company (“Lions Bay Capital”) and has agreed to lend it C$4m to help it try to carry out an acquisition. |
Graham's Section
International Personal Finance (LON:IPF)
Up 6% to 233.5p (£513m) - Recommended Cash Acquisition - Graham - PINK
(At the time of publication, Graham has a long position in IPF.) (Update at 12 noon: I no longer have a position in IPF.)
Significant news here as the potential offer has finally materialised and become a real offer.
The terms are the same as previously announced: 235p plus a 9p dividend.
As noted by today’s announcement, this is a 31% premium to the share price before news of a potential offer came out.
Looking for the official rationale from IPF, we find:
The IPF Board believes that the Acquisition represents an attractive opportunity for IPF Shareholders to realise the full value of their investment set against the inherent uncertainty of realising the value that could be generated by IPF's business in the future, given current global macroeconomic uncertainty, competitive forces, an ever-changing regulatory landscape and the risks of operating in emerging markets undergoing rapid, and often unpredictable, economic and political development.
There are also “risks associated with IPF executing on its strategy and delivering value to IPF Shareholders as an independent listed company, notably when set against shareholders' wishes to see growth opportunities, conservative financial leverage and balance sheet management, a progressive dividend policy and a share buyback programme.” This reads to me like it’s a clue that satisfying the many wishes of IPF’s various shareholders was difficult?
IPF’s major shareholders are various mainstream fund managers - a category of investor that is often amenable to a takeover offer.
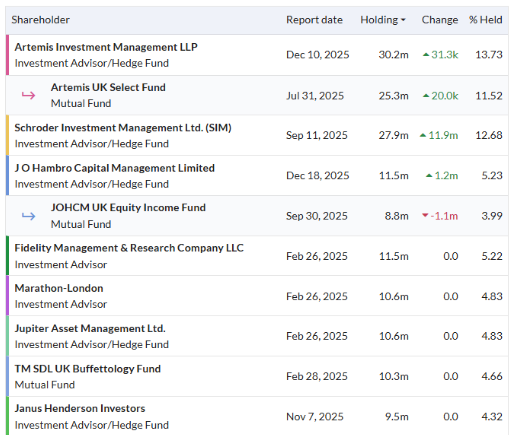
Information on the buyer: we’ve discussed before that there is little public information about the buyer. A basic profile is provided today that’s consistent with what is publicly available:
BasePoint is a leading provider in the United States of asset-based financing and liquidity to select specialty finance companies. BasePoint's borrowers primarily comprise originators of unsecured consumer receivables and originators of small business loans and providers of merchant cash advance solutions.
BasePoint Vehicles have extended over $13 billion in committed financings since 2011.
Timetable: regulatory clearance is needed, and a shareholder vote, but the acquisition is expected to complete in Q3 2026.
Irrevocable undertakings: I don’t see any pledges or promises to support the deal from anyone apart from the IPF Board, who have 1.2% of the company (including 0.9% held by the CEO). But I still very much expect the deal to go through, given the length of time that the Board has had to discuss it with their major shareholders.
Graham’s view
This morning I’ve published a separate article, the review of my 2025 watchlist. In that article, I’ve said that the watchlist is banking the theoretical gains it made from IPF last year, and picking something new for 2026.
I’m inclined to do the same with my personal portfolio - my finger is hovering over the “sell” button today. I did extremely well with my small IPF investment iun 2025, and with the share price now around 233p, I can sell out with a clear conscience.
If I do that, it will mean giving up on the 9p dividend and the full 235p payout. So I haven’t made the final decision yet, but I’m currently inclined to cash out.
This is a share that I was happy to hold for the long-term, and I wanted this takeover offer to fail. But I can accept when things don’t go exactly the way I wanted them to. And losing shares to a takeover offer is definitely a first world problem! So I won’t complain: I’ll thank the IPF management team for doing a fine job, wish them the very best, and move along.
Everyman Media (LON:EMAN)
Unch. at 27p (£25m) - Board change - Graham - RED
We’ve already looked at Everyman twice this month.
On 10th December, there was a profit warning late in the financial year (FY December 2025) which saw EBITDA guidance cut by 15%.
Making the profit morning more serious than just a 15% cut, both Canaccord Genuity (the Nomad) and Cavendish withdrew all of their forecasts, recommendations price targets for the stock, including for 2025. So the market was left to “fly blind” without broker coverage until the January trading update.
Five days later, the Finance Director fell on his sword, “to pursue another opportunity”.
Today we’ve learned that the CEO is also leaving, after nearly five full years in the role. Unlike the FD, who is staying around to help with the transition, the CEO is leaving immediately. A recently appointed NED will take the reins.
[It doesn’t matter very much, but it’s very unusual that Everyman’s website hasn’t been updated yet - neither for the CEO departure, nor for the FD departure, nor for the NED who joined back in September!]
The outgoing CEO is thanked:
We would like to thank Alex for his commitment to Everyman throughout his tenure. He has played a pivotal role in the team that successfully led the business through its recovery from COVID, more than doubling revenue and delivering significant EBITDA growth. He has also built a strong and capable operational team.
Graham’s view
We were already RED on this, and I’m not inclined to change my stance on the news that both the CEO and FD are leaving. While a sudden change in management can be the catalyst for positive change, I think it’s more likely to be followed by an admission that the existing strategy simply hasn’t worked.
For example, if you look back at the profit warning earlier this month, the “challenging economic environment” was blamed, and the company still tried to persuade the market that their 2025 performance had been ok.
While consumer sentiment is certainly a factor, I think it’s far from being the only one. What we might get from a new CEO/FD team is an acknowledgement that the current situation is unsustainable, and perhaps that they need fresh equity.
Net debt of £24m looks to me like a significant burden for a company that:
Hasn’t made a profit since pre-Covid
Has significant operating leases (lease liability >£100m)
Is capital-intensive (H1 adj. EBITDA £8.2m before depreciation and amortisation of £7.4m)
Is sensitive to both consumer sentiment and the movie release cycle, over which it has no control.
While net debt to EBITDA might only be around 1.5x, after taking into account all of the above, this isn’t a share where I’d be tempted to bottom-fish.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Ingenta (LON:ING) rose by 15.70% today, does anybody know why?. I cannot find any particular reason. I don't hold but I have been following it for a while. I was very keen at one stage but as I hold Journeo (LON:JNEO) and Beeks Financial Cloud (LON:BKS) I felt I had enough technology stocks. It might be worth taking another look especially after Mark's article yesterday.
Ingenta (LON:ING) It’s an interesting opportunity, I held at one point however noted the SP not being able to get over 100 and continue on that path. It may be people talking about the opportunity whilst on Xmas holiday and jumping in! I personally will be buying again.
Thanks for your reply Douglas
Illiquid share tipped on Stockopedia.
I read Mark's article Rusty, convinced me to take a chance so bought some today.
Northern Bear (LON:NTBR) has risen well today. Was it tipped somewhere?
I banked International Personal Finance (LON:IPF) this morning also for the aforementioned reasons (1. that the dividend is not guaranteed and 2. because the deal is still not yet 100% confirmed to go through). The total gain for me was 101%.
Thank you to Stockopedia and members here for highlighting this wonderful opportunity. I do not believe that I would have been alerted to this stock if it was not for you and the stock ranks.
On to the next ones in 2026, Merry Christmas and a Happy New Year to all!
I have had my investment with £Pay for some years now and whilst quietly content with the dividend return its repeatedly falls below my invested value. Is it cursed? I suppose its rather complicated business mix doesn't help, and there was a slight underperformance with an acquired business in the last trading statement.
Will one day the market wake up to its value or will it remain one of those companies that the market never takes to?
Many thanks to Graham for highlighting International Personal Finance (LON:IPF) many many months ago. I bailed this morning with a healthy profit which will pay my STOCKO subs for years to come. Two reasons for selling now, the 9p divi is not guaranteed and I didn't want to wait a further 6 months plus for this to go through (or fail).
I did the same with International Personal Finance (LON:IPF) this morning, it's a long time to wait for minimal additional gains, when that money can be deployed elsewhere.
I’ll probably wait till it goes ex-dividend, hopefully early April after results in Feb. On that basis, assuming it’s still a progressive dividend policy, then minimum dividend would be 8 pps (as per earlier this year), which would give me an extra 5.17% return or if the 9 pps (max allowed), then that jumps to 5.7% for the best part of 4 months. Nothing spectacular, it nice and steady and redeploy in April
Posted an article on the Canadian Gold and Silver streamers here: Why the Gold and Silver Streaming Model Is One of the Smartest Structures in the Mining Industry | By jamesalastair | Stockopedia
Will follow up with deep dives on Wheaton Precious Metals (TSE:WPM) and Triple Flag Precious Metals (TSE:TFPM)
Something to keep me occupied between the mince pies and mulled wine. We have minus 10 degrees centigrade here today in the Cairngorms and it is a good day to sit in front of the fire with a laptop.
Very useful articles.
Thank you Epitychia.
Appreciate you work. Read your Babcock International (LON:BAB) piece this morning. Working my way through your Substack over the break. https://alchemist24.substack.c...
Thanks David. I still have to do a DCF valuation for Babcock International (LON:BAB) which I will get round to finishing at some point. I am about to publish some other author's work - the first will be two articles and an interview with the CEO of copper miner Lundin Mining (TSE:LUN) carried out by Will Thomson, the founding partner of US real asset hedge fund, Massif Capital.
A friend and colleague, a retired senior RAF Officer, is going to follow up my work on the two European/UK 6th gen fighter jet programmes and what will happen if (when) Germany jilts the French and joins the Brits, Italians and Japanese. This will have implications for BAE Systems (LON:BA.) and Leonardo SpA (BIT:LDO).
What I would love is if Stocko could create a readily searchable library, organised and searchable by ticker and/or theme so we could just post our thoughts in one place, and not bother with substack.
Agree with that. It's very frustrating that Stockopedia is not fully searchable. Thanks for your thoughtful contributions.
There is an enormous wealth of knowledge hidden away on Stockopedia which is difficult to search for and identify. The notes feature they added to the charts does help a little, but the platform is not really set up for curating a library of company and market analysis resources. I am not sure Substack is either actually as for an investor it is very hard to search for an individual company or theme you are interested in. Seeking Alpha is considerably better at this, but the quality of analysis and writing is very variable. I think it is better on both Stockopedia and Substack. I think Stockopedia has a major business development opportunity but it requires the right architecture, writers/analysts, curatorship and business model.
And a wee glass of something. ;-)
Interesting article but don't look now! Commodities (exc. Oil, Gas & Cocoa) taking a beating today. At time of writing Silver down over 10%, Platinum over 15% (!), Copper & Gold down over 4%. Profit taking or is the boom in these commodities starting to fade?
This is why you need to be deeply informed: Why Today’s Silver Crash Is Paper‑Driven, Not Fundamental
.... otherwise you just react negatively to volatility and you are going to get a lot of volatility in the commodity space.
Morning Graham. I see Sulnox (OFEX:SNOX) have some results out today, watching this one. Would appreciate your view if you have time - thanks.
Sulnox (OFEX:SNOX) - Thank you very much for the request Murray, but I hesitate to comment on Sulnox for a few reasons 1) it's an Aquis share, 2) it makes energy-related technologies, where I have zero expertise. And if I had to add a third reason, it's also an early-stage company, which I try to avoid commenting on when I can! So I will leave it to others to comment on that one if they wish.
Understand Graham, thanks for the reply. Appreciate both your and all the team's efforts. All the best for 2026!
Sulnox (OFEX:SNOX)
Aquis report up 18% on day with not surprisingly tiny turnover. There are some accounts posted showing loss. I haven’t as yet tried to fathom out these financials which are opaque at first glance to me but maybe I would understand better if I had followed for longer.
I do like the product story and have a very small holding to keep me interested. Not for widows and orphans but could take off if product users are seen to be gaining commercial advantage
International Personal Finance (LON:IPF) Morning Graham. I am looking on the Stockopedia IPF description and can’t see any mention of the 9p dividend which you mentioned above. Do you have more details? In particular is there an ex dividend date that anyone is aware of? I hold.
The details are covered in an International Personal Finance (LON:IPF) November RNS in that: "under the terms of which IPF shareholders would receive cash consideration of: 235 pence per IPF share and under which eligible IPF shareholders would additionally be entitled to retain any final dividend that IPF may declare in respect of the financial year of IPF ending on 31 December 2025, up to a maximum final dividend of 9 pence per IPF share (the "Permitted Dividend"). Any such dividend is expected to be declared on 25 February 2026, alongside the Company's 2025 full-year results"
Thank you Marcus. Very helpful
re: International Personal Finance (LON:IPF) (I hold),
spmarriott, it looks like Marcus has answered your question, they have said in today's RNS and in a previous RNS that BasePoint are happy for IPF to pay a 9p dividend before the takeover completes. The dividend hasn't been declared yet, it is just part of the negotiations and the agreement at this stage. Hope that helps! Graham
Secure Trust Bank (LON:STB) I hold. Can’t spot any news either. Could it be a large trade completed?
What is happening at Secure Trust Bank (LON:STB) shares are up 10%, no news on Stockopedia.
l see there was something on 24th December.
RE: Secure Trust Bank (LON:STB) Probably something to do with this:
https://www.stockopedia.com/sh...
timarr
I suppose the sale of the Consumer Vehicle Finance Business announced on the 24th of December when the market was already closed