Daily Stock Market Report (Mon 3 Mar 2025) - Defence stocks, ZTF, SFR, RFX, AVON, KGH, HTG, QTX

Good morning and welcome back - today's Agenda is now complete.
Defence stocks
Thanks to Howard Adams in the comments for pointing out the strength of European defence stocks this morning.
A sub-index that’s available on Stockopedia is the FTSE Eurofirst 300 Aerospace & Defense Index. It has performed amazingly well in recent years and is up by nearly 7% this morning alone.

The difficult meeting between President Trump and Ukraine’s Zelenskyy on Friday was followed up with a weekend of diplomacy in London. Britain and France will shortly present a new peace plan to the United States that envisages European peacekeeping troops in the Ukraine.
When it comes to the financial implications of these developments, we have the following snippet from The Times last night:
Macron also said that European countries should raise their defence spending to between 3 and 3.5 per cent of gross domestic product. Earlier in the day, Mark Rutte, the Nato secretary-general, said “more European countries will ramp up defence spending” but did not go into specifics
The UK’s defence budget is heading for 2.5% of GDP by 2027, with an ambition for it to reach 3% in the next parliament.
On Saturday, the government announced a £2.26bn loan to bolster Ukrainian military capability. This loan will be “fully earmarked for military procurement”.
This morning we’ve seen the following movements:
BAE Systems (LON:BA.) up 15%
Qinetiq (LON:QQ.) up 9%
Chemring (LON:CHG) up 4%
Senior (LON:SNR) down 3% (but they have also published annual results)
Well done to those of you who have invested successfully in defence stocks. It’s not a sector where I claim to have any special insight, but it does seem that it will continue to enjoy strong demand for the foreseeable future.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Bunzl (LON:BNZL) (£11.0bn) | Final Results | Outlook: maintaining guidance for robust revenue growth and operating margin in line with 2024. | |
Londonmetric Property (LON:LMP) (£3.8bn) | Adds £13.2m of annual rental income | 122 lettings, regears and rent reviews. Rent reviews giving a 16% uplift on 5-year basis. | |
Senior (LON:SNR) (£678m) | 2024 Annual Results | Outlook: in line with expectations. Committed to sale of Aerostructures business. | |
Hunting (LON:HTG) (£511m) | Sale of associate company | Sale of 23% equity stake in Rival Downhole Tools for $13.1m. Non core. | GREEN [no section below] (Roland) |
Avon Technologies (LON:AVON) (£433m) | Contract win | Team Wendy Ceradyne has received a US Army helmet order (NG-IHPS) worth $17.6m. | AMBER/RED [no section below] (Roland) |
Severfield (LON:SFR) (£141m) | TU | Profit warning. Client decisions deferred. Low business confidence. Cancels buyback. | BLACK (AMBER/RED) (Roland) |
| Zotefoams (LON:ZTF) (£130m) | CFO Retirement | CFO will retire from his role “during 2025”. The search for a successor is underway. He is thanked. | GREEN (Graham) [no section below] This is not an old-age retirement. ZTF’s CFO has been with the company for 9 years and may simply desire a change. Or perhaps the company’s new CEO wants to get the perspective of a new CFO? Either way I don’t find this announcement concerning. It sounds like there will be an orderly transition. ZTF’s leverage multiple of c. 0.9x suggests little risk of financial stress. |
Knights group (LON:KGH) (£117m) | £30m acquisition | Acquisition of IBB Law LLP, a “premium” firm with 140 fee earners. Exp PBT margin c.26%. | AMBER (Roland) |
Ramsdens Holdings (LON:RFX) (£76m) | AGM TU | Has continued to trade well across its key income streams. | GREEN (Graham) [no section below] It would be best if the RNS had explicitly confirmed that trading was in line with expectations. PanLib’s last-published estimates include PBT of £12m and EPS of 27p in the current year (this gives a PER just below 9x). For now I think it’s right to presume that trading “well” means trading “in line”. I’ll leave my positive stance unchanged. In other news the long-standing Chair of the company retires from the Board today, to be succeeded by the current Senior Independent Director. |
Quartix Technologies (LON:QTX) (£76m) | Final Results | SP +10%. | AMBER/GREEN (Graham) [no section below] 2024's full-year dividend (4.5p) is much higher than the forecast at broker Cavendish and given the strong start to 2025, this year's numbers are upgraded. The revenue forecast is increased by 2% (to £36m) and the adj. EBITDA forecast is increased by 8% (to £7.3m). 2024's accounts are pleasantly free of adjustments and hopefully this will be true again in 2025. The PER is c. 16x currently. On fundamentals, I am still a little concerned about price erosion as an ongoing feature of the telematics sector. QTX has managed to implement price increases across the board but revenue from existing customers still isn't growing with NRR (net revenue retention) below 100%. So I don't know if this truly offers a growth opportunity for the long-term. On balance, I will upgrade our stance on this slightly to AMBER/GREEN. Attractive features include the positive outlook for the current year, oversight by the founder and largest shareholder Andy Walters, and clean accounts for 2024. |
HSS Hire (LON:HSS) (£43m) | FY TU | Adj EBITDA of £48.5m for 12 mo. to 30 Dec. Costs +3% YoY. No guidance for new y/e of 31 March. | |
Petrofac (LON:PFC) (£35m) | Update on restructuring timeline | Court hearing on 28 Feb, adjourned until 20/21 Mar. Sanction hearing finish mid-Apr. | |
Argo Blockchain (LON:ARB) (£23m) | Term Sheet for up to $40m Financing | Interest rate 8%. Convertible. Lender also to get warrants and 3 board seats. | |
Bigblu Broadband (LON:BBB) (£17m) | Proposed return of £6.1m to shareholders | Received £14.9m from a disposal. Proposes a tender offer at 40p (vs. latest share price: 28p). |
Roland's Section
Severfield (LON:SFR)
Down 42% to 28p (£82m) - Trading Update - Roland - BLACK (AMBER/RED)
As such, underlying profit before tax for FY26 is now expected to be below our revised expectations for FY25.
Structural steel group Severfield has issued another profit warning this morning. This is the second in four months, following November’s downgrade which Megan covered here.
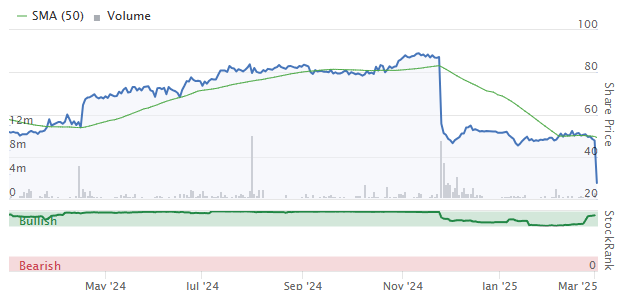
Today’s update relates to the year ending 29 March 2025 and the following (FY26) financial year. The company’s commentary suggests to me that a weak year lies ahead:
Since [our November update], market conditions have shown no signs of improvement, with pricing remaining at tighter levels for longer than expected in a competitive market and project opportunities continuing to be either cancelled or delayed.
The order book has fallen from £410m on 1 Nov 24 to £403m on 1 Feb 25.
Orders for delivery in the next 12 months have fallen from £307m to £281m over the same period.
Cost savings are underway and the share buyback programme has been cancelled but these measures will not generate enough savings to cover factory overheads in Q4, prompting today’s profit warning.
Severfield’s management now expects to report an FY25 underlying pre-tax profit of £18m to £20m.
Estimates: house broker Panmure Liberum has helpfully translated today’s update into revised earnings estimates - many thanks.
Unfortunately, the news isn’t good:
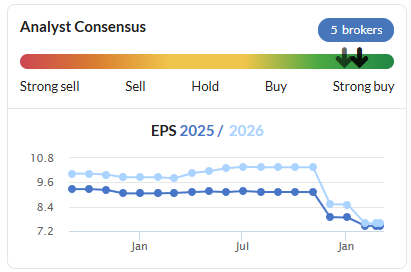
FY25E EPS down 34% to 4.5p
FY26E EPS down 64% to 2.9p
FY27E EPS down 42% to 4.9p
These changes come just three months after September’s profit warning, when Panmure cut its FY25 and FY26 forecasts by 26% and 25% respectively. Stockopedia’s consensus trend chart shows the impact of cuts from the five analysts covering Severfield:
Outlook: the company’s outlook statement reinforces my view that the business has very limited visibility on when a recovery might begin:
client decision-making continues to be deferred and projects are not being awarded or progressing within normal timescales
Management comment on the “lower level of business confidence in the UK economy as a whole” and warn that Severfield does not currently have any “large ‘anchor’ projects” in its order book.
There’s also some uncertainty about the eventual cost of the bridge remedial works programme the company is engaged in. The company took a £20m provision for this in H1, but my impression is that insurance will cover a substantial proportion of the costs being incurred.
The company says we should see some improvement from FY26 onwards:
Looking further ahead, we have already secured some attractive large projects for FY27, and we are also seeing future large opportunities in sectors such as data centres, manufacturing (industrial) and commercial offices, including the emergence of several planned large developments in London.
Roland’s view
As a relatively capital-intensive business with quite high fixed costs, one risk worth considering is that Severfield could become financially stressed.
Today’s update confirms year end net debt (exc. leases) is expected to be between £45m and £50m at the end of March, in line with expectations. The company says this provides “cash headroom of £25m - £30m”.
Panmure’s figures today suggest net debt will improve slightly over the next couple of years, although this is predicated on cuts to the dividend in FY26 and FY27, to maintain 2x earnings cover.
This level of debt isn’t without risk, but it does look manageable to me relative to revised profit forecasts for the next couple of years.
Today’s share price drop leaves the shares trading at nine times revised FY26 estimates and just five times FY27 numbers. The shares could be cheap if and when order intake improves. However, prospective investors need to offset this against the risk of further bad news, which I think is possible.
Megan went RED on Severfield in November. Today’s 40% share price drop has vindicated that caution. However, I don’t yet see any existential risks to this business and I believe some value may be emerging at current levels.
On this basis, I’m going to move tentatively to AMBER/RED today.
Knights group (LON:KGH)
Up 2.5% to 139p (£120m) - Acquisition of IBB Law LLP - Roland - AMBER
Legal services group and serial acquirer Knights has announced that it will pay up to £30m to acquire the business of IBB Law LLP:
IBB brings a team of 140 fee earners delivering premium legal services to both business and private clients, significantly increasing Knights' scale in the South East, an attractive market with a significant concentration of corporates and private wealth.
This is a fairly sizable acquisition for Knights, which has a market cap of £120m. The company says it will be funded out of existing bank facilities – i.e. using debt.
IBB has 29 equity partners who will receive £30m, with an initial cash payment of £21m and deferred cash consideration of £9m paid over three years. So the partners will receive an average of c.£1m each.
The economics of the deal seem interesting and highlight the potential appeal of Knight’s roll-up business model:
In FY24 IBB reported £23m and a “corporatised PBT margin of 6%”
Knight’s management expects to transform this to a PBT margin of c.26%, “following full integration and realisation of synergies”
This implies a possible pro forma purchase multiple of 5x PBT, which doesn’t seem expensive.
Roland’s view
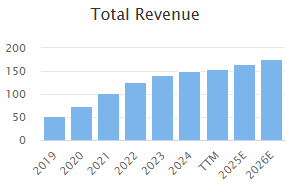
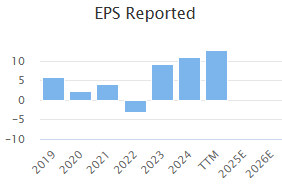
Knights seems to be executing well and is continuing to generate both top line and bottom line growth:
However, I am not all that enthusiastic about professional service partnerships being rolled up into corporate vehicles. This is partly for philosophical reasons and partly because of the risk that key fee earners may take their client relationships elsewhere.
A comment in today’s RNS highlights this risk (my bold):
Prudently assuming 20% revenue churn post-acquisition and excluding the non-core Crime business
Knights reported net debt (exc. leases) of £50m at the end of October 24. Assuming this figure has remained stable, then today’s deal suggests net debt will be £71m after the initial payment for IBB.
The company recently extended its credit facility from £70m to £100m and I estimate that net debt/EBITDA leverage should remain under 2x following this deal.
But on more conservative measures of leverage, relative to net profit or free cash flow, Knights looks more highly geared to me. I don’t see any pressing concerns at the moment, but this is an area I’d watch.
Similarly, I think it’s worth remembering the large divide between the company’s reported and adjusted profits. In January’s half-year results a pre-tax profit of £9.0m was transformed into an underlying PBT of £14.6m.
Even the cash flow statement includes “non-underlying operating costs”.
These adjusting items are generally related to acquisitions and seem perfectly legitimate to me. But they tend to recur in Knights’ accounts and I would tend to view them as routine operating costs.
For this reason, I prefer to value Knights shares on reported earnings, rather than adjusted earnings. On this basis, my sums suggest Knights trades on a trailing 12-month P/E of 10.
Roland’s view
CEO David Beech has a 22% shareholding, suggesting his interests remain well aligned with those of shareholders.
Knights shares look reasonably valued to me at the moment and I can see the potential for further gains.
However, as I’ve commented above, I don’t think the shares are as cheap as adjusted broker earnings forecasts might seem to suggest and I can see some risks in this business model.
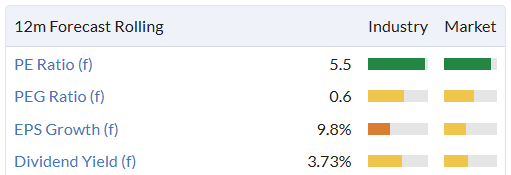
Another concern is that I’d like to see more evidence of organic growth. Knights’ H1 results showed organic revenue flat, with top line growth driven by acquisitions alone.
It’s possible that I’m being a little too cautious. But with no update on trading or full-year guidance today, I’m going to maintain my neutral view from November. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

84 comments
A bit of an aside this was either a hedge or the finest example of insider trading ever
https://www.forbes.com/sites/s...
Good report. Is there an easy way to browse these sector indexes such as the aforementioned FTSE Eurofirst 300 Aerospace & Defense Index ? Appreciate we can type 'FTSE Eurofirst 350' into search, get a list and select each individually but a page listing them all or similar would be most handy
Jennie Daly - CEO of Taylor Wimpey (LON:TW.) with a cheeky £50k buy. Always nice to see
But she had sold £400k worth on 27th Feb - which looks to me like a LTIP maturing as another director also had a very large sale on the same day.
I would therefore think that her LTIP matured, she sold the lot to pay the tax etc and has then used some of the money to buy shares in the market.
Perhaps not a bad sign.
Not sure if this is a dumb question...
How do you invest in this ETF?
FTSE Eurofirst 300 Aerospace & Defense Index
That is an index not an ETF. Unless there is a tracker, l don't think you can invest in it.
As Rusty2 says this is an index. There are a few indices in the sector but no ETF providers appears to offer a fund that tracks any of the European Defence indices. Probably launch one now after the big surge in European Defence Stocks!
There’s the HanETF “Future of Defence” fund (ticker “NATO”) which invests in a similar space. I imagine it includes US as well as European stocks, and it also includes a bunch of cybersecurity stocks (hence the “future of” title). I imagine it’s done rather well over the last couple of weeks!
Future of Defence UCITS ETF USD Acc (LON:NATO) seems ok. VanEck Defense UCITS ETF USD A (LON:DFNS) option plus Blackrocks iShares iShares Global Aerospace & Defence UCITS ETF USD A (EPA:DFND)
They all hold the same stuff - Blackrock, VanEck, Global X, it depends on who are the best. Blackrock/iShares would have thought with 4bn analysts they would cane it but they do not.
The focus away from US to Europe defence contractors is very healthy. Despite the dysfunctional political and financial system it carries some seriously big hitting industries. Shame energy got in the way and sourcing parts for China (and now apparently India lol) - despite share price rises these co's need to deliver on expensive kit - a difficult task.
Remember Avon Technologies (LON:AVON) could not deliver their helmet orders. And so their production facilities have doubled since - if so the whoopee. Back up the truck.
Global X Defence Tech UCITS ETF USD Acc (LON:ARMR) holds Rheinmetall, Palantir, RTX, BAE, Nortrop, General Dynamics, LM, L3H, Thales and Leidos so good smatteing of US and European.
DYOR - trouble is buying them and today all trades closed across the board. How fickle are retail investors - this was coming way back but today 'boom' - dumb.
Hi, to find etf’s if you go on justetf and use the etf screener, you can usually find if an etf exists for a sector/country/theme
I was using justetf.com yesterday to look at ETFs with low US exposure. I found it easily the best source of information I have encountered on ETFs to date. It may be of use if you are still searching for exposure to defence stocks, I don't know.
Plus no stamp duty on them so thats another 0.5% you don't need to make back to get to break even.
Burford Capital (LON:BUR) Annual results have not gone down well, although the share price has recovered somewhat. There were released at 12 noon because they are a US listing.
Hunting plc (LON:HTG) thanks to Roland for his thoughts ahead of their FY results out this Thursday 6th - for anyone wanting to hear from the management then, there is a webinar 10.30am and all are welcome. Registration here: https://us06web.zoom.us/webina...
Nice £220k bod buy for CML Microsystems (LON:CML) announced 90 mins ago
Lots of excitement about defence shares today, but how can you filter out controversial weapons manufacturers with the screener? That is:Taking an ethical approach rather than a large profit!
I am not sure that it is an ethical approach to allow Putin to invade any country that he chooses.
You can't, you will have to do some deeper research.
Surely that's subjective? You'd need to do your own research and then decide for yourself if you deem it controversial and want to exclude it.
Look for companies that just do defense and not offense.
I'd guess it's the controversial weapons manufacturers that are gonna do well now.
The way things are now there's little point spending on weapons that don't provide that big stick. Be it to threaten with or actually wave it.
Not necessarily, the Thales order is for air defence missiles.
UK defence composite ath's
Retail money flowing into ETF's. Fair enough. But the companies the support need to produce the goods. You cant just throw money at a company BAE Systems (LON:BA.) and it increases production overnight - this takes time. See some cos now looking to India or supply chains.
Putin did not expect the push back he got, or maybe was pushed into a corner - Russian Bear - look it up - Napoleon failed, Hitler failed - Vladamir with his European Army similarly so.
At end of days who holds the nukes - US Russia China - everything else is 'noise'.
Forget global/macro - lets try to make money out of Stocko using their metrics.
"Greed is Good"
What - you want to pay more tax than already because you trust the Clown to use it wisely - I have a nice car I want to sell you.
The usual Burford Capital (LON:BUR) reaction to their results this afternoon as no one can really understand whats going on with the company. I should have a strategy of buying after the results and then selling before the next quarter comes out.
Still holding and believe there will be a re-rating here eventually when the Argentinian government look to do a settlement which could be still a year or two off . Who knows all the fun of Burford I guess
#KGH IBB Law LLP a premium law firm ? Hmmm .
I no longer invest in construction Companies and haven’t since Carillion went bust, because too often profit margins are thin, and so any problems and hold ups during a construction project can hit profits hard, and turn the whole project in to a big loss maker.
e.g big problems building the Aberdeen by pass finished off Carillion.
According to this FT update today Severfield (LON:SFR) profit margin is just 0.6%.
https://markets.ft.com/data/eq...
I share your concerns but the figs show revenue of £463m and now, a reduced profit of £18-20m. About as out of line as the current Stocko ratings! Repeat the mantra, for my own benefit - DYOR !
Billington Holdings (LON:BILN) is down today, presumably because of Severfield (LON:SFR) . Does anyone here have reason to think BILN is immune to the headwinds SFR identified?
Unless Billington Holdings (LON:BILN) are eating Severfield (LON:SFR) pie?
I do hold Billington Holdings (LON:BILN) so l do have some concerns.
But this was from their last update in December, 24:
Severfield (LON:SFR) seems to be more UK whilst Billington Holdings (LON:BILN) has more European exposure.
Looking at Chris's point about Severfield with a stock rank of 92, I have 9 stocks currently ranking over 90, of which 6 including Severfield are in the red since purchase. Losses range from 6 to 60%. Am I missing something? Maybe I'd be better in the garden.
Hi John without hopefully sounding condescending read Ed Shings article on a model ETF portfolio last week its the direction I'm heading. I work in the industry yet can't average more than the better funds/trusts per annum so have decided my time 15-20 hours per week in research is better spent elsewhere. I do love the game however so will keep 5% of monies back for sensible UK mid cap gambles but won't spend hours on research.
If you decide to stick with it my brief summary on what not to buy is as per below
Avoid sub 200 mil market cap, Avoid all aim and loss makers, avoid anything with big debt, avoid operating margin below 10%, avoid anything with a spread of more than 2% and as Ken said if a profit warning get out, avoid anything in long term downtrend.
Or read Ed's article on a portfolio that can be reviewed in 30 mins per week, quarterly/half yearly rebalancing, just make sure you learn about how bonds work and understand duration risks and when credit spreads are in (and not in as currently) your favour.
Anything else holla.
Regards
Andy
Hi John and The Phoenix, Great comments thanks. I am beginning to think I am unlucky using Stockopedia with some new investments since 2019. I am now well underwater with larger new holdings bought and still held with WYN & SFR and flat with VSVS. Rankings and charts were positive at the time. The one very bright spot is MGNS. The program has been great in helping me assess my existing holdings owned pre-2019 but many of these have been in existence for years - FTSE 100. In the early years, I did buy and sell a few times with success EZJ, WG & GOG so I am seriously wondering if Stockopedia is better suited to that short-term investing/trading style rather than long-term buy and hold investing. I'd welcome comments.
I am seriously wondering if Stockopedia is better suited to that short-term investing/trading style rather than long-term buy and hold investing
I can't add anything substantive to that point, but I note that the highest Stockranked companies tend to have decent momentum, which itself tends to be mean reverting over a two to three year period. So I'd be surprised if selecting a portfolio of highly ranked companies would be a good long-term buy and hold strategy.
On the other hand, as NAPS has shown, it is a good guide to annual rebalancing.
So perhaps it's neither a LTBH nor a short term trading strategy, but something in between?
timarr
well said what the stock ranks do is sort the dross out from the more quality companies - but they most certainly dont see into the future. hopefully though higher ranked companies are less likely to be dross . For each company though one needs to dyor before investing and take their own responsibility. its pretty clear though that the naps type approach seems to work well so that is itself pretty decent indicator that the indicators and genrally helping albeit for individual companies they may fail.
£card was mentioned today and i personally thought that 140p was perhaps a too high a price to pay - but price has come down now. Ok the stocky rating has dropped but thats more due to the really poor shareprice performance rather than much wrong about financials - albeit 2026 forecasts have been trimmed somewhat.
So its clear that one can take good quality companies and wait it out for pull back before investing sometimes - so again its clear that the stockrank should never be the be all and end of of making decisions ref whether to buy or sell at that time.
Im think there have been quite a few people over time commenting on here that by swapping to higher ranked companies that has paid dividends over the long term.
as ever there isnt any magical fix here
Depends what you mean by short term. I don't think it really suits trading under a month. It was set up more for longer term investing. NAPs runs for 1 year. You can check a few stocks that have performed well for a number of years and their Stockranks. Let's take Rolls-Royce Holdings (LON:RR.) If you had bought when the Stockrank went up to 88 the share price was 145p, in Feb 2023, share price now 776p.
Yu (LON:YU.) did even better going up about 9x in 2 years.
Marks and Spencer (LON:MKS) up about 2.5x in 2 years.
Serabi Gold (LON:SRB) Up 4x in around 17 months.
International Consolidated Airlines SA (LON:IAG) 2x in 18 months.
3i (LON:III) 2x over 2 years.
I'm sure there are loads more.
Agreed. MGNS up 126% and MKS, that I have held for many years, though bought more now up 145% - I am very grateful. It's my smaller caps that are under performing badly.
It has been a though market for small caps, a few are still doing ok, such as Synectics (LON:SNX) and Filtronic (LON:FTC). I think smaller caps are shorter term.
I wish I knew what I did with it but Ed Shing did a brilliant book which I wish that I read when I first started investing, or is that just as simple as putting money in my company pension? The Idle Investor, it had similar high level strategy, which aligned to NAPS so had a momentum factor in, and three levels of how much time a month you could put in for which way to go
Good Luck Tommy
BNZL Shares down 6.4%, so market obviously not quite liking what it sees. Revenue up 3.1% in constant excahnge, operating profit up 1.3%, PBT -3.6%. So maybe the market thinks Fwd PE of 16.5 is too price. On the plus side , "Despite significant uncertainties relating to the
wider economic and geopolitical landscape, the Group expects robust revenue growth in 2025, at constant exchange rates, driven by announced acquisitions and slight underlying revenue growth". I hold
BA Up 14. Zelensky and Trump were due to sign a deal that would have likely settled the Russian invasion, but harsh words at the last minute scuppered the deal. Starmer pledged support for Zelensky. It looks like the rest of Europe will be stepping up a gear militarily as well. The shares have drifted sideways for a year and I was beginning to wonder if I should take profits. The fwd PE is 18 and the shares have gone parabolic. A sensible person would probably be thinking of taking a little off the table. I hold though, with no immediate intention to sell.
Severfield (LON:SFR) is yet another example two things I bore most with here, but repetition if the points made are valid helps to get the message across.
1. Sell on the first hints of bad news and almost always on a profits warning.(The only exception I use is the rare occasions a profits warning is because of temporary issues that Management reassure have now ended). This tactic usually works and means escape from further big share price falls ahead. Often there is more than one profits warning.
So Severfield (LON:SFR) should have been sold around 50p last November on that first profits warning.Sure enough, as so often happens, there's another one today and the share price is down 40% and down nearly 50% from the price at the time of the first profits warning.
Note that Megan gave Severfield (LON:SFR) a red rating on the day of their Results last November.
2. BUYBACKS.
So many, including commentators here, love them. I don’t. With a few exceptions there are far better ways of spending the money wasted on buybacks. Severfield (LON:SFR) had a £10 million buyback programme. Many of those buys were ahead of that first profits warning and mostly around 80p compared with just 27p now. What a waste of money!
(As an aside, Pershing Square Holdings (LON:PSH) is a very successful Investment Trust with a superb 5 year performance record, but the discount was wide. So they wasted $1 billion buying back their shares to reduce the discount. It didn’t work and the discount remains wide, and they admit it was a waste of money. Such a successful Trust could instead have invested that money in new investments or top ups to existing ones. Far better than throwing (as Severfield (LON:SFR) has also done) money down the drain.
Finally, unfortunately Severfield (LON:SFR) is a case where the stock ranks are misleading. Both quality and value and overall score are in the 90s despite that profits warning a few months ago. Raw figures presumably can’t take profits warnings or risky regions where shares like Gulf Keystone Petroleum (LON:GKP) and Ferrexpo (LON:FXPO) operate, in to account?
Well said, Ken. I am suffering from the warning in last Friday's results from Morgan Advanced Materials (LON:MGAM) . Forecasts for 2025 lowered and a cut back in the scale of expansion in their semi-conductors business, but on they go with a second tranche of buy backs after wasting money at higher levels on buybacks throughout 2024. Debt is currently at 1.4x EBITDA.
Thanks, Ken, Indeed stock ranks were very misleading. I could have sold SFR at 60%+ up in the 80's yet now have a sizeable 52% loss. Rankings weren't screaming sell. Maybe I missed something from the charts? I wonder if someone will buy up once trading improves assuming cash / od facilities are adequate in the meantime?
Knights group (LON:KGH) - acquisition is £30m not £39m as noted in the above summary. £21m initially and a further £9m on deferred terms over 3 years on anniversaries in equal instalments
We fixed that, thank you Mark.
how can a stock like Severfield crash 44% on a trading update!?
'means that the Group now expects underlying profit before tax for the full year to be in the range of £18m - £20m.'
they are still going to make a profit!!
2 profit warnings since September and a red rating on here. Can’t say you weren’t warned
A StockRank of 92 for Severfield (LON:SFR) only reinforces the need not to drive by simply looking in the rear-view mirror.
Re :Severfield
From April 24 until the profit warning of Nov 24 the stock rank was in the region of 97/99 and whilst the stock rose from 56 to 88 during the same period - it did not give any indiccation that the trading conditions were declining and the stock was about to tank.
A similar situation with momentum,with the stock report of November 22nd just prior to the crash, showing a momentum rank of 95. Again ,no hint of weakness.
Much has been said about stockranks only working on a basket of stocks, however, it would be very useful in my view to analyse those individual stocks where the stockrank was clearly a poor predictor of future outcome.
Perhaps Stockopedia could use Severfield as a case study to improve the rankings analysis.
Dont hold.
IG Design (LON:IGR) is another, quite similar to Severfield (LON:SFR) then wallop, profit warning, There have quite a few high ranked shares taken a tumble recently. Card Factory (LON:CARD) was ranked 100 at 141p, that was the peak then it fell to around 80p. Shoe Zone (LON:SHOE) ranked 98, shares were 278 then fell to 90p, the Stockranks still remained high until a few weeks ago..
Not sure how Stockopedia can predict these.
Agreed Rusty2
One company didnt have much of a moat (IMHO) and the other was operating in a weak construction market. You didnt need stockranks to avoid these companies.
I still think it would be useful to do some analysis on the stockranks system where it clearly has not worked.
EDIT: just cught your additional comments in your post. Enough subscibers here ( including myself) were posting concerns about Shoezone.
But so is Morgan Sindall (LON:MGNS) in construction and their shares have done very well until last month, they have very low margins as well, one reason why l don't hold them.
Old Robbie Burns does know how to spot the gems in risky areas Rusty for sure.
Yes, l set up his folio just over a year ago, it has outperformed all the other UK folios, l have, up over 45%. Most others have fallen back in the last 6 months but not his. He has quite a bit in defence. Biggest winners are Filtronic (LON:FTC) and Good Energy (LON:GOOD).
I'm convinced he has that Delorian out of back to the future he has an incredible hit rate and his money management on losers is top table also.
Another NT fan! He loves Cohort as well, which has been a nice winner
Any carryover to Billington Holdings (LON:BILN) (down a smidgen today, and now below the 50 SMA) and other similar of which I am unaware?
Mr. Market
Hi
For those interested watch European defence stocks today Rheinmetall AG (ETR:RHM) Leonardo SpA (BIT:LDO) Saab AB (STO:SAAB B) Thales SA (EPA:HO) Hensoldt AG (ETR:HAG) for example, and others.
(I hold small positions in all)
Regards
Howard
I've just set up a SIPP for retirement income for my spouse. She's X RAF and wanted arms manufacturers in her portfolio. Amusingly the three pics - BAE Systems (LON:BA.) Chemring (LON:CHG) Qinetiq (LON:QQ.) have been then three top performers! The last two were really cheap to buy and the fundies don't look bad at all. I couldn't understand it. Even BAE looks reasonable value but I gather suffers from capacity constraints.
Pleased with the bounce in defence stocks. Unsurprisingly one UK defence co. has barely joined the party today - MS International (LON:MSI) . A buying opportunity for those that don't already own this little gem. (I hold).
Future of Defence UCITS ETF USD Acc (LON:NATP) is a defence focused etf, for those that want to use that route.
Have looked at various defence ETFs but all have too much US exposure vis-a-vis Europe. Surprised that none of the ETF providers have launched a product which tracks one of the two indices that appear to be in the European defence space. Probably legacy of ESG concerns which surely after Putin & Trump love in need to be ditched. A recent article on Morningstar argued that Rheinmetall AG (FRA:RHM) , Saab Ab (STO:SAAB BTA B) and Leonardo SpA (BIT:LDO) were the best bets. Clearly investors taking notice - all up c. 12% this morning. Well done to Howard Adams for getting in early! I hold BAE Systems (LON:BA.) and Qinetiq (LON:QQ.) so not missing out entirely but probably too late for the European players. Momentum is all very well but some are up 6x in the space of 3 years - personally would be very uncomfortable joining the party now but could be wrong again!!
A lot of the UK money is going to Thales SA (EPA:HO), which is French, but based in Belfast. Shares currently up 13%.
I do think that you are excessively cautious on the European defence stocks. The result of Trump and Vance's appalling bullying of Zelensky can only be an increase in European defence spending. This was justified well before the weekend, but surely the governments will now be goaded into action.
think that was Trump's plan - get Europe to spend more on defence!
Hi ACounsell & Graham
Thank you for the hat tip :)
Regards
Howard
Agree (and I am fully invested)!
I was looking at my Investment Trust holdings and very few hold any defence shares
The largest holding in the ETF is Palantir on a PE of 135 x
The current US administration (if one can call it that) intend reducing defence spending by 8% a year for each of the next 5 years. Palantir and other US stocks responded accordingly. The best bet in my view are European defence stocks. I hold MS International (LON:MSI) Cohort (LON:CHRT) Kongsberg Gruppen ASA (STO:KOGo) Rolls-Royce Holdings (LON:RR.) Saab AB (STO:SAAB B) (through my holding in Investor AB (STO:INVE B) and Rheinmetall AG (ETR:RHM) .
The best innovative defence stocks are private equity held eg German company AI Drone company, Helsing: Helsing | Artificial intelligence to protect our democracies
I bear in mind that these companies are at the very top of their valuation range and if European increases in defence funding fail to materialise, then we can all expect to take a cold bath. In general I do not like investing in defence because:
a) Too much political influence;
b) Big lumpy contracts, the timing of which can be difficult to determine;
c) Capital intensive
d) Some companies have historically poor ROCE - Leonardo SpA (BIT:LDO) for example is less than7% although MS International (LON:MSI) is much better at 25%. I cannot see how Leonardo is covering its WACC;
e] Opaque contracts with limited visibility.
Having said that, I invested when we took in Ukrainian refugees and defence stocks, along with Argentinian stocks and gold bullion have proved the best performing investments over the past 2 years. I do wonder if the future anticipated cashflows are now baked into these high valuations. I remain invested (for now).
Wow BAE Systems (LON:BA.) were up 17%, MS International (LON:MSI) now up 9%.
Now up 6%
Hi
Additional European (well German really) defence stocks rising a lot today ThyssenKrupp AG (ETR:TKA) and RENK AG (ETR:R3NK) .
I don't hold
Regards
Howard
Defence ETFs are weighted towards the USA (around 60% exposure) and last week weakened on the back of supposedly 8% US defence cuts. However they have been strong over the last year, partly on the back of the rise in Palantir, an AI driven tech stock. Palantir is now the largest world defence stock which I wouldnot have come across if i had not invested in NATP.
Hi Stevenlondon3
Palantir Technologies (NSQ:PLTR) has been a major catalyst in influencing the US Department of Defence (DOD) to tilt towards software and AI. To the extent that the US are now designing systems from the bottom up with software and AI as the core design principle, the physical structures secondary.
If it interests you there is a lot going on in the defence sector with regard to AI, autonomous, drone and robotics space in the US. And to some degree across Europe. The thesis being that modern ware fare will be AI driven, drone swarms, cyber, autonomous entities, and so on.
Regards
Howard
(Disclosure, I hold Palantir Technologies (NSQ:PLTR) )
Interesting that you bring up European shares Howard I started to look at European shares a few years ago and have done quite well with the shares that I have invested in It would be great if Stockopedia gave them more space
Hi Benson
Yes I agree with you, there are some really interesting companies to research, plus each country's market has its own 'vibe'.
As I am less familiar with the markets than I am with UK or US, I apply quite a tight scope to my research by looking at a sub-sector search. Such as Luxury stocks, defence stocks, semi conductor stocks and so on. This has helped me identify stocks I would not normally have encountered.
A big help to this preliminary research is using AI (GROK 3, ChatGPT, Google Gemini or Anthropic's Claude). Plus it gets me a great deal of detailed research without facing website or language barriers.
Regards
Howard
Ramsdens Holdings (LON:RFX)
AGM Business update infers to me trading is at least in line. Close of year trading update to follow next month.
Still good to know that the company is trading well. I am more inclined to think that it will ultimately be trading ahead come the April update, given the gold price. Speculation of course. We shall see. The shares are cheap like many good quality UK small caps
"The Group has continued to trade well across its key income streams during the first five months of the financial year from 1 October 2024 to 28 February 2025, with the purchase of precious metals segment continuing to benefit from the strong gold price.
The Group intends to announce a Trading Update for the six months ended 31 March 2025 in April 2025."
Thanks for the comment jonno! For me, trading "well", with no other info given, means trading in line.
H&T have been a bit stronger of late.
I hold both H & T (LON:HAT) and Ramsdens Holdings (LON:RFX) and hope the trading updates reaffirm that both are trading well and the share price of this unloved sector needs to be reassessed. Never see them trading much higher than 10x Earnings but the current prices are factoring in them collapsing.
Would welcome thoughts on the Knights group (LON:KGH) if you have time?
Hi Neil, I think we'll get around to do doing something on KGH. Cheers!