Daily Stock Market Report (Mon 6 Jan 2025) - GMS, TRU, HERC, S247

Good morning!
It looks like we are going to have one last day without too much news, before things get back to normal tomorrow.
12:30: all done, see you tomorrow for some more interesting announcements!
Spreadsheet accompanying this report (updated to 3/1/2025).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Gulf Marine Services (LON:GMS) (£164m) | Debt refinancing | Debt refinancing completed, reducing cost of debt & allowing higher dividends. | GREEN (Roland) |
Trufin (LON:TRU) (£92m) | TU | FY24 adj PBT expected to be “significantly ahead of market expectations” leading to maiden FY profit of >£0.5m. | AMBER (Roland) |
Hercules Site Services (LON:HERC) (£33m) | Strategic Update | Plans to sell “Suction Excavator” business, including its debt, which will raise HERC’s PBT & EPS. | AMBER (Graham) |
Smarttech247 (LON:S247) (£10m) | FY update | Results for y/e 31 Jul 24 expected later in Jan. Revenue exps “in excess” €13m, +8%. Adj op profit exps over €750k. | AMBER/RED (Graham) |
Summaries
Trufin (LON:TRU) - up 4% to 91p (£96m) - FY trading update - Roland - AMBER
2024 profits are expected to be “significantly ahead of expectations” after a very strong performance from the group’s games business in December. Trufin now expects to report its maiden annual profit one year earlier than planned. I can see attractions in the group’s payment businesses, too. But with management warning that 2025 could be a year of consolidation, I think the share price may be up with events for now.
Hercules Site Services (LON:HERC) - up 2% to 42.9p (£33m) - Strategic Update - Graham - AMBER
I’m upgrading this construction recruitment firm to AMBER as I always appreciate a sensible divestment, and HERC’s proposed disposal of its vehicle rental business sounds reasonable to me. Hopefully we will start to see material profits here before too long, perhaps with the help of some small acquisitions. Existing broker forecasts are for adj. PBT of £1.3m in the current financial year (FY Sep 2025), rising to £1.5m the following year.
Short Sections
Gulf Marine Services (LON:GMS)
15.4p (£164m) (pre-market) - Debt refinancing completed - Roland - GREEN
This offshore support vessel operator completed its debt refinancing on 30 December, as first announced in August. It should be good news for shareholders as debt costs will fall, freeing up cash for debt reduction and – potentially – dividends or share buybacks. According to broker Zeus (many thanks), this will be possible when net debt/EBITDA falls below 1.5x.
Checking back to the August RNS, the new debt package includes a $250m, five-year loan and a $50m working capital facility. GMS will need to repay 16% of the loan each year, with a 20% final payment at the end of the term.
I estimate the new package could result in a c.0.6% reduction in the interest rate being paid by GMS today, with a further reduction when leverage drops below 2x EBITDA. That could save c.$1.3m per year in debt costs, based on the last reported net debt of $234m. That's a useful saving for a company expected to report a net profit of c.$48m in 2025
I’m happy to stay GREEN on GMS ahead of the company’s full-year results, given recent strong trading and the stock’s substantial discount to book value.
Smarttech247 (LON:S247)
Up 16% to 9.8p (£12m) - FY trading update - Graham - AMBER/RED
Smarttech247 (AIM: S247), a multi-award-winning provider of AI-enhanced cybersecurity services providing automated managed detection and response for a portfolio of international clients, announces an update regarding the Company's results for the year ended 31 July 2024 ("FY2024").
This one listed in Dec 2022 and was mentioned by Paul twice - April 29th and April 30th.
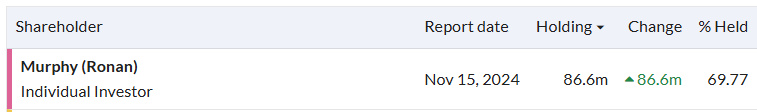
With such a small market cap and with most of that held by the Chairman, the free float is only worth a few million pounds.
The company still hasn’t published its results to July 2024 and says that it will do so “in the second half of January 2025”.
It’s a paradox that I see so often: small companies take an age to get their audits done and their results out, while large international companies have little difficulty getting results out promptly. Shouldn't it be the other way around?
Management at S247 seem happy with progress in FY July 2024, reporting a 50% increase in ARR (now 60% of total revenues), revenues up 8% to €13m, and an adj. operating profit of over €750k.
I don’t have a strong view on this business but with a free float so low I reckon that AMBER/RED is appropriate, purely as a warning to everyone re: illiquidity. Getting involved with companies at this size and with such a small free float brings a different set of risks compared to mid-caps and big-caps, with the main risk being that at some point the company decides it's no longer worth being listed. Hopefully that doesn't happen here, but I just think it's crucial to be aware of this factor.
On the subject of illiquidity and delisting risk, I note in passing that the owner of a quirky bookshop Scholium (LON:SCHO) has left AIM today. This stock spent years trading at a deep discount to its tangible book value. I looked at it several times, but thankfully never bought it. Delisting risk is not something I put up with these days - I've decided that life's too short to hold "deep value" stocks that are too small to have a stock market listing!
Graham's Section
Hercules Site Services (LON:HERC)
Up 2% to 42.9p (£33m) - Strategic Update - Graham - AMBER
An interesting little announcement from HERC as it now intends to sell its “Suction Excavator” business, as it considers it to be “non-core”.
Offloading debt
Suction Excavator Services is said to be responsible for only 5% of HERC’s overall revenues, but 88% of its debt.
It’s is a vehicle rental business, so it’s natural enough that it would use some debt.
It would have been helpful to get an indication of what the debt number is, but I can try guessing at a ballpark figure using the interim results, when HERC’s gross borrowings were £6m. So I would guess that the Suction Excavator business probably has debts in the region of £6m - hopefully this can be confirmed soon..
As we discussed back in October, HERC raised £8m of fresh equity recently, in order to strengthen its balance sheet and give it the firepower for acquisitions. So its balance sheet should already be quite strong, even before going ahead with this disposal.
Concentrating, not diversifying
The proposed sale will allow greater resources to be dedicated to HERC’s core labour supply activities, and will “reinforce the Group’s market positioning” in this area.
In other words, HERC will be more easily recognised by customers as a construction recruitment business, not as a group offering a mix of construction-related services.
As an aside, I’d like to note that when companies do the opposite of HERC and diversify their operations, they rarely acknowledge that it will dilute their market positioning - even though that’s probably true in a lot of cases!
Financially, the planned disposal by HERC “is expected to contribute to higher profit before tax, improved earnings per share, and enhanced returns for shareholders in the near future”.
I’m wondering how that can be true, unless Suction Excavator Services is currently loss-making?
Checking the 2023 Annual Report, I see that Suction Excavators generated an operating profit of £600k for the year (2022: £1.0m).
And things seemed to be going ok for this segment in 2024, when the interim report was published. There was only a small hint that profits might be under pressure:
Demand is strong but the key is focusing on profitable work, and so a number of changes relating to the way we select jobs have been made to ensure we are as efficient as possible.
I wonder if trading has been tougher in recent months. Perhaps the operating profit from Suction Excavator Services is not enough to cover its interest bill.
As this business is now up for sale, it will be reported separately by HERC in the “discontinued operations” section of its 2024 results.
Graham’s view
Divestments can be a great source of investment ideas. In general, I like proposals that reinforce a company’s strengths, improve its balance sheet, and help management to focus on where they can have the greatest success.
However, I must add a few caveats here.
Firstly, there is no guarantee that any disposal will be achieved. Full-year results will be reported on the basis that HERC intends to make this disposal happen, but we can’t know for sure that it will.
And on a related point, what might the Suction Excavator business be worth? The sale price might not be very impressive given that it's a leveraged business model and that current trading might not be very strong (otherwise, how would the disposal result in higher profits for HERC?).
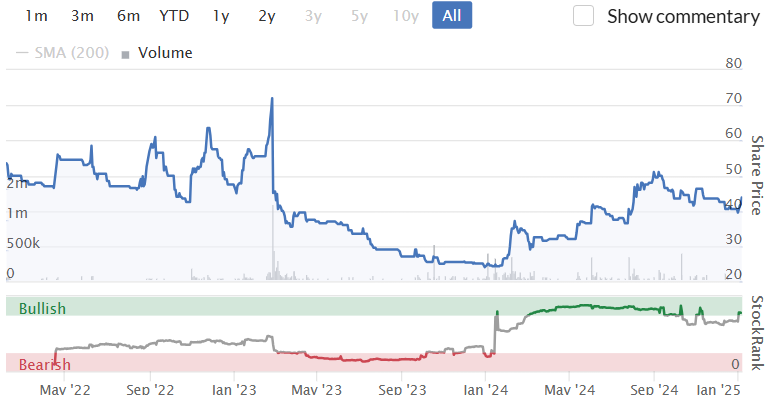
In October, I was AMBER/RED on HERC. I’m inclined to raise this to AMBER now on the basis that the balance sheet should be strong already (given £8m raised previously), and could get even stronger if the proposed disposal goes ahead. With management armed to make relevant acquisitions, hopefully they can start to generate some value for shareholders.
Roland's Section
Trufin (LON:TRU)
Up 4% to 91p (£96m) - FY trading update - Roland - AMBER
Checking back in the archives, Graham last covered this technology and finance group just one month ago, when Trufin said 2024 results would be significantly ahead of expectations.
Today, we have another upgrade:
TruFin is pleased to announce that it expects its adjusted profit before tax ("PBT") to be significantly ahead of market expectations resulting in its first full year profit - a year earlier than forecast.
The company now expects to report revenue of approximately £54m – a 197% increase on FY23. This is expected to translate into an adjusted pre-tax profit of “more than £0.5m”, versus a loss of £6.6m in FY23.
As a result, Trufin expects to report its first ever (adjusted) full-year profit one year earlier than previously expected.
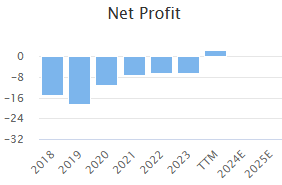
For context, Trufin’s guidance on 6 December 2024 was for full-year revenue of £46m and a pre-tax loss of £1.5m. So performance during the final month of the year must have been pretty outstanding – a good example of the way a big hit can transform results for games producers.
Today’s upgrade is said to have been driven by “exceptional year-end performances” from games Balatro and Abiotic Factor, both published by the company’s Playstack subsidiary.
Balatro is said to have won several industry awards in December, which helped to “significantly boost sales of the game” during the month.
Playstack is one of Trufin’s three operating subsidiaries. The other two can be classed as financial/payments businesses. Today’s update also includes an update on the 2024 performance of each of these.
Oxygen Finance Group: this business provides an early payments service that lets organisations pay their suppliers more quickly. It’s focused on the public sector.
Revenues rose by 21% to “no less than £7.5m” during 2024. EBITDA rose by 65% to no less than £2.1m (FY23: £1.3m).
Oxygen signed up four new early payment clients (EP) in 2024 and all four renewals due signed up for further five year terms. The business ended the year with a record 62 EP clients and says 82% of the next five years’ EP revenues are already contracted.
In his comments, Trufin CEO James van den Bergh commends Oxygen’s newish CEO and notes this is the first year the business has been able to benefit from its “inherent operational gearing”.
Satago Financial Solutions: this invoice factoring business lost a major contract with Lloyds Bank in July. This is said to have been “an enormous shock”.
Satago has since “aggressively realigned its cost base” and is in “advanced talks” with other potential Tier One bank customers.
As a result of the contract loss, 2024 revenue is expected to fall by 37% to “no less than” £2.4m, with a pre-tax loss of no more than £4.9m (FY23: £(4.2m)). The company expects to be able to bounce back from this setback over the next 18 months:
Satago has a fully costed and funded plan to achieve cash flow breakeven in the next 18 months.
Cash: Trufin expects to report a year-end gross cash position of at least £14m, including £12.5m of unrestricted cash. Panmure notes that this is double their previous estimate of £7m.
Outlook: today’s update does not include any new guidance for 2025, other than this somewhat cautious sounding statement:
Although we expect 2025 to be a year of consolidation, we will maintain our disciplined approach to allocating internal resources and expect the Group to grow all the profitability lines in 2025 and beyond.
House broker Panmure Liberum (many thanks) has updated its FY24 forecasts today to suggest earnings of 1.2p per share for 2024.
FY25 and FY26 forecasts have been left unchanged at 1.9p and 4.6p per share, respectively.
Roland’s view
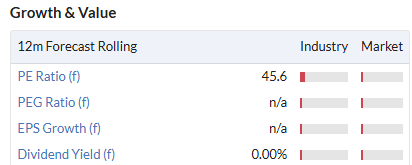
With Trufin shares trading at 90p as I write, broker forecasts price this stock on a lofty 75x 2024 earnings, falling to 47x in FY25 and 20x in FY26.
Playstack’s performance last year also seems impressive. But as we’ve seen with numerous other listed games companies over the last couple of years, results can be volatile and are dependent on a regular supply of successful new games.
However, I can see the potential for the Oxygen Finance business to deliver a lasting improvement in group profitability and cash generation if it can continue to add new clients.
One further attraction for me is Trufin’s net cash position. In addition to providing some protection for equity holders, this should allow the company to invest for growth on favourable terms.
Trufin seems to be performing well, but my feeling is that there’s already plenty of progress priced in. At this stage, I’m happy to retain our neutral view – AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
The price of Cohort (LON:CHRT) has been walloped for 5.8% drop today which appears to reflect a sale by Liontrust of half its holding , taking it down to 4.8%. Does anyone know if this has been discussed elsewhere, in particular does this throw some doubt on CHRT, which I have viewed as a sound stock opportunity for 2025?
I like Cohort too and have sat on the sidelines all 2024 because I just thought the price was up with events. Even with the price drop today, I don’t think it’s cheap and I will look for a softer entry point. Of course it could just keep going up and I will miss the boat, but that’s investing life
2% shifted Gulf Marine Services (LON:GMS) hopefully they hold on to them
"Imperial Financial Holdings Ltd has acquired on 24th December 2024 15224754 shares from Seafox International Ltd as part of a share distribution, as announced by Gulf Marine Services Plc on 19th December 2024"
up to just over 5% now
Update from Cathal on Poolbeg Pharma (LON:POLB) - He's being very cautious on what he says for obvious reasons:
https://www.brrmedia.co.uk/bro...
Maybe it's just one of those times when the market gets becalmed but I cannot get any feeling for trends or anything sensible to justify investing in or for that matter reducing. Obviously there are always bits and pieces of individual companies but otherwise it's just boring big banks. Maybe when we get more ideas about what Trump 2 means things will liven up a bit. Is it just me who feels "out of touch"?
I like listening to Edmund Shing’s Investment Strategy podcasts for the investing macro outlook. I’ve just listened to his strategy outlook for 2025 - a 20 min podcast on investment themes for the upcoming year. Useful to see if your portfolio could benefit from any additions or removals.
Search ‘BNP Paribas podcast 2025.’
He usually does a podcast a week and I always learn something from them.
Just a thought for a quiet day.
I read repeatedly on this site and elsewhere that UK small caps are undervalued, and that there are a lot of bargains. That in itself begs the question, "relative to what?"
If we take large and medium companies (i.e FTSE 100 and 250) as the yardstick, then I would expect small caps to look cheap, because they carry significantly more risk than larger caps.
On a risk adjusted basis, I expect the market has got small cap valuations about right. But there are always likely to be some price anomalies arising from the shortage of research into small caps.
If we take a foreign market as the yardstick (e.g. USA) then price comparisons will reflect the expected macro-economic performance of the two economies. Again, the market probably has got pricing about right.
Happy new year to all, and good luck with identifying the anomalies.
Richard
Well if you look at S&P 500 CAPE ratio, the S&P 500 is at it's third highest level ever. It is around 37.5, the only time it has been above 40 was in 1999, when there was the technology bubble, which was followed by one of the biggest crashes ever. I think the US in an AI bubble, it may well go higher but quite a few such as Warren Buffett, thinks there will be crash soon. Historically the US market is high, the UK is not. You can look at PE ratios, PEG, dividends etc.
Also, the USA CAPE was around 31 when the 1920s Great Depression happened and the stock market crashed. Hence, the current CAPE of 37.5 is a concern.
However, more of a concern is the USA debt at $32trillion. Annual interest repayments are around $728billion. The interest payments represent 14% of the USA annual budget. Can Trump bring an end to the USA deficit? Can Trump start to reduce the debt during his term? Can he turn the USA Ship around or will the USA economy and stock market crash whilst on his watch? I don't know.
There might be a honeymoon period when Trump comes to power but how long will it last? Anyone's guess!!
David.
Hi Dave I have a feeling interest payments are now north of a trillion and the debt is increasing by a trillion every four months.
I can't see him reducing it I think it will be the opposite he will push it higher, I've worried about the debt for years but plenty of others use the Japan debt to gdp argument , reserve currency etc.
I agree the problem is not the actual debt as the US has its own currency (THE Currency actually) but the credit rating agencies.
All the best
Seen a lot of postings about the CAPE ratio and comparing it with previous corrections.
Totally misleading as this ratio does not count buybacks and buybacks are very important from 2017 onwards as they have been accelerating.
Nevertheless the US market is expensive but for a reason!
US debt is of great concern and sooner or later one of the big 3 credit rating agencies will respond.
All the best
Hi Yiannos so your seeing one of the major credit agencies downgrading the US and presumably US bond yields going up 0.25-0.50% increasing the interest burden further ?
As an aside how do you see all the money printed during covid playing out will this just be cancelled off by the central banks that bought it all when it matures all will the billions/trillions borrowed I'm guessing at sub 1% rates roll over and need refinancing at rates currently north of 4% depending on the term ?
Regards
Andy
I study in depth financial statements. All these are irrelevant to me for my investment decisions. I don’t think the FED has an answer to that.
I know that the 3 big credit agencies will at some point downgrade the US debt-I will adjust then. I have 40% now in cash and I will not go below 30% the next two years unless the DOW/S&P correct by 25%.
2025/2026 will be difficult.
All the best
Except that the rating agencies are followers rather than predictors - agency analysts need at least some published evidence to back up their rationale for a politically sensitive downgrade, which means market yields reflect the downgrade long before it happens.
US Treasuries have lost 2 of the 3 AAA ratings from the majors already.
Of course if a government's debt ceases to be accepted as liquid collateral, or the repo market freezes up then it is a different story, but what would you rather accept instead of US Treasuries at the moment?
What’s your point?
Coming from a country and having experienced so many downgrades (not needed).
They hit when everyone is asleep!
You said:
"I know that the 3 big credit agencies will at some point downgrade the US debt-I will adjust then."
My point was that there is absolutely no point in waiting for the ratings agencies before making whatever adjustments you are considering. A certain yield level or spread to comparators perhaps, but the ratings agencies are lagging indicators.
Sovereign ratings are largely ignored or even ridiculed in the bond markets, unless they are emerging markets or there are collateral implications.
I use VIX futures and this was shared in a previous post on another thread -the point of entrance and the point of exit and the 4.5% that was made on the portfolio.
I try to engage with your posts but I find them irrelevant to the discussion. We were discussing about the market and the US debt.
No need to respond again.
All the best
To quote your own words from today's comments, "It’s difficult to understand if you have no experience...."!
Go back and see how much the Dow lost in one day when the debt was downgraded in 2011 and how much was the loss in 4 months.
Another one that sees the name Yiannos and wants to be clever by offering nothing but nonsense in this forum.
BLACK MONDAY 8 AUGUST 2011 after the weekend’s downgrade.
Surely Stockopedia must do something about these trolls!
All the best
No - not a troll, just someone who was there on those dates and lived it in a professional capacity within a major fixed income institution.
I seem to recall there was rather a lot going on, like the threat of a govt shutdown and a game of chicken over the debt limit.
Correlation isn't necessarily causation.
Indeed after the S&P downgrade bond yields actually fell, believe it or not.
Have a read of the ECB's Financial Stability Review from back in Dec 2011:
https://www.ecb.europa.eu/pres...
Personally I had my doubts about extracting too many conclusions from sovereign CDS spreads though - don't assume I agree with all of the analysis.
Monty
I AM GREEK!
Nothing anyone can teach me about spreads government debt and interest rates. The first time the Greek debt was downgraded and the economy collapsed, the debt/GDP was far better than the current US one ratio.
UNFORTUNATELY I have experienced all of them to the max.
You have moved the conversation to something totally irrelevant that I am not interested.
There was a downgrade in the US debt and a 20% correction in 2011. This will happen again and this was the TOPIC of my discussion with other fellow contributors.
Most of your posts are book material that Cambridge University nerds read.
I am not interested so no need to tag me again.
All the best
I can remember trading Greek debt points up front.
We gave up on spreads as the numbers got too big...
They were long days, but fascinating days.
By the way - were you aware that Yanis Varoufakis taught at Cambridge in the 1980s and produced some of those nerds?
The IDIOT that wanted to bring back the drachma-this is what I am talking about!
Have a break mate have a Kit Kat!
Someone tells you to stop tagging them but you still go on trying to teach a Greek the Greek history and its FAILED politicians.
According to Stockopedia, the top 4 companies in the S&P 500 are on forward P/E ratios of more than 30x currently.
That is Apple (NSQ:AAPL) , NVIDIA (NSQ:NVDA), Amazon.com (NSQ:AMZN) and Microsoft (NSQ:MSFT).
Tesla (NSQ:TSLA) is another mega cap with an even higher valuation.
John Authers' daily email today for Bloomberg had a summary of consensus estimates for 2025. None of the analysts surveyed expect the S&P 500 to decline this year and the average return expectation was 12%. The index has just had two years of >20% returns. I think three consecutive years with double digit returns has only happened once before, in the 1990s.
The S&P 500 could of course have another strong year. But consensus is often wrong and my guess is that it may be flat or slightly down (0% to -10%) in 2025, as the earnings multiples for mega cap stocks cool off a little. There are potential macro headwinds with unemployment data nudging up, yields rising and inflation above target.
I think many value SMID stocks might do better than the main indices in the US. And I'm hoping for a solid return from UK SMID stocks... the FTSE 250 and AIM in particular. Sentiment is quite beaten down on this side of the pond, still, and there is plenty of ground to make up before the old 2021 highs would be reached.
Most UK investors are not familiar with the US multiples-NVIDIA (NSQ:NVDA) trades at the same multiple when it was trading at $3.
US themes for the next 5 years :
Space, eVOTL, Quantum, Robotics, Drones, EV’s/Lidar, Alt Energy.
UK themes for the next 5 years : NHS waiting lists and small boats arrivals (although both can be solved in one day).
All the best
PS Yields are rising because of the debt.
Hi yiannos1
I agree with you US themes. I hold all of those except Lidar (will look into options).
I also think Agentic AI will offer investment opportunities.
As will AI data centre build out (the full supply chain of the sub-sector from chips to water cooling etc ....)
Regards
Howard
Yes ZJK Industrial Co (NAQ:ZJK) was up about 30% yesterday!
All the best
Hi yiannos1
Ref LiDAR .... Innoviz Technologies (NAQ:INVZ) up +32% pre market 07/01/25 14:19 GMT
NVIDIA (NSQ:NVDA) partnership
Regards
Howard
Innoviz Technologies (NAQ:INVZ)
Surprise surprise!
They were buying those $2 and $2.5 calls yesterday like there was no tomorrow. Well there wasn’t!
All the best
"US debt is of great concern and sooner or later one of the big 3 credit rating agencies will respond." I've also been saying this for a while to an empty room haha. It's got to happen though.
Interesting article in the FT today reporting a survey by the British Chamber of Commerce. It suggests that more companies will attempt to raise prices in response to rising wage costs.
Suggests that companies most concerned about increased wage costs are hospitality, transport and logistics.
Article behind a paywall but worth checking out the further detail discussed in the survey.
Fund managers
I have held Polar Capital Holdings (LON:POLR) for a long time and am currently down about 10% on my buy price. However this has been more than compensated for by the dividends received. I am of the opinion that Polar is the pick the listed fund mangers. It is differentiated focussing on technology, health care and finance/insurance.
The bull case for active fund managers, especially in the small cap arena is well rehearsed. Their shares are very cheap and they generally have oodles of cash on the balance sheet. Falling interest rates should logically be a positive for shares, especially small caps, which by any sensible metric are undervalued. The unknown is that given the extent to which UK small caps are unloved will sentiment change. Change is the only constant, counterintuitive, but true.
On that view I have opened a position in Premier Miton (LON:PMI). I could have gone for Liontrust Asset Management (LON:LIO), but considered the 10% yield on the former, together with it balance sheet strength make the dividend more sustainable. In addition to which AUM has stabilised with the acquisition of Tellworth asset management. Also it is yet to go ex-dividend the 3p interim.
Just my view, here is hoping the market and sentiment prove my purchase correct over time.
Don't disagree with any of your thoughts Jonno as we both know it will come down to if material inflows ever come back for this sector of the UK market the alternative will be I guess be a managed longer term decline.
It seems the S&P via trackers and ETF's is just hoovering up more and more of any global spare capital.
Polar has some good funds the technology and Insurance funds have strong performance, hopefully 2025 will be the year of the UK mid caps although I'm not betting on it hopefully I will be wrong.
I agree Polar Capital Holdings (LON:POLR) looks the best of the listed fund managers due to is specialist focus and resilient flows. If I had to pick one other then £PMI would be my choice - outflows haven't been too bad and should be well placed if sentiment improves. For me, Liontrust Asset Management (LON:LIO) is too risky due to the sheer size of outflows - if these continue then there won't be much of a business left in a couple of years.
Polar Capital Holdings (LON:POLR) . I too hold this and admire its specialisations.
I also hold Impax Asset Management (LON:IPX) for the same reason albeit its ‘green’ agenda does not appear to be flavour of month and I am nursing a loss. Professional approach from Ian Simm and team keep me invested for a better tomorrow. Have recently put my toes into Jupiter Fund Management (LON:JUP) which just seemed too cheap: anyone got a view?
Hi Jonno- You mention buying Premier Miton (LON:PMI) before the divi is declared - Too many times (generally speaking) Ive seen the SP dive more than the divi and now always check and buy after the exdivi date. Wonder how others face this situation ? Agree Polar Capital Holdings (LON:POLR) is best of bunch and like you am around 10% down
1 thing that I do always check bohenie ( and I appreciate that it won't be everyone's cup of tea ), is where the share price will settle on the chart assuming a full price drop thanks to the dividend... where ' should ' the price settle relative to the 50 day, 200 day, RSI etc... very simplistic I know, but often relevant if a larger yield.... can help with decision making
Any followers of Victoria (LON:VCP) which has more than doubled in a month? Huge debt and price decimated over the last year.
However, there has been significant insider buying recently - £176k + £80k.
One of their divisional MD has added 6m shares to take his stake to over 5%.
Mkt cap £97m , fcst revenue of £1.19bn and a PSR of 0.08
Hi eParo, I have had one eye on it over the last couple of sessions.
Still researching but the loan notes have been appreciating in value, https://www.boerse-frankfurt.d...
Traders buying its debt, Directors buying the shares and looking at the chart momentum buyers taking it out of its bowly bottom, seems to have a few people behind it right now.....
Trading update in April but the price is not hanging around
Victoria (LON:VCP)
Managed by ex bankers with a colourful past!
Negative tangible assets of about half a BILLION with liabilities over a BILLION.
Good luck-just a short squeeze the recent movement that can go higher but still a crap one for me.
All the best
Gulf Marine Services (LON:GMS) I am a holder but fear that the stock will not rerate until the Seafox holding of 7.8% has disappered. Wish Seafox would do a single distribution to remove the overhang.
I don't follow your logic Steven? Presumably the shareholders of Seafox who are getting the distribution of Gulf Marine Services (LON:GMS) are currently selling the shares and that has increased the overhang and reduced the price? If Seafox were to distribute all the shares in a single distribution and the new owners then tried to sell them it would increase the overhang.
I think what Sl3 is implying is an off-market ownership transfer to a new cornerstone owner. My concern with GMS is that Seafox must have tried this and found no interested parties. They operate in the same market, so what do Seafox know? I get Seafox may not want the bal sheet exposure but that still does not answer why they have been unable to find another cornerstone owner, if the debt paydown/asset quality and therefore debt to equity transfer argument is robust. Feels like a free lunch and it's usually the PI's who get eaten.
Trufin (LON:TRU) Today's trading update also says that there will be 8 new games released in 2025.
Andrew Hore, editor of AIM Journal tips Facilities by ADF (LON:ADF) :
"It was hit by the Hollywood writers’ strike that stopped the production of international filming in the UK and productions have not ramped up as quickly as expected after the strike, and projects have been cancelled," he says.
"The outlook for the UK film sector remains positive, thanks to tax incentives and the expense of filming in California. The boom days of streaming services are behind them, but they still need a supply of new programmes. Facilities by ADF can bounce back once utilisation levels of vehicles and equipment improve. The profit will be modest this year, but if the 2025 forecast of £7.9m can be achieved, helped by the acquisition of Autotrak Portable Roadways, the 2025 prospective multiple at 33.75p is six.
"Activist investor Rockwood Strategic recently increased its stake in Facilities by ADF to 4.4% and related Harwood entities hold a further 7.6%. Chief executive Marsden Proctor has bought 79,947 shares at 31.6p each. Rockwood Strategic sees potential for the share price to bounce back and it is likely to intervene if the performance does not improve. Buy for recovery."