Daily Stock Market Report (Mon 7 April 2025) - Black Monday, QTX, VLX, ENSI, MTEC, SHEL, MYX, DLAR, APN

Good morning! There has been chatter that this could be a "Black Monday" if panic continues. At IG, I see that the FTSE is being marked at 7890 (down 2%), while the Dow Jones is marked at 37,200 (down 2.7%), which are on top of the 5% falls on Friday. Looks like we may have another interesting day ahead of us!
To give some context, a year ago the FTSE was 7900. So it's still flat year-on-year, but it has given back all of the gains it made to its recent high at 8870. It has been a sharp 11% correction.
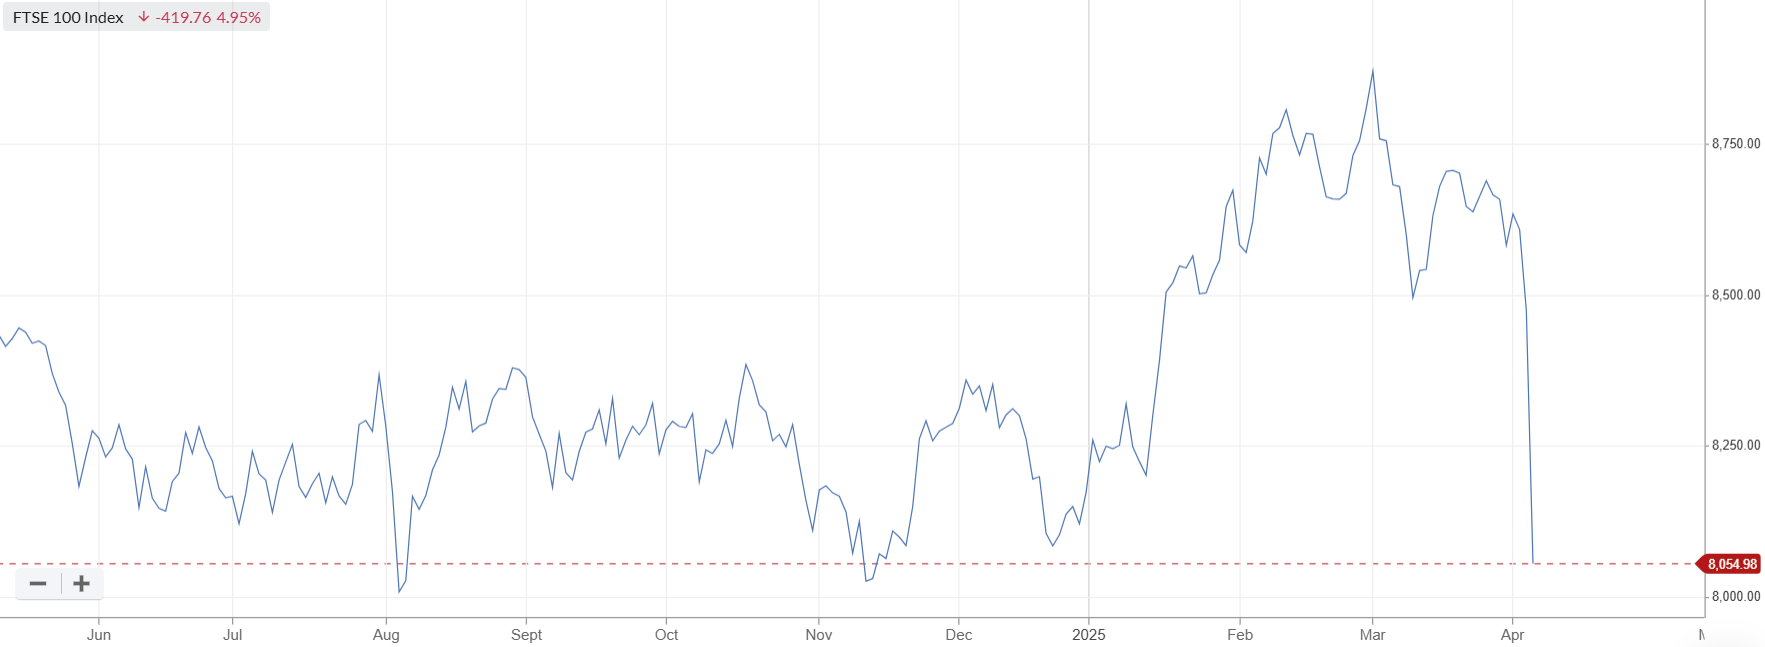
1-year FTSE chart.
The Dow is down 4% year-on-year and it did reach as high as 45,000 a few months ago. So it is down 17% from its high.
Similarly, based on the overnight price of 4910 (down 3%), the S&P 500 is now down by 20% from its high. So it looks like we may officially have a US bear market this week.
8.10am update: the indexes are currently at the following levels in volatile early morning trading.
- FTSE at 7580, down 5.9%
- AIM All-Share at 617.7, down 3.6%
- S&P overnight at 4825, down 4.8%
- Dow Jones overnight at 36,750, down 4.1%
- NASDAQ overnight at 16,410, down 5.7%
The AIM is the best-performing index - who would have guessed!
I haven't sold a single share and look forward to adding to positions when I have available funds.
12:50pm: wrapping up the report there for today. After the initial shock, markets have calmed down with the FTSE recovering slightly and no further overnight falls in the United States. See you tomorrow!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Shell (LON:SHEL) | Q1 update note | Lower Q1 LNG/gas production due to weather/maintenance issues in Australia. Trading results in line. | AMBER (Roland) Today’s update contains a c.4% downgrade to LNG production expectations, but I don’t worry too much about this kind of detail with Shell. For me, this is a macro/commodity play – and in my opinion, the shares remain in the upper half of their likely cyclical range. I don’t think Shell is cheap enough to justify a positive stance, but I am comfortable with a neutral view given the group’s robust health and useful dividend yield. |
Volex (LON:VLX) (£367m) | FY Trading Update | FY26 profit ahead of exps. Rev exp >$1,060m, +16% YoY. Op profit >$100m. | AMBER (Roland) Today’s full-year update from the industrial wiring specialist is positive, but does not include any outlook commentary for the year ahead. While this is understandable, it also makes it hard for me to have any conviction about the near-term outlook here. I’m opting for a neutral stance ahead of the FY results, when we will hopefully get some more granular commentary on the trading outlook and potential impact of tariffs. |
Applied Nutrition (LON:APN) (£278m) | Interim Results | H1 revenue £47.6m “ahead of guidance” given at the IPO, but this revenue figure was already revealed at the February trading update. Adj. EBITDA of £13.8m is “in line”. Outlook for full year also in line. Trading since half year end remains strong. Expected FY revenue up c. 19% to £100m. Revenue capacity is now around £160m as planned. In the medium term does not expect to be materially impacted by US tariffs. Says it could move production from the UK to the US. | AMBER (Graham) [no section below] I was AMBER/RED on this in February at 148p due to concerns that it appeared to be very richly valued for a sports nutrition brand (which I consider to be a difficult sector for investors). It's also a recent IPO, having listed at 140p in October. I'm happy to upgrade my stance one notch to neutral today as some air has come out of the valuation at the current 108p share price. Today's results are fine with H1 PBT of £11.8m and that is after spending nearly £2m on the IPO. Please note that the IPO did not raise any funds for the company and was purely to enable exits for existing shareholders, including £82m for the founder. |
De La Rue (LON:DLAR) (£212m) | Update on sale of Authentication unit | Conditions now satisfied for sale of this unit for £300m, to be held in escrow for 18 mo post completion. | PINK (Graham) [no section below] Edi Truell's consortium previously expressed an interest in taking out De La Rue at 125p. the company launched a formal sale process in February and according to the March trading update, the company continued to be in discussions with various potential counterparties. It will be interesting to see where the best bid finally lands, assuming it proceeds to a takeover. Today's update helps to clear the way for the disposal of the reminder of the group. |
Quartix Technologies (LON:QTX) (£93m) | TU |
In line for FY expectations. Q1 ARR +6% to £34.2m, price indexation now in “virtually all” customer contracts. Q1 customer signups +18% to 2,206, total customer numbers +10% YoY to 31,040. | GREEN (Roland) [no section below] Since returning from retirement to take charge again, founder Andy Walters is getting the business back in shape, focusing on core operations and addressing issues such as price erosion. Today’s update highlights an 18% increase in customer acquisition in Q1, with new ARR split roughly equally between new and existing customers. Given the strong profitability and positive outlook, I think the High Flyer style looks justified. On this basis I remain positive. |
Likewise (LON:LIKE) (£42m) | TU | Gross rev +10.7% in Q1, branded +14.6%. “Every confidence” in achieving FY objectives. | |
EnSilica (LON:ENSI) (£38m) | Trading Update | Profit Warning. Contract delays. FY25 EBITDA forecast slashed. FY26 revenue £33-35m (cons: £38.3m). | BLACK (RED) (Graham) Downgrading this to RED on the back of a serious profit warning that also reduces guidance for future years. I do still believe that the company has speculative potential but our quantitative rules are clear that this should be considered very high-risk. |
Made Tech (LON:MTEC) (£33m) | Contract wins | Year-to-date sales bookings £68.2m, up 89% on prior full-year performance. Outlook in line. Forecasts at Singers are unchanged including FY May 2025 revenues of £43m, EBITDA £3m and adjusted PBT £2.1m. | AMBER/GREEN (Graham) [no section below] This has fallen nearly 30% since I covered it in February. Valuation is therefore less unnerving than it was previously. The company’s cash balance is c. £9m making for an enterprise value of only £24m. Looking ahead, the FY May 2026 adjusted PBT forecast is £2.4m although I do think the adjustments are questionable, including for example share-based payments. Given the strong underlying momentum I’m happy to upgrade this a notch to AMBER/GREEN. |
Pennant International (LON:PEN) (£12m) | Sale of property (£1.2m) | Contracts exchanged on 3 commercial properties. Proceeds to reduce overdraft borrowings. | |
Smarttech247 (LON:S247) (£8m) | Multi-Year Framework with a London Airport | Total potential value of up to £7m across all four suppliers. No guaranteed minimum spend. | |
| Mycelx Technologies (LON:MYX) (£18m) | Operational and Trading Update | SP down 8% Successful US water trial. Tariff revenue warning: new 2025 range $12.5-15.5m (cons:$15.4m). Steel equipment bought by Mycelx in the US is made from imported raw materials and will be more expensive. Projects quoted by Mycelx but not yet signed must be requoted for customer approval. The CEO says she does not expect any major change to the order backlog. | BLACK (RED) (Graham) [no section below] The news of a successful trial in the United States sounds impressive with MYX’s patented solution removing oil from water (which can then be solid) and enabling the recycling of the water. However, I am obliged to give this a red as it is a Sucker Stock with a revenue warning (albeit one that was beyond its control) and also market cap below £10m, which I consider to be a danger zone. The company does say it will be profitable this year even at the lower end of the new revenue guidance, if we include the gains it made on a recent asset sale. I’ll be open to revising my stance when this materialises. |
Graham's Section
EnSilica (LON:ENSI)
Down 15% to 33.04p (£32m) - Trading Update - Graham - RED
EnSilica plc (AIM:ENSI), a leading chip maker of mixed signal ASICs (Application Specific Integrated Circuits), announces the following trading update for the year ending 31 May 2025 ("FY 2025" or the "Period").
I suggested recently that Ensilica might be focusing a little too much on PR after a spate of contract win announcements that didn’t seem to move the needle in terms of the company's financial forecasts.
We now have a full-on profit warning from them. So when it came to actually delivering a financial result, they are unable to deliver what was expected this year. I’m relieved that I stayed sceptical about this one!
Today’s announcement starts off with positive commentary around contract wins, which I guess is not surprising.
They have won six new design and supply contract wins in first ten months of FY May 2025, that will generate non-recurring engineering revenues of more than $40m over the next two years.
But then the bad news:
Despite these successes and as highlighted as a potential issue in the Company's announcement on 10 February 2025, the Company has experienced two customer delays that will materially reduce NRE revenues in the current financial year. The NRE revenues are the fees charged to customers for the design of their chips, including high-value costs such as tape-out fees and other significant third-party costs.
More detail is provided on the two specific contracts.
This is a company that has a history of heavy customer concentration. Checking the 2024 Annual Report (which also included a going concern warning), I find:
The nature of the design services and projects is such that there will be significant customers as a proportion of revenue in any one year but that these may be different customers from year to year. Revenue in respect of one customer amounted to £8.8 million representing 35% of the revenue for the year ended 31 May 2024, with only one other customer contributing over 10% of revenue.
This is phrased in such a way as to not sound very alarming, but it means that about half of revenues came from just two customers for the year. I do expect that customer concentration for FY 2025 will not be as bad as this, but it remains a key risk.
New FY25 guidance: revenues of £19-20m (StockReport estimate: £29m) and EBITDA of £0.1 - 0.5m (the net income estimate was £2.5m).
2026 outlook: guidance is slashed here, too.
The Board is focused on scaling the business and is confident of doing so given the strength of the forward orderbook. However, predicting the timing of contract completions that include customer dependencies has proved difficult as evidenced by the delays in the current financial year. In response, the Company has adopted a more conservative view on future guidance to allow greater flexibility for project completions. To that end, the Board now expects to deliver revenues of between £33 million and £35 million in FY 2026, with approximately 80% of FY 2026 revenue already covered by existing customer contracts.
At the midpoint, this is a 10% cut in revenue guidance and it also implies a substantial cut to EBITDA/net income guidance.
Graham’s view
I’ve been AMBER/RED on this on the basis that it had a small net debt position that I wasn’t sure it could afford, given its lack of profitability. The going concern statement in the Annual Report last year was also a major red flag.
These factors would ordinarily make this an automatic RED from me. However, Ensilica’s stream of contract win announcements made me think that its customers must have confidence in the company’s ability to perform these contracts and therefore that the financial situation must be somewhat stable.
The company insists today that it is stable and sufficiently funded:
With a strong NRE order book coupled with increasing profits from chip supply, the Board is confident of having sufficient capital to reach positive cash generation at the end of financial year 2026.
Should I now admit that this is too risky to be anything but RED on it? Reasons to have misgivings:
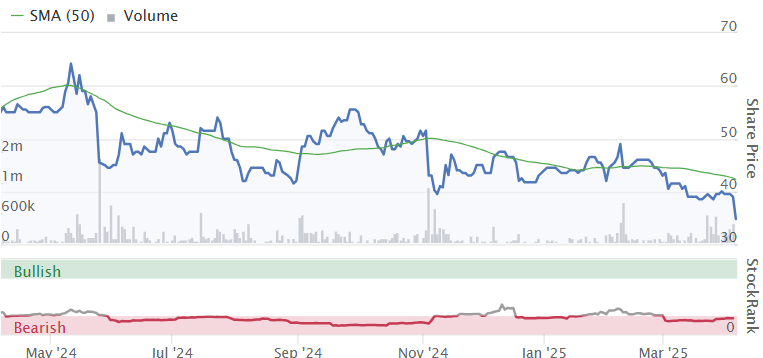
Stockopedia categorises it as a “Sucker Stock”
A serious profit warning for the current year along with downgraded guidance for future years, delaying meaningful profitability
The going concern warning in the last annual report
Heavy customer concentration
Potential impact from tariffs on the chip market? Not mentioned in today's update.
Looking for positives, I would point to:
Backing from customers and partners including the UK Space Agency and European Space Agency
Raised £1.2m in new equity last June
Refinanced its loans in November
Net debt was only £1m as of June 2024, and this includes £2m of lease liabilities.
I think our quantitative rules are clear that this should be a RED, although personally I do still see some high-risk potential upside here.
Roland's Section
Volex (LON:VLX)
Up 10% at 219p (£416m) - FY Trading Update - Roland - AMBER
Volex (AIM: VLX), the specialist integrated manufacturer of critical power and data transmission products, today releases a trading update for the financial year ended 30 March 2025 ("FY2025").
According to Stocko’s index listings, Volex is one of just five shares in the AIM 100 index that have risen this morning!
Today’s update is ahead of expectations, striking a confident note against a chaotic market backdrop (my emphasis):
Underlying operating margins are anticipated to be at the upper end of the target corridor of 9% to 10%, with operating profit of at least $100 million, well ahead of the top end of market estimates.
Here are the main financial highlights from today’s update:
Revenue up 16% to “at least $1,060m” (+8% constant FX)
Underlying operating margin expected to be “at upper end of 9%-10%”
Operating profit of “at least $10 million”, well ahead of market estimates
Net debt to EBITDA leverage 1.1x at 30 March
Last year’s underlying operating margin was 9.8%. This dropped through to a statutory figure of 7.0%. So my impression is that margins for the year just ended were probably similar to the last couple of years on both a reported and adjusted basis:
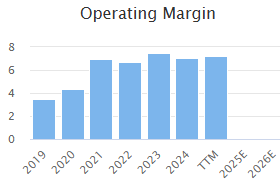
Trading commentary: executive chairman and 25% shareholder Nat Rothschild says the group had “a strong fourth quarter”, with good success in securing new projects.
Improved profit margins were driven by a “favourable product mix, including increased demand for data centre products”. There were also some “incremental operational improvements”.
Performance was mixed across the group’s divisions:
EV & Consumer Electricals: “strong momentum, securing several new key customer relationships”
Complex Industrial Technology: “notable strength, delivering low double-digit organic growth” – this appears to have been driven by data centre demand as “a major customer” accelerated their infrastructure investment
Medical: sales fell against a strong comparative period that benefited from catch-up sales
Off-Highway: revenue flat as softer conditions in some markets were offset by “several strategic customer wins”. Management says that “integration activity continues” in this unit, which includes the recently-acquired Murat Ticaret business.
Outlook/tariffs: no new broker notes are available to me today and perhaps understandably, there is very little commentary in today’s update on the outlook for the year ahead.
The company acknowledges that the impact of tariffs is currently hard to predict:
The breadth and rapid evolution of recent changes in international trade policies and market dynamics are unprecedented, making precise quantification of direct and indirect impacts challenging and increasing operational complexity.
However, Rothschild is keen to emphasise Volex’s value-added and embedded position in its customers’ supply chains:
The majority of Volex's products represent essential components within complex supply chains. In many instances, Volex is either the sole provider or one of very few qualified manufacturers capable of meeting demanding technical and operational requirements, fostering strong customer reliance. Incremental costs arising from tariff changes are expected to be passed through to customers, underscoring the robustness of Volex's competitive positioning.
Checking back to the H1 results, 42% of Volex’s revenue was generated by deliveries to customers in North America. As far as I can see from this map, the group’s manufacturing mainly takes place in China, plus Vietnam, Indonesia, Poland and Mexico.
Volex doesn’t appear to have any manufacturing capacity in the US, so it seems reasonable to assume at least some of its sales will be affected by tariffs.
For what they’re worth, consensus forecasts prior to today showed adjusted earnings falling by 7% to 31.3 cents per share in FY25, before returning to growth in FY26. This view was consistent with H1 adjusted EPS of 15.2 cents per share.
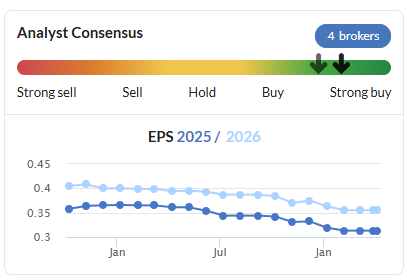
I’m not sure how much of an upgrade to expect to FY25 figures after today’s update, but in some senses I suspect it’s not that relevant. The FY25 year has ended and it looks as though the outlook for FY26 could change.
The forecasts shown above price Volex on a FY26E P/E of eight after this morning’s gains – that seems a reasonable valuation to me, given the likelihood that forecast earnings for the current year could be trimmed.
Roland’s view
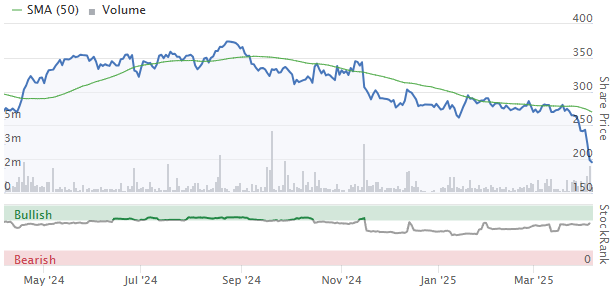
Volex shares have drifted lower over the last year. They then de-rated sharply when Trump’s tariff ‘liberation day’ was announced:
I have owned this stock in the SIF folio in the past (no position at present) and have generally had a fairly positive view on the business.
At this stage, it’s not clear how much of a headwind the tariff regime will be.
In reality, we don’t even know if the situation will be the same in a month from now, far less how it might affect volumes and margins over the coming year.
However, it seems prudent to me to expect an overall negative impact. I think it’s also worth remembering that Volex has a material amount of debt – reported at $205m at the end of H1.
For these reasons, I’m going to take a neutral view on the shares until some clarity emerges and we get updated guidance for the year ahead.
It’s worth emphasising that my view is based on a review of the numbers and a superficial overview of the current trading environment. An investor with deep familiarity of this business might be able to have a stronger conviction (positive or negative) than me. Therein lies the opportunity of DYOR.
Shell (LON:SHEL)
Down 7% at 2,305p (£141bn) - Q1 2025 update note - Roland - AMBER
It’s a big day when Shell is down 7%, single-handedly knocking £9bn off the FTSE 100. I estimate that’s about 0.45% of today’s index fall – or around 10% of the entire UK market move so far this morning.
As we discussed on last week’s webinar, market concentration is a factor in the UK market too, not just the US.
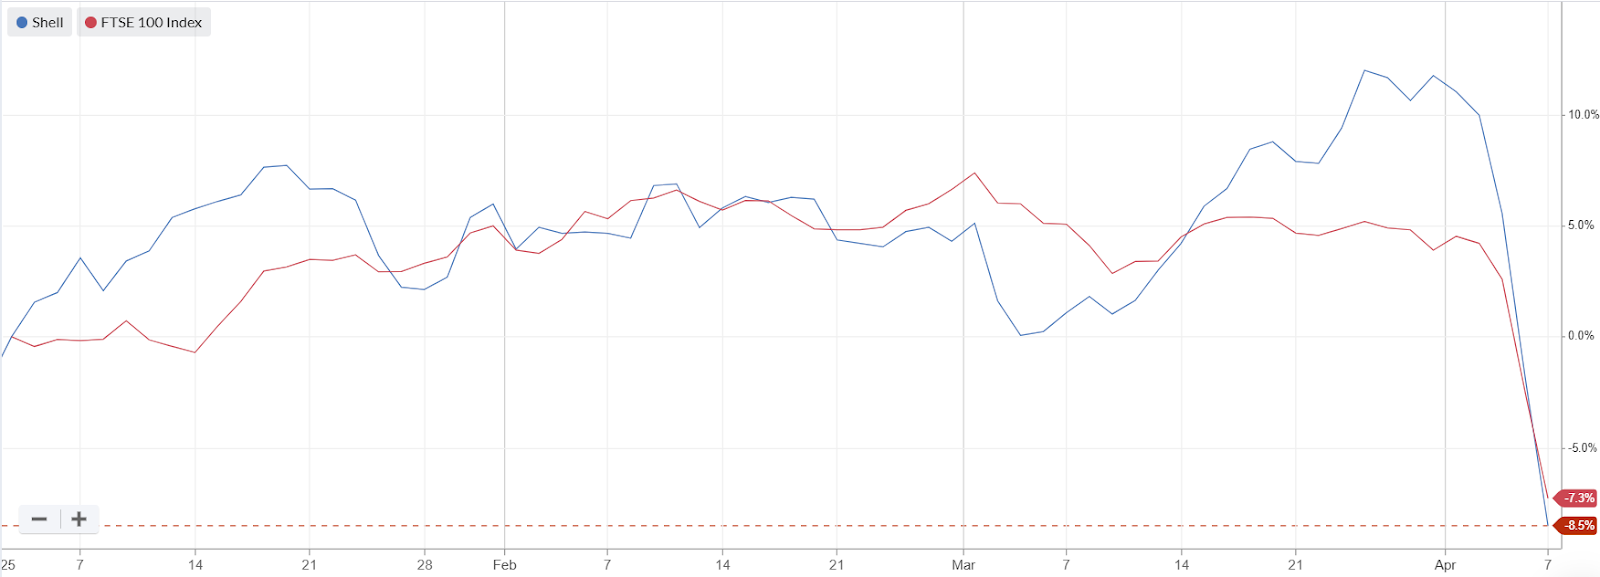
However, I don’t think that much of today’s sell-off is directly linked to Shell’s update this morning. BP is also down 7%, after all.
Q1 update: Shell issues a quarterly “update note” ahead of its quarterly results. These notes contain a list of production metrics and financial details that might affect earnings estimates. It’s an unusual format that seems mostly to be designed for City analysts with detailed models of the group’s business.
I don’t have a detailed spreadsheet to model Shell’s earnings, so I usually just look for anything that suggests a significant variation from previous guidance.
Today’s numbers appear to flag up one main area of disappointment:
Q1 LNG production: now expected to be 6.4-6.8m tonnes, down from 6.6-7.2m tonnes previously. This is said to be due to bad weather (cyclones) in Australia and some unplanned maintenance outages.
All the other main numbers appear to be in line with the Q1 guidance included in January’s 2024 results.
Importantly, the contribution from Shell’s trading division (referred to as Trading & Optimisation) is expected to be in line with previous expectations. Shell and BP make a lot of money from commodity trading, although they’re usually careful to avoid revealing exactly how much.
The only other number I’ll point out is that the contribution from “renewables and energy solutions” is expected to be for adjusted earnings of ($0.3bn)-$0.3bn. Shell generated adjusted earnings of over $28bn last year – renewables are not currently making a meaningful contribution to the group’s bottom line.
Roland’s view
LNG sales are a key element of Shell’s business model, so I guess some analysts may tweak their Q1 forecasts slightly lower following today’s update.
However, I don’t see this as a stock where there’s any point in focusing on such minor details. In my view, this remains a macro commodity play, where what matters are oil and gas prices – and the health of the global economy.
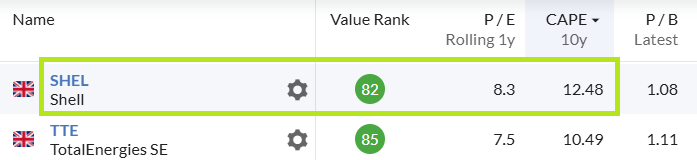
For some time now, I have held the view that Shell’s valuation has been towards the top end of its likely cyclical range.
That remains true – the shares were still trading on a CAPE 10y of 12.5 (prior to today). I’d look for a mid-high single-digit number as an indicator of cyclical value here:
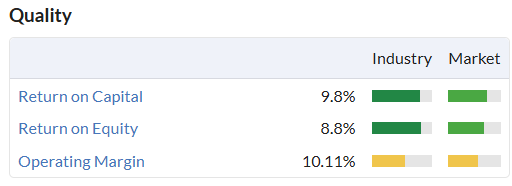
After all, this is a relatively capital-intensive business with quite average quality metrics:
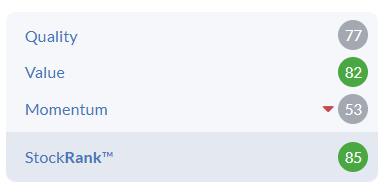
The StockRanks are also now starting to reflect this view, with a Neutral style rating and sharp fall in MomentumRank:
Brent Crude oil has fallen by 16% to $63/barrel over the last week. US natural gas prices are down 10% over the same period.
On a personal, anecdotal level, I’ve been bombarded with emails from my usual heating oil supplier, inviting me to buy oil at “six-month low prices”.
I don’t know if oil and gas prices will drop further, but if the US and other markets do see a recession, I think Shell shares could still have further to fall. Historically, peak-to-trough falls of 30%+ are not unusual for this business:
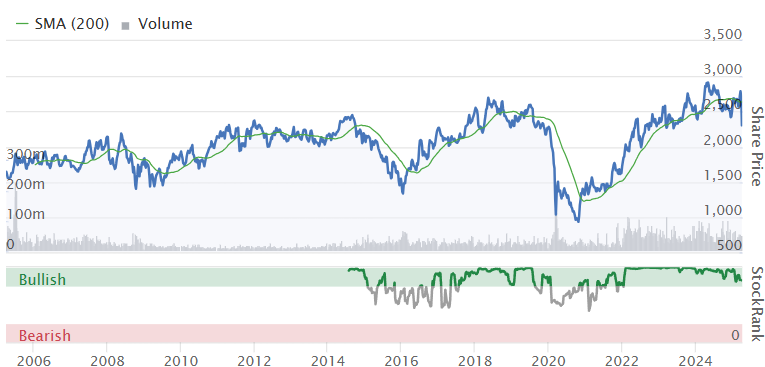
It’s possible I’m being too pessimistic here. Shell stock does offer a useful and well-covered 4.5% dividend yield and I think the business is in robust health.
However, for me, Shell just isn’t cheap enough to justify a strong positive stance, especially given the macro backdrop. I think a neutral view is probably the most appropriate choice, reflecting both risks and possible reward. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
I do not post often, but seeing as we going through a "rough spell" I thought I might share my investing "experience" as it may help someone?.. All my working life when I did not need the cash, I just invested monthly into Funds regardless of the ups/downs of the markets ( I didn't even know about Investment Trusts for some time) and this worked out for me very well indeed I.E "..buy & hold/ time in the market/pound-cost averaging etc, blah, blah, blah etc". Now that I am retired, I am much more conservative with my investments, and I guess I turned into more of a "Trader" ..(NOT a Day-Trader).... I.E I no longer follow the "Buy & Hold" mantra and actually use charts to give me insights into what the Market thinks about a Stock/Investment Trust etc. I am by NO means a technical trader , but if I look at a simple chart and the stock/.I.T is going up or down , I look at the supply or demand for it ( i.e candles with demand tails, shows there is support, candles with supply tails indicate there is not much support and the market is not supportive). I know this is not everyone's "cup of tea" but it has worked for me recently and I have avoided the first Trump win, the Covid sell-off and the recent Liar. sorry Labour win. As stated earlier, I am a very conservative investor and am 90% in cash at the moment, looking for opportunities to arise when the market indicates so? I only invest in potentially "under-valued " stocks and Investment Trusts trading on a decent discount to NAV. I No longer invest in Funds as they generally sell off massively in times like now and it can often take one or two days to get out, whereas with a I.Trust I can sell in 2 clicks of the mouse. I hope this helps somebody on their investment journey ATB. NM.
What's happening..... most of my PF is doing gangbusters, even Tesla (NSQ:TSLA) just turned blue
FTSE will finish blue at this rate
Just heard on Bloomberg Radio that there are reports (didn't catch from where) that Trump is considering a 90 day pause on tariffs for all countries except China
Already denied by the administration as "FAKE NEWS". US Markets went up on the rumour and have dropped again since
Unbelievable whipsaw effect though - it is somewhat sobering to see multi-trillion $ indices roller coastering around like a UK small cap!
I know this is not normal Stockopedia discussion but can I share this?
I have a tiny, highly leveraged, fun account for index trading. I mean I pay more on the spread on some share trades than I have money in this account.
Around 2.30 I received a margin call that my "available funds" in the account was about to hit zero and I would be stopped out. I just could not be bothered so I left it expecting that to be game set and match.
Three quarters of an hour later I pulled up outside the shops and had a quick look on my phone. My account balance had gone up 100x! I sold as fast as I could and treated myself to the largest easter egg I could find.
No skill involved but demonstrates the absolute madness of these markets!
You got the basis of a great system there !
Bung out some optimistic fake news - short the S&P - close position within the hour !
SIMPLES !!
Off to the country now ............
is Cmcx not one to benefits from the turmoil in the market?
Maybe in the short-term. But if people withdraw from markets due to losses/fear then that's not good.
Amidst the market turmoil I read an interesting book last week, Best Loser Wins by Tom Hougaard. Well worth a read, albeit focused more on trading and medium term investing. Has changed my perspective on closing trades, averaging down etc. Would recommend for anyone who struggles to crystallise losses like me!
Thanks for the recommendation JSchoffer. Added to my list of books to read. It sounds similar to a great book I read recently, "The Art of Execution - Lee Freeman-Shor" definitely worth a read in my opinion if you haven't already.
Yep also a great read. The messaging is similar to the 'assassin' type from Freeman-Shor in cutting losses and the 'raiders' in letting profits run. My problem is it takes me 4 or 5 books all saying the same thing before I take note!
Lots of time spent this morning updating alerts! Getting writer's cramp!
It's going to need a lot of thinking time as to which stocks that I've been watching represent best chance of a decent return from these lows, or indeed any further lows.
Same here Raven - inbox stuffed to the gunnels with stop loss alerts. Not a pretty sight....
I have decided just to delete my portfolio I had saved on here. I just need to avoid actually logging into my ISA or SIPP account now. I think not looking for a few months is probably the best option. Exactly what I did during the pandemic.
Interesting decision, Lefty! My systems are set up so that I can't see how much my portfolio has changed on the day. Ignorance is bliss!
When I first started investing, many years ago it was difficult to check on a daily basis, so much less stressful.
I know the feeling.
Hi Graham. I’m with you. Not selling. Good companies will bounce back strongly.
Looking at Spreadex last night before the big fall and 84% of their clients with positions on the FTSE100 were long. That's a heck of a lot of big headaches this morning and a heck of a lot of margin calls, I suspect.
When you consider that 75%+ spread betting accounts loose money that's not surprising.
I see that Bill Ackman is calling for a 90-day timeout and that the advisor(s) who proposed the idea of imposing tariffs on 60 countries should be fired. He also said that these tariffs could lead to "economic nuclear winter"
It is impossible to predict what Trump will do and he has surrounded himself with sycophants - i.e. none of them will challenge his crazy ideas.
Personally I think that we may see the market react positively once the first deal is done, perhaps Vietnam? If the market sees that this is vastly different to the initial punitive tariffs then there should be <some> relief, however it is extremely volatile at the moment and my strategy is to not sell anything and lock in losses. I am luck to have some cash sat on the side-lines as I have been taking some off the table recently and am never fully invested, for this very reason. Cash is king!
I will be selectively buying over the next few weeks and months - looking for deeply discounted situations with good balance sheets and safe yields, which should offer protection on the downside and offer capital growth when the market turns. I hope the community here posts some ideas.
It is tough out there - try not to act on emotion and don't enter the market too quickly, which is difficult, but was probably my biggest learning in 2000, 2008 and 2020.
Has anyone even tried to sell anything this morning? Pretty much impossible. I'm trying to sell my fixed income funds to take advantage of equity falls, but so far, my sell orders are still pending. Anyone trying to sell equities will find it harder.
Sold 6 assorted stocks, only Warpaint London (LON:W7L) did I hit a problem
IG fine. Interactive Investor took an eternity.
Guess who I'm with !
Generally I find its a good idea to have 2-3 accounts with different providers if a couple of the platforms fall over due to super high volume of orders hopefully the third one will be ok and you can at least buy/sell part of your portfolio,
Bought back a few Volex (LON:VLX). Would have bought more but tend to be fully invested. In normal market conditions the trading update would have resulted in a 10 to 20% jump in share price.
Time to be selectively greedy to paraphrase Warren Buffet, although no guarantee shares will not get cheaper.
My take, for what it’s worth, is that now is not the time to sell after some fairly sharp falls. Buffett when others are fearful etc etc!! if you are in quality shares they will definitely recover. I hold VLX and am as confident as I can be after today’s trading update. I think Buffett also said if you can’t cope with falls of up to 50% then you should invest in a tracker.
In a previous market panic I tried to be clever and get in and out - it did not work - I sold FUTR - it went up too much before I could get back in and went on to more than ten bag!
my advice is don’t pay a lot of attention to SPs other than to look for opportunities to buy and focus on operational performance which should always be the case because that ultimately is what will protect your portfolio
I sold all my shares last week. I'm now totally in cash, waiting for the markets to bottom, before I
re-invest
Wow, good luck Meldrew!!
Good call go and enjoy the spring sunshine predicted this week.
Haven't sold anything but have started buying this morning with spare cash I put aside for an apartment. Not going all in but feel Trump has to pull the foot off the pedal later as even he must know what a disaster he's creating.
I am doing the same. I've added to Rolls Royce and S&P trackers but I will look at others over the week.
The problem is that no one knows what will happen next. Trump could announce today or tomorrow that he's delaying the tariffs, which would see everything shoot up. On the other hand, he might stick to his position, and the market could keep falling.
During COVID, it was easy to panic and sell out. But the risk is missing the upside. By the end of that year, markets had rebounded significantly, and it was hard to know when to buy back in.
This time, I’m staying put. Watching everything drop is painful, but hopefully it’s temporary. I prefer to stick it out rather than adjust my portfolio and potentially miss the recovery (which I've made the mistake of in the past).
I think Trump may well reverse his position by the end of the week. But i do think confidence has been seriously damaged. People have been reminded of how risky the market is. They do not want to invest at elevated levels and will therefore only go back in at significantly lower levels.
Where the bottom is no one knows. My guess is that the FTSE will fall around 10% and the US market as much as 30% -40%.
Everyone moaning US tech over valued. Now falls and still moaning. Great companies getting cheaper. Micron Technology (NSQ:MU) . Looking for a Tesla (NSQ:TSLA) support - so much more under the hood than just cars.
Taiwan Semiconductor Manufacturing Co (NYQ:TSM) - 90% of the worlds chips - building in US. Obvs China risk. These were always too expensive unless brave. Still a brave punt but downside risk reducing.
Too early to get back in but Trump could pull it off. Too much cheap rubbish floating around on boats anyway. Oil price the thing to watch and he will stop the war.
Chips are exempt from tariffs but the wording is unclear so not sure if its just actual components of bigger things that contain shit loads of chips like motherboards etc.
Agreed. Horrendous to watch but try and stay put. When it will all turn the other way who knows. Take this time to select new targets and what is currently in portfolio with the potential to top up. I think Rolls-Royce Holdings (LON:RR.) is a good example of a potential top up in my opinion.
Ooops. Hang Seng -12%.
Thought the circuit breakers kick in at -10%.
Personally i think this has more to fall, so i am in cash, gold and silver.
Go back in when FTSE is at 7,000.
"Personally I think this has more to fall". I am intrigued to know why you think your crystal ball is better than Mr Market's, but of course you may well be right and much money is being wagered in both directions every day at the moment. However, what we do know is that market timing is pretty much a lottery. We also know that long-term equity markets perform better than every other asset class. Finally, but most importantly, we know that investors that try to time the market and get it wrong can underperform quite spectacularly.
For the above reasons, I prefer to stay fully invested and simply stop monitoring how much my paper wealth is declining each day right now! Logically, I would also be betting that those who are investing surplus cash at the current fairly extreme short-term lows stand more chance of success in the long run than those the other side of the trade.
Could be a good day to Bed and ISA a few shares now that we are in a new tax year. We will have to wait until this afternoon and the US market opening to get the real action. This is a real global crisis that is likely to trigger a recession - a global tariff war with similarities to the tariffs imposed in 1930. The inverted yield curve reinverted 7 months ago https://fred.stlouisfed.org/se..., so it looks like the "this time is different crowd" are going to find out the hard way. This is on average the precise timing for a recession to start based on history. Money flows have been negative and then below trend since July 2022 so we are getting the long and variable lags of this starting to bite. US earnings estimates are way too bullish (c10% earnings growth in 2025...really!) and valuations excessive (bubble like), so we could see a 50%+ decline in the S&P500 relatively quickly, maybe after a few bear market rallies. Anyway, some great opportunities are coming and investors may, at long last, start allocating away from the US and back to the UK as our markets do not have quite as far too fall! The difficulty is knowing when to deploy surplus cash. I think its too early, but may start deploying some at -20%, then -30%, -40% etc. I have made the mistake of deploying too early in the past so I need a better strategy. Waiting for the stage 2 uptrend is the lowest risk, but that is a long way off. Any thoughts?
Not too sure it's a good day to bed and breakfast in my own shares, might be selling cheap and buying back on a dead cat bounce? I do plan to invest in new money placed in my ISA yesterday in readiness though.
Silver Moon - I normally BED and ISA within minutes, when I do it. It's often to take a small tax loss and move to tax free dividends.
Other than brilliant post Topvest I can't add a lot, like you I added to early in covid then panicked and got out at breakeven after the recovery, I would have been retired now if I had held on doh.
My strategy this time around is similar to yours although I am now pretty much done with single stocks as even with blue chips I never make much on them look at how the banks in the UK have been pummelled in last two days as an example.
My gold bullion ETF which was a full position is helping and also I made a rule to keep 25% of the portfolio in money market funds after covid and a dire 2022 to deploy at times like this (didn't expect it to be deployed only 18 months after the last bear market ended though).
One interesting point I was listening to one of Paul Scott's recent videos over the weekend and he mentioned these bear markets are now happening more frequently, you think we have had three bad ones since March 2020.
Prior to 2020 you generally got 7-8 years of decent markets after a major event but if the world is really changing for good it seems possible it could be 1-3 years of decent markets or even avoiding markets altogether for four years when Maga/Republicans are in power.
Be great to hear lessons learned from other traders today and how they intend to play this bear market or what strartegy worked for them in 2020 and 2022.
Regards
Andy
Really interesting posts today regarding strategies. Like you, Phoenix, I have reduced my individual stocks since some time and predominantly invested in Investment Trusts. I am not selling and hoping that their ability to use reserves to support dividends will enable me to drip feed further purchases for as long as a bear market goes on. I have used this strategy over several years and seen my dividend income increase significantly. I guess it all depends on how long any economic downturn lasts. I still have a few individual small cap 'play' stocks and not sure of my longer term strategy with these but not selling yet.
I agree it is far too early. I am sitting 40% cash and 30% gold bullion., and am only holding onto core long term holdings, some of which like Rolls-Royce Holdings (LON:RR.) have taken a hammering. I had shorts on Tesla (NSQ:TSLA) and ProShares UltraShort QQQ (LON:0YEB) and stupidly closed them out too early. I also managed to buy the Chinese market almost at the top. I have since closed the position as I think we will be able to buy back in much cheaper (it is already cheap).
I won't try to trade it because the bear market rallies can blow up your options account and Trump is so unpredictable. The safest strategy is to hold onto your core long term positions, and make sure you have cash on hand to move when you feel comfortable. Buy positions in 3 or 4 tranches to mitigate the likely event of not calling the bottom. Where to invest? I like the UK, Argentina and Brazil, Poland, Turkey, Kazakhstan, and I have long term holdings in the Nordic countries.
I think you have to develop a response that enables you to sleep at night. I am more worried about the tourist trade on cottage lets on this farm than I am about the entertainment in the stock market.
James Alastair. You seem well positioned. 38% cash for me as of Friday, including short gilts and takeover offers. Think the consensus is its too early to deploy heavily at this early stage unless we get a flash crash.
As you say topvest no one really knows drip feeding into indices is my strategy on declines, if he rows back we could easily see 7-8% upside in a week equally if Europe slap on 20% we could see that on the downside.
Despite the seeming lack of backbone Europe is stronger than it thinks if they got together with the Chinese and Japanese and all threatened to dump their dollar holdings I reckon Trump would roll back in a nano second even more so given they need to refinance $9 trillion this year.
https://www.youtube.com/watch?...
I rewatched this video last night and it shows how if investors follow the 10 / 20 MA crossover on a weekly chart (S&P500, FTSE 250) they would be out of the market for the worst of the falls and in after the market has turned. A must watch today!
FWIW, our current situation is :
2 Stock ISAs (one 36% cash) – no sales planned.
2 Cash ISAs – could move to Stock ISAs
Gold Bullion
Bonded Malt Whisky - can’t see 10% tariff having too much effect
First move will be to switch off the PC this evening and forget this current madness and go across to Somerset for a few days to celebrate our anniversary.
Next week to xfer new funds into Stock ISAs and wait to accumulate at sub bargain basement prices. As others have said, timing is the problem.
Hi Topvest, Bed & Isa of holdings outside an ISA etc good call but its not just for the dividend tax situation... there is also the CGT situation,
If holding a dog fund (guilty) then this may be an opportune time to exit !
Really if you are expecting further falls selling makes sense. If you are expecting future rises then Ben & ISA tax makes sense! If not sure...... it still seems to make sense (nothing else does right now) !!!!
+ Warren Buffett seems pretty good at sensing which way the wind blows.
Big Techologies ? Harwood prodding .
Interesting RNS looks like Harwood may have started buying. Didnt know they had any skin in this gane
Appointment of Ian Johnson as a Non-Executive Director of the Company
The Company is pleased to announce that it has appointed Ian Johnson to the Board of the Company as a Non-Executive Director with immediate effect.
The appointment follows discussions in recent days with Harwood Capital, who contacted the Company stating that they had consulted with certain shareholders who together have a meaningful interest in the Company.
Hard hats at the ready today!
fantastic update from Volex (LON:VLX), they are a great company at a great price imo - so just going to leave it there and try not to look!
I also thought the Volex (LON:VLX) was very positive. I hope the price continues to fall and offer a great top up opportunity! I hold.
Maybe but as always full of adjustments which are never reported in the TUs. I need to see the PBT (un-adjusted) before making a judgement...
I just read the Volex update ... I don't hold, but PE 7.2 and PEG 0.6 is becoming increasingly hard to ignore on a 5-year view. This market is throwing p some astonishing value.