Daily Stock Market Report (Thu 17 July 2025) - WISE, CHH, AGFX, DPLM, CAPD, COA

Good morning and welcome to today's report.
Spreadsheet accompanying this report: link.
08:30 Agenda is complete.
13:50: today's report is now complete.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
GSK (LON:GSK) (£58bn) | FDA has approved a prefilled syringe presentation of Shingrix, simplifying vaccine administration. | ||
Diageo (LON:DGE) (£42bn) | CEO departure and succession plan (y’day pm) | Debra Crew has stepped down with immediate effect and is thanked, CFO Nik Jhangiani is interim CEO. | |
SSE (LON:SSE) (£20.4bn) | Renewable output -4% due to weather, capex +70% to £0.5bn YoY. Financial guidance unch. | ||
Wise (LON:WISE) (£14.1bn) |
SP -10% FY26 guidance unchanged for 15-20% underlying income growth. | AMBER (Roland) Today’s Q1 update has triggered a c.10% share price drop and appears to show a slowdown in growth relative to last year. Underlying income growth during the first quarter was slightly below the company’s FY26 guidance as well, although this was left unchanged today. I don’t think there’s anything serious to worry about here and believe the long-term growth story remains intact – and potentially very impressive. However, Wise shares are trading on c.30x earnings in a sector where mishaps are not unprecedented. The company is also about to move its primary listing to the US. I’m going to maintain our neutral view. | |
Diploma (LON:DPLM) (£6.58bn) |
YTD total rev +12% YTD organic revenue growth +10% YTD acquisition revenue +4% FY25 outlook: FY organic revenue growth now expected to be 10% (prev 8%). | AMBER/GREEN (Roland) [no section below] I’m relieved to see I took a moderately positive view on Diploma when I reviewed its interim results in May. Today’s Q3 update includes upgraded revenue growth guidance for FY25, emphasising the contribution from organic growth while flagging up two recent bolt-on acquisitions totalling c.£39m. Diploma shares never look cheap and now trade on a P/E of c.30x FY25 earnings. But this is a well-run and high-quality business, in my view, and I am happy to maintain my previous view today. | |
Frasers (LON:FRAS) (£2.90bn) | FY25 rev -7.4%, adj PBT +2.8% to £560.2m. FY26: expect £50m extra costs, adj PBT £550-600m. | ||
RS (LON:RS1) (£2.74bn) | Q1 LFL rev -2%. EMEA trading softer, Americas and AsiaPac “more resilient”. FY outlook unch. | ||
Qinetiq (LON:QQ.) (£2.64bn) | Q1 order book c.£5bn, FY revenue cover 75%. Cost savings on track, trading in line, H2 weighting. | ||
Dunelm (LON:DNLM) (£2.3bn) | FY sales +3.8% to £1,771m, gross margin +0.6%. Furniture strong. FY PBT to be in line at c.£210m. | ||
Big Yellow (LON:BYG) (£1.79bn) | Rev +3%, rent/sq ft +5% YoY and costs stable. LFL occupancy +0.7% to 79.4% vs March 25. | ||
Premier Foods (LON:PFD) (£1.68bn) | Rev +0.3%, branded sales +1.2%. Sweet Treats branded +11.4%. FY26 profit exps unchanged. | ||
Coats (LON:COA) (£1.3bn) | Results of Capital Raise, Acquisition (y’day) & interim results (y’day) | H1 rev flat, adj op profit +5% to $140m. FY outlook unch. Acquiring OrthoLite insoles for $770m (10x EV/EBITDA). Part-funded using £250m (20%) placing, completed at 77p. | AMBER (Roland) Coats’ half-year results look fine to me, given the impact of tariff uncertainty and softer conditions in some markets. I’m confident the group’s core business is likely to remain a market leader and would probably have remained moderately positive, without the acquisition. However, the purchase of Ortholite looks a little expensive to me and seems to depend on a three-year programme of cost savings to deliver any meaningful margin benefits. Although the shares are now trading below last night’s placing price of 77p, I am not tempted to jump in given the execution risk commonly seen in larger acquisitions. |
FUTR (CVE:FTRC) (£742m) | US advertising +5%, UK ads -8%. Go.Compare slowed. On track to achieve FY25 market exps. | ||
IP (LON:IPO) (£511m) | Istesso has published results showing tissue repair using an oral medicine for the first time. | ||
NCC (LON:NCC) (£446m) | Sale process for Escode is continuing. Confirms that Cyber business is now also under review. | ||
Funding Circle Holdings (LON:FCH) (£404m) | Credit extended up 21% to £1.1bn, balances of £2.8bn Credit perf in line. Medium-term guidance unch. | ||
DFS Furniture (LON:DFS) (£386m) | FY adj PBT to be slightly ahead of guidance for £25-29m. H2 order intake +10% YoY. | ||
Ashtead Technology Holdings (LON:AT.) (£363m) | PW: H1 pro-forma revenue -6% to c.£99m, adj EBITDA margin c.27.3%. FY adj EBITA now to be “modestly below” exps, but FY adj PBT exps unch. | BLACK | |
Gore Street Energy Storage Fund (LON:GSF) (£322m) | NAV -4% to 102.8p (£519m), NAV Total Return +1.1%. FY operating revenue £35.3m, EBITDA £21m. Outlook: 0.75p quarterly dividend +3p special in H2 2025. | ||
RTW Biotech Opportunities (LON:RTW) (£317m) | “Hengrui Pharma, announced positive topline data from the China Phase 3 clinical trial of HRS9531 in individuals living with obesity or overweight. The trial met both primary endpoints, demonstrating superior weight loss and a greater percentage of participants achieving at least 5% body weight reduction compared to placebo. The safety profile was favourable and consistent with other GLP-1-based treatments…” | ||
Helical (LON:HLCL) (£274m) | “We continue to deliver on our strategy of developing best-in-class buildings in highly desirable central London locations, with further progress made across our three office schemes totalling over 460,000 sq ft, all of which are due for completion in 2026.” | ||
SolGold (LON:SOLG) (£206m) | Advancing early development activities, including securing project funding, drilling, and preparing for the commencement of long-lead construction works. Cascabel Copper-Gold Project in northern Ecuador. | ||
Capital (LON:CAPD) (£168m) | Q2 Revenue -2% y-o-y to $87.4m but +22% on 25Q1. Group revenue guidance increased to $320 - 340 million and MSALABS revenue guidance increased to $55 - 65 million (up from $300 - 320 million and $50 - 60 million, respectively. | AMBER (Mark) This is the first genuinely positive statement for a while from this company. However, the share price has been strong recently and on any near-term forecasts, this looks expensive. Today’s upgrade shows that there may be considerable scope for the 2026 estimates to be beaten. The discount to TBV means that there is upside if these assets can be made productive again. I’m keeping the neutral view for the moment, though. | |
Eurasia Mining (LON:EUA) (£146m) | Dual listing has been successfully completed. | ||
Avacta (LON:AVCT) (£126m) | 10,833,333 new shares at a price of 30p. 13% discount to last night's close. Net proceeds of approximately £3.1 million used to settle the July quarterly repayment of the unsecured convertible bond. | ||
Diaceutics (LON:DXRX) (£102m) | “The expanded agreement is expected to contribute incremental service revenue in FY2025 and further strengthens Diaceutics' position as a strategic partner in the precision medicine ecosystem.” | ||
Pharos Energy (LON:PHAR) (£87.3m) | 1H production 5,642 boepd net vs 2025 production guidance of 5,000 - 6,200boepd. H1 Revenue flat at $65.3m, net cash $22.6m (31 Dec 2024: $16.5m), Capex guidance unchanged at $33-40m. | ||
Ilika (LON:IKA) (£80.5m) | “continues to develop and commercialise its two solid state battery product lines: Stereax® batteries for miniature medical devices and wireless sensors for specialist applications, and large format Goliath™ batteries for electric vehicles and consumer appliances.” | ||
Churchill China (LON:CHH) (£63m) | PW: “hospitality markets remain challenging with reduced demand for our product, particularly in export. Following a late Easter, April performance was broadly in line, however, the financial performance in May and particularly June was materially below target, meaning that the Company will deliver profitability significantly below last year at the half year…will deliver revenue and profits for the full year significantly below the prior year.” | BLACK/AMBER (Mark) | |
Zephyr Energy (LON:ZPHR) (£63m) | Zephyr continues work to deliver the first stage of gas infrastructure for the Paradox project. | ||
KEFI Gold and Copper (LON:KEFI) (£50m) | Successful implementation of our plans will result in Tulu Kapi commissioning gold production in late 2027. | ||
Iofina (LON:IOF) (£50m) | Produced 305.5 MT of crystalline iodine in 25H1, +10.6% on H1 2024 (276.1 MT). slightly higher than revised production guidance for the Period of c.300 MT. 25H2 production to be in the range of 400-440 MT. Spot price firmly above $70/kg and is expected to stay at these levels for the foreseeable future. | ||
Audioboom (LON:BOOM) (£46.2m) | HY Results, Acquisition & Placing (y’day) | H1 Revenue +3% to $35.1m. Adj EBITDA $1.8m, (24H1:$0.3m). PBT $1.3m (24H1:$1.3m loss). Acquisition of Adelicious, a UK focused podcast network for up to £10m (£4.5 million initial consideration, to be settled 60% in cash and 40% in new Ordinary Shares + up to £3.0 million of deferred consideration, + Up to £2.5 million of contingent consideration.) Funded via £3m placing at 270p (6.8% of the share capital at 3.9% discount) | |
Artisanal Spirits (LON:ART) (£35m) | Adj. EBITDA performance in H1-25, broadly in line with the prior year loss of £1m. | ||
Majestic (OFEX:MCJ) (£25m) | Planned launch of a new 50,000 sq. ft. facility in Wrexham, Wales, integral to the strategy to increase the annual volume of processed materials to 100,000 tonnes by 2030. | ||
Transense Technologies (LON:TRT) (£24m) | Revenue +33% to £5.6m, Adj. PBT +8% to £1.6m, Net cash £1.1m (FY24: £1.3m). “well placed to deliver further growth in the upcoming financial year” | ||
James Cropper (LON:CRPR) (£22.5m) | Revenue -4% to £99.3m, flat adj. EBITDA, Adj. PBT +77% to £1.3m, Net debt -17% to £12.9m. Trading in the first quarter was ahead of the Board's expectations and at a similar level to the strong start recorded in FY25. | ||
Renalytix (LON:RENX) (£22m) | “Through this partnership, MVP and Renalytix will collaborate with physician groups across MVP's network, with the goal of introducing and implementing kidneyintelX.dkd advanced risk assessment testing.” | ||
Blencowe Resources (LON:BRES) (£13m) | Successful completion of its Stage 7 drilling program at the Orom-Cross Graphite Project in Uganda | ||
Westminster (LON:WSG) (£11.7m) | Extension of contract to provide a Parliamentary Broadcast System for the parliamentary debating chamber of an East African Parliament for an additional £1.15 million. Expected to be largely, if not completely, delivered in the current financial year. | ||
Argentex (LON:AGFX) (£3.3m) | Individual Liquidity Guidance Company expected that the Individual Liquidity Guidance would be satisfied via the provision of an additional secured Revolving Credit Facility, but has not been able to secure that additional funding, nor does the Company have any other source of alternative funding or liquidity. Argentex LLP is not able to operate. Ordinary Shares suspended. | RED (Mark) [No section below] This sounds terminal, and even the paltry 2.49p takeover over that looked like a done deal is now in doubt. How this could have gone so badly wrong is a cautionary tale that probably deserves to be written once the dust has finally settled. |
* Market caps at previous trading day’s close
Roland’s Section:
Wise (LON:WISE)
Down 10% to 1,024p (£10.5bn) - Q1 FY26 Trading Update - Roland - AMBER
Strong start to the year with continued cross-border volume and customer growth
Today’s first-quarter update has met with a downbeat reception despite seemingly strong growth in volumes during the first quarter.
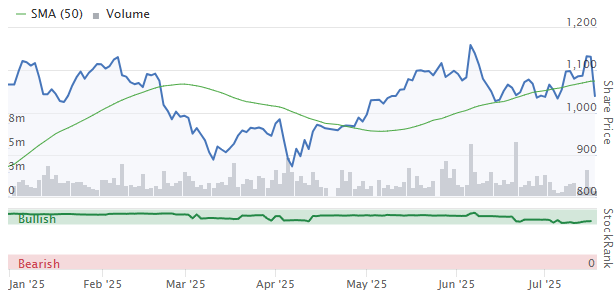
My guess is that today’s share price drop means that growth was less strong than hoped – or that investors are disappointed at the sharp drop-off in the company’s take rate (essentially its fee margin).
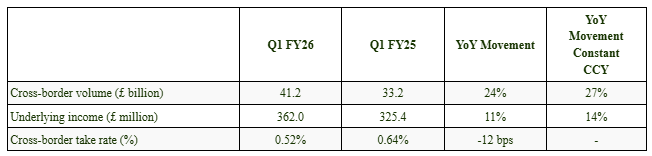
Q1 trading update - here are the key stats:
One other key metric not included in this table is customer growth:
Active customers in Q1: 9.8m (+17% YoY).
Looking at these individually and comparing growth rates to last year suggests a mixed picture to me, with a possible miss on underlying income:
Cross-border volume: 24% growth seen during Q1 is consistent with the 23% growth rate reported last year.
Active customers: this figure rose by 21% in FY25, split between Personal (+22%) and Business (+11%).
Drilling down into today’s increase of 17%, personal customers rose by 17% in Q1, while the number of business customers rose by 15%.
Personal customers still account for the majority of transactions and currency volumes, so this represents a slowdown in growth versus last year.
Underlying income (adjusted revenue): the slower rate of growth in personal customers is reflected in underlying income, which rose by +14% in constant currency. This is below the 16% rate achieved last year.
On a constant currency basis, these Q1 figures are also slightly below the 15-20% constant currency growth rate guidance included in last year’s results.
However, today’s update reiterates that this target is unchanged:
Continue to expect strong growth in underlying income in FY26, in line with our medium-term guidance of 15-20% on a constant currency basis
One quarter does not make a year and I don’t see today’s slight miss as a major concern. But perhaps it’s worth monitoring. Underlying income may also not be the truest measure of total income growth here.
The reason for this is that the underlying income metric is intended to represent the income that will be retained from customers. This includes the first 1% of any interest income earned on customer balances and any interest expense incurred.
The logic here is that Wise would like to pay surplus interest over 1% to its customers, but as I understand it does not always have the regulatory licences required to do so. Hence some of this cash is actually retained.
Last year’s results show the contrast between underlying income and real income:
Reported gross profit (includes all interest income): £1,307.8m
Underlying gross profit (includes 1% yield only): £1,025.1m
Lower interest rates could reduce this additional net interest income. Even so, I think it’s reasonable to assume that actual FY26 income and gross profit are again likely to be significantly higher than the underlying figure.
Cross-border take rate (%): Wise has always been open about its policy of passing economies of scale and other savings onto its customers. It’s probably also fair to say this is a competitive sector where cutting fees to support a land grab makes sense.
The Q1 drop of 12 basis points (0.12%) seems high, but this is a year-on-year figure and most of the reduction took place last year.
Checking back, the Q4 FY25 take rate was 0.53%, so there was only a 1bps sequential reduction in the take rate in Q1.
Outlook: Wise is perhaps taking a leaf out of the Amazon playbook by deliberately not trying to maximise its margins. Last year’s results showed an underlying pre-tax profit margin of 21%. However, the company’s medium-term guidance is for an underlying PBT margin of 13-16%, as it focuses on expanding market share and offering the most competitive pricing for its customers.
Today’s update reiterates this guidance and previous comments that FY26 margins are “expected to be around the top of this range”.
Roland’s view
I have been impressed by Wise since its 2021 IPO and remain so – this looks to me like a business with the potential to become a true platform, with massive scale and market share.
However, it’s fair to point out that in the UK at least, some companies in the currency transfer/FX sector have ended up running into problems periodically. So perhaps a measure of caution is prudent.
Wise was trading on c.30x forward earnings prior to today and 10x book value – so not exactly cheap. Even so, this relative reticence among UK investors seems to have persuaded Wise’s Board to shift its main listing to the US, leaving the UK with a secondary listing only. This plan was flagged up again today:
Last month we also announced our proposal to dual list our shares in the US and the UK, with the strategic and capital market benefits positively received by Owners. We believe the addition of a primary US listing will help us accelerate our journey to becoming 'the' network for the world's money, and ensure our mission and the interests of our customers and Owners remain deeply aligned over the long term.
Graham and Megan have both taken a neutral view of Wise at various points this year. Given that today’s growth rate appears to be at the lower end of guidance and the company is planning to move its listing abroad, I’m going to leave this view unchanged. AMBER
Coats (LON:COA)
Down 11% to 72p (£1.2bn) - Half-Year Report, Acquisition, Capital Raise - Roland - AMBER
Coats is a 250-year-old British business that’s one of the world’s leading suppliers of industrial thread for a wide range of applications, notably footwear and apparel.
The last 24 hours have seen a barrage of news flow from this business. Shortly after markets closed last night, Coats released its interim results and announced the $770m acquisition of insole specialist Ortholite and a £250m equity placing.
This morning we have confirmation that the placing completed at a moderate discount. However, investors seem to have taken a cautious view on either Coats’ results or the Ortholite deal. The firm’s share price is currently below last night’s placing level of 77p. This means that investors have the opportunity to buy shares below the level at which institutional shareholders were willing to invest last night.
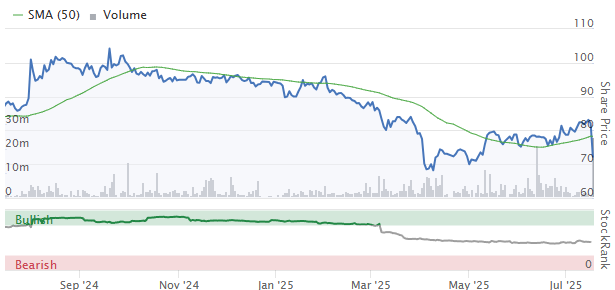
Let’s try and unpick some of this news to see whether this situation could represent an opportunity.
Half-Year Results
These results cover the six months to 30 June 2025 and do not seem to flag up any serious concerns.
While sales growth was sluggish, profits were up and show an attractive level of profitability, suggesting Coats products are valued by its customers and carry a certain level of pricing power:
Revenue flat at $705m (+2% at constant exchange rates)
Operating profit up 6.4% to $128.4m
H1 operating margin: 18.2% (H1 24: 17.1%)
Adjusted EPS up 4% to 4.7c
Net debt down 6% to $501.5m
Net debt is a little higher than I’d like, but still within reasonable limits, in my view.
Divisional results
Apparel: revenue rose by 3% to $381m on a constant currency basis. This translated into an adjusted operating profit of $78m (+11%), giving a margin of 20.5%.
Coats says that demand softened in Q2 due to uncertainty around US tariffs, with Q3 expected to be similar and Q4 potentially stronger.
Pricing and a more favourable mix supported improved margins despite these headwinds and Coats believes it is continuing to gain market share.
Footwear: revenue rose by 1% to $199m. This dropped through to an unchanged adjusted operating profit of $48m and unchanged margin of 24.1%.
Again, management comments on softer demand due to US tariff uncertainty but believe that Coats strong relationships and market share will protect its longer-term position.
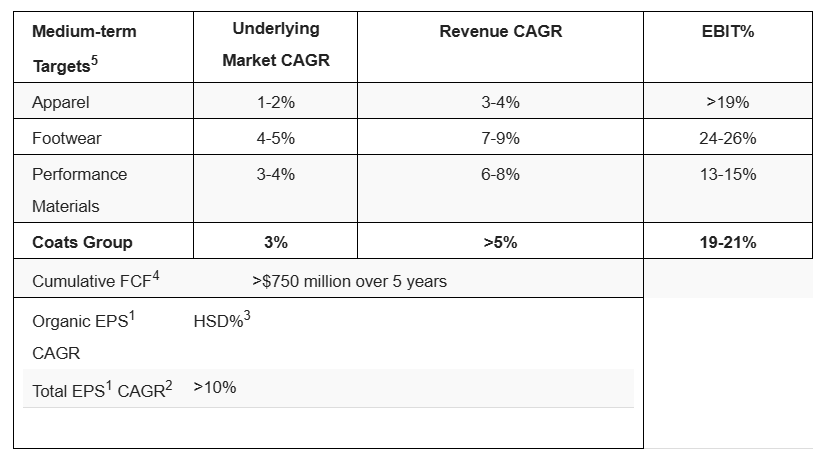
Growth rates are expected to improve to 7-9% CAGR over the medium term, outperforming the wider market thanks to “market share gains and organic expansion into adjacencies”.
Performance materials: revenue fell by 2% to $125m, leaving adjusted operating profit up by 4% at $14m. As a result, operating margin improved to 11.1% (HY 24: 10.6%).
This division provides treads used in PPE and composite products for telecoms/energy markets. The weaker revenue resulted from slower demand in Telecoms.
Medium-term expectations: looking into the future, Coats provides this useful table summarising its growth expectations for these three divisions:
Outlook
Management comments here seem clear and quite reassuring.:
The Group's full year outlook remains unchanged and is in line with current market expectations with a balanced weighting between first and second half trading overall.
With the stock trading on c.12x forward earnings prior to last night’s acquisition/today’s drop, I don’t think these results explain today's fall. Let’s move on to look at the acquisition.
Acquisition & Placing
Coats is buying US firm Ortholite Holdings LLC for an enterprise value of $770m. In addition to this, there will be a potential $10m earn-out payable based on FY25 EBITDA performance and a 5% royalty to Ortholite’s former owners on future sales of the new Cirql technology over the next five years. I have no idea whether this is likely to be a material amount.
Ortholite is described as the global market leader in premium insoles.
This acquisition is seen as a “compelling strategic fit” to help Coats become a “super tier 2” supplier of footwear components. I assume Coats and Ortholite have some customers in common, allowing them to gain a greater share of customer spend and perhaps achieve more favourable terms.
Valuation: we are told that Ortholite generated revenue of $258m and an adjusted EBITDA margin of 28% in calendar 2024. This translates to adjusted EBITDA of $72m.
That gives an EV/EBITDA valuation multiple of 10.7x, although management imply that further growth so far in 2025 has reduced this multiple to 10x.
Expected cost savings are expected to give a pro forma EV/EBITDA multiple of 8x based on $20m of cost savings to achieved by 2028. Personally, I am always very wary about relying on such assumptions, especially when they are going to take three years to realise.
Coats says that it expects the return on invested capital from this acquisition to exceed the company’s weighted average cost of capital by 2028 (i.e. probably not before). Similarly, operating margin gains of c.2% are not expected to be achieved until 2028.
On balance, this deal seems a little pricey to me, although perhaps not outrageous on a longer-term view.
Funding: Coats raised c.£250m in a placing at 77p last night. The remaining c.£340m required will come from new debt facilities with the company’s existing lenders.
As a result, the enlarged group’s net debt to EBITDA ratio is expected to be 2.2x at the end of 2025, falling below 2.0x by the end of 2026.
Roland’s view
I can see some logic in this deal.
But I can’t help feeling that in their ambition to take a step up in scale, Coats’ management are paying a fairly full price for Ortholite.
Personally, I can see why Coats shares are down today. While this deal could work out well in the long-term, in the near term it looks a little expensive and will result in elevated leverage. In my view, there is also some this deal may end up dragging on Coats’ near-term margins and returns on capital.
More broadly, large acquisitions always carry integration risk and do not always add up to more than the sum of their parts.
I think the Coats’ core threads business is proven and attractive, especially now that its historic pension liabilities have been resolved. But given the scale of this deal, I’m going to take a neutral view until we know more.
Mark’s Section:
Churchill China (LON:CHH)
Down 28% to 416p - Trading Update - Mark - BLACK/AMBER
It is a nasty profits warning here, with the company now guiding revenue and profits for the full year significantly below the prior year. Previous updates at the time of AGM and Final Results reported tough hospitality markets and did not specifically mention expectations so this should not perhaps be surprising that they have had to adjust expectations. However, the scale of the recent drop appears to have caught them by surprise:
Following a late Easter, April performance was broadly in line, however, the financial performance in May and particularly June was materially below target, meaning that the Company will deliver profitability significantly below last year at the half year. Whilst UK and USA sales have been robust, European and Rest of the World sales are tracking behind last year. The German market, in particular, has been difficult.
It has also caught shareholders by surprise, as the stock had rallied some 50% off the lows at one point. I had some inkling that the risk had increased and made a minor downgrade to our view following their AGM statement, where I said:
It’s a relatively short statement with little detail. To me it reads quite downbeat, perhaps understandably given the market backdrop. The shares have rallied quite strongly recently, together with many small caps. However, with little sign of any improvement in trading to match the 25% rise in share price, and a middling StockRank, I think this is now more of an AMBER/GREEN.
With hindsight, I wasn’t cautious enough. “Significantly” and “materially” tend to mean at least 20% in market speak. EPS was previously forecast to be flat in 2025, so taking 25% off that would now be around 44p:
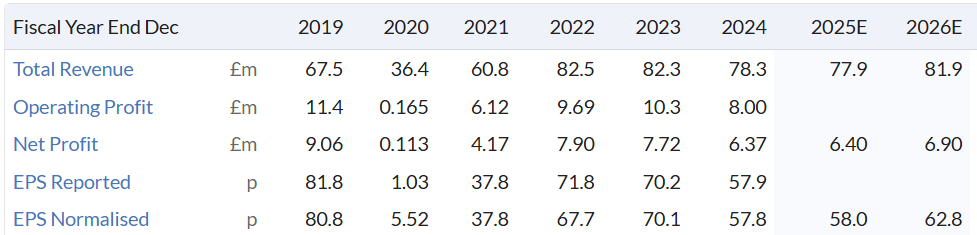
We are largely flying blind here as there is no research available to us on Research Tree.
The company’s actions are what we would expect in this situation - cost cutting:
Capital projects initiated in the first half, focussed on increasing agility and improving our cost base are now broadly complete. We have also identified capital projects to pull forward to further reduce our cost structure. New product introductions, utilising inkjet and pressure cast, are being accelerated to restore growth exploiting our investment in these processes. We continue to review our cost base on an ongoing basis whilst being mindful of retaining skills required for growth.
However, I think that last sentence is important. In a downturn, shareholders often want a company to slash their costs to maintain profitability. However, shareholders like businesses that have a long-term mindset, as this tends to generate higher shareholder value. These two often conflict. It can be expensive to let experienced, long-term employees go in a downturn. Yet, if companies take no action and a downturn lasts longer than expected the extra costs can imperil a company’s survival. This is why many investors like companies with net cash, even though it is tax-inefficient. Churchill follows the more conservative route:
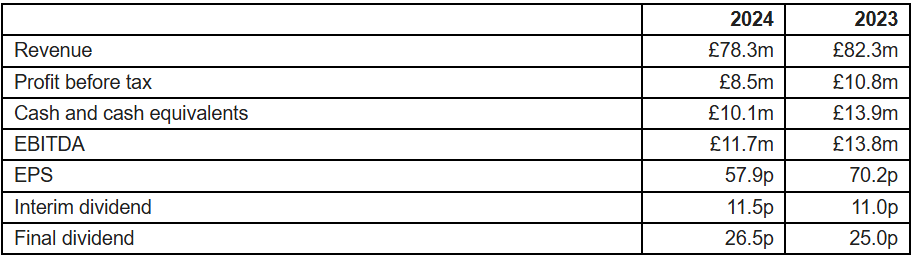
However, that net cash has been declining. The company increased its dividends in 2024, but this was paid out of balance sheet cash not free cash flow. It may not be as bad as it looks as 2024 turned out to be a year where working capital increased by around £5.3m:
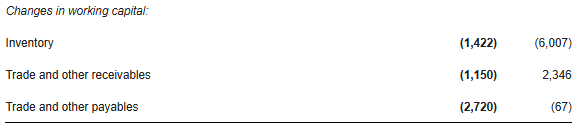
The big questions are if that working capital will reduce due to the downturn in trading, and how big the capital projects that are being pulled forward are. They recognise that cost-saving often comes with a short term capital cost. Given the cash balance, the current dividend looks safe for another year, but perhaps not much longer if we don’t see an improvement in trading. In this update they say:
We continue to prioritise a healthy cash balance which we intend to retain. We expect our markets to recover in the medium term and see no change to the long-term potential of the business.
Which suggests that they won’t be going into debt purely to keep the dividend payout.
Mark’s view
The recent market enthusiasm for this stock has clearly been misplaced and the sell off today reflects that disappointment. However, this remains a conservatively-run cyclical business that is doing the right thing in very difficult conditions for the hospitality market. Until we have access to updated forecast numbers it is hard to judge whether today’s sell-off is an underreaction or an overreaction. One thing that is worth noting is that the company is back trading at a discount to TBV, which can indicate good value for investors that are willing to take the long-term view. However, the short-term outlook looks to be for no recovery, and with the most recent month’s trading being the worst the risk is that it declines further. It would seem to be a brave (foolhardy?) new investor who jumps in today. After all, the share price is close to the level it was trading at in April, and trading is materially below what the expectations were then. The Stockopedia research suggests that the share price will be weaker for sometime on such bad news. However, I can also see existing holders who bought for an eventual recovery being reluctant to sell at a discount to TBV due to a short-term setback. A large spread means that this is not a stock to be jumping in and out of regularly. AMBER feels the best balance between value and outlook.
Capital (LON:CAPD)
Up 2% to 87p - Q2 2025 Trading Update & Increased Guidance - Mark - AMBER
The increase in guidance here is relatively minor:
Increasing 2025 Revenue Guidance: Group revenue guidance increased to $320 - 340 million and MSALABS revenue guidance increased to $55 - 65 million (up from $300 - 320 million and $50 - 60 million, respectively, as originally guided at our FY24 results);
But when your broker consensus looks like this, any increased guidance is good news!
his is driven by a recovery in Q2 results versus Q1, with expected momentum to continue into Q3. However, the revenue is still below Q2 last year. However, looking at the breakdown there is a significant variation between BUs:
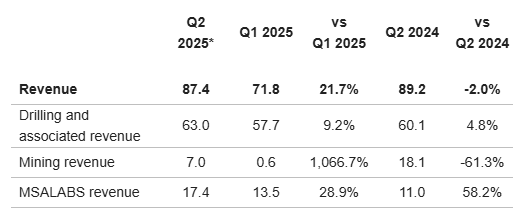
MSALABS continues to grow very strongly, and drilling revenue is higher. Driven by small improvements in both utilisation and rates:
· Fleet utilisation for the quarter increased to 74%, from 73% in Q1 2025 and from 72% in Q2 2024. Utilisation remains broadly in line with our target rate of 75% across the fleet; and
· Average monthly revenue per operating rig ("ARPOR") was $198,000 in Q2 2025, up 8.8% on Q1 2025 ($182,000) and down 4.3% on Q2 2024 ($207,000).
The improvement in performance has largely been driven by management changes at their underperforming US operations. Something the CEO fell on his sword for, and founder and Executive Chair Jamie Boyton has stepped in to sort out.
Mining is still down significantly, but this reflects the redeployment of their fleet from Sukari in Egypt and Belinga in Gabon to the Reko Diq mine in Pakistan. This fleet is now with a long-term customer and mining revenue should be ramping up here, eventually reaching previous levels.
As expected in a strong gold price environment, their equity portfolio is very strong:
The total value of investments (listed and unlisted) was $49.5 million as at 30 June 2025 up from $30.3 million as at 31 December 2024, with the portfolio recording investment gains (realised and unrealised) of $20.3 million in H1 2025;
However, they have written down their Eco Detection stake, and the clock is ticking for their option on the Predictive Discovery takeover that expires at the end of the year.
Mark’s view
This is the first genuinely positive statement for a while from this company. I had sold out recently as this has never been a highly rated company due to its capital-intensity (pun intended!), the share price had been unusually strong and on any near-term forecasts, this looks expensive:
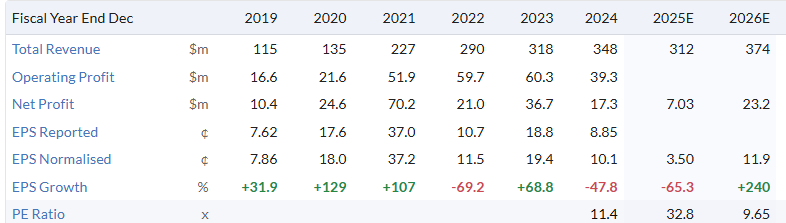
However, this may yet prove to be a mistake, as today’s upgrade shows that there may be considerable scope for the 2026 estimates to be beaten. The discount to TBV means that there is upside if these assets can be made productive again. I’m keeping the AMBER view for the moment, though.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Amusing how Capital (LON:CAPD) highlight all their mark to market gains but then treat the Eco Detection write down (massive in %age terms) as exceptional.
"Our investment in Eco Detection, which does not form part of the above investments value, is progressing toward commercialisation, though at a slower pace than expected. We have now taken a more active role within Eco Detection and have concurrently subscribed to a convertible loan at a significant discount. As a result, the value of the investment will be marked to ~$0.7 million at 30 June 2025 (from $6.3 million)."
So a $5.6m markdown which for some reason isn't offset against the other impressive investment gains
Otherwise all on the up. But can they really be trusted to be open and honest about bad news?
It's a good point, and I get how it looks but I don't think they seek to decieve with this. First up the market has never really given them any credit for the investment portfolio so it's not like the reporting here will really change much. Secondly, I think this is genuinely different to the rest which are all companies they provide driling services for (and in the case of WIA founded the company to exploit a license they owned) and they probably view it as such. Big loss in a short space of time, though, which is a bit embarrassing.
Fair comment Mark, although I do wonder how Capital (LON:CAPD) would have behaved had they made an exceptional gain on Eco Detect
Cohort (LON:CHRT) (I hold)
Big director sells following yesterdays excellent rns update. Chairman trousers c. £6m, plus chunky sells by FD and CEO. Markets not happy (down 3% at time of writing). Buy on a dip opportunity?
I think it is inevitable that after such a stellar performance directors will take opportunity to crystalise options. I think you are right it is an opportunity to buy
Cohort (LON:CHRT) Chairman is in his 70s, founded the business decades ago, needs to be allowed to benefit from his efforts at some point.
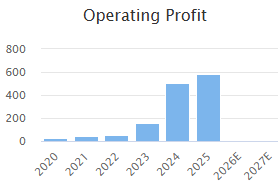
Wise (LON:WISE) Not sure what the market was expecting given the sell-off today, the Q1 update today looked like more of the same to me in terms of steady growth. Latest quarter in red in charts below.
Sure, underlying income is not matching the growth in volume or customer balances, but that's nothing new this quarter, and sacrificing income now in return for locking future competitors out on price appears to be a deliberate strategy. I'm happy to continue holding on this update.
Isn't the other way of looking at Income not matching Volume... that Wise (LON:WISE) are in a deflationary environment where it is being commoditised?
Happens many times in other industries. Telco is a good example. Price per GB of data is going down steadily. Sure, there's top line growth but it's having to run harder every year just to stand still. Is Wise and the cross border payments industry moving to that phase?
"Isn't the other way of looking at Income not matching Volume... that Wise (LON:WISE) are in a deflationary environment where it is being commoditised?"
That's certainly a possibility. I guess everyone interested in the company will have to come to their own opinion on whether Wise (LON:WISE) are passive passengers being swept up in the winds of commodisation along with everyone else, or are themselves wielding the harsh winds of commodisation as a weapon against others.
Clearly as a holder I have my opinion, but I accept it may be wrong. I'm fairly diversified, so my mistakes don't tend to do too much damage, which is fortunate since I've certainly made a fair few!
Is it just me, or seems like a lot of PW and companies warning on slowdowns next year?
I would be interested in the team's view on the acquisition by Coats (LON:COA) late yesterday. Either the deal itself or the Coats interim results appear to have gone down like a lead balloon with investors and those who took part in the placing at a 6% share price discount to yesterday's close are now under water.
Does anyone know why certain news items do not show on Stockopedia?
I literally have every news item box ticked but for Central Asia Metals (LON:CAML) the top two news items are:
but the RNS section on the company website:
Is this a glitch, or am I doing something wrong?
Thanks!
I had similar for a company yesterday - had to go to LSE RNS site
Central Asia Metals (LON:CAML) news flow closed - suggest you complain via the green button
Not sure I understand what you mean by closed?
Central Asia Metals (LON:CAML)
What I mean by closed is just that - Stocko appears to have carried every RNS until the end of June and then stopped. Others have carried on. https://www.investegate.co.uk/...
One clue is that there is a rogue RNS there from Camellia (LON:CAM) but none of those who post here can sort it - you need to use the green button.
I think it is a glitch, some trading updates, have been missing from the news, as well. Can't remember the stocks but there have been at least 2.
One was Diploma (LON:DPLM) interims results, 20 May are missing, from the news.
Diploma (LON:DPLM)
Rusty2 - The interim results are not missing they are here:
https://www.stockopedia.com/sh...
It is labelled 'Governance Notifications' under type so you need to check you have that box ticked.
Why are the interim results under "Governance Notifications"?
Looks like it is wrongly labelled, notifications should be AGM dates, result dates not the actual results.
Yes definitely some kind of ongoing bug have noticed it myself on many companies as well
Annoying but hope they are working on a fix (a large part of the value of stockopedia for me is being able to see what's happening at a glance to decide what to look into)
easyJet (LON:EZJ) have a 3rdQ TU out this morning which most of the market seems to have missed, except the Market Makers of course, down 7%. the numbers seem OK but the Outlook Statement talks of later bookings etc. etc.
Interesting to see that Future (LON:FUTR) has bounced 10% on an 'inline' update even though the numbers themselves are relatively weak. It proves that there are still one or two stocks out there where expectations are so low that any evidence of stabilised trading is sufficient to drive a decent re-rating.
Anybody know why Ocean Wilsons Holdings (LON:OCN) is down 7% today. Seems odd given tender offer effective next week at over 1500p?
Maybe trying to panic holders into tendering if they don’t have enough people doing so
Exactly the same thought, ex divi?
Ex dividend date was 26 June
Tender has now closed so shares are without the attraction of a buyback.
DPLM Blimey, it's the gift that keeps on giving. Organic revenues +10% is impressive.
I hold, although not without some nervousness. I've held since 2015. It just goes to show that if you hold a steady compounder for a long time, it can do good things for your portfolio.
It's far from cheap, having a PE of 28 and a Value score of 10.
It's the top holding of Smithson Investment Trust (LON:SSON) (FundSmith's little brother) as at the end of May. Curiously, it's not in the top 10 according to Hargreaves Lansdown. I'm not sure which is the most current. SSON seem to be more active in turning over their portfolio than formerly.
A polite reminder to all contributors to use @ preceding the ticker code eg @ DPLM which converts to Diploma (LON:DPLM) which allows immediate recognition of the company name and an instant link to the stock report.
Congratulations Mark on such a successful pick and long holding period. I've long been a fan of Diploma (LON:DPLM) and it is one of my top and key holdings. I first bought in in March 2011 at £2.64! Sadly those were the days I stupidly used stop losses so was shaken out then in and out in 2011, 2013, 14 and 15. Bought in again afresh from zero holdings in 2018 and added to ever since. Always regretted those stop losses, the £2.64 buy would look lovely in my portfolio now.
Many thanks.
Ah yes. I held DPLM before my current holding, but sold out when I thought the shares were "high enough". Fortunately I decided to buy back in at a later date. If only I had decided to hold throughout my initial purchase I would have had a 10-bagger on my hands. Now I'm up "only" a little more than 600%.
Other stocks I held but sold way too early were JD Sports Fashion (LON:JD.) and Games Workshop (LON:GAW). I'm sure there are others. Oh man, the money I left on the table with those!
Gore Street Energy Storage Fund (LON:GSF) have a IMC at 11:00 where hopefully more light will be thrown on dividend and the shareholder meeting requisition by a major shareholder to change the board.
The word Gore seems appropriate!
Your not wrong Spender. Submitted 5 questions, not one answered and finished the meeting 10 minutes early. If I was a cynic I would say the questions submitted and answered were set internally. Probably a decent chance they will get bid for though IMO
Decided to sell out of Gore Street Energy Storage Fund (LON:GSF) this afternoon for a scratch trade / small profit including the last few quarters divi's and the upcoming one. I originally got in for the yield and liked that it was growing the asset base but the way they have gone about reducing the divi sucks and even more so because the majority of the payout's were H2 weighted. Anyhow hopefully for the holders a buyer steps up with a good premium or a bidding war starts but I've recycled the funds into Harbour Energy (LON:HBR) and looking to increase that position sub £2 as much as I can.
Sounds a good plan UncleG. I am holding on for now as there was an implication that earnings might be picking up and dividend might be higher. Especially if RM give them a good kick. See the slide they showed.
Hi Charles, I hope RM do put the Doc Martens on and give them a right good kicking ... they deserve it. That being said they have been good with sticking to the plans on expanding and completing the build outs of the asset base. I liked that side of things and still do. I thought the IMC went well today but the red mist came over me this afternoon and I thought I was going to be under water again for the second time with this for the foreseeable and getting paid less to wait.
Thanks very much to you and all the knowledgeable contributors for the work you guys do / share on the Monthly IT update forum. It's a great read and has really helped me a lot.
It is frustrating, I like what GSF are trying to do in terms of the business model. They have just let shareholders down , maybe by paying uncovered dividends for a few years, I guess to try and keep the share price up- which failed . They should have taken steps earlier, cutting £1m off management fees now is a tad late.
Thanks for the kind words on the monthly forum, we try.
That's why I always preferred when Tamzin did company presentations on PI World, she would objectively select and present the questions without advance notice to the company. IMC allows the companies to present to screen and select the questions to answer (ie. the easy ones). When they say that looks like it and there's no more questions to answer you can't tell if they are being misleading. Great that IMC provide us an opportunity to see the company presentations but the format needs to change so companies are challenged and grilled appropriately.
Wildshot GSF were- none of my 5 questions were raised and closed it 10 mins early
Mycelx Technologies (LON:MYX) I hold
Anyone else interested in today's trading update? Very interesting technology for removing contaminants from liquids.
"The Company completed a successful trial with a large oil producer which included both the MYCELX coalescer and REGEN equipment and delivered higher quality, recycled water and oil recovery volumes which would equate to millions of dollars in revenue per year for the producer in addition to its production revenue."
Churchill China (LON:CHH) profit warning - Europe and ROW sales have been hit (especially Germany) - I am clinging on to the fact that they have a strong balance sheet and it is a recovery play (having substantially derated already) but this may now take longer than anticipated. As a holder I'd be interested in opinions here.
<EDIT> Double PW day today.. Ashtead Technology Holdings (LON:AT.) being the other. :(
Then there is Ocado (LON:OCDO)
Still cashflow negative. As ever, they intend to remedy that next year....
There is an interesting bit in the statement tucked away after all the efforts to make the numbers look better:
"It has signed a further deal for a small installation of Ocado's "OSRS" fulfilment solution at an apparel fulfilment site for a large international retailer. The expansion to apparel fulfillment highlights another substantial opportunity for Ocado's technology beyond grocery retail."
Ocado (LON:OCDO) is down about 90% in the last five years. Needs to fall another 90% to reach fair value.
A big tragedy, this is one of the few British technology companies. But it seems that its robots are more costly than a human picking the product off the shelf.
IMO Ocado (LON:OCDO) competitive advanatage was that they had raised mountains of cash from shareholders at incredibly low expected returns. This enabled them to fund all the capex for customers in return for their "technology". After all, if you were a heavily indebted major retailer with a reasonably high cost of capital and someone came in and offered to fund all your distribution centre capex for online delivery that you would have struggled to finance, would you not jump at the chance?
This means that the company should be priced like a bank i.e. a modest disount to TBV. So I think you are too pessimistic with 90% off to fair value, 80% down from here is more like it ;-)
"IMO Ocado (LON:OCDO) competitive advanatage was that they had raised mountains of cash from shareholders at incredibly low expected returns."
Aren't the directors former Goldman Sachs bankers, or something? Careful, lest the vampire squids rip your face off.
The vendor financing bit I agree with entirely. Now Ocado (LON:OCDO) is having to refinance its own debt the world is not such a wonderful place.
And then you wonder why they have to offer exclusivity periods in overseas territories in order to sell their customer fulfillment centres. Does that mean the technology isn't convincing enough (or margin enhancing enough) to sell itself without the exclusivity/vendor finance sweeteners?
Ocado is in the business of providing solutions that get products from retailers to consumers (or not, as my wife once discovered just before trying to feed 12 guest at my birthday dinner....). Does Ford agree not to sell delivery vans to Sainsburys for a year each time the Tesco fleet manager puts in an big order?
Every year or so I take a fresh look and then decide to steer clear. There was a point in the summer last year where OCDO was trading close to the Price/Sales ratio of Walmart (NYQ:WMT) at around 1.2x which got my attention. Deconsolidating the M&S JV has of course changed the picture, but you get my point.
But I suspect the day will come when the technology matures sufficiently for it to become a must-have for all major retailers if they want to stay in business. Will retailers have developed their own internal solutions by then (in Amazon's case I suspect the answer is yes), will there be competing technology providers (hello Autostore, Brightpick et al) and how much of OCDO's "moat" is genuinely patent protected (as opposed to know-how that other's can pick up)?
Given we've seen retailers delay their CFC roll-out (Krogers) and reverse out of partnering with OCDO (John Lewis, Morrissons) it clearly isn't straight-forward, and the dispute with M&S going public is another sign that partnering with OCDO is not always the happiest of experiences.
But is the technology worth something in its own right and competitive without the vendor financing?
Or have they buried £billions of capex into a black hole?
I wish I knew.
Hmmm.... Ocado (LON:OCDO) branching out to other ecommerce sectors...
They only have to look at what a disaster Ingenuity has been, which was part of THG (LON:THG) until last year.
(I hold THG in the Boon Fund)
Qinetiq (LON:QQ.) has a Q1 trading update out.
Given Qinetiq (LON:QQ.) has displayed a tendency to snatch defeat from the jaws of victory in recent trading statements I suspect there will be some relief that everything is in line, and US order flow is described as "good".
3% organic growth is hardly the defence spending boom we keep hearing about though. Record back order book of £5bn is more promising.
Wise (LON:WISE) update looks pretty solid to me, Would be very interested in the Team's view.
Down 3.5% at the open! Perhaps due to less revenue per customer?
Wise (LON:WISE) it's been quite a feature lately. People selling out on results that are fine but not stellar. Maybe short-term traders looking for better options.
WISE I heard a fund manager talk enthusiastically about WISE earlier this year (can't remember who). He thought they'd be able to capture a niche position. Margins might compress, and he was fine with that, as with the valuation (albeit on a PE of 30).
Their returns on capital are high. What's interesting to note is that their revenues have gone up, but their share count has reduced.
I have the suspicion that WISE is onto something major. BWTFDIK. I don't hold.
A few interesting thought pieces about Wise (LON:WISE) at https://hollandadvisors.co.uk in their company research section. Agree that this looks like one of the more interesting companies on the LSE right now, with significant runway potential. Valuation does not look outrageous relative to the potential growth available, assuming they continue to deliver
the Wise (LON:WISE) story sounds good until you consider that they use FX hedging like Argentex (LON:AGFX) . So there has to be a risk that market volatility might blow up the company. How can an outsider quantify the risk?
the Wise (LON:WISE) story sounds good until you consider that they use FX hedging like Argentex (LON:AGFX) . So there has to be a risk that market volatility might blow up the company. How can an outsider quantify the risk?
Why do you think Wise use FX hedging?
As far as I'm aware they don't, but if that's wrong it'd be good to understand how and where it's used.
timarr
WISE 2023 Annual Report p76
RE: Wise (LON:WISE) versus Argentex (LON:AGFX) hedging policies.
The Wise model isn't without risk but it's very different from Argentex's:
The hedging issues that brought Argentex down wouldn't impact Wise - and given that they both went through the same period of heightened volatility we have some empirical evidence that's a valid assertion.
Still, there's never absolute certainly when dealing with risk adjusted models.
timarr
Wise (LON:WISE) .. as far as I'm aware Wise doesn't offer forward dated FX transactions, which as Timarr alludes, is where the collateral issue arises. Wise also uses vast pools of liquidity in each currency and intra day hedging to minimise FX exposure... Its scale helps here and also drives its desire to be the cheapest provider ( Amazon model ) ... The recent interbank contracts were a game changing signal for me ( I hold, 2nd largest position ).... Comments from founder below :
We started out because of the exorbitant fees charged by banks - and we’ve always charged as little as we can. Adding up all the fees, we’re typically eight times cheaper than banks. Long term, we’re sure that prices will only move in one direction.
Moving money is like sending an email: we’re moving bits and bytes around so the marginal cost will approach zero. Can we eventually make it free? We're going to try. That doesn’t mean we won’t be a profit-making business. We believe that being in a strong financial position is the only way to guarantee we can be around for decades to come. That’s how we can help the banking sector become known for transparency and fairness rather than greed.
People are living increasingly global lives. The tools that are available to us to manage our money are outdated and not fit for purpose.
I agree Wise (LON:WISE) results look solid. The share price reaction looks churlish. Perhaps I am being naive in expecting a big bounce when the NYSE listing sucks in US buyers. I hold.
I bought (LON:WISE) recently on my experience as a customer. I work internationally so have some (modest) international money transfers. WISE absolutely trounce Western Union for rates and simplicity of doing business. Did it via Monzo btw. Think I may top up today.
Anyone following Coats (LON:COA) here and any views on the splurge of news yesterday ? I opened up on this a couple of weeks ago as it was one of the 25 co's passing my combined "Fix the Odds" QM & VM screen (along with well discussed names like Serabi Gold (LON:SRB) Ramsdens Holdings (LON:RFX) etc.) and was impressed with the new CEO loading up - all this in advance of the TU which was released yesterday. However, this was somewhat overtaken by events with the purchase announced of Ortholite for $770m and a placing (incl retail offer) which seems to have got away well. Bit naughty releasing this news at 17:45 with an 18:30 deadline but I applied anyhoo for about 15% of my current holding - no news on AJBell yet as to my allocation but I'm encouraged to see the directors doing ~£700k worth of the ~£2.9m retail offering.
The TU seemed strong but I assume all focus will be on this acquisition this morning, so not sure which way this will swing - I'm in for the ride whatever !
Morning Mark.
Perhaps you could add NCC (LON:NCC) to today's list following the late announcement yesterday: https://www.londonstockexchang...
As usual it was stirred up by Sky News : https://news.sky.com/story/lon...
There is little new here. Christopher Mills spelt it out in January - go to https://www.stockopedia.com/co... click "To view click here" in the first line and go to 55 mins in.
The Interims on 19/6 said "As announced on 28 April 2025, the Group is investigating options for its Escode business including a potential sale and is now holding discussions with interested parties".
Good spot, will do, thanks. Also Audioboom (LON:BOOM) & Coats (LON:COA) had late news yesterday so we'll include those.
Great - had just posted to see if anyone was into Coats (LON:COA) so look forward to your thoughts.
Morning Mark. Unless I'm very much mistaken, it's Thursday the 17th today. :)
oops yes, sorry