Daily Stock Market Report (Thu 9th October 2025) - TET, HSW, IGP, DFCH, POLR

Good morning!
07:48 - Agenda complete
13:30 - Report complete
Spreadsheet accompanying this report: link (last updated to: 5th September).
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
Lloyds Banking (LON:LLOY) (£51.2bn) | “Uncertainties remain outstanding… but based on our initial analysis… an additional provision is likely to be required which may be material.” | ||
Johnson Matthey (LON:JMAT) (£3.44bn) | Catalyst Technologies (sale agreed in May) now classified as discontinued. TU: outlook at higher end of initial guidance. | ||
Derwent London (LON:DLN) (£1.92bn) | 25 Baker St. “recently reached practical completion. This marks an important milestone… delivering a yield… of 7.5% and an ungeared IRR of 11.3%.” | ||
Hammerson (LON:HMSO) (£1.51bn) | €350m bond priced at 3.5%. 1st stage of early refinancing of €700m 1.75% bond. Results in downgrade to FY25 earnings expectation by £1m to £101m. | ||
Grainger (LON:GRI) (£1.39bn) | Occupancy high at 98.1%. LfL rental growth in line. On track to deliver 50% earnings growth from FY24 to FY29. | ||
SSP (LON:SSPG) (£1.34bn) | £100m buyback announced “reflecting a healthy balance sheet position and highlighting the Board's confidence in the Company's prospects into FY26.” | ||
Volution (LON:FAN) (£1.29bn) | Rev +20.6%, adj. PBT +18.7% (£83.9m). Organic growth 5.7%. “The new year has started well.” | ||
Polar Capital Holdings (LON:POLR) (£551m) | Net outflows £58m. AUM increases 15% q/q to £26.7bn. “Equity markets have delivered robust returns… Our meaningful exposure to technology has enabled us to benefit from this favourable backdrop.” | AMBER/GREEN (Mark)
With very little in the way of outflows, strong fund performance and some big upgrades in EPS from research provider Equity Development, it is tempting to upgrade our view. This now trades on sector averages for earnings but is outperforming its peers. However, it is still on a significant premium to others on metrics such as Market Cap/AUM, meaning it is at risk if its focus on the technology sector goes from a tailwind to a headwind. There are few storm clouds on the horizon at the moment, though, so it makes sense to remain mostly positive. | |
Central Asia Metals (LON:CAML) (£276m) | Production guidance for FY 2025 maintained. | ||
Anglo Asian Mining (LON:AAZ) (£237m) | Revised guidance: copper of 8,100 to 9,000 tonnes, gold of 25k to 28k oz. (Guidance in February: copper 6,500-8,100, gold 28k-33k.) | ||
Secure Trust Bank (LON:STB) (£231m) | Q3 Net lending book - 4.1% largely driven by the Vehicle Finance run-off. Core net lending down 2.2% QoQ to £3,202m, but +10.3% YoY. Vehicle Finance -15.8% QoQ to £469m, -12.4% YoY. Deposits -1.7% QoQ to £3,449m, but +9.8% YoY . FY25 underlying profit before tax now expected to be up to £9m below market expectations, due to Vehicle Finance performance. | BLACK | |
S&U (LON:SUS) (£208m) | Revenue -14% to £51.8m, PBT +22% to £15.6m, Basic EPS +21% to 95.5p, interim dividend +17% to 35p, Net borrowing -25% to £180m. Recovery underway. | ||
Mobico (LON:MCG) (£170m) | ALSA JV subsidiary has won an eight-year capital-light contract in the KSA, with a total contract value of €500 million revenue. The contract includes the operation of 156 vehicles, 126 of which will be electric, serving Qiddiya, a new city on the outskirts of Riyadh. | ||
Treatt (LON:TET) (£166m) | Heritage revenue -15%, Premium revenue -13% and New revenue -17%, due to continued headwinds. FY25 financial performance is expected to be within the revised management expectations (£130.6m revenue, PBTE £10.0m). Net debt £5.9m (FY24: £0.7m net debt) | PINK (Mark) [no section below] This is an in line update, following two profit warnings, so that has to be viewed positively in some way. However, I can’t help feeling the mid-teens declining revenue in all their segments makes for rather grim reading. Of course, very little of this matters as the company currently has a recommended offer of 290p per share. Many investors will see this offer as too cheap, especially if they bought some time ago and will be crystallising a loss. However, this trading update highlights that if the bid is voted down, the share price will likely decline precipitously from here. Perhaps that’s the key message management wants to get across? | |
Hostelworld (LON:HSW) (£148m) | Q3 generated revenue +5% (+2% bookings, +3% booking value), Commission rate +16.3%, Direct marketing 47% of revenue (25H1: 51%). YTD net revenue flat at €72.6m, YTD Adj. EBITDA -13% to €15.4m, Net cash €6.6m. FY2025 adjusted EBITDA guidance remains in line with the current market consensus of €19.8m. | GREEN (Graham holds) Upgrading this by one notch as I’m hoping that the risk of a profit warning has receded after this in-line update, with only one quarter left to potentially disappoint investors. The company is now a dividend payer and a buyer of its own shares, and trades at a modest earnings multiple of c. 10x, despite building out its own social network and having what I perceive as a very strong brand in the budget accommodation sector. Growth is not too exciting yet, but I see a lot of potential here. | |
Motorpoint (LON:MOTR) (£131m) | Retail volumes +8.9%, Revenue +15% to £648m, PBT +80% to £3.6m. Net debt £0.5m. Remains confident that the Group will achieve its expectations for the full year. | ||
Intercede (LON:IGP) (£104m) | H1 Revenue -3.9% to £8.21m, due to delays in contract awards. Cash £17.8m (31 March: £18.7m). Full-year financial performance will be in line with current market expectations. | AMBER/RED (Mark) This is an in line update, but one that shows that a higher-than-usual H2-weighting is required to hit the FY numbers. Even if they hit those figures, this is another year of negligible EPS growth. Their transition to SaaS sales is gaining some traction, but the overall figures are tiny, especially considering many software companies made this a priority over a decade ago. All this makes their 30x P/E increasingly hard to justify, even considering their good products and strong balance sheet. We were neutral on the company when it was a “High Flyer”, but now it is a "Falling Star”, it looks the right time to take a slightly more negative stance. | |
Distribution Finance Capital Holdings (LON:DFCH) (£91.7m) | Q3 New loan origination 30% to £460m, Loan Book +26% to £759m, Non-performing loans £10.4m, 1.4% of loan book. Confident of achieving full year results in-line with market expectations. | GREEN (Graham) [no section below] DFCH gave us a very nice upgrade in September and I note that the EPS forecast on the StockReport has increased from 5.9p to 7.3p for the current year. The only thing that was missing was a big upgrade for next year, and that has not materialised yet - perhaps some investors were hoping for this today, given the slight fall in the share price today. It is still up by some 44% year-to-date thanks to strong execution and above all very fast growth at this specialist lender. Today’s update reminds us that growth is not risk-free, as I note a jump in the number of dealers who are in arrears, from 25 a year ago to 42 today. Total arrears and amounts in recovery have increased from 0.9% a year to 1.5% of the loan book. The company reassures us that this is “well within expectations” but of course the company and its shareholders must remain vigilant on these metrics. More positively, asset finance (direct lending to buyers) is rolling out and growing, now with a £10m loan book, and this should be a source of high returns. Overall, I remain comfortable with my positive stance here due to an attractive mix of cheapness and growth. And as Roland noted last time, it has done this with a high CET1 ratio, implying a sturdy balance sheet. | |
Zephyr Energy (LON:ZPHR) (£67.2m) | Zephyr will acquire assets and the Investor will make available up to US$100 million to fund 100% of the capital expenditure related to the drilling, completing and equipping of those assets. | ||
Metals One (LON:MET1) (£30.4m) | CA$500,000 investment Fidelity Minerals Corp via 5m shares in private placement. | ||
Challenger Energy (LON:CEG) (£28.7m) | Offer by Sintana Energy Inc for 0.4705 New Sintana Shares for each Challenger Share. Represents an implied value of 16.61 pence per Challenger Share based on C$0.66 Sinatra share price at close, 44% premium. | PINK | |
Petro Matad (LON:MATD) (£15.3m) | Gazelle-1 Well 16bobd on a ⅛” choke, 300bobp on a ¼” choke, will be completed for production. Gobi Bear-1 well delayed to April 2026. Heron-2 well pump fitted to perform well clean out. | ||
Cloudbreak Discovery (LON:CDL) (£15.1m) | Exclusive option for £10k for a two month option period with 56,000,000 new ordinary shares to be issued no later than 31 January 2026 in the event that the option is exercised. |
* Market caps at previous trading day’s close
Graham’s Section:
Hostelworld (LON:HSW)
Up 5% to 123.6p - Trading Statement - Graham (I hold) - GREEN
At the time of publication, Graham has a long position in HSW.
This is an in line update that has been warmly received by the market, as they say:
Improved Q3 Trading and Solid YTD Performance
It appears that the market generally - and I - were concerned about the company’s ability to meet forecasts, given the extent of the seasonal H2 weighting that was baked into forecasts. (See here for our coverage of the interim results, when the company reported EBITDA of €7.4m vs. full-year forecast €19.9m). Today the company reports that the consensus EBITDA estimate is €19.8m, and it expects to hit this.
Some key points for Q3:
Q3 “generated revenue” +5% (number of bookings up 2%, average booking value up 3%). (NB. like other companies in the holiday sector, Hostelworld takes money in advance from travellers, but doesn’t book the revenue until later. This means that in any given period, actual revenue will depend on bookings made in prior periods. I think that “generated revenue” is supposed to show us the value of bookings made in the period itself, less cancellations.)
Elevate - the tool we discussed last time, that allows hostel operators to pay more for increased visibility - has boosted the commission rate year-on-year from 15.2% to 16.3%.
Another key KPI is direct marketing costs as a percentage of net revenue, and it falls to 47% (vs. 51% in H1 and 49% in Q3 last year).
Turning to year-to-date figures, revenue is broadly flat and EBITDA is down:
YTD Adjusted EBITDA for the period was €15.4m with a 21% margin (YTD 2024: €17.8m and 25%), reflecting planned investments in growth initiatives and the timing of deferred revenue.
So with the summer months out of the way, 78% of the full-year EBITDA forecast is in the bag. I guess there’s still the possibility of a profit warning at this late stage, but at least there are now strong limits on how severe a warning could be!
Net cash is €6.6m, up by half a million since the end of H1.
CEO Gary Morrison notes “the continued popularity of low-cost destinations”, which has been a headwind here for some time. At least hostel travellers are continuing to travel, even if they are remaining extremely budget-conscious! He concludes:
Looking ahead, we are on schedule to launch our social network monetisation and the provision of budget accommodation initiatives in the fourth quarter. The timely delivery of these foundational initiatives is a key step towards delivering our growth strategy, as set out at our Capital Markets Day.
Graham’s view
I think there’s a view among some investors that Hostelworld should be substantially more successful than it already is. From my point of view, having a small stake in this, I do see untapped potential. I definitely see it as a growth opportunity rather than a boring value play (even if it’s rated as a value stock) and I have no real interest in the dividend.
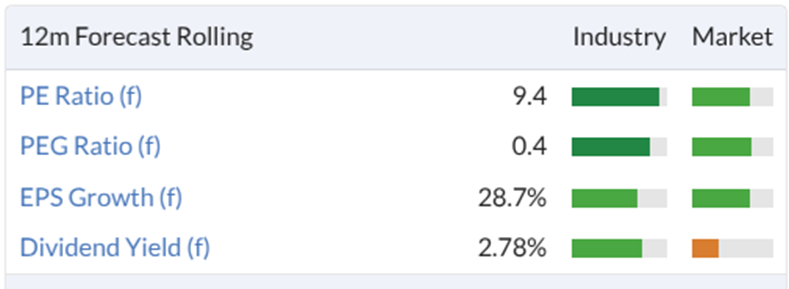
Having said that, I am of course delighted that the company is now in strong enough financial shape to afford dividends and buybacks. But if management could identify more high-return investments in terms of developing its app and its capabilities, I would be even happier!
The year-on-year downturn in EBITDA doesn’t particularly concern me - I’m happy to give management the benefit of the doubt on the investments that they are making in their new social network and in expansion to other types of budget accommodation. As the risk of a profit warning should hopefully have receded, I’ll tentatively upgrade this to GREEN.
Mark’s Section:
Intercede (LON:IGP)
Down 10% at 158p - Trading Update, New Contract awards and Renewals - Mark - AMBER/RED
When Roland looked at the Final Results from this identity verification specialist in June, revenue was down double-digits and adjusted EPS down significantly. However, this was actually slightly ahead of expectations, as FY24 benefitted from a large one-off license sale. The company did communicate that this contract was an exceptional order and deemed 'one-off' at the time, and the broker’s forecasts reflected this. However, looking at the price chart during that reporting period, I’m not sure that message really landed with investors:
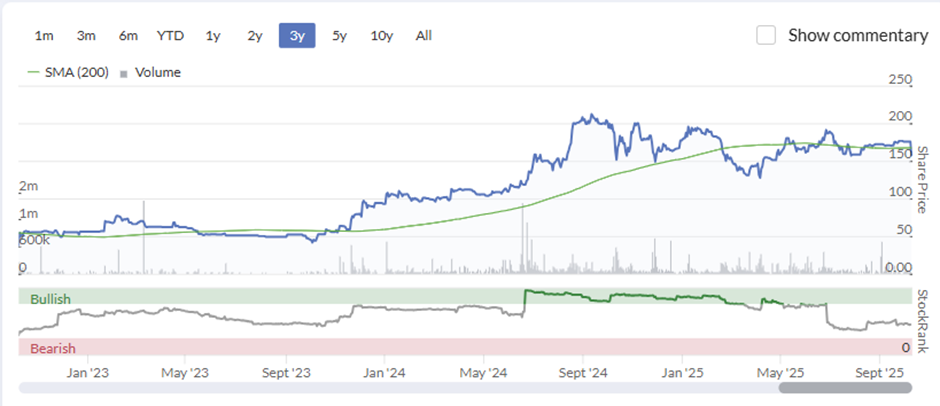
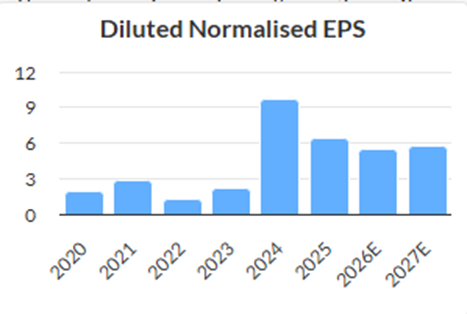
At the time of this year’s Final Results, their broker upgraded FY26 EPS estimates to 5.5p, and today they say:
Given the underlying momentum being seen by the Group, the Board remains confident in the Group's short, medium and long-term growth trajectory and maintains that full-year financial performance will be in line with current market expectations.
However, put into context, the in-line they refer to is another declining EPS figure:
When they refer to “underlying momentum” they presumably want investors to infer some kind of positive movement, rather than a continuation of the overall trend in this H1 update for declining revenue:
The Group expects revenues for H1 FY26 to be approximately £8.21 million (H1 FY25: £8.54 million), representing a year-on-year decrease of 3.9% or a decrease of 4.2% on a constant currency basis.
SaaS Revenue:
As Roland also pointed out in his review of the Final Results, there is some attempt to move to a more subscription-based revenue model, which may dampen short-term revenue, at the benefit of a more sustainable ongoing sales. Today’s trading update shows some sign of this:
Reported revenues includes licence revenue which increased by 65.5% to £1.44 million (H1 FY: £0.87 million) and comprises perpetual licence income of £1.08 million (up 63.6% from H1 FY25: £0.66 million) and subscription licence income of £0.36 million (up 71.4% from H1 FY25: £0.21 million).
But the numbers here are absolutely tiny. That’s an annualised subscription licence income of £0.72m, versus a market cap of over £100m at last night’s close. I also can’t help feeling that 2025 can’t be the first time they realised that there may be some benefit to a SaaS revenue model. Microsoft made the shift to SaaS 14 years ago, in 2011. Many software companies followed this trend and started moving customers to a subscription model a decade ago.
Current trading:
Some of this weakness is put down to:
…temporary delays in some contract awards, primarily attributable to the US federal market. These delays, combined with adverse exchange rate movements and changes in revenue mix, have particularly affected reported US dollar revenues in Q2 of the period.
This is understandable, with the political environment in the US, now is not a good time to be reliant on US government contracts. However, I’m not sure I get the FX point. Most companies with significant dollar revenues but reporting in sterling have nominal movements in revenue greater than constant currency movements. Here constant currency has declined more than reported currency, suggesting that they have actually benefitted from currency movements.
This is also a contract update. They list 11 contract wins or renewals but the average contract value is just $240k. Q2 contract wins and renewals work out to be just 13% of FY26 forecast revenue. This might be quite reasonable if these are all subscription licence income, but the above figures suggest that very few of them will be. Their broker, Cavendish, also points out that a higher H2-weighting is required:
Revenue of £8.2m for 1H26 represents 44% of FY expectations (1H25: 48%), leading to free cash generation of £0.9m, representing 42% (1H25: £-0.7m; 2H25 £+2.9m) of the £2.2m forecast for FY26E, excluding settlement of £1.8m cash relating to the growth scheme award, which vested in July.
Share awards:
Just looking at that share award briefly, it seems the Group CEO received:
· The payment of £1.8 million gross in cash; and
· The issue to Mr Van de Leest of 743,095 ordinary shares in Intercede Group plc, based on the closing share price of an Intercede Share of 173.5p on 7 July 2025, being the day before receipt of the put option (the "New Ordinary Shares").
The criterion for this award appears to have been entirely based on share price, so he was the big winner from shareholders’ exuberance around the one-off $6.6m order in 2024, as it made him £3.09m!
Forecasts:
Looking further out, Cavendish see revenue growth finally being reflected in an EPS forecast rising to 7.4p in FY28, but I rarely put much faith in forecasts that far in the future. All the academic evidence suggests that they are little better than guesswork out that far.
Balance sheet:
When it comes to the balance sheet, things look better:
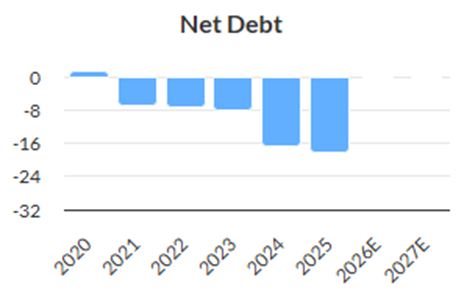
As at 30 September 2025, gross cash balances stood at £17.8 million (30 September 2024: £16.2 million), which includes the payment of £1.8 million on the vesting of a share award as announced on 22 July 2025. Cash balances were £18.7 million as at 31 March 2025. The Group continues to operate with no debt.
Like many software companies, they run with negative working capital, but not exceptionally so. At the year end, there was around £8m of deferred revenue, but as long as revenue doesn’t decline too quickly, this is likely to remain around this level, meaning this cash is available for acquisitions that may improve their growth credentials. However, they have not been short of cash in the past, and have not found something that is the right fit:
Valuation:
A forward P/E of 30 on 2027 EPS would be punchy for any company, let alone one reporting declining H1 revenue:
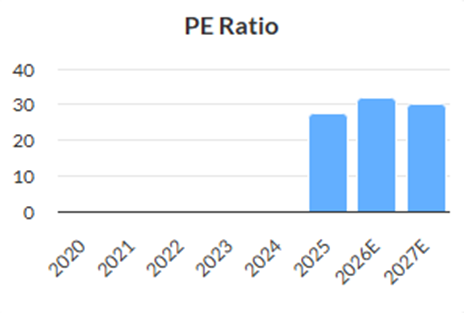
Taking account of today’s 10% fall in share price and if I adjust the c.20% of the market cap in cash, this comes out as an adjusted P/E of around 21. However, this still looks materially overvalued for a company with negligible forecast EPS growth. They need to be significantly exceeding market expectations to justify this rating, and in-line with a higher-than usual H2 weighting just doesn’t cut it.
Mark’s view
What starts as an in line trading update gets worse as you go through it, and I can see why the shares are down 10% today. This is not a terrible company; it has genuinely good products in an in-demand area, and a strong balance sheet. It is no surprise that this is a top-quartile Quality Rank stock. However, it appears to be struggling to generate enough contract wins or ongoing SaaS revenue to generate bottom-line growth. As such, it looks to be overvalued on a forward P/E of around 30. Investors appear to have got a little carried away after a big one-off deal in 2024 generated exceptional profits and this has yet to meaningfully revert to a valuation based on the underlying trend. Something the very low Value Rank confirms:
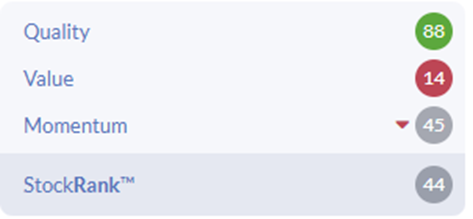
When Roland looked at this in June, it had a Momentum Rank of 69 and was classified as a “High Flyer”. However, with that Momentum Rank dropping to 45, and likely to drop further after today’s price action is assimilated, and now classified a “Falling Star” it makes sense to take a more negative view of AMBER/RED.
Polar Capital Holdings (LON:POLR)
Up 5% at 567p - AuM Update - Mark - AMBER/GREEN
With both of this week’s quarterly updates from Impax and Liontrust (see DSMRs here & here) not being particularly well-received by the market, lots of eyes were on this morning’s Polar Capital AUM update:
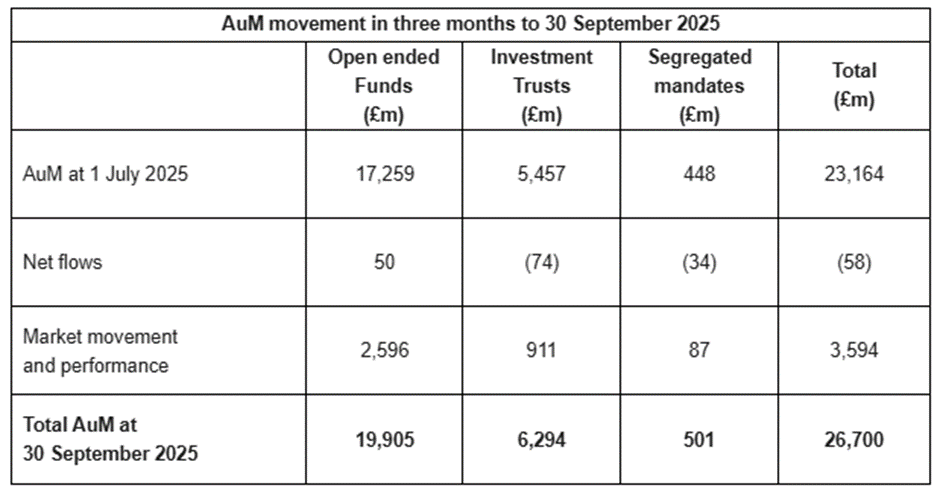
With net outflows of just £58m at Polar, versus £1.09bn for Liontrust and £1.4bn for Impax (both around 5% of AUM), investors have certainly maintained a higher view of Polar’s funds. And you can certainly see why. Whereas Impax offset the outflows with a roughly 4% investment performance, and Liontrust 5%, Polar generated almost double that at 9%.
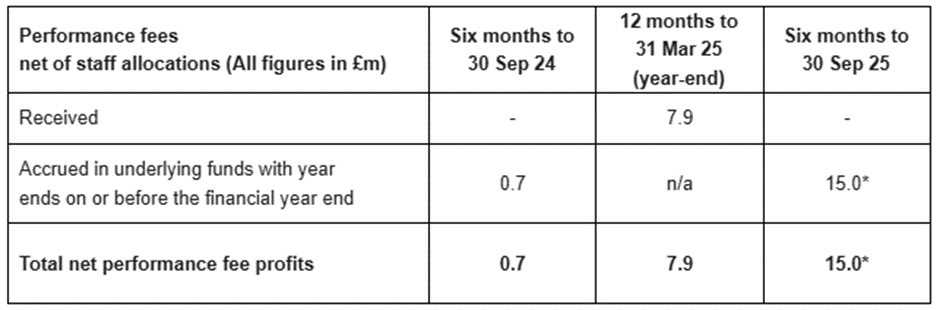
Short-term performance isn’t just important for AUM flows (despite much evidence that it damages long-term returns, fund investors continue to largely invest on short-term performance), it generates performance fees. These make asset managers geared plays on the underlying assets, and it is good news for shareholders that performance fees are rising strongly:
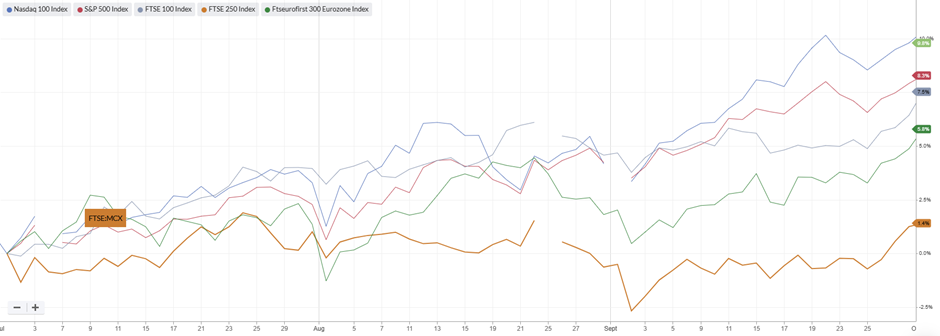
It is Polar’s technology focus that is again leading to these strong returns, with the NASDAQ being the strongest index in the last quarter by some margin:
Research provider, Equity Development update their forecasts in response to this, saying:
We upgrade our FY26 and fY27 forecasts due to:
• The jump in AUM over H1-26 being higher than originally forecast, and
• Mark to market performance fee profits being higher than originally forecast.
They increase their FY26 EPS estimate by a whopping 40% to 57.2p, and lift their FY27E EPS by 24% to 55.6p. To be fair, they appear to be a little behind the consensus:
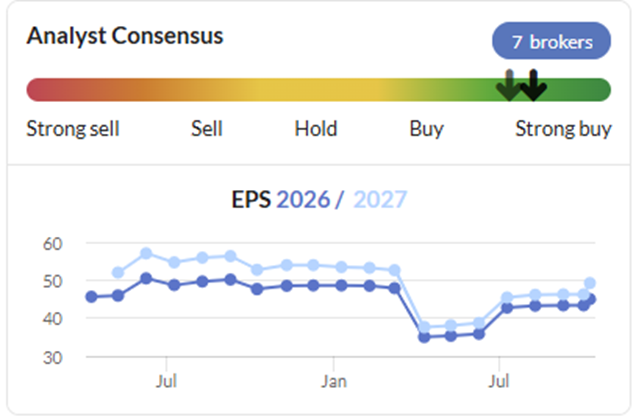
But this is still a big upgrade and means the P/E here is now around 10. This makes them look more favourable on a sector comparison
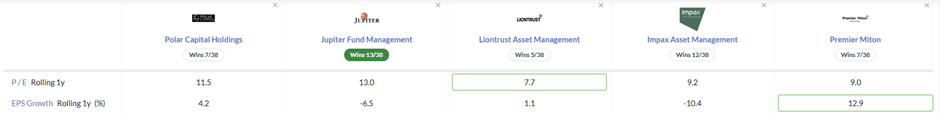
Their P/E is in line with the sector but they have better growth and profitability metrics.
There are a couple of reasons for caution. The first is that both the market cap and EV appear large compared to the AUM:
Firm | Mkt Cap (£m) | EV (£m) | AUM (£bn) | Mkt Cap/AUM | EV/AUM |
Liontrust | 206.6 | 129.4 | 22.6 | 0.009 | 0.006 |
Polar Capital | 550.5 | 370 | 23.2 | 0.024 | 0.016 |
Impax | 238.8 | 163.5 | 26.1 | 0.009 | 0.006 |
At around 2.5x higher than Liontrust and Impax, this means they are more reliant on performance fees or higher management fees as they are on roughly the same P/E ratio. This may be a fair reflection of their better recent underlying performance. Although, it must be noted that until recently, Impax was the stock market darling that was at a premium to the sector on these types of metrics.
Which brings us to the second bear point, which is that markets tend to be cyclical, and the current outperformance of large-cap tech is by no means guaranteed in the future. The tech sector P/S is looking pretty punchy at the moment on 8x sales:
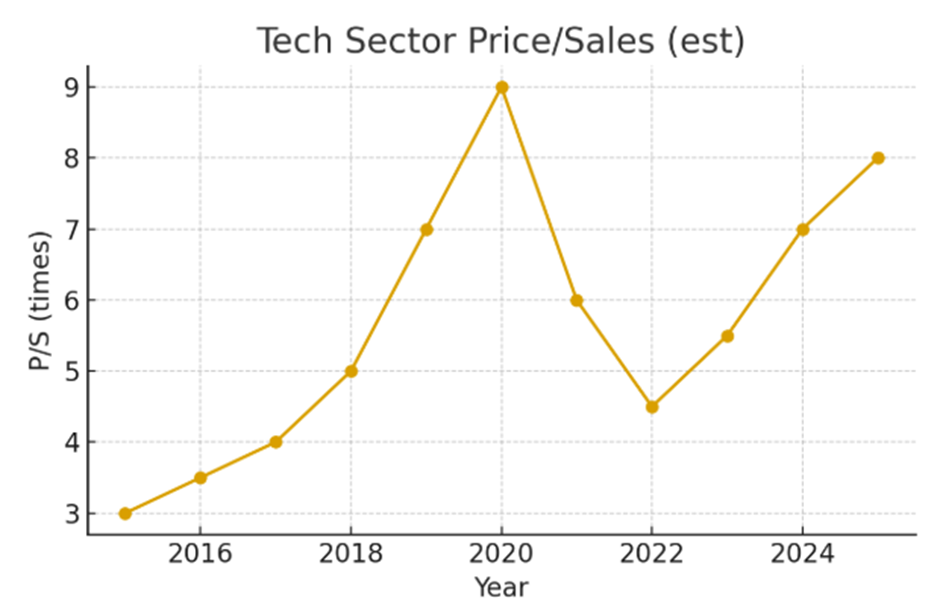
If this reverts to the recent mean, it will mean a painful performance period for Polar’s funds, no matter how well run they are. But for the moment, momentum is with the sector and as former Citigroup CEO Chuck Prince said in 2007 "While the music plays, keep dancing". Today’s AUM update suggests that Polar will still be dancing for some time yet.
Mark’s view
The strength of the EPS upgrade today makes it tempting to upgrade our view here. After all, it is now trading on a sector average rating but with what seem much better near-term prospects. What moderates my view is the nagging thought that the performance here is as much about the sector their funds find themselves in rather than any endogenous characteristics. The AUM/Market Cap metrics suggest that it won’t all be as rosy, if (when) tech stocks face any moderation in valuation. There are few signs of any storm clouds on the horizon, though, so it makes sense to remain mostly positive. AMBER/GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Mark, I think you have used the wrong AUM figure in your comparison of EV/MV/AUM in your section on Polar Capital Holdings (LON:POLR) - you have used the July figure of 23.2bn as opposed to the reported AUM of 26.7bn.
Good spot, thanks. It does make it slightly better on this metric, but doesn’t change the thrust of the argument is that these things tend to be cyclical and despite EV/AUM being a blunt tool it highlights the risk if current market preferences for tech stocks change.
Hostelworld (LON:HSW) As a 68 Yr old single budget traveller [currently paying 110e a night in Hamburg!] my view of hsw is poor. Poor website, poor marking. tiny range of destinations and frequently not cheap. I wish hostels went back to direct booking. It's easier to use booking.com!
I'm not sure if you're the type of customer than pays e110/nt, that you're the target market for Hostelworld (LON:HSW). It's more of a e10-e40/nt type traveler.
So makes sense the HSW website and app experience is not optimised for you.
Booking on the other hand.... Yes, they do plenty of e110/nt accommodations...
No. You misunderstand. I stay in room share/ bath share dorms frequently. In the next 6 countries I have booked via HW one night out of 46 nights! Last year in Nov in an Albanian resort I was the only paying bed, all the others were 'work in kind'. In August it was still 5% free. The kids know this. DYOR
Ohhh I see! Sorry, I assumed that at e110 it wasn't a dorm bed type thing.
Interesting. So HSW is priced uncompetitively to new entrants to hostels (like Booking.com) AND the website experience is not as good? Hmm
Cheapest private hostel room on HW is 71e in Hamburg tonight. I have covid so not sharing atm
Hey, in our view (author), what does BLACK, PINK, etc mean?
Hi Tom, here are the usual classifications:
Colour Shortcuts
GREEN - Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
AMBER/GREEN
AMBER - Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
AMBER/RED
RED - Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
BLACK / COLOUR - for profit warnings.
PINK - for takeover approaches
Mark it might be a good idea to put a link to the classification descriptions within the header to "Our view" and added to the learn tab. This would save the need for you to explain the colour coding to new subscribers.
thanks, I'll have a chat to Graham about it.
Does anyone have any idea why Premier Miton (LON:PMI) is up by 10% today? Can’t see any news or broker upgrades mentioned anywhere. I’m a long suffering shareholder.
Premier Miton (LON:PMI) There was an out-of-spread trade (small) in last night's auction @57.2p. The spread of 62-64 hasn't moved; it is the same today as it was yesterday.
Thank you
Don't miss John Lee assessing and talking about Treatt and the latest bid
We are back for another one next Monday 13th October and will be joined by the very popular Richard Staveley of Rockwood Strategic who will then be followed by three company presentations.
We have a special guest with Lord John Lee joining us to discuss the merits or not of the latest price announced for the takeover of Treatt plc where John is a significant shareholder and has been for many years of course. As ever, the webinar will be rounded off with our popular BASH (buy, avoid, sell, hold) panel. We may also have a couple more sessions which are tbc...
This will be a popular MelloMonday so secure your ticket early as we have a limited capacity on the webinar.
Full details here: https://www.melloevents.com/mm131025
Schedule (subject to some minor change):
5:00pm.... Richard Staveley, Rockwood Strategic (LON:RKW)
5:30pm.... Company Presentation from DSW Capital (LON:DSW)
6:10pm..... Company Presentation from Quartix Technologies (LON:QTX)
6.30pm...... Lord John Lee looks at the Treatt bid
6:45pm.... Company Presentation from Nexus Infrastructure (LON:NEXS)
7:15pm.... BASH (Buy, Avoid, Sell, Hold) Panel
Please note, if you are a shareholder of any presenting company above, you can secure a free ticket.
If not, use code MMSTOCKO50 for 50% off tickets: https://www.tickettailor.com/events/melloeventslimited/1738556
A couple of observations on two shares I hold.
Ramsdens Holdings (LON:RFX) rightly or wrongly I have resisted the temptation to take profits on one of my largest holdings bought at around 230p. I thought the performance would have been stronger, but ahead will do for me.
The company is a significant beneficiary of the gold price, which is now over £3000/ounce but its other revenue streams have also performed, even FX where the take up of its multi-currency card has increased substantially, albeit from a low base. Based on yesterday's closing price of around 370p the forward PE is 10.5.or thereabouts with a yield of 3.6%. It has a sound balance sheet and a CEO who holds around 3.5% of the shares.
There is also the potential for a bid, given the situation with HAT. Selling is notoriously difficult to call, so for the time being I shall run my winners.
Polar Capital Holdings (LON:POLR) Again a largish holding and much of the same applies. It enjoys significant tailwinds from its technology fund/IT. At some point the music will stop, but many of its other funds are performing well and the 15% increase in AUM announced this morning was better than I expected. There is also a very handsome dividend on offer. So again I shall hold and let momentum take the strain, although in fairness I haven't looked at share prices this morning, but would expect a positive reaction?
Graham given your knowledge of financials I would appreciate your views, especially on Polar Capital Holdings (LON:POLR)
Added to POLR this morning on the back of the update. Looking for at least 600 in the near term.
jonno, you are so right, 'Selling is notoriously difficult to call, so for the time being I shall run my winners', I sold my holding of Polar Capital Holdings (LON:POLR) only yesterday at a small profit of 3p/share but there you go. Wish me luck, I put the returns on a gold miner, Serabi Gold (LON:SRB which hopefully will pull more gold out of its mines than Ramsdens will pull out of customers pockets.
Polar Capital Holdings (LON:POLR) have risen by 5%, presumably on their announcement of assets under management rising from £23.164b to £26.7b over the past year.
Polar Capital Holdings (LON:POLR) certainly looks like the pick of the bunch at the moment among the fund managers, when compared to the others that have issued updates this week.
Is Secure Trust Bank (LON:STB) just a temporary profit miss in your opinion? I don’t see how this affects the long term investment case structurally.
Secure Trust Bank (LON:STB)
very poor update today - they were in control of their actions reference vehicle financing - i dont think there was any pressing need to pul the plug in such violent fashion - if theye were going to have exceptionals it would have been nice if they had flagged up at the time - it would have looked more professional doing that.
Lets be frank ref onerous contracts with suppliers - that should have been fully assessed and implication known before tehy pulled teh plug so that market updated at the time.
Seems odd that they would be making extra provisions ref vehicle financing whne portfolio is shrinking faster than expected - hey ho modelling does what it does - rather than always come up with sensible answer. are they saying tehy disagree with modelling and excessive provisions may reverse later ? i wouldnt go that far.
price reation today seems ott with regard to £9 million exceptional hit only - thats real cash though that we had yesterday and dont have today - and fiunance is all about having strong balance sheets - so market aint ever gonna like it 4% of the market cap exits the door stage left with the tagline "thats not magic"
looking at the core trading that was down 2.2% qoq too - so that might play a part in the share price downfall today too - never helps when is ugh and ugh rather than just ugh - so deffo some missing oi here !
Oh and no update ref vehicle finance miselling - please tell us something when you update.
Oh and do they get el cheapo lending from tehn government and are they going to have to pay extra costs when teh government remove the ridiculous freebie that exists at the moment.
Share preformance had been great here since i had bought not so long ago up until yesterday (all my troubles seemed so far away) - that paper profits nearly all gone now. i did only buy a starter position here and i had plans to potentially add more when and if i can ditch my International Personal Finance (LON:IPF) shares for top dollar as its very similar sector/risk - so its not all bad as i have a chance to reassess and add more if i want to at el cheapo prices again.
Will be interesting to what happens with the 2026 dial - when its an update like this the update to the next year that is not really mentioned is probably more important than what they have told us today - i await the nudge and win and broker updates to filter through to us mere mortals - doubt its going to be great news.
Note this is a company forrcast to make £44 mill net profit thsi year and £60 mill next year - so £9 mill one off really shoudl almost be take as a pinch of salt - perhaps tyhey should take £9 mil of the dividend top keep balance sheet the same - oh that doesnt ever happen does it.
Note this is a money company - so by default is full of red flag risks left right and centre thats the nature of the beats - i do actually quite like their niche though which seems kinda "lower" risk if thats a word one could ever use (probably not) with this sector type.
Add to this Lloyds Banking (LON:LLOY) who only yesterday seemed to say no bother now today say will be material. Look also at others players such as CloseBros both around 3% drop today. It really is impossible to predict how the Mkt is going to react. And why HSBC down 5% today - its not exdivi day for them and I don't think they were into car finance ?
HSBC Holdings (LON:HSBA)
Delisting (taking private) Hang Seng Bank
All the best
HSBC: I can't see the problem. HongkongBank bailed out Hang Send Bank in about 1965 and have held the majority of the shares ever since. Now they're buying out the minority interest. Earnings enhancing. Sounds good to me.
No
The market was expecting this amount to be used for buybacks.
All the best
Lloyds Banking (LON:LLOY) Secure Trust Bank (LON:STB)
from my limited knowledge it looks like Martin Lewis was saying that its likely claim might be capped at £700 - but going back further into teh past than previously expected. thast over simplificatioin though and i havent done deep dive.
It does seem to me though thats another step towards companeis being able to calculate the final bill - if the proposal goes ahead as proposed - if the proposal is coming from then FCA - i would expect it would be rubber stamped unless that is waaay more than previously expected for then big players - even then i wouldnt back them in a fight - unlike many who post here its 100% crystal clear that some firms have been less than transparent ref financing and they have broken the rules - payback will come.
I can understand why they may be holding off formall news if this is starter for 10 and they might have hope they can negotiate downwards - what is clear is that different companies will be affected differently due to te length of time they need to go back (proposed) - so some may have to up provisions perhaps and others may not.
I think lloyds may have been one of the sketchier lenders for years and will have been in the game for the full period.
Note it seems like the FCA are setting what they deem to be a reasonable line in the sand ref conduct - so i think there may be some variability of outcome - hopefully the more honest lenders should have less issues than the ones who used every trick they thought they could get away with to maximise "interest and fees". Thats the plain reality here that there was real collusion to max out fees and interestb rather than minimise fees and interest - and that was hidden from sight when people had decided to buy their car and were being railroaded down the a particular route.
I was going to say in the absence of material uplifts in provisions generally - nothing to worry about but i have just checked the lloyds update and it says
but based on our initial analysis and the characteristics of the proposed scheme, an additional provision is likely to be required which may be material.
oh dear
ref
Secure Trust Bank (LON:STB)
in the absence of bad news i really dont know what to think - on the balance of probabilities no news is probably better than bad news - but i am not entirely convinced in my logic - as maybe they havent bothered totting up the bad news yet - they didnt bother totting up the onerous contract provisions when they shut up shop on car finance so not fully convinced they will not update sometimes sooner or later. As far as i can see they have given very little away since the ye update - its a shame they havent at least provided some comment that i can remember seeing (let me know if i have missed update). I would feel much happier if they would provide some updated commentary - i have to presume each time new news comes out they should be in position to see where stuff is trending - its a long time since year end update.
Secure Trust Bank (LON:STB)
Hi Boris
I have a position here and agree with you - the long term investment case doesn't appear to have changed.
Stripping out Vehicle Finance, Core Profit Before Tax is expected to be up 30% = £79m.
Core lending has "slowed" to +10.3% (it was c +11% for H1) and deposits are stable.
The current market cap is £181m
Even if we add on some exceptional costs this still looks awfully cheap.
With Vehicle Finance contributing a loss of £21.8m in FY24, I look forward to seeing this stripped out of the accounts in future periods as the loan book is run down.
A
maybe or hopefully a bit of an overreaction then...also, banking sector in general is not doing well these days with French banks and HSBC...so this might be a headwind for the price today as well. Demand for banks seems low but could catch up. Other times when I sold on a "profit miss" I've regretted it especially when stocks were still cheap and business model has not been impacted...
An over-reaction? Quite possibly. Secure Trust's update has three uncertainties:
1. impairment charges stable - they expected them to improve, but they haven't
2. onerous supplier contracts on the business that they're quitting - provisions promised later
3. the FCA ruling - they're still assessing the implications, although earlier they thought that their lending had not involved the commissions in the same way as others.
Against this is their cash - Stocko figures suggest the cash held is greater than the market cap.
Intercede (LON:IGP) (I hold). Another average trading update from IGP I do struggle to understand why in the current “hacking crisis” companies like this aren’t doing significantly better. Some of the order values are tiny in my view for what is a critical requirement for governments and corporations. I’ve been a long term holder and am now thinking of reducing my position on this one. Would be interested in other holders thoughts. The Microsoft partnership - has it really delivered any material benefit?
Yep totally agree you would think they would be creaming it, they seem like a firework where the touch paper has got damp and is smouldering uber disappointing
Im not an expert on Intercede, but aren’t they more of a verifier than a preventer? As a former IFA we used to use one of their products to verify the identity of a new client. It’s rather different to a cyber security product. I’m happy to be corrected!
You are correct that Intercede products are about confirming identity, but a lot of attacks start with stealing or being given the identity of a person in a key position (which might be someone quite lowly in the IT department). Finding weaknesses in people is a lot easier than finding weakness in the technology. The main two pillars of IT security are (a) ensuring the people accessing the machine are the people you think they are and (b) ensuring each person only has access to the facilities they need. Intercede SW helps on (a) but SW can only take you so far. You have to trust someone somewhere, and the management of identities and access control can't be sloppy.
Actually, Intercede (LON:IGP) do both depending on what the client wants.
A Credential Management System (CMS) manages a person's credentials - i.e. what proves who you are
An Identity Management System (IDMS) manages your digital identity and access to systems/locations.
MyID CMS can do both although sometimes it's just used for the CMS part.
I held Intercede (LON:IGP) a decade ago before I got bored to. Back then it was ramped a lot as a small company on the cusp of massive contracts with huge American blue chips and it all just sounded to familiar this time around to buy into again…..despite the new management.
I watched a video presentation of the new management team on Investor Meet and I must admit I didn't feel very excited at the end. Should have trusted my instincts.
I think Mark is being a bit short-sighted on Intercede (LON:IGP). Last year's interims benefitted from a 1mm professional services boost in order to meet the deadline for the large federal agency rollout. They did say in the IMC webinar that normalised professional services run at 3-4mm rather than the 5mm last year. Strip that out and the underlying licence/S&M revenues grew at over 10% and that's even after the short-term federal delays.
Regarding his other points, subscription revenues were 360k in H1 but they also have just as sticky S&M revenues (provides quarterly upgrades to MyID). Last year that was 10.2mm for the FY which has grown at a 3 year CAGR of 15%. While new corporate clients are now encouraged to take the SaaS route, governments want perpetual licenses (with 20% p.a. S&M going forward) as they want to pay for it out of their capex budget for the year so there will always be an element of lumpiness.
Speaking of which, before selling, you might want to do some research into the PoC they've been running for a large federal agency and this year's DoD budget starting October 1st (when it's finally passed). It wouldn't surprise me if they smashed EPS this year (or next as government timings are always longer than you think).
You could be right Bro.
Both the chairman and ceo have since invested heavily in their shares.
Although it seems they couldnt persuade the CFO to do the same who rather embarrassingly would only go so far as investing his left over small change of £4k. I wonder why …..?
Re Intercede (LON:IGP) He never has. Maybe he has VAT on school fees.