Daily Stock Market Report (Thur 14 Nov 2024) - EXPN, TENG, SMWH, KLR, BRBY, SPX, BOO, AV.

Good morning! Roland will be here soon, but for now we have coverage from myself (Graham) and Megan.
It's a busy day for news, with lots of companies reporting interim results.
That's a wrap for today (12.45pm). See you tomorrow!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023
Companies Reporting
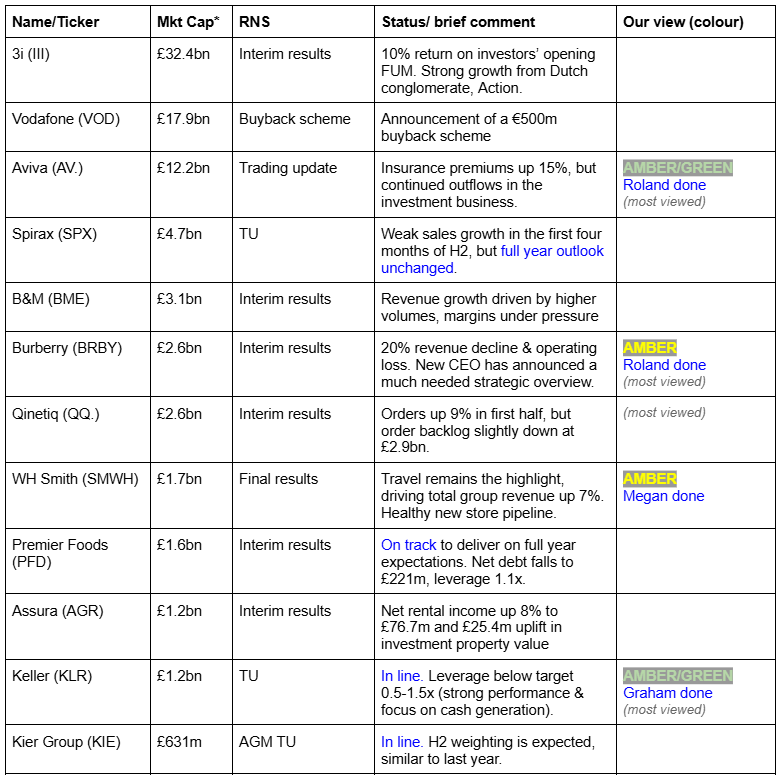
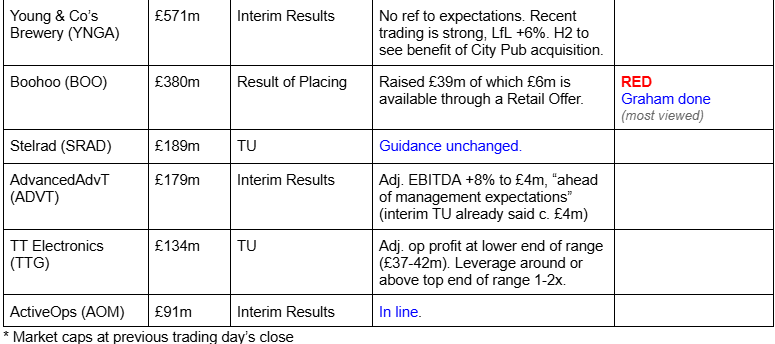
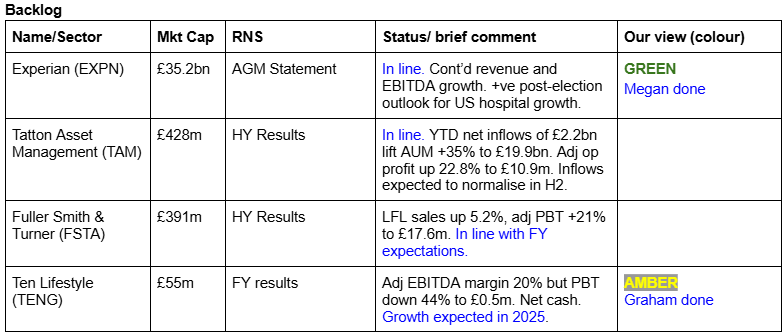
Summaries
WH Smith (LON:SMWH) - up 1% to 1313p (£1.7bn) - Preliminary Results - Megan - AMBER
Continued strong sales growth in the travel business helped to offset the ongoing weakness in the high street. Margins are also recovering in the travel business. But the company remains highly geared which is a cause for concern. And the debt-fuelled earnings growth doesn’t quite justify a price to earnings ratio of 13.4. But I am still hopeful that management can take advantage of the opportunity for growth in the travel sector.
Keller (LON:KLR) - down 12% to £14.37 (£1.05bn) - Trading Update - Graham - AMBER/GREEN
This update includes some mixed/negative commentary, especially in relation to European trading. H2 will be weaker than H1, which enjoyed some temporary advantages. The market dislikes it but the statement is ultimately “in line” and so I’m happy to leave our mildly positive stance unchanged.
Burberry (LON:BRBY) - up 14% to 838p (£3.0bn) - Interim results - Roland - AMBER
Burberry’s half-year results are dire, as expected, but the company isn’t in financial distress and has a credible turnaround plan under new CEO Joshua Schulman. However, I remain concerned about broader market conditions and the difficulty Burberry may have in regaining its former premium valuation rating.
Spirax (LON:SPX) - up 5% to 6665p (£4.9bn) - Trading Update - Megan - AMBER/RED
This morning’s trading update has eased some concerns that things are only getting worse for the engineering business. The company has managed to avoid warning on its expectations again. That doesn’t mean it’s turned a corner. Global industrial production remains weak and the company’s debt position is troubling. But I’ll keep my eyes peeled for a sign of recovery, because this has been a fantastically high quality company in the past - and it hasn’t missed a dividend payment for 56 years.
Aviva (LON:AV.) - up 4.6% to 475p (£12.7bn) - Q3 trading update - Roland - AMBER/GREEN
A solid third-quarter update from the FTSE 100 insurer, albeit highlighting some pressures from elevated severe weather claims in Canada and net outflows in asset management. I think the 8% dividend yield looks sustainable on a medium-term view and remain a fan of this stock as a high-yield pick.
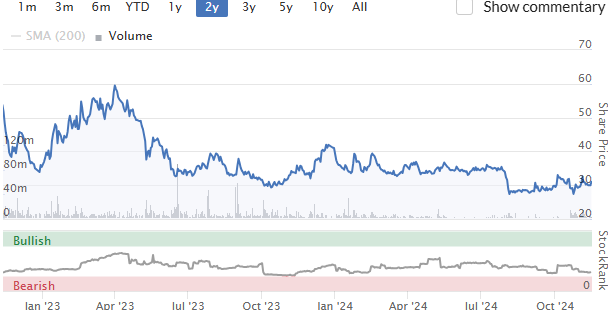
Boohoo (LON:BOO) - up 1% to 30.3p (£385m) - Interim Results & Fundraise - Graham - RED
Results and a fundraising announcement were published at the unusual time of 5.23pm last night. The pre-tax loss widened to £27m with the company proposing to fill the hole with a £39m fundraising. While Frasers and the existing Boohoo Board battle it out I think standing aside, at a distance, is safer.
Short Sections
Experian (LON:EXPN)
Down 3% yesterday to 3748p (£35.2bn) - Half-Year Report - Megan - GREEN
There isn’t much to dislike about Experian from a quality perspective.
The company’s data network and customer relationships mean it poses high barriers to entry for its competitors and boasts considerable pricing power. Gross margins consistently exceed 80%.
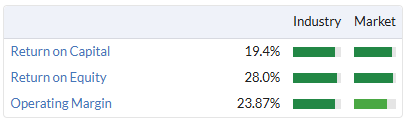
Operating margins have averaged 22.3% over the last five years and rose to 23.6% in 2024. In the FY2025 interim numbers published yesterday, underlying operating margins tipped over 24%. The benchmark EBIT margins (calculated by only taking into account ongoing business activities) were almost 28%.
Return on capital employed (my favourite measure of quality) has been similarly impressive. Over five years it has averaged 17.5% and rose to 19.5% in 2024. That means that for every £1 invested, the company generated 19.5p of profits. I ideally like to see a ROCE of over 20%, but a five year average of 17.5% isn’t to be scoffed at.
And this profitability means the company is well placed to keep investing in its service. Capital expenditures have risen consistently over the last ten years and were the equivalent of 8% of revenues in the first half of FY2025. One slight concern is that the company’s capex to depreciation ratio tends to be less than 1, meaning the company is spending more money maintaining its existing assets than investing in new ones. That is unusual for a tech company of its quality, but as long as capex continues to increase, I am not too worried.
And there are still signs of quality elsewhere in the cash flow statement. Operating cash inflows are always significantly higher than operating profits (an operating cash flow conversion of over 100% is what I like to see in a high quality company). Free cash flow in the first half of the financial year was 77% - slightly shy of the 80% that I like to see, but still not bad.
Management has taken that free cash flow and invested heavily in acquisitions. A total of £818m of purchases, plus £370m of dividends paid widened the company’s net debt position, but as net gearing remains under 100%, I am not too concerned.
The problem for those looking for an entry point is the valuation - the price to earnings ratio rarely falls below 30 and the pace and consistency of earnings growth doesn’t quite manage to justify that. In 2023, earnings per share were lower than the previous year. What’s more, broker expectations have been pretty flat all year - the company delivers against its expectations, but nothing more.
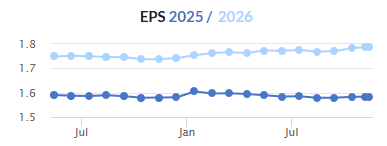
But should we expect more?
Megan’s view: The quality credentials boasted by Experian are a rare find in the UK. As is the company’s exposure to the upside in the proliferation of generative AI. For value investors, Experian will never be especially attractive, but I am not a value investor, so this company hits a lot of the numbers that I like to see.
Sure, earnings aren’t consistently beating expectations, but 11% EPS CAGR over 5 years is pretty impressive, especially as it’s a faster pace of growth than revenue. GREEN
Graham's Section
Ten Lifestyle (LON:TENG)
Down 1% to 56.9p (£55m) - Preliminary Results - Graham - AMBER
Ten Lifestyle Group plc (AIM: TENG) the global concierge platform driving customer loyalty for global financial institutions and other premium brands, is pleased to announce its preliminary results for the year ended 31 August 2024.
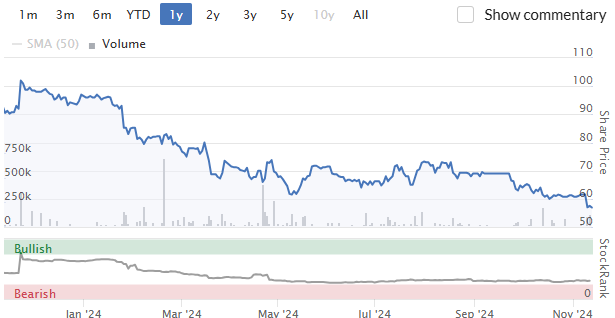
It has been a tough year for those watching the share price here:
The company provides a gateway to exclusive services, typically for the customers of private banks and other institutions catering to the wealthy. The idea is “to improve the engagement and retention of their most valuable customers”.
It has been a while since we’ve covered it in this report. Let’s quickly get up to speed with how it’s been doing.
FY August 2024 results:
Revenue fell very slightly to £62.9m, not helped by a currency headwind.
Adj. EBITDA up £0.8m to £12.8m
Small PBT of £0.5m (last year: £0.9m)
Active members fell slightly to 349,000.
Management make the reasonable point that their numbers had sharply increased in FY 2022 (possibly a post-Covid bounce), and then again in FY 2023. So FY 2024 serves as “a period of consolidation”.
Current trading/outlook: there are some signs of life that revenue will improve in the new financial year.
We expect to continue to convert our strong pipeline of contract opportunities with global financial institutions and premium brands, with new contract developments since the start of the financial year expected to deliver revenues from H2 2025. Since the end of the year, we won a multi-year Extra Large contract in the USA with an existing global client, initially worth £5.0m per year in corporate revenue and a Medium contract in AMEA with a new client.
Net cash ended the year at £4m, no major change there.
In September, just after the new financial year began, TENG raised £6m in a placing at 63p. The purpose: to support the new “Extra Large” contract, and also to generally strengthen their balance sheet.
That seems reasonable to me - their tangible net asset value at year-end (before the placing) was only £2m, and their working capital (current assets minus current liabilities) was negative to the tune of several million pounds. It makes sense that they would want to bolster their position, although it’s a shame that the new contract could not deliver cash quickly enough to do that by itself.
Graham’s view
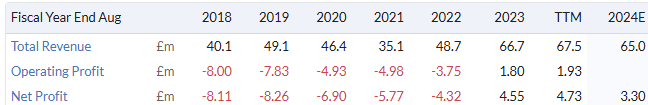
After many years of losses, I’m pleased to see that TENG is now operating in the black:
I wonder what a long-term competitive advantage in this space would look like. Here’s an example of TENG outlining its advantages over competitors:
Our unique "not available on the internet" assets, such as exclusive tables at top restaurants, tickets for sold-out shows, exclusive events, and value-add benefits at hotels, empowered by our AI technology, delivers value for our members via our digital self-serve and high-touch channels. This advantage sets us apart from mass-market AI interfaces reliant on publicly available assets.
I’ve been quite dismissive of TENG in the past (see here for example) and was RED on it at 94p last year.
Some reasons to be more positive on it now:
The placing has strengthened the balance sheet and given some breathing room.
It is winning business from competitors. Revenues are forecast to increase by c. 8% in FY 2025, per the latest research note by Singers.
The share price and market cap are both significantly lower than they were when I looked at it last year (down by 30% - 40%).
As the picture looks to have improved for new investors at this level, I’m happy to switch to a neutral stance now.
Keller (LON:KLR)
Down 12% to £14.37 (£1.05bn) - Trading Update - Graham - AMBER/GREEN
Keller is “the world’s largest geotechnical specialist contractor”.
Well done to Paul for taking a mildly positive stance on Keller this year - see the most recent coverage in August.
Today’s trading update is in line with expectations and confirms that the company’s leverage multiple (net debt/EBITDA) is destined to remain below KLR’s target range of 0.5x-1.5x.
The company has been making more cash than it knows what to do with, with the result that the leverage multiple has fallen as follows:
June 2023: 1.2x
Dec 2023: 0.6x
June 2024: 0.3x
Dec 2024: to be confirmed, but once again below 0.5x.
According to the research note published by Panmure in August, the company’s net debt was forecast to reduce from £237m (Dec 2023) to £113m (Dec 2024), and to continue falling from there.
The summary of trading sounds fine:
Whilst the current macroeconomic environment presents both opportunities and challenges across our markets, the overall performance of the Group, together with our continuing record order book and the groupwide focus on improving project execution, gives us confidence for the short and medium term.
However, looking at the detail of each division, there are a few points of possible concern:
North America: sounds fine overall, but "profitability has tempered as expected” at Suncoast (concrete company), “reflecting the reversion of pricing to more normalised levels and lower residential trading volumes”.
Europe/Middle East: weak European macro environment and weak activity levels in European residential/commercial sectors, plus a competitive pricing environment. Not much to cheer about here.
Asia-Pac: “robust” performance.
I note that there will be a "modest" first-half weighting, i.e. H2 is not expected to match H1’s performance. H2 was "buoyed by some historical items and contractual items".
CEO comment concludes:
The Group's record order book and geographically diverse portfolio provides both visibility and resilience in the current mixed economic conditions, underpinning our confidence as we close the year.
Graham’s view
The greater than 10% fall in the share price seems a little harsh for what is, ultimately, an “in line” statement.
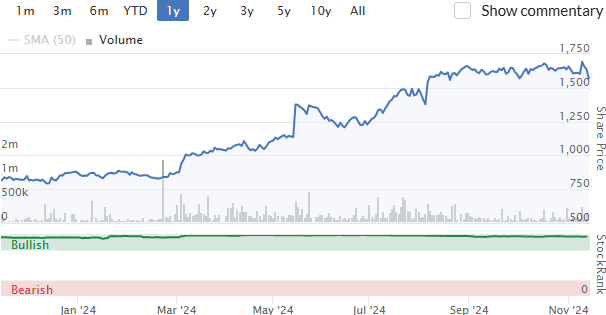
I can only interpret it as profit-taking in a stock that has had a very strong run up (doubling since last year) and where investors might feel that the outlook is not as straightforwardly positive as it was before. Things can turn quickly in construction and engineering, and investors may have reasonable concerns after reading the mixed commentary in Keller’s update this morning. The recent upgrade cycle could easily turn into a downgrade cycle:
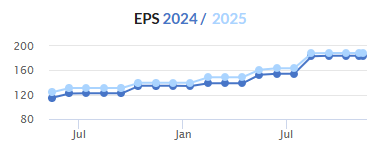
From my point of view, I’m inclined to keep our AMBER/GREEN stance. Perhaps I’m too attached to strong balance sheets, but the trajectory of net debt is very attractive to me. According to the analysts, it could be close to reaching a net cash position by Dec 2026. Granted that a lot can happen between now and then! But for me the declining net debt takes a good deal of the risk out of the equation.
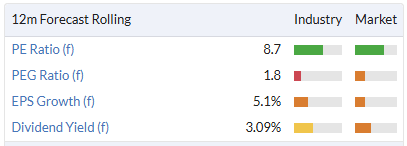
Therefore, while this is not a sector I love, I am happy to maintain a mildly positive stance at this valuation:
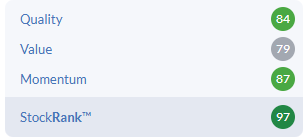
The StockRanks are even more impressed than I am:
Boohoo (LON:BOO)
Up 1% to 30.3p (£385m) - Interim Results & Fundraise - Graham - RED
Boohoo published its interim results last night, along with news of a proposed fundraising.
Results are poor, as expected, as the company’s business model has not been working for some time now. It seems that competition and price pressures have caught up with it.
Key points from the H1 results to August 2024:
Gross Merchandise Value down 7.3% (£1.18bn)
Revenue down 15% (£620m)
Gross margin 50.7% (H1 last year: 53.4%)
Adj. pre-tax loss £27m (H1 last year: loss of £9m)
H1 operating costs were £300m, so the company is well ahead of its cost-cutting targets. Here’s a comparison of income statements in which I’ve highlighted the reduction in operating costs:
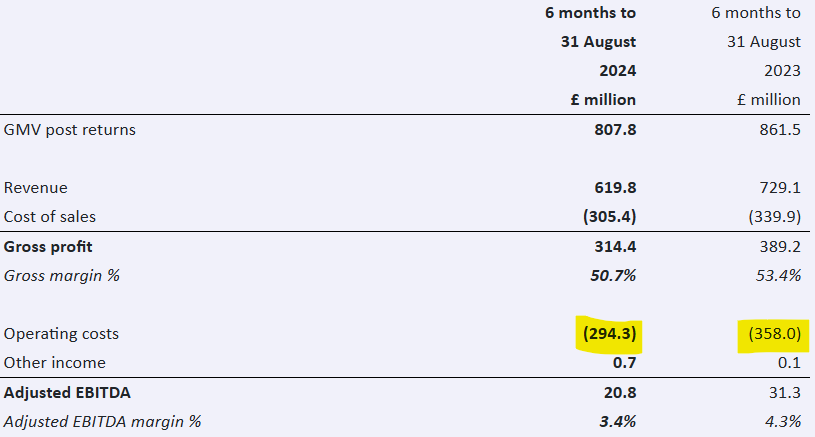
Without that reduction in costs, the adj. EBITDA result could have been much, much worse.
Net debt increased to £143m (six months previously: £95m). New debt financing agreement signed in October.
FY25 outlook: H2 EBITDA to be stronger than H1 (H1 adj. EBITDA was £21m). Capex will be significantly reduced.
Fundraising: in a simultaneous fundraising announcement we learn that £39m is raised, of which up to £6m can be claimed by smaller investors in a Retail Offer.
Details: 127 million new shares at 31p. The Founder/Chairman picks up 50 million while Frasers picks up 39 million. These amounts might be scaled back a little, depending on the demand seen in the Retail Offer.
Rationale for the Fundraise:
The proceeds of the Fundraise are intended to be used:
to part satisfy the first tranche which will become due to be paid under the Term Loan of £50 million by the end of December 2024; and
provide additional strategic flexibility to maximise value for all shareholders as part of the Group's Business Review [GN note: this is too vague!]
Graham’s view
£39m is only a portion of the outstanding net debt so I don’t view this fundraising as providing a fundamental solution to the company’s situation. It does at least demonstrate that the Chairman (and his family), along with Frasers, are still interested in financially supporting the company.
With the shares down by over 90% from their peak, one would hope that they might see some value at this level!
Unfortunately, this continues to look to me like a case of a broken business model. Boohoo in its original form competed on price and fast deliveries, and now it is not able to do this effectively, or at least not able to do it profitably. In an important sign of retrenchment, the US distribution centre has been closed.
Frasers and Boohoo are now locked in a battle over who should run it - Debenhams CEO Dan Finley or Mike Ashley from Frasers. The war of words is getting heated, with Boohoo describing Frasers as a competitor, not a partner, and saying things such as:
Frasers appears intent on disrupting boohoo's Business Review and acting only in its own commercial self-interest. Frasers has prior history of this sort of corporate behaviour
Frasers wants to appoint both Mike Ashley and Mike Lennon, an insolvency/restructuring expert, to the Boohoo board.
For investors who aren’t currently involved in this stock, I don’t see any reason to get involved at this stage.
Either the Boohoo Board are right, and they are being lined up for a cheap takeover by Mike Ashley and his insolvency expert, who are keen on disrupting their business plans.
Or maybe Frasers, owning 27%+ of Boohoo shares, are right. If they are right, then there is a leadership crisis at Boohoo, the existing Board have lost their ability to manage the company, and the new borrowing facility is “terrible” - too short-dated and expensive, forcing Boohoo “to undertake drastic corporate actions”.
Either way, I’d have zero interest in getting involved. It’s tempting to go RED and I think that’s what I’ll do, as I’ve been sceptical of management/governance here for some time and the walls seem to be closing in on them.
Megan's Section
WH Smith (LON:SMWH)
Up 1% to 1313p (£1.7bn) - Preliminary Results - Megan - AMBER
I recently commented that whenever I visit Greggs (which is quite often) it’s always pretty busy. The opposite is true of my (less frequent) visits to WH Smith (LON:SMWH). That is, unless I am at an airport.
A decade ago, high street sales and profits from the stationary company were £684m and £58m respectively, equivalent to 59% and 44% of total revenue respectively. The company operated out of 604 stores and boasted a presence in almost all of the UK’s major high streets. In final results announced today, high street sales fell 4% to £452m (in line with guidance), while headline profits were flat at £32m. There are now just 500 WH Smiths stores on the UK’s high streets.
But in 2024, this weak high street performance doesn’t matter much. The travel business is thriving with sales up 11% to £1.5bn and trading profits up 15% to £189m, representing a slight widening of the margins. The company operates out of 1291 travel hubs around the world.
And so, while in 2014 weakening high street sales and profits caused a drop in the company’s overall operating performance, it barely made a dent in these numbers. Overall revenues rose 7% to £1.9bn and pre-tax profits were up 16% to £166m.
The company’s shift from UK high street stalwart to global travel hub store operator has been crucial in ensuring the survival of WH Smith. The company has managed to outlast many of its high street peers, including Toys R Us, which has begun opening concession stands within WH Smith stores.
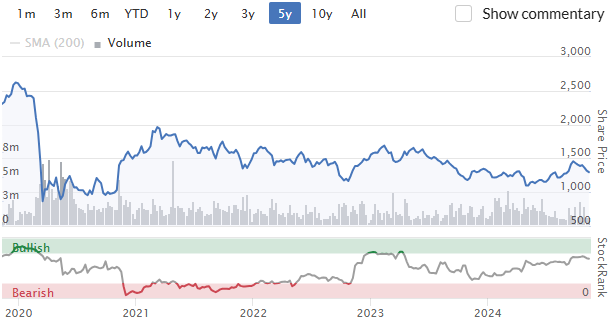
But the expansion of the travel estate has perhaps not provided the pace of growth in revenues and profits that many investors would have wanted. The company’s share price was storming upwards until 2020, when global lockdowns derailed growth and hurt operating margins. Neither the growth strategy nor margins have fully recovered and the share price has trodden water ever since.
More worrying is the debt position which took a big leap up in 2020 and has continued to widen. Net gearing is currently 342% and the current ratio is less than 1, meaning the company doesn’t have enough readily available assets to pay its short term liabilities.
Megan’s view: There is a lot to like about WH Smith’s transformation. Expansion in travel hubs gives an almost limitless scope for growth and it’s good to see margins in these locations continuing to rise.
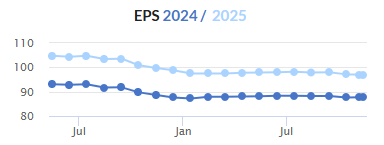
But debt fuelled growth is always a bit of a red flag for me, especially in an era of high interest rates. High finance costs have not helped the company’s earnings growth and analysts have downgraded expectations a number of times this year.
I’d like to see more ambition and less debt before I turn more positive. AMBER
Spirax (LON:SPX)
Up 5% to 6665p (£4.9bn) - Trading Update - Megan - AMBER/RED
Investors who have long searched for an opening into engineering giant Spirax (LON:SPX) (formerly Spirax Sarco) might see the recent share price trajectory as something of an opportunity.
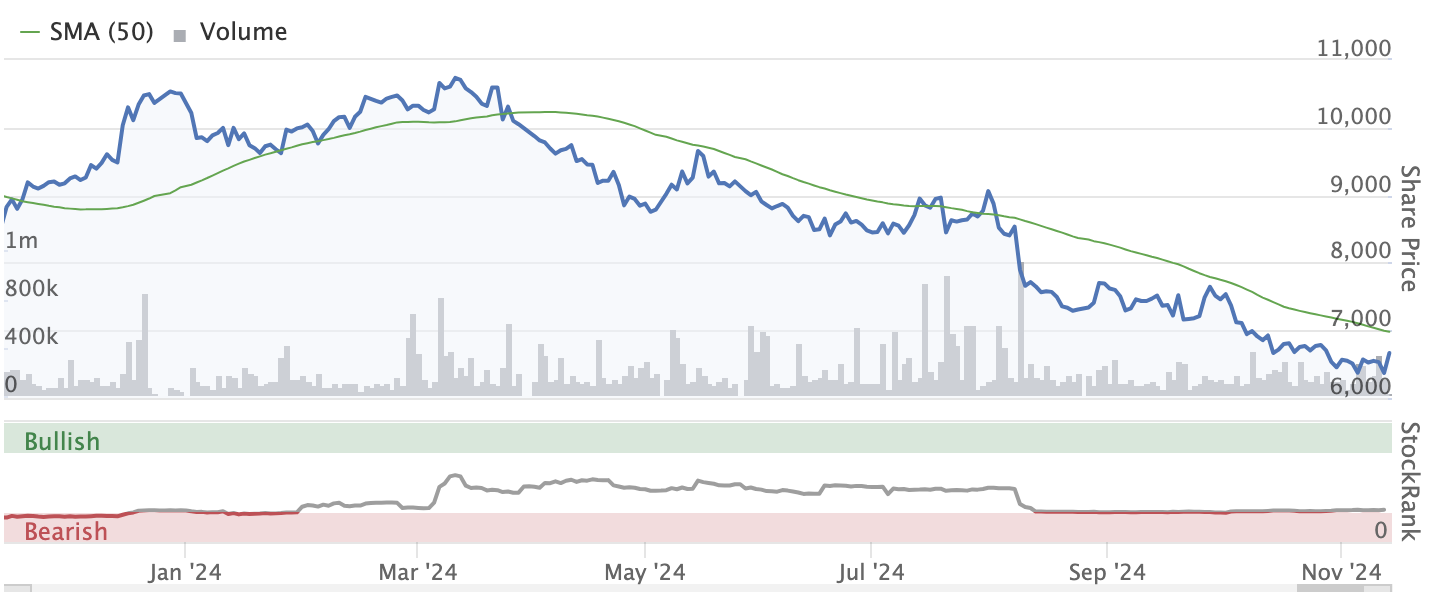
But beware any optimism. Spirax is a lesson in the dangers of investing in high quality companies that fail to live up to expectations. Operating margins have been falling since 2021, profits have declined and earnings, that fell in FY2023, are expected to be lower still in the current financial year.
The problem with this decline in earnings is that, despite the share price fall in recent months, shares aren’t actually looking especially good value, trading on a price to earnings ratio of 20 times and a PEG of 2.7.
In years gone by, that might have seemed like an entry point, but the quality ratios at Spirax are also diminishing. ROCE, which used to average 20% fell to 12.6% last year. In 2022, the company raised £509m of new debt to finance acquisitions. This borrowing came at an interest rate of 4.8% which more than doubled interest costs that year. Operating cash inflows since then have continued to be impressive, but not enough to make a material dent in the debt. Net borrowings at the end of October were £642m and the company’s net gearing stands at a slightly concerning 70%.
So what has gone wrong at this former high flyer and does this morning’s trading update suggest any signs of a turnaround?
Macro conditions
Part of the problem lies in the macroeconomic conditions. Global industrial production growth was just 0.3% in 2023, compared to 2.1% in 2022 and the weakness continued into 2024. Industrial production contracted in Germany, France and the US in the first half of the year - markets that represent 40% of group sales. China (10% of company sales) has seen a material decline in opportunities compared to previous years, with customers seeing a major contraction in their capital budgets. In the first half, management at Spirax chopped their expectations for China for the remainder of the year.
This morning’s numbers show that this former key growth market remains weak. Overall, global industrial production growth for the second half of the year is expected to be even weaker than expected, at 0.9% (excluding China) compared to the 1.5% that was forecast in August.
Management
There has also been considerable overhaul in the senior management at the business in recent years. In January, Nicholas Anderson retired after ten years as chief executive and the company’s finance director was replaced in July. There will also be a new chairman at the start of next year. Added to the name change, the lack of consistency hasn’t provided an awful lot of reassurance to investors.
Balance sheet
Then there is the borrowing. The major increase in debt sent interest expenses up 3-fold in 2023 and they were higher again in the first half of the 2024 financial year. Lower profitability has also impacted the company’s ability to invest in its operations. Capital expenditure fell from £51m in the first half of 2023 to £44m in the first half of the current financial year, equivalent to 5% of sales. Capex fell below depreciation expenses in 2023, which is a red flag for a lack of investment in future growth opportunities.
Meanwhile, the sales mix hasn’t flattered margins. In 2023, revenues were flat in the Steam Thermal Solutions business and they fell in Watson-Marlow Fluid Technology - these two divisions had contributed 97% of operating profits in the previous year. The sales growth has instead been provided by the low margin Electric Thermal Solutions business, which contributed 23% of sales in 2023, but just 8% of operating profits.
But this morning there has been some good news for both the Steam Thermal and Watson-Marlow businesses. The former has returned to organic revenue growth and sales at the latter have stopped declining rapidly. Overall, investors seem relieved that the outlook for the remainder of the year has not worsened further. Management has maintained its guidance for 2024 for mid-single digit revenue growth and no change in adjusted operating margins, despite the concerns about currency headwinds.
Megan’s view
I retain a soft spot for Spirax because it was the company that taught me how to identify quality shares. For now though, the cash inflows remain the only ongoing levers of high quality and there is a lot of work to do before this starts to make a dent in the debt position.
The company does still boast high barriers to entry and opportunities for growth (if the market recovers) so I will keep looking for signs of a recovery. But for now I remain on the fence. AMBER/RED
Roland's Section
Burberry (LON:BRBY)
Up 14% to 838p (£3.0bn) - Interim results - Roland - AMBER
(At the time of writing, Roland has a long position in Burberry.)
We are acting with urgency to stabilise the business and position the brand for a return to sustainable, profitable growth, supported by strong cash generation and balance sheet strength.
As a Burberry shareholder, I’ve been looking forward to these interim results in the hope they’d provide some new clarity on the situation and outlook at this troubled fashion group.
New Chief Executive Joshua Schulman has a strong pedigree in mid-market luxury (he previously ran Coach and Michael Kors). Can he deliver a turnaround at Burberry – and more importantly, can he restore some of the shareholder value that’s been destroyed over the last few years?
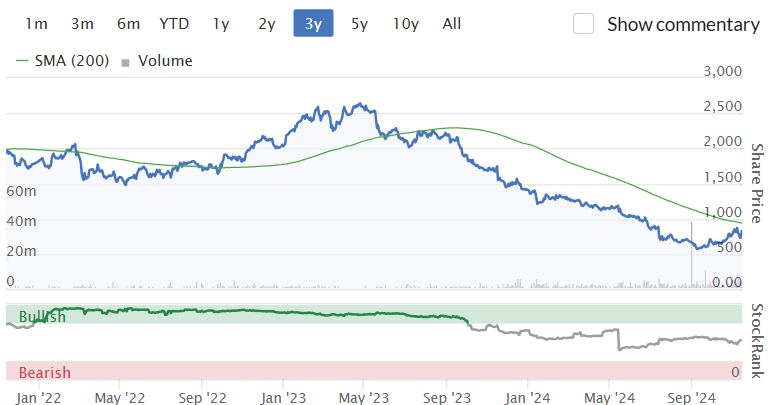
I covered Burberry in a Stock Pitch back in July, outlining the investment case and problems facing the company as I saw them. That article is available here and makes for useful background to the business.
Let’s take a look at today’s results and strategy update.
H1 25 financial summary: there’s no getting away from it. Burberry’s financial performance over the six months to 30 September 2024 was dire:
Revenue down 22% to £1,086m
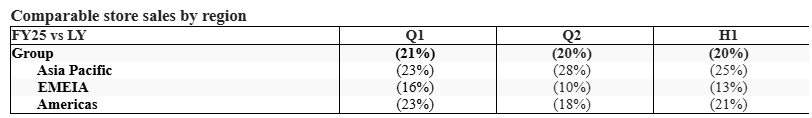
Like-for-like store sales down 20%
Operating loss of £53m (H1 24: profit of £233m)
Free cash outflow of £184m
Dividend suspended
Net debt of £1.4bn (Sept 23: £887m)
Sales performance: geographically, the Asia Pacific region saw a further deterioration during the second quarter, while the rest of the world saw a (relative) improvement in Q2. However, there was bad news everywhere:
In terms of product lines, Burberry’s core outerwear/soft ranges outperformed their accessories ranges. "Accessories" include the company’s ill-advised attempt to compete in ultra-luxury leather goods such as handbags – not a market where it has a competitive advantage:
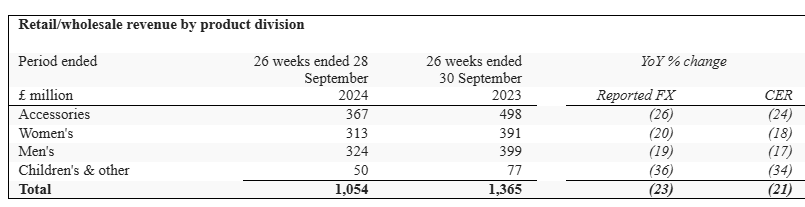
Stories of Burberry leather goods being heavily marked down in outlet stores highlight the problem here – the company has sharply increased its pricing but failed to elevate its brand to capture suitable (full price) customers.
Inventories & working capital: today’s results show inventories of £596m at the end of the half year. That compares to £526m one year earlier. Indeed, as far as I can tell, today’s inventory figure is the highest ever reported by the company.
Another figure is rising, too. Inventory provisions rose by £29m to £102m during the half year. This reflects stock where the realisable value is believed to be less than the cost.
This suggests to me that the company’s “Accelerated plan to address inventory overhang and restore scarcity” may involve some brutal discounting and stock write-offs.
Balance sheet: excluding lease liabilities, Burberry moved from a FY24 net cash position of £63m to a net debt position of £278m during H1.
This reflects the collapse in profitability, paired with seasonal outflows/inventory build and continued store capex.
For me, the ongoing capex bill is a reminder of a potentially more serious problem. The company has £1.3bn in lease liabilities relating to its stores. If some of these prove to be overrented or unsuitable for future requirements, Burberry could be saddled with expensive loss-making stores for some time yet.
An impairment charge of £24m (FY24: £9m) was made against right-of-use assets (essentially store leases) in H1, suggesting this could be an issue worth watching.
Strategy update: the strategy commentary in today’s results is a remarkable buzzword salad, even by corporate PR standards. But I think it boils down to a few key ideas:
Focus more closely on areas where the company has “brand authenticity”. In other words, products people associate with Burberry and admire – outerwear and some other clothing.
Fix pricing mistakes and (probably) abandon a move to target the ultra-luxury segment
Maximise the heritage value and British identity of the brand, which helps to differentiate it
Improve store productivity by stocking more items people actually want to buy (“core category amplification”) and emphasising brand identity
Outlook: Burberry cautions that rebuilding the business won’t happen overnight. While Mr Schulman is confident he can return to £3bn annual revenue over time, the outlook for the remainder of this year is highly uncertain (my bold):
We are confident that our strategic plan will improve our performance and drive long-term value creation. In the short term, with our all-important festive trading period ahead and an uncertain macroeconomic environment, it is too early to determine whether our second-half results will fully offset the first-half adjusted operating loss.
In other words, Burberry may well report a full-year loss for the year to March 2025. If this happens, it would be the first time in the company’s 20+ year history as a listed business.
Roland’s view
The strategy being put forward by Schulman looks sensible to me and is as I expected. His track record suggests that he does know how to drive commercial performance from mid-level luxury brands.
On the other hand, even if he’s successful, I wonder if Burberry may struggle to regain its former luxury valuation. Tapestry (NYQ:TPR) (which owns Coach) and Capri Holdings (NYQ:CPRI) (Michael Kors) both trade on low double-digit P/Es with and appear to generate mid-teen operating margins during normal times.
Viewing Burberry through this lens suggests to me that a return to £20+ share prices could be a tough ask.
On balance, I think there could be a worthwhile turnaround opportunity from current levels.
But the uncertainty around near-term company performance and broader luxury market conditions means that I have no choice but to retain Graham’s previous neutral stance at this early stage in the company’s turnaround.
Aviva (LON:AV.)
Up 4.6% to 475p (£12.7bn) - Q3 trading update - Roland - AMBER/GREEN
We are confident about the outlook for the rest of 2024 and beyond, growing the dividend and achieving the Group’s financial targets.
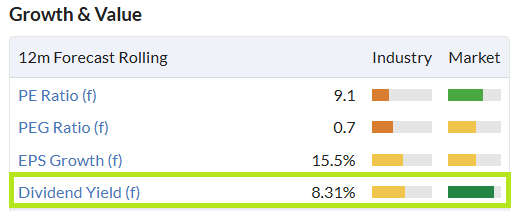
Insurer Aviva’s 8% dividend yield is a notable attraction, even among the high yielders of the FTSE 100 financial sector. Today’s update shows more progress in key areas, so I’m not surprised there’s been a favourable reaction in the share price.
Q3 highlights: I’ve been a big admirer of Aviva’s turnaround under CEO Amanda Blanc. After slimming down the business, she has focused on rebuilding momentum in the group’s core operations in the UK, Ireland and Canada.
Today’s results show continued progress and suggest the group is on track to meet its medium-term targets.
General insurance (e.g. home, motor, commercial): premiums written rose by 15% to £9.1bn during the first nine months of this year. The company says this growth was “balanced” between price rises to offset inflation and new business wins.
However, hail, wildfire and flooding events in Canada resulted in a high level of natural catastrophe claims. Based on estimated claims costs the company expects its Canadian business to have a combined operating ratio (COR) of 110% for Q3 (Q3 23: 104%). What this means is that total claims costs and expenses are expected to exceed premiums received by 10%, resulting in an underwriting loss.
Fortunately, performance in the UK and Ireland was more profitable.
Aviva reports an overall undiscounted COR of 96.8% for the first nine months of 2024. Offsetting investment income against this figure results in an improvement to 92.8% – not a bad result for general insurance, which is a competitive market.
Protection & Health: one area of growth for Aviva is health insurance and other protection type products. Sales during the first nine months of this year rose by 22% to £403m (9M 23: £330m).
This growth was driven by “double-digit growth in Health in-force premiums” and the acquisition of AIG’s UK protection business earlier this year.
Multi-policy customers: Aviva is a well-known brand. A core element of the group’s growth strategy is to expand its direct relationship with its customers.
Over the last four years, customer numbers have risen by 1.2m to 19.6m. In the UK, 5m customers now have more than one policy and the company is focused on increasing this metric. Management hopes to increase these numbers to 21m and 5.7m respectively by 2026. These numbers underpin the group’s financial targets.
Retirement: annuity sales and bulk annuities have been another area of growth. Bulk annuity sales doubled to £6.1bn during the first nine months of this year, lifting total retirement sales to £7.3bn.
The company says that as of today, it has written £7.8bn of bulk annuities in 2024, thus meeting its 2022-24 target of £15-£20bn.
Aviva Investors: the group’s asset management business is not the largest in this market, with assets under management (AUM) of just £238bn.
Performance in Q3 was a little mixed as well, with net outflows of £1.7bn. These were due largely to the impact of run-off in heritage business and divestments. However, external net inflows of £0.6bn were insufficient to replace these expected outflows.
Solvency II coverage: this is the main regulatory measure of surplus capital.
Aviva’s Solvency II cover ratio fell from 205% to 195% during Q3. Capital generation did not cover the combined impact of Canada insurance claims, capital required for new business, and dividend outflows.
However, the position remains comfortable in my view and within the group’s target range.
In addition, the group’s Solvency II debt leverage ratio reduced during the quarter to 29.5% (HY24: 31.5%) following some debt redemption and new issuance.
Outlook: Aviva says it remains confident of meeting its 2024-2026 operating targets:
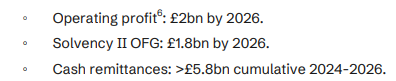
These underpin the company’s dividend guidance for “mid-single digit growth” in the cash cost of the dividend.
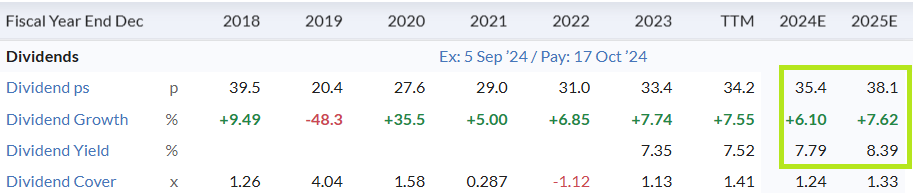
This is reflected in broker forecasts, which have remained fairly stable this year:
Roland’s view
As far as I can see, Aviva is in good financial health and is performing fairly well. While asset management inflows remain relatively weak, this is a problem being faced by most UK asset managers.
The valuation looks reasonable to me and I wouldn’t have any problem buying at this level. With a dividend yield of 8%, only minimal share price gains are required for a stock to provide a total return ahead of the long-term UK market average.
If the current dividend growth policy can be maintained, I would imagine there could be further upside here. I’m happy to take an AMBER/GREEN stance at this time.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
I have taken a full size holding in my daughters ISA Kier (LON:KIE) for a number of reasons, mainly it does look historically cheap even when you take into account the increased share count from raisings in 2018 and 2021 (from memory). I think the increase in public sector projects under Labour will benefit Kier and as a preferential partner this is something that should be taken into account. Debt will be gone very shortly and perhaps interestingly, I mentioned Kier to a friend who is a CEO with a firm who works closely with Kier. He had lunch with them recently and said he they were very bullish on the future (their order book announced yesterday should translate into profits = half their market cap), decent divi too and according to the CEO and CFO after they shrank they are now ready to regrow at scale.
I see Duke Capital (LON:DUKE) announced a £15m placing after the close in case there are any holders here. Might appeal to some high yield investors, I guess. It seems there is an accompanying retail offer.
Kier (LON:KIE)
A little surprised that no one has commented the AGM update, which is generally positive, certainly the market seemed to think so. Kier remains optically cheap relative to its peer group, the reason I suspect is its level of debt. Another consideration being the increase in employers Ni that kicks in next April.
If it can make decent inroads in reducing debt, then, given the anticipated increase in infrastructure spend in the private (water companies) and public sectors the rating should improve. It currently languishes on a PE for FY25 of 7 versus close to 15 for Galliford Try Holdings (LON:GFRD.
I suspect there are also some who avoid the sector as its history is littered with disasters, Carillion being the daddy
I have a medium size holding. Thoughts and views welcome
Kier (LON:KIE)
The company had NET CASH of £167m at 2024 year end and projected to increase to £287m in 2027.
I hold a full position.
All the best
A value comment from Graham on Boohoo (LON:BOO), thanks.
while Frasers and the existing Boohoo Board battle it out I think standing aside, at a distance, is safer.
I went further today and sold my holding. Should have done that a long time ago but denied loss of confidence in the Management. The kennel is getting less crowded.
Silver
Grant Williams holding his own over the pond for anyone interested in US macro.
Hopefully late enough in the day not to be in the way of small or medium cap UK discussions !
https://www.youtube.com/watch?v=4hwPinccnhI
Perhaps of interest regarding Boohoo (LON:BOO, Shein, Temu competition et al., Amazon are entering the fray (not sure if including the fashion segment) rolling out a $20 or less store (called Amazon Haul) in reaction and competition to the low-cost chinese model threat.Even after the US cracking down, and now Trump perhaps furthering the tariffs, on the de minimis rule.Or perhaps instead of a threat to that sgement of their business rendering it unprofitable even for them, they now see an opportunity?Either way Boohoo have definitely gone from being a market darling to the complete opposite.
ADVT - Any views on this? It looks very much like they are delivering - and strip out the cash and their stake in Saatchi makes the business look something of a value proposition.
Today's figures are flattered by an increase in the fair value of SAA. Trying to account for this, and for cash, I get:
Pretax Profit £8.3m - £4.26m (increase in fair value of SAA) - £1.86m interest = £2.18m underlying PTP
I compared this to the EV value of £190m (marcap) - £83m cash - £25m (value of SAA shares) = £82m
An EV of £82m compared to (annualised) PTP of £4.35m (ish) seems about right for a software business with 80% ARR, so perhaps reasonable value given that Vin Murria is running the show.
Interesting bit of news this week, Jet2 (LON:JET2) are opening a hub in Luton, an easyJet (LON:EZJ) stronghold, quite an aggressive move really, 17 destinations from S25
I'm interested in what you (the team) think of B&M European Value Retail SA (LON:BME) ?
With reference to the negative comments about Hargreaves Lansdown (LON:HL.) I and my wife have had Accounts with them for over 20 years. I am used to their systems and would be very reluctant to move to another Broker.
I sent them a Message this week and got a reply within 24 hours.
Apologies if this has been mentioned elsewhere - I haven't had a chance to read all the comments recently.
What do we think about the plan to launch a 'world first' private stock market - Pisces?
I have to say I don't really understand the concept and would there be any liquidity ? If private companies are listed on Pisces then wouldn't they be public companies !? Why not just promote and improve AIM instead ?
Re Pisces
Reports suggest that it would only trade at at "structured intervals" and hence not a market in the sense that many private investors have become accustomed to. Very difficut at this stage to properly assess
I would guess that AIM has not turned out as many hoped it would. Strip out companies which should be private, perpetual loss makers etc and it is a rather small and weak index in my view.
I would not be surprised if AIM was ditched at some stage.
The top 200 AIM companies are far better quality than what is on the FTSE Small cap & they also have far superior disclosure. You try and find an up to date shareholder register for a 'main market' small cap - they don't exist!
RE: AIM
Thank you for the response. My point was about the future of the index - not whether some aspects of AIM are better than the main market.
AIM probably has not worked out as expected with with overall poor performance of the index. It does not surprise me that the Government is looking to create a new market with the emphasis on investment. It is probably easier to create something like PISCIES with a fresh start and a clean slate rather than encourage new investment into AIM.
If PISCIES makes progress it could well take a chunk of AIM business. Rachel Reeves ccould well come back and finish the job on Business Relief. None of this looks overly positive for the index.
Hi bsharman, J P Jenkins already offer a private companies exchange. This includes most of the companies that have recently listed including Superdry.
The concept with Pisces is to provide "some" liquidity, and companies don't have to do all the regulatory requirements that a public listing entails. Like an AGM for shareholders, publicly released results, trading updates against broker forecasts, announcement of large shareholder and director dealings, M&A conversations, etc...
If structured correctly, it would allow individual private investors to buy small amount of shares. Something that just has too many hurdles currently for private companies to offer.
Thank you to the writers stepping into the void created by Paul's departure.
The table of companies reporting is an improvement as well as coverage of a few large cap. stocks. There can also be bargains in this area and their results give a steer on the macro direction.
It must be 15 years ago I used to stand in a queue to buy my papers in WHSmith and walk upstairs for a coffee in Borders in Cambridge? Crikey how times change, I don't tend to read papers at all these days. Thanks for your coverage Megan.
Megan. Thank you for covering WH Smith. I don’t know whether that was prompted by my note this morning, or that you had intended to write on it in any case. Whichever, it’s appreciated and I share your view on the stock. Good market position, improving profits, too much debt. I’m a little surprised at the 5% sell off this morning. It does not look egregiously priced and I would expect a recovery in due course. Yet I was looking for more clarity from management on the effects of the budget changes.
I associate WH Smith with books and music sales. Both hammered by the internet. I wonder how long the travel business will stand up to this?
I think a PER of 13 is too high for a company that is ex growth.
I associate WH Smith with books and music sales. Both hammered by the internet. I wonder how long the travel business will stand up to this?
You’re going to buy your airplane snacks and bottle of water on the internet? The travel shops are for last minute purchases and are going very well.
Captive audience in airports often delayed, liquids after security etc
WH Smith (LON:SMWH) seem to be heading down the motorway service station model - rely on prime retail locations to charge outrageous prices.
I popped into a WHSmith while in a major shopping centre recently, to get my son some stationery items for school...the price for individual biros made my jaw drop. I walked out, got my smartphone out and bought 10x the identical item for the price of 1 in WHSmith - for delivery later the same day. I also took a mental note not to ever bother going in again.
But then I am one of those parsimonious types who has never filled up the fueltank at a motorway service station.
Businesses that gouge their customers eventually come a cropper, even if usually years after the cheapskate brigade like me have taken flight. But I fear for the legacy high street locations - a lot will depend on the lease profile as to how expensive it will be to exit these. I'm afraid I struggle to find enough enthusiasm to do the homework of combing through the accounts in detail.
Perhaps they can sell them to Burberry (LON:BRBY) ....people who pay silly money for biros may also pay silly money for a beige check that someone scribbled on with a red crayon.
You are right, the strategy is aimed at captive markets, motorways & airports , high street shops will close over time the first to go, ones with a post office franchise
I can recommend "Home Bargains" Monte Carlo. I had to equip several dozen Ukrainian children and that was my port of call. Very cheap and a bic is a bic,
Not much choice. Boots were my choice for a cheap sandwich but their quality has gone right down. Maybe Greggs (LON:GRG) should start opening at airports?
They already have eight stores at airports, I knew they had one at Liverpool but didn't know they had so many in airports.
https://corporate.greggs.co.uk...
Greggs (LON:GRG) 8 is not very many. Could not see any Heathrow. When l looked there seemed to one outside the airport. They could easily open 8 at Heathrow on the airside.
I did try to use their one at Liverpool Street station but the queue was too long.
I don't think aggressive comments are helpful.
Honestly I just do not understand when people here try to teach others manners.
BnB just disagrees with your comment.
What’s the problem?
This is the stock market we are talking about and each ones hard earned money are on the table.
All the best
I don't think aggressive comments are helpful.
They are not and I’m sorry if you saw it that way. However the comment was no more than a pithy encapsulation of the company’s captive hold on consumers and its moat vis a vis the internet competition you expressed concern over. I think it’s quite a stretch to accuse me of aggression. Other posters have liked the comment and seen fit to endorse my thoughts with their own reflections.
BnB likes his Ferraris and his luxury goods....and probably buys his biros in WHSmith as well.
I'm too tight for that nonsense and I avoid the luxury goods sector.
End Conclusion
BnB is going to have a lot more fun in retirement, and my children will probably blow the inheritance on Ferraris anyway.
Made me chuckle.
BnB likes his Ferraris and his luxury goods....and probably buys his biros in WHSmith as well.
Biros?? I haven't used a pen in the last two decades. Get with the modern world, MC!
As for the luxury goods, I like owning the producers - not the products. However, I’ll do my best to impress at Mello next week if you like ;-)
A biro is perhaps THE most essential tool in this modern world.
1. What else are you using to constantly reset anything electronic? Please, please don't tell me you own a tie pin.
2. In Japan biros are vital for keeping old ladies alive after they've choked on the local delicacy of pounded rice cakes (mochi). A biro with the ink removed is useful for an emergency tracheostomy. I kid you not.
3. You can turn any old trench coat into a Burberry with a little bit of red biro.
And yes - you own Ferrari shares for the same reason I've owned Apple shares. I believe neither of us ever stooped to anything so vulgar as actually owning the product.
I believe the CIA are trained to kill people by sticking a biro into their ear and hitting it as hard as possible.
Was looking for an entry into Keller (LON:KLR) but then read this in their update and didn't understand what they were on about! "buoyed by some historical items and contractual claims". So is performance all a bit one off. Rest of the statement isn't inspiring either
Keller (LON:KLR) Disappointed by the update. I read it as ‘we’re on target to meet targets perhaps ..but ’. Don’t know if the Cautionary Statements is standard practice for them but it didn’t fill me with confidence. I’ve bailed out for now.
Keller (LON:KLR) i hold. I agree with Graham price drop does seem harsh however the TU is worded in a very uninspiring lukewarm manner. I will hold for now.
Thankfully Burberry (LON:BRBY) has a cunning plan, announced to distract from this mornings trading update:
No broker notes that I can find so far this morning. In fairness brokers are probably still working through the update with a dictionary.
[Chuckles]
My personal favourite was to read that Burberry intend an "Accelerated plan to address inventory overhang and restore scarcity". More discounting then.
Their statement seems a bit contradictory. They're going to reduce the amount of goods available by making more goods available?? Hmm. Unless they mean destroy some of their inventory. I think some luxury goods do that sometimes.
Whenever a reader checks out the site, they report back that the goods seem well overpriced. Having had a look myself, I'd agree with that sentiment.
Anyway, the market seems to like the awful results. Shares up up 8%. Maybe Nick Train is backing up the truck or something.
Morning Mark, I think this is a plan better than no plan, and Burberry (LON:BRBY). What they mean on range is that they'll focus on a more restricted range, basically backing what they perceive as their winners rather than tying up cash on product ranges outside their comfort zone. Basically a sound principle.
The word is Burberry's cunning plan is to sell out to Italian ski-wear brand Moncler. Many Burberry staff seem to "know".
The word is Burberry's cunning plan is to sell out to Italian ski-wear brand Moncler. Many Burberry staff seem to "know".
Moncler has withdrawn interest in a statement earlier this week.
Thank you ... I missed that.
Moncler has withdrawn interest in a statement earlier this week.
Can’t really blame it after seeing today’s results. You know there’s a problem when you have to keep scrolling down the results to find any numbers and the opening is just loads of self absorbed nonsense. As Mr T. would say “Quit that jibber jabber, fool!”.
:D very good simoan : An A Team reference, haven’t heard one of those for years!!
You’re right though - you know a set of results is bad by the amount of words that preface any numbers…….
I wouldn’t buy Burberry (LON:BRBY) anywhere near here. The shift of strategy does not merit a 20% jump in my view.
I thought that the following phrase was telling, in that someone was thinking that the wealthy were falling over each other in haste to convert their cash into Burberry goods; saying prices "did not always align with our category authority".
Hi anyone else having trouble with Hargreaves lansdown this morning. Can’t trade ?
HL is working for me this morning but has been hopeless recently, keep getting logged out etc etc.
But they are not interested in entertaining any complaints, they always tell me that the problems are specific to my account !!
Tell them you going to close your account then, it may get a reaction. I rarely Hargreaves Lansdown (LON:HL.) now, too expensive and the service has gone downhill.
I've tried that many times. They don't seem to care... and I place a lot of trades with them. That tells me that their going to be in trouble in the long term as a business.
Whats the reasoning of going with someone like Hargreaves Lansdown over a commission free platform like Trading212? I know the spreads are worse but if investing with a long enough horizon can forgive that - keen to see if there is something I'm missing
If the spreads are worse then you could well be losing money. Also the ability to trade maybe worse.
The advantage of Trading212 is you can buy and sell small amounts.
If the spread is worse then you are paying more. It’s simple really as the spread makes you pay in most cases 0.5% more.
All the best
I think the trading fee and increased annual charges would put me off HL, I don't mind missing out on extra 0.5% if I'm already in healthy profit when closing a trade - but the HL charges go out no matter what.
Unless you trade with pennies I still do not get the value here. Trading fee is less than a fiver with major companies ie ig markets , HL and Barclays and the annual charge (if any!) is about the value of a trade with a spread.
Unless this is an ad -:)
All the best
You got me.. sign up today for 15% discount with code: JWSchofield.
Only joking - Just trying to learn from the more experienced here! Take your points about the tight spread and longevity of their history/prestige. Still a sucker for the nice looking interface but can see the attraction to HL - thanks
AJ Bell £3.50 if your reasonably active.
IG group (LON:IGG) is £3 or 0.5% on US shares. You have to do 3 trades a month. Spreads exactly the same as Hargreaves Lansdown (LON:HL.) on shares l have checked.
Hargreaves Lansdown (LON:HL.) are about £12 and plus 1% on US. They are under pressure to reduce prices. They did do £100 free trades a while ago. Also had an email today about reducing costs, which looked paltry to me.
My experience with Trading212 is that it's next to useless for UK stocks, unless you're dealing in fairly sizable companies. Most of the time you don't get a quote for a trade on smaller companies and they just submit it for trading at the 'market price'. So you're effectively dealing blind, so the spread is the least of your worries.
That depends what you are using it for - if you primarily purchase shares within SIPP and ISA wrappers, I can't imagine Trading212 offer that in as full a service proposition - i.e. where both can be managed on the same platform and for all family members easily. I don't 'trade' as such, so a bit more on the dealing costs means less to me - more concerned about financial surety of platform and ability to be able to trade on every account on the one app. Will take a look though. I'm more concerned above dividend administration, W8 handling, overseas dividends paid in SIPPs etc.
Whats the reasoning of going with someone like Hargreaves Lansdown over a commission free platform like Trading212?
Tighter spreads, zero fees for direct equity holdings and a long, successful history in the game. These are people’s hard-earned savings are they not?
I have to say I love using Trading 212 its easy to use, the spread does vary, but its not outrageous
Thanks all resolved itself by 8:15. I rang customer services but they seemed to not know why. Luckily the SIPP trade I wanted to do benefitted from the 15 min delay by couple of percent still worrying for future reference.
duplicated
eltorero,
This is none of my business and you may well be very experienced but JUST IN CASE, it is not usually beneficial to trade at the market opening, unless you want to get in or out on a stock that has just RNS'ed good or bad news, the spreads tend to be a lot wider and market makers can take advantage of you in this period. Maybe this is why you are 2% (which is a large movement) better off now.
Boohoo (LON:BOO) staying classy! Interim results released and a c£40m/107m share placing announced, both at twenty past five last night. Results are appalling.
The only remote positive is the founder and his family, have subscribed for c50m shares. No doubt using some of the profits they have made from previous sales, at much higher prices, their various ridiculous options/LTIPS (that never fail to pay out), and their ever generous salaries.
Frasers have also taken part.
I don’t hold/wouldn’t touch with two barge poles.
Gulf Keystone Petroleum (LON:GKP)
APIKUR has finally made a statement and welcomes the Iraqi parliament ‘s proposal to amend article 12 of the budget law.
Everything is done correct this time and the agreement and resumption of oil exports from the Iraqi-Turkish pipeline is getting nearer.
All the best
Good morning Graham Megan and Roland, I can see you've got another busy day ahead but if any of you get a few minutes for a glance at Zytronic and Jarvis Securities I'd appreciate your observations. Both are in our long term sufferers column but with an extra dividend declared today by Jarvis, and the end of the story nigh for Zytronic, the interesting major investor buying there is intriguing, plus Frp Advisory to steer it's departure (ironic that we have shares in that too), is there any uplift anywhere in there?
Hi JASVFS, I'm sad to see that Zytronic is waving goodbye. At a £5m market cap with £3m of cash, I can see why you might hope for a decent outcome here. Which major investor are you referring to? It looks like Peter Gyllenhammar is out. At least if FRP end up sucking most of the value out, you might end up seeing some of that value in your other position!
As for Jarvis, I see that the shares are slightly higher now than they were when I described them as "GREEN (high-risk)"! Paying a dividend in these circumstances is what I'd expect a high-risk stock to do... G
Thank you for taking the trouble on a busy day Graham, Re Zytronic it was the Henry Spain Investment services and the 4 individual investors that was of interest, all in the last month or so, not huge but not peanuts either. Re Jarvis, I'd noted your previous coverage, Green and high risk for me is tempting but probably shouldn't be. Good luck for wading through the work load today.
Re Zytronic (LON:ZYT), looks like Henry Spain (Market Harborough based wealth management company) took out Peter Gyllenhammar at 55p in the last few days (did either of them get wind of the result of the strategic review?) and was also mopping up small sellers in the market. So HS seem to be a believer in the value there. However, the bulk of their holding is of long standing so they may see it as averaging down to reduce the embarrassment of a larger % loss when reported to clients. Likewise, I suspect the four individuals who announced holdings had had the shares for some time. The announcement of the strategic review triggered an "offer period" which requires holders of over1% to announce their opening position (normally that's only if at 3% or more) as well as any subsequent buys and sells, so most of the recent Form 8.3 announcements were not new buys but opening positions.
I too hold both Zytronic (LON:ZYT) and Frp Advisory (LON:FRP!
WH Smith (LON:SMWH) results are impressive and shares start the morning well off recent highs. The question is to what extent UK operations, still the main contributor, though not the growth engine, will be impacted by the budget. Zero comment (that I spotted) in the extensive update on the matter - in contrast to pub groups. Debt remains too high.
Agree BnB WH Smith (LON:SMWH) results do look good on initial reading. I also like Young & Co's Brewery (LON:YNGA) , especially the non voting shares, but debt remains high and the budget headwinds are yet to impact.
I hold neither at present.