Daily Stock Market Report (Thur 16 Jan 2025) - IGG, PMI, RLE, TRST, CARR, WISE, SNWS, DNLM, CABP

Good morning! We have another large collection of year-end updates.
1pm: we're finished for today!
Spreadsheet accompanying this report (updated to 10/1/2025)
Companies Reporting
| Name (Mkt Cap*) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| Pearson (LON:PSON) (£8.6b) | TU | UL Sales +3%, Adj Op Profit +10%. FCF ahead of guidance. | |
| Wise (LON:WISE) (£15.0bn) | Q3 Results | +24% volume growth, U/L income +13%. | AMBER (Graham) |
Taylor Wimpey (LON:TW.) (£4.0bn) | TU | In line op. profit for 2024. Outlook: well placed to grow volumes. Increased build cost pressure. | |
| IG group (LON:IGG) (£3.6bn) | Acquisition of Freetrade | Freetrade purchased for £160m. | GREEN (Graham holds) |
| Dunelm (LON:DNLM) (£2.1bn) | H1 TU | Sales +2.4%, FY25 PBT within the range of market expectations | AMBER (Graham) |
Deliveroo (LON:ROO) (£2.0bn) | Q4 TU | 2024 adj. EBITDA towards top end of range (£110-130m). | |
Savills (LON:SVS) (£1.5bn) | Year End TU | 2024 in line. Year ahead: challenging conditions to continue but most markets are in recovery. | |
| Safestore Holdings (LON:SAFE) (£1.45b) | FY Results | EPRA Basic NTA per Share up 14.6% to 1,091p. | |
Trustpilot (LON:TRST) (£1.1bn) | TU | 21% constant currency bookings growth and adj. EBITDA to be ahead of consensus. | AMBER/GREEN (Graham) |
Bakkavor (LON:BAKK) (£810m) | Full Year TU | Ahead of market expectations. LfL Revenue up 5.1%. Net debt bottom end of 1-2x target range. | |
Ibstock (LON:IBST) (£661m) | TU | Adj. EBITDA £79m, “consistent with previous guidance”. Outlook: improved conditions. | |
Young & Co's Brewery (LON:YNGA) (£518m) | Q3 TU | Traded “exceptionally well” over Christmas/NY. LfLs up 11.6%. Optimistic about the year ahead. | |
Ab Dynamics (LON:ABDP) (£426m) | AGM TU | In line. Net Cash £23.2m. | |
Niox (LON:NIOX) (£235m) | Full Year TU | Adj. EBITDA slightly ahead of exps at £13.8m. | |
| Cab Payments Holdings (LON:CABP) (£169m) | Pre-close TU | Adj. EBITDA within range of analysts' consensus. Sales £105m (2023: £137m). | AMBER (Mark) |
MPAC (LON:MPAC) (£156m) | FY TU | In line. UL PBT £10.5m (FY23: £7.1m). Net debt £37m (FY23: net cash £2.1m). Order book £111m (FY23: £72.5m). | |
Smiths News (LON:SNWS) (£147m) | TU | In line. | AMBER/GREEN (Mark) |
Avingtrans (LON:AVG) (£127m) | TU | In line. | |
Concurrent Technologies (LON:CNC) (£119m) | TU | Rev & PBT 10% ahead of market expectations. | |
SRT Marine Systems (LON:SRT) (£114m) | TU | H1 PBT £2.5m on revenues of £25.5m (H1 last year revenues: £5.5m). £334m active order book. | |
| Carr's (LON:CARR) (£108m) | Sale of Engineering Division | £75m received, 7.1x Adj EBITDA. £70m to be returned via tender offer. | AMBER (Mark) |
Premier Miton (LON:PMI) (£97m) | Q1 AUM | £10.7bn AuM as of Dec 2024 (Sep 2024: £10.7bn). | AMBER/GREEN (Mark holds) |
Pebble Beach Systems (LON:PEBB) (£74m) | TU | In Line. Rev £125m (124.2m), Op Profit £8.4m (£8.0m). Cash generation slightly ahead. | |
Distribution Finance Capital Holdings (LON:DFCH) (£68m) | TU | FY24 adj. PBT >£14m as previously announced. £5m share buyback. New med-term guidance. | |
Real Estate Investors (LON:RLE) (£51m) | TU | £18.9m disposals in 2024, £15,3m debt reduction (“on track”) | AMBER (Mark) |
* Market caps at previous trading day’s close
Graham's Section
IG group (LON:IGG
Unch. at £10.26 (£3.7bn) - Acquisition - Graham holds - GREEN
(At the time of publication, Graham has a a long position in IGG.)
IG is a £3.7 billion company and so a £160m acquisition may or may not be enough to move the needle at this stage. But let’s explore this announcement.
IG is buying Freetrade, the commission-free trading platform.
Comment by IG’s CEO:
This is a rare opportunity to strengthen IG's UK trading and investments offering and broaden our target addressable marketFreetrade is one of the most successful emerging players in the UK direct-to-customer investment market, with a strong brand, highly scalable technology and delivering rapid growth. I am delighted that Viktor and his team will join IG and continue to lead Freetrade."
Freetrade has 720,000 customers and assets under administration (AUA) of £2.5 billion. AUA has apparently more than doubled over the past two years.
Valuation: IG is paying a premium price for this opportunity. Freetrade’s revenue in Q4 2024 was £8.3m (annualises to £33m) and its full-year EBITDA was £2.1m. IG is therefore paying a multiple of around 5x sales, a level that would be appropriate for a fast-growing tech company.
The plan: surprisingly hands-off, IG seems happy for the Freetrade brand to continue growing in its own right:
IG will operate Freetrade as a commercially standalone business with its own brand, existing management team and operational platform to support the successful execution of the strategy…
Freetrade is at a key stage in its development and IG will invest in expanding its product range, hiring talent, adding new features and increasing marketing activity to accelerate growth. IG plans to reinvest the majority of Freetrade's forecast profit in growing the business over the next two years.
Funding: IG tends to be cash-rich, and had over £900m of balance sheet cash as of the last annual report, with “own funds” (after adding and subtracting various items) of £1.1 billion. It has been using some of this cash to buy back its own shares under a £150m buyback programme. The purchase of Freetrade will also be paid for with IG’s own existing cash balance.
Graham’s view: I like this acquisition in theory, but I’m naturally going to be wary about the price paid.
I’m still slightly scarred from when IG paid $1 billion for the US-based tastytrade, a deal that seemed horribly overpriced and that also diluted shareholders.
At least this deal is much smaller, and so if IG has overpaid then the financial damage will be limited.
But I can see the attractions: Freetrade is a modern broker offering international shares, fractional share dealing and zero commissions, and so in that sense is comparable to the likes of US-based Robinhood ($HOOD). We could contrast it on the other hand against a conventional broker such as Jarvis Securities (LON:JIM), which offers none of those things.
Long-term, I wonder what this means for IG’s own share dealing product? IG Invest also now offers commission-free US shares on a modern app. Will it continue to compete with Freetrade? I’ll be curious to see how the relationship develops. But I’m sure IG must already have a very deep understanding of Freetrade, as they are competitors.
For context, IG’s own revenue from stock trading and investments was £40m in FY May 2024, vs. £27.5m generated by Freetrade in FY Dec 2024.
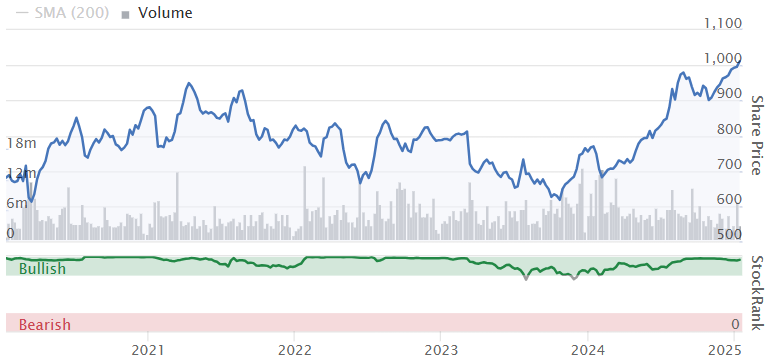
My overall view on IG at this time is naturally going to be positive: I’m a long-term shareholder here and I have positive views on both CMCX and PLUS. H1 results are due later this month. Even after a strong share price performance from IG over the last year, the stock only trades at a PER of about 10x. I think it’s fair that it has broken out to new highs:
Trustpilot (LON:TRST)
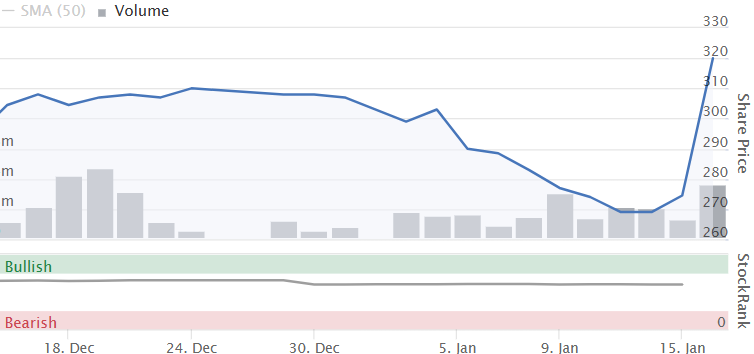
Up 16% to 319.5p (£1.33bn / $1.62bn) - Trading Statement - Graham - AMBER/GREEN
The risk of removing this from my watchlist was that it would continue to go up, and it’s up strongly today, although this does follow some weakness in the first few weeks of 2024.
Here’s a 1-month chart:
The key points: annual recurring revenue is up 21% (at constant currencies) to $231m.
“Bookings”, a similar but slightly more forgiving metric, is also up 21% to $239m.
Revenue, the strictest measure of top-line performance, rose 18% at constant currencies. This is 2% ahead of consensus.
FX: gives a headwind of about 4% to the reported numbers. TRST reports in dollars and the dollar has been strong recently, so the value of non-dollar income has fallen..
Markets: Growth in the key North American market was strongest with bookings up 26%.
Net dollar retention rate: 103%. At the most recent H1 result, this was reported at 101%, so we have a slight improvement in the ability of the company to generate more revenues from existing customers.
Adj. EBITDA: will be ahead of the consensus figure of $22.2m.
CEO comment:
"The Trustpilot platform continues to expand, driving a growth flywheel as more consumers read and write reviews, and more businesses use our products to build trust, grow and improve. In 2024 we focused on B2B product innovation, launching new features combined with new pricing and product packages…
We made considerable strategic and operational progress in 2024 and remain confident in the significant growth opportunities ahead."
Graham’s view
I am nervous that TRST could jump another 100% this year, after I took it off my watchlist. However, I have to remember why I made that decision.
Price to sales (trailing): 7.8x. If it grows 20% this year that would fall to 6.4x. This might be a fair multiple but I don't think it stands out in terms of offering a bargain.
Price to EBITDA (trailing): if 2024 EBITDA is $25m for example, then P/EBITDA is 65x.
ValueRank: 3.
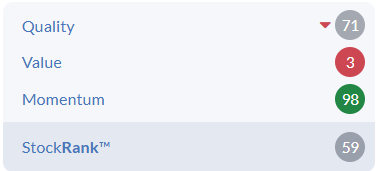
I was still GREEN on this in September at 210.5p. At over 300p today, while I still have tremendous admiration for what this company is doing, I have to moderate back to AMBER/GREEN in light of the stretched valuation.
Wise (LON:WISE)
Down 2% to £10.31 (£10.6bn) - 3rd Quarter Results - Graham - AMBER
I’ll briefly give this a mention today as it’s on Stockopedia’s “most viewed” widget, which suggests that people are interested!
I still think of this company as “Transferwise” but it has been “Wise” since 2021.
Here are the key points from Q3:
Cross-border volume +24% to £37.8 billion
“Underlying income” for Wise +13% to £349.5m, or +20% on a constant currency basis (I would focus on the latter).
The company has a big ambition:
We are making significant strides toward our long-term goal of becoming the network for the world's money as over 9m customers used Wise in Q3 to move or manage their money globally representing 20% growth YoY.
The “take rate”, or fee charged as a percentage of value, fell from 0.67% to 0.56% - this could be interpreted negatively, but Wise says it voluntarily lowered prices for customers and was able to do so thanks to “discipline and focus in reducing unit costs”.
Graham’s view
I don’t have a terribly strong view on this one: It’s clearly a big player in FX, and its growth in recent years has been terrific, but I’ll leave it to readers to investigate further for now. My own stance is neutral: I note that Roland was neutral in November at a share price of 800p, after careful consideration. With the shares already over £10, it would be brave of me to start getting bullish about this.
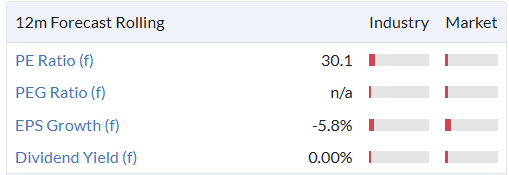
By way of comparison Revolut has been most recently valued at $45bn (£37bn) in private market transactions, nearly four times the market cap of Wise, and I’m inclined to think that it has a stronger chance of becoming “the network for the world’s money”. Revolut is used habitually for small, instant transfers and people are even increasingly trusting it with their monthly salaries, due to its ability to offer a wide range of applications (budgeting, loans, savings, investments).
So Revolut offers a more complete solution, while Wise is more specialised in FX. I think both companies have a bright future, but personally I’m more excited about where Revolut is going.
Dunelm (LON:DNLM)
Down 5% to 975.5p (£1.98bn) - Second quarter and first half trading update - Graham - AMBER
The UK’s leading homewares retailer provides a Q2/H1 update.
Q2 is a little weaker than H1 as a whole, due to a “challenging market”. They think they gained market share:
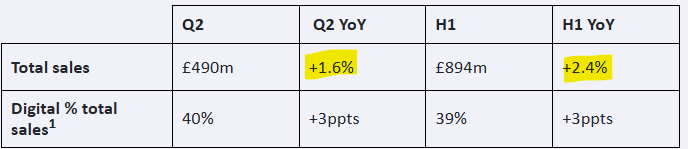
5 new superstores are to be opened in H2, and 13 small stores have been acquired in Ireland, where Dunelm products were already being sold..
Guidance: it sounds like investors should prepare for an outcome most likely at the lower end of expectations, based on the following comment:
Against the market backdrop and ongoing cost challenges facing our sector, PBT for FY25 is still expected to be within the range of market expectations.
Market expectations: FY25 PBT of £207 - 217m.
In a more encouraging comment, gross margin for the year should be in the upper half of the range of 51 - 52%.
As noted by Ken Mitchell in the comments thread below, there is a warning re: National Insurance:
…we are mindful of the impact of the Autumn Budget announcement on our business, suppliers and customers. As a large employer, with over 11,500 colleagues, we have previously highlighted the impact of ongoing wage inflation. Whilst the National Living Wage increase was largely anticipated, the increase in employer National Insurance Contributions is an additional cost headwind. Initiatives to drive productivity across the business are underway, and as these initiatives mature, we anticipate mitigating the upward pressure on costs over the medium term.
Graham’s view
With a financial year-end in June, DNLM is only going to face higher NICs for three months of the current financial year. The real test will be in FY June 2026, when the company might face a continuation of the current difficult market conditions and a major increase in costs. Based on today’s update, it sounds like profitability will be impaired, in the short-term at least, while the company attempts to mitigate upward cost pressure.
I treat the retailing sector very cautiously, as a rule, but I have been willing to go AMBER/GREEN on electronics retailer Currys in recent months.
DNLM is a much higher-margin business, earning gross margins of up to 52% while Currys only earns 17%. But Currys quantified the likely cost of the recent Budget, told us how much of the cost they had anticipated, and gave an overview of how they planned to mitigate it. Dunelm hasn’t done any of this. So I can’t take a positive stance and will instead agree with the AMBER posted by Paul in October. I’m even tempted to turn AMBER/RED as the company’s lack of disclosure re: its plan for higher NICs leads me to worry that there might not be much of a plan in place.
Mark's Section
Premier Miton (LON:PMI)
Unch. at 60p - Q1 AuM update - Mark (I hold) - AMBER/GREEN
Many investors will know this company due to the small and microcap funds it runs, with some well-known fund managers in this space. However, this investment firm does much more than this. UK Equities make up only around 17% of their assets under management. While they continue to see outflows totalling £33m for the quarter, there are some notable details in this update:
Uncertainty ahead of the UK budget was evident during October and this resulted in net outflows during the month. However, it was pleasing to note that flows turned slightly positive in both November and December.
While UK continues to see some weakness, the rest of the strategies are offsetting this:
This was largely driven by positive flow into our US equity, Diversified multi-asset, fixed income and absolute return strategies alongside continued outflows from our UK equity strategies.
With some modest performance gains, the result is AuM flat over the quarter. This doesn’t sound great. However, when compared to the likes of Liontrust that Graham reported on yesterday, which had £1.6bn of outflows, or Impax, which had £2.4bn of outflows even prior to the impact of losing the SJP mandate, this should be considered a strong result.
Importantly, flat AuM means that the company’s 6p dividend is likely covered by EPS:
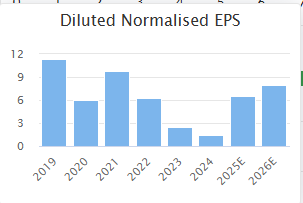
So, unlike Impax or Liontrust, they aren’t maintaining their dividend by paying it out of capital on the balance sheet. The headline yield of 10% may not be as headline-grabbing as Liontrust’s 17%, but it is still very respectable and appears to be covered by earnings. The share price today is unchanged. However, they also went ex-dividend today for a 3p payout, so this could be considered a modest rise.
Mark’s View
All UK asset managers are cheap at the moment, but many with good reason. Premier Miton stands out from the sector by not facing severe redemptions over the last quarter and a dividend that appears covered by earnings. Hence the GREEN/AMBER rating.
Real Estate Investors (LON:RLE)
Up 5% to 31p - Trading Update - Mark - AMBER
This is a fund that is effectively in wind-down, so the progress here is good news:
During 2024, REI completed 20 targeted disposals of £18.9 million, at an aggregate uplift of 6.95% (pre-costs) to 31 December 2023 year end book value
While it is good news that the company is receiving proceeds ahead of book value, we need to be careful about assuming that this carries through to the rest of the portfolio. The first sales are likely to be the most desirable and, hence, most likely to be sold at a premium. There is a decent discount to tangible book value which provides a margin of safety::

Like all such funds this figure is the difference between a definite debt figure and the estimated value of the assets. The real value of the assets depends on what they can get for them on the open market and market conditions still aren’t particularly favourable at the moment:
Whilst the first six months of this year are likely to see a continuation of the trends and activity levels we observed in 2024, we are cautiously optimistic about the second half of 2025 as we expect momentum to build particularly if interest rates continue to gradually reduce and sentiment improves.
So far, these proceeds are used to reduce debt:
Debt reduction of £15.3 million during the year, with total debt reduced to £39.1 million as at 31 December 2024 (FY 2023: £54.4 million)
But the company pays also pays a decent dividend:

Better market conditions would accelerate disposals and allow some capital return as well as simply debt repayment:
This should pave the way for more favourable market conditions and investor optimism which would allow us to accelerate our disposals programme, repay debt more rapidly and commence our capital return to shareholders, all whilst continuing to pay a fully covered dividend.
One way to accelerate the progress would be a block sale. They say:
We remain open to exploring a corporate transaction, including the potential sale of the entire portfolio, in order to maximise shareholder returns.
While this would undoubtedly be good news if it happens, it reads more like hope than a more definite opportunity.
Mark’s view
The discount to TBV looks compelling for a fund in wind-down. However, some doubts remain over the valuation of the remaining assets and how quickly they can be sold, given current market conditions. In the past, I have had concerns over management alignment. Some related party transactions during the fund formation, and the very high remuneration prior to entering into wind-down suggested that incentives were not always aligned. While the fund entering wind-down assuages some of these, I go for an AMBER rating overall to reflect both the risks and opportunity.
Carr's (LON:CARR)
Up 11% to 127.7p (£121m) - Sale of Engineering Division - Mark - AMBER
This reads like a fairly normal disposal of a non-core division until you realise the figures involved:
Sale of the Engineering Division (which, for the avoidance of doubt, excludes Chirton Engineering, which is subject to a separate sale process as outlined in further detail below) on a cash free, debt free basis representing an enterprise value of £75m and multiple of 7.1x FY24 Adjusted EBITDA
The sale of the division was known, but not what they would get for it. The market cap prior to this update was £108m, so this represents 69% of the market cap at last night’s close. There are other asset sales on the way, too:
A separate sale process for Chirton Engineering, which forms a part of the Wider Engineering Division and which is a wholly owned subsidiary located in North Tyneside, UK, specialising in the precision machining of highly complex components and assemblies, is underway and progressing positively;
Completion of the disposal of six non-core properties since 31 August 2024, generating proceeds of approximately £4.0m, with two remaining property sales in progress and expected to complete in FY25;
Of the amount received, £70m is going to be returned via a tender offer. No details are given as to price, but this is largely irrelevant to the outcome. I assume it will be priced to get a reasonable take up from all holders. Carr’s broker, Cavendish, says:
This is an encouraging announcement with a good valuation achieved on the disposed businesses. Our previous sum-of-the-parts valuation had £80m ascribed to the Engineering division. With Chirton still to be sold, this indicates we were broadly correct in our calculation, supporting our target price of 180p. The £70m tender offer represents c74p per share, valuing the continuing business currently at c£35m, or 38p per share, which offers good recovery value.
Adjusting this for today’s rise and excluding the 74p of cash, which will be returned via a tender offer, we have around 54p for the remaining business. Cavendish are already forecasting on a continuing business basis and have 3.0p EPS in for FY25. The forward P/E of 18 isn’t immediately attractive. However, Cavendish are forecasting £84.3m net cash at the end of FY25, or £14.3m after the tender offer. This is around 15.1p per share, which brings that P/E down to a more reasonable 13x. Still not sure how Cavendish manage to get to a 180p SOTP valuation without some pretty aggressive growth assumptions that are outside of their forecast window. The plan is to invest for growth in the agriculture division where they say:
The 'Agriculture Strategy' is comprised of three elements:
1. Improve operating margin across the global portfolio;
2. Deliver profitable commercial growth in the core business; and
3. Expand into new, extensive, grazing based growth geographies.
Mark’s view
While getting 69% of the market cap in cash for the engineering division is undoubtedly good news, I am left a bit underwhelmed by the valuation of the remaining agricultural division. At 18x FY25 earnings, there is a lot of work to do to grow the remaining business into a reasonable valuation. I wouldn’t necessarily bet against them achieving this aim. After all, they now have the capital to invest. However, I’d either need specialist knowledge of the sector or some estimates from the broker that indicate what is possible in the medium term. So far, their broker only seems willing to forecast the current financial year. As such, I am going for an AMBER rating.
Smiths News (LON:SNWS)
Up 1% to 60.4p - Trading Statement - Mark - AMBER/GREEN
A pretty short update today:
The Board confirms that trading for the year ending 30 August 2025 ("FY25") remains in line with market expectations
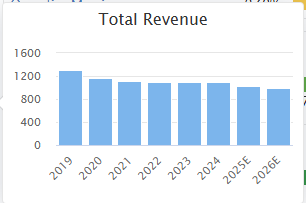
This means a continued decline in revenue:
But EPS maintained:
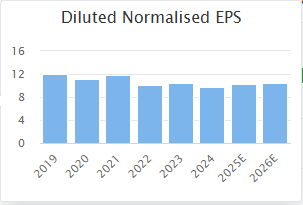
I am consistently impressed with management’s ability to take costs out and maintain profitability in a declining market. The company has an effective geographical monopoly, which enables it to generate good returns despite the obvious headwinds.
However, I have been consistently unimpressed by the diversification efforts here. There have been some good ideas, such as taking back recycling from newsagents or distributing sports drinks. However, the problem is that while these are complementary to their core business, they rely on the core business of existing early-morning deliveries. This isn’t so much a melting ice cube but more a van full of newspapers heading towards a cliff. Sooner or later, publishing physical media will become uneconomic for newspaper publishers. When one goes to digital-only, then this will place higher distribution costs on the remaining ones, which will quickly follow suit. I have no idea whether this will be in 2030 or 2035, but it's coming. What Smiths News needs is a new business that can be grown and doesn't rely on newspaper distribution to make it economic. While comments like this show management are aware of the need to diversify:
Furthermore, the Company continues to leverage its leading early-morning, end-to-end supply chain market capabilities and management look forward to providing an update at the half year results.
I’m just not convinced that they understand that the diversification they need is something that utilises their warehouse space and capabilities, without relying on the early morning distribution of newspapers, which will go completely at some point in the future.
Mark’s view
I can’t be too harsh on the company given how well management are managing the revenue decline here and paying out excess cash to shareholders. However, there is no escaping that physical newspapers will be gone at some point in the future. Unless, the company has a new business model in place at that time, it will be no more. Graham rated this GREEN following the last trading update, but for me, without concrete plans in place for diversification, there has to be an element of AMBER. Perhaps AMBER/GREEN then, overall.
Cab Payments Holdings (LON:CABP)
Unch. at 69.7p - 2024 Pre-close Trading Update - Mark - AMBER
When first reading this update, it read like a profits warning:
Since the trading update in October 2024, the Company continued to be negatively impacted by a stronger dollar, reduction in aid flows and political uncertainty affecting the demand for cross-border payments, impacting both client volume and margin. This trend continued throughout Q4 and as indicated previously, the Company did not benefit from a usual seasonal uplift in revenue in the second half of 2024.
However, they appear to have managed to deliver an in line performance, largely due to cost-cutting:
Operating costs have been rigorously reviewed and immediate action is being taken to right-size the cost base for 2025. H2 2024 operating costs were well controlled with Adjusted EBITDA for 2024 likely to be within the range of analyst consensus estimates.
It is worth noting that adjusted EBITDA leaves a lot of scope for simply excluding the bad stuff, and within range could, of course, mean at the bottom! They say volume held up:
Total Group volumes for 2024 grew approximately 7% to £37.2 billion, in the context of market-wide SWIFT payment flows around the world dropping 4% year-on-year and flows into its core Sub-Saharan Africa market dropping 2% as the Company continues to take market share and deliver for its clients.
But must be facing margin-pressure as:
Gross Income for the financial year-ended 31 December 2024 is expected to be approximately £105 million (2023: £137 million) with performance in the second half of 2024 marginally declining versus the first half.
Which is a miss versus consensus:

Much lower take rates in Emerging Markets appears to have done the damage:
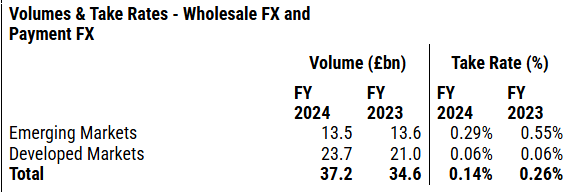
They clearly don’t see this trend reversing soon, as there is a huge headcount reduction on its way:
It is therefore commencing a programme to reduce its head count by approximately 20% including a redundancy program subject to consultation, while also driving higher performance within the organisation.
This restructuring is expected to take place during the first quarter of 2025. It is expected that the impact of headcount reduction savings will counteract the annualisation of strategic hires made throughout 2024, inflation and national insurance rises, resulting in broadly flat growth of staff costs in 2025.
It seems strange that a 20% headcount reduction only gets them to flat costs year-on-year. The saving grace is that the P/E is pretty undemanding:
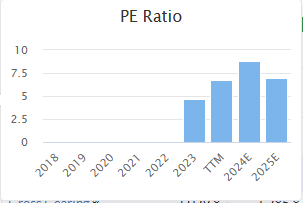
Mark’s view
I’m surprised the market hasn’t taken a more negative view on this trading statement today. While technically an in-line statement, it leaves a lot of wriggle room. Whereas the rest of the update perhaps asks more questions than it answers. H2 weaker than H1, Emerging Market take rates plummeting, a miss on revenue and a huge headcount reduction that doesn’t actually cut costs. The low P/E may yet reveal a bargain if the company can overcome these issues and return to growth. I’d want to see more sign of this before considering anything more than an AMBER at the moment, though.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Interesting email today from Monzo bank around international payments which impacts Wise (LON:WISE)
Not sure how much work Wise gets from Monzo but if more digital banks can offer this then I can see Wise suffering as the streamlined process negates the need of an extra account.
Wise (LON:WISE)
Hi JSchoffer
That's very useful, thank you for sharing.
(with apologies for the possible ignorance of this question - I am not a Monzo customer and do not know how their app works, but I was under the impression that customers could only send GBP in the Monzo App.)
Thanks again for sharing
Not sure how much work Wise (LON:WISE) gets from Monzo but if more digital banks can offer this then I can see Wise suffering as the streamlined process negates the need of an extra account.
Not exactly ...
You no longer need a separate Wise account to transfer money internationally with Monzo because Monzo has partnered with Wise to integrate their international transfer service directly into the Monzo app, meaning you can initiate and complete international transfers without leaving the Monzo platform, effectively eliminating the need to have a separate Wise account to do so; all the functionality is handled within your Monzo app using Wise's technology in the background
Basically this is Monzo powered by Wise, removing the friction Monzo customers previously suffered and further embedding Wise. It's part of Wise's deep integration strategy into domestic payment networks.
The clue to this is that cross border payments are really difficult, there's no way a relatively small bank like Monzo could do this on their own.
EDIT - post crossed with abtan's. His third point is essentially what's happening.
timarr
Thanks Timarr and Abtan, makes sense and bolsters the Wise bull argument. Will keep looking for holes in my investment!
Hi JS
Thanks Timarr and Abtan, makes sense and bolsters the Wise bull argument. Will keep looking for holes in my investment!
Absolutely - it's Charlie Munger's old disconfirm mantra, do everything you can to find the weaknesses.
FWIW my biggest fear for Wise (LON:WISE) is a breach of anti-money laundering regulations, where they somehow become embroiled in a scandal that attracts the US regulator's attention. I can't see any way of insulating myself from that risk, which is why my Wise stake is only half what it otherwise would be.
I should stress I have no reason to think Wise is in anyway doing anything wrong, it's just that it's such a complex area that it's easy to get tangled up in something even if you follow the rules (which are useless and don't work anyway, but this is the world we live in).
Technically, though, what Wise do is really hard to replicate, they have increasingly deep liquidity and the thicket of local regulations they've navigated over a decade is another level of moat. But nothing is ever perfect, or perfectly safe.
timarr
Wise (LON:WISE)
Interesting news article that HSBC have abandoned their attempt at a cross currency app, "Zing": https://www.reuters.com/busine...
Talks about 400 redundancies, so clearly not a trivial project, and the article suggests that it was started to compete with the likes of Wise and Revolut (although it's a news article, so that could be rubbish!).
Wise (LON:WISE)
I hold Wise and there have been enough comments on it today, so 3 quick notes on Revolut:
So anyone interested in transferring money on a regular basis won't use them in the long term when someone like Wise exists.
More info on Revolut's FX fees are here: https://help.revolut.com/en-PT...
They are clearly very different beasts within the FX segment targeting very different customer bases.
Real Estate Investors (LON:RLE)
Hi Mark
Thanks for your analysis. I completely agreed with it, particularly your view on the risk to book values.
I actually held a position last year, but started tracking all the properties they had listed for sale or had sold.
This eventually resulted in me closing my position as it seemed like things were going very slowly and I was sceptical of the dividend being maintained.
In fact, if my tracking is correct (and I think it is because it ties in with the figures in today's announcement) then the last big sale/agreement they made was in August, which seems like a long time ago.
For me therefore there's clearly a risk that book values might come down and the share price with it.
A
Glencore (LON:GLEN) and Rio Tinto (LON:RIO) in talks to move together. Sorry big news not some seller of cards.
Indeed Harry.
But without the Wise card discussion the Daily report comments would have been down about 25%. It seems that something is needed to fill what was once a vibrant thread
Anyway, we haven't yet started to cover other aspects of the Wise service such as savings pots etc.
Thanks Graham & Mark for your time consuming comprehensive report ,truly prodigious .
Wise (LON:WISE) and Revolut are different businesses, although they're meeting in the middle. Comparing them isn't particularly easy, as both companies themselves admit.
If what you want is an international money transfer service then Wise is better - a large proportion of their transfers are instant or near instant, while Revolut will need to go through SWIFT which adds time and risk to the process unless the destination account is also on Revolut.
Wise also allow to you have cards issued by local banks in the target country, which can sometimes be useful if you're trying to register for local apps (taxis for instance). While backpacking around SE Asia last year it was noticable how many local businesses accepted Wise for prepayment. We're very fixated on card payments in the UK, but in many parts of the world they're not the main payment method because they're expensive compared to other methods.
From what I can see it looks like Wise are deliberately targeting deep integration with local payment networks so that they can instantly move money between an account in one country to an account in another. That opens up them operating as an instant cross-border money transfer service for use by corporates like the deal recently signed with Standard Chartered.
But if you want a full service bank account then Revolut is the better option - that's why it has a full banking licence. However, I note that Revolut was named in more fraud reports than any other company last year - although Revolut pointed out that over 60% of that came from Facebook.
Ah, the modern world ...
timarr
Thank you for your excellent review, in Africa for example payment to mobile is common practice and I believe WISE helps facilitate some of these transactions. A firm holder of WISE think it has good growth opportunities
Would recommend digging out the recent Money Week article on Wise. The key to understanding Wise’s potential growth IMO is how they transfer money, why this enables them to be fast and cheap and why no one else can compete.
Essentially Wise do not actually move money across borders which is inevitably slow and expensive (eg Swift, Revolut). Instead they use money that is already where customers want to send it and then debit your account at an agreed exchange rate.
Paul Hill (a.k.a. the most enthusiastic interviewer in finance) interviewed a fund manager named Jamie Ward for The Exchange this month (it's on youtube 2nd January Video). He gave a good overview of Wise too.
Essentially Wise do not actually move money across borders which is inevitably slow and expensive (eg Swift, Revolut). Instead they use money that is already where customers want to send it and then debit your account at an agreed exchange rate.
Hi kevind1875
I know. I'm a payment consultant by day. The Moneyweek article is pretty good though: https://moneyweek.com/currenci...
The Wise model only works between countries where there are large deposits - in more exotic countries they will also use SWIFT or whatever mechanisms are available to them.
However, it's not true no one else can compete - there are plenty of companies trying, but the regulatory burden and the capital needed both represent enormous, and largely unrecognised, moats even before we consider whether the technology is superior.
They could fall into a regulatory pothole, but if they can avoid that it's hard to see the competition catching up.
Note that Revolut is just a bank - they will use whatver mechanisms are available to them to move money. I'd guess they're losing money on their money transfer service, but it may be worth it to attract new accountholders and deposits. Completely different business model to Wise (LON:WISE).
timarr
Carr's (LON:CARR) Time was when the engineering division was a small part of the whole, and the bulk of the profits came from the feedstuffs business. Now they are selling the engineering businesses for rather more than feedstuffs are worth. Is that the right way round? It can surely only be justified if they can return feedstuffs to making the sort of profits they used to earn. I don't hold.
Re:Wise
I use Wise and from my experience it does everything expected and has proved to be useful and reliable.
There are some differences with Revolut as Revolut holds a UK Banking Licence. Wise looks to be subtly changing its offering to position itself away from pure currency transfer - hence possibly the name change.
Before I use these type of services I generally do some research into the business starting with the Wikipedia page.
No position
PS I see a lot of effort has once again gone into today's report with views and comments a bit sparse.
The Wise (LON:WISE) card could be improved, too many fees and restrictions, only £200 per month, from an ATM before high fees kick in. Apparently it not accepted in many shops, unlike Visa and Mastercard. I find Chase Debit card to be far better for travel and there are no fees. Wise you have pay £7 just to get one.
Interesting Rusty
I have not paid any fees for the card - maybe I got some sort of deal.
I don't use the card for cash withdrawals. My main purpose is to use the virtual cards for security and fraud prevention reasons. II like the idea of having 2 virtual cards which can be deleted and replaced immediately.
I don't pay any charges for these. Also being a VISA card it is widely accepted.
I have never had a card declined.
T212 offers virtual cards and I am sure they are the best card for spending abroad at the moment - fees wise inc 0.5% cashback
I still think the Chase is better, 212 only £340 ATM transaction limit and 1% fee on over £400 pm. Many countries have ATM fees, so taking out smaller amounts results in higher fees.
No fees for me either with Wise (LON:WISE) ... only if you take out more than £ 200 per month in cash at an ATM... but cash is not their moat / target market.. moving billions through their pipes is their competitive advantage and as they expand ever further into the wholesale market, that advantage will only get larger IMHO...
Just read today, someone in Bangkok, in large shopping malls, Wise was declined 3 times at different shops, no problem with his other cards. The ATM fees are the main issue.
Chase you can lock the card when not in use. I also have Barclays and Halifax credit cards, which have no fees. I would like to see Wise card to be similar to Chase. Then l may get one.
You don't get a Wise card for withdrawing cash at an ATM .. it's for making fast , secure and extremely cheap payments... I have never been turned down, as intuitive says, it's a Visa card .. from looking at the rates, the Chase card will be comparable for the first £ 1 500 spend per month, but past that , the cashback stops and you're definitely worse off, as the Wise rates are so close to the mid-point of the market...
Why not, l want a card that covers everything. I never spend over £1,500 a month anyway.
Lots of travellers want to use ATMs.
I use a Wise card at ATM's for taking out euros and never been charged- other than sometimes the local bank charge a small %.
From Wise website:
Withdrawing cash from an ATM with a wise card*
Maybe you do 2 transactions, per month, totalling under £200?
No normally €500-600. I did join when transferwise so maybe got a deal ? Or else it has changed. Off to Madrid in March so will see then.
Just logged in- they have changed it .
Actually use little cash nowadays abroad, but will look at options.
Thanks for pointing this out Rusty. Just like so many companies, seduce you in then change the rules. Pretty sure I had no notification.
Wise has always had a £200 limit on withdrawals on my contract. That might explain why there have been no notifications.
It is not an issue for me as that is not why I use the card.
Interesting to see how many people use cash and rely on cash withdrawals.
ONWD factsheet out - 31 Dec 2024 . Mission (LON:TMG) in the Top 10. Looks interesting. Excellent recurring revenues, mkt cap of £28m, p/b 0.37 and psr only 0.14! Insider buy of 82,000 @30p recently.
https://acrobat.adobe.com/id/u...
Lawrence Hulse discusses here (33.25 mins)
https://www.voxmarkets.co.uk/a...
TMG also features as a 2025 NAP tip in a well read tipsheet.
I was hoping that the MPAC (LON:MPAC) trading update today might contain a hint of information about US tariffs as the CEO does refer to the rest of 2025 in his update, but there is no comment about this. A substantial part of the company's revenues are generated in the US and, as far as I can tell, some components for its automated systems are imported to the US. I also note that its recent transformative acquisition included a sizeable subsidiary in Mexico. Probably no worries (I rate MPAC highly) and the tariffs might not materialise but I decided to sell in case tariffs do have a significant impact on its business, with a view to buying back later.
MPAC (LON:MPAC)
I was hoping that the MPAC (LON:MPAC) trading update today might contain a hint of information about US tariffs as the CEO does refer to the rest of 2025 in his update, but there is no comment about this
Thanks for pointing that out always useful to know if there may be issues
Not sure what they are meant to say really - no one knows what trump will do - so its much idle speculation at present until stuff is formally announced - everyone knows Trump shoots his mouth off alot - so i wont blame anyone for waiting to see whats detailed - if the current rants are incoherent and hard to make sense of. I suspect many similar business will be is the same boat - if the costs go up ultimately the customer pays more.
do you have any handle on how much they do in Mexico - if they have sizeable presence in mexico for stuff thats exported to us that might be a higher risk factor that simply having to pay more for imports. It does appear that their Amercas customers in 2023 where very high % us - so it would be nice to know if they have sizeable sales from mexico into us
New update from (the always excellent) ED here
https://www.equitydevelopment....
we have EPS Rptd Dil.(p)
2024 15p 2025 21.1p and 2026 32.4p
and
EPS Adj. Dil. (p)
2024 31.8p 2025 43.4p and 2026 54.7p
net debt now 37 mill** - reducing to next to nowt 2026
Clearly thats a decent trend - but at present al then uplift in numbers is on paper and needs to be delivered
** ref debt slight mismatch between company update and ed calcs which have £26 mill pencilled in. i suspect the text below mostly explains teh difference ?
the Group closes FY24 with net debt of £37.0m (FY23: net cash £2.1m) and a reduction in working capital to £7.0m (FY23: £13.2m), which includes circa £8.0m of invoiced receivables, due in 2024, most of which has been received in early January 2025
I am a content holder who has bought in in the last 6 months - seems like they are on track (they need to be mind!)
Possible impact of Trump's planned US trade tariffs (starts 18:15)
&t=1126sHere you go Peter
MPAC CEO Adam Holland made some comments here (starts 18:15) today wrt the possible impact of Trump's planned US trade tariffs.
https://www.youtube.com/watch?v=ZMKq-ELwQB4&t=1099s
Would some kind soul be able to explain to me what the implication of today's announcement from Carr's (LON:CARR) ? I can understand that they are returning some money to shareholders from the sale of the engineering department. When this happens, what will happen to the share price? Will it re rate lower to take into account that the company is now worth less?
Hi
Some European stock moves, in case some might be interested.
Following on from the US rise from yesterday and catalysed by additional news feeds European stocks are rising nicely. The rally is widespread but from my own limited perspective I note luxury and defence.
COMPAGNIE FINANCIERE RICHEMONT SA (SWX:CFR) reported stronger than expected results.
Short extract from the news feed ...
Jan 16 (Reuters) - European luxury shares soared on Thursday as Cartier owner Richemont's CFR.S third-quarter sales beat revived optimism for the battered sector.
Richemont shares jumped around 16% to an all-time high of 161.40 Swiss francs, surpassing their May 2023 high of 161.10 francs, and were set for their biggest intraday rise since October 2008.
Full report here ...
https://www.stockopedia.com/sh...
As a consequence the whole European luxury sector has notable share price rises, see examples LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) Burberry (LON:BRBY) in UK, Hermes International SCA (EPA:RMS) and Kering SA (EPA:KER) . There are others as well.
I do not currently hold any of these but have done so in the past.
Another sector also rising is European defence. See Leonardo SpA (BIT:LDO) and Rheinmetall AG (ETR:RHM) for example. In addition to several announcements of late, the Trump narrative of wanting 5% defence spending in Europe is also catalysing these rises (I suspect).
I hold both these.
Regards
Howard
The European luxury sector was due for a rerating. My favoured play is Brunello Cucinelli SpA (BIT:BC) -- €900 for a cashmere jumper-- as it appears to have successfully bucked the downward sales trend in China that hit hard rivals like LVMH Moet Hennessy Louis Vuitton SE (EPA:MC), which gets 35% of its sales from Asia.
Brunello is already up 27% in 3 months so I'm tempted to wait until after the Chinese New Year to see if this rally in luxury retailers has legs. Before the pandemic, Chinese consumers were the world’s largest spenders on luxury goods, contributing to one-third of global sales, so any sign of a pickup in demand in China could make the rally more sustainable.
Good analysis here from industry bible Vogue Business:
https://www.voguebusiness.com/...
LVMH, Europe's largest luxury company, reports results on Jan. 28
Jeff
Hi Jeff
Thanks for the added commentary. I have not looked at Brunello Cucinelli SpA (BIT:BC) thanks for the heads up. I will add it to my luxury watch list.
Regards
Howard
Graham - you have mixed up your Pebbles!
Pebble (LON:PEBB) is the company that has issued a preclo statement today
Pebble Beach Systems (LON:PEB) was on Tuesday
The latter is the result of the collapse of the old Vislink and began as a massive pile of debt with the surviving subsidiary company attached. From 2017:
It has had good cash flow so that Tuesday's statement says:
Net debt at the period end will have reduced by c.22% from last year to £3.7m (FY23: £4.8m).
Cavendish now predicts net debt £1.2m at 31/12/25 and net cash £1.3m at 31/12/26
We fixed it sharw! yes, I did mix up the pebbles first thing. Thanks.
Brooks Macdonald (LON:BRK) - Missed this yesterday but intrigued that they have decided to leave AIM and join the main Mkt. The trouble with AIM is that there are far too many tiny coys that simply should not be there at all. This does the mkt no good at all. But, there are plenty of profitable larger coys and I suspect that as time passes many people will be encouraged to invest in eligible AIM companies within their SIPP in order to gain at least some relief from IHT What do others think ?
I appreciate there are a lot of companies reporting today but shouldn’t Dunelm (LON:DNLM) be covered? As one of the stronger players in the retail sector it should offer a good indicator of consumer confidence. The results don’t inspire a huge amount of confidence going forward and Q2 performance was weak. Share price looks to be on a downward trend so would be interested to hear the teams view.
Dunelm (LON:DNLM) share price down after their update, continuing a steady share price decline. Note this paragraph; it’s provbably the that most spooked investors:-
“Finally, we are mindful of the impact of the Autumn Budget announcement on our business, suppliers and customers. As a large employer, with over 11,500 colleagues, we have previously highlighted the impact of ongoing wage inflation. Whilst the National Living Wage increase was largely anticipated, the increase in employer National Insurance Contributions is an additional cost headwind. Initiatives to drive productivity across the business are underway, and as these initiatives mature, we anticipate mitigating the upward pressure on costs over the medium term.”
So many businesses are facing this pressure; retail (especially) , building, hospitality etc . For the likes of Dunelm (LON:DNLM) an added worry is Chinese Company TEMU. I used to hold but not tempted now.
Nice report from your boys at NIOX BnB!
Nice report from your boys at NIOX BnB!
Hello Cantab. Hope you are well. Yes it was. Very cash generative and a leading market position. Full position in the fund.
Fair play to Graham and the team for publishing the list of company news so efficiently. I scanned this morning’s RNS and missed the updates from Avingtrans (LON:AVG) and Premier Miton (LON:PMI, companies which I hold, so had to backtrack to catch up.
An interesting reaction to inflation data, and so a mixed number leaning towards weak led to a rally in Bonds and equities. I have been tracking CPI-U because the data set is longest. Since May 2024 the Month on Month change has been below 0.2%. This month it was flat. Spikes in energy and food have slowly washed through. As previously highlighted the numbers falling away in the first months of 2025 are also high and so if the trend of the last 7 months continues then in the US, inflation pressure will have eased significantly and be considered in range.
So it looks like Trump inherits a tailwind of an interest rate backdrop. It is assumed that tariffs are inflationary but who knows, we don't even know what tariffs will be imposed. Cuts to government spending should not be inflationary...but again we don't know how this will play out either. If the former is muted and the latter aggressive... this could be positive for asset prices. The reverse not so.
If that sounds confusing it's because it is. However we should not confuse the economy with the market. The UK is cheap and broadly speaking we have some good news, on inflation and the conflict in Gaza. So it makes sense that asset prices breath a sigh of relief... Rachel for one must be very pleased.
Back to results and the good fight, best of luck out there.
What good news from the UK? Increasing salaries and national insurance is highly inflationary and makes it tougher for local businesses.
Once budget changes kick in inflation is inevitable, prices will rise
One reason why inflation dropped, was airfares because they used the prices on Christmas Eve, which is not such a popular day to fly.
Energy prices went up in January not by much, but they could rise again in April, if gas prices don't fall. Petrol/diesel prices are up this month.
Minor point Graham but I much appreciate the cleaner format to the layout here at the start of the day. I'm pleased with the table format and not to have to scroll past a whole load of readers term and conditions.
Thanks TEIN!
Smiths News (LON:SNWS)
What does this cryptic statement hint at? Implies something new in the pipeline?
Alongside ensuring we continue to deliver a first-class service to our newspaper and magazine customers, we remain focused on further capitalising on our proven early morning capabilities in order to further enlarge our operational footprint.
"I look forward to updating shareholders on our progress at the half year results in May."
Hi Revs8. I don't hold Smiths News (LON:SNWS) and haven't read the update either. However, in logistics, early morning delivery capabilities are/can be very valuable for parcel delivery and other networks. Newspapers and Magazines are dense products, probably resulting in a fair amount of fresh air being carried on Smiths News (LON:SNWS) vehicles. Filling this empty space on vehicles with other paying freight (whatever that may be) can leverage capacity already paid for and increase margins. This is just a pure guess and I may be completely wrong.
This is correct. They will be using the empty space to pick up recycling, get paid to pick up refuse and also, selling that refuse on. This was confirmed by the CEO in their last video call.
They’ve been running this scheme for the past couple of years but new legislation being introduced in March should ramp it up. Here’s where to find the details….
https://recycle.smithsnews.co....
Smiths News (LON:SNWS) it’s not a bad guess. Imagine some sort of tie up with (I know sounds pie in the sky) Amazon for larger items delivered to sites already with capabilities to take Amazon parcels . Sounds strange but is it?
Not so strange at all Douglas1971. A slice of deliveries to Amazon Lockers would probably be ideal as most of that delivery volume is small sized. As an added bonus, picking up customer/shopper returns from the lockers (as the vans will be empty by then and have plenty of capacity) for drop-off at an Amazon depot could really add very nicely to operational efficiency and, ultimately, margins. You could expect Amazon to seek the keenest possible price for this work though.
Smiths News (LON:SNWS)
Am I the only one who doesn't see Newspapers and magazines dying out in the foreseeable future. I don’t see newsagents up and down the country closing there doors and i think that a lot of people prefer there news or magazines in a readable paper format and without having to scroll past those pesky adverts. I’m guessing of course but maybe they will reach a platau and the stablise .And the likes of Supermarkets Garages etc need them to entice customers into their retail spaces . And i don’t see that many Newspapers going bust so maybe they want to continue with publishing Newspapers and Mags ( not to mention football sticker albums and other popular crazes that come and go .)
It will be a interesting few years coming up .
Now i’m off to read my newspaper and maybe have a read of the Radio TimesMagazine
Do supermarkets sell newspapers anymore, can't recall seeing them for years.
My local shop sells a few but nothing like 10 years ago. Even WH Smiths has closed down, l stopped buying one over 20 years ago. You can get them free in London. Newspapers probably are surviving by their online advertising. It is much cheaper online than printing them on paper.
Am I the only one who doesn't see Newspapers and magazines dying out in the foreseeable future. I don’t see newsagents up and down the country closing there doors and i think that a lot of people prefer there news or magazines in a readable paper format and without having to scroll past those pesky adverts.
The main problem is that the infrastructure needed to support everything will have certain fixed costs that have to be spread over less. There must be a point at which the numbers might not stack up - unless diversification is involved to cover those same overhears. So to me at a minimum they need to ideally have a plan to pimp out the necessary fixed costs with something else that brings in the dough - or some similar cunning plan - you might be right though - heck records seem to have made a comeback - perhaps i will be getting a sony walkman for xmas this year
I agree with your sentiment even although magazine prices are rising, I still buy when visiting a supermarket, same price as a pint. Good mgt will make the strategy work and the company has a good dividend approach tempted to buy more
UK HOUSE PRICES: British property surveyors reported the fastest rise in house prices since September 2022 in December and a continued increase in sales and new buyer enquiries, in contrast to the more mixed picture from some other housing market surveys.
Might be sign of improving sentiment for any building related stocks. I hold Brickability(LON:BRCK) Eurocell (LON:ECEL) and Stelrad (LON:SRAD) .
Lords Trading (LON:LORD) hopefully benefits too. Cavendish view in December:
Valuation: The current share price represents a deeply discounted valuation in our view. The shares trade on an EV/Sales ratio of 0.2x, or 0.3x after adjusting for lease financing. This compares with a historical range of 0.5-1.0x for the merchanting sector. Our target price of 72p has been recalibrated in line with our widened Building Materials & Construction sector universe approach, and represents 99% upside to the current price.