Daily Stock Market Report (Thur 17th September 2026) - BILN, SUP, TBTG, DRX, BYIT, DEBS, VCT

Federal Reserve: as expected, the Fed raised rates to 3.75-4% yesterday, and as expected, President Trump expressed his dissatisfaction (writing “LOWER THE INTEREST RATES” on social media!).
Fed Chair Kevin Warsh said "We removed a dose of accommodation so that financial and credit conditions would be more consistent with our ultimate objectives," and most Fed officials seems to support another rate hike before the end of 2026.
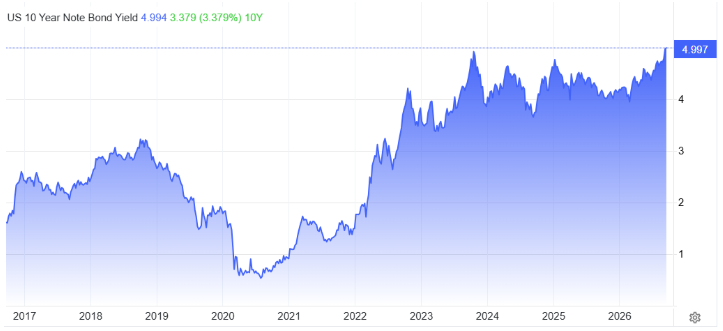
The US 10-year bond yield continues to hover around 5%, which is a long-term high, as the Fed works to gain credibility on the subject of inflation.
UK inflation/BoE: the UK’s headline inflation rate increased to 3.1% in August, but the “core” rate was unchanged at 2.6%. Both readings were in line with consensus. The Bank of England is expected to keep rates steady today at 3.75%, with uncertainty around whether or not a rate hike will be seen this year. There will be plenty of commentary from the BOE to digest later this afternoon.
Overnight market movements:
The FTSE is up 0.2% at 10,715
S&P 500 is up 0.6% at 7,595
Brent crude (November) is down 1% at $104.75/bbl
Gold is up 1% at $4,305/oz
Bitcoin is up 0.25% at $76,350
We are done for today, thank you. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Drax (LON:DRX) (£2.76bn | SR92) | Strong operational performance. Full year 2026 expectations for Adj. EBITDA around top of range of consensus estimates. Analyst consensus was £698m, with a range of £680 – £711m. | AMBER ↑ (Mark) | |
Unite (LON:UTG) (£2.5bn | SR33) | 95% of Unite beds reserved for the 2026/27 academic year (2025/26: 95%). Expect 0.5-1.0% like-for-like income growth. Guidance reiterated for adjusted EPS of 41.5-43.0p in FY2026. | ||
Helios Towers (LON:HTWS) (£2.1bn | SR41) | Board has approved an incremental return of up to US$100m to shareholders through an extension of the buyback programme. Increases buyback US$75m to US$175m. Expected completion pushed back to Dec 2027. | ||
Bytes Technology (LON:BYIT) (£925m | SR65) | Group has traded ahead of expectations in the first half of FY27. Gross Profit estimated to increase by c.18% and Operating Profit by c.6%. Board now expects Gross Profit growth for the full year in the low to mid-teens, with low to mid single-digit Operating Profit growth. | AMBER/RED = (Mark) Roland viewed this most negatively following their FY profits warning in March. I don’t think a slight upgrade for the current year should change that view when the stock has a high PEG ratio and a trading performance that looks well behind sector peers. | |
Galliford Try Holdings (LON:GFRD) (£618m | SR84) | Revenue +3%. Adjusted PBT +24.2% to £55.9m. Year-end cash £259m. Confident outlook for further progress in FY2027. Good visibility with 90% and 62% of the current financial year and FY28 projected revenue secured. | ||
ACG Metals (LON:ACG) (£457m | SR50) | Revenue +27% to $71m. Gold equivalent production of 18,487 oz exceeded the full-year target of 17,500 oz. AISC increased by 52%, reflecting lower volumes in line with mine plan and higher royalties linked to higher gold and silver prices. Financial net debt $140m. | ||
Boohoo (LON:DEBS) (£397m | SR48) | GMV grew 1.8%, accelerating in Q2. Gross margin improved to 53.9% and return rate declined by c. 4%. Adjusted EBITDA up 13.9% to £24m, reported EBITDA improved from £3m loss to £20m profit. Outlook: Adjusted EBITDA as previously guided and in line with consensus of no less than £59m. | AMBER/GREEN ↑ (Graham) | |
Beauty Tech (LON:TBTG) (£388m | SR65) | Revenue +44%, adjusted EBITDA +53%, adjusted PBT +49% (£15.3m). Actual PBT £17.5m. Outlook: revenue in line with previously upgraded guidance but Adjusted EBITDA to be ahead of prior guidance, and no less than £48.5m. | AMBER/GREEN ↑ (Graham)
My IPO rule is that newly-listed stocks should be treated cautiously for about two years, and we should presume that they are overvalued at the time of their IPO. TBTG is breaking the rules with a high-quality financial performance and with earnings upgrades that help make a case that if anything, their stock is undervalued rather than overvalued. Management’s decision to go down the route of buybacks rather than dividends is also a strong statement that they believe in their own undervaluation. I could go fully GREEN on this today but I’d prefer to gradually warm up to the story, so I’ll increase our stance by one notch only. | |
Guardian Metal Resources (LON:GMET) (£328m | SR10) | FY LBT $10.0m (FY25: $2.7m LBT). Net Cash $52.5m (FY25: $1.9m), after $83.7m net raise in the year. Company has an important opportunity to lead the re-establishment of US-mined tungsten production and support the development of a U.S. tungsten supply chain. | ||
Ab Dynamics (LON:ABDP) (£190m | SR30) | Performance for FY2026 is expected to be in line with the guidance provided in July and current market expectations. Revenue £91.6m, adj. operating margin c.20%. Net Cash 31 Aug £24.5m. Order Book £31m. | ||
Supreme (LON:SUP) (£165m | SR73) | Following a solid start to FY27, Supreme expects trading for the year to be in line with market expectations (revenue of £302.1m and Adj. EBITDA of £39.6m). Fully prepared for the introduction of Vaping Products Duty on 1 October 2026. | AMBER ↓ (Mark) | |
Strategic Minerals (LON:SML) (£133m | SR36) | Completion of multiple drillholes, across 3 drill pads, for a total of 5,000m drilled to date. With over 17,500m left to drill, the programme is on time and within budget, following the mobilisation of Rigs 2 and 3. | ||
Home Reit (LON:HOME) (£77.9m | SR22) | Each of the Subsidiaries have now been placed into creditors' voluntary liquidation. | ||
Victoria (LON:VCP) (£66m | SR66) | Organic revenue growth +4% YTD to the end of August. EBITDA to the end of August, excluding Rugs' transitory losses, ahead of the prior year. A total of £70m in property sales being targeted in FY27, and of this, c.£26m have already been completed. Refinancing: secured the required level of support from its Senior Secured Noteholders representing over 90 per cent. | RED = (Graham) Victoria are 100% correct that the proposed refinancing transactions are of enormous benefit to the equity: outstanding debt and preferred share liabilities will reduce by £300m, and the amount of dilution is not nearly as high as it might have been. When I looked at this in September, I saw 68 million new shares being printed (current share count: 115 million). So the equity has been treated kindly so far. However, 2028 noteholders are for the most part receiving 2031 notes, not shares, and so the total amount of leverage will remain very high: net debt as of March 2026 was nearly £900m even if we exclude preferred shares and leases. Victoria are promising "a favourable outcome for stakeholders and substantial value for Shareholders". But the preferred shareholders have already taken a huge blow and I expect that continued heavy dilution is the most likely outcome for ordinary shareholders | |
ECO Animal Health (LON:EAH) (£64m | SR86) | USDA-CVB has confirmed that ECO’s US field safety trial data for ECOVAXXIN® MS, its poultry vaccine against Mycoplasma synoviae, fulfils the requirement to support licensure of the product. | ||
Billington Holdings (LON:BILN) (£54.3m | SR81) | Two further significant contract wins with new clients for data centre projects with an expected combined value of circa £42 million. “These awards add significantly to our now record order book and provide excellent visibility through 2027 and into 2028.” | AMBER/GREEN = (Mark - I hold) | |
Trufin (LON:TRU) (£50.1m | SR95) | H1 Net Revenue +17% to £5.3m, Adj. EBITDA £0.5m (25H1: LBITDA £0.1m), LBT £1.5m (25H1: £1.9m LBT). Now expect Satago to record its first full year of positive EBITDA for 2026, ahead of previous expectations. Overall, trading in line with expectations. It is expected to be loss-making for the full year 2026, with a target of achieving full-year profitability in 2027. | ||
Revolution Beauty (LON:REVB) (£37m | SR41) | H1 revenue broadly in line with last year, but with a gross margin +10%. Expects to report H1 adjusted EBITDA of not less than £2m (25 H1: £12.5m LBITDA). Considers that the Group is trading comfortably ahead of market expectations. | ||
Manx Financial (LON:MFX) (£30.6m | SR39) | Three UK finance subsidiaries, The Business Lending Exchange Limited, Manx Collections Limited and Blue Star Business Solutions Limited combined and will operate under a single market facing brand, Triskel Finance. Triskel PBT expected to increase by £1.0m in 2028 to £1.1m. | ||
Atome (LON:ATOM) (£27.8m | SR-) | Will today serve a Notice of Dispute and Intent to Submit a Claim to Arbitration on the Republic of Paraguay. | ||
Mission (LON:TMG) (£24m | SR80) | “Mongoose” and Bray Leino Events combined. Bray Leino and krow group combined. | ||
SysGroup (LON:SYS) (£20.9m | SR68) | Continuation of the very positive sales and margin trajectory reported earlier in the year as they approach the end of H1 FY27. Remains confident that the Group will deliver full-year results in line with current market expectations. | ||
Energypathways (LON:EPP) (£20.6m | SR12) | Signed a collaboration agreement with Finland's Hycamite TCD Technologies to evaluate its high-grade graphite and low-carbon hydrogen production technology for EnergyPathways' planned hydrogen plant. | ||
Insig Ai (LON:INSG) (£13.6m | SR0) | FY Revenue +45% to £0.77m, Op. Loss £1.9m (FY25:£6.1m Loss). Net debt £1.9m, after £1.35m raise in period. “Despite a slow start to revenue in the current year, sales in July and August averaged £0.1 million per month.” | ||
Serval Resources (LON:SRVL) (£11.9m | SR16) | Geophysics surveys completed on the Somelo prospect and nearing completion on the Sweet Thorn Pan prospect. Processing of data has commenced and is expected to be completed in October 2026 |
Graham's Section
Beauty Tech (LON:TBTG)
Up 13% at 395p (£437m) - Interim Results & Intention to launch share buyback programme - Graham - AMBER/GREEN ↑
This is a recent listing, having joined the main market less than a year ago.
I initially looked at it when it IPO’d and then again in April.
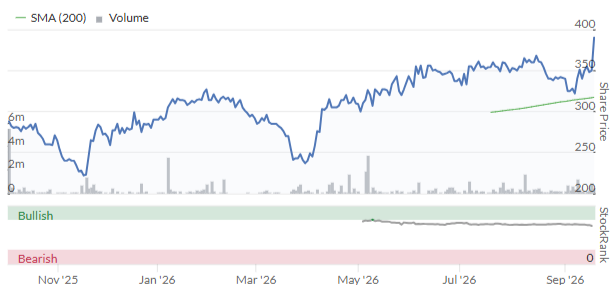
I’ve been cautiously neutral on it, but its share price has been really strong. It’s up 44% compared to its IPO price:
These interim results are sparkling:
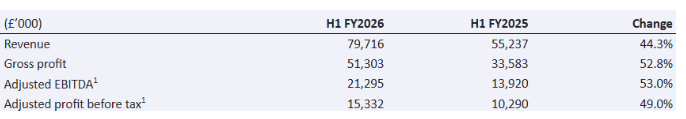
Actual PBT (£17.5m) is even higher than adjusted PBT (£15.3m).
Let’s remind ourselves of what they do:
Currentbody: LED light therapy face masks (reducing lines and wrinkles, hair growth, changing skin tones)
ZIIP Beauty: hand-held electronic devices for the face.
Tria Laser: hair removal.
During H1, Currentbody completed development of its latest range, and these are launching in H2. This is the most important division in the group, responsible for £71m of revenues in H1 (about 90% of the total).
In other news, the company is opening its own lab in early 2027. It’s also working to set up its own European warehouse.
Outlook:
The Board remains confident in delivering full-year revenue in line with the upgraded guidance announced on 7 July 2026 of no less than £170.0m. However, with the strong Adjusted EBITDA margin expansion in H1 FY2026 and increasing confidence in delivering on a typically stronger margin profile in the second half of the year, the Board now anticipates Adjusted EBITDA for the full year to be ahead of its prior guidance, and to be no less than £48.5m
The guidance given by the company in July was for adjusted EBITDA of no less than £45m, which itself was an upgrade on market expectations of £41.5m.
So that makes for a total upgrade of 17% on original expectations, with the upgrade today being c. 8%.
It’s interesting that today’s upgrade does not include a revenue upgrade. I have no problem with that personally: revenue growth is already very strong and if profitability on existing revenues has improved, that only makes for a higher-quality business.
Dividend/buybacks
There’s a very healthy net cash balance of £52m, which leads to some capital allocation questions.
The company is answering these questions with a £20m buyback and no dividends.
Their rationale is simple enough: they have “a robust balance sheet with a substantial cash balance and resilient free cash generation”, and are “committed to maintaining balance sheet efficiency and delivering optimal returns for shareholders”.
They don’t make any particular argument as to why their shares are attractively priced. So it’s up to us to decide if we think this makes sense.
The P/E multiple as of last night:
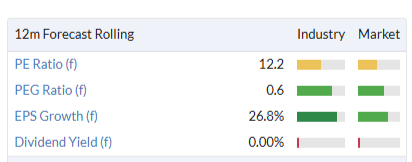
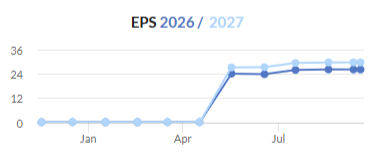
Estimates: Cavendish left their forecasts unchanged in today’s morning note, waiting for the analyst meeting before upgrading. If I naively increased their FY26 EPS forecast by the same percentage as the EBITDA forecast increased, I would get a new EPS forecast of 28.6p.
I would therefore get a P/E multiple of slightly less than 14x at the current share price.
Is that good value for a buyback? I can see why it might be, for a successful, growing business.
Graham’s view
My IPO rule is that newly-listed stocks should be treated cautiously for about two years, and we should presume that they are overvalued at the time of their IPO.
TBTG is breaking the rules with a high-quality financial performance and with earnings upgrades that help make a case that if anything, their stock is undervalued rather than overvalued.
Management’s decision to go down the route of buybacks rather than dividends is also a strong statement that they believe in their own undervaluation.
As for quality, Stockopedia calculated a ROCE of 22% for last year’s performance. TBTG’s more generous calculation of “operating ROCE” says that they’ve improved from 58% last year to 65% in H1.
Whichever source you use, it’s a high-quality performance.
I could go fully GREEN on this today but I’d prefer to gradually warm up to the story, so I’ll increase our stance by one notch only. But there’s something very interesting happening here and for investors who are comfortable looking at new ideas rather than sticking to well-known names, this looks like a great candidate for more detailed research.
Boohoo (LON:DEBS)
Up 1% at 24.8p (£382m) - Trading update for the six months ended 31 August - Graham - AMBER/GREEN ↑
Does anybody else find it amusing that this company is still legally boohoo group plc? Debenhams Group is merely their trading name: they couldn’t change their legal name due to the objections of Mike Ashley/Frasers.
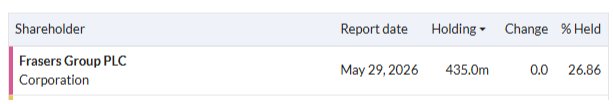
Mike Ashley can't be too upset with these numbers. H1 FY27 is the six months to August 2026:
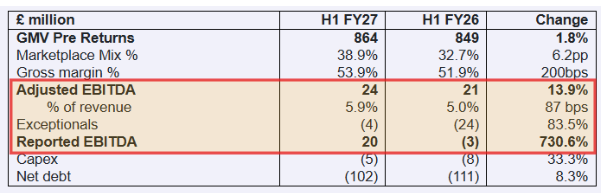
Note that exceptional costs have dropped dramatically, from £24m to only £4m, so “reported EBITDA” is very clean at £20m, only modestly lower than the adjusted figure. And much better than the EBITDA loss that was reported in H1 last year.
Growth was broad-based and accelerated during the course of H1:
GMV grew 1.8% year on year, with growth of 0.5% in the first quarter (“Q1”) accelerating to 2.9% in the second quarter (“Q2”). Performance was most notable across the Debenhams brand, where GMV grew 14.1% to represent c.41% of Group GMV. Pretty Little Thing, boohoo and Karen Millen have all returned to growth.
Two key clothing ecommerce metrics have improved: gross margin and returns.
Gross margin has shifted from 51.9% to 53.9%, while returns are down by c. 4%.
I don’t think it’s a stretch to say that these two metrics, more than any others, are the foundation of a successful online clothing business. So this improvement is highly significant, in my view.
Capex fell from £8m to £5m, which bodes well for free cash flow.
Net debt ended the period at £102m but there’s been really good news on that front in the past month: they are leaving their Sheffield distribution centre and selling all of the equipment in it, receiving a total of £90m by early next year (in fact most of the cash has already been received). The change in business model will see them using a 3rd-party logistics provider instead of operating a large distribution centre themselves.
They’ve also sold Nasty Gal for USD $16m.
Outlook: in line. Adjusted EBITDA for the year of “no less than £59m”. This implies a big performance in H2, with nearly 60% of adjusted EBITDA due in the second half.
Graham’s view
Debt is no longer a real concern and I think that recognising this means taking our stance up to a more positive level.
Roland was neutral in June which itself was an upgrade on our previous perspective.
Today I’m turning AMBER/GREEN.
When it comes to selling cheap clothing to young people, I’m still not sure if it’s possible to compete with even cheaper alternatives (i.e. Shein).
But Debenhams/boohoo are putting their best foot forward. The transition to an “asset-light” business model, emphasising the company as a “marketplace” for other brands, is an enormous change that seems to be already improving performance.
And they are now much better diversified than they were when boohoo/PLT were the main brands.
Finally, I think the UK is going to get involved, like the EU has already done, in assisting domestic companies by implementing measures against cheap Chinese competitors. Things might get more complicated for Shein, starting in 2028.
So I think there are enough positives here for us to be mildly positive at this stage. The elimination of the vast majority of net debt is the single biggest change since the last time I looked at this one. Let’s see how much of this £59m of EBITDA they can convert into real profits and cash flow.
Mark's Section
Billington Holdings (LON:BILN)
Up 8% at 439p (£54.3m) - Contract Wins - Mark (I hold) - AMBER/GREEN =
It is often said that in the US Gold Rush the providers of picks and shovels did best. Some individual prospectors will have struck it rich. But the suppliers of picks, shovels, and general provisions were among the most reliable and consistent beneficiaries of the gold rushes. Notable examples include Samuel Brannan, who became a millionaire by buying up mining equipment and selling it to prospectors at a massive markup. Or Levi Strauss, who started by selling rugged tent canvas and later moved into heavy-duty riveted denim for miners.
In the current AI boom, chip manufacturers have been the most obvious picks and shovel play. While the Microsoft share price is down 16% over the last year, DRAM manufacturer Micron Technology is up 410%.
The spend of the “hyperscalers” in the race for AI gold shows no sign of slowing, and the benefits are being seen in “picks and shovels” further down the supply chain. It is demand from AI-led data centres and related infrastructure that has been behind Somero’s recent recovery. Today, Billington announced that they are seeing the benefits too:
…two further significant contract wins for data centre projects with an expected combined value of circa £42 million.
When the company announced a data centre win in April, they flagged the potential for further wins in this space. The first project is planned for completion in FY27, the second will continue into FY28, so revenue will likely be recognised in those years.
Broker Forecasts:
As with July’s announcement of £28m of non-data centre contracts, Cavendish consider these to be in their existing forecasts, saying:
We maintain our forecasts pending the forthcoming Interim results scheduled for 29 September 2026.
However, the normally conservative management flag that these contracts “add significantly to our now record order book and provide excellent visibility through 2027 and into 2028”. It is possible that this is similar to the listed government IT providers where multiple contract wins were said to “underpin forecasts” before an inevitable upgrade arrived.
Valuation:
Even if there is no upgrade to FY27 numbers in the short-term, Cavendish points out:
The shares trade on an attractive FY27E P/E of 7.9x and an EV/EBITDA of 2.1x (with net cash representing c.48% of its market cap).
These metrics look too low to me for a well-run, conservative business with a record order book, so I hold the shares. However, I note that the real standout metrics are the EV ones, due to the large cash balance. So far, the management seems reluctant to put this cash to use. Perhaps that conservatism is working against them, as they describe the cash as a buffer in challenging times. I also wonder whether the recent closure of their Yate facility means they don’t want to be seen taking big corporate actions or returning capital to shareholders in the short term. Whatever the reasons, I think the cash balance has now gone beyond a sensible buffer, and they need to “use it or lose it”.
So far the shares have risen about 8% on this news, which seems a lot for what is so far an in-line update. However, given the valuation metrics are more aligned with the market expecting a miss on FY27 numbers, anything that builds confidence that they are in line is positive.
Stock Ranks:
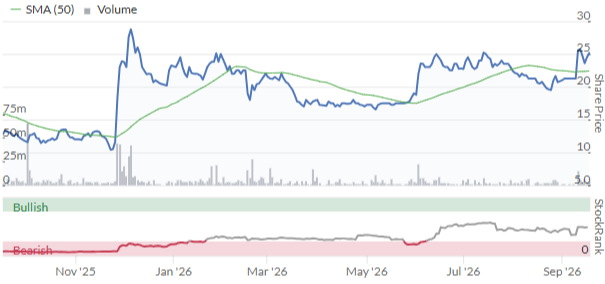
The company has a strong but not outstanding StockRank:
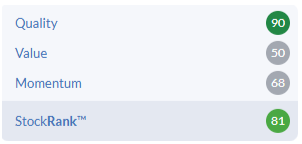
The Value ank reflects the weak FY25 numbers. Assuming there is no material warning for FY26, I expect the Ranks will jump back to Super Stock status with future results. Quant investors may want to wait for confirmation of that jump, at the risk of paying a higher price.
Mark’s view
These wins reinforce my view that this stock looks too cheap for a conservatively run company with a strong full-cycle ROE and a record order book.
That said, it is a cyclical industry and last year’s results show what happens when market conditions conspire against them. I would also prefer they do something with their excess cash in the short term or return it to shareholders.
Overall, I am happy to keep Roland’s previous AMBER/GREEN view.
Supreme (LON:SUP)
Down 2% at 138p (£165m) - AGM Trading Statement - Mark - AMBER ↓
This is an in-line AGM update, and they helpfully give us the past and forecast EBITDA figures. However, what stands out is that these aren’t really going anywhere:
- FY25: £40.5m
- FY26: £40.6m
- FY27: £39.6m
In line is slightly below where they have been in the past. This is despite the acquisition of a number of consumer brands or businesses in the past couple of years.
Looking at the last set of results, the challenge is clear. 55% of revenue and 60% of gross profit came from vaping:
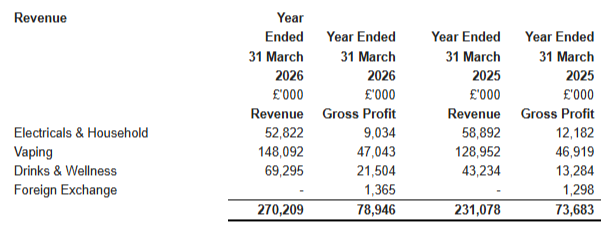
This is an area that is facing increasing regulatory and tax burden. They address this in today’s update:
The Group remains well positioned to deliver organic growth and resilience in the vaping market and is fully prepared for the introduction of Vaping Products Duty on 1 October 2026. The new duty will be charged at 22 pence per millilitre across all vaping liquids. This means a 10ml bottle will attract £2.20 of duty, while a two-pack of 2ml pods will attract 88 pence, before the impact of VAT. Supreme supports the Government’s objectives of creating a more regulated and compliant vaping market.
Including VAT, the shelf price increase for a 10ml bottle is £2.64. A quick Google AI summary suggests the current average 88Vape price is around £1.20 for 10ml “Nic Shot”. The new price will be £3.84, more than 3 times the price. A 50ml “short fill” will more than 4x going from £4 to around £17.
There is a grace period for existing stock until 31st March, and users may well have pulled ahead demand into the current period, which may delay the financial impact into FY28. The company may be relatively sanguine about this change, and it may see some benefits if there is a crack down on unregulated vapes. However, I struggle to see that a 3-4x price increase for their most profitable products isn’t going to have an impact on consumer demand.
Obviously the company has the benefit that their core product is addictive. However, I think it is too soon to conclude that these changes won’t have a material impact on the business. It seems that the brokers may have been starting to anticipate the impact too:
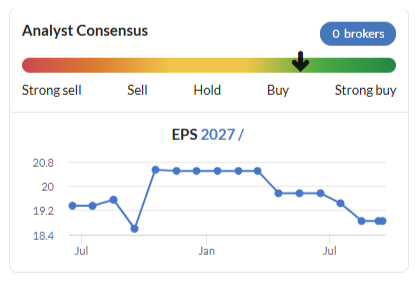
This still implies a forward P/E of around 7, which is low for a company with no real debt and a 20%+RoE. However, if the big price increases on vaping fluids do have an impact on demand, then this EPS figure would surely shift to a much lower level, given the company’s high exposure to this product.
Mark’s view
When Roland last reviewed this he kept our previous mostly positive view. However, at the time this was backed up by a high and rising StockRank. Today, the recent broker downgrades and associated share price reaction have taken their toll on the Ranks:
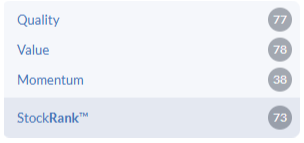
It may seem strange to reduce our view on an in line statement for a company trading on a forward P/E of 7. However, at this stage we just don’t know what a 4x price increase on their key products is going to do to consumer demand. In light of this, I think we should take a more cautious stance of AMBER, at least until it is clear the vaping duty hasn’t severely impacted the company’s profitability.
Drax (LON:DRX)
Flat at 825p (£2.76bn) - Trading Update - Mark - AMBER ↑
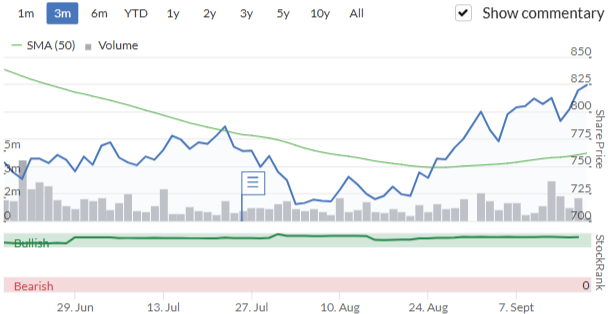
Drax reports “Full year 2026 expectations for Adj. EBITDA around top of range of consensus estimates.” However, the market has shrugged its shoulders. This may be because the guidance range is pretty tight at £698 consensus, with a range of £680 – £711 million, so this is at best a 1.9% upgrade. It also seems to have been expected, with the share price reacting positively to the demand for energy, and increased prices over the summer:
While FY26 has seen upgrades recently, FY27 has been going the other way:
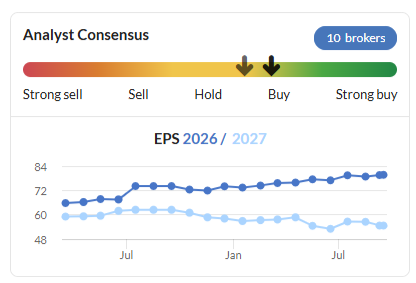
This means a forward P/E of 10 looks like a more challenging 15 for the year after. This may simply reflect more conservative energy pricing assumptions going forward, which may or may not come to pass. However, I think another factor is at play.
Subsidies, subsidies, subsidies:
Drax operates the UK's largest power station in North Yorkshire with 2.6 GW of capacity, having converted four of its six former coal units to biomass, making it the world's largest decarbonised power station. That plant alone still contributes around 6% of the UK's total electricity supply, burning almost entirely imported wood pellets.
Drax has relied heavily on government subsidies of around £700m a year. That's meaningful next to EBITDA that was £1.2bn last year and around £700m forecast for this year, making Drax highly exposed to whatever the subsidy regime does next.
That regimedeliberately is now being wound down deliberately. The UK government and Drax agreed a deal halving subsidies from 2027 to 2031, in exchange for a commitment to source all woody biomass sustainably.
Wood pellets as a sustainable fuel have been controversial, with many pointing out that cutting down forests and shipping the wood to the UK to burn may not be considered sustainable. However, the FCA investigation into Drax's sustainability claims around Canadian biomass closed in June 2026 with no further action taken.
Under that new arrangement, generation is expected to fall by around 55%, taking Drax's share of UK electricity supply down to about 1.8% by 2030, and subsidy costs down to roughly £1.2m a day from about £2m a day currently.
In this environment, it is unsurprising that Drax has been focussing on diversification. In July, Drax completed its acquisition of Bluefield Solar Income Fund, adding 0.9GW of operating and under-construction solar and wind assets plus a 2.9GW development pipeline. This made its combined renewable and flexible generation capacity above the 2.6GW of the Drax Power Station for the first time.
The trend is away from biomass that is only really economic due to subsidies, to true renewables:
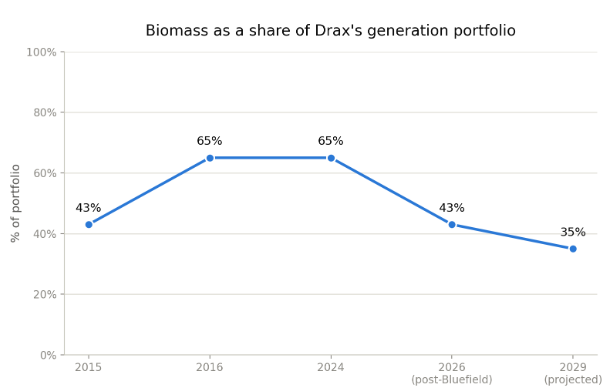
The regulatory risk may have gone away in the short term. However, I think the result is a less profitable medium-term outlook.
StockRanks:
The StockRanks rate this as a SuperStock:
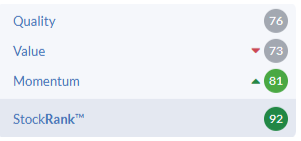
However, I am a bit cautious about this. Declining forward profitability from reduced subsidies will cause the Value Rank to decline going forward. This will also be reflected in lower Quality and Momentum Ranks.
Forecasts:
The only research I can see from Longspur suggests FY27 will be a low point, with EPS growing in FY28 and FY29 as solar projects come on stream. FY29 EPS is still forecast to be some 35% below the FY25 numbers, though.
There’s a 4% dividend yield, but I struggle to get excited by this. Especially as there was £ 1 bn of net debt at 30th June, prior to the debt-funded acquisition of Blue Solar for £561m, with an enterprise value of £1,082m. Overall indebtedness is likely to be over £2bn, which looks a little punchy compared to their £700m EBITDA. Longspur forecasts this to come down to 2.5x EBITDA by the year end.
Mark’s view
While FY26 looks reasonable, declining profitability in FY27 makes the company look more expensive on a forward-looking basis. There is possible upside from the recently acquired wind and solar generation, particularly if UK energy prices remain elevated. There is also some optionality from the ability to co-locate data centres at the Drax power station.
However, this is offset by the risk of further reductions in biomass subsidies, on which they remain highly dependent. Plus, they are now at the limit of what investors would want to see in terms of leverage.
We’ve not reviewed this on the DSMR for a while. Graham had this as AMBER/RED when the news of the FCA investigation broke. While this ultimately passed without action, the reduction in subsidies is going to impact profitability going forward, so a neutral view seems about right. AMBER
Bytes Technology (LON:BYIT)
Up 12% at 452p (£925m) - Half Year Trading Update - Mark - AMBER/RED =
The market has liked this update from what is described as "one of the UK and Ireland's leading software, security, AI and cloud services specialists”:
The Group has traded ahead of expectations in the first half of FY27, continuing the momentum built from H2 FY26. Gross Invoiced Income for the period is estimated to increase by c.19% year-on-year, with Gross Profit estimated to increase by c.18% and Operating Profit by c.6%. The Operating Profit performance reflects the impact of cost normalisation previously communicated. This reflected higher technology costs linked to strategic projects and a return to more normalised bonus levels.
This is said to be ahead of expectations, but I’m a little underwhelmed myself. H1 operating profit is up only 6%. And the guidance is for the full-year operating profit to be slightly below this rate of growth:
As a result of the strong first half performance, the Board now expects Gross Profit growth for the full year in the low to mid-teens, with low to mid single-digit Operating Profit growth.
I can’t see any broker notes on Research Tree to give a direct comparison, but this compares to an EPS growth forecast of 5% in the Stock Report:
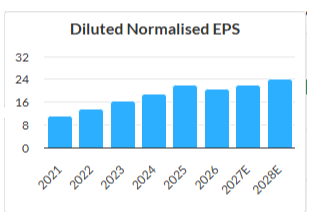
It seems that any beat is relatively slight, and I honestly would have expected any business operating in the IT security space to be doing far better than this.
The rating looks very high for such pedestrian growth rates, with a PEG of 2.4:
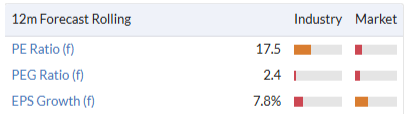
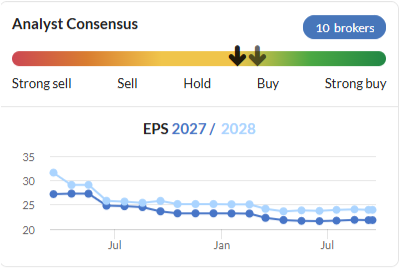
The share price is up year-to-date, despite a consensus that looks to be still below where it started the year:
In comparison, Computacenter reported H1 adj. PBT that was double the previous year and is on a similar forward multiple. At the smaller end, Shearwater expects adj. EBITDA up 40% and is on half the multiple here.
On the plus side, the company has a decent cash balance:
BTG's net cash position at the end of H1 FY27 was c.£68m, after returning £41.3m to shareholders through the payment of the FY26 final dividend of £16.3m and £25.0m of share repurchases under the Group's buyback programme. Cash conversion for the first half was around 45% (H1 FY26: 34%), reflecting the Group's normal weighting towards the second half of the financial year.
However, this isn’t enough to shift the valuation multiple significantly. I also have to question their commitment to a share buyback. On the current forward multiple, this looks more like poor capital allocation rather than shareholder returns.
Mark’s view
Roland rated this as AMBER/RED following their FY profits warning in March. I don’t think a slight upgrade for the current year changes should change that view when the stock has a high PEG ratio and a trading performance that looks well behind sector peers.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Please excuse me if I am late to this because I have been on hols. HL/ appear to have changed their "get a quote" to trade page and once again it appears to be a step backwards i.e. they have taken something that was easy to use and made it less so. If I've missed something please let me know.
Supreme (LON:SUP)
decent trading update today - everything looks tickety boo.
I really like this share but i have a real dislike for the vaping segment and in particular i was slightly worried about vaping sustainability when new rules kick in.
Ref sustainability well we dont have long to wait till the new rules kick in next month - in theory it could aid proper traders if it aids catching the illegal traders
So i am kinda trending towards accepting that high % of profits comes from vapes - hopefully next 12 months is key that they make excellent progress ref new brands - that could be the game changer to help shareprice if they coudl get highe r
% of profits from non vaping.
What i dont like is that the vaping stuff is still clearly targetted at kids - stuff like banana ice , pineapple ice , Maidens Tobacco and Fruit salad - well you are having a laugh if you say the target market there aint kids. I am tempted to abstain on moral grounds ref sketchy advertising - hey ho presumably the regulator and the company think thats fine and dandy - if everyone else is pushing those boundaries well you have to do the same or you wont succeed - so i might accept teh reality that the rules are lax and below what i trhink is acceptable (personally i would have vaping only allowed for ex smokers - my hope there has sailed away i think). I just wish they were a bit more ethical and didnt target kids rather than clearly actively targetting them. Hey ho maybe the 25's love a bit of Maidens Tobacco or Fruit salad when they are out having their part vape sessions - i do accept that there will be elders that do like these variety flavours that might also appeal to kids.
Does anyone know when we might get broker note for next year ref profits - i think it would be helpful to have positive numbers up for next year - my worry is price might rise before i get sight of good numbers for next year if forecasts are decent ref profits next year.
I see this is another company that references adjusted EBITDA - its very sad the trend away from telling us the figure that matters and defaulting to EBITDA for updates. to be fair to Supreme they have been consistent using this methadology so its not new for them.
Supreme (LON:SUP)
As many people will be aware, there is a £2.20 per 10ml (vape liquid) vaping tax which comes into effect on October 1st. However what most people probably don't realise, as far as I'm aware this tax only covers manufactured products from the October 1st date. My research suggests that you will still be able to sell older stock until March 31th without the tax duty added.
So has Supreme built up large inventory? Buyers will be stocking up several months supply either before October 1st, or if they are aware then also before March 31st.
It seems there may be a lot of unpredictability in this sector over the coming months. For instance if Supreme don't build up inventory to last until March 31st - they may have competitors undercut them or get close to Supreme's new price. And while this situation only lasts about 6 months - that's long enough to lose a lot of customers that may find they actually prefer a different product - having only tried a competitors product due to Supreme's price rise.
And of course the opposite could also happen. Supreme could build up large inventory while some of their competitors don't have the resources to do the same. If the competitors prices rise from near October 1st - then Supreme can raise the price on older stock because at that point they would be so much cheaper than the competition.
Anyway I have no idea what their inventory target levels are, or what the model is going to be over the next few months. If anyone knows this that would be great.
What we do know is that their £1 vape liquid will be a lot more expensive from March 31st at the latest. But how they will manage this transition and how disrupted this market might get is a bit of an unknown.
Obviously the October 1st date is looming, so thought it might be interesting to anyone who wasn't aware of this March 31st cut off on older stock and what impacts this may have on the sector.
Edit - My apologise, as I've just repeated what Mark had noted in his analysis (hadn't seen the write up).
So according to Ai. Although Supreme have not given specifics in terms of stock levels, they have said that they intend to manage the transition with the grace period until March 31st. So this suggests they will be building up a lot of stock. They will have to judge it well (with just 2 weeks manufacturing left), there will be huge demand right now, then 6 months still to cover and then more demand towards the cut off date. They are pretty savvy, so I am now thinking this may be a net positive for market share over the coming months as surely not all their competitors have the resources to build up enough inventory.
Supreme (LON:SUP)
House broker Shore has put out a report today. On your question they say "......we believe Supreme has used its very strong balance sheet to proactively build significant inventory in both pods and liquids, As such, management expect to be well positioned to sell duty free product through much if not all of H2 27F, indeed, with other distributors unable or unwilling to build inventory levels beyond the normal 8 weeks, we see demand from retailers and fellow distributors being very healthy through to the end of 2027F. Such inventory build will be temporary, and should be neutral by the end of FY2027, though it will be clear in the interim results, with the FY26A year-end stock position of £37m expected to build to c.£60m at the half-year".
Supreme (LON:SUP)
That's very useful information, many thanks sharw. I suspect they will increase market share over the coming months but beyond March is a bit of an unknown.
Yes, it kind of backs my view that they should be fine for FY27, maybe even ahead due to pull-forward demand before Oct 1 and the ability to generate additional margin on stock manufactured before Oct 1st but sold before 31st March.
However, the knock-on is that FY28 could be truly terrible, as a double-whammy of price hikes and the other side of the wave of pull-forward demand hits them.
Probably not one to buy on any "in-line" or "ahead" statement in the near term, as the stronger FY27 is the weaker FY28 will be.
Beauty Tech (LON:TBTG)
update seems really good (wish i had taken the plunge when i looked at this 10 days ago) - would i be correct in saying that per current forecasts are for H2 sales to only be up 4% on last year (fact check of my maths might be needed?) . Clearly great numbers but if they are expecting just 4% increase in H2 seems like it could end up being an underwhelming update next time out when moaners point out slowing of sales growth rate - having said that if they are making more margin lower % increases can still do the biz.
Perhaps they are just being cautious - thats good discipline if they are being uber cautious till they have the extra in then bag i fully applaud that.
note they are expecting 12% sales increase next year - so it seems potentially odd to have lower expected gorwth now than next year - that 12% stat 12 months though and 4% is H2 so perhaps sales just wont be as second half weighted.
It could just be natural stuff based on new stockists - it kinda makes sense that some periods would have faster growth than others and that growth might be lumpy.
one just needs to look at Warpaint London (LON:W7L) shareprice to find out what happens when companies run into position where they face headwinds rather than tailwinds ref their ability to ramp up sales.
I suspect Beauty Tech (LON:TBTG) may be in a slight less uber competitive market segmet ? i do wander though if their stuff might either be kinda flash in the pan "flavour of the day" stuff ? - or whether they havent as of yet got the cheap knock of chinese type competitors undecutting them yet ? - i know zilch about this sector so i aint got the foggiest about then long term durability of the brand the sector and their products.
For companies like this they really need an Abtan style update - Abtan are you follwing this company by any chance ?
Finally have any brokers updated expectation for next year - often the update ref next year is more important than what they say if its nod and a wink. I would be surprised if there would be any bad news ref next year based on what they did say this morning.
Good point re H2 growth on Beauty Tech (LON:TBTG) rmillaree. I hold, bought recently and shares have been flat. Good short presentation on the cos website this morning. Like this co - several "ahead" announcements already, growing strongly in a growing market, margins up, Cash of £52m (13% of market cap) and lots of new products for H2. I think we will see another "beat" for H2, management come across well and have established a good, if short track, record on the market. Only negative is the level of adjustments - would be keen to see what Stocko team say.
On basis of today, i am likely to increase my position - very small at mo. Shares up 11% as i write - perhaps an Ed "Stock Jumper" if this closes at this level - albeit SR below 75....but sure this will update with these numbers?
Like you, I don't know how long the trend for this type of product will continue, but I am confident that any short term slowing in growth will be a lot less than the current forecasts seem to imply. I think the company are just being very, and probably overly, conservative and will end up upgrading turnover expectations again later in the year. Previous figures show a strong second half weighting which makes sense given it includes Christmas. I will be surprised if full year turnover isn't £180m (which I guess meets their 'not less than £170m' phrase) and maybe some way over. What growth they see from there is harder to say.
I took the plunge 10 days ago after watching this one for three months. Consistent upgrades in their updates were what caught my eye.
I agree with you on all of the points raised, especially the question of the level of next year's growth.
I have a 17 year old daughter who tells me that she has a handful of friends who use this kit. Probably the cheap Chinese knockoffs as the Beauty Tech (LON:TBTG) kit is well outside of their pocket money range, but it tells me something about their addressable market i.e. female, beauty focused.
Saying that, my main concern here is the knockoffs - but I think it's countered by Beauty Tech's commitment to research and development of LEDs that do actually improve the skin rather than any old LED shining a bit of red light on it. The key will be to communicate this superiority and expertise to their market.
Beauty Tech (LON:TBTG) I think we do have time with this one despite the SP jump today. I spotted this looking at the Naked Trader website 4 months ago (he knows how to pick them) added to my watchlist but noted SP bumbled around 300 - 350. Today’s update may be the catalyst to buy or add more…….I am watching!
Next (LON:NXT) half year results missing - another profit upgrade though sales in shop down and online up
Take 'online' sales with a pinch of salt. We have unlimited free delivery (£20 per annum) which is great but for every 10 (better half) items purchased, 9 require a store visit to return and of course, encourages further store purchases/savings(obviously) to be made.
Good Morning Graham, Beauty Tech (LON:TBTG) and Trufin (LON:TRU) interims look decent (though I haven't had my morning coffee yet, so could be wrong). Would appreciate your take on these if possible.
I second Beauty Tech (LON:TBTG) as I think we've only looked at it once before and the numbers look very decent versus market cap. Not a business I understand and looks like its worthy of further consideration!
198p for a litre of diesel near me yesterday. Anyone saying inflation won't go up, lots, is in a dream. Interest rates will follow. Thank you Donald.
Most of that is tax. It is self inflicted inflation.
Are you aware that fuel duty has been decreased in real terms by over 1/3 since 2016 ? Yes taxes are high % of price but taxes are not the reason for the increasing price in real terms - it’s kinda the opposite
Little research and curiosity would have shown that that narrative is false, Reality is, right now, its less than 50% - granted it has been higher as fuel was cheaper.
https://www.racfoundation.org/...
Oil on its way down again today, so who knows!
Trump knows, it's his move.
Just coming into winter, energy bills about to increase to add to the pain....
Our central heating oil tank is on the verge of needing replenishment, more bad timing from yours truly.
That’s not real inflation that’s the trump effect - anyone else counting down the days till trump leaves the building and America gets chance to vote is non buffoon in ? Oh Vance is currently bookies favourite to be next in line
Frying pan into the fire!
what is also interesting is bookies have Alexandria Ocasio-Cortez as most likely Democratic candidate (she aint a shoe in i would add) - so it looks like America may be as divided as ever come next election ref extreme candidates. just seems like yesterday when she turned up on the scene - i must be ageing faster than i would like - (fact checked myself she was elected to congress in 2018 so i am ageing faster than i would like) .
Perhaps if trump doesnt change the rules that dont allow him to run again - value money might be on mini me at silly odds perhaps - Trump Junior?
Seen commentators note Trump may be the last president. That’s a step too far.
The US is big and Americans don't travel—only ~50% hold a passport. Around 25–35% have never traveled beyond their home state or its immediate neighbors, whereas ~94% of the UK population has been abroad.
Individual states hold immense constitutional power. There is an increasing trend toward de facto non-enforcement—states use the 10th Amendment to refuse local resources for enforcing politically sensitive federal laws they oppose. Combine this with 30 years of partisan media and social media algorithms framing the opposition as existential threats (national socialists vs. socialist communists), and national authority fades as geographic and political distance increases.
Rather than a dramatic collapse, the likely outcome is "soft balkanization"—a union where federal laws remain on the books, but red and blue states function as very different legal, social, and economic environments.
I just hope it all stays on that side of the Atlantic.
Funnily enough, US and China have more in common than some think - my favourite chinese proverb is "The mountains are high, and the emperor is far away"
It’s incredible on a national and global basis how chaos Donald Trump has caused. It’s astonishing and all the while enriched his family and himself. If anyone’s interested LBC interview Hunter Biden last night which is on YouTube. He made some very interesting comments.
I don't think Hunter is the most impartial nor reliable of people to listen to.
Actually, I'll have you all know, that Trump is in line for the Nobel Peace Prize. He has stopped the war with Iran eight times! I saw this in MoneyWeek. That's enough about Trump today, too much spoils what is normally a great blog. I like to read what the clever people say about shares, starting with the clever Stockopedia team.
Meanwhile no plan from this government......
Oh I wondered how long it would take to start blaming. The fall guy has gone and is enjoying watching Arsenal from the stands again....oh I know, lets all start blaming Andy!!
And that for UK citizens is far more telling than Mr Trump's activities.
You think they should send in the SAS to take out Trump?