Daily Stock Market Report (Thur 1st Oct 2026) - MSI, RGG

Good morning, no preamble today as I'm under the weather. Mark Simpson is here to help with stock coverage.
Overnight market movements:
The FTSE is down 0.7% at 10,535
S&P 500 is up 0.7% at 7,705
Brent crude (December) is down 0.5% at $97.50/bbl
Gold is up 0.8% at $4,190/oz
Bitcoin is up 0.8% at $84,300
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
SSE (LON:SSE) (£30.4bn | SR69) | Trading Update | Reiterates adjusted Earnings Per Share guidance of between 168 – 193p for 2026/27 and between 225 – 250p for 2029/30. | |
Land Securities (LON:LAND) (£4.65bn | SR39) | Acquires 100% Stake in Metrocentre, Proposed Equity Issue & Retail Offer | Exchanged contracts to acquire a 100% stake in Metrocentre, Gateshead, circa two miles from Newcastle city centre for a net cash consideration of £516m. TU: Landsec has the potential to deliver approximately 5% compound annual growth in EPRA EPS through to FY30. Raising approx £500m of new equity at a placing price to be determined. | |
Primary Health Properties (LON:PHP) (£2.38bn | SR72) | Rental growth remains ahead of guidance. Extra £5.8 million of income generated in the first 9 months of the year from 480 completed reviews. Total increase equivalent to 3.1% (target: >3%) on an annualised basis. | ||
Breedon (LON:BREE) (£1.14bn | SR82) | CEO has decided to retire at the end of 2026 after twelve years with Breedon. New CEO James Brotherton has been CFO since 2021. | ||
Renew Holdings (LON:RNWH) (£746m | SR80) | Trading for the year in line with market consensus. Confidence in the Group’s prospects for the year ahead and beyond. | ||
Filtronic (LON:FTC) (£522m | SR32) | $68.1m (£51.3m) follow-on order from SpaceX for the supply of its Cerus E-band gallium nitride Solid State Power Amplifier units. Expected to be materially fulfilled during FY2028, underpinning the Board’s expectations for FY2028.v | ||
PZ Cussons (LON:PZC) (£420m | SR88) | Group like for like revenue growth in Q1 was 4.5% and expectations for the full year operating profit remain unchanged. | ||
| FW Thorpe (LON:TFW) (£301m | SR86) | Final Results [External Link] | Revenue -1.3% to £172.9m, PBT +2.5% to £32.4m, EPS +9.4% to 23.7p. “Steady start to 2026/27, orders ahead but general performance marginally lower.” | |
Halo Minerals (LON:HALO) (£266m | SR6) | The Board confirms that it is not aware of any operational, financial or corporate reason that would account for the recent decline in the Company’s share price. | ||
Smarter Web (LON:SWC) (£258m | SR27) | On 29 September 2026, the FCA approved the Company’s prospectus and the Company launched the initial public offering of its new preferred shares (“MORE”) on the Main Market of the London Stock Exchange (the first of its kind in the UK). Targeting gross proceeds £15-25m. Dividend payable weekly at an initial rate of 12% (variable). | ||
MS International (LON:MSI) (£233m | SR61) | Awarded a three-year contract with the United States Navy for the continued supply of the MK88 MOD4 MSI-DS Stabilised Gun Mounts and the MK48 MOD2 Electro-Optical Sights with immediate effect. Under the first year of the contract, the US Navy has committed to purchase 22 MK88 Gun Mounts and 23 MK48 Electro-Optical Sights, with a total Year 1 contract value of $61.3m. | GREEN = (Mark) My initial thought was that a 10% jump in the share price this morning looked a bit low on such a material contract win. However, after running some numbers, my estimated impact on PAT almost exactly aligns with the jump in market cap. | |
Pantheon Resources (LON:PANR) (£173m | SR38) | Appointment of accomplished energy executive, David Wilkins, as Chief Executive Officer, succeeding Max Easley with immediate effect. | ||
Rentguarantor Holdings (LON:RGG) (£160m | SR42) | Expects revenue for FY2026 to be materially above current market expectations (£19m vs > £14m). Net profit to be materially ahead of current market expectations for the year (£9m vs >£4m). | GREEN = (Mark) | |
Peel Hunt (LON:PEEL) (£111m | SR69) | 27H1 Revenue -16% to £62.5m, due to a broader and more balanced mix of M&A and ECM activity. Enters the second half with a solid pipeline of opportunities across a diverse range of transactions. | ||
Topps Tiles (LON:TPT) (£70.5m | SR70) | Group revenue incl. CTD -1.3% to £292m, excl. CTD +0.7% to £267m , LFL, -0.1%. Pro Tiler Tools revenue +18% to £42m. Expects Adj. PBT for the full year to be in line with current market expectations (£6.6m, with a range of £6.5 - £6.7m. | ||
Great Western Mining (LON:GWMO) (£16.4m | SR18) | Appointment of John Arthur as CFO with immediate effect. The previous CFO remains Company Secretary. | ||
Light Science Technologies Holdings (LON:LST) (£15.9m | SR11) | Expects to report revenue for FY26 in the range of £9.0 - £9.5m vs £8.6m in FY25. 26H2 revenue is expected to be 50% higher than the first half, however the full year outturn is below previous expectations. Now expects to report adjusted LBT for FY26 in the range £0.8 - £1 million, broadly in line with the prior financial year. H226 is therefore expected to be at breakeven. | PROFIT WARNING | |
Fiinu (LON:BANK) (£13.9m | SR1) | Fiinu's Polish subsidiary, Everfex, has been hit with bankruptcy petitions from people linked to its previous owners. Everfex has responded by asking a Polish court to place it in a court-supervised restructuring. That shields it while the disputed debts are examined, and it keeps operating meanwhile. | ||
DSW Capital (LON:DSW) (£11.4m | SR54) | Has welcomed Apex Employment Solicitors as its first licensee, expanding its legal offering into employment law. |
Mark’s Section
MS International (LON:MSI)
Up 10% at 1550p (£233m) - 3-YEAR CONTRACT TO SUPPLY TO THE US NAVY - Mark - GREEN =
This is a big contract with a key customer:
Under the first year of the contract, the US Navy has committed to purchase 22 MK88 Gun Mounts and 23 MK48 Electro-Optical Sights, with a total Year 1 contract value of $61.3m. The quantities to be supplied in each subsequent year will be agreed annually, in accordance with the customary structure of this type of US Navy contract.
As others have pointed out, this is just one year’s revenue, and the full 3-year contract value is for $197m. This is around £150m of revenue in Sterling at current FX rates, and is material for a company that has averaged £114m of revenue over the last three years. However, there is a key phrase in the RNS: "continued supply”. This is not a new customer, but these orders are a follow-on from existing ones that will have been delivered in previous years.
So the big question is how does this compare to previous US Navy revenue? MSI doesn't publish a separate figure, so this has to be estimated from what it does disclose:
The Group's largest customer, which is reported in the 'Defence and Security' division, contributed 17.7% to the Group's revenue (2025 - 37.1% from a different customer).
MSI doesn't name it, but the jump lines up with the rise in US revenue and the chairman's comment that the US business did particularly well with continued US Navy success, so it is plausibly NAVSEA.
This means £20.3m is likely to be US Navy sales in FY25, up from £4.4m. This is likely to be an additional £30m revenue per year from this contract versus the FY25 baseline. However, we are halfway through FY27, and the Year 1 run rate is lower than the total contract, so as a rough estimate, it’s an additional £13m of revenue for FY27 and then perhaps the full £30m for FY28 and FY29.
Valuation impact:
It can be hard to estimate the impact of this contract, as MSI only provides group-level Gross Margins, which, at around 34%, include the relatively poor-quality Forgings and Petrol Forecourt businesses.
It is clear from the last few years that EBITDA and EBIT margins are higher on higher revenue:
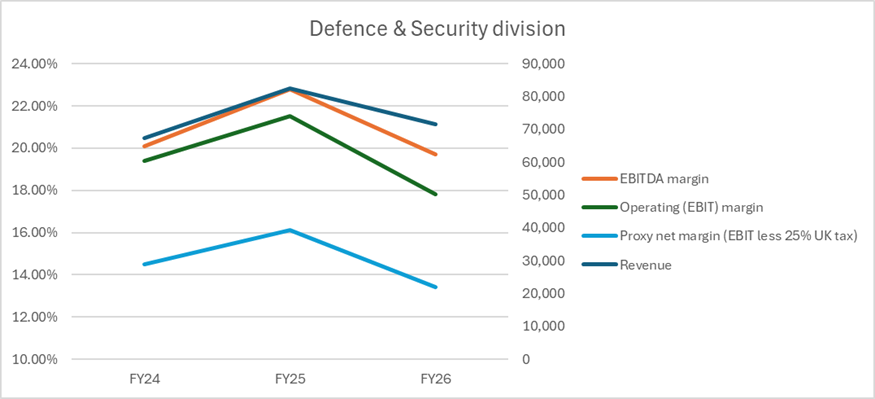
Forward estimates are not helped by a lack of broker forecasts as a baseline. Still, assuming FY27 was tracking in line with FY26 at this point, Defence & Security revenue is now likely to be around FY25 levels, with similar EBITDA and Net Margins. For FY28 & FY29, revenue would be up to around £101m. Typically, £10-15m shifts in revenue have moved proxy net margins by around 2-3%, so I assume that proxy net margins reach 20% in D&S on this incremental revenue.
This would mean I can estimate the NPV impact of this contract win:
FY27 | FY28 | FY29 | FY30 | Total | |
Baseline D&S revenue | 71.5 | 71.5 | 71.5 | 71.5 | |
Baseline D&S Net margin | 13.40% | 13.40% | 13.40% | 13.40% | |
New D&S revenue | 84.5 | 101.5 | 101.5 | 88.5 | |
New D&S Net margin | 16.10% | 20% | 20% | 17% | |
Incremental PAT £m | £ 4.02 | £ 10.72 | £ 10.72 | £ 5.46 | |
NPV10 Incremental PAT £m | £ 3.82 | £ 9.15 | £ 8.24 | £ 3.78 | £ 24.98 |
The share price is up around 10% today, adding around £23m to the market cap. My initial thought was that the market had under-reacted to this contract win this morning. However, the market appears to have actually done a remarkably good job of pricing the impact of this in isolation.
Wider context:
I don’t think we can rule out that the market has already priced in significant forward growth in the Defence and Security business. The historical P/E is very high here for a business that has flat revenue and declining EPS over the past three years:
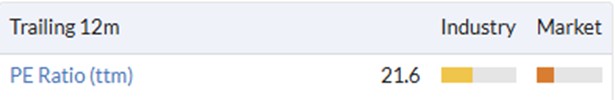
How expected this expansion was, and the path of other defence orders from key customers, is hard to judge, but it's clear that this sort of rating only makes sense if the future is highly likely to be much brighter than the past.
The End Game:
It is widely thought by many holders that the final outcome will be a sale of the business. Michael Bell, who ran the company for over 50 years, stepped down in July. A founder stepping back plus a simplification programme is a common lead-in to a sale. However, Bell has said he intends to stay a substantial shareholder.
It is also worth noting that MSI has said nothing about selling the Defence business. Its stated plan, from the June 2025 strategic review, is the reverse: keep Defence and sell everything else. The Petrol Station Superstructures and Branding sale is still in negotiation. At the AGM on 9 September, the CEO said he still hoped to announce it soon, and Forgings would be dealt with after that. The board has received unsolicited interest in Forgings but hasn't run a formal process.
However, this major contract helps attach a firmer value to the Defence & Security Division, as it gives revenue visibility, and a contracted US Navy backlog means a buyer could pay a defence multiple for it. MSI-Defence Systems US in South Carolina is a sole-source US Navy supplier of the Mk38 Mod4 gun mount and Mk48 sight. A US contractor, or a European group wanting a foothold with the US Navy, might value that highly.
However, there is a risk this ends up much like a Goodwin situation, where enthusiastic long-term shareholders are disappointed with the price achieved, as previously lauded management point to third-party unwillingness to pay up based on one-off factors.
Mark’s view
My initial thought was that a 10% jump in the share price this morning looked a bit low on such a material contract win. However, after running some numbers, the market seems to have reacted remarkably efficiently to the news.
Zooming out, the share price has held up surprisingly well for a company where revenue is flat and EPS down over three years:
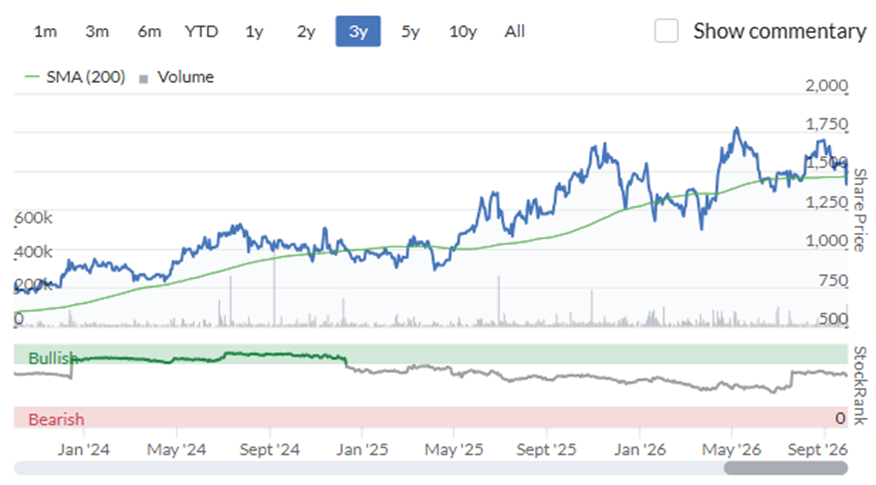
This suggests that shareholders were already expecting this sort of contract win, and perhaps many more on top.
It feels to me that in the absence of corporate action (which, as Goodwin has shown, comes with its own risks!), it is tempting to think the easy money has already been made here, given the low Value Rank:
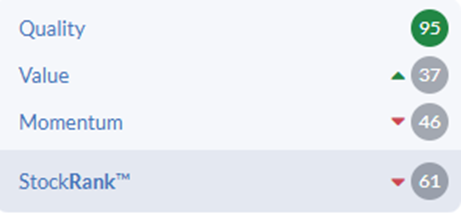
Hence, it may make sense to take a more cautious view. However, the long-term nature of the US Navy supply deal makes the business more attractive to an acquirer, and my fellow commentators have remained very positive about this business for some time. I’m not miserly enough to modify that view on what is clearly a very positive news day for the business GREEN.
Rentguarantor Holdings (LON:RGG)
Up 18% at 113p (£m) - Trading Update - Mark - GREEN =
Shareholders in this company that listed just over a year ago have had quite some ride recently:
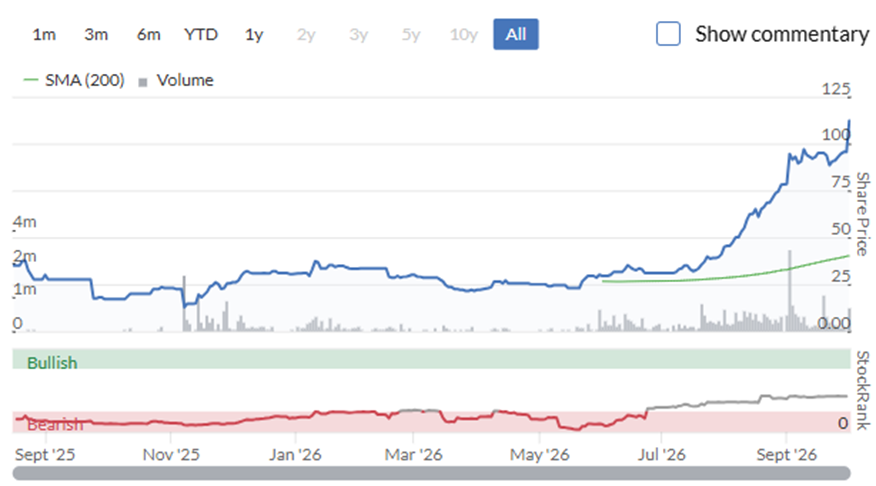
In our coverage, Graham turned neutral in April, when Q1 revenue was up 105% year-on-year, which was said to have “materially exceeded Company forecasts”. He went positive in June, when a positive trading update led their broker, Cavendish, to make further material upgrades of around 25% to all future years, and the company was forecast to now break even for FY26. Only the Value Rank of 4 stopped him from going fully GREEN. But then in September, further material upgrades meant that a fully positive view made sense, with him saying:
I don’t think I have much choice but to turn positive on this today:
- It has crossed over into profitability, and is already producing material profits.
- Huge upgrades to its financial forecasts for the next few years.
- All of this growth is well-explained by the introduction of the Renters’ Rights Act.
That last point makes you wonder whether this phenomenal performance is less about management brilliance and more about being in the right place at the right time. However, this reality can’t be underestimated in investing; it really is better to be lucky than good most of the time!
Exposure to these positive trends continues to drive performance, as today they announce yet another material upgrade, driven by strength during the key student letting period in September:
The Board now expects for the Group to deliver revenue in excess of £19 million (previous guidance of in excess of £14 million) and net profit in excess of £9 million for FY2026 (previous guidance of in excess of £4 million) and is also encouraged by the outlook for FY2027.
I’ve rarely seen a company of this size, where net profit forecasts more than double.
Forecast Changes:
Their broker Cavendish say:
We increase revenue by 36% to £19.1m, adjusted EBITDA by 136% to £9.6m, adjusted PBT by 153% to £9.4m. Our forecasts require £6.1m of revenue in 4Q, below the £9.6m generated in 3Q, reflecting the seasonal weighting towards student rental activity. We also allow costs to rise from the current run-rate to support a substantially larger business.
The previous FY28 estimate of 5.9p of EPS is now largely expected to be delivered this year, with 5.6p EPS pencilled in.
Cavendish also upgrades the outer years. However, it is worth noting that they expect EPS to fall in FY27, saying:
Our forecasts assume paid marketing becomes a more important driver of growth and gross margin falls by one percentage point annually from FY27E to allow for potentially higher arrears and defaults as the contract book grows. FY27E EPS falls to 4.8p despite higher PBT because we assume tax losses are fully utilised in FY26E, and a full tax rate applies thereafter.
Investors are not a big fan of falling EPS, even if it is largely the impact of tax losses being exhausted, so this bears watching carefully. Of course, the current trajectory suggests further material upgrades could come for that year.
Valuation:
With fast-moving forecasts and share price, we need to run our own numbers:
2025A | 2026E | 2027E | 2028E | |
Adj. EBIT | -0.8 | 9.3 | 10.9 | 17.3 |
Net Cash | 1.3 | 13.7 | 21.6 | 33.6 |
EV @ 113p/share | 188 | 176 | 168 | 156 |
EV/Adj. EBIT | - | 18.9 | 15.4 | 9.0 |
If we believe those FY28 numbers, this still looks like good value today, even more so if we assume further upgrades.
With the share price approaching their old price target, it is unsurprising that Cavendish increase their Price Target. However, their methodology looks a little convoluted to me, and I generally don’t like it when you have to make assumptions for 2030 numbers to come up with a valuation argument:
Our target price methodology remains unchanged. We apply a 12x EV/EBIT multiple to FY30E adjusted EBIT, add forecast FY30E net cash and divide by our forecast fully diluted share count. We then discount the resulting value back over four years, compared with five years previously, at 15% pa to reflect execution risk and time to maturity. The updated forecasts and shorter discount period increase our target price from 122p to 165p, implying 73% upside.
Bear points:
Given the phenomenal growth, it is worth pointing out a few things that could go wrong:
- The growth comes from a single change in the law: Since 1 May, landlords can't take more than one month's rent in advance, so tenants who used to prepay now need a guarantor. That is a one-off shift in demand, not something that keeps compounding.
- It's too early to know what claims will cost: The company says its claims rate held steady at around 4% of revenue. But most contracts were written in the last four or five months, so few have had time to go wrong. The Act also means that a tenant who stops paying may now stay much longer before they can be removed, so that each claim could be bigger. The customer base is people who can't provide a UK guarantor of their own, such as students, overseas tenants, people on benefits and the self-employed.
- It's unclear who carries the risk: The model seems to be that underlying risk passes to a panel of insurers; RentGuarantor retains the origination fee. But the company also reports its own claims ratio within its risk policy, which suggests it carries at least some of the risk itself. It raises questions about how much capital it needs to hold and whether it falls under FCA rules. If insurers carry all the risk, those insurers have pricing power and could raise rates or pull out after a bad claims year.
- Competition could squeeze it: Rivals benefit from the same law. Housing Hand, for example, described growth in applications over the last 100 days as phenomenal. Barriers to entry are low, so prices are likely to come under pressure.
- Political risk: This government favours tenants, and annual guarantor fees paid by tenants could attract attention, for example under the Tenant Fees Act or new rules in a future rental-sector bill.
Mark’s view
I think the bear points here represent real risks to high long-term growth rates. However, there are no signs of things slowing down in the near-term, indeed quite the opposite. I’m not convinced by broker valuations that require 2030 numbers, but given the phenomenal growth, investors don’t have to look that far out for this to continue to look like good value on forward numbers. As such, it makes sense to keep our positive view. GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
I read that the usual way for countries to reduce debt is inflation - if their debt is in their sovereign currency. Isn’t that why bonds are selling off?
Certainly a part of it £1 in 2001 buys you roughly 40p worth of goods now, I certainly don't know why anyone would want to be holding long duration bonds at the moment but RD is cleverer than me and may have a different view.
All depends what you think inflation is going to do. If we have a recession then a guaranteed 6% is going to look awesome. Plus the value of the bonds will rocket.
Bond yields are currently at a level where retirees can guarantee a good income with less capital . It now makes sense to have a percentage of a long term portfolio in bonds IMO.
PS. At 6% your £1 from 2001 would now be £4.30.
Fair point Revs and agree with your previous post if your low risk looking for say 5% per annum return having part of the portfolio in 5 year gilts isn't in my opinion a bad call.
Bloomsbury Publishing (LON:BMY)
The releases of Sarah J. Maas next 2 books in the Court of Thrones series are due on 27th October and 12th January. At numbers 3 and 7 respectively they seem to be doing well in the Amazon Best Sellers list Amazon.co.uk Best Sellers: The most popular items in Books.
There has been very large volume recently as the stock has bounced off support.
Many thanks, very interesting re Bloomsbury Publishing (LON:BMY) . I had just assumed the bounce was because I had a price alert at £6 and was waiting to see if it broke down below that :( . No doubt, I suspect it will have a good few months ahead, so I will probably just have to pay up... All the best.
Thanks Helvellyn. I am a long term holder of Bloomsbury Publishing (LON:BMY) and this is my biggest position at around 12%. I think (hope!) sales will be off the charts ..... Holding for a bounce when sales of the first book are announced!
As a follow up I was a little shocked/surprised bond moves had pushed MOVE up to 110.... a tour of US yields is quite interesting. 6M yield over 12 months is flat at 4.35% but 12 months ago the market expected cuts and 2Y yields were 3.7% versus 4.91% now. 10Y yields were 3.82% so little term premium compared to 5.33% now and 30Y were 4.15% compared to 5.66% now..... quite large moves over 12 months but the expected inflation rate hasn't ticked up much and remains anchored at 2.35%. Stubborn inflation and stubborn Oil price plus diesel issues and high energy prices has resulted in quite an exit across bond maturities and the steepener is playing out as expected by many. Personally I put this in the not terribly good news pile.... I would sit out the help to buy at present but things can change.
Interesting discussion on here and surprised nobody has mentioned the possibility of a sovereign debt crisis engulfing the UK with the UK in a much weaker position v other countries in the G7 which some economists are now openly calling out. Thoughts on this anyone ?
Sure - the main reason im looking at geographical spreads on 10 year bonds is watching out for this. My previous post was highlighting that the UK is doing ok at the moment - and France, the US and Italy are picking up distress. If anything one of these countries is likely to overtake the UK and France is top of many lists to kick off the crisis - if it is that even. So I disagree slightly and don't think the UK stands out so much at the moment - the triple lock move suggests the Govt are well aware they can't do a Truss.
Although the UK now has a historically high sovereign debt, it is actually less than the majority of the G7 countries. Currently, with regard to Gross Debt Percentage against GDP, the UK is 6th out of the 7 No. G7 countries. The current percentage for the UK is 104% (1st is Japan at 255%, 2nd Italy at 140% & 3rd USA at 123%) The projections, from the IMF, are that in 2029 the UK will move from the 6th position to the 5th (110%) The projections for other G7 countries in 2029 are 1st Japan 252%, 2nd Italy 145% & 3rd USA 134%. So the UK does not appear to be in a much weaker position than other G7 countries? The conclusion from these figures would seem that this is a global problem, and not one restricted to the UK?
Exactly right. While we are supposedly masters of our own destiny, the decisions get tougher at the higher % end of the scale as so much more has to go on interest payments. Also worth mentioning while Boris Johnson was PM national debt increased from around £1.8 trillion to over £2.4 trillion. BoJo had many qualities but financial prudence is not one of them. Yes we had Covid 19, but the Tories did not keep him under control.
everything red today...probably because the 30yr gilt just hit 6%
which is, ironically, a normal rate for govt. bonds!
10yr a a smidge under ~5.5%
Yes but we no longer have normal levels of government debt - we may have coped fine with 5-6% yields when debt was low but not sure how we'll manage with current debt budens
Sadly for all of us, boring bonds are making front page news as prices continue to fall and yields rise.... in the race higher the UK has been out front for some time but the lead is becoming slender. The US 10Y bond yields are rising to 5.33% versus UK 5.49%. France however are making a good show rising to 4.94% and putting quite a distance from Germany at 3.61% which benefits from not being France or Italy. US, France and Italy look likely to continue making headlines. Andy Burnham's triple lock accounting shuffle looks to win market fans - at least in bonds anyhow - as the UK is showing a little calmness for now. It's not great news though because it means the bond market likes the sound of budget cuts ie fiscal cuts....and this doesn't end that well if everyone has to tighten budgets. We are from this gloomy outcome yet but as the bond yields rise seems to be gathering pace - I don't think this can be ignored for too long. Raising cash early and taking some profit may well be the order of the day .... although the impact of all this on equities is far from obvious.
Andy Burnham's triple lock accounting shuffle looks to win market fans - at least in bonds anyhow
i think it was completely necessary - triple lock was great for its time and really needed for pensioners at the bottom.
Facts are though if we trend out to 20250 - the current system would be ridiculously beneficial to pensioners as pensions would go up materially more than wages and ifnlation over the next 20 years and probably materially increase in real terms. just by statistical quirks.
so its obviously been political votes winning game that no one has blinked before now and no one has admitted that long term triple lock is just lunacy.
the change for now is fair and reasonable (more may be needed) - its just you wont get the head the ball situation where pesnions pimp the best of teh 3 each year - with one of the 3 measures being pretty extreme - their is still the backstop they will go up in line with wages - so imho its a great fairer clever adjust limiting the wages comparison to a period of more than one year - the other two backstops are still in place. under curent system - you may have inflation year one 8% wage growth nil year 2 - inflation 0 % wage growth 8% - its crazy that pension would increase 8% on top of 8% .
key is showing your long tewrm plans arent nonsense - and unlike conservatives and Ks - he has done then necessary adjust.
Note we are talking about £50 bill per year savings from 20250 great stuff - so sensible tweak now really does help - well done AB. yes i wont get as muchn as i would have done - but the triple lock was never gonna last long term end of we simply cant afford it for 30 years in a row.
thats what bond markets like sensible long term thinking and planning finances - thats one thing that bond markets do do - they make politicans think twice about balancing the books - shame it needs to be at crises level for sensible stuff to out.
shame that RR the expert economist couldnt have worked out that sensible solution.
Totally agree the triple lock makes no sense as the population ages and we all live well into 80s etc. This becomes an unfair burden on the younger generations ( Z etc-have we run out of letters yet ?) A continual topic of conversation at the breakfast table, i.e how long before someone sensible actually does something about it. We are well enough placed not to be bothered by a less generous scheme but other issues for those dependent on state pension alone remain unaddressed. Making pensioners pay income tax when this is their only income is not only administratively a burden but in my terms pretty well immoral. So just half a story from Burnham and given most trade unions oppose removing the TL will this actually go anywhere?
I couldn’t agree more about adjusting the triple lock. This country needs a change of direction in many areas and I will take my hat off to Andy Burnham for being brave enough to throw the idea out there rather than keeping quiet about the reality to gain votes at the next election.
I'm in total agreement with you Douglas 1971. It often annoys me to see my friends and neighbours, (mainly in their 70's, with large houses), expending significant sums on cruises and new cars and at the same time complaining that their children cannot afford a deposit for their first home!! Also, as a shareholder in a successfully run Community Pub, I have often been informed by the Landlord that when the WFA (Winter Fuel Allowance) is paid in November there is always a significant increase in bookings for meals!! We need to ensure that our younger generation have a fair and prosperous future in the UK & take the necessary steps to ensure that this happens.
Both of your posts were excellent.
All the best
Appreciated Yiannos!! It is noticeable that the constant flow of misinformation from cetain sections of our press (i.e. Brummer of the DM), does lead to a very gloomy perspective of our current and future economy, which is readily accepted, without question, by a large number of individuals!!
Exactly!
Comparing the UK with the G7 and it is evident enough that we have one of the best public finances. Most things we read in UK newspapers or online, is just pure nonsense written by corrupt people guided by dirty politicians who are trying to destroy this country for their own gain.
Over the last 8 weeks I have moved back 50% of my money back to the UK market.
Takes hard work and patience, but there are some striking opportunities here at the moment.
All the best
The problem is the UK is way down the list of how much pensioners get from the state pension. How anyone is supposed to live on £1k pcm when council tax will easily take 1/5th of that before utilities etc. The prospected saving for the government is small compared to what is spent on benefits and other welfare payments. Maybe public sector pensions should be looked at instead?
The problem is the UK is way down the list of how much pensioners get from the state pension.
we are midpoint of G7 ref overall pensions though - clealry what you get from teh stae is only half the story.
How anyone is supposed to live on £1k pcm when council tax will easily take 1/5th of that before utilities etc
well we are meant to save for retirement arent we - this is a sketchy "benefit debate" - i am ll for old people having roof over their head - heating and enough food. everyone has their own views ref bensfits - some say they are too generoud those that havent worked - some point out that those that arent fortunate enough to have savings will stuggle - not the place for that discusion here really.
. The prospected saving for the government is small compared to what is spent on benefits and other welfare payments.
my simple point is that as this stand it would be compouned growth above real terms for 20 years - that simply cant be afforded - you may say £50 billion saved in 2025 each year is nothing - but to get to end pooint of making figures add up we need many minor tweeks like this.
Maybe public sector pensions should be looked at instead?
everything should be looked at yes - note some progress has been made with reagrd to some pensions.
More the issue is that local government have managed to reduce job numbers and kinda started slimming down (some may say still fat) - but central goverment now employ mopre than they did back in the day - no idea why but thats crazy. yes publish sector and perhaps pensions its harsh reality but perhaps those of pension age - with income materially over 50k pa perhaps some clawback and protection (hard working person paying down debts and not spending silly money ?) - eg tapered tax charge over 50k or 100k but half pension left - benefits were originally designed for "need" - if someone is lucky enough to be earning 100k they dont need it - but we have kinda "promised it in sketchy fashion" so i am not generally a fan of screwing people overnight - unlike others AB has today changed something that will help ! its a starter for 2.5 perhaps. imho 50 bill aint ever pocket money.
Public sector pensions are built up under statute so any clawback ideas on accrued pensions are simply not going to work.
The first person targeted would go to court and would win.
Change the statute, only state paid employees get salary based pensions. The people who pay for them get defined benefit pensions and are told to top up with personal pensions. Even narrow minded socialists can see the unfairness of the position.
Public sector pensions are built up under statute so any clawback ideas on accrued pensions are simply not going to work.
i didnt mean to suggest public pensions should be clawed back i perhaps want clear - i meant ref state pension that could be somewhat means tested via tax charge for those on high incomes.
ref public pensions - simply making the schemes less generous ref future contributions is all that could really be done - as per my prior post its not like there hasnt been some changes there for many (probably not for mp's who benefit from lifetime allowance scrapping)
central goverment now employ mopre than they did back in the day - no idea why but thats crazy
Actually civil service numbers have been falling for decades. But they stopped falling and started rising in 2016, as a result of Brexit. Following the inevitable in-housing of stuff that had been shared, and consequent inefficiencies. Headcount fell from around 750k in 73 when we joined the ECC to around 400k around when we left, and have risen to 550k or so since leaving.
I hear this argument all the time, but the UK has lower taxes and more generous private pensions (eg tax breaks and employer contributions) than other countries, plus free healthcare, which more than offsets the lower state pension. Also pensioners on very low incomes will get additional benefits and not be forced to live solely off the state pension. But ultimately if people want a comfortable living in retirement they need to build up a private pension too and not just rely on the state
They dont they get many other finacial benefits just like those who dont work, you should see my tenannts benefits cheque its ridiculous and tey work part time
That's one of the sweet spots, if your a couple you both work two days per week to use up your 1k personal allowance which is tax and ni free there's 2k gross with no deductions per month.
Assume they have three or more children all sub 18, one has adhd and gets pip, they live in rented accomodation.
In this situation you could quite easily pull another 2.5k-3k down in benefits tax free per month. So for working two days per week each you potentially pull in 5k net per month, 60k net per annum against earning probably 90k gross to get to the same end result.
If you qualify for pension credit though its not quite so bad, you could get 100% council tax write off, £150 warm fuel grant, social tariffs on broadband and water granted you won't be going on cruises but if your single/couple retired happy pottering around your local area you should be okay.
6% on US ten year within the next 12 months do you think RD ?
quid pro quo
Trouble is as per the announcement, savings from triple lock will go into "The Prime Minister announced a new settlement for older people today: a state pension that rises every year, no personal care charges and a high-quality National Care Service to give peace of mind in later life." In a way this is necessary old age care ie either a burden on the NHS or on families. Trouble is free at point of use ie "no personal care charges" - means there is zero financial inceptive for the younger generation to take care of the older rather than having them (me?) carted off to a "wonderful" National Care Service home in wherever. Burnham was quite specific about wanting free at point of use on Lorraine Kelly at the weekend.
However at least this is a decision. The UK Parliament has turned into a specialist at kicking pretty much every can down the road over the last 30 odd years.
Rest a lot and get well soon, the markets and commentary will still all be there next week !
Primary Health Properties (LON:PHP) _There is a Gemini AI summary of the statement on this months Trust thread.
Thanks Graham for going the extra yard for us. This is part of my essential reading of the day. While I almost never pass comment, I want you guys to know that you are read and your efforts appreciated. Get well soon!
MS International (LON:MSI) Worth highlighting for those that haven't opened the .Gov Link that the headline contract size is $197m, versus MSI releasing only the year 1 contract value of $61.3m in the RNS. Good find and hat tip to those on X/LSE that found it.
https://www.war.gov/News/Contracts/Contract/Article/4615442/contracts-for-sept-30-2026/
MS International (LON:MSI) this is the US DOW announcement from this morning.
October's Investment Trus thread is here https://www.stockopedia.com/content/investment-trust-reit-and-etfs-thoughts-october2026-1058340/
Gamma Communications (LON:GAMA) (I hold) Waterland has withdrawn seemingly leaving the takeover with Epiris at 1,120p per share.
Also FW Thorpe (LON:TFW) results:
https://www.londonstockexchange.com/news-article/TFW/final-results/17813887
Nothing exciting, but that's probably as good as we can expect at the moment.
timarr
Pinch & a Punch. It's below the threshold value wise for analysis but BSF Enterprise (LON:BSFA) Great ticker!!! look set to be off to the races anytime soon. Just needs one of the many upcoming announcements.
Fancy a T-Rex handbag???
BSF Enterprise (LON:BSFA) please tell us more, eggandbacon! Stock Rank is a solid zero …
Too much info to go into detail but worth researching when these guys can produce genuine Tyranosaurus Rex skin/leather for the fashion industry!!!
Also injectable cure for damaged corneas instead of human donor transplants.
Both now developed and waiting announcement of supply contracts, marketing concessions, distribution agreements etc.
Worth a pocket money punt on possible multi bagger. I'm a share holder!
BSF Enterprise (LON:BSFA)
That why there is no minus stock ranks -:).
Stock is at least a zero….
All the best
The Stock Report is a sea of red, not something I look for.
Most probably what peeps told Alexander Fleming!
Hope you feel better soon Graham. Chicken soup !
Similar sentiments Graham!
Hope your feeling better soon, loads of hot liquids.......
hope you`re on the mend soon, all the best
Which is more erratic, the Brent crude oil price or the location of the ’thumbs up’? :-)
I don't see the 'thumbs up' going any higher from there.