Daily Stock Market Report (Thur 20 Feb 2025) - WG., ARBB, ZOO, ADVT, BEG, AAL, SRT, ITH, HAS, SAFE

Good morning! The Agenda is ready now.
1pm: that's a wrap! Thanks everyone.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Lloyds Banking (LON:LLOY) (£38.1bn) | 2024 results | 2025 guidance: ROTE c. 13.5% (2024: 12.3% or 14% before provision charge for motor finance) | |
Anglo American (LON:AAL) (£28.7bn) | FY Results | $3.1bn loss includes $3.8bn impairments. Reduced carrying value of De Beers by $2.9bn. | AMBER (Mark) At 18x earnings and flat forecasts, it is hard to see a positive investment case, even for those bullish on copper. |
Centrica (LON:CNA) (£6.8bn) | Final Results | 2025 outlook unchanged. Path towards £1.6bn run-rate EBITDA by the end of 2028. | |
Mondi (LON:MNDI) (£5.7bn) | Final Results | Rev +1%, adj. EBITDA -13% largely due to lower forestry fair value gain. Order books improving. | |
Ithaca Energy (LON:ITH) (£2.2bn) | FY24 TU | Full year performance at top end of management guidance. Strong Q4 production, cost control. | AMBER/GREEN (Mark) |
Safestore Holdings (LON:SAFE) (£1.3bn) | Q1 TU | LfL revenue +2.9% (constant currencies). LfL occupancy improves to 75.9%. | AMBER/GREEN (Graham) My first impression is that there's an appealing discount here vs. tangible NAV. Additionally, the LTV calculations and related commentary from the company suggest that leverage is not a concern. So I'm tentatively positive on the outlook for shareholders. |
Hays (LON:HAS) (£1.2bn) | HY Report | LfL net fees -13% (perm -19%, Contract -9%). Op profit -56%. Ongoing macro uncertainty. | AMBER (Mark) |
Indivior (LON:INDV) (£1.1bn) | Final Results | FY24 Net Rev +9%, Adj. net income flat at $223m. Ahead of guidance. | |
Home Reit (LON:HOME) (£301m) | TU | £12.2m cash, no debt, Jan25 rent collection £1m | RED (Mark) [No section below] |
AdvancedAdvT (LON:ADVT) (£193m) | TU | Materially above the current market expectations (FY25 Rev. & Adj. EBITDA of £41.0m & £8.4m) | AMBER (Graham) The valuation here doesn't put me off. When you consider the low enterprise value, ADVT's software businesses aren't being priced too expensively. The overall structure is a little odd but it's not supposed to make sense: it's about whether or not you wish to back the founder. |
John Wood (LON:WG.) (£167m) | Contract Extension | 2-yr $120m contract extension with Shell UK | RED (Mark) [No section below] |
Begbies Traynor (LON:BEG) (£150m) | Q3 TU | In line | AMBER (Mark) |
Arbuthnot Banking (LON:ARBB) (£147m) | Pre-close TU | in line with PBT consensus of £34.5m. | AMBER (Mark) [No section below] |
SRT Marine Systems (LON:SRT) (£116m) | Response to press | Allegations of procurement irregularity in the Philippines denied by the company. | AMBER/RED (Graham) The company itself and the CFO have been cleared already. According to the Philippine press, SRT's CEO has been ordered to appear in court. I don't have any view on the merits of the case but I feel much safer taking a moderately negative stance on SRT due to its track record. High risk, high potential reward. |
Zoo Digital (LON:ZOO) (£27m) | TU | FY25 Rev $50.5m, EBITDA $1m Below market expecations. | RED (Mark) |
Graham's Section
AdvancedAdvT (LON:ADVT)
Up 11% to 190.9p (£214m) - Trading Update - Graham - AMBER
AdvancedAdvT Limited (AIM: ADVT, "AdvT", the "Group"), the international software solutions provider for the business, compliance, and resource management, today announces a pre-close trading update for the full year to 28 February 2025.
Not too much info in today's announcement but we are told that adj. EBITDA for FY Feb 2025 will be materially above the current market expectations, these expectations being for revenues of £41m and adj. EBITDA of £8.4m.
The reasons: “good growth in both new customers and the renewal of substantial contracts on improved terms”, plus “laser focus on operational efficiencies”.
Comment by Vin Murria:
"Our strong performance reflects the operational changes implemented in the first half of the year and the positive impact of key customer contract wins. These factors provide a solid foundation for continued growth. We remain focused delivering long-term value for our shareholders and continue to pursue further M&A targets."
Estimates: Singers have updated their FY25 revenue forecast to £42.5m and their EBITDA forecast to £9.6m.
Looking ahead to FY Feb 2026, the financial year that starts in less than two weeks, the forecasts have been raised there, too. The revenue estimate is now £45m (prev: £43.2m) and the EBITDA estimate is now £10.1m (prev: £8.8m). Singers says that ADVT has “continued to benefit from the ongoing migration of its customers to the cloud and sustained demand for its digital software and solutions.”
Graham’s view
I did some back-of-the-envelope calculations in September and suggested that ADVT was generating annualised revenues of >£42m and adj. EBITDA of <£9m, thanks to an acquisition it made in July 2024.
FY25 is going to be ahead of that calculation even though the acquisition (Celaton) didn’t start contributing until nearly half-way through the financial year. Impressive!
Celaton provides “intelligent document processing”, consistent with the theme across ADVT’s businesses that they provide productivity-enhancing software.
Checking the interim results to August 2024, I see that ADVT’s cash remained very high at £83m. There was also the near-10% stake in M&C Saatchi (current value: £22m).
Subtracting their value from ADVT’s market cap, we are left with an enterprise value of only £109m.
For that you get a set of software businesses which are forecast to earn EBITDA of £10.1m in the financial year about to start.
And the company did generate what I would call “real profits” (not just positive EBITDA) in H1. Even if you are very strict and don’t allow them to adjust out the amortisation charge, the adjusted operating profit was still £2.5m for H1.
There are some great imponderables at play here, the main one being the ultimate destination of that £83m.
I’m tempted to upgrade my neutral stance but I don’t think I will, for now. As I’ve said before, this stock is really about whether or not you wish to hang on to Vin Murria’s coattails. It is her vehicle: she is the largest individual shareholder and the Chair.
Objectively speaking, I don’t think it makes a lot of sense for a PLC to own an extraordinarily large cash balance, 10% of M&C Saatchi (LON:SAA), and five software businesses. But that’s not the point of the thing: it’s about whether or not you believe in the long-term vision of Vin Murria OBE.
SRT Marine Systems (LON:SRT)
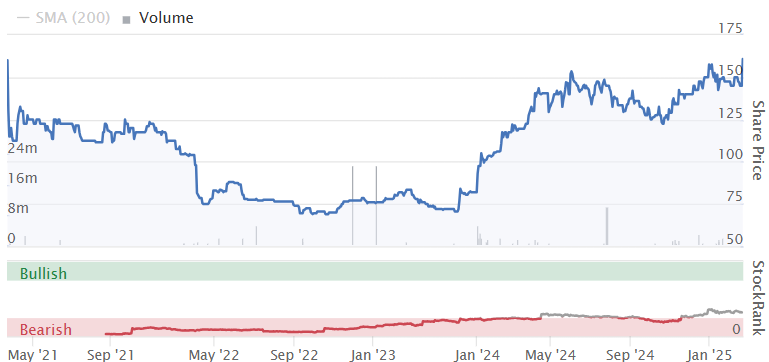
Up 5% to 48.8p (£122m) - Response to reports in Philippines press - Graham - AMBER/RED
This relates to the Integrated Marine Environment Operating Systems (IMEMS) fisheries project in the Philippines.
The relevant press report is thought to be this article in the Daily Tribune, a national broadsheet.
CEO of SRT Marine, Simon Tucker, is named in the article in which they state that he, along with others, “will stand trial on graft charges related to an allegedly anomalous P2 billion vessel monitoring system project in 2018”.
2 billion Philippine pesos are today worth £27m.
The article continues:
The case stems from allegations that the three conspired to award a P2.09 billion contract to SRT-UK, despite the company’s prior disqualification from a French-funded bidding process. The original project, backed by a P1.6 billion French government loan, required bidders to be French or in a joint venture with a French firm.
SRT-France, a subsidiary of SRT-UK, was disqualified by the French Ministry of Finance due to British ownership and lack of operational facilities in France.
And then perhaps most worryingly:
Tucker has yet to surrender to authorities. Judge Alagar ordered Tucker to appear in court and post bail before the 26 February proceedings.
SRT’s response (emphasis added by me):
As noted via an announcement on 24 April 2024, SRT clarifies that the IMEMS contract was won following an open and competitive international tender, which has been successfully implemented and is operational. The Ombudsman has previously confirmed that both SRT and Richard Hurd were cleared of any allegations. The Ombudsman had recommended further investigation into Simon Tucker and other individuals outside of SRT, and we are pleased to see this now moving forward through the Philippine legal process towards a clear resolution. The Board remains fully supportive of Simon who continues with the process to clear his name.
Richard Hurd is SRT's CFO.
It’s good news that the company itself has already been cleared. But Simon Tucker has been CEO since 2008 - I trust that the Board has a succession plan, if a replacement for him was needed at short notice for any reason?
Graham’s view
Long-time readers will know that I’ve never believed in this company. There have been so many false starts and promises that it was about to succeed financially, but it never happened.
Recently, the promises of imminent success became larger than they had ever been.
The last outlook statement said that “the coming years will be transformational” (the Chair’s words). There were said to be £320m of system projects in the order book, to be implemented over the next two years. Another small ($15m) contract has been signed since then.
Historic annual revenues at SRT peaked at £30m (2023) and have been as low as £8m (2022). So the size of the order book now is huge, relative to past revenues.
Accordingly, I switched to neutral (e.g. see my comments in December) as I waited to discover if these huge projects would be delivered soon and if they would, as promised, transform the company’s fortunes.
But it was noteworthy that broker Cavendish did not publish any financial forecasts - not for FY June 2025 or any other year. Perhaps that’s just because the timing of revenue recognition is too difficult to predict, but it’s unusual.
Anyway, after today’s update, I think I’m going to trust my instincts and put AMBER/RED back on this stock again.
This could be overly pessimistic. The case in the Philippines might come to nothing, the company might be about to generate £300m+ of revenues, and the £1.2bn “validated pipeline” might convert well into revenues, too.
Maybe. But an important point of the colour system is to highlight risk and I deem SRT to be extremely risky.
More reliable than profit growth has been the growth in its share count:
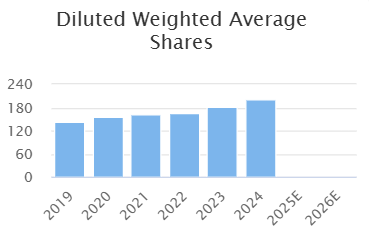
Let me emphasise that I don’t have a strong view on the legal situation in the Philippines. It’s just another risk that gets added into an overall picture that I already believed to be highly uncertain and unpredictable, from a company with many historic promises of success.
Safestore Holdings (LON:SAFE)
Up 2% to 597p (£1.3bn) - 1st Quarter Trading Update - Graham - AMBER/GREEN
It has been many years since we checked in on this self-storage REIT.
Sentiment doesn't look great:
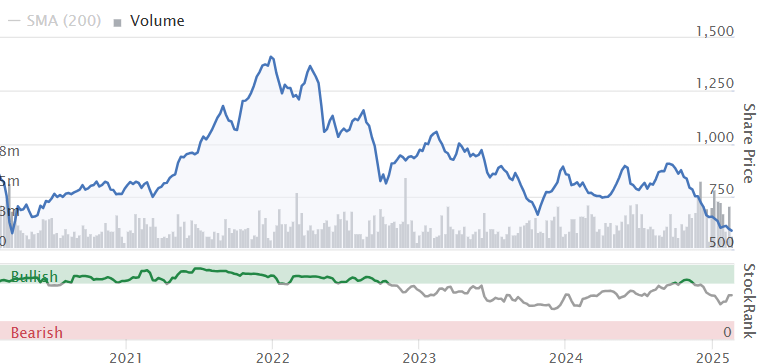
Revenues have grown at a long-term CAGR of 8% according to the StockReport, although there was no growth in 2024 and expected total growth (not like-for-like) in FY October 2025 is modest at 6%.
Some headlines from today’s Q1 update:
Like-for-like revenue +2.9% at constant exchange rates.
Total revenue +3.5% at constant exchange rates.
Like-for-like occupancy 75.9% (Q1 last year: 74.5%).
Like-for-like average store rate £29.88, down 0.6% year-on-year.
It’s all very stable, even unexciting. But I suppose many REIT investors are trying to avoid fireworks.
CEO comment refers to the “improving trajectory” in UK occupancy, with “strong domestic demand”.
There has been >30% growth in revenues from “Expansion markets” (Spain, Netherlands, Belgium) but they are starting from a low base. I think they account for less than 10% of total revenues.
We continue to make progress in opening our pipeline of stores in line with the programme we disclosed in January with six new stores and an extension opening in the quarter, adding over 300,000 sq ft of MLA [maximum lettable area] to the portfolio. Our future development pipeline includes a further seven stores projected to open this year, with a total 8% increase in MLA projected for the year.
I guess the 8% increase in lettable area help should support the total forecast revenue growth.
Graham’s view
I’ll tentatively go AMBER/GREEN on this due to EPRA (real estate) net tangible assets per share of 1,091p as of year-end, October 2024.
Net debt was very significant at £900m. However, the LTV ratio was only 25%, and “the Board considers the current level of gearing is appropriate for the business” (according to the results published in January).
I also take comfort from the debt repayment schedule, with light maturities until FY 2029:
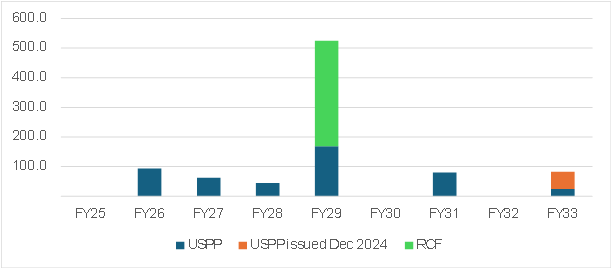
So this is another REIT where I’d be interested - possibly cheap against its existing estate and possibly not too risky in terms of leverage. More research is needed.
Mark's Section
Zoo Digital (LON:ZOO)
Down 33% to 18.5p - Trading Update - Mark - RED
This update sounds ok:
The Board currently expects full year FY25 revenues will be at least $50.5 million, which is up 24% on the prior year. The full year revenues will result in a return to EBITDA profit of at least $1.0 million, compared to a loss of $13.6 million last year.
Until we get to this line:
As a result, FY25 revenues and EBITDA1 are expected to be below market expectations
Helpfully, they give those expectations:
For the purpose of this announcement, the Group believes market consensus for FY25 to be revenue of $55m, and adjusted EBITDA of $2.75m.
So that is a material downgrade in EBITDA. It annoys me when companies say “EBITDA profit”. While they may be trying to distinguish between positive and negative EBITDA, at the end of the day, EBITDA is not profit, unless you have a company with no assets, no cash and doesn’t pay tax!
I can’t see any updated research coverage, so I’m going to have to do my own legwork on this one. The HY results released in November had:
· Adjusted EBITDA1 returned to profit, as previously guided, of $1.6 million (H1 FY24: EBITDA loss of $7.1 million)
· Operating loss of $2.5 million (H1 FY24: loss of $10.9 million)
So that means that H2 actually delivered a $0.6m LossBITDA. There is $4.1m of D&A in H1, so we should expect an operating loss of about $4.7m for H2. To be fair, their capex in H1 was a lot lower than D&A at around $1.2m. However, there was around $200k in interest costs. So unless they have cut capex further, we will see about $2m of cash outflow in H2. This tallies roughly with the guidance today:
The Company has also been closely managing its cash position and it expects the balance at the end of FY25 will exceed c.$1 million, and has invoice discounting facilities of $3m and £2m, which are expected to be largely unutilised.
They had $4.3m cash at the half-year. The difference may be that payables looked elevated at the end of H1 and may have normalised. The invoice discount facilities provide some breathing room, but not that much, given the current level of cash burn.
The company are guiding FY26 to be better:
The Company is seeing a marked increase in customer discussions around new projects to a level greater than at any time over the past two years. Currently, an enlarged proportion of customer assignments relate to them both licensing in third party content and licensing out catalogues, rather than the processing of new original programming. The Board envisages that this will be an ongoing trend, with the additional volumes of original content starting to recover later in FY26.
Although not in dubbing:
Based on current visibility, ZOO expects that dubbing revenues for FY26 will be lower than in FY25. However, with a lower cost base and higher margin revenue mix the overall profitability of the business is expected to improve significantly year on year.
And there is the usual cost-cutting exercise that we are seeing so much of at the moment with UK companies. However, they seem to have been far too slow to cut these when they suffered from the writers and actors strike. The company has only survived until now because the strikes ended when they did and that they raised £12.5m from the market in mid-2023 in order to acquire a Japanese company. They were unable to complete this; hence were able to use the cash to fund their losses. Now they say that:
The ongoing restructuring of the cost base to reduce the unit cost of production provides a strong platform to return to cash breakeven.
Note that “providing a strong platform” is different to actually being cash flow positive! Given all this, I can’t put much weight on FY26 being materially better than FY25, for earnings or cash flow.
Mark’s view
While they say it is often better to be lucky than good, this is not a maxim I want my investments to be run by. This company have been lucky to survive this long. Although they are guiding a better FY26, given the recent history, there must be considerable uncertainty about this. Their luck may be about to run out. RED
Begbies Traynor (LON:BEG)
Up 2% to 96p - Trading Update - Mark - AMBER
It is a short, in-line statement from this professional services group:
Financial performance across both divisions has been consistent with the board's expectations in the quarter. With a strong pipeline and continuing elevated activity levels, our expectations for the full year remain unchanged. This would extend our strong financial track record of growth.
While that “strong financial track record of growth” may be good at the top line:
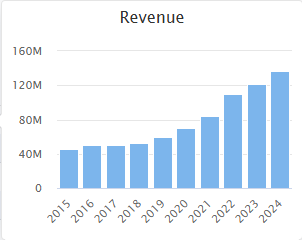
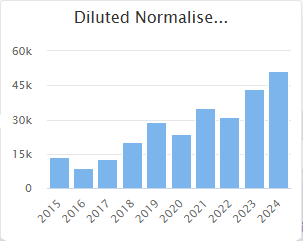
It is far more patchy and linear at the EPS level:
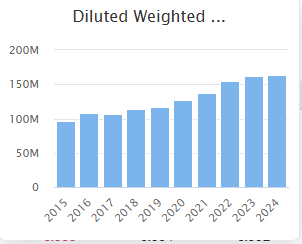
At least partly because that growth has been dilutive to the share count:
Things are looking better for this year with EPS forecast to jump by over 100%:
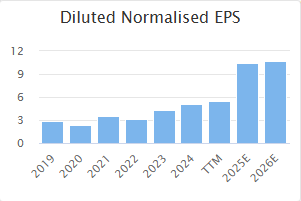
However, it is worth noting that the broker trend has been against them, and now FY26 is forecast to be barely above FY25:
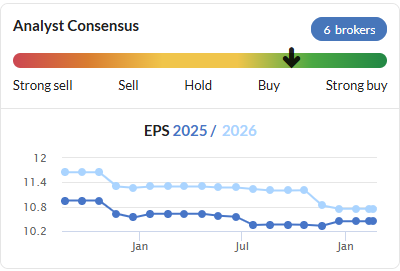
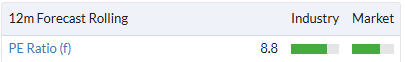
The rating is modest based on these forecasts, so the confirmation of in line is good news:
However, this should be a boom time for insolvency practitioners, so the risk is that these are peak earnings. Equity Development have a note out this morning that includes forecasts out to FY27, but again, these are largely flat in real terms without any further acquisitions, underlining that this company trades at around the right price based on current forecasts.
Free cash flow after acquisitions in recent periods has been close to zero:
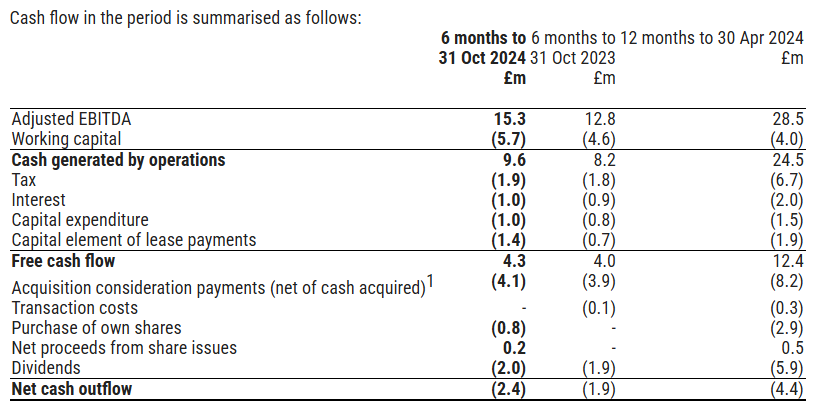
This means that the dividends and buyback in recent years have been funded by increasing debt:
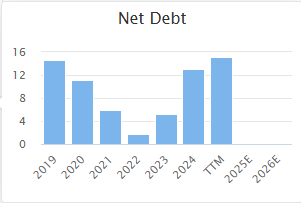
The overall gearing is low, so this isn’t an immediate concern, but sooner or later, they may need to choose between acquisition-led growth and shareholder payouts.
Mark’s view
The shares are modestly rated on forward earnings, but I can see why the market isn’t willing to rate them higher. Acquisition-led growth over the years has come at the cost of shareholder dilution and increased debt. Plus, there is the risk that the current UK economic conditions are peak season for an insolvency practitioner. So, I remain neutral here. AMBER
Anglo American (LON:AAL)
Up 3% to 2447p - Final Results - Mark - AMBER
When I looked at this a couple of weeks ago, following its Q4 production report, I struggled to get excited by its 18x forward earnings. Nor did the brokers who slightly reduced forecasts again:
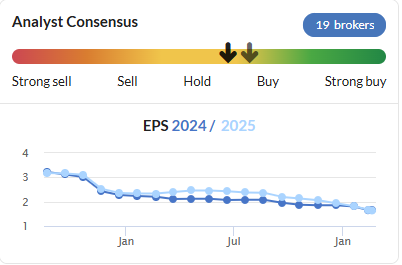
At 160c vs 164c consensus this appears to be another slight miss:
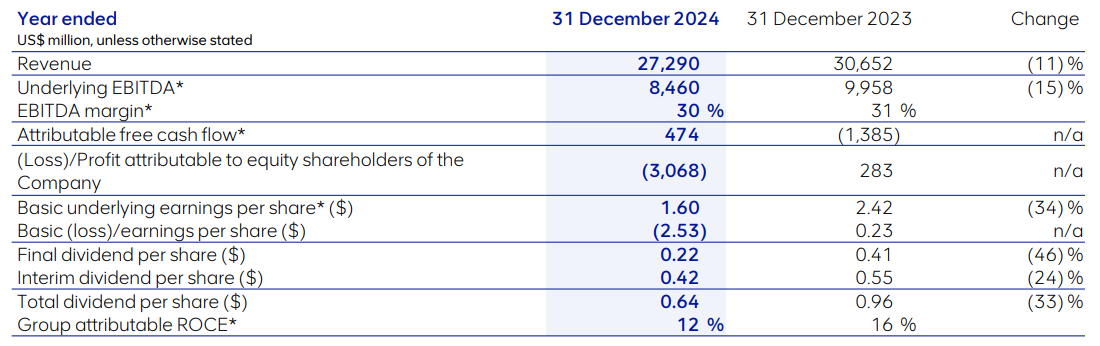
Although, it can be hard to tell with such large caps as it depends how often brokers have updated their notes. A single “stale” forecast can throw these off.
The $3.1b accounting loss is also unimpressive, even if it is largely caused by write-downs in the carrying value of De Beers. Underlying earnings are down, though. Net debt is flat at $10.6b, and the dividend is halved in line with the established dividend policy to pay out 40% of underlying earnings.
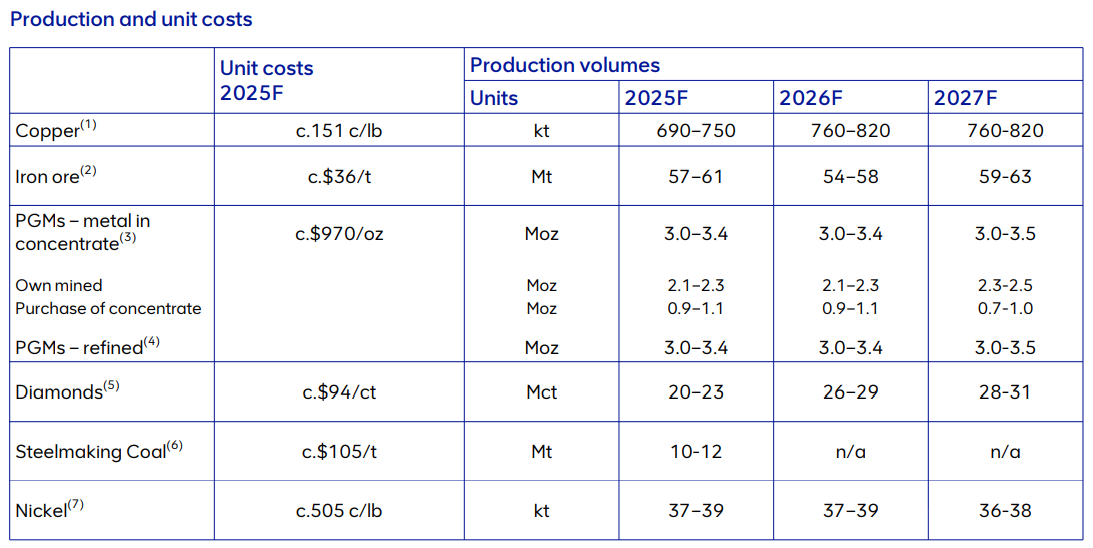
Despite all of this, the market seems to have liked these results, bidding the shares up 2%, on top of a 6% rise in response to the Q4 production report. Presumably, the market is looking forward to FY26, where copper production is forecast to grow:
Plus, they may be noting the recent strength in copper prices in 2025:
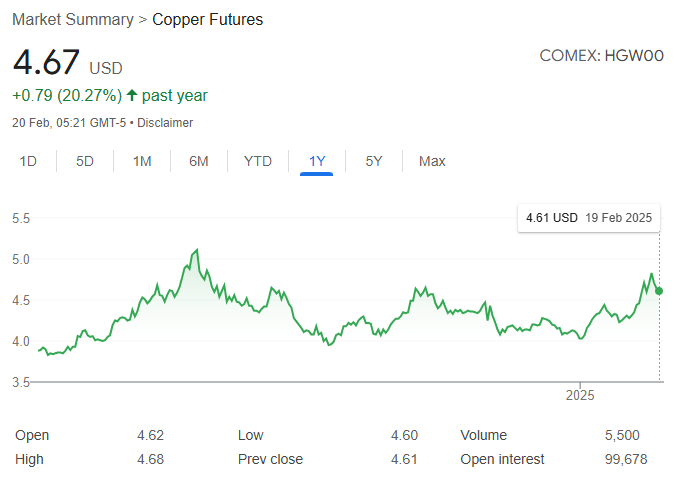
Despite these being known, brokers forecasts are for flat EPS in 2026, suggesting that the growth in production and prices may be being offset by higher costs.
Mark’s view
I don’t know enough about this miner to say that it is overvalued. However, at 18x earnings and flat forecasts, it is hard to see a positive investment case on the given numbers. For those who are bullish on copper, there would appear to be many cleaner and cheaper ways to get exposure than owning Anglo American. AMBER
Ithaca Energy (LON:ITH)
Up 10% to 144p - Trading Update - Mark - AMBER/GREEN
The past couple of years hasn’t been a good time to be a North Sea oiler, as the share price chart of ITH since listing at the end of 2022 attests:
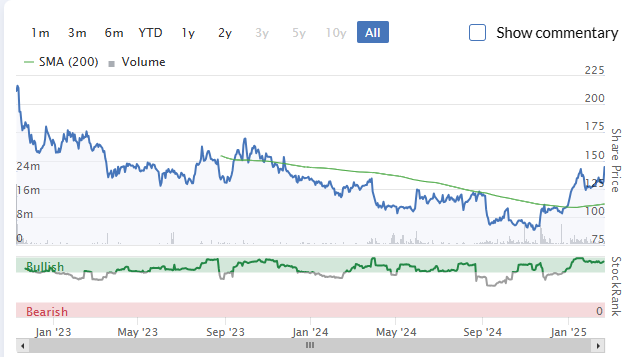
However, the shares bottomed towards the end of 2024 and are up around 50% since then, including around 10% today. The good news is that:
Strong 2024 production of 80.2 kboe/d1 at the top end of market guidance range
Which combined with costs coming in below guidance, will surely mean exceeding expectations at the PBT level. Things are complicated by a material acquisition of assets from ENI, which was completed in October, giving a further significant uplift in production.
Q4 production of 116.0 kboe/d1 and opex per boe of approximately $14/boe delivering estimated Q4 EBITDAX of $642 million
This growth isn’t reflected in earnings per share forecast, though:
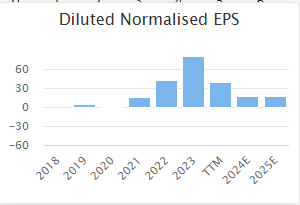
This is because the ENI transaction was a share-based one:
Following Admission of the New Ordinary Shares, the total number of shares in issue in the Company will be 1,653,732,455, of which 50.7% will be held by DKL Energy Limited, an indirect wholly owned subsidiary of Delek Group Limited and 38.7% by Eni UK Limited, an indirect wholly owned subsidiary of Eni S.p.A.
This makes the market cap around £2.4b or $3b, and the forward P/E look quite high at around 10 compared to the sector. Serica, for example, is on half this near-term rating. Their cash flow is clearly good as their commitment to paying a large dividend demonstrates:
The Group remains committed to delivering attractive returns to its shareholders, reaffirming total dividend target of $500 million for 2024 and 2025
Given the dilution and today’s price change, the dividend yield is not quite as good as the StockReport suggests, but at 16.7%, this is not to be ignored.
Mark’s view
A full valuation would require a detailed look at the various assets, reserves and production profiles. Something that is beyond me, not being an oil sector specialist. I cannot see any PI-friendly research notes either. However, this is clearly an ambitious company backed by some big oilers. The 16.7% dividend yield would clearly be attractive to income investors wanting to diversify from the more accident-probe Serica. So for that, I’ll give it in an AMBER/GREEN
Hays (LON:HAS)
Flat at 73p - Half-Year Report - Mark - AMBER
These are poor results, with Net Fee Income down 15% and operating profit (even excluding rather large adjustments) down 58%:
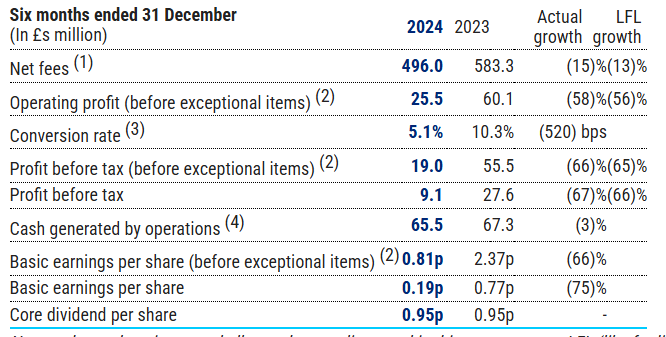
However, this appears to be in line with expectations, as the share price reaction has been negligible. However, this still leaves them with an H2 weighting to hit the 2.34p EPS consensus in the StockReport. When the consensus trend looks like this, there is perhaps a bit of relief that things weren’t worse:
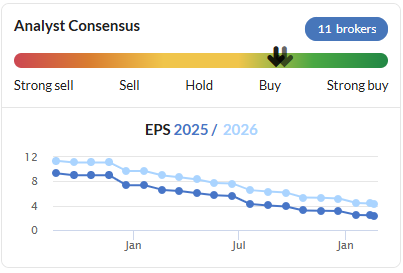
The rest of the story is familiar to anyone who has read the reports of similar recruiters. Cost-cutting, positive operating cash flow as working capital unwinds due to reduced trading, and dividends maintained. There is also the expectation of a medium-term recovery, although current conditions remain challenging. All that makes sense. However, this doesn’t mark Hays out as any different to the other struggling, larger listed recruitment companies.
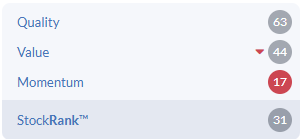
This means that investors taking the long-term view will probably do well from the cyclical rebound in the sector when it does arrive. Calling the bottom (or not) in such things is a fool’s game. However, I can’t help feeling that the time to buy would be when there are at least some tentative signs of a rebound in trading or at least when the Momentum Rank is higher than 17:
Mark’s view
Hays is suffering in the same way as all the other larger recruiters at the moment. This means that it will benefit from the same recovery when it eventually arrives. If it returns to historical EPS highs, then it will look cheap. However, I see nothing that suggests that this will be soon or that Hays will be a particularly strong beneficiary compared to any other similar company. The second half weighting for EPS revealed in today’s results adds to the short-term risks. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
source of lloyds bank income
Chief Financial Officer William Chalmers pointed to a "significant and accelerating" tailwind to income from the structural hedge. The structural hedge reduces interest rate risk and smooths net interest income over the interest rate cycle.
Chalmers expects 2025 structural hedge income to be around GBP1.2 billion higher in 2025 than the GBP4.2 billion in 2024, with a further GBP1.5 billion growth in 2026 from 2025.
The CFO explained 90% of the hedge expectation for 2025 is "locked in", as is 75% for 2026, so "we are pretty certain" it is going to happen.
I thought only the Hedge funds do this sort of clever financial engineering. Good for them and good for the shareholders too with increased dividend.
Who said the banks were boring!?
Poolbeg Pharma (LON:POLB) from the RNS around 4:40 today, I see that HOOKIPA is withdrawing from the current takeover discussions
This Achilles Investment Company Limited IPO is very interesting https://www.londonstockexchang...
Christopher Mills and Robert Naylor have raised £54m gross to actively target the alternatives sector. There is some unbelievable value appearing in renewables and infrastructure at the moment. Unfortunately, the new float is on the Specialist Fund Market but worth following to see what they do.
I have been buying more top quality trusts on very high discounts and c10% covered dividends. Greencoat UK Wind (LON:UKW) and Renewables Infrastructure (LON:TRIG) are unbelievably cheap. I am fully positioned on renewables and real estate, but may add a few more infrastructure trusts. I won't go above 15% portfolio allocation to alternatives: that is my red line.
Looks good news to help revive the sector. Agree, a lot of them look absurdly cheap - just bought some Greencoat UK Wind (LON:UKW) today and also hold Renewables Infrastructure (LON:TRIG) - these two have been particularly hit recently for no obvious reason.
Wonder if its worth buying some Achilles too? Would probably need to trade at a discount to tempt me.
Bouden54 - not much chance of Achilles opening on a discount in my view.
You're probably right but will see where it trades next week. Looks like they're initially going to target a single company - will be interesting to see which one they choose. Would imagine market cap of below £500m if they want to have any real clout.
PayPoint (LON:PAY) An RNS this afternoon shows Harwood Capital have taken >3% holding in PayPoint - maybe by buying up the sales from Columbia Threadneedle as announced yesterday ?
Stocko doesn't show this yet on the Institutions section but may do tomorrow
I think it's a great sign of confidence in PayPoint from Christopher Mills. Hasn't budged the SP today though, but still if he's buying in at current levels I think that can only be a positive sign.
They were definitely a holder before but as you say they’ve reached the ceiling whereby it has to be announced.
Ceres is in clean energy sector, which puts me off for a start. It has a mkt cap of £253m but only £22m of revenues. It has been issuing shares at around 14% pa. Nasty.
It has been public since 2004, yet I see from Stocko's Income statements that it hasn't made a profit in at least 10 years. I assume it has never made a profit. That's a long time to have nothing to show for it.
StockRank of 19, Momentum 13. Oh dear.
Completely blue sky company that has yet to deliver anything despite over 20 years of being listed.
Avoid.
Ceres Power Holdings (LON:CWR) .... and yet, less than a month ago,:
Shares of clean energy technology developer Ceres Power CWR.L up 13.8% at 159p
** Stock top gainer on FTSE smallcap index .FTSC which is up 0.15%
** Co forecasts 2024 revenue at the upper end of guidance, between 55 mln pounds ($68.46 mln) to 60 mln pounds
** Says business restructuring and cost optimisation completed in autumn will reduce annualised cost base by ~15% going forward
** "While FY25 guidance won't be available until March 21, we expect backlog of ~110 mln pounds by 2024-end, providing good visibility for 2025," Jefferies analysts say
** Stock fell 6.5% in 2024
So, at 86p to buy, CWP is down almost 50% from last month's high despite saying that the Bosch announcement doesn't change the December 2025 forecasts.
I'd welcome a view from the experts ...
You don't need to be an 'expert' to realise that the loss of Bosch as a customer is a massive blow for Ceres Power Holdings (LON:CWR) . This year's numbers might not be affected because Bosch has to meet its contractual obligations, but long term forecasts will surely take a big hit. Not good news for a serial loss maker still valued at a big multiple of sales, as Mark says.
Ceres Power Holdings (LON:CWR) l notice is down 34%, looks like Bosch is pulling out.
WG The big problem here is that analyst estimates for 2025 are for a net profit of $84m, whilst its net debt is $1261m. Net debt/profit is well over 10X, which is a huge red flag. Over the last 6 years its highest (and only) net profit was $72m.
It's on a PE of 2.6 and a PBV of 0.08. The market obviously thinks that this is a bankruptcy candidate. The market is not always wrong, either.
This one has shades of Connaught (anyone remember that one?), Carillion and Marconi. The fact that analysts have just revised EPS 2024 forecasts from positive to negative ain't pretty.
Avoid.
Sad, a really capable team of engineers, good delivery reputation in oil& gas, AMEC was not a great fit.
Card Factory (LON:CARD) up over 5% this morning, not found any news out there.
Card Factory (LON:CARD)
Not aware of any news, but when I visited my local shopping mall just before Valentines Day, the Card Factory shop was full and staff confirmed that it had been very busy. Anecdotal, but perhaps indicative of a positive trading performance?
Perhaps one of the team might have time for a brief update on Ithaca Energy (LON:ITH) after their bullish trading update (ahead of full year Results on March 25th) today.
https://www.stockopedia.com/sh...
For fellow fans of very big dividend paying shares with strong likelihood that the huge yield can be maintained, there’s good news on that too in this section from their update posted below. This means a dividend this year about 15%. I originally bought a bit above the current price and averaged down at what looked a way oversold 118p.
The next dividend will probably be announced with their Results and last year it went ex dividend in late March and was paid in April.
“$300 million of 2024 dividends paid to date.
The group remains committed to delivering attractive returns for its shareholders, reaffirming total dividend d target of $500 million for 2024 and 2025.”
In case anyone doesn’t know, this site is superb for accurate dividend information and is updated as soon as a dividend is announced. This link is for the Ithaca Energy (LON:ITH) dividends and history. All the headings at the top are worth having a look at:-
https://www.dividenddata.co.uk...
If you get a chance any possibility to have a look at Safestore Holdings (LON:SAFE) Graham decent covered divi, quite a bit of debt but guessing offset by buildings owned ? churning out decent profits to market cap but stuck in permanent down trend.
As others have said today is it cheap or ex growth and now an income stock that hasn't bottomed yet ?
I hope to get around to that one, Phoenix! Thanks.
Thanks Graham appreciated.
If you get a chance any possibility to have a look at Safestore Holdings (LON:SAFE)Graham decent covered divi, quite a bit of debt but guessing offset by buildings owned ? churning out decent profits to market cap but stuck in permanent down trend.
As others have said today is it cheap or ex growth and now an income stock that hasn't bottomed yet ?
I see it as (at least temporarily) ex-growth and that’s clearly the market view. Discount to NAV is very attractive although interest rates call into question the valuation applied
Thanks BnB always appreciate your input would you be a buyer or on the watch-list for the time being ?
Watchlist for now. Plenty of time to dip in if/when interest rates finally turn down.
My view is that it is not ex-growth and wrote further about it here for anyone interested.
Safestore Holdings (LON:SAFE)
I'm a little late here, but I thought that I'd throw in some of my own thoughts.
As an unbiased holder (ahem) I think the shares are undervalued looking 2-3 years out.
Modelling out:
(c60% of debt is at fixed rates);
(hopefully I'm being prudent, but this seems about right when looking at Big Yellow (LON:BYG) ,Shurgard Self Storage (EBR:SHUR) and when looking at historical margins for Safestore Holdings (LON:SAFE) )
then I would predict underlying free cash flow of c £120m by FY27.
The above excludes M&A.
The current market cap is £1.3b.
I personally believe that the shares should be trading at a free cash flow multiple of at least x15 given the relatively stable cash generation and modest growth - that would be a target market cap of £1.8b, which is 40% above the current value, or an IRR from today of c14%.
There's undoubtedly going to be something wrong with my assumptions, e.g. FX rates will not be constant, but given the short 2-3 year timeframe hopefully they won't be too far off.
In the meantime, I'm happy to collect the c5% dividend.
A
Serabi Gold (LON:SRB) : I would be interested to hear views from holders like myself on potential upside. The current price is sitting at consensus estimates and is a 188% gain from a year ago. With the price of gold continuing to rise, reflecting the macro picture, one suggestion is that there could be a further 50% increase in the share price.
Like all commodity stocks Serabi Gold (LON:SRB) price is linked to the current commodity price and is subject to cyclicality. Currently Gold is enjoying a number of tailwinds - at some point the wind direction will change.
What I like about Serabi is that it has a clear plan and funding to increase production significantly in the medium term - so i think its one of the better plays in the gold sector. The stock rank confirms the quality metrics. But its still subject to cyclicality.
Disclosure - I hold
At what point in the cycle are we? With Trump adding to an already uncertain world and the possibility of more governments switching from the $ to gold, the underlying commodity price may well have material upside.
If the war in Ukraine and the fighting in Gaza ends would this impact the price of gold? I’m no trump fan but hold the view these two conflicts will be brought to an end but uncertain if this happening helps or hinders gold price? I suspect the trade war between US, China card the EU will impact price too and suspect the trade war could be a positive impact on g9ld price. I hold Serabi Gold (LON:SRB) and have some money in gold runs that have done well of late but trying to work out best exit time.
It is a complex situation. The two conflicts may well end but there will be an uneasy peace with Europe less likely to see the US as a reliable ally. China is sitting quietly on the sidelines watching the West weaken whilst by all accounts increasing its gold reserves and reducing reliance on the $.
Not sure it will end soon. If Russia gets its way, then it could lead to other conflicts, such as China invading Taiwan, who is going to stop them? Trump is siding with Russia, at the moment. USA may try to take over some as well. Interesting interview on Newsnight last night about the possible new world order. The EU definitely needs to increase its defence spending.
l think gold is worth holding for some time.
It seems like whatever happens governments will have to spend more and hence increase their already very high debt levels. There is the very real possibility of defaults at some point so I suspect more investors are seeing gold as a better option than bonds etc. I intend to hold gold for some time and as any CGT liability ends on death I might just let my executors sort things out under IHT 8-)
Yes, the "EU is preparing a substantial defense package for Ukraine, estimated at €700 billion,"
Just seen this: "U.S. Defense Secretary Pete Hegseth asks parts of the military to propose what could be cut as part of a potential 8% spending reduction for them over each of the next five years"
Hi Rusty hoping its true where are you seeing the 700 billion euro's ?
It has been on the news, it is being debated by the EU at the moment.
Chainsaw to EUROAID.
Where would Ukraine invest the 700 billion had though a lot of the west buy their equipment from US companies? There are a few UK ones but wouldn’t this be going against Trump? In terms of the US reducing by 8% they are so far ahead of the rest of the world on defense suspect they would still be top with a big cut
I don't think it will be Ukraine investing it, it is the EU, not just for Ukraine but also boosting the EU defences. Apparently it won't be announced until after the German election. Doubt the EU even know how it will be spent yet.
BAE Systems (LON:BA.) could benefit.
The US spends more than China but money goes a lot further in China than in the US.
I don't think Trump would object to European cash being spent in US arms companies - though he might want it to be in ones he has shares in.
Year 1 - remove DEI initiatives & woke crap (8%)
Year 2 - sell more F16s and reduce F35 as unaffordable by anyone else (3% but increase over time) (why is UK developing another Eurofighter ? Nothing with a human in it will be in the air in the future anyway.)
Year 3 - keep Aircraft carriers afloat for longer and close the replacement programme - old tech. Ditto tanks but looks good.
Year 4 - hopefully by then the Defence Industrial Complex lobby has been cleaned up (30%)
Year 5 - now we can think of Taiwan (see Year 1 with Japan squadrons of F16 with top tech, Australia producing minerals rather than diversity reports and Musks Starlink comms systems controlling the show. (no savings just efficiency see year before)
Year 6 - as Dave Allen said "may your god be with you".
Hello Mark, Not sure if you picked up on the RNS from John Wood (LON:WG.) late last night, but the CFO resigned after less than 1 year in the seat.
Turns out he lied on his CV about how good we was at counting. Pretended to be better at it than he actually was. Explains a lot of what has gone on there in the last year. Went from predicting 'significant' cash flow this year to -$200.
Maybe he didn't complete the section on negative numbers that was needed for the chartership!
He wasn't even in the role for 10 months, appointed last April, Wood's problems go back to the acquisition of Amey and the kind of contracts it has engaged over the years - but yes, a bit cheeky embellishment of a qualification hence Wood can't sustain him in a wider credibility crisis. More significantly, who capable is likely to leave their job to step into this role?
I think you mean 'Amec', not 'Amey', but I agree with your comments Edmond.
Jarvis Investment Management announce a 1.5p quarterly dividend and update the glacial progress on the conclusion of their s166 FCA inspection. Welcome signs of life and progress however.
Jarvis Investment Management announce a 1.5p quarterly dividend and update the glacial progress on the conclusion of their s166 FCA inspection. Welcome signs of life and progress however.
It's staggeringly slow progress, but the only slightly reduced dividend does at least suggest there are no major new issues arising.
My experience with JIM has caused me to update my algorithms: on the first sign of regulatory issues -> RUN AWAY QUICKLY.
timarr
Easier said than done though timarr. On-line dealing goes straight off when the market makers get wind and then you're in a queue of people trying to fight for a parachute.
Can’t make up my mind about JIM. A buy for yield and recovery or an outrageous gamble? I tend towards the former but concerned about the don’t know / don’t knows.
Can’t make up my mind about Jarvis Securities (LON:JIM). A buy for yield and recovery or an outrageous gamble? I tend towards the former but concerned about the don’t know / don’t knows.
Hi LG
It's not for the risk adverse that's for sure, but if we assume a 4.5p dividend, it's paying out over 10% and has net cash. It's got family shareholders and chairman who aren't likely to bail on it and who presumably have their own best interests at heart.
I'm too heavily invested to be a disinterested observer, but I can't really see a reason to sell here. When the skilled person finally departs with a trouser load of cash and the fog clears (well, as much as it ever does with Jarvis) it'd be surprising if it doesn't re-rate.
My major concern is the time the changes are taking:
It is anticipated that the majority of this additional remediation work will now be completed by the end of the third quarter 2025. The Skilled Person will then review this additional remediation work. Further updates will be provided as appropriate.
The Skilled Person is paid by Jarvis but directed by the FCA. Either the issues they've found have been massive or the whole thing's being mismanaged. Either way, it doesn't offer a lot of confidence in the company.
On the other hand - 10% dividend while you're waiting, limited downside and possibly 50% upside in a year or so?
Given some of the value lying around in financials and REITS if I wasn't invested I'd probably stay clear.
timarr
Finding myself in the same boat timarr,
I'm too heavily invested to be a disinterested observer, but I can't really see a reason to sell here.
For long-term PI's the dividend is not so encouraging,, my last full year producing one of 2.2 percent. It's looking like there will be another year in the doldrums for Jarvis Securities (LON:JIM) , I'll wait it out but for fresh money the grass is greener elsewhere.
Thanks for the detailed response timarr. I appreciate your time, knowledge and effort. I think JIM must remain as a watch and wait for now. If the share price suddenly starts to move north for no apparent reason I will have another look. Alerts set. 10% yield is no great shake in the current market and I am increasingly risk averse.
Hi LG (and Silver Moon)
Jarvis Securities (LON:JIM) is a rare example of where a stop loss would have saved me a lot of pain. Mostly I have no problem selling at a loss and moving on, but this has been like a frog being slowly boiled alive.
Anyway, I certainly wouldn't be buying at this point, we need to see a definitive end to the endless skilled person review first and it looks like that could easily be another year ...
timarr
I used a broker that cleared through Jarvis Securities (LON:JIM) and having experienced the quality of the service provided by Jarvis, I would never invest in them.
Yes my broker used them too and have since changed to another .
Glacial is the correct word to describe the situation, it was 16.09.2022 we heard about the FCA investigation, nearly 2.5 years.
I do get frustrated that the Jarvis website still shows key dates for 2025 as TBD. How hard can it be?
Was worried about the Q1 dividend as traditionally this would have been announced last week. 1.5p announced today is much better than I was expecting.
At yesterday's close of Jarvis Securities (LON:JIM) shares at 40.2p, this quarterly dividend of 1.5p is a 3.7pc payout. If we get 1.5p for the next three quarters, that's 6p and 14.9pc for the year.
I will keep holding for the dividend, and really hope this skilled person investigation gets completed this year, but I won't be surprised if it doesn't......
Orval, note that to get the currently projected dividend one must buy at the price of this day, a bottom-fisher could well score, or we may see dilution or another share split, who knows?
Jarvis Securities (LON:JIM)
Well I think the last thing to worry about is dilution from a fund raise after announcing this dividend and why on earth would a share split happen. There have been complaints from users of Jarvis settlement via other brokers. This sounds like the problem discussed at the beginning of the FCA examination when white label deals with some other brokers were suspended presumably for lack of care by the third parties regarding customer outcomes and/or money laundering and not the other way around. I note from their website they still administer the Goldman-Sachs employee isa so while they might be the Ryanair no frills end of the market, they are respectable and on the few occasions I've had a complaint over 20 years as a customer, it has been quickly rectified after an email to senior management. Compare charges with the rest of the market.
Be interested to hear thoughts on SRT Marine Systems (LON:SRT) as I was gearing up to buy in
SRT Marine Systems (LON:SRT) I hold
since you asked boheni, this is a unwanted distraction to a business that is on a roll. The story began when SRT won a bid to supply the Philippines with a system to monitor its fisheries. The French government had offered to provide finance but on condition that the contract was awarded to a French company. Unfortunately for them, the system supplied by CLS was expensive and much less capable than the one SRT offered so it was clear that SRT would likely win the bid. They attempted to circumvent the "French company" bit by opening an office in France. However after SRT won the contract the French withdrew their offer of finance and with no budget, the Philippines had to restart the process including finding the money themselves.
Eventually a new competitive tender was issued and SRT again won the bid. The system was installed and is successfully operating today. It was intended that up to 50,000 fishing boats would be monitored but there was significant opposition from powerful commercial fishing companies who wanted to carry on fishing close to shore where small fishermen operated. These small fishermen simply needed fish to feed their families and the large catches of commercial companies are causing fish stocks to plummet.
This is the story that appeared in the Philippines press which gives the background to this case. https://tribune.net.ph/2025/02...
I fear that political influence may be a factor here. Research shows that the wife of the Ombudsman bringing this case is significantly connected to one of the large commercial fishing companies. This is a photo of her https://ibb.co/FLs8xcWk and here she is at a USAID event https://ibb.co/SHFy85L in 2022 https://sustainablefish.org/pr...
Whilst it is open to interpretation, the interest of commercial fishing companies lies in relaxed regulation that allows them to carry on taking the lion's share of fish. It is noteworthy that SRT itself is not implicated and it is unclear exactly what Simon Tucker is accused of.
thanks for this detailed info rhw3ue - what a mess - Must say it does seem a crazy saga but no surprise for this country. BTW I'm sure if USAID had offered the money they would have insisted on American contractors .
Crossing the French and not paying bribes!
From memory Simon Tucker at the recent AGM played down the seriousness of the situation and, contrary to legal advice, said he intended to fight the case. Not sure if that meant actually attending in person…,!
Anyone have a different take away from the meeting ?
Crystal Amber Fund (LON:CRS)
Positive update regarding Morphic Medical and progress of Reset regarding its non invasive medical device for the treatment of obesity and diabetes. Confident of achieving CE certification and subsequent adoption in Germany, UK and other jurisdictions in the near future.
Could be a game changer in the treatment of such diseases, avoiding the use of drugs and surgery.
Jonno, my concern is that if the chances of it being a game changer are so high why did the manager sell 1.75m shares on 18 Feb?
No idea Charles. Crystal Amber Asset Management are effectively Richard Bernstein and Jonathan Marsh. They still hold close to 6% of the company as far as I can work out.
I keep looking at Safestore Holdings (LON:SAFE) it’s looking very cheap now, no growth post pandemic after boom in storage, but I suspect that’s transitory. What’s the catch?
I hold. They have been aggressively investing in new space during the downturn while the CEO has been buying chunks of stock on market. My main concern is the semi-discretionary nature of the business. I think there is a risk that growth remains anaemic as we continue the trend towards more of a needs based economy. Still, I think that reality is largely priced in already.