Daily Stock Market Report (Thur 27 Feb 2025) - AVAP, RR., MACF, TW., JUP, CVSG, PPHE

Good morning! It has been a busy week for updates, let's see what's in store for us today.
And we'll kick things off with a backlog section from Mark on AVAP.
Spreadsheet that accompanies this report: updated to 14/2/2025.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
London Stock Exchange (LON:LSEG) (£61.3bn) | Final Results | Total rev +5.7%, adj EPS +12.2%. Equity FCF of £2.2bn. 2025 exps for >£2.4bn FCF, higher margins. | |
CRH (LON:CRH) (£54.6bn) | Final Results | Rev +2%, net income +15% with higher margins. 2025 outlook +ve, w/ “supportive underlying trends”. | |
Rolls-Royce Holdings (LON:RR.) (£53.6bn) | Final Results | Adj op profit +54% to £2.5bn, FCF of £2.4bn. Net cash £475m. 2025 guidance for £2.7-£2.9bn FCF. | AMBER (Roland) [no section below] |
HALEON (LON:HLN) (£35.8bn) | Final Results | Org rev growth +5%, adj op profit +9.8%. FCF of £1.9bn. 2025 outlook for org revenue +4%-6%. | |
Aviva (LON:AV.) (£14.1bn) | Final Results | GWP +11.9% to £12.2bn, adj op profit +20% to £1,767m. Dividend +6.9% to 35.7pps. | |
WPP (LON:WPP) (£8.3bn) | Prelim Results | Underlying rev -1% LFL. Adj op profit +2% LFL, margin 15.0%. Divi held. 2025 outlook H2 weighted. | |
St James's Place (LON:STJ) (£6.2bn) | Final Results | Adj net profit +14% to £447.2m, net inflows £4.3bn, y/e FUM £190.2bn. Dividend -25% to 18p. | |
Howden Joinery (LON:HWDN) (£4.6n) | Final Results | Rev +0.5% to £2,322m, op profit -0.3% to £339m. 2025 outlook “challenging”. Targeting mkt share. | |
Taylor Wimpey (LON:TW.) (£4.1bn) | Final Results | 2024 new homes -2.3% to 10,593, op profit -11.5%. ASP -1.5%. 2025 outlook in line with market exps. | AMBER/GREEN (Roland) [no section below] TW delivered an improved sales rate from a reduced number of sites last year but now seems to be positioning for a return to growth. The order book at 23 Feb was 8,021 homes, up from 7,402 last year and pricing is now said to be flat YoY. Net cash of £565m is reassuring, but is being used to subsidise the uncovered dividend. With the shares trading slightly below NTAV of 124p, I’m cautiously positive despite subdued profitability. |
Hiscox (LON:HSX) (£3.8bn) | Final Results | GWP +3.7%, PBT +9.5% to $685m. ROE 19.8% (2023: 21.8%). 2025 outlook positive. | |
Ocado (LON:OCDO) (£2.8bn) | Final Results | Group rev +14.1%, adj EBITDA +197% to £153.3m. £224m cash outflow, exp +ve cashflow in FY26. | |
Man (LON:EMG) (£2.6bn) | Final Results | AUM +0.7% $168.6bn. Inv perf +1.0%. Net outflows $3.3bn. NTAV $867m. EPS +29% to 25.1 cents. | |
Shaftesbury Capital (LON:SHC) (£2.5bn) | Final Results | EPRA NTAV +5.2% to 200.2pps/£3.7bn. Portfolio +4.5% LFL. Adj EPS +16.2% to 4.0p. | |
Greencoat UK Wind (LON:UKW) (£2.5bn) | Final Results & £100m buyback | NAV -10% to £3.4bn/151.2pps. Dividend held at 10p. Targeting 10.35p for FY25, £100m buyback. | |
Drax (LON:DRX) (£2.3bn) | Final Results | PBT -5.4% to £753m. DPS +12.6% to 26p. FY25 adj EBITDA outlook in line with consensus. | |
Derwent London (LON:DLN) (£2.2bn) | Final Results | EPRA NTAV +0.6% to 3,149pps. Total return 3.2%. Div +1.3% to 80.5p. FY25: 3-6% rental growth. | |
Serco (LON:SRP) (£1.3bn) | Final Results | Rev £4.8bn, adj op profit +10% to £274m. 2024 guidance for flat revenue, efficiency gains. | |
Genus (LON:GNS) (£1.2bn) | Half-Year Results | H1 rev +1%, op profit +22%. Mkt stable. FY25 outlook in line with recently upgraded expectations. | |
Cairn Homes (LON:CRN) (£1.1bn) | Final Results | Rev +29%, op profit +32% to €150m. ROE 15.1% (LY: 11.3%). 2025 to be another strong year. | |
CVS (LON:CVSG) (£758m) | Interim Results | LfL sales growth -1.1%. Leverage 1.66x. Outlook: in line. Prioritising Australia until CMA finishes work. | AMBER/GREEN (Roland) [no section below] |
Metro Bank Holdings (LON:MTRO) (£658m) | Final Results | Net income £42.5m, includes tax gain. Underlying profit in H2 beats guidance of profitability in Q4. | |
PPHE Hotel (LON:PPH) (£547m) | Final Results | Like-for-like rev +3.3%. PBT £30.6m (LY: £28.8m). Occupancy 74.5%. NRV per share £27.51. | GREEN (Graham) [no section below] Still trading at only 50% of its official NRV (net realisable value) per share. The question is whether this value is meaningful. Nice upward trend in occupancy although there is a lack of progress in terms of RevPAR (revenue per available room). Four new hotels have opened with another due in March 2025 and as these mature we should see this reflected in future EBITDA/PBT growth and hopefully in the NRV, too. The new hotels negatively impacted 2024 results which is considered normal for the pre-opening phase. I still find this very interesting. Net debt of £750m needs to be managed. |
Serica Energy (LON:SQZ) (£489m) | OFAC Licence Renewal | OFAC license & assurance relating to Rhum field is renewed to Feb 2027. | |
Jupiter Fund Management (LON:JUP) (£439m) | Final Results | “Resilient”. PBT £97.5m (LY: £105.2m). Net outflows £10bn+. AUM down 13% to £45bn. | GREEN (Graham) Excellent profit margins despite awful sentiment, and a market cap that’s mostly covered by balance sheet strength. I feel obliged to keep my contrarian stance alive. |
Brooks Macdonald (LON:BRK) (£236m) | Half-Year Results | H1 “solid”. Anticipates full year performance in line with expectations. | |
Macfarlane (LON:MACF) (£172m) | Final Results | Rev -4% (£270m), PBT +3% (£20.9m). 2025 to be challenging, positioned for profitable growth. | GREEN (Roland) |
hVIVO (LON:HVO) (£108m) | Acquisition | £3.2m acq. of storage solutions provider (bio & clinical materials). £2.7m cash, £0.5m equity. | |
Winking Studios (LON:WKS) (£75m) | Prelim Results | Rev +8.9% ($31.9m). Adj net profit -10% ($3.4m). Outlook: strong project pipeline. $20m acquisition. | |
K3 Business Technology (LON:KBT) (£45m) | Final Results | In line. Reduction in revenue was expected. ARR -1% to £16.7m. Cash breakeven from March. | |
Polarean Imaging (LON:POLX) (£16m) | FY TU | Rev $3.0-3.1m, exceeding upper end of guidance. Cash $12.1m, giving runway through Q1 FY26. | |
ITIM (LON:ITIM) (£13m) | TU | Revs up to £17.9m, EBITDA and cash significantly ahead of exps at £2.5m and £3.8m respectively. |
Backlog
Avation (LON:AVAP)
140p (£94m) - HY Results - Mark (I hold) - AMBER/GREEN
Everything seems to be going in the right direction here:
· Revenue and other income increased to US$55.4 million (2023: US$46.3 million) displaying continued business momentum;
· EBITDA increased to US$55.6 million (2023: US$38.3 million) demonstrating enhanced cash generation;
However, the rise appears to be largely due to how maintenance is accounted for:

We adjust our forecasts to account for non-cash movements, as well as incorporating the additional revenues and costs from the A320 purchased. As a result, our revenue expectation in FY25E increases to $102.3m (from $94.8m), this also reflecting maintenance reserve revenues, leading to PBT of $0.9m (from $7.4m) after non-cash movements, with our net debt forecast increasing to $624.4m, reflecting the acquisition of the A320, partly offset by the strong cash performance. For FY26E, we look for revenue of $99.7m (from $95.8m), leading to PBT of $8.4m (from $8.1m).
All of this makes it perhaps more important to focus on cash flow rather than accounting earnings, and here things look better:

Given the debt, we really need to be looking on an EV basis. Annualising the OCF works out to be 6.7x EV/OCF after taxes & financing, so this appears to be good value on that basis. There is also the potential for the finance expense to reduce over time. Earlier this month, the company said that refinancing $85m of debt would lead to $4.8m of improved annual cash flow. Any additional refinancing could be material and will not be in forecasts.
Despite the strong cash flow, the dividend paid to shareholders is very low, with the money instead spent on debt reduction and further building their fleet. In light of this, the acquisition announced today was perhaps not the one shareholders wanted (many AVAP shareholders would prefer to read about the sale of the company to a larger aircraft lessor):
…it has entered into an agreement to acquire an Airbus A320 on lease to Etihad Airlines. This secondary market transaction adds a high credit quality airline to Avation's customer list and further enhances Avation's narrow-body aircraft fleet.
Regardless of the strategic value of this move, I can’t help feeling that with a NAV per share of £2.94 vs a share price of £1.43, they would have been off buying back their own shares in the market. To be fair, they did buy back 10% of their shares in a single transaction at around 50% of NAV at the end of last year. However, the market would perhaps appreciate a more regular purchase schedule.
Mark’s view
While the assets are not particularly productive based on accounting earnings, and even less so following today’s downgrade, the operating cash flow is strong. There is also the catalyst that debt is being refinanced at lower rates that should drop through to the bottom line. When I looked at this in December, it just seemed too cheap on an asset basis, and I see nothing in these results that changes that. AMBER/GREEN
Graham's Section
Jupiter Fund Management (LON:JUP)
Down 4% to 77.5p (£423m) - Annual Financial Report - Graham - GREEN
I haven’t looked at this since July, although Roland and Mark have looked at it since then.
What’s striking to me about today’s results is the profitability that is achievable despite enormous outflows and dire sentiment in the sector.
This is why I’ve been positive on the conventional fund managers. Even in those times of extremely poor flows - surely the worst in the history of the UK asset management industry - they remain profitable, with profit margins far in excess of that which many other industries can achieve.
Today’s results from Jupiter highlight this point.
We have an underlying PBT of £97.5m, down by 7% from £105.2m the previous year.
We have statutory (i.e. unadjusted) PBT of £88m.
This has been achieved despite a horrendous net outflow of £10.3bn, about a fifth of the year’s starting (£52.2bn).
The company does acknowledge that its underlying profit margin has taken a hit, with a “cost: income ratio” of 78%, up from 73% the prior year.
Broadly speaking, if this gets to 100%, it means that administrative expenses are eating up all of the company’s net revenues.
Also, the net management fee margin has reduced from 70 basis points (0.7%) to 65 basis points (0.65%). Fee erosion is an important theme in the sector. As most active fund managers struggle to match, let alone beat, the performance of low-cost ETFs, there is a natural downward force on the fees they can charge.
But still, I go back to that enormous profit margin of £97.5m (underlying PBT) from net revenues of £364m. That’s a pre-tax margin of nearly 27%.
And as a rule, fund managers never have an issue converting their profits into cash. Customers are in no position not to pay, as their liquid assets are available to make immediate payment of fees.
What I'm looking for from fund managers in this environment is a drive for simplicity. The way I see things, one of the main problems with the industry is that there are too many funds. So simplicity is the way forward, I think.
Comment from CEO Matthew Beesley, whose overall strategic direction has been very good in my view:
We have made material progress to better position Jupiter for future success and have progressed in each of our strategic objectives… The actions we took during the last year, together with improving performance and encouraging early signs this year, give us confidence that we will see near-term growth in the majority of our investment capabilities.
We have again delivered on costs, demonstrating strong discipline in non-compensation costs and finishing the year with fewer than 500 FTEs, our fourth year of headcount reduction and lowest level since 2016.
Dividends: the proposed final dividend is 2.2p, so that total dividends for the year are 5.4p.
Total dividends last year were 9.8p, including a final dividend of 3.4p. So this is a significant reduction.
Was it necessary to cut the dividend so much?
Underlying earnings per share were 13.4p (previous year: 14.8p). Actual earnings per share on the income statement were 12.5p.
So in theory there was EPS available to pay a higher dividend than this. But their capital allocation policy is to pay out only 50% of underlying EPS (before performance fees).
Fortunately, the dividend is not their only use of surplus cash. They also announce a £13m share buyback which equates to a payment of 2.5p per share (I know that some readers will shudder when I equate a buyback to a dividend!).
In addition, there is £50m of debt that Jupiter is going to redeem early. It wasn’t set to mature until 2030.
Performance: sounds fine with 61% of mutual fund AUM outperforming its peer group over 3 years.
Graham’s view
This is a highly contrarian stance but I’m going to leave my GREEN unchanged.
The StockRanks concur:
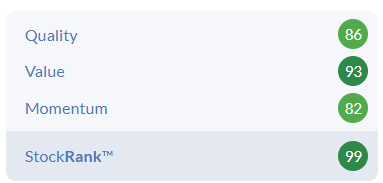
The PER is 10x and that’s without making any adjustment for balance sheet strength. Today’s balance sheet shows equity of £834m of which tangible equity is £327m. This covers more than three quarters of the market cap.
Whether it stays alone or mergers with another fund manager to gain even more efficiency in terms of costs, I think this is a stock I have to remain positive on.
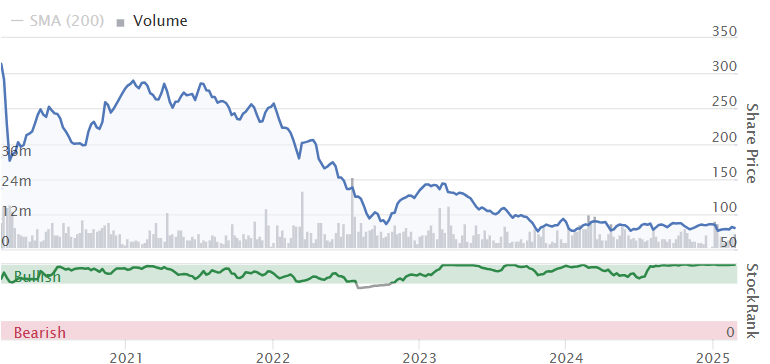
I concede that the share price has not cooperated with me yet. I’ve been positive on this for over two years now, and the stock has been unable to get out of this slump. If I’m wrong, this is a cigar with only a few puffs left.
Roland's Section
Macfarlane (LON:MACF)
Down 1.5% to 106p (£169m) - Annual Results - Roland - GREEN
We start 2025 with new-business momentum as customers increasingly recognise the added-value we can offer both on an environmental and cost-savings basis.
This buy-and-build packaging group features regularly in these pages. Today’s results may not be a vintage set of numbers, but they do not flag up any serious concerns for me.
The headline numbers for 2024 show improved profitability, despite a fall in sales:
Revenue down 4% to £270.4m
Operating margin: 8.7% (2023: 7.9%)
Pre-tax profit up 3% to £20.9m
EPS up 4% to 9.74p
Dividend up 2% to 3.66p
The company says that weak customer demand and selling price deflation affected both its distribution and manufacturing divisions. However, the distribution arm benefited from some new business and acquisitions:
Continued weak customer demand and selling price deflation have been partially offset by a strong new-business performance and the benefit of the acquisitions of Gottlieb in April 2023 and Allpack Direct in March 2024.
Improved operating margins were partly driven by changes in the fair value of deferred consideration due on acquisitions. But this seems a creditable performance to me, in terms of cost control.
Packaging distribution: In the larger distribution division, operating costs fell by 3% “through management action” and gross margin improved to 37.1% (2023: 35.7%).
Manufacturing: Macfarlane’s smaller (but higher margin) manufacturing business produces specialised packaging for industrial and other customers. It earned a gross margin of 43.2% last year (2023: 44.5%).
Although operating expenses rose by 14%, this was due to acquisitions. The company says underlying costs “are being well controlled”. I don’t see any reason to question this, given the group’s overall performance.
Balance sheet/cash flow: net bank debt stood at £1.9m at the end of December, after £15.0m of acquisitions and capital expenditure.
I estimate underlying free cash flow (excluding acquisitions) of £14.3m for 2024. This gives a very respectable 92% conversion from reported net profit of £15.5m.
Outlook: the company strikes a balanced note in its outlook statement, warning of cost pressures and a challenging environment, but also opportunities from new business.
The Group continues to invest in actions to grow sales both organically and through acquisitions. Despite the challenging market conditions the Group is well positioned to benefit from improvements in the macroeconomic outlook.
New Extended Producer Responsibility (EPR) legislation to improve packaging sustainability is expected to add cost. However, Macfarlane says it is working with its customers (in retail particularly) to help manage the impact of EPR.
I suspect EPR may be an opportunity for the company to demonstrate its value over smaller suppliers.
Estimates: with thanks to Shore Capital, we have updated earnings estimates for Macfarlane today:
FY25E EPS: 12.1p (previously 12.4p)
FY26E EPS: 12.3p (previously 12.6p)
These changes appear to be slight tweaks to underlying assumptions rather than an explicit downgrade - revenue expectations are almost unchanged.
Roland’s view
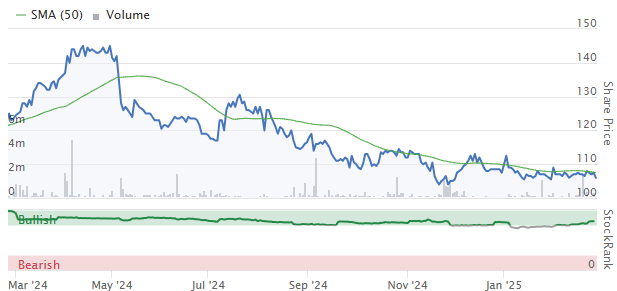
Macfarlane’s one-year chart looks poor:
But on a 10-year view, this is still an impressive growth story:
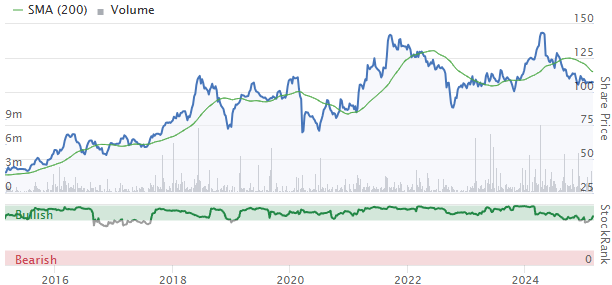
I don’t see any reason why this business can’t continue to progress well over the coming years.
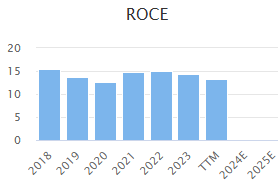
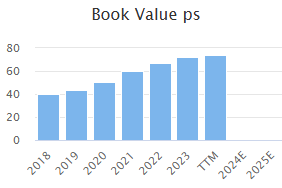
My sums suggest a return on capital employed of 13.7% for 2024. That’s consistent with prior years and high enough, in my view, to allow the group to self-fund growth and generate value for shareholders.
The two charts below show a picture I like to see – stable ROCE with rising book value per share, implying that a company is able to deploy new capital at stable rates of return:
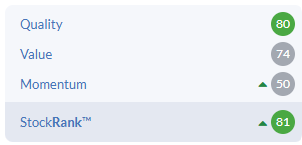
Macfarlane also scores well with the StockRanks, in particular for quality and value:
The shares now trade on a FY25 forecast P/E of 9, with a useful 3.5% dividend yield. This looks a very reasonable valuation to me, underpinned by a well-run business and solid balance sheet.
I think Macfarlane remains attractive on a long-term view and am going to leave our previous GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Thank you for your informative reply raggedtp. They look perfect for what I want a section of my funds to do. The hard part is they look to good to be true.
Went to a big Invesco macro meeting today few points off top of my head they aren't to worried about tariffs they see them as a one off inflationary hit as prices will rebase after a year, they see deportation of illegal immigrants as a possible big inflation issue.
If Trump deports 2 million people this will make jobs market even tighter meaning wages go up further as competition for staff goes up.
The other thing of note mentioned is China spending over 8% of gdp on the military this is reason US is worried about then as it used to be very low but they have really ramped up spending last 2-3 years.
They prefer equal weighted S&P 500 tracker, China very cheap now could be time to get in, Europe should be decent if Ukraine resolved, If mag 7 start to drop money should recycle into UK and Europe.
Talked about different permatations of 60/40 Portfolio best outcome although still negative was 60% in value share, 40% sub 3 year duration bonds.
Rolls-Royce Holdings (LON:RR.) officially a ten-bagger since oct 2022!
yes, i passed on it lol
No comments on Greencoat UK Wind (LON:UKW) today, I have a decent stake and have added today on news. In my view this is pretty much as good an annuity as you can buy; a discounted asset yielding around 9%, inflation proof, and a good cause. Highly unfashionable, which is often a good thing.
I've wondered about Greencoat UK Wind (LON:UKW) and read today's results.
I noticed the NAV per share has fallen by a little more than dividends paid out during the year. So being simplistic, shareholders are only getting their own investment back - possibly with some income tax liability!
Second, I noticed the company has been generating less electricity than expected because avergage wind speeds are lower than assumed. They have adjusted their expectations (fair value of assets perhaps?) accordingly.
I used to work in the renewables industry. It was several decades ago and things may have changed. But one thing that happened suprisingly often is that generation projects we invested in turned out to be less productive than we were led to believe by the project developers.
For me Greencoat does not offer sufficient margin of safety to justify an investment- I would be looking for rising NAV/share and/or a double digit discount to NAV before buying.
With your experience do you see any others in this sector that do justify investment?
I hold NextEnergy Solar Fund (LON:NESF) @ 32% discount and 12.9% yield, Foresight Environmental Infrastructure (LON:FGEN) @ 34% discount and 10.9% yield and SDCL Energy Efficiency Income Trust (LON:SEIT) @ 45% discount and 12.6% yield. Even safer is Bluefield Solar Income Fund (LON:BSIF) which this morning had reasonable results but is now @ c. 30% disc + 10+% yield. The frustration is evident in all. Do read the Bluefield Solar Income Fund (LON:BSIF) RNS. Sales are being made in the secondary market that show individual NAVs are not overblown. Most prices really started to slide with the interest rates going up and they did have to increase the discount rate on which their NAVs were judged. But this has been done and factored in. And now central rates have been going down for a while, but NONE of them have adjusted their discount rates back down yet. Eventually they must, which will make NAVs rise. I know I'm talking my book, but, given these are all diversified to some extent, whether by technology or geography, and, pace the dark, still winter the northern Europe has experienced this last year, their incomes are reasonably predictable and even, in some cases index-linked, is it likely we will see such high income opportunities again? I've already had one bought out in the last year. The Boards are all having to pay attention to offers now. If these all get bought out/taken private in the next year or so, where will anyone find such high and rising income again?
Can anyone explain in simple terms while all the renewable ITs have been battered over the last year? I understand the earlier sell-off was all about higher rates, but rates haven't really moved over the last year so there is clearly another factor at play. Sentiment to all things ESG has clearly taken a dive, but this in itself should have no impact on their underlying cashflows.
Well, I think it is partly that they are simply Investment Trusts, which are out of favour, and also not simply traditonal ITs that are aggregations of other publicly listed shares which can be valued daily. You could say they are trying to do something harder. I could show you similar discounts (if not quite such high yields) in Private Equity and specialist Commercial and Healthcare Real Estate Trusts. As Charles Mitchell over on the Investment Trust discussion thread would say, go to https://www.theaic.co.uk/ and set up a watchlist of these and you'll see. I think it's all too challenging for UK retail punters, who effectively set the price when Fund Managers are down on UK shares and therefore doubly so on 'alternatives'. Quite how investing in a basket of real assets with largely predictable income is harder than, say, bitcoin or a mining company in Africa, is beyond me, though.
The discount to NAV is 27.5% on Greencoat UK Wind (LON:UKW)
Wind speeds are forecast to fall by 10% in the summer over the next 20 - 30 years, according to the latest AI calculations and global warming assumptions.
But...offshore wind is now 50% the cost of gas. Onshore is 25%. That's a huge margin of safety. Greencoat UK Wind (LON:UKW) is about 50% on shore.
Solar is mid priced. It all depends upon whether it is subsidy free. You have to watch for subsidies that are being phased out over the next decade. I'm not sure what the position is. I've only researched wind so far.
Wind turbine blade efficiency is improving, thanks to better software.
In summary, yes there are issues, yes, the company has downgraded wind forecasts. But in my view there is sufficient safety baked into everything, thanks to the huge discounts on offer.
I'd be very sceptical of forecasts which try to calculate what wind speeds will be in 20-30 years.
I've been thinking about taking up a starter position in Greencoat UK Wind (LON:UKW) along with an attractive 9% yield I believe the Trump effect across the pond will strengthen Europe's position in being world leading in renewables. Keep a close eye on this sector.
#TIME
Aptly timed RNS - therefore ahead of expectations.
https://www.lse.co.uk/rns/TIME...
Rolls-royce Holdings (LON:RRN) - with the excellent figures from Rolls Royce I am wondering why the Stock rank isn't higher.
Rolls-royce Holdings (LON:RRN) I often do not understand how some shares are valued so highly, good results today but I felt they were overvalued before todays big price increase, shows what I know…….. I get the how some big tech firms demand high P/E ratios as they can scale very quickly, once up and running they can demand high profit margins but really struggle to understand very high P/E ratios from established businesses in mature markets.
Mello 2025 has just been launched and available to book your place...
Following on from our tenth anniversary show in Derby this year we are back in London and slightly later than our usual mid May conference to allow time for all the companies to get their December year end results done and dusted so free to talk openly with us all..
I am taking a relatively comfortable back seat for this one but the Mello team are thrilled to announce the launch of Mello 2025, which will be back for two days packed full of company presentations, keynote speakers, panel sessions such as the ever popular BASH and of course lots of networking with likeminded investors . Probably half the attendees are fellow subscribers from these Stockopedia boards...
Date: 3rd & 4th June 2025
Location: Clayton Hotel Chiswick 626 Chiswick High Road London, W4 5RY
Highlights of Mello 2025:
Keynote Speakers: Hear from industry leaders and learn from the best in the investing world such as Lord Lee, Andy Brough, Vin Murria, Gervais Williams and many more
Panel Sessions: Gain insights and learn about different investment strategies or approaches.
Networking: Connect with like-minded individuals and other excellent investors.
Exhibitions: explore the different investment opportunities in our exhibitor area and meet management face to face.
Register Now: https://melloevents.com/mello2025/
Discount Code: use code Stocko50 for 50% off tickets
Stay tuned for more updates and exciting announcements. We can't wait to see you at Mello 2025!
#Mello2025
David
Foxtons (LON:FOXT) Staff Faced Groping and Slurs at London Property Broker
" In her two years at Foxtons Group Plc, one of London’s biggest estate agencies, Lucy said her managers and co-workers groped her, sent her explicit messages, discussed her weight in work WhatsApp chats and told her to start an account on OnlyFans, a streaming service used by sex workers. Her story is not unique."
https://www.bloomberg.com/news...
Given the relatively small size of foxtons (market cap) and number of stores this could impact them?
When a similar thing happened at McDonald’s a number of employees came forward to confirm similar things happened to them.
CMO Group (CMO) delisting another scandal
https://x.com/Spread_Bet/statu...
could it be worth a speculative punt at those levels? Unlike some others only 65.90% is held by institutions - how much do they need to get a delisting thru? It might be difficult for them unless they buy more shares in the open market? The stock understandably crashed on the announcement - now its just worth 609k. The business here is real - https://www.cmogroup.com/ internet ventures that should have a future. How feasible would it be to keep holding the stock after de-listing? Surely such a business will be worth more than 609k!??
Many results in my portfolio today. Computer says "No"would be the best way of describing it.
The SCVR summarises things nicely, so there's nothing I can really add by the way of commentary.
CVSG HLN HWDN MACF all taking a bit of a spanking to various degrees. The general impression seems to be one of all round weakness. I'm not exactly feeling any plan for growth to be feeding through.
SRP is the only bright spot.
As the saying goes, sometimes one's purpose in life is to be a lesson to others.
Hi Graham any chance of a look at Jupiter Fund Management (LON:JUP) do you still see any value here or does the death by a thousand cuts continue ?
Yes I'm looking at it, Phoenix!
Thanks Graham appreciate your efforts.
Time Finance (LON:TIME) down 20% in last month on no news I have seen. Anyone see a reason for the drop?
Time Finance (LON:TIME) The brokers forecasts for net profit, have been reduced considerably, for the next 2 years.
Hello Rusty2, wondering if you could point me to where you seen this? Stockopedia doesn't look to have picked this up, and the last report from Cavendish (28/01/25) sounded positive.
It is on the Stockreport, was £7.2m for this year, now only £5.6m.
Thanks Rusty2, I see that now. However I double checked the Cavendish notes from 25th Sept and 28th Jan and they increased Net Profit from £5.4M to £5.6M for 2025. 2026 remained at £6.2M. Not sure where Stocko got the numbers from as it looks like only Cavendish cover TIME.
Time Finance (LON:TIME)
Hi Rusty, I'm looking at Cavendish's latest report. Also viewed Sept '24's report - I see the £7.2mn and £5.6mn - they are as listed in the current year - but it does not seem to be a downgrade.
Simon Thompson's restates in Nov '24 article " the directors expect to deliver at least 22 per cent growth in pre-tax profit to £7.2mn (upgrade from £6.9mn) on 6 per cent higher revenue of £35.1mn in the 12 months to 31 May 2025. On this basis, expect earnings per share (EPS) of 5.9p."
TIME have just updated and guidance has been INCREASED
This positive momentum year-to-date includes record revenues, fifteen consecutive quarters of lending book growth, and arrears remaining well controlled. As a result, the Board is confident that Group performance for FY25 will be ahead of current market expectations1 which were previously raised in November 2024. Following continued strong performance, Revenue and Profit Before Tax for FY25 are now expected to not be less than £36.0m and £7.5m respectively.
Hello David and other readers. I have this moment put down the phone to the Finance Director, James Roberts. He confirms the new RNS and its contents. He has no knowledge where the misinformation has come from and he appreciated my getting in touch. Cavendish and only Cavendish are the official broker and provide the best information as a rule. In this case the latest RNS is the best information. TIME to buy more!!!!
Wow now that's what I call service haha!! Time Finance (LON:TIME)
If only all my idle enquiries resulted in a same-day RNS followed by a phone call to the Finance Director for clarification!!
Time Finance (LON:TIME) could be incorrect figures on Stockopedia. I don't know why the shares went down over 10% today, tempting to top up.
I'm not seeing any reason either. There is a lot of volume being traded so it could be one of the bigger investors selling down. That is pure speculation. I would be tempted to top up if ££ allowed!
Time Finance (LON:TIME) Hi Rusty where did you see that? I don;t see it on the Stocko page:
Hi Dave, It is on the net profit forecasts. It seems the previous forecasts were incorrectly stated on here.
Stocko defines Net Profit as:
"... the profit reported net of all taxes, interest and expenses. Often referred to as the 'bottom line' and used to calculate per share earnings"
If that is the case, the stocko data table for Analyst Forecasts can't be correct as it shows a reduction in net profit and an increase in eps. If net profit goes down (and net profit is the figure used to calculate eps) then eps should go down in proportion, unless the shares in issue has changed... or perhaps I have misunderstood the table.
Time Finance (LON:TIME)
Time Finance (LON:TIME) it seems the figures are correct now but were not before. Where did their data provider get £7.2m net profit from?
Seems £7.2m is profit before tax not the net profit.
In the Cavendish table that Dojosan posted the 7.2 is PBT(reported). It looks as though somebody mixed up pbt and earnings.
Cracking effort with all these results guys, bravo!
Anyone have any idea about why Warpaint London (LON:W7L) continues to get pummeled?
Tariffs?
Unreliable, evasive Board with a lack of candor and integrity ?
interesting positive candle on the chart today. High volume, new low (for this downwave) with long tail but closed near the high !
Hi
Rolls-Royce Holdings (LON:RR.) up +17% as I type.
Extract from some headlines ....
British engine-maker Rolls-Royce RR.L forecast more growth and lifted its mid-term targets after it beat guidance for 2024, posting a 55% rise in annual profit as widebody jets flew more and its cost-saving plan delivered.
The group also announced a dividend of 6 pence per share for 2024, having flagged last August that it would reinstate the payout after a five year break sparked by the pandemic, and said it would start a 1 billion pound ($1.27 billion) share buyback.
(I hold)
Regards
Howard
Hi Howard,
Some really outstanding results from Rolls-Royce Holdings (LON:RR.) this morning. I was expecting the company to hit the top ends of the guidance ranges, but they've blown straight past these.
The upgrade to medium-term guidance figures and confirmation of the rumoured buyback are what impressed me most.
I covered the company in the latest Week Ahead article if you wish to read more on how the company performed compared to market expectations.
https://www.stockopedia.com/co...
Best,
Keelan
Hi Keelan
Yes I read your article a few days ago, good piece, thanks.
Regards
Howard
Water Intelligence (LON:WATR) announces a solid trading update new strategic partnership (plus continued progress of long term strategies like ) and with steady but progressive results - just look at last 5 years profit progress!
Very much a slow burn, runaway success and with a big tailwind from climate change behind it. (Even Trump will not be able to deny drought/water scarcity even if he can deny the causes)
Overwhelmingly still a US business - despite international now growing rapidly, - Water Intelligence (LON:WATR) is listed on AIM as a quirk of its history. It announced it is looking at dual listing to better attract US investors.
Stocko Hive mid - What are the likely implications of that.? To my mind it should help the share price considerably (unless the wider US stock market tanks)
I had a look at this one when it was at it's low point in 2024 but didn't take any action, as I thought what it did was relatively straight forward and others could break into this space relatively easily. Looks like I may have been wrong to make this assumption and it has done better than some of the other shares I picked instead. Well done for picking this one up.
Here you go Zip. Yesterday's live interview with the company
&t=9sThanks for sharing Paul this was very interesting and the team you interviewed seem very capable. Considering aging infrastructure and damage from more frequent storms the potential for growth does seem to be real and their presence in the US is large plus, their franchise approach helps to limit their exposure to expenses. I'm going to do some more research into this one.
Aviva (LON:AV.) ahead of expectations as well.
Sparkling results from Cairn Homes (LON:CRN) with operating profit increased by 30%.
Edit.
Cairn Homes (LON:CRN) 2024 actual sales up 29%, and a "another strong 2025" is forecast. Cairn guidance is modest @ >10% sales, but highly likely to be >15-20%, which makes the PEG look attractive.
I hold
and still the shares fall. There hasn't even been a significant rise recently so why they are falling today I have no idea?
Could it be the modest Cairn Homes (LON:CRN) forecast?
Is it a small miss on forecast EPS? I think this is one of the safest housing companies out there and am considering getting in on the dip.
What an impressive list!
I hold 7 directly and looking forward to comments . In some cases I have made transactions after reading the community expert views.
Greatly appreciated.
Jupiter Fund Management (LON:JUP). The word "resilient" appears twice early one, putting us in the brace position. AUM well down and dividend cut significantly, which will probably cause a minor stampede for the exit today?
Thanks for the comment managed to cash out first thing for 82p
RE: Jupiter Fund Management (LON:JUP)
Actually looks like a beat against forecasts.
Horrible company in a terrible sector, but very cheap. I hold a few.
timarr