Daily Stock Market Report (Thur 27th August 2026) - HFD, MACF, VTU, JSE

Nvidia’s shares have risen 4.7% after hours after beating expectations at its latest quarterly results.
- Q2 revenues rose 18% quarter-on-quarter and 106% year-on-year, to $96.2 billion (consensus: $92.05bn).
- Adjusted (“non-GAAP”) earnings per share were $2.22 (consensus: $2.06).
These results had been previewed here by Dr. James Fox in The Week Ahead.
Founder-CEO Jensen Huang (emphasis added):
AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue. And demand is accelerating. This time last year, one lab alone was driving the buildout; today, we have a golden age of new AI labs and startups, multiple frontier labs scaling in parallel, a thriving open-model ecosystem and physical AI coming online — with strong momentum across the U.S. and around the world. The AI infrastructure buildout is at full steam.
The profit margins achieved by Nvidia are remarkable: 75% gross margins and just $8 billion of operating expenses. The adjusted after-tax net profit margin is 56%.
The result of its incredible growth and profitability is that Nvidia appears to have potentially grown into its valuation, now trading at a forward P/E multiple of less than 20x despite a market cap of $5 trillion:
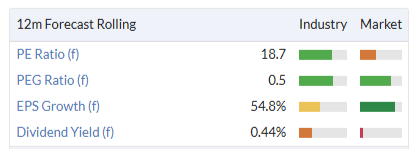
See how the P/E ratio has compressed:
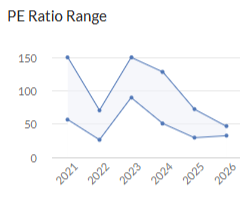
The sustainability of AI-fuelled demand is one of the hottest topics in finance right now. For the time being at least, there is no doubt that it continues to prevail.
Overnight market movements:
The FTSE is down 0.4% at 10,845
S&P 500 is up 0.3% at 7,700
Brent crude (November) is down 0.9% at $86.20/bbl
Gold is up 0.3% at $4,605/oz
Bitcoin is up 0.5% at $78,850
The Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£190bn | SR56) | Positive Phase III results for AstraZeneca and Amgen’s Tezspire treating eosinophilic esophagitis. | ||
Prudential (LON:PRU) (£26bn | SR35) | New business up 8%. H1 adjusted operating profit up 9% to $1,812m. “We remain firmly focused on the delivery of our FY26 guidance of double-digit growth in new business profit, Gross OFSG (“operating free surplus generation”) and Adjusted EPS, together with double-digit dividend per share growth, and on achieving our 2027 financial objectives." | ||
South32 (LON:S32) (£12.2bn | SR61) | Revenue from continuing operations +1% ($5,816m). Profit after tax +410% to $1,087m. "Looking ahead, the outlook for our business is positive as we focus on safe and stable operations and growing our production of base metals into structurally attractive markets.” | ||
Greatland Resources (LON:GGP) (£4.69bn | SR77) | Sales revenue +136% ($2,259m). Net profit after tax +156% ($862m). “As previously announced, gold production guidance for FY27 is 260 - 300koz at an AISC range of $2,900 - $3,330/oz gold produced.” | ||
PPHE Hotel (LON:PPH) (£687m | SR23) | Revenue +4.7%. Adjusted EPRA earnings per share of 125p for the last 12 months, unchanged vs. prior 12 months. “Revenue and EBITDA performance in H1 has been encouraging and the Group continues to trade in line with consensus expectations for FY26.” | ||
Rockhopper Exploration (LON:RKH) (£631m | SR-) | Placing to raise $180m at 70p alongside open offer to raise up to $20m. (Share price prior to suspension: 73.2p.) “This proposed Capital Raising ensures Rockhopper can participate in the acquisition of its pro-rata share of the OSX-1 and associated work in preparation for the consequential accelerated development of the central development area.” | Suspended from trading. | |
Halfords (LON:HFD) (£528m | SR99) | SP +10% FY27 underlying profit before tax to be between £55m and £65m, ahead of current consensus of £52.6m (with a range of £48.9m to £55.1m). Heightened seasonal demand with unusually warm summer weather. FY27 will be “further weighted towards the first half of the year as we accelerate investment in technology and marketing in the second half.” | GREEN ↑ (Graham) I am going to put this on GREEN today, with a note for myself and future writers that I’m doing this primarily because of the positive momentum the business and the stock are experiencing. If they don’t pull another rabbit out of the hat in the next six months with another upgrade, I’ll be inclined to take us back to AMBER/GREEN. | |
Guardian Metal Resources (LON:GMET) (£389m | SR11) | The TRS supports the results of the Company's Pre-Feasibility Study announced on 30 June 2026. | ||
Tharisa (LON:THS) (£370m | SR96) | Thariso’s Karo Platinum has signed a purchase of concentrate binding term sheet with a subsidiary of Valterra Platinum for the offtake of platinum group metals and base metal concentrate from the Karo Platinum Project in Zimbabwe. Tharisa owns 79% of KMH which in turn owns 85% of Karo Platinum. | ||
Empire Metals (LON:EEE) (£330m | SR21) | Pre-revenues. Loss before tax £1.9m. Conducted the largest drilling programme to date at the Pitfield titanium Project. Cash position £12.4m. “The first half of 2026 has been transformational for Empire, representing a period of significant progress for the Pitfield Project.” | ||
Galantas Gold (LON:GAL) (£271m | SR25) | Pre-revenues. Net loss over six months of $7m. $108.9m of cash and cash equivalents. On August 12, 2026, the Company announced the selection of contractors for the Andacollo Gold Project with M3 selected to lead the Preliminary Economic Assessment and the crushing plant relocation program from Mexico to site. The PEA is targeting completion for Q4 2026. | ||
Vertu Motors (LON:VTU) (£267m | SR97) | 5m to 31 July: LFL Revenue +4.6%. Anticipates net debt to be in the range of £74.0m to £77.0m at the end of August, excl. Leases. Anticipates that full year results for FY27 will be ahead of current market expectations (PBT consensus £25.5m). | AMBER = (Mark) In isolation, I don’t see how a company making a huge downgrade and then following it up with a couple of smaller upgrades should suddenly make us more positive on the prospects, particularly as the net impact is to make the shares trade at a multiple far higher than it has in the recent past, hence I keep our neutral view. I do get the rationale that there may be a takeover, given the stakes held by multiple parties. However, it doesn’t make sense to hold purely for this possibility, especially at the current valuation, and with the known industry challenges of the Zero Emission Vehicle Mandate and shift to Chinese Brands in the mix. | |
Jadestone Energy (LON:JSE) (£174m | SR44) | H1 Production -25% to 15,282 boepd, impacted by unplanned downtime at the Stag field due to the impact of Cyclone Narelle and planned maintenance activities associated with the CWLH FPSO dry dock. H1 Revenue before hedging +13% to $261m, Adjusted EBITDAX +1% to US$101.6m. Net loss after tax $4.8 (25H1 $37.6m PAT). Net debt $25.7m. Guidance unchanged. | AMBER = (Mark - I hold) | |
KEFI Gold and Copper (LON:KEFI) (£165m | SR11) | Having launched the development of the Tulu Kapi Open Pit Mine and Processing Facility, it will now commence detailed planning for the development of its second mine, the Tulu Kapi Underground Mine. | ||
Pulsar Helium (LON:PLSR) (£160m | SR14) | 9m Net loss $9.4m (9m25: $8.5m net loss), cash balance not given. | ||
Sintana Energy (LON:SEI) (£119m | SR16) | 3m Net Loss $3.09m (3m25: $2.16m net loss). Net Cash $16.2m (31 Dec: $11.0m) after $9.89m raise in period. | ||
Macfarlane (LON:MACF) (£116m | SR79) | H1 Revenue +2% to £148.9m, Adj. PBT -9% to £7.24m, Adj. EPS -9% to 3.45p. Interim dividend held at 0.96p. Net bank debt £17.9m (31 December 2025: £16.2m). Trading is in line with market expectations for the full year to 31 December 2026. Additional £6m buyback starting in October. | AMBER ↑ (Mark) | |
Ten Lifestyle (LON:TENG) (£86.6m | SR76) | Won a multi-year contract with a new client, part of one of the world's most valuable companies to support launch of the client's new multi-category consumer concierge service, initially in the Americas. Expected to launch during H1 FY2027 and initially categorised as a Medium (£0.25m - £2.0m) contract, with opportunities to grow. | ||
Arrow Exploration (LON:AXL) (£75.8m | SR75) | Q2 Revenue +116% to $34.2m net of royalties. Adj EBITDA +300% to $25.1m, Net income $10.4m (25Q2 $0.9m loss). Net Cash $28.5m. | ||
Aminex (LON:AEX) (£50.3m | SR8) | Confirms that it is participating in ongoing discussions in Tanzania to progress the coordinated implementation of the Ruvuma Development. | ||
hVIVO (LON:HVO) (£44.1m | SR29) | Acquisition of a specialist Phase I/II clinical research unit with an established revenue base, multiple pharma relationships, a strong orderbook and proven track record with 350 studies completed to date for gross earnout of approximately €6 million in cash. Expected to be immediately earnings accretive and contribute positively to both revenue and EBITDA in FY26. | ||
System1 (LON:SYS1) (£42.5m | SR66) | Launch of Test Your Ad Screen, an AI screening tool providing rapid, directional predictions of an advertisement's commercial effectiveness. | ||
Blencowe Resources (LON:BRES) (£38.9m | SR10) | Two leading US graphite specialists are progressing a laboratory demonstration prototype designed to meet 4HN high-performance military battery specifications required by the US Defence Logistics Agency. Subject to successful completion of the prototype programme the parties plan to establish a US pilot production line to demonstrate future commercial prospects, targeting 100 lead-acid cells per month. | ||
Bezant Resources (LON:BZT) (£31.3m | SR25) | Accelerated payment schedule is for a payment of US$5M due by 31 Oct. Interest has been expressed by a third party for a co-investment in relation to the accelerated payment and arrangements are in the process of being finalised which would simplify financing and security arrangements. | ||
Predator Oil & Gas Holdings (LON:PRD) (£28.5m | SR10) | H1 gross oil production of 52,130 barrels was sold from the Icacos and Bonasse fields, generating £1.52m net revenue to Predator. Trinidad: civil engineering works for the Snowcap-3 well pad and production facilities are progressing on schedule. Morocco: civil engineering works for the MOU-6 well pad have now been completed. | ||
Cadence Minerals (LON:KDNC) (£24.8m | SR57) | As of 22 August 2026, refurbishment of the Azteca processing plant at the Amapá Iron Ore Project had reached 97% weighted physical completion, compared with 95% planned and 87% reported on 10 August 2026. | ||
Rome Resources (LON:RMR) (£22.3m | SR21) | Outcrop sampling has returned assays of up to 0.6% tin, 0.2% tungsten, 0.8% bismuth, 17ppm indium and 1.5% copper. | ||
NAHL (LON:NAH) (£16.2m | SR76) | Binding conditional agreement to sellnon-core Searches UK Limited to TM Group for £1.234m on a cash and debt-free basis. £1.122m received after cost will be used to pay down RCF. | ||
Bradda Head Lithium (LON:BHL) (£12.5m | SR30) | net loss $2.92m (FY25: net profit $1.1m. Cash 870k (FY25: $1.09m) prior to £2.41m gross raise post-period end. | ||
Alien Metals (LON:UFO) (£10.8m | SR26) | Diamond drilling results from Elizabeth Hill include 38.3m @ 878g/t Ag from 3.7m. |
Graham's Section
Halfords (LON:HFD)
Up 10% at 264p (£579m) - Trading Update - Graham - GREEN ↑
An excellent little trading update from Halfords, revealing that warm weather has given a big boost to H1 performance (important to note that H1 runs from April to September).
We now expect FY27 underlying profit before tax to be between £55m and £65m, ahead of current consensus of £52.6m (with a range of £48.9m to £55.1m).
£55-65m is still a wide range of possible outcomes, which makes sense as we aren't even halfway through the financial year yet, and this is fundamentally a low margin business.
At the midpoint of the new range, underlying PBT will be 14% higher than the previous consensus.
Their strong performance in recent months reflects that they “continue to deliver against our strategic priorities alongside a very strong performance in seasonal categories, in part reflecting unusually warm summer weather.”
In hindsight, it seems obvious that a series of heatwaves would get people outdoors and spike demand for cycling and camping equipment. The share price has been quite firm during the summer:
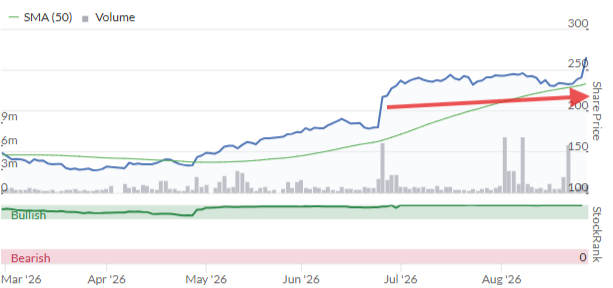
Halfords says that increased seasonal demand has boosted their profits “in the mid-single digit millions of pounds”. Or, as I like to say, by £4-6m. That’s enough to account for the majority of today’s profit upgrade.
H2 will be a very different story in terms of profitability, with no boost from summer weather and with Halfords planning to “accelerate investment in technology and marketing”.
Graham’s view
We maintained our moderately positive view on Halfords in June at a share price of 209p.
I’m a little reluctant to go fully GREEN on it today, seeing as today’s profit upgrade is mostly to do with the weather rather than anything more meaningful than that.
However, the stock doesn’t strike me as being obviously overvalued. Here are the value metrics as of last night:
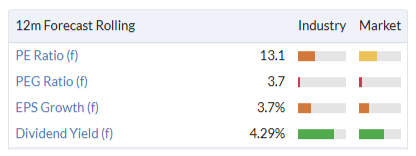
At a 25% assumed tax rate on new guidance, I again get a P/E of 13x this morning against the latest share price.
Stockopedia calls it a Super Stock with above-average value, although Quality and Momentum do score higher:
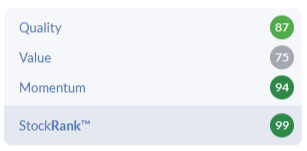
I am going to put this on GREEN today, with a note for myself and future writers that I’m doing this primarily because of the positive momentum the business and the stock are experiencing. If they don’t pull another rabbit out of the hat in the next six months with another upgrade, I’ll be inclined to take us back to AMBER/GREEN.
Mark's Section
Macfarlane (LON:MACF)
Flat at 74.4p (£116m) - Half-year Report - Mark - AMBER ↑
Background:
Macfarlane has earned plaudits for turning a relatively mature sector of packaging distribution into a growth area for investors by acquiring companies relatively cheaply in a fragmented field. This roll-up strategy, combined with the shift to online retail led to the share price rising almost six-fold in the decade to 2022:
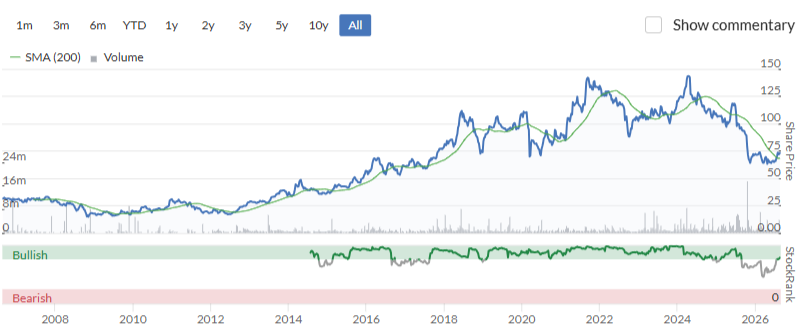
However, like many companies, in the short term, this strategy has not survived the combination of weaker UK economic conditions and a higher-inflationary environment.
Adjusted diluted earnings per share fell from a peak of 12.21p in FY23 to 11.56p in FY24 and then by a much more severe 34% to 7.62p in FY25.
Many investors have been expecting a recovery as inflationary pressures work their way through the supply chain and consumer confidence improves. However, those expectations have repeatedly been dashed on the rocks of reality over the last few years. Indeed, I bought into the company around the middle of last year as it appeared to be a relatively modestly priced high-quality business that has a history of compounding earnings at a reasonable rate (although mainly through acquisition) and was forecast to return to growth. However, a profit warning quickly slashed those forecasts, and I bailed as I considered the market under-reacted to the scale of the downturn.
This proved to be the right decision, as a further profit warning in October last year led to Roland reducing his view to AMBER/RED:
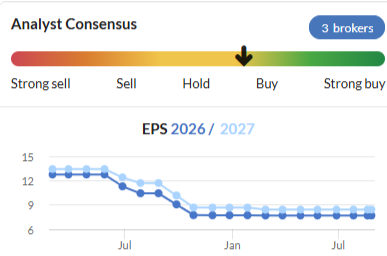
One of the factors that Roland highlighted was the impact of an employee fatality at the recently acquired Pitreavie, showing that acquisitions often come with risks as well as opportunities for highly acquisitive groups.
Since then, forecasts have not seen any further downgrade, and like many companies, the market has started to price in a potential recovery. These HY results come at a critical juncture to judge whether that recovery is underway.
Today’s results:
The headline numbers are not particularly encouraging. Revenue up 2% will be behind inflation, meaning volumes are likely to be down. Key profitability figures are down high single-digit percentages:
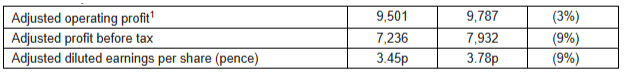
However, the company is keen to point out that Adj. Operating profit at their Packaging Distribution business was up 6.4%. In their Manufacturing Operations, they break out the impact of the Pitreavie. Without this, adjusted operating profit would only be down 1%.
It is hard to describe these as good results, but it does seem that the issues are largely restricted to one manufacturing operation.
Adjustments:
Macfarlane are known for playing with a relatively straight bat. For example, they didn’t try to hide recent warnings, but were up front about the impact.
Prior to 2022, the company didn’t present an adjusted PBT figure. It is tempting to think the shift to adjusted figures signalled where things were heading and to sell the shares. However, looking at the details, all of the adjustments were non-cash:
Adjustment type (£m) | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|
Adjusted PBT | 23.5 | 25.8 | 25.0 | 15.6 |
Amortisation of acquired intangibles | (3.6) | (4.0) | (4.6) | (5.2) |
Deferred/contingent consideration fair value adjustment | — | (1.5) | 0.5 | 1.2 |
Goodwill impairment | — | — | — | (1.6) |
IAS 19 pension past-service cost | — | — | — | (1.9) |
Statutory PBT | 19.9 | 20.3 | 20.9 | 8.1 |
The exclusion of amortisation of acquired intangibles for a highly acquisitive company is open to debate, but at least it is consistent with what most companies present.
In these results, the gap between statutory and adjusted seems higher than usual.
However, a quick check shows that the difference is almost entirely amortisation of £2.4m (where a similar adjustment on a lower unadjusted PBT figure has a larger proportional impact). Many companies would take an exceptional charge for the issues at Pitraevie. That they haven’t booked exceptionals underlines their staid reputation.
[It is worth noting that Stockopedia’s data provider appears to include amortisation in their normalised figures. This means that the historical normalised figures are lower than the company-quoted ones, but also any recovery won’t be as strong as it first appears, as forward broker numbers will be adjusted ones.]
Outlook & Forecasts:
Given the recent history of profit warnings, this is the key line:
Trading is in line with market expectations for the full year to 31 December 2026. Performance in H2 2026 will benefit from momentum in new business growth, control of operating expenses and build on the return to profitability at the Pitreavie business, while continuing to effectively manage the impact of events in the Middle East.
There is typically a small H2 weighting here, with the average H2 weighting from 2019–2025 coming in around 55%. However, this isn’t a given and has varied due to external factors. Still, if this is considered an “average” year, then the FY EPS would be 7.7p on a 55% H2-weighting. This is almost exactly broker consensus in the Stock Report.
Shore is the only coverage we can see, and they have 7.8p pencilled in for FY26, making the point that the ongoing buyback will improve EPS figures on the same PBT. Overall, I see this figure as being achievable.
Shore see EPS rising to 8.3p in FY27 and 9.0p in FY28.
Valuation:
At the current 74.5p to buy, the forward P/E is around 9.6x. This is reasonable but not particularly cheap given that the EPS forecasts for FY26 are essentially flat on FY25, which was in itself a poor year.
On top of this, there is £17.9m of net debt, up slightly from £16.2m at 31 December. This is not huge compared to a £116m market cap, but moves the needle slightly unfavourably if included in any valuation.
The company obviously feels that its shares remain undervalued as they continue with its share buyback, which is due to be extended:
At 30 June 2026 the Group had spent £3.1m of the £4m allocated to the share buyback programme launched in June 2025, buying back 3.8m shares, with the remaining £0.9m expected to be deployed by the end of September 2026.
The Group will allocate an additional £6m to share buybacks to commence in October 2026. At current market valuations and given management focus on the profit recovery programme, the Board believes this is an efficient use of capital. The Group intends to return to executing high-quality acquisitions as business performance improves.
I’m generally not a big fan of buybacks when they are partially funded by increasing net debt. While they reduce the share count, they also increase the risk to equity holders.
The company also started buying back shares at 116p, so I don't think they can be held up as a great judge of when their stock is cheap.
Looking further forward, if Shore’s figures are met, the P/E falls to 9.0x and then 8.3x. However, these would still put the company only on a PEG of around 1.0. At this stage, there has to be some doubt as to whether those forecasts are achievable.
Unless these EPS figures can be beaten, not just met, through organic recovery or further EPS enhancing acquisitions, the shares look fully valued on current forecasts.
Strategy:
It seems a bit strange to me that they want business performance to improve before making further acquisitions. Surely, the time to get a bargain is when competitors are under pressure. This suggests to me that they don’t see any immediate recovery in trading, perhaps making FY27 forecasts optimistic, or they see their balance sheet as under pressure.
As a distributor, they have always run with a low current ratio of around 1, and these results show a similar figure. However, I note the absolute amounts of inventories, trade payables and trade receivables have risen on largely flat revenue, suggesting there may be some working capital timing concerns and hence a lack of capacity for acquisitions. The say:
The Group is operating well within its bank facility of £40m which runs until November 2028 with an option to extend to November 2029.
However, even excluding normal working capital fluctuations, gross debt of £28m doesn’t leave much for acquisitions, especially if they spend £7m on share buybacks. However, this will be offset by any cash generation of the business.
Mark’s view
With no further profits warning, and FY26 figures looking achievable, I think it makes sense to be less negative than when we last reviewed the company. There is also a notable lack of the type of adjustments that other companies would have made, given the challenges they have faced. However, the shares look fully valued on current forecasts out to 2028, and it would seem that they need to start to beat expectations for us to consider a further improved stance.
One way they could achieve EPS growth ahead of forecasts is through acquisitions. However, their balance sheet looks to constrain that possibility at the moment. An ongoing share buyback may support the current share price. However, the company management haven't proved particularly good judges of when their own stock is cheap in the recent past, and this further constrains their ability to make acquisitions. AMBER.
Vertu Motors (LON:VTU)
Up 6% at 91.4p (£267m) - Trading Statement - Mark - AMBER =
A further positive update here this morning:
Given the trading trends and portfolio changes, the Board anticipates that full-year results for FY27 will be ahead of current market expectations.
At 91p, this has pushed the share price close to an all-time high.
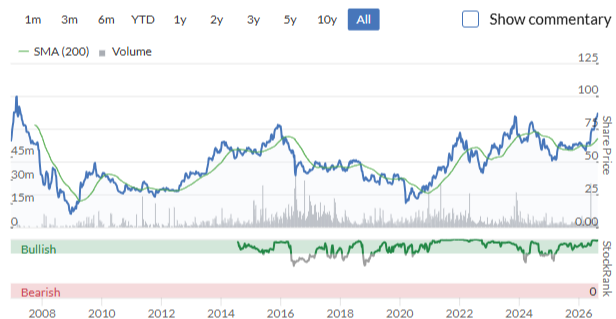
We have to go back almost 20 years to admission to see a higher share price.
They give us the current consensus:
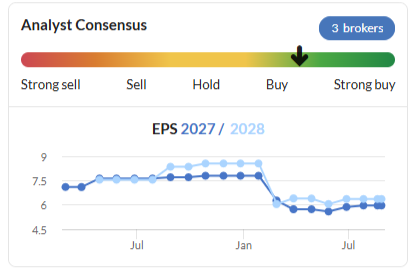
According to compiled data at 26 August 2026, the current consensus of three sell-side analysts' expectations for FY27 adjusted profit before tax is £25.5m with a range of £24.5m to £26.1m
The only coverage we can see is from Progressive, who say:
Having raised our forecasts in June after the AGM update, we are adjusting our forecasts to reflect this positive newsflow, raising adjusted PBT by £1m for FY27.
This takes them to £25.5m, in line with the consensus, and shows this is a minor upgrade. What stands out, though, is that despite recent upgrades, 2027 forecasts are only just above FY26 actuals and FY28 is forecast to be flat:
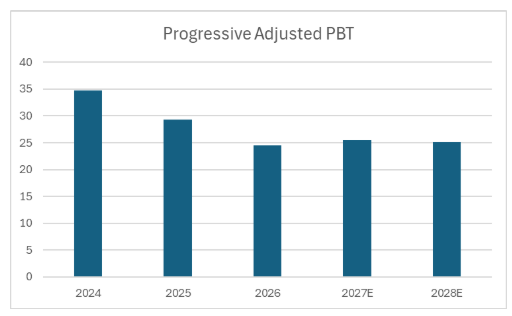
Given broker consensus was given a huge downgrade earlier this year, this appears to be a case of making a huge cut followed by subsequent write-backs fooling the market (or at least the bots and momentum traders!)
The net impact is that shares are more expensive on earnings multiples than they have been since a very weak COVID-impacted FY21:
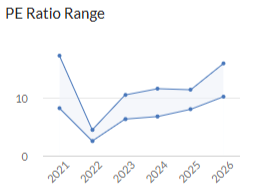
However, I think another factor is at play here.
Takeover speculation:
The industry has seen a huge amount of consolidation over the last few years. All other listed dealerships were bought out, leaving Vertu as the last man standing. Despite some strategic holdings, no offer for Vertu was forthcoming. With the companies that were acquired proving to be perhaps less lucrative than expected to the acquirers, the chance of any deal seemed to be slipping.
However, a recent change in the share register appears to have kickstarted the speculation:
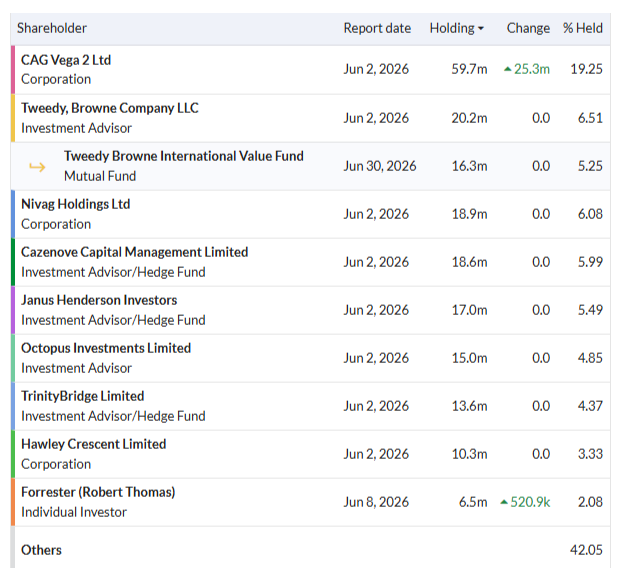
CAG Vega 2 is Constellation Motors, which bought BCA Car Auctions and Marshal Motor Holdings. It is owned by TDR Capital, a UK private equity firm. They increased their stake by buying Shroders’ stake at 86p, when the share price was around 64p. The market has clearly taken this as a sign that they will be interested in the rest.
I may yet be proven wrong, but my understanding is that Constellation is more likely to have purchased these shares as a blocking stake rather than an outright interest in acquiring Vertu, at least in the short term. This view is backed up by others. For example, when Constellation took their initial stake, David Kendrick of Cooper Parry said he didn’t believe that it was a move by Constellation to take over Vertu in the longer term, and instead framed the stake-building as opportunistic buying, meaning Constellation's stake could be about positioning itself as a gatekeeper in that scenario, not being the acquirer.
A more likely acquirer, in my opinion, is Nivag Holdings, owned by Gavin Hydes, CEO and (at least in May 2021 a 90% owner) of Joe Duffy Motors Group / JDM Automotive. Nivag being Gavin backwards, of course. However, if Hydes/Duffy have been outbid for Shroders’ stake, this suggests any offer may not meet shareholders' (including Constellation’s) current expectations and would be a non-starter.
The rationale for an offer is that an acquirer can strip out the property and have an operating company for very little:
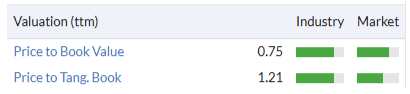
Indeed, many of the acquired companies over the last few years didn’t have such large freehold property assets.
The problem is that the company is currently benefiting from the rent-free aspect of owning freehold property. If they had to pay a market rent on similar assets, the company would be significantly less profitable, reducing the value of the OpCo to any acquirer.
Capital allocation:
The company continues to buy back shares. However, this looks to have been slowed by the requirement to limit the premium to VWAP paid and the rising share price:
The Group continues to repurchase its own shares as part of its Share Buyback programme. 2.4m shares have been purchased in the financial year to date for £1.7m. This represents 0.8% of the opening share capital. To date, 21.9% of the share capital of the Group has been repurchased since the commencement of the programme in 2018. £10.3m remains of the £12m buyback announced on 5 March 2026.
Net debt at FY26 year-end was £61.3m, so with net debt guided to “be in the range of £74.0m to £77.0m at the end of August”, this means this is another largely debt-funded buyback. This may make sense if the company is trying to ensure it doesn’t get taken over. However, it is hard to argue they're getting a bargain when the purchases are close to the current price.
Mark’s view
Roland kept our AMBER view following the last small upgrade, and I am going to take the same stance. In isolation, I don’t see how a company making a huge downgrade and then following it up with a couple of smaller upgrades should suddenly make us more positive on the prospects, particularly as the net impact is to make the shares trade at a multiple far higher than it has in the recent past.
I do get the rationale that there may be a takeover, given the stakes held by multiple parties. However, it doesn’t make sense to hold purely for this possibility, especially at the current valuation, and with the known industry challenges of the Zero Emission Vehicle Mandate and shift to Chinese Brands in the mix.
Jadestone Energy (LON:JSE)
Flat at 32p (£m) - 2026 Half Year Results - Mark (I hold) - AMBER =
[At the time of writing I hold a LONG position in this company.]
The headlines here reveal a tricky period for the company:
…our performance in the first half was affected by two key external events, a delayed production restart at CWLH following the dry dock maintenance campaign, and the impact of Cyclone Narelle on our operated Stag field. These events, combined with the sale of our Thailand assets in April 2025, represent the bulk of the period-on-period production decline in the first half. We now have defined plans in place to reinstate production at both CWLH and Stag.
This led to declining production (15,282 boepd vs 20,368 boepd for 25H1) and revenue only held up due to higher oil prices:
Revenue before hedging increased 13% to US$261.1 million (H1 2025: US$231.0 million)
With the combined impact being a loss:
H1 2026 loss after tax of US$4.8 million (H1 2025: profit after tax of US$37.6 million), primarily driven by higher production costs period-on-period, of which ~40% is explained by non-cash inventory charges, offsetting a small increase in revenue.
And driving them to a net debt position:
Net debt at 30 June 2026 of US$25.7 million reflected cash balances of US$174.3 million of cash (incl. restricted cash) and debt of US$200.0 million.
Although it will take time to fully recover from the issues they’ve faced, the FY outlook is maintained:
All guidance metrics unchanged from July 2026 trading statement:
Production 16,000-18,000 boepd.
Operating costs of US$260-300 million.
Capital expenditure of US$50-80 million.
2025-2027 free cash flow (pre-debt servicing) of US$200-240 million.
That last figure is particularly important as it is calculated at dated Brent of $70/bbl. The oil price has been volatile in response to geopolitical events. Even so, it remains significantly above this benchmark price, and free cash flow is probably $100m higher than this figure if the oil price remains at current levels. With previous hedges rolling off in H2, few companies are as geared to short term oil price. It is this reason why I hold shares in this company, as it acts a bit like a cheap option on the oil price.
Mark’s view
With recent issues with storm damage and maintenance now looking like they are in the rear view mirror, the company should have a materially improved H2, especially if the oil prices remain anywhere close to the current levels. However, there is no doubt that having downtime in a period of exceptionally high oil prices is frustrating.
At current prices, their existing production assets are highly cash-generative. A recent infill campaign adds to production, and they are making plans to develop a new field in Vietnam. Any farm out here, if it happens should concentrate minds on the underlying valuation of their non-producing assets.
However, I’d really want to see some evidence of these positive developments, and the recovery from recent issues, in the numbers before considering an updated view. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Regarding Vertu Motors (LON:VTU) and the comment:
with the known industry challenges of the Zero Emission Vehicle Mandate and shift to Chinese Brands in the mix.
Vertu are themselves getting involved with Chinese Brands (Omoda & Jaecoo), so it seems they can see which way the wind is blowing.
Many thanks to sharw and TheArb for your helpful comments on Bloomsbury Publishing (LON:BMY) following my earlier post today. I will certainly follow up on the suggestions made by TheArb.
I held shares in Macfarlane (LON:MACF), but sold after the fatality announcement. Not because of the impact on the company finances, but because the horrific incident occurred on the 7 October and the first company announcement to shareholders regarding the loss of life was on 22 October as a trading update. Definitely in the "could have done better" category ... and performance is likewise. I no longer follow the company, but it is possible the investigation (and possible fine) is still outstanding.
If any of you do not already have your tickets...
There is a Bank Holiday Weekend offer with 25% off ticket prices for one or both days of MelloLondon
Just apply the code ML26Aug25 and it will reduce https://www.melloevents.com/mellolondon2026
CCC
This IT company issued an Ahead statement on 9 July and the shares rose 6% to £44. Ahead statement is one of Ed. Croft favourite topics where the shares continue to rise for a year or so after the statement. Although he stressed this applies mainly to companies valued at 50-350m range ,but it seems it may well applies to multi billion companies.
CCC shares are up another 5% today at £55
CCC became my first ever double bagger today. Only been subscribed to stock for 11 months. A good feeling.
Somero Enterprises (LON:SOM)
Price 238.62p
Market cap £123.6m
Doubled their buyback programme to US$12.0 million following stronger than expected first half trading results.
Repurchases under this expanded buyback programme are expected to begin after the publication of the company's interim results on 8 September 2026. All shares bought back will be cancelled.
One of the biggest shareholders has recently been involved in takeover bids.
EV/FCF around 12%!
Should see much higher prices before year end and into 2027.
I hold.
All the best
yiannos: did you see https://www.stockopedia.com/a/...https://www.stockopedia.com/a/...that covered Somero Enterprises (LON:SOM) ? I'd be interested to read your views on Mark's opinion.
Experience has taught me to remain confident in my investment selections and ignore outside opinions, especially from people that I have never viewed their own portfolio and performance over the years.
I extensively research and build high-conviction positions in a concentrated portfolio of 12 to 15 stocks at any time.
I get the impression that many here hold 200 stocks-:)
All the best
That’s fair, thanks. Are you willing to share any of your convictions about the UK shares you hold?
I do share from time to time my UK holdings.
I always make sure to explain the logic behind my investment, backed by future numbers (estimates) and not on any pure speculation.
All the best
NVIDIA (NSQ:NVDA)
I was bullish for the last 2-3 years but it is crystal clear now that they are simply offloading their CAPEX to their clients and to the corrupt Wall Street banking system.
NVIDIA (NSQ:NVDA) profit margins are not real as they are using this light capital business model offloading it to companies like CoreWeave (NSQ:CRWV) that will go bust at the end of the day.
I prefer to hold Alphabet (NSQ:GOOGL) for my clients.
I have slowly started shifting funds back to the UK market.
All the best
"I have slowly started shifting funds back to the uk market" - this is very interesting to hear. I would say to some extent it is not surprising as the UK is so bombed-out but it is great to hear it from you!
I am a long term holder of Bloomsbury Publishing (LON:BMY). I have noticed recently that the market makers mark up the share by say 32p to 679p at the opening bell, to catch a few buyers at this price, and then drop the buy price back to 647 and the spread to 2p.
This is happening on a regular basis. Can anyone explain the reasoning behind this action.
Regarding the quote for Bloomsbury Publishing (LON:BMY) I see what you mean:
However, you have to remember that BMY is now in the FTSE250 index and it is the order book that will dominate. The RSPs (Retail Service Providers) try to follow that book.
If you look at the trades the interesting thing is that the first AT trade yesterday was at 09 45 and today at 09 46 and that was when the price started to change. However, the initial high price looks reasonable in relation to the auction with UT 679p on both days.
I wouldn't read too much into it, BMY trades on an order, so you need to look at volumes as well as the price, only around 100 shares uncrossed at 679p in the opening auction today, and the same yesterday. It's meaningless. If you want to participate in these trades you'll need a provider who provides Direct Market Access. For further info do an internet search on RSPs, order book and LSE auctions.
Thank you for your comprehensive work on Macfarlane Mark, our money could probably be put to better use elsewhere but the Pitreavie fatality really hit them hard and I'm minded to hold for that elusive recovery. The £5 million surplus in the pension fund should help when that is sold, if I've understood that correctly.
Central Asia Metals (LON:CAML)
Having watched the presentation not entirely surprised that the share price has come back. The usual curate's egg from CAML. Clear they took their eye off the ball at Sasa and it seems now more closely monitored. There is a significant increase in cap ex here for 2026 which would eat into cash flow if the copper price does not continue to be elevated, unclear if this could affect the dividend pay out ratio
2nd They took out hedging contracts on Zinc etc which did not prove a success so a write off resulted. Unclear who is at fault here if one wants to be critical
3rd Silver price rise does them no favours as there is a contract based on Sasa output. May have made more sense to have hedged that rather than Zinc
the last 2 raise questions on Management ( the CFO still speaks like the Investment Analyst she was in a former life-IMHO)
The good bits
Well if Copper continues to be elevated cash the dividend at current rate should be fine. The Cygnus acquisiton seems on track and it looks good so potentially replacing the ageing Kounoud
Aberdeen Minerals remains promising as do the potential in Kaz for further copper minining given drilling is under way but these are potential rather than fact. Obviously copper would likely be commerical at this price given the company seems positive about the extent of deposits
My summary is
The itch about the quality of the management has not gone away and especially that Cygnus obviously going to be a major undertaking for them to bring to fruition
This is now more of a mining development business then collecting the dividend from waste copper deposits and paying shareholders. That said it is quite lowly rated so there is scope here At best a HOLD from me but the next 12 months is certainly going to be an interesting ride
I hope you send this to their investor team. Not least as I am a new holder!
I thought that same thing after their last investor meetings, I just got bad vibes from the way the CEO talked, which I know is opinion. If it wasn't for the copper price increase this year, would they be improving?
A special thanks to Yiannos for highlighting European Green Transition (LON:EGT) . Closed out this morning for a very quick 35% profit!
European Green Transition (LON:EGT) Agreed. Thank you Yiannos. Not pulled the trigger yet. It’s in my virtual portfolio!
Much appreciated.
More on the way!
Diversify and you will all do very well with them.
All the best
I will stick to what I can understand and where I think that I might have an edge and have some ability to value companies and their earnings. For me that is UK small and mid caps. It may mean that I miss out on American technology behemoths, but I am comfortable with that.
Back to basics. I have a full size holding in Halfords (LON:HFD) that I started buying around 145p shortly after Henry Birch became CEO and have added since, having kicked the tyres ( to quote Peter Lynch) at a few stores and seeing customers waiting to have various purchases fitted to their cars.
I would also throw in the fact that the Tour de France Grand Depart, men and women’s races comes to the UK next summer. Halfords (LON:HFD) is by far the largest bicycle retailer in the UK and it is difficult not to see it benefit from the ensuing publicity. Also it has a progressively growing data base of customer data through it motoring club.
I therefore think that there is more to come. The obvious negative is that operating margins are relatively low. However given that the company has had to contend with the significant increase in NI it has done very well.
Just my thoughts but I am biased.
Views of Graham and the team would be appreciated
Halfords has the Mr Rebel momentum atm, Graham highlights the need for further delivery. As a holder a lov em both!
Good morning Graham and Mark. We hold Macfarlane which you gave Amber Red on their FY Mark 26/2/26. It still looks too soon to add for recovery as you said then, the held dividend is some comfort though, plus an added buy back of shares and FY expectations held. I'd appreciated any comment if you have time today.
Halfords (LON:HFD) profit guidance up roughly 20%. Attributed mostly to hot summer but it's not just that....
They say the one off nature is high single digits, so I call that £7m, strip that out and this is still a great YOY performance
Halfords (LON:HFD) I find that our local Halfords seems like it’s closing down however….when you can’t find what you need the staff are happy to help and engaged. What you searched for in store is found and other suggestions provided. I have two cars which I constantly have tasks to carry out and keep going back to their good service. I was very doubtful about Halfords customer service but my recent experience apart from an aborted MOT test has been positive.
Hi
Two other upbeat results in addition to NVIDIA (NSQ:NVDA) are Salesforce,. (NYQ:CRM) up over +12% in after hours, and Crowdstrike Holdings (NSQ:CRWD) up over +10% in after hours. (I hold the three).
Regards
Howard
And US is overvalued, apparently...
Hi Howard, I own both CrowdStrike and Salesforce as well as Nvidia. To me, Salesforce is the most interesting of the three because this stock was absolutely hammered on fears that AI was going to kill the business . However, last night's earnings show that AI is driving real growth for the business now:
Hi Edward
Thanks for the comment ref Salesforce,. (NYQ:CRM) .
I agree with your comment ...'last night's earnings show that AI is driving real growth for the business now:'
I am seeing this emerge through my close following (I hold) of Palantir Technologies. (NSQ:PLTR). NVIDIA (NSQ:NVDA) is also stating their observations that AI is indeed driving growth in businesses.
For concrete examples you can watch Palantir's AIPCon conferences (see their YouTube channel for multiple conferences and vids).
In each AIPCon clients (from all sorts of sectors) showcase multiple use cases of Palantir's platforms.
In particular how Palantir's Ontology helps the clients to not only use multiple LLM's (both open and closed source), but very importunately implement their uses of AI within their organisations such that their complete use cases, data, prompts, etc are sovereign to themselves i.e. protected from Anthropic or OpenAI or others gaining direct access to their unique intellectual property.
If you were interested to see more details about this important development (Sovereign AI) of the AI story take a look on Palantir's YouTube channel, specifically in the Playlist section, the set of Palantir Sovereign vids. Link here .... https://www.youtube.com/playli...
Regards
Howard
Hi Howard, thanks for this – I am also in PLTR! On last quarter's earnings call they definitely highlighted the sovereign AI story – it was very interesting.
Hi Edward
Good for you. I don't think there are many of us on Stocko :)
Regards
Howard