Daily Stock Market Report (Thur 2nd April 2026) - SATS, BPM, TRCS, DUKE, SDY, JDG, SFR

Good morning! This is the final report until Tuesday 7th.
In the latest overnight moves, Brent Crude is up over $6 at $107, due to some aggressive rhetoric from Trump on Iran ("over the next two to three weeks, we’re going to bring them back to the stone ages where they belong.”).
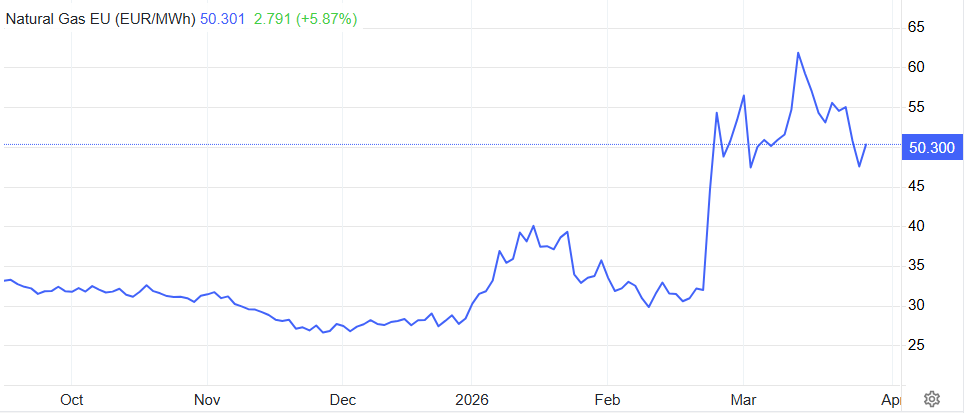
EU natural gas prices are spiking 8% higher as a result, but are still some distance off the highs reached in March:
As for stocks, the FTSE is set to open lower by less than 1%, giving back yesterday's gains at 10,270, while other indices are faring worse: the German DAX is lower by nearly 2%, and the S&P is lower by 1.4%.
We are done, enjoy the break!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£233bn | SR71) | “…statistically significant and clinically meaningful improvement in the primary endpoint of progression-free survival…for patients with unresectable hepatocellular carcinoma eligible for embolisation.” | ||
Lloyds Banking (LON:LLOY) (£57.3bn | SR73) | Does not believe any change to the provision for this issue is required. | ||
Atalaya Mining Copper SA (LON:ATYM) (£1.15bn | SR94) | Has acquired 4,500,000 shares of Lara Exploration Ltd. for C$13.5m. | ||
Rockhopper Exploration (LON:RKH) (£668m | SR30) | An updated independent technical report on the Sea Lion field shows that overall gross resource volumes are consistent with the Company's previous independent resource evaluation. | ||
Halo Minerals (LON:HALO) (£443m | SR N/A) | Has contracted specialised environmental consultancy firm MSTECK SpA. They will conduct a comprehensive bio-accessibility and human health risk assessment study at Halo's Playa Verde Project site in Chañaral, Chile. | ||
McBride (LON:MCB) (£237m | SR85) | Has made a binding offer for the acquisition of Eurotab, for EUR 40 million. Eurotab is a “specialist in the design and manufacture of solid-format cleaning and hygiene solutions, primarily serving private label and certain contract manufacturing markets”. Trading update: elevated input costs in April, has informed all customers about temporary price adjustments, or surcharges to current pricing. | ||
B.P. Marsh & Partners (LON:BPM) (£236m | SR87) | Has acquired an additional 2% equity stake in Pantheon, based on an equity valuation of £275m. Shares purchased from the company’s founders. | GREEN = (Graham - I hold)) [no section below] The major downside of this investment is that it maintains BPM’s fairly limited portfolio diversification. That is a major negative, but I’ve never expected BPM to behave like a mutual fund. It’s a specialist investor and it’s entitled to focus on its best ideas. Sometimes, as with stock market investments, the best ideas are the ones we already own. | |
Sovereign Metals (LON:SVML) (£231m | SR19) | Second year of rehabilitation trials at the Kasiya Rutile-Graphite Project is nearing completion during the upcoming harvest season in Malawi. | ||
Cornish Metals (LON:TIN) (£147m | SR N/A) | “2026 will be a pivotal year as we progress project financing and a final investment decision. With strong stakeholder support, robust economics and clear development momentum, we are well positioned to advance South Crofty towards production and deliver a secure domestic supply of this critical mineral.” Going concern warning as more funding is needed to advance the project. | ||
Activeops (LON:AOM) (£133m | SR44) | Sale of the WorkiQ trademarks to Microsoft for $10m. No impact on the ActiveOps Decision Intelligence software suite of products, and the WorkiQ product will be rebranded in due course. | ||
Scancell Holdings (LON:SCLP) (£117m | SR23) | Current CFO Sath Nirmalananthan to leave on April 24 to pursue other professional opportunities. David Schilansky to serve as a financial advisor and shall become interim Chief Financial Officer. Launched a global recruitment process for a permanent CFO. | ||
Speedy Hire (LON:SDY) (£102m | SR61) | Customer led delays, affecting hire and service revenues now expected to impact the near term. Now expects FY2026 EBITDA to be c.£90m. Net debt £159m. Panmure Liberum: “We reduce our FY 26 and FY 27 EBITDA by 15% and 12%, and expect a small loss before tax in FY 26” Cannacord: “ we cut our FY26E EBITDA estimate by 16% and raise net bank debt by 10%....reduce FY27E/28E EBITDA by 5%/3%” | BLACK (AMBER/RED ↓) (Mark) This company may well look cheap if they hit forward forecasts. However, I have some significant doubts about their ability to do this given today’s profits warning. There is some asset backing at these levels which is probably why the drop today is relatively light compared to EPS forecasts that are now for a loss in FY26 and have been almost halved for FY27. The value of those assets are subject to the depreciation policy being correct, while the large debt levels are not open to judgement. So in keeping with the Stockopedia research that suggests negative news tends to be followed by a further drift downwards in share price, I am reducing our view by one notch. | |
Tracsis (LON:TRCS) (£91.5m | SR62) | Vesputi, a German digital ticketing technology provider acquired for €5.8m (c.£5.1m) with additional consideration of up to €2.4m (c.£2.1m). No profitability given but expected to be earnings enhancing. | AMBER = (Mark) Some investors will appreciate the continued desire to acquire complimentary businesses, as this has been the key growth driver of the company over the years. However, others will be concerned with the multiple paid, which looks like it may be significantly higher than Tracsis shares currently trade on. Overall, this is a relatively small bolt-on that doesn’t move the dial (or our previously neutral view) either way. | |
Christie (LON:CTG) (£35.2m | SR86) | Reached agreement with all scheme members to cease active membership effective from 6th April 2026, and transfer to DC pension arrangements. | ||
Satsuma Technology (LON:SATS) (£22m | SR0) | Cost reduction strategy expected to reduce opex from £6.7m to £2.7m. One off costs £1.35m. Acquired 25.65 BTC. | RED = (Mark) | |
Cadence Minerals (LON:KDNC) (£19.3m | SR50) | No additional archaeological field studies are required in the previously impacted areas. Project remains in execution readiness…subject to receipt of the required permits | ||
Sundae Bar (LON:SBAR) (£18.9m | SR N/A) | Successfully delivered multiple enterprise AI agents, with circa US$10,000 of revenue recognised from these deployments | ||
Eden Research (LON:EDEN) (£17.8m | SR30) | Company's partner, Véto-pharma, has received regulatory approval from the US Environmental Protection Agency ("EPA") for Thymolflex® for use in integrated Varroa management. | ||
Tanfield (LON:TAN) (£11.2m | SR72) | LBT £1.67m (FY24: £0.27m LBT), Cash & S/T Deposits £2.06m (FY24: £3.21m). |
Backlog sections: DUKE, JDG, SFR.
Backlog
Duke Capital (LON:DUKE)
Down 1.5% today at 25.9p (£132m) - Trading and Operational Update - Graham - AMBER
Let’s catch up on this update from Tuesday:
Duke Capital Limited (AIM: DUKE), a leading provider of hybrid capital solutions for SME business owners in Europe and North America, is pleased to provide guidance on its trading for the fourth quarter of the financial year ending 31 March 2026…
This investor in “royalties” continues to make solid progress, with recurring cash revenue ticking up to £7m in Q4:
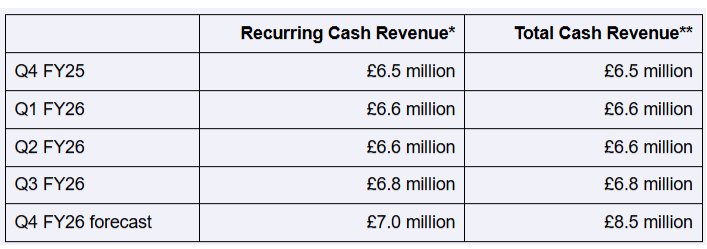
“Total cash revenue” includes not just regular royalty income, but also proceeds from disposals.
Total cash revenue this quarter includes defcon received from the sale of street lighting company Fabrikat.
On a £6.2m investment (in 2021), Duke earned £3.2m in royalties and then £11.4m in disposal proceeds (including deferred consideration).
These figures help to remind us of the very high rates charged by Duke: they were only invested in Fabrikat for 3 years - from Feb 2021 to Feb 2024 - and yet they received more than 50% of their money back in royalties during that time.
A snippet from the comment by Duke’s CEO:
"We are delighted to report another record quarter of recurring cash revenue for Q4 FY26, rounding off a strong finish to the financial year. This performance reflects the resilience of our business model in navigating a challenging macroeconomic environment. Whilst the Bank of England's decision to hold rates in March reflects the ongoing uncertainty in global markets, including the situation in the Middle East, our business model has demonstrated its ability to perform across market cycles.
Graham’s view
I’ve highlighted the reference to interest rates as they are key to the story here: Duke’s share price has never recovered since rates began rising at the BOE.
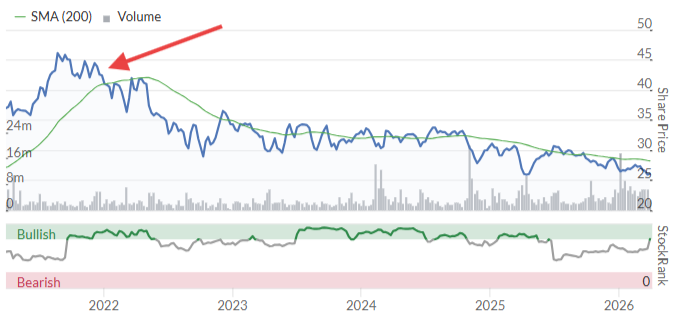
However, the company hasn’t really put a foot wrong. Its investments have been remarkably resilient, with no major blowups and even the occasional profitable exit.
That being said, I do view some of the company’s investments as being inherently very risky - and Mark has noted (here) that a recent follow-on investment seemed to be required to shore up an investee’s finances. So the high returns earned by Duke do reflect what is probably quite high risk.
But it has paid out a stable and attractive dividend stream to investors: 2.8p per share for the last several years.
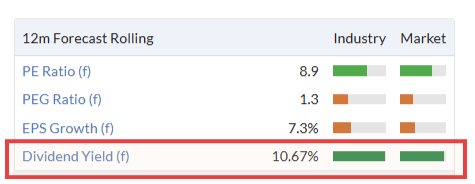
I don’t personally invest for income. For those who do, I continue to think that this has some merit. I’ll leave our AMBER positioning unchanged to reflect the risks.
Judges Scientific (LON:JDG)
Unch. today at £43 (£286m) - Unaudited Preliminary Results - Graham - AMBER/RED =
Judges Scientific plc (AIM:JDG), a group focused on acquiring and developing companies in the scientific instrument sector, announces its final results for the year ended 31 December 2025.
This also came out on Tuesday.
Judges didn’t try to hide the bad news with their headline:
Disappointing FY25, fundamentals intact, 10% dividend increase
Some financial highlights:
Revenue +9.1%, up 6% organically (or up 2% organically if you exclude the lumpy revenue at subsidiary Geotek).
Order intake down 10% organically (down 6% organically if you exclude Geotek).
The order book falls from 18.7 weeks to 15.7 weeks, using the company’s definition of “organically” (i.e. their businesses acquired prior to 2024).
In other words: while 2025 revenue was not bad, the forward-looking order book has weakened substantially.
This is another area where Trump’s administration has significant influence, due to the Federal Government's scientific research funding. Many of JDG’s companies sell into this research.
Comment by the Deputy Chair of Judges:
"2025 was another difficult year. Despite starting with a solid order book and delivering a Geotek coring expedition in the first quarter, the Group subsequently experienced a stark reduction in order intake in the USA, its largest market, as a result of uncertainties around federal funding for scientific research. Additionally, despite general resilience in industrial-focussed markets, H2 saw reduced investments in offshore wind which previously had been a strong growth driver.
That’s just a recap of what we already knew. And to an extent, so is what follows below, but it would have been nice to hear of some green shoots:
As announced in January, the Group started 2026 with a lower than hoped for order book, continued uncertainty around the timing of a recovery in the US, and no expectation of a coring expedition until early 2027. Notwithstanding this turbulence, the fundamentals of the Group, including resilient profitability and strong cash generation, remain intact.
Despite the difficult short-term outlook, the JDG share price did rise by 4% on Tuesday, when this was released. The Deputy Chair reiterated their conviction that the long-term growth drivers were still intact for the business, and that they would carry on with their existing business model.
The “Retired Chief Executive”, David Cicurel, wrote a very nice letter to his “sometimes patient” shareholders, thanking them for helping to raise the company from an initial market cap of £2m, and praising the Judges culture of “respect, integrity, discipline, frugality, patience, and courage”:
This is tested when the environment is turbulent, but I have every confidence that it will again deliver exceptional growth in the capable hands of the new management team.
Graham’s view
I have plenty of admiration for Judges, and don’t really want to be negative. But we turned AMBER/RED on it recently - at the January profit warning - and not much has changed since then.
EPS forecasts are trending downwards:
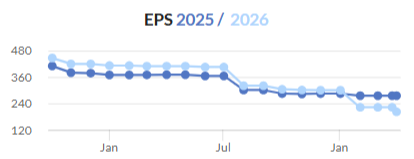
And the stock is still trading expensively against these forecasts:
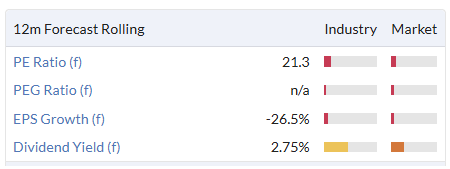
If it was already cheap against forward earnings, I’d be inclined to take our stance back to neutral at the earliest opportunity. But that’s not the case.
There has been a sense of unpredictability around Judges’ results ever since Geotek was acquired, and that unpredictability has been compounded by the Trump presidency and by one or two other more minor issues (e.g. wind farm demand).
There’s a price at which I’d be positive on this stock, and I wish new management every success - but I think caution remains justified.
Severfield (LON:SFR)
Up 3% at 25p on 31st March - Full Year Trading Update - Mark - AMBER
Given the market backdrop this is good news:
FY26 underlying profit before tax expected to be in line with current market expectations of £10.2m
Panmure Liberum worked this out as 2.9p EPS, in line with their previous estimates. However, this doesn’t mean that the company escapes the knife of current market conditions They say:
Accordingly, the Board is adopting a cautious view of the year ahead and now expects FY27 underlying profit before tax to be in the range of £12m-£15m, reflecting increased geopolitical uncertainty, together with broader macroeconomic conditions, the impact of later project start dates, and a continued tight pricing environment.
Which leads PL to cut FY27 forecast EPS is by 27% to 3.6p and FY28 by 22% to 4.7p. So this is a profits warning, although perhaps not an unexpected one. At 24p, the forward P/E is 6.7 for the year just begun, and 5.1x for the year after. If these are achievable this would put the company on a very modest multiple of earnings.
While EPS forecasts are under pressure, there is better news on the debt front which as sizeable for a company with their market cap and EBITDA:
Disciplined cash management during the period providing good liquidity headroom with net debt expected to be ~£28m, lower than current market expectations (Company compiled market consensus: £48.5m), providing year end facility headroom of c.£39m
Liberum forecast this to be partially due to stretching working capital. So I do wonder if this net debt level represents a true position during the year. However, it suggests there is still enough headroom for them to trade as a going concern, which is important in any recovery stock.
Another positive is that they continue to receive insurance payouts for bridge remedial work:
The bridge remedial works programme continues to progress well, with several programmes now complete. Since the half year, the Group has received a further insurance payment of £7.5m, bringing the total amount received to £27.5m. The Group continues to pursue further insurance recoveries and contributions to our costs by third parties. Net costs incurred are expected to be broadly similar to that previously reported.
However, it is worth remembering that the reason they ended up with these payments is that they did work where the steel fabrication did not meet the agreed technical specifications, particularly regarding weld strength and quality, leading to structural integrity concerns. They certainly haven’t covered themselves in glory here, even if they were ultimately insured against these mistakes.
Mark’s view
There still looks to be potential for a recovery here, with cyclically weak market conditions undoubtedly impacting the business. However, that recovery is now forecast to take longer than previously expected. When we last looked at this in December, Roland upgraded this to a neutral view of AMBER on the back of a lack of broker downgrades. With these arriving this week it is tempting to knock this back down again. While nothing is certain at this stage given the impact of higher energy prices and inflation, I feel like the bottom may now be in for forward consensus, and there is a level of conservatism built into these going forwards. If this is true, they trade on a modest forward multiple. Net debt is better than expected which means that they have greater financial flexibility, which means I am willing to take a risk on keeping a neutral stance despite future EPS downgrades this week.
Graham's Section
B.P. Marsh & Partners (LON:BPM)
Unch. at 656p (£236m) - Follow-on equity purchase in Pantheon - Graham - GREEN =
(At the time of writing, Graham has a long position in BPM.)
B.P. Marsh and Partners Plc (AIM: BPM), the specialist private equity investor focused on early-stage financial services businesses, is pleased to announce that it has acquired an additional 2% equity stake in Pantheon, based on an equity valuation of £275m.
This doesn’t do anything for BPM’s diversification, seeing as Pantheon is already by some distance their largest investment.
As of July 2025, it was 30% of their portfolio (apologies for the fuzzy graphic).
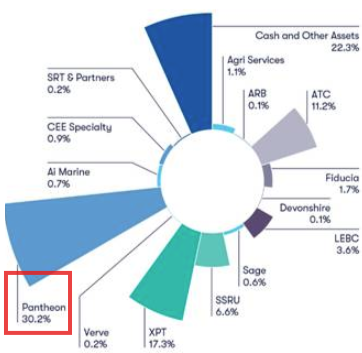
Also worthy of note is that this isn’t growth capital: it’s a purchase from Pantheon’s founders.
If you’re interested to learn more about Pantheon, here’s their website. They are a wholesale broker specialising in complex policies for a range of industries.
Today’s announcement from BPM summarises the achievements at Pantheon since it was launched in 2023, and provides some financial highlights:
Revenue growth from c. £23.8m (FY25) to “approaching £30m” for FY26.
PBT “budgeted to be in excess of £15m” in FY26.
BPM’s initial 25% stake has been increased over time and is now 41%.
Graham’s view
The major downside of this investment is that it maintains BPM’s fairly limited portfolio diversification.
That is a major negative, but I’ve never expected BPM to behave like a mutual fund. It’s a specialist investor and it’s entitled to focus on its best ideas. Sometimes, as with stock market investments, the best ideas are the ones we already own.
Also, BPM has significant cash reserves. As a general principle, I’d rather see the money being put to work rather than sitting idle.
So on balance, I’m comfortable with this news.
Mark's Section
Satsuma Technology (LON:SATS)
Up 5% at 0.2p - Cost Reduction Programme and Bitcoin Purchase - Mark - RED =
This company announces a huge cost cutting program:
…its revised cost reduction strategy that is expected to reduce the Group's annualised operating expenditure from approximately £6.7m to approximately £2.7m, with further reductions expected.
It is not entirely clear what these costs were, or why they were needed (and now not needed). The company reported £2.1m of admin expenses for the 6 month period to 31st August 2025, but no further breakdown was given. This leads me to guess that these costs were mainly salaries to conduct the company's operations.
These operations, as far as I can tell, are buying Bitcoin, and we get the announcement today that they have spent another £1.38m buying more from cash reserves.
However, the highly remunerated team appear to be bad at their main endeavour, as a 40% loss of value on their average purchase price shows:
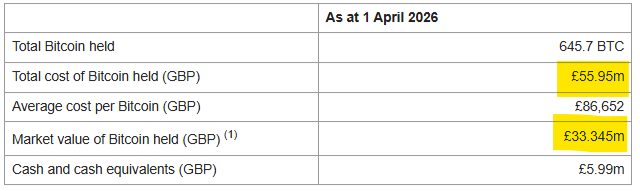
The (only?) interesting part here is that with a market cap of £26.7m, this company now trades at a 32% discount to the £39.3m value of the cash and bitcoin the company holds, which is what piqued my interest.
The problem is that there are no signs of the company liquidating those assets and returning the cash to shareholders. Indeed, they appear to be doubling down on their losing bet and buying more Bitcoin. In this context, the company should trade at a discount to net assets, and that cash balance gives them about 2 years of runway (up from less than 1 year) before they have to start selling assets to fund the corporate structure (or perhaps more realistically, raising money from the market!)
Mark’s view
Despite a purported 32% discount to net assets, it will perhaps come as little surprise that I’m negative on a company spending (even a much reduced) £2.7m a year buying Bitcoin. This seems to me like an activity that a man and a laptop could do effectively, spending about 10 mins a year. Not only is this an activity that doesn’t require the corporate overheads of a listed company, but the company appears to be bad at their main activity, having lost an average of 40% on their historical purchases! We’ve been negative here since the middle of last year, and since then, shareholders have lost 98% of the value of their holding. With a StockRank of zero, I remain negative. RED
Tracsis (LON:TRCS)
Flat at 307p - Acquisition - Mark - AMBER =
This acquisition is described as:
Bolt-on acquisition that expands Tracsis' digital ticketing capability and establishes a small operational foothold in the German public transport market
The core product acquired is Mobilitybox, a B2B standardized API platform that acts as a bridge between public transport operators and third-party companies. It allows businesses to integrate live transit data and ticket booking directly into their own applications and websites. For example, it would allow airlines or event organizers to sell "last mile" transit tickets alongside their primary offerings.
While this may be a good strategic fit and expand Tracsis geographically into a large German market, it is not necessarily been a cheap bolt-on. They are paying €5m + up to €2.4m earnout. Tracsis does not give any financial figures for the acquisition. Third party estimates suggest that Vesputi delivered around €1m in revenue in 2025. This appears to be a very significant premium to Tracsis 1.1x price-to-sales ratio. It is hard to estimate profitability, but again this is likely to represent a high multiple paid, especially if the earnouts are triggered.
The acquisition is said to be “Immediately earnings enhancing” which is good to hear, but doesn’t necessarily mean a lot when the acquisition is paid for in cash, which earned an average of 2.8% interest last year. This means that anything less than a 35x earnings multiple paid could be described as earnings enhancing.
The initial consideration paid is less than 5% of the Tracsis market cap so overall this will have a relatively minor impact on the financials. I can’t see any updated broker coverage today, which again suggests minimal financial impact in the forecast window.
Mark’s view
The company has a long history as an acquirer, and for a number of years, shareholders liked the growth story that this brought. However, by 2022 it had struggled with some of the integration efforts and paused acquisitions while it engaged in restructuring. Some have questioned the ability for the company to grow organically and whether they have generated adequate returns on past acquisitions due to the multiples they paid.
Today’s deal is described as a strategic acquisition rather than a bargain purchase. However, it is only a small percentage of the overall market cap of the company, meaning it doesn’t shift the dial much either way. Some will be encouraged by the continued return to acquiring bolt-ons. However, the apparent multiple paid doesn't do much to assuage the concerns of those who think they may have pursued growth at any cost. Overall, I don’t think there is enough in today’s acquisition to change our previously neutral view either way, so I’ll stick with AMBER.
Speedy Hire (LON:SDY)
Down 13% at 19.2p - Trading Update - Mark - BLACK (AMBER/RED ↓)
The tone here reads like a profits warning, even if the company don’t explicitly say this:
At our interim results on 26 November 2025 we anticipated a continuation of subdued market conditions for the remainder of FY2026. Market conditions have worsened through Q4 with uncertainty around the UK Budget in November and the recent geopolitical events in the Middle East. The Group has also seen certain customer led delays, affecting hire and service revenues, which are now expected to impact positively in the near term. As a result the Board now expects FY2026 EBITDA to be c.£90m.
A quick check of the brokers notes confirms this:
Panmure Liberum: We reduce our FY 26 and FY 27 EBITDA by 15% and 12%, and expect a small loss before tax in FY 26
Canaccord: …we cut our FY26E EBITDA estimate by 16% and raise net bank debt by 10%....reduce FY27E/28E EBITDA by 5%/3%.
Both brokers cut FY26 adjusted EPS forecasts to show a loss. This perhaps should not be a surprise as H1 was loss-making and said that H2 trading conditions would be challenging.
Canaccord reduce FY27 EPS from 5.3p to 4.2p. Panmure are more pessimistic, dropping their number from 5.7p to 3.1p. With the share price only down 13% so far, his looks potentially light versus the scale of these EPS revisions. Although, it could be argued that the market was/is already sceptical about these figures. A scepticism I share. Recent events in the Middle East have the potential to lead to continued construction market weakness beyond the financial year just ended.
ProService:
One of the major reasons for this optimism cited by both the company and brokers is the recent Proservice deal. This was a complex deal that involved HSS being rebranded as pro-service and focusing on its digital platform connecting customers with equipment, materials and training. HSS’s physical hire business was sold for a £1 to private equity, and Speedy became preferred supplier for equipment to the ProService marketplace for an initial five-year term in return for a £35m equity injection into the ProService group.
The part I find difficult is that both HSS and Speedy described this deal as a good one for them. It is possible that they were both winners and the Private Equity Group that bought all the HSS hire equipment business for £1 was the loser, but this seems a little far-fetched. Anyway, Speedy are now significantly underwater on their £35m equity investment with the ProService share price following the market down.
Balance sheet:
Yet, this is one of the main reasons Speedy say their net debt has jumped:
Net debt at 31 March 2026 is expected to be c.£159m, including the £35m invested in ProService. The Group expects to see meaningful deleverage in FY2027 as a result of strong operating cash flow.
One of the benefits of this type of company is that in weaker markets, they can simply not buy any new equipment and run the business for cash. So the question is, why haven’t they been doing this in current market conditions?
Brokers still see net debt being high going forward, with Panmure only seeing this figure (which also excludes lease liabilities) dropping to £152m next year. This is still high compared to their earnings and market cap, making this look particularly high risk at the moment.
The other side of this equation is the assets. At the half-year, they had £227m of owned hire assets:
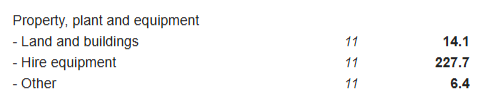
So this potentially covers more than the net debt, and is perhaps why the banks appear relatively sanguine. As anyone who has hired equipment will know, depreciation is a real charge here, and the company can only hold off buying new equipment for so long.
And presumably, it's this net asset backing that means the share haven’t fallen further this morning:
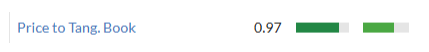
However, I have to question how realistic this figure is. It obviously relies on the depreciation policy being correct. Previously, non-itemised assets were depreciated over 15 years. This was reduced to 7 years which seems more realistic. However, there was an issue where these had to be written down in 2023, when roughly 40% of these items were found to be missing. Itemised Hire Assets are typically depreciated over their expected useful lives on a straight-line basis. However, this may overstate the value of recently purchased items, especially if they have high usage.
The company also invested in hydrogen-electric powered access platforms in 2023 and formed a 50-50 JV with AFC Energy for power generators. While we may applaud Speedy for their forward-looking moves, it is not clear to me if this equipment is particularly practical, as the availability of commercial hydrogen is quite limited.
Mark’s view
Given today’s news, there are only two real positives for the company. The first is that they trade at a discount to tangible book value, and the second is the forecast rapid recovery in FY27. They may well look cheap if they hit (much-reduced) forward forecasts. However, I have some significant doubts about both of these.
The StockRank isn’t exactly inspiring and will likely look much worse once the FY26 results have been released and incorporated into the StockReport:
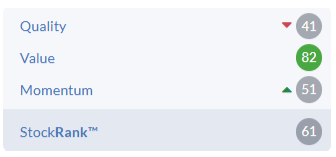
So in keeping with the Stockopedia research that suggests negative news tends to be followed by a further drift downwards in share price for some time, I am reducing our view by one notch to AMBER/RED.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Apoligies Graham / ED this seems like a twitter account.
Politics aside this is about making money.
Do I need to repeat in capital letters.
HOW DO I MAKE MONEY - my politics is my own, not anyone else.
How do I find investment opportunities which Mr Market has missed.
Capiche.
Isn't that from 26th February 2026?
This refers to a significant policy shift by the Zimbabwean government in early 2026. On February 25, 2026, Zimbabwe's Ministry of Mines and Mining Development announced an immediate and indefinite ban on the export of all raw minerals and lithium concentrates.Here is a breakdown of why this happened and what it means:1. The Core Reason: "Value Addition"The
primary goal of this ban is to force mining companies to build
processing plants within Zimbabwe. Instead of shipping raw ore or
concentrates to China or Europe, the government wants to "add value"
locally.
2. Alleged "Malpractices and Leakages"The Ministry cited "malpractices and leakages" as a major trigger for the immediate suspension. This refers to:
3. Impact on LithiumZimbabwe is Africa’s largest lithium producer and holds some of the world's largest hard-rock lithium deposits.
4. Who is affected?
Just saw it on Reuters Today and thought some might want to react fast as a long weekend. Thanks for the response and will unpack. Tend to avoid Africa - all looking good Tharisa (LON:THS) Sylvania Platinum (LON:SLP) etc even Thungela Resources (LON:TGA) (thats in my coffee can).
Trigger ALERT - look away now those with TDS.
What are they going to do with this flippin deficit. All democracies are in the same boat - expenditure increasing, income decreasing. And for those that wish it, well you will regret when the ol doodlebug falls silent over London (sorry slipped).
Solar energy - a personal view. Two years ago I installed 6.6kWh solar panels and a 5.6 kWh storage battery. My rurally located house has no mains gas supply so central heating is oil fired. I also have 2 EV’s which I can charge on the drive. As a result my behaviour has changed and I now do the following:
This has reduced my annual electricity bill significantly. Before I installed solar and became an Octopus customer, my daily usage was around 19 kWh. Now it is just under 13 kWh. However the really big change has occurred in the price I pay for each kWh. Approximately 79% of the electricity I use is at cheap rate (currently fixed at 5.49p) rather than standard rate (34.4p). I also export an average of 8 kWh per day . This credits me @ 12p per kWh and significantly offsets the full price electricity usage.
My annual electricity consumption before installing solar was about 7500 kWh. Today it is 4650 kWh but I export nearly 3000 kWh. If I add in the savings on petrol, ignoring the inflated Iran induced prices, my installation looks set to break even after another couple of years.
I wouldn't bother with heat pumps, far too much disruption to existing pipework and radiators and associated costs. Solar is straightforward as long as you have a roof which gets enough sunlight. You also need to learn how best to exploit the energy it generates and drive EV's rather than ICE vehicles.
It's a personal view but it might help inform anyone considering how to power their homes in the future.
Very interesting rwh3ue. I am thinking along the same lines. Did you consider getting an electric boiler fitted?
Not at the time. The solar was expensive and I didn’t expect such a rapid payback. My oil boiler works well so there’s less incentive to ditch it now. Also I once had a flat with an electric boiler and it was eye wateringly expensive to run. Might look different now so worth considering.
I have a kickspace fan heater in the kitchen. I’m wondering if I should program it to run during the early hours to provide some cheap morning heat.
A 'baseload' system is common sense. The ol oil burner there for anytime a blackout. Like Heinz cans in the cold store, or John Wick style gold coins under the garage floor (no I don't do that - thinking of a solution though - tokenized gold is a thing entering your email at some point. The UK is coming out of its mini-iceage so solar practical for those with some roof space economics and no trees. Greta has moved on to something else. Millubund wants to be PM so needs to get 'real'.
Musk wants to put data centers in space for free cooling and heating (forgot which) - makes sense. Lets hope the little tikes think of clever ways out our predicament after they have expended energy breaking windows in Clapham High Street -nah.
I went to Northern Ireland Belfast once and in the garden under a simple tin hat was a oil burner, really simple piece of kit. Ok the large oil tank feeding it was annoying but that is what they had. No condensing super efficient supposedly £4k British Gas solution (Veismann, Valliant, Gloworm etc etc) with annual maintenance of £200 or more (and lifespan of sub-12 years). Simple, Martin from the pub will fix your boiler Mam for the price of a pint and a bit for the parts. But then Euro regulations entered the space so someone somewhere could clean up.
I'm just a user and payer - no expertise on the industry - but it goes up gas, elec, water annually. The relentless grind of inflation.
If oil was history why the "hoo har" - answers on a postcard.
Great stuff. I'm in a similar situation (solar, battery, EV, cheap overnight tariff), but have a gas combi boiler. Have you considered electrifying your heating/hot water as well?
I took soft options to do this and so reduce my gas usage (running electric underfloor heating overnight, running oil filled radiators on timers overnight), which is cheaper, greener and more efficient than heating via gas. My family ruled out hard options (eg installing a heat pump).
Have you considered similar soft options, for e.g. using the immersion heater in your hot water tank overnight (assuming you have one), using electric heating where possible? Given the high and increasing cost of oil your savings might be significant.
Anyway, back to topic, FTSE just jumped 1%, I wonder what Trump has said now?!
EDIT: having just seen your reply to fifth I would say definitely use that fan heater overnight. + any other forms of electric heating that you have.
And agree, an electric boiler as a sole source of heating is ruinous (especially if on a standard tariff...)
You raise interesting questions. My oil boiler heats hot water as a biproduct of heating the house. I was offered the option of wiring the immersion heater to the solar but cost/value wasn’t good. Summer months need little oil heating and we get quite a bit of solar gain too so ekes out oil supply. I last topped up just before Iran war broke out. Oil is now 2.5 times the price.
Winter is poor for solar input and obviously needs oil heating so one has to look at 12 months rolling costs. Hope this helps.
The SP movements in Quartix Technologies (LON:QTX) AIM) and SNOX (Aquis Exchange) demonstrate a lack of understanding of what these companies deliver at a time when fuel prices arising from the Iran War are sky high and destined to remain so for a long time to come.
SNOX delivers to land based diesel users (eg construction and haulage) an immediate fuel cost saving from day 1 building to an optimum and then permanent level after the product has completed its cleansing process on internal combustion engines. This comes to roughly 8% in carefully run practical tests. A UK haulage fleet generated near 8% after 3 months in spring 2023, translated into their 40 HGV fleet saving £173k pa, They remain current users, representing bottom-line savings in excess of £500k after these 3 years. There are also additional benefits from other characteristics of Sulnox Eco™ which generate maintenance and parts savings of an extra c.2%, and after the product cost for this fuel conditioner of around 1-2%, this generates a permanent saving change straight to the bottom line of c.8%. Saves fuel; improves emissions ; zero capex, simple pour-in solution pre-fill up. Full compliance with all international fuel regulations, so no threat to voiding warranties. What’s there not to like and implement immediately?
QTX on the other hand offers very low cost and highly effective telemetry for vehicle fleets with performance improving all the time with further technical innovation. The typical reason for customers’ satisfaction is fuel savings of up to16%. Yet the SP remains in the doldrums, though despite going XD today for a 7.5p divi coming up, the SP has only fallen around 4p. Again what’s not to like for investors and especially with the 4 principal growth channels they use to generate new business across several international markets, as well as UK.
with the Iran War continuing and the fall out for many months, perhaps years to come, they seem to be very promising opportunities for appropriate companies to save even more money.
I have bought Sulnox in the past for my Volvo diesel via Amazon. It is not currently available on Amazon. which is strange and for me annoying.
Topical news and de-risking update from Rockhopper Exploration (LON:RKH) today. A new oil province in a British Overseas Territory. 2P Reserves (Gross) -314 million barrels...Reserves (RKH 35%) - 110 million barrels. Reserves moved from contingent to booked following FID. Funded for phase 1 and first oil early 2028
Why did Argentina go to war. The Gulf will get back to 'normal' so the Falklands will be on the back burner. But a huge resource that could wipe out any budget deficit. We don't own or can drill it on our own (BP/Shell) so will rely on er America (oops own goal alert).
Its easy to say "let's open up the North Sea again". But the facts are that hundreds of exploration licences were granted between 2010 and 2024, and they didn't make a significant find. I can't see it would do much harm to carry on looking, but the Government has to focus on renewables and nuclear.
Why ? We are losing our manufacturing and basic industries to the highest energy costs across Europe whilst paying land owners huge rents for intermittent windmills that require fossil fuel - imported- as back up
Several reasons but the main one is rising sea levels. Have we all forgotten that climate change will decimate large parts of the world. Yes we all want to bury our heads in the sand and ignore what's happening but opening more oilfields will not help. Like it or not, renewables have to be the future, if we are to have one.
Stop hating windmills. It's boring. They look nice, improve the landscape, bird diversity and protect our seas from foreign submarine or surface invaders. When they decide to blow up due to being basically a generator in the ocean working 24/7 (ish) requiring huge oil assets to produce and keep them running then whats not to like.
Some bloke (it must be a bloke) has run a cable over the pavement to charge his EV. Ok has gone on Amazon and got a nice plastic high-viz thing so ok for occularly challenged persons. There is a lamp-post with a charger point in it but seems 'innovation' and 'work arounds' a thing in any society (suspect a multi-occupation premises so 'he' does not pay the overall bill). Clever guy - maybe works for Google (London Kings Cross).
Is there any mileage to going back to coal from memory we have stacks of the stuff and I would have thought there must be ways to capture most of the carbon/rubbish that is emitted from the burning, plus doesn't it take roughly 100kg to of coal to make one solar panel.
Drax has been subsidised by the UK taxpayer to develop carbon capture. It's been at it for year - and no sign of it working yet.
Coal is the worst polluter and sure, you can argue that China burns it to make solar panels but once in place, solar generates cheap electricity and helps to limit our country's dependency on imported energy.
Surely all the coal power stations have been decommissioned by now?
We exported overseas, to nations that generate energy with coal, industries that used coal generated energy. Global annual coal consumption is increasing.
The only way to produce steel. Nothing else gets hot enough to melt iron ore.
And billions in third world countries still cook with coal (go on youtube and look at vietnam etc cooking videos) soon we will be there but without the amazing views and crop/animal farms.
Can we all conclude the mkt seems like a headless chicken running up and down the yard. UK house builders back to the worts of covid valuations, surely value here but when
Graham hitting the nail on the head with the best investing insight that I have seen this year. Absolutely brilliant. It needs to go onto the stocko quotes list that appear occasionally. "Investors interested in crypto currencies can easily lose money directly rather than paying someone else to lose it for them!"
Credit where it’s due, the comment was Mark’s.
oops, sorry Mark.
Crypto is not just Bitcon, or alt-cons. The financial world will, when we are ready for it, a national BritCon. Your wealth is held by whom. A guarantor to give it back at any time instantly on demand. More fool you, and me.
Oh we had an 'outage' some switch didn't work on our servers. We see it with HL, IG even. When market hot liquidity disapears. Pick up the phone (lol).
Lets hope for more normality in markets - but then the Market likes the volatility, thats where the money is made.
Q: where does all this money go. Its not to taxpayer funded stuff like welfare, defence etc its somewhere else. Land most likely. Why are they looking at the Moon i'm a bit behind the news.
Stockoplaying up today, refresh on company pages going error 404. for me.
same for me - frustrating!!
Fixed now, thanked Oliver, and am glad it wasn't just me.
I see UK politicians are still quarrelling between themselves on the granting of more North Sea oil and gas licenses https://www.theguardian.com/bu... What fools!? No one mentioned ENERGY SECURITY - imagine being at the mercy of Trump and the USA's capitalistic whims. LNG tankers are diverting as Asian buyers offer to pay more https://www.reuters.com/busine... And no one mentioned that investors aren't going to invest in UK oil and gas anyway unless the prohibitive tax terms improve!! I think companies like Enquest are a buy at current levels - politicians will soon see their silly ways as they find out that people can't get gasoline at any price!
I totally agree there is no strategic intelligence in Politicians these days which is worrying. How are we going to move all households from gas boilers to other sources given the price of heat pumps and electricity. The penny will drop when a true crisis hits but it will be too late. Ever heard anyone say bad things about Norway continuing to drill in the North Sea!
I'm really struggling to understand how the market reacts positively when Trump says the war will be over soon as he normally says the opposite in the same sentence!
It's not just the cost of heat pumps which makes them a false solution for many. What about the need for space for the ancillaries (particularly for flat owners) and the cost of associated works? Where is the clear and incentivised route for the government's stated policy of Fabric First, ie home insulation? Add to that, landlords are still waiting for publication of the specific requirements, and methodology for EPCs to move to a minimum of C by the end of this decade.
Today, the Tories say they will rip up their own carbon regime, including doubling down on the recent Labour raid on low carbon generation with no thought on what this will do to future investment or the value of existing investments - many of which are already at a significant discount to NAVs.
It is also the cost of insulation, to make heat pumps viable, in many older properties. I would probably have to spend around £10k on that.
Including ripping out your existing radiators and then people say in older buildings it still doesnt work.
Add another 5 grand to that unless you live up north.
I've never heard heat pumps being referred to as a silver bullet for all though? So stay dependent on oil / gas and just get hit indirectly for the cost of not transitioning away when we do this dance again in future?
the tories were the ones who slapped the savage windfall tax due to pressure from labour and others so they are as guilty as labour in my book.
The real crazy thing with all the Green policy makings is, it actually creates more Co2 in the world, just less in the UK. Importing of wood pellets from Canada and the US increases Co2. Higher energy costs in the UK makes it difficult for the UK businesses' to survive and compete, so we import even more. That is just shifting the Co2 production to other countries and adding more Co2 with transport. Then there is the loss of tax revenues. The North sea oil used to contribute 6% of the UK tax revenues! Our politicians are absolute numpties that only care about short term policies that will help get them re-elected. On the current trajectory, in a few years time we will need to import a bigger percentage of gas than we do now, and that is with a gradual reduction in usage. We may have the US as our only option to import from and who's to say they will not one day stop exports and look after themselves? The North sea needs to be opened up again.
The North sea oil used to contribute 6% of the UK tax revenues!
To be fair the UK's North Sea basin is 90% exhausted, and 180 out of 280 fields are expected to close by 2030. They just aren't making oil and gas anymore - we are never going back to those kinds of volumes and revenues.
That said the lack of any kind of joined up thinking from the government is a self-inflicted wound. The best that can be said for this is that they're no worse than governments over the last 40 years who've known this day would come and have done sod all to prepare, preferring to keep taxes low and social benefits high and kick the can down the road.
Being slightly more positive the UK generated 47% of its energy from renewables last year, that's nearly doubled in a decade. The cost of renewables projects has cratered in the same time scale. The problem with the current plan, with the massive network upgrade costs and marginal pricing mechanisms is that people and businesses won't feel the benefits of this until 2040.
We will still need gas as backup even then - the lack of kind of national gas storage facility is a disgrace. And we will need nuclear as backup to intermittent renewables - again, a decade away.
I agree the current government is a mess, but let's not let previous ones off the hook - this is a multi-generational problem, not something that's occurred overnight. However, the problems are real and politicians promoting easy solutions - drill more, cancel net-zero - are offering snake oil to replace the real stuff.
timarr
Agreed Tim probably 25 years of poor decision making, printing trillions of debt to keep the masses onside which has encouraged hundreds of thousands to drop out of work.
Its took a while but its getting harder for the West in general now to kick the can. The issue is you then get these populists who promise easy answers to all the problems and 50% of the electorate who don't understand the global macro situation believe them.
Farage promised £90 bil odd of tax cuts but since he realised he might win he's walked back every penny if there were easy answers out there even Reeves and Starmer would just put the personal allowance up to £20k.
While preparing the ground for the Self Assessment I have been thinking 25k personal tax allownce would be nearer the mark.
The story of Robbin Hood is educational. Kevin Costner iteration was entertaining.
The problem with the current plan, with the massive network upgrade costs and marginal pricing mechanisms is that people and businesses won't feel the benefits of this until 2040.
Agree with the general sentiment of the post - but struggle to see what benefits are to be had? If one of the benefits are lower energy costs, then I suspect that many people will be disappointed.
For the reasons you state, we have left it very late to implement a joined up energy strategy. Normally, when something of this magnitude has to be done quickly, it becomes very expensive. Even if renewable energy is cheaper, the Government of the day will probably find a way to increase the tax burden to service the debt
I could be wrong, but I lean towards the UK being a high energy cost country for as far as the eye can see. If so, this is quite a failing seeing we had oil, gas and coal at our disposal. A very poor outcome.
Unfortunately, moving to sustainable energy sources is not going to cut costs overnight. That's a message that shouldn't be fudged. And no doubt we will need to keep some gas generation at least during transition. But longer term it will reduce energy costs and increase energy security, as well as helping reduce or minimise global warming, with the horrendous costs that will entail if unabated.
I think we will have to disagree on this one.
I dont see any route to reducing energy costs, that is using any combination of fosil fuels and renewables over whatever timescale any one wishes to consider.
We are human. We want to eat. We need heat in our caves. And to cook for our kids and olduns.
Zealots can go do one.
For me the issue is extremely complex and it is easy to take a simplistic view on this and also incidentally to blame the Politicians for having no joined up policies. Regardless of Political party there is confusion on how to approach it. The issue is that saying that Global Warming doesn't exist and that mankind doesn't create the problem is not true and doesn't help solve the problem it simply will be the major issue coming down the line. Also if I may proffer were we to create much of our energy from renewables it would reduce the need to wage war on such a regular basis. On the otherhand we have a global population addicted to hydrocarbons and to suggest we can solve that in a generation is just not going to happen. We have a huge problem and all of you as investors will pay a huge price if you ignore it. That said I and all the Politicians don't have an answer, it is a Gordian Knot.
Trump satates that Sir Starmer is no Churchill. A young Churchill might see Ukraine as a mere stepping stone to Siberian oil and gas and if that might be the case Trump would be right.
I often find myself nodding when I read your posts timarr. I'm no expert on oil and gas but a quick Google search on the largest gas fields in the world suggest Qatar, Iran and Russia are the main producers by some way.
https://en.wikipedia.org/wiki/List_of_natural_gas_fields
The US has developed a decent amount of shale oil and gas. And Australian politics has shifted a long way to start developing potentially large reserves in Northern Territory. I have a small legacy holding in Falcon Oil & Gas (LON:FOG) which is being acquired by Tamboran Resources (NYQ:TBN) which is now reporting positive news in Northern Territory and looking to become a producer later this year.
As for the UK, the National Grid web site shows how important renewables are now but China has a tight grip on the rare earth minerals required to build wind turbines and limited their export after the US tariffs were announced in April 2025. The UK grid also needs to be better built out as electricity gets created in many more places than traditional coal/gas power stations.
https://grid.iamkate.com/
Reports say the Jackdaw gas field could be brought online by the end of the year but it's small compared to what exists elsewhere. Rosebank is west of Shetland and I know from relatives the weather there is awful so it is dangerous and expensive to develop.
Norway keeps making significant finds in the North Sea. Is the geology just different on their side ? I don't know but it seems they have more appetite to develop the North Sea than we do.
https://www.equinor.com/news/20260310-two-new-discoveries-north-sea
The inmates running the asylum comes to mind......
Just the 5th form without any experience
What Numpty Trumpty giveth , Numpty Trumpty taketh away. The markets and the world work on stability and confidence. Until Mr Trump leaves office, we are unlikely to see that. We still have another couple of years of his presidency, oh happy days. I have never felt that Britain and Europe should move away from America as a trading and security partner. However, I now think that might be the way forward.
If he loses the senate in the mid terms (Nov) it should be over for him having a free reign to do crazy stuff. He really is turning into the mad king he's got himself into one all mighty mess and is now lashing around at anyone else to desperately try and find a way out whilst chanting "stone age, stone age".
I raise this as a query rather than a comment. But I hear so many people talk of how we only have a couple more years of Trump and I wonder how we think he is going to leave. He still contests the 2020 election and has filled the CIA, FBI and Govt servants with deniers and people who have given their commitment to him rather than the constitution. If he pops his clogs Vance is waiting to fill his shoes. Vance who was sponsored by Thiel. Thiel the billionaire who mentored Musk in Paypal and teamed up with Curtis Yarvin (Mencius Moldbug) who is the mind behind Thiel saying he doesn't believe in democracy and countries should be run like businesses etc etc. My point being this is a very well organised movement. Driven by billionaires money and supported by organisations like Christian Nationalists who twenty years ago influenced over 50 seats in the Senate. It is no coincidence that Hegseth is holding prayer sessions in the Pentagon. They are not going to just disappear. So is it going to be any better without Trump?
I thnk MAGA will die with Trump. He has uniquely tapped into a very disaffected part of society. After him the Republicans will probably turn into the Tea party, which i do not think will get elected.
No11 could do with reading the Berkley update today. They are hitting less than 10% of the build target for London, abysmal. Rhetoric V reality
Trump sure knows how to move markets
Feels like his mates are getting on the right side of a trade before trump speaks.
Maybe someone will even outperform the Pelosi portfolio this year.
Its possible the whole purpose of the war was to make millions by insider trading.