Daily Stock Market Report (Thur 30 Jan 2025) - SOM, TPFG, NFG, MUL, KETL, FEVR, SAGA, KMK, CAM, RCDO

Good morning!
Sorry if you've been having any difficulties loading this page, I'm told that the developers are working to fix the problem as soon as possible. (EDIT: you shouldn't have any issues now.)
1.15pm: we've run out of time now, cheers!
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Shell (LON:SHEL) (£157bn) | Fourth quarter press release | 2024 “another year of strong financial performance”. 4% divi increase, $3.5bn buyback. | |
3i (LON:III) (£36.8bn) | Q3 performance update | Total return 20% for nine months to Dec 2024. NAV rises from 2261p (Sep) to 2457p (Dec). | |
BT (LON:BT.A).A (£14.3bn) | Q3 TU | “On track to deliver our financial outlook for this year. Year-to-date adj. rev -3%, adj. EBITDA +2%. | |
Sage (LON:SGE) (£13.4bn) | TU | Reiterate guidance for the full year. Q1 revenue +10%. | |
St James's Place (LON:STJ) (£5.0bn) | 2024 New Business Inflows & FUM | “Strong final quarter”, “successful year”. New charging structure on track for H2 2025. FUM £190bn. | |
Airtel Africa (LON:AAF) (£4.9bn) | Q3 Results | Year-to-date revenue down 5.8%, EBITDA down 11.9%. Affected by currency devaluation. | |
Serco (LON:SRP) (£1.5bn) | Acquires leading US defence business | Price is ~£264m in cash. | |
Wizz Air Holdings (LON:WIZZ) (£1.4bn) | Q3 FY25 Results | Load factor 90.3%. Rev +10%. Loss-making (grounding of 20% of its fleet, FX). Net debt €5.1bn. | |
Future (LON:FUTR) (£983m) | Appointment of CEO | An internal hire, he has been with Future for over 20 years. | |
Greencore (LON:GNC) (£810m) | TU | Outlook is in line. Unprecedented labour cost challenge. Committed to offsetting it in full. | |
Fevertree Drinks (LON:FEVR) (£768m) | US Strategic Partnership with Molson Coors | Network of distributors/customers. MC invests £71m in FEVR, FEVR to buy back £71m of its shares. | AMBER/GREEN (Graham) Very exciting deal to take advantage of the opportunity to grow market share in the US. A little expensive in P/E terms but worth it in my view. |
Auction Technology (LON:ATG) (£740m) | AGM Statement | Trading in Q1 is consistent with FY25 outlook. | |
CVS (LON:CVSG) (£737m) | Half Year TU | H1 LfLs -1.1%, softer conditions. Tax changes to cost £11m before mitigation. Outlook in line. | |
Alfa Financial Software Holdings (LON:ALFA) (£608m) | Q4 TU | FY24 op profit +13% to £34m, 5% ahead of exps. Rev in line, costs lower. Well positioned for 2025. | |
Discoverie (LON:DSCV) (£603m) | Q3 TU | In line. Sales for Q3 flat year-on-year at constant FX. Organic performance recovering. | |
Hollywood Bowl (LON:BOWL) (£501m) | AGM TU | In line. Total revenue for FY25 is up 11.3% year-to-date. Well positioned to mitigate NICs/NLW. | |
Resolute Mining (LON:RSG) (£434m) | Quarterly Report | Production slightly <guidance, costs above guidance. Lower production forecast for 2025. | |
Rank (LON:RNK) (£420m) | Half-year Report | Underlying LfL operating profit for FY June 2052 to be slightly ahead of current expectations. | |
Next 15 (LON:NFG) (£346m) | TU | FY Jan 2025 to be at bottom of analyst exps. New business wins to come through in new year. |
AMBER (Mark) |
Tullow Oil (LON:TLW) (£283m) | Ops Update | Considering disposals of non-core assets to accelerate deleveraging. Net debt $1.45 billion. | |
LSL Property Services (LON:LSL) (£282m) | TU | Trading is in line. 2024 revenues were up c. 20%. | |
Fintel (LON:FNTL) (£275m) | TU | Full-year results in line. Revenues up 21% to £78m. | |
XP Power (LON:XPP) (£312m) | Legal Judgement | $19m in total is to be paid by the XP power, $10m above the existing provision. Net debt now 2.65x Adj. EBITDA | |
Treatt (LON:TET) (£261m) | AGM TU | In line. Q1 rev in line with management's expectations, Q2 has started well. | |
Property Franchise (LON:TPFG) (£261m) | TU | In line with market expectations. Revenue +146% to £67.2m due to acquisitions. Net debt of £9.1m. FY25 has started with strong momentum. | GREEN (Graham) A reassuring update with few obvious obstacles to another good performance in 2025. High-quality franchisor at reasonable valuation. |
Ricardo (LON:RCDO) (£218m) | TU | Below consensus expectation for FY 24/25, due to order delays. Net debt £18.5m due to £64.3m disposal of Defence business. | AMBER/RED (Graham) Huge cuts to EPS forecasts on the back of delays and I downgrade my stance. I'm not sure this is very cheap even if profits recover as expected by 2026. |
ITM Power (LON:ITM) (£216m) | Interim Results | Rev. £15.5m (H124: £8.9m), Adj. EBITDA loss £16.8m (H124: £18.1m). Cash £203.1m (H124: £253.7m). FY Rev in line, improved EBITDA losses versus original guidance | |
Somero Enterprises (LON:SOM) (£166m) | TU | Rev in line, profit small miss. Rev $109.2m, Adj. EBITDA $29.1m, cash $29.5m |
AMBER (Mark) |
Saga (LON:SAGA) (£163m) | TU | U/L PBT marginally higher than the prior year, ahead of our previous guidance. Travel U/L PBT in the high single-digit millions. Insurance Broking U/L PBT materially lower than in 2023/24. Insurance Underwriting U/L PBT high-single digit millions. | RED (Graham) RED might be a little harsh given the positive trading update and refinancing announced today, but I've never been a fan of this one and the interim balance sheet had deeply negative tangible value. It still looks to me like a disaster waiting to happen. |
Camellia (LON:CAM) (£131m) | TU | Ahead of expectations. £4-5m loss vs previous £7-9m. |
AMBER/GREEN Mark (I hold) |
Strix (LON:KETL) (£106m) | TU | Ahead of market consensus.Adj. PBT £18m-19m |
AMBER (Mark) |
Scancell Holdings (LON:SCLP) (£100m) | Interim Results | Operating loss £10.5m (FY24: £8.1m). Cash 31 Oct £9.1m. Cash runway to H2 2026 beyond multiple clinical milestones due to £11.3m raise in Dec 24. | |
Futura Medical (LON:FUM) (£94m) | TU | FY24 Revenue and Profit after Tax ahead of market expectations. FY25 revenue will be materially below expectations and, as a result, will make a loss after tax in FY25. Cash of £6.6m. | |
Mulberry (LON:MUL) (£68m) | Strategy Update, TU | In line with the Board's expectations, | AMBER/RED (Graham) Tempted to go fully RED on this but the company is cutting costs and trying a simpler strategy. Fingers crossed for them. |
Science in Sport (LON:SIS) (£58m) | TU | Adj. EBITDA & Net Debt are expected to be ahead of current market expectations. Rev down 17.5% to £51.9m, Adj. EBITDA +105% to £4.2m, Net debt £5.9m. FY25 trading has started well. | |
Flowtech Fluidpower (LON:FLO) (£46m) | TU | Underlying EBITDA is broadly in line with expectations. Rev down 4% to £107.3, Net debt £15.1m (£14.8m FY23) | |
Tissue Regenix (LON:TRX) (£42m) | TU | Rev +8% to $28.4m, Adj. EBITDA above expectations. Cash $1.9m. Review of strategic options is continuing | |
Inspecs (LON:SPEC) (£40m) | TU | 2024 did not meet the full expectations of the Board. Revenue £200.5m (2023: £203.3m), U/L EBITDA £17.5m (2023: £18.0m). Net debt £22.9m. Solid start to 2025. | |
Novacyt SA (LON:NCYT) (£36m) | TU | Rev £19.6m (FY23 £10.6m), Cash £30.5m (£32.9m) | |
Kromek (LON:KMK) (£34m) | Interim Results | Rev £3.7m (24H1 £7.1m), Adj. EBITDA loss £2.3m (£0.1m). Cash £0.6m | AMBER/RED (Graham) Getting out of net debt at least temporarily as a consequence of a large deal with Siemens Healthineers. Could it be a sign of things to come? |
Vianet (LON:VNET) (£30m) | TU | PW. FY25 rev. c£15.7m (FY24 £15.2m), EBITA c£3.6m (FY24 £3.5m). | |
Poolbeg Pharma (LON:POLB) (£26m) | Extension to PUSU Deadline | Positive discussions and due diligence continue re: takeover.. | |
Gusbourne (LON:GUS) (£23m) | TU | Net rev +1%, FY adj. EBITDA loss is expected to be around £0.7m, unchanged on the prior year. Net debt £22.6m. | |
Eenergy (LON:EAAS) (£16m) | TU | Rev +88% to £27.1m Adj. EBITDA £0.4m (-£3.6m). Net cash £2.3m. Significantly improved EBITDA and cash generation in FY2025. | |
Empresaria (LON:EMR) (£13m) | TU | Adj PBT In line. NFI down 6% CC (down 12% reported to £50.4m). Net debt increased to £15.3m (FY23 £10.8m). | |
Merit (LON:MRIT) (£5m) | Recommended cancellation of listing | Expected cancellation 5th March. |
Graham's Section
Property Franchise (LON:TPFG)
Unch. at 410p (£261m) - FY24 Trading Update - Graham - GREEN
We have an in line full-year trading update from “the UK’s largest multi-brand property franchisor”.
As it has now merged with Belvoir (BLV), there is revenue growth of 146%, bringing the total to £67m.
Just over half of total revenue is considered to be “recurring”.
The merger took place in March 2024, with people from TPFG keeping majority control of the combined group.
Franchising: the group now includes 15 brands and manages 153,000 rental properties.
On a like-for-like basis, the management service fees charged to franchisees increased 11% during the year.
Hybrid offering Ewemove saw year-on-year revenue growth of 17%.
Financial Services: a big point of the Belvoir merger was to bring in financial services revenue and this is now £19m for the year.
Licensing: this is a new division after the acquisition of GPEA which included both Fine and Country and the Guild of Property Professionals. Revenues of £7m were generated since acquisition in June 2024.
Outlook
FY25 has started with “strong momentum”. The outlook statement focuses on lettings and financial services:
We anticipate the lettings business to continue to grow in 2025, with the upcoming Renters Reform Bill expected to provide an additional opportunity for the Group, given the tough compliance requirements, to convert more landlords to the managed property model.
We have seen strong demand in January within our financial services business as customers continue to enjoy more affordable rates. The combination of a strong sales pipeline which has increased by 71% to £39.4m (2023: £23.1m) and current mortgage rates give us confidence in achieving a positive H1. H2 will be influenced by the anticipated interest rate cuts.
Graham’s view
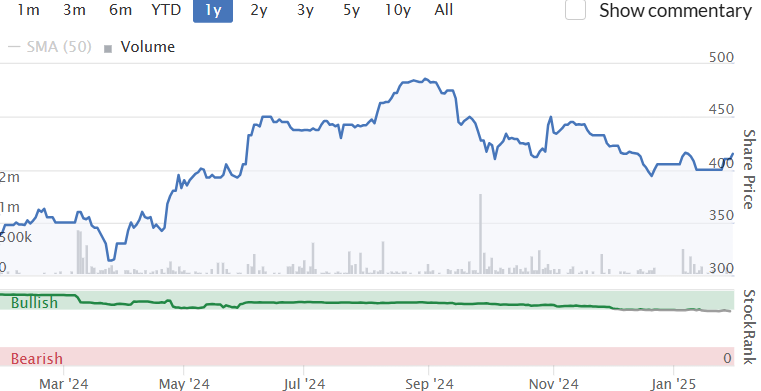
I tend to be GREEN on this one. The last time was at 465p in August 2024, when I said that the market cap was “starting to price in the company’s excellent prospects”.
The high for the year was seen shortly afterwards:
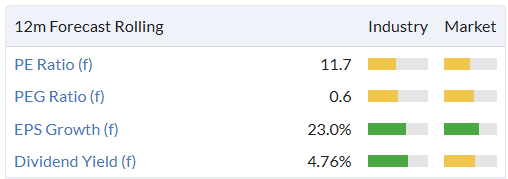
Now at 410p nearly six months later, the valuation has cooled down a little:
A few quick points before I conclude this section:
Sales vs. Lettings: Sales are currently outperforming Lettings (as measured by like-for-like management service fees), but the attraction of Lettings is that they anchor performance even when Sales are very poor, as happened in 2023.
Debt: the company is now carrying £9.1m of net debt. This does not concern me in the context of an adj. PBT forecast of £22m for 2024, rising to £30.1m for 2025 (estimates courtesy of Singers). There shouldn't be any problems paying off this debt. Indeed, it wouldn't surprise me if the company remains on the lookout for more acquisitions.
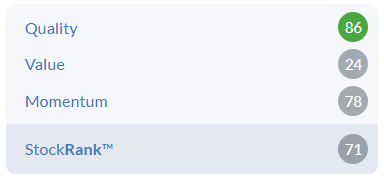
In summary: I remain a big fan of this one and am comfortable with the valuation. I acknowledge it’s not priced at bargain levels, given the sector. But considering its underlying quality, I think it’s still attractive:
Mulberry (LON:MUL)
Up 2.5% to 100p (£70m) - Trading Update - Graham - AMBER/RED
This handbag maker has had a difficult few years. As we reported here in November, the most recent drama concerned the attempt by Frasers to take it out at 130p and then 150p, but this was not entertained by Mulberry’s Singaporean owners.
The company raised £10m in fresh equity last year, an amount that was smaller than its underlying pre-tax loss in H1.
Today we have a triple-barreled announcement.
Strategy Update
The new CEO and the Board are focusing on three priorities: simplification (includes refocus on the UK at the expense of China), brand refresh (as a British lifestyle brand with a new creative team), and finally customer connection (customer insights, personalisation, etc.)
On the cost front, there is a “forensic spending review” as the company seeks to cut operating costs by about 25%. It is amazing how spending at luxury companies can spiral out of control - I’ve seen it at Burberry before (disclosure: I have a long position in BRBY).
2. Appointment of CFO
It’s good to see Mulberry solve this problem quickly, as the departure of the previous FD was announced only last week.
3. Trading Update
Trading over the festive period was “satisfactory”:
In line with the Board's expectations, Group revenue for the period declined 18.3% (-17.1% on constant exchange rates "CER") versus the same period in the prior year, as a result of the continuing challenging macro-economic environment…
The Company continued to take actions to manage costs and inventories during the period to ensure they aligned with revenues.
FY March 2025 will be H2-weighted, but I don’t think anyone is expecting much from these results.
Estimates: Peel Hunt’s estimates can be seen on the StockReport but I don’t think they are worth much given the volatility of MUL’s performance right now.
Graham’s view: I’m going to stick with my AMBER/RED stance.
As it is a very small player in the luxury space, I’ve been worried about MUL, thinking that it might be too subscale to survive.
During this generalised slowdown in luxury spending, even the much bigger BRBY is loss-making and in need of simplification and cost reduction.
If BRBY needs that, then MUL definitely needs it, as it doesn’t have the economies of scale and purchasing power enjoyed by its larger rivals. It simply can't afford to be inefficient. So it is surely doing the right thing by simplifying and going back to basics.
Net debt in November was £16m, with less than £6m of available liquidity.
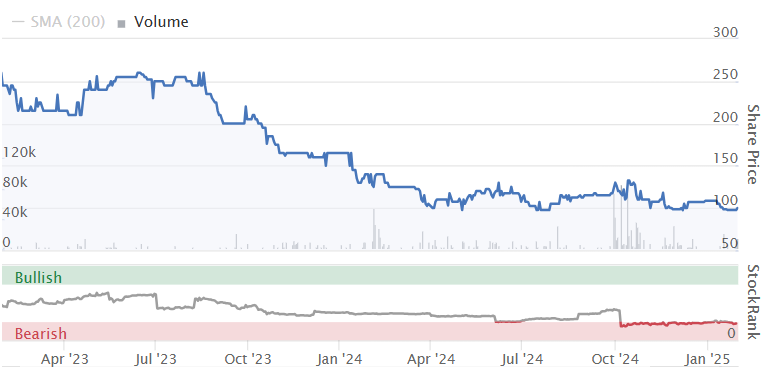
Normally I would be RED on a company in that position, and perhaps I should be fully RED on this, but I think there is still a chance that MUL can turn things around. Its rich owners (Frasers and the Singaporean billionaires) would surely be interested to bail it out if it gets into difficulty, although of course it's hard to say what effect this might have on smaller shareholders.
I may need to downgrade my stance on this further if there are no green shoots by the time of the full-year results.
Fevertree Drinks (LON:FEVR)
Up 21% to 797.5p (£932m) - US Strategic Partnership - Graham - AMBER/GREEN
This stock gave us an exciting deal announcement with drinks giant Molson Coors ($TAP) this morning
Under an exclusive license agreement, Colson Moors will get involved in the distribution of Fever-Tree, and in supply chain, procurement and the onshoring of US-based production.
Not only that, it’s injecting £71m into FEVR in fresh equity, at a price of 654.2p.
And in a really classy move, FEVR is sending that money straight back to shareholders with a £71m buyback.
It reported a cash balance of £66m as of June 2024, so I guess it doesn’t really need that surplus cash.
Molson Coors will have consented to the buyback. In effect, they are buying out a portion of the shareholder base, making no change to the FEVR’s balance sheet.
It does mean that FEVR will have sold shares at 654.2p and then bought shares at a higher price, given the share price movement we’ve had this morning. So there will be some dilution left over when all is said and done, but it shouldn’t be too large.
In a very confident statement, FEVR say they “will consider the opportunity for further shareholder returns beyond this initial buyback programme”, as the agreement with Molson Coors is expected to result in “enhanced cash generation”.
Comment by FEVR’s CEO:
"Today's announcement marks a transformational step for the Fever-Tree brand in the US. Thanks to the superb work of our US team, we have seen Fever-Tree become the number one brand in both the tonic and ginger beer categories, a remarkable achievement which has redefined the US mixer category amongst consumers and customers alike…
With a national network providing significant scale and muscle, alongside its proven track record, supply chain expertise and clearly stated strategic desire to drive the future of their business beyond beer, Molson Coors are the ideal long-term partner to take the Fever-Tree brand to the next level across the US.
Trading update: adjusted EBITDA for FY Dec 2024 is expected to see a strong uplift, in line with expectations.
The financial highlights illustrate that the US is where most of the growth is:
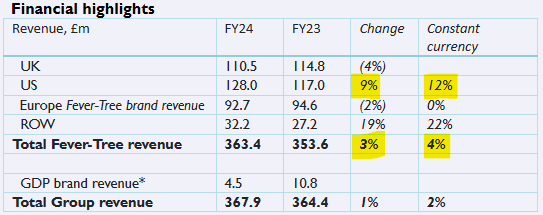
Outlook: the partnership with Molson Coors will “drive a step change in the quality of earnings” over the medium term.
2025 guidance: low single digit revenue growth, and a short-term EBITDA impact from the US transition.
2026: double digit revenue and EBITDA growth.
Then a sustained uplift in revenue and EBITDA growth.
Graham’s view
Roland covered this in detail in September, taking a neutral stance at 784p.
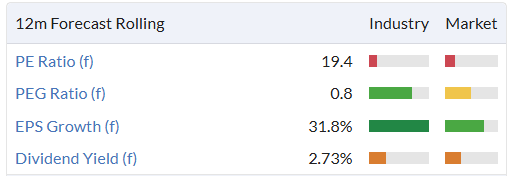
The share price is only a little higher today, but now have a giant of the US drinks industry getting involved as a shareholder and helping the company to take advantage of its US growth opportunity.
Perhaps I’m getting swept up in the hype, but I feel obliged to upgrade my stance here.
Yes, it’s a little expensive in P/E terms but drinks companies are worth paying up for. FEVR is not just a successful drinks company, but it operates in a niche (mixers) where it’s possible to lock up a very high market share for many years, as Schweppes did. In my view this makes it more attractive than the average, successful drinks business. With Molson Coors on board, I think the excitement is justified.
Saga (LON:SAGA)
Up 5% to 120.1p (£172m) - Trading Update - Graham - RED
It’s a positive update: underlying PBT for FY Jan 2025 is now expected to be ahead of previous guidance and marginally higher than last year.
Underlying PBT last year was £38m, but the unadjusted pre-tax loss was £129m.
All divisions seem to have had a good year with the exception of Insurance Broking, although even that division was in line with guidance.
Insurance Underwriting almost achieved a profitable underwriting result, with a combined operating ratio of just over 100% (this needs to get below 100% to be profitable). The division is to be sold in Q2 for net proceeds of £43m.
Available cash is c. £60-70m, which excludes a £50m undrawn RCF and £10m from the Chairman/largest shareholder Sir Roger de Haan.
Net debt is “slightly lower” than the £615m figure reported for July 2024.
Refinancing: in a separate announcement, Saga announces the full refinancing of its corporate debt.
The new facilities “materially enhance the Group's liquidity position, significantly increase covenant headroom and provide funding certainty”.
They include a £335m term loan, plus another £100m term loan to be used for specific purposes, and a £50m RCF.
Saga’s overall blended interest rate after this deal is 7.6%, which strikes me as a nice outcome for the company given its risk levels.
Outlook: Cruise bookings are slightly higher than where they were last year, as measured by load factors. Travel bookings are 10% higher.
Graham’s view: this share doesn’t appeal to me at all. I may have said this before, but I don’t understand why these different types of businesses should hang together in the same corporate structure. The disposals and partnership agreements announced in recent times are therefore a step in the right direction, in my view.
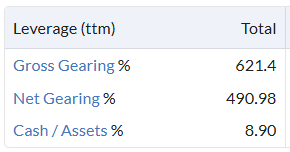
I especially don’t understand why it needs to use so much leverage. Borrowing to fund cruise ships is understandable, in a sense, but still risky. But why leverage up every other part of the business, too?
The recent interim balance sheet showed the company having equity of £116m but the number becomes deeply negative after you subtract intangibles.
The refinancing announced today and disposals are good news but I continue to view this stock as a disaster waiting to happen. Of course high rewards are possible for those who take high risk.
I’m on the fence between RED and AMBER/RED, but I’m going with AMBER/RED on the basis of the interim balance sheet.
Some leverage numbers from the StockReport:
Kromek (LON:KMK)
Up 29% to 6.8p (£44m) - Multi-year Agreements with Siements Healthineers - Graham - AMBER/RED
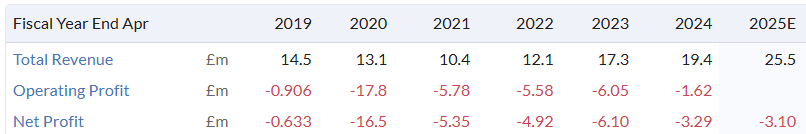
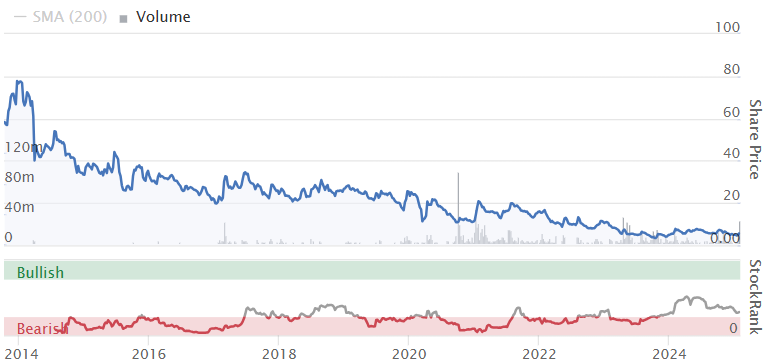
After many years of losses, I admit that I gave up on the potential for this one to come good:
Kromek is “a leading developer of radiation and bio-detection technology solutions for the advanced imaging and CBRN detection segments”.
CBRN refers to chemical, biological, radiological and nuclear.
The company has a year-end in April. Today it announces both interim results and a new agreement with Siemens Healthineers.
The interim results are more of the same: another EBITDA loss, bigger than last year’s.
However, the agreement with Siemens is exciting:
Kromek has signed agreements with Siemens Medical Solutions USA, Inc. ("Siemens Healthineers") to enable the production of cadmium zinc telluride ("CZT") detectors for single photon emission computed tomography ("SPECT") application…
I don’t pretend to know what this means but the financial result is that $37.5m will be paid to Kromek in cash in four installments over four years. The first installment is $25m and will be paid in the current financial year.
It’s non-exclusive: Kromek will be able to supply other customers.
New forecasts: Cavendish have issued new forecasts which see the company making an adj. PBT of £4.9m in the current year (FY April 2025), although this is expected to drop back substantially in subsequent years: only £2.1m in FY April 2026, and £1.0m in FY April 2027.
Graham’s view
It looks to me as if Kromek will need to find more deals of this magnitude, on the basis of the forecasts published today.
However, now that they have this one under their belt, maybe it will be easier to find the next?
One of the best aspects of the announcement is that the company is expected to at least temporarily get out of net debt, and have a small year-end net cash position.
Accordingly I’m giving this an upgrade to AMBER/RED.
Ricardo (LON:RCDO)
Down 23% to 270p (£168m) - Trading Update - Graham - AMBER/RED
Roland covered this one most recently - see his January article.
RCDO is exiting defence and focusing on energy/the environment.
Today’s H1 update starts off fine in terms of continuing operations, with order intake up 10% and the order book up 2%. Revenue rose 1%.
Unfortunately, there is some bad news from the now-key “Energy and Environment” segment:
Energy and Environment (EE) delivered strong order growth driven by multi-year contract wins within air quality and policy, but phasing of orders impacted H1 revenue and profit, due to global elections, the delay in spend ramping for UK water asset management plan (AMP) cycles and global macro uncertainties. We expect good profit growth in the second half, with the impact of delays in orders reducing as we go into the next financial year.
There was also a delay in “Rail” due to the California wildfires. The other segments seemed to perform as expected.
Net debt: £18.5m, much lower than before thanks to the Defense disposal, but before spending £51m on the infrastructure advisory firm E3.
Outlook is a fully-fledged profit warning.
Due to the delay in orders identified above we will be below consensus expectation for FY 24/25. We still expect to see good Group organic underlying profit growth for the year, in addition to the profit from the Acquisition of E3 Advisory. H2 will show good profit growth in EE, however due to the order delays described above, will be broadly flat for the full year…
I must say that I dislike the phrasing used. H2 will show “good profit growth in EE” - I think they mean that H2 will be better than H1. But then the full-year result will be flat for that segment.
Estimates: Zeus has an adj. PBT forecast for the current year of £12.4m. Panmure are similar at £12.9m, rising to £15.5m the following year and then £21.8m the year after that
EPS forecasts have been cut by 32% for this year and 48% for next year.
Graham’s view
I’m not sure if I should downgrade this to AMBER/RED. It’s a debt-ridden consultancy group that’s suffering some complications in its key division, after it sold off its most profitable business. Maybe that’s priced in now at the current market cap?
On balance I think I will downgrade it, as the large net debt figure (£60m+) produces an enterprise value of about £230m. Against the pre-tax profit forecasts mentioned above, that seems to me a high price to pay.
Even if we get a recovery in profits by 2026, this doesn't strike me as an obvious bargain at this level. So I think a moderately negative stance is justified.
Mark's Section
Somero Enterprises (LON:SOM)
Down 6% to 285p - Trading Update - Mark - AMBER
A stronger H2 here sees revenue in line:
It expects the Company to report 2024 revenue of US$ 109.2m, in line with previous guidance and market expectations, with H2 revenues improving by 10.8% to $57.4m
As is often the case here, it is North America doing the heavy lifting:
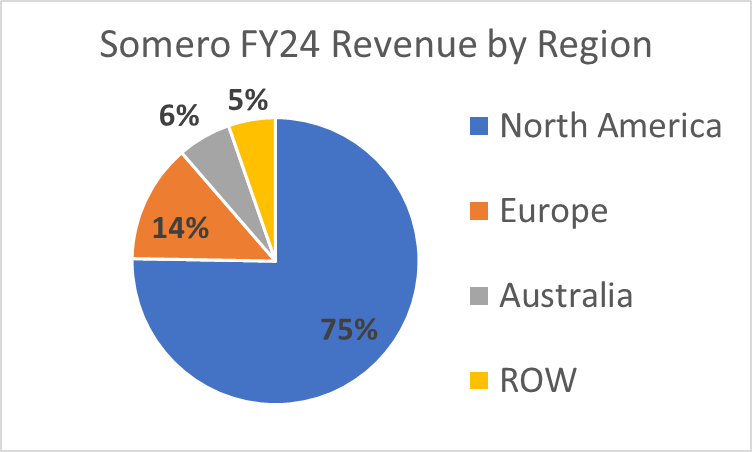
We’ll have to wait for the results on 11th March to see the breakdown by machine, but my expectation is that boomed screeds will again be the bulk of the sales.
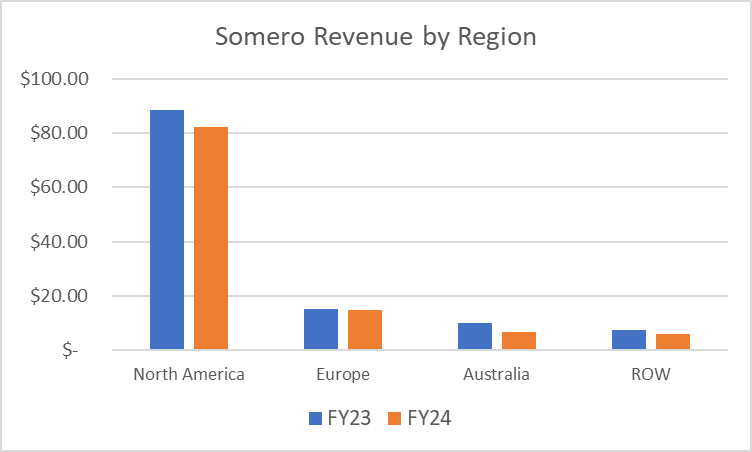
All regions showed a decline versus 2023, although it was slight in Europe:
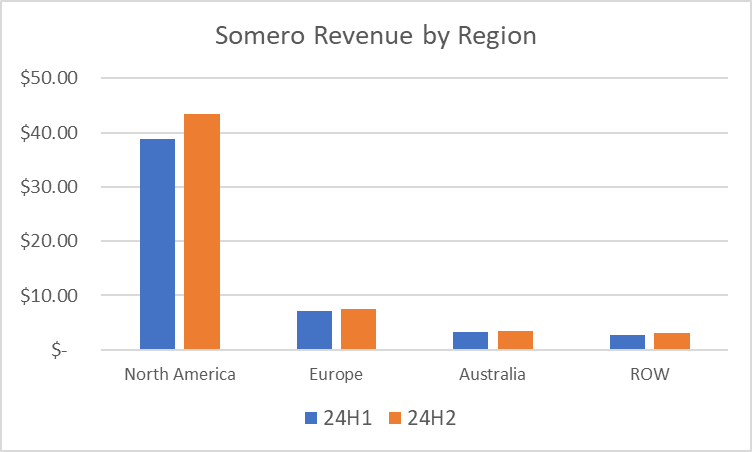
But perhaps more importantly, all regions saw growth in revenue versus H1:
The result is:
Excluding separation-related expenses, the Board expects the Company to report 2024 adjusted EBITDA of US$ 29.1m. The year-end cash position is anticipated to be US$ 29.5m reflecting lower net working capital investment. These estimates remain subject to any audit adjustments.
However, Cavendish describes this as “profit broadly in line” as their previous EBITDA forecast was $30m. They have taken 6% off their EPS forecasts, to give 35.5c for FY24E. The good news is that the cash balance was above their previous $27.1m forecast, but this hasn’t been enough to maintain the dividend forecast, which has been cut by 13%.
The outlook is better, and the company say:
the Board expects trading in 2025 to moderately improve on 2024 with commensurate profits and cash generation.
Cavendish translate this into 4% Revenue growth, flat EPS and a 22.6c dividend, for a 6% yield. These look conservative, given the momentum in North America in H2. However, as usual, it comes down to demand for warehousing and data centres in the US and concrete availability, which can be hard to predict. While the company has an enviable market share in North America, the lack of progress in Europe leaves the company mainly exposed to the US market. The slow pace of development of features demanded in Europe, such as battery power or being able to fit on standard European trailers, has allowed competitors to gain a foothold here. They still have great brand recognition, but the growth that many expected in Europe to match the US may now not be possible.
Mark’s view
Graham rated this AMBER in December. Since then, we’ve had this minor profit warning taking 6% off forecasts, but the share price has dropped 12%, perhaps making them look slightly better value. The newly introduced 2025 forecasts are not exactly inspiring, but they do look conservative, given the momentum in the US. I am slightly more positive than Graham, as I think there is always a chance that some of their innovations (with R&D all expensed) could start to gain traction. Also, with Jack Cooney retiring, this could be a good time for any interested parties to make an offer for what would typically be a cheap rating for a US company. However, without seeing further details of how 2025 trading is progressing, I am not quite ready to change the AMBER rating.
Next 15 (LON:NFG)
Up 1% to 347p - Trading Update - Mark - AMBER
This is a company that investors were talking about last year following a precipitous fall on the loss of a major contract for their “growth consultancy” arm. This made a major dent in their previously growing revenue:
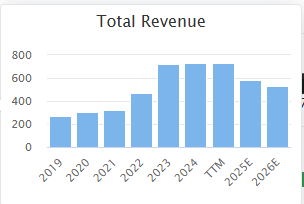
The irony of a “growth consultancy” being unable to grow is not lost on me! But did leave them on a very low P/E for a mid-cap stock:
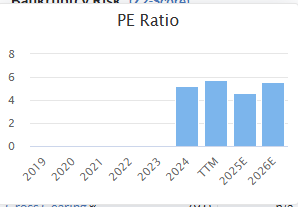
This piqued my interest enough to write up the company as a StockPitch. I concluded:
Cautious investors may wish to wait until there are signs of momentum reversing in both the financial results and share price before considering this further.
Sadly, this uptick has yet to arrive, as today they say:
Profits are expected to be at the bottom of analyst expectations
Helpfully, they quantify this:
Analyst expectations are currently £107m to £112m for adjusted operating profit
The problem is that this company has huge adjustments. The bulk of them are acquisition-related employee payments, restructuring and amortisation of acquired intangibles. It may be standard practice to exclude these, but given their acquisitive nature, I think it is hard to argue that the majority of these aren’t genuine ongoing costs to the business.
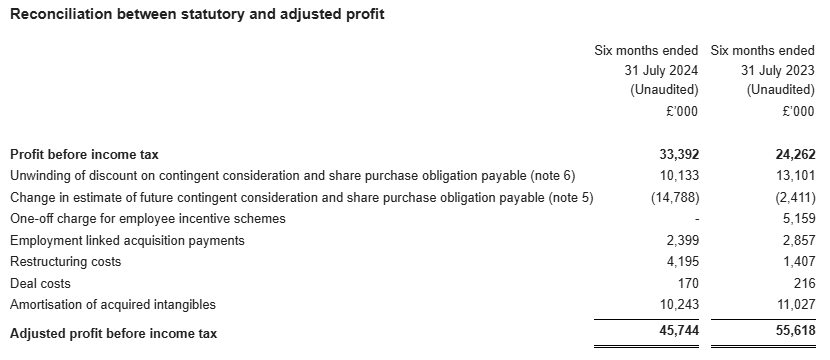
Looks like there will be even more adjustments than usual this year:
Over the last six months the Group has continued to review operations to focus on meeting customer needs while driving efficiency that can fund further investment. Restructuring across the Group will deliver net annualised savings of approximately £40m, of which £14m relates to employees previously engaged within Mach49. Of the residual £26m saving, approximately £9m will have been realised in the current financial year. As a result of this work, the Group expects to post exceptional redundancy costs of approximately £15m in its results for the year to 31 January 2025.
That’s £11m of redundancy costs in H2 alone. The CFO may be among those being rationalised:
The Group also announced its CFO, Peter Harris has informed the Board of his intention to step down from the Board
The good news is that they should save £40m a year going forward. It may be this that means the share price hasn’t reacted negatively to the trading update today.
In terms of outlook, they say:
The Group has maintained, what it believes is, an appropriately cautious outlook for the new financial year.
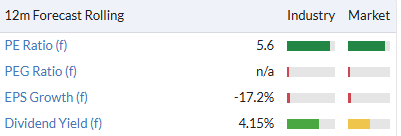
This suggests that they are confident of meeting future expectations, at least on an adjusted basis. Which will make them look cheap:
Mark’s view
It is tempting to call the bottom here, but considerable uncertainty remains for me. This is highlighted by the CFO leaving. It is common for incoming management to “kitchen-sink” their first set of results and hence make subsequent results look better. Given the nature of the business, there is considerable scope for this to happen (although they will undoubtedly adjust these out!). On fundamentals, I think the balance of probabilities favours undervaluation at the moment. However, I’d want to see at least one period of in-line trading before reconsidering the AMBER rating.
Strix (LON:KETL)
Up 1% to 47p - Trading Update - Mark - AMBER
This seems a confusing statement:
Strix is pleased to confirm that it will report adjusted profit before tax for FY24 ahead of market consensus (as at close on 29 January 2025) and comfortably within the previously announced range of £18m to £19m (on a constant currency basis ("CER")).
In November, they said:
As a result of the above, Strix now expects to report adjusted profit before tax for FY24 in the range of £18m to £19m (on a constant currency basis).
But this was a profit warning, with broker Zeus reducing their estimates at the time from £23.6m to £17.5m. The reason for the disparity was given as:
Zeus factor in a c. £500k impact from currency as the statement indicates ccy pre tax profit will be in the range of £18.0m to £19.0m.
Now Zeus say:
We update forecasts to reflect the improved Q4 trading which leads to a 5% increase in FY24 adj. PBT to £18.4m (prev. £17.5m) and a £4.6m improvement in net debt (excl. leases) to £68.0m.
So this is good news, but not in the wider context of previous downgrades. Nor is it clear what part currency moves have played in these changes. Today, Zeus also upgraded FY25 estimates but downgraded FY26 on lower growth forecast. It is no wonder the share price reaction has been mixed this morning!
One of the issues here has been the debt levels, which led them to cancel their interim dividend In November, they said:
Strix's debt position has remained a priority for the management team, with latest reported net debt leverage at c.2x. Reflecting management's confidence in the underlying business, it remains the intention to reinstate the FY24 final dividend for payment in 2025.
And now:
The net debt position remains a key priority for the management team. Ongoing cash conservation actions have resulted in strong cash generation in the period, allowing the Group to maintain a year-end net debt leverage of below 2x.
2x is an important level as below this they pay a lower interest rate. Given the debt levels, EV/EBITDA is probably the best measure here. At 4.9x on a forward basis, it looks reasonable but not outstanding value. However compares well to the rest of the Machinery, Equipment and Components sector. Only Renold looks cheaper, but the figures exclude the significant Pension Deficit at Renold, which may make Strix (LON:KETL) the cheapest stock in the sector.
Mark’s View
Roland rated this AMBER/RED in November. However, that now looks a little bit harsh as a strong Q4 has swung momentum back their way, and debt is reducing. They are now likely the cheapest stock in the Machinery, Equipment and Components Sector. However, some doubts remain as to whether the weakness in kettle controls is simply market conditions or represents increased competition, and we are likely to see prospects here permanently downgraded. So, that cheap rating may be justified. It's an AMBER for me until we can get a clearer picture of whether kettle controls can return to growth again.
Camellia (LON:CAM)
Up 1% to 4800p - Trading Update - Mark (I hold) - GREEN/AMBER
A short but positive statement here:
Trading is now expected to be ahead of previously communicated market expectations. Adjusted losses for 2024 are forecast in the range of £4-5 million, down from the previous £7-9 million.
In October, they said:
…adjusted losses for 2024 are now forecast in the range of £7-9 million from a previous range of £10-12 million. This improvement is primarily the result of an improved outlook for our Indian operations.
So that’s quite a significant shift over the last four months of the year. The reasons given are:
…better than forecast results in Eastern Produce Kenya and in its Indian companies and increased interest income and foreign exchange benefits following the successful sale of BF&M.
It shows that agriculture is a cyclical business and that investors should not get too elated in the good years, nor too pessimistic in the bad. However, the company is still loss-making, so it shouldn’t pat itself on the back too firmly. What it does, though, is slow the decline in book value. When the company trades on 0.4x TBV, this is important:
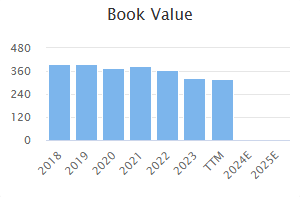
Following recent sales, a significant portion of the assets here are cash, and the ongoing share buyback at these levels enhances value. However, I would have preferred a much larger buyback or tender offer rather than them retaining capital to invest in further agricultural businesses for which we have no news yet.
Mark’s view
While it is nice to have an improvement in trading, they are still reporting a trading loss. These things tend to be cyclical, and it is likely that the assets will be productive again at some point. Hence, the main attraction for now is the big discount to tangible book value. Recent asset sales have demonstrated that these do have real value. It is just difficult to predict when the agricultural cycle will turn in their favour. However, today’s announcement could be an early sign of positive trends in their commodities. I don’t see any reason to change the AMBER/GREEN rating from the previous update.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
I hold and got paid a juicy dividend today ,so looking forward to any upside
Which stock, might that be?
Sorry Rusty this was supposed to be a reply, but must have just hit the comments box. Smiths News (LON:SNWS)
It wa thoughts on the comments about smiths news stealing market share…potentially from rival
LSL Property Services (LON:LSL) (market cap = £300m)
I've bought heavily in the last year and I thought today's update was excellent. It completely smashed my own forecasts and I remain cautiously optimistic for the year ahead.
Some very brief thoughts:
1 - Financial Services
New Lending market share up to 11.6%, an upward trend over the last 2 years.
For context the latest Mortgage Advice Bureau (Holdings) (LON:MAB1) (market cap =£400m) market share equivalent figure was 8.2%, albeit this was reported in their half-year report and they operate somewhat differently to LSL (for now.)
2 - Surveying & Valuation Division
Last year the group decided to retain staff so that they were prepared when the market returned to normal.
It looks like that decision is now bearing fruit, with Underlying Operating Profit Margins of 23% compared with 8% last year.
3 - Group Operating Profit %
16% for the year, implying underlying operating profit of £27.7m
For context these figures were 7.1% and £10.3m in 2023.
4 - Director Buy
Finally, a director purchase today, the first one in a year.
It wasn't that large (£25k), but it's better than no purchases at all.
Fingers crossed more directors buy soon.
£SLS
cheers abtan - info as useful as always.
Its a nice refreshing change to see a company that exactly the same number of sahres in issue as 11 years ago - now if only they had been buying back 5% of the shares every year for the last 11 years !! the shareprice may have actually gone somewhere had they done that ?
Many thanks to Graham and the team for such an in-depth report today.
Anyone else still in Cavendish Financial (LON:CAV) ?
So dull watching it tick down constantly but it just seems really cheap and if the doom and gloom on uk small caps passes, as it surely will surely they are well placed to benefit from this.
not sure if they are more of a lifestyle company than a real business, 10% down and considering buying something a bit more interesting
Yes I still hold Cavendish Financial (LON:CAV. Currently I’m down7% after averaging up! . Don’t know why the share has turned down recently. Unless it’s because of bad news leaking Cavendish Financial (LON:CAV) looks very cheap now. Graham gave it a green rating at 11.5p (up 7% that day) when analysing their most recent Results. Note though the bit about it being run for the benefit of the Managers. As the leading AIM broker, the AIM index waking up and some IPOs at long last could see the share rocket. I’ll be holding until the next update. Here’s the link to Graham’s commentary:-
https://www.stockopedia.com/co...
Fevertree Drinks (LON:FEVR) directors buying in the market today. Follow them?
- Domenic De Lorenzo, Non-Executive Chairman, purchased 8,872 ordinary shares in the Company at a price of £7.85 per share;
- Andy Branchflower, Chief Financial Officer and Executive Director, purchased 31,688 ordinary shares in the Company at a price of £7.85 per share; and
- Kevin Havelock, Senior Independent Non-Executive Director, purchased 122,492 ordinary shares in the Company at an average price of £7.71 per share.
I hold- showing a loss at the moment though better than it was. I bought after the Britvic bid expecting something to happen re FEVR. Taken time, and not sure anything will happen re a takeover for 3-4 years. But this announcement today does resolve expanding in the USA without financial pain.
Agree 100% Camtab.
Boards like share buy backs because they flatter EPS. By doing nothing. As an investor, I don't buy shares in a company for their ability to buy back their own stock. More often than not, they buy at the wrong price and end up losing shareholders money.
Many, many years ago I worked on one of first buybacks - for SWEB (a regional electricity company in the South West). The Treasurer was very happy with the numbers... and this was over 30 years ago! Now unfortunately they are very common.
If they have excess cash, pay a divi or a special div. At least that puts money in our pockets. Take EKF Diagnostics Holdings (LON:EKF) this week. Said that they may do a share backback, or even worse - another acquisition (which they should be completely barred from doing because they have p!ssed shareholder money up the wall over the years on ill-timed, overpaid acquisitions). Just reinstate the dividend!
A Stirling effort today Graham & Mark, a mountain of releases, Many Thanks.
As another alternative view on the future of this thread...
In any on day it could 60% or so of the posts are nothing to do with the shares discussed. If anything the percentage now is greater than ever before.
I don't know the reason for this but there is probably an argument for just starting a daily thread with summary box (zero comment) where everyone then posts their thoughts.
If Stocko wish to write reports then they might want to follow demand in the thread.
At the moment, these reports are splendid for building a library of reports for subsequent searches. This might be the intention. But it seems to be proving difficult to please everyone who wants detailed/non detailed summary.
I just don't agree that buying back your shares is tantamount to returning cash to shareholders. I find it so frustrating to see management across the board doing this. Surely we can find investment opportunities and if not well just return the money to the shareholders in the form of a special dividend.
Special dividends are fine if you hold the shares in a tax-remote vehicle like an ISA or SIPP, but a major tax bill for everyone else, which is why they can be unpopular if too large.
If the shares are bought back and cancelled, then for a constant P/E ratio you should get a commensurate rise in the P to match the increased E (because E is per share, and there are fewer shares).
Then at least you can time your disposal of any shares to minimise your tax liability should you wish to cash out, and CGT rates are generally lower as well.
Surely all but the wealthiest minority can shelter their investments in an ISA or SIPP without too much trouble? Lord Lee became the first ISA millionaire many years ago when the annual allowance was a lot lower. He might be more skilled at stock selection than most , but at £20,000 per year (or £40,000 a couple) it is easy to build a portfolio worth several hundred thousand in not that many years within an ISA. By reinvesting all the income too the total compounds nicely.
Perhaps I am underestimating the net worth of Stocko subscribers but I would think that most of us wouldn't need to utilise these allowances for too many years before having their full stock market portfolio free of tax. Or am I mistaken?
I'm afraid Stocko subscribers are neither here nor there.
If you were to look at the shareholder register of a listed company you can broadly tell which shares are held within in SIPPs/ISAs because they will be in nominee accounts. It is far from all, and overseas investors can't use ISAs/SIPPs either.
Most importantly - you can bet that management won't be able to shelter all of their share awards in ISAs and SIPPs....there are limits to annual pension contributions.
Then throw in property sale proceeds and inheritances - it can take many years to get those lumps of cash into your ISA. You don't have to be a billionaire to get hit by income/dividend tax.
Sparkler, I agree with you here as each year I Bed and ISA across from my trading account and see the time coming when all of my shares will be in my (and Christine's) ISA. If anybody should be shamed it is the Chancellor who could yet reduce the tax allowance on dividends earned from the paltry £500 further.
Interesting news on Kromek - (LON:KMK) I hold. It's a bit of a Plexus (LON:POS) moment -see archives. Agree it will need more to justify any major price rise but a huge step forward IMO. The deal is as much as the market cap - before opening. Wonder if it doesn't become a bid target.
Tein I just spotted your reply on Tuesday concerning Serica Energy (LON:SQZ)
After reading your comments I listened to the Q and A part again and I was like you impressed that Serica is playing a major role in talking to Government about the importance of North Sea Oil to the UK going forward.
It is reported in the Media today that a certain Scottish judge doesn't care much for the importance of North Sea Oil, basically placing two undeveloped oilfields on ice.
Just Googled (sorry MindSeeked) "blackouts in the UK". Not sure why I did that :(
Hi Portugull, as the Two Paul's discussed in last week's Vox weekly review, HM Gov always arrive at the right policy decision once all other options have been exhausted.
Any views regarding the tender offer for XLMedia PLC
I don't know, I pulled out selling the last shares last March at 13.8 pence thus saving my bacon but I do know that when I took up the Tender Offer by RockRose Energy the share price subsequently shot up, netting the company a healthy profit from its own shares. Anything can happen on the stock market and experience can only warn.
EXCLUSIVE: Major blow to Menzies as NewsTeam Group starts delivering papers from Smiths News (LON:SNWS) in Menzies areas.
Millions of pounds in retail sales will pass through Smiths News rather than Menzies
https://www.betterretailing.co...
Still no RNS though?
Smiths News (LON:SNWS) looks too cheap IMHO. (I hold).
The story was 'what can they do with their overnight delivery network' and kicking a main competitor in Menzies this could be good for them. Great intel and a good read - tks. Sorry should just have ticked lol.
While I appreciate the work required to produce these in-depth analyses covering TUs and results each morning, I think that SMR would be more useful and possibly attract more readers -- and comments! -- if the format was changed to cover more companies with shorter write-ups.
For example, Graham writes up Property Franchise (LON:TPFG) in much detail, but the announcement didn't move the price and for me, as a former owner, all I needed to know was in the summary he later posted in the summary table:
"Reassuring update with few obvious obstacles to another good performance in 2025. High-quality franchisor at reasonable valuation."
That's sufficient for me So let's move on to the next in the list.
Of course, when there's a company that hasn't been covered before, or it makes some big market-moving announcement, a full write-up is justified.
Why change? Well, for me at least its frustrating to see 50-odd companies flagged as making announcments today, but only a handful will actually be analysed, and only Somero is of much interest to me.
Meanwhile, if I want to learn a bit more about the announcements made by Serco, Ricardo, BT, Hikma, Mulberry, discoverIE, Saga, XP Power, etc -- most of which have been covered in the SMR in the past, some frequently -- I m not going to find it on the SMR today.
I appreciate most of the value of the Stocko subscription lies in the data and so effectively the SMR is bundled in for free and probably doesnt have the resources to do more.
But the coverage I'm seeing at the moment seems haphazard and frustratingly inconsistent, particularly when writers stray beyond the traditional UK small-cap universe and try to cover megacaps like NVIDIA (NSQ:NVDA) or Novo Nordisk A/S (CPH:NOVO B).
Just my thoughts.
I for one could survive without the American glamour/meme stock coverage, tho it seems to have lessened lately.
They are covered everywhere ad nauseum. UK stocks though, not many other places cover them like Stockopedia. The reports here have been the starting point for many shares that many here otherwise would not know about and have indeed become successful investments. Reading here about stocks that are literally a meme, that make the main evening news, that make the "top tips" on the motleyfool or yahoo front page or have 5 rockets and a diamond on wallstreetbets etc gives us zero edge.
Not to take anything away from the writers who I am sure we all agree do great work, but if time is an issue I think we can survive here without the glamour/meme stocks.
Just my two pence. Or two cents.
Please stop the constant negative comments about certain content of the SMR. It seems that some people take any opportunity to jump on a bandwagon with the purpose of putting certain people down. Certainly inappropriate today!
Not sure what you mean.
I've not put anyone down, quite the opposite I've even said the writers do great work which they do else I wouldn't be as keen for them to write about stocks that aren't covered elsewhere.
However if I have indeed offended anyone then I apologize It certainly wasn't intended. Not here to jump on any bandwagon or put anyone down.
Simply saying my preference for if/when time is an issue for the writers stick to what makes this place unique and gives us an investing edge over those who do not subscribe.
I think merbb was perhaps referring to Jeff in his post. I actually do find the current table summary format really useful as it gives me a very quick summary of the results/updates and anything which looks interesting, I can then delve much deeper myself.
Just my take on it, people might have their own take on things, but I don’t think it would be possible for the team to cover in depth the majority of announcements.
Following the theme, rather than responding directly to Jeff....
I don't think Stocko can ever hope to compete in providing rapid coverage after the opening bell - even institutions with teams of analysts struggle to provide full market coverage.
I tend to go to the LSE news feed and scan the updates myself. Sort by "Most Read" at 7.01am and then in each RNS you'll find that CTRL+"F" and "Outlook" tends to get you straight to the point quite efficiently.
As I've just done with Alfa Financial Software Holdings (LON:ALFA) , I do find perusing past in-depth updates at the single company level useful, if only to uncover issues more quickly that I can stumble upon them myself.
Even though small caps were only a tiny proportion of my portfolio, the SCVR comments section provided food for thought, and even the odd evening comment added welcome colour to an otherwise quite dry analytical endeavour.....
In that light I'm not a fan of moderators intervening unless they absolutely have to. The easily offended can easily scroll on. Let flags convey disapproval without demanding removal.
Rudeness is quite a subjective thing, and I refuse to believe that we have all grown so old and tedious that the school day isn't enhanced by a good fight in the playground.
How can you expect the team to analyse 50 companies in a day? They are working hard and maybe appreciate their efforts?
Not asking for 50, but the average is now around 6, of those about 4 are small caps. We were promised that small coverage, would be maintained but it has not been. With so many companies reporting at the moment, there is now large gaps in the coverage. I prefer more small cap coverage even if the reports are shorter.
While I appreciate the work required to produce these in-depth analyses covering TUs and results each morning, I think that SMR would be more useful and possibly attract more readers -- and comments! -- if the format was changed to cover more companies with shorter write-ups.
And to put another point of view, I'd like fewer write ups but in more detail. Stockopedia won't please everyone, no matter what they do.
Towards the end of PS's stint on the SCVR I felt the quality dropped off as the number of companies covered increased. Perhaps coincidentally the quality of the discussions section also fell markedly, some days there were virtually no stock discussions, in part because the commentary didn't provoke any (although it often provoked wildly off-topic discussions that gave a small minority of posters the opportunity to demonstrate that nature abhors a vacuum).
I find the new summary table very useful, it frequently flags ups stocks I'd missed on busy days, and is enough to identify what I'd be interested in, but I'll analyse what I want and in my own time. What is really useful to me as an investor is where there's a view expressed by one of the writers which forces me to reassess my own analysis.
If I was able to choose I'd like to see:
What PS did really well was educate and I felt it was sad that many posters clearly ignored that education in favour of treating him as a mere tipster. Where the daily report can add value is in that education piece - particularly explaining where things have changed and how we might have spotted this.
I think today's coverage is reasonably balanced - I'd have like to have seen LSL Property Services (LON:LSL) covered (up 12% at time of writing) as there's a really interesting turnaround in progress there (including franchising, which ought to pique Graham's interest!). But that's a personal preference.
As we say, it takes all sorts to make a market.
timarr
I fully agree.
This is what Cavendish put out in its Morning Note this morning --- free of charge to us punters-- on Somero Enterprises (LON:SOM), which is obviously a client, so they are obliged to write about them:
Somero Enterprises (SOM): CORP FY24 update – Improved 2H, profit broadly in line The FY24 trading update confirms a better second half for Somero, with recovery in US activity and the benefit of three recent new product launches. Adj EBITDA before separation expenses is expected to be broadly in line with previous guidance, while net cash at $29.5m is better than expected, due to lower working capital levels. We introduce new FY25 forecasts based on modest revenue growth of 4% resulting in EPS of 35.3¢, down 5.8%. We maintain our 485p target price, which we believe offers good upside to current attractive valuation, trading on a FY25 P/E of 10.5x and an appealing 6.0% dividend yield.
A Stocko writer familiar with the company could quickly write a short analysis of similar length, but more critical and without the inherent bias of a house broker and maybe quoting any initial opening price movement. A dozen of these before lunch is easily doable with two writers, I would have thought.
Later in the day, or even the next day, some in-depth commentary using the familiar long-form format with charts and pasted quotes from the announcement for those companies where something significant has changed and the writer has upgraded or downgraded the stockRank.
The aim should be to be more selective with the long-form analyses but cover more companies with short "quick fire" analyses.
That would reduce the workload on a busy news day while still allowing writers time to produce the in-depth commentary when they feel it is justified.
That would work for me!
I'm afraid it just doesn't work quite like that. To be "more critical, without the inherent bias" of the Cavendish statement you have to be very, very well informed indeed.
Behind that Cavendish short statement will be hours/days of work. There will be a very big spreadsheet (much larger than what they may publish as a one page summary of the financials in a note). They will have sat down with the company FD to make sure their modelling broadly agrees with his internal forecasting and cost expectations (such as the pending NI changes)
Without a model like that it is difficult read between the lines of a trading update and work out the implications of the current outlook statement for future years - i.e. whether earnings expectations should should be upgraded beyond the current period or not. It is these revisions to earnings expectations that drive most price movement.
There is simply no way any Stocko writer can maintain models like that for every company that reports each day. Professional buy-side analysts (i.e. the people at fund management and pension firms) will often borrow a broker's model as a starting point and enhance it to maintain their own internal view. Even then they probably don't maintain more than 20-30 models each.
I have worked with analysts and their models they are detailed, a 3 yr horizon, regularly tweaked to reflect qrtly results and changes in the business environment. The guys & gals at stockpedia do a great daily job, of sorting out the runners and their prospects. The subscribers comments are for most part are hugely insightful, generously sharing their experience. The one thing that would be helpful to me would be providing a commentary on why the stock ranks have moved.
Thank you to the stockpedia team you do a great job
In addition to an entertaining turn of phrase, PS often gave his view on where sales and profits might reasonably be expected to be compared to the official broker estimates. This involved calculated extrapolation and was very helpful IMHO.
We now have far more coverage but, I think, far less extrapolation.
Personally, I am not particularly bothered about coverage of larger companies, but I would greatly appreciate MORE CALCULATED EXTRAPOLATION.
Obviously all investment decisions are our own responsibility BUT it’s very interesting to read decent arguments as to why the market forecasts might well be well off the mark.
Hope this is helpful. All the best to our writers on their daily Herculean efforts.
Best wishes, Martin
Just adding a few thoughts mostly in addition to those covered by timarr.
The summary section is superb and so where it is used are the brief “Our View” summaries.
The write ups are consistently very good too and for me the “Green and Amber/Green” are the right length and detail. But is it worth writing in similar depth on the “Amber/Red and Red” shares? I read the “Green” updates carefully, but don’t bother with those rated as Red or Amber/Red. Just knowing that RED is their conclusion is enough and after that wouldn’t shorter summary on why suffice?
I also agree about not covering shares like NVIDIA (NSQ:NVDA) . For shares like that it’s easy to find analysis elsewhere, including for the big US shares on CNBC Channel 210 Freesat. Reducing the team workload removes some of the stress for them too.
Are people so quick to criticise aware of the time it takes to analyse shares even before the time it takes to write detailed analysis after that? The way they cover so much so fast is a big plus. Anything to reduce the pressure a bit reduces the risk of burnout. Paul Scott was at serious risk of that happening and is even more so now with his rush in to his new venture.
Finally on reader comments. Are too many now like this one and not on any of the shares updated today? I really liked it when there was far more quality follow up on the shares covered.
I think it is important, to know the reasons, why a stock is rated red, writers don't always get it right, they may have misunderstood something. Yu (LON:YU.) was rated Amber/Red and that has been one of biggest multi-baggers, in the last few years. See Ed's articles about it.
The comments have changed, because quite a few small cap commentators, are no longer here. I don't know how many comments there are on Paul's site, as l'm not a subscriber.
"I appreciate most of the value of the Stocko subscription lies in the data and so effectively the SMR is bundled in for free and probably doesnt have the resources to do more."
I think that was what was envisaged by Stockopedia when it started, that subscribers would drill down remorselessly into data and presumably want to discuss this in incredible detail on an attached forum.
Not so
I think it must have come as a bit of a shock to Stocko when its main forum developed into a small cap environment where investors would post on all sorts of stuff, to the point where some subscribers were apparently oblivious to any other threads.
Some subscribers would post openly that the only reason they did subscribe was for the SCVR.
I would guess that the recent changes and more data driven articles are an attempt to stop the tail wagging the dog and to bring Stocko back to its original concept. Just a guess.
Great job getting detailed full reports out on such busy days. It is appreciated.
I've been looking through numerous historic posts on Alfa Financial Software Holdings (LON:ALFA) , with Graham (& occasionally Jack) having covered this one in some detail since it fell from grace post IPO.
One thing that always needs checking with software businesses is whether they are capitalising their software development costs instead of expensing them, thus flattering profitability. It isn't necessarily wrong to do this, it is just whether it is excessive or not.
You have to wade through (oh the verbiage...it is now beyond silly) to page 171 of the last accounts to get the detail. Relative to operating profit of £30m in 2023, £2.8m of additions to intangible assets which is then amortised over 3-5 years doesn't strike me as too concerning.
Hikma Pharmaceuticals (LON:HIK) - not a TU but an MOU which may be the sort of thing we see more and more. Now trending on a nice upward curve, back to where it was in 2021
https://www.hikma.com/news/hik...
What is wrong with this site, been down for nearly 30 minutes.
Second day running there have been problems.
Problem seems resolved now
Ricardo (LON:RCDO) turning into something of a sh*tshow. First they sell their highly profitable defence arm for a pittance and simultaneously buy an expensive consultancy business and today they report poor trading in EE and Rail. I don't hold.
I read their RNS - complete gibberish - what the hell do they do?!
As a determined bull of BT (LON:BT.A) (I hold) I latch on to "we continue to make progress towards becoming fully focussed on the UK", a new UK centric CEO of BT Business and .. " enables Bas Burger to dedicate his time to optimisation of international, which is progressing to plan" to mean ... the ill fated global will be disposed off. This would remove a drag on group revenue. Nos inline, guidance in line and EBITDA up just about offsetting continued weakness in total broadband lines. To date the mkt has tended to focus on this rather than improved business mix on results day, marking the shares down. Any weakness tends to be short lived though ... I believe reflecting better buyback prospects in the future as improved FCF comes through.
If they have spare cash shouldn't they be paying back their enormous debt rather than any buyback?
Fair point chrisgb, excluding leases net debt is c£15bn compared to forecast EBITDA £8.2bn ... it's not totally outlandish. The problem is two fold, a low equity valuation and a low equity value compared to the debt. The dividend yield is fair but there would be more confidence in the dividend with a buyback in place. However if the FCF comes through as guided, as Capex falls, then actually buying back stock or debt would have a similar impact...both being accretive to equity.
The idea, that may or may not work, is to refocus on the UK and arrest the revenue grind lower. If this works the equity valuation should improve and surplus free cashflow could be used to buyback stock, debt and finance some growth. It may never be a growth stock ... but a refocussed business should be inflation proof. I think a normal free cash flow yield should give a decent share price return in a defensive business.
Interesting mixed bag of stuff today:
Generally, trading updates coming through seem moderately more positive in tone apart from those companies caught in the National Insurance crosshairs. Although I note Hollywood Bowl (LON:BOWL) today are relatively sanguine about that - and, of course, the minimum wage uplift will actually benefit them.
timarr
LON:SOM cash cow, in need of new CEO/owner
Hi timarr
Property Franchise (LON:TPFG)
A positive update, even ebullient. That is my take. Not sure how to interpret your comment about ‘canary in the coal mine’, regarding financial services. The phrase often has a negative association, but presumably this is not what you intend to convey?
Hi jonno
Property Franchise (LON:TPFG)
Not sure how to interpret your comment about ‘canary in the coal mine’, regarding financial services. The phrase often has a negative association, but presumably this is not what you intend to convey?
Yes, "green shoots" would have been a better choice of words. And it was more about the general trend in the property market than PF themselves, although the update is clearly positive. We've also had positive updates from LSL Property Services (LON:LSL) and Foxtons (LON:FOXT) this week, and it feels like there's some positive movement in sentiment.
timarr
Personally I wondered then assumed the canary had not fallen off its perch.
Cheers Timarr. My view as well, but as holder of Property Franchise (LON:TPFG) I am somewhat biased.
Property Franchise (LON:TPFG) mentioned that with the Rent Reform act going through parliament will give rise to more opportunities and to mitigate landlords leaving this sector. For those who are unfamiliar with the impending legislation, it will give rise to more rights to tenants and less security to landlord.
Without resorting too much detail here, tenants will be able give one months notice and landlord I recall 3 months at least, there will be no minimum term of 6 months and no landlord can demand for example 6 months upfront rent even if it was initiated by the tenant.
There is a very small listed company Rentguarantor Holdings (OFEX:RGG) who are approaching many letting agents (and I am sure they have approached Property Franchise (LON:TPFG) or one of their franchise groups) to take on a novel rent guarantee scheme which provides rent guarantee to the landlord but the tenant pays as part of their tenancy agreement.
As expected last night, the Federal Reserve held US interest rates at 4.25%-4.50%.
With Chairman Jerome Powell saying he would need to see "real progress on inflation, or unexpected weakness in the labour market before considering further rate reductions".
In response, investors interpreted this to mean, that they'll be two US 0.25% cuts in 2025. One in June and another in December (see below charts).
Similarly for the UK, it appears markets are now pricing in three rate reductions later this year - ending Jan'26 at around 4.0% vs 4.75% today.
Albeit worryingly - despite 5y/5y RPI inflation swaps falling to 3.2% - wage growth has recently shot up again, partly reflecting the government's agreed public sector pay rises.
Saga (LON:SAGA) Trading update:
"Throughout the last financial year, we made significant operational and financial progress. We concluded our review of opportunities that would optimise Saga's financial and strategic outlook and entered into the 20-year arrangement with Ageas for our motor and home Insurance Broking business and the sale of AICL, our Insurance Underwriting business.
Alongside this, we successfully refinanced our corporate debt.
We continued to generate strong demand for both our Cruise and Travel businesses and the Group expects to report an Underlying Profit Before Tax that is marginally higher than the prior year on a like-for-like basis1 and ahead of our previous guidance."
https://www.investegate.co.uk/...
Sky news scoop last night confirmed by Saga (LON:SAGA) . Should calm the market now a big uncertainty removed.
Saga successfully refinances corporate debt in full
Saga plc (Saga or the Group), the UK's specialist in products and services for people over 50, announces that it has secured new credit facilities (the New Facilities) which will refinance the Group's corporate debt in full. The New Facilities materially enhance the Group's liquidity position, significantly increase covenant headroom and provide funding certainty as the Group moves to execute its growth plans.
https://newsfile.refinitiv.com...