Daily Stock Market Report (Thur 5 Dec 2024) - FRAS, BAR, W7L, CARD, SQZ, WOSG, SDI, FUTR, CAM

Good morning!
To kick off the discussion this morning, I thought I'd mention the proposed IPO of Shein in London.
Over the last few days, reports in mainstream media have suggested that the FCA might allow this IPO to go ahead, despite human rights concerns. Shein is said to have filed initial paperwork back in June.
From MorningStar:
Financial Conduct Authority Chief Executive Nikhil Rathi told the FT that it was “not unusual” for UK-listed companies to carry legal risks globally. However, a priority is ensuring risks are disclosed, so investors can make informed decisions.
“What parliament has not asked us to do is to be a broad regulator around every aspect of corporate behaviour,” Rathi said, but declined to comment on Shein specifically.
In a market that has been starved of IPOs for some time, a £50 billion IPO would be of great benefit to many in the City.
And from an investor point of view, it would be fascinating to see the successor to Boohoo (LON:BOO) and Asos (LON:ASC) exposed to the limelight. Readers will remember that Boohoo has in the past faced accusations over working conditions.
How would you feel about investing in Shein?
1pm: we're all done for today, cheers!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
Companies Reporting
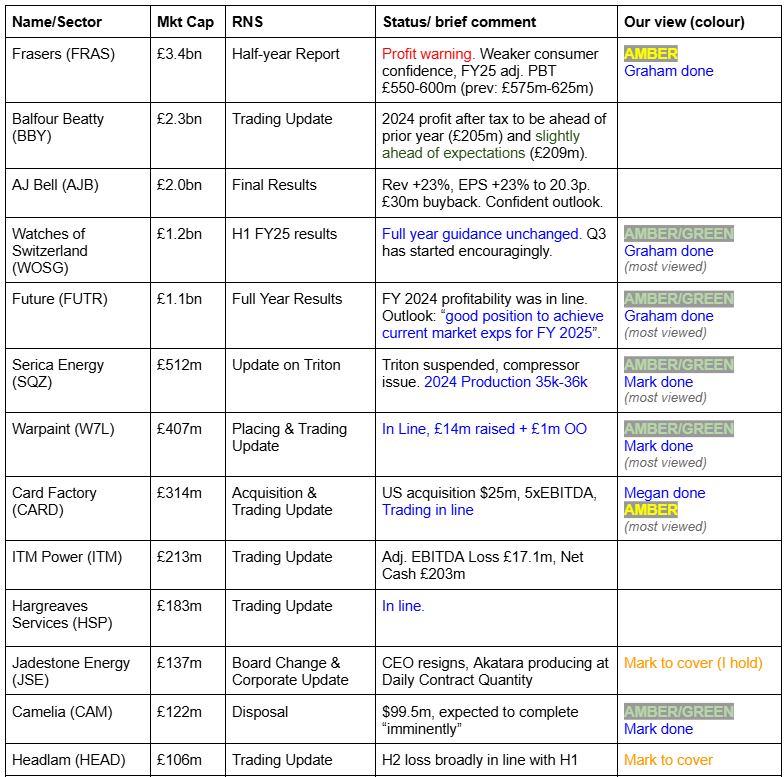
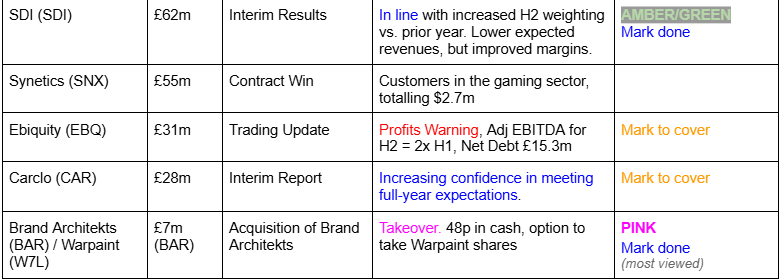
Summaries
Frasers (LON:FRAS) - down 12% to 649p (£2.9 billion) - Half-year Report - Graham - AMBER
It’s a slight profit warning from Frasers due to weak consumer confidence before and after the recent Budget announcement. H1 revenues are down 8% which includes the effect of planned decline at low margin businesses. Profits have been protected thanks to automation and synergies.
Watches of Switzerland (LON:WOSG) - up 11% to 553.5p (£1.2 billion) - H1 FY25 Results - Graham - AMBER/GREEN
Full year guidance is unchanged and the market breathes another sigh of relief. Organic revenue is still on the retreat but WOSG has shored up its numbers with acquisitions and has a growing exposure to the US consumer (45% of H1 revenues). I’m happy to maintain a mildly positive stance on this one, seeing it as an interesting recovery and growth story, not a sleep-sound type of stock.
Brand Architekts (LON:BAR) - up 88% to 45p - Takeover - Mark - PINK
100% premium. While this is only just above tangible book value, this looks a good deal for both shareholders here, given the ongoing losses, and the acquirer Warpaint.
Warpaint London (LON:W7L) - Up 3% to 540p - Placing and Trading Update - Mark - AMBER/GREEN
As part of the acquisition documents, Warpaint provides a trading update which re-iterates the in line statement from September. Some investors will be reassured by this, but many will be expecting (and the market rating implies) that the company will beat, not just hit forecasts.
The placing of £15m at 510p to fund a £13.9m acquisition of a company with £7m net cash, raises questions as to whether the management of this £400m market cap business are just being extremely cautious or whether their willingness to pay fees to issue shares at this price reflects their unstated opinion on the current valuation.
Serica Energy (LON:SQZ) - Down 3% to 128p - Update on Triton FPSO - Mark (I hold) - AMBER/GREEN
Further production problems at the non-operated Triton field hub hit production estimates for FY2024. However, plans remain in place to improve the robustness of this platform in 25Q1, and in the medium term, this doesn’t impact the very cash-generating nature of this business nor the 18% forecast dividend yield.
SDI (LON:SDI) - Up 5% to 62p - Interim Results - Mark - AMBER/GREEN
The results themselves are weak, and leave a lot to do in H2. However, the detailed narrative reveals a positive outlook. New management appears to be following the right strategy of driving organic growth and improving synergies and best-practice sharing between the subsidiaries. With this strategy in place, this is a decent business; it just isn’t particularly cheap based on current forecasts.
Future (LON:FUTR) - up 12% to £11 (£1.2bn) - Full Year Results - Graham - AMBER/GREEN
This media group says it’s in a good position to achieve current market expectations for the new financial year. The results for 2024 show very modest organic growth which is at least an improvement on 2023. I’m downgrading this to AMBER/GREEN as the only part of the business I have investment conviction in is Go.Compare, and the shares have enjoyed a very strong run higher over the past year.
Camellia (LON:CAM) - up 15% to 5082p - Disposal - Mark (I hold) - AMBER/GREEN
A bonkers corporate structure is slowly being rationalised, with the $100m sale of an insurance subsidiary comparing favourably to the £141m market cap, even after a share price rise today. Some doubts remain as to how much of the cash will be returned via buybacks, but given the ongoing discount to tangible book value, any buybacks would likely add shareholder value.
Short Sections
Card Factory (LON:CARD)
Up 7% to 96p (£314m) - Trading update and acquisition announcement - Megan - AMBER
In September, Card Factory (LON:CARD) shares sold off hard after H1 results were hit by higher wage costs. At the time, the company said it was still on track to meet full year expectations and analysts only trimmed their forecasts by a small amount.
The sell off, which took the share price down to a low of 80p and trading on a forecast PER of 5.5x at the start of November, perhaps seemed a little overdone.
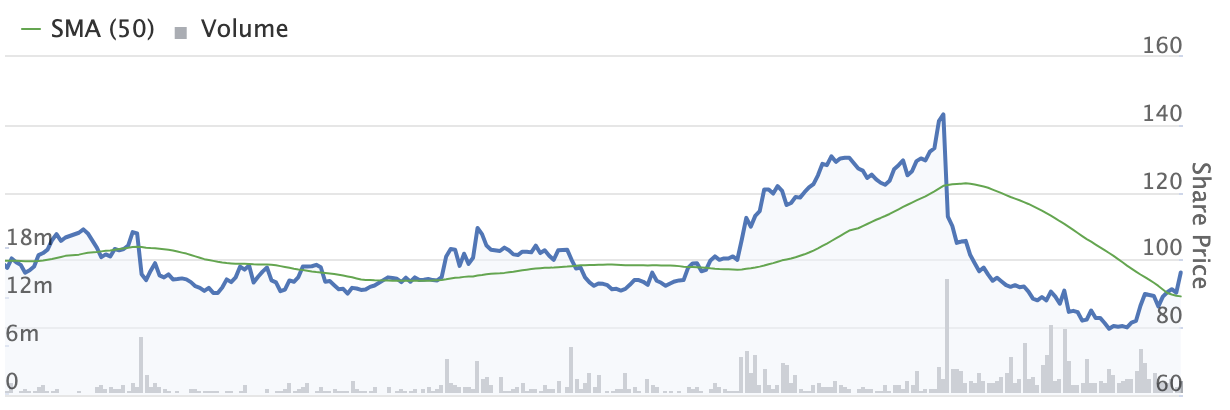
This morning the company has once again reiterated its full year guidance, although management does concede that the peak Christmas trading period is still to come. Investors only sent the shares up 7% in early trading following the announcement - suggesting that the market is waiting for more clarity on Christmas sales (a trading announcement is due on 14 January) before they leap back in.
This morning’s trading announcement also contains details of its acquisition of a gifting wholesaler based in Minnesota. This marks the company’s first entry into physical retail space in the US, a market which management say is worth £70bn.
Card Factory has been pursuing an international growth strategy based on locating partners for domestic sales. Today’s acquisition is a bit of a departure from this partnership strategy, but it reiterates the company’s commitment to international expansion.
Megan’s view
Card Factory shares look cheap. The EV to EBITDA ratio is just 4.2x, which is less than the acquisition multiple of the US company it has just bought. Trading on 5x EV/EBITDA would give a share price of more than 120p - over 25% up on the price today.
This is certainly a tempting price for value investors, but I share the market’s hesitancy. If the company misses earnings expectations (currently 14.4p) investors might have longer to wait for the recovery.
And that 14.4p forecast looks a little ambitious given first half adjusted EPS of just 3.1p. Last year Card Factory made 8.5p per share in the second half. To hit this year’s expectations the company is going to need a 32% increase in earnings in the second half.
At this price, I am perhaps being overly cautious and maybe a value investor might be more tempted. But I would rather wait for clarity on 14 January. AMBER
Serica Energy (LON:SQZ)
Down 3% to 128p - Update on Triton FPSO - Mark (I hold) - AMBER/GREEN
Serica have had a number of operational issues recently on their Triton hub. In May they had an unplanned shutdown due to a compressor failure. Then, the planned shutdown in July lasted three weeks longer than expected. At the end of October there was a further shutdown due to a seal failure. Production was anticipated to start again at the start of December. Today we find out that:
…after a limited resumption of production at the Triton FPSO last week, an issue with one of the compressor seals has been discovered which has resulted in production being suspended.
This has had quite a big effect on production:
H1 actual - 43,700 boepd
2nd Oct FY guidance - towards the bottom of the 41,000 to 46,000 boepd range
29th Oct FY guidance - expected to be slightly below this previous guidance (41,000 boepd)
Today's FY guidance - 35,000-36,0000
The reason is that the Bruce hub and other assets only produce around 28,000 boepd, around half of their anticipated production. However, the company highlight that they have plans in place to improve the resilience of their operations:
As previously stated, the operational vulnerability will remain until the ongoing works to restore two-compressor operations are completed, expected in Q1 2025.
There is also some good news on gas prices:
October price per therm - 97.9p
Current price per therm - 115-120p/therm
Given the majority of their current production is gas and that costs are largely fixed, a 20% rise in short-term gas prices will help offset the impact of the missed production.
Mark’s View
While it is disappointing to have further production issues in 2024, these don’t impact the reserves of the company, or its medium-term production. Serica is not the operator of the assets that have had issues, so I don’t think we can fully blame them for the miss. In the last results presentation, the company highlighted their ability to generate the current market cap in cash over the next four years or so. I see nothing in today’s announcement that changes that. The budget was negative for the company but not as bad as it could have been. So it is a AMBER/GREEN for me, and I remain happy to hold for the 18% dividend yield.
Graham's Section
Frasers (LON:FRAS)
Down 12% to 649p (£2.9 billion) - Half-year Report - Graham - AMBER
This serial acquirer of retail shares has published its own interim results this morning.
However, this does include a mild profit warning:
We are set to deliver another year of profitable growth but, given recent weaker consumer confidence leading up to and following the Budget, FY25 APBT is now expected to be in the range of £550m to £600m."
Guidance given at the full-year results was for APBT of £575-625m. So from midpoint to midpoint, this is a 4% cut in the estimate.
As for H1 itself, here are the key facts:
Revenue down 8.3% (to £2.5 billion)
“Group profit from trading” - similar to adj. EBITDA - down 2.9% (to £400.6m)
The unadjusted profit figures are badly impacted by foreign exchange (there is a headwind in H1 this year, vs. a tailwind in H1 last year). So unadjusted H1 operating profit is down 10.5% year-on-year. I’m happy to look past this, as it’s something entirely beyond the company’s control.
Tight cost control has saved the result, with an overall 11% reduction in retail operating costs worth £85m. There has been a planned decline at video game retailer GAME and at Studio Retail (we previously knew this as Findel).
In addition, the company talks about “right-sizing” the brands acquired from JD Sports and points to warehouse automation/rationalisation and synergies from acquisitions.
In the luxury segment, I note with interest the following:
Our long-term ambitions for the luxury business remain unchanged, although it is likely that progress will remain subdued for the short to medium term in the face of a challenging market. However, we continue to view this as an opportunity for consolidation in order to further strengthen our position.
The company remains very much in expansion mode. On top of the stories we’ve spoken about in this report (battles with Boohoo and Mulberry, for example) there are various international adventures for Frasers including:
i. Completed the acquisition of Twinsport in the Netherlands.
ii. Invested in Australia/New Zealand group Accent.
iii. Invested in Maltese/North Africa retailer/Nike distributor Hudson.
iv. After period end, announced the acquisition of Holdsport in South Africa/Namibia.
There is a helpful (but incomplete) list of strategic investments:
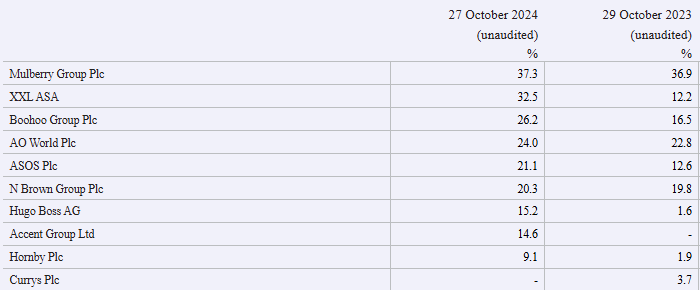
With the following note on strategy:
Our strategic investments are intended to allow us to develop relationships and commercial partnerships with the relevant retailers and brands. The Group is actively seeking a board seat at Hugo Boss and has recently had a representative appointed to the board of Accent Group.
Net debt has increased to £831m, or to £725m if you’re willing to exclude loans securitised on assets. The balance sheet has net assets of £2.1 billion.
Relationship with Mike Ashley (73% shareholder):
Mike stepped down as CEO in 2022. He also stepped down from the Board of Directors later in 2022 and has no day-to-day involvement or responsibility for the strategic direction of the Group or any Board matters.
However, given his extensive involvement in leading the business for over forty years, the Board has an agreement with Mr Ashley, through his own company MASH Holdings Limited, which provides for management to seek his expertise in discrete areas where he has specific knowledge, for example in warehousing, logistics or strategic relationships with the supply chain. He does not receive any remuneration for providing this advice to management and has no decision-making powers.
I checked the 2024 Annual Report and can find no mention anywhere that the very young CEO of Frasers, Michael Murray, is Mike Ashley’s son-in-law.
According to the Daily Mail in 2022:
Mr Murray is said to be extremely close to his mentor, with one source previously describing how the pair would 'thrash out business deals over drinks or dinner or on family holidays away from the wider management team'.
Graham’s view
I tend to spend more time looking at the deals done by Frasers than I do looking at Frasers itself.
When it comes to Frasers itself, I must say that I find the CEO appointment off-putting. I’d much prefer if Mike Ashley was Chairman, rather than having a member of his extended family as CEO and telling us that he has no decision-making powers.
The expansion and acquisition strategy has been working well for Frasers. As readers may know, I’m a shareholder in Next and personally I like what Next does: buying up brands out of administration and plugging them into the Next machine.
Frasers takes a more aggressive approach: buying shares on the stock market and then sometimes haranguing the Directors of the companies it owns shares in.
I admit that the Frasers valuation does looks tempting, especially considering the discount to net assets.
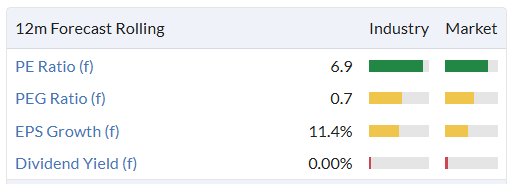
It might be a little harsh, but personally I can’t give FRAS anything better than a neutral stance. I don’t like the governance situation, and I prefer an M&A strategy that is seen as friendly and helpful by the companies it targets (in the Warren Buffett tradition), as I think this tends to work out better for everyone in the long-term.
For these reasons, I wouldn’t want to pay a high multiple for FRAS shares. But I acknowledge that FRAS may already be too “cheap” at only six times adjusted PBT, and that my concerns might be unfounded and cause me to miss out on an undervalued stock. I’ll have to think about what conditions would allow me to take a more positive view - perhaps a meaningful reduction of the outstanding debt.
Watches of Switzerland (LON:WOSG)
Up 11% to 553.5p (£1.2 billion) - H1 FY25 Results - Graham - AMBER/GREEN
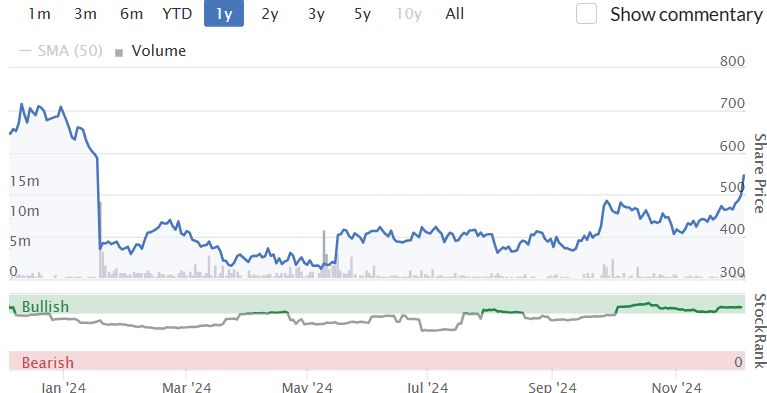
Full-year guidance is unchanged at Watches of Switzerland and the market is enthused.
It has been a rough year, so I guess that stability of expectations is seen as welcome news:
I covered the in-line trading update in September. Today now have interim results to October.
Revenue from watches is down 2% at constant currencies, despite acquiring 19 Ernest Jones stores a year ago. Revenue from jewellery (excluding the impact of the newly-acquired Roberto Coin Inc.) is down 5% at constant currencies.
I think these should be the headlines, but the company instead leads with the headline of 4% total revenue growth.
PBT is down 39% to £41m, not helped by “exceptional” costs of £16.5m (H1 last year: only £4m of exceptional costs). The main exceptional cost is a £13m impairment caused by “the current macroeconomic environment, high interest rates and inflationary landscape”. The value of PPE and leases have been written down.
Net debt has jumped to £120m following the acquisition of Roberto Coin Inc.
Inventory is up by £77m due to the acquisition of RCI and Ernest Jones stores, and now stands at a remarkable £477m. They say they are well-stocked for the holiday season - I should hope so! For context, the full-year revenue estimate on the StockReport is £1.7 billion.
ROCE according to the company has fallen from nearly 24% to 16.5%.
Guidance: revenue of c. £1.7 billion, with an adj. EBIT margin +0.2 to +0.6 percentage points expansion from FY24.
The adj. EBIT margin in FY24 was 8.8%. At 9.2% (+0.4% expansion), adj. EBIT would be c. £156m.
Graham’s view
I’ve been tentatively positive on this since May, when the share price was 328p. With the shares up by nearly 70% since then, it would be quite reasonable of me to switch back to a neutral stance.
However, I like to let the winners run and so I’ll let this run a little longer before switching back to neutral. The P/E ratio is still at a reasonable level and the festive period is about to begin. The company has significant exposure to the US economy (£355m of revenue in H1), and the market in luxury watches should soon start to rebuild from a new base, after the bursting of its post-Covid bubble.
In short, I think there is still enough potential excitement here to keep my mildly positive stance.
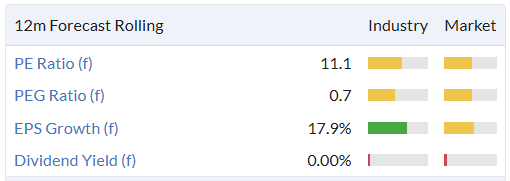
Please note that there are no dividends on offer from WOSG and they seem unlikely for the foreseeable future. Showroom investments and strategic acquisitions come first.
Future (LON:FUTR)
Up 12% to £11 (£1.2bn) - Full Year Results - Graham - AMBER/GREEN
Revenue is up 1% organically at Future, an improvement on last year when it was down 10%!
The same can’t be said for adj. operating profit, which has fallen at a faster rate (11%) than it did last year (9%), using constant currency rates, and comes in at £222m (in line with expectations).
Leverage has reduced to 1.1x (from 1.3x), with net debt falling to £256m despite £65m of buybacks plus a token dividend. This debt level should be manageable.
Management: the CEO is leaving next year and the company is searching for a replacement. A new CFO joined in September.
Outlook:
Our return to revenue growth in H2, driven by the execution of GAS [growth acceleration strategy], puts the Group in a good position to achieve current market expectations for FY 2025. We expect to continue to operate at an adjusted operating profit margin of 28% for the coming year reflecting the planned incremental GAS costs, and to maintain strong cash conversion.
Beyond FY 2025, we now expect to deliver accelerating organic revenue growth, in line with current market expectations.
Graham’s view
As I’ve said before, my favourite part of FUTR is the price comparison business Go.Compare, which generates more than a quarter of its revenues. This is the only part of FUTR where I am fully convinced that it’s a high-quality investment.
In total, the group has about 200 media brands including some well-recognised titles.
An important adjustment to the earnings numbers is the amortisation of intangibles. I’m happy with the principle of allowing this adjustment if we are happy to assume that intangibles on the balance sheet are all worthless: that assumption leads to a net asset value for FUTR of minus £450m. So there is zero balance sheet support and really the company is in the hole for a few hundred million pounds.
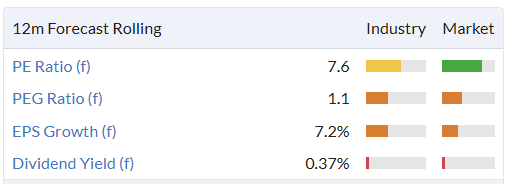
I’m going to downgrade this to AMBER/GREEN, even though it might still offer good value at this level. It has had a very good run.
Mark's Section
Brand Architekts (LON:BAR)
Up 88% to 45p - Takeover - Mark - PINK
This is below the normal market cap size for the DSMR, but given that the acquirer is the well-known Warpaint, it is worth covering. Warpaint are offering 48p in cash for the company, and it represents a significant premium to last night's close:
· 100 per cent. to the Closing Price of 24 pence per Brand Architekts Share on 4 December 2024 (being the last Business Day before the date of this announcement);
· 85.42 per cent. to the average price of 25.89 pence per Brand Architekts Share for the 3-month period ended 4 December 2024 (being the last Business Day before the date of this announcement); and
· 95.78 per cent. to the average price of 24.52 pence per Brand Architekts Share for the 12-month period ended 4 December 2024 (being the last Business Day before the date of this announcement).
There is also the option for shareholders to take Warpaint shares equal to the same 48p value.
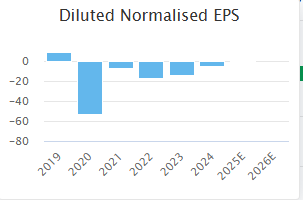
Brand Architekts has been one of the few net nets on the UK market recently. (Net nets are companies trading at a discount to their liquid assets, netting off all liabilities.) The company sold off their manufacturing operations for a large cash sum to focus on the brand side of their business. However, they were continuously loss-making:
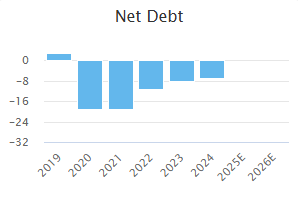
And the cash pile was dwindling:
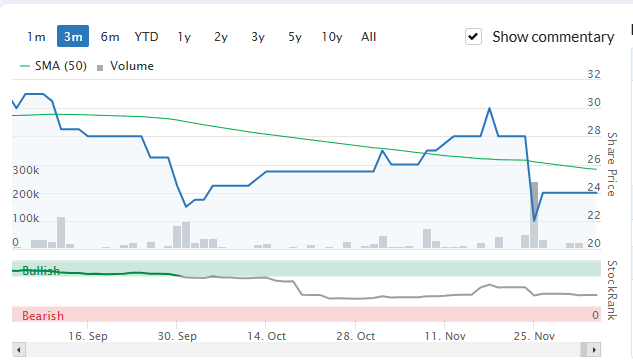
This, plus extreme illiquidity, put off many value investors, such as myself. The market didn’t get wind of any offer, and whoever the keen seller at the end of November will no doubt be kicking themselves:
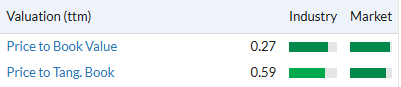
The reality is that Warpaint appear to have got a good deal here. They are paying only a small premium to tangible book value, which is mainly cash and inventory. These are the figures from last night’s close:
They are getting the brands, which are not the most high-quality but probably worth something, for free. They will be able to rationalise costs, and without the overhead of the additional listing this will no doubt make them money. Long-term, Brand Architekts shareholders may not be happy to sell out given how far the shares have fallen over the years:
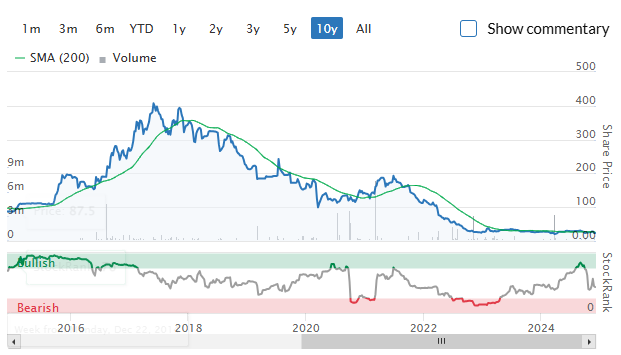
But objectively, the future is much brighter under Warpaint’s stewardship. This looks like a win-win for all.
The offer will be implemented via a scheme of arrangement. Warpaint has received around 31% irrevocable undertakings, including the largest shareholder, Peter Gyllenhammar. While this isn’t a slam dunk, given the premium, I can’t see a higher offer coming from elsewhere. Brand Architekts also has a pension deficit, which may put off smaller potential acquirers. Given his value-bent, it is perhaps unsurprising that Gyllenhammar has opted for the cash option, not shares.
Warpaint London (LON:W7L)
Up 3% to 540p - Placing and Trading Update - Mark - AMBER/GREEN
As part of the Brand Achitekts takeover, Warpaint has announced a £15m capital raise, consisting of a placing:
It is expected that the Fundraising will result in the Company raising total gross proceeds (before fees and expenses) of up to £15 million. Warpaint proposes to use the net proceeds of the Placing to repay the bridging loans which have been used to fund the maximum cash consideration payable by the Company pursuant to the Acquisition.
The dilution is small:
The Placing Shares will represent approximately 3.53 per cent. of the existing issued ordinary share capital of the Company
And given this, the discount is minor:
…the Issue Price represents a discount of approximately 2.67 per cent. to the closing mid-market price of 524 pence per Existing Ordinary Share on 4 December 2024
It is worth noting that companies often pay 5-10% fees on placings such as this, so there is a genuine cost to shareholders, even if the discount is small.
It does raise questions as to why they needed a placing at all. They are paying £13.9m for Brand Architeckts, but will be getting £7m of cash which is on their balance sheet, minus any losses since 30th June. Some Brand Architekts shareholders will probably opt for Warpaint equity, and the company had £5.5m in cash at the last balance sheet date and no bank debt. This may reflect a high level of caution by management and the fact that this takeover comes at the point of peak working capital for the business. However, surely no bank would worry about lending a £400m market cap company £5-10m for an acquisition. The alternative view is that management view their equity as fully priced at current levels.
As part of the announcement, the company has provided a trading statement. However, this is just a re-iteration of what they said on September 17th, when the crux of the matter was:
…the board expects the results for the year ended 31 December 2024 to be in line with its expectations.
This will be reassuring to many investors as we head into the Christmas trading period. However, many expect this company to not just meet but beat expectations and will be looking for upgrades in the FY trading update.
Mark’s View
When Paul looked at this in September, he highlighted that the forecasts looked too low, and that upgrades would make the valuation look much more reasonable. However, with only in-line trading confirmed today and perhaps a few signs that management aren’t shy about issuing equity at the 510p level, this is an AMBER/GREEN for me. However, if that upgrade does arrive, this may well be back to GREEN.
SDI (LON:SDI)
Up 5% to 62p - Interim Results - Mark - AMBER/GREEN
It is a weak half for this roll-up of scientific instruments businesses:
Revenues of £30.9m (H1 FY24: £32.2m) reflecting reduced activity in the life sciences and biomedical markets
Gross margins (on materials only) improved to 65.4% (H1 FY24: 63.0%)
Adjusted operating profit* of £3.9m ( H1 FY24 : £4.4m) and reported operating profit of £2.4m ( H1 FY24 : £3.4m)
Adjusted profit before tax* of £3.2m ( H1 FY24: £3.7m) and reported profit before tax of £1.7m ( H1 FY24: £2.7m)
However, these results are not terrible. An increase in an already strong gross margin means that adjusted operating profit is only down 11%. There is a big gap to statutory profits, though, and in such cases, it is worth looking into the details. This is what they say they exclude:
…share based payments, acquisition costs, reorganisation costs, divestment of subsidiary undertaking (in FY24) and amortisation of acquired intangible assets.
And here is the breakdown:
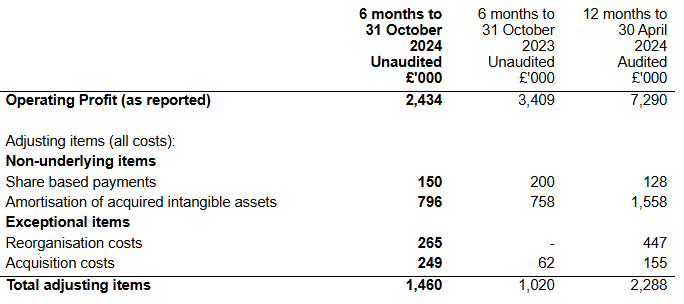
I think excluding share-based payments is fair as long as investors use the fully diluted share count. Amortisation of acquired intangibles is normal these days. However, I am less convinced about acquisition costs and reorganisation costs. These are real cash costs and not one-off for this company. Indeed, they say:
…we continue to drive our active M&A pipeline to expand our portfolio across key markets.
It seems to me that many companies want to have their cake and eat it. They want investors to price the growth that comes from acquisitions but not the cost of doing so. They want investors to report a profit improvement from headcount reductions but exclude the costs of making employees redundant. Acquisitive companies are always going to have reorganisation costs, as the rationale for making acquisitions is that they have synergies to unlock.
Adding back these costs, we would have an operating profit of £3.38m in H1 versus £4.37m for H1 last year, meaning operating profit would be down a more substantial 23%.
It is not all about the past, and H2 is looking better:
Increased activity towards the end of the half, following the previously reported slower start to the financial year. Positive momentum continuing into H2 FY25
…Order intake significantly up on a like for like basis compared to the second half of FY24
This still leaves a lot to do in H2 to go from adjusted diluted EPS of 2.37p in H1 to the 6.2p their broker, Cavendish, is forecasting. There seems to be some confidence that they will do it, though, with Cavendish saying:
We make no changes to FY25 profit forecasts. We introduce FY26 forecasts with revenue growth of 9.2%, with improving organic growth of 6.5% and the drive to improve internal efficiencies continuing. This drives adj PBT growth of 12% to £9.4m resulting in EPS of 6.8p, up 9%. We forecast stronger cash generation reducing net bank debt to £6.1m, offering greater scope to make accretive acquisitions.
Personally, I like this strategy change:
From an organic growth perspective, we have made progress in actively fostering synergies between portfolio companies operating in overlapping markets and/or offering similar products. The senior management at Safelab Systems ('Safelab') and Monmouth Scientific ('Monmouth') have been combined, and the two individual businesses are now working closely together. Furthermore, businesses within the laboratory equipment segment are increasingly engaging in white-label partnerships to secure larger contracts.
The previous SDI management appeared to follow the Judges Scientific strategy of leaving acquisitions alone. However, they appear to have lacked Judges' skill in finding suitable quality acquisitions at bargain prices. A COVID boom in the demand for certain imaging products hid the issues for a number of years, before the current situation came to light. That new management are now pushing the synergies and best practices that should be present between similar businesses seems to me to be exactly the kind of thing the board of this sort of business should be doing.
In terms of valuation, Cavendish forecasts are for an adjusted EPS of 6.8p in FY26, which means they are on a P/E of around 10 for this year, falling to 9 the year after. That’s a PEG of around 1, suggesting that the shares are fully valued at the moment. However, if management initiatives start to bear fruit, this could easily see broker upgrades make it look better value.
Mark’s view
I was a fan of SDI in the early days. However, more recently, I’ve been critical of the company. They appeared to be making acquisitions of poorer-quality businesses at higher multiples yet doing little to improve their prospects. A new management team appears to have grasped the nettle and are making the necessary changes to drive organic growth as well as cut costs and drive synergies between businesses. There is little sign of these changes in these H1 numbers, and their adjustments look a little aggressive to me. However, it takes time for strategy to be reflected in results. Roland rated this AMBER following the last trading update, and not a lot has changed numbers-wise since then. However, I feel this was a little harsh. Under new management, this is a decent business; it just isn’t particularly cheap based on current forecasts. Hence, an AMBER/GREEN rating seems best.
Camellia (LON:CAM)
Up 15% to 5082p - Disposal - Mark (I hold) - AMBER/GREEN
This is a short statement, but one with a lot of history behind it:
…is pleased to announce that the regulatory and tax approvals required in connection with the proposed sale of its shares in BF&M Limited …have been received, and the sale is anticipated to be completed imminently.
This sale was previously known about, but the regulatory approvals were making it a long process. When you include the context, an even longer process!
Camelia has been a value trap for many years. It is a strange conglomerate of agricultural, insurance and banking assets, plus listed and unlisted investments across the globe. The sort of business that could only exist after many decades of empire-building. It almost always traded at a discount to tangible book value, but it is liquid and a family trust owns 50%, making any attempt by external shareholders to shake things up futile.
In this case, either the family trust or management decided enough was enough and have been slowly rationalising the business. They have been selling off non-core holdings and closing down loss-making subsidiaries such as their UK apple farms.
Last month, they sold their “Bangledesh associate companies” for £7.9m having to take a haircut to the £9.5m book value. However, the sale of their stake in an insurance business has been much more lucrative:
At Completion, the Company expects to receive the full gross consideration of $100 million in cash. Net proceeds are expected to be c.$99.5 million (c.£78.7 million) and the transaction will crystalise a net profit of c.£10.7 million including accumulated exchange gains and losses.
£78.7m is clearly material to a business with £123m market cap at last night’s close. The shares are up 15%, adding about £18m to the market cap. A £141m market cap remains a material discount to TBV of £328m minus any losses since last balance sheet date, adjusting for recent losses and gains on disposal.
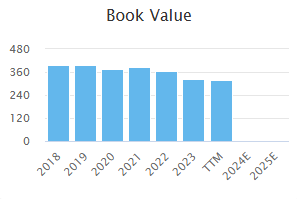
Originally, the company had to take a loan note for half of the $100m proceeds from BF&M but with today’s announcement, it seems it will all be paid in cash. This means the company will have over £100m in cash,
They say:
The Company will update shareholders on the use of funds upon receipt of the net proceeds from the sale.
So that is quite vague. Previously they said:
…the receipt of the funds realised by this sale, together with funds raised from the disposal of other non-core assets, will enable the Company to accelerate its development programme and continue to diversify its agricultural production by crop and geographic location. The Board considers Camellia's shares to be significantly undervalued and, in the event of any surplus funds arising, will also therefore consider the merit of returning these to shareholders by means of a share buy-back.
So not all that cash will be returned, but it seems likely that some kind of buyback will be implemented. Investing further in agricultural production is a risk. After all the current business goes through wild swings in profitability based on crop pricing and yield. Balancing this is the possibility of further asset divestments. A £30m stately home is being actively marketed, and their “heritage assets”, old manuscripts etc. are also for sale. These may provide further cash for buybacks, but also highlight how bonkers this company structure still is!
Mark’s View
Having been an obvious value trap for many years, today’s announcement highlights that things here appear to have changed. Management are committed to simplifying and rationalising the business. The assets they are divesting are real, and have a value that still appears to be significantly in excess of the current market cap. It is not without risks, though. A currently loss-making agricultural business and a lack of clarity on buybacks remain. The bonkers factor remains high, but the discount to TBV is enough for me to hold, and consider this AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

99 comments
I’m 50% (51.9%, to be accurate) down on Serica so don’t beat yourself up too much…
I would add to the late night thank you, just finished work for the week and catching up on all the reports in a "boxset" session, thank you to the Team for the excellent content, and also to the contributors too.
Apologies I have been very lax in terms of contributions, major life event ongoing, I am ok but it depends on the minute, still invested, still keeping trying, still looking after the family pennies, and overall "in the game" so :)
Tommy
Best wishes Tommy …life is never straightforward
Just back from work to have a quick read and what a huge amount of content and work put into the report (and comments too). Big thanks to Graham, Mark and Megan for today’s excellent report. Will be a longer night than planned consuming it all. Keep up the great work, it is much appreciated
Volex (LON:VLX)
I hold. The shares have been under the hammer since the interims and the bid for TT electronics (LON:TTG) in mid November. At the interims Nat Rothschild stated that the company was confident in achieving full year expectations.
The shares are looking increasingly cheap but buying at present looks like standing in front of a bus. When the share price stabilises I may look to add depending on price. Whether or not the share price weakness is a result of the market anticipating an equity raise as a prelude to a further bid for TT electronics (LON:TTG), who knows.
Any thoughts, any one?
Volex (LON:VLX)
agreed that it looks cheap- i would say on the basis that they may acquire TTG - i think that would add chomping amount to debt as TTG itself is a very indebted company - so thats a game changed ref risk level for a buisness that has ben in downward spiral (that appears to me to be down solely due to poor management as fare as i can work out)
If one is critical one could say that the market has been downgrading forecasts regularly this Calendar year for both this year and next year profits - indeed stocky has made further downgrades in the last 30 days. If the stocky data is accurate it sounds like there is some mismatch here if Natty is saying they are on track. Is it posible stuff has beden downgraded behind the scenes to then say they are on track with those lower expectations? even then we have further downgrade after he has spoken.
One thing i look for is the trend in expectations and its clearly on a worsening trend - is there any reason why things keep getting worse over time? Note the downgrades are very minor in % terms so i am probably being slight picky here - it might simply be arouge broker who was over optimistic coming back into line perhaps ?
Note sometimes downgrades make sense - eg budget updates etc - so there may be reasonable explantation here - note ZIGUP (LON:ZIG) has properley flagged up lowering expectations ages ago and provdied full detail and still got hammered on results day - i thing anything that is lower than previous always looks bad .
One slight worry is how reliant are they on EV supply ref excellent profts they have been delivering - if there is upcoming strife ref electric car production are they likely to be affected ?
If they supply Tesla i would guess Telsa are probably the calm waters in a chjopy sea nowadays - can anyone believe we woudl have benm saying that 10 years ago ?
Dividends aren’t a non event. The 18% a year annualised from that yield from Serica Energy (LON:SQZ) is a very good return even with no share price gain. If they maintain the dividend there would be the high chance of a substantial share price gain in time to bring the dividend yield back to more normal levels. Obviously such a high yield might be unsustainable.
e.g I bought Legal & General (LON:LGEN) at about 150p and my yield is about 13% a year, and the capital gain is about 50%. A friend did much better. He bought Legal & General (LON:LGEN) years ago at 32p and is now getting 70% a year yield every year AND the share has gone up more than sevenfold.
I guess you saw yesterday that Legal & General (LON:LGEN) intend to return a proportion of capital from their institutional retirement business to shareholders, in addition to the existing dividend.
Hi ken
To put the dividend from Serica Energy (LON:SQZ) into perspective I'm showing a 25% total loss on the stock including received dividends because I bought at the wrong time, although it was offering a 6% yield at my time of purchase. I continue to hold because I think it's stupidly undervalued but the evidence so far suggests it's me that's stupid, not the price.
If you pick your start date and price you can always show a good return. The challenge is to show a method that's repeatable. The two data points you've described in your email are so unusual that it's possible to accurately date them both - Legal & General (LON:LGEN) last traded at 150p around about March 16th 2021 and at 32p around March 2nd 2009.
The former was peak Covid panic and the latter peak GFC panic, both prices being achieved right at the absolute nadir of the market.
What you appear to showing is that if you have the guts to buy decent stocks when blood is running in the street you'll get great returns. It doesn't prove anything about the superior returns of high dividend payers, it's a trivial exercise to identify low dividend payers that if bought on the same dates would have provided similar or superior returns.
timarr
Hi timarr
That’s all fair comment as usual. My favoured investment tactic is to buy the big dips like after the banking crisis and as the markets began to recover after the covid falls and most recently the Truss chaos falls. But the buying then is not only big dividend paying shares. It’s a tactic that works end very well. I was not making a case for higher returns from big dividend payers. Most of my big winners post the 2009 crash were non dividend payers. Also I was replying to this comment in a post earlier today:-
”Also, people tend to focus a lot on dividends but for me its a non-event - once a dividend is paid the market cap of the company goes down by the amount of the dividend paid.”
Hi ken
My favoured investment tactic is to buy the big dips like after the banking crisis and as the markets began to recover after the covid falls and most recently the Truss chaos falls.
Snap.
Most of my big winners after the 2009 were low dividend payers. Stupidly I sold most of them after I'd made what I thought were decent gains - London Stock Exchange (LON:LSEG, Diploma (LON:DPLM), Renishaw (LON:RSW), Halma (LON:HLMA). Sigh ...
Still, regrets are for the afterlife, eh?
timarr
I also sold big winning non dividend payers I bought in 2009 far too soon, unlike my friend who (unlike me) didn’t sell his Legal & General (LON:LGEN) buy at 32p then. I remember David Holding advising me to buy Uniq (Unigate) at 4p. I was unconvinced so only bought a small stake. That small stake I sold after it 10 bagged in a few weeks.
Predicting markets is a mugs game but I’ve a hunch there might well be big falls in the US before too long, and possibly another big bear market to provide another of those once or twice in a decade buy opportunities.
Now we just need a cash buffer / find some down the back of the sofa when these 2009 like falls occur :)
Thanks for covering Serica Energy (LON:SQZ) this morning, Graham. It's good to see that Oil & Gas companies are being followed and certainly IMO adds another dimension to the coverage here. I do admit to being a little biased as nearly half of my portfolio is in that sector (including Serica Energy (LON:SQZ) ) so I hope you have the time and resources to keep doing so.
You're welcome Barry but the credit for that goes to Mr. Simpson!
Sorry Graham. Happy to thank Mark for that. Look forward to reading many more reviews from mark of that beleaguered sector.
Megan have you looked into Lululemon Athletica (NSQ:LULU) ? l was reading an article in the Guardian, about working conditions in factories, they use in Bangladesh, to make their leggings. I don't think they are as squeaky clean as you think. A lot of the money you are paying is for marketing, high profit margins and expensive retail shops. The founders comments on child labour are interesting.
Of course the west is a far more safer space letting them free use of TickToc, Robux, Fortnite etc. Little scamps learning the value of money, hard work and supporting their families is a crime. Tongue in cheek but who knows the facts. We certainly do not.
Mark, Warpaint London (LON:W7L) W7L. Your comment "or whether their willingness to pay fees to issue shares at this price reflects their unstated opinion on the current valuation."
What does that mean? I am afraid I am not smart enough to decode that.
I think he could have postulated that perhaps managment may think its smart to issue equity rather than tap debt as they may possibly view equity as currently not undervalued or a little rich, as that's usually why companies use their own equity to acquire others when they don't have to.Personally i've no opinion.
Thanks
Nice update from Goldplat (LON:GDP) today, looking at £6 million pbt for final results. Material increase.
Sorry, just seen this - I will stick WATR in the backlog! Thanks for the notification Mark.
Bucket.
Serica Energy (LON:SQZ) Mark, You suggest SQZ is paying 18% divi but Stockreport shows the yield @ 8.4% which is correct
I think with companies like Serica there should be an analysis of what profits will be left (if any) after the government gets his big pound of flesh. How much profit is left for shareholders? Will Serica at some point be forced to cut the dividend? Also, people tend to focus a lot on dividends but for me its a non-event - once a dividend is paid the market cap of the company goes down by the amount of the dividend paid.
If you watch their last results presentation, they suggested it was their market cap in cash in 4-5 years based on worst-case budget outcome, i.e. all capital allowances were gone, and things were bad but not as bad as that as come capital allowances are allowed.
Thanks for highlighting this, it seems like a data anomaly to me, probably caused by the switch in currency by the company. They definitely paid out 23p TTM:
The forecast yield is roughly 18%, according to brokers.
I think they will hold the 23p (or $ equivalent)., which will be slightly above 18% at current market prices.
Nobody picking up Shell (LON:SHEL) to combine with Equinor ASA (NYQ:EQNR) - big news would have thought. Shell can slowly delist from the UK into US and Europe exchanges and dump the communists.
Rockhopper Exploration (LON:RKH) keep an eye. North Sea II.
Stocko has 17.88% on Serica Energy (LON:SQZ) future dividend and that is based on yesterday's share price.
Where is the 8.4%?
But Stocko figures are not that reliable on dividend forecasts.
23/125p = 18.4%
This link is for an excellent site for right up to date dividend yields etc. Just click on the various headings at the top. This link is for the Serica Energy (LON:SQZ) dividends, and it’s the far left heading. Next heading is for dividend payment dates.
It‘s clear. For the last 2 years Serica Energy (LON:SQZ) have paid a total of 23p a year (2 dividends a year; one 9p and then a bigger 14p) which equates to around 18% annual yield at the current share price. This Dividend data site updates immediately a dividend is announced. It’s a must use site for ACCURATE dividend information.
https://www.dividenddata.co.uk...
Hi Megan,
I am afraid I am struggling a bit with the analysis on Card Factory (LON:CARD.
The company were clear well ahead of the H1 results that wage increases would impact H1 and were mitigated in H2. The CFO showed how that would play out in both halves.
Then at H1 the CFO put up a slide showing the levers used by mgmt that meant that full year expectations were unchanged. The slide showed the bridge of H1 and H2. This was clear : impact of cost reductions, impact of seasonality (normal) and impact of price rises. Each one can be tracked back.
Quite how investors and the market missed all this and seem to continue with the perception that H2 was somehow too “ambitious” is beyond me. People are taking a straight line approach to the numbers without paying any attention to the business context or when certain initiatives kick in during the financial year. No one should ever value a business that way, its bonkers.
It’s not like the H2 expectations anticipate large extra volume growth that might be tricky to generate either. If it was then I’d take a different view.
So the risk is the same as for any year, ie. they are dependent on Christmas trading being normal. If it is then they should meet expectations, if it is weak that would be a problem. The rest is noise and seems to be some invented narrative that doesn’t bear resemblance to the reality. I’d have sympathy for that if the CFO hadn’t been quite so clear in their presentations but given that he spelt this all out it really does beg the question as to what analysis investors are actually doing.
SDI (LON:SDI) were a multibagger for me some years ago. In those days they funded their acquisitions from earnings and had low levels of debt. They then started to borrow heavily in order to fund new acquisitions, and the share price plummeted. Debt is still almost three times operating profit, so for me they are still too heavily indebted.
I don’t really get how warpaint is amber green simply because it didn’t do an ahead of update, the forecasts already have good growth figures that any o Neil disciple would have been pleased with and very favorable forward commentary. I doubt anyone will get much on the retail placing so you’re best buying the bullet and getting what you can before this retests highs imo
Goldplat has announced that it expects a profit before tax of approximately £6 million for the year https://x.com/Spread_Bet/statu...
Card Factory (LON:CARD)
Undoubtedly the shares are cheap for a company that is currently trading in line and on balance appears to have completed a decent acquisition. Management is cognisant of the financial headwinds posed by the Budget. Would the CFO spend £20,000 today on shares, admittedly a modest sum, if he didn’t consider the the risk/reward was in his favour, if only 55/45?
Difficult call, anyway I have reopened a position, again modest, so if things go pear shaped it would bring the house down.
Congratulations to all the writers of the Daily Stock Market Report.
The views have never been so well balanced and provide a solid basis for further research.
All the best
Yiannos1 a second to an excellent contribution!
Your understanding and challenge is missed!
FRAS I bought a small position earlier today. Wish me luck. Results are a bit manky, to be sure, but it's trading on a PE of 7, P/FCF of 8, and EV/EBITDA of 5.5. Cheap as chips, innit.
ROE has also been pretty good, and the interest cover is also OK. Revenue growth has been pretty good.
It's the top holding of Aurora UK Alpha (LON:ARR. I saw a presentation by them some time ago (alas I can't find my notes or a link off the cuff), which swung me further in favour of Big Mike's outfit. FRAS operates a duopoly with JD. They also have a distribution centre that is highly efficient and gives them a scale advantage. There's also an angle that they have plenty of scope to expand in luxury goods. Luxury goods aren't exactly on everyone's buy list right now, of course. So there's an element of faith that things will come good.
So there's an element of risk (are shares anything but?), but I decided to have a punt.
They actually have some decent quality characteristics in recent years with rising ROCE, NAV and operating profit. My only concern is that every time I visit my local store it is like a graveyard. However, I think it is a good punt given the duopoly you mention.
Card Factory (LON:CARD) cfo buys 21k shares
Software Circle (LON:SFT) [Mkt Cap £93m, 24p unch.] Today's H1 results see return to profit.
They describe themselves as "Home to a growing family of software businesses, across a variety of sectors including, Graphics, E-commerce, Finance, Property and Care Management"
Thinly traded with 5% spread, I hold for the recovery play
Results from Future (LON:FUTR) for the full year reaffirm my opinion that it is undervalued (I hold).
Sales were flat and adjusted EPS down 12%, which might account for the lowly rating. What I like about this share is the high cash generation. In latest results free cashflow was £230m, down 5% on the prior year.
Given the enterprise value of £1.4bn and equity value of £1.1, this level of cashflow makes the shares look cheap. Perhaps the markets perceive the gearing of 1.1X (£256.5m debt) as too high for the type of business, though I notice net debt reduced in the year.
Future (LON:FUTR)
Hi Mark
I'm not sure why the company has emphasised this £222m Adjusted Free Cash Flow figure, as it excludes taxes and interest payments.
It looks likely that debt levels will be maintained at their current levels so I'm not expecting the latter of these to go down anytime soon either, especially as interest on the debt is fixed at c6%.
FWIW the Abtan Adjusted Free Cash Flow calculation (TM) comes closer to £140m.
£140m of cash generation vs an EV of £1.5b looks like the lowest it should be in my opinion.
I personally apply a multiple of c. x13 to reflect:
Rationally speaking therefore, there's still more upside to come, but I am now tempted to reduce my holding after today's results.
I must admit to being in 2 minds on this though for several reasons:
On this last point I went into the detail and calculated that Car Insurance revenues increased 26% vs last year, with "Other" GoCompare revenues up 32%.
It's probably sensible to add that:
However, if GoCompare can continue to grow its 'Other' verticals, then there could be upside here as well.
On reflection I will probably take some profits off the table, but keep a FOMO holding in case the company is able to return to the c £190m of free cash flow it was generating just a couple of years ago.
A
Warpaint London (LON:W7L) Mark, 'However, surely no bank would worry about lending a £400m market cap company £5-10m for an acquisition.' I recall from watching Sam Bazini's presentations that he has a strong aversion to debt. (I hold)
Agree and I suspect there is an element of working capital required by Warpaint London (LON:W7L) to increase stock as they scale further and also to increase the marketing spend on the newly acquired brands.
Shein I do hope it's a success. If it's a complete flop over the medium term, then it won't help the credibility of the UK stock market. It's a pretty speculative share, so expect a lot of volatility.
Look at the share price of Alibaba Holding (NYQ:BABA), for example. Floated in 2014 at ~$94, it went over $300 in Oct 2020, but now crashed to $85, below its IPO price. Ouch. According to Yahoo it has a PE of 18.
Now that I look, I'll tell you what's strange about BABA. It had total revenues of CNY 941.1b for its Y/E Mar 2024, and and total current assets of CNY 752.9. That's a ratio of 80%. That's vastly higher than the figures you'll see for UK retailers.
Chinese companies seem to keep excessive amounts of cash. "Short term investments" went from 32.7b in 2020 to 323b in 2024. How was such a feat accomplished? I don't know what's going on (this is the first time I've looked at their financials), but I'd actually be worried about this. We've seen Chinese AIM companies in the past that have exhibited these kinds of characteristics, and they've ended badly.
Sad to say it, but everything Chinese always seems a bit iffy. The only consolation is that BABA has been listed for a decade, so any nasties should have come out of the woodwork by now.
Mark - are you not aware that anything that exists in China only exists to the extent that the Authorities allow it to exist. eg if the authorities say tomorow they want all of the assets trade and cash that the company has the company will hand over everything asked for if it wants to continue to have any connection or dealings with China - or even if the relevnat important people feel the need even if that is not in the interests fo shareholders. china has specifically asked Alibaba previously to hand over billions of pounds at short notice and then company has complied.
Everyone who invests in any company earning its crust form China must know that fact and discount accordingly.
I am somewhat gobsmacked that you find anything strange about this companies finances - you should be fully epxecting everything to be odd as practicably speakaing anything China related is ultimately owned by China PLC and the technical owners only have temporary custodionship of the stuff the powers that be are happy to let tham have (for now)
so any nasties should have come out of the woodwork by now.
these comments suggest to me you have no idea how things work in China - similar logic has previously been used before with this very company. That was prior to China saying oh and can we have £2 billion now please and the company hapily hander over £2 on request.
hey ho good news for shareholders is that the company are paying dividends so hopefully some payback for owners for now.
Note this is not a prediction on my part that China would screw over shareholders here in the future - just that anyone not presuming that couldnt happen anytime in the future imho doesnt undersatnd how china works at the most basic level!
Frasers (LON:FRAS) Graham, you refer to JD in the analysis, should that be SportsDirect?
snowdrop, I've edited it to clarify that Frasers have right-sized the brands it acquired from JD.
Sorry, I forgot they had bought some JD brands.
Graham, I'm worried that the new focus means that DSMN is simply trying to do too much and too late in terms of daily announcements coverage. I appreciate that resources are limited and apparently not all writers work full time, but having one writer attempt to cover nine companies today seems over ambitious. The only write-up you have published in the first 90 minutes of market opening is Frasers' profit warning, which ideally should have been subject to some snap analysis BEFORE the market opened -- not just flagged in the summary table.
Are there any plans to tighten coverage and make it more time sensitive?
Hi Jeff, it's 9.55 and we have four companies covered now. I appreciate the thought that some snap early analysis might be helpful for profit warnings. We are always trying to get faster. On the goal to cover nine companies by one writer - I admire his ambition! His goal is to cover more companies faster which I think is consistent with what you are asking for? G
Never bought from Shein, is it a similar set up to Temu, which has many different sellers?
Graham - I see that Marlowe (LON:MRL) is missing from today's list. They have released interim results this morning. This might be a tricky one to analyse after all the disposal and de-merger activity but nevertheless an interesting stock for exposure to the trend of ever increasing testing and inspection requirements in regulated industries. Any chance of a look at the numbers? Thanks.
sorry sparkler, this one was overlooked. G
"How would you feel about investing in Shein?"
My thoughts are not that important. Institutions must be interested or the idea would not have got this far down the line.
Agreed. Who cares what small punters think? It will either happen or it wont based on institutional appetite and "market conditions". Why bother discussing here the hypothetical investment case for a company you can't yet invest in?
Carclo (LON:CAR) update looks reasonable. Board confident of meeting full year expectations. EPS 2025 still aiming for 6p. Stock cheap at 35p if this looks likely. I hold.
Is the gearing not very high ? Net debt is £25.4m
Will you be covering Water Intelligence trading update?
Graham previously suggested that he would like to see margins improving before giving a better traffic light score. Margins remain at the same level but the update suggests that the building blocks for improved margins are being built steadily and coherently. I hold and may add on any dips.
Shock horror! UK company Card Factory (LON:CARD) buys a foreign one :-)
Looks on the face of it a good deal. Plus if board are still confident of meeting full year expectations the price still looks attractive.
About time UK companies were buying abroad - at the rate of foreign companies buying UK there won’t be much left in the UK market otherwise!!
Card Factory (LON:CARD) has fallen from 150p to 90p over the course of the last few months despite being in-line with expectations all the way through. Bizarre investor reactions to very well flagged expectations in H1. Not unsurprising in this market though as too many investors dont seem to look at anything other than headline numbers. Anyone doing even reasonable diligence could see how H1 to FY results map out. The CFO even provided a bridge slide showing where cost reductions would be realised, how price rises impacted and normal seasonality (based on previous years) play out. It is quite simple - unless actual trading was weaker than expected then the results would be in line with the 14.5p eps.
Today they have said start of festive period has started well but obviously they still have to trade through the key weeks so I think it really is as simple as a view on how investors consider Christmas trading to look like in general. If you think it will be fairly normal then Card Factory (LON:CARD) look unreasonably cheap to me at a PER of 6, if you think Christmas trading will be weak then you’d be looking at downgrades to the EPS.
Acquisition looks pretty good to me. If they can get a strong foothold in the US that’s potentially game changing. I dislike UK companies entering the US market by themselves as I think it nearly always goes wrong. I’m a much bigger fan of buying a decent business already located in the US, retaining management and growing from there, so I am glad Card Factory (LON:CARD) have taken this approach. MPAC (LON:MPAC) were an example of a company that did that US acquisition very successfully previously and made a big difference.
Card Factory (LON:CARD) Agree - the headline H1 numbers looked very bad but if you drilled down you could see they were actually well positioned to meet full year guidance. Underlying revenue growth was solid in H1, but profits hit by the fact they hadn't yet taken measures to offset higher costs - the fact this occurred in the much quieter H1 period meant the operational gearing impact was quite strong (costs are largely fixed and evenly spread over the year, so profits down sharply in percentage terms). Importantly, they seemed to have a credible plan to offset costs in H2 (price rises, cheaper cards, etc) so was always fairly hopeful that they would deliver - it surely can't be that difficult to increase card prices by a few pence, and perhaps make a few other savings here and there. I guess we'll see in January.
Card Factory (LON:CARD) suspect the disproportionate increase in UK postal charges will lead to reduced sales this Christmas.
Couldn't you say the same about Moonpig (LON:MOON) who are 100% reliant on postal services, whereas many of Card Factory (LON:CARD) customers can give in person....at Christmas....
Card Factory (LON:CARD) Second class postage has not gone up. I give out far cards than l send.
The Shein topic is an interesting one. I haven't had a proper look at the company from an investment perspective, but from a consumer perspective, I never touch it.
Perhaps I no longer fall into the bracket of 'ideal consumer' for Shein (I'm 32), but even among younger audiences I do feel the trends are swinging away from fast fashion.
ESG might not be quite as 'in vogue' as it was a few years ago, but environmental consciousness does still turn people away from the type of cheap goods sold by the likes of Shein, Asos and Boohoo. And the extensive packaging which comes from buying online.
Two of my younger sisters (22 and 26) like to frequent charity shops for their clothes, because they're cheap, good for the environment and (if you get good at charity shop shopping) good quality.
There is an interesting discussion on the Week Ahead thread about LuluLemon, which is the polar opposite to Shein - high quality, high price, strong brand, high barriers to entry, impressive margins.
I know which company I would rather shop at and I know which stock I would prefer to buy.
I do a lot of work with teenagers around Europe. Shein often comes up in conversation. They all seem very happy to buy clothes from Shein and talk about how good Shein is to buy from. Maybe ESG is not as important in Europe as it is over here? All I know is the kids I speak to say they frequently use it and love it.
I first remember seeing their name somewhere on youtube or something about 10 years ago.I never thought they'd get this big to be fair, but paid no attention to the sector (was never a Boohoo (LON:BOO) investor).But then again Primark, Boohoo etc... are and/or have been very popular for a long time.
Fast, cheap fashion which you can potentially wear a new outfit every weekend, it doesn't matter if it's trashed and throw it away, if you're at university or early 20s.I think they're big on TikTok, and make full use of social media, and have evolved with the poplarity of TikTok and influencers.
What 'we' prefer and what the market/customers want may not align.
Despite being aware of all the ESG concerns, all the teenagers I know are flocking to SHEIN and cannot be bothered to actually visit physical stores, unless kicked and dragged - and then will only want to visit vastly overpriced stores like JD Sports.
If SHEIN start to have a physical presence, then the game is over for lots of retailers.
I agree viz, reminds me of a middle class family on TV who'd recycled a pallet for use as a coffee table, they thought it was great and they were helping to save the planet. Anyone who has to save up for something nice for their house wouldn't be seen dead with an old pallet in their living room.
I've bought from Shein before, the service was good and the quality fine. After all the fuss politicians made about Boohoo, why wouldn't customers buy from Shein especially now the same politicians are keen on a London listing.
I think a lot of ppl say ESG is important on the one hand and even claim to be very pro ESG but then flock to Shein etc because it's the cheaper option still without seeing the hypocrisy in it. Same with a lot of things. But hey, we're all hypocrites really.
Lululemon Athletica (NSQ:LULU) is a very controversial company. Some of their goods are made in China. Just because they charge high prices does not make them better.
I think from an ethical perspective it is hard to get behind Shein.
Allegedly chemical toxic clothing, violating labour laws, 75 hour working weeks, ripping off designers, an unverified supply chain. Interesting article explains it all well https://www.elle.com.au/fashio...
That's not to mention the quality of the goods - a sacrifice they make to match the crazy scale and low cost of output.
Hopefully fast fashion continues to decline and consumers turn their backs on companies like Shein but as times get harder I can see how some people will be attracted to the major discounts and plead ignorant to the social and ethical issues.
I invest in Lululemon Athletica (NSQ:LULU) so I am biased but agree that whilst they've had some scandals with the previous CEO, I can sleep well at night knowing they're nothing like Shein.
Two of my younger sisters (22 and 26) like to frequent charity shops for their clothes, because they're cheap, good for the environment and (if you get good at charity shop shopping) good quality.
Megan, good on them for thinking of the environment!
I have to say though, I hate charity shops!! They are bad for the economy. Everyone complains about how the town centres are dying. Charity shops do bring in more people to the towns but let’s face it, that is all. They only pay a manager in general, staff they get for free. They undercut the real shops making it hard for them to exist. They do not pay tax, rates or employees. How are the real businesses meant to compete with that? Don’t get me wrong, many of the charities do a Stella job but how much of the money they raise actually goes to the needed? I always remember when the banks were hit and the Icelandic bank went bust. A pet charity lost so much money, so much in fact that they could have vaccinated every cat and dog in Europe. So why did the charity have so much money just sitting in a bank.
If people want to give to charities, setup a dd, don’t help them destroy our town centres because the small business can not compete with them which means less taxes are paid and then we end up paying more in other ways.
Sorry, rant over.
My main concern is that fast fashion is not supportable by our planet. There will come a time when governments will be forced to introduce regulations to make companies deal with end of life products. Charities can't currently cope with the volume of clothing being donated and a large portion of it ends up being shipped abroad to places like Ghana, where it stacks up on beaches and pollutes the sea https://earth.org/statistics-a...
Unfortunately, people don't actually think about the macro economics, when they can donate a fiver to 'Africa' and pat themselves on the back for believing they are somehow intellectually/socially consciously superior in doing what they do.
Seems like a sensible acquisition for Warpaint London (LON:W7L) . Earnings enhancing in calendar 2025 due to strong operational synergies. Retail placing of £1m, to which I will probably subscribe. (I hold).
I have no interest in the IPO of Shein. I am not going to support Chinese companies intent on taking over our retail sector, either by investing in them or buying from them.
Curious - or inept - is why the new government didn't close their tax loophole, while going after farmers and raising capital gains tax. Cathy Wood was on R4 earlier saying the 20% top rate of CGT in the US is significantly why they have a big venture capital industry which is a catalyst for growth companies. Very bad mistake by UK gov, she said, putting UK at a competitive disadvantage.
Reaction
hardly surprising ineptness is the government major skillset
Warpaint London (LON:W7L) I like this deal and I am a big fan of this business, but I am surprised a £400m mkt company can't self fund such a small £14m acquisition, or maybe just me?
Hargreaves Services (LON:HSP) - Solid trading update, the cash machine that is HSP continues as it follows its asset realisation plan and continued strong performance.
Card Factory (LON:CARD) buys Garv
en, a U.S based retailer of cards. This appears to be not related to a deal they have with 1100 other wholesale retailers.
They still maintain they are on course to meet expectations, so the recent 40% drop looks well overdone, large bounce today expected, but in this market who knows.
Decent trading update Card Factory (LON:CARD)
Trading in the second half to date has been in line with our expectations and we have been encouraged by the start of the Christmas season. Our programme of productivity and efficiency savings, as announced at our Interim results in September 2024, also remains on track. Our expectations for the full year are unchanged, albeit we are yet to trade through the peak Christmas trading period. We will provide a further update to the market in our January trading statement which is scheduled for 14 January 2025.
Stocko has eps 14.4p for FY 1/2025. Yields 5.5%, p/e of 6.28 with peg 0.57
Interesting topic Graham. I’ll look forward to what people have to say on this.
Another £2.7m in contracts for Synectics (LON:SNX) . I wonder if broker will upgrade forecasts.
The Today programme contained back-to-back interviews with Cathy Wood and the CEO of Premier Miton (LON:PMI) this morning. Topics covered included crypto currencies, the disincentives to invest in start ups in the UK and the UK small cap investment world. You can listen on BBC Sounds starting at 06.17.
Yes, dreadfulPremier Miton (LON:PMI)
Why dreadfulPremier Miton (LON:PMI)?
There’s a longer interview with her on R5 Wake up to money 5am-6am…Gervais Williams was a guest on that whole show
Guys CW is a media guru only when tech is on a meteoric rise, evil when it's going down. Gervais is stuck record on U K small caps. And the PM director incentives shown in the recent results show why. The BBC should have a media trained Stocko hack on! Or for real click bait Yannios1!
GW like others in the industry have to talk their own book, so are always bullish.
This is a guy who wrote a book in 2013 " The future is small: why AIM will be the world's best market beyond the credit boom.
Turns out its probably been the world's worst market since.
Taking financial advice from Cathy Wood and Gervais Williams is like taking medical advice from Harold Shipman.
The great UK fund manager that very strongly supported 8 years ago that ETF’s should be dismissed by investors and at the end will just vanish into thin air…….
What a prediction by a fund manager!!!
All the best
Darkest before down and all that ;-)