Daily Stock Market Report (Thur 7 Nov 2024) - BMS, NOVO, KITW, SFOR, ITV, WG., MCG, TRD

Good morning! And welcome to today's report.
I've made some adjustments to our summary table: the company name and the ticker are now in the same column, freeing up more space for our brief comments. Thank you for all the suggestions yesterday - I hope this is an improvement! Cheers.
1pm update: the report is finished for today. Thanks for all the feedback!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices).
My video explaining/reviewing it. My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Agenda
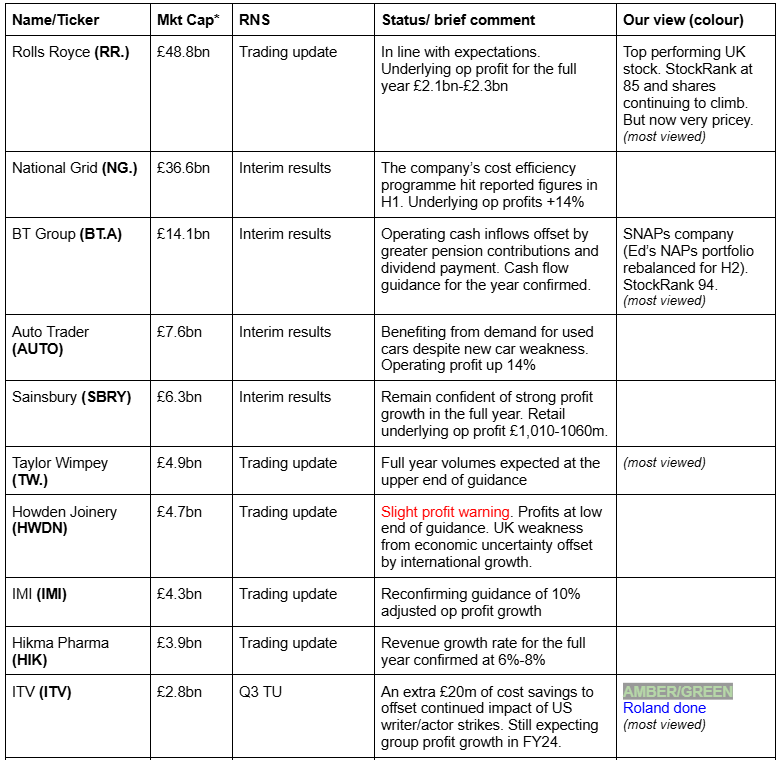
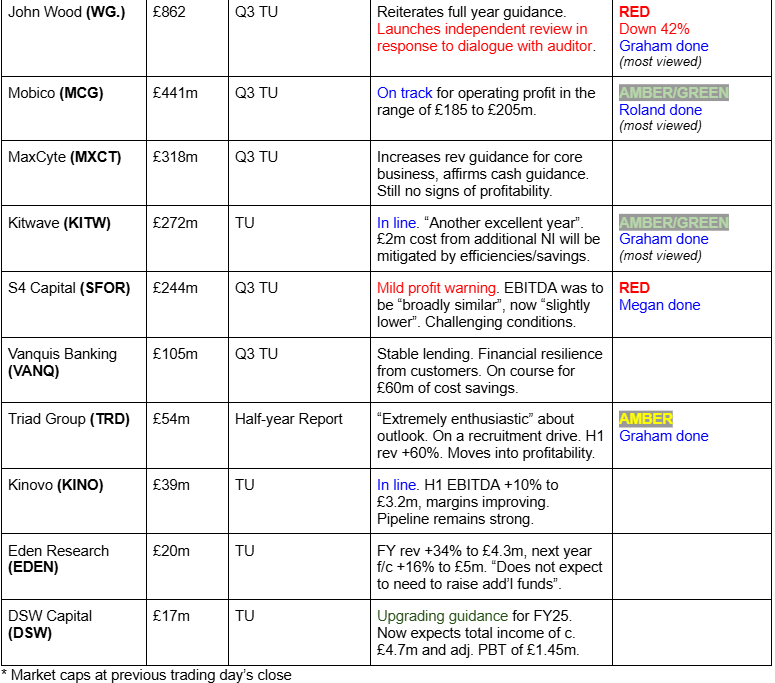
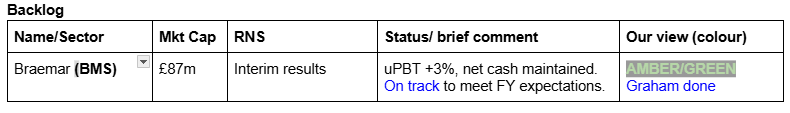
Short Sections
Novo Nordisk A/S (CPH:NOVO B) - up 4% yesterday to DKK750 (£370bn) - third quarter results - Megan - AMBER
The problem with launching a drug as successful as Novo Nordisk’s Ozempic is that the whole industry wants a slice of the success. Since Eli Lilly launched its own weight loss drug earlier in the year, shares in the Danish pharma company (the largest listed business in Europe) have been sliding.
Results this week suggest that investor concern was perhaps premature. Eli Lilly has struggled to get its weight loss drug off the ground, but yesterday, Novo Nordisk revealed that sales in Ozempic were up 48% on the previous quarter to 17.3bn DKr ($2.5bn), some way ahead of the 15.9bn DKr forecast by analysts.
Ozempic is part of a category of drugs called GLP-1 inhibitors, which support weight loss by stimulating hormones to suppress appetite. It’s a class of drug that has also proven success in patients with type 2 diabetes. Diabetes is at the heart of Novo Nordisk. It was the first company in the world to commercialise injectable insulin for diabetes patients and it now boasts a 33.9% share of the global market.
The combined strength of the weight loss and diabetes indications of the GLP-1 bracket of drugs sent sales in the first nine months of the financial year up 24% at constant currencies to 204.7bn DKr.
Importantly, for investors, Novo’s management confirmed its guidance for the remainder of the year, with sales forecast to rise between 23% and 27%. Shares rose as much as 12% yesterday.
The challenge for Novo Nordisk lies beyond 2024. Pharma companies can never rest on their laurels and enjoy the success of one star drug, they have to keep innovating to avoid the patent cliff (pharmaceutical patents expire after 10 years).
In the first three quarters of 2024 the company has invested 13.3% of its sales into research and development, which is a decent measure compared to some of its peers, but could be higher given gross and operating profit margins at 84% and 47% respectively.
Novo Nordisk is an incredible company, but it’s shares are too expensive at 27 times forecast earnings. And investors should beware a change in momentum from high quality companies. Once momentum reverses, it’s quite hard to regain. AMBER
Triad (LON:TRD)
Down 2% to 323p (£54m) - Half-year Report - Graham - AMBER
It has been years since we’ve said a word about this IT consultancy.
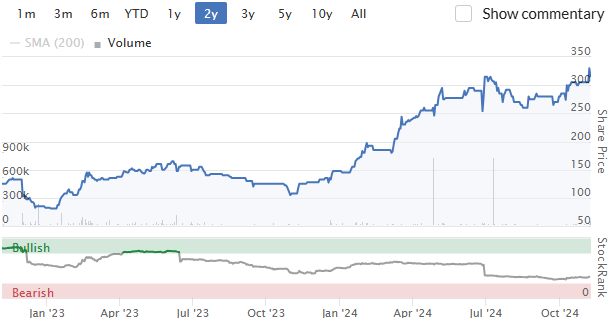
The share price has multi-bagged since 2023, giving it a more respectable market cap:
Let’s quickly check the half-year report, to see what all the fuss is about.
It has moved into profitability on significantly higher revenues in the latest H1 period:
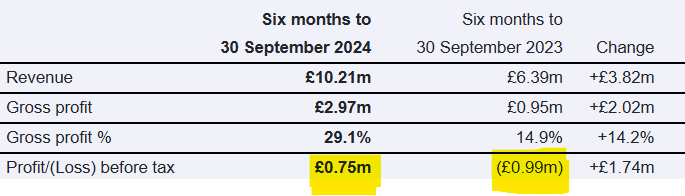
The Chairman is ebullient. Some snippets:
The six months' results up to 30th September 2024, reported today, reflect a sound and sustainable transformation…
We are building long term relationships which will enable us to provide additional operational and financial benefits to the public sector and thereby support the new Government in its welcome drive to apply the benefits of digital technology to efficiency and cost control….
Our cash balance is strengthening nicely and reflecting the increase in profits with the usual slight lag due to payment terms. We are continuing our recruitment drive and focusing even more closely on the very highest quality of new joiners.
Interim dividend is maintained at 2p.
Cash improves to £2.9m at the end of H1, up by £0.8m in six months. There are no financial debts, only the usual payables and leases. The balance sheet as a whole gives me no cause for concern.
Graham’s view: I applaud these results, although it’s not clear to me how a £50m market cap makes sense. It’s a consultancy, with very low profit margins, trading at a price to sales multiple of almost 3x. Why? Perhaps we have readers who’ve already studied this in depth, who might chime in?
On valuation, I’d be AMBER/RED but as I’ve not studied it for some time and don't want to put the boot in unnecessarily, I’ll just leave it at AMBER for now.
Summaries
Braemar (LON:BMS) - up 3% yesterday to 274p (£90m) - Interim Results - Graham - AMBER/GREEN
This advisor to the shipping and energy markets has confirmed that it’s on course to meet expectations for FY February 2025. Valuation is on the cheaper end of the spectrum at a single-digit PER (if you’re happy to go along with the company’s adjustments) so I’ve left our mildly positive stance unchanged.
S4 Capital (LON:SFOR) - Megan - down 12% to 34.58p (£242m) - Trading Update - RED
The digital marketing company has reported disappointing revenue figures for the third quarter of 2024 after lower spending from a major client. Revenues for the year are now expected at the lower end of guidance. There is not a lot that I can see to like in this company right now, so am downgrading our view to RED.
Kitwave (LON:KITW) - down 2% to 331p (£266m) - Trading Update - Graham - AMBER/GREEN
This food distributor announces that it believes it has hit expectations for the full-year. Currently trading at a PER of about 10x, I take a look at its recent large acquisition (£60m) and come away with a positive impression. This is a candidate for an upgrade to GREEN in due course.
John Wood (LON:WG.) - down 44% to 70p (£482m) - Q3 Trading Update - Graham - RED
Full-year guidance is reiterated but serious questions are raised around previous results and the value of Wood Group’s balance sheet positions. With net debt last seen at nearly $700m, weak profitability and a balance sheet that’s deeply in the red, I’d steer well clear of this.
ITV (LON:ITV) - down 9% to 65p (£2.6bn) - Q3 trading update - Roland (I hold) - AMBER/GREEN
Ad revenue is up this year but ITV Studios continues to struggle with knock-on impacts from the Hollywood strikes. This update suggests that ITV Studios revenue fell by nearly a third in Q3. A strong Q4 performance and cost-cutting mean that Studios’ adjusted profits are still expected to set a new record this year. I think the value appeal remains, but I wonder if the bear case is getting stronger.
Mobico (LON:MCG) - up 5% to 75p (£457m) - Q3 trading update - Roland - AMBER/GREEN
A broadly positive update from this bus company, flagging up strong progress in Spain and continued challenges in the UK and Germany. FY profit guidance is unchanged while the planned sale of the North American school bus unit remains “on track”, providing a potential opportunity for rapid deleveraging.
Graham's Section
Braemar (LON:BMS)
Up 3% yesterday to 274p (£90m) - Interim Results - Graham - AMBER/GREEN
We had a reader request on this from JASVFS so let’s take a look.
I remember this company as “Braemar Shipping” (or “Braemar Shipping Services”).
It currently describes itself as “a leading provider of expert investment, chartering and risk management advice to the shipping and energy markets”.
Paul studied it in May, eventually concluding with AMBER/GREEN.
Yesterday it published interim results. Key points:
“On course to meet market expectations”, these being revenue of £150.8-154.7m, and underlying operating profit of £17.4-18.4m. Braemar's year-end is in February, so still a few months left to determine the final outcome.
Underlying operating profit in H1 was £7.3m. That’s a nice increase on the prior year (£6.7m) but leaves plenty to do in H2 to meet the full-year target.
Net cash is modest at £3.3m. Not much change there.
The interim dividend of 4.5p is well-covered by underlying EPS of 14.55p, but not so well-covered by statutory EPS of only 6.83p.
Which brings us to the thorny question of adjustments. Fortunately these have declined in the most recent period.
In H1 last year, the company identified £4.5m of “specific items” (i.e. adjustments). This tripled the operating profit of £2.2m to “underlying” operating profit of £6.7m.
In H1 this year, the company makes only £2.7m of adjustments.
This inflates operating profit from £4.6m to an “underlying” operating profit of £7.3m.
The adjustments are:
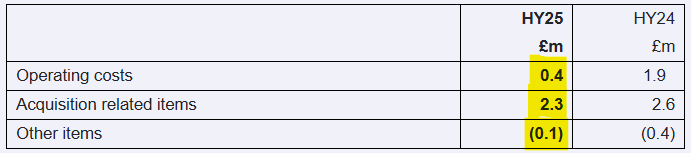
This again goes back to modern accounting rules which require some acquisition payments to be treated as employment costs. I agree with the logic behind these rules! But I accept that they can make things a little fuzzy for investors.
My suggestion is to allow the £2.3m adjustment for acquisition-related items but to be aware of what this item emphasises: that the acquired company (Southport Maritime) might rely heavily on the continued employment of certain key individuals
Outlook
Market conditions are “healthy” and the forward order book is “strong” at $85.8m (Sep 2024).
The diversification across shipbroking and the growing securities business is delivering a more balanced business with sustainable revenue
Opportunities exist for both organic and inorganic growth with a number of complementary opportunities being considered, and the executive team remains focused on further executing the Group's growth strategy
Balance sheet
There is officially £85m of balance sheet equity but take out goodwill and other intangibles and you’re left with only £11m.
The interim balance sheet has cash of £26m but that’s offset by long-term borrowings of £25m.
Overall, I don’t see the balance sheet supporting the valuation here.
Graham’s view
I’m inclined to leave AMBER/GREEN alone here on the basis that it’s trading at a single-digit earnings multiple so there isn’t a great deal of optimism priced in already.
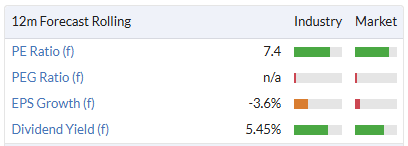
It does have a respectable track record of profitability and dividends, and quality is not bad.
In summary: I don’t see this one shooting the lights out, but it could be worth a deeper investigation at this level.
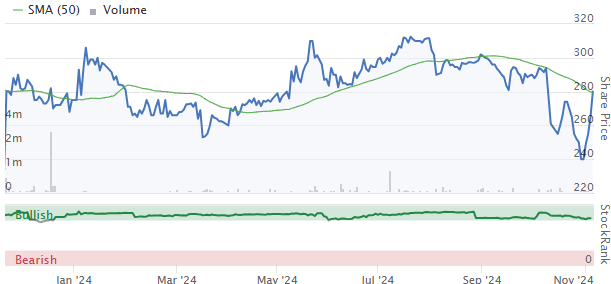
Note that the big falls in October relate to media reports around the company’s dealings as they relate to Russia
“Russia” was not mentioned in yesterday’s results announcement and I don’t think Braemar has said much about these allegations. Judging by the bounce back in the share price, perhaps they are not too relevant to the investment case.
Kitwave (LON:KITW)
Down 2% to 331p (£266m) - Trading Update - Graham - AMBER/GREEN
Kitwave Group plc (AIM: KITW), the delivered wholesale business, today announces a pre-close trading update for the year ended 31 October 2024
We’ve been AMBER/GREEN on this one for a while, with Paul’s most recent coverage in September suggesting that the risk of an H2 profit warning had abated.
Today we get a full-year update which confirms that yes, the company believes it has hit expectations for the financial year (FY Oct 2024).
Kitwave IPO’d in 2021 but unlike so many IPOs from that year that turned out to be duds, Kitwave has gone from strength to strength.
The company has a “buy-and-build” strategy in the food wholesale distribution sector. It now has 37 depots in its network, having made 15 acquisitions over the years (including in the decade prior to its IPO).
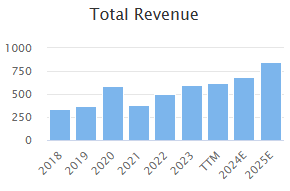
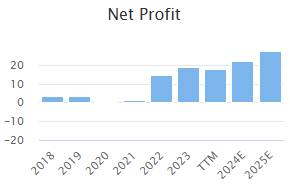
It appears that the M&A strategy has been a big success. Revenues:
Net profit:
And earnings per share:
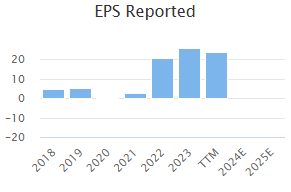
All of this growth was achieved without share count dilution - until this year.
In September, the company announced a £70m acquisition (of which £60m was payable upfront). The target: Creed Catering Supplies.
KITW was already carrying c. £50m of net debt and therefore in order to help pay for this new deal, it issued £31m of new equity at 305p, resulting in the creation of 10 million new shares. A small retail offer accompanied this.
So its ambitious growth plans have ultimately resulted in some dilution for shareholders. But lenders and the company’s own cash flow have paid for most of the growth over the years.
Let’s get back to today’s full-year trading update.
Key points:
New 80,000 sq ft. distribution centre in the South West has opened as planned.
Budget: the increase in national insurance contributions was not anticipated and will cost c. £2m annually. KITW plans to mitigate it with “efficiencies and other savings” (not specified).
Summary:
As the Group moves forward, the Board believe the Company is well-positioned to continue to execute its organic and M&A strategy during 2025 and beyond.
CEO comment:
"I am delighted that Kitwave continues to make significant financial and operational progress. We are particularly pleased to have completed three acquisitions in the Period, taking our total to 15 acquisitions since 2011. The trade from Wilds of Oldham and Total Foodservice Solutions has now been integrated into the Group in line with plans, whilst we expect both trade and operational efficiencies from the Creed acquisition to start to be realised in FY 2025.
Estimates: many thanks to Canaccord Genuity for publishing a research note this morning. They reiterate their forecast for FY 24 adj. PBT of £28.5m (+3.4% year-on-year).
With the addition of Creed Catering, they see adj. PBT rising to £35.9m for FY Oct 2025.
Graham’s view
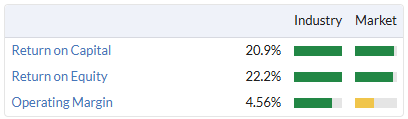
I’m inclined to maintain a positive view on this one, as it combines both a reasonable valuation (PER of 10x, according to both Stockopedia and Canaccord Genuity) with some really nice quality metrics:
I’m curious to check if they paid a reasonable price for the Creed takeover, so let’s take a look. Remember that Creed cost £60m upfront, plus another £10m contingent on performance in the first two years.
Creed’s figures: as of May 2024 it had trailing annual revenues of £130m, EBITDA of £10.2m, and adj. operating profit of £8.3m.
Applying corporation tax, we get a theoretical NOPAT (net operating profit after tax) of about £6m.
So in my mind, KITW has paid a trailing PER multiple of about 10-12x for Creed (£60-70m divided by £6m).
That’s Creed valued on a standalone basis. But within KITW, there should hopefully be synergies that boost performance and make it cheaper, in reality.
Comment by CEO Ben Maxted on the deal:
Creed has an exceptional heritage and is one of the UK's leading foodservice wholesalers, so we are delighted to have reached this agreement which will extend our Foodservice division.
Strategically, Creed will significantly expand our geographical presence, bridging our operations in the North and South and creating a fully integrated national delivery network. In line with our buy and build strategy, Creed is also expected to significantly enhance the Group's earnings along with providing material buying, operational and financial synergies.
I’m going to give this deal the thumbs up on the basis that KITW have probably not overpaid and it’s perfectly consistent with their strategy.
I rarely welcome share count dilution but using some equity to pay for the deal was probably sensible in the circumstances. Net debt is forecast to end the current financial year at £62m.
I’m going to keep us AMBER/GREEN on this one and I could consider switching up to GREEN if the Creed takeover proves to be successful over the next year (assuming no major increase in the share price).
John Wood (LON:WG.)
Down 44% to 70p (£482m) -Q3 Trading Update - Graham - RED
This short trading update has clobbered the share price.
It starts out fine, confirming full-year guidance in a large headline.
This guidance is for “high single digit growth in EBITDA and net debt to be broadly flat compared to last year” (assuming that a disposal completes by year end).
Q3 revenue is up 1% year-on-year.
Q3 EBITDA is “lower than last year” (not quantified) but the company says year-to-date EBITDA is up 4%.
At the interim results, adj. EBITDA was up 8.5% for H1. Assuming an even spread of EBITDA throughout the year, this suggests to me Q3 EBITDA might have been down by about 4%?
It’s at this point that the update starts to go downhill. Here’s the entire section covering the “independent review” (emphasis added):
Following the exceptional contract write-offs relating to the exit from lump sum turnkey and large-scale EPC reported at the half year 2024 results, and in conjunction with the auditor's ongoing work, the Board, in response to dialogue with its auditor, has agreed to commission an independent review to be performed by Deloitte.
This review will focus on reported positions on contracts in Projects, accounting, governance and controls, including whether any prior year restatement may be required. An update will be provided as appropriate following its conclusion.
The results presented in this trading update, and our full year outlook, are before any potential impacts from the independent review.
I’ve had a quick look at the half-year results referred to above and they are horrific: $219m of adj. EBITDA translates to an operating loss of $899m! There are nearly $1 billion of exceptional items.
Admittedly most of the exceptional items are goodwill impairment, but there’s also $140m under the heading of “LSTK and large-scale EPC”, i.e. lump sum turnkey and large-scale engineering, procurement and construction.
As I understand it, these are construction contracts where the contractor (in this instance, Wood Group) takes on the greatest level of responsibility to finish a project and, where a lump sum payment applies, the contractor is exposed to the financial risk of non-payment.
In 2022, Wood Group ceased operating in the LSTK and large-scale EPC business segments. But getting out of business is not so easy when there are very large liabilities between a company and its customers.
From the interim report this year, explaining the $140m of exceptional costs:
We continue to have a significant balance sheet position and claims exposure across some legacy contracts. The closure of these businesses, has reduced our leverage to negotiate commercial close outs and the staff involved have now all been exited from the business, making claims recovery or defence of litigation considerably more challenging.
The $140m hit included $53m of provisions against receivables (i.e. customers refusing to pay), $61m of provisions for additional claims (i.e. Wood Group being pursued by customers) and $26m of final settlements (Wood Group paying out to settle contracts with customers). What a mess.
Graham’s view
I don’t touch companies in this sector and this update from Wood Group doesn’t make me any more inclined to do so. What's worse is that the independent review seems to have been instigated by the auditor, not the company itself realising that it needed to figure out what was really happening with its contracts.
Having said that, you can always ask if a sell-off might be overdone. A fall of over 40% today, wiping hundreds of millions of pounds off the market cap, might be considered a harsh reaction.
But let’s go back to the interim balance sheet.
There were net assets of $2.6 billion. Deduct intangibles and you’re left with a tangible book value of minus $850m.
Now let’s look at some of the other items.
Receivables were an eye-watering $1.6 billion, i.e. multiples of the current market cap.
How much of this can be counted on to convert into cash? I don’t know, but it doesn’t sound as if the company is sure, either. And even if it converted into cash at an acceptable rate, the tangible value of the company would still be deeply in the red.
Checking the H1 income statement, I note that even if you leave out all of the exceptional items, the company still made a loss from continuing operations. Net debt, excluding leases, was nearly $700m.
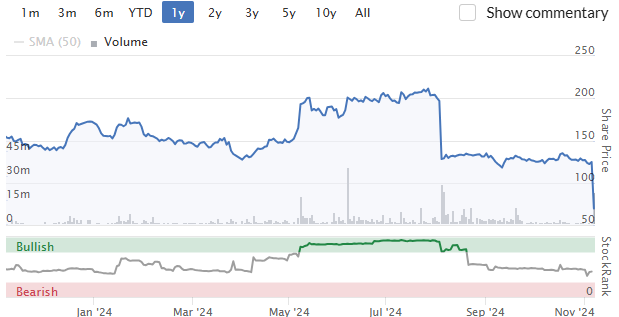
Unfortunately this has to be a RED from me due what I perceive as extraordinarily high risk and a lack of redeeming features. I tend to be biased against this sector, due to the general complexity of contracts and poor quality of profits. Perhaps a sector specialist would disagree with me, but for now I suspect that my negative bias against this sector is justified in this case.
Megan's Section
S4 Capital (LON:SFOR)
Down 12% to 34.58p (£242m) - Trading Update - Megan - RED
Martin Sorrell’s rationale for starting up a “tech-led, new age” digital marketing firm in 2018, after he was unceremoniously removed from WPP was a sound one. The company he’d left 47 years after he founded it, was struggling to modernise. A fresh start with a tech focus could have been a roaring success.
But for most of S4’s short life, the economy has not played ball. Marketing budgets tend to be the first ones to be slashed in periods of economic frailty and after a promising start, S4 has struggled to grow.
The company operates in three divisions - content, data & digital media and technology services - and all three have posted a material decline in revenue in the first nine months of this year.
Overall, billings have fallen 16% to £621m and net revenue for the year so far is down 13% to £555m. Revenues for the year are now expected to fall by a low double-digit percentage. House broker Dowgate Capital is forecasting net revenue of £748m in 2024 and £763m in 202, down from £873m last year and £892m in 2022.
The trouble, from a revenue perspective, cannot solely be blamed on challenging economic conditions. Global spending on digital media is expected to grow 8.7% to $564bn in 2024, according to media agency GroupM (a WPP company). Publicis, the world’s biggest marketing agency, reported a 7.4% like-for-like increase in net revenues in the first half of 2024 and recently upgraded its guidance.
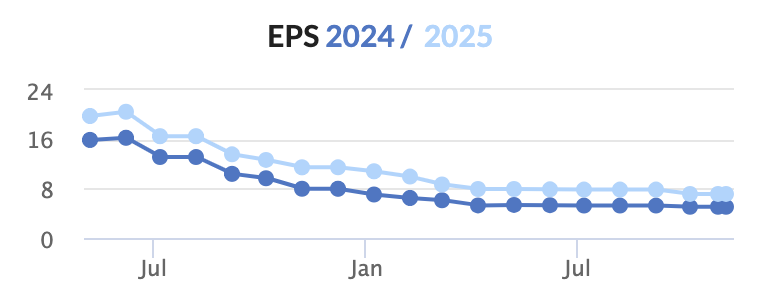
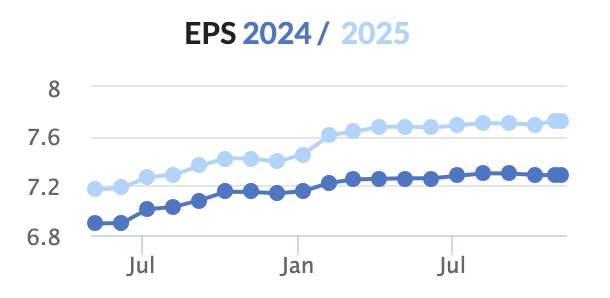
The following two charts show the difference in analyst expectations for S4 and Publicis respectively:
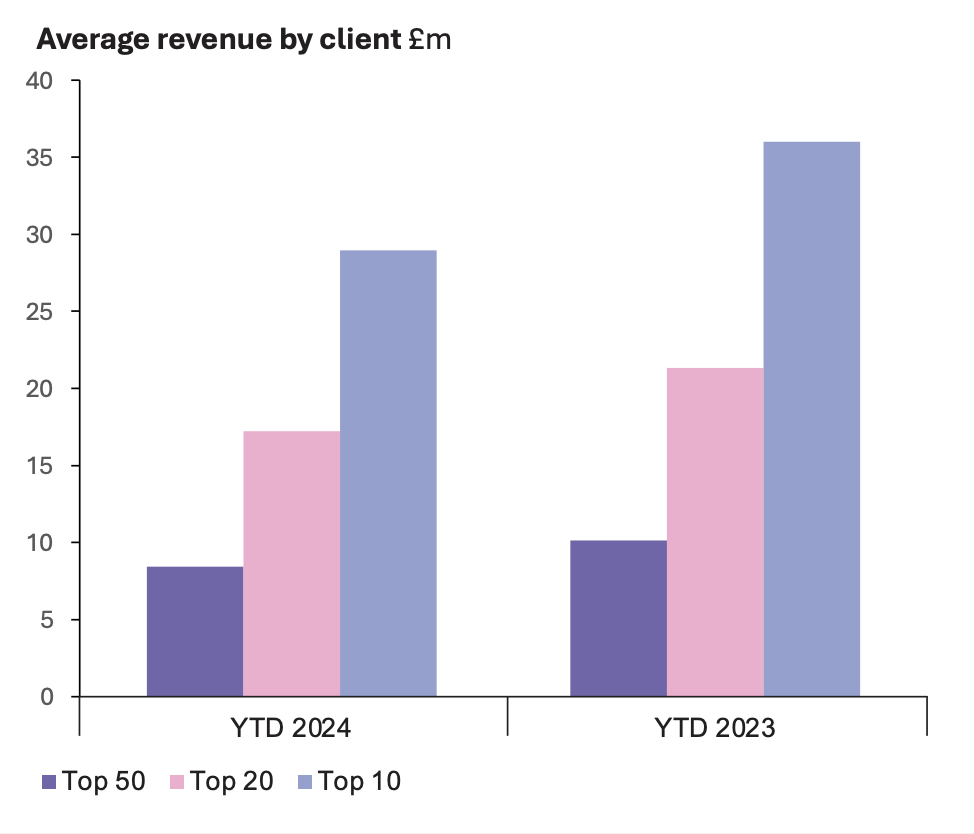
Instead, S4’s problem seems to lie in its exposure to a handful of major tech clients. Last year, S4 had 12 clients which spent over £10m each and contributed 55% to the company’s top line. This year that number has fallen to 9 and the biggest spending clients have only generated 45% of the group revenue.
Management blames the 42% decline in like-for-like revenues in the technology services business on decreased activity from just one key client. Over-exposure to just a handful of clients is a monumental risk.
The company says ‘operational EBITDA’ (which is a horrible measure of profits) is now expected to be slightly below the previous year. Dowgate Capital forecasts £85m of adjusted EBITDA, down from £94m last year and £124m in 2022.
Reported figures of profitability have been similarly worrying ever since S4 listed. Operating margins have never risen above 2.5% and the company has never reported net profits.
More concerning is the fact that S4 has reported operating cash outflows in both of the last two years. That is a particularly bad sign considering the company’s major debt burden, which stood at £313m at the half year point. Net debt is currently £180m, equivalent to 2.2 times EBITDA and well within the group’s financial covenants, according to management. That’s a relief from a bankruptcy perspective, but it’s never a great sign when a company has to reassure that it’s operating within its financial covenants.
Megan’s view: To my mind, there is not a lot to like about the way this company operates. Digital marketing could be an exciting and highly profitable industry to work in, but S4 has over leveraged and put itself at risk from its over-exposure to a small handful of key clients. What’s more, the company needs to innovate. Digital marketing is accelerating at rapid pace thanks to artificial intelligence and companies in this market are going to need deep pockets and creativity to keep up. Neither of which seem to be available at S4. RED
Roland's Section
ITV (LON:ITV) - down 9% to 65p (£2.6bn) - Q3 trading update - Roland (I hold) - AMBER/GREEN
(At the time of writing, Roland has a long position in ITV.)
ITV Studios is on track to deliver record adjusted EBITA in FY 2024, reflecting efficiency gains and a significant Q4 delivery schedule.
I’ll start with a confession. I have been long and potentially wrong on ITV for quite a while now. Although the stock is no longer a great fit in my portfolio, I’ve kept the position because I believe in the value on offer and I think the strategy and execution have been fairly good. There’s also been a useful dividend.
The StockRanks have also liked the shares, awarding it Super Stock status (until today) and suggesting a potential VM/turnaround opportunity:
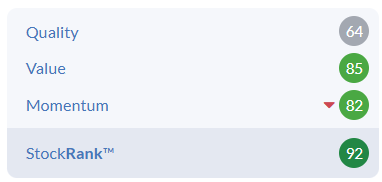
Today’s update has had a poor reception, suggesting it may prove a further test for long-suffering shareholders like me. Let’s take a look.
Q3 trading update: ITV’s business essentially has two arms, selling advertising (UK television) and selling programmes (ITV Studios, UK/Europe/USA).
The last couple of years have seen an advertising downturn described by CEO Carolyn McCall as the worst since 2009.
At the same time, last year’s Hollywood writers’ and actors’ strikes had an understandable impact on programme production pipelines. There’s been something of a slowdown in streaming growth as well.
It’s been a tough environment, but during this time ITV has remained in decent shape, continuing its shift to digital (ITVX) and the development of the Studios business.
That brings us to today’s update. Here are the headline figures for the nine months to 30 September 2024:
Group revenue down 8% to £2,321m
ITV Studios revenue down 20% to £1,217m
ITV Media & Entertainment (UK TV) revenue up 4% to £1,524m
M&E: The improved M&E result highlights some recovery in the advertising market and the benefit of the Olympics and World Cup this summer.
The final quarter of the year is expected to be softer for advertising than 2023, due to the Rugby World Cup last year. Pre-budget uncertainty is also said to have held back advertising bookings.
However, I don’t think there’s anything serious to worry about. Digital advertising revenue is continuing to rise (+15% YTD) and streaming hours on ITVX are still rising. Meanwhile, the broadcast business is protecting its share, with a 32% share of linear commercial viewing and 92% of the top 1,000 commercial broadcast programmes.
ITV Studios: unfortunately, ITV hasn’t provided Q3-only figures today. Checking back to the half-year results suggests why – it looks like Q3 was a truly dire period for ITV Studios.
My sums suggest ITV Studios Q3 24 revenue was £348m, down 33% from £516m in Q3 23. In its defence, the company has said previously (and reiterates today) that some of this revenue has merely been pushed back into Q4 and 2025.
Production deliveries are said to be “heavily-weighted” to Q4, leading to a full-year Studios result of revenue down by “mid-single digits”.
Looking further ahead, management specifically identifies £80m of revenue that has been pushed from 2024 to 2025 due to the strikes.
To offset these headwinds, ITV has been cutting costs furiously. In addition to £40m of savings previously announced, the company has revealed another £20m today, split equally between content costs and non-content costs.
As a result, ITV Studios full-year adjusted EBITA (effectively adjusted op profit) is expected to set a new record. For reference, in 2023 ITV Studios generated adj EBITA of £286m, 58% of group total.
Margin guidance is also reiterated – ITV Studios is expected to generate an EBITA margin within the targeted 13%-15% range.
Outlook: I don’t think there’s any formal change in guidance today, but I wouldn’t be surprised to see consensus forecasts edge slightly lower.
Prior to today, forecasts on Stockopedia suggested FY24 earnings of 9.1p per share, comfortably covering the 5p dividend. On that basis, today’s slump has left the stock trading at a potentially cheap seven times earnings with a 7.5% yield.
Roland’s view
Earlier this year, ITV shares received a notable boost when the company announced that its large final pension scheme would no longer require any additional cash contributions. This had previously been a big drag on free cash flow. Paul covered this here.
ITV’s balance sheet continues to look fine to me, fortunately. Footnotes in today’s update note net debt of £437m, or £573m excluding cash earmarked for the ongoing £235m share buyback. This is being done using the proceeds from the BritBox sale earlier this year.
This looks a reasonable level of indebtedness to me, relative to forecast full-year profit of £353m. ITV remains a double-digit margin business with good cash generation and high returns on equity – one of the reason I have persisted with the stock.
However, the bear case here is also worth considering, I think. As I see it, we could argue that ITV Studios will not grow quickly enough to allow the company to escape the drag of its declining core broadcast business. Similarly, while ITVX is growing fast, digital advertising is generally less lucrative than traditional broadcast advertising.
The result could be a perpetual struggle that remains (rightly) on a low valuation, unless a takeover offer materialises.
I’m not quite ready to sell my shares yet, but I am considering it more actively than I have done before.
One reason for this is that the outlook for 2025 has been steadily weakening; earnings growth next year is now expected to be much lower than previously hoped for:
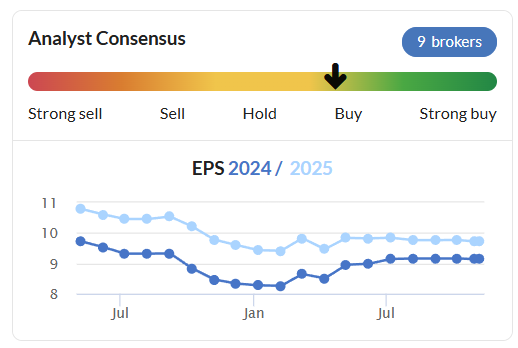
Paul rated ITV as GREEN in May. I would have made the same choice myself at that point.
But after considering today’s update, I think it’s sensible to go down a notch to AMBER/GREEN to reflect what I see as a greater risk of disappointment.
Mobico (LON:MCG)
Up 5% to 75p (£457m) - Q3 trading update - Roland - AMBER/GREEN
we are on-track to deliver FY 24 adjusted Operating Profit in the range of £185m to £205m, in-line with our earlier guidance
We’ve covered this international bus operator extensively this year, so it’s worth checking out the archive here.
Today’s third-quarter update suggests to me that progress remains on track across most of the group’s key divisions, with only a couple of softer areas.
The main headlines look reassuring:
Group revenue up 12% in Q3 versus 2023
Cost saving programmes on track to deliver £40m in 2024 and £50m annualised from 2025 onwards
Cash savings targeted to help reduce debt levels
Plans for sale of North American school bus business “on track”, update in due course
Drilling down, problems seem to be centred in the UK and Germany, with the core Spanish and North American units performing well.
ALSA (Spain): revenue up 23% vs Q3 23. This was boosted by the acquisition of CanaryBus earlier this year, unfortunately the company doesn’t provide an organic revenue growth figure.
However, we can see growth seems to be driven by passenger numbers more than price rises:
Long haul revenue +15%, passengers +14%
Regional revenue +13%, passengers +9%
Urban revenue +8%, passengers +7%
I tend to see an increase in volume as preferable to price-driven growth, especially in a heavily regulated sector like public transport.
ALSA generated 81% of adjusted profit and all of the group’s statutory profit last year, so it’s a key asset.
North America revenue up 19% vs Q3 23.
Revenue from the school bus business rose by 11% in Q3 due to rate increases and additional routes. This positive momentum should help with negotiating a sale.
The WeDriveU business (charter buses, I think) seems to serve corporate contracts and saw revenue rise 29% during the quarter, benefiting from customers consolidating their suppliers.
UK revenue fell by 2% during Q3. This was linked to poor performance at the UK coach business (National Express) which benefited from rail strikes during the same period last year. On a normalised business, Mobico says coach revenue was 4% higher.
The UK coach division remains in turnaround with several improvement processes actively underway.
In UK Buses, revenue rose by 2%, with passenger numbers up 5%. This is being distorted by government subsidies as part of the £2 scheme which are recorded as grant income rather than revenue. So in reality, I don’t think revenue per passenger is falling in the way these numbers imply.
It remains to be seen whether next year’s bus fare cap increase from £2 to £3 will have an impact on passenger numbers.
Germany - this sounds a bit of a mess. Revenue fell by 21% during the quarter, including impact from driver shortages. Negotiations are underway to resolve the problems with the current contracts, which the company suggests are industry-wide, not just relating to Mobico.
Roland’s view
The investment opportunity here seems to be that if Mobico can complete the turnaround or divestment of its non-Spain operations, then profits could rise significantly. In turn this would aid debt reduction and support a higher rating for the equity.
On the other hand, operating buses is generally a low-margin and heavily-regulated business. Mobico’s H1 results showed an adjusted return on capital employed of 7.8% in H1. At this level, the group is hardlycovering its cost of capital, I suspect.
Add in net debt/EBITDA leverage of c. 3x, and I wouldn’t want to pay a high multiple of earnings here.
Hence I would only look at this stock as a trade, not a long-term holding.
Having said that, I can see that a trade has been playing out well so far this year, with the shares up c.50% since July:
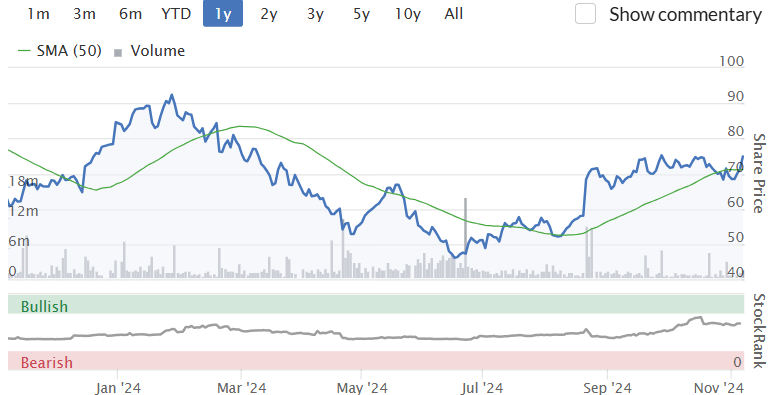
If the planned sale of the North American school bus unit brings in enough cash to make a meaningful impact on net debt, I think this could support further gains. So too could a successful turnaround in the UK and Germany.
None of these things are guaranteed, of course.
Looking at consensus estimates for the current year, Mobico shares are trading on 10x FY24 earnings, falling to about 6x earnings in FY25. The dividend is expected to remain suspended in 2025.
On balance, I’m going to maintain our stance at AMBER/GREEN. I think there’s still some potential upside here, but leverage remains a risk and I think the value opportunity is gradually shrinking.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
S4 Capital (LON:SFOR)
My goodness...our new chancellor merely has to tax Mr. Sorrell's share options and that will be the £22bn hole plugged:
The company says ‘operational EBITDA’ (which is a horrible measure ofprofits) is now expected to be slightly below the previous year. Dowgate Capital forecasts £85bn of adjusted EBITDA, down from £94bn last year and £124bn in 2022.
Don't worry - I've been there. I was writing a report on the costs of Britain's nuclear reprocessing for a Japanese client many years ago when I inadvertently got American billions (10^9) and old English billions (10^12) mixed up while translating....there were some chuckles.
At $4.92B market cap Lantheus Holdings (NMQ:LNTH) is not a small cap but I am not confident that it will be immune to pricing scrutiny.
Brickability (LON:BRCK)
Discerning the runes or at least trying. I have added a few more Brickability (LON:BRCK) to the family ISAs. I have re-read the recent trading update of 22 October. The company is trading in line and full year expectations are unchanged. Accepting that demand for building materials and in particular bricks remains subdued, I have highlighted the narrative that feeds in to my investment case going forward.
"Brickability Group plc (AIM: BRCK), a leading distributor and provider of specialist products and services to the UK construction industry, issues the following trading update for the six-month period ended 30 September 2024.
The Group's financial performance in the first half of the year was in line with the Board's expectations, with revenues in excess of £330 million, an increase of 2 per cent. on the prior year period, and 7 per cent. lower on a like-for-like1 basis.
Trading during September reflected a continuation of the trends across the Group as noted in the recent AGM statement. Revenue and volumes in the Bricks and Building Materials, and Importing divisions were lower than the prior year, consistent with the wider commentary around new build housing, whilst Distribution has returned to growth, driven by a doubling of sales of solar PV in Upowa.
The Group is benefiting from an increasingly diversified product and service offering, with the recently acquired specialist cladding and fire remediation contracting businesses delivering a strong first half. As a result of the timing of projects, the performance of the contracting division is expected to be first half weighted.
The new build housing, residential and commercial RMI markets remain supressed, although the Group sees positive momentum, particularly in brick order intakes, which is contributing to a well-balanced forward order book for the second half of the year. An increase in inquiries for the Group's products in recent weeks indicate, alongside other leading indicators, improving sentiment around a recovery commencing in the current financial year.
Net debt as at 30 September 2024 is expected to be approximately £56 million on a pre-IFRS basis, after making deferred and contingent consideration acquisition payments of in excess of £8 million.
The Board anticipates reporting adjusted EBITDA2 for the six-month period of at least £27.5 million, (HY 2024: £25.6m) and its expectations for the full year remain unchanged."
The anecdotal evidence is that demand in the housing market and new build is very slowly starting to pick up. This will stimulate demand for building materials across the board. Brickability (LON:BRCK) is slowly moving away from being a general merchandiser of building materials to higher margin specialist products and services. The acquisition of two specialist cladding companies earlier this year are examples of this shift.
So in no particular order the investment thesis encompasses the following:
Debt at around £56m is higher than I would wish but is not prohibitively excessive at around 1.25 last years adjusted cash profits.
On balance the risk/reward seesaw appears to me to be skewed to the upside. Time will tell.
All the best
I welcome a broader coverage. Given the poor quality and shrinking numbers on AIM it’s hard to see how application of analytical resources exclusively to that market makes sense for most investors with a broader portfolio. Obviously that’s a big ask of a small Stocko team so I think they should focus on likely serial compounders rather than chuggers and some of those will be in Europe.
Rumours/speculation swirling from Betaville about a possible Indivior (LON:INDV) takeover offer.Remember Paul pointing out this one due to its p/e a while back.But its very niche sector specific knowledge here as its pharma with all the sector specific risks, although still currently very profitable.Not up massively though.It's not Sky News which is reporting before the market afterall!
Well, I think this format is fine, but I would just like the team to consider investment companies as companies. Having just got off the analyst/investor call with Chenavari Toro Income Fund (LON:TORO) , I can't see why a good number of people here wouldn't consider what is effectively a specialist lender, consistently paying 10% of NAV as dividend, which, at 25% discount is currently 12.5%, particularly on a day the central interest rate falls again. The rate decline might be gentle, but won't it decline to 4% next year? With inflation sub 3%. The fund manager itself owns over 50% of this, but prices are really set by PIs. No, it's not a mulit-bagger, but getting close to NAV would give 20% on top of 12.5%. These WILL disappear at this rate, like Atrato Onsite Energy (LON:ROOF) . I'm upset to see Atrato Onsite Energy (LON:ROOF) bought out, but at least we got 25% return this year, while the div lets us sleep at night. These are listed companies too!
Sad to see Paul go, but would also like to thank the new team for their reports plus coverage of the additional companies outside the norm, I think this is an excellent service. I'm just wondering if anyone has scope to review Beximco Pharmaceuticals (LON:BXP) whilst on the subject Stocko fundamentals looks as cheap as chips apart from fact that its a foreign listing which may detract people from investing. Kind regards to all and best wishes to Paul
I am familiar with Beximco Pharmaceuticals (LON:BXP) and it isn't really a case of conventional investment analysis....you need to have an informed view on how things in Bangladesh will play out, and a crystal ball on how independent the judiciary will be in a time of national turmoil.
The vice-chairman (Rahman) was close to the old regime, and is no longer in favour (to put it mildly). There have been legal shenanigans and an attempt to appoint a receiver over the wider Beximco Group.
Then there is the problem of sourcing US$. London shareholders have often experienced a delay in dividend receipts owing to a chronic shortage of foreign currency.
Yes, it trades in London at a big discount to the local listing.
No, there is no mechanism I am aware of to make the two share listing fungible such that the difference could be arbitraged.
In years gone by it has been discussed several times by a colourful investor known as Evil Knievel (Simon Cawkwell).
Be careful not to buy it in an ISA (it doesn't qualify, as some platforms decided rather too late)!
Beximco Pharmaceuticals (LON:BXP) I would also add - what put me off, was that the UK shares are non fungible. There are details on their website under the investor tab (fungibility of shares) - this is a deal breaker for me.
Beximco Pharmaceuticals (LON:BXP)
The vice-chairman (Rahman)
Is that the same guy they chucked in Jail back in the day ? - i briefly owned this many years ago and it was never a dull day back then - i think normal logic does not apply with this company. I sold back in 2007 and 55p - looks like dividend is fairly chunky so its possibly proved itself over the years? despite then lowly rating now (if p/e of 3.2 is correct)
Just want to chip in and say this is exactly the report I always hoped Stocko would produce! Thank you team
Nice work covering Novo Nordisk! I would like to see more of this kind of analysis here.
'Burford Capital (LON:BUR) my largest holding have justed issued a RNS to confirm that the huge swings in the SP this morning are as a result of inaccurate reporting in the media.
Having opened at 1050p Burford fell to a low of 800p before recovering to 1000p at 12.15pm. A worrying morning for holders.
Burford Capital (LON:BUR) Brutal for those that sold on the false news. SP now in the black for the day! (perhaps a reason not to use automatic stop losses).
I think perhaps give Megan a break here, maybe with the new pressure added to having to produce these reports so quickly the addition of the term ''too'' may have just been an oversight? Teething troubles. I think it is a useful analysis and if it is an actual opinion then so be it, time will tell if she is correct. I like to skim the table for anything interesting and then dig a little deeper. Obviously Paul has more of a track record and people trusted his and Graham's judgement, so the new team will need some time to build that trust. I for one mostly appreciate the quick colour coding and initial comment that was often released before being followed up with detail, it meant I didn't have to waste my own time on anything not worth it. It would be great if that could be a priority in my opinion. I am mostly here looking for ideas and learning.
Personally I don't really have any interest in the large caps, if I did I would probably just put my money in a tracker. It's the small and mid caps where I see the Alpha, and hopefully growth in the economy.
Cynically, what % of membership have the European membership and can actually see the Novo financials?
Are we going to see more and more international stocks to try and upsell other regions?
Whilst I am far from delighted by recent developments, and also the communication of recent developments, (especially given it was just after my subscription rolled) I think we should give the team a chance and not be too cynical, yet.
If you subscribe for US markets then you will be able to see the numbers & stock ranks forNovo Nordisk A/S (CPH:NOVO B) via its ADR listing on the NYSE Novo Nordisk A/S (NYQ:NVO).
You are also better off going to the company website for financials anyway - by the time they've been through the Refinitiv sausage machine and been adapted for the Stocko layout all sorts of nuances can get lost in translation. For instance, very few readers seem to be aware that the "Cash etc" number on Stocko actually includes short-term investments (which may not be what you expect), and I recently commented on how this made a huge difference when looking at Manolete Partners (LON:MANO).
@ CautiousValue, Novo Nordisk have ADR's (American Depository Receipts) so if you have a subscription that lets you see US stocks you can read more about them here..... Novo Nordisk A/S (NYQ:NVO)
I do think Megan missed a trick by only linking to the Danish listing, and not removing the spurious link to Novo Resources. Albeit the latter is an easy mistake to make, whenever I enter Novo in any spreadsheets and link it to the live price I often get Novo Resources instead.
Also, the shares didn't "....rose (sic) as much as 12% yesterday", that should be corrected.
Edit, I see @ Monty Carlo beat me to it
The trouble with this change of direction is that we will no longer get to follow the stocks that for years we’ve been getting a feel for and building up knowledge of. The larger stocks are too large to be able to do that. I appeal to you to reconsider the change of direction it’s like throwing the baby out with the bath water. It feels like the direction has changed in order to play to the strengths of the writers over the subscribers needs.
I'd like to see all the FTSE250 stocks included and only occasional FTSE100 stocks if they happen to be of particular interest.
Agree with that .
There is a “closeness” you can get with some small caps that gives a true engagement feel along the lines to quote Warren Buffet think and feel that you are buying part of the company .
Not sure if I can really explain it that well but having only ever owned a business I want to replicate that in the companies I own.
Dont get that feeling with mid caps and certainly not danish companies .
Croma hasnt been covered. In the past. Few days which would have been good .
If graham and the team are noving away from the shares we have all been following for years and moving to mid caaps probably worth putting us out of our mysery now
planetx, don't fret, there will be continuity as I will continue to track the same UK small-cap shares as I did before, and a lot more, as I will be here for longer every day. There is no major change in mandate. We are just letting ourselves cover bigger companies when the audience (i.e. you) are interested in them and when we think we have something useful to say about them. G
I hold Rolls-Royce Holdings (LON:RR.) as well as small caps and to be honest I was pleased to see RR in the list to be covered today. The Stocko team expertise and knowledge is so valuable and their opinion of the TU from RR is extremely useful.
We have to give the new coverage to settle down. I think Megan did quite well covering Novo Nordisk in a few words. Personally, I prefer the wider coverage including larger cap and Europe. Markets are inefficient: mid/large caps , high PE stocks often stumble (like JD Sports) to give you an opportunity to buy low and sell high. There are biases such asinstitutional investors who think Europe is a basket case with no growth. The broad brush approach is helpful as it leaves value under the table. Sell Side analysts and fund managers are too focused on short term performance giving patient individual investors a chance . There are several in Europe today, added to by sell side brokers scaring people of Trump tariffs before we have seen any action. Some examples of European opportunities….Nestle, Cap Gemini, Edenred, Pluxee, Pernod Ricard, David’s Campari, Diageo, SCOR, ENAV, and more.
This report can help us all to work together to analyse the fundamentals of a a broader set of companies regardless of size or location.
planetx - you can always complement Stocko's coverage with Paul Scotts coverage on his new channel https://paulypilot.substack.co....
(BTW - Assuming it's the same Planetx - I took delivery of a Planetx Tempest gravel bike a few weeks ago - love it!!! ... keep up the great work! when's your IPO?)
A couple of points on NOVO Nordisk. 1) I think writers and read alike would benefit from a clearer definition of what sort of companies are going to be analysed on here. 2) 27 x forecast earnings is certainly expensive. But whether or not it is TOO expensive would depend on ones strategy and likely holding period. E.g. if one intends to hold for ten years, them maybe it's a sensible investment. And if one intends to hold it for 3 months, then maybe it's not a sensible investment.
And, of course, that's if you simply trust the expected earnings. If you do your own research then maybe you estimate it at 22x, or 45x. And that might change your view.
I'd much more appreciate a detailed analysis of the business, and leave the valuation up to the reader. e.g. there are suggestions on X that Nvidia might do a bit of massaging some of their numbers. Why not look into that? Or tell us more about Novo and it's history with diabetes drugs and how that led to Ozempic, given it's the first time it's been mentioned here.
John Wood
Down a staggering 45% .
Trying to look into it but got jetlag and monster headache going round the bendiest roads in the world with crap wifi .
Bizarrely my ii account works great !
Anyone up to speed john wood looks overdone
(In sukabumi java)
Planetx.
Im actually quite concerned for you, and it makes me feel rather sad, that you are posting stuff like this to a wholly impersonal investing website to people you have never, and will never, meet.
I really hope you gain a better grasp of self awareness in due course
Who said this was a wholly impersonal investing website?
Those familiar with Planet X's many interesting contributions over the years will not be overly concerned. We will probably spot some rather interesting additions to his selection of roof tents and bike parts in a few weeks' time.
Inhabitants of the cycling world like a few bends.
I never did manage to buy a bike off him in his glory years as I was too tall, but his current line in portable saunas has put a smile on my face ;-)
Thanks Planetx
I'm checking out WG. now, planetx, we'll have something up on it in a little while. G
I hope your not in Cornwall terrible roads and minimal wifi when I was there last week, scenery stunning though, so every cloud.
ironically it's the cloud he wants not the silver lining
underrated comment here. LOL. Bravo 305020
Very good :)
John Wood (LON:WG.)
Ongoing contracts to be evaluated along with accounting procedures. Need to be careful here.
All the best
Im caught in the headlights for now. Whilst I thought John Wood (LON:WG.) a cheap stock pre today's falls I have always had a rule never to buy a contractor on the first warning. Bad news travels slowly... but the reaction appears extreme.
Will John Wood (LON:WG.) be covered today? It is currently down 45% on 3Q update.
And to hopefully add some value as well as asking questions here's my snapshot for Auto Trader (LON:AUTO) H1 results, now this isn't purely a small cap report.
Auto Trader (LON:AUTO)
Hi Phil P
Thanks for your analysis this morning.
I actually used to work for the company in a financial capacity many moons ago.
You highlighted the rise in used cars sold, which had no impact on revenues.
My take from this was that:
Things have probably changed a lot since I last worked there (pre-IPO) and I have not looked at their reports in detail for a long time (including this morning's), but this is how I would interprete this statement.
A
Hi abtan, thanks for your insight. Yes I think you're correct, reading through some of the commentary in the report. I guess it's just a special situation, as in normal times those add-ons would be essential to boost revenue growth. Ironically they may get higher revenue with slower car sales.
Morning all. Could I ask a question & thanks in advance for any responses.
I took a small punt on the gold miner Hummingbird Resources (LON:HUM) a while ago (it was less than 1% of portfolio, so no material damage). I saw it as a high risk play, if it goes wrong I could lose 100%, if it goes right I could 5-10x. Well it's gone wrong :) & they are delisting, being bought out by their lender & now largest shareholder at a heavy discount of 2.67p (trading at 6p yesterday). Fair enough as they couldn't pay their debt. The cause is poor management & on ground execution. They have said they will honour the same 2.67p price to shareholders.
“The pre-conditions for the making of the Offer are the completion of Nioko's due diligence to its satisfaction, the entry into of the subscription agreement for the Debt-to-Equity Conversion and the Company posting the circular and convening the requisite General Meeting for the Rule 9 Waiver. Nioko has confirmed that the proposed price for the Offer, if made, would be 2.6777 pence per share (the "Offer Price"), which is the same price as the proposed Debt-to-Equity Conversion. The Offer would be subject, among other things, to Independent Shareholders approving the Rule 9 Waiver Resolution for the Debt-to-Equity Conversion. The Debt-to-Equity Conversion and subscription agreement would be conditional upon the Offer being made and such condition shall not be capable of waiver by Nioko. It is intended that, once the Debt-for-Equity Conversion has become unconditional, there would be no further regulatory conditions to the Offer and no acceptance condition.”
I have a few questions:
Do they have to honour this price now?
Is there any way that shareholders can be screwed further & end up with zero?
What would be the process if I waited for this offer?
Hopefully this is useful to other people as well, as at some point we may all be holding a stock that gets delisted & I can't think of a more knowledgeable group of people to ask. I have to say it's been a great learning experience if nothing else.
This is really nasty, other companies have had it in for Hummingbird it's sad to say. I hold.
Hi phil i also HAD a position in hummingbird... i've traded it since 39p, with the understanding it's always good to have some gold in the portfolio.... (that is of course until your gold miner goes bust). and it's been good to me as its volatility over the years has helped me profit.
. So losing 70% of my current investment is not as soul destroying (3% of portfolio) as it first felt yesterday evening when i read this.
This slow motion car crash since the beginnning of the year has been managed terribly . Dan Betts really should be ashamed of how badly he messed this up... Should really go to jail!
This whole set up since the haulage company stopped working in march, seems almost fraudulent in it's execution. They had assets and runaway to avert this. how can you "miss" a $25 million bill!
The company has been given to the creditors and just carries on as usual as it hits it's peak Gold output at peak price... I"m livid that this arrived without any warning...
BOD kept saying lenders were being fine and supportive etc etc... big lesson for me in management trust... and not reading the risk in the tea-leaves
Anyhow rant over back to the original question. i've lost all trust with this investment and set a stop loss last night and got out 2.1p and am grateful to get 30% back tbh. The lenders are in full control here and can do whatever they want. you could wait it out for more but why risk the cash when it could be redeployed..?
Just my tuppence worth. Good luck and commiserations. i think Mark Simpson is a holder too?
frustrated trader
p
I sold Hummingbird Resources (LON:HUM) once I saw the writing on the wall for Mali when they moved into the Russian sphere of influence. Assimi Goïta is nationalizing some of their gold mines so it isn't looking good for their Yanfolila Gold Mine. Barrick Gold (TSE:ABX) face the same problem with their loulo-gounkoto mine etc...however unlike Hummingbird Resources (LON:HUM) they are fairly well diversified in terms of their operations.
Something like Serabi Gold (LON:SRB) in Brazil was the better small cap investment so far anyway post these Sahel region nations turning their backs on the west....
Thanks for your comment Patrick. I completely agree that this whole situation has been a car crash. This is the only gold stock I've ever invested in & I chose it to force myself to learn a bit more about the industry. It's certainly been an education on what to avoid!
I rather naively thought they were near a turning point, although I had been thinking that for over a year which probably says it all. The timing is frustrating though, just as they have the new mine up & running, albeit not very efficiently, and peak gold prices. It could have been such a cash machine if it was run properly & no doubt will be eventually for the new owners.
I have also decided to sell. More so just to not have to think about the stock any more or read any of their statements. But also, as you say, to redeploy the capital somewhere else.
Well done on at least cashing out some profits in the past. I was up 60% at one point but never sold any, doh!
Give they guys/girls a break and a chance to find their groove here... some of the comments seem a little nippy.
I'm loving the broader market coverage. Thanks guys - keep up the good work!
Mobico (LON:MCG)
Positive trading update today and the share price looks like its breaking out to the upside, they say the sale of the US school bus business is on track (trading is 'strong') and I'm speculating now election uncertainty is removed we may well see an acceleration in the sale process, the US definitely has momentum....
Novo Nordisk A/S (CPH:NOVO B) strange analysis of world-leading drug company. 28 times earnings hardly expensive when you have a true blockbuster first-in-class drug. And it didn't go up 14% yesterday....
Novo Nordisk A/S (NYQ:NVO)
Don’t think so. Great analysis by Megan.
28X is hardly cheap considering the ongoing/future competition and Trump’s future tactics.
Price down about 30% from its highs in this bullish environment-that says a lot.
All the best
Novo Nordisk A/S (CPH:NOVO B) Fair points Yiannos. Opposing views make The Market! The clamour for Ozempic etc from patients who are unable to lose weight is enormous(!) We haven't seen the like for many years. I see this as a brief correction given the expected revenue and EPS growth. Probably getting the ticker wrong and the price change wrong was not something that inspired confidence in the commentary.
*patients who are unwilling to lose weight using traditional methods.
Kitwave (LON:KITW)
A company I like. Such an easy company to understand, which for me is important. This reminds me of the quip by Peter Lynch, to paraphrase, invest in companies that can be run by someone who is not the sharpest knive in the box, because one day they might. I am glad to say that Ben Maxted and the founder Paul Young who retains 15% of the business are far from that description and form part of a very competent management team.
It buys, in the main, small independent “food distribution” businesses and integrates them and as such achieves efficiencies relating to economies of scale. Delivers to customers whose orders are too small to attract larger industry players and has first class customer service.
I hold.
I am very grateful for your observations and analysis on Braemar Graham, perhaps I was a bit hasty to add to our holding yesterday, they've had to cope with some large waves over the last few years and I was relieved to see a better forecast. Binoculars on the bridge for the next hazard.
Positive update from Kitwave (LON:KITW) this morning. In line. Interesting comments about the NI changes - the rate change was anticipated but not the threshold change - and they expect to absorb the cost increases through efficiencies rather than price increases.
Yes, I'll cover this one amshaw. G
Kitwave (LON:KITW) - I expect they'll tweak prices up a little too, despite what they say. In my business, the largest component of our selling price by far was steel, which went up and down like billy-o (what even is billy-o???). We used it as an oportunity to improve margins, as customers expected price rises. It's not as if Kitwave have competition from overseas; their competitors are all in the same boat with NI. The other option for their customers is to go themselves to wholesalers, but wholesalers too suffer the same NI increase. I like transparent input cost volatility, especially on the up-slope.
I really like and hold, though sadly bought 18% higher than today's SP. I'm hoping the Creed aquisition, which looks a super quality business, will soon start moving the SP in the right direction.
Are they being held back by flippin' Liontrust? Kitwave is another one suffering from big sell-offs by Liontrust. There doesn't seem to be much buying activity either.
Founder Paul Young also sold half of his holding recently. Not at all helpful.
I may have got that last part wrong...looks like the founder transfered shares to family rather than a sale. Good!
Isn't Billy-O the trader's go to on the duke box, with favourite such as "Red light spells danger", "When the going gets tough" and "Suddenly"?
Why are you covering Danish companies anyway?
The analysis isn’t up to scratch, but I’ll defend its inclusion on the basis that it is one of the world’s highest quality companies trading at a discount.
BnB you have to understand sometimes all people like me want is stock flagged up to start the conversation - in that respect it’s job very much done - you can’t expect commentators to do detailed dive on big pharma companies lie this that’s our job to go off and door/dyor
My sentiment too rmillaree .... I love the fact I was forced into thinking about this stock today. Im all to often guilty of just thinking oh I missed it... blah blah .... I also think you have to be careful to distinguish what really counts as analysis... when throwing stones at others. Give Megan a break....
re high ratings. Like say 28x.... these often come as a result of high returns on capital and high growth. So when assessing whether 28x is too much it's normally an assessment of how quickly returns fade back to average... and growth prospects diminish. Saying it's a world class company doesn't qualify as analysis either for the record. Being aware of competitive and regulatory threats probably alleviate some concerns.
In journalistic terms Megan must get a thumbs up because the prod really triggered a response which is, after all, the point of the forum isn't it.
I have to agree.
As a recent suscriber to what was the SCVR, Im a bit disappointed with the broadening of focus that the SMR represents. I don't see how SMR can add much value or specific insight to trading announcements from large caps, whether based in UK, Denmark or anywhere else, to be brutally honest.
The whole point about the SCVR was that it analysed a relatively small number of stocks that were not widely folllowed by institutions helping level the infomation playing field for small investors.
If you're not going to the analyst calls and don't have the resources to recruit sector experts, then the level of analysis that SMR writers can offer for a widely-followed company in a specialist sector like Novo is always going to be superficial and reactionary, unfortunately.
By the time the price Megan had written her summary, the analysts had already written their in-depth reports and the price had long since moved.
I was an investor in Novo and bailed not on momentum or valuation grounds but on concerns about the pipeline , and of course, the possibility that Trump will penalise European pharma companies -- not mentioned in Megan's analysis.
I think SMR should do some research on what small & mid-stock stocks are really worth following, either because of strong subscriber interest, relatively poor analyst coverage, history of surprises, sector familiarity.. .whatever factors you want to use. Then you should mostly stick to that short list instead of trying to cover everything that moves and doing it late and superficially.
If Im looking for a site that tells me Rolls Royce, BT Group and National Grid have today put out results -- without any further analysis -- and Novo reported yesterday, i can get that information for free elsewhere.
Good luck!
Hi jeff, thanks for the comment. Just to reiterate what I said to planetx: we intend to continue covering UK small-caps. We are not suddenly dropping coverage of all the usual favourites that we've all been following for years - rest assured! G
Its really a question of how you best use the limited resources you have. Spending an hour trying to understand all the moving parts in the announcement of a large cap that hasnt been covered before, offering an informed opinion , and trying to do three or four before lunchtime represents a heroic effort but is probably overambitious.
Nevertheless, I'm sure the teething troubles can be resolved.ERROR.........Rusty2 is right. Novo resources is a small Canadian miner.
Why are you covering Danish companies anyway?
Not sure what is being covered anymore.
The blurb talks about uk small caps still.
l would prefer foreign stocks to be covered elsewhere.
I don't think we are suddenly going to cover a lot of foreign stocks here. NOVO is just a stock that Megan is familiar with and has a reasonably high profile. We'll be covering plenty of the usual suspects today. G
For those who haven't the time to fully dissect today's RNS from Plus500 (LON:PLUS), I'm hoping that my brief translation may be helpful:
"We've listened to shareholder's concerns about our top secret director's remuneration framework and concluded that we're smarter than you and you can all just do one!"
Very handy translation thanks. Much easier to digest than the waffle in the RNS. As long as the shares and dividends keep going up I can't say I am worried about a few people voting against the report
To keep them on their toes.
Novo Nordisk is an incredible company, but it’s shares are too expensive at 27 times forecast earnings. And investors should beware a change in momentum from high quality companies
Oh dear. Can we drop this UK value mindset, please? If this is the quality of analysis we can look forward to as the report moves into larger cap and higher quality companies, then I won’t be hanging around. Novo is at a discount to pharma overall when you compare growth rate to valuation mulitiple, has far better growth visibility and an astounding record of innovation and monetisation. It’s pretty much the cheapest I’ve ever seen it! Clearly every pharma and his dog is trying to jump on the GLP-1 bus, but Novo and Lilly have a huge lead, not just in terms of regulatory approvals, but also manufacturing and fulfilment capability. A setback would be a failure of the Catalent (manufacturing capacity) deal to go through.
Novo nordisk - I think drug companies will always be niche ref ability of commentators to add much - one very firmly needs to do one’s own research to judge the long term prospects.
Clearly with their blockbuster wight loss drug they must be in a very sweet spot.
I think it’s impossible for those who have not done detailed research to add much ref valuations - I would say as general comment that 28 * earnings isn’t cheap seems fair comment to me in the absence of clear reason for rerating. That’s where we need the plus case highlighted though - they seem to be sector leading in what is possibly one of the best potential drug ls that can revolutionise people’s health - diabetes. Does anyone know what earning might be in 5-10 years could we be taking multiples of what it makes now ? Presumably that would be the bull case here
Megan didn’t say Novo is expensive, which it is a statement of fact. She said it is TOO expensive, which is an analytical opinion, not shared by the entire investment banking community. If Megan turns out to be correct, it will be for the wrong reason (UK valuation anchor) and if wrong it will be because she hasn’t performed enough analysis. I don’t share your view that simply raising the ticker and leaving it to us to sort out is the service here. And it is certainly not what we are accustomed to from Paul, with his lightning reviews of balance sheet risk, and Graham with his narrower but more forward-thinking analysis.
I think we will have to disagree here - if something is expensive or too expensive from viewpoint of commentator thats just their opinion which is what i was saying.
I don’t share your view that simply raising the ticker and leaving it to us to sort out is the service here
My point was that you cant expect detailed ninja analysis on EVERY stock raised - Paul is a quality hard act to follow too - i am sure stocky commentators are trying their best here obviously its not the same without Paul but that life unfortunately
Yes this is more of an ideas factory as I see it. If you disagree who cares, only you I expect: buy, hold or sell those are your options.
I also think we need to steer away from Paul being some sort of all seeing savant, in what I’ve seen from him he has never claimed to be and certainly isn’t (and I’m not trying to be disrespectful)
Keep churning out the analysis, I’m enjoying the broadened list of companies.
"then I won’t be hanging around"
Oh dear. I hope we don't get puerile threats to leave every time someone disagrees with the analysis. Give them a chance!
Yes it was a bit grumpy. My bad.
It's a tough gig going up on stage after Paul :-)
BnB, rmillaree
Thank you for your feedback on Novo Nordisk.
First, to address your point about 'UK value mindset'. I certainly do not struggle with this affliction - something that has, on more than one occasion come a cost to my personal portfolio. The vast majority of my portfolio is in US tech stocks. I am never scared away by a high valuation of a truly quality company.
I am, however, learning. High valuations can only be sustained if the company never fails to hit expectations and a quality, growth company can only continue to be classed as such if the investment case doesn't change. With Novo Nordisk, I am not 100% sure that either of these things hold true. As you will see from the analyst consensus chart on the company's StockReport, earnings forecasts have started to temper. Operating margins have also been lower in the last 12 months than in the previous year.
Now, I am not saying that this is a major cause for concern. I reiterate, Novo Nordisk is a truly fabulous company. But the warning signs of a quality company coming off the boil are worth paying attention to. On a much smaller scale, we saw it with Bioventix a couple of weeks ago.
The investment case has also changed a little this year with the arrival of Eli Lily's GLP-1 inhibitor. This of course doesn't mean that demand is going to fall. By contrast, GLP-1 inhibitors are set to increase in demand across many different disease areas. But there is no denying that a second drug in the same market could create some pricing pressure. Again, this is not something that is a cause for concern right now (especially given Eli Lilly's struggles to gain traction). But for those who bought at the start of the year, the investment landscape is now a little different.
Second, to your point about pharmaceutical knowledge. I agree, it's one of those industries that requires specialist analysis. Fortunately I spent the first half of my career exclusively analysing pharmaceutical companies. With Novo Nordisk, I have looked at the key statistics which I think are important when analysing pharma companies and my main concern here is R&D expenditure as a % of sales is not as high as I would like to see. Part of the reason for this is that the company has also had to spend extensively on its manufacturing capabilities. A high proportion of that R&D spending remains in expanding the indication of GLP-1s . I reiterate, this is a fantastic company, but for me it's another component that raises a question for me.
Megan I would be very interested to hear your analysis of another US pharmaceutical stock, Lantheus Holdings (NMQ:LNTH) if you have time. It fell 20% yesterday following its quarterly earnings report with brokers reducing their target prices today. It has high quality metrics with negative net debt. Was the fall in the price a temporary blip and will the Trump presidency be a break on the growth of the sector as a whole?
It seems like the market is concerned about future growth of PYLARIFY and reimbursement rates.The Ceo answers questions on this in the call.The american healthcare system sure can get complicated.I got burnt on Semler Scientific (NAQ:SMLR) ~(before they changed to being a Bitcoin treasury like Microstrategy- sure got lucky there!) when Medicaid decided to remove its product which was selling well from some reimbursed list or another!The US market doesn't do restrained.However the UK market hasn't seemed to do it lately either in places.
Thanks for your reply. I was hoping Megan might look at the US pharma sector under a Trump administration. I hold Lantheus but am nervous on how much control it will have over its pricing.
I hold Lantheus but am nervous on how much control it will have over its pricing.
In my experience of small cap medtech, next to none!
Thanks for a detailed response Megan and sorry if I came across as too critical. Unlike many here I support the move into larger caps although I don’t see any value in moving above mid caps. Analysis of the likes of Novo is easy to access.
Great stuff, Megan. More please!
Amgen (NSQ:AMGN) for one, another large cap us pharma are hot on their heels with Mari-Tide their phase 2 weight loss drug due to read out soon, and have the obvious manufacturing capacity ability too.And they said in earnings they are planning on launching a broad phase 3 program targeting obesity and diabetes.Apparently it could well have blockbuster potential.All still to play for for them!
The market is also betting heavily on (as a currently pre revenue pharma bringing glps still through regulatory trials) Viking Therapeutics (NAQ:VKTX) (check out the large market cap for pre revenue pharma, especially compared to its us listed competitors such as Altimmune (NMQ:ALT) and even Structure Therapeutics (NMQ:GPCR), who are working on an oral pill).However they have no manufacturing facilities naturally and lack the capital currently to produce if they get fda approval (which is a while away still!).Some folk are betting on a big pharma buy out there pre possible phase 3 approval.Although if they do get approval, they'll natually be able to raise a whole bunch of money i'm sure.
A lot are working on an oral pill version now too.That's the hot new thing as obviously most people would prefer a regular pill to a jab.
Hi Jonno
I picked up on the intensification of cladding remediation in the budget and came to the same conclusion as you. I’ve also been impressed by the frequency and scale of director buys. Needless to say,Brickability (LON:BRCK) is one of the few true cyclicals in the fund that have not been rotated back out after gains. Although there could be cause to rotate back in to more/add to positions if yields keep rising.
Think you have tagged the wrong Novo? Can't see Novo Nordisk A/S (CPH:NOVO B) being up 14% though.
Fixed that Rusty. Cheers!