Daily Stock Market Report (Thur 9 Jan 2025) - HAT, GRG, MRK, IPX, BME, TSCO, MKS

Good morning! The newswire has now officially come back to life.
1pm: this report is finished! I'll hopefully get something from the backlog covered for tomorrow.
Analyst Roundtable: last night's webinar with Ed, Megan and me is available on replay here.
Spreadsheet accompanying this report (updated to 3/1/2025).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Tesco (LON:TSCO) (£24.8bn) | Q3 & Christmas TU | ‘Biggest ever Christmas’ and largest market share since 2016. Sales +3.1% over Q3 + Christmas. | AMBER/GREEN (Graham) |
Marks and Spencer (LON:MKS) (£7.6bn) | Christmas TU | “Another good Christmas”. LfL rev +8.9% (food), +1.9% (clothing). Confident of further progress. | AMBER/GREEN (Megan) |
Unite (LON:UTG) (£3.9bn) | Q4 TU | Strong demand and increased rental for 2025/26 academic year. Guidance confirmed. | |
B&M European Value Retail SA (LON:BME) (£3.5bn) | Q3 TU | Narrows adj. EBITDA guidance to £620m-650m (prev: £620m-660m). | AMBER (Graham) |
Greggs (LON:GRG) (£2.7bn) | Q4 TU | Slower Q4 sales, but full year revenue and profits in line with board expectations. | AMBER/GREEN (Megan) |
Assura (LON:AGR) (£1.2bn) | Q3 TU | Rent roll slightly down, but disposal programme on track with net proceeds of £48.4m. | |
Hilton Food (LON:HFG) (£804m) | TU | 2024 results in line with expectations. Confident for 2025. FX rates an area of focus. | |
IP (LON:IPO) (£481m) | Share buyback programme update | Launches £25m buyback extension, bringing it up to £70m. | |
Boohoo (LON:BOO) (£433m) | Letter from the Board | Again urging shareholders to reject proposals by Frasers. Resolution seeks to remove Mahmud Kamani. | |
Foresight group (LON:FSG) (£423m) | TU | AUM down 2% over 3 months. Fundraising in line. On track to double core profitability by FY29. | |
Mears (LON:MER) (£317m) | TU | FY24 marginally ahead of exps. Company increasingly confident of delivering exps for FY 25. | |
Impax Asset Management (LON:IPX) (£310m) | Q1 AUM Update | AUM falls 8.3% to £34.1bn. Termination of large mandate with STJ takes effect in Feb 2025. | GREEN (Graham holds) |
SIG (LON:SHI) (£176m) | 2024 Full Year TU | LfL rev -4%. Adj. op profit c. £25m, in line. Continued market softness at least in H1 2025 is expected. | |
H & T (LON:HAT) (£150m) | TU | Pledge book ahead of expectations. Comment on higher NI costs which management will attempt to mitigate. | GREEN (Graham) |
Ground Rents Income Fund (LON:GRIO) (£31m) | Response to possible offer | BoD believes the offer undervalues the company. BoD is now receiving feedback from shareholders. | |
Cirata (LON:CRTA) (£27m) | Q4 TU | Q4 cash burn $3.2m. Cash $9.7m. Does not anticipate FY25 fundraise for working capital. |
Summaries
H & T (LON:HAT) - up 2% to 341.9p (£150m) - Trading Update - Graham - GREEN
A good update from this pawnbroking group with the pledge book continuing to grow at a very impressive rate for a mature business, up over 25% in a year although that is boosted by a small acquisition. Higher-value secured loans to people who may use the funds for business purposes are becoming increasingly important. Looking ahead, estimates for FY25 are unchanged for now at the company’s broker Canaccord, as it is thought that the higher-than expected growth in the pledge book will help to offset the c. £2m expense from higher national insurance contributions.
Greggs (LON:GRG) - down 9.5% to 2376p (£2.7bn) - trading update - Megan - AMBER/GREEN
Final quarter sales suffered amid lower than anticipated high street footfall meaning like-for-like sales for the full year are lower than many investors would have liked. The store estate continues to be bolstered by new openings, which helped Greggs report its first annual revenue of more than £2bn. Cost inflation thanks to rising national insurance contributions is likely to kick in in April, although management insists this won’t hurt the company’s value proposition.
Marks and Spencer (LON:MKS) - down 6% to 353p (£7.7bn) - Christmas trading update - Megan - AMBER/GREEN
Continued very strong sales growth in the food division (64% of total sales) was offset slightly by a weaker than expected non-food performance. Overall the company reported a 5.6% increase in sales to £4bn over the 13 weeks to 28 December. The challenge for the company (which has been a phenomenal turnaround story over the last couple of years) will be where the next level of growth comes from.
Impax Asset Management (LON:IPX) - down 4% to 233.7p (£310m) - Q1 AUM Update - Graham holds - GREEN
It’s a poor AUM update but I find a few reasons to look on the bright side. Equity Development have left their profit forecasts virtually unchanged, and a large chunk of the outflow this quarter is attributable to the loss of one of the St. James’s Place mandates, with the loss of these mandates striking me as a one-off event. Valuation is in the dumps compared to Impax’s history; I think that risk:reward is positive from this level, but the trend in terms of flows and share price momentum is against me.
B&M European Value Retail SA (LON:BME) - down 12% to 305.7p (£3.1bn) - 3rd Quarter Trading Update - Graham - AMBER
There is only a slight narrowing of the range of profit expectations by BME, along with confident commentary from management, but the market is unimpressed - even with the announcement of a £150m dividend. Perhaps investors think that management should be more careful, given net debt (before leases) of nearly £800m?
Tesco (LON:TSCO) - down 1% to 366p (£24.5bn) - Q3 & Christmas Trading Statement - Graham - AMBER/GREEN
This update confirms guidance for adj. operating profit of £2.9 billion this year, and also reaffirms guidance for retail free cash flow of £1.4 - 1.8 billion. Like-for-like sales numbers are up by 3.1% with strength in UK/ROI offset by a little weakness at wholesale distributor Booker. I’m happy to take a mildly positive stance given the robust performance and moderate PER of 13x.
Graham's Section
H & T (LON:HAT)
Up 2% to 341.9p (£150m) - Trading Update - Graham - GREEN
This update is in line with expectations. Key points:
Pledge book grows ahead of management expectations to £127m as of the end of December (Dec 2023: £101m). Includes £6m pledge book at the acquired company Maxcroft.
18% of the pledge book now consists of loans for over £5k, often used for business purposes (Dec 2023: 13%).
Back in August, a big topic for H&T was the increased seasonality of pawnbroking demand. There was a pattern of high redemptions (i.e. customers repaying loans and taking back their items) in March and April, “to wear them at religious and family celebrations”.
The company is even changing its accounting year-end in response to this, apparently to get a more even split between H1 and H2.
That’s the context in which H&T says:
The Group's current planning assumption is that there will be lower pledge book growth in the spring, due to increased levels of redemptions, followed by a period of stronger growth in later months. This is consistent with the way the pledge book developed in 2024. As such, we do not anticipate material pledge book growth in the first or second calendar quarters of 2025, with growth expected to return in the third and fourth calendar quarters of the year.
Their accounting year-end will change to September, so that H1 will not include the two weakest calendar quarters (Jan-March and April-June).
Other points: retail sales in the peak trading period met expectations. The pre-owned watch market has stabilised. Foreign exchange revenues also in line.
National insurance: employment costs to increase by c. £2m p.a. They are “reviewing options to mitigate the impact where possible”. However, I can’t imagine what direct options they have when it comes to mitigation, other than hiring fewer part-time staff.
Estimates: Canaccord say that they are still confident in their FY25 forecasts, thinking that revenues from the higher-than-expected pawnbroking pledge book should largely offset higher national insurance costs.
H&T is fortunate that its current profitability gives it a cushion to deal with higher NICs. Adj. PBT is expected to come in at £29m for FY24, £32.2m for FY25, and £34.8m for FY25.
The EPS estimates are 49.2p (FY24), 54.6p (FY25), and 59p (FY26).
Graham’s view
I’ve been a fan of this one for many years and I was GREEN on it in August despite a little frustration with what I perceived as a covert profit warning.
The share price in August was over 400p and at c. 340p now, I think I have to remain positive on it today. The main news since August is the national insurance, and while that’s a blow, I’m not sure that it’s enough on its own to justify the 15% decline in the share price since then.
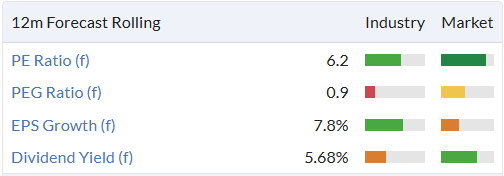
So I’m happy to stay positive on this one as a value play: its ValueRank is 94 and the company remains the market leader by far in UK pawnbroking, with a legacy going back well over 100 years:
Impax Asset Management (LON:IPX)
Down 4% to 233.7p (£310m) - Q1 AUM Update - Graham - GREEN
(At the time of publication, Graham has a long position in IPX.)
This ESG-focused fund manager provides an assets under management update that makes for grim reading:
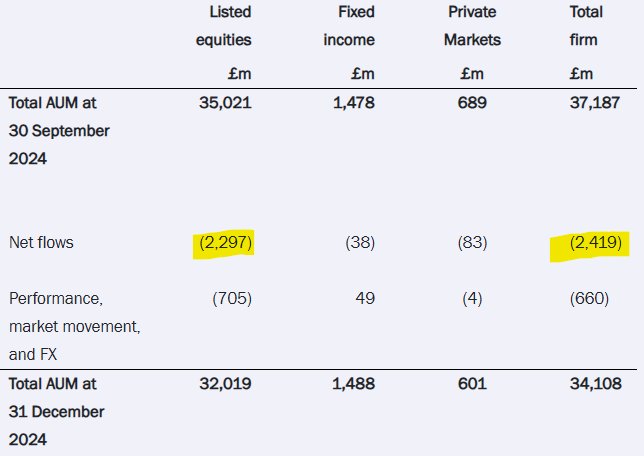
We have a £2.3 billion outflow from listed equities, creating a £2.4 billion outflow across the group.
Market movements didn’t help either; the overall result is an 8.3% decline in AuM in a single 3-month period.
The CEO comment now emphasises the need for efficiency and cost management:
"This quarter we saw relatively high outflows, notably the closure of our smaller mandate with St. James's Place and redemptions driven by industry consolidation in our institutional channel in the Asia-Pacific region. More positively, we have continued to see a slow-down in outflows from our largest European distribution partner, BNP Paribas Asset Management, and from our US mutual funds…
…we continue to pay close attention to the efficiency of the business and the management of costs in the context of providing an excellent service to clients.
The larger mandate with St James’s Place, worth £5bn, will be lost in February.
Graham’s view
You can find my most recent writeup of Impax here, in the 12 Stocks of Christmas series.
I initiated a position here, after the announcement of the loss of the larger STJ mandate, as I thought the valuation had reached such an extreme level that it would be difficult for the stock to offer much better value than this.
Unfortunately, things have gotten a little worse with the continuation of the trend of outflows, as announced today. Let’s review flows over the past year:
Q1 FY24: net flows minus £1.0 billion
Q2 FY24: net flows minus £1.7 billion
Q3 FY24: net flows minus £1.9 billion
Q4 FY24: net flows minus £1.2 billion
Q1 FY25 (announced today): net flows minus £2.4 billion.
The only consolation I can find is that this very poor outflow figure announced today includes a one-off event in the form of the loss of one of the STJ mandates. I think that mandate was possibly worth c. £750m. So if it was not for that loss, IPX’s outflows in Q1 FY25 would have been similar in size to some of the previous quarterly outflows.
How long can this trend of outflows last - indefinitely? As I said in yesterday’s webinar, some people will take the stance that conventional fund management is dead. Personally I don’t believe that, but I do agree that it needs to change. The industry needs to work harder to make its fees competitive and to make its offerings as relevant and as specialised as possible.
I think that Impax still has a great deal of credibility as an ESG investor. However, it’s proven now that it’s not immune to the general wave of pessimism around UK fund managers.
Is all of the bad news priced in here? Personally I believe that it is, but that’s just my opinion:
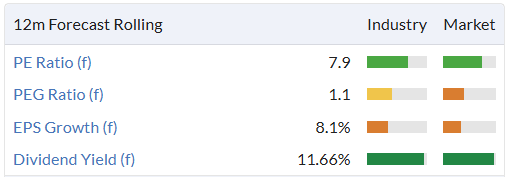
Estimates: Equity Development have cut their AUM forecast but other forecasts are virtually unchanged, e.g. they still expected 23.9p of EPS in FY Sep 2025 (previous forecast: 24p).
B&M European Value Retail SA (LON:BME)
Down 12% to 305.7p (£3.1bn) - 3rd Quarter Trading Update - Graham - AMBER
BME hasn’t been covered much in this report historically, as it’s been considered too big.
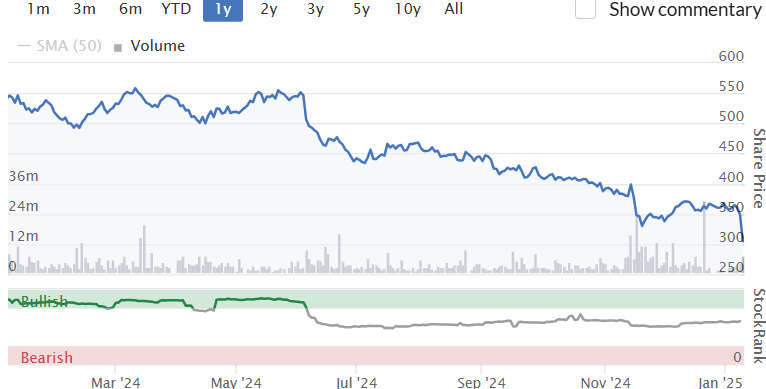
I see that Paul briefly mentioned it in June, when the share price was over 500p.
The 1-year chart shows it making progress towards small-cap territory:
Let’s investigate today’s Q3 update (Oct-Dec, as financial year-end is March). Highlights table:
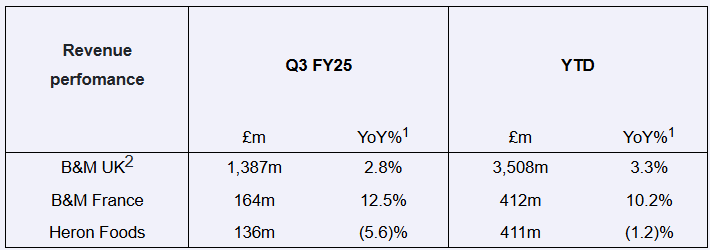
Unfortunately the numbers in this table are not like-for-like, as store openings are growing total revenue.
The like-for-like revenue figure for B&M UK in Q3 was actually minus 2.8%. However, the performance sounds fine apart from that:
B&M UK gross margin and profit performance was strong in the quarter, with a clean inventory exit position. January seasonal transition is well on track and availability is very strong
Further confidence is seen in the announcement of a special dividend of 15p per share, or £151m.
The company’s leverage multiple was 1.2x at the interim results, a modest level but I think in physical retailing, where store leases create additional leverage, we need to be particularly careful about debt. BME’s net debt figure was £788m.
CEO comment: he narrows the adj. EBITDA guidance slightly to £620-650m (previously: £620-660m).
Our performance across the Golden Quarter reflects disciplined operational execution across our businesses, driving volume and in turn profit growth. The business remains undistracted by the current economic headlines. Our operating model is well set up to give customers exceptional value when they need it most. Pricing, availability, store standards and a disciplined opening programme will underpin positive volume growth across our ranges…
Graham’s view
The 12% fall in the share price seems a little over-dramatic to me, given that there has been such a small downward revision to the profit guidance.
However, value retailers are out of favour these days and so I suppose any slight disappointment can be a reason to sell. The negative like-for-like sales figure in the main UK segment is an easy excuse to hit the sell button, even if many investors were already expecting a poor number.
I also think that the company’s ambitious growth plans (73 new stores in FY25, and dozens more in FY26), along with the announcement of a special dividend, seem inconsistent with a business where like-for-likes are negative and where profits have been struggling to tread water in recent years. Perhaps the sell-off could also reflect nervousness that management are taking on too much risk?
I am extremely selective in this sector and B&M doesn’t stand out to me as a particularly good candidate for investment in it. I’m happy to take a neutral stance on it while its profits are holding up, but I wouldn't sleep soundly owning it.
Tesco (LON:TSCO)
Down 1% to 366p (£24.5bn) - Q3 & Christmas Trading Statement - Graham - AMBER/GREEN
Let’s briefly check in on Tesco: like-for-like retail sales are up 3.1% in UK/ROI, with the Christmas period slightly stronger than the Q3 period that preceded it:
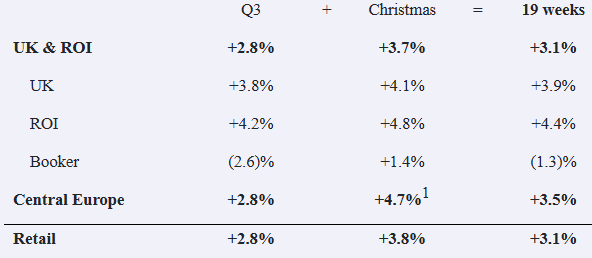
The CEO has nothing but praise for the result:
Our strong performance reflects the investments we have made, positioning Tesco as the UK's cheapest full-line grocer for over two years, improving quality across all our ranges, with more than half of this year's Christmas range new or improved, and providing the best experience for our customers in-store and online, supported by an extra 28,000 colleagues over the Christmas period.
TSCO’s share price has been very strong over the last couple of years:
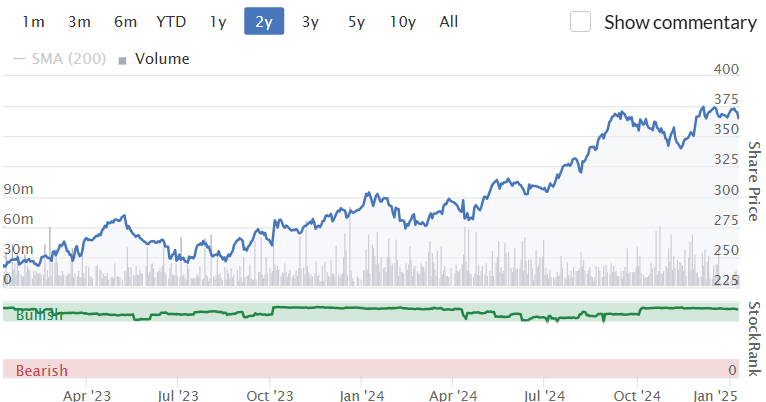
It is hard to criticise the company’s achievements, such as 19 consecutive periods of market share gains with share taken from competitors at both the higher and lower end of the price spectrum.
Outlook: in line with previous guidance.
The ongoing investments in our customer offer continue to drive volume momentum and set us up well to deliver long-term growth. As a result, we continue to expect to deliver retail adjusted operating profit for the 2024/25 financial year of around £2.9bn, in line with the upgraded guidance we gave at our Interim Results.
In addition, we continue to expect retail free cash flow within our medium-term guidance range of £1.4bn-£1.8bn and adjusted operating profit contribution from the retained Tesco Bank business of around £120m.
Graham’s view: I have no criticism to make of Tesco whatsoever but from an investment point of view, it’s virtually the definition of a mature business in a below-average sector. Even at a StockRank of 90, I’d struggle to get very excited about this one. However, as I gave BME an AMBER today, I think I should make this AMBER/GREEN to differentiate it.
Megan's Section
Greggs (LON:GRG)
Down 9.5% to 2376p (£2.7bn) - Trading Update - Megan - AMBER/GREEN
For the second time in as many updates, Greggs’ management has managed to avoid using the dreaded term ‘below expectations’ thanks to previous vagueness on what those expectations might be.
In the first half of 2024, like-for-like sales (which takes into account revenue generated at the company’s own managed stores) rose 7.4%. In Q3 that had fallen to 5% and in these numbers (for the three months to December) like-for-like sales growth was just 2.5%. Management blames that performance on the “well-publised” lower consumer confidence in the UK in the last few months, which impacted high street footfall over Christmas.
I have written before about my penchant for a Greggs baguette and Q4 2024 was no different. I visited seven different Greggs stores in the period under review (four of them on local high streets) and each one was just as full as I have ever seen it. The most significant queue was at the Cherwell service station on the M40, when I gave up and went to Burger King instead.
Now my survey of one is not as reliable as the very real trading statement, which does show that the company as a whole is struggling to maintain growth across its existing store estate. But the demand in certain locations, especially in the south of England demonstrates how there should still be optimism for the roll-out programme.
In 2024, Greggs opened a record 226 new shops, closing the year with 2618 stores in total. That is now more than the number of UK McDonald’s, KFC and Burger King restaurants put together. Greggs’ management have plans to add at least another 140 stores in 2025.
Adding new stores has been key to the Greggs growth journey. In 2024, total revenues rose 11%, passing the £2bn mark for the first time. In the last five years, sales have risen at a compound annual rate of 12%.
Price inflation concerns?
In 2023, Greggs employed an average of just over 30,000 staff, 25,400 of whom worked on the shop floor and are likely to be part-time or lower paid. In other words, the kind of staff who are most likely to be caught up by higher national insurance bills, due to come into effect in April. Greggs’ total wage bill in 2023 was £519m, equivalent to roughly 60% of the company’s selling costs.
Management says that higher employment costs will impact the company’s overall cost base in 2025, but seems unconcerned about the potential impact on margins:
“Greggs has demonstrated its ability to mitigate cost inflation in recent years whilst retaining its value leadership, and we are confident we can continue to do so.”
There is likely room for some inflation in a Greggs meal. Compared to its peers, the company’s food offering is phenomenally cheap. But being cheap is part of the demand, so Greggs will want to ensure it maintains its position.
There are other ways of mitigating rising staff costs and that is through increased automation. Many of the company’s larger, American peers are already using self-service machines in their stores and there could be scope for Greggs to decrease the number of in-store staff, especially in some of its newer locations.
Megan’s view:
A price to earnings ratio of 18x is a more enticing valuation than Greggs has had for some time and likely reflects some of the fears around price inflation. This is a high quality company which reports decent operating margins and a very strong return on capital (ROCE has averaged 21% in the last five years, adjusting for the loss-making period during the pandemic).
But to justify that sort of PE ratio, the company must keep growing and an expansion of a store estate, which at some point is surely going to start saturating the UK market, feels like quite a tall order.
I really would like to be fully positive about Greggs, because I think it is a fantastic business, but I am hedging my bets and waiting for more clarity on the cost inflation in the annual results. AMBER/GREEN
Marks and Spencer (LON:MKS)
Down 6% to 353p (£7.7bn) - Christmas trading update - Megan - AMBER/GREEN
Marks & Spencer seems to have swerved the cost of living crisis. More customers than ever ticked off their whole shopping list at M&S according to the company’s Christmas trading update, with like-for-like food sales up 8.9%. Food contributed just over two thirds of overall revenue in the period, with the remainder coming from the far slower growth clothing business and the insignificant international division.
Food has been central to the turnaround at MKS, which has enjoyed an uninterrupted growth trajectory since the middle of 2022 when the share price fell below 100p. Now at 353p investors who backed the turnaround have made a handsome profit.
But where next?
In this trading update, Stuart Machin, chief executive commented:
“Transforming M&S is a marathon, not a sprint, and we go into 2025 shifting up a gear and raring to go as we accelerate the scale and pace of change.”
That change is expected to come from continued improvements in the supply chain, which will help improve the volume of goods that can be delivered, especially in some of the company's smaller food stores. In clothing, home and beauty there remains scope for greater use of digital channels. In the first half, online sales contributed a third of the division’s overall revenue after reporting 11% growth. Management hasn’t given an exact update on the online growth in these numbers, but did say online sales grew strongly.
Megan’s view:
The turnaround at MKS has been fantastic, but growth in the food division alone is no longer going to cut it, shareholders seem to have been spooked today by the slowdown in non-food growth, which was only 1.9% on a like-for-like basis.
Ongoing economic jitters also create some level of concern for a company which is known for its more premium price point (although that didn’t seem to have much of an effect in 2024).
In November, Graham downgraded Paul’s GREEN rating as the easy share price gains seemed to have all been achieved. Now trading on 12 times forecast earnings, the company will need to step up a gear. And while management has promised some acceleration, the disappointing non-food sales don’t instill as much confidence as I would like. AMBER/GREEN .
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Just note that Asda announcements yesterday could have a bad effect on profits for Tesco going forwards at least temporarily.
I'm not a Marks and Spencer (LON:MKS) shareholder but I really enjoyed the below 2 part podcast. To a certain extent, it's Stuart Machin blowing his own trumpet but to be fair he talks about the issues that are still to be resolved at Marks and Spencer (LON:MKS) as well as expected headwinds in 2025. I shop at MKS once a week, mainly for fruit & veg, I've got to say the staff are friendly & helpful, you can almost feel the change that has happened at MKS over the past few years.
https://tinyurl.com/2r3n3akz
Podcast 1
Stuart Machin joined MKS in 2018 when clothing generated the majority of the bottom line profit for MKS (SSB: staggering really when you think how popular the food offering is now).
SM has been CEO for 3 years.
SM: “protect the magic, modernise the rest”.
SM joined as MD of the food business & bought every single product plus compared it against some of MKS competitor’s products.
Brixton was the very first MKS store & SM used this store to start the modernisation of the company.
MKS has traditionally been a retailer where you pay a little bit more but it’s worth it (ie: quality but not premium).
SM took clothing completely out of the Brixton store because target was to get to 50% of clothing sales online.
Archie Norman was already Chairman and supported free speech ie: raising concerns.
Celebrate the good news and own the bad news.
All the store managers and food managers have direct access to SM via text message etc.
SM reads all the reports & visits all the stores (SSB: is there a risk that SM burns out and the next CEO cannot maintain the same work ethic ?).
Staff suggestion scheme went from a few hundred every year to a few hundred every day! 25,0000 people have written to SM in 968 days (ie: since SM became CEO). SSB: it’s not clear to me whether these are only staff or customers as well (MKS employs 68,000 people).
SM completely disagrees with the thinking that owner managers understand more and care more about their businesses than employee managers.
SM is the number 1 menswear customer because he tests every item of clothing.
But SM was not the number 1 Xmas food shopper in 2024!
Podcast 2
SM shocked at the state of the technology & realised it would have to be invested in.
Also shocked at the state of the store estate & realised that would have to be upgraded as well. The age of the stores is typically quite old anyway.
The supply chain was not owned by MKS. Plus it was expensive and MKS was in contractual disagreement with the provider.
SM wanted MKS to have fresher produce on offer for customers.
Used similar food retailers in Canada and fashion retailers in Spain especially to learn from.
SM worked for Coles & Target in Australia and learned from those experiences; has encouraged new joiners to question existing practices.
SM is fine with owning up to mistakes and making changes going forward. He questions why people in Government can’t be the same ? SSB: I think this is brilliant and I'd like more high profile business people to say this.
SM is grateful to have Archie Norman as Chairman as he provides guidance rather than making decisions himself.
2025 will be a challenging year because of cost increases (all staff have just been given a +5% pay rise), SM didn’t foresee both changes to Employers NI (ie: rate and threshold). Government has a lack of understanding of business.
Marble Arch store is MKS most profitable store but it’s not a sustainable store and requires re-development.
Focus going forward is on giving the customer what they want whether that be in store or online.
https://www.fenwick.co.uk/bist...Megan, you like Greg's, if you're ever in their home town of Newcastle, try Greg's Benedict at Fenwicks.
Hi Graham, many thanks for your write ups on Tesco (TSCO) and BME. How did you calculate the net debt figure, excluding leases, for BME using the Stockopedia data? It's something that I have not been able to get to grips with. Thank you.
How did you calculate the net debt figure, excluding leases, for BME using the Stockopedia data? It's something that I have not been able to get to grips with.
If its not shown in Stockopedia (ie IF debt includes leases in Stocky) - then you simply cant get owt from stocky , normally that means you simply go back to last update where the company has done the donkey work of telling you - looking at the interims looks like the figure was provided at 28/09/2024 - so i have to presume info came from that update. i search for debt in trading update and that drew a blank
per interims
7. Net debt comprises interest bearing loans and borrowings, overdrafts and cash and cash equivalents. Net debt was £788m at the half year end (H1 FY24: £700m), reflecting £973m (H1 FY24: £924m) as the carrying value of gross debt netted against £185m of cash (H1 FY24: £224m). See note 7 of the financial information for more details.
Note the wording is unhelpful here as it doesnt clarify whether leases are included or not (most companies are clear) - but the notes confirm lease liabilities themselves are over £1 billion - so i have to presume above figures simply dont include leases - i know not what thestocky totals are
I just posted this as a response in yesterday's comments, but will repeat here for anyone who might be interested in the thought process of an overseas investor considering a purchase of a gilt (and yes this is simplified, I'm ducking words like "convexity" and "duration").
An overseas buyer of gilts will want to know:
1. Will he get his coupons on time and repayment at maturity?
2. What will £ be worth against his home currency when the bond repays?
3. Will the bond pay a return that is higher than projected inflation over its lifetime?
4. What will the Bank of England do with interest rates while he holds the bond? He looks silly if the BofE hikes rates after he buys such that he could have earned more over the bond's lifetime leaving his money on deposit.
5. Are there other sovereign bonds which appear to be better value on a risk adjusted basis?
6. Is the UK govt likely to flood the gilt market with new issuance after he buys his gilt and depress the value of all gilts trading in the 2nd hand market by permanently altering the balance of supply & demand?
7. Is the maturity of the bond (its lifespan) a good match for his portfolio - are they issuing a 10 year bond when he would really prefer a 20 year bond to match his pension scheme payout profile more precisely?
8. What is the Bank of England planning to do with those gilts it hoovered up during QE (Quanititative Easing) and is sitting on? Will they sell after he buys?
9. Can he lend the bond out in the repo market and is it considered eligible collateral for any derivative positions he might wish to try in the swap market?
Once he has taken those into account he will decide what yield he needs to earn to persuade him to buy the bond. Bonds are usually issued close to par (i.e. a price of 100) and they vary the attraction of the bond by tinkering with the coupon.
So an overseas buyer may see that 10 year US treasuries are trading at 5% and decide he needs to earn a coupon of of at least 5.5% to persuade him to buy a 10yr UK gilt instead. That 0.5% would be referred to as a "50 basis point spread" in bond dealing jargon.
Can the UK be truss ted ? September 22 did see a spike in CDS but not serious compared to say the banking crisis- all major global banks traded with CDS 300 - 1000+ ... never the less the spike was clearly serious for markets. So far CDS isn't moving. Sterling is weak, it's down 8% since the budget. It's far from crisis levels though, it traded at 1.1 to the dollar back when Liz Truss made the headlines, which is 11% lower. The govt needs to get on the front foot and daily tweets from Mr Musk aren't helping. Still the above is a little reassuring.
CDS spreads reflect the probability of default - I don't think this is an issue for the UK hence no significant widening in spreads. The rise in the gilt yields is more due to concerns over inflation than worries about a defualt.
Agree but I was trying to identify a signal of crisis in respeonse to Topvest.
Always respect your views around yield curves RD any thoughts on how you see this playing out over the next few months say best and worst case scenarios ?
Still trying to think through worst case but trade deals with China, US and EU would all be growth positive. As an example. Think the market freaking out over Trump tariffs.
I think the best signal of crisis is that the Treasury saw fit to comment on markets (or at least certain newspapers said there an "intervention", even if there was no statement on the Treasury website that I could find).
Things can get an awful lot worse than what we are seeing. An uncovered gilt auction for starters (I believe the last one was 2009), not just being forced to nudge the coupon....
I am not sure that the 5 year CDS helps here. If I thought that the UK was not able to honour its debt obligations I would be out of here pretty quickly.
The 10 and 30 year gilt yields at the moment suggest that the market does not believe that the Government can deliver the budget programme.
Sentiment might change, but as a cautious investor I am a little concerned. TSB already reported to have raised mortgage rates. Shows how quickly these situations can develop.
Well, we tried the other extreme and Mr Market did not like it.
We're trying the opposite he still does like it.
Is there a solution that is palatable? I suspect nobody knows. We're pretty much in the brown in the stuff.
Hi Graham,
Thanks for the write-up on Impax Asset Management (LON:IPX) ). I've been interested in this company for some time but have been concerned by a comment the CEO made at the last Investor Meet Company presentation about the possibility of taking the company private.
This is a real concern I have with companies experiencing share price weakness despite what I believe is often reasonable business performance in terms of profitability, cash flow, dividend payments etc.
Are you concerned about this aspect in the case of Impax Asset Management?
Do you have any insights into how they might treat shareholders in a potential privatisation scenario and do you think they would be respectful of shareholders' interests by ensuring they have the opportunity to exit at a fair price and avoid significant share price declines?
Thanks and kind regards,
Michael
Micheal,
When I look at the shareholder register I don't see many names who I imagine would want the company to go private, unless Ian Simm himself wanted that.
More generally, all cheap companies are vulnerable to takeover and it will be up to Impax shareholders such as those on the list above to ensure that any takeover happens at an attractive price. Would Ian Simm himself be happy to give away his creation at a bargain price - I hope not!
Listening back to that IMC meeting, what I'm hearing is that Ian Simm didn't rule anything out: the company could private, but it could also graduate to the main market. Personally I would see a move to the main market as being the far more likely change. That's just my opinion!
Thanks for the question
Cheers
Graham
(long IPX)
I wonder if they might merge with Liontrust Asset Management (LON:LIO) Graham there was rumours last year that Artemis and Liontrust were going to merge but nothing came of it.
I can't see it being much of a premium though if they did go the merger route.
Many thanks Graham - I am somwhat comforted by the shareholder register as you mention. I didn't think Ian would be allowing his stake to go at a bargain price, more that if it went private (Ian remaining and other insitutional holders likely remaining until they can sell in an orderly way if they wish) current PI's often rush to the exits and without something in place to protect them e.g. company to buy shares at a fair market price not specifically a premium, then there could be a precipitous drop. Sorry if I didn't make that clear, I am somwhat comforted by the shareholder register as you mention. Best wishes, Michael
For anyone wondering about the sharp drop in Smiths News (LON:SNWS) today, it went XD for two dividends.
Just on this has the special dividend also gone Ex div today or is that tomorrow.
Slightly annoyingly they have used different language.
"The ex-dividend date will be 9 January 2025."
" the Company proposes to pay a special dividend of 2.0 pence per share, to be paid alongside the final ordinary dividend on 6 February 2025 to shareholder on the register at 10 January 2025."
Dividend
Following the interim ordinary dividend of 1.75p, paid in July 2024, the Company proposes to pay a final ordinary dividend of 3.4 pence per share on 6 February 2025 (FY 2023: 2.75p per share) to shareholders on the register on 10 January 2025, which will bring the total proposed dividend for the year to 5.15 pence per share. The ex-dividend date will be 9 January 2025.
Additionally - in line with the Company's revised capital allocation policy and reflecting the greater discretion relating to shareholder distributions allowed by the renegotiation of its banking facilities - the Company proposes to pay a special dividend of 2.0 pence per share, to be paid alongside the final ordinary dividend on 6 February 2025 to shareholder on the register at 10 January 2025.
Stockopedia listed 9th as XD for both Smiths News (LON:SNWS) dividends
Sky News reporting take-over bid for De La Rue (LON:DLAR) - all cash. I don't hold :-(
Buying US small cap ETF’s fed up with UK No11 has dug themselves a pit and it’s full of !
10-yr gilts now 4.86% in the UK. I suspect if they > 5% this could well cause a financial crisis. Rachel from accounts has not had a good start, that's for sure. Although its global, the UK is doing the worst of all the bige economies on rates. It's all about inflation. Labour are starting to make Liz Truss look good!
https://tradingeconomics.com/u...
Inflation, coupled with lack of growth (stagflation) - pretty much what you'd expect following the NI and minimum wage increases.
Well, we tried the other extreme and Mr Market did not like it.
We're trying the opposite he still does like it.
Is there a solution that is palatable? I suspect nobody knows. We're pretty much in the brown in the stuff.
I think the most palatable solution would have been to increase income tax by a couple of pence - that way the pain would have been evenly spread without disproportionately hammering businesses and denting growth. The government boxed itself in by ruling out any tax rises, but it's suffering now.
Could you expand? Im sat here a little confused to be honest. The yield on bonds rising affects future issuance but not historic issuance. The treasury can issue anywhere on the curve...so they issue into 3 year say ... a technical rule breach is hardly a crisis. Like I say though im confused.... but can't see why we should panic.
The treasury is continually having to issue more debt both to cover the deficit as well as replace maturing debt. This debt will incur higher interest costs as the result of higher gilt yields. The recent rise in gilt yields alone will cost several billion in additional interest costs. Yields are high across the curve so even short-term debt will be costly.
Hi Topinvest, sorry, on a different topic as I just wrote a comment to Graham re Impax Asset Management (LON:IPX) and the possibility of the company being taken private based on a comment the CEO made. As a seasoned investor and if I recall correctly a longer term holder of Impax, is this something you have concerns about or given the shareholder register or possibly the integrity of management and you feel shareholders would be given a chance to exit at a fair price if this were to happen? I appreciate this is not something anyone can say with certainty but longer term holders and more experienced investors no doubt get a feel for companies and also the type of management that are in place. Thanks and best wishes, Michael
Do you know what the planned fund raising by the Government in Gilt market are over the next 6 months ?
The gilt issuance calendar only goes out to Feb at the moment:
https://www.dmo.gov.uk/data/pd...
Hi Charles I'm not sure other than from what I have been reading they have an avalanche of Gilts to try and shift this year as an aside I have also been reading US will need to roll over a third of their $36 trillion this year (although some google searches say this was 2024) anyone know if they have already rolled it over or if its happening in 2025 as it its this year somehow Donald is going to need to shift $12 trillion of existing debt plus new issuance.
It looks like a challenging year for the Bond markets. I am just sticking to equities with reasonable-and secure - dividends and see what happens.
Morning Charles, I've read your interesting comment about it might be a 'challenging year for the Bond markets'.
I would be interested to learn why you believe this might be the case with all the government debt around the world which needs financing?
Many thanks David.
LogicalDavid- For that reason- the amount of expiring Government debt in the US alone is trillions. UK institutions have moved significantly from UK equities to debt- over the last 30 years from 53% to 6%. Possible changes to Pension fund rules could encourage more equity investment, aat a time when the Government will be tapping the Gilt market for large sums. Having said that i am looking at buying Gilts if rates increase another few points.
Do you think rates on ten year gilts will get over 5% Charles ?
I hope not- if they do mortgage rates looked difficult for those re mortgaging . https://tradingeconomics.com/u...
Morning All,
So many shares breaking through support and rolling over currently, not the start to the year I was hoping for!
ME International (LON:MEGP) one of my largest holdings, now below 200p. Sigh...
I bought a significant holding of ME International (LON:MEGP) on 25.03.2024.
Bought at 170.5p, trailing PE 12.5, PE+2 11.1, (Stockopedia) Value 44 (thus below average)
I sold the majority of that holding on 21.11.2024.
Sold at 207.1p, trailing PE 15.3, PE+2 13.6, (Stockopedia) Value 34
While I generally run winners, I thought MEGP was getting pricey, hence why I sold the majority.
Currently price 198.6p, trailing PE 14.8, PE+2 13.0, (Stockopedia) Value 37
So I don't think its that cheap anymore, certainly the Stockopedia Value ratings don't think so either. In my spreadsheet I currently estimate that it is 12pc above fair price, so its not a share I will get back in to at the moment.
The eps estimates are +5% for this year, then +8% for following year. So unless trading and earning estimates are increased, I am not interested at moment as it seems to be on too high a multiple at moment.
Same with PayPoint (LON:PAY) l sold quite a few around the last update, think just before, in both. The latest updates were not that good. Not surprised there was a pullback. But many small caps are in the same boat.
Really the market has been falling since September.
Budget changes have done nothing to grow the economy.
200p or just below is a strong support point. I’ve been looking for a point to buy back in. I’m just put off because the sentiment in UK business is so low at the moment. (Maybe that means it’s time to buy).
B&M European Value Retail SA (LON:BME) getting slaughtered on in Q3 TU, shares down 11%. 310p
As it happens, I bought shares in BME in Sep 2023 at 561p and sold them in Jun 2024 at 501p. So I got my buy wrong, but my sell right.
Nevertheless, BME is on my watchlist as a potential recovery play. Stocko's momentum score is 18. I've set a trigger point for when M>19.
Mark - are you worried at all about the debt levels at B&M?
Given the narrowing projected profits and increasing costs, does the lack of cash create an issue?
I like B&M and can see it continuing to be popular as the population look to cut costs but feel a little uneasy looking at the balance sheet
I like B&M and can see it continuing to be popular as the population look to cut costs
This thesis has not worked out well in the United States with the examples of Dollar Tree and Dollar General. The middle classes have not traded down to discount stores while their traditional low income customer base has cut out all discretionary spending. Temu has done a lot of damage as well.
I like the company and overall, I think it operates well. That said, I would like to see them pay down the debt to a level below 5 x Net Profit, to give the company more breathing room to handle any upward movements to the borrowing rate. I'm still accumulating shares, so this is good for me as I see it (the depressed valuation) as temporary, but I have a very long term holding span.
BME Re: debt - I take your point (After all, no-one wants to be holding another Woolies). If I'm looking for recovery plays then I expect things to be hairy. There's going to be a scare card. That's why I have a momentum trigger to give me some idea that things are turning around. The nice thing about Stocko's M score is that it contains both a share price and earnings momentum.
The thing I like about the M score is that it gives you some confidence that you're not catching a falling knife, and that some kind of stability is settling in.
Nothing is 100% guaranteed, of course.
B&M European Value Retail SA (LON:BME) looking to re-domicile in Jersey or Ireland, should reduce corporation taxation and make all the difference. I bought for the first time today. Rachel eat your heart out, oops sorry to be thinking this way.
I posted a while back when Ultimate Products disappointed that this might be a signal for some concerns amongst the value retailers.
I suspect that the likes of B&M might be getting squeezed from above as conventional retailers fight it out.
I dont think that B&M has a direct competitor, however, Home Bargains do overlap perhaps 60/70 % of the range? Home Bargains is under private ownership and seems to be a well run business. I would imagine that in locations where they both have stores that Home Bargains would be a nuisance to B&M.
No interest in Ultimate Products, B&M or Home Bargains
The Range sell many of the same products, often at lower prices than B&M European Value Retail SA (LON:BME), in my area their stores are close together. I go in B&M European Value Retail SA (LON:BME) but rarely buy anything. I don't find B&M cheap. The Range has taken over some Wilko products.
Both sectors getting dumped.
Graham, just wanted to say thanks to you, Megan and Ed for the discussion last night. I thought it was an interesting and insightful overview.
Although I forgot that they are acquiring SKY harbor capital which looking back had 'US$4.2 billion in assets under management (as of 30 June 2024)'. That will mop up some of the lost AuM from SJP although I am still wary of whether they will hit the broker's estimates.
Apologies this was meant in reply to my own earlier post but I think the unthreaded view probably confused me!
Oh dear Garmin - a bit of a let-down re. last night's tip! Before seeing this I had thought in reaction to the case made, how Garmin users are (effectively) rather addicted implying quality long-term revenues: a similar case could be made for Xiaomi which has been very successful at both the top end of mobile phones (Xiaomi 14 and 14 Ultra, very well regarded last year) also the budget end with the Redmi and Poco brands; and they are diversifying into a wider range of consumer devices; yet delivery of shareholder value has been weak, partly because Xiaomi appears to be investing in electric vehicle development. Garmin Connect down: Smart watches around the world not working properly amid online outage | The Independent
Marks and Spencer (LON:MKS) l thought was a good update but shares are down 7.5%, what am l missing?
No new Marks and Spencer (LON:MKS) broker upgrade Rusty, probably signalling slower rate of shareholder gains from here. Non food store sales soft, especially given new stores and refurbs are probably masking even slower performance in older store estate. UK economy and business taxes a concern. Market jittery given recent events and yesterday's economic woes.
The Directors have been significant sellers of stock since late 2023. I never think that's a very good sign.
Marks and Spencer (LON:MKS) Yet the share price increased significantly since then. Seems a lot of the selling was share options.
Marks and Spencer (LON:MKS) new government in Sept 2024...budget followed in Oct. Massive concerns for any business on the high street. Employers NI hike eating away at profits and the consumer is struggling to shoulder any further price increases.
Agreed its the threshold drop to £5k that's the real killer given a lot of these retailers work on part time staff who are either semi retired or students.
That was all known about before today. Think the new Government was in July.
Yes, but its not necessarily the case that they need to sell them despite immediate tax implications. I want management in for the long haul.
In almost all cases you will find that companies offer management the ability to satisfy their tax obligations as soon as share options vest and in almost all cases execs tick that box. That doesn’t mean they are not in for the long haul or that they don’t believe in their company. It means they don’t want to take tax risk and it’s pretty universal.
If they are selling the shares they own or those after tax it is a weaker signal. In Marks and Spencer (LON:MKS) case they are not.
Im not sure the personal tax affairs of the management are in the public domain.
Even Tesco (LON:TSCO) with their exceptional Xmas results - down. So much is down today its hard to believe the FTSE100 is actually up over 0.5%
Guessing oil and miners pushing up due to inflation worries.
No. It’s China news that affects Mining share prices. Longer term so will green demand for commodities. Mining shares are cheap. Big Mining sector bull market is coming and current prices for the likes of Rio Tinto (LON:RIO) Anglo American (LON:AAL) BHP (LON:BHP) Glencore (LON:GLEN) and Investment Trust BlackRock World Mining Trust (LON:BRWM) will see big gains in time. Short term the Mining sector is likely to continue to see big up and down days, and the time to buy them is on the dips.
See this link for a bit more:-
https://www.euronews.com/busin...
It is the other way around, higher oil and gas prices, will cause inflation.
That's what I'm getting at Rusty they are going up today off the back of future inflation fears which they are normally a cause of so that should benefit them.
Trading update from H & T (LON:HAT) today, I hold (for income).
In line trading, a rise in prospective revenue, but a warning of a £2m impact to come from increased NI. This is a significant hit, representing around 10% of future PBT. Not easily recovered either.
I rate this as a Hold, but only just, on the basis of a low valuation and a decent yield.
A typical UK company, dealing with quite a hostile environment. Lending rising due to an increase in average loan sizes/pledges.
Been a long term holder of H & T (LON:HAT) and have admittedly become bored of it and would like next time it gets to a fairer rating (PE of around 10) move onto something more interesting. In the meantime as you say I will continue to pick up the dividends. Always made me wonder if this will ever become a target of a PE company who would have access to capital.
Year after year, H&T has a huge normalisation gap. Can anyone explain why this doesn't matter?
On Impax Asset Management (LON:IPX) update i think Equity Development might be optimistic to assume AuM will be the same at end of financial year as end of the last quarter given 1) the falls seen in the last quarter and 2) we still have the exit of the large mandate from St James's to come.
So maybe a further profit warning is likely?
Impax Asset Management (LON:IPX) Yes outflows have been heavy for a while and would expect this to countinue. Performance of their funds not great either which isn't going to help. Much prefer Polar Capital Holdings (LON:POLR) in this space.
"smaller mandate with St. James's Place" according to Impax Asset Management (LON:IPX)
Impax Asset Management (LON:IPX)
On 31 December 2024, the Company's AUM totalled £34.1 billion, representing a decrease of 8.3% over the three-month period.
"This quarter we saw relatively high outflows, notably the closure of our smaller mandate with St. James's Place and redemptions driven by industry consolidation in our institutional channel in the Asia-Pacific region. More positively, we have continued to see a slow-down in outflows from our largest European distribution partner, BNP Paribas Asset Management, and from our US mutual funds.
Berenberg BUY, lowers target price to 470p (prev. 510p), a 94% upside
Good Morning, considering the announcement of the St James's Place mandate termination back on 13-Dec-24, do you think today's announcement was largely expected?
Impax Asset Management (LON:IPX) I considered the ESG aspect was overplayed as was the Greening of everything ,the target dates were far too soon, should have been linked to the rate that the rest of the world actually achieved, consequently our economy has been crippled and individuals become a lot poorer. There is likely a realisation it was all too fast & folks rethinking across many fronts.....including pulling out of such funds....there are far fewer willing to Buy In..
At last, some trading statements coming through on the RNS.