Daily Stock Market Report (Thur 9th July 2026) - PEBB, HSW, CPI, CCC, POLR

It turned out to be a rough day for the FTSE yesterday, down 1.7%, as markets were rattled by Trump’s declaration that the agreement to end the war was “over”.
Last night saw another 90 Iranian military targets hit.
If things escalate from here, it may involve the United States taking over Kharg Island, a strategically vital piece of land that’s just five miles long and three miles wide. It supposedly handles 90% of Iran’s oil exports.
Last night, the influential Larry Kudlow said on Fox:
Talking to military analysts, I have come to the view that the next big step in the Iranian war should be an American takeover of Kharg Island. That would completely cripple what’s left of Iran’s already decimated economy.
For those of us who were hoping for a quick peace deal, it sounds like things might be about to get worse, before they get better.
6.30am update: Trump says that Iran "called a little while ago. They want to make a deal so badly." Sounds promising, but Brent Crude is still up $6 this week - something more concrete than this will be needed to calm nerves.
Overnight market movements:
The FTSE is up 0.4% at 10,500
S&P 500 is up 0.3% at 7,505
Brent crude (September) is down 0.3% at $77.70/bbl
Gold is up 0.4% at $4,090/oz
Bitcoin is up 0.8% at $62,650
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Informa (LON:INF) (£11.1bn | SR61) | Tom Glocer was CEO of Reuters/Thomson Reuters. | ||
Severn Trent (LON:SVT) (£8.94bn | SR62) | Operational and financial performance in line with expectations. Confident of delivering at least £50 million of total performance incentives this year. | ||
Computacenter (LON:CCC) (£4.39bn | SR90) | Strong Q2 performance, ahead of expectations, following an excellent first quarter. Now expects H1 adjusted profit before tax to be c. double the prior year's relatively soft comparative (H1 2025: £81.5m). Now expects to deliver full-year results comfortably ahead of market expectations. | AMBER/GREEN = (Mark) The scale of the increase in H1 PBT, even if it comes against soft comparatives, suggests there may be more to come here. The overall impact is hard to judge, though, as we don’t have access to any of the broker coverage. | |
Londonmetric Property (LON:LMP) (£4.35bn | SR40) | £7.6 billion NNN (triple-net) lease continues to perform well. Investment activity “has maintained our sector leading income metrics with average lease lengths at 17 years and occupancy increasing to 98.3% from 97.7% at the start of the financial year.” | ||
Renewables Infrastructure (LON:TRIG) (£1.67bn | SR79) | The Sale and Purchase Agreement has been signed for the divestment of its 17.5% stake in the Beatrice offshore wind farm for c. £155m. | ||
Playtech (LON:PTEC) (£990m | SR66) | Playtech's trading in H1 has delivered results significantly ahead of market expectations. H2 to be lower than H1. PTEC now expects Adjusted EBITDA for 2026 to be at least €270m, significantly above the current analyst consensus (€219m). | ||
Bytes Technology (LON:BYIT) (£918m | SR68) | “The Group traded well during the first four months of the financial year, delivering double-digit year-on-year growth… and operating profit broadly flat year-on-year. The Board is pleased with progress to date, which is consistent with the outlook provided in our full-year results announcement.” | ||
Polar Capital Holdings (LON:POLR) (£917m | SR96) | Quarterly net flows £2.5bn, AUM rises from £30.6 billion to £45bn. £11.9 billion of positive market movements and fund performance..Strong performance in Technology, Artificial Intelligence and Smart Energy strategies. | GREEN = (Graham)
As I noted at the full-year results, the boom in the Technology sector has resulted in a very high concentration of Polar’s AUM in that sector. Technology accounted for 55% of Polar’s AUM at the end of March, up from 42% a year earlier, and it’s probably much higher now. So that's the main risk exposure: a change in sentiment in Tech. But the shares are still not very expensive in P/E terms, and the StockRank is 96. So while I acknowledge the Tech concentration, there is no need to change my stance here. | |
Spire Healthcare (LON:SPI) (£852m | SR58) | Due diligence by Toscafund is well advanced as it works towards the announcement of a 250p per share offer. Toscafund has requested a further extension to enable it to finalise its financing arrangements. | TAKEOVER | |
ITM Power (LON:ITM) (£781m | SR22) | The grant of £46.5m from the Department for Energy Security and Net Zero has now been formally awarded. | ||
Workspace (LON:WKP) (£626m | SR31) | The Saba Board “continues to firmly believe Saba's proposal to accelerate or increase the volume of disposals is unrealistic in the current market, and it positions Workspace as a forced seller and will likely result in wider discounts than we have recently achieved.” | ||
GlobalData (LON:DATA) (£573m | SR37) | H1 revenue +3%, underlying revenue growth +1%. Expects full year Adjusted EBITDA at the low end of consensus, reflecting planned actions in the second half to accelerate margin. £30m tender offer at 85p. | BLACK (low end of consensus range) | |
Capita (LON:CPI) (£337m | SR21) | Secured contracts with a Total Contract Value of £1bn in the first half of 2026, strongest H1 TCV performance since 2021 in Public Services. Adjusted revenue growth 1.6%. Pension scheme issues now expected to impact adjusted operating profit in 2026 by £25m – £40m with a £35m – £50m free cash flow impact, compared to previous expectations. “We now expect the Group to deliver positive free cash flow, before the impact of business exits, in 2027.” | BLACK (adjusted op. profit £25m – £40m lower than expectations) (AMBER/RED =) (Mark) | |
Brooks Macdonald (LON:BRK) (£210m | SR43) | Net inflows of £226m for FY26 incl. Q4 net inflows of £167m. Total FUMA increased 13.6% to £21.7bn. “…anticipates the full year 2026 financial performance to be in line with market expectations.” | ||
Cornish Metals (LON:TIN) (£141m | SR19) | Assay results received for drillhole SDD26_001A, the first hole of the two-hole Roskear programme, returning tin mineralisation across multiple intercepts, including 0.79m at 4.18% Sn. | ||
Hostelworld (LON:HSW) (£136m | SR26) | H1 Net Revenue +12% to €52.2m, Adj. EBITDA +11% to €8.2m. Net Cash €2.5m. “…no change in our guidance for the full year” | GREEN = (Graham) | |
Trufin (LON:TRU) (£126m | SR84) | Proposed return of £80 million by way of a tender offer and dividend. £56.81m (43% of share capital) as a tender offer at £1.40/share (c5% premium to last night’s close). Currently intends to return a minimum of £23.19m as a Special Dividend. | ||
Amcomri (LON:AMCO) (£103m | SR73) | Completed the acquisition of North West Transport Supplies Limited on a cash free/debt free basis for £3m +£1m deferred. NTS revenue of £3.2m and PBT £1.1m for the year ended 31 Mar 2026. | ||
Taylor Maritime (LON:TMI) (£85.7m | SR94) | $45m returned to shareholders via compulsory redemption. 37% of the Company's issued share capital will be redeemed at US85.83c/share (versus a 80c close last night). | ||
Pebble (LON:PEBB) (£82.8m | SR98) | 26H1 revenue and Adj. EBITDA ahead of last year, in line with management expectations. Facilisgroup revenue +7%, Brand Addition Revenue +4%. £2m extension to buyback program. Net cash at 31 Dec 26 expected to be c. £5m. | AMBER/GREEN ↑ (Mark) | |
First Tin (LON:1SN) (£52.8m | SR33) | Rock chip sampling has returned very high REE and technology metal assays from pegmatitic and biotitic zones within the highly radiometric Mole Leucogranite. | ||
Bango (LON:BGO) (£44.3m | SR15) | H1 Revenue +3% to $25.9m, Adj. EBITDA +34% to at least $9.0m, Cash EBITDA +16% to $4.3m. Net Debt $8.7m (31 Dec: $9.2m). “We have entered the second half of the financial year with confidence in both our strategy and in our ability to deliver FY26 in line with expectations.” | ||
East Star Resources (LON:EST) (£25.6m | SR13) | Programme c5,000 metres of diamond core drilling has commenced. Expected to take up to 3 months with assays and an updated resource to follow shortly after. East Star fully carried to production, with 30% interest. | ||
Kendrick Resources (LON:KEN) (£22.7m | SR14) | Discovery of high-grade rare earth element carbonatite mineralisation hosted within breccia at the Teufelskuppe Carbonatite Complex. | ||
Kazera Global (LON:KZG) (£13.2m | SR7) | has entered into a long-term Mining Cooperation and Production Sharing Agreement with South Africa AT Investments establishing a fully funded strategic partnership for the development of the Company's flagship Heavy Mineral Sands project. Retains 20% exposure without contributing to Capex or Opex. First production targeted by the end of 2026. | ||
GSTechnologies (LON:GST) (£12.8m | SR1) | Agreed to invest US$1.0m in Sodales AI in exchange for a 10% equity interest. | ||
Alien Metals (LON:UFO) (£10.8m | SR30) | Has received significant assay results for the last 15 of 32 reverse circulation (RC) drill holes completed in May 2026 plus recent diamond drill holes, including 3m @ 524g/t Ag from 183m; including 1.5m @ 1,039g/t Ag from 184.5m. |
Graham's Section
Hostelworld (LON:HSW)
Down 3.5% at 106.2p (£132m) - Trading Statement - Graham - GREEN =
(At the time of writing, Graham has a long position in HSW.)
The headline from this online travel agent is:
FY 2026 guidance reiterated, strong revenue momentum sustained through H1 2026
Here’s an overview of H1:
Net revenue +12% year-on-year to €52.2m (despite a volume reduction estimated at 3% from the conflict in the Middle East).
Commission rate improved to 17.7% (H1 last year: 15.8%) thanks to Elevate (hostels paying for additional visibility).
Adj. EBITDA +11% year-on-year to €8.2m.
Net cash finished H1 at €2.5m (as of December 2025, there was net debt of €1.6m).
Acquisition: the purchase of OccasionGenius will soon bear fruit with event calendars going up for travellers in Q3 2026.
A key financial metric - direct marketing costs as a percentage of revenue - reduced from 51% in H1 last year to 49% in H1 2026.
CEO comment:
We continued to make good progress against our strategic roadmap during the first half of 2026. Our third-party budget accommodation offering is expanding across platforms and languages, event discovery is due to go-live in Q3 across the platform, following our acquisition of OccasionGenius, and Social Passes are broadening our addressable market…
…Our full-year guidance assumes that the disruption associated with the Middle East conflict eases through the second half and broader trading conditions normalise, with the contribution from our growth initiatives increasing as the year progresses. The Group continues to monitor the ongoing geopolitical environment but on the basis of the above, we reiterate our guidance for the full year."
Given the disruption in the Middle East in over the past 24 hours, which inhibits travel to Asia and Oceania, it makes sense that the Hostelworld share price might dip by a few percentage points today. The outlook statement above is pretty clear: hitting full-year guidance will require this problem to go away.
Graham’s view
I’m a shareholder here, and I’ve been GREEN on it, as I think it’s far too cheap for what it is.
In my view, a successful online platform, with majority market share in its niche, and that benefits from network effects, is worthy of a premium rating.
It does not currently enjoy that:
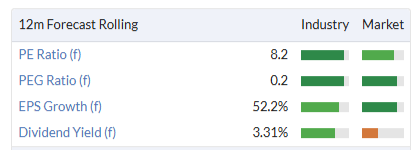
If it hits City forecasts this year (that is a big IF), then adjusted EPS will be heading for 14 cents, then 17 cents in 2027. The share price equates to about 125 cents.
With six months left in the year, there is every chance of a minor profit warning if Middle East disruption continues. But the range of possible outcomes surely cannot be all that wide, given that so many 2026 travellers will have already travelled or made their bookings by now?
Another question worth asking is whether we can trust the adjusted EPS figures. I do think they are inflated slightly by SBPs (share-based payments), but not egregiously so. SBPs were €1.8m in 2024 and €1.5m in 2025, while total adjusted profits were €17.4m and €15m, respectively.
Overall, therefore, I’m inclined to stay GREEN on this today.
There are some decent arguments for downgrading our stance. The share price reaction this morning suggests that there is some doubt around the company’s ability to hit forecasts this year. The outlook statement itself says that their assumption is that conditions will normalise. So if conditions don’t normalise, we can expect a profit warning here.
But from my point of view, this is already priced in. An adjusted P/E multiple of 8x for a company like this says it all. That’s a pessimistic rating and so I remain positive on the risk/reward that this offers.
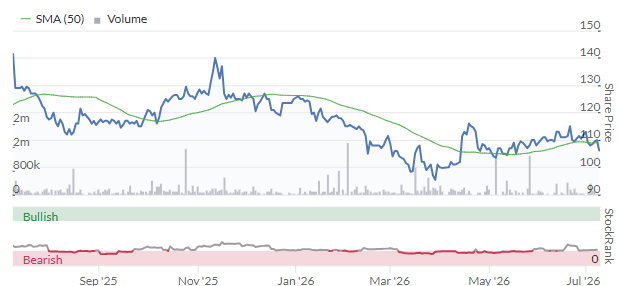
In closing, I'd like to note that Stockopedia no longer rates this as a Sucker Stock, as it did the last time I looked at it in March. The StockRank is only 26, but the category has improved to Neutral. Perhaps the computers will slowly come to agree with me on this one!
Polar Capital Holdings (LON:POLR)
Down 3% at 888p (£899m) - AUM Update - Graham - GREEN =
At the full-year results last week, we were already told that Polar’s AUM had spiked to £44.7 billion..
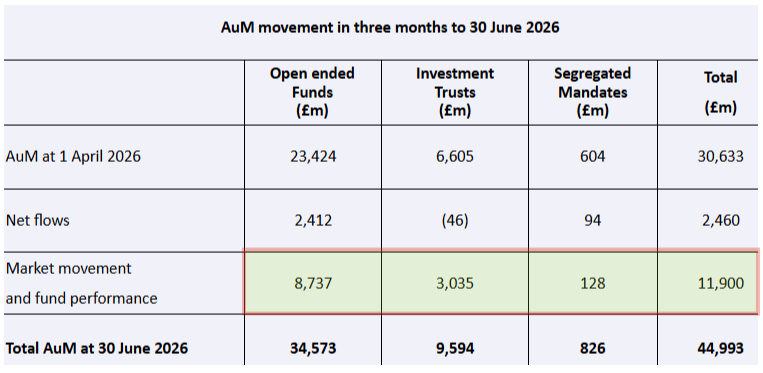
Today’s AUM update lets us know the official figure for Q1 (June 2026), which is £44,993m.
We also knew that there had been £2.3bn of net inflows since year-end.
The official figure for Q1 is £2,460m.
While the positive flows are both impressive and very welcome, they are overshadowed by the enormous c. £12bn surge in assets values flowing from market movements and fund performance:
CEO comment:
Strong absolute and relative performance from our Technology, Artificial Intelligence and Smart Energy strategies was a key contributor, supported by high-conviction thematic positioning.
Client demand was led by our Technology and AI funds, with positive contributions from Healthcare, Smart Energy, Global Absolute Return and Japan Value. Net outflows were primarily from Emerging Markets Stars and Global Insurance, with redemptions remaining largely client specific.
Graham's view
As I noted at the full-year results, the boom in the Technology sector has resulted in a very high concentration of Polar’s AUM in that sector. Technology accounted for 55% of Polar’s AUM at the end of March, up from 42% a year earlier, and it’s probably much higher now. So that's the main risk exposure: a change in sentiment in Tech.
I don’t see any new earnings forecasts today, so I can only refer you to the one I saw last time: EPS of 97.7p in FY March 2027.
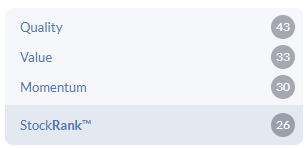
The shares are still not very expensive in P/E terms, and the StockRank is 96:
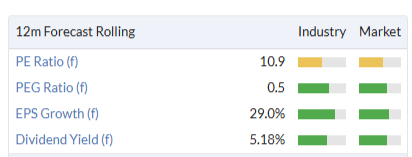
So while I acknowledge the Tech concentration, there is no need to change my stance here.
I note that the share price is off 3% today, and 8% over the past week.
This is on the back of a very strong run up in recent months - so I’ll interpret it as some ordinary profit-taking (i.e. “sell the news”). Correction: today's fall can largely be explained by going ex-dividend. Thank you to the reader who pointed this out!
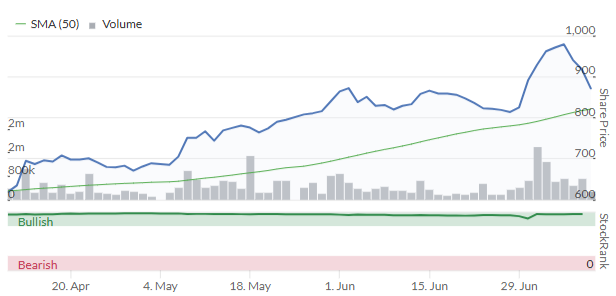
The rally has been driven by real earnings upgrades:
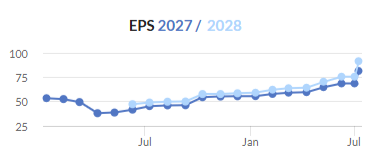
My overall view is unchanged: this fund manager is best-in-class.
Mark's Section
Pebble (LON:PEBB)
Down 1% at 58p (£82.8m) - HY Trading Update - Mark - AMBER/GREEN
I recently wrote a StockPitch article on this company, so I won’t provide much background today. It came to my attention when it appeared on a screen that I created to look for companies that are forecast to grow despite weak economic conditions, and looked like good value. Pebble (LON:PEBB) continues to feature on that screen despite the share price rising since I wrote the article.
Importantly, they continue to grow:
We expect to report a positive trading performance for HY 26 with Group revenue ahead of the prior year. HY 26 Adjusted EBITDA is also expected to be ahead of HY 25, reflecting the impact of revenue growth and the continued investment to support scaling at Facilisgroup.
However, this line is a little vague, so I am pleased they added some more detail:
Facilsgroup: revenue +7%. “...our approach to long-term partnerships has supported the constructive evolution of the pricing structure for our enhanced technology.” Sounds like they can increase prices by adding desirable features, which is a good place to be.
Brand Addition: revenue +4%. “...driven primarily by incremental revenue from new contract wins secured over the last year.”
These don’t look particularly strong revenue growth rates. However, they are ahead of the 2.4% revenue growth that is forecast by brokers. And there are signs that this is not just a one-off. For Facilsgroup, they suggest that their pricing strategy “will positively impact revenue growth from H2 26 onwards and significantly extends our committed revenues by entry into multi-year contracts.”
Profitability:
So, although this is an in-line update, I view this positively. There is a strong H2 weighting to EPS, so I can see why they may want to remain cautious:
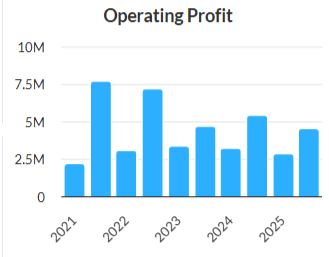
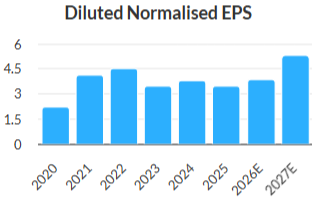
FY26 EPS is predicted to bounce back from a slightly weaker FY25, with the real growth in FY27. History is a little bit patchy, though, with periods of growth being followed by times of retracement:
In March, Panmure Liberum cut FY26 EPS but increased FY27:
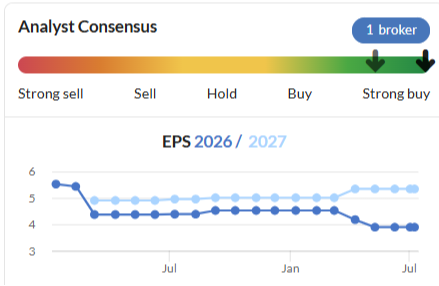
This was due to the company flagging increased investment in Facilisgroup to drive higher growth. I am naturally sceptical of these sorts of moves as they often leave scope for brokers to simply do the same next year if targets are not met. Also, my experience tells me that markets hate any short-term hit to EPS forecasts, even if it's due to investment in higher long-term growth.
These kinds of moves often give great opportunities for investors willing to look through a short-term decline (if the higher growth does arrive), so it is key for me that the high-margin Facilsgroup is showing signs of that improving growth profile in H1.
Cashflow & Buybacks:
One of the attractions of the company is its continued strong cash flow generation:
The Group's balance sheet remains strong and its excellent free cash flow generation is supporting both organic growth and, as announced today, a £2.0m extension of the existing Share Buyback Programme.
The company continues to view their shares as good value, with an extended £2m buyback today. Some investors may take umbrage at these buybacks being described as shareholder returns:
In the 12 months to 30 June 2026, the Company returned £14.3m to shareholders (12 months to 30 June 2025: £6.0m). Following these distributions, net debt as at 30 June 2026 was £1.2m (net cash as at 30 June 2025: £6.0m). Assuming the full utilisation of the £2.0m extended Share Buyback Programme, net cash as at 31 December 2026 is expected to be approximately £5.0m (31 December 2025: £9.6m).
However, it is clear that if you believe that the shares are undervalued enough to hold, then the company buying back shares should add shareholder value.
Panmure Liberum keep forecasts essentially the same, saying:
We maintain our EBIT estimates, but increase FY 26 and FY 27 FD EPS by 1% and 3% due to the new buyback.
PL suggests the company will report modest net debt at the H1 end, but reaffirms the company’s view that it will return to net cash by year-end.
Valuation:
EBITDA isn’t a great measure for this sort of company as they capitalise intangibles. The £5m forenet cash is a nice buffer, but doesn’t significantly move the needle for a company with an £80m+ market cap, so price-earnings measures are going to be the best way to value this.
A forward P/E of 15 isn’t obviously great value. However, this falls to 11 for FY27. Panmure Liberum have a FY28 forecast of 6.3p EPS, taking the multiple down towards 9x, making them look better value. We have to take brokers' forecasts with a pinch of salt when they are that far out. However, it is worth noting that promotional products' performance is tied to corporate confidence, and better end-market conditions may turn current headwinds into tailwinds.
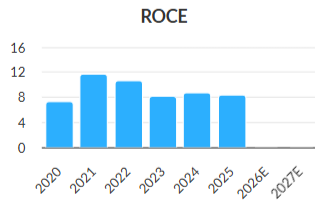
Strong cash generation means that they pay a dividend approaching 4% while buying back shares. This suggests that growth from here should be relatively capital light, and that the incremental returns on capital may be much better than the rather mediocre figures that the historical analysis suggests:
Mark’s view
While the forward P/E of 15 doesn’t scream great value, I think there are reasons to think that this company will grow revenue and EPS from here, at least in line with brokers' forecasts. This makes it look like a much better value for investors willing to take the long-term view.
Importantly, this trading update shows the key high-margin Facilsgroup leading the way, with H1 revenue growth ahead of FY revenue forecasts. There is still a strong H2-weighting, so I can see why management and brokers remain conservative. However, there are also signs that recent product investment is starting to show results, with customers willing to pay up for an increased feature set.
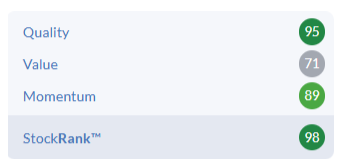
Strong cash generation, a reasonable dividend, and an ongoing buyback suggest investors may be relatively sanguine about the wait. Last time I looked at this company on the DSMR, I had a neutral view given the lack of previous coverage or a more detailed look at the prospects. However, my view has since been informed by writing a StockPitch article on the company. Despite a modest share price rise since my StockPitch article, I remain relatively positive about the company with an improved AMBER/GREEN view. Especially as it remains a SuperStock:
Capita (LON:CPI)
Down 17% at 232p (£m) - Trading and Civil Service Pension Scheme Contract Update - Mark - AMBER/RED =
That Capita were struggling with the Civil Service Pension Scheme contract was already known. On Tuesday they said:
Despite the progress made to date, we recognise the service has not been good enough, particularly for members waiting on bereavement, retirement and quotation cases and we are sorry for the distress and inconvenience experienced by those members. We now have the processes, automation and technology in place to work through the backlog…Capita is assessing the implications of the matters contained in the statement and, if required, will update the market as soon as it is able to do so.
This caused a 14% drop in the share price, but now it looks like an underreaction. Today, we find out that:
The issues with the Civil Service Pension Scheme contract and impact to the wider Pension Solutions divisions, post mitigating actions across the Group, are now expected to impact adjusted operating profit in 2026 by £25m – £40m with a £35m – £50m free cash flow impact, compared to our previous expectations.
I can’t see any updated broker coverage, but given that adjusted operating profit was around £114m in FY25, this is a 22-35% hit compared to historical numbers. Third-party reporting suggests that RBC cut their 2026 EBITA forecast by a whopping £40m to £64.8 million. RBC also reduced its 2027 EBITA forecast by £10 million to £127.9 million.
The problem:
The Cabinet Office officially awarded Capita the £239 million contract to administer the Civil Service Pension Scheme in November 2023. Following the contract award, Capita entered a two-year operational transition period before formally taking control of the scheme's administration in December 2025, replacing the previous provider, MyCSP.
This week, Paymaster General, Nick Thomas-Symonds, issued a highly critical update to parliament on Capita's handling of the Civil Service Pension Scheme, claiming that its systems were “overwhelmed” and the company was “completely unprepared” for taking it on.
It seems the government is withholding £9.9m of payments and seeking to recover the cost of deploying more than 140 Cabinet Office officials to help clear the backlog.
We have to be careful with political statements, as there can be an element of apportioning blame wherever it doesn’t fall on the government. However, there is no getting around that this is a damning public assessment of Capita’s capabilities by a key client.
With some government officials wanting to simply in-source the contract back into public administration, this will be an ongoing risk for the company.
Valuation impact:
Without being able to see the update notes from brokers, it is really hard to give a precise impact assessment. A simple calculation of a £40m pre-tax impact for FY26, with £30m post-tax, suggests EPS falls by 25p/share, perhaps a bit more due to the cash flow impact; with perhaps a £3-5m higher interest payment as a result? This looks to be at least a 50% cut in FY26 EPS.
At the moment, RBC estimates the FY27 impact to be much lower, at £10m EBITA, so maybe around 10p/share EPS reduction? So perhaps a 20% cut on consensus. The market appears to be looking through the FY26 impact and basing the reaction on the more modest drop in FY27. At this stage, there must be significant uncertainty about the eventual figure.
The bull case:
There has been an argument from holders here that this company is undergoing a significant re-invention. Selling off non-core businesses to reduce debt and focussing on key public sector contracts. For example, very smart investors Rockwood Strategic said this about Capita in their 2026 Annual Report:
Critical to our investment thesis, the company announced the exit of its loss-making legacy Life & Pension contracts and exited its Contact Centre activities during the year. This almost concludes the turnaround process which has stabilised the balance sheet, focused the business and transformed profitability. We expect a significant increase in free cash flow generation as the restructuring concludes in 2026 and 2027, justifying a large re-rating, the building blocks of which are now in place.
And they specifically highlight the ability for AI to transform public sector efficiency:
…in one investment, namely Capita Plc, we believe they are at the absolute forefront of the biggest AI efficiency opportunity in the country; the inefficiency of public sector services and should be a major beneficiary of adoption.
Rockwood may be right in the long term. However, this week's events highlight that transformational opportunities also carry significant operational delivery risks. A concept that investors need to keep in mind every time a company trumpets their use of AI in business processes.
Mark’s view
I’m pleased to say that Graham has been mostly negative here recently, highlighting that while there is evidence of business simplification and an improving balance sheet, there is still a long way to go on the turnaround. Backing this up is the Sucker Stock status, which is surely due to take a further dive once the algos have processed recent events.
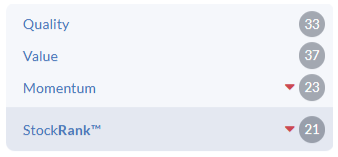
That distance to eventual turnaround appears to have widened further today, so I keep our broadly negative view of AMBER/RED, as it is not clear whether this week’s price falls have sufficiently priced in the risk of a further deterioration in the company's relationship with its key client.
Computacenter (LON:CCC)
Up 6%at 4403p (£4.39bn) - Trading Statement - Mark - AMBER/GREEN =
Good news:
The Group delivered a further strong performance in the second quarter, ahead of our expectations, following an excellent first quarter. As a result, we now expect first half adjusted profit before tax to be approximately double the prior year's relatively soft comparative (H1 2025: £81.5m).
Leading to:
Looking to the full year, while we remain mindful of a tougher comparative in the second half of the year, we now expect to deliver full-year results comfortably ahead of market expectations.
Again, the market cap size means we don’t have access to the actual notes, and I can’t find any details from third-party sources. My instinct says that the 6% rise in share price will be low compared to the possible EPS upgrade, given the doubling of H1 PBT, even after adjusting for weak comparatives.
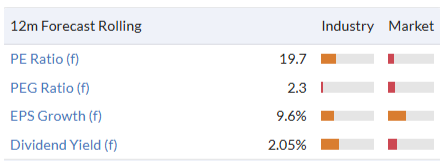
However, the valuation was already quite punchy for a software reseller, even one that offers many value-added services and handles the entire implementation. Even if we assume an upgrade to EPS higher than today’s share price, the algos are likely to still view this as expensive compared to the market and industry:
Sentiment shift:
What is most interesting to me is the shift in narrative. When Roland reviewed the same timed trading statement last year, the 2027 EPS going into the update was 210p and the share price was £22, making the 2027 P/E 10.5x. Since then, expectations have moderated before more recent upgrades kicked in:
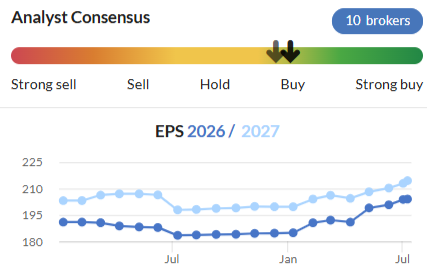
Today, the 2027 EPS consensus is 214p, prior to any upgrades stemming from today’s FY26 beat, so this has not changed significantly, yet the 2027E P/E is now around 20.
What has really changed is the market sentiment regarding Computacenter’s relationship with AI. The company has experienced a massive shift from cautious scepticism to treating it as a big AI winner. Fears lingered even into early 2026 that an enterprise IT spending slowdown would deplete the company's order books. Instead, the order book has been increasing:
At 30 June 2026, our committed product order backlog was well ahead of the position at the end of 2025 (31 December 2025: £7.1bn), reflecting strong order intake during the half.
Given this, the rise in share price is not necessarily illogical, especially as they upgraded expectations today. However, it shows how much sentiment and outlook can move share prices in the short term, even in FTSE 100 companies.
Mark’s view
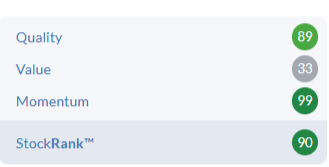
Given today’s upgrade and continued momentum, it makes sense to remain mostly positive at the moment. The scale of the increase in H1, even if it comes against soft comparatives, suggests there may be more to come. However, the rating has now almost doubled since Roland gave the company the thumbs up last year, and the Value Rank no longer provides any obvious downside protection should Momentum reverse:
So we will be vigilant for signs that recent trading strength may normalise or the order book weaken. However, with no sign of that on the horizon, I keep our mostly positive view of AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Catching up at the weekend as per usual. Thanks for the write-up on Polar Capital Holdings (LON:POLR). I wonder how much of the +£11,900m is due to improved profitability in the underlying holdings versus multiple expansion. The Thursday RNS did not give anything away but I wonder if someone at Polar Capital Holdings (LON:POLR) has done that calculation.
Anyone who has seen any clips of senior Civil Servants being grilled at select committee hearings over the last 6 months won't be surprised at the apparent lack of ability to do any kind of credible due diligence before awarding Capita (LON:CPI) the contract. Surely it shouldn't have taken much to discover that they were 'woefully unprepared' to take the contract on?
Time & again these senior people are unable to explain issues such as project costs ballooning, how contracts are awarded or even who's responsible for various cock ups. Add that to the terrible reputation of Capita (LON:CPI) and it was a recipe for disaster.
The Polar Capital Holdings (LON:POLR) fall today is more likely to be due to going ex dividend. Broker Cavendish raised expectations slightly in a note out this afternoon.
CAPITA CPI
A couple of comments.
Rockwood Strategic and Harwood Capital are the the only companies I have heard extolling the virtues of Capita, publicly and quite often. The two have a close relationship.
Rockwood grew its NAV by 8.9% in the twelve months to end June though in the three months to June it achieved a very creditable 14.6% helped by the Space X effect on Filtronic and two takeovers . The longer term (5 year and more) performance has been very good in a very difficult market for UK small caps.
Prior to the recent Capita freefall Rockwood had just under £11mn in Capita which was 6.1% of their Aum. (https://dtbjgrx62nat1.cloudfro...) large but not stupidly so. I don't know if they have just been unlucky with this investment, or misinformed, or whether the management at Capita has just not simply overreached its capabilities. Perhaps all those and then some. I don't know any investor, institutional or otherwise, who has not made some dreadful errors.
This - the Civil Service pension debacle - however is indubitably ghastly news for Capita and deals another body blow to their already shaky reputation. I can imagine that this fund is a nightmare to administer though I would be grateful if someone in a better position could enlighten me as to exactly what the responsibilities involve. I assume this is regular payments to beneficiaries, registration of new entrants, dealing with bereavement changes. i.e. glorified clerical. Who actually manages this pension fund?
My own experience with this company gave me a highly unfavourable impression some years back. I just thought they were a hopelessly bureaucratic organisation with clueless staff. I realise the newish management has been trying to simplify the operations but i wonder if now they will be given the time - though I do also wonder who might be competing for their mandates?
P.S. I have a small short position in capita
Oasis Capital Mgmt is Capita (LON:CPI) largest shareholder with ~15% and they are a very successful deep value turnaround hedge fund that have had a lot of success in the UK (Restaurant Group, Trainline, Kier, Costain) and I believe they will be successful here as well, given they have recently taken a board seat at Capita. The government has a short memory and Capita will continue to winning large government contracts.
Given the very low PE rating (<5x PE '27E), I believe this is a very good entry point on a 2-3 year horizon. Post their contract centre disposal they are no longer a BPO business, but a public sector and pension biz, similar to Serco and XPS Pension who are on more than twice Capita's rating. You therefore have the double benefit of increasing EPS (+50% over N2Y) and closing the PE rating discount to peers, which in itself could lead to a doubling of SP. I added to my positioin today
Brooks Macdonald (LON:BRK) could be at an inflection point here - This is appears to be a materially positive trading update & one of the better UK wealth management flow announcements of recent Qs. The significance isn't simply that assets have increased, the key point is that organic growth has clearly inflected upwards, suggesting management's turnaround strategy is beginning to work. Peel Hunt analysts note that "while flows are better, headwinds remain with respect to mix" and that "further delivery will be required to drive stronger profit growth"
Good that they've got in front of the interest fees which the FCA didn't like at Rathbones (LON:RAT) - so BRK is in the clear - a potential bid target perhaps now, the share price doesn't factor much - given today's update suggests the turnaround may be gaining traction
Liontrust Asset Management (LON:LIO) looks like a lot of shares are changing hands decently price rise today
I don't think that Richard Staveley has got this wrong, yet. It is clearly in his stabilisation phase, which he stated would be volatile. It is clearly a classic turnaround situation, and to turn around it needs to be crap to start with. It is a top five holding in Rockwood Strategic (LON:RKW) - 6.1% (Capita (LON:CPI) )
Capita (LON:CPI)
"we believe they are at the absolute forefront of the biggest AI
efficiency opportunity in the country; the inefficiency of public sector
services and should be a major beneficiary of adoption."
May the saints preserve us! AI may or may not have its places, but customer support is not one of them. I've interacted with them with some banks and InteractiveBrokers (I recommend avoiding them). They're garbage! Yeah, they're "efficient" if you don't want to employ anyone and don't care if the service is zero.
The thing is, if you have a problem, then it usually has some complexity to it which needs human resolution. AI spitting out canned answers usually doesn't cut it.
SK HYNIX IS SAID TO GUIDE ITS U.S. OFFERING PRICE AT $149 PER ADR, ABOUT 3.1% ABOVE ITS KOREA CLOSE.
All the best
Another MelloMonday next week... Monday 13th July from 5pm do join us.
We will have a lot on show as three companies join us (VP (LON:VP.) European Green Transition (LON:EGT) & Oxford Technology. There will be a couple of educational sessions on finding your forgotten investments and ‘Pensions in 2027’. Familiar Stocko face Mark Simpson will then round off MelloMonday with an insights session.
Full schedule and more info available here: https://www.melloevents.com/mm130726
Use code MMSTOCKO50 for 50% off. Shareholders of our presenting companies are eligible for a complimentary ticket with code SHMM26.
Trump and Iran
Trump will wait after the midterms in order to completely take over the Strait. All depends on the results though.
All the best
Lindsell Train Investment Trust (LON:LTI) down 6% today, although I can't see any news. It reported a NAV of 697p, so a discount of nearly 22%. Contrast that with a few years ago, where it was on a premium (as a general rule, never buy a trust on a premium).
A lot of his holdings have fallen out of bed and are at reasonable valuations. I think he will make a sizeable comeback. BWTFDIK. Dividend yield of 5.2%, too.
Hmm, today's chart looks interesting.
544p seems to be a magic number, acting as a floor on the price.
I don't hold.
Record insider buying across the US tech sector overall with purchase transactions hitting the highest levels in 15+ years. It's a broad signal from many tech execs, suggesting they see value after dips.
All the best
Are you deploying your cash yet?
We have deployed most of the cash available yesterday.
FuelCell Energy (NMQ:FCEL) was a position initiated yesterday and sold this morning after the Siemens (NSI:SIEMENS) MOU announcement.
All the best
I held Capita (LON:CPI) partly because of Richard Harwood’s seemingly strong case for it in Rockwood Strategic (LON:RKW) updates. RKW has way outperformed all the other UK Smaller Companies Trusts over both 5 and 10 years. This link shows all the Trusts in the sector and their 1 year, 5 year and 10 year performance records…..along with a lot lot more:-
https://www.theaic.co.uk/aic/f...
But I took the profit at £3.30. A combination of again the share price falling back from £4 along with those negative updates about the civil service pension scheme made that decision easy. Perhaps it’s a rare example of Richard Harwood getting it wrong? If still believing in the long term recovery story then there’s a case for buying after the big recent falls, including today, but I’m unlikely to get tempted again.
I think it is a case of Harwood being sold a story by the capita board and sadly the distance from ground truth to the capita board was bigger than it should have been - the centre did not hold; Mere anarchy was loosed.
Agreed, Andrew. I've recently retired from the Civil Service and there is no sign of my pension, so I have been following the various hearings and statements quite closely. This statement by the Paymaster General is worth a read (and the debate that follows, if people have the time) https://hansard.parliament.uk/...
Promises have been made and broken to the Cabinet Office and the Public Accounts Committee. It's highly likely that those same promises were made to Capita's board and they (reasonably enough) believed them. This is a story about corporate culture and telling the truth to your superiors and customers, however uncomfortable. Even simple things like the time taken to answer calls are misreported.
I would say this has further to run and more pain is in store for Capita shareholders.
Well Harwood and/or Richard Staveley does not suffer fools or bad management gladly. However think their stake in Capita (LON:CPI) is small in % terms so don't know what influence they will have on other shareholders.
As of June 30, 2026, Capita (LON:CPI) was Rockwood's 5th largest position making up 6% of NAV, so wouldn't say it is is small
Capita (LON:CPI) it might be 6% of Rockwood's NAV, but it's only 2.86% of Capita (LON:CPI)'s share base.
I just wouldn't touch it with a bargepole. The Eye has always been critical of the lack of value that Capita (LON:CPI) provides (referring to it as "Crapita"). It baffles me why government departments keep handing them big contracts despite historical failings.
Capita (LON:CPI) , I had dealings with Capita years ago when i was in the insurance claims business and they bought a then well-known and respected loss adjuster. Capita had no experience whatsoever of loss adjusting. and it didn't take them long to completely destroy it and eventually they had to divest I think at a nominal sum.
It was one disaster after the other - even then we referred to them as 'Crapita', as also referenced by another poster here. I thought perhaps they had turned a corner, as despite their (many) failures they kept being awarded government contracts - but then again, government contracts have always been regarded as milking cows.
The sp did well on the back of the latter so I thought perhaps I'd misjudged, however not surprised to hear of the latest debacle, succeeding a number of previous ones. In my view Richard Harwood definitely got this one wrong.
Computacenter (LON:CCC) Up 12% early trading. Woohoo! Some companies have really been popping lately.
I first bought these in 2022, with a couple of top-up along the way lower down, which fortunately turned out to be a good idea. My first price was at 2902p. The stock had a fwd PE of 17.4. That was suboptimal, I think. I'll generally only buy a share now when the fwd PE is less than 16. Stocko is great for this, as I can easily set up alerts.
My second entry was at 2257p. The fwd PE was 14, so a much better proposition.
CCC has an avg ROE of 21.8% and has been growing its revenues nicely. It fits my quality profile nicely.
So that's what I look for to buy in: good quality company, fwd PE < 16. There's actually a number of them. I probably could have bought companies like AJB, RELX, EXPN (probably) if I had been more disciplined and mechanical in my approach. They've rebounded nicely since then. There are still a number of Nick Train's digital disasters (or "winners", as he likes to calls them) available. I jest. What I mean is they are good companies but Train got in at the wrong price.
CCC is involved in the AI build-up, so there's probably more fuel in the tank on that one. Fwd PE is 19, so I personally wouldn't buy in now.
It's difficult to know when to sell. I like to operate a buy-and-hold strategy, but I think I've been to rigid in my approach. It's trying to find a nice trade-off been letting your winners run, and avoiding the up hill and down dale (or going sideways for many years) companies.
My thinking so far is to set a Stocko alert when the value score is less than 19. That's my cue to sell or top-slice. That gives you leeway for the share price to get ahead of itself, but not so far ahead that it really makes sense to take some off the table.
So that's the lesson I've been learning lately. Buy and hold, sure, don't rush to sell, but top-slice when things are getting too absurd.
So CCC is a hold from me. Make of that what you will.
Not wanting to overplay the point but as least today we can see that in recovery stocks - looking to rebuild rating and reputation - free cash flow is the magic number everything rests on. When it works Rolls-Royce Holdings (LON:RR.) eventually came through - it's very powerful. Alas it's a more depressing event when it does not.
I would add little revenue growth can make FCF a hard number to manage.
Capita (LON:CPI) apologies to holders but what a difficult one this is....whenever it seems to be going better they find a new cashflow consuming banana skin. So today free cash flow targets are postponed leaving them looking optimistic in the first place and RCF is increased and extended. For equity in a business with too much debt, free cash is everything yet remains elusive. Lots of chat with the statement but hard to ignore another year where they disappointedly miss free cash targets - the only positive surprise in the last twelve months has been hitting cost saving targets and so delivered last years numbers. Attempts to guide that followed sadly disappointed yet the shares seem to be expecting poor news. I have no position having exited when revenue looked weak last year.
RE: Capita (LON:CPI)
The ministerial statement on this on July 6th was a clear red flag:
https://hansard.parliament.uk/...
We are executing robust, continuous action with immediate financial consequences. We have already hit Capita’s bottom line by withholding £9.9 million in payments, because the Government will only ever pay for what is successfully delivered ...
... I am not ruling out further interventions, but we need to build the unvarnished evidence base that will serve as a strict prerequisite for further formal escalation, including potential litigation or step-in remedies, should performance fail to improve. In October, the House will receive a further update on the findings of the independent audit, the performance of the remedial adviser and the longer-term structural options being considered, including meeting our manifesto commitment by bringing the scheme in-house.
So there could be worse to come.
Meanwhile Capita has had the Royal Mail pension contract terminated due to performance failures and lost the Learning Frameworks 2.0 contract as a direct result of the civil service pension contract failure. Plus there's increasing pressure to apply the Procurement Act to ban Capita from future government contracts.
Against all of this there are only a handful of suppliers who have the capacity to tender for these government contracts - Capita still run over 80 such projects. The government aim to in-source these types of projects is a fantasy as it stands.
All too tricky for me and it's a rare case where I struggle to see why Harwood have got themselves involved.
timarr
It had two years of transition to prepare, and its senior leadership gave me explicit personal assurances ahead of the handover that they were fully capable of managing the workload
This episode highlights the severe limitations of outsourcing the civil service pension scheme.
why not put the penalty provisions in the contract then you ffin idiot - is it not clear that verbal assurances perhaps mean didly squat if its not in the contract. would have been easy to it into contract - that payment is not made if everything does not work "on spec" as promised.
the funny bit is that there is perhaps no one more unreilable than the "powers that be" promising the earth and delivering nowt themselves.
A civil service failure rather than Political?
RE: Capita (LON:CPI)
why not put the penalty provisions in the contract then you ffin idiot
The contract was negotiated by the previous Conservative administration.
timarr
normal govt procurement is based on "lowest cost bid that sounds realistic".
Competition drives the price down to a level at which a certain level of failure is certain ( in terms of time-cost-quality). the trick is to keep it minor.
it's a Systemic feature of outsourcing, it impacts government outsourcing because govts are bigger and more complicated than companies.
when there are Contractual penalties that have real impact the bid pool dries up.
I understand the strategic idea from Harwood's presentations, however with Capita the issue seems to be bad execution. The latest "mishaps" along with change of Gov (Civil Service pension deal predates Labour) - suggests Capita will face an uphill battle for the next few years to "help" Gov improve on inefficiency.
Given the unfortunate but apt Crapita monkier - why they didn't change the name years ago is beyond me. Had experience of dealing with them in the 1990s not good back then! Given the amount of effort large companies put into corporate ethos / branding you would have thought....
Trump has now said the Iranian regime has been in touch wanting a deal! Yesterday may have been a buying opportunity IMO.
What are the odds that either Sat or Sun we here the usual old boast of "tremendous talks have taken place"
Taking Kharg island
Does anybody still believe what Trump says? I find it remarkable. Liars lie. Swindlers trade ahead of information. He has probably shorted oil again.
Agreed 100% but he still moves markets, it also staggers me that nobody seems fussed with the industrial level of corruption that is being done without even trying to hide it.
How many times can trump pump and dump thne oil price ? withn the same old same old - someone has to be making a killing here,
Trump is desperate now. If you believe what he says then yes maybe the pull back was a buying opp.
Only two ways I can see out is they give Iran control of the straight and the rest of the world pays the tolls or its full on invasion to try and topple the Republican Guard and personally i don't see them fancying the second choice.
True. Iran though only needs to survive. The longer it goes on, the worse it gets for the US and the rest of the world. There may be ships leaving the straits, but how many are actually trying to re-enter?
There is another option - to provide convoys moving through the straits with military protection. I find it extraordinary that the USA didn't plan for this from the beginning. Even more extraordinary is the thought that perhaps they aren't able to do this - that a few cheap drones can overwhelm the largest navy in the world! If that is the case, it is a classic case of planning for the last war not the next one.
Personally think they should have looked at the mess Russia has gotten into in Ukraine before the off. The US is vastly superior on all levels military wise but with this waterway all you need is a load of fellas setting off dumb drones from the back of a flat back truck and you can cause massive problems.
As a military guy said Iran don't need to control the straight just need to make it dangerous.
The strait accounts for more than 90% of Iran’s annual trade. Kharg island is also important and any closure will immediate destroy the regime that controls Iran.
In less than six months they will collapse.
Has someone actually said this misleading statement? Unless he had a lot to drink!
All the best
That's not so different to what Trump thought about Iran more generally before giving in to pressure from Netanyahu to attack. One thing it's proved is that while Iran can be hit harder, the regime can withstand the pressure far better than Trump and the US can. $1 on gas and the shit hits the fan. And putting serious numbers of US military at risk with an invasion? ...... And after the midterms he's likely to have a less compliant congress, who won't be so forgiving to the executive ignoring the constitution.
Wait till after the midterms
President of the US does not need to control the house or the senate because of his presidential war powers.
He will make sure to have the spending/funding available.
Would be ideal for him though to control both.
All the best
Just run a network of oil + gas pipeline(s) - new or enlarged, through Oman + a new / enlarged port - bypasses Straight of Hormuz.
Will take a bit of time to organise. Would have to consider the Houthi threat on the left hand side but doable.
Meh, Trump says a lot of things. I suspect he's actually right on this, though; on the basis that sometimes the sun shines even on a dog's arse.
It's difficult to know if the situation will be "fully resolved". There may not even be such a thing per se.
To understand what is going on with Trump i have found Dr John Gartner to be the best source. A clinical psychologist at John Hopkins.
Doctor Alarmed by Trump’s Dangerous Health Crisis | The Daily Beast Podcast
Trump has a malignant narcissistic personality and now suffers from fronto temporal dementia. When looked at through a clinical lens it all makes sense.
I suspect that he launched the strikes because he was upset that the crowd size at Khomeini's funeral was larger than the crowd size at his 4th July speech.
I must read. He always slips in a 'how great he is' comment in very communique lending support to the narcissism argument. Then again aren't most political leaders narcissistic in some way albeit having the sense to have good advisors.
Are most political leaders narcissistic? Not to the extent that Trump is.
Democratic ones surround themselves by those they considered most suitable for their roles and welcome discussion and debate - the same goes for chief executives. Populist ones only consider yes-men. Leaders pursue the policies they think are right - so need to withstand criticism but that's not the same as being narcissistic.
Anyone going into politics these days has to be resilient and self-confident because of the barrage of online abuse and personal threats that 'free speech' allows to happen - being self-confident is not the same as narcissism.