Daily Stock Market Report (Tue 1 April 2025) - PEEL, SQZ, SAG, GNC, RNWH, TPK, PINT, PINE, CLI

Good morning! A special reminder to watch out for false announcements this morning.
Today's Agenda is complete, we think!
1pm: wrapping it up there, thanks everyone.
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| Travis Perkins (LON:TPK) (£1.1bn) | Full Year Results | Rev -4.7% to 4,607m, with adj op profit -23% to £152m. Management blame price deflation and lower volumes. Outlook is for adj. operating profit to be “broadly flat” in FY25. This appears to be significantly below previous consensus forecasts. | BLACK (AMBER/RED) (Roland) Weak results were aided by some working capital inflows. However, today’s outlook statement appears to equate to a significant cut to previous expectations for FY25. Management believes macro conditions will have to improve to stimulate a recovery – hard to predict right now. In addition, the company is without a CEO, as September’s appointee has resigned due to ill health. I’m inclined to take a mildly negative view at this point as I’m not convinced the shares are especially cheap relative to today’s guidance. |
Greencore (LON:GNC) (£747m) | TU | Strong Q2 revenue & vol growth, driven by new and existing customers. Good cost control has improved profitability. FY25 adj op profit to be ahead of expectations in the range £112-£115m. | GREEN (PINK) (Roland) [no section below] A short but positive update from Greencore this morning. The sandwich and ready meal producer says that “profit conversion” was better than expected in Q2, supporting an upgrade to full-year guidance. This situation is complicated slightly by GNC’s possible interest in acquiring BAKK (I hold). More broadly, GNC is a low-margin business that I’d not want to pay a high P/E multiple for. But earnings forecasts have trended higher over the last year and the P/E of 11 looks reasonable to me. The shares have Super Stock styling and I agree that a positive view makes sense. |
Serica Energy (LON:SQZ) (£525m) | Full Year Results | Rev -21%, PBT -58% to $160m. Final div 10p. Triton exp complete June, FY prod 33-37kboepd. | AMBER/GREEN (PINK) (Roland - I hold) Today’s results show the expected shortfall in revenue and cash flow as a result of last year’s unscheduled outages. We now learn that the current Triton outage is expected to continue to the end of June. In the meantime, the final dividend has been cut to allow more flexibility for field development and M&A spending. I can see the logic in this, assuming that the threshold for return on investment is not diluted. No updated forecasts are available to me today, but the apparent value on offer here suggests a mildly positive view remains appropriate. |
Renew Holdings (LON:RNWH) (£524m) | H1 TU | H1 trading in line with revised expectations. Rail still slow, but lower capex being partly offset by maintenance demand. Water strong with growth potential, energy and infrastructure stable. FY25 adj op profit exp >2024 result of £70.9m. | AMBER (Roland) [no section below] Investors will be relieved that today’s update is in line with revised expectations, following January’s profit warning. There are still some signs of weakness in rail, but other sectors appear to be performing well. Nuclear expertise remains a differentiator here vs listed peers. While there is perhaps still some risk of a further warning, I think the P/E of 10 looks sensible and could justify a closer look. I’m staying neutral out of respect for the recent warning, but I’d hope that May’s H1 results will validate a more positive view. |
Pantheon Infrastructure (LON:PINT) (£449m) | Full Year Results | NAV per share 118.1p (Dec 23: 106.6p). NAV total return 14.3%. Div 4.2p. Agreed first realisation. | GREEN (Graham) Studying this infrastructure investor for the first time, I like what I see with a 20% discount to NAV and good diversification across sectors, although I would like to see a bigger portfolio with a larger collection of individual investments. Valuations are based on DCF forecasts with PINT's cash flows being index-linked in many cases. I'm going to go out on a limb and suggest that the risk/reward looks promising here. |
Pinewood Technologies (LON:PINE) (£325m) | Full Year Results | Revenue +15.1%, adj PBT unchanged at £8.5m. Total users up 6.3% to 35.2k. Rollout at partner Lithia completed. | AMBER/GREEN (Graham) [no section below] (formerly Pendragon - changed its name after sale of dealerships) There is scope for this to grow substantially with 5 of the top 20 UK dealership groups currently supplied by Pinewood and with another major contract announced in February. In addition, the company is preparing to roll out in North America with a new HQ in Florida. So the upside from growth could potentially be very exciting. For now, the PEG ratio is below 1x (only 0.5x according to the StockReport) with a ValueRank of only 10. It is ranked as a High Flyer and I’m going to upgrade it to AMBER/GREEN as the near to medium-term growth prospects strike me as interesting and may justify the current high valuation. |
Niox (LON:NIOX) (£302m) | Full Year Results | Rev +14%, PBT +90% to £7.8m. Takeover discussions at prelim stage. Outlook confident. | PINK |
CLS Holdings (LON:CLI) (£280m) | Full Year Results | Down 6% to 66.2p | AMBER/GRAHAM (Graham) [no section below] I’m taking a moderately positive view on this as I believe this entire sector is undervalued. However, the enormous discount to NAV at play here is causing me concern that serious issues might be hiding under the bonnet. Of course I may be overthinking it. 99% of rent has been collected and they have made some large disposals including a £101m disposal, at values in line with book. More negatively, loan to value is a little high and is above their target range of 35% to 45%, and the underlying vacancy rate is not very good at 10%. However, bad news should be priced in and barring a catastrophe it ought to be too cheap here. More research needed. |
Big Technologies (LON:BIG) (£215m) | Contract award | Contract to provide electronic monitoring in Northern Ireland for 5 years, value £20m. | (Graham) |
Science (LON:SAG) (£192m) | Increased shareholding in Ricardo | SAG now owns 17.3% of RCDO. Average cost 233p. | AMBER/GREEN (Graham) [no section below] |
Peel Hunt (LON:PEEL) (£96m) | FY Trading Update | Rev +5%. Challenging H2. Smaller LBT than expectations. Encouraging pipeline. | GREEN (Graham) I remain positive on this on the basis that the balance sheet should help to support market cap at this valuation. As ever, it's hard to say when a proper recovery in IPOs/M&A will materialise. |
Corero Network Security (LON:CNS) (£86m) | Full Year Results | Rev +10% ($24.6m). EBITDA +42% ($2.5m). Solid start to 2025. |
Graham's Section
Peel Hunt (LON:PEEL)
Unch. at 79p (£97m) - Year End Trading Update - Graham - GREEN
We have a brief full-year update from this boutique investment bank.
Revenues are up 5% to £90m. This appears to be a miss against expectations.
However, the blow is softened with a smaller loss than expected:
This followed a challenging second half with a number of macro-economic events that weighed on market volumes and corporate activity. During the year we took action to reduce costs, and we expect to deliver a smaller loss before tax than market expectations.
I will say that it would have been helpful if the reduced loss could have been estimated in the RNS.
Strategically, they now act for 52 FTSE-350 clients. Checking last year’s update, I see that they reported acting for 150 clients in total, of which 43 were in the FTSE-350. So they are doing well when it comes to attracting more blue-chip customers.
Outlook:
Against a backdrop of continuing slow market conditions, we have an encouraging pipeline of investment banking transactions across both M&A and IPOs. A number of announced M&A transactions are expected to complete in the first quarter of our new financial year.
Graham’s view
I’m starting to think I made a mistake by leaving both Cavendish (LON:CAV) and Peel Hunt (LON:PEEL) on my watchlist this year. Probably I should have just picked one of them.
That said, I still think there’s a lot to be said for Peel Hunt at this valuation.
The most recent half-year report showed net assets of c. £95m, almost entirely tangible. I’d like to think that should provide some support for the current £97m market cap!
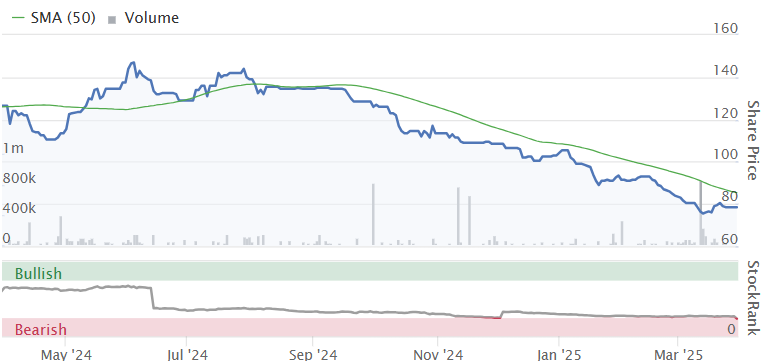
Ongoing losses do eat into net assets but at least that blow will be smaller than expected for FY March 2025.
There have been murmurings in the media about a possible increase in corporate activity this year. For example, this recent article in City AM noted 5 IPOs on AIM so far in 2025 (by mid-March), vs. 11 for the entirety of 2024.
So I do expect 2025 to be better for the likes of Peel Hunt, although at this stage it’s not shaping up to be a bumper year by any means. However, the IPO and M&A markets might not be as deathly quiet as they have been in recent times.
The merger of Cenkos and finnCap, creating Cavendish, made good sense to me and I’d be in favour of more deals of that nature, to reduce the number of firms competing for the same business. Because when the recovery finally materialises, I’d like to think that the financial performance of these investment banks will justify the long wait - and weakened competition might help!
A big event that the City has been waiting for is the $50 billion IPO of Shein. It was originally supposed to happen in H1. That timeline was postponed to H2 as the company got to grips with President Trump’s new trade rules.
Bulge bracket banks will be handling Shein’s business, rather than the likes of Peel Hunt, but hopefully this IPO will indeed happen and will help to promote renewed interest in the London market.
Pantheon Infrastructure (LON:PINT)
Unch. at 95.6p (£448m) - Full Year Results - Graham - GREEN
As mentioned recently, I’ve added a new holding to my portfolio - Pantheon International (LON:PIN). This is a private equity investment trust in the FTSE-250, managed by Pantheon Ventures.
PINT is a related entity, also managed within the Pantheon family. But it’s much newer, only launching in 2021.
The description on the website:
Pantheon Infrastructure Plc aims to provide exposure to a global, diversified portfolio of high-quality, infrastructure assets. We will seek to build a portfolio of co-investments in infrastructure assets with strong defensive characteristics, typically benefitting from contracted cash flows, inflation protection and conservative leverage profiles.
The Company is targeting an annual NAV total return of 8-10% and a dividend yield of 4% once fully invested.
Key points from today’s full-year results:
Dec 2024 NAV £553m, equivalent to 118.1p per share.
NAV total return 14.3% for the year (previous year: 10.4%).
Total dividends 4.2p (previous year: 4p).
Sectors in which they are invested: digital (wireless towers, data centres, fibre optic networks), power & utilities (gas, electricity, district heating), renewables & energy efficiency, transport & logistics (ports, rail, road, airports).
So it’s a very broad exposure to all types of infrastructure, despite not yet being a very large trust in terms of AUM. The investment manager says “we do not carry material exposure to any single sector specific risk”.
Chairman comment:
We are pleased to report a strong year for the Company. This performance, during a period of market challenges, reflects the resilience of our portfolio, which remains diversified and well positioned, providing shareholders with unrivalled exposure to assets with proven upside potential, in sectors benefiting from notable tailwinds, meaningful yield, and resilient downside protection.
Graham’s view
While I’m impressed by the returns at PINT, I do think there are some cautionary observations to be made.
Firstly, despite the claim that the company doesn’t take on sector specific risk, the portfolio is not all that well diversified yet. There were 13 investments at the year-end with the largest of them (excluding American electricity company Calpine, which has been sold) being worth close to 10% of their aggregate value.
Secondly, as with all private investments, there is necessarily some trust involved when it comes to the calculation of their value. Valuations for each asset are provided by their individual sponsors:
These valuations are typically calculated on a discounted cash flow (DCF) basis, which are subject to a variety of underlying assumptions that are specific to the sector and characteristics of each Portfolio Company. The degree to which these long-term assumptions change or are adjusted has the potential to impact the Company’s NAV.
The good news is that discounted cash flow valuations should be much more objective than valuations based on earnings multiples.
This chart was published today:
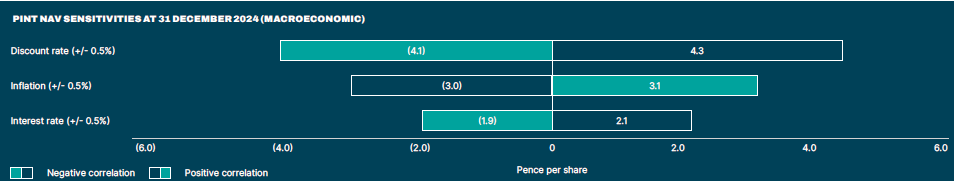
So for example - if you assume a 0.5% increase in interest rates, this takes nearly 2p off of NAV.
In conclusion, I'm leaning towards the view that PINT is potentially a very pleasant investment opportunity with hopefully not too much risk and reasonable prospects of earning an annual return of 8-10%. Even if it can’t quite hit that target every year, it should still beat inflation by a comfortable margin. I note that the cash flows at many of PINT’s investments are index-linked, i.e. having built-in inflation protection.
At a 20% discount to its official NAV I like what I’m seeing. And Pantheon - the broader private equity group, not just PINT - has really impressed me. So I’m giving this a GREEN.
Roland's Section
Serica Energy (LON:SQZ)
Up 4% to 141p (£559m) - Full Year Results - Roland - AMBER/GREEN (PINK)
(At the time of publication, Roland has a long position in SQZ.)
Serica Energy plc (AIM: SQZ), a British independent upstream oil and gas company with operations in the UK North Sea, today announces its audited financial results for the year ended 31 December 2024.
Today’s results from North Sea oil and gas producer Serica were always likely to be a little downbeat, given the impact of the Triton FPSO outages and last year’s lower gas prices.
CEO Chris Cox wastes no time in reminding investors how much better things could be if the Triton FPSO (which is not operated by Serica) was working properly:
The highly positive results of the drilling campaign at Triton are not yet being reflected in our production and cashflow due to ongoing issues at the Triton FPSO. Our frustration is exacerbated by the fact that the Triton area alone could be delivering up to 30,000 boepd net to Serica with the addition of the wells already drilled.
Mark and I have both covered Serica quite regularly in recent months, so I’ll try to focus on what’s new in today’s results.
2024 financial summary: last year’s financial performance was adversely affected by the combination of various unscheduled outages, mainly at Triton, and lower gas prices. For a quarter of the year, Triton produced nothing at all:
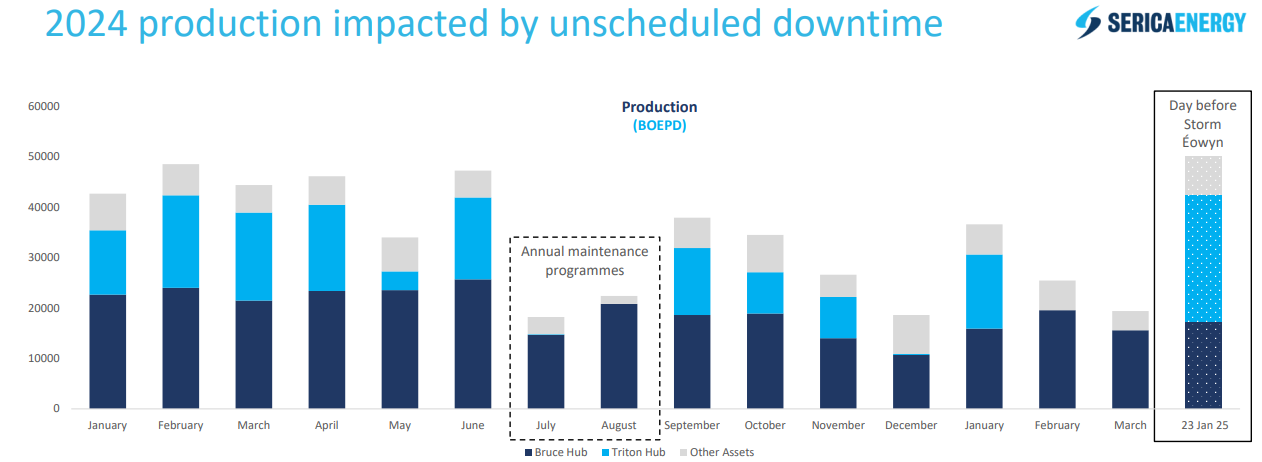
Here are some of the key numbers from today’s results:
Revenue down 20.7% to $727m
Operating costs up 20.8% to $330m
Capital expenditure up 168% to $260m
Pre-tax profit down 57.9% to $160m
Cash tax paid: $153m (2023: $348m)
Free cash flow: $(1m) (2023: $16m)
Adjusted net debt: $(83m) (2023: adj net cash of $99m)
These numbers do deserve some explanation. Free cash flow would obviously have been significantly stronger without last year’s Triton outages.
In addition, Serica ended up overpaying tax last year and expects to receive a $71m cash tax rebate in 2025 that will aid cash generation. Overall cash tax payments are expected to be “significantly reduced” in 2025.
In terms of production, here are the key numbers:
Production down 13.7% to 34,600 boepd
Average realised Brent oil price: $75/bbl (2023: $67/bbl)
Average realised gas price: 76p/therm (2023: 94p/therm)
One key attraction for many shareholders here, including me, is the generous dividend on offer. Today’s results offer mixed news on that front.
Dividend & shareholder returns: the total spent on dividends and buybacks last year was broadly unchanged, at $114m. But Serica has cut its final dividend today to provide more flexibility to allocate capital to M&A, development programmes or buybacks, as suitable opportunities arise.
Final dividend: 10p (2023: 14p)
Total dividend: 19p (2023: 24p)
Assuming a 19p payout for 2025, the shares offer a potential 13.5% yield at current levels. I’m only guessing, but I would not be surprised to see this further reduced by increased buybacks. With the shares trading below book value, this could offer value for shareholders.
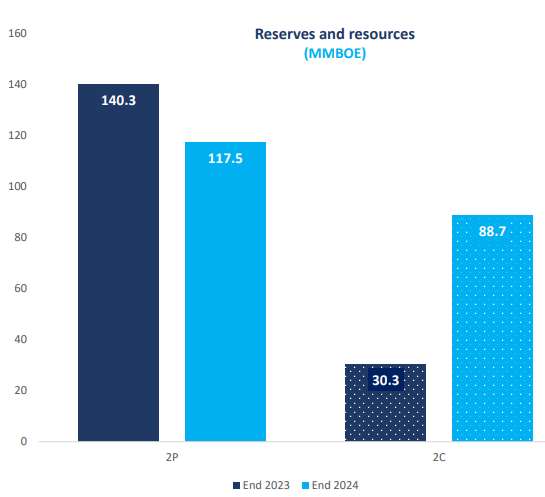
More broadly, my feeling is that the dividend cut has also been driven by a shift in the shape of Serica’s resource portfolio. Last year saw a fall in reserves (assets available for commercial production), but a large increase in contingent resources (discovered assets that require further development).
The company hasn’t been replacing its reserves fast enough to offset production. To put a number to this, last year’s production of 34.6kboepd is equivalent to around 12.6mmboe per year.
So with production at 34.6k, reserves remaining fell from 11.1 years to 9.3 years in 2024. Of course, without the Triton outages, the decline in reserves would have been greater:
I think the company is also keen to do more acquisitions in the region in order to strengthen its position as a consolidator and gain further tax and scale benefits.
Over time, spending more now could lengthen the producing lifespan of the group’s portfolio. Of course, future spending may not deliver the attractive returns of past spending – this is where we have to trust management not to squander cash on empire building (rather than simply returning it to shareholders and winding down the business).
Triton FPSO: repair work on Triton is now expected to complete “at the end of June”, meaning that it will have been offline for around five months. The only silver lining here is that the previously scheduled summer maintenance will also be carried out during the repair period, so no further outages will be scheduled for the remainder of the year.
As a result, Serica expects a significant H2 weighting to production (and potentially to profits):
With maintenance work at the Triton FPSO set to complete in June, and no summer shutdown to then follow, portfolio production in H2 is forecast to be materially ahead of the full-year 2025 guidance range
2025 guidance: Serica’s 2025 production outlook has been a tail of woe. Today we have another downgrade due to the extended Triton FPSO outage:
Following operational issues at Triton in Q1, production guidance for 2025 has been amended to 33,000-37,000 boepd
For context, here’s the history of 2025 guidance:
7 Jan 25: production net to Serica running at 46,400 boepd
21 Jan 25: FY25 production guidance for “around 40,000 boepd”, reflecting planned maintenance
18 Feb 25: January 2025: averaged 37,000 boepd, February 2025: “averaging 27kboepd to date”
In fairness, the Triton issues are out of Serica’s control. And the group’s portfolio does have the latent capacity to produce at a far higher level (my emphasis):
With all assets producing, our portfolio is capable of delivering over 50,000 boepd. Issues at Triton during the first quarter which, albeit different, compound on the challenges of Q4 2024, mean that we have been a long way from our production potential in the first quarter, and our production guidance for 2025 has today been set at a revised range of 33,000 to 37,000 boepd. Given the potential flow rates, a period of stable production will help us to strive for the top end of this range.
Outlook: unfortunately I don’t have access to any updated broker notes for Serica today, so I can’t see how estimates have changed as a result of today’s updated production guidance.
Forecasts from Auctus Advisors in February suggested Serica could generate $187m of free cash flow in 2025 – equivalent to around 37p per share. That’s equivalent to a P/FCF of 4.
Whether this is still achievable will depend on oil and gas prices and the extent of the production recovery in H2. But even a reduction would leave SQZ shares looking very cheap relative to cash flow.
Roland’s view
Today’s share price reaction suggests investors are slightly more positive about today’s results than I am.
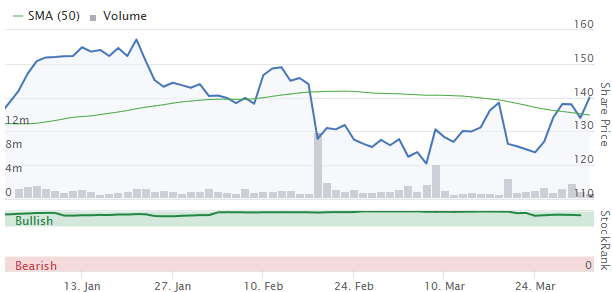
Serica shares certainly still look attractively valued to me at current levels, with a potential double-digit dividend yield and low single-digit P/E.
In addition, there’s still the prospect of an all-share merger or takeover with Enquest. I would expect this to deliver reasonable value to Serica shareholders, given that commodity group Mercuria is the company’s largest shareholder (24.7%).
On balance I’m going to maintain our AMBER/GREEN view due to the apparent value on offer here. But I would caveat this with heightened uncertainty about the outlook for 2025.
Travis Perkins (LON:TPK)
Down 7% to 511p (£1.1bn) - Full Year Results - Roland - AMBER/RED
Travis Perkins plc, the UK’s largest distributor of building materials, announces its full year results for the year to 31 December 2024
Last week, we had downbeat results from Kingfisher, which owns B&Q and Screwfix. Today we have further evidence from builders’ merchanting group Travis Perkins that conditions in this sector remain tough.
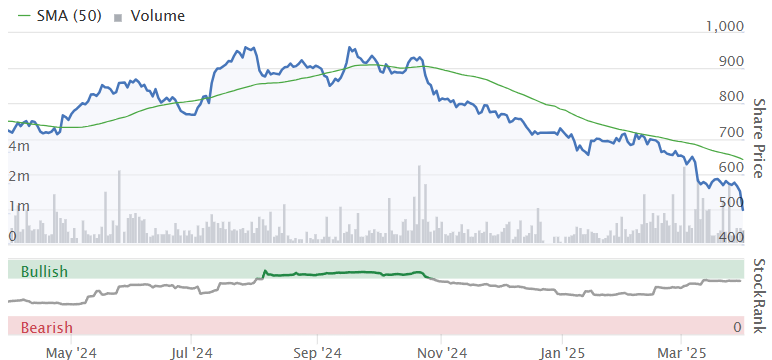
2024 results summary: all the numbers are moving in the wrong direction here, as Travis Perkins reports a nasty combination of falling volumes and price deflation. That’s hard for a low-margin, volume-driven business to combat:
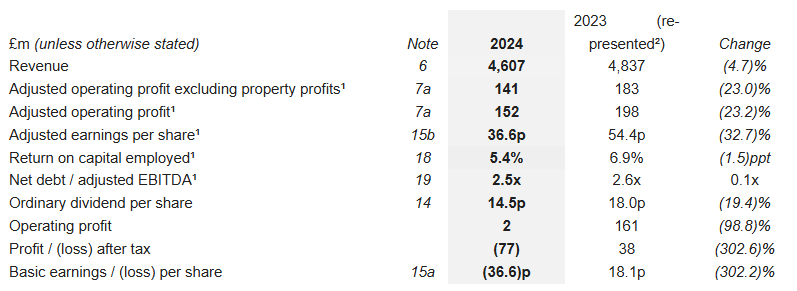
At an adjusted level, operating margins fell from 4.1% to 3.3% last year.
But to give credit to Travis Perkins, today’s results do also highlight a couple of (relatively) positive points.
Operating costs fell by 5.2% to £1,051m last year, presumably due to cost savings and the impact of lower volumes (e.g. lower delivery costs);
The group was also still able to generate free cash flow of £125m, giving a matching £123m reduction in net debt. This was achieved through careful management of working capital (£64m inventory reduction) and capital expenditure. But in a market like this, it’s a sensible (if one-off) win.
Net debt: at a statutory level, the business looks quite highly geared.
Net debt of 845m (including leases) was 2.5x EBITDA at the end of 2024, although net debt falls to £191m (0.6x EBITDA) if leases are excluded.
Statutory leverage still appears to be well below the covenant level of 4x EBITDA, but this is clearly an area management is focusing on.
Checking the balance sheet shows net lease liabilities of £109m, which suggests some sites may not be operating profitably at the moment, relative to their lease costs. This deficit could reverse in an upturn but is a possible source of cash leakage over the coming years as things stand.
CEO departure: unfortunately, former CEO Pete Redfern resigned on 10 March 2025 due to ill health. Redfern only took up the role in September 2024, so the business could also be suffering from a lack of consistent leadership.
The CEO role is being covered by chair Geoff Drabble while a search is underway for a new CEO. Drabble only joined TPK as chair in October, but was CEO of FTSE 100 equipment hire group Ashstead from 2006-2019. So he has an impressive pedigree in this sector.
Outlook: Kingfisher’s strongest performing business is Screwfix and the situation is similar here, with TPK’s Toolstation chain outperforming the core merchanting business:
The Group has experienced a mixed start to 2025. Trading conditions have continued to be challenging in our Merchanting businesses with pricing now stabilised but volumes in modest decline. By contrast, Toolstation has started the year more positively and continues to deliver good growth.
The company says it’s seeing some pockets of improvement, but management note that further cuts to interest rates and improved consumer confidence are needed to stimulate “a meaningful increase in demand”.
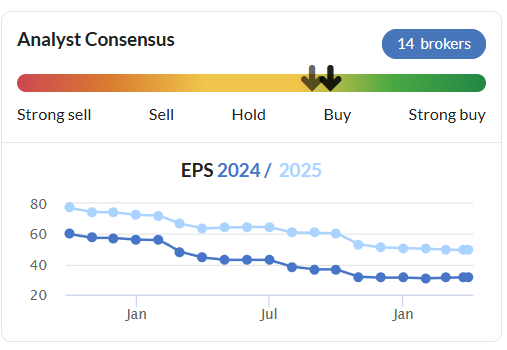
Guidance for the year ahead is for FY25 adjusted operating profit to be broadly in line with FY24, excluding any profits from property disposals.
This appears to be below previous City expectations, based on previous consensus forecasts on Stocko for a strong recovery in earnings this year:
Roland’s view
Profits were heavily adjusted last year, due to impairment charges and other factors. Adjusted operating profit of £151.8m translated into statutory operating profit of just £2.3m.
Likewise, the strong free cash flow showing seems to have been due to a large reduction in inventory that I suspect is a one-time gain.
All of this makes it hard for me to guess what the likely cash performance of the business will be this year.
However, using today’s adjusted earnings of 36.6p as a guide translates to a possible FY25E P/E of around 14, after today’s share price drop.
This doesn’t immediately strike me as good value, unless you have a strong conviction that market conditions will soon start to improve.
I’m not sure I’m that confident, so I’m going to take a mildly negative view today, to reflect today’s weak results and outlook.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Don't you just love it when you come across an old alert on a stock and think Jesus I was hoping there.. Just come across one for Rolls-Royce Holdings (LON:RR.) to alert when drops below 214p. Not sure what the plan was but it would appear I've missed that boat. ... Had to laugh.
Alphawave IP (LON:AWE) in play.
Talk this morning of ARM having taken a look, and Qualcomm have confirmed they are considering an offer.
Hasn't sent the shares anywhere near their 410p IPO price back in 2021 though.....
Any thoughts out there about the IPO coming later this week for Quantum Base Holdings ?
Good spot. It looks a tiddler, but the more the merrier. I would guess the upturn starts small and then hopefully accelerates in both size and volume.
Seems to be aiming for £5-6m total raise. Cavendish (LON:CAV) is the broker, a company called Strand Hanson is the nomad. So Cavendish should get a nice fee.
Cheers
Chris
Thanks for the commentary on Pantheon Infrastructure (LON:PINT) and for those who requested it - new to me but initially looks interesting. Will take a bit of a dive as have some cash freed up from selling Warehouse Reit (LON:WHR) (and still sitting on some cash anyway from exiting all US positions in Feb)
Pantheon Infrastructure (LON:PINT) agree that this looks quite interesting on the current discount. The only reason I don't hold is that 3i Infrastructure (LON:3IN) is on only a slightly lower discount, but given its much longer and very impressive track record I would argue this is actually the better value of the two. I would certainly add PINT if it drops back a few per cent, as it tends to do every so often for no apparent reason.
Agreed re 3i Infrastructure (LON:3IN) , it has a superb long term record.
Produced an impressive pre-close update yesterday including a significant reduction in gearing following realisations and distributions from its holdings.
I like 3i Infrastructure (LON:3IN) as they have strategy which focuses on small number of assets in arenas with strong growth, and the experience to add value through period of ownership.
The US trade commission have contacted the #Mello2025 team advising us that as we don't have any investment companies from the States at #Mello2025 there will be a 60% tariff added to tickets sold to US registered investors
Any Investors living in the States and coming to the show and having a UK address do use it to save money
That's a good one David, especially on April 1st.
Peel Hunt (LON:PEEL)
In commenting on Peel Hunt, I actually want to comment on Cavendish (LON:CAV), or rather try a little comparison. Peel didn't mention any IPO activity in the year they were reporting on, which is to 31 March (very prompt TU btw). They only said:
"Against a backdrop of continuing slow market conditions, we have an encouraging pipeline of investment banking transactions across both M&A and IPOs. A number of announced M&A transactions are expected to complete in the first quarter of our new financial year."
No mention of specific IPOs upcoming. Whereas, we know that Cavendish completed 2 small IPOs already (one in Dec, Amcomri (LON:AMCO), and one in Feb, RC Fornax (LON:RCFX)), and has the bigger MHA IPO lined up for sometime soon (no date announced), bigger than the previous two by about ten times.
This would point to Cavendish being more appealing to potential IPO candidates than Peel, therefore being the better bet between the two. Although the tangible assets point Graham makes is a strong point for Peel.
I think there will be an update from Cavendish this week, which could give a real boost to the shares. I already have a small holding, and as tempted as I am to have a punt before the TU, I'm not going to. Been there too many times where it's not worked out as planned.
Cheers
Chris
Thanks for this! I hold Cavendish (LON:CAV) and also noted the two IPOs already out the door... your most reminded me to quickly check how they've done. Looks... OK. No "pop" but trading at IPO price or thereabouts.
What really needs to happen is an IPO with a big pop on day one, or within the first 30 days... get investors excited about IPOs, which then feeds into greater appetite for institutions to support the float... and therefore more companies finding it attractive to IPO... that virtuous cycle is so dead at the moment.
Last year Cavendish (LON:CAV) issued a trading update on April 4th. Good chance if there is one that it will be positive including for reasons you covered. I couldn’t resist adding a few today. Fingers crossed.
Saga (LON:SAGA)
DEUTSCHE BANK RESEARCH RAISES SAGA TARGET TO 185 (154) PENCE - 'BUY'
Fcst PE 3.5 and PEG 0.2, mkt cap £175m
50d SMA crossed today. Above 200d SMA too
Bookings up 91% as retirees spend cash to avoid IHT
https://www.theguardian.com/mo...
Corporate debt refinanced in full. Ageas deal concluded on the insurance business. Results 9th April should be very good on the travel side imo.
I'm not sure if you're planning to cover it Graham, but I wrote a little about CLS Holdings (LON:CLI) for anyone interested.
Travis Perkins marked down 10% on full year results. Reuters reports shares now on a 16 year low.
Not a stock that I follow but interested as a read across to general construction activity.
EDIT: comment from Reuters below
Travis Perkins TPK.L slides as much as 13% to 478p, lowest since July 2009
Travis Perkins (LON:TPK)
It is a pretty horrible statement, so with the shares only off 10% you've got to assume a fair degree of pessimism was in the price beforehand.
They are looking for a new CEO (again - the last one became ill very quickly, having only started in Sept 2024) , and in the meantime they seem determined to sell us the largest kitchen sink you can buy in the UK.....
Just look at these snippets from the commentary:
- "it is clear to the management team that there are a number of areas where the business needs to refocus and change the way it operates"
- "to begin rebuilding trust and confidence, both internally and externally,"
- "uncertainty remains regarding the strength and timing of a recovery in UK construction activity,"
- "driven by price deflation and increased competitive intensity"
- "However, the Group has become distracted in a challenging market"
- "The Group’s key end markets have seen a progressive deterioration in demand over the past three years driven by high inflation, rising interest rates and weak consumer confidence"
- "Group’s approach to capital allocation and overhead management has diluted returns, exacerbated profit decline and resulted in leverage increasing beyond the Group’s target range."
- "During this period, the business has seen significant personnel change at all levels of the
business"
And surprise, surprise, there is also the admission that they've had a few problems rolling out their new Oracle ERP system. These always seem to go wrong....
Invading France did not go well - they've had to close most of the French toolstation operation after failing to find a buyer. For good measure they've closed 50+ Merchant branches in the UK as well.
Is anyone else getting the impression that they are talking the business down?
And yet, after all that, the operating cashflow is positive, and indeed ahead of last year.....
Anyway, if you are the incoming CEO and you can't make yourself look good after that litany of disaster then it is because someone else has swooped in and grabbed it first??
It is trading at 0.57x book value. There have to be people running the slide rule over this one. If you know the industry well there must be an opportunity here?
Someone is going to make money, but it probably won't be me as I don't know the industry well enough to catch the proverbial falling knife. There is a big bond maturity in Feb 2026 (they've raised some private debt is advance of the roll) and staff costs are about to jump - still plenty that can go even more wrong!
Travis Perkins (LON:TPK)
not saying its not bargain now - but the plenty of very obvious red flags are on top of a continuing reduction in excectations over the last 18 months - it doesnt paint a pretty picture.
If one wants to be fair looking at £HWDN - they also have downward trajectory ref expectation - i have howden as probably being the best run company of te listed bunch - so the fact they are struggling confirms that there is probably still excess capacity in the market - perhaps one or tow of the bigger players need to leave the scene.
I would quite happily pay premium for howden (15 * pe compared to 11) over travis pekin but not convinced either has reach the end ref downgrades in expectations.
I think Eurocell (LON:ECEL) and Epwin (LON:EPWN) - seem to be doing better - perhaps they concentrate better on their niches - with regard to delivering compared to pearlier romises - perhaps thats simply doing the more cautious sensible thing of not promising growth in earnings when there is little evidence that the growth in earnings is anything other than a future projection.
Serica Energy (LON:SQZ) results seemed poor but the market appears to have liked the update
According to Roland the 2024 tail has been wagging the dog:-)
SQZ is ridiculously cheap imo, taking a medium to longer term view, once the operational issues are sorted
The update gave clarity on a number of things, from bad news that was already known (now we have clarity on the impact and timelines)
Imo it is a very well run company that has faced some challenges and handled them well. The proposed reverse acquisition to harvest tax losses is another sign of a savvy management team.
Serica is very cheap on a free cash flow basis, underloved right now, but very well run. A good combination for the patient investor.
The new monthly Investment trust thoughts for April 2025 is on the Discussion board https://www.stockopedia.com/co...
If you have time Graham would be great if you could have a look at Pantheon Infrastructure (LON:PINT) looks good value in a sector seeing a lot of takeover activity.
Thanks
Andy
Andy there were comments on this on the Investment Trust march discussion board. And sure there will be in April. It was up 6.4% in March. The whole infrastructure and reit sector is "on fire" in the normally staid world of Investment trusts! Gore Street Energy Storage Fund (LON:GSF) was up 18.9%. Top 10 and bottom 10 trusts for March are here.
Thanks Charles
Cor my portfolio took a bit of a clattering yesterday what happened? Was it a kind of pre-April fools?? Looks like all the promising smaller caps got a trouncing I missed any relevant news...
You can definitely blame it on a fool.
Yep I would be surprised to learn at some point that he is benefitting from shorting the market. His “strategy” on the auto sector will damage it massively in my view (for years) given the tariffs on key raw materials and all imports (cars and parts). Elon must be pulling his hair out.
I would need a lot of convincing (He) hasn’t people who have set up shorts to benefit from this mess. He’s far too clever too not benefit.
Swap clever for crooked
Its an odd thing that any basic economics textbook will show in a couple of pages how tariffs damage the country levying them as well as other countries. But he blunders on unchallenged.
The US auto makers will simply raise their prices by a lttle under 25%, to maintain their market share. Increasing production is risky and difficult and will reduce prices, so why bother?
It is possible he knows this and has been paid off by the US auto makers.
I’d go back to sleep if I were you.
We are hosting a webinar with fantastic British engineering company Rotork later today. Kiet Huynh, CEO and Andrew Carter, Investor Relations Director, will conduct a live presentation to retail investors at 12pm on Tuesday 1 April. Kiet and Andrew, will present the FY24 results and discuss prospects for the year ahead. If you’d like to attend register here
https://us02web.zoom.us/webinar/register/8617393689133/WN_DLCcLC62RlaKQZ58NB1D8w
Undoubtedly, everyday is April 1st listening to the US Fox News.
No reason to watch Fox News
Same with cnn when biden was president. Their and others covering up of his issues is a big reason we are where we are imo.