Daily Stock Market Report (Tue 12 Nov 2024) - KNOS, GDP, TIME, ADF, AZN, MRK, CBOX, ZOO

Good morning! Mark Simpson is joining us today to help out with the report.
Wrapping it up there for today (1pm). Huge thanks to Mark for his first contribution to the daily report!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Companies Reporting
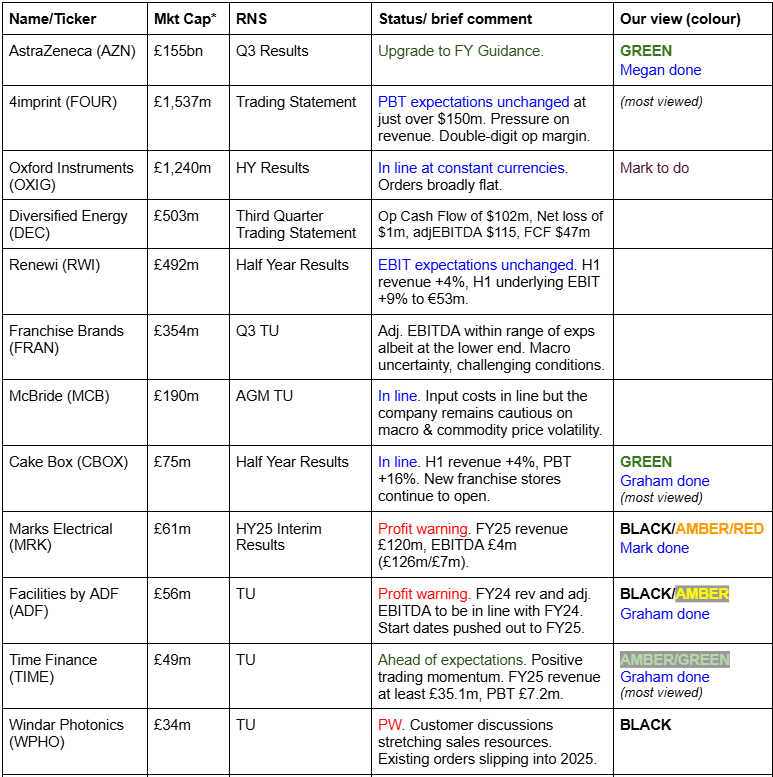
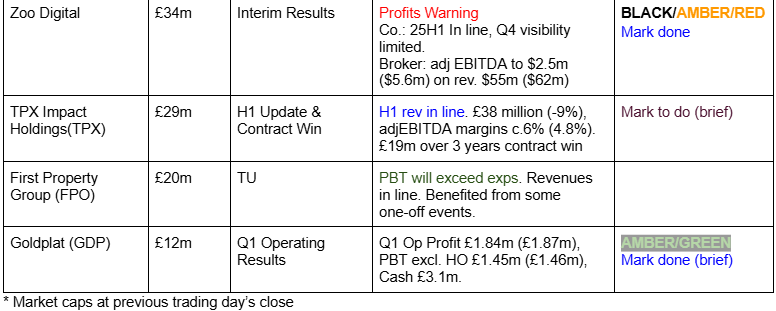
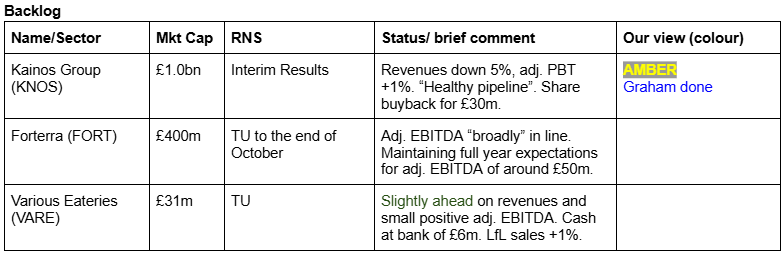
Summaries
Kainos (LON:KNOS) - up 6% to 844p (£1.06bn) - Interim Results - Graham - AMBER
After a recent profit warning, this Belfast-based provider of software services and consultancy published its full interim results yesterday. While the outlook is uninspiring, and the company is hugely dependent on factors beyond its control (public sector spending and demand for Workday products), its financial performance is objectively quite good and it is cash-rich. So I’m happy with a neutral stance here.
Facilities by ADF (LON:ADF) - down 36% to 33.5p (£36m) - Trading Update - Graham - AMBER
Investors must wait another year for recovery as the anticipated H2 revenues have not come through and the risk of a further profit warning has materialised in full. 2024 is now expected around breakeven and 2025 forecasts also get cut (new adj. profit after tax forecast £6.8m, previously £11m).
Cake Box Holdings (LON:CBOX) - up 1% to 189.5p (£74m) - Half Year Results - Graham - GREEN
A pleasant update from this franchisor of fresh cream cake shops. Like-for-like growth is not running too hot (4% in October) but the company continues to expand with 7 new franchise stores opened in H1. It’s difficult for me to not be positive on a successful franchisor, and the valuation here seems reasonable.
Marks Electrical (LON:MRK) - Down 15% to 50p - FY25 Interim Results - Mark - BLACK
Another major profit warning here with Canaccord cutting 2025 EPS from 3.5p to 1.5p and 2026 from 3.8p to 1.9p (now down 75% in the last year.) The blame is put on restrained deliveries during a new ERP implementation plus a move away from premium products in the search for volume. This is now viewed as a mistake but leaves them stuck between a rock and a hard place. Revenue growth was about the only thing going for a company on a forward P/E of 26. Growth now looks unlikely in the medium term, leaving them on an aggressive rating despite the share price almost halving this year.
Zoo Digital (LON:ZOO) - Up 4% to 36p - Interim Results - Mark - AMBER/RED
The company reports that these results are in line but raise some doubt as to whether their Q4 bookings will deliver. Progressive Research are less circumspect and reduce adjusted EBITDA to $2.5m from $5.6m on revenue reduced to $55.0m from $61.8m, implying that revenue in H2 will be slightly down, and Adjusted EBITDA in H2 will be just $0.9m versus $1.6m in H1. The company seems confident that their cash and debt facilities will see them through to cash flow break even. On current forecasts that looks to be the case, but it doesn’t leave a lot of wiggle room for any further slips. With so much of the value based on an expected recovery in trading far in the future, and much of that already being priced in, it is hard to feel positive about taking a position now in the hope that an even better future arrives.
Short Sections
Goldplat (LON:GDP)
Down 5% to 6.75p (£12m) - Q1 Operating Results - Mark (I hold) - GREEN/AMBER
Steady as she goes from this company that recovers gold from mine waste in South Africa and Ghana:
The two recovery operations achieved a combined operating profit for the quarter of £1,838,000 (excluding listing and head office costs, finance cost and foreign exchange losses) (FY Q1 2024 - £1,865,000). The finance cost and foreign exchange losses incurred in Q1 mainly related to trading activities and resulted in a combined profit before tax excluding listing and head office costs for Q1 of £1,451,000 (FY Q1 2024 - £1,455,000).
Head office and listing costs typically run at about £200k per quarter, so a PBT of around £1.2m for the quarter compares favourably with the £12m market cap. In addition, the company holds net cash on the balance sheet:
Our cash balances in the group remained strong at £3,100,000 at the end of Q1. The cash balances will mainly be used to manage working capital requirements in Ghana and repayment of intercompany loan balances and other capital requirements.
The Value Rank here is 97, with a lot of green on the StockReport:
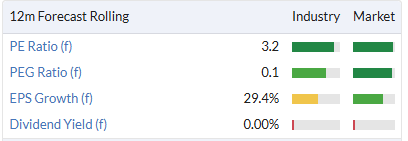
However, shareholders have yet to see any return from that as the dividend payout has been zero over the last few years, and only a very minor share buyback has been conducted. Instead, changes in business strategy are requiring greater short-term working capital. Ghanaian authorities want gold producers in the country to produce doré bars instead of concentrate, and this requires additional equipment to be installed and a greater pipeline of material on-site in Ghana. In the medium term, this should give a working capital benefit, as bars can be sold quickly. However, the share price reaction today tells observers everything they need to know - shareholders are fed up with waiting.
Mark’s opinion - it is hard to ignore the valuation metrics here which make it one of the cheapest shares on the UK market (hence I hold). However, significant risks are present too - the geographic locations the company operates in are not straightforward. While the company has operated for many years without major problems, the reality is that the challenges present themselves in other ways, namely delays. The patient shareholder will probably do well…eventually!
Time Finance (LON:TIME)
Up 10% to 57.8p (£53m) - Trading Update - Graham - AMBER/GREEN
It’s the briefest of updates from this SME lender; let’s quote it almost in its entirety:
Time Finance plc, the AIM listed independent specialist finance provider, announces that it has continued to enjoy positive trading momentum throughout the first five months of the 2024/25 financial year…
This positive momentum year-to-date includes record revenues, a lending book hitting new heights, and arrears remaining well under control. As a result, the Board now has increased confidence that Group performance for FY25 will be ahead of current market expectations. Revenue and Profit Before Tax for FY25 are now expected to not be less than £35.1m and £7.2m respectively.
Prior expectations were for revenue of £34.5m and PBT of £6.9m.
Graham’s view
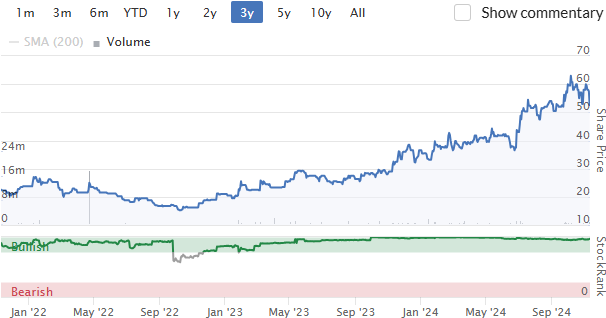
Roland covered TIME’s full-year results in excellent detail here, in September, and was AMBER/GREEN on the stock (share price at the time: 57.8p).
After a positive trading update today, further boosting the investment case, I’m inclined to leave the existing positive stance unchanged.
The company’s tangible net assets as of May 2024 (the year-end date) were £39m, so TIME is trading at a substantial (c. 35%) premium to this.
Looking ahead, broker Cavendish argues that the stock is trading at only 1.1x FY 2026 tangible net assets, i.e. at a 10% premium. But it seems generous to value the company on its 2026 numbers.
Well done to those who’ve held this during its tremendous bull run. I’ll leave our mildly positive stance alone for the time being, as the business goes from strength to strength.
Perhaps if it declares a dividend, attracting even more investors to the story, that will be a good moment to switch to neutral? Based on the premium to TNAV, I do think a switch to neutral could be justified before too long.
AstraZeneca (LON:AZN)
Up 1% to 10,040p (£155bn) - Third quarter results - Megan - GREEN
When AstraZeneca’s management team rebuffed Pfizer’s £69bn takeover in 2014 they said that the offer materially undervalued the company. The British company is now worth more than twice what Pfizer offered and, with a market capitalisation of £155bn it is now bigger than Pfizer itself (£149bn).
Astra offers a lesson in the importance of innovation in the pharmaceutical industry. Revenue in the first nine months of 2024 has risen 19% to £39.2bn, driven by continued strength in oncology. When Pfizer came calling, cancer treatments weren’t worth splitting out as their own operating division, now they’re equivalent to 43% of product sales.
Importantly the investment in innovation continues at pace. In 2024, the company has invested 23% of its revenue into research and development. It’s also had some significant read-outs from clinical trials. Tagrisso and Imfinzi (both chemotherapies) have been approved for the treatment of more cancers in the US and EU. Meanwhile Lynparza, the targeted cancer therapy which is significantly less invasive than chemotherapy, has been approved for endometrial cancer in the EU. Ongoing label expansions to these cancer medicines should help keep revenue ticking up and protect sales from falling off a cliff when patents expire.
Beyond oncology, Astra has today reported positive clinical results from its neurofibromatosis trial - a rare disease that causes tumours to grow along the nerves, for which there is currently no approved treatment. Rare disease is the third largest revenue-generating division of the company, but growth here has lagged other parts of the business in 2024.
Megan’s view: Astra lost its crown as the largest company in the UK last week after a new report fueled fears of an escalating insurance fraud investigation in China. On Tuesday the share price fell 8.4% or £15bn, equivalent to roughly three years worth of the group’s total sales in China.
The report suggested that the financial implications of these allegations could be significant, a statement that has spooked the markets. But for me, this seems like something of an over-reaction. China is not a meaningful part of the investment case; it’s a market that is hard for foreign pharma companies to operate in and it’s not growing as quickly as Astra’s other markets.
So does this sell-off provide an opportunity for those looking to benefit from share price weakness? Quite possibly. The company has increased its earnings estimates for the full year in these numbers and shares are now trading on a PEG ratio of less than 1. Worth a closer look in my opinion. GREEN
Graham's Section
Kainos (LON:KNOS)
Up 6% to 844p (£1.06bn) - Interim Results - Graham - AMBER
Kainos Group plc (KNOS), a UK-headquartered IT provider with expertise across three divisions - Digital Services, Workday Services and Workday Products - is pleased to announce its results for the six months ended 30 September 2024.
We had a profit warning from Kainos on 31st October (covered here) and so it would have been surprising if there was any bad news left to be revealed in yesterday’s interim results.
The main reasons for the October profit warning, as summarised in a helpful broker note from Canaccord, were: a) a pre-Budget slowdown in public sector spending; b) smaller contracts relating to Workday.
Yesterday's H1 results showed a modest decline in revenues (down 5% to £183m), with a 1% increase in adj. PBT to £38.2m.
Bookings were down 11%.
The company proudly stated that “our disciplined execution and strong growth in higher-margin products have supported profitability”.
They finished the period with cash of £152m of cash and have earmarked £30m of this for a share buyback programme. It’s nice to have the flexibility to do that but bear in mind that this will only reduce the share count by c. 3% at the current market cap, so it’s not going to be a meaningful driver of EPS.
Current trading/outlook
First a reminder of what happened:
On 31 October, we moderately reduced revenue expectations for the full year reflecting the poor macro-economic conditions and delayed UK Government decision-making. We expect the majority of the revenue reduction (along with the impact of the additional investment to support our products partnership with Workday) to flow through to lower adjusted profit before tax.
Looking ahead, the watchword is “flat” for the time being.
We continue to have a healthy pipeline, ongoing cost discipline, a strong balance sheet and a significant contracted backlog…
In Digital Services, we expect a slight revenue decrease in the remainder of the year and a flat outlook into FY26, as slow UK Government decision making persists, before the new Government determines and executes its investment priorities in both central Government and the NHS.
We expect flat Workday Services revenue in the second half and into FY26 in a soft market…
Graham’s view
My biases say that this is an IT consultancy with limited intellectual property of its own, probably labour-intensive, and reliant on the fortunes of a particular software company (Workday).
But if I put those biases to one side, I have to admit that the financial statements themselves are appealing from an investment point of view.
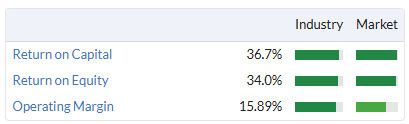
The income statement published yesterday (for the six months to Sep 2024) has an operating margin of 17% - nothing wrong with that at all.
Stockopedia finds impressive ROCE/ROE in addition to an attractive operating margin:
On the balance sheet, there is positive tangible equity (£118m) and a large cash pile (£137m), with zero borrowings. I note a very large (£41m) basket of deferred income, which is a good thing - customers paying upfront for services they will receive later, or over a period of time.
The cash flow statement is attractive too, at least over this brief 6-month window, with hardly any capex to detract from nearly £37m of operating cash flow (before movements in working capital). Capex over the entire year to March 2024 was less than £6m.
I’m therefore leaning towards the view that this stock might be worth a second look. But bear in mind that with a “flat” outlook, we aren't expecting much growth for the foreseeable future.
And the stock isn’t all that cheap on traditional metrics. Back-of-the-envelope calculations suggest that at the latest share price (844p) it’s trading at a PER of about 20x. Adjust for the cash balance and you can maybe get this down to 17x.
Personally, I wouldn’t want to pay so much for a company in this sector. However, given the objectively strong financial performance, I shouldn’t let my biases force me to take a negative view on the stock. Let’s go AMBER.
Facilities by ADF (LON:ADF)
Down 36% to 33.5p (£36m) - Trading Update - Graham - AMBER
Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television industry ("HETV"), today provides an update on trading in respect of the full year ended 31 December 2024...
I’m afraid this is one that I got wrong, as I was AMBER/GREEN on it after studying the interim results in September.
Today we get a profit warning that results in massive cuts to profit forecasts for the current year.
At the time of the interim results, there was hope that film and TV production was normalising and that ADF was about to return to very high levels of activity.
Unfortunately, it hasn’t panned out:
…following the conclusion of macro-economic events on both sides of the Atlantic, it is now clear that a significant number of the productions that ADF had in its sales pipeline for H2-FY24 will have start dates pushed out into FY25, and some will not proceed at all.
Compounding the misery, ADF’s decision to focus on “shorter duration” productions during the Hollywood Strikes means that its follow-on revenue (“add-ons”) is lower than usual.
Estimates: Cavendish have slashed their revenue forecast for the current year by 28%, to bring it down to ADF’s guidance of £35m.
As for profits, the less said the better! The adj. profit after tax forecast falls from £5.2m to breakeven, and I assume that the unadjusted result will be in the red.
Looking ahead to 2025, that year doesn’t escape cuts either. Cavendish are rebasing forecasts due to the risk that a return to pre-Strikes levels of activity might continue to take longer than anticipated. This mere possibility results in the adj. profit after tax forecast for 2025 reducing from £11m to £6.8m.
Outlook: let’s hear the company’s own views on 2025.
The sales pipeline for FY25 has been steadily building across the Summer and supports what many in the industry believe will be a full return to previous activity levels of film & HETV production. Adding the deferred work from the back end of FY24, for which the Group has the fleet capacity to deliver alongside the pre-existing FY25 pipeline, will ensure ADF begins FY25 with a significant pipeline. ADF is in discussion with several new customers for large, multi-series productions with Netflix, Apple and Marvel.
Graham’s view
I don’t think I can argue that the market is overreacting today. The percentage share price fall (36%) is similar to the percentage reduction in the profit forecast for 2025 (38%).
This creates an opportunity for investors who are willing to bet on recovery by 2026. At a market cap of £36m, the stock is now trading at a low single-digit multiple (only c. 3.3x) of the after-tax earnings it was previously forecast to earn in 2025. Is there any chance it could achieve this on a one-year delay?
However, the timing of the recent £21m acquisition (discussed here) now looks unfortunate in the short-term, as it was accompanied by both share dilution and higher net debt, with debt now forecast to end 2024 at £14.5m.
If the company hadn’t taken on that acquisition and if it had a net cash position, maybe I could stick my neck out and stay AMBER/GREEN despite today’s profit warning.
However, I need to be mindful of the risk:reward when there is a substantial acquisition in the works and net debt accompanying a profit warning. I very much expect that ADF will be profitable again soon but for now I must take a neutral stance on the stock.
Cake Box Holdings (LON:CBOX)
Up 1% to 189.5p (£74m) - Half Year Results - Graham - GREEN
This is “the UK’s largest retailer of fresh cream celebration cakes”, i.e. vegetarian cakes. The store count is now at 232, as of the end of H1 (September 2024) and is growing at a rate of about 10% p.a.
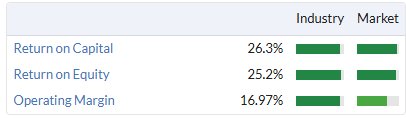
CBOX operates a successful franchise model, meaning high returns for shareholders:
Today’s trading update from the company is a pleasant read: they are on track to deliver full year results in line with expectations, and all metrics seem to be going in the right direction.
Key bullet points for H1:
Like-for-like sales growth of 2% is “against strong comparatives” in the prior year.
Total revenue up 4.3% to £18.7m, driven by freshly opened stores and higher sales volumes at stores that opened in the previous year.
Pre-tax profit up 16% to £2.8m
Net cash hasn’t changed much at £5.6m.
Interim dividend gets a boost to 3.4p.
Current trading/outlook: like-for-like sales were +4% in October. Nice growth in online sales of 23%.
CEO comment:
"During the first half of the year, we delivered strong growth across key financial metrics and expanded our customer base, resulting in double digit increases in profits and dividends. We have seen continued growth in online sales as well as brand awareness. Importantly, we increased our customer database by 40% and launched our customer loyalty programme in the period.
Graham’s view
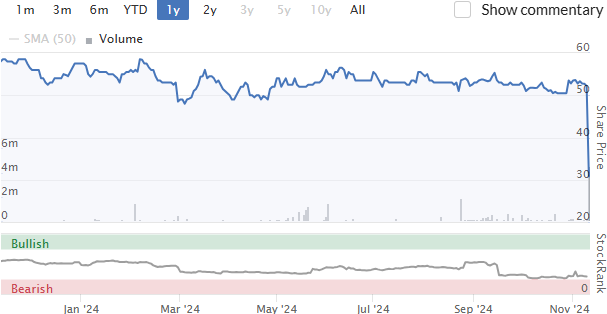
This company had some accounting drama in 2022, and the share price has still not recovered:
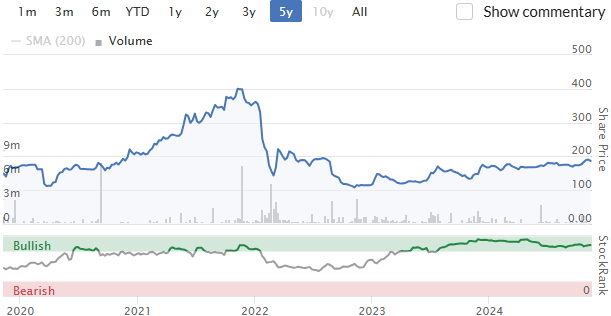
When I see a damaged chart like this, the contrarian in me wants to be GREEN. But fundamentally, the point of this stock is the franchising model, which is a dream when it works - and it seems to be working at CBOX.
The main danger for investors is probably related to those accounting problems - can we trust CBOX now, or could it be another CAKE (Patisserie Valerie)?
As with CAKE, CBOX investors can take comfort from the fact that their Chairman has a significant exposure to any potential problems (or more optimistically, he is aligned with his fellow investors). Co-founder Sukh Chamdal maintains a 25% stake in the company. With a new CFO since last year, and another few years of trading and expansion under their belt, maybe it’s plain sailing for the company from here on out?
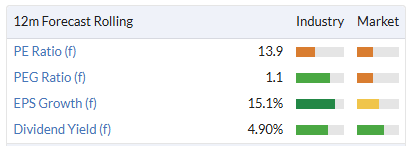
It warrants further investigation but my overall impressions are positive and it doesn’t seem excessively priced:
Marks Electrical (LON:MRK)
Down 15% to 50p - FY25 Interim Results - BLACK
This distributor of consumer goods is continues to grow revenue:
· Robust first half trading period with revenue growth of 9.3% to £58.8m (H1-24: £53.9m).
· Particularly strong volume growth with Major Domestic appliances achieving 13% volume growth during the Period and Consumer Electronics over 90% volume growth against H1-24.
However, like many companies at the moment, increasing costs means this is not reaching the bottom line:
· Adjusted EBITDA(1) of £2.0m (H1-24: £2.3m) at 3.4% margin (H1-24: 4.3%)...
· Adjusted EPS of 0.72p (H1-24: 1.11p)(2), Statutory EPS of (0.79)p (H1-24: 0.83p).
I note that there is a large gap between the adjusted and statutory figures, which they explain as:
This decrease is primarily driven by exceptional costs incurred in relation to our ERP implementation project of £1.9m incurred in the Period.
These may be one-off, but they are not small and an ERP system is part of the core of what the company does - distributing consumer goods. Not only are there considerable exceptional costs, but the outlook reveals that this is a major profits warning:
As a result, we now expect to achieve revenue in FY25 of circa £120.0m with EBITDA in excess of £4.0m.
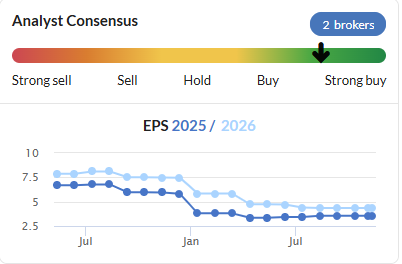
Previous forecasts were £126m revenue and £7m EBITDA so this is a big reduction. The broker, Canaccord, cuts 2025 EPS from 3.5p to 1.5p and 2026 from 3.8p to 1.9p, suggesting that there are no easy fixes to the company's current woes. Indeed, the broker trend here is not exactly encouraging, with the 2026 forecast dropping 75% in the last year:
The reasons they give for today's multi-year profits warning are:
· Outbound deliveries in September and to a lesser extent, October were reduced to enable the successful implementation and switchover to our new ERP system. Whilst this held back H2-25 growth, we still anticipate a recovery in revenue growth in the second half.
· During the Period we saw a significant reduction in average order values (-9%) as demonstrated by our volume growth outstripping the pace of our revenue growth. Whilst this is positive from a customer acquisition and market share perspective, it means that distribution costs represent a higher proportion of revenue, which ultimately has a detrimental impact on profit margin and unit economics, given the relatively fixed cost of delivery.
It seems the three scariest letters for shareholders to hear are E, R, and P. The implementation of a new ERP system often costs far more than planned and causes significant business disruption. While things have gone relatively smoothly here, it has still meant they had to reduce deliveries, which has led to significant (statutory) losses.
The reduction in average order values is more worrying. Historically, Marks has been a supplier of premium-branded goods, doing its own nationwide logistics, all from its warehouse in Leicester. While margins are very similar, premium products mean that the value of the goods on a van is higher, the gross profit per van is higher, and logistics costs are a lower proportion of gross profit. Recently, they appear to have been going for volume growth by selling lower-value products, which has negated their previous advantage. Their solution now is:
As the consumer has continued to trade-down, we have evolved our business to meet those needs, perhaps leaning too much into non-premium products, which has led to erosion in our premium average order value. The knock-on implications of this on our distribution costs are something that we need to actively address moving forward by pivoting back to our historically premium focussed operating model.
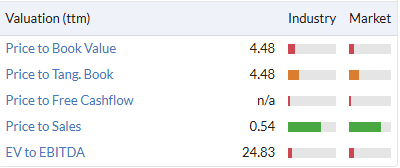
This leaves them between a rock and a hard place. While the problems caused by changing their ERP system and leaving the Euronics buying group may be behind them, in order to try to recover profitability, they are going to have to forgo sales growth. It seems there is a limit to the number of premium brand customers, at least in the current market. And high sales growth is one of the only reasons to own a stock with historical valuation metrics like this:
The good news is that they have time to turn things around. We are often sceptical about companies that describe their balance sheet as “strong” or “robust”:
Robust, debt-free balance sheet with closing net cash position of £6.7m(3) (H1-24: £10.9m)
However, here, the current ratio is reasonable at 1.36, suggesting no immediate worries:
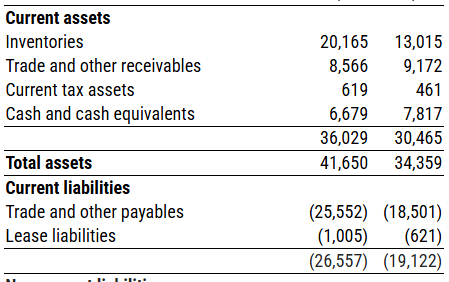
This is down from 1.59 last year, though, and there is no asset support to protect the downside. So, this is something investors may want to pay a closer eye on in the future.
Mark’s View
When Paul reviewed this at the start of the year, in response to the profits warning at that time, he rated it AMBER/RED. The shares have almost halved since then. Even so, they appear to be significantly overvalued on medium-term earnings forecasts. At 50p the company is still trading on 26x 2026E EPS, and the current 15% move down in response to this further warning looks too light. With no easy fix for the core issue of demand for premium products to make the distribution costs low, that AMBER/RED stance has to remain.
Zoo Digital (LON:ZOO)
Up 4% to 36p - Interim Results - Mark - AMBER/RED
Zoo Digital has been a highly volatile stock in the last year:
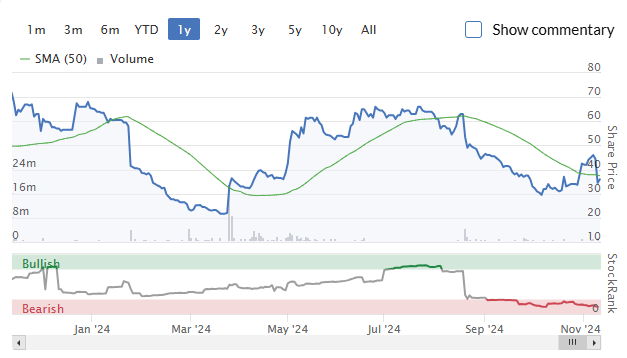
Historically, this supplier of local services to the TV and Film industry has been an investor favourite. Rapid revenue growth from 2020-2023 meant that this became highly rated.
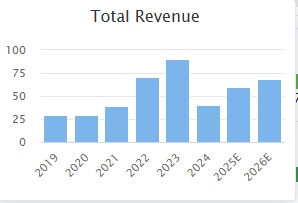
However, a strike by actors and writers in 2023, highlighted the level of customer concentration here. When that customer cut orders, revenue more than halved. However, Zoo was slow to cut its costs in response, and significant losses ensued:
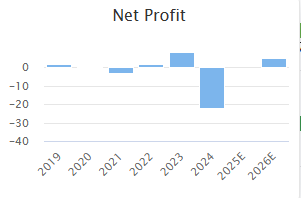
The company was only saved from insolvency because it had raised £10m from shareholders at 160p for an acquisition that didn’t complete. Today’s results reflect the ending of the strike and new orders being received from their major customer:
· Revenues increased by 29% to $27.6 million (H1 FY24: $21.4 million) as content output continues to recover following the Hollywood writers' and actors' strikes of 2023
· Gross profit increased by 386% to $10.1 million (H1 FY24: $2.1 million)
However, this isn’t enough to bring them into profitability:
· Operating loss of $2.5 million (H1 FY24: loss of $10.9 million)
So there are only two major things to consider in the short term - can they grow revenue fast enough to break even? And do they have enough cash to get there?
This is what they say about revenue:
· Entertainment industry recovery expected to continue steadily in H2 FY25, gradually improving through calendar 2025
· While H1 FY25 trading was in line with full year expectations, visibility of Q4 orders remains limited
That seems to be quite a caveated statement and raises doubt as to whether forecasts will be achieved. In their updated note, paid-for broker, Progressive, seem to think so too, saying:
Forecast revisions due to limited visibility. The pace of recovery remains key, and we understand that it is taking time for ordering patterns to resume as the major players grapple with revised business models. While order flow is improving, visibility remains limited and we have revised our FY25E estimates, with adjusted EBITDA moving to $2.5m ($5.6m) on revenue of $55.0m ($61.8m). Net cash is expected to be $2.6m.
The implication of this is that revenue in H2 will be slightly down, and Adjusted EBITDA in H2 will be just $0.9m versus $1.6m in H1. So this is a profits warning, even though the company don’t explicitly say this. It seems Paul was prescient when he reviewed Zoo in August and said: "It wouldn’t surprise me if ZOO warns again on profit in Q3 or Q4. Cash could get tight by then if a more convincing recovery hasn’t started."
Progressive also introduces a 2026 forecast with $60m revenue and $7m EBITDA and 1c EPS. This shows how sensitive the business is to changes in revenue but must also include assumptions over cost-cutting. Here they have made progress:
o Salary costs reduced by $4.5 million to $13.5 million (H1 FY24 $18.0 million)
However, things still appear to be quite tight on the cash front. They say:
· Cash balance of $4.3 million at period end (H1 FY24: $16.8 million)
However, this is gross cash, not net. A look at the balance sheet shows $5.6m of debt. The bulk of this will be lease liabilities, but unfortunately, they don’t break it out during the half-year. The annual report has $5.5m of lease liabilities out of $5.7m gross debt. They made $750k of lease capital repayments during the period, suggesting there may be up to $1m of bank debt. Progressive is forecasting $2.6m net cash at year-end, plus they have:
Secured additional debt facility of £2 million giving $5.6 million funding in total…
Board believes its cash and debt facilities provide the Company with sufficient working capital to meet its operating requirements for the foreseeable future
So it seems the company are correct about this on current forecasts, but perhaps it doesn’t leave much headroom if there is any further delay in revenue. Working capital is quite finely balanced, with a current ratio of less than 1, excluding the lease liabilities. Operating cash flow has been positive over the last six months, which helps the case here:
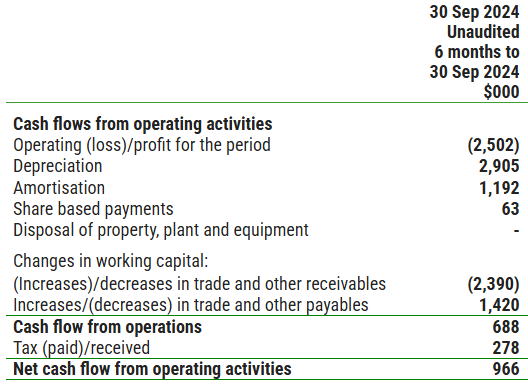
Capex and capitalised development are understandably being constrained and much lower than depreciation and amortisation, which helps with free cash flow but doesn’t get them into positive territory.
The bull case is that they have managed to grow revenue rapidly in the past, and if they can do so again, the rating will come down quickly from the current 59x P/E multiple that Progressive have for FY26. The problem is that this is outside the forecast window. The shares are actually up today, but this may well have more to do with the big fall in share price yesterday. I’m not sure we can conclude that there was foul play at work in the fall. The reality is that this hasn’t been a stock to hold into results for quite some time now.
Mark’s View
I have held Zoo in the past as a recovery stock. Unfortunately, that recovery took far longer than I expected, and I bailed when I realised they were not cutting costs anywhere near fast enough to reflect their current financial situation. With today’s update, the recovery takes a further step back. Although they may have finally grasped the nettle on costs, you have to hope it isn’t too late. Paul rated this as AMBER, but with a further warning and Progressive forecasting more cash outflows in H2, I think this has to go to AMBER/RED.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
Good big picture analysis by Megan of AstraZeneca (LON:AZN) . I Hold. The only large company i do.
It seems like a stellar set of Q3 results and yet the market was completely unmoved.
Not sure why. The China situation is clearly disturbing. It appears that the authorities there are refusing to engage with AZN . But how bad could it get ? If this was the Sopranos you would say they are being ‘lent on’ !
From today’s presentation it seems that the US is a big part of the future. China 13% of revenues not to be sniffed at of course.
AZN is a huge big beast now. They are as big as governments. If they are treated badly, they can just put their resources elsewhere. China might not care, but the UK certainly would if AZN pulled out of further investment in the uk because previous promises have been reneged on.
I would be interested in an article of what stocks might benefit and which might not so much in light of Trump victory.
Frankly , I have sold nearly all of my European portfolio as I just see better opportunities in the USA. The European stocks I see benefiting from Trump are defensive as there is no doubt that Europeans can no longer rely on the USA to bail them out , and there is a good chance that Trump will pull the USA out of NATO unless the Europeans significantly increase their share of defense spending . So a stock that should definitely benefit is BAE Systems (LON:BA.)
I will wait for the pullback before buying a couple :)
Long list of updates today team. Well done.
I will post this in the morning but I’ve just read that PayPoint (LON:PAY) will be added to the FTSE 250 index and deleted from the FTSE SmallCap index as of 15th Nov.
Is this what’s been driving the price higher? Will trackers need to balance portfolios? We’re in the volume gap at the moment, so not much supply. I hold.
The way we have sold off today and the pace at which capital is fleeing the UK you would think this Government was inadvertently steering us towards a recession.....the rise in unemployment coupled with higher grocery inflation would not have helped sentiment, and it will get worse after Xmas, especially once hospitality and retail lay people off, still I'm sure they know what they are doing.
Hi Burnt Onions
"The way we have sold off today and the pace at which capital is fleeing the UK you would think this Government was inadvertently steering us towards a recession....."
Unless the PM and cabinet are stupid beyond belief, I don't see anything inadvertent about what they're doing
So its deliberate then?
Don't you think the threat of a global trade war has something to do with it? The Stoxx 250 is off over 2% today.
Michelmersh Brick Holdings (LON:MBH)
Up 5%ish on above average volume in an otherwise grim and all too usual market for small caps. There has been speculation of an approach by Forterra (LON:FORT) , but probably just that.
Also I suspect an acquisition by a UK listed peer, were it to happen, would likely raise competition issues.
Great to see mining covered again. Thanks Mark. Hope you get a chance to cover Atalaya mining 3rd quarter results tomorrow
Copper? All that glitters ..... it will have its day but does not seem now. Phoenix Copper (LON:PXC) I still hold, in hope.
Good trading strategy is Hope, or is it Dope. Mr Munger has a book and sure not mentions it (not read it but its out there).
Never heard of Goldplat (LON:GDP) and sorry Mark, will pass on that opportunity, but as they say "good luck to holders" and "well done for spotting that".
This discussion past liked Sylvania Platinum (LON:SLP) and suspect many still do, so there was a miner in there lurking around.
Platinum is super rare so one to keep a close eye on and its 'green' uses.
Copper is not yet scarce - dread the day when it is. Remember cables from train lines getting nicked.
Gold has gone up in the last year. Advice do not have coins bullion etc delivered to your house because you will be burgled. Sorry recent experience - conspiracy theory maybe but I'm sure a targeted attack - my bad wanted to look at said small investment not hide it away where only has value if the grandkids find where you hid it.
We live and learn .. as we should in investing. The cost of learning.
What!! The Thruvision (LON:THRU) that went up 17% today? And which I hold! Seriously though I do understand frustration with the cover of some hopeless tiddlers, particularly in the pre-revenue space. But I do admit that I like having the light shone occasionally into the areas of obscurity of under £50mm Cap where I house about 10% of my portfolio. This is really the only forum for this stuff outside the ramper loons. Will Kromek (LON:KMK) hit the long promised pay dirt? Maybe not, but by throwing 1Spatial (LON:SPA) and Brave Bison (LON:BBSN) into the pot as well I think there's a chance of outsize gain and so makes these, and some others, worthy of occasional comment.
Thruvision (LON:THRU)
Another holding of Mark’s or ex holding that he was going on for some time . A graph of its overall performance shows the true picture and not todays dead cat bounce.
Another dilution today and the stock is up only because the fundraise was at a slightly higher price.
Another pointless small cap crap UK listing. A definite red for me.
All the best
Hi
Concurrent Technologies (LON:CNC) up +10.24% as I type. I think it has been covered in the SCVR a bit in the past. The news feed ......
12 November 2024
Concurrent Technologies Plc
(the "Company" or the "Group")
$3.72m Systems contract secured with leading defence provider in Asia
Concurrent Technologies Plc (AIM: CNC), a designer and manufacturer of leading-edge computer products, systems, and mission-critical solutions used in high-performance markets by some of the world's major OEMs, announces that its Systems business unit in Los Angeles has secured a $3.72m contract, with a leading defence platforms provider in Asia.
Working closely with the Company's local sales partner, Concurrent will deliver rugged systems to be used in next-generation armoured vehicle demonstrators, and earlier deliverables include air-cool R&D units to enable software development. Delivery of the finished systems is due during 2025, and therefore it is expected that most of the associated revenue will be recognised in that year. The demonstrations trials may inform a future decision to make more same or similar system.
Outside the Company's direct sales markets in the UK and USA, Concurrent works with distributors. Earlier this year, the Group hosted a well-attended global conference which introduced distributors to Concurrent's growth ambitions and new Systems offering. The event played a key role in unlocking this opportunity in Asia, following which Concurrent sent a team to the region to work with the distributor team for several days to shape the solution.
Miles Adcock, CEO of Concurrent Technologies Plc, commented: "This is one of the most significant orders ever received by Concurrent, secured after competing against some large well-established corporations. It is a clear testament to our ability to win complex systems development and delivery contracts. This contract, along with our growing portfolio of smaller wins, is also fuelling our Systems business in LA. Following the acquisition of Phillips Aerospace in September 2023, we are poised to see the business rapidly expand in 2025. It's great timing as we prepare to move into our new LA facility in Q1 2025, with our recruitment efforts well underway to bring in top talent."
I just bought starter position as had been watching it for a while.
Might be one of the limited few UK based technology/innovation companies.
Also interesting overlaps of key people crossing over with Filtronic (LON:FTC) as well as Beeks Financial Cloud (LON:BKS) and Craneware (LON:CRW) . Further, previous experiences in other UK defence related companies.
Here a YTD view of the four.
Regards
Howard
Hi Howard I have been tempted in the past with this company but hesitated partly due size (though now over my £100m min) and also dismayed at the lack of investment from their own directors. With a company of this size I regard this as a major factor. But YES they have done well past few months - well done.
Totally agree bohenie, its disappointing that the directors haven't bought shares with their own money. Although I hold Concurrent Technologies (LON:CNC), I have always felt it an anomaly.
I wonder why they haven't ? The prospects have looked very good for a while now and their appears to be lots of confidence and excitement in the company's future ? I guess its just a lot easier getting cheaply priced share options ( if thats what they are) year after year.
Even in unlisted businesses backed by pe/vc there is generally a requirement to invest an amount equivalent to a proportion of salary.
Although I suppose if they own lots of options then they are at least aligned with shareholders in wanting to see the share price rise.
Would it be possible for each Stocko author of the individual company reports to state at the beginning or end whether they hold or not? It just helps to maybe get a feel for negative or positive slant. The workload here from Graham & team continues to impress, Thank You!
On a broader news front....
The FT has reported that the Government may need to spend up to £2 billion in order to keep the two blast furnaces open at British Steel Scunthorpe whilst transitioning to green electric arc furnaces.
The FT suggests that this is well in excess of the original proposal (circa £300)m which was previously offered to the Chinese owner of British Steel.
This is a huge amount of money - does anyone have any knowledge of which companies might benefit from such a cash injection?
Vesuvius (LON:VSVS) or Hargreaves Services (LON:HSP) perhaps?
Thank you for the response Richard. I will do a little more research.
Add Morgan Advanced Materials (LON:MGAM) to that list too
Goldplat (LON:GDP)
Personally I am not interested to read about these small caps (£10m market cap) just because the writer has a holding and has been rather biased for years with the valuation.
Surely we will not have a detailed analysis of Thruvision (LON:THRU) next!
All the best
Completely agree. Don’t like that writers are pumping their own stocks here. Mark provides very good analysis generally on Stocko but has held Goldplat for years and it’s never really fulfilled its potential.
I’m not paying a subscription service to just read views on stocks held by the writer. It was getting a bit like that with Paul, despite my utmost respect for Paul he’d refused to cover commodity / O&G stocks previously then posted incessantly about POS because it was his largest holding, then GMS. Sorry, know folks won’t like that but would personally prefer they don’t cover stocks they hold unless requested by the subscribers.
Bit unnecessary Yiannos. Personally I am welcoming of a bit more variety. I have always foud Mark's comments to be balanced and fair.
Totally agree Mark.
Mark
I don’t quite understand your comment as I have stated that this is a personal one and indeed necessary for me.
Goldplat (LON:GDP) is a company that (after such a bullish year on gold) has never done anything really and with a spread that kills.
I know the ending of these kind of companies.
I am not interested about another Plexus Holdings (LON:POS) (have been warned around 22p).
I welcome as well more companies covered but about larger market caps with a future and not writers holdings.
I am not paying a subscription to read about writers holdings. I don’t get the Green/Amber philosophy on Goldplat (LON:GDP) as well-amber/red for me.
All the best
Hi yiannos1,
Sorry, you feel I overstepped the mark with this one. I ummed and aahed about including it, given the market cap is close to the £10m market cap limit. However, in general, subscribers have been asking for more commodity coverage, and I would be looking at it anyway, so I thought a quick look in the short section was a good compromise.
I get that commodity stocks end up being Marmite, mainly because so few pre-production stocks make decent returns. I always feel that processors like Sylvania Platinum (LON:SLP) and Goldplat (LON:GDP) are a kind of different breed in that they don't have the mine risk, which is the biggest issue with most mining stocks, and are (mostly) profitable and cash-generative. There is usually a lot to dislike too, commodity risk and operating jurisdiction being some of many. This is often why they end up being the cheapest stocks on the market at certain points of the cycle. And I am drawn, like a moth to the flame, to the type of stocks that everyone else hates so much that they would never consider owning it! Perhaps commodity stocks will have their day in the sun again, everyone will be partying, and I'll be standing in the corner shouting, "You do know it's called a commodity cycle for a reason!"
When I said I'd help out with the DSMR, a friend joked that I'd be in trouble because I'd be so countercyclical I'd downgrade everyone's favourite stocks to RED on valuation concerns. So, at least, I appear to have avoided that side of the controversy ;-)
Not sure what the Thruvision (LON:THRU) link is to commodity stocks, though. Loss-making tech stocks aren't really my thing, especially those that look like they need a placing. So that would have probably gotten a RED from me if they had reported today, even if that would have proved controversial. They are a real business with a decent product, just a commercial failure so far, so I don't know why there would be an issue reviewing them on the DSMR and saying that, though. But I am all ears if you think differently?
Cheers,
Mark
Hi Mark
You haven’t overstepped anything and I do apologise if my post seemed like that.
Simply we have different opinions on Goldplat (LON:GDP). It will not be the first nor the last time.
If I didn’t value your opinion I wouldn’t have read it.
I do feel though from my vast experience that these kind of companies very rarely make money for investors and I have explained the reasons.
All the best
Just my personal view, but I consider the small cap mining stocks to be uninvestable so would prefer them not to be covered. Obviously just my opinion and if there's demand from other readers then fair enough. Would be interested to see what others think.
I use quantitatives first then expert commentary as the next filter. Goldplat (LON:GDP) has appeared in one of my screens previously so I had a passing interest(I don’t hold)and if it appears again I can retrospectively read Marks analysis, no issue at all with it . The fact Mark holds is likely to enhance the analysis as he will be closer to the historic news flow.
Quarter cash burn £700k (Q4 to current Q1), Capex Ghana planned circa £900k (would think outturn £1m+), cash £3.1m.
Stocko earnings manipulation high risk. Gold price at all time highs and GDP flat profit. Think processing their old TSF has been in the pipeline now for what must be 8-10 years, which will also require more capital.
Personally wouldn’t touch GDP with the proverbial and disappointed to see it being written about here. But understand it may interest some but cannot for the life of me see how it’s Green / Amber. Doesn’t align IMO with the grading at all.
Assessing geological risk, drilling results etc is a specialist skill and I can see why the writers quite sensibly steer clear of these in the mining and oil industry spaces. However where these features are less important - Goldplat (LON:GDP) are a processor, Plexus Holdings (LON:POS) are in the oil services business, Serica Energy (LON:SQZ) are a producer no longer an explorer - then why not? I thought the write-up on Goldplat was very balanced and informed.
Goldplat (LON:GDP) does interest me although I no longer hold any shares in it. Between 2018 and 2020 I bought in 3 times and sold all every time and made money each time which goes to prove that small gold miners can profit the PI. However, I haven't been so lucky(?) with Hummingbird Resources (LON:HUM) which is about to disappear. Greatland Gold (LON:GGP) which I also hold may go the same way, bridge too far and all that. It is those who are actually getting the stuff out of the ground with little debt and preferably paying a dividend who are likely to be a solid investment, then things can go wrong if they go off at a tangent and start looking for the next big mine. Ariana Resources (LON:AAU) which I hold springs to mind.
I'm still waiting for Condor Gold (LON:CNR) to get bought out - but have realised not a clever strategy unless have some insider input.
Isn't James Mellor the Big Insider? I held Condor but concluded that he pulls the strings so I pulled out.
This is your guide to who will be there...
ONLY ONE WEEK until Mello's 10 Year Anniversary! Join us at the Derby Conference Centre, on Tuesday 19th & Wednesday 20th November, 9:00am - 7:00pm.
You asked, we answered! Calling all investors to our first show outside of London since 2018! If you are based in the Midlands / North of England, you must not miss our Anniversary show but everyone welcome wherever you are travelling from!
We have created a two-day investor conference that will include top quality keynote speakers, panel sessions such as our popular Mello BASH (Buy, Avoid, Sell, Hold) with professional investors and analysts, over 40 exhibiting companies and over 60 company presentations!
Tuesday's line up includes:
Keynote speakers Ben Rogoff, Alan Charlton, Peter Pereira Gray, Leon Boros, Twin Pete's Investing, Gervais Williams
Companies Rockwood Strategic, Aeorema Communications, Polar Capital, AJ Bell, Manx Financial Group, The Property Franchise Group, Filtronic, Transense Technologies, Light Science Technologies, Time to ACT, Oxford Technology, SharePad, Different Kind, Helios Underwriting, Rent Guarantor, N4 Pharma, Select Invoice Finance, Brave Bison, Edison Group
Wednesday's line up includes:
Keynote Speakers Paul Hill, Mark Simpson, Rosemary Banyard, Paul Scott, Gareth Evans
Companies Smiths News, 1spatial, Aeorema Communications, Time Finance, AJ Bell, Image Scan, Oxford Technology, Rent Guarantor, Spectra Systems, SharePad, Select Invoice Finance, Graft Polymer, Progressive, Mortgage Advice Bureau, Goldcore
For more information & to buy tickets, click here: https://melloevents.com/mello10tickets/ For half price tickets apply this code MMSTOCKO50
Not a news item, but I continue to follow my holding in Warpaint London (LON:W7L) and find it puzzling that although still a very profitable holding, that it continues to drift inexorably down for almost six months now, being 23% below its ATH. This sort of market movement is not uncommon in AIM as low visibility leads to a bored decline. But Warpaint is constantly mentioned so I am surprised that it is apparently not immune, or is there something in the air that I am not seeing?
Aside from general market sentiment, the prospect of Trump tariffs on US imports, especially any sourced from China, might impact sales and profit growth in Warpaint London (LON:W7L) key growth market
I'm in a similar position to you with regard to Warpaint London (LON:W7L) . If you look at the historical figures on the stock report, there was a huge leap in both revenue and profit between 2022 and 2023 which accounted for the accelerated increase in the share price. Both factors are forecast to continue growing, but not at the same rate, so I am happy to hold for the time being. PE ratio has declined from 25.7% in July to 19.5% at the moment, which is fine for a growing company.
There was an unfortunate reaction to the exaggerated worries over what Reeves might do with regard to IHT relief in the budget - I don't think this was ever likely to have a large effect on the Warpaint share price since two directors hold over 40% of the shares between them. And now people are panicking over Trump's tariffs. I think that this is another over-reaction - their products will still be good value in the US even after a 10 to 20% tariff is added to the price.
Warpaint London (LON:W7L) I just had a look at Elf elf Beauty (NYQ:ELF) (the large US competitor) and it has gone up since the election: "e.l.f. Beauty Inc. primarily manufactures its products in China through third-party suppliers. However, they have also partnered with Fair Trade USA to certify some of their manufacturing facilities as Fair Trade Certified, which includes facilities in other locations". So the China issue would affect both equally.
Is the manufacturing in China really an issue for Warpaint London (LON:W7L) ? I don't know for certain, but I assume that the product is shipped from China to the UK then from the UK to USA. I also note that they consider the Chinese market their biggest source of future growth.
Warpaint London (LON:W7L) What I should have added was "or not at all" which is really what I was implying. I was responding to the comment "And now people are panicking over Trump's tariffs." I was wondering if elf Beauty (NYQ:ELF) had moved down, and it hadn't. Elf makes stuff in China so it is not being hit by tariff worries. Obviously, who knows what happens if it did happen.
Whenever I see one of my positions go against me, I revisit the reasons for buying and read the last Warpaint London (LON:W7L) update, so this is what I've just done, here's a key snippet for me:
"We anticipate updating further on trading later in the year, and with significant opportunities for continued growth, both already secured with our existing retailers and in discussion with additional major retailers globally, I am confident that the Group will continue to perform well for the remainder of the year and beyond."
A trading update should be released anytime now (10th Nov last year). The market might punish an in line update, but there were lots of opportunities mentioned in the last update for H2. Also the CEO said he is very focused on protecting and improving margins in the recent Mello, so perhaps we'll see a profit beat at least.
On the sales growth point mentioned on another comment, agree it is valid, interestingly in the last update they said they'd yet to implement an inflationary price increase this year, so when this happens you'd imagine it will boost the YOY revenue number.
Warpaint London (LON:W7L) If you follow the trading pattern over the last 6 months, yes there has been weakness in the share price, this may possibly have been the result over budget fears and tariffs however the graph resembles something of a small dipper, so although these might be factors I think the predominant reason for the ups and downs are day traders buying at lows around £5 and then selling at levels around £5.50.
MJ GLEESON (LON:GLE) - Any thoughts out there why MJGleeson has fallen so heavily this month ? The AGM is scheduled for Friday so maybe a TU ?
Persimmon (LON:PSN) are down a similar amount maybe slightly more. Taking longer than expected for the building boom to happen. I hold Gleeson.
See Barratt Redrow (LON:BTRW) ,Persimmon (LON:PSN) ,Taylor Wimpey (LON:TW.) . All doing the same thing. Looks like interest rates aren't coming down any time soon and building lots of new houses isn't easy when there is still a lot of price inflaton in build costs.
Apparently we need to be building 500,000 new homes pa to keep up with the current growth in our population.
And that’s just the illegal immigrants…!
Hi Graham, regarding Time Finance (LON:TIME) (I hold). Can you clarify, 'I do think a switch to neutral could be justified before too long'. How does 'Neutral' fit in to the colour coding system in a potential move from Amber/Green? Thanks to you and the rest of the team for your continued quality analysis of the DSMR.
Morning,
Facilities by ADF (LON:ADF) (I hold)
Quite a hit today. Looking at the commentary I am concerned that since the screen writers strike there has been a fundamental shift in the market.
I would have thought that there would be a massive backlog of productions and the market would be booming but the opposite seems to be the case - delays and cancellations. It also seems that clients are cutting back on production costs and not paying for "add-ons" - whatever they consist of - no sauna and spa for the A-List actors? Anyone have a view on whether we should believe the management or views on whether the market has fundamentally changed and become much more challenging ? Cheers!
Zoo Digital (LON:ZOO) 's revenues up 29% from a low base naturally,From the streamers' localisation company (obviously they're internationally based, but could give some basic indication of the state of the streaming industry's direction of new productions), interims today : '
'After a long period of significant reduced activity, companies are now commissioning more shows, but the resumption of business in Los Angeles continues to be significantly below its peak.The recovery of the streaming sector so far has been led by both Netflix and Amazon, which are responsible for a large share of the programming launched since the end of the strikes.The Board currently anticipates a continuing industry recovery, steady during H2 FY25 and gradually improving through calendar 2025.'
Facilities by ADF (LON:ADF)
I would have thought that there would be a massive backlog of productions and the market would be booming but the opposite seems to be the case
Everything i have seen suggests that the "splashing the cash" phase of companies like netflix et al has peaked - it made sense to throw any money at stuff if you are going to get double digit % increases in sticky customers - once the landgrab is over and its back to more normal growth its probably "subsistence" level of spending matched to income (or less if they have to pay back prior splurges) for most. I would say uk is also probably one of more expensive places to film too perhaps and throw AI into the mix too - then to me its not unexpected that their are headwinds here that will continue longer than then glass most full brigade would hav eexpected. Easier to cancel or delay by full year plus if money is tight. Ok perhaps some may do 2 series at once (to me that would seem cost effective) - but its no surprise stuff isnt "bouncing back".
Should we expect anything will bounce back strongly nowadays if there is no strong indication its happening ? possibly not. Perhaps lesson learned here for similar industries that we may not have though of prior times as being "good times" but they are definately better than the now in lots of sectors.
I have no reason to believe uk wont be good place to film stuff long terms - so hopefully normality will return so that future stuff will have the relevant semi reliable follow up stuff that one would normally hope for some of the time that should keep companies like this on tickover - all this stopping and starting must be a delight to all the bean counters who will no doubt find it easier to chop it rather than have delays and exra costs and longer payback times.
Facilities by ADF (LON:ADF)
Have re-read the Cavendish note. Their forecast for FY25 of 6p adjusted eps takes account of the budget changes to NI.
The company is the dominant player in its industry in the UK and despite the current screw up, has cash on the books. So following the view of Howard Marks that the most important factor in successful investing is the price one pays, I have increased my holding by 50% at 32 p. Even after doing so it remains my smallest holding in my 23 share portfolio.
The Art of Execution, perhaps, we shall see.
Facilities by ADF (LON:ADF)
I have a very modest holding fortunately. Now significantly more modest.
Cavendish have adjusted earnings of 6p for next year, so at this morning's price of around 32p we have a PE of 5ish, but as Burnt Onions has said, management’s credibility is down the tubes, given the very recent equity raise.
Not sure I can bring myself to add, if I decide not to I will jettison.
I suspect that Richard Staveley will be in the market this morning, but he is much more savvy that me.
Yep, a lot of red flags with Facilities by ADF (LON:ADF . Even if they do turn the business around in a year or two, the sp will likely be stagnant until then or slowly drop more over time. Better places to invest until the company shows a turn around.
You are right gmtrader, they are better places to invest.
This phrase prompted a re-think and I have therefore reversed my earlier decision and exited Facilities by ADF (LON:ADF) . Fortunately my earlier decision to add has cost me a minimal amount and frees up funds to add one of my other holdings.
I suspect that Mr Staveley has mopped up my modest holding along with others. At least he may be able to exert some influence over the discredited management team than
Onwards and hopefully upward.
Quite a few softer 'resilient' trading statements and profit warnings emerging.....
Investors having good fun in the US and crypto and gold whereas it's a tin hats and hunker down situation in the UK.
I'd go as far as to bet the S&P gets to 10,000 before the FTSE does
Facilities by ADF (LON:ADF)
You can't do that, you can't raise millions for an acquisition and then a couple of months later issue a profit warning. They have just burnt all their bridges in the City and I would imagine Christopher Mills is on his way to their offices right now with a bunch of heavies demanding to know what the @@@@ they are playing at.
Big red mark now against this management team which is a shame cause I quite liked the business....
Quite. It had/ has potential, but this has blown it. I'd add an outlook for 2025 that things will be better with no reference to the 325 staff and subsequent impacts from NI, suggests a casual approach either to running the business or informing the owners as to what is going on. Either is enough for me to black list it. Shame - I also liked the concept.
As well as the size of warning, I'm surprised by how late in the year the profit warning has come.
My rationale for holding whilst others (e.g. Paul Scott) anticipated a profit warning was that services for large productions would be booked many weeks, if not months, in advance. I incorrectly took comfort from the investor meet call in mid Sept, the mid October 'in line' update and being so close to year end. Lesson learned.
The statement seems to focus on add ons and slippage to FY25, but the FY25 forecasts have also been taken down significantly this morning - alongside the price target. Management seem to be promising in FY25 what they had been promising for FY24. But this is based on a strong pipeline as opposed to confirmed bookings.
Add to this the great points raised above on the impact of headwinds from being a UK focussed company and I think management have some work to do to regain investor confidence.
Facilities by ADF (LON:ADF) Wow Ive never shown interest in the company but a quick Look at the list of major shareholders shows an impressive list of smallcap fund investors - How the might can fail. And how is it that the tab for Directors Dealings is not showing anything?
Facilities by ADF (LON:ADF)
bohenie asks why Stocko does not show Directors Dealings. Answer - there aren't any. 3 of the directors were with the company before IPO: M Proctor and J Richards have held their shares throughout and N Evans has never held any. The non execs have never held any:
McBride (LON:MCB)
Strong trading update from Mcbride, I'm assuming they have managed to retain their pricing power and market share and I put that down to three things (just my opinion);
1. Steady commodity prices
2. The rise of the German discounters in recent years has disrupted the hegemony (and price bullying) of the traditional Big 4 UK supermarkets
3. Private label was once looked down upon but i feel that is no longer the case, people have switched in the cost of living period and that customer has stayed captured
20% free cash flow yield, continuing to pay down their debt, this is another cheap, defensive, debt to equity play that will do well whatever the economic climate.
Point 3, absolutely. I feel consumers have seen through the Brand Premium, especially younger generations, and it could be a long time for that to change. My daughter kept telling me that Sainsbury's Baked Beans were just as good at 40p as Heinz at 140p and she is correct IMO.
I feel this is one reason that Marks and Spencer (LON:MKS) have succeeded in the grocery sector, their 'Remarksable Value' range for everyday food items is of good quality and as cheap as anywhere else.
and yet the share price is down today, i'm starting to give up on all UK stocks , its utterly depressing. McBride (LON:MCB) is trading at historical highs with significant tailwinds , yet it trades on a PE of 3. I could buy any loss making US company at the moment and see astronomical gains. The market is broken
Although I have some concerns about the efficiency of the UK market, in the case of McBride (LON:MCB) that I see on Stocko, it is currently 24% below its high, the p/e is ( a low) 5.6, there is a net debt at 4X the net profit and a pension deficit equivalent to net profit. There is marginal projected profit growth over the next couple of years. There is no dividend and market cap is 3X the book value. I quite like McBride myself and am aware of the bull thesis but I don’t think the market is completely unreasonable.
Hi Graham,
Thanks for the comment on Kainos (LON:KNOS) .
However, I am not sure I agree with the comment with regard to the company having 'limited IP of its own'.
The Workday products division is all based on products they build and for which they own the IP.
These include the Smart suite set of products, SmartTest, SmartAudit and SmartShield as well as the new Employee Document management (EDM) product.
These look like they should be a major driver of revenue going forward and are much higher margin that the two services division, so hopefully will turn out to be the jewel in the crown.
They are already gaining traction in the market, with revenue, hopefully of about 80m for this financial year and 100m in FY26 and estimated 200m by FY30.
The agreement that they have signed with Workday, means that Workday sales staff are incentivised to cross-sell these products to the broader Workday client base, so they seem to be fairly confident that they will hit these figures.
There will be a drag on profits in the short term as there are costs of about 7million annually associated with the agreement, so they are flagging that it will only be FY26, before they really start to see the benefits from this flow through in a significant way.
However, once companies start to use these products as part of their everyday product suite, it should be fairly sticky, high margin revenue going forward, so I see alot of reasons for optimism.
Sure, this is all based on the continued success of Workday, but I don't see Workday going anywhere in the near future.
Thanks Tom
Hi - Can you please have a look at Oxford Instruments (LON:OXIG) - the 1stH figs they show and then comment on dont seem to add up. Looks as if there's a typo with some figs shown in the wrong column - or am I having a bad day?
Morning All,
Cake Box Holdings (LON:CBOX) interims, look decent to me. Profits, earnings and divi double digit growth, gross margin up, like for like ahead of last year post period end.
Under the radar in my view!
RE: Cake Box Holdings (LON:CBOX)
Hi JohnDoe2378
Agreed that it's interesting - they've struggled to escape the fairly damning report Maynard Payton produced on them a year or so back, but the issues raised were relatively small and the response was good. I will keep an eye on the board changes as their CEO is a fairly dominant character.
I'd also note a very downbeat update from Facilities by ADF (LON:ADF) - can't help thinking it's not a scalable business and very much at the mercy of events - and a much more upbeat one from 4imprint (LON:FOUR), which continues to look like a quality outfit.
On Kainos (LON:KNOS) I agree with OzzieTom, the current slow market looks like an opportunity rather than an issue. There is both risk and opportunity in the relationship with Workday but, on balance, it's skewed to the upside.
Hold all of those.
timarr
Im a long term holder and am continuing to hold. nothing negative in my view from todays update.
Do you mean Cake Box Holdings (LON:CBOX) ?
I am a long term holder too, it is my biggest position. The fundamentals and business model look solid, the CEO owns over 25% of the shares and there is room for much growth. I even topped up this morning after reading the report :)