Daily Stock Market Report (Tue 21 Jan 2025) - SYS1, YU., SQZ, AGFX, QQ., ABDN

Good morning!
It looks like we have a large collection of updates that do not include any profit warnings - only "in line" and "ahead of" updates.
It's a rare "good news only" day - let's enjoy it while it lasts!
1pm: wrapping this up for now, cheers.
Spreadsheet accompanying this report (updated to 17/1/2025)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Cranswick (LON:CWK) (£2.6bn) | Q3 TU | FY25 trading remains in line with market expectations. | |
Abrdn (LON:ABDN) (£2.6bn) | Q4 AUMA & TU | Net inflow of £1.2bn in Q4, AUMA up to £511bn. FY24 adj op profit in line with market exps. | GREEN (Graham) An in line update. Much improved flows. Cheap valuation. |
Qinetiq (LON:QQ.) (£2.4bn) | Q3 TU | FY expectations unchanged. FY revenue exps “high single digit organic” growth at stable margins. | AMBER (Roland) |
Premier Foods (LON:PFD) (£1.6bn) | TU | Q3 sales up 3.1%. FY adj profit at upper end of expectations. | |
4imprint (LON:FOUR) (£1.4bn) | TU | 2024 rev +3% to $1.37bn. PBT “not less than” $153m, above the upper end of forecast range. | |
Alpha International (LON:ALPH) (£944m) | TU | FY24 rev +23% to £135m, total income +18% to £221m. Adj PBT in line with exps. | |
Alphawave IP (LON:AWE) (£935m) | TU | FY24 adj EBITDA to “exceed $50m” with revenue at lower end of guidance ($310m-$330m). | |
Elementis (LON:ELM) (£862m) | TU | Strong Q4. FY adj op profit now expected to be $126-128m, ahead of expectations. | |
Marshalls (LON:MSLH) (£641m) | Full Year TU | Revenue -8% to £619m. Net debt reduced. FY adj PBT to be within range of exps. | |
Kier (LON:KIE) (£627m) | TU | Trading in line with expectations. H2 weighting expected, order book +2% to £11bn at 31 Dec 24. | |
Serica Energy (LON:SQZ) (£599m) | TU | 2024 rev -21% to $726m. Net debt $71m. “Significant” increase in production in 2025. | AMBER/GREEN (Roland - I hold) |
WAG Payment Solutions (LON:WPS) (£586m) | TU | FY24 revenue +13.8% to €256m. Results in line with guidance. | |
Essentra (LON:ESNT) (£351m) | TU | FY24 rev +0.3%. Trading mixed. Adj op profit expected to be in line with current exps. | |
XP Power (LON:XPP) (£313m) | TU | 2024 adj. op profit within the range of exps (£25.1 - 27.6m). 2025 likely to be H2-weighted. | |
Yu (LON:YU.) (£311m) | TU | FY24 rev +40%, EBITDA margin above exps. Confidence in delivering FY25 exps. | AMBER/GREEN (Roland - I hold) |
Marston's (LON:MARS) (£269m) | TU | Adj. PBT “within the range” of exps (£52-53.7m). Cautious outlook for 2025. | |
Gulf Marine Services (LON:GMS) (£159m) | Contract extension | 171-day extension to an existing contract. Backlog now $483m. | |
Epwin (LON:EPWN) (£128m) | TU | “Resilient”. Adj. op profit marginally ahead of exps. Confident outlook for 2025. | |
System1 (LON:SYS1) (£75m) | TU | Full-year revenue “at least in line” with exps, and adj. PBT £5m, “comfortably above” exps. | GREEN (Graham) |
Shoe Zone (LON:SHOE) (£46m) | Final Results | Rev falls to £161m, PBT to £10.1m. Store refits/relocations to complete by end-2026. | |
Argentex (LON:AGFX) (£44m) | TU | Full year revenues £50.3m ahead of market expectation, full year EBITDA margin in line. | AMBER/GREEN (Graham) Excellent revenue performance. Mkt cap not supported by profits yet but balance sheet worth c. £40m. |
Ilika (LON:IKA) (£34m) | Half-year Results | “Significant progress”. H1 revenue £1m, includes grant funding £0.9m. EBITDA loss £1.9m. | |
Gear4music (HOLDINGS) (LON:G4M) (£31m) | TU | FY25 EBITDA in line with consensus markets exps. | |
Mission (LON:TMG) (£29m) | Full Year TU | “Resilient” H2. Full-year revenue +2%. Headline operating profit in line with exps at £9 - 9.2m. | |
Christie (LON:CTG) (£27m) | Full Year TU | Full year adj. op profit £1.4m, ahead of the £1.0m upper range previously indicated |
Graham's Section
System1 (LON:SYS1)
Up 3% to 605p (£77m) - Trading Update - Graham - GREEN
This provider of a “marketing decision-making platform” (helping companies to test their ads) provides an update for Q3 (Oct-Dec).
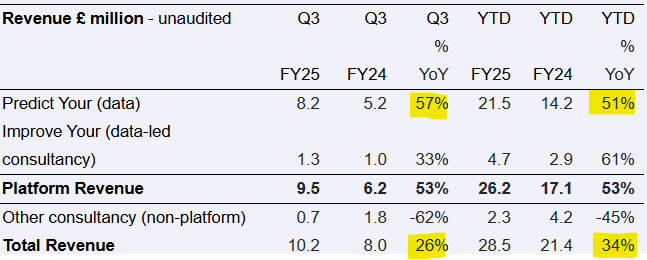
The main data-oriented products are enjoying a burst of growth as can be seen in the top row of the above table.
I think it’s a little bit more complicated when it comes to interpreting SYS1’s consultancy-based income streams. Yes, their “data-led” consultancy is up, but in my mind it’s just replacing the “other consultancy” income stream that has been abandoned.
So personally I would either focus on the performance of the data-oriented products (top row) or the growth of the total revenue figure (bottom row).
Q3’s strong performance reflected “growth in ad testing together with completion of a large project for a US-based client in December 2024” - we might still need to be careful that particular projects and clients can have a big impact on results in the short-term.
Clients: 120 new clients in Q3 contributed over a quarter of SYS’s “Platform Revenue” during that quarter. Tiktok is named as one of the new clients.
Outlook:
System1 enters the final three months of this financial year on the back of a record third quarter achieved while facing some economic headwinds in Europe and the UK. The Board now believes that the Group is well placed to achieve full-year revenue at least in line with current market expectations and deliver a full-year adjusted profit before taxation of approximately £5m, comfortably above current market expectations (FY24: £3.1m).
Existing market expectations for FY March 2025 are helpfully provided: revenue of £37m and adj. PBT £4.4m. So an additional £600k of adj. PBT is on the cards..
Estimates: Canaccord have updated both their FY March 2025 and FY March 2026 figures in response to this.
For next year (FY March 2026), they are now expecting revenues of £45.1m (prev: £44m), converting to adj. PBT of £5.9m (prev: £5.6m). This upgrade to next year’s profit forecast reverses the downgrade I mentioned in December.
Graham’s view
In December, I left this one fully GREEN despite having some concerns around valuation. On the back of this positive update, I’m happy to leave that stance unchanged.
There is little doubt in my mind that the shares are expensive:
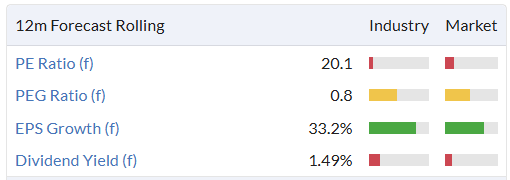
But what we’re getting for this price is a company that’s offering genuine organic growth: hundreds of new blue-chip clients signing up in a very short period of time (230 in the first nine months of the current financial year).
We don’t see this sort of organic growth very often and when we do, I think it’s important to recognise it and celebrate it. While SYS1’s clients already include many of the world’s largest advertisers, I would be surprised if they started to run out of prospective new customers too soon. There’s also the potential for continued revenue growth from existing clients - the net retention rate for Platform Revenue was 120% in H1.
So yes, there is a chance that this stock is overvalued, but I’d like to let this winner run a little longer.
Argentex (LON:AGFX)
Up 10% to 39.8p (£48m) - Trading Update - Graham - AMBER/GREEN
It’s a nice little full-year update from this “global specialist in currency risk management and alternative banking”.
Key points:
Full-year revenues of £50.3m, ahead of market expectations and slightly ahead of 2023..
Full-year EBITDA margin in line with expectation, in the low single digits.
Australia and Dubai regions are now fully operational. These “significantly increase our addressable market”.
Some commentary on how the year panned out:
Whilst the adverse market conditions experienced during 2023 in the core FX business continued into the first quarter of 2024, trading momentum improved subsequently, with the business returning to year on year growth in the second half and revenues in H2 exceeding those generated in H1.
Besides the geographic diversification, there is product diversification into “the broader payments and alternative banking markets”, which according to the company will improve customer retention.
CEO comment excerpt:
It has been a busy year and I am delighted with the progress made. We have invested for growth in 2024 and have made major changes to the business. With a strong team now in place, and a clear roadmap for the future, I am excited about the prospects for 2025 as multiple new profit generating revenue streams commence.
Estimates: thanks to Singers for updating on their client today.
They had previously expected just £43.4m of revenues for 2024, so the new guidance of £50.3m is a very substantial beat.
The previous EBITDA forecast was just £0.7m; this now doubles to £1.5m.
However, they leave their EBITDA forecasts for subsequent years unchanged, “for the moment”. So their 2025 EBITDA forecast remains at £1.7m (on flat revenues) and then in 2026 they continue to expect a step-change to £8.1m of EBITDA.
They acknowledge that this is a “cautious” estimate for 2025..
Graham’s view
There were some interesting comments in a recent thread around the FX space including Wise (LON:WISE) and Revolut.
With smaller players such as AGFX, we may have to look a little harder for their unique selling proposition: why pick Argentex over anyone else who can provide a currency service?
With Argentex I get the impression that there’s a great deal of emphasis on customer service and bespoke solutions, so for me this goes in the category of traditional FX brokers where there is a lot of human-to-human interaction (rather than something like Revolut, where if you need help you have to talk to their AI bot first!)
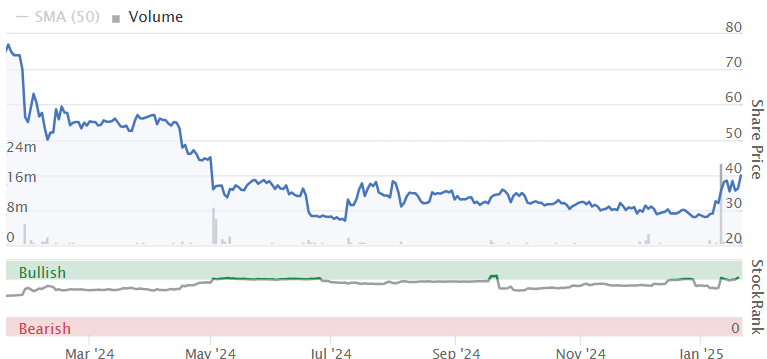
Paul put this at AMBER/GREEN in July (share price at the time: 29p) on the basis that it seemed to be stabilising under new management, after it had a torrid 2023. He was right and the shares are up by nearly 40% since then.
The interim balance sheet published since then shows net assets (tangible only) worth about £40m.
If I was valuing this purely on earnings I’d move to AMBER, because even if EBITDA does see a step change next year, I would not wish to pay a very high multiple for a traditional FX broker.
However, given the balance sheet strength which supports most of the market cap, I’m happy to leave it at AMBER/GREEN for now.
Hopefully there is plenty of recovery left in this one:
Abrdn (LON:ABDN)
Up 5% to 148.1p (£2.7bn) - Q4 Update - Graham - GREEN
Thanks to Ken Mitchell in the comments for bringing this one up.
I tend to follow the smaller fund managers in detail but why not check in on this giant? Even if I still don’t accept the name change that it went through in 2021.
The company’s new CEO has been forced to defend it again this morning, saying “The name is the name and we will be continuing with it.”
They should just change it back to Aberdeen, shouldn’t they? I wonder how many millions the branding agency was paid for this.
Anyway, let’s check out the contents of today’s Q4 update.
I think these are the key points. Firstly, an improvement in flows against last year:
Q4 positive net flows £1.2 billion (vs. last year: negative net flows £5.7bn).
Full-year negative net flows £1.1 billion (vs. last year: negative net flows much worse at £17.6 billion).
Assets under management and administration (AUMA) are up 3% for the year as a whole (to £210bn) and are also up slightly during Q4.
At Interactive Investor, there was a strong inflow of £5.7bn for the year, with AUMA up 17% to £77.5bn. It looks like it was responsible for most of ABDN’s AUMA growth in 2024.
It now has 81,000 SIPP customers, up 29% in a year.
Group P&L: £100m of annualised cost savings have been achieved, with £150m targeted by the end of 2025.
Operating expenses: in line.
Adjusted operating profit for the year: in line.
CEO comment:
We made significant progress in 2024, exceeding our cost transformation targets and also laying the foundations for the new management team to achieve growth and efficiency as we enter 2025…
Outflows in Adviser are being addressed, with an absolute focus on an improved service and value proposition for our clients.
Graham’s view
I don’t think I can be anything except GREEN on this, given my stance on (nearly) all other fund managers.
The picture of flows presented today is not all that bad, and yet here is the valuation on offer:
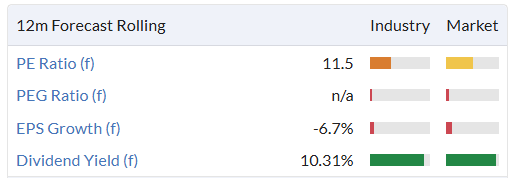
It’s more of a multi-faceted picture than the other fund managers I cover, as it includes not just traditional fund management but also Interactive Investor and the “Adviser” business.
Arguably this boosts the appeal, given the state of the fund management industry. Interactive Investor appears to be a high-quality business, and the Adviser segment provides another type of diversification.
It's staggering to think that £1.5bn was paid for Interactive Investor, and now the entire group is valued at £2.7bn.
I’m happy to take a GREEN stance.
But they really do need to change their name back.
Roland's Section
Yu (LON:YU.)
Down 7% to 1,729p (£288m) - Y/E Trading Update - Roland (I hold) - AMBER/GREEN
Business energy supplier Yu Group is a holding in the SIF portfolio and a stock I hold personally. Today’s year-end trading update tells us that growth slowed during the second half of last year, leaving full-year revenue below expectations.
However, profit margins are higher than expected and the company’s broker has upgraded its earnings forecasts today, so I don’t think this update is too disappointing (my emphasis below):
FY24 revenues grew c.40% and are expected to be approaching £650m (FY23: £460m).
Delivery of FY24 EBITDA margin forecasted above expectations driven by strong contract profitability in H2 24, robust hedging policy and tightly managed bad debt.
Net cash position of £80.2m (FY23: £32.1m).
For context, the consensus revenue forecast prior to today was £674m, so today’s guidance is perhaps 4% below expectations.
The increase in the year-end net cash position isn’t as impressive as it seems, either. Yu moved to a new trading facility with Shell last year, which resulted in c.£50m of cash being released from its previous counterparty. Stripping this out, year-end net cash appears to be broadly unchanged from 2023.
Energy supply: headline operational growth in the core energy supply business was strong last year, but today’s numbers reveal a slowdown in H2:
Meter points supplied: FY24 +65% to 88k (H1: +35%, H2: +22%)
Avg monthly new bookings: FY24 £42.6m (H1: £46.9m, H2: £38.3m), partly due to lower energy prices
Volume of energy supplied: FY24 +c.78%
Smart meters: Yu is building a smart meter business that is expected to provide an annuity-like revenue stream over time.
Income from this operation is described as Index-linked annualised recurring revenue (ILARR) - this rose to £1.3m last year from 27.2k meters owned.
Dividend: a progressive dividend policy is being maintained, targeting 3x earnings cover.
Outlook: organic growth in 2025 is expected to reflect “more normalised” energy prices. At the end of 2024, contracted revenue for the year ahead was £566m, an increase of 9% on the end of 2023.
Broker Panmure Liberum has updated its forecasts today, cutting its 2024 revenue estimate to £645m but increasing its 2024 eps estimate by 5% to 198.4p.
The company says it is confident of delivering FY25 expectations and Panmure’s earnings estimates for 2025 are unchanged at 213p per share.
Incidentally, the Panmure note (available on Research Tree) provides lots of detail on the business and is worth a read for anyone interested in Yu.
Roland’s view
While I’m slightly disappointed to see growth (apparently) fall below expectations in H2, I don’t think today’s update is too bad. The business is still adding new meter points at double-digit rates and is doing so with improved profitability.
Revenue is closely linked to energy prices and so may be more volatile than we’re used to seeing with other types of business.
CEO Bobby Kalar owns 51.6% of the stock, so his interests are well aligned with those of other shareholders. This gives me confidence that he will continue to manage the business to provide consistent profitability and cash generation.
Today’s update has left the shares trading on a 2024 forecast P/E of 8.6 with a 3.3% yield. While this isn’t a business I’d buy on a high rating, I think this looks reasonable given YU’s growth prospects and improving profitability. AMBER/GREEN
Serica Energy (LON:SQZ)
Up 3% to 157p (£618m) - Trading and operations update - Roland (I hold) - AMBER/GREEN
I last covered Serica just two weeks ago, when the company warned 2024 production would fall below expectations.
Today’s update covers the full year and the outlook for 2025. The company takes a positive tone, but as I’ll explain shortly, I think today’s guidance may be slightly weaker than originally expected.
The outlook for 2025 is promising, with ongoing work to increase asset reliability and further positive results from the Triton drilling programme expected to boost production and help deliver material free cash flow.
CEO Chris Cox says he expects to “continue delivering material direct returns to our shareholders” in 2025, which seems to suggest Serica’s existing generous dividend may remain sustainable. Based on last year’s 23p per share distribution, the yield is currently over 14%.
Financial summary:
2024 production of 34,600 boepd (2023 pro forma: 40,100 boepd)
2024 revenue of $726m (2023 pro forma: $920m)
Avg Brent oil price $81/bbl (2023: $81/bbl)
Avg NBP gas price of 83p/therm (2023: 99p/therm)
Dividends of $114m (23p/share) and $19m buyback
Free cash outflow of $1m
Net debt of $71m at 31 Dec 24, improved cash generation expected in 2025
Operationally, recent work appears to be paying dividends:
Triton production ramping up after the recent restart and is being boosted by the new Gannet GE05 well. This is producing at 6,000 bopd, “well ahead of expectations”
Additional wells are being drilled and expected to add to production over the coming year
The Triton compressor fix is expected to be completed by the end of March 2025
Outlook:
2025 production is expected to rise by c.15% to around 40,000 boepd, evenly split between oil and gas
Spending will be similar to 2024, improved cash flows are expected to support further shareholder returns
Preparatory work underway regarding a move from AIM to the Main Market in 2025.
Company remains active in screening for M&A opportunities in the North Sea and elsewhere
The company doesn’t mention whether the 2025 outlook is in line with expectations. I think it may actually be slightly below previous forecasts.
In my last review, I speculated that Serica’s ageing assets may require more regular maintenance than some others.
Today the company advised that production will be H1 weighted, largely because of two planned outages this year, including a 45-day outage on the Triton FPSO:
Production weighted to H1, with annual maintenance programmes at the Bruce Hub and Triton FPSO expected to take production offline in Q3 for 12 and 45 days respectively
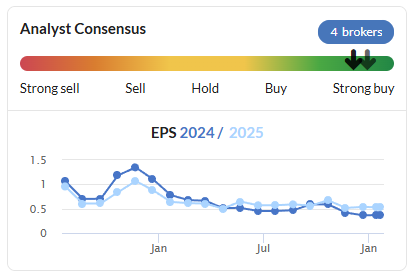
An updated note from broker Auctus Advisors is available on Research Tree today. Comparing this with the previous Auctus note on 7 Jan shows they have cut their 2025 production estimate from 41.4k to 40.1k boepd to reflect lower expected oil production, presumably because of this new planned outage.
Auctus’s 2025 eps estimate has been cut by 25% from $0.56 to $0.42 since 7 Jan.
This is only one estimate and other brokers covering Serica may take a different view – Stockopedia’s data suggests 4 brokers cover the shares.
Roland’s view
My impression is that earnings (and free cash flow) expectations for 2025 have been trimmed in today’s update.
However, the guidance laid out today still suggests to me that Serica’s current dividend will be comfortably supported by free cash flow in 2025. If so, then the shares could still offer a 14% dividend yield.
There are no free lunches in investing though, and I think it’s sensible to remember the risks here. Serica’s main assets are mature and increasingly appear to be relatively high maintenance.
Regular additional drilling is needed to maintain or expand production. Current broker forecasts suggest production may peak in 2027 before starting to fall quite sharply – hence management’s focus on M&A opportunities.
I remain positive at the current valuation and continue to hold the shares. But I plan to continue to view this business as something of a special situation, requiring regular monitoring and (perhaps) decisive action at some point. AMBER/GREEN.
Qinetiq (LON:QQ.)
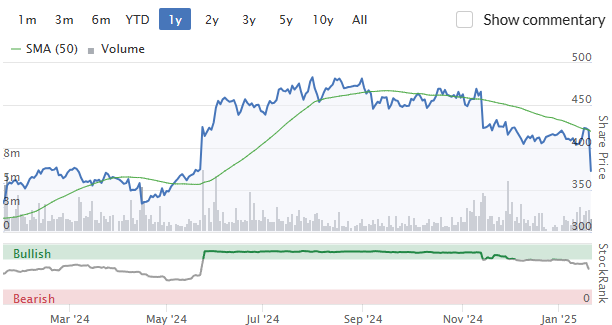
Down 11% to 372p (£2.1bn) - Third Quarter Trading Update - Roland - AMBER
Today’s update from defence contractor QinetiQ is headlined as being in line with expectations, and this was my first impression when quickly skimming the RNS feed at 7am.
Closer inspection reveals that it turns out that UK order intake has been “slower than expected”, prompting an 11% share price drop at the time of writing.
Let’s take a look.
QinetiQ has a 31 March year end, so today’s update covers fiscal Q3, the three months to 31 Dec 24.
Trading summary: the company has seen growth in its EMEA Services business (75% of revenue). “Good visibility” is said to be supported by a strong opportunity set from several major programmes.
However, within EMEA Services, the UK Intelligence business has suffered a sufficiently large slowdown to justify some restructuring activity:
Short-term order intake in the UK has been slower than expected due to the fiscal environment and we have taken proactive action to resize some of our capabilities in our UK Intelligence business.
UK Intelligence generated 29% of EMEA Services revenue in H1. So the affected business has previously generated more than 20% of total group revenue.
Fortunately, the far larger UK Defence business (59% of EMEA Services) is said to be unaffected by this slowdown. The company says it has greater exposure to long duration contracts which are unaffected by short-term spending decisions.
QinetiQ’s other operating segment is Global Solutions. Revenue is said to be stable in this business “despite headwinds in the contracting environment in the US”.
Order intake: year-to-date order intake is £1.3bn, slightly below last year’s figure of £1.35bn.
FY & mid-term expectations unchanged: CEO Steve Wadey does not seem to expect the shortfall in UK orders to affect full-year results:
Our expectations for the full year remain unchanged
Outlook: the company expects to report “high single digit organic revenue growth at stable underlying operating margin” this year. This is the same wording that was used in November’s interim results.
I don’t have access to broker notes for QinetiQ, but this comment seems consistent with consensus forecasts on Stockopedia for FY25 revenue growth of 7% and an implied adjusted net profit margin of 8.8% (FY24: 8.9%).
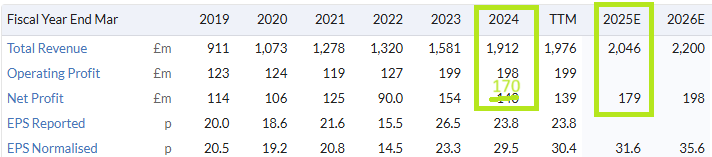
Over the medium term, QinetiQ is maintaining its target of achieving £2.4bn of annual revenue at c.12% margin by 2027.
Assuming forecasts remain unchanged, today’s fall leaves the stock trading on a FY25e P/E of 12, with a 2.3% yield.
Roland’s view
Today’s update stops short of giving us any idea of the scale of the shortfall in orders in UK Intelligence. So it’s hard to estimate the real severity of this issue. It may be minor and temporary, but the company’s decision to “resize some of our capabilities” suggests to me that it could be more severe.
I wonder if we might see a profit warning at some point in the coming months. The double-digit share price drop we’ve seen today (for a £2bn mid cap held by institutions) suggests to me that some brokers covering the stock may have trimmed their FY25 estimates following today’s news.
As always, there’s not a level playing field here. Institutional investors will have received updated broker notes this morning, but we’ll have to wait for updated consensus estimates to filter through.
Despite these concerns, today’s update doesn’t sound like a calamity to me. The current valuation suggests to me that a reasonably cautious outlook may now be priced in.
I’m going to take a neutral view ahead of the company’s usual year-end update in April. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Shoe Zone (LON:SHOE) £10m Profit with market cap £46m looks cheap what’s the catch?
Look at the 2025 estimates.
There is also some internal fallout between the 2 largest shareholders who own the company. Lack of control over quality and freight costs and SHEIN et al cannibalising their market made me sell at £1.50 having rode the wave from below 50p and taking some decent dividends. Is that 4 profit warnings now in a year? I couldn't invest unless these issues were looked at and resolved - lack of online presence and the refits do not seem to be working as well as they wanted - although I do commend them at looking at efficiencies, the scale of which just aren't large enough to make a big enough impact.
SDI (LON:SDI) was added to the Stocko QVM portfolio last week:
"SDI (LON:SDI) - a once high flyer that has struggled recently. For a long time, many viewed it as the heir to Judges Scientific - as an acquisitive rollup company in the healthcare space. But it's not been as successful in choosing self-managing companies to acquire. The big question is whether they can turn things around?
Well, that's not a question for me to answer. Just like the NAPS, the QVM Portfolio is going to load up on high-ranked stocks, and let the weighing machine of the market do its work. SDI has a really horrible chart, and the only smooth trend is downward. I don't like the technicals but it trades far below its long term P/E, and maybe the bearishness is overdone. Mark seemed to think so recently in the DSMR with an Amber/Green rating."
https://www.stockopedia.com/co...
Cavendish reiterated a 135p target on 5th December:
Interims – On track for FY25 forecasts with a stronger 2H
"The half-year results provide some encouraging signs despite overall numbers being down. This was due to the tough start to the year in biomedical and life science markets. There has been an improvement in trading in these markets recently and with a stronger order book it is expected momentum will continue through 2H.
We are encouraged to see internal actions bearing early fruit with a 240bps increase in the gross margin and greater collaboration between units to give better efficiencies. Management signal they are on track for current market expectations, with no change to our profit outlook for FY25E, we introduce FY26 forecasts that point to stronger organic growth and YoY EPS growth of 9%.
Our unchanged 135p target price offers significant upside to current levels, which highlights a low FY26E P/E of 8.7x and a FCF yield of 13.2%."
Mkt cap of £54m and 12mth rolling forecast p/e 7.9 leaves peg at 0.5. Price has come down from 62p to 53p since the last update. Latest director buy was end of September worth £57,780.
Recent acquisition InspecVision deemed to be immediately earnings enhancing and brings AI and machine learning capabilities with a strong IP which SDI hopes to leverage.
I have followed the QVM portfolio and added recently.
Residential Secure Income (LON:RESI) has results out tomorrow with a managed winding-up.
Life Science Reit (LON:LABS) and Residential Secure Income (LON:RESI) - does anyone know why these have fallen so much today?
Epwin (LON:EPWN)
shoutout to epwin with their update today - they have delivered again as promised (plus a bit ). They clearly have headwinds ref consumer spending and construction activity level activities so well done to mangement here for navigating very tough markets with aplomb - particular credit to the fact they have explicitly advised that they can cope with the unexpected chunky hit they will take with ref ers ni within their existing forecasts - the reality buisness need to face is that this is a cost increase like other cost increases and like any cost increases needs to be passed on - ok they may not like it and some may comment that they see it is unfair , i quite like a company that doesnt make a song and dance about costs going up - after all thats what they are paid to do manage stuff like that.
Revenues for the year were in line with market expectations1, however, H2 saw an improving trend and since the start of September monthly revenues have encouragingly all been slightly ahead of their respective 2023 comparatives.
Confident outlook for both FY 2025 and the medium-term
The Group expects to make further strategic and financial progress in 2025, despite the ongoing current macroeconomic and fiscal conditions which are expected to continue to temper demand in our markets in the first half of 2025.
The increases to Employers' National Insurance and the National Living Wage announced by the Government in the Budget in October 2024 will cost the Group an annualised c.£3 million, before taking account of any impact on other pay thresholds. The Group is confident in its ability to manage these additional unforeseen costs by making adjustments to its operational footprint and through pricing, in order to meet existing market forecast expectations.
This company to me takes a very nice fair line between acquisitions for growth (or to keep earnings from getting stale perhaps abit) , dividends , share buybacks and managing debt. Not often you get a bit of everything but they seem to tread that fine line nicely.
Cash generation has remained strong and the Group expects to report covenant net debt (pre-IFRS 16) at 31 December 2024 of c. £15.5 million (2023: £14.4 million), an improvement compared to current market expectations. This represents year-end leverage of less than 0.5x adjusted EBITDA.
This year-end net debt position was delivered after returning a total of £14.1 million to shareholders including paying out £6.9 million in ordinary dividends and an additional £7.2 million returned to shareholders through the continuing share buyback programme. We also invested £2.9 million in the bolt-on acquisitions.
I dont expect this company to command a premium rating - but on reasonably cheap p/e rating (8.5 per stock today) its a lovely little tuck away stock to have in my portfolio.
Car finance providers bouncing after Reeves intervenes. Secure Trust Bank (LON:STB) Close Brothers (LON:CBG) S&U (LON:SUS)
Rachel Reeves intervenes in UK car finance mis-selling case to protect lenders
Treasury approach to Supreme Court is blow to consumer groups but chancellor fears damage to sector
https://archive.ph/Zs1hw
Rachel Reeves intervenes in UK car finance mis-selling case to protect lenders
wowsers - very odd decsion by RR here - hmmmmm does anyone in the finance industry have close ties to labour per chance? . If these companies have been lying to people they give finance to one would expect that the chancellor would not step in to when the normal course of events should probably play out. Very peculiar.
Probably a minority view but I see this as a rare good decision from Rachel Reeves. Most car buyers going for CPC deals, including me, had no idea they were being misled and were happy with the deals they got, especially so when the car dealers were helping by adding big deposits for free. Anyone then paying off the CPC deal immediately, as I did, got a great deal.
The winners in these big claims situations are too often the sharks who take a big chunk of the payout from the too many people who don’t realise it is easy to deal with it themselves to get the lot.
Fully agree. I'd suspect most people if they were told the exact breakdown of costs would have still bought the car at that price. It's not like it was an additional cost added once they had signed up.
Fully agree. I'd suspect most people if they were told the exact breakdown of costs would have still bought the car at that price. It's not like it was an additional cost added once they had signed up.
Basically the specific issue here is that sales people made up apr rates of say 13% that they could then syphon excess off on top of say 5%.
I think at any basic levek you would not be expeting that the saleperson is the one dictating the apr rate charged when you are presented a finance documeny - on that level there should be no sympathy with those shysters who acted in such manner. How they could ever make a case that the apr was not anything other than a con when that fact existed i know not.
Seems strange that RR woudl protect those shysters from the peope who have been conned.
Yes they may have paid the extra anyway but its about not directly misleading people with regard to material element of the price paid.
Hey ho if one cant se the obvious conflict of interest here i give up.
is the one dictating the apr rate charged when you are presented a
finance document"
I don't think this latest intervention refers to the discretionary commission arrangements where the commission was dependent on the APR that the salesman could get away with. I don't think there's any argument that they were immoral and that there will be redress.
I think this latest intervention is only aimed at the court case escalation of this to all cases where the fact the salesman was receiving commission was not disclosed. There is no suggestion that the salesman could set the APR rate in these additional cases, and these cases are far more numerous than the original discretionary commission cases.
IMO if the FCA wants all commission to be disclosed, then it should make that clear, and redress should only be available after that date. Retrospectively applying current standards to past conduct that was legal at the time is a recipe for disaster.
feel free to correct me if i am wrong but the following link suggests the 3 cases that went to the high court recently might all perhaps have been DCA cases
https://www.fca.org.uk/news/st....
ref DCA
A discretionary commission arrangement (DCA) is when the finance provider pays the car dealer commission – or a fee – based on the interest rate paid in the car finance agreement. The car dealer can set or adjust this interest rate. Often, the higher the interest rate, the more commission the car dealer will receive.
Do you have any links to confirm that this action does not relate to DCA cases ?
My understanding was that the high court actions were indeed related to DCA cases, but that the judgement surprised everyone by also drawing in non-DCA cases.
There's a useful summary at the link below:
https://kpmg.com/xx/en/our-ins...
I entirely agree, this whole thing is a confected horror story whipped up by the media. People signed up to pay an amount of pounds per month and they got their car. They were not interested in how the money was split and had no reason to want to chase around finding if there was some cheaper deal (and there probably wasn’t).
This complaint should have been thrown out by the courts on a caveat emptor basis.
I agree 100000% with you and this is one of the many downfalls of the UK economy and by that I mean the likes of Martin Lewis.
I have signed a deal to buy a car and I know what’s my monthly payment and I have agreed to it- that’s it.
A highly trusted source tells me he is trying to find a similar storyline in the housing market!
All the best
At what point do people ever take personal responsibility for their actions and just do some basic due diligence?
Although that said, sometimes I feel like kicking myself as I never seem to get a payout for PPI or similar because I questioned what I was being charged on everything...
"At what point do people ever take personal responsibility for their actions and just do some basic due diligence?"
A bygone era. Disappeared along with telephones on cords, physical car keys etc. Why bother when there is huge safety net of claiming culture to pay up.
The Treasury statement actually says..
"The Treasury will seek to persuade the Court that any remedy should be proportionate to the loss actually suffered by the consumer and avoid conferring a windfall upon her"
Sounds reasonable - but not a huge row back.
I would be interested to see how Reeves pulls this one off. Kier Starmer (former Director of Public Prosecutions) is very cautious about the Government interfering with the Law. Intriguing.
Deleted comment
Yu. Is really being hammered today. Did I ever buy in at the wrong time! :-/
Always falls on results day. Was a bit disappointed personally with the update as a whole
Yeah I know, seems a bit overdone though.
Thanks for looking at Serica Energy (LON:SQZ) Roland, if anyone also gets time to look at 4imprint (LON:FOUR) that would also be appreciated, decent results, net cash, main market listing, reasonable dividend yield in excess of 3.5% which is covered and you normally find the good news effect can run for quite a while when it comes to share prices.
I’m really impressed by Gulf Marine Services (LON:GMS) regular updates. Hopefully the sea fox clear their shares soon and it starts moving up again.
Gulf Marine Services (LON:GMS) - to be clear - are they saying that the 'backlog' of $483m is the estimated revenue booked over the next 3 years ?
Not sure, but the figure was $503 at the last announcement in Dec, so no idea what’s going on
CWK Q3 TS and acquisition announcement. ".Strong revenue growth during the period was again underpinned by excellent volume growth across our core UK food business." I didn't choose this for the "12 shares for xmas" as the fwd PE is 17. It's a good quality company, and a good long-term hold.
FOUR TU. "The Group has delivered a strong financial performance for the year." Shares up 6% as of writing. One of my "12 shares for xmas". Glad to see I don't (currenlty) have egg on my face. Fwd PE of 15 which still looks very reasonable for a business of this quality.
I hold both.
Do you know if CWK have said anything about how well they'll be able to mitigate the NI and living wage increases? There were a couple of vague comments in the interim presentation slides "Labour and National Insurance cost increases to be managed with customers" and "Anticipated headwinds due to impact of National Insurance and Living Wage increases" but they're just stating the obvious really
A decent update from Abrdn (LON:ABDN) today, with Interactive Investor(they overpaid but at least it was a decent business to buy) doing particularly well.
Share price performance has been awful for years, but now down 70% from £5 when they started a £multi billion (and 5 year) buyback, to just 148p today (and recent low 135p). This surely means all the bad news looks priced in while recovery, or possibly a bid, isn’t.
The buybacks were a terrible waste of money and continuing them all the while the share price fell month after month (and for 5 years) was senseless. BUT one plus is that it has reduced the share count considerably and means good chance the 14.6p dividend can be maintained to give a near 10% yield.
The buyback decisions along with the idiotic name change to ABDN reflects the quality of Management.
I sold as the share fell away from £5 put off by the combination of buying back and falling share price, with the buybacks meaning big investors wanting out had a willing buyer in Aberdeen themselves. I bought again at £1.60 over 2 years ago. That’s proved to be far too soon, but could the clear signs of improvement in their update today mean at last a good share price recovery? . The sum of the parts is worth a good bit more than the current dismal share price.
Interesting that a name change and in particular a daft name change is so important. It signals that the brand is worthless and the management are embarrased about working for that company.
For this reason i'm not touching Zigup.
Other signals include building an enormous grand HQ, think Royal Bank of Scotland, putting a fountain in the entrance or having an atrium in the head office.
I think you're right on Zigup - the share price has been very weak recently and sure the silly name change has at least something to do with it.
I can think of a few stocks that have fallen after name changes: System1 (LON:SYS1) and Gattaca (LON:GATC) are 2. I preferred the previous names.
ZIG
I think you're right on Zigup - the share price has been very weak recently and sure the silly name change has at least something to do with it.
personally i doubt it but what do i know ?
Note at present zigup is expecting lower earnings in 2025 than 2024 and lower again in 2026 than 2025. I dont need to go to a conspiracy theory to find an answer for the shareprice weakness here.Note debt is up too!
Note i m a zigup fanboy and content holder - to me the company has flagged up in advance in reasonable manner why profits wil be declining - those reasons have very little to do with how well they are trading (more residual bvalues in vehciles and change in depreciation policy).
Yes i think the the price decline ins unwarranted to a certain degree but i understand the metrics here will put peoole off investing and often when there is a downtrend that can continue on past the point where it makes sense. Whilst its common that peple offload when they are a set % down we should expect stuff like this to happen. who konws though eprhaps bad news is on the way and we havent as of yet ben face slapped (i have zero evidence that they are doing anything other than fine)
What is very intersting to me is that the 2026 eps numbers on stocky have taken a huge jump in the last ten days - going from eps of 46.6p to 51.6p.
As far as i can see this adjustment is on no new news - is there any mechism to find out if this entry is a mistake or what is the reason fro the adjust if its correct. I guess its too much to expect that this is stocky looking into the future and saying there is good news on the way soon?
I bought Abrdn (LON:ABDN) recently around the £1.40 levels, precisely because I thought all the bad news must now be priced in, and the attraction of the high dividend - looking at the positive update today, I don't see any reason why the dividend can't be maintained in the short term at least. Hopefully the update today is the start of a recovery. But I'll be keeping an eye open for any possibility of dividend cuts.
'The buyback decisions along with the idiotic name change to ABDN reflects the quality of Management.'
To be fair to the current CEO Ken, he has only been in position for 8 months and at the company for 15 months ... share price unchanged over that period, but large dividends paid... you could possibly have said ' prior management ' as the aforementioned decisions were under the auspices of a different CEO and CFO...
Good point Cancun and I should have included it was past Abrdn (LON:ABDN) Management, responsible for the bad decisions that hammered the share price. Also different CEO and CFO is another plus point.
Good to see Graham’s analysis, and agree with all of it, including about the idiotic name change which they don’t have to stick with surely, and paying far too much for Interactive Investor, but imo that’s now the jewel in their crown.
The share price has bounced each time it’s fallen to around 140p, and after the encouraging update today this time could it lead to a sustained share price gain?
"Interactive Investor, but imo that’s now the jewel in their crown"
I agree Ken - ii has to be one of the cheapest/cheaper platforms to hold investments with, in terms of flat mthly fee (not % based commission), low dealing charge, free mthly investing etc., but also (and probably most importantly given the rise of passive investing) gives access to all the main tracker/passive investing funds out there.
Abrdn (LON:ABDN) a company of this size and scale should have an enormous bench of talent to promote to run it instead of bringing in outsiders. I think that tells you all you need to know about the quality of the business.
Alternatively, given the greater than 70% share price fall in the preceding few years, the Board decided to hire a top quality, external candidate who didn't suffer from ' Group Think '.
I've worked in big UK financial services companies, would say 1% of top management have real talent, these businesses fall foul time and again to new big dogs coming in promising the world they then go on a big sales push prime example in my time buying in final salary pension schemes at the same time as they are shutting their own.
Sales quadrupled over two years but they lost hundreds of millions on the deals then the person who put the idea forward then jumps ship but on his cv he now has "look I quadrupled sales in two years when i was at x" but he/she leaves off "er yes but the result was it was all unprofitable business and we lost hundreds of millions"
Something in the Q3 trading update from Qinetiq (LON:QQ.) seems to have spooked the market. I wonder if the phrase "short-term order intake in the UK has been slower than expected" is leading to downgrades for next year? This year's numbers are on track according to the statement.
It doesn't take much to spook the market these days. I think it is reasonable to guess that defence spending will rise in the medium term, but there is yet another review so it's hard to guess the winners and losers. In almost all areas the government has not laid out its spending plans. (I hold Qinetiq (LON:QQ.) )
All fair points. And yet Qinetiq (LON:QQ.) is so cheap on fundamentals. It was already trading at a discount to other defence companies here and abroad. The LT operational track record is excellent. Has a relatively unique niche (so decent moat) competitive
position. ROCE is double digits. Debt modest. Post this morning’s mark down the Mar 26 PE is barely above 10x. That is ludicrous for a company of this quality. The saving grace is the buyback which at these levels is super value accretive for LT shareholders. I also hold. But just so dispiriting. The UK is not a serious market anymore. That’s my conclusion. No serious liquidity outside the FTSE 100. And the end game here will most likely be like so many others ie a cheeky bid from a US PE or strategic. Anyone remember Cobham, which was much more operationally troubled. And there will be the usual platitudes / crocodile tears about another quality name disappearing in the press. Why but why? And in the financial pages how in retrospect it was such a sitting duck at this valuation. So why aren’t UK fund managers buying now. Answer. Because everyone is pulling money from the UK to put into the MAG 7 and crypto. And so the madness continues. Bubble there and death spiral here. Anyways. Rant over. Thank you for listening… :)
So why have Avon Technologies (LON:AVON) and Cohort (LON:CHRT) been rising then?
The FTSE100 is at an all time high, so somebody must be putting some money in?
The FTSE may be at an all time but there is general agreement that the UK market has ‘relatively’ underperformed peers and particularly the US. I think there is general acknowledgment that UK companies are cheap. Why are we getting so many takeover bids? So someone is buying but not enough. And we know plenty are selling. And of course there will always be exceptions. I can’t tell you why Avon Technologies (LON:AVON) is rising. I do note that it’s coming after a stumble that saw it wipe out 80% of market cap. That said it is a company that seems to fascinate PIs and certain stock commentators in a way that Qinetiq (LON:QQ.) just doesn’t. I assume the volatility is a draw. QQ. is more boring in comparison. That doesn’t mean it deserves to trade at 11x PE. It’s the sort of stock that Pension Funds would have owned in the old days. Tuck away and forget. But of course they don’t own UK stocks anymore - 4% of their AUM I believe. Just to be clear I’m not worried about QQ.. Value will out in the end. But I’m just generally echoing what so many are saying. Why would you even think of listing in this market right now? Why wouldn’t you move listing to the extent you have, say, any meaningful US revenues and / or shareholder base? Our pensions funds don’t care. The govt doesn’t care. There has been talk of at least ditching stamp duty. But given the need for every penny that ain’t going to happen. Our active fund mgmt sector is dying by a thousand cuts, ahem redemptions. For me QQ. and I can list you countless other stocks is just the canary in the coal mine…
I agree with the vast majority of the points made but would add that Chemring and QinetiQ have both included comments on slower orders from their main customer, the UKs MOD. QinetiQ today stated: “Short-term order intake in the UK has been slower than expected due to the fiscal environment and we have taken proactive action to resize some of our capabilities in our UK Intelligence business.” Over 65% of their turnover is from the UK, 20% US.
Avon Technologies receives over 80% of its earnings from the US, where the falling pound benefits its earnings. Cohort is benefiting from overseas M&A activity and growth in Germany
Hi Phil
Because everyone is pulling money from the UK to put into the MAG 7 and crypto. And so the madness continues. Bubble there and death spiral here.
Nothing lasts forever - and it isn't just the UK, Singapore is seeing the same problem. Currently the US is a swirling vortex that's sucking capital out of the rest of the world. That's OK until you need the rest of the world to pay for stuff ...
The endgame here is boringly predictable - money sucks in dumb money and as sure as night follows day there'll eventually be a blow out when earnings expectations can't meet the weight of incoming cash and indexes go into reverse. When the dust settles boring companies that actually make money will come back into fashion for a few years.
However, this could take a year or more, so there's no point in fighting it. And who knows, maybe AI will turn out to be the productivity booster that our PM expects it to be. Away from the big names and the meme stocks there's plenty of value in the US. In fact, despite everything Alphabet (NSQ:GOOG) looks reasonable value, especially if you think the US anti-trust issues are going away.
And yes, Qinetiq (LON:QQ.) looks cheap, but in a forest of cheap stocks it's sometimes hard to pick out the trees ...
timarr
I have been a holder of Qinetiq (LON:QQ.) in the past and I'm quite tempted by the lowly current valuation. However, I think that you are forgetting some of the issues that the company has had in the past. If I remember correctly, they had big issues in the US and sold out of that business before more recently acquiring there again.
They also had a heavy capex programme in the UK that hit cashflow for some time together with occasional warnings that led to write-offs etc. So whilst their medium-term outlook is encouraging I think the shares have often traded at a discount due to wariness about the long-term track record.
https://www.ft.com/content/897...
I do wonder wether the fact that Qinetiq (LON:QQ.) biggest share holder is the major backer of the Reform party may put the current government off favouring them in contract negotiations. Must admit I sold my shares as soon as I read the above article.
Hi chrisgb
European defence stocks seem to be rising nicely at the moment.
I hold Leonardo SpA (BIT:LDO) up over 10% YTD and Rheinmetall AG (ETR:RHM) up over 15% YTD. These have had some positive news feeds recently and I suspect the Trump narrative of Europeans needing to increase defence spending (possibly up to 5%) might be catalising these rises.
I also hold Rolls-Royce Holdings (LON:RR.) up just over 1% YTD for a broader play on defence but nuclear as well.
Regards
Howard
I topped up this morning but like this sector for a long hold and it seems many people aren't interested in trading for the long term these days.
Spending thrift (reduction/cuts - whatever term suits you) are taking place in MoD. I work with a number of suppliers to that market and the mood is not positive. I suspect all government departments are facing a similar scenario.
Would be good to hear your latest thoughts on Serica Energy (LON:SQZ) Roland looks so cheap but tempered by Labour's determination to destroy UK gas industry.
This Government will change and the oil and gas will still be there. When the honesty of net zero materializes, then the realization that we do need our oil and gas will happen and then whoever is in government will know that extracting the oil and gas from fields that they can tax is so much better than importing it where the only tax is at the consumer end. Too much tax and there'll be no profit, so it needs to be balanced. Energy self sufficiency needs engineers and scientists with less interference from politicians who don't represent the needs of the majority of the population. So, my hope is that the price goes lower and I can keep accumulating until common sense prevails.
So many companies reporting positive trading news today, bodes well for the trajectory of the overall market.
You can take your pick from the list above, all very encouraging....
Agree Onions! More like this and even Jupiter Fund Management (LON:JUP) may show signs of life!! (I hold)
There’s a lot of bad news factored in today. The results by companies will determine the next path I feel. Onwards and upwards hopefully
CBG up 20% not sure why but lloyds is up 4% and maybe all banks and financials are doing well.
Stocko choice for turn around asset funds ( abrdn and jupiter), proved 50% correct. Abrdn is up 8% . JUP is still struggling.
"UK finance minister Rachel Reeves launched a bid to protect car-loan providers from multibillion-pound payouts, FT reports"
Secure Trust Bank (LON:STB) up 15%.
Missed that data thanks
not a surprise government needs growth dealers sell car finance packages not cars. If its been misold should have refunds pre 2010 labour government cover up?
Well Mr. Market is not so happy, with some of these updates, marking some down 6-12%.