Daily Stock Market Report (Tue 22nd Sep 2026) - SRB, BPM, LUCE, MAB1, YU.

It’s been another quiet day for macro news. The lead story on Bloomberg is that global AI stocks have rallied thanks to Meta’s new AI agent app, Muse, having risen to the top of Apple’s charts for free apps:
The strong debut is helping revive confidence in the AI trade after concerns over lofty valuations triggered a July rout, and recent warnings from tech leaders about the existential threats from advanced models fueled fresh volatility.
The newly-launched app is only available in the United States at the moment, but it’s supposed to be very helpful for everyday tasks. I guess we’ll find out soon!
Personally, I wouldn’t read too much into Muse becoming the most popular free app. The only way AI valuations will make sense is through profitability: the question of adoption has already been answered in the affirmative, in my view.
If we were told in 2014 that downloads of Flappy Bird had triggered a rally in global stock markets, I’m sure we would all have found that rather silly! How different is this, really?
Overnight market movements:
The FTSE is up 0.2% at 10,755
S&P 500 is unchanged at 7,770
Brent crude (November) is up 1.7% at $102.05/bbl
Gold is down 0.6% at $4,320/oz
Bitcoin is down 1.9% at $85,350
Mark Simpson joins me today.
I'm sorry I've run out of steam, I'll try to catch up with Fonix later in the week! Cheers. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Rentokil Initial (LON:RTO) (£8.03bn | SR68) | Agreement with Bain Capital for the sale of SOLitude Lake Management. $230m on a cash-free, debt-free basis. After tax cash proceeds to be c. $180m. | ||
Smiths (LON:SMIN) (£7.4bn | SR48) | FY26 organic growth 1.2%, headline operating profit +1.9% (£399m). “As we enter FY2027, underlying market conditions remain challenging, but our robust order book and business momentum underpins our expectation of organic revenue growth of ~4%… we will more quickly deliver our 5-7% organic growth target in the medium term.” | ||
Kingfisher (LON:KGF) (£5.04bn | SR99) | Total sales including marketplace +1.6%. Underlying LfL +0.3%. Adjusted PBT +9.9% to £404m. Upgrading FY27 guidance: adjusted PBT £595-635m (previously £565-625m). £300m buyback ongoing. | ||
Oxford BioMedica (LON:OXB) (£563m | SR9) | Revenue at constant currencies up 10% to £80.2m. Operating loss £29.1m. Net cash £21.4m. All FY 2026 and medium-term guidance reiterated following August trading update. | ||
Luceco (LON:LUCE) (£378m | SR91) | Revenue +13.4%. Adjusted operating profit +14.5% to £15.8m. Bank net debt £69.6m (leverage multiple 1.5x). Now expects Adjusted Operating Profit for 2026 to be ahead of market expectations. | AMBER/GREEN ↑ (Mark) The upgrade here is relatively minor (at least according to the only broker research we can see). However, it comes at a time where a strong H2-weighting was required to hit forecasts so would be particularly welcomed by shareholders. EV chargers continue to be behind the strong performance. However 6.5% organic core revenue growth is still good considering the market backdrop. The costs of the CEO transition raise some eyebrows, and the lack of short-term cash generation requires careful watching. | |
Origin Enterprises (LON:OGN) (£372m | SR74) | Revenue +2.3% at constant currencies. Group operating profit (including JVs) +2.8% at constant currencies to €100.7m. Net debt €77.8m. New set of medium-term financial ambitions to be outlined at Capital Markets Day on 17th November 2026. | ||
| Porvair (LON:PRV) (£410m | SR75) | Nine Month Trading Update | Constant currency revenue growth 14%, organic constant currency growth 5%. Trading to be slightly ahead of full-year expectations due to acquisition of GV Filtri in September. Underlying trading across the Group remains in line with the Board’s expectations for the full year. | |
SThree (LON:STEM) (£371m | SR98) | Q3 net fees down 2% (sequential improvement vs. Q2 -6%, Q1 -8%). Net cash £36m. FY26 PBT is expected to be at least £12m, ahead of previously announced c. £10m PBT guidance. Reason: working capital efficiencies and other one-off benefits which are not expected to recur. | ||
Yu (LON:YU.). (£314m | SR97) | Revenue +19%, adjusted EBITDA +4% (£24m), PBT -4% (£22m). Cash £129m. 25% growth in volume offset by reducing market prices in 2025. “On target to deliver Revenue, adjusted EBITDA and adjusted diluted EPS metrics for FY26 in-line with current market expectations, despite a backdrop of market uncertainty.” | NO VIEW (Mark) (our previous view: GREEN) There’s strong revenue growth but lower gross margins and increasing costs mean that it doesn't make it to the bottom line. Still, an inline FY guidance means H2 should be better. On a quant-basis this makes the shares look good value. However, looking at the Trustpilot reviews and the cash flow statement I have enough concerns that I would not own the equity in this company. Given that this makes it quite the dichotomy of opinion, I am going to give no view | |
Puretech Health (LON:PRTC) (£297m | SR23) | Royalty revenue $3.6m, operating loss $52.3m. Other income $159m (gains on investments). “We expect capital returns to play a more meaningful role in our allocation of future proceeds than they have historically.” Operational runway at least through the end of 2028, assuming no future monetisation events and full deployment of $70m to support Celea. | ||
B.P. Marsh & Partners (LON:BPM) (£241m | SR67) | Three new investments plus follow-on investment. Group funds £37.4m. Commercial insurance rates still declining, down 6% in Q2. “The Group’s focus on specialist and niche areas of the insurance market provides some resilience to broader rating pressures.” | AMBER/GREEN ↓ (Graham - I hold)
I have a modest stake here reflecting my very positive impression of BPM management, while also acknowledging that there’s a lot of trust involved. I’ve been GREEN on it and while personally I still have a lot of conviction in it as a long-term hold, I’m going to temporarily put us on AMBER/GREEN today, because it does seem to me that growth at key investment Pantheon Specialty has slowed down a little. Hopefully I can go back to GREEN soon, maybe even at the interims, when there’s a stronger update. | |
Mortgage Advice Bureau (Holdings) (LON:MAB1) (£222m | SR58) | Revenue +8.6%. Adjusted PBT +2.1% (£14.8m). Net debt £15.1m. Trading in line with recently revised expectations for 2026. “While the revision to our expectations for 2026 was disappointing, we continue to expect Group adjusted PBT growth of approximately 5% compared with 2025…” | AMBER = (Graham)
I remain a fan of this business, despite the Fluent Money disappointment. It’s a successful franchise business with the quality metrics to back it up. But it's now a heavily contrarian pick. Given how recent the profit warning was, I am going to leave us on AMBER today. | |
Serabi Gold (LON:SRB) (£205m | SR92) | results for the three-and six-month periods ended 30 June 2026 | H1 Revenue +60% to $100.1m, EBITDA +69% to $33.4m, PAT +59% to $30.1m. Net Cash $65.7m. 53koz production target maintained, but based on GUIA license being extended to 200kt, or full licence being awarded. Currently confident that the GUIA term will either be extended and / or the annual tonnage limit extended shortly by the ANM to avoid any temporary production interruption at Coringa in Q4-2026. Still anticipate full license in Q4. | AMBER/GREEN = (Mark - I hold) |
Henry Boot (LON:BOOT) (£189m | SR43) | H1 Revenue -19% to £80.7m, NAV PS -4% to 298p, Net Debt £132.9m (25H1: £108.0m). H2-weighting. Anticipate delivering profit before tax in line with consensus expectations for 2026 (£9.7m). Medium-term guidance remains suspended. | ||
M&C Saatchi (LON:SAA) (£177m | SR77) | H1 LFL Net Revenue -1.4% to £86.2m, Op Profit -32% to £6.2m, PBT - 21% to £4.8m. Net Cash £2.5m (25H1: £8.7m). FY LFL results expected to be in line with market expectations. | ||
Fonix (LON:FNX) (£167m | SR74) | FY26 Revenue +14% to £83.3m, Adj. EBITDA +11% to £16.2m (slightly ahead of market expectations), Adj. EPS +7.1% to 12.1p. U/L Cash £9.4m (2025: £9.9m). FY27: a return to double-digit growth in gross profit and adjusted EBITDA, ahead of expectations. | ||
Midwich (LON:MIDW) (£155m | SR59) | H1 Revenue +2.4% to £640.3m, Adj PBT +10% to £10.6m, Adj EPS +14% to 7.86p. Adj. Net Debt £138.1m (25H1: £148.2m), 2.4x Net Debt/EBITDA. Trading in line with the Board’s profit expectations for the full year. | ||
Diaceutics (LON:DXRX) (£145m | SR36) | ARR+79% to £29.4m, H1 Revenue +22% to £17.5m, Order Book +38% to £43.7m. LBT £3.97m (25H1: £3.01m LBT). Cash £8.1m (25H1: £10.4m. By the end of August pipeline coverage had increased to 107% of the FY 2026 median consensus revenue estimates. | ||
Record (LON:REC) (£85.6m | SR85) | Albert Soleiman appointed as Chief Financial Officer. Was CFO of CMC Markets for 17 months to February 2025. | ||
Microlise (LON:SAAS) (£57.4m | SR38) | ARR +4% to £60.8m. H1 Revenue -10% to £39.5m, Op Profit -19% to £1.4m, Adj. EPS -54% to 1.2p. Cash £13.8m (25H1: £11.2m). Confident in delivering FY26 revenues broadly in line with current market expectations and adjusted EBITDA in line with current market expectations. (Revenue in the range of £82.1-£84.2m, adjusted EBITDA in the range of £10.0- £11.1m. | ||
East Star Resources (LON:EST) (£52.3m | SR14) | LBT £224k (25H1: £756k LBT), Cash £2.26m (25H1: £737k) following £277k equity raise and £1.7m convertible loan issued. | ||
PCI- PAL (LON:PCIP) (£51.8m | SR52) | Formally confirm its reseller partnership with BT following announcement on 18 March. “With the sales pipeline now beginning to build and the first customers acquired under the partnership, the Company is now looking ahead to further activation activities and building momentum through FY27.” | ||
Portmeirion (LON:PMP) (£26.4m | SR50) | Adrian Wilding appointed interim CFO, succeeding Jonathan Hill, who has taken the decision to leave the business due to health reasons. | ||
Mission (LON:TMG) (£23.5m | SR81) | Revenue -3% to £33m, Headline Op. Profit +15% to £2.5m, Headline EPS +33% to 1.2p. Net bank debt £11m (25H1: £13.7m). Expects the Group to deliver against full year revenue expectations of £69.0m and to meet full-year headline operating profit of £8.0m and margin expectations of 12%. Non exec Chair, David Morgan, will step down from the Board on 31 Dec. | ||
Petro Matad (LON:MATD) (£22.4m | SR15) | PetroChina has now advised that internal discussions are still ongoing within its head office. PetroChina’s Mongolia subsidiary has said it cannot process Petro Matad’s invoices until these discussions are completed. Continues to manage its cash resources very carefully and has sufficient cash on hand to continue operating into 2027. | ||
Skinbiotherapeutics (LON:SBTX) (£19.4m | SR11) | Expects to report revenue growth of approximately 20.5% to £4.7m. Adjusted LBITDA expected to be £1.6m (FY25: LBITDA £1.7m). Cash £1.5m (2025: 4.8m). Trading in the early months of FY27 has been ahead of management’s internal expectations. | ||
Light Science Technologies Holdings (LON:LST) (£16.4m | SR11) | Received an additional order from a healthcare devices client worth £342k, with revenues expected to be recognised between November 2026 and February 2027. | ||
Oriole Resources (LON:ORR) (£14.9m | SR23) | PBT £0.99m (FY25: LBT £0.57m), Cash £1.48m (31 Dec: £2.50m) | ||
Sunda Energy (LON:SNDA) (£12.6m | SR-) | Placing and Subscription to raise £5.25m (before expenses) + Retail Offer for £0.525m |
Graham's Section
B.P. Marsh & Partners (LON:BPM)
Down 1.6% at 654.5p (£236m) - Trading Update - Graham - AMBER/GREEN ↓
[At the time of publication, Graham has a long position in BPM]
This is a handy little update from this investor in the insurance sector, covering H1 (February to July), mostly serving as an overview of the past six months.
BPM has a very long track record of successfully compounding its capital, and the process continues.
Overview:
Three new investments in H1, one disposal
One follow-on investment in Pantheon Specialty Group
“Robust pipeline of new opportunities, supported by attractive market conditions”
I mentioned the follow-on investment into Pantheon here and then here.
It’s important to highlight that BPM’s investments do not make for a particularly well-diversified portfolio, and Pantheon plays a big role in this lack of diversification. At the last full-year results, Pantheon represented nearly 30% of total assets:
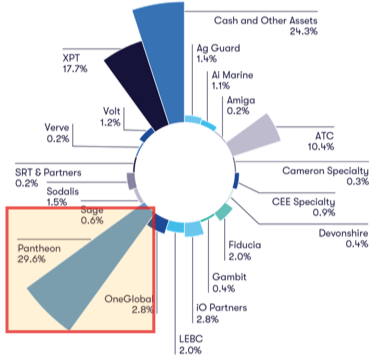
BPM now owns 41% of Pantheon, with the most recent investment happening at a £275m valuation. So that’s almost £113m of notional value now tied up in this investment (at the full-year results, BPM’s stake was valued at £107m).
If you’re interested in researching this Pantheon Specialty business in more detail, here’s its website. It launched in 2023 and is now a “full-sevice London market wholesale insurance broker”.
From today’s update:
Pantheon has established itself as a high-quality, scalable specialty broking platform, underpinned by an experienced leadership team and long-standing relationships with global brokers, MGAs and carriers…
Revenue is budgeted to approach £27.7m in the 2026 financial year, up from c.£23.8m in 2025. Margins remain strong and the business continues to generate significant cash, supporting further reinvestment and growth.
New business opportunities: there were “45 new business enquiries during the Period (31 July 2025: 32)”, I’m not sure how important this metric is for BPM shareholders - surely what matters is that there are a few great opportunities, and the number of new business enquiries is secondary?
Liquidity: cash has fallen from £49.5m to £37.4m. I’m totally comfortable with this, as excessive cash drag has been a risk here from my perspective. After some very successful investments and disposals in recent years, BPM has had more cash than it can deploy!
Cash outflows over the six months, rounding numbers for simplicity:
£10m of portfolio investments
£18m of loans to the portfolio
£13m of dividends to BPM shareholders
£1m of share buybacks
Cash inflows, again using round numbers:
£21m of portfolio disposals/defcon received
£10m of loans to the portfolio repaid.
This all seems pretty healthy to me. Cash is being used, rather than sitting idle, with a nice mix of cash flowing to and from the portfolio, and shareholders also getting paid:
The Board remains comfortable that the Group has sufficient resources to support the existing portfolio, pursue its current pipeline of opportunities and reward shareholders.
Insurance industry outlook: the insurance industry continues to see falling rates.
…global commercial insurance rates declined by 6% in the second quarter of 2026, following a 5% reduction in the first quarter and marking the eighth consecutive quarter of declining rates… The Group’s focus on specialist and niche areas of the insurance market provides some resilience to broader rating pressures.
If history offers any clue, I think BPM’s portfolio of MGAs/brokerages should do ok in this environment. Of course there’s no guarantee. But volumes seem to be more important than pricing.
Graham’s view
I have a modest stake here reflecting my very positive impression of BPM management, while also acknowledging that there’s a lot of trust involved.
I’m keenly aware that if they’ve made dud investments, I probably won’t be able to figure this out in advance. I’ll wake up some day to the news that some investees have gone bad and that net asset value has been written down.
The reasons I’m comfortable taking this risk with a small portion of my portfolio are:
The track record and integrity of management (which we’ve discussed before)
The discount to NAV.
NAV was £360m in January 2026.
Subtract £1m of share buybacks and £13m of dividends, and we are still left with NAV of £346m, before any valuation movements.
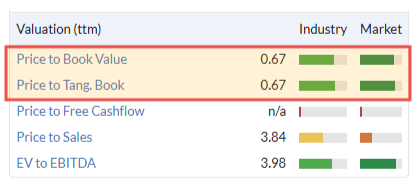
There are 36.2 million shares outstanding, so I get a NAV per share of 955.8p (Jan 2026: 959.8p). But we really need to see what else happens at the interims. But it seems like the discount to NAV at the current share price is in the region of 31-32% (or in pound terms, well over £100m).
Stockopedia gets a similar answer:
One word of warning: I do think that today’s update could be interpreted as a profit warning at Pantheon Speciality. When they made their follow-on investment into Pantheon in April, BPM said:
Revenue growth from c.£23.8m in the 2025 Financial Year to approaching £30m for the 2026 Financial Year
Profit before tax budgeted to be in excess of £15m in the 2026 Financial Year, representing significant growth since inception
Today they said “Revenue is budgeted to approach £27.7m in the 2026 financial year, up from c.£23.8m in 2025” and they didn’t provide any PBT estimate.
So the expected growth rate at Pantheon has been slashed from approaching 26% to only 16%.
It’s supposedly a high-margin business, so I’d still expect a decent PBT number. But perhaps it will be a little trickier to justify Pantheon’s £275m valuation on the basis of this year’s results? Just something to watch out for.
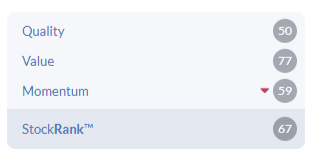
I’ve been GREEN on this and while personally I still have a lot of conviction in it as a long-term hold, I’m going to temporarily put us on AMBER/GREEN today, because it does seem to me that growth at Pantheon Specialty has slowed down a little.
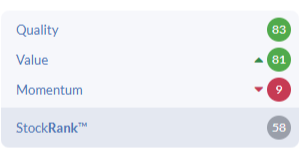
The StockRanks would approve of my more measured take:
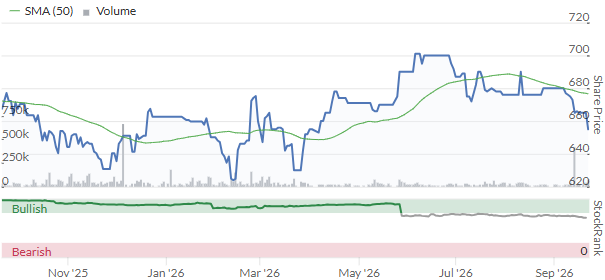
Hopefully I can go back to GREEN soon, maybe even at the interims, when there’s a stronger update.
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Up 0.5% to 385p (£223m) - Interim Results - Graham - AMBER =
Mortgage Advice Bureau issued an unfortunate profit warning earlier this month, covered by Roland.
Their adjusted PBT guidance for FY 2026 was cut from £43.4m - the consensus figure - to only £38m.
The main problem, as outlined by Roland, was slower-than-expected growth at specialist mortgage broker Fluent Money, for which it seems that MAB might have overpaid (they paid £72.7m for 75% of it).
Today’s trading update with the interim results is “in line with recently revised expectations for 2026”.
The overall picture seems pretty good to me:
H1 revenue up 8.6% to £161m
Adj. PBT +9.2% to £14.8m
Net debt £15m, leverage multiple 0.4x
They let us know that their market share of new mortgage lending is stable at 8.2%.
Comment by Founder-CEO Peter Brodnicki:
“MAB delivered a resilient performance in the first half, with total mortgage completions¹ up 16% to £16.5bn (H1 2025: £14.2bn), despite mortgage pricing volatility creating a complex environment for customers and advisers. Growth was led by refinancing, particularly Product Transfers, which supported strong activity levels but carry a lower revenue contribution than purchase lending.
Mr. Brodnicki points out that there is “increasing uncertainty around inflation and the path of borrowing costs” - a diplomatic way of putting it!
On top of the interest rate headwind, the “the activation and build-up of digital lead flows from Fluent’s partner relationships has taken longer than expected”. He still seems confident that Fluent will grow as expected, but on a longer schedule into 2027.
He also says that fixed-rate mortgage maturities in 2027 will be around 30% higher year-on-year. It’s important to bear in mind, however, that remortgages are lower-margin business than purchase mortgages/FTBs. In H1, “purchase activity was resilient but has yet to develop meaningful momentum”.
Growth in the mortgage market has been heavily biased towards remortgages rather than purchase:
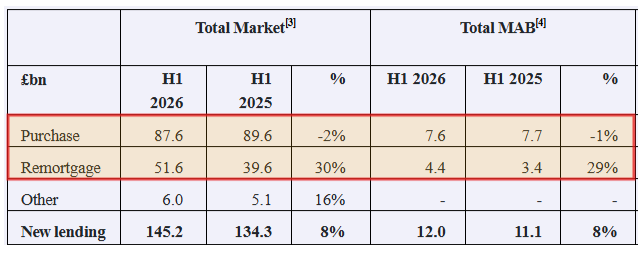
Given the inflation/interest picture, they “do not expect a meaningful recovery in purchase activity in the short term”.
Graham’s view
I’ve long viewed this as a quality business, and I think that today’s numbers continue to back up that idea, even on lower guidance.
The company continues to demonstrate decent KPIs:
“Productivity” (revenue per adviser) is almost unchanged from last year at £74,400.
Gross margin up 1.7 percentage points to 29.4% thanks to overall growth.
Adjusted PBT margin down 0.6 percentage points to 9.2% due to lower-margin refinancing activity and higher central costs.
However, the cash performance wasn’t great: there was only £12.7m of cash generated from operating activities (H1 last year: £17.6m), and net debt increased significantly over the six month period. This reflects £9m of dividends and various acquisition-related payments adding up to about £6m.
Graham’s view
I remain a fan of this business, despite the Fluent Money disappointment. It’s a successful franchise business with the quality metrics to back it up.
As a value play, I really like it and I’m tempted to add it to my personal portfolio:
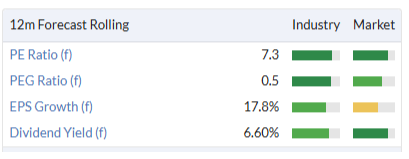
But it’s no surprise that I’m tempted: Contrarian is my favourite investment style. And this is now a heavily contrarian pick. Given how recent the profit warning was, I am going to leave us on AMBER today.
Mark's Section
Serabi Gold (LON:SRB)
Flat at 271p (£205m) - results for the three-and six-month periods ended 30 June 2026 - Mark (I hold) - AMBER/GREEN
[At the time of publication, Mark has a long position in Serabi]
The six-month results look pretty strong here:
EBITDA for the six-month period of $44.4 million (corresponding six-month period of 2025: $26.3 million).
Profit after taxation for the six-month period of $30.1 million (corresponding six-month period of 2025: $18.9 million).
Earnings per share of 39.71 cents (corresponding six-month period of 2025: 24.99 cents).
It is worth noting that these would have been even stronger if they had sold as many ounces as they had produced. Roughly 1,700 ounces went into inventory. This is normal for a gold producer where gold is transported and sold in batches. However, this gives some variability in results as the vast majority of costs are typically incurred in the mining and processing, not transport and refining.
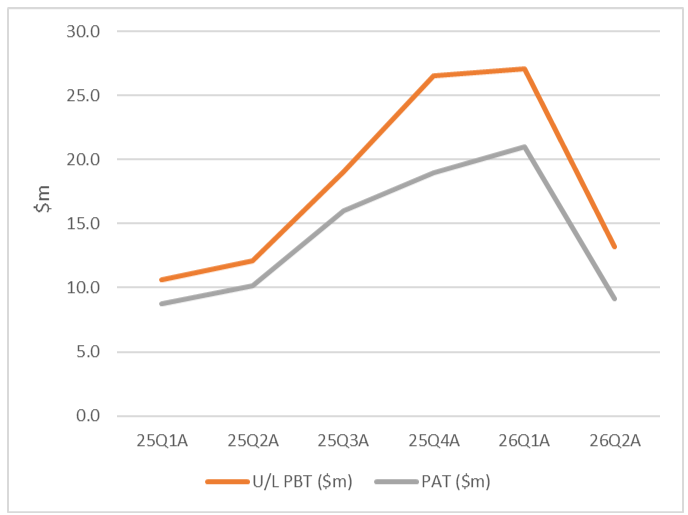
However, this is very much a tale of two quarters. The EBITDA for the 3 months to 30th June was $15.2m versus $29.2m for Q1. PAT is back to the levels of last year, when the gold price was around $3k/oz:
Part of this is increased tax rates, and there is some good news on this front today:
Superintendência do Desenvolvimento da Amazônia ("SUDAM") has formally approved the renewal of the Corporate Income Tax (IRPJ) reduction incentive for the Palito Gold Complex ("Palito"), located in Pará State, Brazil.
With this approval, the Brazilian nominal corporate income tax rate applicable to Palito will be maintained at approximately 15.25% (reduced from 34%), extending the benefit for an additional 10 years, through 2035.
This actually has a significant positive impact on the long-term NPV for Serabi.
However, the real negative impact on this quarter was rising costs:
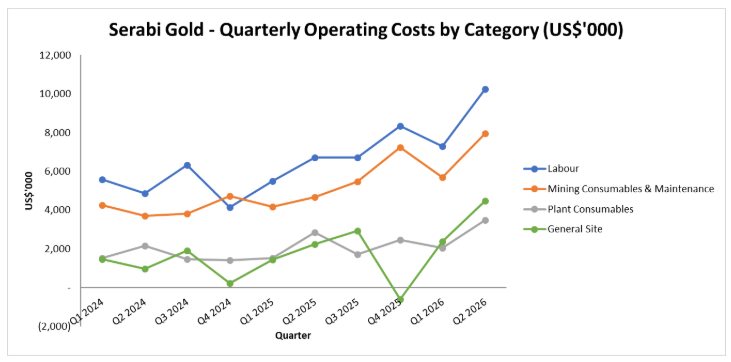
This is what they say about this in their more detailed Q2 report on their website:
Operating costs are 45% higher than the same period of 2025 reflecting the 9% increase in ounces sold as well as the strengthening of the Brazilian Real in comparison to the US Dollar. Specific cost increases reflect higher plant and site costs, including increased diesel consumption for power generation, elevated use of processing consumables, and expanded site infrastructure and maintenance activities.
One of the big impacts will be diesel prices, given they operate the plant via generators and truck Coringa ore. Plus, labour costs will be sensitive to the exchange rate. So these rises are perhaps understandable. However, given the scale of the increase, I would have liked to see more commentary on these. Guidance on whether these costs are now the new normal or due to one-off factors would be particularly useful.
One positive point is that both sites are planned to connect to grid power in 2026, which should reduce the exposure to diesel prices. However, if this had actually happened by now, I think they would have told us.
Of course, costs are not the only worry that has held back Serabi’s share price in the last year. Investors have become increasingly worried about the company’s license to operate at Coringa. The company has become increasingly reliant on Coringa ore over the last 18 months:
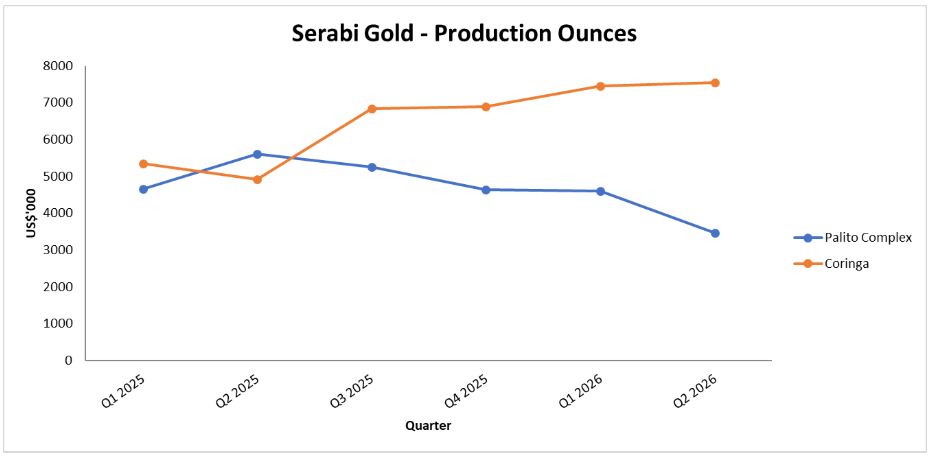
Indeed, the company’s guidance of 53k was reiterated today, and it specifically mentions this as a risk:
As the Company reported in the Q2-2026 operational update, production guidance is set at 53,000 plus ounces of gold. This target has been based on one of either of two assumptions. Firstly, the GUIA licence issued for Coringa from the ANM (Ministry of Mines) under which the Company is currently permitted to transport annually 100,000 tonnes of ore to Palito was to be increased to 200,000 tonnes. Alternatively, the guidance target also assumed receipt of the full mining concession by Q4-2026, thereby lifting all tonnage constraints at Coringa. In both scenarios, the Company would be able to transport much greater volumes of ore in Q4-2026 and utilise the soon-to-be-commissioned fourth ball mill at Palito.
I may have been a bit dim before, but I think this is the first time I’ve realised the link between guidance and the license. The problem appears to be that they will max out their tonnage before the end of 2026 and hence have to rely only on Palito ore.
However, in both cases - an extension of the existing temporary license and the issue of the full license - the company appears to be confident these will arrive. For example, on the full license:
With respect to the Full Mining Concession, the two fundamental approvals required are in their final stages. The approval of the Indigenous Component Study (ECI) is now very close, and it only remains for the Federal Agency for Indigenous Lands (FUNAI) Board of Directors to approve the study. The FUNAI Legal and Technical departments are recommending approval. We still anticipate this happening in Q4-2026. In addition, the approval for the change of land use from Agriculture to Mineral Exploitation by the Land Registry (INCRA) is also now in its final stages, which has been technically and legally approved. The final steps are for the Directors of INCRA to approve at the Board level of INCRA. The Board of Serabi also anticipates this happening in Q4-2026. Once these two approvals from FUNAI and INCRA are received, SEMAS can issue Serabi with an Operating Licence.
This sounds positive to me, and would be a game changer. I suspect that this will slip beyond the end of the year, given the way bureaucracy tends to work. However, even with a short delay, the ability to use unlimited amounts of Coringa ore in the future would catapult production upwards.
Forecasts:
Where does this leave us?
Given the progress, I think they will keep Coringa going, but I have to raise my cost estimates to match the Q2 numbers. However, I can be more relaxed on tax rate assumptions:
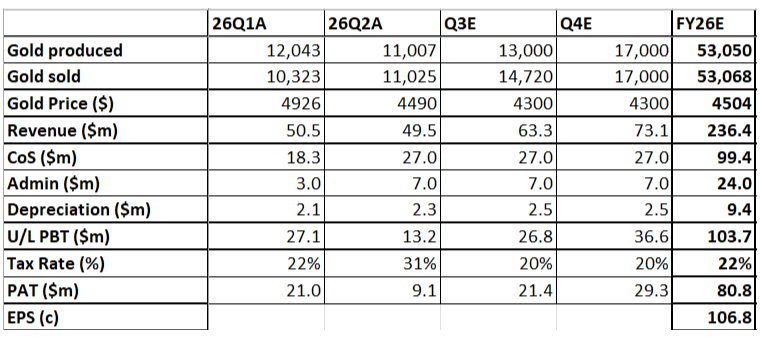
This gives around 107c for FY EPS, quite some way short of 137c in the Stock Report, so on one level, this could be considered a miss.
However, I would expect net cash to build to somewhere around the $100m mark by year-end despite increased exploration spend. The market cap is around $273m, giving an EV of around $173m and an EV/EBIT of around 1.7x.
FWIW, I still get an NPV10 of at least double the current market cap at the current gold price, with a shift in tax rates largely offsetting the near-term higher costs.
Mark’s view
This is a bad news/good news update for me. The cost increases in Q2, combined with relatively weak production from Palito, have meant profitability declined significantly in Q2. I think we have to assume that these cost levels are the new normal, at least until grid power connection is confirmed.
However, there is good news on the tax rate and progress appears to be being made on the key license issues. There is certainly a short-term risk that they don’t get one of these options in before they have to stop trucking Coringa ore, which would negatively impact short-term results. However, I think the risk that Coringa will never be able to provide ore to Palito in the future is low.
The company continues to trade at a very low valuation multiple, even assuming Q2’s costs are the new normal. On a forward EV/EBIT of less than 2, I think we should remain broadly positive. AMBER/GREEN
Luceco (LON:LUCE)
Down 6% at 222p (£378m) - Interim Results - Mark - AMBER/GREEN ↑
When I previewed these results on the Week Ahead, I noted the revenue and operating profit figures were given in the trading statement, so the three key things to watch were second-half guidance, adjustments, and cash generation. Let’s go through each one:
Second-half guidance:
With only £15.8m of operating profit booked in H1, there was a clear H2-weighting required to reach the £40m full-year guidance. So it is especially good news that the outlook is upgraded today:
The Board now expects Adjusted Operating Profit for 2026 to be ahead of market expectations.
The only research I can see is from Longspur. They increase their adjusted operating profit estimate from £40.9 to £41.9m. This is just a 2% upgrade, so it is perhaps more a reflection of the tightness of the range of broker estimates (which were given as £40.5m to £41.0m, before this update).
Still, it shows trading momentum behind the business. They don’t break it out as a segment, and this is already known, but it's worth repeating that the growth here is largely driven by EV charging infrastructure:
Growth engine of Energy Transition delivered growth of 119.5% year-on-year, with the core business continuing to perform well with growth of 6.5%
Last year, core organic growth was negative, and the UK housing market is going through challenges, so I think even 6.5% core organic growth is reasonably positive.
Adjustments:
They didn’t make an acquisition in the period but still managed to book £0.4m of acquisition costs, so this bears watching closely in the future. The rest of the £2.0m will be amortisation:
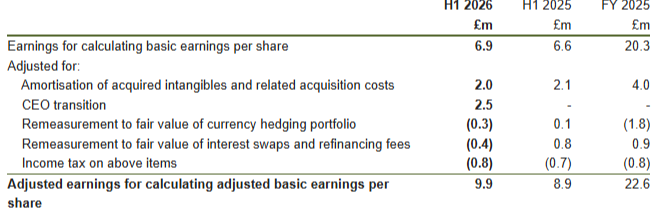
Perhaps also worrying is the appearance of a £2.5m charge for CEO transition. This is described as:
All costs associated with transition from prior to new CEO, including remuneration, recruitment and share-based payment charges
It surely doesn’t cost £2.5m to search on LinkedIn and run a few interviews. So my fear here is that there has been some kind of golden hello or goodbye. A look at the cash flow statement shows Share-Based Payments jump from £0.7m to £2.4m, so the bulk may well be SPB. This may well be new CEO options, but if so, why not say this? It seems to me that a retiring CEO who owns 15% of the company shouldn’t need incentivising to remain involved in hand-over, via options or anything similar. Until we can see more detail in the annual report, this is a black mark for the board, in my opinion. The good news is this should hopefully be a one-off.
Cash generation:
Net debt is up slightly, but the leverage ratio is down because EBITDA is higher.
Working capital flows are largely behind this, with £8.8m going into inventory and other minor changes taking a £19.4m operating cash flow figure down to just £7.2m after working capital.
Cash taxes and investment activities meant free cash flow was negative for the period, and the dividend and share buyback were funded out of debt.
They upped the interim dividend by 17%, so they must feel confident that these working capital flows will reverse in H2. This is one aspect to keep an eye on, as the debt level has worried the market (unnecessarily IMO) in the past and saw the shares dip as low as 70p in 2022 due to these concerns. Another concern is that debt levels may constrain acquisitions, which have historically been one of their main growth engines. (SyncEV, which is now behind the revenue growth in 2026, was acquired in 2022.) They say they continue to “...pursue selective bolt‑on acquisitions, consistent with our capital allocation policy.” We are more likely to see some minor additions than a game-changing acquisition.
Valuation:
Despite a 91 Stock Rank, the Value Rank is low enough that the algorithms classify this as a High Flyer, not a Super Stock:
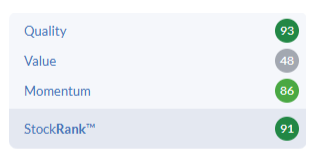
Despite today’s minor upgrade (Longspur go to 17.7p EPS versus 17.5p consensus in the Stock Report), the forward P/E is 13. This is around the middle of where the stock typically trades:
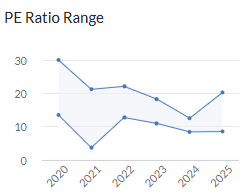
This may be why the market has sold off on today’s upgrade (a jump in the share price yesterday in anticipation of these results may also have been a contributor)
However, I have always been a fan of the company’s execution. The business itself sounds rather mediocre, but the quality metrics are great. They consistently generate returns on capital in excess of their cost of capital and, through organic and inorganic growth, have delivered significant shareholder value over the years. In light of this, a forward P/E of 13 perhaps looks like good value.
Perhaps more worrying is the lack of enthusiasm from Longspur Research. Their note is described as a marketing communication, which means that it is corporate-sponsored equity research. In such cases, investors may expect a certain optimism in valuation methodologies.
This research is no different, as they choose to use a 8.5% discount rate, saying:
We have valued Luceco using a DCF approach with a discount rate of 8.5% using the median beta of comparator companies. In our central case valuation, we have assumed healthy performance of the core business, combined with strong growth in the Portable Power segment coming from the Energy Transition (EV charging). This gives us a central case valuation of GBp 257 per share. Our low case assumes 3% revenue growth with flat margins from FY27-FY30, giving a valuation of GBp 206. In our upside valuation, we have modelled revenue growth and margins increasingly supported by Energy Transition contribution. This gives an upside valuation of GBp 282.
Typically, this can be thought of as the return investors would accept to hold the company's equity. The historical returns of the stock market as a whole are around 10% pa, which is why many DCFs use a 10% discount rate. Should we consider Luceco to be less risky than the wider market, and hence accept a lower return? I’m not sure about that, given the debt and cyclical end markets, regardless of what the “median beta of comparator companies” is!
Anyway, with this discount rate, they come up with a range of 202-282p. Their price target is just 16% above the current price, which doesn’t seem like a big return to aim for.
From what I can tell, other brokers such as Peel Hunt and Jefferies have Price Targets above £3/share, but without seeing the assumptions used to get there, I deploy a certain amount of scepticism.
Mark’s view
Despite a rather lacklustre upgrade, at least from the one broker we can see, this is a company trading ahead and on a reasonable rating. I have a few concerns regarding the CEO transition costs and the short-term cash generation. However, I continue to rate their execution very highly, and this strength is reflected in a return on capital consistently above their cost of capital.
We have been neutral here most recently, reflecting the retirement of the long-running CEO and the subsequent sale of some of his shares. However, with a new CEO in place and given the current positive trading momentum, could we afford to be a bit more charitable with our view? I think we could. AMBER/GREEN.
Yu (LON:YU.)
Down 4% at 1,731p (£314m) - Results for the six months to 30 June 2026 - Mark - NO VIEW (our previous stance: GREEN)
This is a strong half for this energy supplier to SMEs. Meter points supplied was up 43%, energy supplied rose 25%, leading to a 19% increase in Revenue.
However, things are less rosy as you go down the income statement. Adjusted EBITDA only rose by 4%, and PBT declined by 4%.
They have been hit by both a reduction in gross margin from 13.6% to 12.6% and operating costs rising by around 19%.
However, they say they are trading in line for the full year, which would see EPS rise by around 5%.
The Group is on target to deliver Revenue, adjusted EBITDA and adjusted diluted EPS metrics for FY26 in-line with current market expectations, despite a backdrop of market uncertainty.
Plus cash flow appears to be reasonable, delivering £38m of operating cash in flow (only slightly down from £40m last year).
My concerns:
However, the good news appears to end there. I have to say I am not an expert on energy company accounts but a few things stand out from the cash flow statement.
There are two big numbers, and both have jumped:
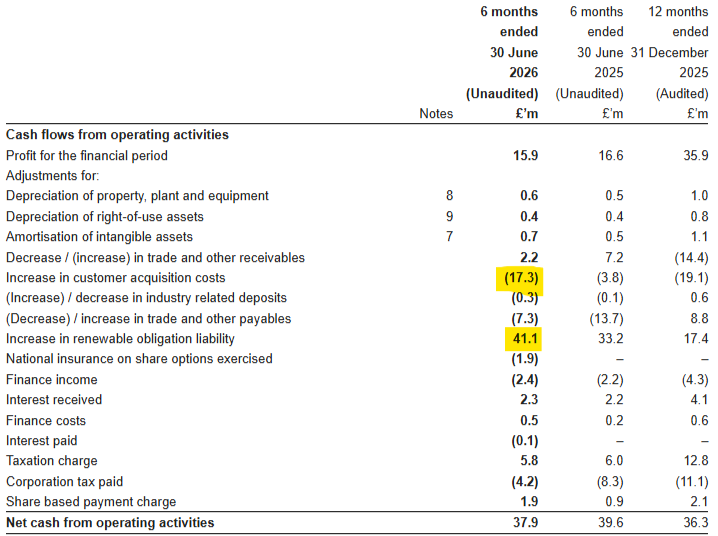
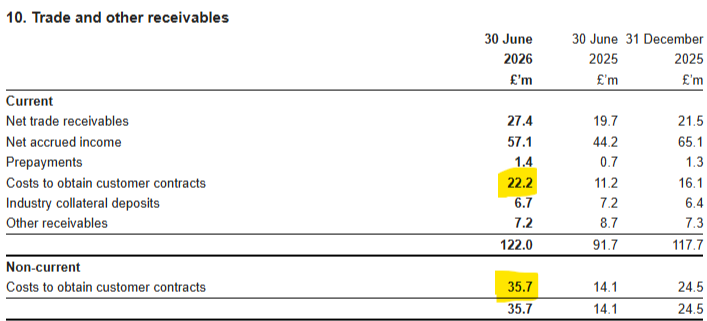
Firstly, they appear to be capitalising customer acquisition costs. While this may be perfectly normal accounting practice, I personally don’t like this. It can flatter profits, especially for a company pursuing growth.
Secondly, they may have booked the costs for paying the renewable obligation but not yet paid this out.
The risk is that the benefits from the customer acquisition may prove illusory and the costs of the renewable obligation very real.
In both cases, the absolute value of these is increasing on the balance sheet, making the risk greater over time:
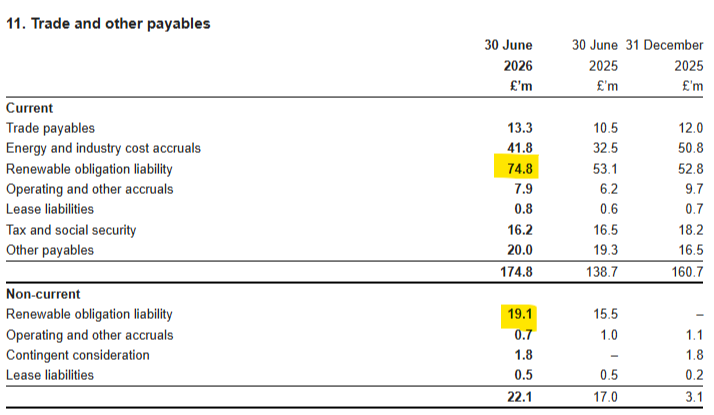
I have no idea if any of this is realistic. However, with these sort of characteristics, I’d want the company to have a spotless reputation in every other sphere. The 5% decline in their Trustpilot score from 3.8 to 3.8 on their highlights a potential issue.
I know the temptation is to only leave a review when things go wrong, but some 25% of all reviews are 1*, and Yu have a paid Trustpilot subscription which means they actively ask customers to leave a positive review.
I won’t repeat what the accusations of the 1* reviewers are because I cannot independently verify them. However, if just some of these are accurate then it gives me some very serious concerns.
One thing that may back up these concerns is the large level of doubtful debt as a proportion of trade receivables:
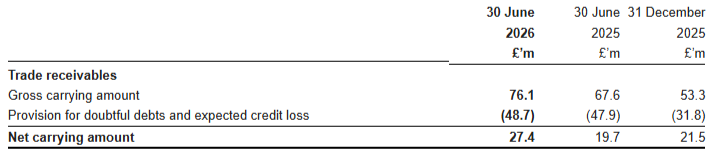
This may well just be because SMEs are struggling with high energy prices at the moment. The company say that they have a “consistent performance on customer bad debt.” However, it may also be a sign that many customers don’t believe they owe Yu what they claim they do. I just have no way of making a judgement on this either way.
The counterpoint:
Despite a hard to fully untangle cash flow statement, the company pays an increasing 4% dividend and has £128m of net cash. It is hard for things to go that wrong that these don’t give investors a significant buffer against adverse outcomes.
Mark’s view
I’ve got to say, I’m in a bit of a quandary. I respect the views of my fellow commentators greatly, which is why we so rarely see big changes of views on the DSMR, despite multiple writers. Roland upgraded this to GREEN in July following the trading update that produced these results.
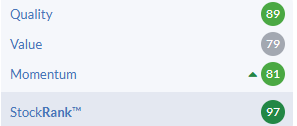
The truth is that if the reported profit numbers are an accurate reflection of the long-term cash flow generation of the business then the current valuation should make the investment case a strong one:
However, would I own shares here given those TrustPilot reviews and the cash flow statement? Absolutely not.
In light of this I’m going to cop out and give it NO VIEW.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Kingfisher (LON:KGF) Looks like an upgrade, does this mean your Amber Green on this is now Green - IMO Id much rather have more RAG status's in the Summary section than too many big detailed analysis ones
Anyone with an interest in Weight loss drugs going forward may want to read the Edison report which does mention IP Group being a client etc
https://www.edisongroup.com/th...
Interesting Martin. I have held IP (LON:IPO) in the past and have been watching it, so this is useful. Maybe post on the Investment Trust thread as well- not a I.T but there are holders on the thread.
Serabi Gold (LON:SRB) today reported revenue grew 60%. Shares down 5%. Make sense of that.
Graham already has
Re Serabi Gold
As with any gold miner there are a lot of moving parts with costs, licences, remaining life of mines and of course, geo political risks.
Also the issue of it being an AIM stock where price movements can be very random.
Serabi was a long term hold for me until I sold at the beginning of September.
Looks like a great buying opportunity now - this looks so cheap on most metrics
Would the team be able to take a look at Diaceutics (LON:DXRX) today? Thanks
DXRX, although signals inline, displays excellent traction.
HY update said 91% of FY revs were covered by order book and weighted pipeline (HY25 79%)
Interims report this figure has now increased to 107% of FY (end Dec) expectations
Usual H1/H2 weighting due to US pharma knowing what's left in their end of year budgets towards the end of year. Also means potential to add further sales
ARR £29.4m (+79%)
NRR 149% (118%) - significant as customers who left or paused in 2025 returned and increased their spend - strong validation of the value of DXRX model.
Organic growth only
There are many additional positives in this update so worth reading
High probability of an FY beat.
(Long term holder so biased)
Most bullish company reporting today, and probably the cheapest with nearly half the market cap in cash, surely has to be Aeorema Communications (LON:AEO), but maybe a bit small for comment?
Not many positives from the M&C Saatchi (LON:SAA) results today.
I've been having my eye on this company for a while now. Think they have some gems inside, masked by the weaker advertising divisions, and overseas problems.
Think they need some more radical restructuring and strategic focus. However, you don't get the sense that is happening from today's results. Trading performance is poor. Financials are not rock solid (albeit in a bad place either). So hard to see any catalysts here that could transform their prospects? Vin Murria took a board seat recently but so far not delivering results yet.
With these numbers, I wouldn't be surprised if the SP floor is closer to 100p than the 136p its at now, as disappointed shareholders continue to exit until the next set of updates.
Kingfisher (LON:KGF)
Well shock KGF produces a half decent set of results or more likely Screwfix does. I was, yesterday, stuck behind a VLT ( very large truck) embossed with Screwfix same day delivery so just in time maybe going well for them. If one judges Wickes as a comparator ( with B&Q) on the competance of your local store and its footfall, here in Shrewbury we have both, within half a mile. B&Q is messily laid out has far too many products and is more expensive relative to Wickes which here seems to attract more trade footfall. The B&Q trade area is always deserted when I go in and as for customer service well finding someone who knows where a product is.......... Wickes wins on all counts
If only KGF would demerge Screwfix there maybe a decent business in which to invest
I echo your thoughts on Wickes vs B &Q. No doubt the experience varies up and down the country, but my local B&Q is one of the giant warehouse type ones. They only have a couple of tills, most of the time unmanned, and 3 self checkouts. The queues are usually enough to make you want to give up!
It mystifies me how the very efficient Screwfix can be owned by the same company as B&Q!
Same in Norwich bare bones staff and self service tills which I don't have a huge issue with but if you have people in front unfamiliar with the protocol it can be a nightmare.
Hello Graham, will you be doing a deeper dive into LON:BPM by any chance? I would be interested in your and others for their opinions. I am a holder for the longer term.
B.P. Marsh & Partners (LON:BPM)
I think its hard to gleen anything of material value out of the trading update today - genrally ref these updates - on quick skim read it all seems fine and dandy. With glut of sales the last couple of years banking good gains - i dont see there necessarily being any huge material progress (nav uplift) until they have their next big payday.
Note it will be the results time where the all important proof of then pudding is delivered - its only really about then fully diluted NAV here - not too long to waiot till we get that more tangible update. With it being mostly tickover i am not expecting outsized gains - they can revalue portfolio though so perhaps there may be pleasant surprise ref NAV. Note there seems to be some headwinds at present ref theie wider market segment - text below. I think the companies they invest in have tended to outperform the market though so no reason to worry.
It seems as good value now as it has been last few years - albeit their investments need to perform going forward thats never a given in that regard they have not dissapointed up till now for me.
The Group continually monitors key rends across the wider risk transfer market, particularly premium rate developments and M&A activity. According to the Global Insurance Market Index published by Marsh Limited (“Marsh”), global commercial insurance rates declined by 6% in the second quarter of 2026, following a 5% reduction in the first quarter and marking the eighth consecutive quarter of declining rates.
By product line, global property rates declined by 12%, while casualty rates increased by 2%, including a 7% increase in the US. Financial and professional lines rates declined by 3% globally, while overall UK commercial insurance rates fell by 8%. The Group’s focus on specialist and niche areas of the insurance market provides some resilience to broader rating pressures.
Hi RM I hold B.P. Marsh & Partners (LON:BPM) as well indeed it is my only PE exposure if you want to term it as such . I take the view they know what they are doing, judging by buy outs etc. I think their contact book on new business funding is very hard to criticise. A strong hold for me whilst being aware that the insurance cycle never goes away......
thank you
thank you
Hi Mark, I did indeed cover BPM! Was very interested as I'm also holding it. Any feedback v. welcome. G
Thank you Graham. My thoughts: I think we're in a soft environment in the Lloyds market, so I would not be surprised if we see the SP weaken and I see that as an opportunity to buy more shares. The sun will shine again, I don't think it's possible to say when. I like the history of the company which shows good management so I'm comfortable holding this for a long time unless something fundamentally changes with the management.
Press release, but no RNS, from Filtronic (LON:FTC) this morning. Goodness knows what the financial implications are.
https://filtronic.com/news-eve...
Filtronic (LON:FTC) Yes I saw this as well ( I hold). UK Government funding usually comes with caveats. One wonders what those are
The Fonix (LON:FNX) PE and P/FCF does'nt look expensive for a business with 95% UK market share, no debt, terrific ROCE, zero customer churn, 3 new markets generating income, and a CEO who in the RNS just said, "I have never been more confident in Fonix's ability to deliver its next phase of growth." I hold.
looks good I hold
Fonix (LON:FNX)
The prelims read well. Looks very interesting. A founder led capital light business that appears to be executing well.
Would welcome a view from Graham and the team.
I would add my vote for Graham and team to cast their eye over this.
Yep, finally some traction!! Held a while, divs always nice
Fonix (LON:FNX)
I have been an interested observer for quite a long time as I am always on the look out for additions to my income ' portfolio. I am going to listen to the presentation this PM and take a view. Potentially well placed to benefit from growth in the ' prize' mentality that is seemingly gripping the nation. Never been sure about the ' moat' here and hard to see this as anything but an income play
Pobably should add, one wonders how secure the contract is with ITV given the broadcasting sale to Sky?
Be interested in how the presentation went during the afternoon yesterday (if that's ok to ask?)
Porvair (PRV) 9 month trading update. https://www.londonstockexchang...
nice one Via, I've added that to the table! thank you.
Good morning Graham!
Decent looking results from both Yu (LON:YU.) and Luceco (LON:LUCE) today.
It would be great if we could get the team's views on these.
I second that. Slight concern that outgoing CEO Luceco (LON:LUCE) has circa 12M shares that he’s been selling.
Luceco (LON:LUCE) Including very recently, before todays update. Surely that falls within a closed period ? Isn't that illegal ? He will clearly have been aware of the contents of the update (and that the very strange golden goodbye would provoke a fair amount of market incredulity)
good morning Felix - I've taken note of that! cheers. G
Tough initial reaction by the market to Luceco (LON:LUCE) and Yu (LON:YU. Very low volume ATM. Keen to hear your thoughts and let's see if there are any broker comments later.
Luceco (LON:LUCE) was up nearly 5% but now down over 6%.
Yu (LON:YU.
I dont think the price movement is a huge shock - share has had a nice run up into results - bottom line Profit After Tax is down on comparative and down on average for last year. Overdu customer invoices up a tad too (7%) - so its not uncommon for their to be pullback on the day despite company being on track - perhaps a tad annoying with cheap rating.
So overall its not super shouting out buy me - note there seems to be some decent stuff there ref operational progress - so hopefully its just simply lower energy prices = lower profits.
I have only recently bought in here - with pe of under 8 ish - decent cash in the bank and expectations trending up into 2027 i dont see anything not to like here if we accept the bottom line profit delivery is anemic at best and leaves work for H2.
Note they currently have very decent growth factored in for 2027 - so perhaps those growth ambitions at soem stage might need to be moderated - either that or share perhaps should rerate as long as 2027 isnt simply bumper year.
Happy to carry on holding this one here presuming there are no nasties from what brokers say and update. Note i would say i dont particularly expect premium rating here being the sector it is - company probably has to deliver profits and cashflow of said profits before the market will give the company then benefitof believing it.
Yu (LON:YU.) solid if unspectacular, a tad disappointing
Yu (LON:YU.)
a tad disappointing
well they are on target for year end as things stand and comments about future look ok - so unless you were expecting outperformance or less second half weighting (ok thats a danger perhaps) - the fact they are on track is ok for me.
ref future
Meter growth remains on plan with our aspirations to secure a 7-9% market share by 2028. We remain optimistic with a strong contract book running into 2027 underpinning our growth ambitions.
Kingfisher (LON:KGF) raises guidance. ScrewFix doing particularly well. Does this mean DIY and small building projects are increasing due to the high costs of moving? When people don’t move they renovate. I expect a positive SP reaction today. I hold.
People will be careful not to renovate their properties into the wealth tax bracket. If the threshold for that is lowered in the upcoming budget, that could put many projects on hold would be my guess.
Really doubt that is the first thing people think about when the roof is leaking.
Marshalls (LON:MSLH)
Agreed, but you might delay an extension and large improvements. I’m a holder so hope that’s not the case!
Interesting thought. If I demolish the third bathroom on my mansion and take the roof off staff quarters will it be tax efficient? Has govt a new cunning plan to disrupt/destroy housing market?
What I don't like about Kingfisher (LON:KGF) is that net debt is well over four times operating profit.