Daily Stock Market Report (Tue 25 Mar 2025) - MGNS, AO., ABDP, MPE, TIME, GAMA, POLN, KGF, JNEO, MBH, FEVR, PGH, TON, XAR

Good morning! We're expecting a lot of results announcements today, please stay tuned!
Phew! I think that's everything - let us know if we missed anything.
1pm: all done for today! Thank you for reading and thanks to Roland and Megan for making this truly a team effort today.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
SEGRO (LON:SGRO) (£9.4bn) | JV to develop a £1bn data centre | JV with Pure DC for 56MW / £1bn data centre in Park Royal London. Expect to pre-let to hyperscaler. | |
Smiths (LON:SMIN) (£6.8bn) | Interim Results | Organic rev +9.1%, improved margins with adj EPS +14%. Full year guidance unchanged. | |
Kingfisher (LON:KGF) (£5.0bn) | Full Year Results | In line. LFL revenue -1.7%, adj PBT -7% to £528m. FCF stable at £511m. Share gains in main mkts. | AMBER (Roland) Kingfisher is arguably cheap and has a growing trade business. The group also continues to generate plenty of cash. On the other hand, a lack of growth highlights cyclical exposure, while onerous lease liabilities suggest a possible drag on future cash flow. I’m neutral at this level. |
Bellway (LON:BWY) (£2.9bn) | Interim results | In line. Completions up 12% to 4,577. Rev +12%, adj PBT +12% to £150m. Outlook unchanged. | |
Morgan Sindall (LON:MGNS) (£1.5bn) | Trading Update | Strong trading in Fit Out division means FY25 results to be slightly ahead of consensus. Other divisions are “broadly on track to perform in line”. | GREEN [no section below] (Roland) Upgrades to guidance are almost routine for this well-run and founder-led construction group. The shares have pulled back somewhat recently and look reasonably priced to me on a P/E of 11. The StockRanks concur at 98/100. |
Gamma Communications (LON:GAMA) (£1.2bn) | Full Year Results | In line. Rev +11%, adj EPS +13% to 85.1p. Growth in all business units. Confident outlook. | GREEN (Megan) I always long for something a bit more exciting from Gamma, but perhaps steady boring growth is all this company really needs to deliver. The numbers for FY2024 are as solid as ever. |
Fevertree Drinks (LON:FEVR) (£938m) | Full Year Results | Group revenue flat despite 12% growth in the US (the group’s largest market). PBT rose by 60% to £35.5m. This was mainly due to glass costs and freight rates normalising, generating a £17m saving.Outlook bolstered by strategic partnership with Molson Coors, but 2025 guidance unchanged for low-single digit sales growth and reduced EBITDA margin, as the US business transitions. | AMBER (Roland) [no section below] Fevertree has a strong brand and continued US growth potential. But it’s not clear to me if the company can regain the high profitability seen in the past. Last year’s 10% operating margin is fine for this sector, but a long way from the 20%+ seen prior to 2020. There could be a long-term opportunity here. But with the stock trading on a P/E of 30 and a flat earnings outlook for 2025, I’m most comfortable taking a neutral view at this point. |
A G Barr (LON:BAG) (£695m) | Full Year results | Operating margins widening ahead of plan to 13.6%. Sales +5% and adj pre-tax profits +16%. | |
AO World (LON:AO.). (£556m) | Trading Statement | LFL rev +7% to £1.1bn. FY adj PBT +30%, around “top end of guidance”. | AMBER (Graham) [no section below] |
M P Evans (LON:MPE) (£500m) | Full Year results | Revenue +14.8% to $353m, reflecting 13% increase in average mill-gate CPO prices to $823/t and lower fertiliser costs. | GREEN (Roland) [no section below] I think this is a good business with scale and a very respectable record in this sector. Sustainable oil increased to 69% of output last year and mgt are targeting further increases. Today’s 16.7% dividend increase to 52.5p maintains a record stretching back over 30 years. With y/end net cash of $46m, MPE is in a good position to make acquisitions. Palm oil pricing is a risk, but broker Cavendish has upgraded FY25 EPS estimates today, albeit below FY24 record levels. I remain positive given the strong balance sheet and track record. |
Pollen Street (LON:POLN) (£437m) | Full Year Results | Ahead of exps. AUM +29% to £5.4bn. PBT +24% to £49.6m. EPS 78.8p. Confident outlook. | GREEN (Graham) I'm upgrading my stance on this as I'm finding nothing to dislike and plenty to like about the growth story at this private equity and private credit fund manager. |
Warehouse Reit (LON:WHR) (£435m) | Final possible offer from Blackstone of 115pps/£489m. | Offer represents 39.6% premium to 24 Feb 25 close, but is 10% below Sept 24 NAV of 127.5pps. | |
Ashtead Technology Holdings (LON:AT.) (£433m) | Full year Results | Acquisitions contributed the majority of the 52% revenue growth (organic revenue +14%), which ‘exceeded financial and strategic objectives’. | |
Ab Dynamics (LON:ABDP) (£427m) | Trading update | In line with guidance updated in November for the year to August 2025. First half revenues +11% to £58m thanks to strong order growth especially from the Asia Pacific and North American regions. | GREEN (Megan) [no section below] I still miss the days of wonderfully high quality metrics at AB Dynamics, which have been eroded by the company’s long list of acquisitions in recent years. But the growth brought in by these acquisitions is exciting. A series of earnings upgrades in the last few months means EPS is now expected to rise 26% in FY2025. Management has set out ambitions to get operating margins back towards 20%. I’m staying positive. |
IP (LON:IPO) (£423m) | Full year results | NAV declined to £952m (down 15% per share). Cash proceeds from exits of £183m. | |
WAG Payment Solutions (LON:WPS) (£409m) | Full Year Results | Net revenue +14%, adj PBT -18% to €46.3m due to higher finance costs. FY25 outlook in line. | |
FD Technologies (LON:FDP) (£367m) | Trading Statement | Ahead of exps. ARR +13% to £81.8m, contract value added +33% to £18m. Losses reduced. | |
Henry Boot (LON:BOOT) (£283m) | Final Results | In line with expectations after stronger second half. Land and property sales marginally lower at £224m. NAV per share +3.6%. | |
Tullow Oil (LON:TLW) (£204m) | Full Year Results | Revenue and capex marginally down at $1.5bn and $231m. Net debt reduced to $1.5bn. Drilling resumed at key oil wells. | |
Regional REIT (LON:RGL) (£169m) | Full Year Results | EPRA NAV +17% to £340.7m. LTV reduced to 41.8% (FY23: 55%) through £100m placing. 7.8p divi. | |
Michelmersh Brick Holdings (LON:MBH) (£97m) | Full Year Results | SP down 4% | AMBER (Graham) [no section below] |
EKF Diagnostics Holdings (LON:EKF) (£93m) | Full Year Results | Rev falls (move away from lower margin products). PBT £6.3m (LY: £2.1m). Internal hire for CEO. | |
Personal group (LON:PGH) (£66m) | Full Year Results | Momentum carried through into 2025. Revenue up 13% to £43.8m, with pre-tax profit up 34% to £6.8m. | AMBER/GREEN (Roland) [no section below] Strong numbers showing 14% growth in insurance income and a 10% increase in ARR for the group’s benefits platform. Good customer retention and continued growth. Perhaps my main concern is that the insurance division is so profitable, with an apparent operating margin of nearly 50%. I wonder if this might be seen as uncompetitive by a regulator at some point in the future. However, I can’t help remaining broadly positive at the current valuation. |
Fairview International (LON:FIL) (£61m) | Interim Results | H1 PBT £1.15m (last year: £1.4m). Organic growth: existing capacity, acquisition or new build schools. | |
Ultimate Products (LON:ULTP) (£60m) | Interim Results | Trading in line with revised expectations. Expected flat topline. Margins to improve in H2. | |
Real Estate Investors (LON:RLE) (£50m) | Final Results | LTV falls to 25%. Makes a pre-tax loss due to revaluations. EPRA net tangible assets 51.3p. | |
Time Finance (LON:TIME) (£49m) | Trading update | Full-year to be at least in line with recently upgraded market guidance (rev £36m, PBT £7.5m). | GREEN (Graham) [no section below] |
Xaar (LON:XAR) (£48m) | Full Year Results | SP +12% Rev -13%, adj. PBT -89% (£0.3m). Results “solid”? 2025: renewed optimism for the medium-term. The adjusted PBT forecast for2025 from Progressive has reduced from c. £200k to -£300k. Checking my notes from September, this forecast was previously as high as £1.6m. | AMBER/RED (Graham) [no section below] Leaving my mildly negative stance unchanged as I've been disappointed by this advanced printing company's financial results too many times in the past. Today's CEO commentary is optimistic and suggests that the ceramics market is nearing its trough, but how would we know? No revenue growth is forecast this year and the fresh downgrade to the profit forecast - into negative territory - leaves me with little faith in the recovery. At least the company still has a positive net cash balance (£9m) and a tangible balance sheet net worth of about £50m. |
Journeo (LON:JNEO) (£45m) | Full Year results | Rev +8% (£50m). PBT +33% (£5m). Cash £14m. Strong order book, unprecedented pipeline. | GREEN (Megan) Is there a bit of identity crisis going on here? This has the potential to be a high growth company, but it doesn’t seem to be behaving as such, with very little investment in 2024. Still, it’s got potential for more impressive growth and the shares aren’t prohibitively expensive. |
Getbusy (LON:GETB) (£25m) | Full Year Results | ARR +6% to £21.6m. Adj. EBTIDA £1.5m. Actual profit ~breakeven. Revenue outlook: in line. | |
Mission (LON:TMG) (£25m) | Full Year results and results of placing | Rev +1%, headline operating profit +80% to £9m, in line. Actual PBT +15% to £3m. Outlook: in line. | |
Kakuzi (LON:KAKU) (£18m) | Full Year results | Agricultural company reports in Kenyan Shillings. Pre-tax loss despite fair value asset gains. | |
Sareum Holdings (LON:SAR) (£16m) | Interim results | Completed Phase1 clinical trial. H1 after-tax loss £1.2m, in line. Cash £4.1m plus raised £1.1m. | |
Titon Holdings (LON:TON) (£8m) | AGM TU | Trading is slightly ahead of the Board's expectations. Net operating loss on an improved trajectory. Outlook: in line. Estimates from Shore Capital: adjusted PBT -0.1m in the current year. Market outlook remains challenging. | AMBER/RED (Graham) [no section below] This manufacturer of ventilation systems and window/door hardware is still loss-making but should be close to breakeven for the full year. The most recent balance sheet (Sep 2024) showed tangible equity of £10m. So there's plenty of asset backing but the assets have struggled to generate meaningful profits. I'm downgrading this slightly to AMBER/RED, to reflect the heightened risk (e.g. delisting risk) that goes with unprofitable nano-caps. Harwood Capital now own 28%. |
CPPGroup (LON:CPP) (£8m) | Full Year Results | PBT -£2.7m (LY: -£5.7m). Cash £9.7m. Change management programme completed. |
Graham's Section
Pollen Street (LON:POLN)
Up 5% to 750p (£457m) - Full Year Results - Graham - GREEN
This is a growing asset manager and an investor of its own funds that I’ve been slowly familiarising myself with.
The opening paragraph of today’s results is worth quoting in full:
2024 has been a pivotal year for Pollen Street with strong financial performance and strategic progress marked by growing Asset Management revenue and profits together with consistent Investment Company returns. Assets under Management ("AuM") increased 29%, with healthy growth across both private equity and private credit strategies. Pollen Street has entered 2025 with strong momentum and, with continued focus on its core specialisms, it looks forward to continued growth towards its medium-term target of £10 billion total AuM.
The medium-term target represents a near-doubling of current AUM (£5.4m).
Today's summary income statement shows a 72% increase in “Fund Management EBITDA”, from £14.9m to £25.7m. This is what I’d hope and expect to see from a fund manager that is scaling up - higher income dropping down efficiently into profits.
Pollen Street also earns income on its own portfolio, so that its total EBITDA is £57.5m. This is converted extremely well into £49.6m of after-tax net income.
I note that the company returned £48m to shareholders in 2024 - more than 10% of the current market cap.
Outlook: their priorities for 2025 are all eminently reasonable. They want to complete the fundraising efforts for their latest private equity and private credit funds, grow AUM towards the £10bn target, pay a progressive dividend, and return capital to shareholders through buybacks “subject to relative attractiveness compared to other value-creation opportunities”.
The €1 billion fundraising target for their latest private equity fund (mentioned here) was surpassed by the end of 2024.
CEO comment excerpt:
2025 has started well with continued fundraising momentum, solid asset performance and a promising pipeline of deployment opportunities. Looking ahead, we are strategically positioned to capture future growth with our specialist focus, diversified investor base and long track record of performance setting us apart.
Graham’s view
The company claims to have a specialist focus - I want to dig into this a little.
In private equity, their strategy is “buying and building great businesses serving the financial ecosystem across five key sub-sectors”, namely:
Payments
Wealth
Insurance;
Technology-enabled services
Lending.
In private credit, they provide “asset-based lending ("ABL") to mid-market companies across Europe”.
We provide funding to support everything from building homes, to funding SMEs, to vehicle financing…
Our team focuses on the mid-market where we believe the greatest opportunity and largest financing gap exists meaning we can create the most favourable risk-reward profile. This has increasingly led to Pollen Street having a reputation as the "go-to" provider in the market.
So it seems to me that the private equity strategy is very well focused on particular sectors, whereas the private credit strategy is more focused on a particular size of company rather than any specific sectors.
Their fund management fee rate on AUM was a very healthy 1.5% in 2024. This is much higher than we see at conventional fund managers (more vulnerable to competition from passives). Pollen Street are guiding for their rate to be 1.25% - 1.5% long-term.
On the balance sheet there is net equity of £579m, of which about £350m is tangible.
I’m going to upgrade my stance on this to GREEN as this is my second time looking at Pollen Street in recent times. I’m finding almost nothing to dislike and plenty to like:
The StockRank is 97 - it’s classified as a Super Stock.
PER only about 10x.
Operating leverage kicking in as the fund management platform grows
Attractive fee rates.
Shareholder orientation with lots of cash being returned to shareholders in a mix of dividends and buybacks.
There must be some risks I’m missing - please let me know in the comments!
Megan's Section
Gamma Communications (LON:GAMA)
Up 4.5% to £12.60 (£1.21bn) - Full year results - Megan - GREEN
Gamma Communications (LON:GAMA) never does an awful lot to generate huge excitement. It’s a telecoms company, operating across Europe and developing (or acquiring) communications technology to support businesses.
But it’s always been high quality. In the last five years, sales growth has averaged 13%, operating profits have climbed by an average 14%, operating margins have averaged 14.5% and ROCE averaged 23%. In 2022 and 2023, those super high quality metrics took a little bit of a stumble (nothing too drastic, but enough to stop the previously high performing share price in its tracks). It’s good to see that in 2024, those quality metrics seem to have returned to previous strengths.
Strong sales growth across the board
Underlying sales growth driven by price rises and greater uptake of newer products was reported across both of the group’s core divisions (business and enterprise). And this was supported by the first-time contribution of three acquisitions.
Debtor days for the company have risen slightly to 55 (that means it takes an average of 55 days for the company to collect the cash for services delivered), which isn’t anything too concerning.
Gross margins have widened slightly, which means the cost of delivering its services hasn’t risen as quickly as sales have. Operating costs ticked up slightly owing to the expenses arising from acquisitions. But overall operating margins have returned to 15.5%.
Resilient cash flows to fund further acquisitions
Cash generated from operations fell slightly to £117m, equivalent to an operating cash conversion of 129%. Capital expenditure was also slightly lower than the previous year at £19.2m - the majority of which was spent on development costs (and a small fraction on maintaining the network infrastructure).
Gamma rarely leans on its debt facilities to acquire new businesses and the same was true in 2024, with £24.9m of cash spent on the three acquisitions (or £12.5m net of the cash brought in with those businesses). Net cash inflows after taking into account the acquisitions, £27m of share buybacks and £17m of dividends was £17.8m.
Asset-lite business model
Both Gamma and its acquisitions are very light on assets. Most of the value on the balance sheet lies in the cash (£154m at the year end) and the value of its intangible assets, many of which are customer contracts.
The same is true of the businesses Gamma acquires. In 2024, the three newly acquired businesses brought in £21.7m of intangible assets, £10m of which was in customer contracts.
Megan’s view:
There’s really nothing bad to say about Gamma Communications. It’s generating cash which it uses to fund a sensible acquisition strategy and expand its footprint, especially in Europe. The market has been unimpressed of late, despite the fact analysts keep upgrading their forecasts. Based on current expectations for the year to December 2025, Gamma is trading on a quite-reasonable 13x forecasts. I have no reason not to stay Green. But investors really shouldn’t expect anything other than consistent (boring) growth.
Journeo (LON:JNEO)
Down 1% to 260p (£44.5m) - Full year results - Megan - GREEN
I am often surprised to find out that companies which provide vital infrastructure systems (like the technology which powers real-time information systems in transport hubs) are small companies listed on Aim.
The good news is that for these types of companies (and Journeo is one of them), the opportunities for growth are exciting. In 2024, the company made just under £50m of revenue selling its technology and transport management systems to the operators of rail, bus and airport travel hubs, mostly in the UK. Not one customer contributed more than 10% of the total revenue and there are plenty more of these types of customers who could be persuaded to use Journeo’s services.
In 2024, the 8% sales growth was largely thanks to a series of significant purchase orders across both of the company’s main divisions. The Fleet division signed two purchase orders for the company’s camera monitoring systems (designed to improve the safety of buses) with organisations operating bus services in London. The Passenger Systems division welcomed a number of new councils in the UK as customers.
Signing new customers is significant because most of the services provided are quite sticky. Although recurring revenues only contributed 14% of the total sales, customers signing up to install Journeo cameras in all their buses are unlikely to switch to another supplier any time soon. That means that it doesn’t cost the company very much to keep its customers and most of the operating expenses go towards signing new customers. Operating margins are climbing towards 10% - a good sign of this improving operating leverage.
Megan’s view:
I am struggling to really identify the type of stock Journeo is. It’s been listed since 2006 and it’s been a star growth company in the last five years, but it’s still not trading on a particularly steep price to earnings multiple.
Earnings have risen at a phenomenal pace in the last couple of years and they’re up another 46% in these numbers, which is ahead of consensus analyse expectations.
But the forecasts for next year are less impressive and investors seem wary of this - the share price has dropped sharply in the last year and the market hasn’t responded especially positively to these numbers.
There are questions that the company should maybe start to pay a dividend - after generating £7.5m of cash but only spending just over £1m on investing and financing activities. I would argue that it’s not a dividend that should be paid for, but a more aggressive growth strategy, one that can sign up slightly more material contracts which promise to deliver more recurring revenues.
I can’t tell which way this one is going to go, but leaning on the numbers and the statistics (which is what we like at Stockopedia) suggests that this is a decent investment. The quality metrics are ticking in the right direction and there is definitely scope for some further earnings upgrades if the company can keep up its track record of signing new customers. GREEN.
Roland's Section
Kingfisher (LON:KGF)
Down -12% to 246p (£4.4bn) - Final Results - Roland - AMBER
Today’s results from B&Q and Screwfix owner Kingfisher have received a poor reception, despite appearing to be in line with expectations.
For the first time in over six years, we grew our market share in all key regions. We delivered profit and free cash flow in line with or ahead of our initial guidance, with strong delivery against our strategic objectives.
Kingfisher is the biggest mover in the FTSE 100 today and is also a member of Ed’s 2025 NAPS portfolio, so I thought it might be worth a closer look on this crowded results day.
2024/25 results summary (y/e 31 Jan 25): trading commentary in today’s results highlights focuses on the positive factors – Kingfisher says it gained market share “in all key regions” and expanded its ecommerce operations in UK, Ireland, France, Poland and Iberia. Trade penetration also improved through the group’s main brands (excluding Screwfix, which is already focused on trade).
The UK was more resilient than France, with LFL sales up 0.2% despite a 7% LFL decline in big-ticket sales such as kitchens. In contrast, LFL sales in France fell by 6.2% with weakness across all categories.
Online is becoming an important channel for the group. Total ecommerce sales rose by 8.3% to £2.5bn last year, accounting for 19% of group sales (23/24: 17.4%). Most of these are click-and-collect, so won’t necessarily reduce the need for a large, costly store estate – but online capabilities may help to protect and enhance Kingfisher’s market share.
Turning to the numbers, there are not many positives on offer:
Sales down 0.8% at constant FX to £12,784m
Gross margin up 0.5% to 37.3%
Adjusted earnings down per share 5.2% to 20.7p
Reported earnings per share down 44.7% to 10.1p
Dividend unchanged at 12.4p per share
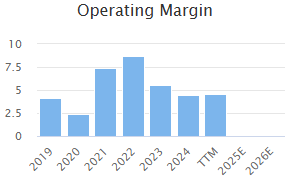
The improvement in gross margins did not translate into an improved operating margin figure, even at an adjusted level – Kingfisher’s retail profit margin fell by 0.4% to 5.4%.
At a statutory level, operating margin fell to 3.2% (23/24: 4.5%). This is well below historic average levels:
Perhaps the only bright spot was cash generation. The company’s own measure of free cash flow was stable at £511m (23/24: £514m). However, my sums suggest a slightly lower figure of £466m, versus £501m in 23/24. Not a disaster – but a more material decline.
Even so, Kingfisher’s cash generation remains a significant attraction – £466m of free cash flow gives a c.10% free cash flow yield after today’s drop.
The only problem I can see with this is that if the business doesn’t return to growth soon, future cash generation could be threatened by onerous leases.
My sums suggest net lease liabilities on the balance sheet of £440m (23/24: £486m). This reflects the present value of future lease payments, in excess of expected cash generation from these stores. In other words, it seems that a substantial proportion of Kingfisher’s store estate is potentially loss making.
These figures are regularly recalculated and may improve if trading picks up. But as things stand, this is a headwind to future profitability and free cash flow.
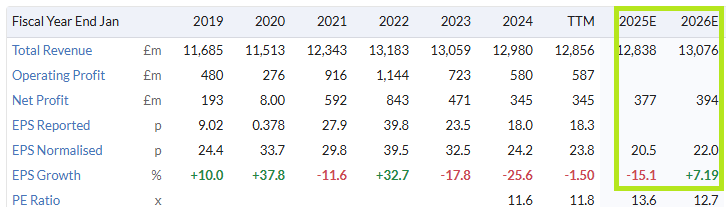
Outlook: Kingfisher is guiding for an adjusted PBT of £480m to £540m for 25/26, with free cash flow of £420m to £480m.
Adjusted pre-tax profit last year was £528m, so taking the mid-point of this fairly wide range suggests to me that adjusted PBT could fall to £510m this year. Assuming this drops through similarly to earnings, this appears to be a downgrade from previous expectations for a recovery in earnings this year:
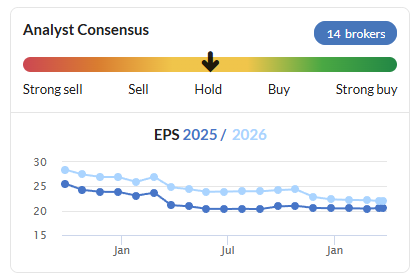
Earnings estimates have trended downwards for much of the last 18 months:
Assuming flat earnings would leave Kingfisher on a P/E of 12 with a 5% dividend yield after this morning’s slump.
Roland’s view
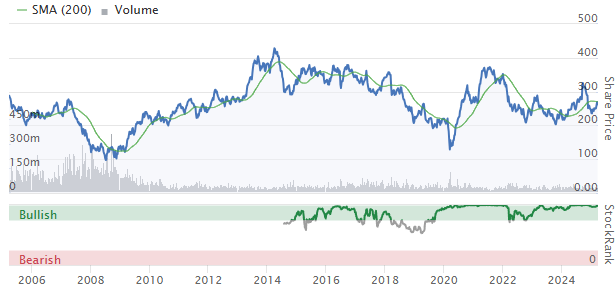
Fundamentally, I think Kingfisher’s problem is that it’s pushing on a piece of string. CEO Thierry Garnier may be improving operations, but the group’s end markets are weak. Kingfisher’s long-term share price chart tells the story of its dependence on consumer spending and housing cycles – the shares are trading at similar levels to 20 years ago:
However, this business continues to generate plenty of cash and the shares can deliver a decent result for investors who are willing to trade in and out of them. The 5% dividend yield also continues to look fairly well supported to me, providing a useful income.
Meanwhile, a further £300m buyback programme could theoretically create shareholder value, as Kingfisher stock is currently trading below its book value of £6.3bn.
In my view, Kingfisher is reasonably cheap and remains in reasonable financial health. On the other hand, profitability is weakening and the company is exposed to headwinds such as next month’s minimum wage and NI increases.
In addition to this, Kingfisher appears to have very little ability to stimulate customer demand and is instead dependent on economic conditions and consumer sentiment.
The StockRanks scored Kingfisher highly prior to today, but I think this rosy view could be downgraded when the algorithms digest today’s results. I’m going to go AMBER here to reflect the combination of value and today’s downbeat guidance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Hello All,
Volex (LON:VLX) approaching another 52 week low, what is going on?
Another share about to be cut...
I don't know the details but do they not have a substantial interest in Turkey where the lira has collapsed (again) following the much-publicised imprisonment of the mayor of Istanbul and the resultant demonstrations of anti-Erdogan citizens? That can't be helping...
Volex (LON:VLX)
looks like there may have been a slight uptick recently but the trend ref expected earnings both this year and next seems to be on downward trajectory - last 12 months. If they keep sneakily lowering forecasts should you not expect shareprice to be going downward - to be fair to company perahps external brokers are reducing on traiff worries etc - so perhaps the company aint being that sneaky perhaps ?
Perhaps being hit by cratering sales of Swasticars?
Volex (LON:VLX)
Before considering Volex (LON:VLX) and the share price weakness, I think to put things in context it is worth remembering that the market in UK small caps, particularly AIM shares has been awful for an extended period. As a result there are some good companies with attractive dividend yields to be had at very attractive prices.
I have been tinkering around the edges of my portfolio, selling one or two shares where events look to be in the price and adding to others on weakness where in view they offer good value on a 12 month view.
I have exited Sigmaroc (LON:SRC) and ME International (LON:MEGP) and top sliced Volex (LON:VLX) all for good returns having held all three for quite sometime. I have for various reasons bought or added to Zotefoams (LON:ZTF) Wynnstay (LON:WYN) Sabre Insurance (LON:SBRE) Tracsis (LON:TRCS) MPAC (LON:MPAC) and WH Smith (LON:SMWH)
Back to Volex (LON:VLX) I think that there are several issues weighing on the share price:
On the plus side the Turkish employees are paid in lira, which has been very weak against major currencies such as the dollar and euro, while the goods produced in Turkey are sold in the latter currencies. Also the recent trading update confirmed that the company was trading in line.
I retain a reasonable holding in Volex (LON:VLX) despite having taken some profits. It looks like we will have to wait until next month's trading update to get a clearer picture of the situation. In the meantime no news is good news I would suggest.
Just my thoughts.
PS: My portfolio of mainly AIM listed small caps, excepting WH Smith (LON:SMWH) is down 5% YTD.
Jonno, can I ask please Sabre Insurance (LON:SBRE) what were your thoughts on sabre insurance leading to taking a position. unlike admiral (I kept missing the opportunity with admiral) it appears cheaper, unnoticed and I have placed a price alert/watchlisted.
Hi Douglas
Firstly my apologies for this very late reply. A consequence of UK small and mid cap shares being completely unloved is that the value on offer, provided one does a little research is eye watering.
I am usually a buy and hold investor and do not use stop losses, but have modified this approach in an attempt to navigate a difficult investing environment and take advantage of some of the value on offer. I continue not to use stop losses.
Regarding Sabre Insurance (LON:SBRE) my attention was first drawn to the company by Richard Crow, aka Cockney Rebel, a few months ago, when he mentioned the yield and considered the outlook . Move on a month or so to the finals on 18 March and the shares are cheaper, plus the company announces a special dividend of 2.9p along with the final dividend of 8.4p, 11.3p in total given a yield of 8.7% at a share price of 130p. The 2025 forecast is for a yield is around 10.5% and PE of 8.2, a substantial discount to the likes of Admiral (LON:ADM) . Sabre's solvency ratio looks robust to me, although this is not an area where I have any great expertise, so after watching the webinar presentation of the prelims on the company website I bought a few. The dividend was just too tempting!
There is also the outside chance of a bid for the company given what happened to Direct Line, but this is just the potential cherry on the cake. I have cut and pasted the outlook statement from Sabre Insurance (LON:SBRE) at the end of this post.
On the subject of yield in conjunction with asset backing/balance sheet strength I have also opened positions in Renewables Infrastructure (LON:TRIG) James Halstead (LON:JHD) Fuller Smith & Turner (LON:FSTA) and as mentioned previously Wynnstay (LON:WYN. As I operate exclusively within my ISA this has meant having to sell to buy. So RM (LON:RM.) Sigmaroc (LON:SRC) Volex (LON:VLX) all went for a profit
SABRE : 2025 OUTLOOK AND BEYOND
" Good volume momentum later in Q1 but against a very high growth comparative period in 2024
- Anticipate strong underwriting performance and profitability in 2025 as polices written at good margins in 2024 earn through
- Ambition 2030 growth strategy launched with initiatives on track. As previously guided, there will be modest impact on premium in H2 2025 with the more material contribution to premium coming through from 2026 onward
- Sabre will maintain underwriting discipline, whilst maximising absolute profit as market pricing finds equilibrium, and expect 2025's margin to be within our target 18% to 22% range"
All the best
Hi Jonno, thanks for your reply. I have taken a position yesterday for the reasons you have highlighted but the deciding factor was the high volume yesterday and I note volume was also high today. Time will tell. Good luck!
Any ideas why Intercede (LON:IGP) has risen today?
FEVR Simon Barnard of Smithson Investment Trust (LON:SSON) sold out of this share. SSON is connected with Fundsmith. He explains his reasoning around the 24 minute mark.
FEVR has recently done a deal in the US with Molson Coors. The US is their largest and fastest growing business. It is their least profitable market, and potentially loss-making. He says that the Coors deal caps the profitability, taking a lot of the upside away.
The UK is the second-biggest, most profitable, but going backwards.
So they may never reach the margins they had in the past. Given these facts, Simon thought the valuation no longer made sense
MPE A nice set of results. High palm oil prices helped the results, mind. I made the mistake of buying at relatively high prices in May 2022 (I still hold, and never sold). So you need to be a bit careful. Also, when palm oil prices are high farmers tend to want to sell at higher prices, making acquisitions trickier. Management seem fairly sensible though.
GAMA I bought in April 2024 at 1338p. The price is currently 1250p [Oh,. some of my commentary seems to have been chopped off]. GAMA is a high-quality company: its Q score is 99 and has consistently high ROCE. Its revenues have been growing at a rapid pace. It trades on a modest PE if 13.1. I decided to increase my holdings a little bit.
Great coverage today by the Stockopedia team. Many thanks.
Didn't even notice the Kingfisher (LON:KGF) drop in my portfolio today as so many other shares are doing well at the same time, today's drop gives back all of the gain I had seen since buying it, no big deal. Bit disappointing but nothing today has changed my view whatsoever, cheap on a free cash flow basis with a nice dividend. It will have its day when it has its day. No one can say when, but it will come. In the meantime, a nice dividend. I'm happy to keep holding and potentially top up at these prices.
Anyone have any thoughts on whether anything Reeves says tomorrow will have any positive/negative impact on any sector?
Or is it just tinkering around the edges?
spring budget surprises
BANK TAX!
Is this a "known" rumour or something that you personally think might occur? How would it be justified by the government (other than a tax grab when government funding is under pressure)?
Fuel duty holiday is over. With tariff concerns on digital tax, I'd say the betting sector is worth a wager.
Two posts in a day - that's really unusual for me but two of my shareholdings reported today Gamma Communications (LON:GAMA) which I have commented on below and Pollen Street (LON:POLN) which is another one of my holdings which I would like to talk about now . I am pleased that Graham has devoted some of his time to have an in depth look at them because they are in an unusual sector - they are described in Stocko as an alternative asset manager company . When the traditional asset managers such as Liontrust Asset Management (LON:LIO) were starting to stutter back in 2023 I had a long hard look at alternatives and the stocko screens came up with Pollen Street (LON:POLN) and Petershill Partners (LON:PHLL) and boy am I pleased that I bought into both of them- the shares are up 20% and 46% respectively but for me (income investor ) they have also paid a yield of about 8% as well . What more can an investor ask for and it may be an idea for someone in the Stocko team to have a look at this sector
fred9566,
Pollen Street (LON:POLN) and Petershill Partners (LON:PHLL)
SNAP!!
Chris
Interesting update as I keep looking at Journeo (LON:JNEO) myself and can't quite bring myself to hit the buy button. The thing that worries me is that their individual physical products and SaaS offering may be superceded by a more integrated SaaS transport solution from a bigger player.
I can't get my head around whether their offering is used by customers just for Journeo products. Network rail as an example will probably have lots of product suppliers each with accompanying SaaS offerings. Will customers start to insist that the company pushes data from Journeo products into their own solution, or worse still a competitor SaaS offering?
I'm not clear if their SaaS solution currently takes data from other sources and developments in that direction would interest me from a growth perspective. Does anyone know if they do this? If they can become the chosen SaaS solution integrator they'll then potentially drive revenue from accepting data from competitor physical products too and be very difficult to replace.
Journeo (LON:JNEO)
Cayman69 - you ask some good questions - why not put them to the CEO and CFO - noon tomorrow on IMC? "Questions can be submitted pre-event via your Investor Meet Company dashboard up until 26 March 2025, 09:00 GMT, or at any time during the live presentation".
Thanks sharw, I've done that.
Not sure I can agree with your description of Gamma Communications (LON:GAMA) as boring .Hhaving completed 3 acquisitions in 2024 that are described as enhancing future organic growth they also reported that in post period end they acquired Starface in Germany in February The acquisition cost aprox £165million so it is reasonably significant but the I note the following from the CEO .
"I am also pleased to be able to say that Gamma is now a significant player in the German market following the acquisitions of Placetel and STARFACE; this gives us a fantastic opportunity to build a business in Europe's largest market. We expect significant medium- and long-term growth in this market as new technologies are adopted.I believe our increased scale in Germany through acquisitions will drive more significant returns, allowing Europe to contribute more meaningfully to group growth in 2025 and beyond. Our resilient business model continues to help us mitigate the current macro-economic uncertainties and I look forward with confidence given the medium-term market opportunity.""
I have been a shareholder in Gamma since early 2023 and the ride has been exciting with a high of over 1700 in September 2024 ( currently 1256 ) and hopefully these latest moves from Gamma will return us to those levels seen last year -their performance certainly warrants it . We shall see!!!!
·
Megan, thank you for your analysis on Gamma Communications (LON:GAMA). "Consistent (boring) growth" is a phrase that makes me happy to hold. I hope the momentum (rank 64 and falling) turns around.
Would you please post the link to your colour coded spreadsheet at the top of the DSMR - I find it hard to locate. Thanks
Would there be any chance of a look at Pollen Street (LON:POLN) Graham a lot of shrewd investors like this one and it comes up on my quality garp screen but I have always held back as part of their business model is buying up IFA firms for the recurring revenue.
The likes of Quilter (LON:QLT) and St James's Place (LON:STJ) have already had to set tens of millions aside for annual reviews that weren't done but I don't think they (FCA) have got down to the likes of Pollen Street (LON:POLN) yet so its to be an unknown if they will get battered or not.
Regards
Andy
The Phoenix.
Lincs made the same well recommended request for Graham to cover Pollen Street (LON:POLN) at 8.33 this morning. The Result has been Graham’s excellent analysis, and it’s clear that Pollen Street (LON:POLN) looks well worth checking out. Is it worth at least a quick scroll through the posts here before we post a request?
Noted Ken, hopefully I was just adding a bit more a nudge to get Graham to cover it which he has.
Ken, it’s Grecian, don’t post here like I did on Mike’s site but I reckon Pollen is an under the radar dirt cheap share, I’ve held the shares for a while but even after todays rise am only just about 25% ahead. Yes, well worth researching imo
Grecian great to see you here, be great if you have time to chip in a bit more as you had an awesome track record on the old Mike Walters board and a style similar to Naked Trader from memory.
As I mentioned Pollen Street (LON:POLN) has came up on my quality garp screen, I work in weath management and have seen a lot of medium sized IFA's buyers getting caught out by the fca as the firms they have bought haven't done all their client reviews and some big numbers are being set aside for compo.
As an example if a firm says they have set aside say £50 mil for redress this is often 25% of the total figure as the fca works on the basis not everyone will claim and 25% of the total possible seems to be the percentage firms are allowed to get away with as minimum benchmark when the true figure say in this example could be £200 mil.
I'm not saying for one minute Pollen Street (LON:POLN) are going to get caught up in this but a lot of firms buying IFA's have been getting caught out as the annual review issue has only become a major focus for the fca in the last year.
Thanks for that Pheonix, I’ve held Pollen since March last year and although the price shot up from my £6 buying price quickly it has trodden water for the last 6 months so I’ll bear in mind what you’ve said about IFA’s starting to get hit in the past year and as always will be out on the first sign of any trouble. But for now, on current newsflow I think the chances are good for further upside.
Hi Grecian. I also remember some great pointers from you on the old MW site - the cash seive check (I think that was yours) was / is brilliant, and still used regularly. I was watching Pollen when I think you posted about it on the Reddit (MW rehash) site - that post confirmed my buy intentions so thanks for that too.
Out of interest Lincs I never moved over to the Reddit site is it any good any of the old faces on their ?
Phoenix - I wouldn't waste your time ;-) N33 still posts the KITE Portfolio updates (which are on here anyway) and the odd post but beyond that it has unfortunately now descended into being a board for one of Mike's disciples to irregularly post about a handful of loss making blue sky companies - including Eden (now hitting new all time lows), Jay / 80M etc. But that's only my opinion :-) Regards
Fair comment Lincs I was always far more on the same page as yourself and Ken if its 99% discussions around sub £100 mil loss making companies I will give it a swerve.
The Phoenix.
Just adding to Lincs’s comment; apart from the weekly KITE update and the delusional poster Lincs mentioned, there are never any other posts there. Also the awful Eden Research (LON:EDEN) is down another 40% this year on top of the previous 98% fall, and the equally awful JAY (now 80 Mile (LON:80M) and Reabold Resources (LON:RBD) also already down 98%, are both down another 20%+ over 1 year. It beggars belief that Mike and so many others too, stayed convinced by the case to invest in them all the way down, and for all I know are still convinced.
Good to see a post from you Grecian. Hope you will post especially so whenever a share you hold or follow updates. Pollen Street (LON:POLN) already sounded worth following up after reading Graham’s analysis today.
Can’t remember whether Investment Trusts (where a lot is happening at present) appeal to you. If they do presumably you know there’s a thriving Investment Trust thread here run by Charles Mitchell, and he starts a new thread every new month.
Two portfolio holdings reported this morning. Both have been marked down, initially anyway.
Journeo (LON:JNEO) I thought the results were good, certainly on my first quick skim. Positives for me:
Clearly the market is impatient and is focussing at the absence of near term growth. The absence of dividends given the strength of the balance sheet may also be a factor. In the meantime the shares are hardly expensive!
Michelmersh Brick Holdings (LON:MBH) Challenging markets continue for building supply companies, but at some point, who knows when, house building and demand for bricks will improve. Until then it is a matter of more patience.. Michelmersh is trading close to book, pays a decent dividend and is unencumbered by debt, unlike its contemporaries.
A positive is that order intake is running ahead of manufacturing capacity.
Journeo (LON:JNEO)
Yes, the results were good and eps at 25.0 came in a little above Cavendish's 24.7. However, the 25 estimate has been left unchanged at 24.9 - see https://www.cavendish.com/rese...
I suspect that this is because the outlook is about "...we are increasing our investment to develop the environment from which we can grow; creating new systems and solutions, strengthening our management teams and targeting acquisitions that align with our strategy and fuel our growth....".
There are those in the market who will not want to wait for this investment to seep down to the bottom line.
Journeo (LON:JNEO)
However, the 25 estimate has been left unchanged at 24.9
are there any 2026 estimates available ?
Journeo (LON:JNEO)
No - last year Cavendish did not publish their 2025 estimates until the Interim Preclo statement - 30/7/24
Journeo (LON:JNEO)
thanks for that - hey ho perhaps they are saving up some good news for the equivalent day this year - i do have a bit of sympathy for lumpy revenue companies trying to predict exact year end/next year outcomes too soon. so certainly it makes sense to wait till there is some more firm detail before "moving the dial" one way or another.
With Gamma Communications (LON:GAMA) it is worth bearing in mind that they are soon to transition away from AIM and list on the main market, where they will rank well into the FTSE 250.
I presume this will be having all sorts of impacts on their shareholder base, given it was one of the higher quality stocks on AIM and therefore probably held by lots of AIM-specific vehicles.
I'm not personally interested in the tax angle and it is complicated, but I wouldn't be surprised if some existing shareholders needed to transact to crystallise some tax benefits one way or another before the move to main market.
And if you are a potential buyer, while they are still on AIM there is no stamp duty.
Phew, Personal group (LON:PGH) issued ‘clean as a whistle’ results this morning… where is that long lost bunting!
With a market cap of £66m at yesterday’s closing price, Personal group (LON:PGH) reported a net cash balance of £27m. Leaving £10m for the regulators, gives an EV of circa £50m generating FY25 adjusted EBIT of £6.9m and PAT of £5.5m.
Statutory PAT was even better at £6.5m following a disposal which lowered revenue but not profits. I calculate FCF at £6.5m, not too shabby!
On adjusted numbers, I calculate a ROCE above 15% and a FCF yield above 10%…quality is good and improving.
In the medium term, management reiterate confidence in growing Revenue and EBITDA to £100m and £30m respectively by 2030. Unusually, this is with good old fashioned organic growth. For next year this translates to Revenue and EPS growth of 10% and 30%. Growth is also good and improving.
Even Canaccord appears to have capitulated, increasing its target price from 209p to 316p…one of the last dominos to fall.
Steady Eddies get a 7%+ dividend yield and for the charties….there’s a bowl ‘to die for’.
I expect it to OBBLT (one bag by lunch time) when the team hit the stage on InvestorMeet.
Worth noting that Personal group (LON:PGH) passes the SAAS “Rule of 40” guide for companies with high sustainable growth, whereby the combined revenue growth (+13%) EBitda growth (+29%) exceed 40%.
All this on a 2025 PE of <12 – Far too cheap in my view, (I hold)
I believe the Rule of 40 combines the revenue growth and EBITDA margin (not EBITDA growth). Personal group (LON:PGH) therefore does not quite make the cut
Nurzel - You are correct - I should have used Ebitda margin% which gives a combined total of 36.
I have just listened the IMC seminar with the lady CEO and CFO and was tremendously impressed. Rarely have I heard such clear sales goals with a well thought out strategy to achieve them. Add this to a Trustpilot score of 4.9/5 and I fully expect the company will exceed 40, by the end of this current year.
Personal group (LON:PGH) Great post Cuddlesticks and I thought the IMC presentation was very reassuring, what a cracking little business this is....
I brought up the topic of the accuracy of the charts yesterday, having noted that the UK top value momentum ranks (VM>90) chart went up 11% on July 3rd last year which seems strange. I wonder if someone from Stockopedia could comment (Oliver, Ed?) as we do need to be confident in the accuracy of the charts and a 11% swing in one day seems extreme. Many thanks. DD
I assume the list of companies in the rankings are companies that obey the filter criteria now and the history is how those companies have performed in the past. Of course, those companies may not have obeyed the criteria in the past. It might be more interesting to see the history of companies that obeyed the criteria a year ago, say, and you might have a rather different picture. I also wonder if the history takes into account share consolidations or splits. In any event, I would take the histories with a large pinch of salt.
Hi Chris, no the rankings are not done like that. They are forward-looking; for example the VM screen takes those with a VM rank over 90 and looks at forward performance, resetting the group every so often (quarterly, twice a year or annually, I'm not sure which). So a 10% change in a single day is not really plausible and looks like an error for a group that may comprise around a hundred stocks. It would be really great if someone from the technical team could offer an explanation. Accuracy of these graphs is obviously a key part of the value of Stockopedia. DD
No, it is the top 25 VM stocks, rebalanced quarterly. I presume done on the 1st January and then every quarter. A 11% change in a day is highly unlikely.
There have been several similar events, that have been manually adjusted by Stockopedia staff, could be share splits.
This is picking to top stocks for the next quarter, the performance is impressive for some ranks.
.....if it is accurate!!!
The most obvious answer is a share split not accounted for properly.
Could be but the accompanying notes express how carefully Stockopedia adjust correctly for these.... it's a large part of the year's overperformance so an explanation would be great.
Don't get me started on the accuracy of Stockpedia data. In my view, it is all over the place, and there's not even an understanding of basic maths (I'm a mathematician by background). I have wasted many hours with Stockopedia staff about incorrect calculations in my portfolio - like that's not even complicated, it's just a simple addition of the transactions that I've input. Never mind data that actually does something more complicated that their whole ranking system is based on. My portfolio has a good number of share splits in there now, and the answer is no, they don't do these accurately at all.
All they do on a share split is keep the amount paid the same. This means that as the number of shares go down, your buy price goes up, even though that isn't the price you bought at. That might be fine, except for the fact that Stockopedia have no way of dealing with a part return of capital under this process (the only way to input this seems to be as a dividend which is a fix but it's wrong). They also apply the share split to dividends (why? *insert crying face emoji*) which there's absolutely no need to do except that they have some very basic algorithm that can only apply a share consolidation to every transaction under a particular share.
Of course, all this means that the calculations they produce across your whole portfolio (profit, realised returns, etc.) gets increasinly incorrect as time goes by.
*rant over*
Ah.....disappointing to hear. Perhaps one of the Stockopedia team would be able to answer the specific question about the 10%-in-a-day increase in the VM portfolio, which accounted for a lot of that year's outperformance?
Morning Graham. Any chance you can run your slide rule over Pollen Street (LON:POLN) ? I've held for around a year and topped up along the way. I am surprised by this mornings somewhat muted share price reaction to what I consider to be excellent results. It is paying a Divi of over 8% and looks to have a good runway ahead.
Thanks for the suggestion Lincs, I'll do my best to include this. G
Thanks for your attention to this one Graham. If pushed, the only downside I can see is that it appears to be doing so well due to a select few skippering the ship - if any of them were to leave then it might impact on performance / sentiment. I can't see anything to suggest that might happen anytime soon - since November 2022 there has been a steady stream of appreciable director purchases. The top 10 holders hold > 69%. The few institutionals in that mix have held since prior to 2022 (when they voted for the merger between Honeycomb and Pollen) so they appear to be happy with the way things are going. Onward and upward - definitely one for investors to research for themselves.
M P Evans (LON:MPE) reads well and should do well today (but who knows.) Very well run company paying nice dividends. Will never be on a high PE as its reliant on palm oil prices but see no reason to sell on these prices.
Journeo (LON:JNEO) an ex holding of mine continues to do well but still trading at an high SP for me compared to its actual growth.
Graham, you have Ultimate Products (LON:ULTP) twice on the table.
I believe that's fixed now, Rusty.
Personal group (LON:PGH) - it would be good if this could be covered. Momentum seems to be very strong on their core insurance product.
Time Finance (LON:TIME) seems to be an excellent Q3 update, matching the whole of last years figures in 9 months. Some forward looking visibility would be nice, but looks a decent buy at these levels.
Like Journeo (LON:JNEO) it would be good to see Time Finance (LON:TIME) start paying dividends. (I hold both)
Are others still getting issues with their news feeds - none of my PF holdings have come through today - GAMA, PGH & POLN.
I've reported it through the Green Button, but this is happening too often.
Yes 3 of mine (Ashtead Technology Holdings (LON:AT.) EKF Diagnostics Holdings (LON:EKF) and Gamma Communications (LON:GAMA) missing today until about 7.20am. on the Stockreport. 2 others were out on time.
Even then, did not appear on my newsfeed, even after refresh, until after went into change filters and back out, then they appeared.
I have had problems for a long time, I use Sharepad to check for News.
Morgan Sindall (LON:MGNS) posting a 'slightly ahead of expectations' today on a strong momentum in their fit out division
Why has SP fallen so much?
Up today nicely on the good news but recent performance can be down to any of the following:
- taking a breather after a decent run up
- profit taking
- industry sentiment
- General pessimism in the UK market
- just because
Three NAPS stocks report today. Strong results from M P Evans (LON:MPE) and Journeo (LON:JNEO) , not so good from Kingfisher (LON:KGF) .