Daily Stock Market Report (Tue 26 Nov 2024) - DIA, IGP, SFR, BRCK, AO., SUP, IGR, CWK

Good morning!
Wrapping this up at 12.40. We'll try and mop up some of the extras for short sections tomorrow, so get your requests in if there is anything you would like for us to look at. Have a good afternoon.
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
Companies Reporting
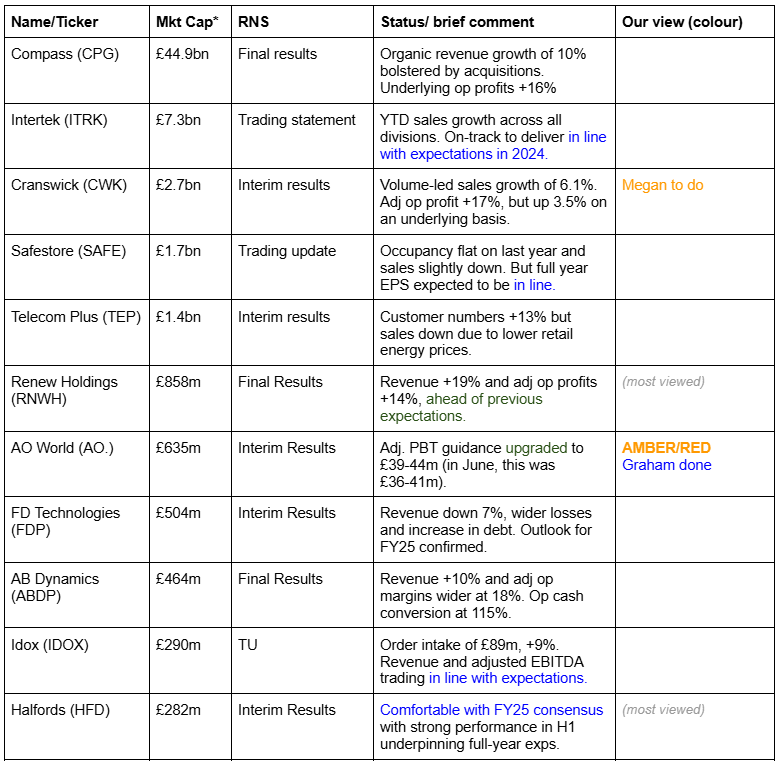
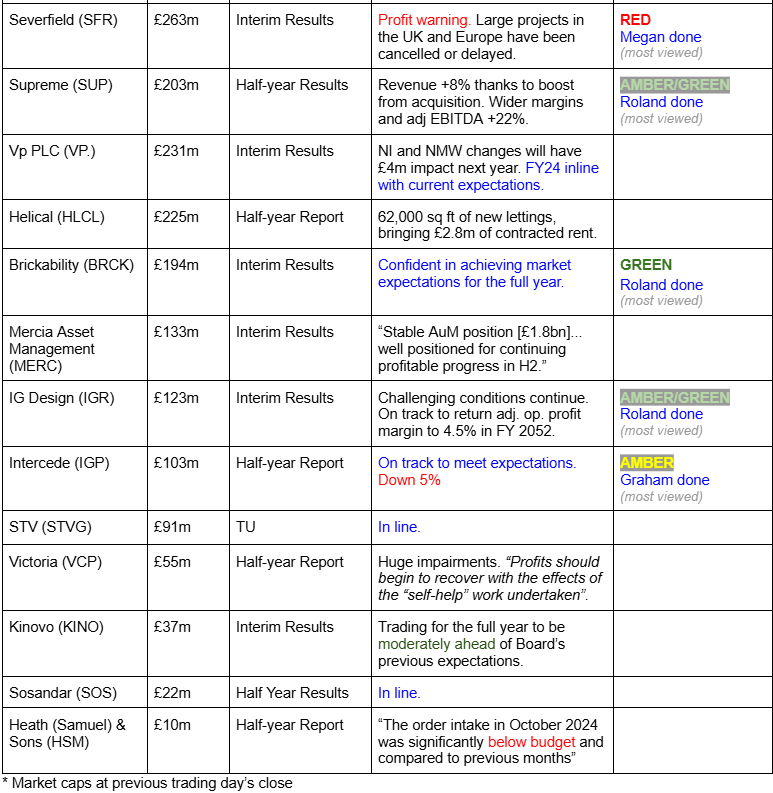
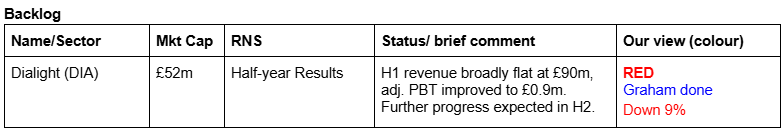
Summaries
Dialight (LON:DIA) - down 9% to 118p (£47m) - Half-Year Report - Graham - RED
I’m taking a negative stance on this one due to a terrible “going concern” statement that talks of a potential covenant breach (although I expect that the bank will be forgiving) and potential difficulty in paying costs associated with a recent court decision in the United States. They have no CFO: the lights are on but no one is at home.
Brickability (LON:BRCK) - up 9% to 61p (£194m) - Interim Results - Roland - GREEN
Broadly reassuring results from this construction materials group suggest to me that the business could perform well when the construction market recovers. Management confirms that full-year expectations are unchanged. I’m happy to stay positive here, given the modest valuation and useful 6% dividend yield.
AO World (LON:AO.) - down 1% to 108.2p (£628m) - Interim Results - Graham - AMBER/RED
A fine report from AO World where there has been no shortage of interesting news flow. The £10m acquisition of Musicmagpie is imminent and at the same time, Frasers have been building a position. Perhaps too cautious, I leave our mildly negative stance unchanged on valuation grounds.
Supreme (LON:SUP) - up 1% to 175p (£203m) - Interim Results - Roland - AMBER/GREEN
Supreme has upgraded its full-year EBITDA guidance by around 10% today, but the share price has been strangely unmoved. My review of today’s half-year results does not suggest any serious problems, but I note that brokers expect a shortfall in earnings in FY26 as the ban on disposable vapes kicks in.
Short Sections
Intercede (LON:IGP)
Down 5% to 166.5p (£98m) - Half-year Report - Graham - AMBER
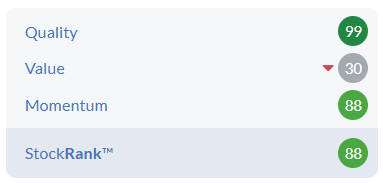
Intercede is “the leading specialist in digital identity, credential management and secure mobility”. It trades richly (PER 40x) due to long-term growth expectations.
Today’s interims show 22% revenue growth (to £8.5m), 55% PBT growth (to £1.7m), and a year-on-year rise in the cash balance to £16m (if I was being really fussy, I’d point out that the cash balance fell from where it was six months previously).
Outlook
…the Group has various opportunities in the pipeline which, when converted, have the ability to solidify and embed the growth ambitions of the Group in the coming years…
…The Company's overall pipeline has continued to expand and geo-diversified with the weighted pipeline being materially ahead of last year and together with no debt and a strong cash position the Group has the foundations in place to build and grow for the future, both organically and through M&A.
Share buyback
I find the company’s decision to launch a £1m buyback in October quite odd.
On the one hand, £1m is not a hugely material figure in the context of this company and its market cap.
And it could be interpreted purely as a means of satisfying future share-based payments for employees.
But the company itself said that it had been prompted into this decision by its share price volatility, and that it was being done at least partially in order to “take advantage of current market conditions” and “improve shareholder returns”. So it must really believe that it’s undervalued.
Estimates at Cavendish are unchanged: revenue of £16.1m in FY March 2025 (down from £20m in FY24) and adj. PBT of £3.7m (down from £6.2m in FY24). They say there is “potential” for upgrades, but also that “the timing of contract completions remains out of IGP’s control”.
Graham’s view: Paul has been a huge supporter of this one, but personally I’m struggling to see how it is worth c. £100m, at least based on the financial forecasts for the next 18 months. The justification for the current market cap must lie in FY27 and beyond. I’m afraid I don’t “get it” and therefore I’m downgrading this all the way to AMBER.
It’s a High Flyer with Quality and Momentum, but not much in the way of Value:
Severfield (LON:SFR)
Down 40% to 52p (£160m) - Interim Results - Megan - RED
As expected, trading in the period under review at structural steel contractor Severfield (LON:SFR) was pretty good. Sales rose 17% to £252m, to make a decent dent in the order book which stood at a total of £659m in June (£478m in the UK and Europe division, £181m in India).
But it’s the outlook which has caused the whopping share price collapse this morning. Market conditions (which management had said were looking up when it announced its results in the summer) have taken a turn for the worst.
Now,
“[the] previously anticipated recovery in some sectors has been slower than expected and tighter prices are continuing to impact our profitability in the short-term.”
That means some of the large projects that had been anticipated in the year to March 2025 and also in FY26 have been delayed or cancelled entirely. The UK and Europe order book is £68m lower than it was in June at £410m.
To make matters worse, since the last announcement, the company has discovered that some of its bridge structures fell short of the compliance requirements of its clients and has therefore booked a one-off charge of £20m. There are still four more dodgy bridges (out of a total of 12) that the company has yet to estimate the total cost of repair, so the £20m figure is likely to increase by the end of the financial year.
The cost of bridge repair work has also impacted cash flows, with operating cash inflows £25m lower in the first half at £6.8m. This impacted the company’s cash position which was half of what it was at the end of the financial year. The company took out a loan to pay for its acquisitions last year of which £16.9m is still outstanding. However, there is still considerable headroom in the total credit facility. Net gearing is just 13%. So I think the balance sheet is still sound.
The company is currently £6.8m through its £10m share buyback programme, so further buybacks (at a much cheaper price following this morning’s fall) could provide some support to the share price in the coming months.
Megan’s view
What I don’t particularly like about this statement is the fact that management has revealed that in July the UK and Europe order book was already £18m smaller than it had been only a month earlier, so why it has taken until November to reveal the extent of the disappointment is a mystery. The bridge remedial work, which has had a major impact on profits, was also known several months ago.
The 40% share price fall this morning is perhaps a bit of an over-reaction, but it does show the extent to which the market feels burned by surprises. Perhaps management could have handled this situation better.
Some may see this morning’s fall as an opportunity. Wiping £80m of value in one swipe does feel a bit drastic, especially given the widening margins and strengthening balance sheet that the company had been reporting up until today.
The bridge repair work is likely to remove almost all of the company’s reported profits for the FY25 financial year, so a valuation based on earnings is going to be difficult to calculate.
Optimism in recent months was largely thanks to the expected improvement in market conditions; these seem to have disappeared. Add this to management’s reluctance to keep investors informed about the challenging market conditions and I think this is one to steer clear of for now. RED.
IG Design (LON:IGR)
Down 10% to 112p (£110m) - interim results - Roland - AMBER/GREEN
Today’s half-year results from giftware firm IG Design have received a poor reception, sending the stock down a further 10%. As a quick recap, IG issued a profit warning in September, which Paul covered here.
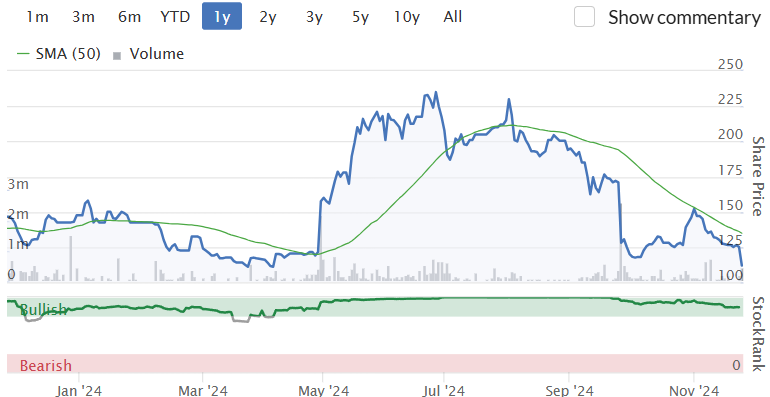
The good news, as far as it goes, is that today’s half-year results do not appear to contain another profit warning. The bad news is that the results aren’t great, and external conditions do not seem to be improving as quickly as might have been hoped for.
The challenging market conditions and retail trends experienced in the period are expected to continue in H2
Taking a quick look at today’s results, the company reports revenue down by 11% to $393.1m, with adjusted pre-tax profit down by 62% to $13.3m. A nasty example of operating leverage in reverse.
Fortunately, the balance sheet appears to remain in reasonable health, with net cash of $7.4m at the end of September (Sept 23: net debt of $15.1m). Given that working capital tends to peak in H1 as stock builds ahead of Christmas, this looks reassuring to me.
Unfortunately, trading conditions in the US remain difficult, with revenue down by 14% to $241.8m. This compares to a 6% fall in sales in the international business.
The US situation is made more complicated by ongoing restructuring and the reshoring of manufacturing operations from China, where IG Design is closing its factory.
Outlook: the company has maintained its main financial target for the current year following today’s results:
Remain on track to return adjusted operating profit margins to proforma pre-pandemic levels of at least 4.5% in FY2025
This is confirmed in an updated broker note from Canaccord Genuity, which leaves full-year forecasts for adjusted earnings of $0.21 per share unchanged.
That puts IG Design shares on a P/E of about seven after today’s slump – potentially cheap if the company can deliver on its turnaround plans.
Roland’s view
IG Design appears to be a great example of the dangers of transformative acquisitions. Since acquiring CSS Industries in 2020, the group has suffered a series of problems. It’s now in the third year of its turnaround plan.
External conditions in the US and the perceived necessity to move manufacturing away from China are making life even more difficult. I think there’s a chance this business could continue to struggle.
However, forecasts have been held unchanged today and IG Design still has a net cash position. On this basis, I think I can just about justify holding onto our previous AMBER/GREEN stance, ahead of the key seasonal trading period.
Cranswick (LON:CWK)
Down 4% to 4877p (£2.8bn) - Interim Results - Megan - GREEN
The farming industry has not been far from the headlines in recent weeks after the nation’s farmers took to the Westminster streets to bemoan the inheritance tax changes proposed in last month’s budget, which pour more heat on an already embattled industry.
Wherever you stand on the political debate swirling around agricultural relief from IHT, it’s hard to deny that farming is tough. The industry is tightly regulated with prices set by policy rather than supply and demand economics, meaning farmers can’t pass rising input costs onto their customers. The UK’s weather makes things a whole lot worse.
But Cranswick, whose Yorkshire roots are firmly embedded in the farming industry, remains resistant to these challenges. Rising demand for its farmed animal products sent revenue in the UK food business up 6.4%, despite a decline in average prices. Volumes of fresh pork (which contributes just under a quarter of total revenues) rose 13% year-on-year in the UK. Poultry revenues rose 16% and now contribute just under a fifth of the group total. Gourmet products (including its pigs in blankets range, which is expected to have a busy Christmas season) had a strong first half, with sales up 9%. Convenience foods (which include the company’s range of cooked meats and its halloumi-centered mediterranean offering) was up a slightly less impressive 1%. Convenience foods is the single largest contributor to group revenue.
The company has bolstered its core farm-led growth with a recent expansion into the pet food business, where sales rose 71% in the first half, thanks to the ongoing roll-out of a major contract with Pets at Home. In its core food offering its customers include most of the major UK supermarkets, which is an enviable position to be in.
Meanwhile, investment in farm efficiency has helped support company margins, which were 67bps wider at the operating level at 7.5% in the first half. Cranswick now boasts the largest herd of pigs in the UK, with almost 900,000 “on the ground” at any one time. Over 34,000 “finished pigs” are produced every week, which is an 18% increase on the same period last year, thanks to improved efficiency and acquisitions.
The company remains very cash generative, converting 111% of net profits into free cash inflows in the first half. And the strong cash position brings capacity for additional investments. In the first six months, total capital expenditure reached £48m, £20m of which was spent on ‘earnings enhancing projects’ across three distinct areas of the business.
Megan’s view
I carry some reservations about companies in the farming sector because of the challenges in controlling price. It’s also worth noting the shift in consumer demand in favour of plant-based proteins in recent years. Cranswick is currently investing £25m in its humous processing factory, but overall it remains a distinctly carnivorous company.
But despite the challenges posed by the market, growth remains strong across the top and bottom line. Analysts have upgraded their FY25 earnings expectations for the company from 240p in January to 261p following today’s results.
Based on those forecasts, shares are trading on 19 times forecast earnings, which is rich for companies operating in the sector. But not too unreasonable for those with such impressive quality metrics. The company’s return on capital employed has averaged 15% in the last five years.
Importantly, Cranswick is the market leader in the UK with a completely domestic supply chain which keeps it sheltered from pesky tariffs currently dominating business headlines. With its earnings enhancing investments likely to deliver more in the coming years, I am giving this one a cautious green rating.
Graham's Section
Dialight (LON:DIA)
Down 9% yesterday to 118p (£47m) - Half-Year Report - Graham - RED
I note in passing that DIA’s CFO recently stepped down “for personal reasons and will be leaving the Company, with immediate effect, by mutual agreement with the Board” (Nov 11th). This caused a rescheduling of the interim results.
CFO resignations are often seen as potential bear signals. DIA’s CFO had only joined the company in February of this year, and she was not thanked for her contribution in the announcement of her departure.
Today’s interim results show a small reduction in revenue (£90.3m vs £91m in H1 last year) and an improvement in underlying operating profit (£0.9m vs a loss of £2.5m in H1 last year).
Unfortunately, the “non-underlying” costs are enormous, so the statutory result is deeply in the red:
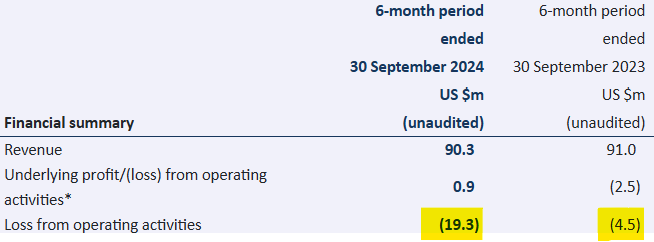
The “underlying” result was impacted by challenging market conditions in the Lighting segment - one thing I’ve learned over the years is that the demand for lighting products tends to be very volatile, and more often than not, conditions are challenging.
Weakness in lighting was partially offset by increased revenues in Signals & Components.
Overall group orders fell 7%.
The “non-underlying” costs were:
“Sanmina litigation” ($22.3m provision): a dispute with a former manufacturing partnering, dating back to 2018, went to trial in September. A mixed verdict was returned and $22.3m is management’s best estimate of the cost.
I have no problem with treating this as a one-off expense, but it does hit DIA’s balance sheet.
Transformation project ($3.1m cost): I don’t treat these as one-off expenses. DIA itself says that the transformation plan is a “multi-year change programme”.
Offsetting these costs, DIA benefited from the sale of a business in North America ($5.2m).
Therefore, despite the income statement showing an underlying profit ($0.9m), I would treat it as an underlying loss after deducting the costs of the transformation project ($3.1m).
On the balance sheet, the net effect of everything that occurred in H1 sees a reduction of net assets from $64m (March 2024) to $46m (Sep 2024).
Net current assets fall from $27m to $7m, if we exclude the fact that the company’s borrowing facility (RCF) was reclassified during the period, from a current liability to a non-liability.
Going concern: the footnotes to the financial statements describe a potential breach of an RCF covenant in Q3, due to the weak trading performance. And it continues with more bad news:
At the balance sheet date the Group does not have sufficient liquidity to settle the [Sanmina] provision without taking mitigating actions or securing additional funding within the going concern period which may include seeking to agree a payment plan with Sanmina and/or new equity funding. The amount, timing, and receipt of any such funding is uncertain at the date of the approval of the interim financial statements.
These circumstances give rise to material uncertainty, which may cast significant doubt on the entity's ability to continue as a going concern, meaning it may be unable to realise it assets and discharge its liabilities in the normal course of business.
Graham’s view: it’s an automatic RED from me. I dislike this sector and if you throw in an abrupt CFO departure plus (most importantly) a going concern warning, I’m out.
AO World (LON:AO.)
Down 1% to 108.2p (£628m) - Interim Results - Graham - AMBER/RED
Nice results from AO World, which has been transformed since it pivoted to focus on profit and cash generation - the previous business model was allergic to both of those things!
H1 revenue is up 6% to £512m, while adj. PBT is up 30% to £17m.
As observed by Paul in June, it’s a fundamentally low-margin business. That’s the nature of electrical retailing: AO achieved a PBT of 3.3% in H1 (H1 last year: 2.7%). The company’s medium-term ambition is to increase this to over 5%.
I appreciate the efforts by founder John Roberts to inject some life into his comments:
"We've had a Morecambe and Wise summer sales period; all the right volumes just not in the right categories. The wet summer weather meant we sold fewer fridges and air conditioning units and more tumble driers than we had planned. Overall, our team did a fantastic job to play this out as a satisfying score draw.
Outlook: FY March 2025 adjusted PBT is upgraded to £39-44m (in June, the range given was £36-41m).
Checking Equity Development’s note published in June, they put out a forecast of £38.7m.
Of course the PBT forecast is not the only thing that matters, but I note that the share price has made little progress since June despite the upgrade, and is even down today:
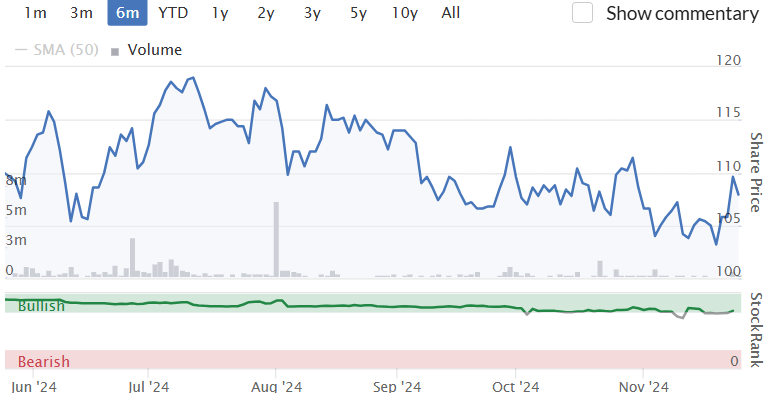
M&A: AO is buying Musicmagpie for £10m of cash. We never liked Musicmagpie in this report but at £10m, AO can afford to pick it up and try to improve it (net funds £38m as of Sep 2024).
Separately, let’s take a note that Frasers have been building their position in AO World and are now over 24%.
Graham’s view: I used to find this company an appealing short and did indeed short it. That was in the old days. It’s now being run as a proper business: I’ve been amazed by the evolution of John Roberts into a profit-focused, hard-nosed businessman and I applaud the change in strategy. He continues to own more than 16% of the company, so is very well-aligned with other shareholders.
Perhaps the reason the share price is struggling to get any higher is due to an already high valuation for a retailer:
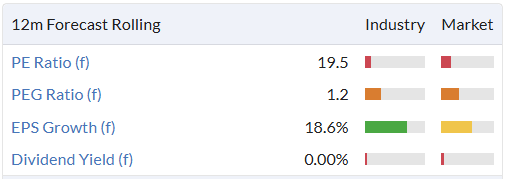
Purely in terms of my improved sentiment towards this company, I’d like to give it an upgrade. But I can’t avoid the conclusion that it remains expensive for what it is, so I’ll leave AMBER/RED unchanged
Roland's Section
Brickability (LON:BRCK)
Up 9% to 61p (£194m) - Interim Results - Roland - GREEN
This morning’s half-year results from building materials distribution group Brickability seem broadly reassuring to me, and the market seems to agree, as the shares are up nearly 10% at the time of writing. A clear outlook statement helps to set a positive tone:
The business remains committed to growing in a sustainable manner, the Board's outlook for the 2025 full year remain unchanged, and is consistent with market expectations.
Today’s results cover the six months to 30 September and seem broadly positive, against a market backdrop of subdued activity, especially in housing.
Revenue for the six months rose by 1.9% to £330.9m, while adjusted pre-tax profit was 0.5% higher, at £21.9m. Encouragingly, gross profit rose by 14.5% to £63m, lifting the company’s gross margin to 19% (H1 24: 16.9%).
Management says this improvement was driven by the contribution from recently acquired specialist cladding and fire remediation businesses, which have lifted overall margins. This market is of course benefiting from structural demand from unsafe cladding remediation projects, work that’s expected to continue for some years.
Another highlight was the contribution from the Upowa renewables business, where sales of solar panels doubled during the half year.
While Brickability’s buy-and-build model is not without risk, diversification does seem to be helping to support the group’s performance at the moment.
This business is relatively capital light and should benefit from operating leverage as volumes recover. So I’d hope higher margins from acquisitions might help to support higher operating margins for the whole group when volumes recover in the core brick business.
Drilling down a little further there are a couple of points worth noting. Reported profits were held back by a £5.3m impairment charge relating to a joint venture that’s been allowed to fall into administration.
Net debt ended the six month period largely unchanged at £56.3m, but is significantly higher than the £30.9m reported one year ago. This level of borrowing looks reasonable to me against expected net profit of £28m, but it’s worth remembering this distribution-focused business runs a big balance sheet.
Receivables and payables were both c.£120m at the end of September (around 2.5 months’ revenue). This means that movements in stock levels or slower sales can lead to big swings in cash flow. Good liquidity is important in this model, so I would not want to see too much more debt.
Roland’s view
Brickability shares have slipped lower since our last look at the shares in July, perhaps because of a slower-than-expected reduction in interest rates.
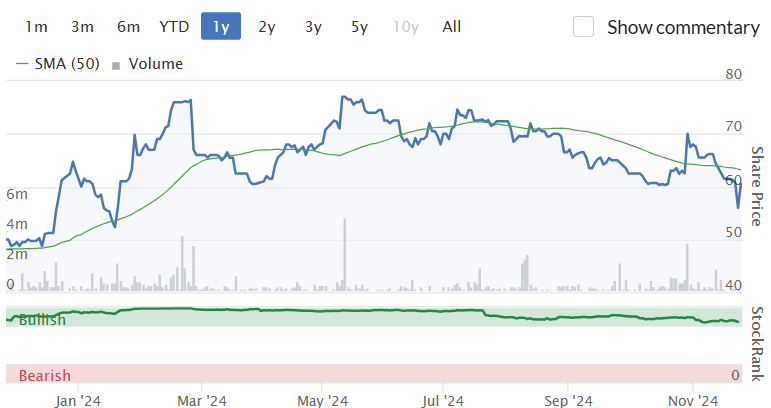
However, today’s results suggest to me that this business remains in decent shape and may well offer value at current levels.
I’m also encouraged by comments from CEO Frank Hanna, who has now been in the role for six months. Hanna says his focus will be on “improving systems and processes” to provide a stronger platform for growth and improved cyclical resilience. This sounds like a prudent approach to me to maintain good controls as the group scales.
Hanna’s previous role was as co-CEO at Michelmersh Brick Holdings, which I see as a well-run and good quality business. So I’m hopeful he’ll bring the same discipline and careful execution to Brickability.
After this morning’s gains, Brickability shares trade on around seven times forecast earnings and offer a 6% dividend yield. I’m happy to maintain our GREEN stance on this stock.
Supreme (LON:SUP)
Up 1% to 175p (£203m) - Interim Results - Roland - AMBER/GREEN
Supreme styles itself as a consumer goods group, but the majority of revenue and profits come from its vaping business, both as a manufacturer and distributor.
Without taking a view on vaping, this market undeniably carries political and regulatory risks. These are now starting to come into focus, with disposable vapes to be banned from June 2025 and the introduction of excise duty on vape liquid from October 2026.
This may help to explain the market’s muted valuation to today’s upgraded profit guidance for the current year (my bold):
The Group has made a strong start to the second half of FY 2025 and expects trading for FY 2025 to be ahead of expectations, with revenue guidance of around £240 million and Adjusted EBITDA guidance of at least £40 million.
Checking back, in September Supreme cited market expectations for adjusted EBITDA of £37m. So today’s new guidance represents an upgrade of c.10% to full-year expectations.
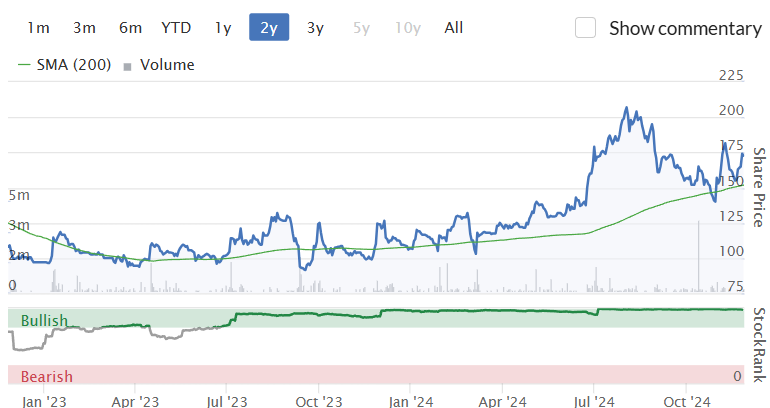
Half-year results summary: there are no obvious concerns in the headline numbers:
Revenue up 8% to £113m
Gross margin up 3% to 30%
Adjusted pre-tax profit up 25% to £14.7m
Reported pre-tax profit up 5% to £12.9m
Adjusted earnings up 37% to 11.1p per share
Interim dividend up 20% to 1.8p per share
Net cash exc leases of £2.3m (Sept 23: net debt £4.8m)
Trading commentary also seems mostly positive. The acquisition of Clearly Drinks for £15.6m earlier this year has been achieved without debt. This soft drinks business is expected to generate £3.5m of annualised EBITDA and provide additional cross-selling and growth opportunities.
As a result of this deal, Supreme says that non-vape annualised revenue should rise to around £100m, or 45% of group revenue.
However, this still means that 55% of revenue will be vaping related. In addition, today’s note from Equity Development suggests that vaping remains a much higher margin business than the majority of Supreme’s other operations. This means vapes may contribute significantly more than 55% of group profit at the moment.
Supreme is already scaling back sales of disposable vapes to reflect next year’s ban. This led to a 13% reduction in total vaping sales during the half year:
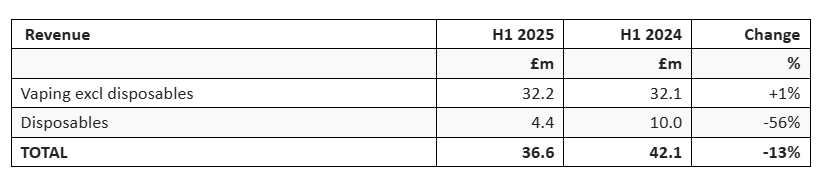
However, some of this spend was redirected to the company’s Branded Distribution segment, which distributes the popular ElfBar and Lost Mary disposable brands. Revenue in this segment rose by 12% to £34.4m, partially offsetting the decline in Supreme’s own-branded disposable sales.
Over time, management believes that greater vaping regulation is likely to lead to sector consolidation and could favour larger, well-run businesses. I share this view, although I think it’s too soon to know whether positives will outweigh the negatives.
Diversification remains on the cards and the company currently has plenty of financial firepower for further acquisitions:
Supreme has developed a stable, highly profitable and growing core business, is currently pursuing a buoyant and diverse M&A pipeline, has a healthy balance sheet and has more than £50 million of unutilised borrowing facilities, providing the Company with a strong base for further growth in the long term.
Outlook: Supreme is bullish about the possibilities for growth in its soft drink and sports nutrition businesses, citing opportunities to combine the expertise of these two divisions. This seems fair to me, but for now vaping remains a key driver of near-term profits.
Today’s upgrade to guidance should translate into a modest increase in adjusted earnings for this year.
While we often complain that no broker notes are available to private investors for some of the companies we cover, today’s results from Supreme have been accompanied by no fewer than three new notes available via Research Tree.
This almost feels like a PR campaign to me, but the additional insight does provide some useful benefit.
Equity Development expects today’s upgrade to translate into FY25 adjusted earnings of 20.2p per share. I assume management has approved this estimate, as it’s a paid note.
Zeus and Shore Capital take a slightly more bullish stance, estimating FY25 eps of around 21p.
In either case, this leaves Supreme shares trading on around 8.5 times FY25 earnings, with a c.2.8% dividend yield.
However, the outlook for FY26 seems a little more muted. Depending on which note you read, the ban on disposable vapes is expected to lead to a c.10% fall in EBITDA to c.£36-37m in FY26, with adjusted earnings falling to 19-20p per share. That’s roughly in line with last year’s earnings.
There are no FY27 forecasts yet, but the introduction of excise duty in October 2026 could potentially have a further impact on sales and profits.
Roland’s view
This isn’t the place for a discussion about the merits (or otherwise) of vaping. But to me, it seems that a business with this level of evolving regulatory exposure is probably fairly priced on a relatively low P/E multiple, despite very attractive quality metrics:
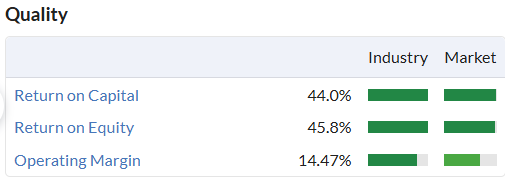
Having said that, I think Supreme is generally a good operator and I would not bet against CEO (and 56% shareholder) Sandy Chadha to continue finding opportunities for growth.
On balance, I think it’s reasonable to take a moderately positive view on this stock at current levels. I’m going to maintain our previous view of AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

115 comments
PEG ratio on Stocko. On the Stockreport, top right it has the PE (f) PEG and EPS growth figures.
Looking at one stock, PE is 54, Growth 155%, yet PEG is 0.9, l expected it to be 0.3.
Or is Stocko using some different figures?
VP (LON:VP.) - video recording now available - Investor Presentation (Interim Results) - November 2024
Anna Bielby (Chief Executive) and Keith Winstanley (CFO) of Vp plc hosted an Investor Presentation covering highlights of the company's Interim Results for the six month period ended 30th September 2024. The company reported robust performance despite challenges in some end markets, and highlighted their solid balance sheet and an interim dividend of 11.5 pence per share (continuing 30+ years of uninterrupted track record). Management discussed the launch of Vp Rail, an integrated rail solution providing customers with direct access to all the Group's rail specialisms, and the acquisition in October of CPH, one of Ireland's leading specialist powered access companies. The team provided a financial, operational and strategic update with some illustrative case studies, and then answered a range of questions submitted by viewers.
?si=7X4nTQFtCuOqJlBcSupreme (LON:SUP) video recording now available - Investor Presentation (Interim Results) - November 2024
Sandy Chadha (CEO) and Suzanne Smith (CFO) of Supreme discuss the factors behind the 8% increase in revenue and 22% rise in adjusted EBITDA. The interim dividend was increased by 20% to 1.8p, and Supreme raised guidance for FY2025 results, now expecting an adjusted EBITDA of "at least £40 million." Management provided a detailed run through of Vaping and the evolving landscape in the UK, and key points for each of their business divisions which now includes the new Soft Drinks product vertical, increasing diversification. Finally, the team took part in a wide-ranging Q&A session, taking questions submitted by viewers. The Investor Presentation was covering highlights of the company's interim results for the six-month period to 30th September 2024.
?si=szkVFCunYl8mrUKsI hold Severfield (LON:SFR) so while the huge drop today concerns me I do feel it is an over reaction. Slower than expected economic recovery, tighter pricing, delays and cancelation of future projects as well as full year profits forecast to be below expectation provide only part of the reason. They are not completely surprising in the current climate and don't justify such a dramatic fall.
The big issue is no doubt the £20m charge for remedial repair work to 12 of its bridges that fell short of compliance requirements is a serious setback for shareholders. I am worried but for now I am going to sit tight and wait and see. Severfield (LON:SFR) has a lot of good going for it, increased revenue , a good dividend and buyback scheme, a prospering operation in India and a decent balance sheet. I would be grateful for to hear anybody's thoughts or idea's.
Aston Martin Lagonda Global Holdings (LON:AML) Announcing a placing after close today. I wonder what the price will be?
Hi Graham, Megan and Roland, Since subscribing in 2019 my investment performance has massively improved, through adding undervalued quality names with strong rankings. You'd think I knew what I was doing over 45 years plus but hey! My portfolio is focused towards value shares with reasonable dividends with a good smattering of growth stocks. All UK listed 100/250 shares plus one well known fund. I try not to sell, I'm not a trader, though have done on a few of my older pedestrian performers to buy into a few names that Stockopedia have alerted me to. However, maybe we have been unlucky this year but a couple of potential strong performers that I have put cash in, like VSVS and SFR have seriously disappointed, and of course we know of others. In these two cases boards have given very positive updates only to backtrack in a big way. May I ask a 64M$ question - is there anything from share price movements before trading updates that subscribers could have spotted to possibly consider taking profits rather than see those disappear into losses? Not a one line answer I know but maybe I (and possibly others) need more help in selling! Many thanks, Andy
Andy, after several decades of stockpicking, I still find deciding what and when to sell at least ten times harder than deciding what and when to buy - you are certainly not alone! So I too will be interested in any words of wisdom from the home team and indeed the many wise subscribers who post comments here.
"is there anything from share price movements before trading updates that subscribers could have spotted to possibly consider taking profits rather than see those disappear into losses?"
A very good question. I will try to give a view for discussion.
The short answer from my experience is no. In some cases there will be price decline prior to a profit warning yet in other cases the price could have had a good run up to to results only to fall back on poor figures. Frustrating.
There are some instances however where you might be able to move the dial a little in your direction.....
Does the company have good public visibility of its business ? If so, the private investor has more useful information to work with prior to results when deciding whether to buy or sell. Some businesses are just too opaque for the private investor to understand.
Is there a key metric which underpins the share price? One example might be steelmaking for instance where the high fixed costs mean that there is great sensitivity to whether the sale price is rising or declining. The selling price of steel is critical to the investment case and could give an a very useful indicator of profit or loss.
As an aside, go back a number of years and you might recall Corus ( the old British Steel). You could have bought Corus at any stage between 10p and £6 with a key indicator being whether the company was achieving sales price.
Another factor is the quality of management and do they treat all shareholders equally? Good management will be even handed and less likely to leak information selectively. We have all seen a share price decline prior to poor results and wondered if the private investor was being treated fairly.
For context, my own style of investing is buy and hold looking for very steady returns over many years, so maybe I am not the best at monitoring prices around results. It would be very interesting to hear other views.
What to do... I try to have a virtual stop loss at -15% Team17 (LON:TM17) just hit it, do I sell in the morning....
Decisions, decisions...
The same rule did make me sell my Bitcoin at $19k last year so it's not always right :)
I see a director of Team17 (LON:TM17) sold £6m at 210p on 7/11/24.
True but more buys than sells amongst the major shareholders Team17 (LON:TM17)
Yes but not by directors.
Yep - Debbie Bestwick, the co-founder and long-time CEO of Team17, stepped down after over 30 years at the company. She will remain in the CEO role until her successor is appointed, after which she will transition to a non-executive position on the board. Bestwick stated that this decision allows her to focus on family while continuing to support the company's leadership and growth strategy.
Recently, Bestwick reduced her stake in the company by selling over 3 million shares, leaving her with an 18.7% ownership. This move reflects a shift in her involvement as Team17 continues its operations under new leadership.
A falling knife, albeit presume thought you had found the bottom.
From books I've read (reading) hope is the last man standing.
Taking losses is hard, running winners is hard - It's just hard - but fun yes :) - hence don't risk too much on one punt.
I know I'll get hated but why fight trends. The market has no regard to your circumstances.
Harry, I agree 100%. "The trend is your friend."
There's a bit of weirdness going on at Team17 (LON:TM17) (and has been for a few days).
Take today, 1.5 million shares traded essentially at between 191p and 195p. Then we get a closing uncrossing trade (UT) of 126 shares and hey presto the closing price is 185.5p.
As far as I'm aware no other exchange does this UT/Closing auction thing - one more reason for companies to avoid London.
As is mentioned on this thread, on the face of it Brickability (LON:BRCK) is up over 9% today, but if you remove the spurious UT at yesterday's close it's hardly moved.
(Giggles and smirks from the city boys, but they'll be getting their P45's in the future as London contracts.)
Don't hold either.
Hi Albertos, With regards the Closing auction - both NYSE & Nasdaq have closing auctions. They also have opening auctions too.
Rather it is the way most AIM stocks which Team17 (LON:TM17) is, are traded, which is generally via SETSqx ( a combination of Market Maker and auctions) but most volume is traded via market makers and so the auction, be it the open or close is generally a small volume event.
If you look at stocks traded via SETS (FTSE 100, 250 and others ) then the auctions are generally much bigger volume events. Eg. Tesco (LON:TSCO) 36% of todays volume traded on the the closing cross and Telecom Plus (LON:TEP) 16% of todays volume traded on the closing cross.
Team17 (LON:TM17) up 10% today, just another brick in the wall,
Supreme (LON:SUP)
Is there some sort of hidden censorship going on here? Earlier I published a link to the CEO and CFO talking about today's results that I had found helpful. My post got a couple of thumbs up and then vanished. It was not replaced by the usual banner saying it had gone because it violated rules. I have not received an email saying why. This is not good.
If you want to listen to them speak about the results then go to www dot youtube dot com and put e7t4RrKAgH0 in the search box.
Lets see how long this post stays up.
I was one of the thumbs up!
Hi Graham, thanks for all today's in-depth coverage.
I don't hold but would be interested to see Halfords (LON:HFD) reviewed if time allows tomorrow please; I ask because partly factored in or not the wage and NI increases seem pretty frightening, and also because there are a number of moving parts here, there is more to Halfords than just car parts and bicycle shops, and some interesting developments, for example the Fusion business perhaps being one of the factors behind the SP bouncing today. There are also good comments from subscribers below on debt and dividend worth considering.
My lovely local tyre shop I have been using for years has just changed logo and is now part of "Halfords (LON:HFD) " complaining the IT system doesn't work but wonder if that is more people who are really good at fitting tyres and not IT professionals coping with week 1 of a new system? With all the wonders of rather than just calling and asking do you have a R185/55/15, and getting a call back when it is in stock, with a quick when should I drop in, so like yesterday I just drove my mum's car in, 10 minutes later two new tyres and out I go, I had ordered the tyres on Friday afternoon.
Anyway for a small town, two of the independent tyre shops are now Halfords, plus the main Halfords store on the industrial estate, which sells the usual stuff but will fit your wipers/light bulbs/roof rack. I can see a gentle consolidation going on, people will always need a new tyre!
I use Tyres on the Drive for tyre changes, another Halfords brand Tommy. If you pardon the pun there are 'a lot of moving parts' to this business.
I use Black Circles, don't think they use Halfords, get discount on the normal prices. Tyres last me about 7 years, so rarely change them.
No love for Telecom Plus (LON:TEP) and their interim results today - double digit growth in customer numbers continues to drive bottom line increases (revenue dropped, as did expenses, due to the drops in energy prices in this period compared to the prior year)...
But a p/e of about 15-ish according to the back of my envelope, and an update on their dividend policy to promise a full year dividend of "at least" 94p... so at the current share price of about 1810p, that's a yield of about 5.2%.
I continue to hold - no reasons not to. Think I originally bought at about 130p or something back in 2003... ;)
There's a lot more output here since Paul left. I welcome the wider coverage too and have just renewed my subscription. Thanks Graham and team!
I agree with eParo re coverage--thanks to team
Halfords (LON:HFD) l see estimates the change in NI, will cost them about £23m, they have 12,000 staff. That is over 40% of their net profit.
This figure looks a lot higher than other estimates, l thought it was about £600 per employee? Not nearly £2k? Seems these figures are for more than one year, they estimate £9m for 2026.
Halfords (LON:HFD)
good question Rusty - best answer is to email the company i suspect they would be more and happy to share the details of their calcs. I suspect many companies are happy to use highest value here possible so that if there are shortfalls in future performance its seen to be "not their fault"
Ref the £600 per person - thats only a % of the extra costs . the extra Ni is £600 per person (presuming everyone at 9.1k) plus 1.2% of salary costs over 9.1k.
The extra 1.2% is probbaly going to be an extra 50% of the £600 per person though so i doubt NI alone could make up the £23 mill.
The obvious reason for the difference might be minimum/living wage increases - it would make sense that they would have planned for that going up anyway. So if i had to guess i would say diff is most wage increases that were partly already factored in but not fully. What they might need to do is up salaries for those on more the minimum wage by more than previosuly expected so as not to overly annoy those staff.
It is closer to £2k when you factor in the minimum wage rise.
That will be a huge hit to profits then. Can't see companies increasing their prices by 40%. I think the Government has done too much at the same time, these changes, should have been more gradual.
If profits fall then so will taxes.
Supreme (LON:SUP) some additional thoughts on the future.
They market their own vapes and eliquids and can considerably undercut competitors. This will be excellent news when duty starts to be charged as those £4 vapes become £6. Supreme will be able to sell their own vapes at £4 including duty, taking market share. They have stated this will be their operating strategy in this regard.
They will be going into their own brand energy drinks business using their recently acquired drinks company. Think of Red Bull or Prime, but at a significant discount, also working with discounters to provide their own brands. Still a growing and exciting market to penetrate.
Wellness / protein style drinks, again, only the tip of the iceberg so far, but getting traction, already in Boots so expanded market coming down the road.
Those in themselves should be good enough, but if you add to the fact that people may be considering switching to cheaper alternatives, then this will drive even more business their way.
I'm of the view that regulation will help the company, they can quickly adjust to market conditions, deliver at speed and the smoking vote today will only shine the light on why vapes are required, even if just to wean off tobacco - I heard a smoking charity advise that if the smoking ban does come in, then there will just be a stream of younger people moving towards vapes.
Supreme (LON:SUP)
They market their own vapes and eliquids and can considerably undercut competitors. This will be excellent news when duty starts to be charged as those £4 vapes become £6. Supreme will be able to sell their own vapes at £4 including duty, taking market share. They have stated this will be their operating strategy in this regard.
I was thinking the opposite to what you are saying. I think the vape tax could really hurt their competitive edge. At the moment most e-liquids are about £3 - £5 per 10ml. Supreme sells theirs at £1.20 - significantly undercutting the competition. So you currently get about 30ml of 88 vape (supreme e-liquid) for the same price as 10ml vs competitors - so approx. 3 x cheaper.
The tax will be £2.20 + vat, so £2.64 / per 10ml. So Supreme's price goes to £3.84 per 10ml. The competition that are at about £3 per 10ml - will then be about £5.64 per 10ml. So Supreme goes from a position of offering the consumer 3 x the amount the competition offers - but after the tax it will only cost you 50% more to switch away from Supreme (£3.84 instead of £5.64) - at the moment it will cost you at least 200% more to switch away - thus their competitive edge will be weaker.
If we assume that a lot of their sales is based on price, then the competitive edge will be less. Personally I don't like the 88 product (really dislike it) and therefore have always paid about £4 - £5 per 10ml for a 'higher end' product. I do assume that many of the customers vape 88 because it is so cheap. If the price of the competitor is no longer that much more, then surely a lot of people are going to move to a product they prefer but couldn't justify the mammoth price difference.
I know Sandy is talking it up as good news - Sandy is certainly a very good talker. Personally I am not sure exactly how this will play out, but I think they will need to stay nimble and smart to keep their market share. The tax isn't until Oct 26 so I am holding for the time being as I think it is still undervalued, but I will not be holding in the months leading up to Oct 26 as I think this one is far from obvious as to whether Supreme will end up a winner or loser as a result of the tax. Other regulation I do think will strengthen the reputable players like Supreme. But this tax really does screw up the business model - regardless of the spin Sandy's putting on it. Just my opinion.
Very good point about 'addiction'. Can raise the price but doesn't necessarily affect demand, if the product is good/better etc, a couple of pounds doesn't make you give it up.
There seem shed loads of protein meal replacement/workout supplement products including my early days investment genius buy of THG (LON:THG) - perhaps snake oil is more appropriate.
See a famous car maker is seeking retail funds on Primary Bid - are these people crazy. Who is their market - suggest not people who subscribe to Stockopedia.
Looking at car manufacturers from the golden age of the 50's and 60's see China not only has MG but Lotus Technology (NSQ:LOT) - good god in heaven. Where I work there is an electric black cab prep/maint workshop LEVC which googled is owned by Geely a Chinese co. Daily see two or three transporters turn up offloading. They even have a van (super cool not like Musk's back to the future offering).
All interesting, fun (maybe) and don't put all the eggs in one basket (I mean the FTSE).
I see your point but as a former newsagent and smoker, when the price goes up the amount of people that moved from Benson to Lambert and Butler was noticeable.
I’ve yet to see people move up to a ‘better’ brand when prices increase.
When I was a smoker I stayed on Embassy come what may and there will always be those who are loyal to their brands.
Supreme aren’t aiming for that (10%?) of the market. They will always go for those who are price sensitive.
That's a really interesting point. Perhaps when prices go up, consumers become more price sensitive and they will gain more market share. Glad I have a while to think on it. I was surprised the tax wasn't coming in earlier but at least I won't have to rush any decisions in this regard. Many thanks for your response, certainly a very valid point and may well be the case.
Other thing to consider with Supreme (LON:SUP) is that they will generate circa £60m of net cash by then which is 30% of their market cap. So even if they dont invest and flatline at 20p (and I doubt that) we are looking at a fwd cash adjusted PER of 6 or less.
Yep it does still seem undervalued regardless of the tax implications. But this market has such poor sentiment - I am still unsure about holding it going into Oct 26. But at least we have some time to ponder. Many thanks for the input - I had thought you had left the forum. Good to see you're still about. Much appreciate your insights!
great!
Shore: CMC needs to communicate its strategy
CMC Markets (LON:CMCX) has established impressive business relationships, but Shore Capital says the market won’t get behind the share-dealing and spread-betting company until it communicates a monetisation strategy.
Analyst Vivek Raja retained his ‘hold’ recommendation but cut his ‘fair value’ target price to 280p after half-year figures on Friday. The shares rose 3.4% to 273p, recovering some of their decline on results today. This year the shares have soared 158%.
‘CMC has proved its technological competence amply, having secured impressive business-to-business relationships over the years with the likes of ANZ Bank, and more recently Revolut and ASB Bank,’ he said.
However, he said the issue has been about how the company ‘communicates monetising these relationships in a way public markets can sustainably get behind’.
This has created significant share price volatility and ‘sharp earnings upgrade and downgrade cycles in the past two years’.
‘Furthermore, in our view, limited disclosure pertaining to the core trading division reduces forecast confidence. Until these situations improve, we are unlikely to be able to recommend CMC’s shares,’ said Raja.
My first instinct when I read this is that they must have missed the 200% rally!
This is what Shore said on the 15th Jan. They had a 70p price target and SELL previously., right at the bottom.
"Shore Capital Markets lifted CMC Markets to 'hold' on Monday, and said that if the firm's momentum continues, its recommendation could turn even more "constructive".
The broker had rated CMC at 'sell' but took heart from the trading platform provider's recent trading update. CMC shares rose 4.4% to 136.92 pence. Shore has a fair value of 130p, lifted markedly from 70p...................................
Shore predicts CMC will achieve a pretax profit of GBP41 million for the current financial, a much more bullish prediction than the GBP15 million it previously had.
CMC Markets (LON:CMCX)
i must admit generally nowadays although i dont pay much attention to forecasts - i think most brokers seem to play quite a straight bat ref commentary on numbers and outlook generally - albeit it should always be buyer beware when everything sounds rosy.
It does seem here that for whatever reason Shore simply refuse to ascribe any value for stuff thats they are not being spoonfed ref future profits or has full expplanation as to wy it willm deffo turn up. Perhaps thats the issue - if the company dont know that they will have a good next 6-12 months or not its sensible for them to be open and honest in that regard - my reading between the lines is that the broker then presumably has to presume its worse that it might be and therefore is unable to put any positive spin on it.
No idea what solution if but to me it perhaps seems reasonably clear that shore should perhaps be ignored whilst tyhey are presuming doom and glolom and moaning about bnot getting what they want. all buyers need to be aware of is thats how it is and they kinds need to make their own judgement call here.
Does anyone really believe Shore would be deliberately negative for purposes that they can benefit from financially or their clients can ? that wouldnt seem right or proper to me if it is the case and i would be defaulting to that not being the case. Who knows the secret of the black magic box - not me for sure.
I think the negative critics have no idea or else own a hidden agenda.
I propose to hold Severfield (LON:SFR) though I do agree that management have been naff about their presentation. I'm interested to follow the link to "Full quote" and see how few shares are shown to have passed hands. Is this feature of any use whatsoever? Is it just a tiny indication of the last hour of trading, or more than that? Does it show a real relection of what is going on? Can we not be shown more datas and with some sort of timeline?
Go to LondonStockexchange website where you will find loads of info on todays trades
Buggering around ? Cebtaur media
Can anyone explain why there is a pretty daily trade of buys at 25p sells at 21p in cebtaur media ?
Is this some sort of market makers trying to stimulate some activity by selling 1 shate at 21p or buying 3 shares at 25p .
Actual buy is 23.8 and sell is 22,1 which is wider than normal and dont think there is any volune at all at the moment
Not sure who or why someome is dicking around buying 21p of shares and selling a quids worth
Further to my previous comments on Brickability (LON:BRCK) your comments, planetx, on Centaur Media (LON:CAU) seem to be another example of the fact that MM's seem to be able to manipulate SP's with impunity. Nothing new I suppose but it stinks.
The SP movement with CAU had got my attention so the ploy was working until I looked a bit deeper.
I don't know if other markets around the world are policed so poorly.
I can’t believe this BBC news item today.
“The UK's main financial regulator, the Financial Conduct Authority (FCA), has been condemned in a scathing report from a group of MPs and peers.”
https://www.bbc.co.uk/news/articles/cp9z332j4npo
However, as it’s written by such an expert, elite group I’d better take note.
“Current and former FCA staff said the regulator had a “defective culture” in which “errors and inaction" were "too common””.
Perhaps no point asking they look at Market Maker practices.
Public servants - chatting, sick, on holiday or diversity training. Work? that's a stretch.
A MM cant trade with himself in a quote driven listing or any other listing. This may be just brokers adjusting their holdings. Or if there has been a buy back then the same might apply.
A high multiple and the market hoping for Intercede (LON:IGP) to announce ‘ahead of’ rather than ‘meets’ expectations for FY25 causes today’s big SP fall. I think this is a good business with lots of potential. It’s not without risk so I’ve set out some pluses and minuses below. The results and share price are likely to remain volatile over the next 12 / 18 months. But if you exclude a large one off contract win, the underlying business appears to be building a track record of consistent progress.
Positive:
FY23
FY25
FY26
Annualised growth
£'m
£'m
£'m
FY23 to FY26
Revenue
12.1
16.1
17.7
13.5%
adj PBT
1.1
3.7
3.3
44%
Downside risks
Love the overview, cuddlesticks! G
I think that you need to add in that Intercede is under pinned by regulation. Which is already in force in the US, so US government are unlikely to reduce this cost under budget revues, This regulation is now coming to Europe. This is a big positive for the company.
Looking forward to Megan's comments on the Cranswick (LON:CWK) results.
I hold and briefly worked in the pig sector back in the day on a supply chain/marketing project with Scotlean Pigs. It is difficult to find quality agricultural-food business in the UK worthy of investment and Cranswick is a reliable long-term compounder. They have a 100% UK supply chain so zero exposure to Trump's tariffs; serious biosecurity (which is by far the biggest risk in a protein business); Adam Couch is a first-rate CEO, and I like their category dominance of pork and push into chicken and more value added.
Cranswick (LON:CWK) have delivered stable ROCE figures around 15% albeit with tight margins around 6.4%. They have a clean balance sheet with little debt and plenty of hard assets and have a long record of careful competence.
They supply all the UK's grocers - Tesco, Sainsburys, Aldo, Lidl, ASDA, Morrisons, M&S, COOP, and Iceland. I spent 20 years supplying the supermarkets and that customer breadth (outside of the big FMCG companies like Unilever and Nestle) is unusual. They are sufficiently confident to publish sales and trends for each customer which I have never seen before.
Growth is accelerating and they are working on several major initiatives to drive category volume in the pork sector. Aldi , for example, are investing heavily in driving protein sales, and see pork as a key player in the category. We are seeing an acceleration in growth at Cranswick (LON:CWK) over the past three years as they move up a gear, so look at the past 3 years performance, and compare it to the 5-year performance.
I think I have talked myself into buying some more.
Brickability (LON:BRCK) Roland. Is the SP really up 9% today or is this as a result of some manipulation of the SP late yesterday when the SP was taken down to 56p, or nearly 8%, on low volume after previously trading all day at about 60.5p (this was discussed briefly late in yesterday's DSMR)?
If it is a ploy, it seems to be working with headlines issued saying how the SP has surged but it hasn't really imho.
Peter, it was just an uncrossing trade at 56p after close yesterday. Spread was 60.4 -61p during market hours.
Was always going to open up again with similar spread (unless results were awful) spread now is 60.6-62p so no real change from yesterday.
Brickability (LON:BRCK)
is it manipulation or was it simply a fact that perhaps if some didnt want be holding "on update day" price was down due to there being more demand on the low side that high side. At present with little sign of general recovery and some companies still being too "glass full" ref outlook - it makes sense (without consipracy) that there would be weakness pre numbers on the basis news is more likely to be bad than good and people would be more likely to be selling pre news and waiting fro solid news before buying.
I would love to think most companies probbaly would be sensible now not presuming things would pick up lovely jubbly sometime about now if there aint much sign of that actually happening.
imho at times like these - the companies that can deliver in the harder times and show resiliance are the companies we should probably be wanting to be holding long term. Nowt worse that having glass half full at start of year only to have 3/4 of that glass taken off you at cloing time with no notice - if i am going to have beer confiscated i want six months advance notice cheers.
The market seems to like the cut of Halfords (LON:HFD) (I hold) results today. What catches my eye is thet they have gone net cash following good working capital management.
Previously amber/green, today's outlook comment is "comfortable with FY '25 consensus".
With a 6% yield and prior takeover interest rumoured (Oct '23 when the SP was 180p), perhaps the bottom is in here?
There was a suggestion on the call that the final dividend may be cut as they have stated they want to maintain cover at 1.5 to 2.5 times underlying profit after tax, which they are forecast to fall some way short of.
They said the board would take a decision at the finals but with trading conditions not picking up and the effect of the NI increases to at least partly absorb, the chances of them basing a decision not to cut based on better times ahead are diminishing and having stated their dividend criteria, they stand to lose credibility by not adhering to it, so I think the odds of a cut to say a 3p final (last year 5p) are rising, giving a yield just over 4%
Thank for your review of Brickability (LON:BRCK) Roland. Any thoughts on VP (LON:VP.) ?
Very creditable results from Brickability (LON:BRCK) and VP (LON:VP.) in what is a crap market and I suspect bottom of the cycle earnings.
it is rare for me to rant, but if only politicians, most of whom are useless could manage the country as well it would be in a better place. The current government has hardly covered itself in glory, but it appears a little less opaque than the previous bunch and has some ideas about getting infrastructure, construction and house building moving.
Simon Wolfson, CEO of Next (LON:NXT) gets my vote for PM with Kevin Roundtree, CEO of Games Workshop (LON:GAW) as Chancellor. One can dream.
We agree, great to see 55% of FY operating profit expectations already covered in H1 for VP (LON:VP.) https://www.equitydevelopment....
Thanks for your comments on IGP Graham and the early market seems to agree with you. I always struggle to buy shares on these sort of multiples. That said I do hold them but largely as an example of a great little british company and I think we all need to get onboard with rule britannia given the way the world seems to be going.
You're welcome, Camtab! I've always thought that there's nothing wrong with owning a few shares for non-financial reasons.
Hi Graham,
Will you be looking at Brickability (LON:BRCK) sometime this morning? Thank you to you and the Team for all your work so far!
Kind regards, Graham.
Hi Graham, Roland is working on BRCK as we speak! You're welcome!
I have written what I hope is an interesting and informative report on the Mello meeting in Derby last week. You can find it on my substack which is FOC. Please go to substack.com/charlesford It will give me a buzz if you subscribe, totally FOC.
Thanks for this; would never have found it on substack (which looks like a rabbit warren to me..). I can never justify going to Mello (even though this one was +/- local to me).
I love Mello physical investor events for so many reasons. They are busy and certainly value for money. Great opportunity to network, listen to experienced professionals and interact with companies presenting. If you have never been you can even take up the offer of a free trial ticket.
Free ticket? mmm.. Good thought. Thank you
I think that should be substack.com/@charlesford (you've missed out the '@')
AO World (LON:AO.) - just a reminder that we are hosting an Investor Presentation with management at 11.15am this morning - sign up to register at the link: https://www.equitydevelopment....
Surprised no-one has mentioned IG Design (LON:IGR), does not look good, profits are way down, shares down 13%.
Severfield (LON:SFR) huge drop today. Yet a stock ranking of 98…. :/
Severfield (LON:SFR) Drop here looks just a bit other the top - outlook not great but not exactly catastrophic. Stock ranks certainly no guarantee against major sell off - I think Card Factory (LON:CARD) had a 99 rank but lost almost half its value recently.
IG Design (LON:IGR) is down over 50%, that was a high ranking stock. Stockopedia only looks backwards. Enwell Energy (LON:ENW) another down over 50%. Kingfisher (LON:KGF) down around 25%.
As well as the worse outlook they seem to have lost £20m on work done on 8 bridges with a contingent liability for 4 more where costs not yet known. Not a hint of any problems in last agm statement. Have sold.
Card Factory (LON:CARD) I hold and think the fall is overdone.
I think they should be able to pass on the NI rise by increasing prices.
Yet at 08.30 Stocko still showing yesterdays SP.
Yes Stocko slow in updating big fallers.
Severfield (LON:SFR)
OUTLOOK
In the UK and Europe, the market backdrop is currently challenging. The previously anticipated recovery in some sectors has been slower than expected and tighter prices are continuing to impact our profitability in the short-term. In addition, some large project opportunities for FY25 and FY26 have been either delayed or cancelled and, given the current market backdrop, we remain vigilant to the increased risk of delay to expected orders in the short-term. As such, the Group now expects underlying profits for the full year to be below our previous expectations. The increase in employer national insurance rates announced by the UK Government in the October budget will impact our business from FY26 onwards. We estimate the combination of lowering the earnings threshold at which employers start paying national insurance contributions together with the increase in rate will in aggregate increase our employment costs by c.£2m per annum before any possible mitigation.
Severfield (LON:SFR) As well as the poor outlook there was also a £20m hit from bridge repairs - I don't believe this was previously announced so this will also have spooked markets.
Severfield (LON:SFR) There may recoveries from third parties sand/or insurers for the bridge repairs.
I think the big drop in Severfield is more to do with the bridge problems and their initial, and perhaps continuing, lack of disclosure. If the remaining 4 bridges without a remedial work plan were, for instance, all rail bridges, the contingency sum (which I couldn't find clearly identified in the report - you appear to have to deduce it) might well be completely inadequate with very expensive and difficult to obtain access to investigative work, followed probably by extremely expensive remedials with very limited access and lots of extra costs to pay from Network Rail. Of all the authorities I had dealings with for Civils work access the rail work was the most awkward and involved the lowest productivity during the work.
Not sure what they think are the possibilities in terms of claims from the clients, but I feel that they have just about disclosed that there are a few clients involved which makes it less likely, imo, that claims would be valid, leaving just insurance claims of unknown validity further down the road perhaps.
Ideally we will cover HFD and AO, it's a busy morning but we'll do our best to cover as much as we can. Megan is here and Roland will be joining shortly.
Graham - will AO World (LON:AO.) make it onto the list today ? It's an interesting one with the whole MusicMagpie thing happening for increased mobile phone action, Frasers Group increasing to over 24% and today's RNS showing the continued swing to profitable business rather than volume - loving the "outlook upgraded again" statement. I bought into it in June after Equity Development's note, so hoping they update today also.
Marks Electrical (LON:MRK)
Frasers have taken a stake in Marks Electrical announced today
Anyone one know what Mike Ashley's strategy is because i am completely confused!
Scatter gun? :)) to be fair he’s a trader isn't he? I’m sure he has a n angle on every purchase, maybe just punting, maybe just getting a seat at the table maybe learning from another business. But it is puzzling.
We are hosting an Investor Presentation with AO World management this morning at 11.15am if you're keen to listen in: https://www.equitydevelopment....
Mobile is very interesting and so is their membership scheme. Who thought people would pay c£40 for membership to an electrical retailer...but they are. Opportunity for greater loyalty, basket size etc. And the competition is shrinking - size (or perhaps scale) really does matter.
Will you be covering Halfords HY Results today? Thanks
Cranswick (LON:CWK) interims look encouraging on the face of it, running a business myself in the same industry it is very positive to see growth in some of the meat and poultry categories at a time where margins are becoming very squeezed. Vertical integration is the key here I think
Agreed ... also hold.
VP (LON:VP.) - Robust results confirm quality and growth ambition - new research here: https://www.equitydevelopment....
Vp has delivered another robust H1 performance, with revenue and profits essentially in line with the prior year. This achievement should not be underestimated in the context of significant end market headwinds. Good progress has been made with the refreshed operating model, with the overarching aim of increasing collaboration across the Group and improving customer engagement.
Full-year guidance has been reiterated and the half-year results provide cover for 55% of our operating profit forecast. Increasing National Insurance contributions will have an impact in FY26 but we expect this to be partially mitigated and continue to anticipate a return to profit growth next year. Management is committed to delivering long term growth, driven by operational improvements, targeted capex and strategic M&A. In our view, a track record of consistently high returns warrants a higher rating.
We reiterate our 1000p / share Fair Value estimate.
Mercia Asset Management (LON:MERC) - A rarity in the sector: Revenue +19%, EBITDA +34% - new detailed research report available here: https://www.equitydevelopment....
H1-25 (to 30 Sep 24) saw further progress of the Mercia 27 strategy which targets £3bn AUM (FUM + proprietary capital) and c.£10m EBITDA by FY27.
AUM was up 26% y-o-y and 1% over H1-25, following a series of large mandate wins in late FY24. Mercia is one of very few London-listed asset managers with positive net flows over recent periods.
H1 revenue was up 19% y-o-y and EBITDA +34%, a margin of 20.8%, up from 18.4% in H1-24. This is likely to ratchet up over the longer term as the business scales. PBT increased 75% and basic EPS increased 37%.
Our valuation is sum-of-the-parts based coming out at 52p, and we see no reason to discount the direct portfolio NAV given Mercia’s record of exits at a premium to holding NAV.
Until they get some PR skills and respond to shareholders emails I will not touch them.
Half year results from Caledonia Investments (LON:CLDN) today. I appreciate that this is outside the normal scope of this board.
I am a holder of this venerable investment trust, which has produced decent long term results but is impacted by a) large private equity investments and b) an enormous family holding, amounting to half the share capital. The Cayzer family must have done pretty well out of it, despite the discount.
My observation is simply that this is a decent long term performer, trading at a huge discount of around 40% to NAV. I have a good sized holding, acquired over the last 6 months. It's difficult to see how the discount can get much worse, so the margin of safety is substantial. 30% of the holdings are publicly quoted and liquid, so the 40% discount applies to 70% of the portfolio. I make that a 57% discount on a pretty reasonable private equity portfolio.
I note that RIT Capital Partners (LON:RCP) is reducing it's discount, simply through better communication.
Both companies are buying back shares in reasonable quantities, RIT Capital Partners (LON:RCP) especially ( I think they've retired 7% of the company).
This is what happens when the UK stock market is disinvesting.......
I'm a plodding investor, so both of the above suit me, as does AVI Global Trust (LON:AGT) , which is effectively an activist investor in discounted trusts and companies.
I have held #CLDN for 12 years or so and plodding is exactly what it gives you. It’s conservatively managed but produces decent returns over the longer term. Issue is as they continue to buy back the Gayser family ownership is increasing and will be close soon to 49.9% limiting the ability to buy more shares back unless they sell some. Either way something needs to give on this one in the next year or two to realize the value to shareholders
Hi Appreciate the update on Caledonia Investment been looking at this for a while maybe a good home for funds in these volatile times
Intercede (LON:IGP) is on track and continuing to make progress. Seems to have a very good niche in the market and demand looks robust. I continue to hold
A very positive set of results from Intercede (LON:IGP).
Continuing growth and adding new contracts with very high gross margins and cash positive supported by deferred revenue of £6.1m which equates to 66.6% of current H1 revenue. However, it is difficult to determine how much of the deferred income will relate to H2.
Intercede (LON:IGP) is on track and continuing to make progress. Seems to have a very good niche in the market and demand looks robust. I continue to hold
Supreme (LON:SUP) - Interim Results: "margin improvement and FY25 outlook raised" - new research freely accessible here: https://www.equitydevelopment.co.uk/research/h1-25-margin-improvement-and-fy25-outlook-raised
For the six months to 30 September 2024, Supreme reported healthy revenue growth of +8%YoY (£113m) based on both ongoing business and the acquisition of Clearly Drinks Ltd., with (adj.) EBITDA +22%YoY at £18.5m, underpinned by gross margin improvement +299bp to 29.6%. The (adj.) EBITDA margin was 16.3%, compared to 14.5% a year earlier. The improvement in profitability underlines Supreme’s breadth of market position and depth of expertise in the distribution of a wide range of household goods. The Group notes a strong start to H2 and has issued raised FY 25 (adj.) EBITDA guidance of “at least £40 million”.
With our FY25 guidance raised from £37.0m (adj.) EBITDA to £40.0m, our FY26 outlook remains unchanged, principally reflecting the full impact of the ban on disposable vapes. Our Fair Value remains 225p/share.
Sparkling result by Supreme (LON:SUP) for the half year, with FY25 ahead of expectations almost 10%, interim div up and excellent prospects going forwards in all divisions. I already hold a fairly full position, but if there is ANY weakness today I will fill my boots.
yes looks promising. ive been building a position in supreme for the last year and growing nicely
just bought some more at 175 ish