Daily Stock Market Report (Tue 4 Feb 2025) - US Tariffs, GMR, FTC, ALU, FCH, VOD, MAB1, DGE

Good morning!
The FTSE fell by 1% yesterday and the S&P 500 was down by 0.8% on concerns over Trump's tariff plans.
FTSE futures this morning are slightly lower again, down by 0.1% to 8560.
Tariffs on Mexico and Canada have been delayed by one month, and Trump has said that the UK may be able to avoid tariffs.
However, he also says that tariffs on the EU will "definitely happen". Tariffs of 10% on Chinese goods have already been implemented, and China has immediately retaliated with tariffs of their own on US exports: 15% for US coal and LNG and 10% for crude oil, farm equipment and some autos, starting next week.
I'm hopeful that the UK will not be directly impacted by Trump's tariff plans, and that many of the stocks we cover in this report will be able to avoid major disruption caused by this issue. But it seems inevitable that a trade war between the two largest global economies, and probably involving several other major economies, will have far-reaching effects.
1.15pm: we've reached the cut-off time for today, thank you everyone.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Diageo (LON:DGE) (£53bn) | Interim Results | Volumes -0.2%, op profit -4.9%, leverage 3.1x EBITDA. Dividend held. Tariff/macro headwinds. Removed medium-term guidance. | AMBER/GREEN (Graham) Tariff and general macro uncertainty leaves DGE unable to make useful forecasts for now. I'm a huge fan of this one but I accept that there are plenty of reasons for investors to stay away. |
Vodafone (LON:VOD) (£18bn) | TU | Revenue +5% to €9.8bn in Q3. On track to grow in line with FY guidance, reiterated today. | AMBER (Roland) |
Crest Nicholson Holdings (LON:CRST) (£449m) | Final Results | Results in line with guidance. Rev -6% to £618m, adj PBT -53% to £22.4m. Completions -7%. Interest rates holding back outlook. | |
YouGov (LON:YOU) (£423m) | TU | Modest underlying H1 growth, core biz stabilising. Performance in line with mgt exps. CEO leaves. | |
Mortgage Advice Bureau (Holdings) (LON:MAB1) (£416m) | Business update (CMD) | Possible move to Main Market. Medium term target to double revs with adj PBT margin >15%. | GREEN (Graham) Excellent news that they are considering a move to the Main Market, and aiming to join the prestigious FTSE-250. Ambitious growth targets announced too, which I hope are realistic. |
| Funding Circle Holdings (LON:FCH) (£405m) | Response to press article | They are confident that the purchaser of defaulted loans on their platform will be successful at trial. | AMBER (Graham) I'm cautiously switching to a neutral stance as it's not clear to me how serious this problem might be for FCH's existing loan book. |
Filtronic (LON:FTC) (£218m) | Interim Results | Rev +200% to £25.6m, op profit £6.8m. “Strong start” to H2 supports current exps. | AMBER (Roland) |
Devolver Digital (LON:DEVO) (£107m) | FY TU | Returned to +ve adj EBITDA, in line with exps. Double-digit YoY rev growth to >$100m. $42m cash. | |
Alumasc (LON:ALU) (£104m) | Interim Results | H1 rev +20%. Adj. PBT +19% to £7.5m. Outlook: confident in achieving FY25 expectations. | GREEN (Roland) |
Gaming Realms (LON:GMR) (£104m) | FY TU | Adj. EBITDA +30% to £13m, in line. Early trading in 2025 is encouraging. | GREEN (Graham) Nothing obviously wrong and lots to like at first glance: a growing company with net cash and an undemanding earnings multiple. |
NWF (LON:NWF) (£77m) | Interim Results | Revenue -4% but adj. op profit +25% to £5m. H1 is in line. Expectations are unchanged. | |
Venture Life (LON:VLG) (£44m) | TU | Adj. EBITDA “broadly in line”. Some unexpected de-stocking. “Extremely positive” for 2025. | |
Various Eateries (LON:VARE) (£27m) | Final Results | Rev +9% to £49.5m, adj. EBITDA £0.3m, pre-tax loss £3.4m. Currently trading in line with exps. | |
Staffline (LON:STAF) (£27m) | TU | 2024: ahead of exps. Adj. profit £11.1m, cash £4.4m. 2025 outlook: impacted by macro uncertainty. | |
B90 Holdings (LON:B90) (£12m) | TU | Expects to at least meet exps for 2024, with further growth anticipated in 2025. |
Graham's Section
Gaming Realms (LON:GMR)
Up 4% to 36.85p (£109m) - Pre-Close Trading Update - Graham - GREEN
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile focused gaming content, is pleased to announce its pre-close trading update for the full year to 31 December 2024….
It’s a pleasant update from GMR which confirms that FY Dec 2024 was in line with expectations.
Revenues rose 22% to c. £28.5m while adj. EBITDA rose 30% to £13m.
The “Slingo” game (a mix of slots and bingo) seems to go from strength to strength:
This strong performance was driven primarily by content licensing, supported by growth across all major markets. During FY24, Gaming Realms launched its Slingo portfolio with 44 new partners globally and successfully introduced its games in West Virginia, the Company's fifth US iGaming market. Gaming Realms' content is currently active in 20 regulated markets.
Outlook: we learn that early trading in 2025 has been encouraging.
Licensing agreement: the Slingo brand has been licensed for many years by Scientific Games, one of the world’s largest lottery companies (headquartered in Atlanta). The two companies have agreed to work together for another five years, bringing Slingo games to Australia, Canada, Europe, New Zealand and the US.
CEO comment:
We are delighted to announce these strong results for FY24, which underline the continued appeal of our Slingo portfolio and other unique gaming content. Our success in entering new regulated markets, coupled with the addition of multiple new partners, has fuelled significant growth. We look forward to building on this momentum in 2025 as we broaden our market reach and further expand our innovative content portfolio.
Estimates
Many thanks to Canaccord for covering this, despite not being one of GMR’s joint brokers. Canaccord’s Wealth Management business owns c. 4% of the company.
GMR is beating Canaccord’s 2024 revenue forecast (£28.5m actual, vs. £27.1m forecast) and I’m guessing that Canaccord’s 2025 revenue forecast of £30.7m is probably too low now?
The adj. EBITDA forecast for the new year is £15.4m.
If these forecasts turned out to be accurate then the adj. EBITDA margin would improve even further to 50%+, having reached 45.6% in 2024. A reminder that this business is highly profitable.
Graham’s view
I’m happy to leave our existing GREEN stance unchanged here.
Simply put, I cannot find anything obviously wrong here.
The Exec Chairman owns nearly 9% which is a comforting level of alignment with other shareholders.
Growth in recent years has been really impressive with revenues approximately doubling since 2021, as Slingo's popularity spreads internationally and through a wide variety of channels.
The company earns very high quality metrics and EBITDA margins implying high levels of cash conversion (N.B. will want to double check this when we get the full accounts).
The company is expected to already have a healthy cash balance of c. £14m, according to forecasts, and will rise significantly during 2025 if expected profitability is achieved. GMR does not yet pay a dividend.
Given the attractions, the earnings multiple here does not strike me as excessive. Earnings per share for 2025 will hopefully be 3p+, depending on the level of adjustments that are applied and depending on which source you use. The StockReport, for example, shows a 2025 EPS forecast of 3.45p. So the earnings multiple is somewhere between 10x and 12x, depending on how you calculate it.
With no obvious red flags and apparently lots of reasons to like it, I’m keeping this GREEN to reflect my view that it’s a very strong candidate for further research, so that you can make up your own mind.
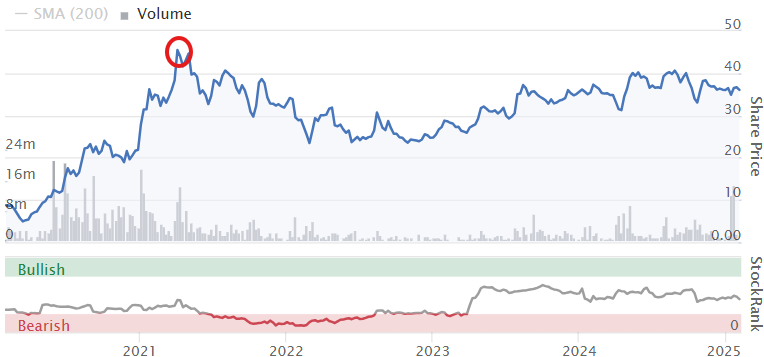
GMR shares are still trading below their 2021 high. The company only generated revenues of £15m in 2021, and hardly any profits, versus over £30m of revenues forecast for the current year:
Funding Circle Holdings (LON:FCH)
Down 26% to 92.4p (£304m) - Response to press article - Graham - AMBER
There was no early morning RNS from this today but the company was in the news.
The Times has published an article, “Court to rule if firm owned by Elliott hedge fund can pursue debts”, which refers to attempts by a debt purchaser to pursue business owners over personal guarantees. The loans in question originated at Funding Circle.
The article notes the following:
Last year, in an interim ruling, a judge said the two guarantors had a “real prospect of success” in establishing at trial that money they had personally guaranteed was not in fact payable to Azzurro or Funding Circle because of alleged issues with documentation and processes.
The article further notes claims that this debt purchaser may have bought 10,000 loans from Funding circle with a combined face value of c. £500m.
So the case going to trial may in effect serve as a test case for 10,000 Funding Circle loans, and perhaps many other Funding Circle loans.
If small business owners learned that the personal guarantees associated with their Funding Circle loans were to some degree not enforceable, it’s not hard to imagine that this could have serious consequences on the Funding Circle loan book.
The Times quotes Funding Circle’s CEO: “We’re really confident in our position.”
And they quote Funding Circle’s chief legal officer: “It is not disputed that the loans were validly entered into and that there is money owed under the personal guarantees. We are confident that Azzurro will be successful at trial.”
Graham’s view
I’m not a legal expert but I find it hard to imagine that guarantors will be able to avoid the liability altogether, although the Times article seems to suggest that this is possible.
I would say it’s far more likely that if there is a problem, it is to do with the attempted transfer of the loan from Funding Circle to the debt purchaser, Azzurro. And if the transfer isn’t possible or has failed for now, due to problems with documentation, it implies that Funding Circle might be left with the job of attempting to enforce their debts until this is sorted out.
What does all of this mean for the shares? Unfortunately, it creates two bear arguments against FCH.
Firstly, there are now claims in the media that FCH has been “totally unprofessional” in terms of how it handles loans and guarantees. So there is an argument that FCH is simply not very good at its core business, and that they needlessly created this situation.
Secondly, there are the immediate - and potentially long-term - financial consequences of loans getting stuck in the justice system. I’m referring not just to the test cases going to trial but any other of Azzurro’s loans that require legal input, and any other FCH loans that may end up in the same boat.
This situation is inherently uncertain and I’m downgrading our stance on this all the way from GREEN to AMBER, as I can’t properly assess FCH shares at this time.
As of July 2024, immediately following the sale of its US business, FCH had balance sheet net assets of £237m. Therefore the stock is still trading at a premium to book value, even after today’s fall.
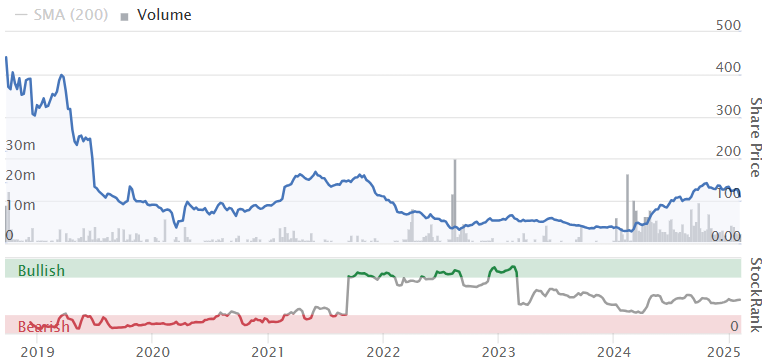
It has been a rough ride for long-term shareholders:
Edit to add: the company has released an RNS which states:
No question has been raised as to the general enforceability of loans and personal guarantees on the Funding Circle platform. It is not disputed that the loans were validly entered into and that there is money owed under the personal guarantees.
The case is going to full trial and we are confident that Azzurro will be successful.
I think this is consistent with what I said above: it is probably not a question of whether or not the money is owed, but more to do with the question of who the money is owed to.
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Up 4% to 748p (£433m) - Business Update - Graham - GREEN
We already covered a trading update from MAB1 very recently - see here. The company has beaten estimates for 2024, delivering adj. PBT of over £30m.
Today we have a “business update” rather than a trading update, that relates to the strategy for the next few years.
Those who are interested in learning more can look into the company’s “Capital Markets Day” at the LSE, which will also be available on webcast.
New medium-term growth targets:
Double revenues (2024: £266m)
Adj. PBT margin >15% (2024: I calculate 11.5%)
Cash conversion >100%
Double the company’s market share of new mortgage lending
Dividend policy: the company has had a policy of paying out at least 75% of profits to shareholders.
In order to attack the growth targets shown above, that dividend policy is being scrapped in favour of a progressive policy with no specific percentage target.
In other words, MAB1’s dividends might not grow as quickly as profits do in future, as more funds are likely to be kept inside the business for growth.
The dividend for FY Dec 2025 (to be paid in 2025 and 2026) is likely to be set at just 50% of profits.
However, there will be an annual review which may result in share buybacks or special dividends, if there is surplus capital over and above what the business needs.
Move to the Main Market? MAB1 are considering a move away from AIM and onto the Main Market, “with the ambition of meeting the criteria for inclusion in the FTSE 250 index”.
Graham’s view
This update is undiluted good news. As I’ve said before, I think that AIM stocks that can get into the FTSE 250 should do so, as it’s a prestigious index that’s worth being a part of. The companies in that list today with the smallest market caps include the likes of SThree (LON:STEM) , Jupiter Fund Management (LON:JUP) and Crest Nicholson Holdings (LON:CRST). MAB1’s current market cap should be big enough to get onto the bottom tier of this index, if they decide that this is what they want.
As for the medium-term strategy, the only question in my mind is whether it might possibly be unrealistic to double revenues and to double market share in a medium-term timeframe. Will acquisitions be needed to do this?
Doubling revenues doesn’t seem out of the question, particularly if market conditions are favourable.
But doubling market share means growing faster than everyone else, even in a rising market - MAB1 does have a track record of outperformance, but it sounds like they are planning to push themselves very hard indeed over the next few years.
This stock has been a regular fixture on my annual watchlist and I’m excited to see what they might achieve next.
Diageo (LON:DGE)
Down 1% to £23.48 (£52bn) - Interim Results - Graham - AMBER/GREEN
(Disclosure: at the time of writing, I have an indirect interest in DGE shares.)
These interim results have attracted negative media coverage and I can understand why, as the company takes the unusual step of removing its medium-term guidance.
Before getting into that, here are the headlines in terms of sales.
Reported sales down 0.6% due to unfavourable foreign exchange.
Organic sales up 1%
Volumes down 0.2%
And profits:
Reported operating profit down 5% to $3.15bn. Driven by foreign exchange and a reduction in operating margin.
Organic operating profit down 1.2%. On an organic basis, margin has fallen due to “continued investment primarily in overheads”. The curse of an extremely mature business!
Adjusted EPS falls nearly 10% to 97.7 US cents (equivalent to 78.7p at latest exchange rates).
So there is nothing much to write home about in terms of sales, volumes or profits.
Leverage multiple is 3.1x, which is at the very high end of what I consider to be acceptable, but DGE is the type of business that should be able to operate at this level.
The interim dividend is unchanged at 40.5 cents (32.6p)
Medium-term guidance. Here is the really bad news:
Medium-term guidance has been removed due to the current macroeconomic and geopolitical uncertainty in many of our key markets impacting the pace of recovery. We remain confident of favourable industry fundamentals and our ability to outperform. Instead in the interim, we will provide more regular near term guidance.
Medium-term guidance had been for sales growth of 5 - 7%.
CEO Debra Crew has this to say within her comments (emphasis added):
Diageo has anticipated and planned for a number of potential scenarios regarding tariffs in recent months. The confirmation at the weekend of the implementation of tariffs in the US, whilst anticipated, could very well impact this building momentum. It also adds further complexity in our ability to provide updated forward guidance given this is a new and dynamic situation.
DGE’s CFO is quoted in media reports as saying that planned tariffs would reduce operating profits by c. $200m in the current financial year (FY June 2025), before any mitigation measures. For context, total operating profit last year was $6.0 billion.
The tariffs would hit tequila and whisky that are imported to the US from Mexico and Canada.
Graham’s view
I’m going to be a little bit contrarian and express an AMBER/GREEN stance on this one, as I view it as one of the highest-quality large companies listed in the UK.
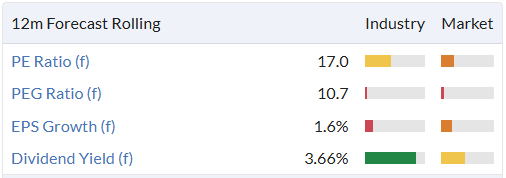
Some may reasonably take the view that it’s still too expensive, especially considering the enormous debt pile:
For me, the quality of the brands in the DGE portfolio is beyond question. But of course it is a very mature business and reduced alcohol consumption may ultimately see drinks companies rated in the same way that tobacco companies are rated - as legacy companies. That is possible.
As for the tariffs, I’m wondering if Trump is using China as an example and if the threats against Canada, Mexico, the UK and Europe might be little more than negotiation tactics. I presume there are a wide range of concessions he is looking for and would be willing to accept, over the next month, in exchange for the continuation of a light tariff regime. Negotiation is what he's all about, isn't it? So I think there must be a very wide range of possible outcomes in terms of the tariffs, if any, that might ultimately be applied against America’s allies.
And besides, making tequila and whisky expensive is hardly going to do anything for his popularity (not that he needs to worry about the next election!).
Bottom line: withdrawing guidance is a reasonable move by DGE, given the importance of the US market to them and the uncertainty hanging over the trade rules that may soon govern this market.Roland's Section
Filtronic (LON:FTC)
Down 3.4% to 96p (£210m) - Interim Results - Roland - AMBER
Filtronic plc (AIM: FTC), the designer and manufacturer of products and sub-systems for the aerospace, defence, telecoms infrastructure, space and critical communications markets, announces its half year results for the six months ended 30 November 2024 ("H1 2025").
We’ve covered Filtronic several times in recent months as it’s upgraded expectations for 2024/25. This has mainly been driven by a large contract with Elon Musk’s company SpaceX.
Today’s half-year results confirm that current expectations should be underpinned by a strong start to H2, but do not include any further upgrades. Let’s take a look.
H1 summary: I think it’s fair to say the SpaceX work has been transformational for Filtronic this year. These numbers cover the six months to 30 November 2024:
Revenue +200% to £25.6m
Operating profit of £6.8m (H1 24: (£0.4m)
Earnings of 3.08p per share (H1 24: (0.24p))
Cash generated from operating activities up 16.7% to £2.1m
Net cash exc leases: £5.1m (H1 24: £5.2m)
Filtronic’s half-year results show a healthy 26.5% operating margin against a reported loss for the same period last year.
This was achieved despite a 62% increase in the company’s overhead cost base during the period, reflecting a 16% increase in headcount and expanded manufacturing facilities. Two new production lines were installed during the half year.
Cash performance: the cash flow statement gives us a feel for some of the moving parts behind the scenes here.
£6.6m working capital outflow, due to rise in inventories and receivables
£1.6m spent on plant, equipment & intangible assets (software?)
£0.5m of capitalised development costs
The working capital movements explain why operating cash flow of £2.1m was so much lower than operating profit of £6.8m. However, I’d expect these to reverse over time if the pace of growth slows.
Overall, Filtronic operated at free cash flow breakeven for the half year, with net cash unchanged. I think that’s probably a creditable result in this situation.
Update on key markets: SpaceX has been the big story for Filtronics this year and the company seems hopeful of further growth:
Our strategic partnership with the market leader, SpaceX, continues to strengthen and grow. The success of the relationship has enabled us to deliver at high volume and high quality, working closely with our business and supply chain partners. This achievement has enabled both parties to consider further collaboration following the remarkable success of the Starlink constellation.
Low Earth Orbit satellites remain Filtronic’s key market and the company believes there will be further opportunities elsewhere in this sector.
However, all the company’s main live programmes with other customers appear to be due for completion in the next 12 months or so:
European Space Agency: a “prestigious programme” completes “over the next year”, material revenues to be recognised in FY26
QinetiQ: an active defence programme “will substantially complete in FY2025”
BAE Maritime Systems: defence programme will complete “within FY2026”
The UK’s Strategic Defence Review “pushed back the planned timing of a number of prospective opportunities”
My feeling is that there are opportunities in both space and defence, but some lack of visibility at the moment.
Outlook: the company reminds us that the “positive cadence of order intake” has resulted in material upgrades over the last two months.
Our order book is healthy and underpins the recent upgrades, whilst the opportunity pipeline continues to build serving us well as we move towards the next financial year.
However, there are no further upgrades today and nor is there any new guidance for FY25, according to Chairman Jonathan Neale:
we look forward to being able to communicate more about the next financial year as things develop during H2
An updated note from house broker Cavendish leaves forecasts unchanged today, highlighting the current lack of visibility on FY26 earnings:
FY25 adjusted EPS: 4.8p
FY26 adjusted EPS: 3.0p
Roland’s view
I can’t fault Filtronic for seizing the opportunity with SpaceX. My concern is that it looks to me like there’s some risk of earnings falling substantially below current levels next year.
From what I understand of the SpaceX agreement (I haven’t studied it in detail), there could be a lull in demand for Filtronic’s products next year, before a second phase of ordering begins in 2026 onwards.
From a long-term perspective, I can see that it might be worth accepting some volatility in earnings to continue benefiting from the company’s long-term growth.
On the other hand, the level of customer concentration here would concern me. In addition to the financial risk, I wonder if it might make Filtronic less attractive to other potential partners, who might feel they were always in second place for resources.
Filtronic doesn’t seem to split out the SpaceX revenue in today’s results, but the company does say that £23.5m (92%) of H1 revenue was to US customers. I don’t know how many other US customers Filtronic has.
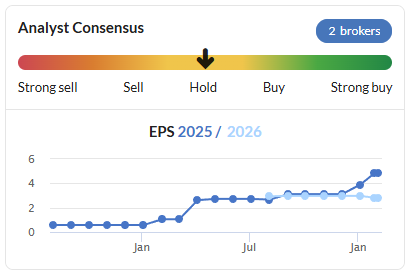
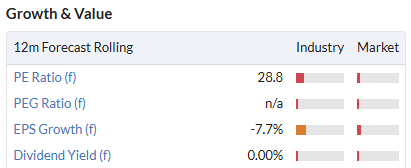
So where are we today? Filtronic is poised to deliver record results this year, but the current order book does not yet support a repeat performance in FY26. Current forecasts suggest earnings could fall by nearly 40% next year.
As a result, the shares are starting to look quite expensive on a rolling 12-month view:
Given the current lack of visibility and the apparent customer concentration risks, I’m going to maintain my neutral view here. AMBER.
Alumasc (LON:ALU)
Up 4.1% to 299p (£108m) - Half-Year Results - Roland - GREEN
This sustainable building products and solutions group is reporting its half-year results for the six months to 31 December 2024.
We are pleased to report a record first half, driven by both organic and inorganic growth. Group revenue grew by 20% compared to the prior period, which is a particularly impressive result given the challenging market environment.
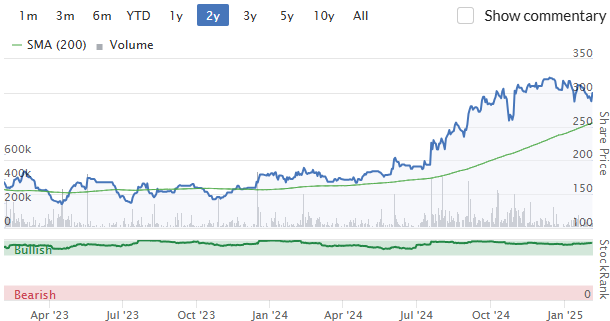
Alumasc has been an impressive trade over the last couple of years. The shares have been buoyed by strong trading, but also by the imminent prospect of the company’s pension deficit being eradicated.
H1 results summary: Alumasc saw half-year revenue rise by 20% to £57.4m, while pre-tax profit rose by 16% to £6.5m.
These numbers lift Alumasc’s trailing 12-month reported operating margin to 23.9% and its TTM ROCE to 24.0%. Both are very respectable figures, in my view, that seem likely to support continued value creation for shareholders.
Net debt was reduced to an insignificant £4.6m at the end of December, reflecting free cash flow of £5.4m for the period. That represents 110% cash conversion from H1 net profit, an excellent performance.
Cash generation could also receive a further boost if the pension deficit is eradicated. Alumasc contributed £600k to its pension scheme in H1 but says that the scheme is now “approaching self sufficiency”.
The group achieved growth in all of its divisions during the half year:
Water Management: revenue up 34% to £29.6m (15.8% op margin)
Building Envelope: revenue up 8% to £20.2m (12.5% op margin)
Housebuilding Products: revenue up 6% to £7.5m (25.0% op margin)
The company says that its largest business, Water Management, benefited from accelerated deliveries to a Hong Kong airport project during the period.
Water Management revenue was also boosted by a £5.7m contribution from ARP Group, which was acquired in December 2023. It’s nice to see this disclosed clearly.
Stripping the ARP revenue out tells me that Water Management’s organic revenue rose by 8.6% to £23.9m during the half year – consistent with the growth seen in the other two divisions.
Outlook: Alumasc believes it is well positioned “to continue to outperform the UK general construction market” while investing selectively to drive overseas growth.
Guidance for the full year remains unchanged:
The Board continues to remain confident both in the Group achieving its expectations for the year to June 2025, and in the significant opportunities available over the medium and longer term.
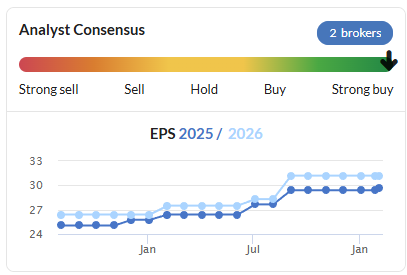
With thanks to broker Cavendish, I can also see that its FY25 and FY26 EPS forecasts are unchanged today at 29.4p and 31.4p respectively. That’s broadly in line with the estimates on the StockReport, which have been upgraded several times over the last year:
Roland’s view
Alumasc’s forward valuation doesn’t look too demanding to me, given the company’s strong profitability and balance sheet:
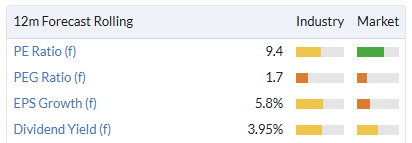
It’s also worth noting that strong cash conversion means the shares also offer a free cash flow yield in excess of 9% – an attractive measure, in my view.
The StockRanks are also very strong and I imagine they will remain so when today’s interim numbers are digested by Stocko’s algorithms:
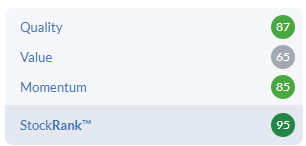
Alumasc’s double-digit profit margins and high ROCE suggest to me that the company’s products do have pricing power and perhaps some level of competitive advantage.
While this probably isn’t a business where I’d want to pay a high multiple of earnings, I’ve been impressed with progress at this business in recent years. I’m happy to maintain our previous GREEN view after today’s numbers.
Vodafone (LON:VOD)
Down 5.9% to 65.9p (£16.7bn) - Q3 FY25 Trading Update - Roland - AMBER
This third-quarter update from the FTSE 100 telecoms giant looked relatively positive to me at 7am, However, markets have taken a more cautious view due to ongoing challenges in Germany, Vodafone’s largest market.
Vodafone’s headline figures showed a return to top line growth during the three months to 31 December 2024:
Group total revenue: Increased by 5.0% to €9.8 billion in Q3 with good organic service revenue growth partially offset by adverse foreign exchange movements.
The company’s measure of organic service revenue grew in all its main markets except Germany:
Germany: -6.4%
UK: +3.3%
Other Europe & Turkey: +2.6% and 53.1% respectively (reflecting hyperinflation)
Africa: +11.6%
Business: +4.3%
The company also reiterated its full-year guidance for the year ending 31 March 2025:
On track to deliver Group Adjusted EBITDA of c.€11 billion and Group Adjusted free cash flow of at least €2.4 billion.
This compares to adjusted free cash flow of €2.6bn in FY24, but I think it should continue to underpin the current dividend, giving a prospective yield over 6%.
Disposals/M&A: the sale of Vodafone Italy also completed in December 2024 for €8bn, while Vodafone UK achieved regulatory approval for its planned merger with Three. This is expected to support higher utilisation and improved returns on capital in the future – a big weakness in this sector.
Germany: Vodafone also offers cable television in Germany, but changes to the law last year have had a big impact on this market. My understanding is that TV was frequently bundled by apartment landlords into rental packages, leaving tenants with no option. This is no longer permitted and tenants have free choice – meaning some have left Vodafone and many have had to be re-recruited.
This process is now nearing an end and Vodafone says it’s retained 49% of affected customers, or 4.1m households, against a target of 50%. I see this as a one-off headwind that should ease over time.
Vodafone’s other businesses in Germany saw mixed performance, with broadband customers -7k but mobile customers +23k. However, pricing remains under pressure in mobile and broadband, with both businesses seeing small falls in underlying revenue per user during the period.
Outlook: Vodafone’s FY25 guidance is unchanged today and the company expects to complete the merger with Three UK in “the next few months”.
The €8bn proceeds from the Vodafone Italy sale have been used to reduce debt and the board is targeting a further €2bn in share buybacks when the current buyback programme is completed.
Broker forecasts suggest earnings of 7.9 Euro cents per share this year, with a dividend of 5.3 cents. This prices the stock on a forecast P/E of 10 with a yield of c.6.5%.
Roland’s view
The bear arguments on Vodafone are well-known and largely justified. It’s generated returns on capital below its cost of capital for many years, has too much debt, and has destroyed a lot of shareholder value.
However, CEO Margherita Della Valle has done everything she has promised so far since taking charge in 2023. The changes have been substantial – Vodafone has sold its operations in Spain and Italy and secured agreement to merge with Three in the UK, reducing the number of incumbent networks from four to three.
This merger is expected to improve returns on capital – a critical challenge for the company and the wider sectors.
The group’s net debt has already fallen by c. 20% from its peak of €55bn, according to Stockopedia.
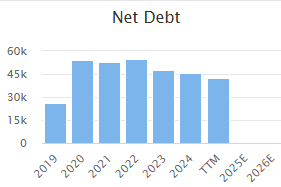
Germany remains a challenge, but Della Valle has made it clear this is now her main priority.
In the meantime, I think the group’s business in Africa – where it is one of the largest mobile operators and has an important mobile banking service – remains an attractive long-term growth opportunity.
Despite my cautious optimism, I think it would be naive to think that Vodafone couldn’t continue to disappoint as it has in the past.
On balance, I’m going to start our coverage with a neutral view. I think this is a fair reflection of the current situation. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
Ferrexpo (LON:FXPO) huge drop today will you be covering this?
Any chance of the p word Ben ?
Hi Lochiver, are you suggesting P could be for patience as well as P***se. Perhaps Ben doesn't realise that Ferrexpo (LON:FXPO) news causing the downward SP move came after 1pm which is the close off for the daily report. I'm sure it wasn't the only late news causing a large SP move yesterday.
We have been down this road on this forum before - So for those new here, PLEASE make a request with some narrative behind it, that way you may then spike interest in the hard working Team creating the daily MORNING output - they may then even respond the next day as a follow up!
Look at the reports daily word count, I couldn't produce my share each and every day as all the Team do - It is impossible to cover everything any one of us may be interested in.
Simply a request for some common courtesy ez when posters request stuff from the Stocko team.
Thank you Roland for an excellent summary of Vodafone's situation. I hold the stock and am fed up with the lack of progress. Your comments help understand it better. i will hold for a while longer. At least being paid to wait.
Really surprised how the market has reacted by the news. Expected the high dividend yield would hold the price with effectively an in line with guidance announcement.
At the moment, although there are prospects of future on board applications, I believe that the business for Filtronic is all in the ground stations, so the satellite refresh rate is not relevant.
Venture Life (LON:VLG) update for year to 12/24. (I hold).
The dreaded "broadly in line" which here, as often, means "a bit below". Cavendish have reduced their forecast for the year just ended by a few % - ajd. EBITDA is down from £11.7 to £11.3m. However, the outlook has actually improve and they have raised 25 and 26 estimates and added 27 giving £13.8m, £15.9m and £18.6m. They have also raised the sp target from 68p to 88p.
That boost is from several quite different factors coming together. These are discussed between PH and the CEO in a 12 minute Q&A that you can view here.
Nice write-up on Diageo (LON:DGE), Graham, although I dont agree with your Amber/Green rating and would concur with Stockopedia in calling it a “Falling Star”, Its a stock I would love to own because of its amazing brands portfolio, market dominance and “sleep easily at night” investment potential.
But since Debra Crew took over as CEO it never seems to be firing on all cylinders and never seems to get sufficiently cheap, presumably because it is widely held by income funds, to be rated as a substitute for a legacy tobacco stock- Graham’s thesis.
In 2023 it warned on weak sales in LatAm/Caribbean, 8 months later Crew said things were improving but the market was “unpredictable” as she reported a drop in total sales for FY24.
Trump’s tariff wars take unpredictability to a whole new level now and will potentially hit hardest in its biggest market, the US,so until guidance is restored it has to be Red/Amber.
I have to say that I am concerned about the enthusiasm that so many subscribers seem to have for widening this forum out to global stocks. We have three analyst contributors to DSMR and they are stretched enough adding larger cap UK stocks to their coverage. If asked to go global then how much actual analysis do you expect them to undertake?
Essentially, I think most of those who want even wider coverage are just feeling FOMO because US tech is massively outperforming UK small cap. That is fair enough, and for a balanced global portfolio you would want exposure to that area. Personally, I would gain that exposure through investment trusts but for those who want individual stocks then surely you want to find more localised expertise to guide you.
Absolutely no offence intended to Howard, who was simply enthusiastic about his own success story, but am I going to buy a stock I know nothing about that has a mkt cap some 52x forecast revenues for 2025 on the back of one post? No I am not! Importantly, this still wouldn't change if Graham, Roland or Meg gave it a thumbs up after a fifteen minute look through the numbers.
This is still a very useful site for me, but please can we keep it that way. I don't mind the odd comment on the likes of Diageo and Vodafone , but l mostly want to see incisive commentary on small and mid cap stocks, including those little snippets from some of the more knowledgeable subscribers that we are fortunate to have contributing here.
Well said, let’s focus on area of competitive advantage with long term opportunity, let’s avoid the FOMO trades, buy an ETF for these.
I agree with your sentiments Sparkler and especially your thoughts re the analysts workload... their ' value ' background and on the ground experience / expertise gives them a competitive advantage in the small and mid cap UK space ...
The US generally seems expensive relative to the UK but a) 'twas always thus ( more entrepreneurial / better resources etc ) and b) sharp sell offs of 20-30% tend to correct back up ever quicker these days... for those very expensive individual names, its great to have call levels in 20 - 30 % below the market ... without experts like Howard flagging to me ( Palantir Technologies (NSQ:PLTR) since $ 30 ), I'm unlikely to uncover them on my own ... As Ken Mitchell often notes, many readers gravitate to this report and won't necessarily see research ideas posted elsewhere...
We have already lost so many great contributors for various reasons, it would be great to encourage ideas from every source... absolutely nothing wrong with counter arguments against a stock, but personally I'd love this place to be as inclusive as possible...
Hi Cancun
Thank you for the kind words. I hope a few interesting non-UK stocks do get mentioned occasionally. Several of my interesting investments have come from random comments/posts on all sorts of forums.
Regards
Howard
Thankyou Cancun, I agree with your sentiment. this site should be as inclusive as possible. I believe that markets are inefficient and broker research troubled by conflicts, lack of experience and ability to take a long term view. We paint with a very broad brush when we ewxclude the US market with a view that it is overvalued. There are plenty of stocks there that may have potential there outside the Mag 7, 8 or 9 that rises to the lip whenever the US market is mentioned.
This is an excellent forum for learning and share ideas that can make money. that should be the general principal applied to its use. rather than narrowly focusing on UK small and mid cap. Lets be open minded when investing.
Well said, sparkler. Investing in US stocks when the market is at an all-time high is not for the faint-hearted, as the heroic ratings given to @Palantir Technologies (NSQ:PLTR) or NVIDIA (NSQ:NVDA) demonstrate.
You need a very bullish attitude to risk, which US investors tend to have, and you need some sort of information edge or sector experience before investing in these widely followed stocks, whose prices can move dramatically with each quarterly update -- or each time Trump posts something on Truth Social.
If all you have to go on are on the statements of CEOs and recommendations of sell-side analysts, you really don't have any edge and, while you can get lucky, the more risk-adverse would be better off investing in a US-focussed ETF or IT.
Let's keep the site anchored n familiar territory of small and mid-sized UK companies.
An alternative view...
I personally don't mind subscribers posting from a wider universe of stocks. There is no obligation for the writers of the DSMR to widen the scope of their output to match - its just user generated content.
I think my concern is that if we dissuade people from posting through various content rules etc that the thread will slowly die. Some days - unless an argument breaks out, there are very few posts and the thread looks a bit thin.
I would like to see, if possible, the main thread tidied up a little. Perhaps the "securities mentioned" box could be reduced or minimised, which in turn would free up space and make the discussion more readable? Just a thought.
I fear despite the great work from the Graham, Roland, Megan and the rest of the team they will spread their expertise too thin, dilute their quality and subscribers will lose interest bogged down with too much information.
Stonking set of results from Alumasc (LON:ALU) again this morning. 20% top line growth; 20% profit growth and 20% EPS growth! These guys are in a right sweet spot at the moment.... any business doing that level of outperformance vs the market must have quality products and a real need from customers
Agreed. Alumasc (LON:ALU) appear to be outperforming the building materials sector significantly. Better margins and better revenue growth. It does appear as though their product set is appealing to customers due to its quality and its green credentials. I hold.
Well done to holders of Brand Architekts (LON:BAR) .... agreed all cash offer from Warpaint London (LON:W7L) for £13.9 m, representing a very tasty 85% premium to the average price for the past three months. Sadly I don't hold Brand Arckitekts but I do have a decent position in Warpaint,
Warpaint London secures ‘exciting’ Brand Arkitekts takeover | AJ Bell
Isn't this news from Dec 5th, or did I miss something? Share price unchanged today.
Read the dateline, james: Dec 5th
Really Jeff .... ? James had already been alerted to it half an hour ago .. We all make mistakes... this sums up the negativity that has pervaded on this forum over the last few weeks ... I know that the markets are tough, but as Paul Scott used to say ' Its a team game '.... we're in danger of descending into ADVFN....
It's OK ... quite right; it is indeed Dec 5th and I completely missed it. Maybe an argument for holding fewer shares?!
It’s still good news either way. Hopefully Warpaint London (LON:W7L) stock price will move later in February when finer details are finalised.
This report has widened its scope to large cap and global stocks which is welcome. There is analysis/comment however on two big names today…Diageo and Vodafone. Any thoughts.
When I saw Gaming Realms (LON:GMR) numbers last year I downloaded Slingo.
I spent some money on it as a test.
It wasn't a native iOS game - felt like a java applet throwback. Horrible UX. I really struggled navigating it. I also thought the game itself was very poor.
I deleted it after about 24 hours and £10 spent!
Contrast that with a game that's genuinely amazing - Balatro (owned by Trufin (LON:TRU). I spent £10 on that and lost at least 8 hours playing it on a flight back from Australia. I've had to delete it too as it's far too addictive. Won game of the year at all the awards. It's a poker-esque game (no gambling at all). Top of Apple Arcade etc etc.
The irony is Trufin have no way of me (or anyone else) spending more money on Balatro after first purchase - even though I will probably play it many times over the years. Gaming Realms will never earn a penny from me again, but the poor people who get addicted to their game will keep spending on it.
I find the economics of the above comparison rather sad.
Hi
Strong results from Palantir Technologies (NSQ:PLTR) Q4 and annual results, after US session yesterday.
Share price up +22.75% in after hours (as at 8:11 GMT).
An extract from their results.
Full results report here ...
https://investors.palantir.com...
An extract for their outlook ....
Outlook
For Q1 2025, we expect:
For full year 2025, we expect:
Note the line .....
More colour with graphs about the results is outlined in Alex Karp's (CEO) letter here ...
https://www.palantir.com/q4-20...
Disclosure Palantir Technologies (NSQ:PLTR) is my largest holding.
Regards
Howard
I'm sure you are feeling pretty euphoric about your largest holding, Howard, but can I request that you post about a huge US stock somewhere other than this UK small/mid cap focused forum. Thanks.
I don't agree - I welcome the comment - this forum is no longer just limited to small / mid caps. I hold Palantir via VanEck Defense UCITS ETF USD A (LON:DFNG). Like it or not the tech / disruptors sector are the biggest market movers IMO.
I agree. Its an interesting comment and well done Howard
Hi grout123
Thanks for the comment.
Regards
Howard
Hi Trader Jack
I was also under impression the forum had opened up beyond UK small/mid cap focused forum.
Regards
Howard
Agreed TJ
For the football fans amongst us there was a lot of focus on the phrase “stay humble” over the last weekend
It’s really quite sad when posters come across as anything but humble on here
Hi sparkler
I apologise, I am under the impression this daily thread had opened up beyond a UK small/mid cap focused forum.
Regards
Howard
Nice numbers, but I think you ought to mention the market cap, which is $193Bn. So 50X revenue. A gamble IMO. Well done you, but others be wary.
hi Howard - Surely just a one or two line comment with a link to read the full blurb is enough
Hi bohenie
Ok will do.
Regards
Howard
Posting results announcements of stocks you hold and that have performed well without any analysis or explanation for why we could be interested doesnt add much value. Less so if its a foreign stock that fewer readers probably know or hold.
Palantir Technologies (NSQ:PLTR) is soaring because investors expect it to be a major beneficiary of Elon Musk's war on waste in US Govt and will possibly be given the job of modernizing defense procurement. But nothing has been announced so DYOR.
A bit of back-of-the-envelope analysis like I just wrote is helpful; telling us that your largest holding soared 22.75% yesterday is not.
Hi jeff narin
I have posted several times over the past, and at length the bull and bear case
Regards
Howard
Many congratulations Howard and thank you very much for flagging this one at $ 30 - 40 .... not that I pulled the trigger :(... inspired, well done...
Hi Cancun
Thanks for your response. If you are one for deep dives into possible investments I believe Palantir Technologies (NSQ:PLTR) has a lot more to go. But strong conviction is useful to see through the very obvious and undeniable bear case for the stock (valuation).
If you wished to look deeper these are some factors I place value on.
Quality of people and products. Presence (and leaderships) in government and commercial (notably US). Demands for their AI solutions which provide real value rapidly. Tangible alignment with the climate the new US administration seems to be forming. The rate of change (growth) they are sustaining over several reporting periods across many metrics.
It's not for the faint of heart I do not deny.
Regards
Howard
Many thanks indeed Howard and much appreciated....
Incidentally, I did just read the letter from Alex Karp that you posted above. I would urge other readers to have a look themselves and see if you agree that it is rather bizarre for a CEO commentary!
What do you think of the stock based comp and the directors selling billions recently?
Hi CautiousValue
The Palantir Technologies (NSQ:PLTR) Stock Based Comp. (SBC). has been reducing steadily over the years and I think it's in line or below most similar players such as Snowflake (NYQ:SNOW) and ServiceNow (NYQ:NOW) .
The whole SBC issue has been deeply debated by the investing community over quite some time.
My own personal opinion is this - the people have worked on the products for over 20 years, they DPO'd rather than doing an IPO precisely so insiders could achieve benefits from their long term efforts and risk taking. They used SBC to attract and retain the very best engineering talents in the world (which has unquestionably worked). They have not relented at all over the 20 years even while the market hated them (and many still do). IMO the SBC strategy was a key pillar which has helped to foster their unique culture and never slowing entrepreneurial spirit.
So, personally I supported their SBC strategy and I applaud the key people selling they shares as they see fit, they have earned it.
Regards
Howard
Good Morning, is there a news on FCH that I have missed this morning, as it seems to be taking a bit of a battering.
Re: FCH
www.sharecast.com/news/press-round-up-short-premium/tuesday-newspaper-round-up-astrazeneca-thames-water-funding-circle--18754482.html
There is a piece in the Times regarding administrative failures in the wording of Funding Circle’s loan agreements the casts doubts on the recoverability of loans made.
Thanks jonno - just caught up with this - and surprised the Mkt didn't react last year when the pre trial hearing came up - or did it escape the press at the time?
I really like the macro summary at the top and some content first thing, gets the comments section active!
Happy on first glance to read the RNS with Filtronic (LON:FTC. Figures look strong, but we knew they should be. Should meet the current years projection by simply matching what they have done in H1, although they have a strong pipeline. I would expect broker upgrades this year and next year.
Good news on other companies they will be supplying and the use of their tech in more arenas, and with the European Space Agency, shows that they have some other longer term contracts apart from Starlink.
Expansion will be key and delivering this at pace, would you see a need for a fund raise? This is by far my biggest holding in my portfolio having been in from on avg 0.14p, might even see my first '10 bagger' soon, and I've taken all my money off the table and will let the profits do their thing, although now represents 22% of my folio!
EPS 3.1p H1 with a broker target of 4.8p (recently raised) for the year, and not much visibility into 2026 (2.8p expected). Looks like a business that is under declaring and over delivering.
Filtronic (LON:FTC) sorry....
Yes, they have a habit of doing this. A lot of material revenue often is not there, especially for 2026. In a way I'm glad that the UK defence strategic review has been delayed so they can get on with what seems like a full order book...
A drop this morning, I expect the price will recover by the end of the week when people start digesting the news of their tech now being deployed in space. Still no news on other competitors to Starlink using their tech. I watched Richard Staveley's interview last week with Paul Hill, and I'm sure he had to pull back from talking about things that were not in the public domain.
I heard that and thought exactly the same thing, he almost had to stop himself from saying anymore! Cavendish p/t upped to 110p (Roland didn’t mention that in his downbeat summary) and it’s fair to say the short term traders were looking for more contract news, hence the price reaction today.
They were downbeat on it (amber) when it was back in the 60-70p range, so far putting too much faith in forecasts that to date have been later surpassed or upgraded. They’ll likely be wrong again.
Stockopedia writers, are often downbeat, on the big winners, probably because most of them are value investors. Also they start reviewing them after they have already multibagged.
TBF Rusty, it was historically called the Small Cap Value Report, so there was a natural bias there...
I'm glad it wasn't just me! I don't get access to Cavendish - when did they upgrade?
Filtronic's mmWave technology being deployed in space is significant because it enhances the performance of satellite communication systems, particularly in LEO constellations like Starlink. Previously, this was limited to ground stations. In my layman's view this appears to be a massive step forward; especially as Starlink is in its infancy, so worries about lack of growth are totally unfounded IMO.
For balance - these are the 'negative' points to take away from today's announcement:
High Market Concentration: Heavy reliance on SpaceX for revenue.
Cost Increases: Overheads +62% YoY, (although justified by scaling efforts?)
Government Defence Delays: Some UK defence projects have been pushed back.
Cash Flow Considerations: Significant investment required for expansion.
The last point is what is most 'concerning' however - that's what happens when you get a growth company. Given that Trump has made it clear that space will be on the USA's agenda, this is a massive growth industry, first mover advantage and established links with Musk, I'm hopeful that this is just the start of the journey...
How will this affect Filtronic (LON:FTC:
"ONTARIO TO CANCEL $100-MILLION STARLINK CONTRACT IN RESPONSE TO US TARIFF THREAT"
With an estimated revenue of $8billion for Starlink last year, not much.
Also Starlink require regular (every 5 years) refresh of satellites, so that's nailed recurring revenue...
Thanks that is good to know.
Apparently Canada are reevaluating it and may still go ahead with Starlink , since it seems their noisy neighbour is just using tariffs as a negotiating tool
Filtronic (LON:FTC)
Viz - you can sign up for free access to Cavendish reports at https://www.cavendish.com/rese...
I tried that: "No Access - This Portal is for Institutional, High Net Worth and Sophisticated Investors." Charming.
See above about Research Tree
Thanks, did not realise Research Tree was free now.
Could not access Cavendish site anyway.
Cavendish upgraded this am p/t 110 from 90p, waiting for Edison comments. You can get the Cavendish comments via Research Tree, no cost just a sign up.
Morning Graham, YouGov with a TU and CEO change today (not on your table)
YOU defaulted to a foreign ticker, that's fixed now! cheers.