Daily Stock Market Report (Tue 7th July 2026) - KLR, STCM, CRN

The unusual volatility of the Korean index continues to make headlines, with Bloomberg noting that it fell 8% at one point during the overnight session, resulting in a trading halt. Samsung shares are down 6% despite the company posting strong results.
More broadly, the atmosphere around AI and tech stocks is increasingly jittery. Bloomberg penned the following sentences in its review of recent price action:
Traders have increasingly become skeptical on the AI boom after massive gains in stock prices this year. Investors have also largely priced in hefty profit margins from a historic buildout of AI infrastructure worldwide.
Daily headlines on capacity additions, tech delays and rising debt levels that barely raised an eyebrow over the past few years are now seen as reasons to dump tech shares.
There is always a post hoc explanation for unpredictable short-term price movements that seems obvious.
In the case of AI-related tech stocks, the answer for a sell-off is always obvious: they are overpriced. There is too much capacity and expectations are too high. But this has been true for a long time.
Overnight market movements:
The FTSE is up 0.2% at 10,665
S&P 500 is down 0.3% at 7,520
Brent crude (September) is up 1.2% at $72.85/bbl
Gold is down 0.9% at $4,125/oz
Bitcoin is down 1% at $63,150
Sorry, I've run out of time for today. See you tomorrow! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Halma (LON:HLMA) (£14.8bn | SR75) | Initial cash consideration €154m (£132m). Earn-out of up to a maximum €121m (£104m) based on performance over two years to March 2028. Dreampath’s FY March 2027 revenue is forecast to be €33m (£28m). Dreampath provides “automated systems that enable anatomical pathology laboratories to safely and efficiently track, store and manage patient tissue samples throughout the diagnostic process.” | ||
Keller (LON:KLR) (£1.86bn | SR96) | Positive momentum has accelerated since the May 20th update. Revenue and underlying operating profit for the full year 2026 will be materially ahead of current market consensus. | AMBER/GREEN = (James) Keller Group upgraded FY26 guidance, saying revenue and operating profit will be materially ahead of consensus (£3,150m revenue, £223m profit). North America, 60% of sales, is driving it via data centre and infrastructure demand; order book hit a record £1.9bn. Stock surged, now around 12.8x forward earnings. Bullish, but thin margin (6.7%) and North America concentration and data centre capex exposure warrant caution after run-up. | |
| Cairn Homes (LON:CRN) (£1.37bn | SR84) | H1 2026 Trading Update | H1 revenue €450m, up 60% year-on-year. Well positioned for strong cash generation into H2 and 2027. Will provide an update on our capital allocation plans in September. Reaffirms FY26 guidance. | GREEN = (Graham) |
Firstgroup (LON:FGP) (£1.0bn | SR69) | Awarded the contract to operate worker transport and site shuttle services from points across Suffolk, to and from the Sizewell C nuclear power plant construction site. Term of up to five years from July 2026. | ||
Young & Cos Brewery (LON:YNGA) (£516m | SR96) | Strong trading momentum has continued. Revenue for the first 14 weeks up 5.5% on a like-for-like basis. “While the backdrop remains challenging, we are well positioned and looking ahead to the rest of the year with confidence.” | ||
Victrex (LON:VCT) (£507m | SR87) | Full-year guidance maintained. Q3 revenue +18%. Year-to-date revenue +7%. “Q3 maintained the positive momentum we saw through our second quarter.” | ||
Capita (LON:CPI) (£393m | SR24) | “We continue to work at pace to resolve the operational issues in collaboration with the Cabinet Office… we are sorry for the distress and inconvenience experienced by those members… Capita is assessing the implications of the matters contained in the statement and, if required, will update the market as soon as it is able to do so.” | ||
NCC (LON:NCC) (£371m | SR80) | Proposing to return £185m to shareholders via £170m tender offer at 145p and a £15m general share buyback programme. | ||
Beauty Tech (LON:TBTG) (£369m | SR70) | Now anticipates that revenue and adjusted EBITDA for the year ending 31 December 2026 will be ahead of current market expectations, being no less than £170 million and £45 million, respectively. Current market expectations: revenue of £161.7 million and adjusted EBITDA of £41.5 million. | ||
Afentra (LON:AET) (£146.8m | SR72) | Afentra to pursue its next phase of growth as an independent E&P company. Gross average production for the six months ended June 2026 was 19,379 bopd. Revenue $91m. Net cash $28.4m. "The first half of 2026 has been a period of significant progress across every dimension of our business.” | ||
EnSilica (LON:ENSI) (£109m | SR52) | Has conditionally raised £14m gross at 91p. This will enable ENSI “to accelerate new products and projects and its growing contract pipeline”. | ||
Clean Power Hydrogen (LON:CPH2) (£68m | SR N/A) | Requested the suspension of trading in shares to be lifted today. £2.5m placing expected to complete today and address CPH2’s constrained working capital position by providing sufficient working capital through to December 2026. Remaining elements of the fundraising to provide sufficient working capital until June 2027. | ||
Steppe Cement (LON:STCM) (£45m | SR99) | Cement sales were up 15% to 978,950 tonnes in H1 FY26, revenue up 42% to KZT 29,588 (approx $61m) versus KZT 20,717m ($40m) in H1 2025. Average price per tonne rose to KZT 30,224 ($62.1), helped by a 7% tenge appreciation. Domestic market share up 2pp to 15%. FY26 sales guided at 1.95m tonnes, below 2025 due to lower opening clinker stock. Capacity expansion project to 2.5m tonnes is 90% contracted and on track for summer 2027 commissioning (self funded from cash flow). | AMBER = (James) Steppe's H1 FY26 update beat expectations: volumes up 15% in a flat market (share gains), revenue up 43% in KZT on higher prices and a stronger Tenge. Given this revenue expansion, the stock doesn’t look expensive at 17.9x TTM earnings, 5.93x EV-to-EBITDA and with a net cash position. And that contributes to a StockRank of 99. But it's single-site, single-country, pays no dividend, and 3-4m tonnes of new Kazakh capacity lands within 18 months. Bullish on quality, cautious on concentration and incoming supply. | |
Coiled Therapeutics (LON:COIL) (£41m | SR1) | Switching its Phase I cancer drug AO-252 to a new softgel formulation to fix absorption issues seen with the tablet version, with first patients dosed on the new version this month. The tablet’s absorption is capped at higher doses – the softgel is meant to remove that ceiling. | ||
Enwell Energy (LON:ENW) (£40.8m | SR26) | No change on the core issues for Enwell Energy – its three production licences in Ukraine remain suspended, so zero production this quarter again. The company is pursuing ICSID arbitration against Ukraine over the suspensions. One bright spot: temporary equipment being installed to get some gas/condensate flowing from the SC-4 well via trucking to existing facilities. | ||
Vianet (LON:VNET) (£19m | SR79) | Q1 FY27 trading ahead of expectations. The business reported 3.1% revenue growth and recurring revenue up 5.8%, which now represents 88% of turnover. | ||
IXICO (LON:IXI) (£17m | SR15) | Positive trading update – FY26 revenue now seen at £8m+, above a prior £7.5m guide, inferring circa 22% growth on FY25 vs the circa 15% previously expected. | ||
Great Western Mining (LON:GWMO) (£14m | SR24) | New channel sampling at its Nevada project confirms tungsten mineralisation over a circa 3km trend, with best results 27m at 0.15% WO3 and a high grade patch of 11m at 0.25% WO3. | ||
Tekcapital (LON:TEK) (£13m | SR12) | Portfolio company Innovative Eyewear landed a deal to roll out its Lucyd Armor smart safety glasses in 345 FYidoctors/Visique optical stores across Canada, starting in Q3 2026. |
Graham's Section
Cairn Homes (LON:CRN)
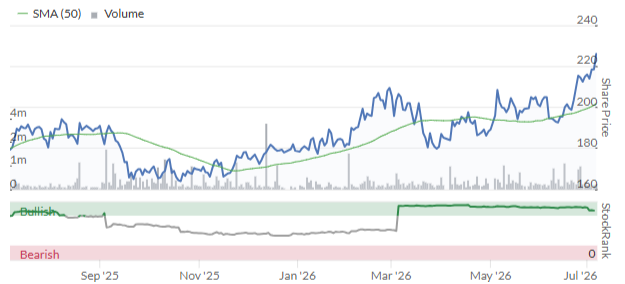
Up 2% at 223p (£1.41bn) - H1 2026 Trading Update - Graham - GREEN =
This Irish housebuilder issues a fine update that reaffirms guidance.
For context, the stock has already had a very strong few months:
I’ve been positive on it due to its excellent earnings outlook. Here’s the unchanged FY26 guidance:
Revenue of c.€1.05 – €1.08 billion;
Operating profit of c.€180 – €185 million; and
ROE of c.16.5%.
This implies a very chunky operating profit margin of 17%. An expected ROE of 16.5% is also looking very impressive.
These numbers can’t be matched by the large UK housebuilders, although you’d expect their results to be much more predictable than Cairn’s.
Barratt Redrow (LON:BTRW), for example, reported an adjusted operating profit margin of 8% in H1, with very low ROCE/ROE metrics.
At the most recent full-year results from Persimmon (LON:PSN), there was an underlying operating margin of 14.3% and an underlying ROCE of 11.7%.
Some more details from today’s Cairn update:
H1 revenue is up 60% year-on-year to €450m.
c. 1130 units sold vs. 708 units in H1 last year.
Order book grows to €1.8 billion (last year: €1.4 billion)
Build cost inflation is just 2.5%.
Cairn is in the sweet spot: extraordinarily high demand, and yet the cost of meeting that demand isn’t rising very rapidly.
Interim dividend: 4.5 cents (last year’s interim dividend: 4.1 cents).
Outlook:
The Company’s significant investment in scaling its operations is clearly delivering results, reflected in strong sales performance, a growing order book, a sector-leading ROE of 16.6% (FY25) and continued business growth. With investment in our landbank and construction work-in-progress (WIP) now at a level that supports our ambitious growth plans, we are well positioned for strong cash generation into H2 and 2027. As a result, the Company expects to provide an update on our capital allocation plans in September.
This sounds promising to me: it says that the company will generate so much cash in H2, that it will need to come up with a fresh plan on what to do with this cash.
Net debt as of December 2025 was €171m. With operating profit for 2026 set to be higher than that figure, it may have some very nice options in terms of shareholders rewards and/or reinvesting for growth.
Continuing with the outlook statement:
The structural undersupply of homes in Ireland remains acute. Cairn will continue to lead the response and expects to deliver a 35% increase in our housing output across 2026 and 2027, representing c.6,000 new homes, including c.3,200 homes in 2027. The Company today reaffirms FY26 guidance:
The CEO comment says: “targeted Government interventions are beginning to deliver tangible results. Greater policy certainty, stronger public-private collaboration and committed funding are supporting increased housing delivery, particularly in apartments.”
Graham’s view
I’ve been positive on this one and it seems clear to me that the bull thesis remains very well intact.
The Irish housing market is characterised by very limited supply in comparison to demand, especially for renters and first-time buyers.
As a well-established and trusted housebuilder, Cairn is profiting enormously from this situation.
Of course it won’t last forever. This probably isn’t one of those stocks that you can put in the bottom drawer and forget about. Housebuilders don’t really fit that category. But for now there are no signs of a slowdown.
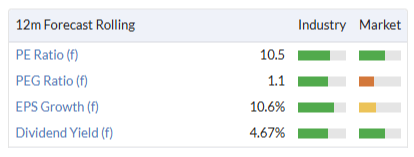
As things stand, the earnings multiples are still reasonable:
The billion-dollar question is whether current levels of profitability might be unsustainably high.
I’ll attempt to answer this in broad strokes: I do think that current returns are unsustainably high. I don’t expect ROE of 16.5% to continue ad infinitum. That level of return reflects very favourable price-cost dynamics (modest build cost inflation combined with very strong housing demand). That can’t be expected to last more than a few years.
However, that’s not to say that I think profits necessarily have to shrink in absolute terms. The growing population has caused housing bottlenecks around Dublin and the surrounding areas. These have persisted for years and in my opinion are likely to persist over the long term, even if they don’t remain at the current extreme levels. Cairn can therefore continue to grow on an absolute basis even if its economic returns moderate over time.
I’m therefore happy to stay positive on this one, even with its share price making fresh all-time highs.
James's Section
Keller (LON:KLR)
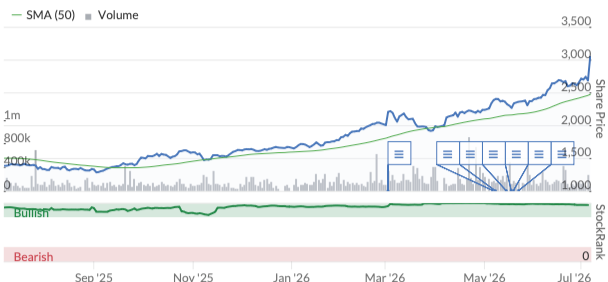
Up 13% at 3,048p (£2.1bn) - Trading Update - James - AMBER/GREEN =
Keller Group has told us that it expects operating profit for FY26 to be materially ahead of current market consensus, and stock is surging. It’s bitter-sweet for me – it’s a stock I’ve touted in the past (notably around the turn of the year) but never purchased it myself.
The company has been getting some more coverage recently – check out Ed Sheldon’s excellent article from early May – and quite rightly. Keller is the world's largest geotechnical specialist contractor – essentially the company that does the foundations and ground engineering work for major construction projects, from data centres to highways. It's not a household name, but it's a big, global operation with around 10,000 staff.
Today, the upgrade is being driven almost entirely by North America, which makes up roughly 60% of group revenue. Demand there has been running hot – data centre construction and infrastructure projects have picked up sharply, more than offsetting a softer patch in Florida's housing market. The order book now sits at a record £1.9bn, boosted by a large multi-year US highway remediation contract, so there's decent visibility on future work too.
There's no number attached to "materially ahead" — Keller hasn't said by how much it'll beat consensus, just that it will. The one hard number we do have is the consensus itself: analysts (seven of them, company-compiled) currently pencil in £3,150m revenue and £223m underlying operating profit for the full year.
Europe and the Middle East is described as “robust,” with growth markets like Scandinavia and the Gulf offsetting a weak western Europe. Asia Pacific is “in line with expectations” – Australia's foundations business is under pricing pressure even though activity levels are strong, which is offset by the Austral business. The heavy lifting is happening in the US.
Two things worth watching. First, there’s concentration risk with North America now around 60% of revenue and the upgrade almost entirely attributable to US/Canada data centre and infrastructure demand – more of a concern if you subscribe to the peak AI capex narrative.
Second, the order book: a record at £1.9bn, but a chunk of that increase comes from a single large contract (the I-40 highway remediation job), so it's worth knowing that's not pure organic breadth across many smaller wins.
Still not expensive
Taking into account today’s surge, the stock is trading around 12.8x earnings on a forward-12 month basis. That puts it at a slight premium to its engineering and construction peer group but a discount to the global industrials average which sits closer to 21x. The PEG ratio currently sits around 1.7 (not great) but that doesn’t factor in today’s improved guidance.
The market will also want to factor in Keller’s strong profitability metrics and robust balance sheet. The business boasts a return on capital of 19.7%, return on equity of 23.1%, and an operating market of 6.7% – all of which are stronger than the sector average.
Net debt, meanwhile, has fallen from £299m in 2022 to just £28.9m in 2025, providing financial flexibility for a company with apparent operational momentum. The EV-to-EBITDA ratio of 6.5 represents a modest discount to the engineering and construction peer group average.
Collectively, these metrics result in a very strong StockRank of 96. It’s worth noting that the StockRank has actually remained above 90 since mid-November – since then, and factoring in the dividend at the time, the stock has returned 99% for shareholders.
James’s View
The data suggests that Keller Group could continue to impress. However, after the recent run up, it’s entirely possible we will see some profit taking. I'm broadly bullish, but conscious that Keller's operating margin – around 6.7%, above the peer group average – is still thin in absolute terms. The MasTec/Sterling precedent shows the market will pay high multiples for low-margin infrastructure names when the growth story is strong enough, so margin alone isn't a hard ceiling on the rating. It does mean the re-rating depends on Keller continuing to prove the growth story, rather than the multiple expanding on its own.
Steppe Cement (LON:STCM)
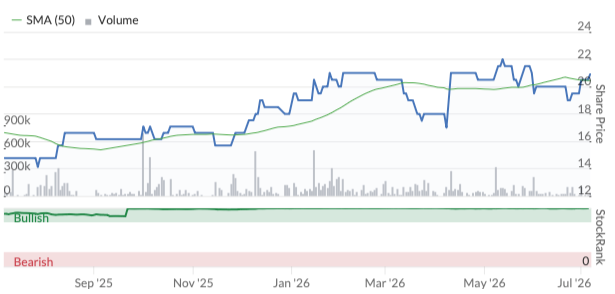
Up 2% at 20.90p (£45.4m) - Trading Update and Investor Presentation - James - AMBER
Steppe Cement’s H1 FY26 update was taken positively by the market. Cement sales rose 15%, which sounds like an impressive achievement in a market that was described as being flat year-on-year. This suggests that the growth came largely from market share gains (up 2 points to 15%).
But there’s a pricing story here too. Revenue in local currency was up even more, 43%, as average delivered prices climbed from KZT 24,361 to KZT 30,224 per tonne. Part of the USD-equivalent improvement (revenue of “approximately $61m” vs $40m) is currency, not cement or pricing: the Tenge has appreciated 7% against the dollar over the past year (486 KZT/USD vs 520 KZT/USD), flattering the dollar numbers on top of genuine underlying gains.
Steppe is listed through a Malaysian holdings company – I’ve never understood why – and describes itself as “primarily engaged in the production and sale of cement.” It runs two working dry kilns (plus four mothballed wet kilns) at a single site in Aktau Village, Kazakhstan – it’s about as concentrated as a producer gets: one country, one plant, one product.
This is an important piece of context because it tells us a lot about the guidance. FY26 sales are guided at 1.95m tonnes, actually below 2025 levels, because of lower clinker (an intermediate product in cement) inventory carried into the year.
The company is also explicit that rising transport and electricity costs are squeezing it from the cost side, saying it's “focused on markets near the factory” as a result. As such, cost inflation, not weak demand, looks like the binding constraint on where it can profitably sell right now.
Scaling up
Steppe is a company that's always intrigued me. At one point it was the largest dividend payer on the UK market, with a yield of around 20% – and it wasn't a distressed yield inflated by a collapsing share price, just a genuinely huge payout as net profit surged in the post-Covid years.
I also studied Russian and Politics at undergrad, so there's always something interesting about digging into a business like this: the plant traces back to 1953, when it was built by the Soviet state-owned Karagandacement with four wet kilns; the two dry kilns Steppe actually runs today were later additions from 1976 and 1981.
The company is now opening another chapter, with Steppe building out capacity to 2.5m tonnes on the same Aktau site. The project is 90% contracted, funded entirely from cash flow rather than debt, and targeting commissioning in summer 2027. Doing some crude maths, the additional capacity represents around a 3.5% addition to the national supply.
But it's not the only capacity coming online. There are at least two other new plants under construction (a 1.3m tonne plant in Aktobe's Baikaninsky district, and a 2m tonne plant in Aktobe's Alginsky district, both targeted for completion by end-2026) adding roughly 3.3m tonnes between them.
Cheapish, from what we can work with
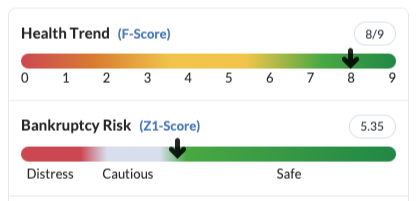
Steppe trades at 17.9x trailing earnings and 5.93x EV-to-EBITDA, against a net cash balance sheet – roughly $8.8m of net cash at FY25. H1 results suggest the forward P/E is likely cheaper than 17.9x, but there's no consensus data to confirm it. Quality metrics screen well too: an F-Score of 8/9 and a Z-Score of 5.35 ("safe"), with earnings manipulation risk rated low.
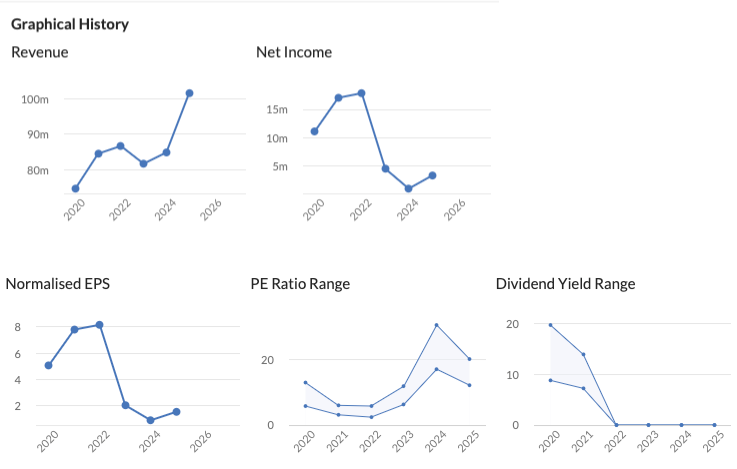
Set against that, actual profitability is still thin – operating margin of just 3.35% (ttm), return on capital of 5.2%, return on equity of 5.8%. The eye-catching EPS growth figure (+237.6% ttm) is a low-base effect. The progression has been anything but consistent in recent years.
No broker currently covers the stock, so there's no consensus to measure this update against.
One more thing worth flagging: there's no dividend. Steppe paid one in 2020 and 2021 before cutting it entirely from 2022 onward, and hasn't reinstated it despite the balance sheet now comfortably able to support one.
James’s View
Steppe still intrigues me, but it’s a risky proposition. While it’s a relatively simple business to follow, it's a single facility, a single country, and there's a wave of new capacity landing across the next 18 months. The market is cyclical despite some long-term growth drivers in Kazakhstan, and there are no analyst numbers for us to benchmark our assumptions against.
However, the quant case is genuinely strong, with a StockRank of 99. That’s why I’m keeping this one at Amber. Some reasons to be bullish, some reasons to be cautious.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
SanDisk (NSQ:SNDK) multiple days of -10% ish drops recently, looks awful until you zoom out and see that it 10x'd since beginning of year and is now at 7x its price at the beginning of the year.
What a time to be in the market (and the world itself).
It was up over 40x in the last year. I did not see until it was around $900, thought it was too late but it still more than doubled, afterwards. Hardly any mention of SanDisk (NSQ:SNDK) on this site. A lot of US tech. are down by similar amounts, in the last 10 days. My trending US folio has been hammered.
Cairn Homes (LON:CRN) in Ireland having double the operating margin of the UK housebuilders....
I think that also shows what an opportunity for UK housebuilder shares are, IF the market normalises from its current paralysis of regulation and structural issues.
15%+ operating profit margins achieved by Cairn is double what the likes of Barratt Redrow (LON:BTRW) have at the moment. And Barratt has done that consistently before 2020 (in a "more normal" market). So its conceivable it could get back to those margins.
So the key question - will Burnham prioritise housebuilding reform? And get his MPs behind it? Will the market naturally normalise itself to 15%+ operating margins even without regulation reform? The million dollar questions...
(I hold BTRW in the Boon Fund)
Market volatility seems to be the name of the game at the moment. I am holding a lot more cash than usual. I have been slowly adding to my positions in AJ Bell (LON:AJB), Games Workshop (LON:GAW) and IG group (LON:IGG) but for the most part I'm selling and holding cash as portfolio at pleasant all time highs and I'm pretty happy with a fair bit of money in MMF for a while at current rates, compounding the pleasant growth I already had this year. Might regret it later but I am expecting there will be some better buying opportunities still to come this year (so many possible catalysts), but overall bullish about the direction of markets and just want to refocus my portfolio onto higher quality businesses when opportunities arise.
Impax Asset Management (LON:IPX) down 5% , looks like we going to get another nasty outflow RNS next text few days
Here's an aside chaps with the impending tax on isa interest rules due to come in I'm just wondering what the outlook with be for the likes of a j bell given a large proportion of profits come from cash skimming.
Personally I do not believe it will happen in the end, its a stupid proposal which accomplishes nothing while making everything more complicated to understand and implement
Should also say, I looked into this when the news came out (a little) as I have been building a position in AJ, my notes say that I concluded that most of the cream comes from SIPPs and not ISAs, when it comes to the cash grab you're talking about. Happy to learn otherwise if anyone else knows better.
Here's an aside chaps with the impending tax on isa interest rules due to come in I'm just wondering what the outlook with be for the likes of a j bell given a large proportion of profits come from cash skimming.
Hi TP
As a AJ Bell (LON:AJB) holder I'd been wondering this myself. They don't break out ISA cash balances so it's hard to know exactly but if we assume about 35% of the cash balances are in ISAs then the pure unmitigated impact is about £25m - so maybe up to 15% of PBT.
That will get mitigated because the money will be reinvested - so there will be transaction fees, custody fees, etc plus there will be short-term money where people are in between trades. Take all that into account and stick a finger in the air and I'd guess you're looking at about 6% to 8% of PBT, so still not to be sniffed at.
There are (sort of) competition risks from the neo-brokers who don't rely on cash balance interest at all - their margins won't be impacted and I can imagine they'll be targeting AJB and ii's potential customer base and will take most of the smaller, younger new customers. Conversely, the additional complexity around managing the new rules impacts neo-brokers, who typically run lean and simple operations, much more than the larger brokers.
There are unintended consequences everywhere. For example, there's a huge push by brokers to capture customer volume right now, because they recognise that when the new rules come in then there will be big fees to be earned from customers deploying cash into stocks. This is particularly true for overseas trading where many neobrokers make a big turn on FX. For AJB this trading effect would probably mitigate most of the lost income in year one.
Meanwhile there's heavy lobbying going on to modify or simplify or change the rules. And who knows what a new Chancellor will do?
However, we also need to recognise that the client base that AJB are serving is distinct from that of the neo-brokers. HNW individuals don't care about whether trades are free or not, they care about customer service and breadth of offering. The typical investor route goes from low cost platforms to higher cost platforms. In many ways these are two distinct markets.
And while all of this is going probably the biggest driver of AJB's earnings will be ... Hargreaves Lansdown.
HL have hiked fees while claiming they're reducing them (they have reduced their main platform fee while raising other fees - e.g. the ISA Share Cap has gone from £45 to £150). This is private equity at work - they're prepared to sacrifice 20% of their customer base in order to drive more income from the remainder. And the customers leaving are prime AJB accounts. Following HL's pricing announcement there was a 200% spike in asset transfer requests and the median amount being transferred was £85,000 (this implies older investors - over 65's have an average of £65,000 in their share ISAs and this drops off as accountholders get younger).
In short - I don't have a clue how this will work out, and I don't believe anyone else does either. I'm keeping my AJ Bell (LON:AJB) and Aberdeen (LON:ABDN) shares and not worrying about it.
timarr
Great post timarr!
Hi Timarr, I'd have thought that the cash I hold in my ii ISA which earns me - not ii - a little interest is nothing to do with ii regarding tax on unearned income. It will be down to me to add this to my tax return, won't it? Or is HMRC setting up ii to be an unpaid taxation reporter. I know nothing about the affairs of AJB, it does sound like their administration will find itself in a morass.
Silver Moon, if this goes ahead, you'll taxed at source.
I'd have thought that the cash I hold in my ii ISA which earns me - not ii - a little interest is nothing to do with ii regarding tax on unearned income
Hi Silver Moon
You earn a little interest on your money, ii makes a lot more.
ii makes about 2.2% on ISA cash balances - that's the difference between what they get on top market rates from high-yield wholesale banks and what they pay you. AJB do the same, but retain slightly less income. HL too. It's only neo-brokers like Robinhood and Trading 212 that don't do this, but there are no free lunches, they have other ways of taking their cut.
Under the new rules ISA brokers will need to comply with HMRC anti-circumvention rules - they'll need to withhold tax at source. As it stands (the rules could still change) individuals won't need to declare this income. There are a number of other admin functions they'll need to support including the under-65 / over-65 transition.
Basically it's a fairly big deal, and requires quite significant updates to broker systems. If this is the route the government wanted to go down they should just have scrapped cash ISAs for the under 65s. Better still they could have left well alone and actually made some changes to encourage people to invest.
Even as it stands today, if investors tend to hold a lot of cash in their ISAs they'd be better off putting it into a money market fund or a short term bond fund.
timarr
AJ Bell (LON:AJB)
Hi Timarr
I'm not sure if this helps, but:
I don't follow AJ Bell (LON:AJB) closely enough, but a quick check gets me close to your £25m lost PBT figure.
This also ties in with HL's AUA and ISA interest figures, proportionally speaking.
Although as a caveat to the above ii's net yield on customer cash was 2.2% in 2025.
If AJ Bell are achieving a similar yield then the £25m PBT figure above could be much higher.
---
On a related note the recent ii presentation might be of interest.
Some snippets included below.
SOURCE PRESENTATION: https://www.aberdeeninvestment...
SNIPPETS:
Cairn Homes (LON:CRN) The question is...will the Irish property market be affected by the impending property crash due in mainland Great Britain.
Were Irish property prices affected in 1990/91 and 2007/8?
Impending property crash? What do you know that I don't? I've just employed two new conveyancers!
Property prices in the UK have a correction or a crash (which lasts about two years before recovering) every 18 years give or take. And has done so for the last hundred years or more - most likely since the first property mutual were set up. Check the dates on AI. circa - 1954,1972,1991,2008 and wait for it.....2026/????
Try Googling - Fred Harrison economist.
Just for interest - In South Devon where I live there are now five times as many properties on Rightmove as there are normally -say three or four years ago, OK there's a lot of rentals and holiday lets but the same applies in central London as well where prices of top end properties are already falling.
A lot of the oversupply due to landlords leaving the market due to the stupid renters reforms brought in by the government.
Also double tax on second homes and 5% stamp duty on second homes. People in seaside towns are heading for the exit.
Every time I think the UK should have a property crash, the government finds a new way to artificially stimulate the market. I wouldn't hold your breath for one!
Thank you for a very interesting analysis of STCM James. I note your Russian and Politics expertise, one of my Grandsons took economics and Politics and he's had a career in financial analysis since then. He concentrates on mid-caps and laughs at some of the shares I buy -- I don't ask him for tips or advice, I'd rather be on here.
Volex (LON:VLX)
IHT selling looks to be presenting an opportunity to add to my holding.
Yes, may be best to wait until after 24th
Not such a dull day after all, gold's future seems to be getting brighter and Clacton is to get a free vote.
STCM Steppe Cement does pay out
attention Dr. James Fox
and poster JASVFS
I hold and received an amount equivalent to an 8% yield for an ex date in December 2024 and 2025.
If you click on 'Accounts' tab and then 'Dividend history' in Stockopedia you will see this.
Why Stocko lists the dividend yield as zero on the Stock report tab is a mystery and needs correction.
It may be a return of capital.
A reason to hold if it continues.
Illiquidity, however, means my holding will remain small.
Ed gave Steppe Cement Amber on April 10th Graham, we added a few more to a long term modest holding. I'm tempted to add again on today's statement. Sales are up 15% turnover up 43% and their new project to increase production to 2.5 million tonnes in 27 is being financed out of cash flow so far. Their market share has increased 2% too. I'm aware of the risks here so would appreciate any comments on this small company if you have time.
I'm aware of the dividend on Steppe Cement aflash, as I mentioned we're long term holders. The Chairman has been a steady buyer of their shares, not in large amounts but he has a decent holding at over 8% now. I'm optimistic about the increased production from summer 27 but James has pointed out a competitors increased production this year. I haven't added yet but may still do so.
As I read it, the increased production will be in Aktobe, which is 1000+ miles from Karaganda! That's a lot of transport cost
Keller (LON:KLR) I have been bullish on this company since I brought it early March last year using Stock Ranks to rebalance my portfolio as I wanted to diversify into industrials at that time. I liked what I saw and have added since that time and was even more excited about it following Ed's analysis back in May, I also added a little more yesterday, to my delight this morning! I will be holding now though and watch how things pan out in the US.
Anyone got any thoughts why ITV (LON:ITV) off 7% today, the market seemed pretty neutral on the Sky deal yesterday ?
Thinking the same thing. I feel like myself and others have been waiting for a deal and it finally comes through and nothing, market seems meh about it all. Perhaps there wasn't the big bump people were waiting for and now am selling out to move money elsewhere.
I think the deal valuation is seen as being viewed as underwhelming. (EBITDA of 5.6-6.4), there is also lots of execution and regulatory risk, brokers have downgraded ITV (LON:ITV) and investors have to wait ages H2 2027 for the deal to close and the 25p - I hold and am annoyed, although think(hope) that someone like Netflix will now buy the production arm of the business.
At 75p per share and a 25p per share payout coming, that is a 33% future yield at today's price ? Have they set a date for when you'll need to be on the register to get that or was that from yesterday holdings?
No, ITV has not set a record date or ex-dividend date yet. I suppose it depends on the likely valuation of the production business too?
ITV (LON:ITV) the cash return to ITV shareholders will be after completion of the deal with Sky, so presumably some way down the road. If the shares then reprice from today's 75p to take into account the 25p return, ( this is not a dividend) you could be underwater if you were to buy at todays price. So this is definitely not a 33% yield.
HTH
RE: ITV (LON:ITV)
At 75p per share and a 25p per share payout coming, that is a 33% future yield at today's price ? Have they set a date for when you'll need to be on the register to get that or was that from yesterday holdings?
The return of capital will happen after the deal completes. expected in Q2 of 2027. That assumes that it clears all of the various regulatory hurdles. The current dividend policy remain intact until the deal completes - so presumably 1.7p in November and 3.3p in May if the deal hasn't completed. The qualification dates for both dividends and return of capital will be announced whenever the payouts are. I'd imagine the return of capital is at least a year away, assuming it ever happens.
In theory, the remaining ITV Studios company will be worth less than the current company to reflect the money returned to shareholders - although I'd be hopeful that the standalone company will be revalued to reflect the potential of the business with the more difficult, regulated, broadcasting arm removed.
Note that the fall today is probably due to a JP Morgan downgrade, presumably because they've just come back from a long vacation on Mars and have been catching up with the news.
timarr
Love it Timarr. Attributed to Peter Lynch ...if you think like an institution you invest like an institution
Its had a broker downgrade today- J P Morgan downgraded it to neutral from overweight
In addition they lowered their Target Price from 104p to 85p citing that the ITV deal as only fair value
Great news on Keller (LON:KLR) but where is Volex (LON:VLX) heading - down to 500 ? Are there still IHT sellers out there The Momentum ranking meanwhile still at 97
Keller (LON:KLR) Like Mark, I bought into Keller recently (June 2026) and then added on 1 July. My reasons were much the same and in addition I was impressed by the company’s progress in North America, where so many forays by UK businesses have been a disaster. I think there progress, with good management at the helm should gain momentum in the next few years, provided, there isn’t a disastrous downturn in the US. Looking forward to your comments Graham.
Keller (LON:KLR) I'm well cuffed with the TU. Shares up 17% in early trading.
I bought these back in May, and thankfully this time, I didn't regret my buy.
The attraction seemed fairly straighforward. Low PE, revenues have been growing by about 6.3% pa over the last 9 years. Not spectacular, but pretty solid. Low debt, safe interest coverage on loans, and high ROE.
As a bonus it has a StockRank of 96.
I took your lead, Mark Thank you!
I hope it works out well for you!
It would be great if you could look at the turnaround at Victrex (LON:VCT)
Highlighted by Richard Crow. Always worth watching. Need to be careful chasing. Worth watching the price action develop.
Ed gave Steppe Cement Amber on April 10th Graham, we added a few more to a long term modest holding. I'm tempted to add again on today's statement. Sales are up 15% turnover up 43% and their new project to increase production to 2.5 million tonnes in 27 is being financed out of cash flow so far. Their market share has increased 2% too. I'm aware of the risks here so would appreciate any comments on this small company if you have time.
Morning Graham , I guess you will be covering CRN trading update ? It makes most pleasant reading ,especially i you would like a builder in your portfolio . Tony
Morning Tony, yes - happy to cover that! G
The trading update from Keller (LON:KLR) looks good! I hope you will be able to cover this today in the DSMR?
(I hold)
Hi Richard, yes, we can cover that one! G
A shout out to Ed Sheldon for the analysis back in May for Keller! Up 35% since his article.