Daily Stock Market Report (Wed 16th September 2026) - SUPR, GAW, CTA, FTC, BTRW, VLE

Good morning everyone! I’ve not been around much for the past week, except for posting last Friday’s Week Ahead article.
That article focused on the Federal Reserve’s interest rate decision which is due this evening (7pm UK time).
Markets are pricing in a 90% probability of a rate hike today, which is an important event for several reasons:
It will be the first rate hike since 2023, a change in the trend which has seen rates fall from 5.5% to the current 3.75% (or more precisely, the rate is currently 3.5%-3.75%).
It will prove that the Fed is willing to act on persistently above-target inflation, even when it can point to valid supply-driven excuses for this inflation (i.e. the closure of the Strait of Hormuz).
It will prove the independence of new Fed Chair Kevin Warsh, despite pressure from President Trump (who appointed Warsh to this position).
So there’s a lot on the line.
Overall, the market is expecting two rate hikes in the remainder of this year and for another rate hike in early 2027.
It makes for an interesting backdrop at the Bank of England, which will be publishing its own interest rate decision tomorrow.
Overnight market movements:
The FTSE is up 0.3% at 10,685
S&P 500 is up 0.2% at 7,600
Brent crude (November) is down 0.5% at $108.25/bbl
Gold is up 0.8% at $4,325/oz
Bitcoin is up 0.1% at $76,000
Calling it there for today, thanks all. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| Games Workshop (LON:GAW) (£5.9bn | SR63) | Dividend Declaration | Trading to 30 August 2026 is in line with the Board's expectations for the current financial year. Dividend of £0.70 per share, taking dividends announced so far in 2026/27 to £3.00 (2025/26: £2.25). | GREEN = (Graham)
I tend to be GREEN on this one. Since my last comment on it in July, I note that the valuation has cooled: £5.9bn market cap today, vs. £6.7bn market cap then. While I tend to rant and rave about the quality of Games Workshop, there is something healthy about the occasional pullback of any highly-rated stock. It’s true that in the short-term, the company hasn’t been generating enough surplus cash to increase its annual dividends much compared to 2024/2025. But it seems that there’s a lot to look forward to in terms of future licensing profits, and successful shows and video games could in turn help to boost demand for the company’s core physical products (I suppose the relationship goes both ways). For these reasons I’m happy staying GREEN on Games Workshop, even at a P/E multiple of 28x! |
Babcock International (LON:BAB) (£4.9bn | SR27) | “Strong performance in Nuclear and Aviation, with demand across our core defence markets remaining robust”. Outlook: in line, full year expectations unchanged. | ||
Barratt Redrow (LON:BTRW) (£3.8bn | SR) | Home completions +5% to 17,667 with revenue +6.6% to £6,055m. Adjusted pre-tax profit -7.1% to £572.8m with adj EPS -11% to 28.5p. FY27 outlook: YTD reservation rate and forward sales are slightly ahead of the same period last year, but FY27 completion guidance reduced to 17,500-17,900 due to planning delays (prev. 17,700-18,200). | AMBER/GREEN = (Roland) Today’s results highlight the pressure on profitability in this business at the moment, but that’s not unusual in this sector. I think the risks are offset by the stock’s 30% discount to NAV and strong balance sheet. The ongoing FY27 buyback could reduce the sharecount by 10%, potentially providing a big boost to earnings when market conditions improve. Although there could be an opportunity cost to holding these shares given the lack of apparent catalysts for housing, I think the valuation offsets this and justifies a moderately-positive view. | |
Pan African Resources (LON:PAF) (£2.8bn | SR61) | Gold production +38.6% to 272,310oz (below prev. Guidance of 275-292koz). Revenue +114% to $1,156.6m with net profit +153.8% to $356.9m. Average gold price +54.8% to $4,235/oz. FY27 guidance: production to be 280-302koz. | ||
Oxford Nanopore Technologies (LON:ONT) (£1.55bn | SR47) | The Unified Patent Court has granted a preliminary injunction against MGI Tech GmbH relating to the CycloneSEQ-WT02, CycloneSEQ- WY01, G100-ER and G400-ER systems and any other sequencer system embodying materially the same sequencing technology, preventing MGI from supplying these products. A trial hearing is scheduled for October 2027. | ||
Supermarket Income REIT (LON:SUPR) (£1.13bn | SR65) | Portfolio valuation +23.7% to £2,010m with EPRA NTA per share +0.4% to 87.5p. EPRA earnings -4.1% to 5.7p, with dividend +1% to 6.2p, reducing dividend cover to 93%. Outlook: targeting minimum dividend growth of 2% from FY27. | AMBER/GREEN = (Roland - I hold) These results reflect the expansion of the company’s portfolio over the last year and the impact of the JV setup and resulting reinvestment period on earnings, which failed to cover the dividend. I’m confident this should be a transitional issue and expect cover to resume in FY27. Although the value on offer is less than it was, I think the 7.6% yield remains attractive, as do the niche focus and quality tenants of this REIT. I continue to hold and see no reason to change my moderately-positive view. | |
Moonpig (LON:MOON) (£773m | SR80) | Revenue growth is being driven by both orders and average order value. “Group trading has been in line with our expectations since the start of the year, therefore the FY27 outlook remains unchanged.” | ||
Advanced Medical Solutions (LON:AMS) (£620m | SR62) | H1 revenue +4% to £115.5m with adj pre-tax profit +11% to £18.1m and net debt +20% to £60.3m. No interim dividend. US Liquidband suffered from adverse phasing vs H1 25 and was -15%, ROW Liquiband was +4%. Outlook: expect further progress in H2. | TAKEOVER | |
Harworth (LON:HWG) (£578m | SR25) | Bidder Peel has made an increased cash offer of 177.5p per Harworth share and provides arguments in favour of its offer in today’s RNS. | TAKEOVER - RH note: This offer is still 15% below the NAV of 208.8p per share reported in today’s RNS and is only a 2.9% increase on the cash offer of 6 August 26. | |
WH Smith (LON:SMWH) (£552m | SR31) | FY26 revenue +5% vs FY25 at constant currency (+2% LFL). Guidance: FY26 adj pre-tax profit expected to be c.£75m (previous guidance £75-90m). Net debt expected to be in line with expectations at c.£325m (2x EBITDA). | ||
Filtronic (LON:FTC) (£473m | SR36) | Secured follow-on contract with US customer for “design, development and build of prototype units to be deployed on satellites”. Follows on from the $0.5m initial development contract announced in June 2026. Expect revenue to be recognised “across FY2027 and FY2028”. | AMBER = (Roland) [no section below] Investors have pushed up Filtronic’s share price today, but there is no change to forecasts from either Edison or house broker Cavendish. Both emphasise that this contract underpins existing forecasts, rather than adding to them. While it’s positive that the initial development contract with this newish US customer was successful enough to justify a larger prototype effort, I don’t have any idea what the potential production scale of this product might be. Investors will be hoping for another transformative deal like that enjoyed with SpaceX, but this won’t necessarily happen. With Filtronic trading on 50x FY28 forecast earnings, I don’t see any reason to change our neutral view today. | |
London Security (LON:LSC) (£447m | SR78) | Revenue +9.2% to £127.6m with operating profit +13.7% to £14.1m and EPS +14% to 80.4p. Cost pressures continue. Demand remains strong as products are non-discretionary. | ||
Avacta (LON:AVCT) (£377m | SR14) | Preliminary data from the Phase 1a trial of AVA6103 in patients with select solid tumors has demonstrated proof of mechanism. | ||
AdvancedAdvT (LON:ADVT) (£223m | SR39) | H1 trading in line with expectations. Completed £10m buyback and is now planning a further £10m buyback. Further returns of capital may be possible. | ||
Focusrite (LON:TUNE) (£158m | SR89) | H1 revenue growth to be +3%, with improved profits and gross margin. Also received £2.3m of US tariff refunds. Outlook: FY27 expectations remain unchanged. | ||
Aptitude Software (LON:APTD) (£117m | SR40) | Revenue -12% to £28.8m with adj operating profit +4% to £5.1m. Sale process: continuing discussions with certain parties regarding a cash sale, “with discussions with one such party being more advanced”. | TAKEOVER | |
Ten Technologies (LON:TENG) (£100m | SR71) | Net revenue to be +6% to c.£69.7m with adj EBITDA +10% to c.£16.1m at an improved 23% margin. Active members +23% to 461k. | ||
Helix Exploration (LON:HEX) (£67m | SR5) | Ollie #1 is intended to be the fourth production well in the Northern Dome of the Rudyard field and is expected to take c.21 days to drill, with a total depth of c.5,500ft. | ||
PCI- PAL (LON:PCIP) (£53m | SR52) | FY26 results will be delayed as more time is required to finalise “certain revenue recognition and related matters”. Based on the work to date, ARR is expected to increase to c.£24.8m, with revenue and adj EBITDA to be no less than previous guidance of £24.6m and £1.1m, respectively. A revised date for the results will be announced in due course. | ||
Ilika (LON:IKA) (£47m | SR9) | Has appointed a retired British Army general to provide advice on the defence sector. | ||
Volvere (LON:VLE) (£47m | SR63) | H1 revenue -7% to £22.2m with pre-tax profit -76% to £0.69m. Net assets +10% to 2,013p per share. Outlook for Shire Food remains positive. | AMBER/GREEN (Graham - I hold) I’m staying AMBER/GREEN on this for the same reasons as before. I think it’s very cheap, even with lower profitability in the short-term. I think that management are highly trustworthy. And I appreciate their cautious approach to risk management. But I also believe that the right thing for them to do is probably to liquidate, and I’m not convinced that is going to happen any time soon. | |
Cobra Resources (LON:COBR) (£45m | SR6) | ANSTO tested bulk composites prepared from samples across 26 intervals from 24 drillholes. Results demonstrate that Wudinna recoveries can be managed across a range of lixiviant strengths, potentially improving project economics. | ||
Star Energy (LON:STAR) (£44m | SR67) | Revenues £23.2m (H1 last year: £18.3m). Adjusted EBITDA of £6.2m from oil and gas, minus £0.6m from geothermal. Net cash £4.6m. Raised £8.5m in May 2026. Full year production is expected to be between 1,900-1,950 boe/d, reflecting temporary operational and reliability issues and the delay in the Singleton gas-to-wire project. | PROFIT WARNING? Guidance in April was for 2026 production of approximately 2,000 boepd. | |
System1 (LON:SYS1) (£43m | SR63) | “The Board remains firmly of the view that Brave Bison’s Fourth Offer materially undervalues System1 and is not in the best interests of shareholders.” Lord Ashcroft confirms he has no intention of accepting the offer. | TAKEOVER | |
80 Mile (LON:80M) (£40m | SR4) | Pre-tax loss of £1,464,625. Net cash balance as at 30 June 2026 was £285,941. | TAKEOVER (proposed acquisition by Greenland Energy) | |
European Green Transition (LON:EGT) (£35m | SR19) | Revenue £6.9m in the four months since completion of the acquisition of the Wind Services business, operating loss £1.3m. Cash balance of c.£5.8m as at 30 June 2026. The Board expects the Wind Services business to generate revenue of £17 million to £18 million for the twelve months ending 31 December 2026. Continues to target selective bolt-on acquisitions. | ||
Blencowe Resources (LON:BRES) (£30m | SR10) | The Board received notification from Mr Ralston, the Company's former CEO, of historical PDMR notification matters on Saturday 12 September 2026. The relevant notifications and disclosures were made without delay on 14 September 2026. BRES has decided not to engage Mr Ralston as a consultant and notifies that all performance shares and share options held by Mr Ralston have lapsed. | ||
Atome (LON:ATOM) (£28m | SR n/a) | Working towards release of both the delayed audited accounts for the year ended 31 December 2025 and the unaudited half year accounts to 30 June 2026 by 30 September 2026 whereupon it is anticipated that the shares of ATOME will cease to be suspended from trading. | Shares are currently suspended. | |
CT Automotive (LON:CTA) (£24m | SR87) | Revenue rose by 14% in H1, but adjusted pre-tax profit fell 57% to $1.6m due to a range of temporary factors, most of which had been previously flagged. Unfortunately the expected H2 weighting to profit is now unlikely due to the impact of litigation with a key customer that’s currently in Chapter 11 in the US. Revised FY26 adj PBT guidance is $4.9m to $9.4m (prev. $10.2m). | PROFIT WARNING (AMBER/RED ↓) (Roland) I’m moving our view down two notches to reflect the wide range of possible outcomes from the legal action reported today and the increased pressure on CT’s balance sheet. While my best guess is that leverage will remain manageable, visibility on earnings and cash flow now seems very poor to me, so I think a cautious view is justified. | |
M Winkworth (LON:WINK) (£22m | SR87) | Network revenues 1% lower. Winkworth revenues down 10% “largely due to the winding down of DCI and the deconsolidation of Crystal Palace”. PBT down 5% to £0.78m. | ||
Quadrise (LON:QED) (£22m | SR6) | Valkor has informed QED that drilling has commenced at two new pilot wells. Valkor expects to pay the outstanding US$0.95m balance of the site licence fee by the end of October 2026 upon receipt of project funding due next month. | ||
Energypathways (LON:EPP) (£21m | SR12) | Has filed patent applications covering key technology innovations it has developed in-house. | ||
Cirata (LON:CRTA) (£19m | SR7) | Revenue $1m (H1 last year: £4.8m). Adjusted EBITDA loss $5.3m. Cash $2.6m. “...certain anticipated deals may close over a longer timeframe than initially expected. As a result, whilst commercial momentum and pipeline build will continue to grow through H2, this may delay the Company’s ambition to be cash flow breakeven…” | PROFIT WARNING | |
Symphony Environmental Technologies (LON:SYM) (£18m | SR20) | Revenue up 23% to £3.6m. Net profit £55k (H1 last year: £503k loss). “The Group enters the second half of 2026 with a stronger operating platform, improved gross margins, reduced cash outflow and a return to profitability.” | ||
Artisanal Spirits (LON:ART) (£17m | SR17) | Revenue down 5% to £9.2m. Loss before tax unchanged at £3.6m. Net debt £34m. “Assuming trade cask transactions complete as anticipated and Branded business trading continues to perform in line with expectations, the Board expects the Group to meet current market expectations for FY26.” | ||
Great Western Mining (LON:GWMO) (£16m | SR23) | Highly encouraging initial metallurgical results from bench-scale flotation test work on representative run-of-mine material from its Defender Tungsten Project. | ||
Cambridge Cognition Holdings (LON:COG) (£15m | SR10) | Revenues up 16% to £5m. FY 2026 revenues will be not less than £10.0m. Adjusted EBITDA loss £0.3m (H1 last year: loss of £0.4m). Key start dates for two clinical studies recently rescheduled from 2026 into early 2027 due to the client’s internal processes. | ||
Facilities by ADF (LON:ADF) (£14m | SR70) | Revenue down 4.6%. Loss before tax £3.3m (H1 last year: £2m). “The lower than anticipated H1 performance and the current shape of the Q4 pipeline mean that management now expects full year results to be below current market expectations.” | PROFIT WARNING |
Graham's Section
Games Workshop (LON:GAW)
Down 0.1% at £176.90 (£5.9bn) - Dividend Declaration - Graham - GREEN =
The briefest of updates, but it was concealed within an RNS titled “Dividend Declaration”, and therefore I missed it in my early sweep of today’s announcements::
Games Workshop, the maker of Warhammer, announces that trading to 30 August 2026 is in line with the Board's expectations for the current financial year.
Thanks to today’s new 70p dividend, dividends in the current financial year are running ahead of where they were this time last year. Total dividends last year were £4.85.
Graham’s view
I tend to be GREEN on this one. Since my last comment on it in July, I note that the valuation has cooled: £5.9bn market cap today, vs. £6.7bn market cap then.
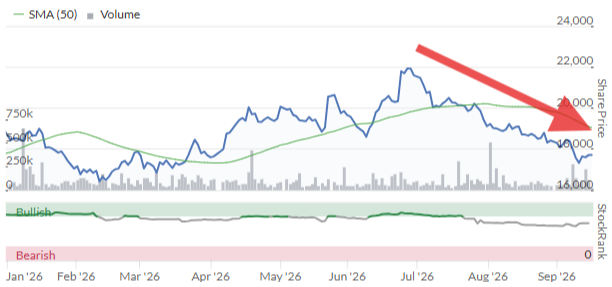
If I’d been watching the technicals more closely, I’d have noted it falling through the 50-day moving average around the time I wrote that note in July.
The earnings multiple has fallen from around 33x to 28x:
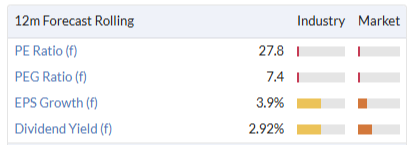
While I tend to rant and rave about the quality of Games Workshop, there is something healthy about the occasional pullback of any highly-rated stock.
And some readers here raised some excellent points in July as to why they might take a more cautious stance.
Let’s take note of a couple of the reasons why investors might be a little cautious.
Flat/declining dividends
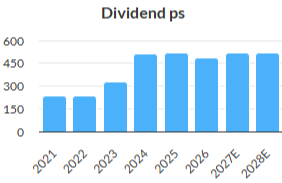
Although dividends in FY27 are running ahead of FY26, that year was itself a weaker one than prior years. And FY27 is expected to be similar to FY24 and FY25.
2023: £3.25
2024: £5.10
2025: £5.20
2026: £4.85
2027: £5.15 forecast.
Now if you look back to 2023 and any prior years, you’ll instantly see that the company these days is paying out far, far more than it ever did before. And if you still believe in the company’s long-term trajectory, I don’t think a couple of flat years should be a concern. Growth doesn’t happen in a straight line.
But it’s true that in the short-term, the company hasn’t been generating enough surplus cash to increase its annual dividends much compared to 2024/2025.
This in turn relates to…
Lumpy licensing revenue
Licensing revenue is almost pure profit for Games Workshop, so that it has the potential to generate enormous amounts of surplus cash, but it ebbs and flows. It was £52.5m in 2025, and then fell to £32.9m in 2024.
Or to put it another way: in FY25, licensing activities boosted operating profit by 23%. In FY26, they boosted operating profit by only 12% (my own calculations).
It’s difficult to put a value on this business, due to this inherent lumpiness and the fact that it depends on what other companies wish to do with the brand, and whether they are successful. Or in the words of Games Workshop:
…the viability and ongoing success of any of our licensing deals is broadly out of our control, we are reliant on the successful development and delivery of projects by our licensing partners.
Looking ahead, there is a long-term, ongoing partnership with Amazon. An article in Variety last month discussed the animated series that is currently in development.
Multiple new video games have also been announced over the past year and there is a major release coming up in December: Warhammer 40,000: Dawn of War IV. One million Steam users have apparently put this game on their wishlist.
So it seems that there’s a lot to look forward to in terms of future licensing profits, and successful shows and video games could in turn help to further boost demand for the company’s core physical products (I suppose the relationship goes both ways).
For these reasons I’m happy staying GREEN on Games Workshop, even at a P/E multiple of 28x!
Volvere (LON:VLE)
Down 6.5% at £20.20 (£44m) - Half-year Report - Graham - AMBER/GREEN =
(At the time of publication, Graham has a long position in Volvere.)
Volvere plc (AIM: VLE), the growth and turnaround investment company, announces its unaudited Interim Results for the six months ended 30 June 2026.
It’s important that I highlight that I have a very strong personal interest here: Volvere is 26% of my single-stock portfolio.
That may sound extreme - and I guess it is - but it was 32% in March. It would have been even higher if I hadn’t been selling it earlier this year!
My plan remains to gradually reduce my holding.
So with that disclosure nice and clear, let’s move on and look at these interims.
Volvere only has one operating subsidiary, the pie maker Shire Foods. Let’s scroll down to see how it’s doing:
H1 revenue down 7% to £22.2m.
Underlying profit down 76% to £695k
Management remind us that they did previously warn that profits in Shire would be down in 2026. They explain that FY25 “included relatively high sales of "value" products for one of our large retail customers” and that one particular low-margin product was discontinued during FY25.
The 76% reduction in H1 underlying profit is severe, but it’s worth pointing out that this is a seasonal business.
Last year, 55% of Shire’s revenues were generated in H2, along with the majority of its profits. So we can still reasonably hope for a rebound in the second half. They have been building inventory in advance of winter and, having reduced headcount, are now recruiting again for Q4 and “for the volumes we can reasonably predict for 2027”.
Some grounds for optimism?
After a full re-tender, we were pleased to be able to maintain our partnership with our largest customer. One of our largest customers continues to innovate heavily with us in the savoury pastry category and we have been encouraged by the resulting level of sales. We have launched a range of mini pies and expect to see these forming part of more customers' party food offerings over time. Whilst launches with our fuel station food-to-go customer have taken longer than initially anticipated, we are now seeing incremental sales in the second half of the year as further new products are launched, with early indications of robust volumes and a strengthening partnership.
Food manufacturing is highly competitive and businesses like this are often reliant on a handful of key customers. So I’m under no illusion that Shire deserves a sky-high valuation. But I do think it deserves some sort of earnings multiple that makes sense.
Indeed, later in today’s results statement, Nick Lander breaks from tradition and tell us something about how Shire is expected to perform this year: “Shire's internal revenue target for 2027 shows growth not only over the full year forecast for 2026, but also over that achieved in 2025. As noted above, the impact of costs is harder to predict - but volume is the key driver in the business - and it is for this reason that we continue to be confident in Shire's medium-term outlook.”
This doesn’t reassure us on profits at all, at least not in the short-term, but it does indicate that the company is still winning plenty of business. In a tough year for profits, I’m satisfied with this performance.
Acquisitions and future strategy: they are adopting a “cautious” approach to investment decisions.
Whilst we have looked at a number of targets in the period, our primary management focus has been on ensuring Shire's implied long-term value to the Group is recognised and protected. This is, I believe, our most important task.
Graham’s view
My view is the same as I expressed before: I believe that Volvere should be thinking about how and when it might sell Shire Foods and return capital to shareholders.
Today’s balance sheet has net assets of £44m (excluding the minority interest in Shire Foods), which is fully tangible and matches the company’s market cap.
Within these net assets, cash is £25m and “current asset investments” another £5.3m.
Shire generated an underlying PBT of £6m+ in 2024 and 2025 and while it won’t do that in 2026, it seems that there is a good chance of another strong performance in 2027.
As things stand, Volvere’s 80% stake in Shire is being valued at only about £14m. The implied earnings multiple is about 3-4x.
So I think that Volvere should be trying to buy back its own shares at around the current level (£20). They seem very open to the idea:
Whilst the Company did not purchase its own shares in the period, it remains committed to doing so where the Board considers it in the interests of all shareholders to do so. This could include substantial holdings where a shareholder wishes to sell all or part of their holding. Any shareholder who wishes to do so is invited to contact the Company's joint broker, Hobart Capital Markets LLP.
They did not make any buybacks in H1, due to “more retail demand for the Company's shares”, with the stock reaching highs of £26-27.
I’m staying AMBER/GREEN on this for the same reasons as before. I think it’s very cheap, even with lower profitability in the short-term. I think that management are highly trustworthy. And I appreciate their cautious approach to risk management. But I also believe that the right thing for them to do is probably to liquidate, and I’m not convinced that is going to happen any time soon.
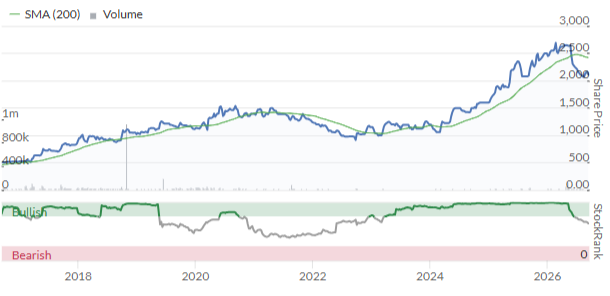
I remain a very grateful shareholder, although with my holding likely to continue reducing over time:
Roland's Section
Supermarket Income REIT (LON:SUPR)
Up 1.6% at 84p (£1.13bn) - Annual Results for y/e 30 June 2026 - Roland - AMBER/GREEN =
(At the time of publication, Roland had a long position in SUPR)
Supermarket Income REIT’s discount to book value has narrowed from a peak of around 25% in early 2025 to c.5% today. This alone makes it relatively unusual in the UK market. It’s also one of the larger players, with a market cap comfortably above £1bn.
This recovery partly reflects the resilient cash flows of its tenants and appealing high dividend yield. But I think it’s probably also a reflection of the way SUPR has adapted to the impact of higher interest rates and inflation by cutting costs and scaling up its portfolio.
The result has been that SUPR has comfortably outperformed the FTSE 350 Real Estate Index since the start of 2025:
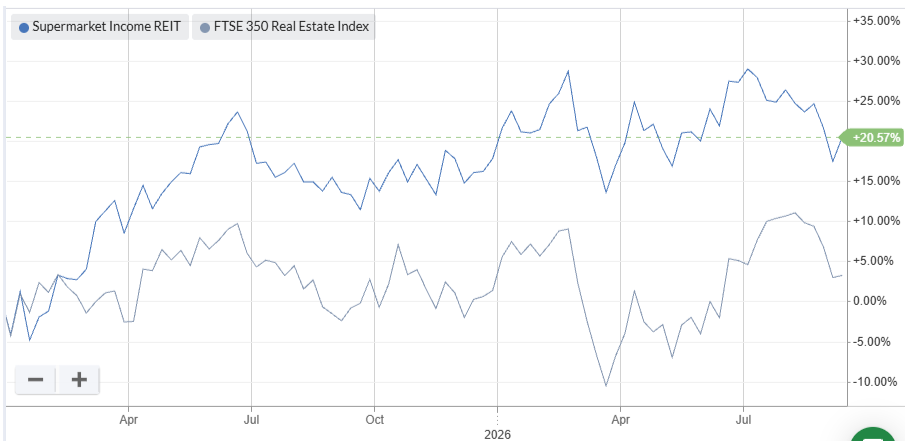
Today’s results show the evidence of the REIT’s revised strategy, but they also confirm that last year’s dividend was not covered by earnings. I don’t think this is a serious concern, but it does deserve an explanation.
FY26 results summary
The highlights table in this morning’s results gives us most of the information we need to review performance over the last year:
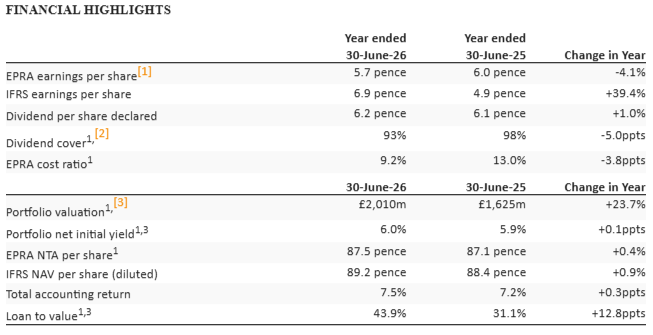
I tend to focus on the EPRA metrics rather than the IFRS numbers. EPRA is a trade body whose formulae are intended to focus on rental income while excluding unrealised changes to portfolio valuations. This means the EPRA numbers are a better proxy for cash generation and thus dividend cover.
Portfolio value/NAV per share: the big change over the last year is a 23.7% increase in the value of SUPR’s portfolio to £2bn. This reflects £454m of property purchases during the year, some of which were carried out through the company’s £855m joint venture with alternative asset manager Blue Owl.
The increase in portfolio value isn’t reflected in NAV per share because SUPR also raised £100m in new equity last year. This is pretty standard practice for REITs, but it’s difficult to do when your shares are at a large discount to NAV. Many listed REITs can’t raise equity at the moment for this reason.
SUPR’s EPRA NTA per share was essentially unchanged at the end of the year, suggesting to me that the equity raise was well judged to allow the business to expand with the right mix of dilution and leverage.
Supermarket tenants favour long leases and rarely close stores, providing some attractive characteristics for a landlord:
12-year average unexpired lease term;
80% of rental income is linked to inflation;
70% of rental income comes from investment grade tenants;
90% of rental income comes from groceries (a highly defensive market).
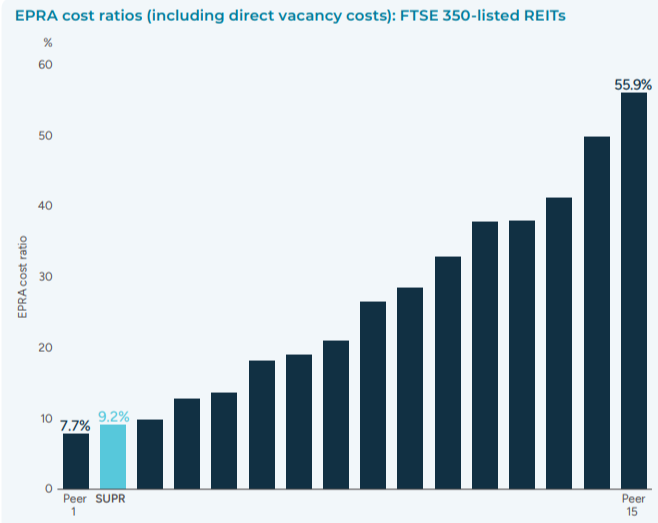
Expense ratio: one of the attractions of the REIT model is that it’s often possible to manage a larger portfolio without a corresponding increase in costs. That’s evident here. SUPR’s EPRA cost ratio fell from 13% to 9.2% last year, reflecting both additional scale and the lower management fees that took effect in July 2025.
Management claim to have one of the lowest cost ratios in the sector:
Dividend cover: EPRA earnings per share only supported 93% of last year’s 6.2p dividend. This would normally be a concern for me, but in this case I think it’s a transitional effect from the creation of the JV. This saw SUPR move some of its owned assets into the JV, freeing up cash for new acquisitions.
Deploying the cash into new properties took some time, resulting in a temporary loss of rental income. Today’s results suggest this shortfall has now been addressed:
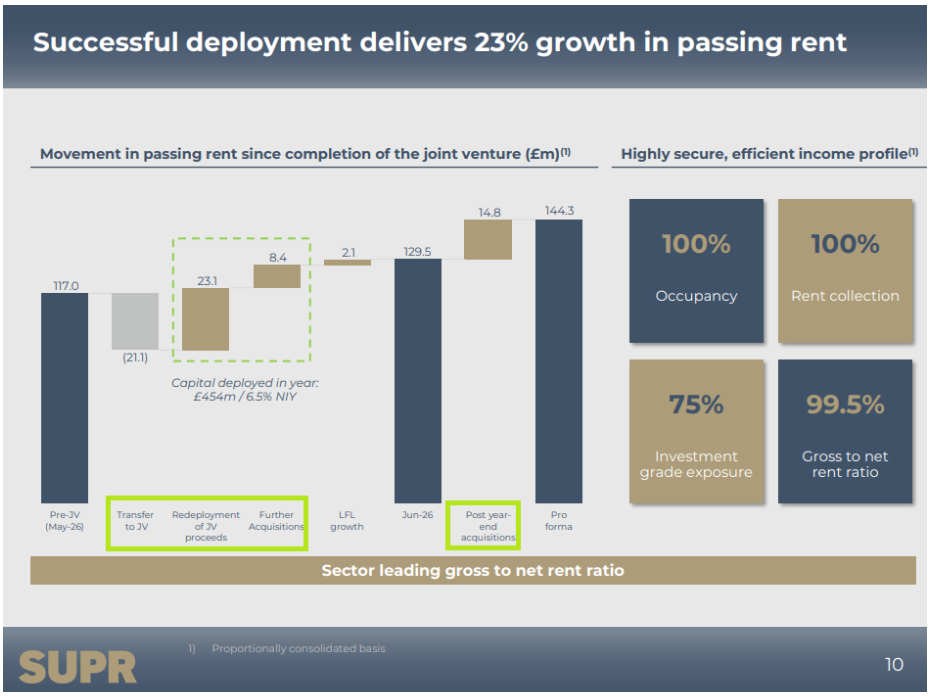
Source: SUPR FY26 presentation
Leverage: SUPR’s loan-to-value ratio did rise last year. Drilling down into the results suggests this mainly reflects the impact of the JV, which is more highly geared than SUPR’s own portfolio. I don’t see any real concerns here given the quality and longevity of the company’s tenants.
SUPR has also refinanced successfully over the last year, increasing its average debt maturity while maintaining a hedged interest rate between 4.4% and 4.8%.
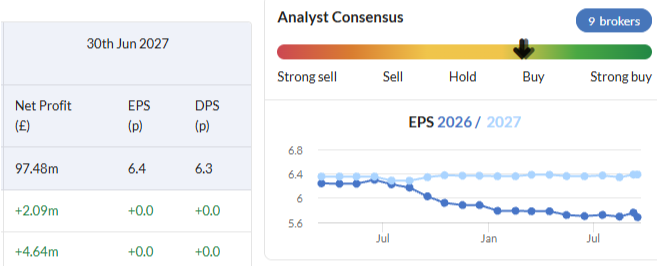
Outlook: the main guidance point is for dividend growth of at least 2% annually from FY27. A dividend target of 6.3p per share has been set for the year ending 30 June 2027.
The main attraction of a REIT is usually income, so I think this focus makes sense.
Broker forecasts prior to today suggest dividend cover should rise back above 1.0x this year, as recent acquisitions contribute a full year of earnings. As far as I can see, today’s guidance is in line with existing expectations:
Roland’s view
SUPR’s management (who are regular buyers of the stock) plan to continue expanding and diversifying the portfolio, with a view to doubling the value again:
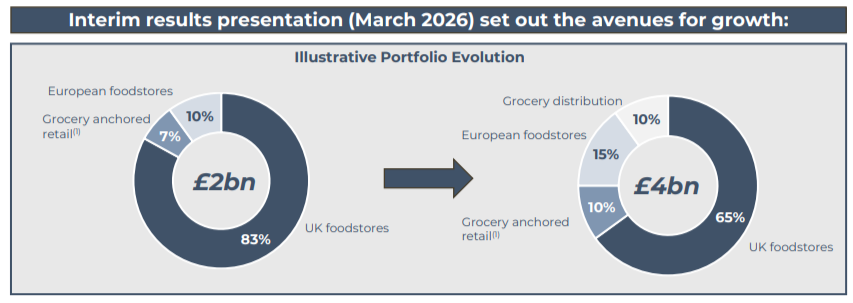
Source: SUPR FY26 presentation
While the company’s plans to expand and diversify its portfolio aren’t without risk, I think the core appeal of this specialist business should remain safe.
I was attracted to the stock because of its niche focus and high quality tenants and am happy to continue holding and collecting the generous income.
The reduction in the stock’s discount to NAV means the value on offer isn’t quite as attractive as it was, but the shares still offer a forecast dividend yield of 7.6%. That’s still very competitive, in my view.
I was AMBER/GREEN on SUPR in March and don’t see any reason to change that view today.
CT Automotive (LON:CTA)
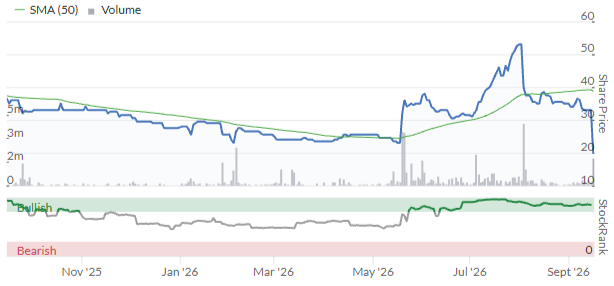
Down 32% at 23p (£18m) - Half-Year Report - Roland - PROFIT WARNING (AMBER/RED ↓)
Today’s half-year results from this car parts manufacturer are unfortunately overshadowed by a hefty profit warning. This appears to have caught the market by surprise – understandably, given that we had an in-line trading update on 4 August (see here).
Here’s the explanation of what’s happened:
Since our last trading update, issued on Tuesday 4 August 2026, a key customer has contested standard contractual cost increase mechanisms in our business awards designed to protect both parties against FX movements and typically used across the automotive industry to adjust for the impact of inflation. Whilst we are confident that we will reach a successful outcome, discussions are ongoing and more complex due to the key customer currently being in Chapter 11 in the US.
This isn’t expected to have a material impact on FY26 revenue, but it is going to cause a big hit to full-year profits (my emphasis):
As a result of the negotiations we now consider FY26 Adj PBT to be in a range between $4.9 million and $9.4 million, a range the Board will seek to narrow based on the progress and conclusion of these discussions. FY26 revenue, supported by strong demand, is not expected to be negatively impacted.
Previous consensus for adjusted pre-tax profit was $10.2m, so this could be a big downgrade. However, I think the key takeaway here is the size of the guidance range. There’s clearly a very high level of uncertainty.
To its credit, the company does provide some additional explanation of this today:
The delta reflects $2.9 million of price increases which we are pursuing in full and a further $1.6 million of inefficiencies, post 15 September 2026, caused by the tightening of working capital largely related to this key customer.
Unfortunately, this also serves to highlight a secondary issue. Because the customer in question is in Chapter 11 bankruptcy protection, $4.5m of invoice factoring facilities previously used on this “key customer” have been withdrawn by the lender, forcing CTA to find alternative financing.
The working capital crunch was compounded by a number of other issues:
Availability of working capital, primarily due to FGI withdrawing $4.5 million of invoice financing on our key customer, and $6.2M being held in the Mexican VAT office, also had an impact on H1 26 profitability. Raw material for operations was constrained forcing CT Automotive to incur expedited freight costs ($1.1 million) and labour costs ($0.5 million). Additionally increased demurrage charges ($0.4 million) were incurred as containers remained at the port.
Net debt: as a result of all these issues, net debt is now expected to be higher than current market forecasts at the end of 2026. Singer Capital’s August note suggested year end net debt of c.$6m, which would be lower than the $12.2m reported today. I would guess that year end net debt is now likely to be closer to the half-year figure, or possibly above it.
Half-year results
Today’s warning would be disappointing enough if it came on the back of a strong H1. Unfortunately, that’s not the case. As Mark discussed in August, various temporary factors meant that CT’s full-year results were already expected to have a very heavy H2 weighting (previously estimated at 70-80% by broker Singer).
The headline numbers from today’s results confirm this. While revenue growth is encouraging, profit figures are less so:
Revenue up 14% to $61.7m
Gross profit down 1% to $16.4m
Adj pre-tax profit down 57% to $1.6m
Earnings per share down 55% to 2.1c
One factor that’s affected profitability during the half year was the working capital restriction mentioned above. Perhaps a good example of why it’s so important for some businesses to have more liquidity than they might appear to need.
Trading commentary: it’s not all bad news. The company says it has secured six new contract wins so far this year, with annualised revenue of $6m once fully ramped up. Further opportunities are in “advanced discussions”.
Increased sales are expected to provide some offset to the impact of the legal situation with “our key customer”.
The company’s plants in China and Turkey are said to be operating well. Its Mexico plant is continuing to ramp up and is expected to support around 40% of annualised revenue over time. A new paint line is expected to reduce dependence on imports with long lead times.
Outlook
The Board expects strong demand to continue in H2 26, and revenue for FY 26 to remain broadly unchanged with increased sales performance offsetting the uncertainty surrounding the price negotiations with our key customer.
This positive statement is of course offset by today’s guidance for adjusted pre-tax profit of $4.9m to $9.4m, versus previous expectations of $10.2m.
I don’t have access to any updated broker coverage today, but in any case I don’t think it’s possible to make a meaningful estimate of full-year earnings at this time.
Roland’s view
Markets hate uncertainty and I don’t like it when multiple items of seemingly unrelated bad news all start to accumulate at once.
I don’t know if the key customer referred to today is Marelli Group (which went into administration last year) or another large supplier. However, this is possibly a reminder that CT’s business is dependent on a relatively small number of large customers, reflecting the pyramid-like structure of the car parts industry.
CT Automotive has previously looked too cheap to us. For this reason, we’ve previously taken an AMBER/GREEN view, despite the evident risks.
While it might be tempting to dismiss these additional problems as further temporary issues (which they may be), I suspect the knock-on effects may continue into next year and could weaken the group’s financial position for a time.
Given the heightened uncertainty and balance sheet risks suggested by today’s announcement, I think we need to be more cautious. While my best guess is that leverage will remain manageable, visibility on earnings and cash flow now seems very poor indeed.
To reflect this situation, I’m dropping our view down by two notches to AMBER/RED today, pending further clarity.
Barratt Redrow (LON:BTRW)
Up 9% at 303p (£3.9bn) - Full Year 2026 Results - Roland - AMBER/GREEN =
In April I upgraded our view on housebuilder Barratt Redrow, noting that “everything has its price” and suggesting shares in this FTSE 100 firm could be too cheap.
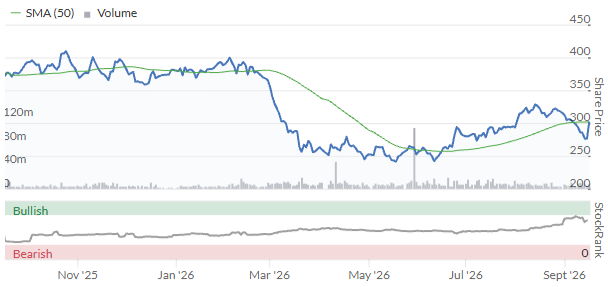
The stock has risen by c.15% since then, but my view is broadly unchanged and I think today’s results support the case for further patience.
Full-year results summary
Headline metrics for the 52 weeks ended 28 June 2026 are mostly positive:
Revenue up 6.6% to £6,055m
Completions up 5% to 17,667
Adjusted operating profit up 0.6% to £598m
Adjusted operating margin down 0.6% to 9.9%
Adjusted EPS down 11% to 28.5p
Tangible net assets per share up 0.7% to 439.8p
Net cash unchanged at £773m
While underlying profitability suffered last year, this shouldn’t be a surprise. Input cost inflation and affordability issues for buyers are being felt across the sector, limiting builders’ ability to increase selling prices.
What’s more important to me when reviewing these companies is the value on offer and the current run-rate profitability. Are they still generating an economic return?
Here’s how these measures stack up based on today’s results:
The current share price of 302p provides a 31% discount to stable tangible net assets of c.440p per share.
Barratt reports an adjusted return on capital employed (ROCE) of 8.4% today
I calculate a more standard ROCE of 4.8%
Barratt’s ROCE calculation suggests profits are probably covering the group’s cost of capital, whereas my ROCE estimate suggests a likely shortfall.
The key difference between them is that Barratt uses adjusted operating profit to calculate ROCE. The main exclusions are costs associated with legacy properties (building safety remediation) of £73.5m and restructuring costs of £32.5m relating to the merger with Redrow.
I would be inclined to include these costs as they are real cash outflows. The building safety issues will hopefully not recur, but they are undeniably a risk of doing business in this sector.
However, I don’t see the low ROCE as a dealbreaker at this point in the cycle, especially given the strength of Barratt’s balance sheet and its capital return plans.
Buyback benefit: one mitigating factor for shareholders is probably that the company has been buying back shares at large discounts to book value. This should be accretive to NAV, helping to offset the current lack of profitability. When market conditions improve, it should boost future earnings per share.
Buybacks totalled £100m last year, many of which must have been made at very attractive prices.
Outlook
Guidance for home completions has been trimmed today, with management now expecting to complete 17,500 to 17,900 homes this year (previously 17,700 to 18,200). This is blamed on “continued planning delays” and a resulting reduction in the number of expected sales outlets this year.
The good news, potentially, is that Barratt is ramping up its capital returns instead of its housebuilding.
In July the company announced plans for £400m of capital returns in FY27, including a c.£386m share buyback.
At current levels, this buyback could reduce the company’s share count by c.10% and provide a similar boost to future earnings per share.
Roland’s view
My view on this sector at the moment is that it could make sense to buy profitable housebuilders with strong balance sheets when they are trading at discounts to book value.
The main risk is the opportunity cost: I expect housing market conditions to improve at some point, but I have no idea how soon this might happen. It’s worth reiterating that there doesn’t seem to be any obvious catalyst on the horizon that could address the margin and volume pressures under which housebuilders are labouring.
Nevertheless, Barratt is a FTSE 100 housebuilder with good scale, a strong balance sheet and a large discount to NAV. I think a lot of bad news is already priced in, so I’m leaving my previous AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
RE:CLIG
This has been a long term hold for me (16 years) so my interest was tweaked by the going concern comment. I think the paragraph which might have caused concern was..
"Going concern and viability
In accordance with the provisions of the UK Corporate Governance Code, the Directors have assessed the viability of the Group over a three-year period, considering the Group’s current position and prospects, Internal Capital Adequacy and Risk Assessment (ICARA) and the potential impact of principal risks and how they are managed as detailed in the risk management report on pages 38 to 40."
In turn this dealt with in a subsequent paragraph..
Based on the results of this analysis, the Board confirms it has a reasonable expectation that the Company and the Group will be able to continue in operation and meet their liabilities as they fall due over the next three years.
Like other posters here - I don't see a problem.
Hi intuitive6191
RE:City of London Investment (LON:CLIG)
This has been a long term hold for me (16 years) so my interest was tweaked by the going concern comment. I think the paragraph which might have caused concern was..
I believe the problem was an AI on Simply Wall St that erroneously reported a going concern issue which was then promulgated by other sites without any cross-checks. As you note, the definitive source - the annual report - doesn't say any such thing.
Chinese whispers, 2026 style.
timarr
CLIG announcement today and shares rise >500p. However, auditors report of a "Going Concern doubt". Can Stocko give us an update tomorrow please as the rise in price does not seem to make semse.
I don't see a "Going Concern doubt" in CLIG's annual report. There is no debt and the company appears to be doing quite well. This is what I've found:
the Board confirms it has a reasonable expectation that the Company and the Group will be able to continue in operation and meet their liabilities as they fall due over the next three years.
On that basis, the Directors also considered it appropriate to prepare the financial statements on the going concern basis
That all seems quite standard.
Where do you see a "Going Concern doubt"? City of London Investment (LON:CLIG)
City of London Investment (LON:CLIG) announcement today and shares rise >500p. However, auditors report of a "Going Concern doubt". Can Stocko give us an update tomorrow please as the rise in price does not seem to make semse.
Hi RayDC
I can't see any going concern issues expressed in the annual report: https://clig.com/wp-content/up...
With a 13.9% rise in FuM, a 9.7% increase in net fee income and a 19.3% increase in PBT the rise seems a tad underdone if anything.
timarr
I completely agree with your comments about LON:CLIG, timmar. There is no going concern doubt. In fact, the company is debt free and has materially improved its cash balance. I was very pleased with the results. The only concerns I have are the slightly decreased average fee margins and the ongoing outflow of fund - also a problem for many of CLIG's peers.
Bravo Roland. Head of the class on this one. Covered my stocko sub and someCity of London Investment (LON:CLIG)
Kick in the teeth for Barratt Redrow shareholders I hold) with the effective cancellation of dividends in favour of share buy backs. Was there any warning ? Compare with Games Workshop (I hold) !!
Focusrite (LON:TUNE)
An in line statement for today's preclose. Mid morning the sp is down 5.6% at 252.5p. It was around 200p at the last annual results at the end of June so maybe some profit taking from those who had hoped for an 'ahead' statement.
Cavendish does not change forecasts or TP on this but under the heading 'Share price catalyst' looks forward to the CMD on 25/11 providing more detail on features and strategy and also the new proprietary silicon chip. I also think this chip could be interesting. TUNE is held by the Buffettology fund and in their review of June they say "Intriguingly, the company has been working on its own silicon to provide a one-chip audio solution which will be used to improve both the cost and efficiency of next generation audio products while in the future it could eventually be a product in its own right and licenced to third parties".
That’s a superb analysis on Supermarket Income REIT (LON:SUPR) today Roland. Really informative. Many thanks.
Harworth (LON:HWG) -What is going on here - Does Peel seriously think an increased offer of just 5p is going to sway shareholders ? (They already control near 30% via Goodweather) It all seems to hinge on the near 30% owned by Ldn & Amsterdam and the PPF holding of 17.5%
A 12 month fixed term savings product has just popped up on the Hargreaves Lansdown savings platform with GB Bank for 4.96%. That's quite a jump from what's been offered recently.
Indeed! First time in a while seeing a 5% for a one year fixed.
My pick would be Investec's offering - exactly 5% for 1 year bond. Bigger more credible bank. In case. Albeit its not on HL's platform, so requires opening a separate account.
My go-to place to check rates available for various different savings and ISAs: https://moneyfactscompare.co.u...
Re : Savings Rates
4.96 is a decent rate - but I would expect better rates to come through.
The Homeowners Alliance ( and other various other publications) report..
"Economists are divided, with most expecting interest rates to remain at 3.75% for the rest of 2026. Markets are pricing in a rise later this year and further increases in 2027, with four quarter-point rises in total by July 2027 potentially taking rates to 4.75%."
I wouldn't be surprised if a risk free 5.5% becomes available at some stage and would expect that will put pressure on fixed interest investments and some REITS.
Nationwide have a limited access regular saver account which pays 6.5% on up to £200 a month.
Lloyds and Santander have regular saver accounts paying 8% but only on £300 and £200 per month unfortunately.
This could start happening the day after tomorrow depending on today's outcome in the US.
Morning Silver Moon,
CT Automotive (LON:CTA)
Four successful decades in the game, and it still amazes me how defensive people get the moment you question a stock they own. They treat extensive research, putting many hours of study, like a personal insult.
At least we have tried to warn people about this one!
All the best
Not saying that 5.5% isn't possible, the BOE could hike tomorrow and the direction of travel has been 1 way for the last 10 days, but just to remind anyone that wasn't aware, that the 4.96 % includes that expectation of 4 rate rises priced into the market ...
Will also put pressure on equities, why take risk if 5.5% in an ISA/Bond is available?
BRCK (LON:BRCK)
I have this on my ' recovery' watch list ( nice stock for the ISA one may think ) and looked at the results and Stocko review. The gearing to a recovery in housebuilding is obvious. Not sure we are there yet and I do see a base rate rise coming so no rush one may think. Given the share issuance for Jacksons and recent large sales by a couple of large investors one wonders some more skin the game would not go amiss and is the large holding by Liontrust possibly under review as well following River Mercantile acquisition?
Seems budget optimism for housebuilding remains an open question
I know it is a bit off-topic for UK equities but since we are including the price of bitcoin in the daily summary it is worth noting that the US Senate blocked the Clarity Act which some see as a major blow to the crypto industry. Bitcoin is down around 5% from 1 week ago so as yet it hasn't translated into drastic price falls. Commentary I read made it seem like Democrats were opposed to it because the US President has personally profited from crypto, more so than because Democrats are in principle opposed to making crypto regulation better and more transparent. This potentially could impact the price of gold positively if it is seen as a safer inflation hedge or simply an asset that isn't as prone to political and regulatory changes.
Even 4 Republicans voted against it!
Will be fun to watch after the midterms on all issues that need to be addressed and voted….
All the best
Yes that's a fair point. One of those did so in a procedural move so that he could potentially reintroduce the measure at a later date. The Act would have need bipartisan support to be successful. There was an extensive public debate about what it would have meant for the US banking industry. Traditional banks were opposed to it but the crypto industry invested heavily to lobby in favour of it.
This also had an impact on equities related to crypto for example Coinbase fell 10% yesterday.
Volvere (LON:VLE) results today are actually weaker than I would have guessed despite caution from Nick Lander in the final results. It is pleasing the NAV could rise and is somewhat supportive. However historical book value is not so relevant for Shire Foods since the revenue has made so much progress since acquisition....and the difference between market cap and cash etc is relatively small - so in NAV shire is valued at a fraction of revenue at £17m but the true value is most likely nearer 1x revenue which is nearer £50m. Of course coming through and delivering against the guidance which sounds quite upbeat for a recovery in H2 and 2027 will help close the gap. Fortunately I rate Nick Lander very highly and definitely not the type of person to make positive noises without the business to support it. Since the share have traded weakly recently, with the premium to NAV falling and therefore the value of Shire falling, I think much of todays` news is in the price and will limit further falls. The fact Nick sounds quite keen to buy stock back would support this view.
Volvere (LON:VLE) remains conservatively valued and excellently run and so im happy to run my position which I did lighten after the finals. Im confident Shire is in much better health than today's results imply.
really like to hear your thoughts on CT Automotive (LON:CTA) if you have the time and inclination!
This post is not restarting the tedious buybacks debate but simply to point out that Games Workshop (LON:GAW) prefer using surplus cash to reward shareholders rather than buybacks. So far in 2025 and 2026 they have paid out £5.25 in dividends.
It was only a few years ago that I bought Games Workshop (LON:GAW) at under £5 before selling way too soon. Had I continued to hold some of that stake the dividend yield would now be well over 100% in just 2 years…..along with all the other dividends on top before that.
(Also on a different theme, Games Workshop (LON:GAW) share price is up over £4 today and almost double what I originally paid. I wasn’t applying the run your winners tactic then. Run our winners unless there’s a profits warning, and cut losers quickly, including on the first bad news/profits warning, works so well).
Those big and frequent dividends are a fabulous “reward to shareholders” and genuinely “returning money to shareholders.” My portfolio is full of high yielders, with a few now paying over 20% in dividends, and CQS Natural Resources Growth and Income (LON:CYN) paying over 30% a year. That’s thanks to my buy the big dips tactic, and City Natural Resources Growth and Income (LON:CYN) has quintupled.
Dividends now finance new buys. It feels like free money.
Obviously those who much prefer buybacks over dividends are free to do do so. No point yet again debating this. I’m just pointing out why I prefer dividends. It’s each to their own own on things like this.
your system has missed the Games Workshop (LON:GAW) ( I hold ) Trading Statement up to 30th August 2026 being in line . In addition they announced another 70 pps per share dividend which is the fifth they have paid in the 2026 calender year - they are becoming a cash machine . Long may it continue .
Thanks, that's added! I do filter out dividend declarations, they got their trading update past me!
That is because it is hidden in a dividend statement.
Supermarket Income REIT (LON:SUPR) Results looking good overall including commitment to annual 2% dividend increase, though presently it is only 93% covered. Starting yield is 7.6%. Supermarkets a good area to be in if there’s a recesssion? We have to eat. Any chance Graham of you covering their Results today please?
Thanks Ken, your request has been noted! G