Daily Stock Market Report (Wed 1st October 2025) - NTBR, PEEL, TATE, GRG, DUKE, CCT, TPT, CAV

Good morning! With October upon us, we're expecting a normal quantity of news today.
Finished for today, cheers!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Taylor Wimpey (LON:TW.) (£3.65bn) | On track to deliver 2025 guidance range 10,400-10,800 UK completions, excluding JVs, and operating profit c. £424m. | ||
Tate & Lyle (LON:TATE) (£2bn) | SP -10% Slowdown in market demand. H1 rev down 3-4%. FY26 outlook: revenue and EBITDA to fall by low single digit percentage. | BLACK (AMBER/RED) (Graham) Giving this a one-notch downgrade after a significant profit warning that we are told stems from market weakness. While the shares were already trading at a cheap-ish earnings multiple, a leverage multiple of 2.2x prevents me from getting too excited about a quick rebound, and the fact that the company was buying its own shares back at higher levels last year leaves a bitter aftertaste. | |
Greggs (LON:GRG) (£1.64bn) | Full year outlook unchanged. LfL sales +1.5% over the last 13 weeks, +2.2% year-to-date. | AMBER (Graham) [no section below] The target for new openings gets slightly reduced although it will still be a busy Q4: there have only been 57 net new openings year-to-date, but 120 net new openings are expected for the year as a whole. Importantly, the “pipeline remains strong into 2026”, so we should continue to see a little bit of roll-out growth on top of small LfL growth. Overall I see little reason to change from the neutral stance expressed by Roland in July. Profitability is under pressure, but the company is continuing to expand in a disciplined way and improve its distribution capabilities (two new distribution centres to open over the next two years). At a P/E of 12x for a business that is much-loved but currently ex-growth, I think it’s fairly valued here. | |
James Halstead (LON:JHD) (£647m) | Outlook: positive sentiment in North America but low customer confidence in Central Europe. Cautious in the short term. | ||
Renew Holdings (LON:RNWH) (£641m) | Trading in line with consensus (adj. revenue £1,117m, adj. op profit £72m, net debt £6.9m). Record order book. | ||
Kosmos Energy (LON:KOS) (£591m) | Successful re-determination of reserve-based lending facility ($1.35bn). Senior secured term loan with Shell (up to $250m). | ||
MS International (LON:MSI) (£223m) | Contract to supply gun mounts worth $34.5m, and another contract worth $7.6m. No longer-term contracts are available as previously hoped for. | ||
Duke Capital (LON:DUKE) (£145m) | £6m investment into a portfolio of care homes across South East of England, facilitating the acquisition of a freehold care home in Brighton. | AMBER/GREEN (Graham) [no section below] We already had a trading update from DUKE this week, which indicated that quarterly recurring revenue was flat. The transaction announced today is quite large and brings DUKE’s total investment into this care home portfolio to over £20m, on which DUKE earns a 13% yield plus or minus adjustments for revenue growth. I think it’s important to recognise that in many cases, including this one, DUKE’s cash injections enable takeovers by DUKE’s investees. An established, profitable care home might be a low-risk bet, but in other cases the DUKE-enabled takeovers can appear rather risky. In any case I’m happy to leave my moderately positive stance on DUKE unchanged today. | |
Peel Hunt (LON:PEEL) (£133m) | Revenue +37% to £73.8m, cost-savings expected to be reflected in the profitability over this financial year. ECM activity, including IPOs, is beginning to emerge, transactions continue to be weighted towards M&A. | GREEN (Graham) H1 revenues are up 37% with the company well on track to hit the full-year estimates, but do bear in mind that revenues can be lumpy. I'm pleased to read that they have reduced some fixed costs, creating a "leaner and better aligned cost base" - I'd like to see them reach breakeven even in the bad years. This current financial year is shaping up reasonably well anyway, and I do expect a small profit. My main reasons for staying bullish are unchanged: the very strong balance sheet and therefore the potential for a takeover by a larger bank. Even without a takeover, I think investors here should do quite well if the UK equity market returns to anything resembling its former state of health. | |
Defence Holdings (LON:ALRT) (£81.4m) | Classified build focused on edge analysis, identification and decision-support capability. No figures given. | ||
Shield Therapeutics (LON:STX) (£78m) | “This first publication of results confirming the safety and effectiveness of ferric maltol treatment in children as young as 2 months is an important milestone for Shield…” | ||
Victoria (LON:VCP) (£75.7m) | Philippe Hamers has proposed to the Board that he retires from his position as Group CEO around the middle of next year. | ||
Topps Tiles (LON:TPT) (£69m) | FY Adj. Sales +6.8% to £265m, (incl. CTD +18% to £296m), adjusted profit for the year is expected to be in the range of market expectations (£8.3-£9.2m). Expects to finish the year in a net cash position. | AMBER/GREEN (Mark)
This is an inline update but one that gives increasing confidence that the company is trading well in difficult markets. As such, it confirms that the shares are very modestly rated, especially as the cash flow get paid out as a generous dividend. My only real concerns are how representative the adjustments are to the underlying performance and how rangebound the stock is this year, but not enough to change our mostly positive view. | |
Zanaga Iron Ore (LON:ZIOC) (£67.2m) | H1 LBT £$3.5m (24H1:$1.1m LBT), Cash $3.9m (24H1: $90k) following $23m raise in period, $15m of which used to acquire Glencore’s 43% equity stake leading to the termination of Glencore's Offtake Agreement and Relationship Agreement with the Company. | ||
Character (LON:CCT) (£51.3m) | FY to 31 Aug 2025 revenue -20%, PBT at least £1m, FY26 PBT to be higher than FY25. No cash figure given. | AMBER/RED (Mark) | |
Cavendish (LON:CAV) (£46.5m) | H1 revenue +2% to £28m, profitable, cash +15% to £19.8m, solid pipeline of both public and private transactions. Fiscal uncertainty ahead of the November Budget is tempering market sentiment. | AMBER/GREEN (Mark) [no section below] | |
Videndum (LON:VID) (£45.6m) | Brian Morgan appointed Group Chief Financial Officer, previously CFO at Victoria Carpets! | ||
Arrow Exploration (LON:AXL) (£39.7m) | Mateguafa Oeste 1 well exhibited thin oil pay over water, being abandoned due to the lack of an economic discovery. | ||
Pulsar Helium (LON:PLSR) (£35.3m) | Jetstream #1 well sustained helium-3 concentrations up to 14.5 parts per billion. | ||
Litigation Capital Management (LON:LIT) (£30.3m) | Net realised gains of A$22.2m (FY24: A$23.0m) on concluded cases. Total loss of A$82.0m (FY24: Total income of A$44.7m) following trial losses. Loss after tax A$72.9m (FY24: PAT A$12.7m). Net assets down 39% to A$114.4m. Strategic review ongoing, still in discussions with lender. | ||
Upland Resources (LON:UPL) (£24.2m) | Acquisition of Vanguard Drilling’s intellectual property, advanced drilling management systems, and the integration of select senior personnel. No figures given. | ||
Northern Bear (LON:NTBR) (£13.1m) | Currently trading ahead of expectations. Full year EBIT is expected to be broadly consistent with prior year after adjusting out a £1.0m non-recurring profit. Term debt repaid. | AMBER/GREEN (Mark) | |
Orchard Funding (LON:ORCH) (£12.3m) | Loan Book -1% to £66.3m, Total Income +20% to £8.30m, Operating Profit +90% to £4.01m. 1p Interim |
Graham's Section
Peel Hunt (LON:PEEL)
Down 1% to 107p (£131m) - Half Year Trading Update - Graham - GREEN
Peel Hunt, a leading UK investment bank, today issues a trading update for the six-month period ended 30 September 2025 (H1 FY26).
Let’s get up to speed on how this investment bank is faring.
H1 revenues are up 37% to £73.8m; this is far in excess of 50% of the full-year forecast.
I imagine that this will be of little comfort to the company’s IPO investors:
At the time of our IPO in 2021, Peel Hunt outlined clear strategic ambitions. Despite the challenging macro-economic and market environment in the period since, the Group has been successful in delivering against those ambitions. We are now pleased to see this progress reflected in our financial performance.
It’s no surprise that an IPO manager timed its own IPO rather well:
That being said, Peel Hunt’s FTSE-350 client coverage is now very impressive at 57 companies, up from 32 at the time of IPO. Although I can’t help noticing that this is down from 58 companies in their September update!
This is also impressive:
In H1 FY26, we acted as lead financial advisor on 11 M&A transactions with a total deal value of £8.4bn, ranking third in the UK M&A league tables behind only global investment banks
A new Abu Dhabi office is opening. They are already in New York and Copenhagen.
Outlook
This sounds good: “our strong revenue performance is now supported by a leaner and better aligned cost base, which we expect to be reflected in the profitability of the Group over this financial year.”
I did criticise Peel Hunt’s full-year results in June, as the company posted another £3m+ loss; it seems to me that a people-driven business like this should be able to dial its variable costs up and down as appropriate, so that it can always reach breakeven, even in the bad years. Cenkos (now known as Cavendish) always did that in the past.
So hopefully we’ll see some improvement on that front soon.
Turning to the outlook:
Following the typically quieter summer holiday period, trading activity resumed in September. Our Investment Banking pipeline remains healthy, benefitting from several announced transactions expected to complete in the second half of the financial year. While ECM activity, including IPOs, is beginning to emerge, transactions continue to be weighted towards M&A. Despite the ongoing economic and geopolitical uncertainty, we remain optimistic about our performance for the remainder of the year.
Graham’s view
There’s not much here to change my view. We know that there are some signs of renewed interest in UK IPOs, but they remain rare. Despite this, Peel Hunt has succeeded in growing its revenues at an impressive pace and is expected to generate a modest profit this year.
For me, the balance sheet and its potential attractions as a takeover target are a large part of what’s keeping me interested. Net assets were last seen at £89m (March 2025), almost fully tangible and consisting primarily of liquid, short-term assets, including cash. I’m sure that most large, blue-chip banks would be delighted to own this, if they could pick it up for a modest premium over net assets, which is what the current market cap of c. £131m amounts to.
So I’m staying GREEN on this.
Tate & Lyle (LON:TATE)
Down 10% to 406.5p (£1.81bn) - Pre-Close Trading Update - Graham - AMBER/RED
This large ingredients maker has faced some challenges in H1 (the period from April to September):
Overall, we saw a slowdown in market demand as the first half progressed. In the Americas, we expect revenue in the first half to be slightly lower reflecting softer consumer demand. In Europe, Middle East and Africa, revenue is expected to be mid-single digit lower despite slightly higher demand. In Asia Pacific, revenue is expected to be broadly in line after absorbing the impact of tariffs.
The result: H1 revenue will be 3-4% lower, and H1 EBITDA will be “high-single digit percent lower”, i.e. 7-9% lower.
Full year outlook:
While we anticipate the near-term market demand environment will remain challenging, we expect performance to improve as we move into the fourth quarter…
Therefore,for the year ending 31 March 2026, in constant currency and compared to pro forma comparatives, we now expect revenue and EBITDA to decline by low-single digit percent compared to the prior year.
Be careful if you’re trying to match this new guidance against prior forecasts: TATE made a very large acquisition during FY25 (CP Kelco), which has boosted the figures. The key word above is pro forma - we are looking at growth rates that remove the timing effect of when that acquisition occurred.
The company’s official guidance prior to this update was for constant-currency, pro forma revenue growth in FY26 that was “at, or slightly below, the bottom of our medium-term range” (that range being 4-6%).
So revenue growth was supposed to be at or slightly below 4%.
Instead it’s headed to be down by low-single digits; let’s call that -1% to -3%. It’s a downgrade of 5% to 7%.
Turning back to the previous official guidance (published in May), full-year EBITDA was supposed to grow faster than revenues. It’s not clear now whether the EBITDA decline will be better or worse than the revenue decline. So the EBITDA cut is worse than the revenue cut, to my eyes.
Graham’s view
We were AMBER on this previously and I think that a cut to AMBER/RED is in order today, given that this is a serious revenue and profits warning for a company of this size.
I also note that its significantly leveraged: net debt to EBITDA was 2.2x at March 2025, with the net debt figure at £961m.
That’s after the company spent over £200m on share buybacks, at prices that now look rather expensive:
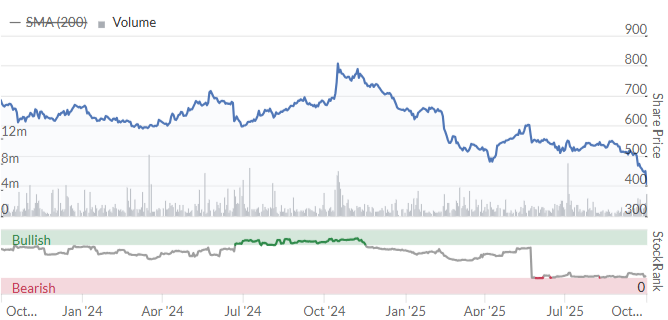
The good news is that it was already on a cheap multiple, before today’s news:
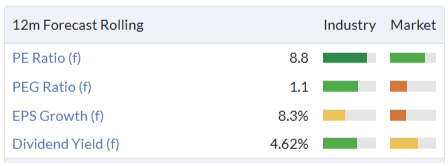
But the trend when it comes to earnings forecasts are generally lower:
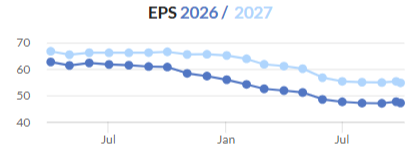
Ingredients is not a sector where I have all that much experience, but I know that Treatt has struggled against the competition. At the much larger Tate & Lyle, it seems to be more about general market weakness rather than direct competition, but in both cases, organic growth has been limited and ROCE has been unexciting. Tate has gone down the M&A route and the CP Kelco acquisition is said to have gone well so far, but I think the negatives still outweigh the positives here for now, especially considering the debt load.
Mark's Section
Northern Bear (LON:NTBR)
Up12% at 106p - Trading Update - Mark - AMBER/GREEN
A nice start to the year so far, no doubt aided by the lack of rain over the summer, benefitting their roofing projects:
Northern Bear confirms that the Group is currently trading ahead of expectations since the publication of the preliminary results on 15 July 2025.
Although I am a little confused by the details:
Based on EBIT for the first half of FY26, the full year outcome is expected to be broadly consistent with the strong underlying profit performance for the year ended 31 March 2025, after adjusting for H Peel & Sons Limited losses and related closure costs in FY25 ("Adjusted FY25 EBIT") and excluding the non-recurring profit noted below.
Broadly, of course, means slightly below. However, in the Full Year Results they said:
The latest expectations for FY26 are for operating profits to remain consistent with the excellent results in FY25 notwithstanding significant investments in both personnel and premises to generate further growth.
So, they say they are trading “ahead of expectations”, but between the Final Results and now trading has gone from “consistent” to “broadly consistent” which sounds more like a slight miss than an ahead statement. Perhaps the kindest explanation is that they didn’t consider the exceptional gain as exceptional when writing the FY results commentary?
Overall, this is relatively minor and not necessarily an issue, as FY25 was very strong in a historical context and benefited from a very mild winter. However, adding to the confusion, the broker forecasts were for EPS to rise anyway:
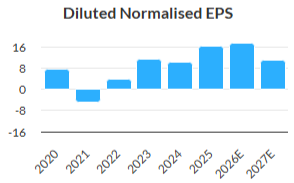
I think the answer to this conundrum is that they are referring to EBIT, and that interest costs in FY25 had gone up to £368k:

Now they say:
In addition, we are pleased to report a non-recurring operating profit of approximately £1.0 million, which has enabled the Group to fully repay its outstanding term debt of £1.275 million relating to the tender offer settled on 8 December 2023.
This is another mystery - what exactly has generated an exceptional operating profit of this size? If any readers know the details, please post these in the comments.] However, this is at least a good mystery! With the debt reducing by about £1.5m during FY25, this explains how brokers could be forecasting a reduced EBIT but increasing EPS. With the term debt repaid at the HY, this would presumably add to EPS further. I can’t see any updated research in RT, but I can’t see the adj. EPS going up by that much on this update, after all EBIT is still guided to be down slightly. However, on a P/E of around 5, it doesn’t need to.
The big question is will this positive trend continue? The existing forecast are for revenue to fall 7% to £76.2m but because of cost rises, EPS to fall 35%:
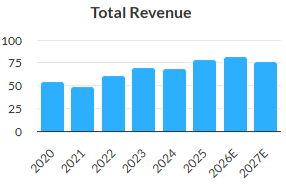
A forward P/E of around 9 suddenly doesn’t look as great value. This should benefit from the same dynamics around lower interest charges as FY26, but what investors really want to know is if this positive trading is a permanent shift to better profitability, or merely weather-related? I’m not sure we can judge until there is a prolonged period of bad weather.
Mark’s view
Today’s update seems a little confused. I’m not sure what exactly is “ahead”, and comparing the language around recent trading suggests they are slightly behind where they thought they’d be at the Final Results. Is this about the broker not believing them when they produced forecasts after the FY results? While Adj. EBIT may be slightly down on a very strong prior year, exceptional gains meaning that they have paid off their term debt, and hence have lower interest charges, means that EPS should rise further. This makes them very cheap on forward earnings. However, some doubt remains as to whether this is a fundamental change in the nature of the business, or merely a beneficiary of some unusually nice weather in the UK. Until we get some bad weather, it seems hard to say for definite. In light of this, I keep our generally positive view of AMBER/GREEN.
Character (LON:CCT)
Down 5% at 271p - Trading Update - Mark - AMBER/RED
Forecasts have been suspended here since their April 11th Trading Update when they announced:
The Board's visibility for forecasting sales to USA (which were c.20% of Group turnover in the last financial year) and its ability to assess the financial implications for the Group have been considerably obscured by these events. Consequently, the effect of the imposition of the trade tariffs will be felt in the second half by the Group and, as a result, the Company is withdrawing the market guidance for the year ending 31 August 2025. Despite this, the Board remains confident that the Group will be profitable for the current financial year as a whole.
Their H1 is to the end of February so was unaffected. However, at that time of release in May, we also learnt that:
The uncertainty flowing from the imposition of these tariffs has been felt in other parts of the world as customers have become increasingly cautious and are not committing to orders to our expectations. This is impacting sales in all our key territories. Despite this, the Board remains confident that the Group will be profitable in the current financial year as a whole, although it is too early to forecast short to medium term trading at this juncture.
Today is the first time we get these statements quantified:
Whilst full year revenue has reduced by c. 20% when compared with the previous year as a result of customers reducing their commitments, the Board expects the Group's audited adjusted profit before tax for the financial year to be at least £1.0m.
The numbers:
Doing the maths, this makes the FY revenue around £99m, which means H2 revenue was around £46m, which is down around 31%. The run rate revenue will be even worse as the tariff announcement came around 6 weeks into H2. This is clearly about much more than just US sales dropping off a cliff, as these were only around 20% of turnover in 2025. There is a H2-weighting here, as Christmas ordering normally happens over the summer period. So it is possible that this may be the effect of delays due to uncertainty. However, if they had seen a significant uptake in ordering in September you would expect them to mention it.
In terms of profitability, they made £2.1m Adj. PBT in H1, meaning that they have only lost around £1m in H2. This is actually one of the advantages of a company where the Gross Margins are quite low, at 26.5% in FY25. A £20m reduction in revenue only takes £5.3m out of gross profit. Assuming similar gross margins, they would have generated £12m gross profit in H2 and to lose £1m means they will have had similar costs to the £13.7m H1 costs (made up of £4.1m distribution costs and £9.5m admin expenses). Given they may have had to eat some margin in the US, and freight rates have been coming down, I expect the true figures to be for slightly lower gross profit and lower costs. However, it does suggest that they haven’t been able to (or wanted to) take significant costs out of their admin expenses.
Outlook:
The only outlook we get is:
With a strong product portfolio, backed by a resilient balance sheet and continuing good cash position, the Board looks to the year ahead with optimism, and expects the adjusted profit forecast to increase when compared to the year ended August 2025.
This is quite vague, an improvement could be anywhere between £1.5m PBT to back to 2024 levels of £6.5m. I’m guessing management simply don’t know, as the brokers have kept forecasts suspended today.
Balance sheet:
The balance sheet is indeed strong here with around £16m of net cash. (Breaking our general rule on the DSMR that if a company has to say it has a strong balance sheet, it probably doesn’t!). As companies such as IG Design have shown, we have to be careful with seasonality as net cash on a balance sheet date does not necessarily represent the normal position. With Character, in normal times, there is definitely a seasonality with inventory being lower at the half year:
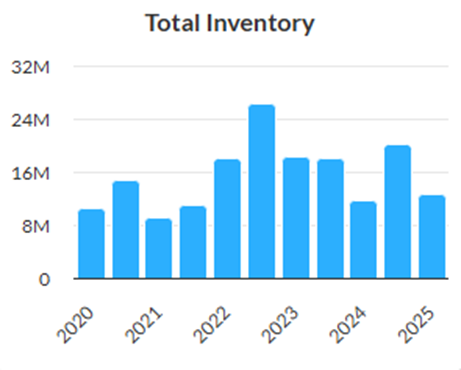
However, given the way it is funded by suppliers, the net working capital tends to show much less seasonality:
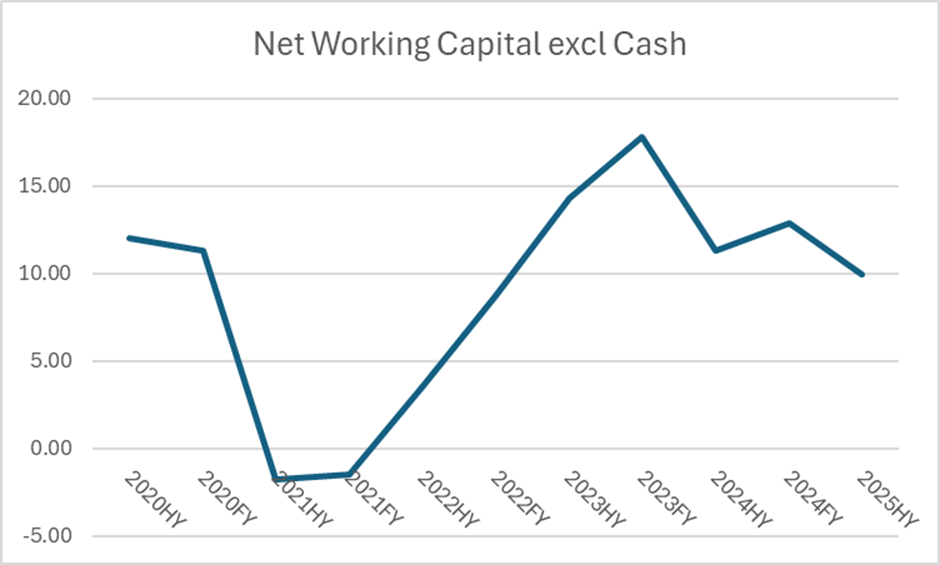
And the cash balance little seasonality at all in recent years:
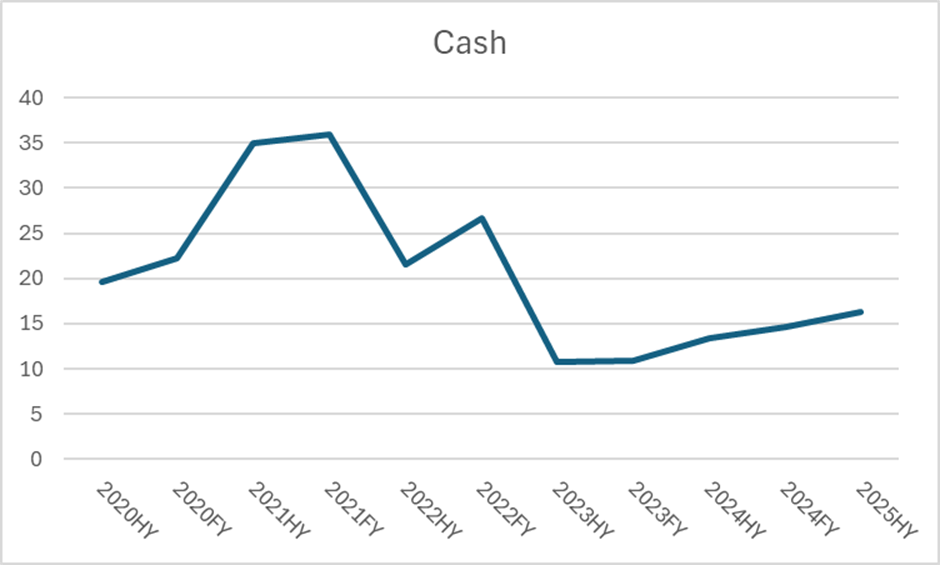
My understanding is that several of their properties are surplus to requirements, or could be freed by consolidation. These would probably be worth more than book value. Although, there doesn’t seem to be any progress/urgency on realising value with these. Property is also only around 30% of their Tangible Book Value and they trade at a premium to book, so it would have to be a very significant uplift in value to make this an asset play:
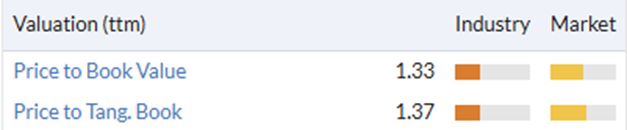
If they sold some of the surplus property it would bolster their cash resources. However, I have some doubts as to the logic behind their uses of that cash. They reduced their interim dividend but at the same time have been buying back shares:
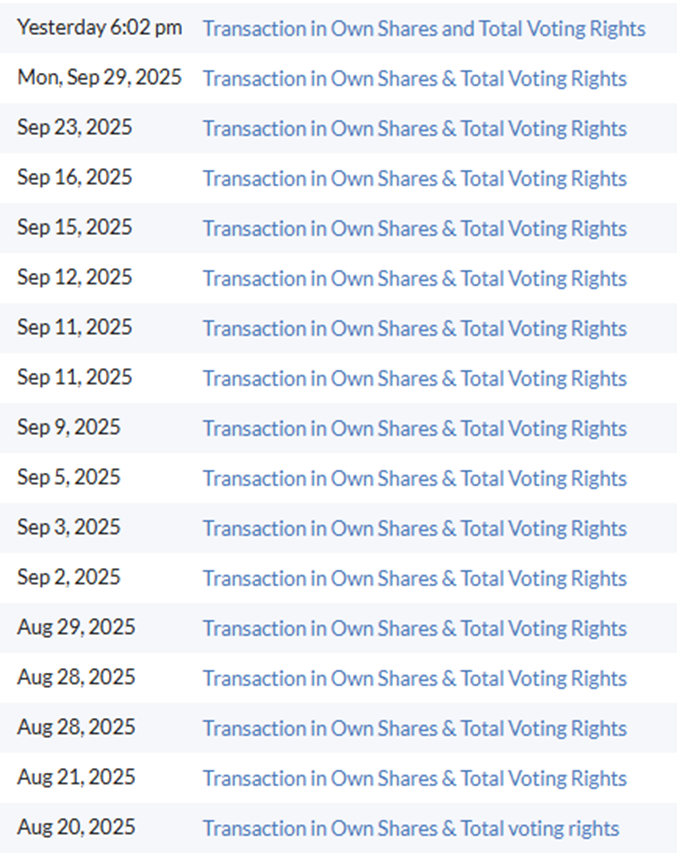
The effect of this on an illiquid stock seems the most likely explanation of why the share price went up between June and Mid-August:
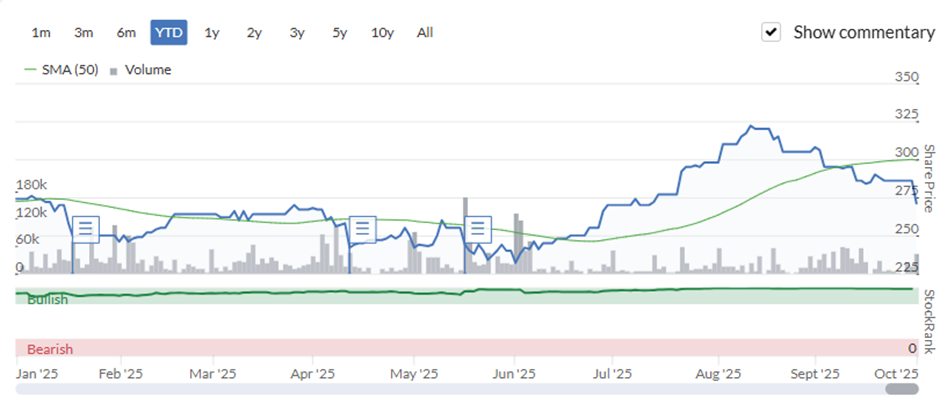
Indeed the shares are flat YTD, despite an absolutely huge profits warning. It has clearly helped shareholders keep a positive view of the company. I am less sure it has added shareholder value buying back stock at a premium to book value and what has turned out to be somewhere in the region of 50x forward earnings. They extended the buyback by £1.0m in May, having completed £1.6m of the original £2.0m. They may well extend again if they reach the £3.0m.
Their largest shareholder has not been put off by the current trading and has been adding recently:
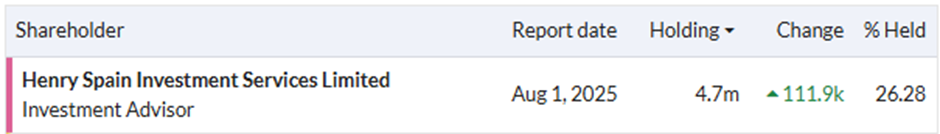
However, having Henry Spain above 25% is not without risks. Their actions over the wind-down of now-delisted Zytronic raise some questions over how they would treat minority holders. While they have no doubt suffered from small-cap/AIM, there is also no getting away from a poor recent investment record.
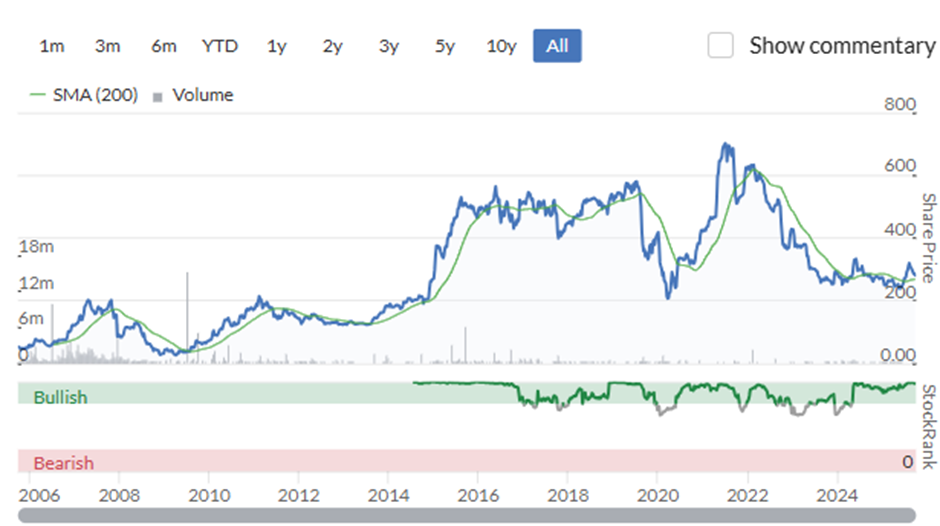
Of course, these near-term earnings are unusually depressed, and this company has a long history of going through cycles of profitability, and this is reflected in the share price:
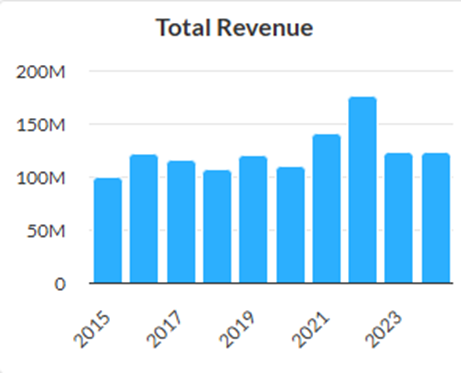
However, it has no real history of revenue growth:
It certainly seems possible that they may return to the 45p EPS eventually, which would put them on a cheap multiple:
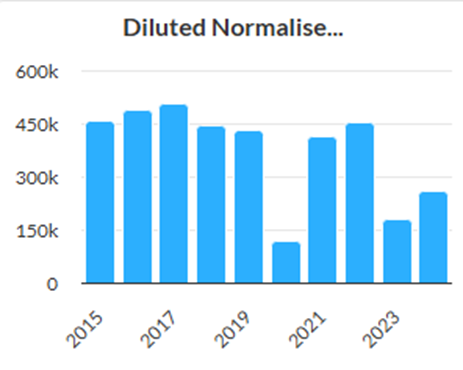
However, with FY25’s results this seems a very long way away, and with no long-term growth and little IP, this should be cheap.
Mark’s view
While this is conservatively financed and not shy about using its cash balance to buyback shares, it is not clear if they are actually adding shareholder value by doing so. The short term trading is extremely uncertain and today’s price already reflects expectations of a big bounce-back in trading and profitability. Graham rated this as AMBER at 245p following the HY results, but having done the maths on H2 (Revenue down 31% and £1m loss), I feel a further reduction to AMBER/RED is probably fairer. At least until the company is willing to commit to market forecasts again, or we get news on the realisation of property assets.
Topps Tiles (LON:TPT)
Up 7% at 37.5p - Q4 Trading Update - Mark - AMBER/GREEN
This is billed as a Q4 trading update, but the figures we get are for the FY:
The Group's strong trading performance has continued throughout the second half, resulting in another record year of turnover for the Group of approximately £265 million of adjusted sales, up 6.8% year-on-year.
This is what they said for Q3:
Group adjusted sales were up 10.1% in the third quarter, a notable acceleration compared to 4.1% growth in the first half. On a year-to-date basis, Group adjusted sales were 6.1% higher year-on-year.
So thinking through the logic, that must mean that Q4 sales were up by more than 6.8% but probably less than Q3’s 10.1%. Total FY25 revenue looks slightly ahead of the Stockopedia consensus.
That they are facing cost pressures is not new news which is why this is an inline statement overall, and they helpfully quantify that:
Company compiled market expectations for adjusted profit before tax are in a range of £8.3 million to £9.2 million for FY25
Adjusted PBT last year was £6.3m, so this is a decent increase. Although, this presumably excludes the property costs and other adjustments, plus the losses and exceptionals from the acquired CTD. While many of these sound one-off, they seem largely like things this sort of business should be doing as part of its normal operations.
They are guiding positive adjusted net cash, which is good news, but not a huge difference to the £1.2m net debt at the half year. It will exclude lease liabilities and around £3m of provisions. How we treat net lease liabilities is open for debate, but it is worth noting that liabilities were a whopping £26m more than lease assets at the half year. It is clear that not all their stores are performing as originally planned.
If we are willing to exclude these this looks cheap on soon to be released FY25 numbers and very good value on FY26 forecasts. Today’s trading update must surely give greater confidence that these will be hit:
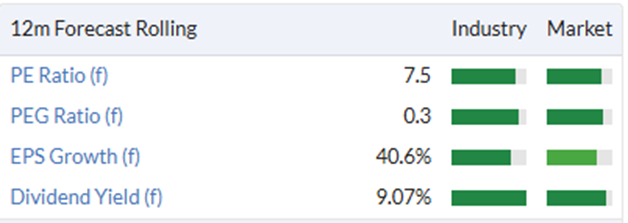
And as we often point out on the DSMR, if a company with significant housing market exposure is cheap at the moment, it may look even more so in better market conditions.
Mark’s view
The share price has responded positively this morning to what is an inline statement but one that builds confidence in the medium-term future, so I can see why investors will want to own this at the current valuation. My only real concerns are firstly how representative the adjustments are to the underlying performance. However, the cash flow is often very good and supports a high yield which assuages my concern here. Secondly, the shares seem quite rangebound this year:
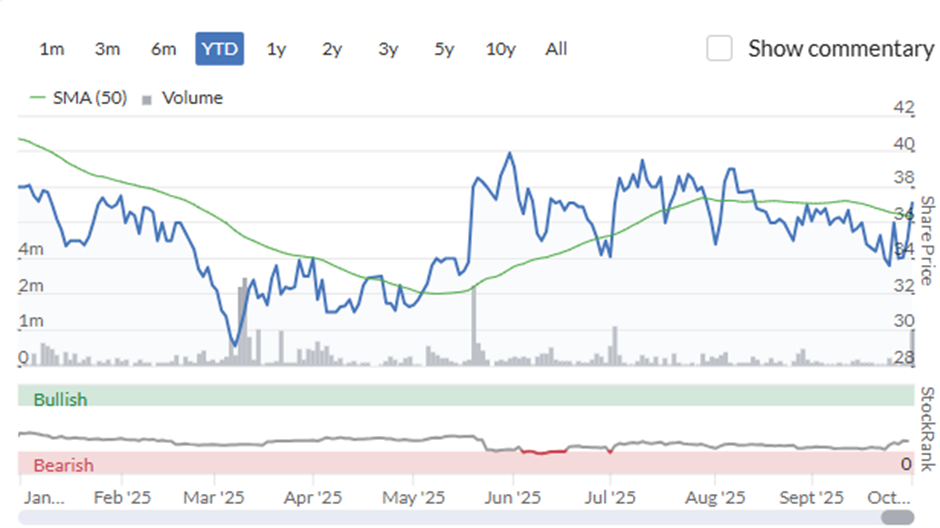
They seem to respond positively after a trading statement and then fall back as investors climb the wall of worry about the sector. The risk is that today’s initial gain will be sold into, as usual. It perhaps needs a beer sector outlook or an ahead statement to see the shares break out of this pattern. I’m no great chartist, though, so very happy to keep Roland’s previously mostly positive view of AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Could you do a review of Renew please. The market seems to be warming towards them again? Thank you
I hold EnSilica (LON:ENSI) despite a stock rank of 15, a category of “Highly Speculative, Sucker Stock” and James Montier short sell category . It tends to react to news but today has rocketed 21% without any news that I can see ( not even Sky News!)
Does anyone have any insight on this (welcome) move. Knowledgeable contributors here have warned me against expecting any company to extract significant value from the ASIC space, so I have no reason to be optimistic but I have a few “long shot” stocks where it is fun to dream.
Aislabie, I had an email yesterday from Simply Wall Street tipping it and saying it could be worth 13x current share price. I don't know if that would have been the catalyst as the article is dated 22/09/25 but it's all I've seen. (There is some discussion on London South East chat)
Edit: here's a link. ENSI - Why EnSilica is Worth Possibly 13x its Current Price
Thank you very much for that reference, I shall go forward with additional confidence that things could turn out (very) right for ENSI
There is a post from Double Bubbler and petesays on London South East showing a links to very positive articles. Apparently Simply Wall Street has 7 million subscribers.
https://simplywall.st/communit...
https://www.electronicsweekly....
Xaar (LON:XAR) released an RNS just after midday referencing in line trading and notice of previously unidentified overseas tax liabilities of £3-£4 M . I'm not sure what the main driver was for a midday RNS, relief at being inline or a sense of urgency to inform the market of the tax liability. The shares have since bounced around +5-10%.
https://www.stockopedia.com/sh...
Today's trading update from Character (LON:CCT, a 'Balanced, Super Stock') looks a first glance pretty negative. Sales Revenue for the FY 2025 to August 31 likely down around 20% to c. £100m with profit before tax at least £1m. Looking at the interims to 28th February this implies 2H sales of c. £47m and a 2H loss of anything between £1.1-2.2M depending on which profit measure is being used (including or excluding FX gains). Despite the positive tone about prospects for FY 2026 the business seems to be going backwards at the moment. Previous commentary from the Stockopedia analysts suggests that the strong cash flow and solid balance sheet were supportive but is this benefit beginning to unwind with the fall offin trading. Share price is down 5%+ today and as I hold in a NAPs (QVM style) portfolio interested to hear any views from the team or other subscribers/holders.
Northern Bear (LON:NTBR)
This is another mystery - what exactly has generated an exceptional operating profit of this size?
possibly long shot
they have previously had a settlement agreement back in 2022 ref prior roofing work that was done - they provided for £0.6 mill (£1.9 mill claim) at the time rather than fighting the insrance company. Note that disputed stuff went via insuers too. So perhaps they took the hit at the time on the basis that if it later turns out the insurance company picks up the cost without finding fault - that they get that money back. If the customer thought they were covered by insurance they may have carried on fighting the insurance company ref the stuff that ntbr were not reponsible for - if they won perhaps that meant that by default what ntbr had done was also pukka and somehow that reverses out now.
Request for Topps Tiles (LON:TPT) please :)
I note that there's potential momentum in the traffic light recently... last 5 daily stock report traffic lights were:
(oldest to latest) Amber, Amber, Amber, Amber, Amber/Green (Jul25).
Today's update looks quite positive in a very challenging trading environment, especially in the last 6 months of their FY H2, given the low housebuilding volumes and housing transactions. Fully Green perhaps?
(I hold in the Boon Fund)
Topps Tiles (LON:TPT) This looks like a very good update to me, no debt, attractive yield, top line growing, margins healthy and all this in a depressed RMI market?
What am i missing? Are they always lowly rated or is there a history here with the management I'm not familiar with?
Just trying to get up to speed, thanks Boon.
Topps Tiles (LON:TPT)
it does look interesting and the price does seem to have flipped above the green line - so nice candidate perpahs for future momentum perhaps?
its not too disimilar to much stuff in the building maintenance construction sector ref lowly rating.
what is interesting is that - they seem fairly confident ref increasing profits in 2026 - i think many other companies are still at the stage where there is no uptick at present.
Note i dont know much about ctd acquisition - so perhaps they are benefitting from tailwinds there perhaps ?
Overall, the Group's improving trading momentum, strategic progress and strong balance sheet leave it well positioned to continue to grow sales and profit into 2026.
Not convinced the quality metrics are the highest profits as % of sales is small - they have very high trade payables > £50 mill. when yoiu get credit from suppliers you can be one quick step away from oblivion if suppliers need credit isnurance cover and you cant manage without the free credit. To be fair they dont have high net debt.
this company was a dependable plodder back in the day.
for me it does seem to tick quite a few boxes here if things are on the up - they have the benfit of being a tried and tested brand - i think that helps if you dont over need to advertise the fact that you exist - if you search for tiles topps name is never going to be far away from being mentioned.
RMillaree, thank you, that all makes sense, agree with all of it.......I suppose the issue is do I want to open a fresh position in a consumer facing sector with this macro backdrop, with this government ahead of what is likely to be a crappy budget?
Probably not, which means I probably should.....
I think this is a medium term hold (6-12 months), driven by a few things:
Ultimately I see a 5p EPS in the next 24 months. Brokers only have 4.7p for FY Sep26. Think it can't trade lower than 8x, so that's 40p minimum. In a rosier scenario (especially if housing market optimism comes back) then this goes to 12x in anticipation of future growth recovery, and that's 60p. Bought in at 35p as I thought almost minimal downside risk, but 70% upside risk in a year, not a bad risk to take.
CEO and CFO have been recently pushed out of the business though, by the large shareholder I think. Don't think the new CEO is any better, so that's not a positive in my book. But maybe its gearing up for some M&A type action by the largest shareholder....
Definitely not a stellar "coffee can" type stock, for those that seek this type. But the risk/reward here is compelling, and IMHO very minimal risk at this price.
Topps Tiles (LON:TPT)
CEO and CFO have been recently pushed out of the business though, by the large shareholder I think. Don't think the new CEO is any better, so that's not a positive in my book. But maybe its gearing up for some M&A type action by the largest shareholder....
I would take that as a positive that at least they are trying and presumably would also boot the new lot if they are no good. I think boards should be fired more often if its clear that they are only doing enough to keep themselves in a job that is "very well paid"/. i would say salaries in 2024 are not a pittance !.
On the flip side you probably want someone suitably skilled at this retail segment here running the business - i ssupect those that have delivered success recently may not come cheap !
per copilot in 2024 pay was
Topps Tiles (LON:TPT)
oh dear looks like pay totals got chopped out - here they are for 2024
Executive Directors
Rob Parker - Chief Executive Officer
Base Salary: £438,000
Total Remuneration: £538,000
Stephen Hopson - Chief Financial Officer
Base Salary: £280,000
Total Remuneration: £345,000
Non-Executive Directors
Paul Forman - Chair
Total Fees: £150,000
Cavendish (LON:CAV) also had an update today, seems to be similar to the Peel Hunt (LON:PEEL) in terms of current trading momentum, future outlook statements.
I continue to hold for an IPO recovery, which does seem to have picked up steam given the number of leaks/rumours of investment banks and advisors being appointed for several private companies. But the volumes don't quite look like an tsunami yet. If there was a time there would be tsunami, it would be now (after the summer break, tariffs now "stable"). So October would be a key month to watch out for announcements, for a 2026 IPO pipeline.
(I hold in the Boon Fund)
I also hold Cavendish, following encouraging noises in the UK M&A sector but also because I was hoping to see significant synergies coming through from the merger of the two boutiques which formed Cavendish last year. I'm a bit disappointed with the market reaction to the results.
Interesting announcement today, Reuters report that VISA has started trials to allow businesses to use Stablecoins to fund international payments rather than having to pre-deposit cash. The Genius Act in the US is cited as making the process more legitimate and adding regulatory clarity.
There is some further comment in the article that the trial, should it prove successful, could erode the market dominance of existing players.
Comment in the article concludes by suggesting that Stablecoin is moving from being a gimmick to becoming a future key component in money transfer.
EDIT: link now attached
https://www.reuters.com/techno...
Stablecoins potentially solve one of the cross-border problems, which is that of interconnectivity. However, the stablecoins still need to be exchanged into fiat currency at either end so that means the end parties need the liquidity to support this and there needs to be stablisation mechanisms for the stablecoins to ensure they don't drift from the parity rates.
Also remember that Visa don't take any intermediary risk - they're offering networking services and some rules. The actual money needs to come from the end parties. The main dominant party in this space is SWIFT who are doing their own thing on blockchain:
https://www.swift.com/news-eve...
Stablecoins have a role to play, but they don't come close to solving most of the cross-border problems.
timarr
Hi intuitive6191
Thanks for sharing that article.
As a holder of Wise (LON:WISE) I'm keeping a close eye on the Stablecoin (SC) world and what it might mean for cross-border remittances.
I still can't get my head around how SC will truly challenge the Wise business model, which, simplistically speaking, aims to:
The way I see it, this is also the only way a StableCoin model could work as well.
---
Here's a podcast on the subject from the founder of Bridge that some may find interesting.
This company is also aiming to use StableCoins and I was hoping there would be some "aha" moment where I realised that my thinking was wrong, but I didn't hear it.
I'm therefore yet to be convinced that StableCoins - without some sort of government involvement - are going to drastically revolutionise cross-border payments.
https://open.spotify.com/episo...
Cheers again for sharing
A
Hi abtan
Stablecoins are a messaging mechanism for money - you can, theoretically, use them as a store of value, but I'm unclear why you'd want to do that as it simply adds another layer of risk.
Wise (LON:WISE) could use stablecoins - but when it has point to point connections across the major currency corridors, increasingly has direct connections into peoples' bank accounts so the cash lands in the account with no user involvement and vast pools of liquidity to fund these transfers it's unclear what benefit they'd get.
If, on the other hand, I'm connecting two different institutions across countries together and managing wholesale scale payments then stablecoins may well be an improvement over something like SWIFT - but only if the rules and regulations apply across both the countries involved.
Broadly the people and companies involved don't care about how the money moves as long as it does so quickly and at low cost.
It's perhaps also worth noting that stablecoins aren't always stable - there are lots of examples where they've lost their peg to the underlying currency: this can happen due liquidity issues or, as in the case of USDC, where the bank holding their reserves collapsed.
timarr
Good to see that my post had been of some interest.
ABTAN - my interest here is really only on Crypto/Blockchain in general. I had always thought that the establishment would eventually have to embrace or respond to the Crypto world.
As regards WISE, I use it in a limited way. I think that its web site is well designed and the features easy to use. I don't hold WISE but it is on the radar as a potential investment.
Nice to see a post that grasps the idea of how markets actually work.
The establishment has embraced the Crypto world!
Let’s see how the new Blackrock BTC ETP performs when it hits the market here in the UK in a few days. The FCA has finally woken up although more has to be done for an ETF similar to the US ones.
All the best
You mention Defence Holdings (LON:ALRT) . Have you any comments or concerns about this stock that has recently reinvented itself?
The monthly Investment Trust thread is now up for October. Added ETF's coverage on https://www.stockopedia.com/co...
Good TU from Northern Bear (LON:NTBR) .
SR 99. Low PE,, decent yield. Term debt repaid. We hold.
Northern Bear (LON:NTBR)
yes very nice - one issue with Northern Bear is that whenever they have a good spell they have traditionally defaulted to it being unexpectedly good - and they may not say it but that often means that the following years comparatives should be expected to drop back down to lower levels . As most companies are valued on the future that never really helps the shareprice.
For there to be tangible long term progres they need to set the base level at higher expectations - i think the market is giving them more credit than they did previously in that regard - but not fully.
But i still get the feeling from todays update that - yes this year looks great - to match last years great - but we should necessarily expect the same for 2027 - will be intersting to see if the 2027 numbers are upgraded at some time. Note 2027 expectation sare materially lower than 2026 at present - the £1 windfall today though complicate things if that is pimping up the 2026 numbers.
Either way they are making sold progress - what they really need to do though is to get to base level of £2 mill pa clean net profit.
What has clearly helped here is the sharebuybacks done too - we own materially more of the company than we did do previously so looks they money sepnt on buying back shares was very well spent.
Note if we look at next years EPS thats only 11.3p with current shareprice of 105p - if 2027 forecasts are NOT upped or beaten i am slighly worried that price might retrace. Thats one problem if they are consistently being over cautious ref "next year" the good times for shareprice (perhaps now) might not hang around for long.
Northern Bear (LON:NTBR) - I confess I've read the RNS a few times and I am still not sure of precisely what they are trying to say and it would be nice to know where this one-off profit came from.
I think they are saying that the current year's EBIT is broadly equivalent (which as Mark said may mean slightly below) to last year's Adjusted EBIT of £3.8m (i.e. before the closure costs of H Peel, etc. reduced this to a £3.4m EBIT) and then they have this one-off profit on top? I would love to hear if anyone gets any further clarification.
Given current trading and last year's results they do seem to have made a step change to profits even if this has been with the assistance of good weather. EPS has benefitted even more due to the last share count reduction.
I'll be happy to hold through until the interim results, but will then be keeping a close eye on the weather over the winter. I also find that they are one of the shares that tend to drift down quite markedly in periods of no news so may take some profits (hopefully) after the interims.
Northern Bear (LON:NTBR)
And it ends the day qualifying for Ed's 3 rules
1. Trading ahead of expectations
2. SR > 75
3. SP up > 10%
Why is Airtel Africa share price up yesterday and holding
can't see anything - I normally check BBs like LSE CHAT if I am not sure what's driving a share on any day but nothing mentioned re Airtel Africa (LON:AAF)
From Deutsche yesterday:
Airtel Africa spin off could fuel share rise, says Deutsche Bank. Airtel Africa (AAF) is planning to list its mobile money unit, a move that Deutsche Bank predicts could fire up the group's shares.
Analyst John Karaidis retained his 'buy' recommendation and target price of 280p on the telecoms and mobile money services provider to 14 African countries.
On Tuesday, it was trading down 2.8% at 217p but has soared 86% over the past 12 months.
Airtel Africa said it is 'absolutely committed' to listing its mobile money unit by 2026. 'Subject to AAF disclosing further substantive information about [the mobile money unit] pre its initial public offering (IPO), we believe this business may be worth at least 12.5 times full-year 2027 Ebitda,' said Karadis.
'Thus, and also valuing AAF Telecom at seven times full-year 2027 Ebitda at least, we estimate group value could reach at least 380p per share, up 71% versus the stock's last close.'
On top of this, he said the IPO of the mobile money division would 'compel most to assess AAF's value mainly on a sum-of-the-parts basis, which is not the case now'.
Morning All,
MS International (LON:MSI) nice contract wins, 42.1M dollars by next year end. About time!!