Daily Stock Market Report (Wed 20 Nov 2024) - CML, DPLM, CHH, SGE, RNO, FRP, KGH, MTEC

Good morning!
That's it for today (12pm). See you next time!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023
Companies Reporting
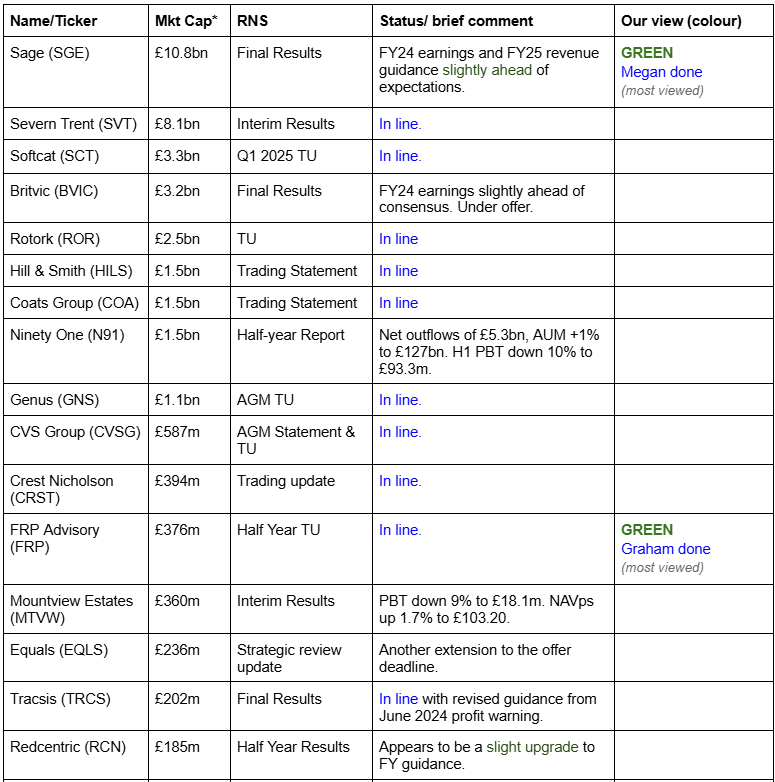
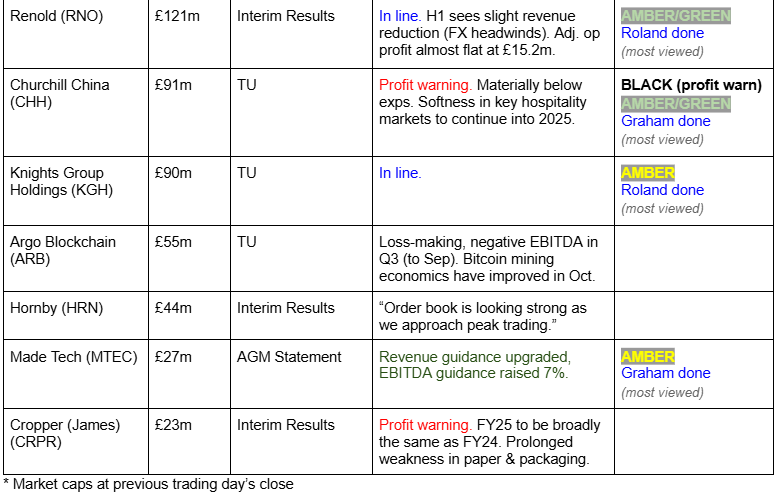
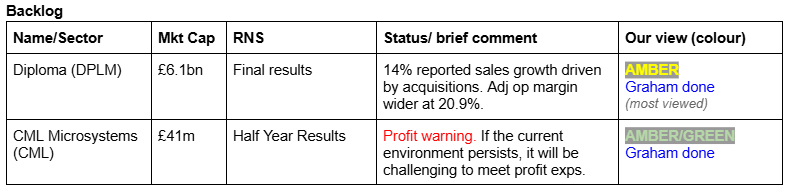
Summaries
CML Microsystems (LON:CML) - down 12% yesterday to 226p (£37m) - Half Year Results - Graham - AMBER/GREEN
This semiconductor developer conceded yesterday that if current conditions continue, it will struggle to meet forecasts. Existing forecasts are for revenues of £24m and adj. PBT of £2.1m. With the company still holding cash of £15m, I think it could be worth a second look.
Churchill China (LON:CHH) - down 27% to 600p (£66m) - Trading Update (profit warning) - Graham - BLACK (AMBER/GREEN)
A severe profit warning with 2024 is now shaping up to be materially below expectations, as the usual seasonal uplift has not appeared. Looking ahead, CHH also reduces expectations for 2025 on the grounds of higher NICs affecting both itself and its customers. I keep our mildly positive stance unchanged as this is possibly not far off deep value territory.
Sage (LON:SGE) - up 16% to 1250p (£10.8bn) - Results for year ended Sep 2024 - Megan - GREEN
Spectacular results from the accounting and software company, alongside the announcement of another massive share buyback scheme have added to the momentum Sage shares have enjoyed since the election of Donald Trump. Management has also hiked expectations for next year. And with quality metrics ticking back up to their historic highs, I think this is now worthy of its lofty PE ratio.
Renold (LON:RNO) - down 6.7% to 50.2p (£112m) - Interim results - Roland - AMBER/GREEN
Full-year expectations are unchanged from this industrial chain manufacturer, but there’s underlying weakness in some core markets and increased debt from acquisitions. The shares look cheap but investors may want to consider the ongoing cash drain to service the pension deficit.
Frp Advisory (LON:FRP) - up 6% to 156p (£385m) - Half Year Trading Update - Graham - GREEN
Leaving our positive stance unchanged as FRP gives a very nice update with more than 50% of full-year revenue and adj. EBITDA already in the bag. Net cash of £13m is left after a busy period for acquisitions which has seen the company’s impressive growth trend continue. More of the same please.
Knights group (LON:KGH) - up 5% to 113p (£97m) - HY trading update - Roland - AMBER
Today’s half-year update shows a respectable 3% increase in adjusted pre-tax profit margins, lifting HY adj PBT by 26%. However, I’m wary of the scale of adjustments employed by this legal services business. I’d like to see a full set of accounts before forming a stronger view, so am remaining neutral for now.
Short Sections
Diploma (LON:DPLM) - down 8% to £41.74 (£5.6 billion) - Preliminary Results - Graham - AMBER
This was mentioned in the comments thread yesterday, as readers noted it fell 8% despite posting what appeared to be solid results with a positive outlook for FY Sep 2025 (organic growth c. 6%, plus net growth from acquisitions announced to date of 2%, and an operating margin of c. 21%).
According to a Thomson Reuters alert, citing LSE data, the FY 2024 result was a very slight miss in terms of revenue (£1.36bn vs £1.37bn forecast). They also said that the adj. operating profit result (£285m) was below forecast, but according to their own figures that wasn’t true.
I can understand the frustration that holders might feel when a stock reacts in an exaggerated, downward fashion to results that seem absolutely fine. When this happens to a highly-rated stock, I interpret it as profit-taking: highly-rated, successful stocks tend to be sensitive to any perceived miss, however slight.
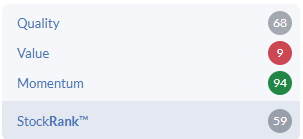
Reflecting its high quality DPLM trades on a forward PER of 25x, and has a ValueRank of only 9.
Made Tech (LON:MTEC)
Up 16% to 21.5p (£28m) - AGM Statement - Graham - AMBER
This is a busted out 2021 IPO, but its share price found a floor earlier this year:
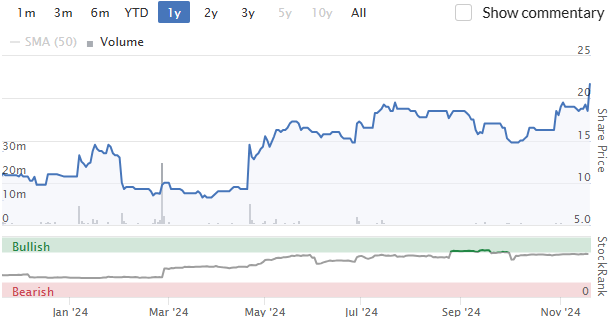
Today’s AGM statement reports that “Sales Bookings” (the value of contracts awarded) is at £37.5m for the year-to-date, versus £36m for the entire prior year.
The board now anticipates that, as a result of these encouraging sales bookings and ongoing delivery momentum, Group revenue for FY25 will be ahead of market expectations set at the start of the financial year. Adjusted EBITDA is expected to increase as margins are maintained, and the Group continues to be on track to generate positive free cash flow in FY25.
Unlike other companies that have been at the sharp end of the new government’s tax increases, Made Tech is a supplier to the public sector and is therefore a potential beneficiary of government spending trends:
The commitment to digital transformation that the UK Government signalled in the recent Budget is expected to unlock a number of further public sector digital transformation programmes in early 2025, and in particular following the UK Government Spending Review in Spring 2025.
Graham’s view: MTEC had £8m of net cash as of May 2024, so the enterprise value is only £20m for a business with forecast revenues of £38m and forecast adj. EBITDA of £2.8m (with thanks to h2Radnor for the estimates).
Unfortunately the company’s track record of converting adj. EBITDA to real profits looks poor to me, so the best I can do for now is AMBER
Graham's Section
CML Microsystems (LON:CML)
Down 12% yesterday to 226p (£37m) - Half Year Results - Graham - AMBER/GREEN
CML Microsystems Plc which develops mixed-signal, RF and microwave semiconductors for global communications markets, today announces its unaudited results for the six months ended 30 September 2024.
I note that CML’s broker Shore Capital left forecasts unchanged, despite the following sentence in yesterday’s outlook statement:
…given the investment efforts to unlock future financial and operational gains alongside the protracted US building permit process and related costs, if the current trading environment persists, it will become challenging to meet management's full year expectations for trading profitability.
Explaining their decision not to change forecasts (an unusual one, in my view), Shore observed that “there may be opportunities in the near-term to unlock exceptional value from the Group’s non-operational property assets”. They left the revenue forecast at £24m and the adj. PBT forecast at £2.1m.
The overarching message from CML’s report was that trading was “resilient”, despite the industry-wide and macroeconomic challenges they face.
For a list of industries they serve, see here - wireless & satellite, 5G network infrastructure, internet of things, and aerospace/defence.
The headline financial numbers were:
Revenue +18% to £12.5m (H1 last year: £10.6m) but this includes £3.5m from an acquisition.
Profit from operations £0.6m (H1 last year: £1.6m).
Without the revenue gains from the acquisition, it looks like revenue would have been down 11% organically.
Cash balance: £15m. That supports a decent chunk of the market cap. Zero borrowings.
The interim dividend is unchanged at 5p (total cost to the company less than £1m).
Comment by the MD, again emphasising resilience:
The progress we've made this period despite the ongoing headwinds in some industrial markets showcases the resilience and adaptability of our business model…
While market conditions remain subdued in the near term, our ongoing investments, strategic initiatives and a strong balance sheet lay the foundations on which to build sustained, meaningful growth in the medium term.
Graham’s view
I try to be reasonable when a company is suffering temporary problems and some of the problems in this report are very likely to be temporary in nature, such as delays in getting building permits from local authorities in the United States.
“Customer inventory management” (AKA destocking) also gets a mention. CML has been talking about this for a while: see Paul’s commentary in July.
With an enterprise value now of only £22m, I’m wondering if I should upgrade this to GREEN, as a value play? Especially if those property sales materialise and bump up the cash even more, the enterprise value here could start to look very low indeed. The EV/sales multiple is already below 1x.
The shares have been under pressure for some time:
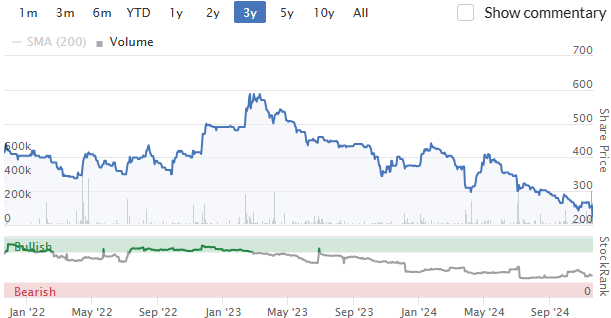
On balance, I’m inclined to leave this one at AMBER/GREEN. There is upside potential from a recovery in trading, from new product development, and/or from property sales. The cash pile helps to support a chunk of the valuation. And it is still profitable, albeit marginally so.
I think there’s more to like here than to dislike. AMBER/GREEN it is.
Churchill China (LON:CHH)
Down 27% to 600p (£66m) - Trading Update (profit warning) - Graham - AMBER/GREEN
The H2 profit warning has landed - see Paul’s commentary in September when a subdued outlook statement raised concerns that this might happen.
Unfortunately this is about as bad a profit warning as it gets, with weak trading expected to continue into 2025.
Year to September: revenue below expectations, but profit not affected as significantly. No huge surprise there; at the interim results, CHH said that markets were subdued and they were dependent on the normal seasonal uplift in the final four months of the year.
Q4 to date: “the Company has not seen the normal seasonal uplift in order intake from, particularly, the independent sector”. As a result, full-year profitability will be “materially below market expectations”.
Looking forward to 2025, the recent UK budget is named as an issue both for CHH’s customers and for CHH’s own cost base - a rotten combination.
It is anticipated that this softness in our key hospitality markets will continue into 2025 driven by the effects of the UK budget and political uncertainty in some key European markets. In addition, implications of the recent UK budget will materially impact the cost base which can only partially be offset by price increases.
The result: cost cuts at CHH, and a reduction in the profit forecast for next year, too.
Chairman comment:
"The current macro-economic uncertainty combined with significant increases in our cost base creates near term challenges. We are, however, confident that our core strategy will continue to deliver growth as markets improve."
Estimates: brokers Investec do not make their reports easily accessible to the public. The prior forecast was for nearly 80p of EPS, which was already looking optimistic before today’s profit warning:
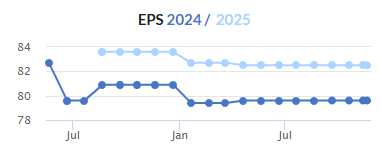
Graham’s view
We were AMBER/GREEN up until now, on the basis that the company had a strong balance sheet with net cash (£8m as of June 2024) and net assets of £60m, including freehold property.
The market cap (£66m) is now only a little higher than net assets.
I’m therefore inclined to leave this at AMBER/GREEN, despite the profit warning. That’s not a statement about what I think might happen with the share price in the short-term, it’s more a reflection of my view that this is a fundamentally sound business with plenty of assets to see it through a period of economic weakness.
With the share price down by nearly 30% today, after quite a long period of negative momentum, I think there’s a chance that this is heading into deep value territory - and I wouldn’t want to be neutral or negative on it if that happens.
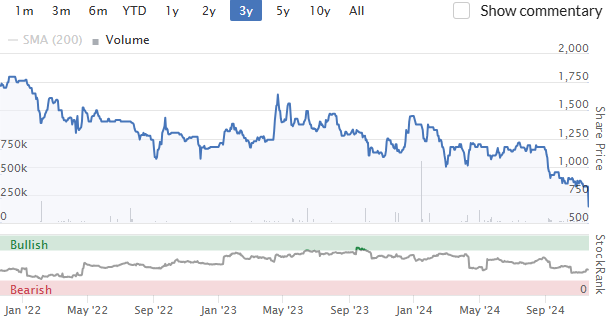
The most obvious downside risk is that higher NICs create a problem for the hospitality sector that lasts for several years, permanently reducing demand and shrinking the size of CHH’s business. After a period of high inflation and a cost of living crisis, the embattled sector is now facing a higher tax burden.
I tend to find that businesses can adapt to higher taxes, although it does take some time. Perhaps by 2026, both CHH and its customers will be comfortable with the new circumstances?
Incidentally, I would urge CHH to make a set of forecasts available to the public. With a market cap well below £100m, and a free float smaller than that, why not make it easier for small investors to access information about the company’s prospects?
Megan's Section
Sage (LON:SGE)
Up 16% to 1250p (£10.8bn) - Results for year ended Sep 2024 - Megan - GREEN
Final results from accounting software group Sage are truly fabulous.
Sales are up 9% to £2.3bn, with like-for-like numbers up across all three of the group’s operating regions.
Software subscription sales, which are recurring, now account for 81% of group revenue. And as accounting software is not the easiest thing to unravel once it’s embedded into a business, these sales are very sticky and reliable.
That means that when management says that sales in FY2025 are expected to be 9% higher (which is an improvement on previous forecasts), myself and the market have great faith that these numbers will be achieved.
As is common with software companies, cost of sales is incredibly low at Sage meaning gross margins tend to exceed 90% (92% in FY2024). But the margin number that I am especially impressed with in these numbers is operating margin.
Sales and administrative expenses fell FY24 compared to FY23, despite the massive hike in sales. That means that the company has spent less to achieve more. Operating margins are 19% - creeping back towards the 20% mark that I like to see in very high quality companies.
I also like the annual recurring revenue number which is £227m higher at £2.3bn, with £190m of that coming from new customers. The company hasn’t split out marketing and sales expenses in these numbers, but presumably they weren’t massive given the decrease in overall cost of sales.
Revenue retention is at 101%, which reflects low churn and an increase in average revenue per customer thanks to price rises and upselling new products.
Underlying earnings are 23% higher at 32.1p, ahead of previous expectations, which had been hiked slightly during the year.
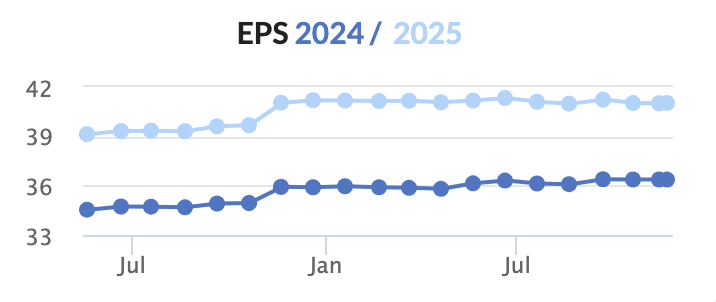
These numbers also continue Sage’s strong track record of turning profit into cash. Operating cash inflows have materially exceeded operating profits in every one of the last ten years. In FY24 the company reported free cash inflows of £524m - a 30% increase on the previous year and equivalent to cash conversion of 123%.
That cash has been put to work in the business via £24m of capital expenditure (primarily invested into research and development) and £34m of acquisitions. The company also uses its cash to reward shareholders, spending £199m on dividends and £348m on share buybacks in FY2024.
The company has today announced a 6% hike to the dividend (to 20.45p) and a further £400m share buyback programme.
Megan’s view
The only thing I can find to complain about in these numbers is the fact that management hasn’t split out where it is spending its money. Otherwise, the company is fully deserving of the 16% hike in its share price following this announcement.
Overall, Sage’s shares have been trending upwards since the election of Donald Trump. As a major provider to small and medium sized businesses in the US (39% of sales come from the US), the company could be a big beneficiary of pro-business domestic policies of the incoming president.
This isn’t a value play. But with forecast earnings expectations likely to be boosted following these numbers, there could still be further gains to come.
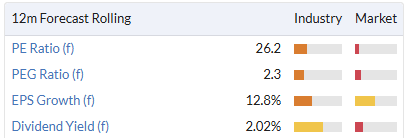
Sage has long been one of the UK’s highest quality operators. I have grown nervous in recent years by the slight decline in operating margins and ROCE, and a stagnation in operating profit growth (despite continued revenue increases). My preference in the sector has instead been for US company Intuit (NSQ:INTU) which has reported double digit CAGR in revenues and profits over the last five years.
But Intuit is trading on an even greater earnings multiple to Sage and if the British company can start generating the same sort of results as its US counterpart, it could be rewarded with multiple expansion as well. GREEN.
Frp Advisory (LON:FRP)
Up 6% to 156p (£385m) - Half Year Trading Update - Graham - GREEN
FRP Advisory Group plc, a leading national specialist business advisory firm, announces a trading update for the half year ended 31 October 2024 ("H1 2025").
This is a confident update, with FRP expecting to meet full year expectations for FY April 2025 (revenue £146.7m, adj. EBITDA £39.5m).
Some bullet points:
H1 revenue +32% to £77.6m (23% organic growth, 9% growth from acquisitions)
Underlying adj. EBITDA +44% to £22.3m
I note that the company has already achieved more than 50% of full-year expectations in terms of both revenue and adj. EBITDA.
Restructuring
I tend to associate FRP’s name with financial trouble (at other companies) and there has been no shortage of trouble in recent months.
FRP worked on the restructuring of the Body Shop in H1. Then in the run-up to the Budget, there was “a spike in the number of solvent liquidations”, due to uncertainty and economic stagnation in advance of that Budget.
The topic du jour is the Budget’s hike in National Insurance contributions, and they are again relevant here:
The increase in employers' National Insurance Contributions announced in the recent budget is likely to put further pressure on businesses with large workforces and lower margins. The retail and hospitality sectors in particular, which were already navigating post-Covid debt service and other inflationary cost pressures, are expected to face additional financial challenges.
Corporate Finance & Debt Advisory: the pipeline of new opportunities is “solid”. Three acquisitions were made during H1 (two in corporate finance, one in debt advisory).
Forensic Services: “relatively buoyant… especially in litigation and contentious insolvency related matters”.
Financial Advisory: this also saw an increase in pre-Budget activity.
Net cash at the end of October was £13m, down from £39m as of April 2024. As we noted above, a number of acquisitions took place during H1.
CEO comment:
FRP has delivered another strong performance in the first half of the year, reporting increased revenue and profits. In line with our proven strategy, we continued to be acquisitive, strengthening the Group with four acquisitions across three of our service pillars. In doing so, we have enhanced our offering and are even better positioned to provide optimum solutions for our clients.
"I am confident that we will make further progress in the remainder of the year, as we support corporates through the entire business cycle."
Graham’s view
As with Begbies Traynor (LON:BEG) I think there is an argument to hold these shares from the point of view of providing some counter-cyclical exposure: a hedge against economic weakness.
It hasn’t all been plain sailing but the shares are approaching highs that have not been seen in nearly two years:
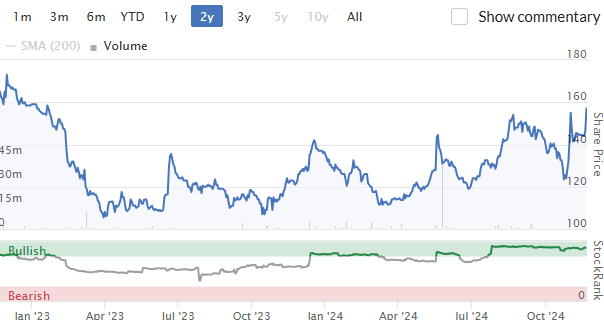
As an investment category, the professional services sector always makes me nervous due to its labour intensity - companies in this sector don’t strike me as likely compounders of value. But I’m happy to leave our GREEN stance on FRP unchanged for a variety of reasons:
Excellent H1 numbers leave them well-placed to hit (maybe exceed?) full-year forecasts
Valuation is not demanding at 14x earnings, but do watch out for the adjustments that will be made to the headline figures.
The company tends to run a net cash position and not to over-extend itself, despite its active acquisition strategy.
So I think I can leave this one GREEN with a healthy conscience.
Roland's Section
Renold (LON:RNO)
Down 6.7% to 50.2p (£112m) - Interim results - Roland - AMBER/GREEN
Underlying full year expectations unchanged
This morning’s half-year results from industrial chain manufacturer Renold seem broadly reassuring at first sight. However, they’ve been cautiously received by the market and I think they may flag up some potential concerns.
While full-year expectations have been left unchanged, I think today’s numbers highlight the sluggish top line growth I mentioned when I last looked at the shares in September.
H1 results summary: the company describes today’s results as resilient, with improved margins, despite ongoing market uncertainty:
Global markets continue to be uncertain, with activity levels in both mainland Europe and China recovering more slowly than initially anticipated. However, material and labour cost inflation is now reducing.
Revenue for the six months to 30 September rose by 0.6% to £123.4m on a constant currency basis, while adjusted pre-tax profit was flat at £11.3m.
On an adjusted basis, operating margin improved to 12.3% (H1 24: 12.0%). Adjusted earnings for the half year rose by 10.5% to 4.2p per share.
However, results at a statutory level were somewhat weaker. Operating profit fell by 17% to £13.4m while interim earnings dropped 25% to 3.3p per share.
The difference between the two was driven by costs relating to acquisitions (£1.2m) and amortisation charges (£0.6m). While I recognise that some of these are one off in nature, Renold has made regular acquisitions in recent years.
In my view, excluding all of these costs may be unduly flattering to results – but as always, this is an individual decision for investors.
Spain flooding: the company says that its YUK manufacturing facility in Valencia (acquired in 2023) was affected by recent flooding. The financial impact is expected to be c. £10.5m. The majority of this is expected to be recovered from insurance, except for a c.£1m deductible.
Fortunately, Renold’s logistics facility in the region was unaffected – this accounts for 70% of the group’s business in Spain.
The company does not “expect any medium term material impact” from the flooding.
Chain division: this is the company’s larger business, accounting for nearly 80% of revenue and a similar proportion of profit.
The acquisition of Canadian company Mac Chain (see here) was completed on 9 September, around three weeks prior to the end of the half year.
The company says that Mac contributed £1.2m of revenue during the period and is performing in line with expectations.
However, without this bought-in growth, the group’s Chain division would have reported a drop in revenue for the period, even at constant currencies:
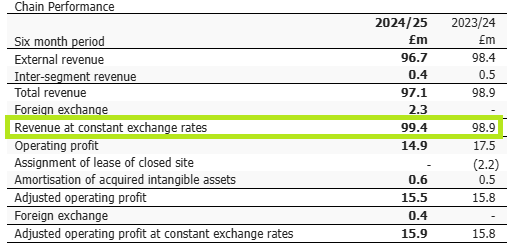
The main area of weakness was in Europe, where Chain sales fell by 1.8% at constant currency. Softness in Germany and Switzerland was blamed.
Disappointingly, the company decided not to share actual figures for these markets, even though positive figures for other countries (UK +4.6%, France +17.7%) and other regions (Americas +0.9%, Australasia +20.4% and India +17%) were included.
This leads me to think that the fall in sales in Germany and Switzerland may have been quite severe.
Reassuringly, order intake for the chains division increased by 4.8% at constant currency to £92.6m.
Torque Transmission: performance in this division also benefited from forex tailwinds, with revenue at constant currency up 2.8% to £29.6m. On an equivalent basis, divisional operating profit rose by 11% to £5.1m, giving an improved 17.2% operating margin (H1 24: 16.0%).
The company says that growth in the US, Chinese and French markets offset weakness in Spain.
Long-term military contracts are said to be continuing as expected, supporting the increase in profitability.
Order intake was boosted by a £10.6m order for the Royal Canadian Navy. Excluding this lumpy deal, order intake at constant exchange rates rose by 3.6% to give a closing order book for this division of £43m.
Balance sheet & cash flow: net debt rose by £13.9m to £42.2m during the half year, due largely to a £22.2m outflow relating to the acquisition of Mac Chain (a further £2.4m is deferred).
This level of debt gives a multiple of 1x EBITDA which looks manageable to me, albeit not ideal given the increased cost of debt – finance costs totalled £3.9m for the half year.
The pension deficit is also a significant factor here. Although the deficit fell slightly to £52.7m during the half year, cash payments in the UK and Germany are expected to total £6.9m this year. That’s equivalent to almost 30% of forecast pre-tax profit!
Finance and deficit reduction payments eat into a company’s free cash flow. In this case, I think the deficit contribution explains why the dividend is expected to be held at just 0.5p (covered 15 times by earnings!):
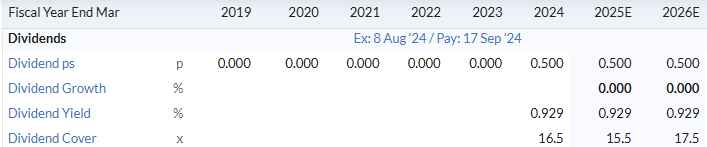
Free cash flow: my sums suggest underlying free cash flow of £4.8m for the half year, equivalent to 74% conversion from net profit of £6.5m. I think the main reason conversion isn’t greater is the cash outflow to pensions, which isn’t reflected in the income statement.
Outlook: Renold’s order book at the end of the half year was £80.8m, down slightly from the “historic level” of £83.6m reported at the end of September last year.
Full-year guidance has been left unchanged:
Board remains confident of delivering underlying full year results in line with market expectations
With thanks to broker Cavendish, I can see that earnings forecasts for the year to 30 March 2025 are unchanged at 7.5p per share. This prices Renold on a P/E of 6.7 with a 1% dividend yield.
Roland’s view
I think Renold is a good business that’s probably reasonably priced. I would hope to see a cyclical recovery over time.
However, I can’t ignore the underlying weakness in revenue, increase in debt and hefty cash outflows to address the pension deficit. In my view, these factors justify a relatively modest rating for this stock, despite some strong quality metrics:
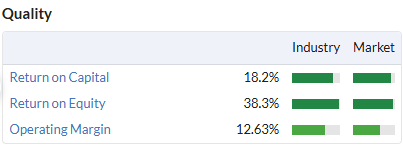
When I last looked at the shares in September, I went GREEN. Having considered today’s results I’m inclined to moderate my view slightly to AMBER/GREEN to reflect the apparent weakness in some core markets and the increased leverage on the balance sheet.
Knights group (LON:KGH)
Up 5% to 113p (£97m) - HY trading update - Roland - AMBER
Confident in delivering a FY performance in line with market expectations
Legal services business Knights Group drew an AMBER rating from Paul when he considered the company’s full-year results in July.
Today’s trading update covers the six months to 31 October 2024 and appears positive and highlights a substantial improvement in profit margins.
While revenue for the first half of the year is expected to have risen by 5.4% to £79.4m, Knights expects to report a 25.9% increase in underlying pre-tax profit to £14.6m.
This reflects a 3% increase in pre-tax profit margin to 18.4% (HY24: 15.4%, HY23: 12.6%).
This is certainly an impressive progression in margins, but I think there are a couple of points to consider here.
Profit adjustments: these are adjusted profit figures. As Paul highlighted in his review of last year’s results, this company is quite an aggressive adjuster. Last year’s pre-tax profit of £14.8m was translated into an underlying pre-tax profit of £25.3m:
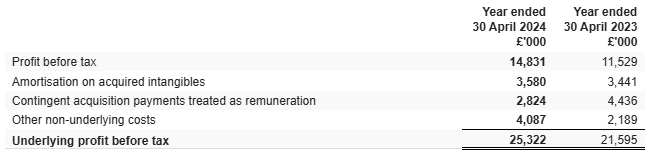
I imagine that this year’s statutory profit figures will be similarly lower. This may not affect the scale of the margin improvement, but it does impact the actual level of profitability and the valuation of the stock.
For example, last year’s reported pre-tax margin was 9.9%, versus an adjusted PBT margin of 16.9%.
For context, Knights Group is a serial acquirer of legal businesses. From what I understand, the majority of the charges that are adjusted out of the underlying PBT figure (see above) probably reflect actual cash costs.
Personally, I’m not comfortable excluding these costs from my view of profits. So I’d probably want to wait for the half-year results before drawing too many conclusions about Knights’ improved profitability.
Balance sheet & acquisitions: net debt rose to £50.1m during the half year (Apr 24: £35.2m), reflecting £8.9m of acquisition-related outflows. The company has secured an increase in committed debt funding from £70m to £100m, providing further headroom for acquisitions.
The current level of debt looks manageable to me, but I’d note that debt is being drawn down for deferred consideration as well as new deals. This suggests that cash flows from the acquired businesses are not fully funding deferred payouts.
On a similar note, there was a slight increase in debtor days to 33 days (H1 24: 31 days).
Outlook: I don’t have access to any updated broker notes today, but consensus forecasts ahead of today’s update suggested adjusted earnings of 23.7p per share for the current (FY25) financial year.
This estimate would price Knights shares at less than five times forecast earnings, with a well-supported 4.5% dividend yield.
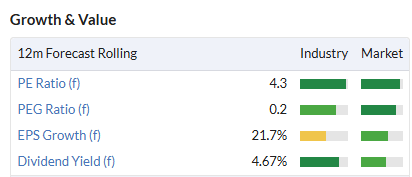
However, I estimate that my preference for using reported earnings would be likely to give a P/E ratio closer to 10-11. This is more consistent with the 4.5% dividend yield, too. To me, this suggests the market may already be pricing the stock fairly, based on real distributable earnings.
Roland’s view
Today’s update seems broadly positive and suggests the company’s quality metrics may be improving.
However, given the company’s approach to profit adjustments and its rising debt, I’m wary about drawing too many conclusions from today’s update.
My feeling is that the shares are probably quite reasonably priced, and perhaps offer some value at this level.
Without seeing a fresh set of accounts, I don’t have a strong conviction here, so I’m going to maintain our view at AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
Like the suggestion of commenting on future trading updates.
Safestore Holdings (LON:SAFE) due 26 Nov.
Agree can go either way so not a short term trade op.
900 was a resistance imo and 800 support, but it broke on the downside so became a "falling knife”, which is horrible for an otherwise business doing business and the catcher of course.
My note on the co is:
The business is driven by life events, selling a house, moving home, carrying out home improvements, getting married or separated, starting a family, downsizing, dealing with inheritance or just needing somewhere to put excess ‘stuff’.
If the housing market takes off then this could fly again. But that is not clear imo. But that does not explain its current negative sentiment.
Just my 2p worth and no hate if don't cover :)
Safestore Holdings (LON:SAFE)
the only thing i can think is quite alot of people i know use satestore type facilities for extended periods of time - if not semi permanently. Perhaps in tough times its one of the easiest expenses to ditch. I doubt they will be struggling but sometimes having boyouant demand allows you to pimp out your customers magins wise - if customers are becoming more picky then preumably they cant do as much pimping.
Note it looks like there has been reasonably frequent downgrading ref expectations here this year - not sure if this is happening behind the scenes - is the weak shareprice not simply a symptom of that fact that they are expecting to deliver less profits than they expected 3 months ago and that 3 months ago expectation was worse than 6 months ago. Kinda like a profit warning spread over long enough a period that its not actually a profit warning?
I kinda see companies like like this as being very defensive - certainly up north in my neck of the woods you cant get commercial premises for love nor money - so backup plan of stuff being easily sellable aint all bad.
Is this companmy actually trading below the TNAV here ? if it is that strikes me as being pretty damn cheap without doing any diligence if its ata material discount. I guess the facts its not on a cheap p/e perhaps makes people think elsewhere may deliver more?
Certainly looks like a decent prospect if the tnav discount is real.
I've got nothing to back this up other than gut instinct but I'm getting a nagging feeling we could be in for a rough period and the usual santa rally won't turn up.
I've noticed pretty much all my investment trusts covering Europe, US, UK small Cap, Vietnam, Oil and mining are all off last 3-4 weeks and showing no signs of turning, the only thing holding up currently is my gold bullion etf.
Hoping i'm wrong but in the words of Han Solo "I've got a bad feeling about this"
Chewbacca does not agree.
British American Tobacco (LON:BATS)
Until Trump comes out on the trade war tariff thing then markets will always want to worry about something, well the pundits anyways.
See Nissan in trouble due to Chinese car imports. Sunderland watch out. Germany as well,
Love the comeback quip Harry
Hi Megan
Thanks for your write-up on Sage (LON:SGE) . It's certainly one that I've never looked at before and I've now added it to my research list.
Incidentally I have used other SME accounting software and completely agree that it's very tricky to migrate to another one once you've started using it.
---
As you mentioned Intuit (NSQ:INTU) in your write-up I hope it's okay to add a few comments.
I held H & R Block (NYQ:HRB) - one of their competitors in the US tax business - until quite recently. It was a lovely holding over the last few years, but I sold out on fears of a Federal free tax submission software that has been trialled in a few US states.
I would have thought the "pro-business" Trump government would have shelved this plan, but it seems like a nationwide rollout is high up on their agenda.
I'm not sure if it's common knowledge, but unlike in the UK, everyone in the US needs to file a tax return every year, even if there's nothing extra to pay. Indeed, I file US taxes every year on behalf of an expat family member who hasn't lived there since she was a child, but remains a US citizen.
It's a complete faff, takes me hours to do, I pay an online company to use their software (not Intuit or H&R Block) and in every year that I've done this there's been no tax to pay anyway.
I imagine most Americans have the same experience as me/us.
I therefore welcome the introduction of a free easy-to-use service, as I'm sure many Americans will - I imagine it will be a big vote winner for the incoming administration, even if it was started by the current administration.
Of course, this will have a huge impact on Intuit (NSQ:INTU) and H & R Block (NYQ:HRB) which explains the drops in their share prices in the last week. The former especially has been an amazing company to hold for a long time, but I wonder if the risks are now too great to justify such a premium valuation if their sticky revenues are not so sticky any more.
A
Incidentally I have used other SME accounting software and completely agree that it's very tricky to migrate to another one once you've started using it.
note if anyone wants to move software movemybooks is the go to solution - if you go from sage/xero/quickbooks (or others) to one of the others its normally as simple as uploading or linking up software to movemybooks and the system will move across at least 2 years complete transaction data for free (extra years at a fee) - this process might not ALWAYS be 100% perfect (eg you may lose pdf attachments often in some software and there can be oddities ) , but it mostly works well without any fuss (as long as you follow the script) - so there are options than can make the move fairly effortless - so whilst its still a chow making the decision to change (you need to learn new) - practicably speaking its no biggie moving from sage to xero or xero to sage for most people - most people though might not realise these solutions exist. As a sage shareholder myself (first share io ever bought back in the day) - i probably should be keeping quiet here about these options =).
Bsharman, I no longer pay for research tree but I do still get some reports for free. If you will to subscribe, do it through The naked trader here:https://www.research-tree.com/...
25% off but also a 14 day free trial. Worth doing even if just for the trial. I still use research tree a lot despite not being a paid subscriber.
I just wanted to say to Graham and the other authors, that I think this new style Daily Stock Market Report is working really well.
Having the status/brief comments column completed before 8AM is so super useful. It means I can read any RNS in a targeted way before market open. Then peruse the remaining at my leisure.
Thank you!
Thanks for taking a look at CML Microsystems (LON:CML) Graham.
Value play is my thought too. Personally I do not see the company recovery in the next 6 months but I do think it is close to the bottom as far as the share price is. It certainly has a fair amount of technology that is needed and little competition. Cash is down on last year but that’s just because of the last company it bought which is doing very well. It may well sell land in the uk which is meant to be worth about £2.5m.
There is a very good write up by broker on research tree about the company (it’s free to view for those who do not subscribe).
worth mentioning is the fact the company did a buy back of 30k shares yesterday, which was a bit out of the blue, so that suggests the bod see value in the current price. Also worth noting is it has a low share count of 17m shares, so it can move the sp quite easily, both ways.
Thanks for posting - I had a look on research tree but the research is behind the paywall?
Have you registered?
Hi gmtrader, If the BOD believe that CML shares offer value why are they using shareholders funds to buy shares and not their own money?
That’s a good point. Maybe they don’t have enough cash of their own?
Thanks. I thought that was a really good write-up on CML Microsystems. Regards, Andrew
You're very welcome Andrew!
Paul said at Mello last night that he thinks Vistry (LON:VTY) is cheap. Today;s RNS announces the departure of the COO. The Vistry TU on Nov 8 said that one of the Board's actions was " People: organisation changes are under review and new appointments are under consideration with the objective of improving transparency, enhancing management capability, reducing the length of reporting lines and ensuring closer proximity of the CEO to the business. ...", and the announcement of the departure of the COO says it's to shorten reporting lines so probably reflects a Board view that the COO has to bear accountability for the problems in the South division. Continued share buying by the directors and their associated organisations suggests that they think the COO's departure should draw a line under the price fall. They have collectively lost a huge sum from their purchases since the TU.
Vistry's SP has continued to slide since the open today (it's 624-625 as I type this at 13.15).
Vistry (LON:VTY) - Thanks for pointing this out FREng - thought it was just another bad day - which it is. As you point out - the Directors and Instns must be sitting very uncomfortably on their losses now as they have all topped up earlier this year. Seems the volume of Vistry shares traded today is double the norm
Vistry (LON:VTY)
i think management here really created this issue by saying there may be more issues to come out that havent as yet been quantified - if ever there is a marker that you dont know whats going on in your business its saying stuff like that AFTER you have had a full investigation. The fact the extra stuff is likely to be non material according to them presumbaly doesnt wash based on whats gone on under their watch.
IMHO them blaming one area management as well is an utter complete cop out - is the boards main job not to ensure that everything is done in the right manner ? surely if they couldnt spot £300 million hole in the books its suggests they are not fit and proper personages to be running a company of that size.
It wouldnt surprise me if this company bounces back nicely at some stage but from everything i have seen up to now the board appear to be the main issue here ref credibility (they have non in my eyes)
Foolishly bought on the first profit warning. It's a 2bn company not some blue sky small cap. Never try to catch a falling knife. Wait for the break up not the bear flag. Another one for the "coffee can". Hope is not a good trading strategy. The cost of learning. Who would want to buy the 'ruins'.
What do we recon, best in or out for tomorrows trading update??
Liontrust Asset Management (LON:LIO)
Liontrust Asset Management (LON:LIO)
I'll look to add on any gross over reaction tomorrow morning. Divi cut likely so probably sell off but hopefully will recover over time as funds flow back into the UK eventually.
Made Tech (LON:MTEC)
Since this is not listed in the US I can still comment (at least until the end of the month!)
Honestly I am very disappointed why Graham thinks that this is not GREEN.
Made Tech (LON:MTEC) is bidding and winning big contracts and has won EVEN TODAY new contracts about £3m.
The company has no debt and increasing its cash pile. In my calculations the cash will be over 50% of the current market cap in 2026.
This is as GREEN as it can get with the new well proven CFO. Early days.
I hold from 14p and have mentioned that this will be a multi multi multi bagger.
All the best
Made Tech (LON:MTEC) : "....this will be a multi multi multi bagger." So, I take it you're fairly optimistic then, yiannos1?! Seriously, thank you for all your insight and valuable input over the years and I wish you all the best in the US.
P.S.
I've joined you in Made Tech (LON:MTEC) today so I hope you're right!
Good luck on the West Coast of the US Yiannos ... you will be missed.
Is this a people business so likely whacked by the NI bomb.
And what is the AI angle - a disruptor in all these type of sectors. Long way off in our 'public services' for sure, and will get mugged on the way to the efficiency tree.
Trump seems to be more experience this time imo maybe setting up for his daughter (Dynasty) so the uncertainty will be part of the negotiation play. His Energy guy is from er Energy, so not some idiot who's dissertation was on the (whatever).
Bring back Jim Hacker - he will sort it out (well maybe - still listening on Audible on the commute).
I will not pretend that I understand what are you talking about other than story telling.
I make my investment decisions based on numbers , clean balance sheets , FCF generation and my own calculation of the intrinsic value of the company in question-in this case Made Tech (LON:MTEC) .
All the best
hVIVO (LON:HVO)
Anybody any idea why price has crashed over the last week?
They presented at Jefferies Healthcare Conference yesterday - perhaps some bad news?
Paul and Roland have both liked it this year.
I've increased my smallish holding today.
It's very odd. Octopus have been buying hVIVO (LON:HVO) steadily for weeks, in tranches of 1% of market cap. I haven't seen who is selling, which is odd as it must have taken them below a notification threshold.
I imagine this is related to the possible appointment of RFK Jr as head of US Department of Health and Human Services. This could have implications for pharma companies.
But if that is the case, it should be good for hVIVO (LON:HVO) . As I understand it, RFK Jr is pro DATA, i.e. if companies can show their products are effective, and safe, then they should get approved, regardless if it's a vaccine or something else. But if the data shows otherwise, or companies withhold data they shouldn't be prescribed/on sale.
That climate should suit hVIVO (LON:HVO) I would have thought.
I agree with that af20001. I think investors have just dumped the whole sector though. US-listed Medpace Holdings, which offers similar services to hVIVO, is down 10%+ over the last five days.
Thanks for all the useful comments.
Just noticed the little flags on the stock reports linking to articles.
Thanks to the tech guys, this is a major improvement and really helps. In my view Stocko are by far the best platform for private investors.
Yes the links are a great little enhancement. I always look at the chart and want to see the related news flow when I start researching a new idea.
I agree. And I also like the latest option (account/notifications) that selects whether one wants an alert when a comment receives a reply.
Thanks to BnB for Sage (LON:SGE) and Yiannos for @APLD comments. You have opened up a world of opportunity for me! When combined with the Daily SM Report and PS the Stocko community has improved my life.
Thanks to BnB for Sage (LON:SGE) and Yiannos for Applied Digital (NSQ:APLD) comments.
Happy if I have been of some help but regretting the size of my position. It wasn’t bullish enough! Truly great set of results.
Excellent results from Sage (LON:SGE) today. Solid growth and a decent buyback. This stock is a great example of the fact that expensive stocks can still generate brilliant returns.
£SGE
It been a bit of a long slog for sage it took them 23 years to match the peak price back in 2000!!! So it probably depends on when you first bought !
operationally they have delivered and they are now clearly starting to benefit from the move from old school desktop to mostly sass.sage50 is still alive tho !
I would say the peak price in 2020 was ridiculously too high - pretty much based on earnings 20 odd years later !!
Hi Graham, many thanks to you and the team for the excellent analysis and increased coverage of stocks for our DYOR. I would appreciate analysis of Frp Advisory (LON:FRP) and Knights group (LON:KGH) (I hold). Both with excellent half year reports and confident 'in line' statements for the full year. Both sound like laying the ground for future 'ahead of expectation' updates?
Frp Advisory (LON:FRP) agree looks very good and should pick up further business following the various announcements at the budget (both restructurings and financial advisory as business owners look to sell-up). On 13x earnings, still looks quite cheap given the growth.
I'd be very interested in your views of the Churchill China (LON:CHH) trading statement. I had this on my potential turnaround value (trap) watchlist. Looks like it was a value trap as hospitality remains 'subdued' and costs in the UK will increase due to the budget. It has a good balance sheet and product, so it should recover in the future.
Made Tech (LON:MTEC) in a sweet spot now as govt. ups spending on digital transformation. Mtk cap £30m, cash £8m, peg 0.4
AGM STATEMENT
Strong sales performance in HY25 with trading ahead of expectations
"The commitment to digital transformation that the UK Government signalled in the recent Budget is expected to unlock a number of further public sector digital transformation programmes in early 2025, and in particular following the UK Government Spending Review in Spring 2025."
https://newsfile.refinitiv.com...
Renold (LON:RNO) seems mainly a mgt enrichment enterprise…hard to see why shareholders go along with it
Thanks for letting me know. I was thinking of investing but not now. More than 10% of total shares issued to management each year!
I think you have misunderstood the numbers in the Renold (LON:RNO) table quoted by Rhomboid.
The charge for the half year is £0.8 million. Last year was £0.7 m for the corresponding half year and £1.4 million for the full year. Greedy? Yes, undoubtedly in my view, but nowhere near what you are suggesting!
Renold (LON:RNO) AR has the details https://investors.renold.com/~...
the total numbers here are way too high imho..and base remuneration is also way above reasonable levels…so any attempt to value the business needs to account for the costs of buying these shares to give to mgt & also the hefty pension contributions that bypass the P&L too.
Renold (LON:RNO)
Worrying also the 7 thumps up -:)
And those Renold (LON:RNO) management bungs to themselves really need to go through the P/L (morally not legally) to make obvious the level of greed
Worth noting that this doesn't mean the CEO and CFO are getting £29M this year! It's merely the amount in the kitty available to all future management incentive schemes. The current award scheme does not vest until July2027, whereupon if the SP were to hit 69p, the CEO would stand to gain ~£880k and the CFO rather less. That doesn't sound quite so bad to me. Of course Id be first to agree that putting so much into the kitty for future management payouts gives a real pigs-at-the-trough impression and they'd have done far better to have simply cancelled some of the shares bought cheaply in the first half of the year as suggested by Paul previously. On the back of the huge pension payments the question of whether this is a company run for shareholders as much as employees is fair, but in my opinion not to be over done, with a substantial SP increase over the last year.
My stronger concern is the potential affect of any incoming trade tariffs on future sales, particularly with steel and steel products always being such a hotly disputed tariff area. RNO have bases in pretty much every corner of the world including major chains facilities in the US, so we'd need to understand the breakdown of orders for each plant by geography and have a crystal ball re future trade deals. I don't think any of us can even begin to guess - but it's hard to believe that Renold would remain blithely unaffected. I'll try to join the webinar this evening and ask the company for it's thoughts on this issue.
Renold (LON:RNO) From today's webinar. CEO view on risks related to increasing tarrifs:
Also some interesting observations in relation to their acquisitions strategy:
Frp Advisory (LON:FRP) half year trading update, looks pretty good, the market likes it, maybe could be reviewed?
Where has Davidjhill gone? Anyone know?? Missing his solid analytical input.....
Was just wondering that myself, especially as he is/was a long-term holder of hVIVO (LON:HVO). Anyone have any ideas what is happening here? The stock is absolutely tanking day after day on no news. Seems well-managed, plenty of net cash, good prospects. Is this just marketmakers walking the stock down to shake people like me out of it or could there be something else going on? I hold, though not as many as before.
I was also wondering what news I had missed with hVIVO (LON:HVO). Any insight from Graham (or anyone else) would be very much appreciated.
Wonder if it being dented by the Trump, Kennedy appointment who is an anti vaccine person. This is hitting Pharma shares and they may cut back on vaccine research which is one of the areas HVIVO do clinical studies on - I believe.
It is an absolutely insane stance, vaccines have saved millions of lives since they were discovered and have much greater potential even for things like cancer treatments.
Trump believes in bleach, l really do wonder sometimes about political leaders.
hVIVO (LON:HVO)
Wonder if it being dented by the Trump, Kennedy appointment who is an anti vaccine person. This is hitting Pharma shares and they may cut back on vaccine research which is one of the areas HVIVO do clinical studies on - I believe
It’s partly this but actually as much to do with the threat from the DOGE (Musk - government efficiency) where it is feared that the FDA will come under great scrutiny that will hamper its operations, slowing the pace of drug discovery and development. Holders can take reassurance from the similar trajectory of US-based CROs - it’s not an idiosyncratic move down, but one hat is exaggerated by the lower liquidity.
Is the issue not that due to bribes (practically speaking ) these drug and insurance companies engage in blatant price gouging tactics with no recourse - I am all for freedom but very little done by many of these drug firms sits easy with me - obviously they won’t all be up to it but. To me if doge that out it’s no bad thing. I may be wide if the mark here these 2 may be looking after the interests of their mates - I suspect in the real world it’s not as easy to chop costs as musk thinks it will be
Maybe he's at Mello in Derby? I'm guessing that accounts for part of the quietness of the board this week.
£BVIC With the results out today, and takeover still some way off would be interested to hear thoughts if it's worth selling now or holding on. Thanks
Britvic (LON:BVIC) - Done my research and FWIW will hold on simply to insure a small profit but above all - nothing lost
We have three holdings with interesting RNS reports today Graham, if you or any team members get time, your observations would be much appreciated. Frp Advisory is probably the simpler one with everything going in the right direction, Ninety One is by far the most interesting and significant with a take over of Sanlam who will retain a stake of 12.3% in Ninety One. Ninety One claim it will be profitable for them from the start but only after three years for Sanlam. Finally Mountview Estates, everything down, including the share price but net asset value up. It's a long term holding of Maynard Paton who topped up on Mountview recently and has written in depth about it.
Mountview Estates P.L.C. (LON:MTVW) pushed by Simon Thomson in years past but seems to be another of his turkeys.
Renold (LON:RNO) maintaining their stance of being eerily quiet about the impact of their acquisitions. First full 6 months of the Davidson chain numbers and not a mention I can see, without which constant currency revenue is surely declining.
Putting aside the still sizeable pension deficit, it’s going to be a monumental diversion of cash if you have to do acquisitions just to stand still. I like this company as the type of business I’d choose to invest it - but something is dragging on performance and management don’t seem to want to talk about it.
Renold (LON:RNO) plus all the money they spend on share options, for some directors, which Paul Scott uncovered. What was it £9m over 3 years?
Something like 99% of shareholders voted in favour of the Renold (LON:RNO) directors remuneration report/LTIP at the AGM - ridiculous in itself in my eyes - but no wonder therefore management think they can get away with such poor disclosure on the performance of the businesses they acquire.
Looking to get shot of my few remaining Renold (LON:RNO) shares, noticed the spread is very narrow, 48.97p to sell, 49p to buy, not sure what that means, maybe lots of trading?
Spread narrowing sometimes reflects a turning point or move imminent.
Hi Graham. Your thoughts on Renold (LON:RNO) would be appreciated. I hold.
Hi Revs, request noted, someone is v. likely to cover this. G
Graham, thanks for covering Diploma (LON:DPLM), the Stockrank value is now 9, presume the PE will change if share price stays the same.
The PE was 33 at the 2024 FY results.
CML Microsystems (LON:CML) do you mean building permits in the USA or UK, l thought their land was UK based?
Morning Rusty. Re: DPLM I updated the graphic to show the new ValueRank, forgot to update the text! Many thanks. Re: CML the building permits are in the US, they need to reconfigure their operations. G
There have been disappointing delays in obtaining local US government building permits that are needed to unlock efficiency improvements and cost reductions within the Group's Silicon Valley-based facilities. The first half results include elevated costs relating to those delays with additional expenses stretching into the second half. Whilst it is not possible to put a definitive date on a resolution, current expectations are for the situation to be resolved by the end of the calendar year.
I see thanks for clarifying, on CML Microsystems (LON:CML). I used to hold, will have another look.