Daily Stock Market Report (Wed 21st Jan 2026) -VLX, JNEO, PFD, CURY, GFRD, BRBY, EXPN, JDW

Good morning! Hoping for another batch of "ahead" updates, but yesterday will be hard to beat...
Today's Agenda is complete.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Rio Tinto (LON:RIO) (£103bn | SR77) | Copper production +11% in 2025, ahead of guidance. Pilbara iron ore flat. Aluminium production +3% (upper end of guidance). 2026 production guidance unchanged. | ||
Experian (LON:EXPN) (£29.6bn | SR62) | Q3 revenue +12% (+8% organic), in line with expectations. FY26 expectations unchanged. | AMBER/GREEN (Roland) [no section below] This credit data company is the top faller in the FTSE 100 today. It’s also down by 25% over the last six months. It’s a business I’ve always admired, but not been willing to pay the price for. So I’m interested to see if a buying opportunity could be opening up. At first glance, today’s reaction seems harsh in response to Q3 organic revenue growth of 8%. From what I can see, the market’s disappointment today appears to reflect the in-line guidance and potential external pressures on the business, in the US in particular. Newswire commentary suggests falling interest rates could support a recovery in lending (positive), while possible negatives include a new US programme allowing mortgage lenders to access credit scores directly without using companies such as Experian. I don’t have a strong view on the near-term outlook but remain convinced this is a high-quality business that’s likely to perform well over longer periods. The valuation is starting to look potentially interesting to me, too. The StockReport suggests a trailing free cash flow yield of 3.6% and FY26E P/E of 24. I’m not quite there yet on price, but if Experian shares continue to fall with no downgrade to forecasts, I think the stock could come onto my radar as a possible long-term buy. | |
Pearson (LON:PSON) (£6.0bn | SR73) | £350m share buyback programme. First tranche of £175m to complete by 21 May 26. | ||
ICG (LON:ICG) (£5.9bn | SR82) | Fee-earning AUM of $85bn, +1% QoQ, +11% YoY. $36bn of dry powder, completed $4.4bn fundraising. | ||
Burberry (LON:BRBY) (£4.4bn | SR57) | Q3 revenue +1% to £665m. Comparable store sales +3%. Expected FY26 adj operating profit to be in line with consensus of £149m. | AMBER = (Graham holds) Forecasts in the market suggest that profitability is about to bounce back next year, with earnings per share of nearly 40p pencilled in for FY March 2027 (the financial year starting in less than two months). From that perspective, the P/E multiple is 32x. | |
British Land (LON:BLND) (£4.1bn | SR66) | Strong leasing momentum, with 151 deals averaging 8.5% ahead of ERV. FY26 expectations unchanged for adj EPS of at least 28.5p. | ||
Aberdeen (LON:ABDN) (£4.0bn | SR90) | AUMA +9% to £556bn, with positive market movements offsetting net outflows of £3.9bn. FY25 adj operating profit to be in line with expectations. FY26 adj op profit to be at least £300m. | ||
JD Sports Fashion (LON:JD.) (£3.9bn | SR78) | Q4 revenue +1.4% (-1.8% LFL). YTD revenue +2.2% (-2.1% LFL). Improved sales in NAm, weaker in Europe and UK. FY26 adj PBT to be in line with market exps, expect free cash flow of c.£400m. | ||
Hochschild Mining (LON:HOC) (£3.1bn | SR74) | FY production in line with revised guidance. Gold equiv. -10.5% to 311.5koz. AISC “marginally above” guidance of $1,980-$2,080/GE oz. 2026 guidance 300-328k GE oz with AISC of $2,157-$2,320/GE oz. | ||
Drax (LON:DRX) (£3.0bn | SR99) | Acquired Flexitricity Limited from Quinbrook for £36m. Provides optimisation and route-to-market for flexible energy assets (e.g. battery storage). | ||
Quilter (LON:QLT) (£2.6bn | SR85) | Q4 AUMA of £141.2bn, +5% vs Q3. Q4 core net inflows of £2.4bn, FY25 core net inflows of £9.1bn. | ||
Premier Foods (LON:PFD) (£1.47bn | SR79) | Strong Christmas, Q3 Branded revenue +5.2%, total revenue +4.1%. Expect FY trading profit at upper end of expectations (£193.0 to 198.2m). | AMBER/GREEN = (Roland) Today’s update suggests continued good progress across the group’s core UK brands and its newer growth initiatives. My overall impression is positive, with the caveat that this isn’t a business I’d want to pay a very high multiple for. It’s also worth noting that the company’s house broker – presumably well-informed – does not see the need to change its forecasts today, as they were already close to updated guidance. On balance, I don’t see any reason to alter our broadly positive view today. | |
Currys (LON:CURY) (£1.39bn | SR96) | Peak LFL revenue +6%, H1 revenue +4% LFL. Gross margin improvements. Adj pre-tax profit to be £180 to 190m, ahead of consensus exps of £180m. | GREEN = (Graham) No reason to change my stance after an "ahead" update. The shares continue to trade on a PER of 10x and I don't object to the company buying back its own shares at this level. While they might not be buying back at a very steep discount to fair value, I still view this as a reasonable use of surplus cash and something that can help contribute to EPS growth over the medium-term. Also, I think this strong update says a lot about robustness of the UK consumer, with modest like-for-like growth from Currys UK&I division. | |
Elementis (LON:ELM) (£940m | SR68) | 2025 revenue to be in line, adj operating profit “marginally ahead” of consensus. | ||
J D Wetherspoon (LON:JDW) (£824m | SR49) | LFL sales +4.7% in 25 weeks to 18 Jan, total sales +5.3% YTD. Costs higher than expected, H1 profit likely to be lower than last year, currently anticipates FY profit “slightly below” FY25. | AMBER/RED ↓ (Graham) Downgrading our stance on this by one notch after a mild profit warning that comes on the back of another cautious trading announcement in November. With operating expenses increasing all the time and margins naturally very low, this continues to look vulnerable to more bad news. | |
Workspace (LON:WKP) (£793m | SR49) | Enquiries lower in Q3, but letting conversion improved. LFL occupancy +0.9% to 81.2%, with LFL rent/sq ft -1.4%. £106m of disposals secured. Trading in line with expectations. | ||
Serica Energy (LON:SQZ) (£774m | SR91) | 2025 production -20% to 34,600 boepd, in line with guidance. Revenue -17.3% to $601m. Net debt $200m at 31 Dec 25. 2026: expect production “over 40,000 boepd”, with the potential to reach 65kboped following completion of recently announced acquisitions. | ||
Volex (LON:VLX) (£756m | SR90) | 9M revenue +14.8% to $902.7m, benefiting from Data Centre demand. FY26 revenue and adj operating profit now expected to be ahead of consensus ($1,152.3m & $112.7m, respectively). | AMBER/GREEN = (Roland) Volex appears to be executing well and profiting from the AI Data Centre boom. While performance in other parts of the business appears to have been flatter in Q3, I continue to think that the outlook and valuation are broadly positive, so my view remains unchanged today. | |
Galliford Try Holdings (LON:GFRD) (£528m | SR95) | Trading ahead of the prior year, and the Board's expectations. Now expects full-year revenue to be towards the upper end of expectations and for adjusted profit before tax to be slightly above the top end of expectations (current range: £46.8m to £47.7m). Average month-end cash for 2025 was £189.9m. Strong pipeline of medium and long-term opportunities. Panmure Liberum FY26E EPS +4.3% to 36.8p Cavendish FY26E EPS +9.1% to 40.2p | AMBER/GREEN = (Roland) [no section below] In October, I suggested that “the shares could still be reasonably valued”. One area where I may have underestimated growth potential is the “significantly enlarged AMP8 water framework programmes”. The company’s focus on infrastructure is said to be aligned with Government spending plans and should provide decent long-term visibility. Today’s upgrade is relatively mild, but has pushed FY26E EPS forecasts up by between 4% and 9%, depending on which broker estimate you use (see left). Changes to revenue forecasts are much smaller, suggesting to me that the bulk of today’s upgrade is driven by the business achieving stronger margins than expected so far this year. I remain positive but somewhat cautious, given the low-margin nature of this business – hence my view is unchanged today. | |
Everplay (LON:EVPL) (£486m | SR57) | Adjusted EBITDA for FY 2025 in line with current market expectations (£48.5m). Exited a low-margin distribution business, which is a headwind to revenues. Revenues therefore broadly flat and below expectations. “New release line up for 2026 is set to be one of everplay's most exciting and extensive to date.” | BLACK (revenue warning only, adjusted EBITDA in line. £173.6m revenuew was expected, actual revenue will be broadly flat on last year’s £167m). | |
Avacta (LON:AVCT) (£231m | SR24) | FDA clearance of the Investigational New Drug (IND) application for the Company's second program FAP-Exd (AVA6103), the first pre|CISION® peptide drug conjugate based on the highly potent topoisomerase I inhibitor, exatecan. | ||
Kenmare Resources (LON:KMR) (£227m | SR47) | Achieved production guidance. Capital expenditure will be significantly reduced in the year ahead. Primary operating focus for 2026 will be on value over volume. Annual production guidance for 2026 is therefore lower than in recent years. Further reduction in pricing assumptions to cause an impairment charge that is not anticipated to exceed $300 million for the year. | ||
City of London Investment (LON:CLIG) (£197m | SR97) | Cooper Abbott was President and Chairman at Carillon Tower Advisors which he founded and built into a $70+ billion global asset management company. | ||
Avingtrans (LON:AVG) (£179m | SR79) | H1 trading to 30 November 2025 was in line with management expectations. “We remain confident in our ability to meet market expectations for FY26…” | ||
Foxtons (LON:FOXT) (£155m | SR54) | Acquisition builds on the Group's strategy to grow non‑cyclical, recurring Lettings earnings whilst also expanding the Group's footprint into Birmingham. Initial consideration of £3.2m, with a further £0.8m deferred. FleetMilne’s recent revenue and PBT were £1.5m and £0.2m. | ||
KEFI Gold and Copper (LON:KEFI) (£148m | SR35) | Final documentation with respect to the US$240M Loan Facility is fully signed. $100m of equity-risk capital is undergoing final documentation. Additional offerings which are “not dilutive at the plc or asset level” for $36m are being considered. Following the December placing, a number of works related to the Tulu Kapi Gold Project have commenced or advanced this month. | ||
AFC Energy (LON:AFC) (£137m | SR13) | Completion of the first build of new generation LC30 30kW liquid-cooled fuel cell generator. Now undergoing operational testing and producing power in accordance with its design specification. | ||
Shield Therapeutics (LON:STX) (£119m | SR36) | In line with guidance, achieved positive operating cash flow in Q4 2025 (“a significant milestone”). FY25 total revenues c. $50m ($32m in FY24). ACCRUFeR® contributed $46m of this and saw 21% growth in average net selling price to $223 and 33% growth in total prescriptions to c.199,000. | ||
Journeo (LON:JNEO) (£84m | SR87) | Revenues for FY25 of £55m (2024: £50m), with adjusted PBT slightly ahead of market expectations at £5.7m (2024: £5.0m). “We enter 2026 with confidence in delivering on another year of significant growth.” Cavendish updated forecasts: | GREEN ↑ (Roland) [no section below] Today’s ahead update is Journeo’s third broker upgrade in four months. The company is effectively telling us that Journeo’s adjusted pre-tax margin for the year is now expected to be 10.4%, versus 10.0% previously. This improvement in profitability outweighs the slight downgrade to revenue guidance, which is cut from £56m to £55m. My reading of this is that costs have come in slightly lower than expected for some reason. This is obviously good news, although I’d be more excited if revenue was also being upgraded as that would indicate a potential increase in sales growth. Stripping out the year-end net cash balance of £12m gives me a cash-adjusted FY25E P/E of 15, falling to a P/E of 12 in FY26. I don’t think this looks too expensive for a business that’s generating high-teens returns on capital and is expected to report 25% earnings growth in 2026. I’m going to take a chance today and upgrade our view to be fully positive. | |
Andrada Mining (LON:ATM) (£79m | SR26) | Conditional, staged earn-in agreement. ACAM could provide up to $51 million in staged funding to accelerate the exploration and development of the Brandberg West polymetallic prospecting licence. | ||
1Spatial (LON:SPA) (£76m | SR26) | 73p per share in cash. 57% premium. Follows on from the announcement of an agreement in principle in December. Irrevocable undertakings and non-binding letters of intent to vote in favour for 52.45% of shares. | PINK | |
Ilika (LON:IKA) (£66m | SR19) | First revenue-generating purchase order from Cirtec Medical (Cirtec) for the supply of Stereax electrodes, marking the commercial transition of this strategic partnership. | ||
Getbusy (LON:GETB) (£42m | SR38) | Group ARR +8% (cc) to £22.6m. Revenue at least £22m (+ 5% cc) and adjusted EBITDA £0.3m, in line. Net cash £0.9m. Company “well positioned to deliver material cash returns to shareholders in the medium term”. | ||
Headlam (LON:HEAD) (£37m | SR32) | Full year results in line with expectations, with trading in the final months of 2025 having been as expected. | ||
Tan Delta Systems (LON:TAND) (£24m | SR25) | 2025 revenue is expected to be c. £1.2m, 20% ahead of management expectations as of Sep 2025. Cash c. £1.5m with no debt. 2026 pipeline of interest remains strong. |
Graham's Section
Currys (LON:CURY)
Up 5% to 132p (£1.47bn) - Profit guidance above market expectations - Graham - GREEN =
It’s an excellent trading update from this retailer that has impressed us so much over the past year or so, covering the 10-week period to 10th January 2026 (referred to as “Peak”).
Key points:
Like-for-like revenue growth accelerated to 6%
UK +3% with progress across the board in recurring service revenue (+7%) credit adoption up to 25%, B2B sales +21% and new categories +42%.
Nordics +12%, “a standout performance” (important because Nordics are 40% of the total group).
Market share gains in both the UK and Nordics.
Outlook (bearing in mind that year-end is in April):
Group adjusted profit before tax is expected to be £180-190m, +11-17% YoY and ahead of consensus expectations
£50m share buyback programme underway, bringing total cash returned to shareholders to c.£75m for the year.
Expect year end net cash to finish above £100m target
The £50m buyback is not news - it has been going on for a while.
The big news is of course the “ahead of consensus” PBT. The company helpfully points out that the consensus forecast is £180m, and that is now the lower bound of official guidance.
Clear and detailed guidance is provided on a range of important inputs such as interest and capex, but these are largely unchanged.
CEO comment snippets:
"Our Omnichannel model is winning. We gained market share in both UK&I and Nordics, in both stores and online, and our fastest growth was where customers use both channels together. This is a competitive advantage we'll keep building....
In the UK&I, we grew sales in our core business and the growth areas we've targeted. Our sales to small and medium-sized businesses grew by +21%, iD mobile reached 2.5 million customers, and credit adoption of 25% was double that of five years ago. These are all sources of higher-margin and recurring revenue. We maintained healthy underlying gross margins which, alongside cost savings, are offsetting unhelpful cost headwinds."
Longer-term guidance: there is an unchanged target EBIT margin (3%), capex is to remain below £100m annually, and exceptional cash costs should be kept below £10m for the upcoming financial year FY April 2027. All of this sounds fine.
Pension contributions will be £13m per annum for five years, starting next year.
Balance sheet net cash is to remain over £100m: this is excellent. I wish more retailers were as careful as this!
Grahams’ view
Over the years, we’ve seen so many mishaps in the retailing sector, that I am sometimes tempted to avoid it completely. But there are exceptions.
Over the last year, we’ve been very positive on Currys (LON:CURY). Originally, around the time that higher NICs were announced, I was impressed by management’s transparency.
Since then, they’ve continued to report with what I perceive to be a very high degree of clarity and transparency, which definitely helps to inspire confidence in their strategy.
Additionally, they’ve run a cash-rich balance sheet, which I see as a form of insurance policy against macro conditions (and well worth it).
My positivity is aligned with what the StockRanks are saying:
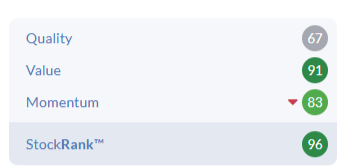
The shares continue to trade on a PER of around 10x and I don’t have any major objection to the company buying back its own shares at this level - perhaps they aren’t buying at an enormous discount to fair value, but I’d still argue that it’s a reasonable use of surplus cash.
Overall, then, no reason to change my positive stance after an “ahead” update. And we have yet another good reason to think that the UK consumer is not so weak after all!
Burberry (LON:BRBY)
Up 5% to £12.84 (£4.6 billion) - Third Quarter Trading Update - Graham - AMBER =
At the time of publication, Graham has a long position in Burberry.
I’ve been holding this through thick and thin, and it hasn’t been pleasant:
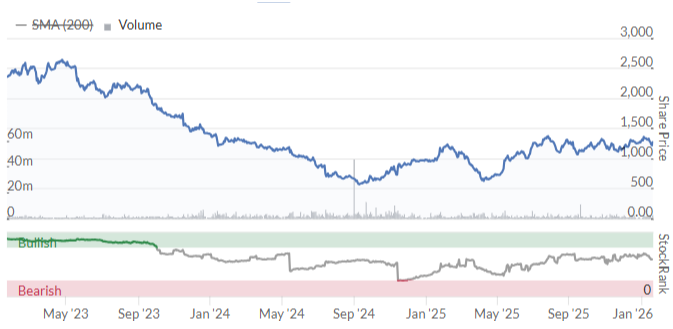
Fortunately there are some green shoots of recovery with this trading update. Importantly, the operating profit outlook is in line with consensus expectations.
Key points:
Retail revenue +3% at constant exchange rates, +1% at actual exchange rates.
Comparable stores sales +3% (compared to -4% last year)
Best performance in Greater China (6%) and Asia Pacific (+5%)
EMEIA region flat (Europe, Middle East, India and Africa!)
Americas +2%
For a company that has been on the back foot for some time, this is not a bad showing during the important Q3 period.
Also, the “quality of revenue” is said to have improved, with a “shorter, shallower and more discreet markdown period”.
The CEO comment strikes a triumphant tone:
During the festive quarter, we continued to build momentum with our Burberry Forward strategy, delivering sequential improvement in comparable sales growth and an improved quality of revenue across channels and geographies. Our customers responded to our immersive Timeless British Luxury campaigns and experiences while the continued strength in our core outerwear category is now extending into accessories and ready-to-wear. As we move into 170 years of Burberry, these results reaffirm the enduring strength of our iconic brand and give us confidence in the path ahead.
FY26 outlook:
As we move into the final quarter of the year, the impact of our initiatives continues to build, giving us increased confidence in the direction of the business. We expect adjusted operating profit to be in line with consensus for FY26*. We are confident that we can build on the progress we’ve made in quality of earnings, continuing to improve performance and driving sustainable long-term value.
Estimates: for a stock in the FTSE-100 (although it was temporarily dumped from this index last year), you expect decent information from the company itself re: estimates. Burberry provides:
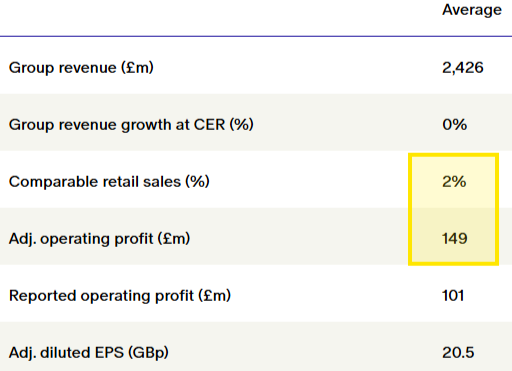
Graham’s view
Unfortunately, the adjusted EPS figure for FY March 2026 doesn’t give rise to a sensible P/E ratio (the latest stock price is £12.84, vs. adjusted earnings per share of only 20p!).
As I noted in November, the stock is already pricing in a recovery of profits to more than double the current level. As I said then, we would realistically need clean after-tax profits over £200m+ to justify the current market.
Forecasts in the market do suggest that profitability is about to bounce back next year, with earnings per share of nearly 40p pencilled in for FY March 2027 (the financial year starting in less than two months).
From that perspective, the P/E multiple is a much more sensible 32x.
Even though I’m a holder of this stock, I’m inclined to leave our neutral stance unchanged here. Today's update is merely "in line", after all. And we will still need further progress in FY28 to justify the current market cap. There is plenty that could go wrong between now and then (if I’m not careful, I’m going to talk myself into selling out!).
So while I still count myself as an admirer of this business, I think caution remains justified.
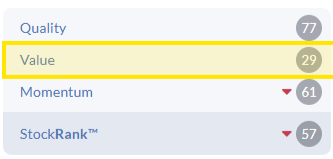
The StockRanks agree, seeing little value to back it up at this level:
J D Wetherspoon (LON:JDW)
Down 6% to 691.2p (£763m) - Trading Update Announcement - Graham - AMBER/RED ↓
This one is always a bit of a guessing game, as we decipher the words of Sir Tim Martin. He tends to speak very plainly when it comes to his view of the government, but his company outlook statements can be rather cloudy.
Here are the key points from today’s update, for the 25 weeks to 18th January (roughly speaking, H1):
LfL sales +4.7%, which is better than we saw in Q1 (3.7%), as Q2 saw LfL sales up 6.1%.
Bar sales +6.9%, food +1.3%, slot/fruit machines +9.1%.
Total sales are only a little higher than LfL sales at 5.3%, as the estate is barely growing.
All of this is fine, but the big issue is costs, not sales.
Let’s hand it over to the Chairman:
"We are pleased with the sales growth in the financial year, and with the increased momentum in the second quarter.
"Costs have been higher than anticipated, with energy, wages, repairs and business rates, for example, increasing by £45 million in the first 25 weeks.
"Profits in the first half are likely to be lower than the comparable period in the previous financial year.
"If the current sales momentum continues, the company currently anticipates a full year trading outcome slightly below that achieved in FY25.
"We will provide updates as we progress through the financial year."
Graham’s view
Funnily enough, I don’t think the profit outlook published today is all that bad, compared to current estimates.
Last year, adjusted PBT was £81.4m, and adjusted operating profit was £146.4m.
I think that current forecasts already suggest that FY26 results will be similar to, or slightly below, these numbers.
But perhaps what has really spooked the market is the disclosure of £45m of additional costs across the four categories mentioned (energy, wages, repairs and rates).
It’s a reminder of just how operationally leveraged this business is. On sales of £2.2 billion+, earning a net profit margin of about 3%, these hikes in expenses could have a disproportionate impact on profits at some point.
That’s what I’ve been worried about, although I don’t see today’s update as a vindication of my stance.
But I am going to reduce us down to AMBER/RED, seeing as it comes on the back of another cautious trading update in November (which we categorised as “BLACK” that day). It appears that this stock remains vulnerable to more bad news.
Roland's Section
Volex (LON:VLX)
Up 6.5% at 435p (£822m) - Trading Update - Roland - AMBER/GREEN
Booming demand for AI Data Centres has allowed cabling manufacturer Volex to upgrade its full-year guidance today.
The company says that revenue and underlying operating profit for the full year are now expected to exceed previous consensus forecasts of $1,152.3m and $112.7m respectively.
By the numbers:
Strong trading reported in H1 continued into the company’s third quarter, which saw revenue rise by 14.8% on a constant currency basis. CEO Nat Rothschild says the company’s Data Centre business saw “elevated demand”, reflecting global investment in AI and digital infrastructure.
Growth from other industrial customers was said to be robust, with flatter performances in other markets such as Electric Vehicles, Medical and Consumer Electricals.
Operating margins are said to have remained strong, “around the upper end of the group’s 9-10% target range”. This result has been supported by price rises, cost control and efficiency gains.
Net debt is also said to have fallen, with covenant leverage now around 1.0x. This appears to address a concern I flagged in November.
Improved Outlook for FY26
With the year end approaching in March, Volex now has sufficient visibility to upgrade guidance:
With good momentum into the final quarter, we now expect to exceed current market expectations, thereby giving increased confidence in achieving our five-year plan targets.
Volex helpfully provides details of FY26 consensus forecasts in today’s update:
Revenue: $1,145.1m to $1,167.4m (average: $1,152.3m);
Underlying operating profit: $111.7m to $114.9m (average: $112.7m).
We already know that brokers upgraded forecasts following November’s half-year results:
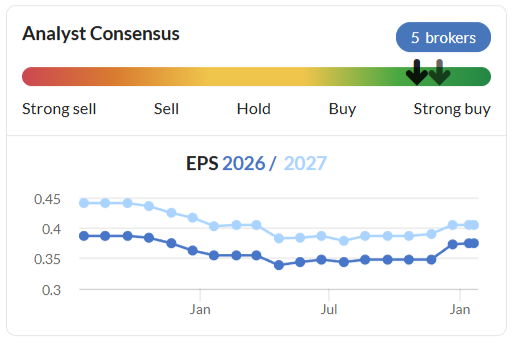
Today’s upgrade should extend this positive trend. While I don’t have access to any updated broker forecasts this morning, the c.7% share price rise this morning suggests to me that we could see full-year results perhaps 5% above previous estimates.
Based on Stockopedia’s FY26 consensus earnings of 37.5 cents per share, I’d estimate updated forecasts could be 39-40 cents per share, equivalent to a FY26E P/E of 15.
Roland’s view
I highlighted Volex as a UK-listed beneficiary of the AI data centre boom in our Stockopedia Panel discussion at November’s Mello. The company reported an 80% rise in Data Centre-related sales during H1, driving 48% revenue growth in its Complex Industrial Technology division.
Q3 sales growth appears to be a little more measured than this, but was still strong. My impression from today’s update is that Data Centres were the only substantial area of growth during the quarter.
I continue to see both risk and opportunity here. While demand for Data Centre products remains strong, Volex seems well positioned to benefit.
However, weaker sales performances elsewhere highlight the risk of a slowdown at some point.
In November, I concluded that the valuation and outlook were both broadly positive. That view is unchanged today, so I’m going to remain at AMBER/GREEN.
Premier Foods (LON:PFD)
Up 6% at 179p (£1.57bn) - Q3 Trading Update - Roland - AMBER/GREEN =
The maker of brands such as Mr Kipling and Bisto is the top riser on the Main Market this morning after a strong Christmas trading update. Full year trading profit is now expected to be at the upper end of expectations.
By the numbers:
Q3 branded revenue up 5.2%, total revenue up 4.1%
Grocery Branded revenue up 5.8%, Sweet Treats Branded revenue up 3.1%
Market share gains in Grocery and Sweet Treats
Revenue from new categories up by 29%
International revenue up 10%
Recent acquisitions delivered double-digit sales growth
Why it matters:
As we’ve discussed recently, Tesco reported sales growth of 3.8% over the comparable period, while Sainsbury’s managed 4.9%.
This means that Premier Foods’ performance appears to have broadly matched that of its supermarket customers.
In the Grocery category, which includes Christmas staples such as Paxo, Bisto and Ambrosia, it looks like Premier Foods’ sales may have been ahead of the biggest supermarkets.
Double-digit sales growth from recent acquisitions such as FUEL10K and Merchant Gourmet is also encouraging. In addition to providing evidence of the company’s successful approach to buy-and-build, these brands (which sell various high protein/fibre products) are also seen as having good potential in the weight-loss drug era, as consumers seek out healthier products.
While International revenue remains below 10% of the group total (as of H1 26), my feeling is that this could be a promising route for growth beyond the natural limit the company’s UK-centric brands are likely to face in their home market.
Outlook & Broker Estimates
Outlook guidance for the year to March 2026 is upbeat:
Trading profit for the FY25/26 financial year is now expected to be at the upper end of market expectations.
Premier Foods helpfully cites previous market expectations for trading profit (adjusted operating profit) as being £193.0m to £198.2m, with an average of £195.3m.
This is already a fairly narrow range. This suggests to me that any upgrade to broker estimates will be fairly modest.
Indeed, house broker Shore Capital has left its FY26 forecasts unchanged today, commenting that its estimate for a trading profit of c.£197m is already “broadly within that guided zone”.
On this basis (and given its status as the house broker), it seems logical for me to use Shore’s earnings forecasts as a guide to updated expectations:
FY26E adj EPS: 15.0p
FY27E adj EPS: 15.5p
These numbers are already similar to the consensus numbers on the StockReport and leave Premier Foods trading on a FY26E P/E of 12 after this morning’s gains.
Roland’s view
After a strong four-year run, Premier stock has cooled recently:
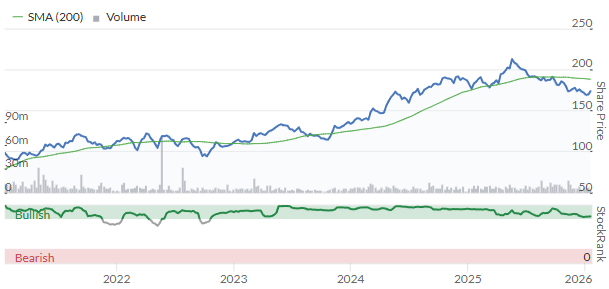
Despite this, earnings estimates were already moving higher before today’s update:
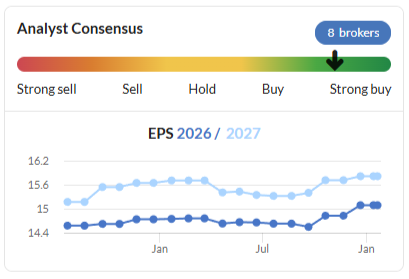
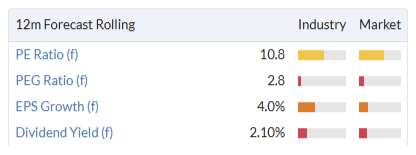
Assuming limited increase to EPS estimates, today’s share price gain means investors have re-rated the stock modestly higher. The P/E of 12 implied by Shore Capital’s latest forecasts compares to a P/E of 11 prior to today:
A QualityRank of 87 is encouraging, supported by mid-teens operating margins. But Premier Foods’ return on capital employed of <10% is a reminder that this is a relatively capital-intensive manufacturing business:
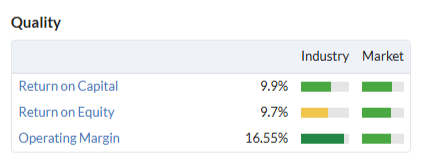
I would imagine that pricing will always be under pressure from the group’s much larger supermarket customers, too.
For these reasons, I wouldn’t want to pay a high multiple of earnings for this business. Looked at differently, the stock’s price/book ratio of 1.05 looks about right to me for a business generating a sub-10% return on equity.
This caveat aside, I am encouraged by progress and have a positive view of management. On balance, I’m going to leave our AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Trading 212 update
130+ new AIM stocks are now available to buy
https://community.trading212.c...
Roland - thanks for what you have written in a busy period for end-Dec. trading statements and for covering all 3 of my holdings reporting today:-
Volex (LON:VLX) - a good 'ahead' statement (and with SP rise>10% and SR 90 would have qualified for Ed's screen but for MCap) has resulted in a new high post the Sept. 21 small cap bubble. I think that to really appreciate the way this company is put together you need to listen to Nat Rothschild, CEO and 25.6% shareholder, on the IMC presentations to realise how carefully the company has been constructed so that it has dealt with needs for 'nearshoring' and that those have been invaluable in the age of Trump tariffs. He has drawn a number of very useful people in on this, for example Sir Peter Westmacott whose knowledge of Turkey has, I suspect, enabled VLX to operate so well there.
Journeo (LON:JNEO) was my 4th largest holding until VLX jumped over it today! I find the market reaction to 'slightly ahead' rather odd but given that the SP broke up through the 300p mark at the end of last May it may have been that the market was expecting a 'strongly ahead'. There is always going to be some lumpiness regarding contracts here but as time has gone by I have been very impressed by the way management has integrated acquisitions (in complete contrast to Tracsis (LON:TRCS) which was badly managed. I got out at a loss at 790p - today it is at 285p).
Experian (LON:EXPN) - my holding here is fairly small but at least still in profit despite the fall from 4000p in the last 6 months. I cannot understand today's fall on an 'in line' statement when the recent SP slide suggested the market expected a 'below'.
I noted that today's RNS gave 68% of revenue coming from N. America and as you say there has been a change regarding credit scores for mortgages - see https://www.realtor.com/advice... . Now I read that Trump wants interest rates on credit cards capped at 10% - see https://eu.usatoday.com/story/... So, with their largest market being so volatile I may be making an exit.
Now I read that Trump wants interest rates on credit cards capped at 10%
Never a dull day with trump in office
As an aside does anyone know how you can sign up for the free daily John Arthurs email the only one I can find online now seems paid subscription.
His newsletter is called 'Points of Return' if you google John Authers Points of return it will take you to a page where you can sign up to the free email. It is daily Mon-Thurs but not on US market holidays.
Thanks Jim
Thanks Helvellyn
Phoenix - John Authers
https://www.bloomberg.com/acco...
Works co uk (LON:WRKS) people buying in today in anticipation of good results tomorrow....
Works co uk (LON:WRKS) goodness, up 17% awaiting tomorrow.
That's a lot of anticipation.....or a little inside knowledge?
Serica Energy (LON:SQZ) is my largest holding being 9% of my portfolio.
I have not yet listened to the Investor Meet recording but the future looks promising or am I deluding myself?
Fingers crossed at Triton, but I saw today's ImC presentation as positive. I hold....with crossed fingers.
The numbers look promising and the trend is upwards. I have bought some this morning!
The future is positive, the main market move alone provides a catalyst for share price growth
Looking at current Market roughly £800m today should see it included in the FTSE250.
For disclosure I do hold Serica with them being my 4th largest at 12%
Great to see Next (LON:NXT) buy up Russel & Bromley in a very well crafted deal
https://www.stockopedia.com/sh...
Volex (LON:VLX) 'AHEAD' breeds 'AHEAD' thanks Ed https://tinyurl.com/43uaavrv
B.P. Marsh & Partners (LON:BPM) Interim Dividend Declaration
Is this date in todays RNS a mistake?
It remains the Company's intention to pay a dividend of at least £5.0m in the financial year ending 31 January 2028, subject always to the Board's right to recommend an increased or decreased Final Dividend, for example in the event of significant realisations or capital commitments.
B.P. Marsh & Partners (LON:BPM)
No - the first part of the announcement is dealing with dividends for FYE 31 Jan 2027. The sentence you have quoted is dealing with (previously announced) intentions the year after that.
Thank you ricardow
Ricardow is correct. In the 15/12/26 RNS it states: "the Company's intention is to pay a dividend of at least £5.0m per annum in each of the financial years ending 31st January 2027 and 31st January 2028"
Journeo (LON:JNEO)
There is a note out from Cavendish. They tweak adj. eps following the company's "slightly ahead" from 26.5p to 26.9p. What is more interesting is that they have reviewed their price target. Based on the next year p/e of a peer group this rises from 602p to 740p.
Edit - charlie51 posted while I was composing this so sorry for the duplication.
J D Wetherspoon (LON:JDW)
Graham was spot on here with his prior worries that spoons may deliver a profit warning - here it is. I was slightly more confident that as they didnt specifically downgrade that they might be ok. To be fair to spoons and me i think the last update was pre budget and i think rates in particular may have been materially upped in budget post that prior update - so if thats the case not sure that could have been anticipated.
Todays update is kinda odd - its lacking any of the normal added value comments what we can come to expect from Sir Tim. Its almost as if he is beaten into submission with regard to "moaning" about cost increases.
Not sure how material rates increases are - lack of speciofic commentary here is unhelpful bearing in mind some companies have reported huge hikes. Are they not too badly hit so are cleverly keeping quiet ? personally i would have wanted to know unless they have good reasons for keeping quiet. It looks like some of the worst changes to rates increases may be rolled back - so could they be holding something back for formal u turn later - that begs the question where they are today ref forecasts - are they ignoring the possible part reversal of rates increases and have they turned over gloomy ref outlook - if thgey may have good news coming in that regard.
None if really matters to me they will have times when they do well and times when they do bad they are still making solid real profits - if high street footfall has been quiet - its natural that they would have have struggled a tad - food and hotel lfl's are poor.
Nothing has changed ref the bigger picture to me - i could perhaps be happy to buy some more if it gets closer to 600p. I would have hoped that debt might start coming down soon - thats not happening but i am comfortable that they know what they are doing in that regard - buying freeholds and share buyback is perfectly good use of cashflow from my point of view.
In the latest Spoon newsletter Tim outlines a lot of concerns. The key standout for me was the fact that their energy costs have risen and and that 62% of the cost was related to "green" taxes which are then re allocated to fund other organisations, which he lists! Minimum wages; business rates; alcohol taxes all add to their costs.
Some of the additional costs are simply going back to pre covid. ie end of subsidy. The extensive use of non NICS part timers by the hospitality sector was discussed at the time on Stocko (350,000 to 500,000 people?). I enjoy spoons as a customer, it's superior management shines at all times of the day.
i have to say i'm very disappointed with Stockopedia.
The information displayed is FALSE and MISLEADING.
Look at
GAL – Galantas Gold the market cap is still showing as £16.38m!
We are paying for this information and some investors could be misled into thinking the company is a 'steal'. Some would even think that Stockopedia is responsible for misleading them and I wouldn't blame them.
We are paying for this data and we expect updated stats!!
Not sure this is the right forum for this.
Not sure - ben has a fair point. Look at the detail on Rosebank for example - appallingly misleading. Many use the Stocko material as the basis for further research. No matter the forum the point he makes is valid and Stocko need to act.
I think a little perspective is only fair here. Both Galantas Gold (LON:GAL) and ROSEBANK INDUSTRIES (LON:ROSE) are pre-revenue stocks that don't have any sensible figures yet. Any investors in these special situations will surely do their own homework before investing. I would be more concerned if a longstanding established company had incorrect data.
Entirely the right forum ... Stocko is a data-base service and if the data is wrong, what exactly are we paying for apart from the pleasure of each others company on this forum?
Other data is also wrong on Stockopedia as outlined by another person last week. If you have bought and sold a share it is likely that your personal stats are wrong. For example the cost figure will be likely wrong and also the % gain and the sterling figure gain. For example I have top sliced and then rebought (a different amount) of Sylvania Platinum on one occasion. My cost figure is wrong. It should be £21,000 but is listed as £28,343. Therefore all the following figures are wrong as well: gain and percentage gain. Therefore all the other overall stats for my portfolio are also wrong. Im sure many people dont realise this.
Hi James - Be interested to hear your take on Volex (LON:VLX) following your critique earlier this week - and todays TU
It's obviously not a good thing is data shown on Stockopedia is incorrect. But surely you realise that the staff of Stockopedia are not themselves extracting the numbers out of co announcements and accounts and typing them into the Stocko database. They will be subscribing to commercial providers of such data. And they can't be expected to check the accuracy of every detail.
If you find errors the thing to do is to inform Stocko and they can then take it up with their data provider. Being human, they'll probably be more motivated to do that if you stay polite and friendly.
As for the comment - "We are paying for this data and we expect updated stats!!" I think that's wrong headed.
Stocko's USP is not a database of co financials. You can get those from any number of sources, including your brokers and any of the web based data providers.
What makes Stocko unique is the analysis - the powerful algorithmic system they have built, the human assets they deploy and the insights they provide.
I am amazed that anyone would make significant investment decisions which rely on the accuracy of any one set of numbers. I don't place reliance on Stockopedia or anything else and certainly don't expect them to be infallible. For me Stockopedia is only ever a provider of interesting ideas which I investigate/research/analyse further. But it does that brilliantly and enables me to achieve much better outcomes than I used to before I subscribed.
I agree with Sam Aritan.
Having used Thompson Reuters databases in the past i have been shocked at the number of errors. The data is obviously typed in by poorly paid people in India, so errors are expected. But it seems there is very little review, numbers in pounds and not pence for example, so they are out by a factor of 100. A simple sense check would correct most of these problems.
This is not Stockos fault but they should complain to their data provider.
I do agree with your general points. But when I started noticing obvious errors on data e.g. p/e ratio's being completely wrong based on the other numbers in the table. I messaged Stocko with one of them through the green button explaining that it doesn't make sense - the basic maths is wrong.
I expected them to say they will speak to the data provider and have it updated. Instead they asked me what the right numbers were and to provide my calculations. I felt this was a bit of a joke to be honest. It was clear to me there was an error. Instead of either explaining why the error is there (perhaps its my mistake and I am not understanding something) - or telling me they would raise it with the data provider. Instead there response was - for me to submit my own data to provide the accurate numbers - obviously I did not respond and have never bothered raising another case (I see data errors all the time).
I found this response totally unacceptable. To put the responsibility on me when I am paying for the data left a bad taste. Also it was obvious that the numbers didn't add up - they did not even acknowledge this at all. So while I do agree generally with what your are saying - I have found the Stock support in this aspect to be close to useless and the main concern for me was they actually just didn't care. I never responded to there request, I never heard back from them, and I assume the data was never updated and no data provider alerted of the error - this isn't acceptable in my opinion.
To me this sounds like they might be wanting to find out themselves - for example if they dont know whether error is withn source data or internally - to most easily work out the score - fact checking to your calcs would most quickly show where the issue is. Without your fact checked calcs - its much harder for them to fact check whether your query is wrong.
You say its basic maths but its to much hassle to provide that basic maths to them.
sometimes in life its a two way process to find out why data is different - if you are asking the questions and cant be bothered to supply the info to solve the question i would put that right back on you.
Yes they could perhaps check without your data . but it sounds like you havent even checked whether they might have acted on that initial request either and updated data anyway ? - if you are going to moan is it too much to double check that they havent updated it still ?
I mean no offence by my comments - you may expect top banana accurate data with them running around to correct any of the "thousands" or probably tens of thousands" of data points - soem of which may be wrong - i simply accept there is tens of thousands of data points and its not possible for them to all be right.
This is not quite what happened. I did supply the numbers to them in my initial enquiry. I can't remember specifically, I think it was a p/e ratio error where it was showing a growth in net profit and eps but the p/e ratio had risen and didn't make sense based on the numbers in the column (wasn't due to share price movement or dilution). I was then asked to provide the correct numbers. But the point was that the numbers didn't add up, so surely there is an error!
Now obviously you expect me to provide this information (hence why you claim I am lazy). But this was me pointing out an obvious error on a random stock report. This was not a stock I owned or was considering purchasing. But I thought if you notice an obvious error it should be reported and dealt with i.e. let the data provider know.
You're welcome to your opinion (which I think calling me lazy, can't be bothered etc pretty harsh) - but personally I see it differently. I am paying for the data. I have let them know of what appears a clear error. The minimum I would expect is either an explanation as to why I am wrong, or at least that they will raise the issue with the provider. Fair enough, you think its up to me to tell them why 5+5 = 10 and not 25? I think its just an error and should be flagged with the provider. You think they should throw it back at me and I should do further leg work - we will have to agree to disagree on this.
. I was then asked to provide the correct numbers. But the point was that the numbers didn't add up, so surely there is an error!
Its easy for stuff like this to get lost in translation - perhaps they thought you wanted to check back to your numbers or soemthing - who knwos . They did repond though and it was you that chose not to follow it up then moan later - when you have said you havenmt even checked to see if it was updated later that doesnt help as you are giving the inference that they wont have done when you havent checked. No biggie here my thoughts mean nothing in the scheme of things
That's a fair comment and perhaps I should have pursued it further. Your views are not unreasonable. However there are people that have raised issues which didn't need further clarification and it seems they have not always been adequately followed up by Stocko support.
I agree that with the many thousands of data fields there will inevitably be errors. But I think for me the point is, that when people have raised the issues they haven't always been dealt with properly. I thought users went by the principle, that if you see a data error, then you can use the green button support, and it will be followed up with the data provider - after all they are paying a lot of money for a service which relies on accuracy to be worthwhile.
Overall I am a massive supporter of Stocko and love the offerings available. However in regard to this specific situation, I think they can do more to follow up these when alerted, which judging from certain comments / experiences, has not always been the case. Or if it is being followed up, it's not been made clear to the Stocko subscriber. Which is frustrating for those raising the issue.
Re: data
Just another point worth checking. This problem has been discussed in the past and I thought that Stockopedia should check its data interface with the data supplier.
This might help solve the issue where data is updated at the supplier end - but not picked up by Stockopedia.
I raised the fact (green button) that the share count for Hercules (LON:HERC) is incorrect (8m rather than 80m) in December... still not corrected.
Hercules (LON:HERC) Has 80m on my screen, it was last November as well..
80,585,543
Where are you seeing 8m shares? If it was only 8m then the Mcap would be incorrect.
this is usually my quick visual check as to how much the share count is increasing. I only mention this as I have noticed alot of data errors, some I sort out using the green button, in this case it hasn't been fixed. I am firmly in the 'data should be correct' camp. Any systematic method of investing (whether fundemental or technical) relies on getting the data right. I would prefer if Stockopedia made it explicit as to whether the data errors are their responsiblity or that of Refinitiv - the issue seems to be smeared around, probably deliberately.
Hercules (LON:HERC) has taken quite a cold shower. Presumably people unimpressed by the "accounts delayed by so much action" story??
The concern would be that usually companies accompany a delay rns with a one liner that trading is in line with expectations or will be at least in line. Hopefully they have not uncovered a hole. Its a poor judgement call on their part not to comment on trading
Hi Dave, Hercules (LON:HERC). I was also a little disconcerted with the delay in reporting - have they found some 'unforeseen' figures in their recent company purchases? (i.e. Advantage NRG). I was however, reassured with the additional information issued yesterday, that confirmed that they had secured the status of Preferred Supplier to Balfour Beatty. This is no mean feat for Hercules to achieve, and should, in theory, ensure that they have a constant flow of ongoing & hopefully profitable work in the next few years.
Balfour Beatty (The largest construction/infrastructure company in the UK with turnover of circa. £8.5B) would only have granted this Preferred Status to HERC after months of monitoring their performance, analyzing their accounts, reviewing KPI's (Key Performance Indicators) etc. etc. I am a holder of HERC and have purchased further shares today.
Agree I think it is just a nervous response to delayed audit....Hercules (LON:HERC)
Journeo (LON:JNEO) is one I’ve looked at and ducked several times only to see its SP rise. I’m again a bit underwhelmed by the trading update with revenues a bit below market expectations from my reading of it. I’m not seeing where the significant increases are coming from to meet future estimates. Will be interesting to see how the market reacts. I’m not inclined to hit buy though based on this. What do others think?
Cayman - look at the underlying FCF generation, £8.4m or 10% FCF yield, they can self fund another CFDS each year without debt
Journeo (LON:JNEO)
I’m again a bit underwhelmed by the trading update with revenues a bit below market expectations from my reading of it
£1 mil shy on revenue
Its a company with lumpy contracts and many moving parts - very hard to predict whats going on. Note they had acquisition this year so adding that into the forecasts mix is an extra hassle
Note they may have high value lower margin pass through sales and costs here what key is delivering promised booked profits.
the old saying is true revenue is for vanity and profit is for sanity.
They delivered on the money ref profits (i am not going to call £0.1 mil above expectations a beat personally) - so its odd when they have delivered exactly as promised in a "very demanding year" - that you would be underwhelmed. Slightly odd.
Facts are - this year was always going to be tough to make themselves look decent - the prior year was exceptionally good with large contract for the New York Subway stopping. For them to be broadly consistent with prior bumper year was good out-take.
Clearly some on here were expecting that more would be delivered than was promised - i will sideswipe that subject other than to say imho its safer to simply follow what the company say unless you have goodactual evidence otherwise. I will say it again that contracts normally mean didly squat if they are not accompanied by revised expoectations or at least some commentary better may be to come. this company needs to deliver £72 mil sales in 2026 - tahst alot of lump cotracts tey need to deliver - we have had a fraction of that showing up via rns!!
What matters more is that they are on track to deliver something like 10% plus pa compounded organic growth - or something acceptable if not 10% . I have made the 10% figure up so we will have to see what pencilled in for 2027 before we can fully review whether the further out future will have similar growth to 2026.
If company can push on with decent compunded organic growth from this sold base then it looks cheap. For now though until we see them saying 2027 is going to be great it seems reasonably priced at present. Main thing is they are expecting to do better in 2026 and i have no reason to think 2027 wont be beter again. If i was on the sidelines i would eprhaps be waiting to see what they pencil in for 2027 - as that imho is the key with how they think they will be next 24 months. Would be nice if all te positive murmourings turned into real extra profits - that was never promised for 2025 due to 2024 having that lumpy contract
Journeo (LON:JNEO) It's a solid update. Nothing wrong in 'solid'. Cavendish have increased their PT to 740p from 602p. FCF is strong. Acquisitions will change the picture positively imv - to what extent is not predictable. But the latest one should contribute significantly.
The Cavendish update:
Positive FY25E trading update
Journeo’s FY25E update points to another strong year, with 10% YoY revenue growth to £55m
and adj. PBT +14% YoY to £5.7m, slightly ahead of the £5.6m forecast. Net cash was £12m,
significantly ahead of the £9m forecast, primarily due to disciplined working capital
management. CFDS has already demonstrated its value following the £5m UK utility
framework win immediately post-acquisition in September and subsequent £2.3m purchase
orders under the framework for high-security infrastructure protection solutions across three
sites. Infotec’s success in FY25E saw the US region move from being just a large one-off
project to an increasingly sustained strategic growth avenue. Infotec’s $5m purchase order in
2H25E from Outfront Media is for the first displays it has supplied for Digital Out of Home
advertising on subway platforms and positions it well for further opportunities across US transit
networks. Journeo’s valuation looks compelling on an FY26E Adj P/E of 14x (12x ex-cash P/E)
versus peers on 20x, with further upside being seen if the c.£12m of net cash balances are
deployed on additional organic or acquisition opportunities. We have updated our 12-month
price target by taking the FY1 peer group P/E of 22x and applying it to Journeo’s FY2 adj EPS
of 33.2p, giving a price target of 740p offering over 50% upside.
Thanks Charlie and everyone else for commenting. I know I'm possibly not viewing this stock objectively due to having decided not to buy previously, hence reaching out for others opinions. It's a bit like holding onto a failing stock and ignoring bad news and trying to find good points to support a hold position instead of taking a fresh look and selling out. With Journeo I'm often finding myself searching for reasons not to buy, probably to prove my original decision correct! Stubborn mule that I am.
The SP is not moved much today and I still feel nervy about them hitting the growth numbers in FY26 so I think I'll jump on their next results call and make a decision after that.
Thanks Cayman (not named after the car? I ask as 981 owner)... To recount my own experience. I originally got in at circa 55p (100k shares) way back when and then sold at circa 50p through impatience and ineptitude.... before re-entering again in 2023 at levels between 140 and 217. It is my biggest holding even after selling down quite a few (nigh on 50%) at 500p and a bit. The more I meet or see the management the greater the conviction I have. Do I see the Cavendish 740p target as achievable? Assuming the markets don't tank then I believe it may well happen.
The triple of the fav holiday, a racehorse and the car. A cracking 718 S with all the trimmings but sold that after Covid as it was gathering dust. Loved the 981. Sounded and drove better imo. I daren't go near the showroom as I'll be tempted ;-)
Agree on the sentiment! My 718 stolen (Met not interested at all) replaced with a low mileage 981 GTS Boxster - never enjoyed a machine with 4 wheels more, and I have been fortunate in what i have been able to enjoy. Get tempted!
"ahead" updates" could it be possible Graham, that companies catch on and use this catchphrase as a worm on a hook?
If it's true, does it matter?
Well, yes, too many choices lead to bad decisions.
Maybe you need to work a bit harder then?
20 hours plus each week on research on the stock market and making decisions not enough. eh Charlie?
Not bad. But as my school report frequently said 'could do better'. And my investment returns reflect that (also on about 20 hours a week)!
One of my school reports said 'economical of effort' but that was at the Grammar 67 years ago.
Good morning all.
Email alerts not working for me today - anyone else?
No problem here. Suggest you contact support via green tab.
Another positive trading update from Volex (LON:VLX.) exceeding market expectations. I really like this.
With all the negative feelings expressed in yesterday's DSMR I should have bought to add to what I already hold.
Long list. Looking forward to your opinions.