Daily Stock Market Report (Wed 23 April 2025) - AGFX, PAY, BOWL, SRB, SUP, BAB, ABDP, SYS1, CRDA, TSLA, THG

Good morning! The FTSE is set to open up by another >1% this morning, over 8400, as the recovery continues.
1pm: I'm wrapping this up for now, thanks everyone!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Reckitt Benckiser (LON:RKT) (£33.7bn) | “We maintain our outlook for full year 2025 whilst recognising the more challenging macro outlook.” | ||
Fresnillo (LON:FRES) (£7.7bn) | Started 2025 in line. Full year guidance unchanged. Q1 silver production -8.4% vs Q1 2024. | ||
Babcock International (LON:BAB) (£3.8bn) | FY March 2025 “strong”, rev £4.83bn (organically +11%), adj. operating profit £363m (+17%). Contracted backlog of £10.1bn at 31 Mar 25, versus £9.5bn at HY25. | AMBER/GREEN (Roland) [no section below] Today’s update confirms FY25 results should be largely as expected, with a modest improvement in margins. The FY26 outlook seems positive, with £1.8bn of recent contract wins highlighted. | |
Croda International (LON:CRDA) (£3.8bn) | Rev +8%, Q1 PBT in line. FY25 outlook unchanged, adj. PBT £265-295m (FY24: £260m). Local manufacturing is expected to mitigate tariff impact, but there will be a tariff surcharge for customers where needed. | AMBER (Roland) [no section below] I’ve been waiting a long while for signs that this chemicals group may have reached a turning point. I wonder if today could be that time. Reiterated FY25 guidance suggests a return to profit growth, after two years of declines. The Q1 update highlights sales growth in all three divisions, with improving factory utilisation. I wonder if Croda’s Falling Star styling could soon shift to a neutral or positive style. I’m going to take a neutral view today to reflect the forward P/E of 18 and macro risks, but I’m encouraged by this update. | |
Quilter (LON:QLT) (£1.9bn) | AUMA broadly unchanged during Q1 at £119.6bn. Net inflows £2.2bn offset by market declines. | ||
Hochschild Mining (LON:HOC) (£1.6bn) | Peru: solid performance. Argentina: easing of FX controls to improve cost position in long-term. | ||
Ibstock (LON:IBST) (£688m) | Core revs in line. EBITDA margin fell as expected. Full year exps unchanged (incl. H2 weighting). | ||
PayPoint (LON:PAY) (£458m) | FY March 2025 in line with adj. EBITDA c. £90m, adj. PBT in line and net debt <£100m. | GREEN (Graham) [no section below] A brief, comforting update. The stock is nearly 10% cheaper than it was when I covered it in January. I was positive on it then and I see no reason to change my stance after an in line update. With a moderate debt load (£109m) and a highly cash-generative set of businesses whose collective profitability is growing, I remain a long-term fan of this one. The StockRank is 96; making it a “Super Stock”! | |
Hollywood Bowl (LON:BOWL) (£452m) | H1 revenue +8.4%, LfL revenue +2.1%. Net cash £23m. 2035 target for 130 centres unchanged. Confident in outlook for FY2025. | AMBER/GREEN (Roland) Despite some concerns about weak LFL growth and possible margin pressure in the UK, my overall impression of this update is positive and I'm opting for a moderately positive view. If current profitability can be maintained and the group can achieve its growth targets for the next decade, I think the shares could be worth a closer look at current levels. The StockRanks are neutral. Interim results are due next month. | |
Nichols (LON:NICL) (£440m) | Q1 rev +1.2%, in line. Net cash £60m. Expectations unchanged (rev £178.9m, adj. PBT £33.1m). | ||
THG (LON:THG) (£420m) | £400-600m bid for Myprotein from Selkirk (LON:SELK) was “wholly unsolicited, largely unfunded”. Rejected. | PINK (offer rejected) RED (Graham) I remain RED on THG for reasons explained previously. As for Selkirk, it raised £7.5m in November 2024 with a view to making an acquisition (it currently has no business operations). The unfunded approach to THG appears to me to be an exercise merely in creating publicity, as they search for a more realistic deal. There is a complicated web of relationships to be aware of, e.g. Kelso group (LON:KLSO) owns 18% of Selkirk, and 25% of Kelso’s portfolio also consists of THG shares. Additionally, THG's CEO is the second-largest Kelso shareholder. I would be extremely cautious when it comes to touching any of these shares as an outside investor. | |
Ab Dynamics (LON:ABDP) (£394m) | Rev +11%, adj. op profit +21%. Potential macro disruption but adj. op profit for FY2025 to be in line. | AMBER (Megan) | |
B.P. Marsh & Partners (LON:BPM) (£263m) | BPM has taken £10m/8% holding in iO Partners, a buy-and-build operator in private credit. | ||
Supreme (LON:SUP) (£199m) | FY25 results to be in line with market expectations, with revenue of £235m and adj EBITDA of “at least” £40m. Net cash at year end. Outlook for FY26 is also in line with expectations. | AMBER/GREEN (Roland) Given SUP’s reasonable valuation and decent track record, I’m going to maintain our moderately positive view. | |
Foxtons (LON:FOXT) (£172m) | Q1 rev +24% with sales revenue +73% ahead of Stamp Duty deadline. Confident outlook. | ||
Capital (LON:CAPD) (£137m) | Q1 rev -10.5%, in line with exps. H2 weighting. FY25 rev guidance of $300-320m unchanged. | ||
| Serabi Gold (LON:SRB) (£132m) | Placing & Board Change | Two of Serabi’s major shareholders (Greenstone and Fratelli) have collectively sold 15.7m shares, raising £21.2m. The sale is equivalent to 20.7% of SRB’s share capital. Fratelli retains a 9.99% holding, Greenstone no longer has a position. Board directors representing both investors have now stood down. | AMBER/GREEN (Roland) [no section below] Serabi shares have risen fivefold in two years. It seems that these two substantial shareholders have decided to take some profits. Of course, there are investors on the other side of this deal, notably Brazilian PE firm Starboard Asset Ltda, which recently took the other 20% of Greenstone’s former 25% holding. With Serabi trading on a P/E of 3 I took a moderately positive view on this Super Stock on 14/4, while highlighting the possible downside risk if the gold price weakens. That view is unchanged today, although personally I am inclined to be cautious re. gold. |
Anexo (LON:ANX) (£72m) | Possible offer from DBAY in the form of loan notes and shares in new entity. No details provided yet. | PINK | |
System1 (LON:SYS1) (£68m) | FY25 rev +25% to £37.4m. Adj PBT +68% to £5.2m. Outlook: growth could slow due to macro. | AMBER/GREEN (Graham) Downgrading my stance on this one notch to reflect a cloudy outlook with lower growth and some risk to forecasts. On the plus side of the equation, I'm much less concerned by the company's valuation here than I was previously. | |
Ten Lifestyle (LON:TENG) (£58m) | Net rev +3%, PBT +£0.8m to £1.1m. Net cash. FY exps unch, new contracts underpin growth. | ||
Argentex (LON:AGFX) (£52m) | Liquidity worsened y’day, Seeking “immediate cash injection”. In bid discussions with IFX Payments. | PINK (RED) (Graham) I doubt that IFX will need to pay much to pick up Argentex's existing equity. If the potential deals fall through, I suspect that this is a zero. | |
iomart (LON:IOM) (£29m) | FY25 to be in line, adj PBT £6.5m. Outlook: margin dilution, broker FY26E EPS “break even”. | ||
First Property (LON:FPO) (£18m) | PBT to significantly exceed exps due to one-off events. Underlying trading now profitable. | ||
Finseta (LON:FIN) (£17m) | Rev +26%, PBT +7.7% to £1.4m. Active customers 17% to 1,059. Outlook: strong YTD, in line. | ||
Northcoders (LON:CODE) (£8.7m) | Rev +24%, adj EBITDA in line at £1.0m. 3,976 people trained (FY23: 2,852). Outlook mixed. | ||
Pebble Beach Systems (LON:PEB) (£7.5m) | Order intake +24% to £13.6m, rev -7% to £11.5m. PBT loss £1.3m. Outlook: YTD trading in line. |
Graham's Section
Argentex (LON:AGFX)
Suspended yesterday at 43.2p (£52m) - Response to Media Speculation & Financial Position - Graham - RED
Following on from yesterday’s bombshell announcement we have an update today on the unfolding situation at Argentex.
Yesterday, it was clear that the company was in some difficulty but it wasn’t clear exactly how serious it was - whether it was something less serious that could be overcome with a little luck and a little patience, or whether it was something that the company could not recover from.
Today’s update spells it out: the company needs cash now and a fire sale is on the cards with multiple suitors having already contacted the company.
A brief outline of today’s update:
Three potential offerors have made non-binding proposals.
The offerors are
A vehicle owned by Pollen Street (LON:POLN)
IFX Payments (another payments/FX firm catering to businesses and private clients), and
Terry Clune (a fintech entrepreneur) and Harry Adams (founder-CEO of Argentex who unceremoniously left the company in October 2023).
The Pollen Street and Clune/Adams proposals have been rejected already, but discussions with IFX are “at an advanced stage”.
Unfortunately, the financial emergency has deteriorated further in the last 24 hours:
As detailed in the announcement on 22 April 2025, Argentex has been exposed to significant volatility in foreign exchange rates which has resulted in a rapid and significant decline in its liquidity position as a result of increasing margin calls on its FX Forward and options book. This liquidity position further deteriorated yesterday and the Company remains in regular discussions with its Liquidity Providers.
This further reduction in liquidity necessitates an immediate cash injection to ensure the Company's continued solvency, without which the Board would have to take immediate steps to secure the Company's future and protect value in the business for the Company's creditors and other stakeholders.
Whenever “creditors and other stakeholders” are being prioritised, equity owners have to be braced for the possibility of a zero return.
Due to the liquidity crunch, Argentex needs “an initial bridging loan in addition to further ongoing liquidity support over the near term”.
They again refer to “creditors and other stakeholders”:
The Board cautions that there can be no certainty that the Bridging Loan will be finalised and made available to the Company. In the event that such Bridging Loan is not agreed, then the Board will take immediate steps to protect value in the business for the Company's creditors and other stakeholders.
Graham’s view
This is almost the worst possible outcome for shareholders.
The need for “an immediate cash injection” rules out buyers who might be unwilling or unable to offer this, even if they valued the existing equity higher than other buyers.
And the time-sensitive nature of the situation undermines Argentex’s ability to negotiate an attractive deal for shareholders. Given that there are creditors and other important stakeholders who have an interest in the outcome (e.g. employees, HMRC), the outcome for shareholders becomes relatively less important in this situation.
Therefore, I do not expect that IFX will feel obliged to offer very much at all for Argentex’s existing equity.
And if the deal can’t be pushed through quickly enough, then the existing equity should be presumed worthless in my view.
I’m very sorry for anyone who was holding this over the Easter weekend - they have been very badly let down by management.
1pm update: the drama continued this morning with Lumon Acquisitions, the Pollen Street Vehicle, stating that they remain prepared to make a cash offer for Argentex which will include a bridging loan and liquidity support. They urge the Argentex board to resume working with them to make this happen. Let's hope that the competition between IFX and Pollen can result in a safe outcome for all stakeholders and perhaps a slightly higher bid for the equity!
System1 (LON:SYS1)
Down 14% to 458p (£58m) - Trading Statement - Graham - AMBER/GREEN
System1, the marketing decision-making platform www.system1group.com today issues an update on trading for the quarter ("Q4") and financial year ended 31 March 2025 ("FY25").
Total revenue is up 25% for FY25, thanks to strong growth of 39% in “Platform Revenue” to £34.6m.
“Non-platform” revenue falls 45% to £2.9m.
The US growth strategy appears to be working with 49% US growth.
Profitability: full-year adj. EBITDA rises strongly to £6.5m (previous year: £4.4m).
Adjusted PBT isn’t too far behind at £5.2m (previous year: £3.1m).
The adjustments are of no concern this year as actual PBT comes in higher than adjusted PBT at £5.3m. Adjustments were zero last year as well - a sign of nice and clean accounts.
Net cash finished the year at £12.9m.
Outlook
Despite the excellent full-year results, there are indications of a possible growth slowdown incoming.
I note that for Q4, the year-on-year revenue growth rate was only 2% as there was a tough comparative quarter in the previous financial year.
In the outlook statement, the company says:
While it is too early for us to gauge the effect that the current volatility in global markets will have on our clients' budgets, inevitably at this stage there is more downside than upside risk and we will provide a further update in our full year results. While we remain focused on continuing the profitable growth momentum in the business, replicating 40%+ platform revenue growth may be challenging in the current global economic and political climate, however we do anticipate continuing to deliver strong revenue growth. We strongly believe that with 25 years of advertising and innovation experience, and a methodology rooted in behavioural science, System1 is well placed to achieve our long-term goals by enabling the world's largest brands to create with confidence.
Estimates
Thanks to Canaccord for posting an update on their client today.
I note that the revenue result posted today was slightly (1.5%) below their estimate, although thanks to increased automation and higher margins, profits were slightly ahead of their estimates.
For FY March 2026, the current financial year, Canaccord are forecasting sales of £45.1m (+20%) and adj. PBT of £5.9m (+13%). These are the same upgraded forecasts that they published in January.
Graham’s view
The shares are lower by 25% since I covered them in January. Since then, the US economy has become significantly more uncertain and today’s update confirms that we need to lower our growth expectations for the year ahead, and brace ourselves for a period of uncertainty.
In that context, Canaccord’s forecasts appear vulnerable to me although clearly the company has acquiesced in allowing them to be republished.
This Stock is categorised as a High Flyer which is a winning style - high quality and high momentum, although with perhaps limited value on offer. Valuation is something I’ve worried about a lot here, but I’ve been willing to stay positive thanks to the company’s impressive stream of new business wins. Hundreds of new clients have signed up for System1’s ad-testing, idea-testing and brand-testing services in a short period of time, many of them being successful US-based businesses.
On balance, I am going to downgrade my stance on this just one notch, to AMBER/GREEN, to reflect the fact that this is a High Flyer where growth in the current year is uncertain and is likely to be much lower than the prior year. I remain very impressed by their recent sales achievements, but I also need to acknowledge that the outlook is perhaps less rosy in the short-term than it was before.
One nice bonus is the cash balance, covering more than 20% of the market cap at the current share price and reducing the effective P/E ratio. At the latest share price, I think the cash-adjusted forward P/E ratio is only about 11.5x. So after the recent falls, valuation is much less of a concern for me than it was previously.
That being said, there is a high risk that the company fails to hit this year’s forecasts, which will nudge up that forward P/E ratio.
Megan's Section
Ab Dynamics (LON:ABDP)
Unchanged at 1710p (£393m) - Half year results - Megan - AMBER
Investors who have sent shares in vehicle testing company AB Dynamics down in the midst of the Trump tariff saga have probably had good reason. The company generates two thirds of its revenue in Asia and North America, with both the US and China key markets within those regions.
But it’s also fair enough that management currently isn’t sure how badly the tariffs will impact business going forwards, such is the pace of change in the trade war:
The Group's direct exposure to the most significant increases in tariffs announced to date is likely to be limited but the more general inflationary impacts of increasing global tariffs and possible indirect effects will be kept under review and mitigated where possible through price increases
The good news is that the long-term outlook is positive regardless of what is happening in the wider macro environment. And demand for vehicle testing services remains high, especially with the adoption of electric vehicles and development of autonomous vehicles.
As manufacturers invest heavily in research and development to stay ahead of the competition, they need the likes of AB Dynamics to test their new products, which is why the long-term outlook remains optimistic.
The regulatory environment is also increasingly positive, with greater need for tighter road safety as autonomous vehicles begin development. Management says that this regulatory environment has caused an increase in demand for the testing products division (where the company sells testing robots and simulation machines) which is the biggest contributor to sales. In the first half, revenue rose 7% to £37.5m, equivalent to 65% of the company’s total sales.
The much smaller testing services division is expected to benefit from a new ruling from US regulatory body NHTSA. The ruling will require all light vehicles to be equipped with automatic braking with pedestrian detection from 2029 and was pushed through by the new administration, which tempered some fears that Donald Trump and his team might be a bit more relaxed about vehicle safety.
Improving financial strength
In the last five years, the fundamentals of AB Dynamics have suffered with the combined impacts of uncertain markets and questionable management.
Prior to the departure of the company’s founder Tony Best, AB Dynamics was a lean operation which generated significant cash for reinvestment in organic growth. Since 2019, the company has spent significant volumes of cash on external acquisitions, which haven’t always been integrated efficiently. Operating margins have taken a significant knock, averaging less than 10% in the last four years, compared to almost 20% in the years before that.
And in that time, as shares have stumbled, the senior management team have been busy patting themselves on the back (and filling their pockets) for a job well done. In 2024, chief executive James Routh took a £433k bonus, which took his total pay packet up to 16 times that of the average employee at the company. Both he and the group CFO have been selling the shares rewarded in the incentive scheme of late and own less than 0.5% of the company between them.
But in these interim numbers, there are signs of improvement. Adjusted operating margins are back up to 18.6%, driven by rising sales and operating leverage. On a statutory basis (when the £4.1m of amortisation and acquisition-related adjustments are included) operating margins were 11.6%. Not as strong as the historical norm, but still heading in the right direction.
The company remains debt free with a significant chunk of cash on the balance sheet, which will hopefully be deployed into organic growth and capital expenditure, rather than over-ambitious acquisitions which bulk up the top line, but leave profits in tatters.
Megan’s view:
AB Dynamics is one that I struggle to ‘get over’. It’s a wonderful business in an exciting market, but it hasn’t been well managed and that has cost shareholders in the last few years. It’s not a good sign that many of the larger shareholders have been selling recently, including the company’s founder who sold just shy of £4.5m worth of shares in September. (To caveat, Mr Best still has a 24% stake and is 88 years old, so there could have been some pension requirements at play there).
Selling from Liontrust, Cannacord and Sandford DeLand’s Buffettology fund is less easy to explain away. Perhaps, like me, these fund managers have been disappointed by a company where the investment case (long term compounding growth and lots of cash) no longer stacks up.
But, as I say. I struggle to get over this one because it should be so much better than it is.
It’s a falling star based on Stockopedia’s rankings because the share price has been trending downwards. And it’s not that cheap based, trading on a price to forecast earnings ratio of 22x (although that’s not a bad valuation compared to the company’s history).
If those margins can keep heading in the right direction, I think I would be more tempted. But for now, I am staying neutral and will try and fight my urge to base the investment rationale on the company’s ‘good old days’. AMBER
Tesla (NSQ:TSLA)
Up 6% pre-market to $238 ($746bn) - Q1 results - Megan - RED
Tesla epitomises John Maynard Keynes’ famous advice:
Markets can remain irrational longer than you can remain solvent.
Last night the company announced financial results for the first quarter which revealed revenue from car production down a fifth and earnings per share down 71%. And yet, pre-market activity suggests the company’s shares will open up 6% today.
Why? One explanation could be that Elon Musk has promised to spend more time in his car company and less time dismantling Twitter, disrupting the US government and sending celebrities into space. Such is Musk’s celebrity, the news of his renewed focus on Tesla seems to have been taken as a positive by the market (whether employees feel the same way is a different matter).
The movement could also be a response to a shift in short interest. Tesla has substantial short interest and the shorters have had a good year as the company’s share price has plummeted. A tariff war which revolves around the automotive industry was never going to be a good thing for the company, even if its founder has the ear of the president. One Tesla short fund is up 61% in the year to date. Short sellers have reportedly made $11.5bn from the stock so far this year.
Whatever the reason for the share price movement, it makes analysis of the company’s first quarter results feel futile. This is a company which is worth more than all of the world’s car companies combined. It’s trading on over 100x forecast earnings and those earnings are not exactly reliable. There is no fundamental investment case to be made here.
There was a time when Tesla led the way in the electric vehicle market. And when promises like ‘Teslas will be able to drive themselves across America soon’ could just about be believed. Now the rest of the global automotive market is catching up. In 2024, Chinese company BYD was the most popular brand of electric vehicle, selling more total units than Tesla. In Europe, the range of models from Volkswagen, Audi, Skoda and Volvo have encroached on Tesla’s potential market share. Even in the US, there are now competitors.
Tesla says that the decline in car sales is largely the result of updates made to the hugely popular Model Y, which were disrupted in production. But the company has also reported a decline in average selling price, which suggests competition is having more of a negative impact than Musk would like to admit.
Megan’s view
This is a company whose entire valuation seems to be based on the promise of things to come. While enigmatic management can keep making those promises, there will clearly be investors who keep believing them. And there are times when there is money to be made in the madness, both long and short.
But I have no idea how to monitor those times or understand what on earth makes this such an expensive stock. So I am staying well clear. RED
Roland's Section
Hollywood Bowl (LON:BOWL)
Up 3.5% to 276p (£466m) - Half-Year Trading Update - Roland - AMBER/GREEN
Hollywood Bowl Group, operator of the UK's and Canada's largest ten-pin bowling brands, is pleased to announce a trading update for the six months ended 31 March 2025.
Today’s update from this bowling operator looks fairly positive to me. The company’s expansion into Canada appears to be progressing well and may address any concerns over UK market saturation.
Headline numbers highlight the strong contrast between the two markets:
Group revenue +8.4% to £129.2m
UK revenue +4.7% to £108.2m
Canada revenue +40.8% to £21.1m (at constant FX)
UK: the picture here is relatively straightforward. Like-for-like revenue rose by 1.3%, with the remaining increase coming from three new centres. This takes the total UK estate to 75.
This is an improved LFL performance from FY24, when UK LFL was flat, but it should probably be seen against a backdrop of cost inflation.
The company says this year’s National Insurance rise will add £1.2m in costs (i.e. 1.1% of UK revenue), which it’s “well positioned to mitigate”. However, all else being equal, this suggests to me that BOWL could do well to maintain flat margins in the UK.
Four refurbishments were completed in H1. Two new centres + one refurb are on track to open in H2.
Canada: Hollywood Bowl’s expansion into Canada started in May 2022, when the company acquired Splitsville (5 bowling centres plus Striker Bowling Solutions, an equipment supplier).
The estate has now reached 15 centres, with 2 new centres and two refurbs opened during H1.
In H2, a further four refurbs are due to complete, while another new centre is due to open in H1 FY26.
Two like-for-like growth figures are provided for Canada:
Total LFL +13.6%
Bowling centre LFL +3.7%
If I’ve understood this correctly, these figures suggest that Striker may have achieved 10% LFL sales growth in H1. Given that Striker’s FY24 revenue was £4.5m, this seems a plausible assumption to me, given its position as a key supplier for the group’s new centres and refurbishment projects.
The company has previously commented on the benefits of owning a key supplier – it seems vertical integration is coming back into fashion!
However, the Bowling Centre LFL growth of 3.7% is below the figure of 5.9% achieved last year, even after adjusting for the timing of Easter and an extra trading day in FY24.
I had wondered if the application of BOWL’s operating model might support a higher initial rate of growth in its Canadian centres, but if so, this effect seems relatively small.
Outlook: trading in H1 is said to have been strong and included a record revenue month in both the UK and Canada.
New and refurbished centres are said to be performing well and delivering target returns.
The company notes that 70% of revenue is “not subject to cost-of-goods inflation” and believes tariffs will have no material impact.
Full year guidance is unchanged:
The Group remains confident in the outlook for the business in FY2025
Roland’s view
I haven’t looked at Hollywood Bowl for a while now, but I don’t see too much to dislike.
Management say the group remains on track to have a total of 130 centres by 2035, which would imply a further 44% expansion of the portfolio.
My main concern would be the risk of margin pressure, due to the combination of weak LFL growth and possible cost inflation. Today’s update does not tell us much about profitability, but the company’s commentary on costs does seem broadly encouraging.
The StockRanks currently have a neutral view on this stock:
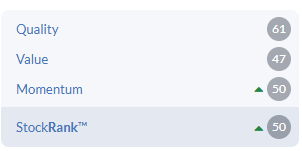
However, I wonder if the half-year results (due on 29 May) could lead to a more positive rating.
Over the last year, the shares have fallen by more than 15%:
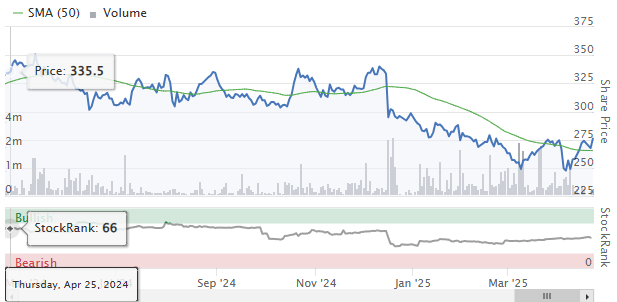
But over the same period, earnings estimates have fallen by less than 3%:
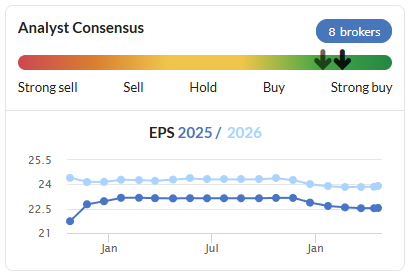
The resulting de-rating of the stock has left BOWL shares on a rolling forward P/E of 11.45, with a dividend yield of nearly 5%:
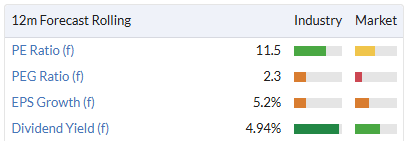
I think that could potentially be attractive if the group can maintain its steady growth and decent quality metrics:

On balance, I’m going to take a moderately positive stance here today, at AMBER/GREEN. We will check back in May to see if the half-year results justify my optimism.
Supreme (LON:SUP)
Down 7% to 158p (£185m) - Trading Update - Roland - AMBER/GREEN
FY25 results are to be in line with market expectatios, with revenue of £235m and adj EBITDA of “at least” £40m. Net cash at year end.
Zeus has FY25E EPS at 21.2p.
Outlook for FY26 is also in line with expectations.
Zeus has FY26E EPS at 19.4p, implying a c. 8% fall vs FY25.
Roland's View
The market seems disappointed by today’s update, perhaps because today’s unchanged guidance implies an earnings fall in FY26.
Recent acquisitions Clearly Drinks and Typhoo Tea are both said to be performing well.
The big unknown is over how vape sales will change following the introduction of a ban on disposables on 1 June 25. Today’s update states that vape sales remain “in line with internal estimates”, but this isn’t very helpful.
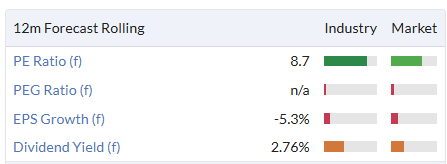
Supreme has invested in rechargeable pod systems and has good distribution reach in the UK retail sector. My feeling is that the company could adapt to this change somewhat successfully, although I don’t see any easy way to predict the near-term impact on sales and margins.
Given SUP’s reasonable valuation and decent track record, I’m going to maintain our moderately positive view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Mr Neary - I'm a bit disappointed - No write up on Finseta (LON:FIN)
Hollywood Bowl BOWL - well this is a trading update and we really want to see the full interim results but it seems to me that the business is sound, that they are progressing both in the UK and (especially) Canada, and that the drop in the stock price makes the company look pretty cheap. Note that they should again be achieving a decent double digit RoCE. Personally I don't see the need for any further share buybacks (nor do I for any UK companies in fact). I shall be disappointed if we don't see some institutions recognising that despite two awful years during the coronavirus pandemic the company has increased its net profit by more than 70% over the past five years (subject to final figures!). Seems a good value steady eddie to me. (I have a few).
Judging by the share price of several UK small caps, Mr Market appears to have his sunglasses on this afternoon. It is something Donald said or the tenuous possibilty of a real cease fire in the tragedy that is Ukraine, or just the usual market gyrations?
The stock market rally comes after Trump told reporters Tuesday afternoon — after the market closed — he has “no intention” to fire Fed Chair Jerome Powell despite repeatedly criticizing him and threatening his job security throughout the past two weeks.
The president also told reporters he likely would slash the 145 percent import tax rate he imposed on Chinese goods, and voiced optimism in a trade pact with Beijing.
“145 percent is very high. It won’t be that high, it’s not going to be that high … it won’t be anywhere near that high,” Trump told reporters Tuesday in the Oval Office. “It will come down substantially, but it won’t be zero.”
Afternoon Jonno, have you got any views on the small SP dip of Sabre Insurance (LON:SBRE) which i think by memory you hold too. I can see it’s gone Ex Div but is there something I have missed?
Supreme (LON:SUP)
Not a very good market reaction to an in line statement. Roland suggests "..perhaps because today’s unchanged guidance implies an earnings fall in FY26". However that fall was already in the figures so my guess is that we have had a number of "above expectations" statements in the past so being just in line was a disappointment for some.
The Zeus report left numbers little changed as did that from Equity Development that you can read here. They also retained their Fair Value of 225p/share.
Does anyone know why TEAM PLC (TEAM) is up 49% today please? Thank you (I HOLD)
What the Lords of the Stock Exchange take away with one hand they (potentially) giveth with the other.
I hold Argentex (LON:AGFX), soon to no longer be, and Cavendish (LON:CAV).
I've mentally written AGFX off now as a £0, but interested to see what money CAV can make out of this situation as banker to Lumon (the Pollen Street entity). I'm aware this is wishful thinking, but Lumon has in the last half an hour come back with an announcement saying it will provide bridging finance, as well as a possible offer for the shareholders, and wants the AGFX board to re-engage.
Watch this space.
Cheers
Chris
P.S I was also interested to see the Holdings announcement in AGFX released this morning saying that Harwood had only just (Thursday last week, literally the last trading day) upped its stake in AGFX to over 5%. So I guess this demonstrates (i) that AGFX's risk management incompetence was total, and no one saw this coming; and (ii) these things happen to investors of every size and shape. Some small comfort.
Cavendish (LON:CAV)
Whatever they make will eventually end in the pockets of the directors and employees. SBP of £1.5m in the interims for generating nothing!
Another pointless UK small cap listing run for the benefit of everyone except the shareholders. SP will continue to trade downwards with the odd uptick. The cash balance will deteriorate further.
All the best
I agree with that concern yiannos1 - SBP basically absorbed all the adjusted PBT in the most recent results. BUT in the good years the share can still multi-bag. In 2019 Finncap made 2.56p of EPS, 4.8p in 2021, 4.5p in 2022 (still comparable EPS figures despite the merger because Finncap and Cenkos effectively were the same market cap). From this level you could be looking at a 4-5 bagger despite the ridiculous share-based payments.
A £150m market cap with the yearly dilution and the cash burn?
EPS is a manipulated metric that means nothing in real life; especially for companies that are being run for the directors.
Cavendish (LON:CAV) will be something close to zero as the AIM shares and in general the UK small cap will vanish.
All the best
I hold Argentex (LON:AGFX) and don't expect any return at this stage. I was intrigued by the summary dismissal of the Lumon advance - have IFX refused to engage unless they were given an exclusive period? or is the situation sufficiently acute they only have time to deal with one party?
The GBPUSD rate has fluctuated between 1.27 and 1.34 in the last couple of weeks, volatile but not bonkers. The only conclusion I can draw with any confidence is the business has been run with astonishing incompetence.
And what about the Deloitte, the auditor? Clean report signed 2 April 2025!
Auditor - do you have enough cash to meet margin calls in a stress scenario?
AGFX Risk Manager - do you mean initial margin or variation margin, cleared or non-cleared?
Auditor (scratching head) - all the margin you could be called for in a stress scenario...
AGFX Risk Manager - we have a risk model
Auditor - show me
AGFX Risk Manager - here it is, we bought it from a company whose name you will have heard of.
Auditor - do you do have a stress scenario for higher volatility?
AGFX Risk Manager - Yes - here is the report we ran last week....it says £10m is plenty
Auditor - you've rounded the MTM up to the nearest pound and we need you to round it down to match the accounts. Please correct that.
Auditor looks at bank statement, sees more than £10m, ticks box and moves on.
Very good , MC !
I have very little idea what Argentex (LON:AGFX) does, or how they do it. As a lifelong manufacturing specialist, its not a sector I have any knowledge or understanding of.
But I am very interested in learning from the calamitous situation it has found itself in. Can anyone please explain to me, in laymen's terms, what has gone wrong here ?
The company says it has “been exposed to significant volatility in foreign exchange rates ”. Have they really been that volatile ? Personally I only keep an eye on the dollar and euro and, although there have been movements in the dollar, they dont appear to be much different to what has frequently happened over the last 25 years or so ?
Also, could other companies also be facing similar situations to argx ?
People really do misunderstand what the job of an auditor is - yes they should test internal controls, but verifying that a stochastic VAR model at a small firm is in the hands of a suitably competent individual, and is being fed with the right data, is really asking rather a lot.
Have a look at what I posted yesterday for a less flippant take on the situation:
https://www.stockopedia.com/co...
Thanks Monte C , I’m beginning to get it
I am right in thinking that AGTX have borrowed money from someone to fund buying an asset ( something to do with FX) . The value of that asset has fallen for whatever reason (to do with the Trump nonsense) , and now the funder is demanding AGTX pay more money into their account to cover that shortfall. And in this case, that shortfall is so big that AGTX simply doesn’t have the funds to cover it ? Plus the funder has the rights to take any asset it wants from AGTX to cover itself
Have I got that right ?
Finally ( sorry to be a pain ) what was it, do you think, that caused the business to fall over the edge so abruptly over the last days or week ?
It all reminds me of that excellent film Margin Call !!
Many thanks for your help MC, it’s always really great to have someone who knows something about which I know very little !
Thanks again
I bet the Chairman is not happy either.. bought £120,000 on the apr 11 and other directors bought in April also!
Serabi Gold
down 24% to 147 after the institutional placing of 15m shares at 135 .
the reaction is exaggerated on bad day for gold miners following the gold retreat from $3500 yesterday.
Don’t really understand what they are raising cash for? They seem to hold a decent amount of cash + revenues and profits are increasing due to increased gold price. They are cash generative don’t pay divs.
They're not issuing new shares; it's large shareholders selling facilitated the company.
The placing by a major shareholder to other institutions doesn’t change the value of Serabi Gold (LON:SRB) at all, just the dynamics of supply and demand.
But it sets a price. Same happened to ME International (LON:MEGP) from which SP is only just recovering.
Serabi Gold (LON:SRB) - I just don't get it. Agree there's no new money going into Serabi itself - it's just shares changing hands between existing and new shareholders. That being the case - why the need for this procedure. Why did the parties not simply agree a private deal with this new shareholder? Was it perhaps at the insistence of the Advisors who wanted to make some money themselves?
Hi Bohemia, It’s not one new shareholder, but multiple institutions who bought via the standard book-building process. I’m not surprised by the discount it took to clear the block of shares as this is a volatile small-cap (albeit with a massive following tail wind from the gold price surge in the last year). I hold
So a tempory set-back then and in the case of Serabi Gold (LON:SRB) some profit-taking must have taken place as well. Having held Serabi for some time today's share price has hit my stop loss so I top-sliced Rightmove (LON:RMV) to buy some more. There is nothing quite like being a Contrarian.
Ah I’ve miss read this not a rights issue but a share sale - but why such a negative reaction today if shares are just changing hands.
Ab Dynamics (LON:ABDP) I hold
Solid interims and given the turmoil created by Trumps tariffs a reasonably confident outlook. I was struck by this comment:
"The Group is a leader in all key global markets and, with 145 customers, its broad customer base and geographic mix of revenue means it is largely agnostic to the success or failure of individual OEMs"
It's not just automotive products:
"A number of opportunities for niche mining applications for the robotic automation retrofit system, Indigo Drive, are in progress. Initial production units have also been delivered of the retrofit human form recognition system, InVu, which provides an AI driven solution to industry mandated safety requirements for construction vehicles, using rFpro simulation software for training of the AI system."
I would be interested in knowing more about this new development if anyone can comment:
"......ABD Solutions has also provided enabling technology into a new automated mileage accumulation solution with initial revenues delivered during the first half."
Dividend is small but is being increased by 20% which implies confidence going forward. Please can the team cover these results?
Would be great if you have time to look at Hollywood Bowl (LON:BOWL) and PayPoint (LON:PAY) team couple of mid cap faves on here just had a skim of Hollywood Bowl (LON:BOWL) results all looks fine to me but does seem its now ex growth so maybe not much upside from here ?
Hi Phoenix, yes - I like to keep an eye on PAY and we are likely to cover BOWL too. Cheers!
Thanks Graham top man as always.
Hi phoenix, first glance I was a bit disappointed at Hollywood Bowl (LON:BOWL) .
22M net cash though, Canada still large growth opportunity. UK possibly ex growth.
Hoping some PE in US fancies this for around 350p...
Thats kind of my thoughts John all be it with current US carnage not sure if PE types will be opening their wallets until things settle down (hopefully).
Artisanal Spirits (LON:ART) webinar today at 2pm.
Andrew Dane, CEO and Billy McCarter, CFO, provide an introduction to the company and update on recent performance.
Interesting company currently trading on a c75% discount to NAV. Owns over18,000 casks of mainly Single Malt Scotch Whisky, (and other spirits) from 150 different distilleries across 20 countries. Listen in to understand how shareholders can profit from this big discount.
Register: https://us02web.zoom.us/webina...
Supreme (LON:SUP) traded strongly across FY25, delivering a record financial performance which was supported by the positive impact of strategic acquisitions and continued management of the Company's cost base.
https://www.investegate.co.uk/...
Yes but 2026 forecast is for reduced sales and profit (due to disposable vape sales?) so no growth this year. I sold this morning but it’s on the watchlist as I feel there may be upgrades during the year if the acquisitions trade well.