Daily Stock Market Report (Wed 6 Nov 2024) - ABF, SOS, ENSI, SOLI, WISE, MKS, JDW, YOU, DOTD

Good morning! It's Roland and Graham with you today, plus an overnight section from Megan.
US Election - Donald Trump is destined to be sworn in as the 47th president of the United States. The FTSE has responded positively as of 11am this morning and Megan has covered the response in more detail here.
This report is all done for today (just before 1pm). Phew!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
Akey assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices).
My video explaining/reviewing it. My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
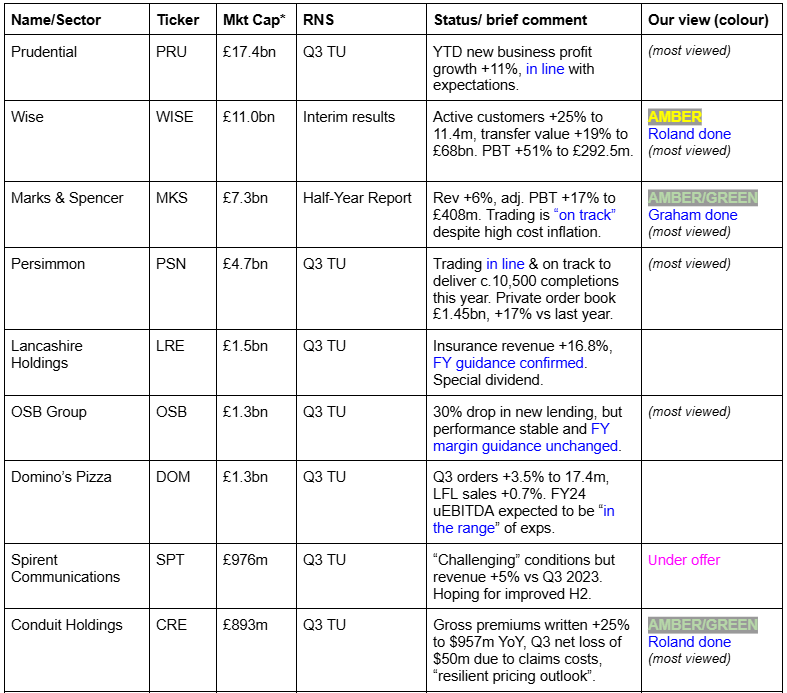
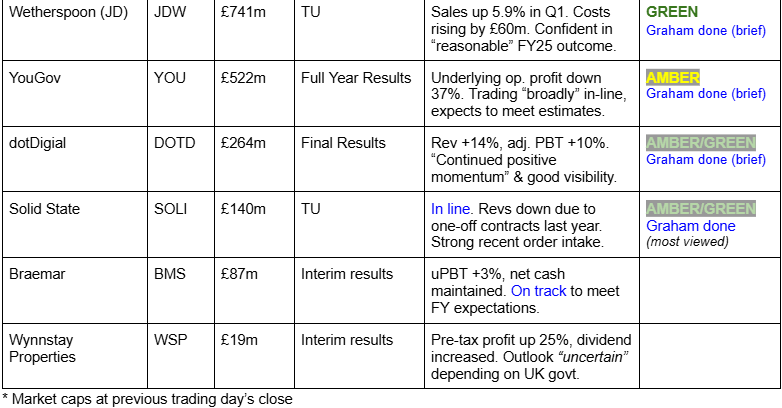
Backlog
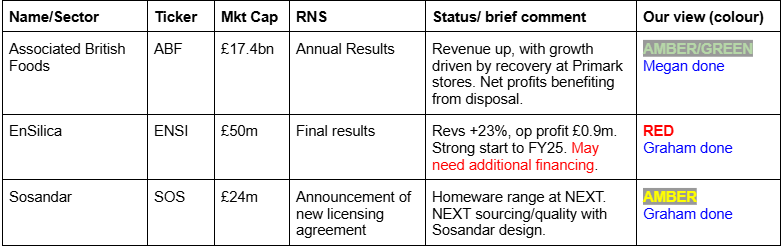
Summaries
Solid State (LON:SOLI) - down 10% to 221p (£140m) - Trading Update - Graham - AMBER/GREEN
This update is in line but the market seems unimpressed: H1 revenues (£62m) and adjusted profits (£2.5m) are significantly down on last year, due to the loss of one-off contracts, and hitting this year’s expectations relies on orders that have not yet been secured. I downgrade my stance from GREEN.
Wise (LON:WISE) - up 4% to 801p ( £8.3bn) - Interim results - Roland - AMBER
A strong set of results from the currency transfer specialist. The benefit from higher interest rates has provided a big boost, but as I discuss I think there are reasons to expect profitability to start to normalise. I like the business but think the shares are probably already fairly priced.
Marks and Spencer (LON:MKS) - up 7% to 409p (£8.4bn) - Half-year Report - Graham - AMBER/GREEN
MKS reports that it’s on track for a good year and brokers have upgraded forecasts with Shore Capital now pencilling in PBT of £830m for FY March 2025. Additional costs of around £120m are on the cards as a result of the recent Budget, but the company is finding cost savings elsewhere to pay for this.
Conduit Holdings (LON:CRE) - down 9% to 493p ( £813m) - Q3 TU - Roland - AMBER/GREEN
This specialist reinsurer has revealed chunky losses for Q3 and potentially Q4, driven by an active US hurricane season. There is likely to be a big hit to earnings this year, but Conduit’s capital position appears to be robust and I can see some potential value here if the company can develop a longer record of successful underwriting.
Short Sections
Associated British Foods (LON:ABF)
Up 2.8% yesterday to 2,353p (£17.4bn) - Annual results - Megan - AMBER/GREEN
I have never paid Associated British Food (ABF) the attention it perhaps deserves. The company for me has always been synonymous with Primark - and to be fair, the ‘retail’ division which makes up Primark’s contribution to the business does account for 47% of group revenues and 55% of group profits. In my mind, this makes the company more of a retailer than a diversified wholesaler and brand owner. One that operates in the same market as Next and Marks & Spencer, rather than Unilever and Nestle.
I have also often questioned the purpose in housing a distinctly retail focused business within the same walls as an FMCG, agriculture and ingredients business. High quality FMCG companies come with far higher margins and returns than retail businesses.
And yet, these annual results have given me pause for thought.
Revenues rose 4% at constant currencies to £20.1bn. This is consistent with the sales growth of the last five years which have seen a CAGR of just under 5%. Revenue growth was strongest in the retail (Primark) and sugar divisions of the business, which together contributed 60% of the top line.
More significant was the increase in operating margins. Adjusted operating margins were wider in all five business divisions, most notably a 3.5pp increase in adjusted operating margins in retail. Group operating margins have recovered to 10%, from 7% last year and 6.9% on average over the last five years.
The return on capital employed (a key measure of quality) is also ticking up year on year. In these numbers, ROCE was 10.5% from 9.1% last year. And the company is converting its profits to cash. All hallmarks of a quality company that I like to see.
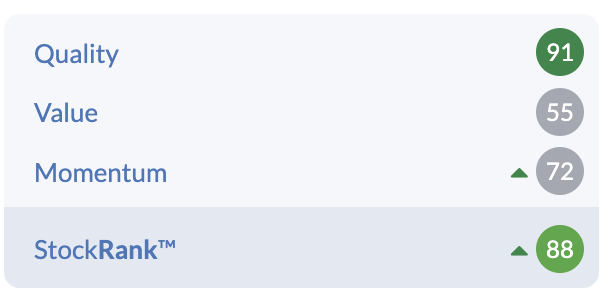
Megan’s view: A price to earnings multiple of 12 times isn’t especially attractive for a retailer, but as ABF continues to tick up the quality scale, that multiple isn’t looking especially prohibitive. Especially with the momentum heading in the right direction. Earnings forecasts for 2025 were tempered earlier in the year, which gives me some pause for thought, but this is one that I won’t overlook so readily in the future. AMBER/GREEN
Sosandar (LON:SOS)
Up 1.5% yesterday to 9.9p (£25m) - Licensing agreement with NEXT - Graham - AMBER
We had a short update from Sosandar on Tuesday morning with the news that it has signed a licensing agreement with Next (LON:NXT) (disclosure: at the time of writing, Graham has a long position in NXT).
In more detail:
Following the success of Sosandar's clothing range sold through NEXT, NEXT is extending its partnership to licensing the Sosandar brand to develop a homeware range… the licensing deal will combine NEXT's sourcing and quality expertise with Sosandar's design inspiration. The range will include a full set of living room furniture and accessories, including sofas, accent chairs, rugs and lighting. It will be sold online exclusively at NEXT.co.uk and expects to launch in Autumn 2025.
Licensing is amazing when it works - a “licence” to print money!. As Sosandar highlight today, this agreement requires no capex. But in order to work, you need to have very strong brand equity. Does Sosandar have this? At least NEXT must see the potential for it to work, which is saying something.
Graham’s view: the most recent H1 trading update from SOS showed the company’s revenue retreating as it focused on full-price sales at higher margins (62% vs 55% the previous year). The pre-tax loss for H1 reduced in size and was a more manageable £0.7m. Net cash stood at £7m.
My stance on this one is instinctively sceptical as management’s unexpected (to me) decision to open physical stores goes against the grain in an era of online shopping. However, I’m intrigued to see if it might work as the chosen locations are “affluent, thriving locations where Sosandar customers over-index”.
The main point that prevents me from taking a negative stance on this one is the £7m cash balance, covering a large chunk of the market cap. However, if store-related capex and ongoing losses eat away at that cash pile, I’ll be quick to downgrade my stance.
EnSilica (LON:ENSI)
Down 16.5% to 43p (£41.5m) - Audited Full Year Results - Graham - RED
We last covered this chip-maker in May, when Paul analysed a £4.9m equity fundraise it carried out at 45p.
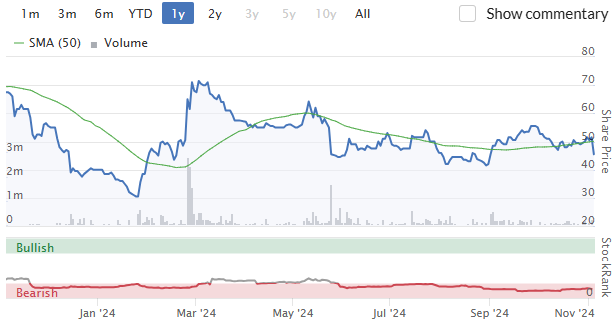
The share price has been reasonably stable since then:
On Monday, it announced a new debt facility for up to £9m, replacing its existing facilities.
On Tuesday, it announced full-year results with some positive-sounding figures: revenues +23% (£25m), EBITDA up slightly to £1.7m, and operating profit up slightly to £0.9m.
But these full-year results only take us to May 2024. It is already November, and H1 is nearly over!
In the outlook section, ENSI says that FY25 started strongly with the achievement of key milestones and new business momentum.
But there is a fly in the ointment:
Whilst the Board is confident of the short-term revenue pipeline, additional external financing may be required should the Company experience further delays in contracted customer receipts
Footnotes to the report explain that the company failed a covenant on its previous lending facility, as it did not receive funds from a customer that it had expected to receive (although this failure was due to a delay on a customer signing a contract, so was the payment really “contracted”?)
The going concern statement includes the following blunt assessment (emphasis added):
Due to the Company's investment in the co-development of ASICs with customers in order to achieve long term future recurring revenues from supply, the Company requires additional financing in the form of loan financing or equity financing, or advance contract payments in order to continue its operations and current capabilities.
It goes on to concede that there is a material uncertainty around the assumption that the company can continue as a going concern.
Net debt as of May 2024 was as follows:
Loans £4m
Leases £2.1m
Offset by cash of £5.2m.
Result: Net debt £1m.
However, considerable time has passed since then. And the net debt figure of only £1m doesn’t tell the whole story, if the company lacks headroom on its lending facility and if the gross cash pile (£5.2m) is needed for use inside the business.
Graham’s view: as there is a stated need for additional financing, I’m going to be RED on this for now. I can switch back to AMBER when this problem is fixed, but not before.
J D Wetherspoon (LON:JDW)
Up 3% to 616p (£762m) - Trading Update - Graham - GREEN
This appears to be a very solid update with like-for-like (LfL) sales up 5.9% in Q1 (it’s actually Q1 plus an extra week, but who’s counting!).
There have been a small number of pub disposals, reducing total sales.
A monthly tracker of the hospitality industry puts LfL sales growing at 1.3% in August and 1.7% in September, far below JDW’s numbers. JDW says it has outperformed the tracker for 25 consecutive months.
Costs - set to rise by £60m following the recent Budget, of which two-thirds are due to higher NI contributions.
Outlook - the company is “confident of a reasonable outcome for the year, although forecasting is more difficult given the extent of increased costs”.
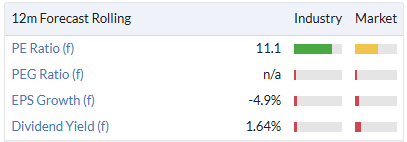
Graham’s view - Paul was positive on this at 729p as recently as October, and I don’t see any need to change the stance on this based on today’s update. It could still offer decent value here despite increased uncertainty:
YouGov (LON:YOU)
Up 3% to 458p (£532m) - Full year Results - Graham - AMBER
YouGov already published full-year results (to July) last week covered by Paul here. It’s back today with results that don’t carry this disclaimer:
Although the audit procedures are substantially complete and the Group does not expect any material changes to the results, the Group's auditor has requested more time to complete the audit. As a result, YouGov is today publishing its results on an unaudited basis.
Numbers at YouGov have always been a little complicated, but recently they have become even more complicated. These full-year results include £38.7m of adjustments, which is an enormous increase on last year. It’s a lot to process:
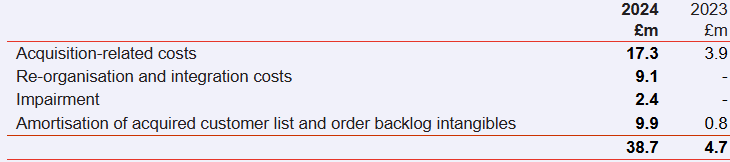
Without these adjustments, operating profit for the year is a mere £10.9m. But if you allow for them, you get £49.6m.
Cash flow analysis is also complicated, as the company has always capitalised much of its spending on intangibles. And this year there has been a large acquisition (€315m), bringing lots more intangible assets in, for the accountants to keep track of.
Net debt at YouGov is now £148m (July 2024), vs a net cash position of £105m the previous year.
Graham’s view - there’s no need for me to change stance, I just wanted to flag that audited results have now been published. This one is in my “too difficult” tray.
dotDigital (LON:DOTD)
Up 3.5% to 90.1p (£276m) - Final Results - Graham - AMBER/GREEN
It’s a pleasant set of numbers from “the leading SaaS provider of an all-in-one customer experience and data platform”. Or as I called it in July, a provider of online marketing tools to businesses.
Revenue +14% to £79m, with organic revenue up 9% at constant currencies.
Adj. EBITDA +10% to £24.3m.
Cash at year-end (June) of £24m. Dividend gets a top-up to 1.1p (from 1p).
Outlook:
The Group enters the new financial year with continued positive momentum and a good level of visibility of future revenues. While economic conditions remain challenging across our end markets, the impact on trading has been limited to date
Graham’s view: I was AMBER/GREEN on this in July (share price at the time: 93p) and am happy to leave that unchanged today at a share price of 90p. I like the company and the stock but others do too, and it’s priced accordingly.
Graham's Section
Solid State (LON:SOLI)
Down 10% to 221p (£140m) - Trading Update - Graham - AMBER/GREEN
Solid State plc (AIM: SOLI), the specialist value added component supplier and design-in manufacturer of computing, power, and communications products, announces a trading update for the six months ending 30 September 2024…
It’s surprising to see that this is down 10% when SOLI is trading “in-line with market expectations for the full year”.
These expectations do imply a substantial fall in revenues and profits in the current year (FY March 2025):
The previous financial year ended 31 March 2024 was characterised by two very sizable defence orders which whilst welcome at the time, could not be expected to reflect normalised annual trading for the business as reflected by market expectations for the current year.
For H1, revenues are forecast at c. £62m (H1 LY: £88m) and adj. PBT of c. £2.5m (H1 LY: £7.3m).
For the full-year, it looks like things might be a little rushed, if the company is to meet expectations?
Management expects (based upon the visible order pipeline) that orders, particularly from the defence sector, will be secured and delivered in the second half of the year to enable the Group to meet market expectations.
So orders will need to be received, contracts will need to be signed and product delivered in the next few months, for the company to meet expectations.
“Systems” - weaker order intake as a result of political uncertainty, leading to delays to various programmes..
“Components” - this market is normalising. Billing in H1 (nearly £27m) will be below last year (£31.4m). Should be strong in H2.
Outlook:
The October orderbook has increased to £84m (with ~ 60% billable in FY24-25). The significant improvement in order intake in the most recent months, combined with the opportunities in security and defence, means we are confident we will deliver a much stronger second half.
Estimates: Cavendish have made no change to forecasts. Full year revenues are expected to fall from £163m last year to £144m. Adj. EPS to fall from 20p to 13.1p.
Graham’s view
The archives confused me a little bit, until I realised that SOLI has multiplied its share count by five with a bonus share issue! It issued four new shares for every existing share, to improve liquidity.
Unfortunately the shares have been in reverse in recent months:
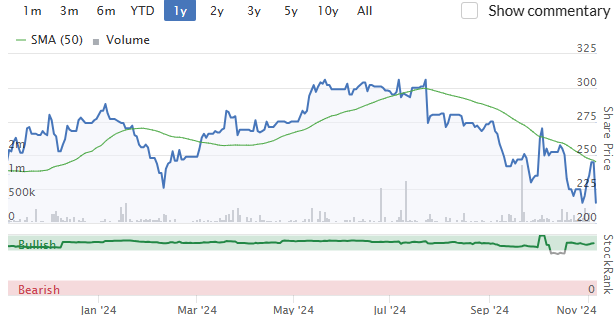
I was positive on the stock last year at a share price of 1168p (equivalent to 234p in new money, I believe).
The PER at the time was 13x and the company was enjoying very strong momentum in orders and EPS estimates.
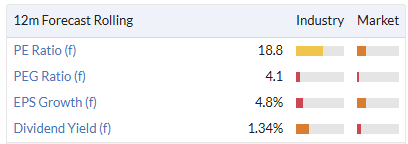
Today, the current-year PER is about 17x (dividing the current share price by the adj. EPS estimate).
Stockopedia comes up with the same number using its rolling calculation:
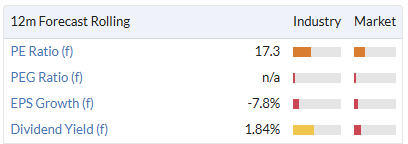
So the valuation on current/forecast earnings is at a higher PER than it was a year ago, and I don’t have total confidence that these earnings estimates will be achieved.
It therefore seems reasonable to adjust my position on this slightly lower to AMBER/GREEN.
The balance sheet should still be fine, with net debt last seen at £5m (March 2024) and only a few tiny acquisitions carried out since then.
Plus with UK and US elections out of the way, spending programmes might start ramping up again to their usual speed.
So I still have a positive impression of this one, even if it’s not looking quite as attractive as it did a year ago.
Marks and Spencer (LON:MKS)
Up 7% to 409p (£8.4bn) - Half-year Report - Graham - AMBER/GREEN
There are some excellent comments in the thread below about the impact of the Budget on companies such as MKS and JDW.
Let’s take a look at the MKS perspective.
Firstly, an overview of H1:
Sales +5.8% to £6.5 billion
Adj. PBT +17% to £408m
PBT +20% to £392m
All very encouraging on its face. We also have an unchanged dividend of 1p and a move from net debt (£320m) to net cash (£22m), excluding leases.
CEO comment excerpts:
"Executing our strategy to 'Reshape M&S for Growth' has again delivered an increase in customers, sales value and volume, market share, profit and returns. Both Food and Clothing have now delivered market share growth for four consecutive years…
The easy thing to do today would simply be to say that these are good results, but that wouldn't be the right thing to do. In the spirit of being positively dissatisfied, we have so much to do over this year and beyond…
The business remains in robust financial health. We have improved our return on capital employed to 15% and further strengthened our balance sheet, giving us the capacity and flexibility to invest for growth and deliver structural cost reduction, demonstrating our ability to deliver value for shareholders.
And now let’s skip ahead to the outlook section where we get a view on costs:
During the first half of the year, cost inflation has continued to be elevated, running well ahead of price inflation and the consumer environment has been uncertain. Despite this, the business has traded well growing volume and value market share.
As we enter the second half, we expect this backdrop to persist. Nevertheless, in the first five weeks of the second half overall trading remains on track and we are confident of making further progress in the remainder of the year.
Elsewhere in today’s report, MKS says that it’s still targeting £500m of cost savings by FY28 in stores, the support centre and the supply chain.
However cutting labour costs is proving more difficult with labour cost inflation currently running at 10%. They say that “structural cost savings have largely offset the impact of operating cost inflation”.
This is something I’ve become more cautious of. When a company says that it’s targeting cost savings of X, as many companies do, this doesn’t neatly translate into a financial gain for shareholders, as it might only be a partial mitigation for a cost increase somewhere else! Or it might give management the impetus to upgrade software or invest in something else. So the outcome of cost savings is rarely as neat and tidy as I might have hoped for.
Anyway, getting back to MKS, CEO Stuart Machin is said to have told reporters today that the recent Budget changes to national insurance and minimum wage will each cost MKS £60m, for a total cost of £120m. So it’s clear that structural savings and savings in the supply chain will be needed purely to offset this.
Estimates: fortunately, according to brokers, MKS is set to have an excellent financial year. Shore Capital have today upgraded their FY March 2025 forecasts by 9%. Their PBT estimate shoots up from £760m to £830m, with EPS of 28.7p.
FY March 2026 also gets an 11% upgrade, with a new PBT estimate of £894m and EPS of 30.9p.
Balance sheet: MKS has bought back £190m of its medium-term bonds. This action alone doesn’t change net debt, as cash and debt are both reduced by the same amount, but it does reduce net debt if the cash might otherwise have been spent on something else!
MKS has four bonds outstanding, one of which isn’t due until 2037. MKS will need to manage the repayment or refinancing of the other three over the next three years:
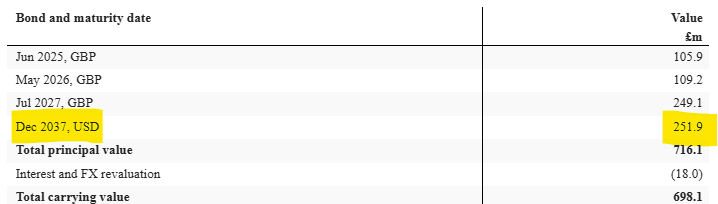
There is balance sheet equity of £3 billion, almost fully tangible, and including £5.2 billion of property, plant and equipment. Physical retailing is capital intensive but MKS has succeeded in generating an attractive return on capital in recent years, as trading has improved. Today it reports an adjusted ROCE of 15% (H1 last year: 13.2%). Stockopedia awards it a remarkable QualityRank of 97 thanks to some nice quality metrics:
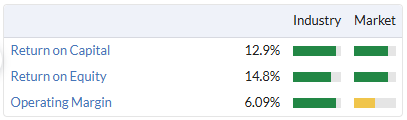
Graham’s view
Paul was GREEN on this at 288p in May. With the shares up by over 40% since then, and now commanding a respectable PER that’s back in the teens, I’m inclined to nudge the stance on this slightly lower to AMBER/GREEN. Not because the company has done anything wrong - to the contrary, it has done brilliantly - but because perhaps most of the easy money has been made now.
The share price has already quadrupled in two years. For traders who like momentum, it’s currently scoring a perfect 99 in momentum according to the StockRanks.
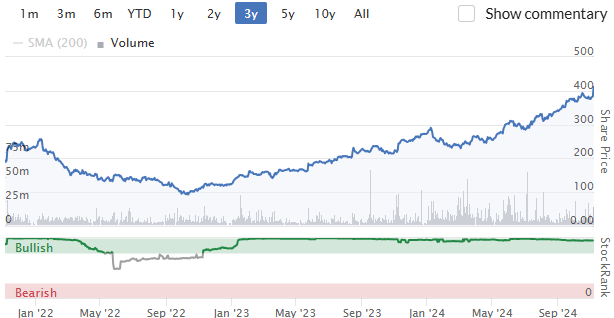
When MKS does poorly, it does very poorly - and we see the dangers inherent in low profit margins and high operational leverage. But for now it’s doing very well and the sun is shining - long may this continue.
Roland's Section
Wise (LON:WISE) - up 4% to 801p ( £8.3bn) - Interim results - Roland - AMBER
..another six months of strong financial performance with YoY growth in active customers of 25%, underlying income of 19%, cross border volume of 19% and a 31% increase in customer holdings...
This currency transfer and payments business has had something of a rollercoaster ride since its IPO in 2021, but it’s intrigued and impressed me. Not least because it’s been consistently profitable, while growing fast.
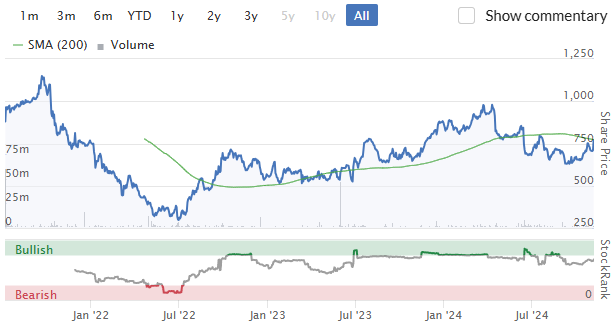
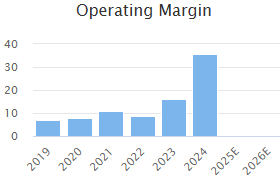
Profitability has soared as interest rates have risen, but this is not entirely intentional and may not be sustainable, as I’ll explain below.
H1 results summary: today’s half-year results from Wise have been well received and the shares are up in early trading. The headline figures certainly seem quite impressive to me:
Revenue up 19% to £591.9m
Underlying pre-tax profit (before interest income) up 57% to £147.1m
Interest income on customer balances up 42% to £300.7m
Pre-tax profit (inc. net interest income) up 51% to £292.5m
Underlying PBT margin (pre-interest): 22.2% (H1 23: 16.8%)
One point worth highlighting is that the company expects this underlying PBT margin to fall back to its target range of 13-16% in H2 as price cuts take effect. So the 22% underlying margin achieved in H1 shouldn’t be seen as the new normal.
These financial metrics were driven by strong operational growth:
Total active customers +25% to 11.4m
Cross border volumes +19% to £68.4bn
Cross border revenue +9% to £419.1m
Card and other revenue up 52% to £172.8m (mostly interchange fees from card use)
Cross-border take rate -5bps to 0.62% (H1 23: 0.67%)
Trading commentary: the company says that continuing upgrades to its infrastructure mean that 63% of transfers are now completed instantly (within 20 seconds) and 83% within an hour.
New regulatory approvals were received allowing the company to integrate directly into domestic payments systems in Brazil, Japan and the Philippines. A 5,000USD cap on outward transfers was lifted in India.
Wise’s strategy is to integrate as deeply as possible into domestic payment systems so the company can control transactions from end-to-end, cutting costs and improving speed. However, while the company currently operates in 160 countries and 40 currencies, it only has six direct connections to local payment systems currently live. So I’d imagine there’s considerable scope for the network to continue developing.
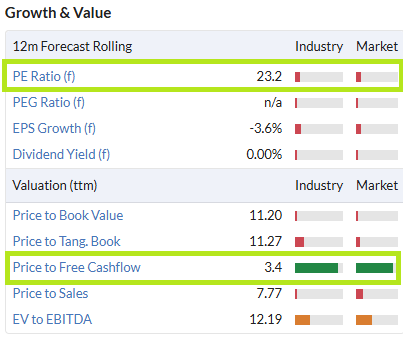
Cash generation: this business is cash generative, but it’s worth pointing out that the free cash flow metrics on the StockReport are boosted by cash deposited by new customers. This explains the difference between the elevated P/E and super-low P/FCF ratios:
The company provides a free cash flow figure used internally of £257m, up from £192m for the same period last year. The majority of this was used to repay £200m of debt, leaving Wise’s own cash balance of £1.1bn broadly unchanged from the end of FY24.
Borrowings have now been reduced to £52.4m at the end of September and Wise says it has “group eligible capital of £883m”, significantly above regulatory requirements. The situation looks comfortable to me.
Interest rates: Wise’s strategy is to continually cut its fees to provide the best possible pricing. The average take rate fell from 0.67% to 0.62% in H1 and was apparently down to 0.59% by the end of September.
However, rising interest rates have dramatically increased the profitability of this business, regardless of fee income growth:
I have to admit that my first assumption was that (like many other platforms), the company was happy to retain the majority of interest income to boost profits.
But it looks like I was being unfair. At least, I think so.
Wise’s interest rate strategy appears to be to retain the first 1% yield and then return 80% of any excess above this to customers. The problem is that in the UK, the company’s licence does not allow it to pay interest directly to Wise Account holders.
For this H1, Wise’s interest income above 1% was £230.2m. So the company would have returned £184m to customers, but was only actually able to return £84.8m. The remaining £99.4m was “incidentally retained”.
Wise does not say if it expects this situation to change. But perhaps it will, over time.
Roland’s view
Wise’s growth continues to be driven mainly by new customer acquisition. Customers numbers have risen by 2.8x in four years, while cross-border volume growth is almost identical, at 2.9x. This seems logical to me – changing service provider is not likely to result in an increase in transfer requirements.
According to Wise, the company currently has a 5% share of the personal market and 1% share of SME. I would imagine there’s still plenty of further growth potential.
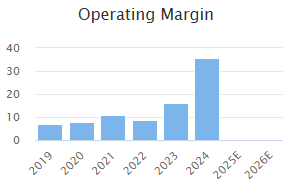
However, my feeling from today’s results is that the current level of profitability – with statutory operating margin of 51% – may be a peak. Interest rates have stayed higher for longer, providing a boost. The company’s apparent inability to return interest with many UK customers is also contributing to this.
Over time, I suspect we may see operating margins return to a mid-teens level.
Profitability may stay above this range for a while yet though, especially if interest rates don’t come down.
Outlook & valuation: the company expects underlying income (revenue) to rise by 15%-20% in the year ending 30 March 2025. This appears to be close to the consensus figure shown on Stockopedia, which implies 15% revenue growth.
I don’t think today’s results imply any significant change to earnings expectations.
Wise’s FY24 basic earnings were 34p per share. Stockopedia shows similar figures for FY25 and FY26:
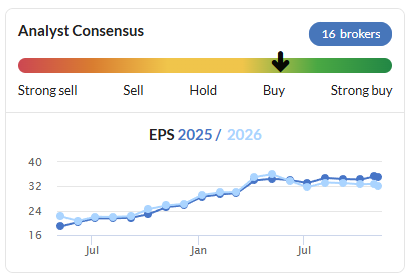
With the shares now trading on a forward P/E of 23, my feeling is that Wise’s share price is probably about right for now, so I’m going to remain neutral.
Conduit Holdings (LON:CRE)
Down 9% to 493p ( £813m) - Q3 TU - Roland - AMBER/GREEN
Activity across smaller and mid-size natural catastrophe and risk events has been elevated
Conduit is holding an Investor Meet Company presentation at 16.00 today for retail investors.
Conduit Holdings is a Bermuda-based reinsurance business that listed on the London market in late 2020. The company says its main business is quota share reinsurance. This means it is responsible for a fixed share of an insurer’s losses, in return for a matching percentage of the relevant premium income.
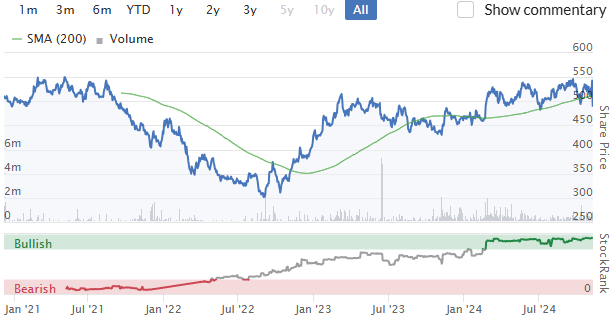
Conduit is a new business that’s in its fifth year of operation. It’s grown quickly and achieved profitability last year:
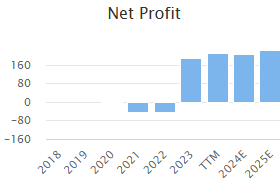
However, today’s trading update has been poorly received. Q3 and expected Q4 losses seem to suggest a significant downgrade in earnings expectations for this year.
Let’s take a look.
Conduit says gross premiums written during the first nine months of 2024 rose by 25.2% to $957.3m.
Reinsurance revenue over the same period rose by 30.3% to $588.2m.
Risk-adjusted pricing (excluding claims inflation) rose by 1%
Estimated undiscounted Q3 net loss of $50m
Continued top-line growth appears encouraging and was driven by property and specialty insurance categories, where pricing has been stronger than in casualty:
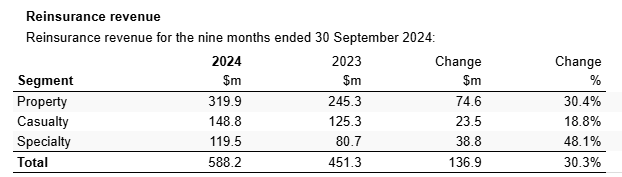
However, as Warren Buffett may once have said, collecting insurance premiums is much easier than generating an underwriting profit. So let’s take a look at the firm’s disclosure on Q3 and Q4 losses.
Impact of catastrophe losses: today’s share price slump highlights concern at the potential impact of this year’s catastrophe losses, primarily driven by an active US hurricane season.
Today’s statement provides some insight into the company’s current assessment of its exposure:
Q3 net loss: $50m
Undiscounted combined ratio* “in the mid-90s on a year-to-date basis” to 30 Sept 24 (worsened from 85.7% at the end of June 2024)
Q4: undiscounted loss from Hurricane Milton (Florida) in October estimated at $30m-$50m
We also know that Conduit suffered an undiscounted net loss of $19.8m due to the Baltimore bridge collapse in H1
*this measures underwriting profitability, lower is better. A combined ratio of 100% = breakeven
Prior to today’s result, only the Baltimore loss was reflected in broker forecasts. So we can see there’s probably going to be an extra $80-$100m of losses to factor into this year’s results.
With Stockopedia showing an expected net profit of $206m for Conduit this year, I think it’s fair to expect a significant downgrade.
Fortunately there’s an updated note from Panmure Liberum available on Research Tree this morning - many thanks.
PanLib’s analysts have crunched the numbers and cut their earnings forecasts for FY24 by 38% to 59p per share. That’s equivalent to a FY24e P/E of 8.
Earnings forecasts for FY25 and FY26 have been left unchanged and the (house) broker is confident that Conduit’s capital position will allow it to absorb this year’s expected losses without any adverse effects.
Checking the RNS, Conduit’s available capital was $1.05bn at the end of September, unchanged from the H1 accounts at the end of June. This seems fairly reassuring to me.
Panmure Liberum’s confidence is expressed in an unchanged forecast for a dividend of 28.1p per share (£46m) this year, giving a useful 5.7% yield.
Roland’s view
These relatively large losses are coming on the back of several years of strong pricing. So the impact on profitability is much less than it might have been at a softer point in the cycle.
I would guess that Conduit may still be able to generate a respectable c.10% return on equity this year (FY23: 22%).
It’s always worth remembering that unpredictable, large losses are a normal part of business for insurers. As CEO Trevor Carvey admits, the company expects to pick up “our fair share” of catastrophe losses.
Carvey says he believes the company has a “well-diversified” portfolio and can continue to grow the business in a “measured and balanced manner”.
However, it’s perhaps not surprising that the company says it is focusing on “non-catastrophe elements of both Property and Specialty” at the moment, where it sees “good opportunities for selective growth”.
I’m not an expert on this sector, but my impression is that today’s update is not a disaster. It may however help to explain why Conduit shares were trading on a P/E of five ahead of today’s earnings downgrade.
On balance, I’m happy to go AMBER/GREEN on Conduit today, on the basis that the valuation still seems reasonable and the company’s capital position appears to be robust.
However, one caveat I’d add is that Conduit has a very short track record so far. We don’t yet know how profitably it will navigate complete insurance cycles.
For this reason, if I was investing in this sector, I might be more inclined to consider companies with longer records such as Lancashire Holdings (LON:LRE) (not a recommendation). That’s just a personal preference, though.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

144 comments
Wise (LON:WISE)
Hi Roland
Thanks for very much for your analysis today, it was much appreciated.
I'm a holder so I hope that it's okay to add some of my own thoughts:
I'm of the opinion that profitability levels are still on the rise.
2 reasons immediately come to mind:
e.g. the Assets feature is relatively new - only 2 years old - and yet balances are already close to £4b.
The company, I believe, makes a c.0.16% on this, most of which, I imagine, will flow straight to the bottom line.
In H1 these accounted for 22% of Revenue, which is the lowest that I have seen it.
For context it was 29% in 2019.
I imagine that this % will continue to decline as the company progresses with the development of their own payment rails. In the call the CEO laid out an example that the LT plan is to charge a user only £5 for a £10,000 transfer and still be very profitable.
The company has been pretty clear that they will grow sustainably, target 13%-16% margins and return excess to customers through price cuts and feature improvements.
I think this is excellent in both the short run (drives customer loyalty) and the long run (the lowest priced player with the best service will be a huge winner.)
The company could probably keep margins higher, but they don't need to do this to carry out their plans.
Takes rates i.e. how much they charge for FX transactions, were voluntarily lowered to 0.59% in Q2.
This is the lowest it has ever been.
For context Remitly Global (NSQ:RELY), a US-based competitor, (market cap $4b) were charging 2.32% in their latest report, which was published a few days ago.
---
I may as well add these. Below are notes I made today (with apologies for duplication from above):
FY25 Interims
FX transaction volumes continue to pick up pace: +21% YOY in Q2
It was 29% back in 2019 and has been going down consistently since then.
Kristo (the CEO) mentioned in the call that there is plenty of demand.
Amazing for a service that started 2 years ago.
Now able to offers Assets in Australia.
Wise take 0.16% of this I believe = £6.1m per year - should be pure profit
"Assets" are off-balance sheet.
Kristo: "Eventually all the large banks are going to be there. It's just a matter of time"
Cocky or true?
I do like reports covering larger cap stocks. Over the last two years I have avoided all but a few small cap stocks as liquidity seemed to drain away causing a downward pressure on price. I did read small cap report as a source of trying to find gems, but the wider coverage is more attuned to my portfolio. Half of portfolio is US stocks, but too much to ask of stockopedia to have a daily US thread!!
Greyster
US market thread would be timely given how dominant the US is now.
London market is pricing a Kamala win :-)
Yes ... the UK market reaction to the Trump win is a little odd. Wait until all those tariffs kick in and the retaliatory tariffs start. But then who knows what will happen ... I'm the guy who convinced himself Harris was going to win. The UK market reaction could just be the injection of certainty and a relief that the result is clear cut and unequivocal.
Still, I did have a look through my holdings and muse a bit on impact:
Many of my defence and aerospace holdings are so intimately entwined with US defence companies, that I think they should be OK.
A lot of other holdings like Next (LON:NXT, Marks and Spencer (LON:MKS) and Pandora A/S (CPH:PNDORA) have limited to zero exposure tariffs. Ditto Cranswick, Premier Foods (LON:PFD) (LON:CWK) and A G Barr (LON:BAG)
One or two companies like Intercede (LON:IGP) and Filtronic (LON:FTC) seem to be indispensable to their US customers. I think my largest holding, Swedish-listed Investor AB (STO:INVE B) might be impacted, Berkshire Hathaway (NYQ:BRK.A) no impact, and my favourite small cap stock, Warpaint London (LON:W7L) is surely nimble enough to move production from China to Vietnam? Bloomsbury Publishing (LON:BMY) own US academic publisher Rowman & Littlefield and have a NY-based office - they could easily list over the pond and delist here. When is a UK company a US company? What do you look at ... the main listing, location of the HQ, staffing, markets, or production?
19% of Alk-Abello A/S (CPH:ALK B) sales are to North America, including Canada, so there could be some impact for them, but it will be modest.
My Argentinian holdings listed on NYSE such as PAMPA ENERGIA SA (NYQ:PAM), YPF SA (NYQ:YPF) and Cresud SACIF y A (NSQ:CRESY) ... who knows? Niox (LON:NIOX) have sales of £8.7m to the US of total sales of £36.8m, so possibly an impact, who knows; NIOX is a highly likely takeover target for a US-based medical device company.
My only Ukrainian holding, Ferrexpo (LON:FXPO) loves the Trump trade.
I think I will do nothing.
Yes a bizarre reaction which has now come up against reality. The FTSE 100 actually down on the day and FTSE 250 which was up more than 2% finished only around 0.5% up. Perhaps the early morning surge was some sort of 'short squeeze' as traders (or their algorithms) closed positions. Perhaps some one with more expertise in this sort of situation could throw some light on the market gyrations.
AC,
I wonder if a lot of the SP gyrations, m(*in small caps) sometimes are to do with Market Makers manipulating prices and reactions as they have to make a living too. Not so easy to do with the large liquid companies, I know, but still feel that over the past months they may have been exacerbating movements.
Watch the PIworld interviews on YouTube with the Market Maker,recorded about 5 years ago? 2 x interviews, where he explains how the would react on Tipsters comments like ST in the Investors Chronical and other journalists and publications. I often wondered if sometimes they would hike shares on the comments from writers here, Paul et al.
Graham.
"Do nothing" - my favourite action in investing! Great bit of analysis there James. G
Haha….that made me chuckle
Smiths News (LON:SNWS) I hold
I see that CEO Jonathan Bunting has sold 1.18M of his shares today for avge price 60.5p. Of course we never do know the real reason Directors do sell but given the excellent recent results, reduction of debt and stellar increase in dividends announced, now would seem an odd time to sell??
By my calculations he has c1.5M shares left. I guess the only thing to do is to keep a sharp eye on the remainder and see what happens.....unless anyone attending Mello this month would like to ask him!
He has about 1.6 million and I'm assuming he will continue to take up options. Given he has been at the company since 1994 and CEO since the lows of the sp, the market doesn't seem that bothered. Maybe he's just position sizing?
M&G have declared a 5.34% holding today in Smiths News (LON:SNWS)
Hi eParo
Where did you see that? Aren't they already 4% holders as of Nov 7th last year??
I know all the noise is the Trump trade but tomorrow we do get BOE and Fed decisions. The market expects cuts of 25bps. The last cut from the Fed resulted in higher yields. US yields are up 15bp today on the Tres 10Y. How the markets take these cuts will be somewhat pivotal in terms of how the picture evolves from here. Should yields continue to rise then its a signal that inflation remains a significant concern...so lets hope for a more conventional fall in yields. I was holding off selling a bond for the cut...this is no doubt destined to be a mistake.
Regarding Wise (LON:WISE) and other companies mentioned in the DMSR it would be handier if I could right-click on the flag in the performance graph and get the report in question up in a new tab. So the 13th June 2024 report only mentioned Wise in the Movers part but went into great detail in PayPoint (LON:PAY) . I hold both.
It might not be the right thing to say but in the absence of Paul, I think the chances on me renewing my Stockopedia subscription are slim.
24 hours in? Seriously? I call that a knee jerk reaction and BTW, you are right, it is not the right thing to say.
Like Andy is not entitled to his opinion …
Ah well.
I think today's report is excellent as was yesterday's. Paul will surely be missed but Stockopedia isn't just about the SCVR.
I must admit i did wonder where the scvr was the other day and was a little surprised and sad.However, life's all about change, unfortunately at times.Personally i'm willing to give the new format a shot, even disregarding all of Stocko's great quant, selection tools.Graham's still here too and i like getting to know some of the team who perhaps were more behind the scenes beforehand, including through the video presentations.
Totally up to yourself. Do not need to post it and let everyone know.
Like you did not need to post this either, Mr Hypercrip
Hi TEIN, thanks again for the very helpful feedback!
I like the idea of putting the company name and ticker in the same column. Will have to try that out. Many thanks.
Graham
On a similar theme would it be impracticable/impossible to provide a link to members' comments on companies as there can be discussion on days when the company has not been covered in the review section?
Perhaps along the lines of companies mentioned by members in a tabulated format allowing a click to quickly locate those of interest.
Good point, ManxMann!!
It’s a truism here that nimble investors benefit from the lack of research available on small caps. And certainly the likes of Vodafone (LON:VOD) and AstraZeneca (LON:AZN) are well covered at the other end of the scale. But I find the mid cap space less accessible than small caps. My bank covers all the global names but doesn’t reach down to the likes of UK mid caps. While I get what I need on small caps from ResearchTree and UKC. So I welcome the shift up the cap ladder, but with an appeal to the writers to emphasise tthe middle ground over the large caps, without ignoring the smaller stuff, of course. After all, that’s where you find the best balance of growth and quality.
The trouble with mid caps is there is a lot of quality research available only to institutions from the likes of Peel Hunt, Numis, Berenberg etc. As PIs we are often totally in the dark as to how RNS's are being translated into new forecasts. I appreciate that for the truly long term investor who's not playing the short term earnings game there may still be an opportunity but it's quite an unfair advantage to have no access to research whatsoever
The trouble with mid caps is there is a lot of quality research available only to institutions from the likes of Peel Hunt, Numis, Berenberg etc. As PIs we are often totally in the dark as to how RNS's are being translated into new forecasts
My point exactly. Small cap research is actually moire readily available. So the likes of Graham poring over say Spectris (LON:SXS) results would be very helpful.
Analysts comment on Trump's return to the White House:
Citi: "Already, the first Trump presidency had profound consequences for the EU, and the policy proposals presented and discussed during the campaign suggest a second term could be at least as transformative. On the basis of the Republican manifesto and various Trump speeches and interviews, four policy areas with spillovers to Europe and the rest of the world stand out: trade, security, energy, and fiscal policy. We expect highly uncertain but potentially mixed growth implications, and on balance, lower inflation and policy rates in Europe.”
UBS: “Technology, utilities, and financials are among the equity sectors we see as attractive. In technology, Trump’s win could lead to heightened fears about the impact of tariffs on earnings for hardware and semiconductor companies. But we do not believe this will outweigh the structural growth story over the medium term. AI infrastructure spending remains robust as businesses experiment with AI use cases and companies race to stake out leading positions. We expect semiconductor components needed for AI will likely remain supply-constrained into next year, supporting pricing.”
Wolfe Research: “House control is relevant to markets primarily in terms of fiscal questions—tax cuts, IRA rollback, ACA tax credits, Medicaid cuts, and deficits/rates. If Republicans fall short in the House, that would be bullish for clean energy and for healthcare names levered to Medicaid/ACA, and bearish for REITs and MLPs based on sector-specific tax risks.”
Berenberg: “The consensus view is that the European defense sector will react negatively to a Trump victory given Trump’s ambition to rapidly broker peace in Ukraine, while Harris is viewed more as a status quo candidate, based on our investor interactions. Weakness on signs of a Trump victory would offer an attractive entry point into a structural growth sector, in our view. A Trump presidency would add further impetus to accelerate European defense spending, as evidenced by his first term in 2017-21. We reiterate our positive stance on the sector.”
ING: “Donald Trump’s victory will ensure a lower tax environment that should boost sentiment and spending in the near term. However, promised tariffs, immigration controls and higher borrowing costs will increasingly become headwinds through his presidential term.”
With the budget not being as bad as forecast for AIM stocks, ISA's and SIPP'S and this morning's Trump Bump, leaving politics out of the discussion, what are subscribers thoughts on the possibility of decent markets for the last two months of 2024 and a Santa Rally?
I’m positive. Valuations in the U.K. seem cheap, and much uncertainty has been removed. I feel that we will see a strong finish to the year.
Morning All
Best wishes to Graham, Megan and Roland as we venture into a slightly new format. Also all the best to Paul. I shall be following both.
I have probably missed something, but other than the expected reduction in interest rates I can't quite fathom why small caps are on the rise this morning. I can't imagine that a Trump presidency is good for UK shares or for the global economy. Views from those better informed than me and that will be the majority welcome.
All the best
I agree, the market reaction is odd. I am just writing something up which will be with you asap.
I don't understand the small cap rise either. A Trump presidency will be inflationary if he implements his tariffs and tax reductions - US treasuries are already forecasting a substantial interest rate rise. In fact, I wonder if the BOE will still reduce interest rates.
Hedges for a non result are being removed, the uncertainty of not knowing has now passed.... and the world didn't stop. This is why in the short term the dollar rallies although really it should fall. Its just a risk on move but the Bond market is perhaps more telling, with yields rising and therefore implied rising inflation. This is less good than the risk on move suggests.
Just some random thoughts as to why Stocks rallied:
1. Above all the fact that the result is decisive means that there is a much smaller likelihood of it being challenged and hence the US descending into chaos I.e. we have a classic relief rally
2. Didn’t seem to get much coverage in the UK but Harris was keen to layer additional regulations / taxes on the Corporate Sector, which would have been valuation negative
3. As has been mentioned up thread to the extent Trump can push for peace in Ukraine that is obviously positive for Energy (lower prices) owing to some trade normalisation and hence ultimately for Europe, especially Germany but UK too
4. For me (and appreciate this is highly subjective) it lowers the chance of Xi trying to take Taiwan. Given its key role in chip production it’s hard to overestimate the damage that would be done to the world economy and financial markets if things got hot there
On the downside you have a continued US deficit that is absurd for an economy close to full employment and at this point in the cycle. So rates will not fall as far as people hope. But then ditto the same on this side of the pond…
re Taiwan, genuinely interested why? With an inward looking USA I'd have thought it more likely. China seems to think so, Reuters repored "China suggested on Wednesday (Oct. 30) that if Donald Trump became president, he could “discard” Taiwan to pursue an “America First” policy."
Fair question. Because under Trump’s previous term his very unpredictability meant that no one dared to do crazy stuff. Did Iran dare to respond when he killed Soleimani. Nope. Did the ME go up in flames when he moved his embassy to Jerusalem. Nope. We had the Abraham Accords. On whose watch did Putin invade Ukraine? On whose watch did Iranian proxies so confidently attack Israel? Could it have had something to do with the US’s utterly embarrassing flight from Kabul in an echo of the fall of Saigon. And then sending mixed messages in kowtowing to Iran and not really knowing how to handle Russia. I grant you
there is an isolationist streak in elements of the Republican Party. But the US also understands that those Taiwanese chips are pretty important. Despite record investment in reshoring chip production they are not even close to being able to give up on Taiwan, if only for pragmatic reasons. Now Xi may just be crazy enough to challenge the US. But I think he knows that he would get a more robust response from a Trump administration than the record of the last 4 years suggest he would have gotten from a Harris one
All markets hate uncertainty? I know it's a cliche but............
Regards
Michael
One possibility- the potential chaos following a dead heat election is now off the table.
The lack of chaos will have been a mjor driver. Additionally if he follows The Heritage Foundation Project 2025 agenda possible/likely(?) this will mean a reduction in Corporation Tax to, from memory, 15%, which will significantly boost after tax returns.
We will see
Good Energy (LON:GOOD) I posted the following elsewhere to get other people's thoughts on this situation. I think the risk / reward looks quite good at the current share price and even better if the price drifts lower. I would be very interested to hear other people's views.
"In the absence of a figure for the indicative proposal, the share price here has reached the boundary of traders' imagination - i.e. it has increased roughly 25% from the circa 290p undisturbed price. In the absence of any inside information or the release of further public information, it feels unlikely that the share price will increase from here and may even drift back to around 340p.
Based on my estimates of the respective probabilities of different take-out points and factoring in a fall back to around 300p in the event no bid is forthcoming, I would say that, at the current price, the market is discounting the possibility of a high take-out price too much. The fundamental reason for this is that unlike many other bid situations where the uncertainty about the probability of a bid going ahead is largely about the take-out price, here we have a blocking shareholder who is a direct competitor. On the one hand we have a wealthy bidder seeking to enter the UK market who knows that they are going to have to make a knock-out bid to succeed. On the other hand we have a blocking shareholder who will be fully aware of the threat that a well-funded competitor could be to his own business and who may be more than normally motivated by ideological considerations rather than the profit motive. Against the latter are that Vince already has a well-funded competitor and that he has publicly spoken about selling Ecotricity quite recently.
Consequently, I see the current share price as allocating too much probability to either no bid or to a bid that is too low to make sense in the context of Vince's failed bid and too little probability to the possibility of a high take-out bid. I don't see that changing because, as I say, it requires more imagination from market makers than my experience of their boundary of imagination allows.
For discussion, here are my calculations of the probabilities of different take-out prices that suggest the current share price significantly underestimates the overall probability-weighted share price. I accept that there are multiple other scenarios which would produce a different and lower result. But I suspect, knowing how the small cap market works, there are few people out there who have performed a similar probability-weighted exercise and the price is being set by current very low levels of trading. It would not, consequently, take much volume to push this higher up to, say 400p but, as I say, in the absence of any inside or public information, I don't think it could go any higher.
I have allocated only quite small probabilities to much higher take-outs but I do see this as a special situation where a well-funded bidder wanting to enter a market comes up against a shareholder who has both ideological and competitive reasons to block the bid. Hence, I would say the probability of a very high take-out price here is significantly higher than in other bid situations. Given that the company is cheap, has expectations of future growth and a large stake in a market-leading tech business, I see further reason why a high take-out price should be allocated higher probability than normal.
This is why, at 350p or below in the absence of any further information I will continue to take the bet that Vince will sell for the right price and that that right price could be much higher than the market is currently anticipating.
Wise (LON:WISE) results look very good with a large increase in customers and profits. i topped up on the results and planning to hold as looks to have good momentum. Can we have your thoughts please Graham?
Hi Shark Trader, I hope you saw that WISE got covered by Roland this morning! Cheers.
To view the table more easily on a phone (as I do every day) try either view in landscape mode or use accessibility settings to enable the screen magnifer. If your screen is really small, do both! Hope this helps.
Good tip
Hi
For those following/holding UK or European defence stocks. This newsfeed .....
** Shares in European defence stocks rise as Donald Trump claims a victory in the U.S. presidential election, which analysts say could prompt higher spending on weapons in Europe
** Index of the region's aerospace and defence companies .SXPARO is up 3.5%
** Hensoldt HAGG.DE, BAE Systems BAES.L, Dassault Aviation AM.PA, Rheinmetall RHMG.DE, Leonardo LDOF.MI rise between 4% and 7%
** Thales TCFP.PA, Renk R3NK.DE and Saab SAABb.ST are up around 3%
** "A Trump presidency would add further impetus to accelerate European defence spending, as evidenced by his first term in 2017-21," Berenberg says
** Earlier in the year, Trump said, the U.S. could withdraw from NATO if the European members of the pact did not increase their defence budgets
I hold Leonardo SpA (BIT:LDO) , Rheinmetall AG (ETR:RHM) I used to hold BAE Systems (LON:BA.) but note Rolls-Royce Holdings (LON:RR.) which I hold is also rising this morning
EDIT: forgot to mention Leonardo SpA (BIT:LDO) and Rheinmetall AG (ETR:RHM) report tomorrow 7/11.
Regards
Howard
Thanks for this, very good insight.
It's scary to think the US could potentially pull out of NATO.
What is the likelyhood of this so we think?
Hi smatthews1
I sense the key driver to these share price rises is that the markets expect the Trump administration to continue to encourage the Europeans to elevate their defence capabilities.
Several European countries who are members of NATO have been under funding their defence budgets for years. Germany being a particularly notable example.
Personally I do not think US will pull out of NATO. But I think US will be increasingly tilting defence resources towards the Asian theater.
Regards
Howard
Interesting as I was expecting a potential Ukraine cease fire to result in a sell off.
Hi RDHOWARTH
My thoughts to your comment ..
Interesting as I was expecting a potential Ukraine cease fire to result in a sell off.
In addition to the new incoming sentiment in US administration which will encourage Europeans to increase defence spending, to counter the under spending they have done in past years.
In my opinion the Ukraine war has revealed to all countries that how and what they spent defence budgets on in the past has to change dramatically. Pivoting toward autonomous warfare and all associated technologies. So I think the market is reacting to the new political leadership but also the advancement to a new modern warfare paradigm.
Regards
Howard
Sure but this is already happening... say German increase in allocation to defence. Im with you it's an interesting trend to invest in just would not have thought the cease fire a catalyst ( if it happens).
To which I would add Kongsberg Gruppen ASA (STO:KOGo) +2.2%, but strangely Cohort (LON:CHRT) is slightly down and Chemring (LON:CHG) up less than 1%.
The US does not have to pull out of NATO to do immense damage to NATO's credibility. I can see them reducing their input (removing 100,000 troops from European soil?) but leaving the nuclear umbrella in place. However, even the US nuclear umbrella is currently being debated in Europe and only France and the UK have a nuclear deterrent among NATO countries other than the US, although the UK nuclear deterrent is not independent from the US. I can hear Micron singing in the bath in the Elysee from high in the Cairngorm mountains here.
European defences companies are in a long term structural bull market although some, like Rheinmetall AG (ETR:RHM) and BAE Systems (LON:BA.) got a little ahead of themselves and are taking a breather.
The big issue for European members of NATO is scale. For example, the Americans run 2 main battlefield tank designs, and the rest of Europe run 14. We need to coordinate and simplify across all battlefield platforms, but I predict national pride and what passes for an industrial policy in the EU will put paid to that. I also noted that the Poles have recently bought Korean, further complicating the smorgasbord of battlefield platforms across tanks and air defence. Given all this, I find it interesting the Germans have decided to get a lot closer to us within NATO by placing anti-submarine air capability in Scotland and Rheinmetall and BAE working together in missile development.
Other issues are that not all NATO think the same, and where will AUKUS fit into all of this in a Trump world? I hold most of the stocks mentioned. It is an enormously complicated picture, and it is only when I talk to RNVR colleagues from years ago, Ukrainian refugees I work with, or military people in the military charity I volunteer for, that I realise just how little I know. Stocko and a bit of background reading still outperform any of the Defence ETFs I researched though.
Today the US military are test-firing a Minuteman II to let the World know that it can WFH.
Hi jamesalasair
Many thanks for your interesting post.
I think I have far less knowledge of the sector than you so I welcome your observations.
An aspect the defence space I do have a little more insight into though is the edge computing space. That is sensors and data capture from space to under sea. The associated data analytics, and use of AI and software as a means of offense and defence. Then, combining these platforms and technologies into the fast evolving autonomous drones space.
I think this aspect of defence investment and development is going to attract quite a bit of sustained attention.
Regards
Howard
I agree with you Howard ... subsea and space-based sensors and data capture form one of Kongsberg Gruppen ASA (STO:KOGo) profit centres. Who else do you think is well placed in this space?
This article from RUSI is worth a read as well:
The UK Defence Space Strategy | Royal United Services Institute
I would like to meet the comedian in the MOD who called it Skynet.
Subsea and space-based sensors and data capture form one of Kongsberg Gruppen ASA (STO:KOGo) profit centres. Who else do you think is well placed in this space?
Amphenol (NYQ:APH) is one I hold. Exceptional quality with the price to match.
Thank you
James,
you raise some good points on military and space technology. The UK has always had a good research base for sensor technologies and luckily there is still a good University, Research Council, MoD/Metoffice/etc and industry capability in sensors today. One reason why I am reasonably confident that the US will play ball with us - at least on defence. The other is that we are such a good customer for the 'cousins'.
I would like to meet the comedian in the MOD who called it Skynet.
Ha! It was the other way around. Skynet is a very old MoD satellite program. Seems you were not paying enough attention to Blue Peter back in the day? I think I'm giving my age away?
Skynet 1A was the first military satellite in geostationary orbit, in 1969. The Royal Air Force displayed a model of the Skynet satellite on the children's television show Blue Peter in 1969, the show also described the new British satellite control centre at RAF Oakhanger.
I have exposure to defence through my holdings in MS International (LON:MSI), Science (LON:SAG) and Goodwin (LON:GDWN)
Cheers
Mark (quite probably the worst ever Chair of the UK's Space Technology Advisory Board for a couple of years)
Thank you so much for this .... fascinating. I am also a fan and holder of Goodwin (LON:GDWN) and MS International (LON:MSI)
Good morning and good luck Roland and Graham, I can see you've got a busy day but if you get chance for a brief look at Braemar's results I would appreciate it. Revenue up slightly 1% Statutory profit 89% but PBT 3.7%, EPS down 17.7% , net cash up 5% and dividend up13%. We're long term holders and decided to hold through the recent adverse publicity. As the incoming president says he will end the war in Ukraine on day one and sort the Middle East out too (!) perhaps shipping routes will normalize next year?
Hi JASVFS, I'm afraid I won't get around to that one today but it's a candidate for backlog coverage! Cheers. G
Lancashire Holdings (LON:LRE) stock up 10% following their trading statement, which included a special divi equivalent to over 8%. Interesting contrast to Conduit Holdings (LON:CRE) which also reported today but is heading the other way. I hold both.
I'm glad we've got CRE covered by Roland today! Thanks for the comment spmarriott.
I am assuming that the change of name, coverage and scope was driven by feedback from users and therefore it will be given a thumbs up here.
However, I for one wish it was still the SCVR and that the DSMR was a separate (daily) post elsewhere. I’ve been a member since 2012 and think I have read 99.9% of the reports and most of the comments. And posted occasionally also.
I would read both.
What do other members here think?
Regards
Michael
Not sure we have a choice! Here is the separate DSMR and Paul's SCVR is now in a separate place on substack.
What do other members here think?
I think that after the departure of their most prolific writer, the team shouldn’t be dispersing itself over multiple threads. And sticking to the SCVR format puts them in direct competition with Paul’s new output. Better to have a main thread that is somewhat contrasting in emphasis. I like the move up the market cap scale, particularly if it is to sideline the AIM crap (keeping the good stuff, please) and I think they are doing well so far.
Oh gosh I didn’t realise Paul had left.
I must have missed that.
point taken.
Regards
Michael
Paul left immediately without warning or ceremony.
Was it in a huff having spat the dummy having been put in an impossible position?
Or alternatively was he told to "walk the plank", the point of a cutlas pressed to his back?
None of us knows the exact circumstances but on the basis there's no smoke without fire its evident a inferno raged through Stockpedia HQ on Monday/Tuesday.
The result is there is now a significantly change to the entire coverage approach . . . . . . . . . . Paul and Graham were historically covering smaller company and adding significant vale as these often have very limited coverage, perhaps only a house broker. I can't see any value-add in writing pieces on heavily researched companies.
Paul is already publishing his daily review on Substack and I see Mr Contrarian will be providing his very prompt and always amusing daily results/news summary.
That "I can't see any value-add in writing pieces on heavily researched companies." was my thought as well but I will give it time and see how things pan out.
Regards
Michael
I know I am not in the majority but for me personally Im very in favour of the move into midcap and wider coverage. We have the scope to focus on interesting small caps and the wider coverage reflects what I actually do. I hang out here because it's one of the only places you can have sensible stock discussions. I welcome any discussion and realise many of us are xBuy Sell side with various info chains still open. Others are x industry which is even better. Generally the pump and dump aggressors stay away. May it continue.
I also realise there is a perceived advantage in Smallcap since it is less covered by professional investors. I tend to think this is exaggerated since institutions get first look at everything, and if they aren't interested then that tells you everything you probably need to know. Research doesn't really make any money and the City functions based on deals. The fact there is less research on small caps doesn't make that much difference IMO. The advantage private investors have is liquidity but the volatility of small cap doesn't help. Obviously historically and in particular the noughties small cap significantly out performed. The move to global indices has massively impacted small cap performance, even in the US. This trend may well reverse at some point...since the rise of passive from 20% to 60% of indices appears to be driving valuations too high. UK equities have suffered in this trend and my hope is this reverses....creating a better backdrop across All UK equities.
The biggest improvement I think Stocko should pursue is building as accurate a consensus ( forecast) as possible. If "house" research could be made available to Stocko to assist this then all the better. If a forum like this also had an ability to write about published research this would be fantastic for us....since we can't really access it. ( Brokers send it to Stocko). It's great when companies tell us they are inline but unless they actually collate the data we often do not have an accurate forecast to judge it by. The current split on stocko between revenue, operating profit and EPS is not normally enough to judge what consensus is....but it's a tough job to tighten it up.
In summary I am all for the change in focus even though we bear the loss of our unfettered access to Pauls great wisdom and input.
Hi RDHOWARTH, I agree that any improvements to Stocko consensus forecasts would be very welcome. I use ResearchTree for forecasts. Don't the people who are paid to write for Stocko use it too? I don't really understand what you are getting at, when you say "If "house" research could be made available to Stocko to assist this then all the better." Then you go onto to say "Brokers send it to Stocko" which refers to published research. I am not trying to find fault with what you are saying, it's just that I don't really get the point. Please will you elaborate and explain because I suspect that you are onto something?
By house research, I mean the company broker, who provide co approved nos and therefore are normally close to consensus. So I would weight this accordingly in a consensus expectation. If the house cuts....it's a miss....whatever anyone else says.
By broker research generally I mean away from the appointed broker... I know they provide to mainstream news outlets, like bloomberg, so why not stocko. Then stocko journalists could make reference to it in the same way they comment on RNS etc.
In summary, Stocko could be a platform to make research available to private investors.
RDHOWARTH. Thank you for your reply. So I will pay more attention to the forecasts of the house broker. So what would Stocko have to do to get better access to broker research that is "non-house"? Is it just a question of making a once only request to all the brokers for it? Or is the problem that Stocko would have to pay for it? I am sure that many of us would support your idea that Stocko could be a platform for making more research available to private investors.
RDHOWARTH
I also realise there is a perceived advantage in Smallcap since it is less covered by professional investors. I tend to think this is exaggerated since institutions get first look at everything, and if they aren't interested then that tells you everything you probably need to know.
Thats a very valid point - what to me is most dangerous is that i know we are at the bottom of the feed chain with small companies and bad news. I think with the current lip service paid by many smaller companies with regard to updating the market in clear and transparent fashion - without that news leaking out earlier to those that seem able to exit if needs be . Note i wont put all companies into this bucket - i have plenty of holdings where i feel like management are honest and doing their best ref updates (that doesnt mean i would fully trust them though)
Regarding consensus forecasts, as I understand it, not all brokers send or make available research to Stockopedia. Changes to forecasts and data are picked up by Stocko from Refinitiv. I don’t know how this works in practice but I would assume it comes with delays to feed through compared to instant access institutions have.
Take example of Saga (LON:SAGA )
House broker Numis and other broker coverage Peel Hunt neither of whom make research accessible to private investors. I think the only way Stockopedia can pick up forecast changes is when Refinitiv does. I recall a webinar with previous management a couple of years ago where FD basically said there was no problem with forecast of 45p of EPS. Inevitably with passage of time forecasts got crushed . There was quite a delay before the amended forecasts were reflected in the Stockopedia data.
I think it is in companies interests to state what they believe to be consensus market expectations , particularly companies like the example above. Many companies do a version of this already.
I think it is in companies interests to state what they believe to be consensus market expectations , particularly companies like the example above
I think we would all agree on that - i must say i have no annoyance at stocky they can only work with the data they are provided with. If house broker though is updating "hidden" on not in plain sight downgrades and company inst telling us before 8 am on the day that really gets my goat up - particulary if they have updated teh market with wishy washy nothingness that day.
RDHOWARTH
Fair comment. We will have to wait and see whether there is any value add to be gained by Stockopedia writers commenting mid and large caps, as well as small caps.
Regards
Michael
One way I would certainly get value is if they write a short piece on a larger stock, and it triggers a lot of comment interest...this pushes me to take a closer look.... and then judge for myself. The value is in the feedback and response as much as the writing.
Michael, surely it all depended on Paul Scott, I've thought for some time that Paul was going too deep down the well in his research there being more and more time needed before 7 am 5 days each week, All good things come to an end and not without reason.
Hi SM
My first comment was before I realised Paul had left. As on Monday he was doing the SCVR and on Tuesday he wasn't and so I suspect that he was pushed or stormed out.
I am not going to speculate why but with around 10,000 reads here and a larger market on Substack Paul can make a reasonable return for all the effoort he puts in at £100 a year sub.
I will for one will be subscribing when it goes subsriber only.
Regards
Michael
“more and more time needed before 7am”
Blimey, what a bizarre thing to say !
Dear oh dear
I could be wrong but what I think Silver Moon was expressing were his fears for Paul’s well-being, working ever harder to deliver backlogged content before the RNSs come out at 7am each day and the whole process starts again with the new day’s news in urgent need of comment. In other words a concern that Paul might burn out.
Just thought I would say thanks the Graham and team for the volume of updates they are providing. I own all sizes of companies, so the broader range on mkt cap is very useful
You're very welcome, nanotrader!
Big hat tip to yiannos1 re Gulf Keystone Petroleum (LON:GKP) and the potential of an SP bump up if there was news of the opening up of the Kurdish oil exports.
Up 8% on the news this morning.
Interesting that there’s no RNS after such a big announcement.
It’s not done and dusted yet for Gulf Keystone Petroleum (LON:GKP) and hence only 8% gain today. I shared yiannos’s enthusiasm forGulf Keystone Petroleum (LON:GKP) and held the share until the Pipeline closure and bought and posted here again as did yiannos when it was clear from their updates that they were coping well despite that big hurdle, and renewing their big dividends. They’ve already paid over 12p in dividends this year….so how much will they be paying when the pipeline opens? It was 88p in dividends in the year before the closure, a yield of around 70% a year at the current GKP share price!
yiannos didn’t agree when I also included Ferrexpo (LON:FXPO) (which was up 30% today but now dropping back) on top of going up 50% already) and from memory it was the valid point about corruption risk. The reason for the big gain today is the election of Donald Trump and his campaign promise to end the War at once. Prior to the war (I held then but sold at the start of it) Ferrexpo (LON:FXPO) paid 52p in dividends in 2021.
Both Gulf Keystone Petroleum (LON:GKP) and Ferrexpo (LON:FXPO) were great buys ahead of the gains and are still worth checking out for further capital gains and in both cases for locking in possibly fast increasing dividends too…..assuming the pipeline is definitely going to open again and the Ukraine War end. Doubts about that might be behind Ferrexpo (LON:FXPO) falling back now. But as yiannos has posted, with Gulf Keystone Petroleum (LON:GKP) it’s a question of WHEN the pipeline reopens and not IF.
Re. GKP and Kiurdish oil exports. But no RNS from GKP, and the Genel SP , who are similarly affected, unchanged! There's clearly some way to go to see what price they get and how much they will export
Brief comment on Gulf Keystone Petroleum (LON:GKP)
No one is expecting an announcement. The Iraqi government has passed a law for compensation for oil costs and transports of $16 per barrel. IOC ‘s we’re asking for $26! IOC’s will not make any announcement unless all is agreed and signed.
They will probably meet in the middle but then there is the payments owed to IOC’s that they have to get sorted. Then we have the profit arrangement to be agreed and the payments to be paid in advance from any future exports.
Long story short- they will agree but needs more time.
All the best
I read it here last week after the positive market reaction (AIM) of the budget, someone wrote we need a budget announcement every week...
As I see the indices now' why we don't have U.S. election weekly as well? :)
250 buyont, AIM or perhaps we should call it the LAME dire days for these stocks
There was some reaction here (or the SCVR, R.I.P) when I last posted about Amedeo Air Four Plus (LON:AA4) so thought I would mention todays published FactSheet.
Air travel remains strong which is an obvious positive for this airplane leasing company.
Boeings struggles are mentioned. Although the strike seems to have been resolved, this will still impact production as they ramp up again. A potential positive for the valuation of second hand planes in the near/mid term, AND/OR the need for airlines to lengthen leases.
The best bit of news for me was the confirmation that Emirates "requested permission to upgrade the interiors of all of our 8 aircraft.". This includes the B777s, I thought they were only interested in the A380s. That is good. Strangely it did not mention that AA4 had given permission to Emirates to go ahead with the upgrades. I don't no why they wouldn't. To me this indicates that Emirates are committed to these planes past some of their current leases (2 to expire 2026, 2 expiring 2027 the other 4 2028).
One comment I'm not sure I understood why it was made was "as higher costs are imposed on airlines, they are becoming faster at cutting surplus or unprofitable capacity." My take is this is a potential risk for the A380s which are less profitable. So if costs at Emirates increase, and they take the same approach seen in the US, the A380 fleet might be at risk of being cut when the lease ends!?
Ferrexpo (LON:FXPO) Ion Ore miner Up 20% on Trump win and expectation Donald can end the terrible war in Ukraine.
Hi TEIN, I can confirm that we have no plans to drop the summary table but if there's anything we can do to make it look better on mobile I'd be up for trying that! How is it looking today? G
Hi Graham,
I've sure the Devs could sort you something that enables you to generate some nicely formated HTML from your spreadsheets for easy insertion into the reports to assist with Mobile Rendering.
Sorry, I missed your comment. Completely agree.
Good morning Graham, and thanks for asking. Watching other comments and thumbs up I might be in a minority but hope my comments are useful, I can't believe I'm the only one squinting!
Really it's about the size of the print, which I end up enlarging, which means scrolling left to right to see all the columns. The table content is in a smaller font than the articles, and for me that font is too small.
With tables you end up with a lot of white space, as all expand to the depth of the one with the most text. Fewer columns would enable a larger font, and as one example why do we need separate columns for the company name and ticker?
I read on my laptop whenever I can, but end of day catch up's or when on the move are more likely using mobile. Of course I can turn the screen landspace but that's hardly the answer.
Anyway, I figured as the DSMR is a new dawn that you'd be looking at all things anew. Continual improvement and all that.
Great content yesterday and today, thank you.
You’ve described what I have to do - enlarge and move it around the screen. If there’s a better way, that would be good. All the better to see the fab content!
Hi Graham. Is it not possible to have the table as 'live' text within a responsive html table? That would then be much more visible and avoid everyone peering at the screen through, or over, their glasses! I reckon one of your devs should be able to do that fairly easily :)
It sounds like I need a conversation with developers! I will be chatting with them in the next week. G
When I use my phone in portrait mode the print is indeed small.
However, what I do is rotate my phone 90 degrees into landscape mode and voila the print is double the size and it nicely fills my screen and it becomes easily readable.
It is just a matter of scrolling up & down. No need for side to side scrolling.
David.
Hi Graham & Megan - I'd love if you were able to keep an eye on what companies are saying about the impact of the Budget on their business. There are some shares like J D Wetherspoon (LON:JDW) that have come off a lot recently so might present a buying opportunity. I had a (very!) quick skim of the Marks and Spencer (LON:MKS) this morning but I couldn't see any clear indication from them albeit they talk about cost inflation in the business running ahead of price inflation.
Yes, would be good to see what the 60 million extra costs actually means for JDW, (67% noted to NI rises)
Hi Tortoise!
Thanks for the suggestion. This morning, JDW said (sorry for the extended quote but it's all relevant):
Following the government budget of 30 October, taxes and business costs are expected to increase by approximately £60 million, on an annualised basis, in calendar year 2025, including an estimated 67% increase in national insurance contributions.
"Cost inflation, which had jumped to elevated levels in 2022, slowly abated in the following two years, but has now jumped substantially again following the budget.
"All hospitality businesses, we believe, plan to increase prices, as a result. Wetherspoon will, as always, make every attempt to stay as competitive as possible.
"The company is confident of a reasonable outcome for the year, although forecasting is more difficult given the extent of the increased costs."
Thanks Graham
That fits with the narrative I’ve been arguing - rather than necessarily expecting a swathe of downgrades (as Paul thinks) I expect all direct to consumer businesses will be planning on price increases to cover the extra NI. The bond market suggests the same - ie inflationary.
I saw interestingly on Smiths News (LON:SNWS) yesterday that the broker tweaked down estimates by about 0.3p EPS for the NI rises though the company itself said it was on track to meet expectations. Of course this is an example of a business that can’t quite so easily pass on costs as it has locked in long term contracts with the publishers.
I noticed that Marks and Spencer (LON:MKS) said the long term impacts of the budget were uncertain but it expected to continue to make progress. I read that as “we expect to see suppliers asking for price rises and we expect to manage that through price increases of our own” but I could be wrong.
Hi david, a quick follow-up to your comment - it's interesting to hear the Marks and Spencer (LON:MKS) CEO quoted in the media with a number of £120m, including £60m from NI. MKS is now included in today's report. They are somehow managing costs very well and have even been upgraded today! Very impressive indeed. G
Marks and Spencer (LON:MKS)
I believe the first signs of bullishness was three years ago (price still around £1) when the ownership of Marks and Spencer (LON:MKS) slowly started to slowly shift from the bondholders back to its shareholders. In 2022 total bond carrying value was £1.4B whereas today is only £700m with more bond repurchases to come. Well done to Marks and Spencer (LON:MKS) management here.
All the best
Indeed Yiannos
Super well run company Marks and Spencer (LON:MKS) with plenty yet to go for. Alas I really only got involved around 240p mark but at c. 400p this year thats not too shabby!!
Anyway I am biding my time currently on Gulf Keystone Petroleum (LON:GKP) as I am just not sure quite how long this is going to take. Agree with you that it will happen in time but in that region things have a habit of dragging on!
Following the government budget of 30 October, taxes and business costs are expected to increase by approximately £60 million, on an annualised basis, in calendar year 2025, including an estimated 67% increase in national insurance contributions.
well yes bearing in mind the employer had complete freebie on paying ANY NI on employees paid below £175 per week previously - obviously the increase will look ridiculously high in % terms when there are plenty of nils to compare to. I dont think anyone does themselves favours cherry picking % increases when there is alot of nils being involved in the lower figure being referenced. The actual cash increase per employeee is chunky enough that quoting that would have done the job. Hey ho the 67% is perhaps a real increase nonetheless compared to the previously much more modest prior comparative. Note the reality here is that if employer pays part timer £10k pa - they now pay £750 employers NI - that 7.5% of salary on top !
Marks and Spencer (LON:MKS) Shore Capital
They've only gone and done it again... Marks & Spencer is probably in its best condition approaching a key Christmas trading period than it has been for many years reflected in a further smashing of both our & consensus forecasts in H1 FY25F; PBT of £408m (SC, £360m, consensus, £361m) including an ORL drag of £16m and near halving of International EBIT. We upgrade FY25F PBT by 9% to £830m, a good Christmas 2024 could mean more still; for now the Group equity trades on a PER of 13.3x, EV/EBITDA 6.4x. Such an ongoing performance can feed rating expansion, which means the M&S share price may just have some way to run yet. The profit doors have been blown off again.
The analyst obviously loves the film the Italian Job.
Really really good results from Marks and Spencer (LON:MKS) from my perspective Dragon
A good Christmas and we could be closing in on 30p eps. Think the re-rate may have quite a bit further to go. I’ve held since around 240p so was a bit late to the party but happy to hold here
I'm glad you posted that davidjhill because from my estimates Marks and Spencer (LON:MKS) should do 30p eps for FY25 which is a beat as far as i can see.
Obviously the management have learnt that under promising and over achieving is the way to go.
SP now over 400p and plenty of blue sky to move into.
Forecasts are around 26-27p I think Helvellyn after today (c. 8%+ on 25p) but that looks a bit light to me based on momentum in earnings at Marks and Spencer (LON:MKS). My own calls have them around 28p and a good Christmas could push that further but let’s see. Irrespective, I’m happy anywhere around 27-30p and see a 15-16* multiple as reasonably valued for such a strong brand.
As Norm MacDonald joked after Hillary Clinton vs Trump. 'The American people hated Hillary Clinton so much, they voted for the only person they hated even more, just to spite her.'
Looks like a rerun. Thoughts and prayers for Channel4 and the BBC at this difficult time.
US futures so far are up bigly.
Thank you Wolf, I laughed so much I split my coffee.
C4 are in trouble already…Emily Maitless effing and jeffing on air when she heard Trump winning :))
I rarely get political on a forum that should be sticking to investments, but is it really that funny that we are going to get a criminal megalomaniac back in the most important seat in the world for global security? I personally think it is a terrifying and depressing prospect that far outweighs a one day gain for equities.
Rather frightening for US facing green investments and possibly for pharma too
Don't worry so, we could be living under Putin or even Xi.
Well the people of America think he will do better job that the other one and thats all that matters. That may not be a ringing endorsement of him if they simply found the other candidate worse but thats free speech and democracy. Note he did actually run the country previously for 4 years - so i for one am not convinced he will be any worse than the other candidate in the round despite not wholly disagreeing with your assertion that he is a "criminal megalomaniac". Not sure what that says about politics ! To be fair to trump he did manage to avoid starting or joining an any wars- new military campaigns - which is probably quite an acheivement for a us president.
The point being made is that apparently professional broadcasters should be able to objectively present news and associated analysis objectively and dispassionately, setting aside any personal political preferences.
While Trump is a morally bankrupt meglomaniac, he is also shrewd - his instinctive acuity made him among the first to warn of the emerging threat from China and further back in the day sniffing out Ali G's attempt to induce him into looking foolish in an "interview".
As I was. Who in their right mind is happy with this result
You forgot the Guardian Wolf.
Good morning Graham, is the summary table being retained in future reports? I'd like to argue the case against, which is very simply that it's useless in mobile. I very like the summaries however which provide a great overview.
Good morning Graham, is the summary table being retained in future reports? I'd like to argue the case against, which is very simply that it's useless in mobile
I’ve never felt that frustrated by it. Surely it can be retained for those that view in a larger format.
I like it on the mobile screen too.
Even Kamala isn't losing the argument by that much. Think I'll gracefully accept defeat and book to see the optician...
I find the summary table useful and readable on my iPhone mini
Works and looks fine on my mobile.
No problem on my mobile.
Graham
It works fine on my mobile (iPhone 15 pro) though a larger font and the “Status/Brief Comment” placed below each company row and occupying the whole row, would make for better readability on mobile.
Personally I would vote to keep the table.
Regards
Michael.
Interesting suggestion Michael, and thanks for the feedback on the table. I'm happy to experiment with font sizes (bigger the better) but an extra row wouldn't be ideal as we need to keep the dimensions as small as possible! Glad to hear it's working fine on your phone. G
Hi Graham
Thank you for your reply. I see it is an image rather than fonts formatted by CSS.
On the dimensions thing, currently the comments wrap to three or four lines where as if given it's own row the comment might be contained to one and at most two rows, so the overall height of the table probably wouldn't change.
Regards
Michael
When I use my phone in portrait mode the print is indeed small.
However, what I do is rotate my phone 90 degrees into landscape mode and voila the print is double the size and it nicely fills my screen and it becomes easily readable.
Problem solved
David.
Reflecting on Megan's review of Asos (LON:ASC) yesterday (thank you!), one simple rule of thumb for retail is to look at who the major holders are. ASOS are slightly over 50% owned by Bestseller and Frasers (LON:FRAS) . If the latter in particular has a stake then it's often a red flag for the companies short term prospects and major change is likely. [I do not hold ASOS or Frasers]
Spectris (LON:SXS) coordinated but substantial director buying yesterday. Nice to be able to comment on mid cap action and not feel it is out of place.
YouGov (LON:YOU) nos contain no surprises....and trading is in line for 2025. Sadly trading is "broadly" in line reflecting slower sales cycle in H224. Nothing to push a rerate argument here. The pick up in Q2-Q3 will be needed to meet expectations and convince investors there isn't something wrong. It's so tempting to tuck away a starter position but it seems somewhat hopeful of a pick up that won't materialise as the economy muddles on. I think we need to know just how second half weighted it is... because a downturn in the economy would not be positive. Having said that the aggressive derating of a previous multi bagger does leave some margin of safety ... which previous holders might find too tempting. I remain on the side lines.
Trading statement out from Conduit Holdings (LON:CRE) today, I have a substantial holding. Difficult to pin down quite what it means but the combined ratio looks to be in the mid 90s, following the hurricanes and other losses. This won't be as good a year as the last, but so far the balance sheet looks to be OK.
In general, this will not be a good year for reinsurers and a shame they have not mentioned anything about involvement in Spain, but thats not within Q3 . I suspect the losses here will largely be swallowed by the well established reinsurers such as Munich and Swiss and of course Mapfre.
Hi Bohenie, on Spain reinsurers should be largely unscathed as Nat Cat is covered under the Goverment Pool Consorcio so very little of the loss will make its way to reinsurers
Thanks for this Rob - Crazy day - Lancs up 10% and Conduit Holdings (LON:CRE) down 10%