Dialight keeps shining with another upgrade, but the good news may be priced in

Analyst’s view:
Roland was moderately positive on Dialight last time, and that stance continues to make sense to me. The company has made enormous progress and appears to be doing everything right. However, that may already be priced in. As of last night, the earnings multiple was over 20x. The metric probably hasn't moved far today, even with the positive outlook statement, considering that the share price has risen by 7%. With a ValueRank of 24, the StockReport also struggles to find much value here. The bottom line is that I think new investors at the current share price will need further upgrades to do well.
Up 7% at 594.3p (£242m) - Half-year Financial Report
We already upgraded our stance on Dialight in September on a strong trading update.
Earnings forecasts have been trending upwards for some time here:
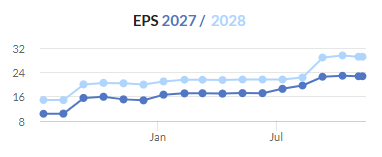
This has fed through to a multi-bagging share price performance over the last two years, from 100p to 600p:
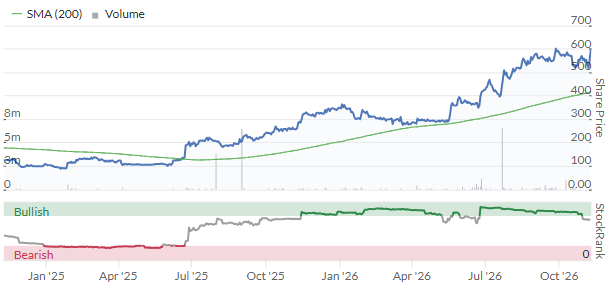
For a company that has struggled in recent years, it's a remarkable turnaround.
New guidance: before reviewing H1, let's highlight that the company has once again raised expectations today.
We enter the second half of the year with a strong outlook and are targeting continued sales growth and gross margins meeting our upgraded guidance. The Board therefore believes the Group has the potential to significantly exceed current market expectations for net income for the full financial year. Subject to wider macroeconomic conditions, we are optimistic also on our medium-term potential.
The company helpfully provides existing forecasts from Investec (PBT $17.3m) and Singer Capital Markets (PBT $17.6m).
A "significant" beat over these numbers should be 10%+ for a company of this size, in my view, i.e. I would look for PBT of $19m+. Although I also note the use of the word "potential" in the above paragraph.
H1 performance: in this report we've often been sceptical of lighting companies - such as Dialight - on the basis that demand is volatile and results are often hit-and-miss. Dialight's own performance demonstrates this:
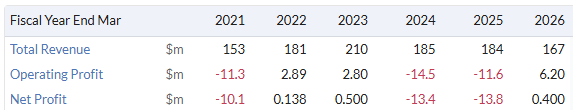
This latest H1 performance, however, shows what the company is capable of:
Revenue +9% ($94.4m), or up 19.8% organically (excluding the effect of a disposal).
Operating profit +152% ($14.9m)
PBT up over 200% ($14.2m)
Another concern here has been the balance sheet. Over the past year, Dialight has swung from net debt of over $10m to net cash of $4.5m.
I often think of lighting companies as selling low-margin, commoditised products. But Dialight is generating solid and improving gross margins - up from 35.3% in H1 last year to 39% in the current year.
These results also benefited from "pricing discipline" in its main Lighting division, which helped to drive revenue growth to over 14.4%.
In its Components division, growth was even better at 37.5%, "driven by a new strategic focus on the OE product line".
CEO comment:
“The Group continues to realise the financial benefits of all five pillars of the Transformation Plan, which have underpinned the significant improvement in performance over the past three years. We are continuing to deliver profitable sales growth and strong cash generation, and reaching a positive net cash position is an important milestone for the Group..."
Tariffs: Dialight primarily manufactures in Mexico, and its products are "tariff-free under the United States-Mexico-Canada Agreement free trade agreement". The impact of tariffs on products imported from elsewhere is "negligible".
Capacity: the Mexican operations are " currently operating at less than half theoretical capacity", providing enormous scope for continued growth.
Financial metrics: Dialight has achieved all of its target financial metrics in H1. It will of course be important to see that they are also achieved for the full year:
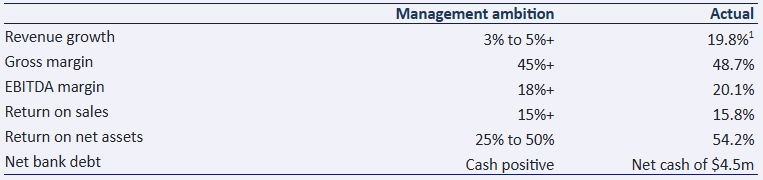
A few points stand out.
Firstly, the fact that revenue growth is so much higher than target should be a big clue that it's not sustainable.
As for the other metrics, the ones that stand out to me are return on sales (the name the company uses for operating margin) and return on net assets (the name the company uses for operating profit divided by net assets. This is similar to ROE and annualised).
These are high-quality metrics to focus on, the company is achieving excellent numbers with them, and it is doing so cleanly. They even charged share-based payments ($0.5m) before calculating these metrics, which I fear that many companies would not do.
As for non-underlying costs, there were none in H1, and only $0.4m in H1 last year.
The one obvious negative in the performance is the increase in inventories from $30m to $36m, but I wouldn't punish the company for that during a period of organic growth. There's also been a slight increase in its "aged inventory provision".
Balance sheet: total net assets of $55m with only $8m of intangibles. The company did benefit from capitalising $1.2m of spend on intangible assets, but this was offset by a $1.2m amortisation charge.
Graham's view
As you may be able to tell, I'm warming to this one. Of course the share price has already multiplied several times, and it's no surprise that performance is excellent at this stage after a long series of earnings upgrades.
Roland was moderately positive on Dialight last time, and that stance continues to make sense to me.
The company has made enormous progress and appears to be doing everything right. However, that may already be priced in. As of last night, the earnings multiple was over 20x:
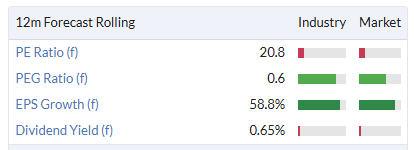
The metric probably hasn't moved far today, even with the positive outlook statement, considering that the share price has risen by 7%.
With a ValueRank of 24, the StockReport also struggles to find much value here.
The bottom line is that I think new investors at the current share price will need further upgrades to do well.
That is certainly possible, considering the availability of additional capacity in Mexico. And that's why I am going to stay at least moderately positive here. But given the historical riskiness of this sector and the high earnings multiple, I think it would be imprudent to go any higher than AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Dialight (1)
Comments here are also visible in the Daily Stock Market Report
Dialight (LON:DIA) . Sorry Ed and for the sake of consistency I had to pick you up on this.