Does the Prudential's Asian growth story mean it's a good investment?

The stock market can be a funny old place. One day (last week actually) you might look at the price of Prudential, the FTSE 100 listed, multi-billion pound global insurance and financial services giant, and see that it’s valued at £17.8 billion. Then a few days later, it announces some positive results for the previous year, including rapid growth in Asia and, hey presto, the market value of the company increases by some £2.2 billion, or 12%.
Okay, so some of that gain came before the latest results in anticipation, but a change in value of £2.2 billion in a week? That’s a pretty big swing.
So were investors right to jump in on the back of these results?
We all enjoy a good-news story, but it’s another thing entirely to base investment decisions on such short-term and potentially short-lived results. So let’s step back a bit and look at how existing shareholders have faired in the last decade.
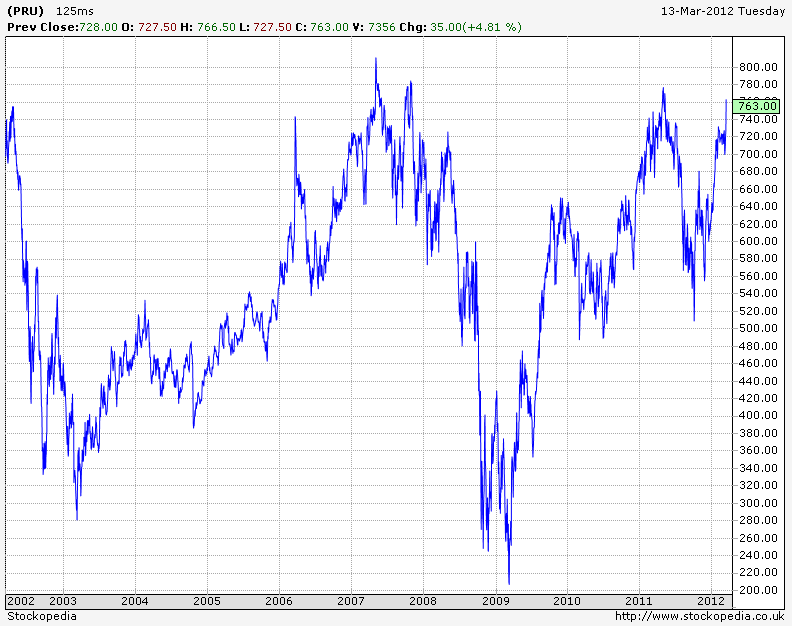
That’s one seriously bumpy ride, especially if you though you were buying a boring and safe blue chip. As you can see, those investors who were brave enough to jump in when everyone thought it was the end of the world (early 2009) have made a colossal amount of money. They may be tired old clichés, but “being greedy when others are fearful” and “buy when there’s blood in the streets” are as close to Newton’s Laws as investors are ever likely to get.
Over this 10 year period the share price, despite the massive swings in value, have gone precisely nowhere. So the next question is;
Can the investors who are piling in today expect anything better?
Of course I do not have a crystal ball, but then neither does anyone else. The next best thing is to understand what drives investment returns in the long-term, and to have the discipline to avoid getting caught up in the random noise which the financial media generates every day.
Returns driver #1: Growth
The first driver of long-term returns is growth. Unsurprisingly, those companies that can continue to grow for years and even decades, will tend to have better share price growth in the long-term than those that can’t.
Growth can be measured in various ways but I prefer plain old earnings growth; and a little dividend growth doesn’t hurt either. The table below shows both Prudential’s earnings and dividends over the last 10 years:

These results show a fairly typical history, with peaks and troughs in earnings and dividends. Overall the trend does seem to be upward, although the earnings growth figure over these 10 years comes out at something like 17% a year, which is skewed upward by the poor results near the start of the period. This was a difficult period for many insurance companies as the previous easy money from equity investments evaporated once the dot com bubble burst.
If I look back just a couple more years to the previous peak earnings in 2000 then the growth rate since then is nearer 7%. The median growth rate for the companies I track is 7.5%, so it looks like the growth rate is about average in the long-term.
Returns driver #2: Valuation
Finding a good company is only half the battle. To really beat the market you have to buy low, and that’s where valuation comes in. Although looking at today’s PE ratio can be helpful, a much more useful measure is PE10, the price relative to the company’s 10 year earnings average.
The general guideline is to avoid paying more than 20 times the earnings average. In the past decade the Prudential has earned an average of 43p each year. The price in the chart above is 763p, so that that price investors are paying almost 18 times the 10 year average earnings.
That’s pretty much bang on the median value that I have for the almost 200 medium and large-cap stocks that I track. So in terms of valuation, the Pru is once again Mr Average.
Of course, if you’d bought in around 700p in the week before the price explosion then you would have been paying just over 16 times the earnings average and, while that’s not spectacularly cheap, it’s always better to pay less.
Returns driver #3: Dividend Yield
The yield at 763p is about 3.3% which, much like the PE10 value of 18, is very average. It’s about the same as the median value of the stocks that I track and it’s also about the same as the FTSE 100.
Investors who are looking purely for yield would probably find more attractive opportunities elsewhere. And speaking of looking elsewhere:
How does the Prudential stack up against other large-caps?
By now you probably won’t be surprised if I say that I think this one is very average. The valuation is average, the yield is average and the growth average for medium and large-cap companies.
My watch-list has the company down in position 73 out of 192 which is skewed slightly by that misleading 17% growth figure, but even then it certainly wouldn’t be on my ‘hot’ list, it’s on more of a ‘warm’ list, waiting for the share price to drop to give a better entry point.
Would an index tracker be better?
As a stock picker I have to think that every investment I make is going to turn out better than the index tracking alternative, otherwise why should I both with all the work and the additional risk of investing in individual shares?
That’s why every time I pick a stock I compare it to the index. In this case the comparison comes out like this:
If I put 7% in the growth column above then you’d see that the Pru is really very similar to the FTSE 100 in terms of potential.
The key difference is that as usual, the stock of an individual company are more risky than an index tracker. The risk of things going badly are higher, but the higher share price volatility also gives the opportunity for better medium-term results if you can time it right.
So in summary, I wouldn’t personally bother with the Prudential at the moment, Asian growth story or not. It’s a good company and so a fall in the share price might change that, but at current levels there are more attractive fish in the sea.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
5 comments
Thanks for the detailed reply.
Sometimes I look at stocks I sold or did not buy that subsequently increased significantly in price and try and examine what mistake I made or what caused me to not buy/sell what would have turned out to be a good investment and whether I could have stopped myself from not buying/selling too early.
Two examples:
I bought £F for my sons JISA (the overriding rule for his JISA is that I will never sell a stock I have purchased and I have to be able to justify the purchase to his mother!) but I toyed with £AMZN. But even though I am a committed user of Amazon I could not bring myself to buy £AMZN at the valuation. £F is down 9% and £AMZN is up 300%. I have learnt that I should go with my convictions even if the market is valuing a stock "too" highly. I am still looking to buy £AMZN and have taken a small position for my own portfolio so that I can keep an eye on it.
I bought Signet Jewelers (LON:SIG) (having heard about it on Bloomberg TV) and when nothing had happened in 9 months I sold only to miss out on a 100% rise. I learnt that I have to have patience if I have bought stock out of conviction and nothing has changed since buying it. I am much more patient now!
So I was wondering if you ever look back at stocks you didn't buy that subsequently appreciated to try and understand where your analysis went "wrong" so as to refine your analysis in the future?
Also is there anything you can do about the graphics in the article?
Thanks.
.
The Stockrank is now 18. I agree it does not look good. I bought some after Brexit, thought they were oversold and much of their revenue is from overseas, since Brexit the share price has gone form 1100 to 1400, so a 27% increase. My problem is they seem to have quire a bit of exposure to UK stocks, since buying them I'm always getting alerts about their holdings, also they own M&G, so I'm considering selling them soon.
none of the images in the article are visible!
Hi John
Interesting read which I have only just come across. I bought Prudential (LON:PRU) in May 2010 and re-invested my divis. I sold a bit late but still made a healthy 100%+ profit. This was only a small investment as it was early in my investing journey.
From the date you wrote the article the stock climbed steadily from 700 ish to around 1700 before pulling back to where it is now at around 1400.
Do you think your assessment was wrong back in March 2012 or has the market pushed the price up to an unsustainable level for no valid reason. Stockopedia Stockrank is an awful 11.
At the moment I have no intention of buying back into the stock.
Thanks.
Michael
Hi purpleski
I haven't looked at Pru in detail for a long time, but going purely by the numbers it ranks very well on my stock screen at 1400p (21st out of 233 dividend-paying stocks).
There are a few reasons for this increase in attractiveness, despite the share price doubling:
First, I've added a few bits to my screen that factor in 1) growth quality, i.e. consistency, and 2) profitability, i.e. ROE in the case of insurance companies.
Prudential scores well for both growth quality and profitability, which will make it look more attractive at a given valuation multiple than a less consistent, less profitable company.
Second, its growth rate has picked up from the 7% mentioned in the article. The 10-yr growth rate I have for it now is 12%, and higher growth also makes stocks look more attractive on my screen.
Third, the price has doubled, but book value, earnings and dividends have all gone up substantially too, although they haven't doubled since 2012.
One other thing is that it isn't a purely 'defensive' stock as it's an insurance company and so probably has some exposure to markets via its invested insurance float. Haven't look at that in detail though and there was no dividend cut during the financial crisis.
So without going deep into it, the company now looks like a high growth, high consistency, high profitability company that is trading on a reasonable valuation, although it does operate in a cyclical sector. The combination of reasonable valuation and high growth/quality makes it attractive (to me), at least quantitatively.
But as I say I haven't looked under the covers in detail, so if there are any hidden gremlins then I haven't factored them in.
- John