dotDigital - SaaS Quality on a single-digit P/E

Yesterday, I wrote an article looking at how investors may be able to find companies largely unaffected by recent global events, trading at bargain prices, due to investor flows out of smaller companies.
It may be surprising to see a few software companies on the list of cheap companies. However, recent concerns about the impact of AI, together with general market weakness for smaller companies, mean that several appear too cheap to ignore. Having never looked at dotDigital before, I was keen to see if it lives up to the initial promise of a high-quality, cheap and growing business. What better way to take an initial look than writing it up as one of our new shorter Stock Pitches.
Disclosure: At the time of publication, I have no position in dotDigital.
The Pitch
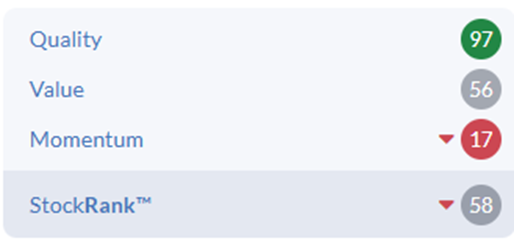
dotDigital (LON:DOTD) is an AIM-listed marketing automation SaaS platform founded in 1999, providing AI-powered customer experience solutions to 4,000+ brands across 150 countries. With a £140m market cap, this is a small but not insignificant business. The StockRank is unimpressive, being let down by an average Value Rank and a declining Momentum Rank:
However, the company has a strong growth track record, delivering a 12% CAGR in revenue over the last 5 years. 2026H1 showed contracted ARR up 13% to £75.4m (+6% organic) with recurring revenue at 84% of the total.
The company says it is trading in line with expectations, which would put its forward P/E at just 9 based on the current broker consensus. This seems low for a company with high recurring revenue, an excellent growth track record and strong cash generation.
The Big Picture
dotDigital stands out for several reasons:
- Quality SaaS Metrics: Recurring revenue at 84% of the total provides good forward visibility. 2026H1 average revenue per customer increased 7% to £1,968 per month.
- Earnings-Enhancing Acquisitions: The acquisition of Social Snowball in June 2025 brought 1,500+ Shopify customers and $5m+ in run-rate revenue. The platform achieved 200% revenue growth to $3m in 2024 and became cash flow positive in H1 2025. ARR was up 30% annualised since completion, with significant cross-sell opportunities. US-based SaaS platform Alia was acquired this month, adding another $8m in ARR. Again, this acquisition creates additional opportunities for retention, cross‑sell and upsell across the Group's customer base.
- Blue-Chip Customers: FY2025 wins included KFC, New York Botanical Gardens, The Royal National Ballet, FujiFilm, The Body Shop, and BBC Children in Need. International regions now account for around 30% of revenue, with North America delivering approximately 28% revenue growth.
- Strong Cash Generation: Despite the $20m acquisition of Social Snowball, cash stood at £36.1m at the Half Year, reflecting continued strong cash generation. Post period end, $30m was spent on the Alia acquistion, but this still leaves them with net cash. A progressive dividend policy saw the FY2025 dividend rise by 10% to 1.21p. The dividend is forecast to rise again this year, putting them on a prospective yield of around 3%.
Going Deeper
Several factors suggest that dotDigital will continue to perform well:
- Platform Consolidation Trend: CEO Milan Patel noted customers are consolidating around "fewer, more capable systems" with clear ROI demands. dotDigital's integrated CXDP meets this need. Management stated: "With AI, data and mobile messaging advances, plus Social Snowball and Fresh Relevance, our CXDP is broader and more valuable than ever."
- Double-Digit ARR Growth: H1 FY2026 contracted ARR was up 13% (6% organic) to £75.4m on an annualised basis. Core CXDP recurring revenue accounted for 84% of total revenue, up from 80% in the prior year, demonstrating improved revenue quality.
- Influencer Marketing Expansion: Social Snowball positions dotDigital in the fast-growing influencer, affiliate, and referral marketing space. This "significant new market opportunity" expands beyond traditional email/SMS automation into a high-growth adjacent category with 1,500+ cross-sell targets.
- Higher-Value Pipeline: The Group entered FY2026 with a "broader product suite, higher-value pipeline and expectation of continued sustainable growth." High retention and expansion demonstrate the strategic value clients place on the platform.
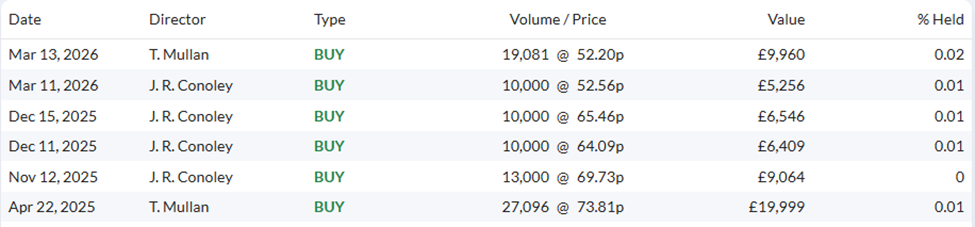
- Director Buys: While the amounts are relatively small, directors have been consistent buyers of stock over the last year:
What The Brokers Say
The analysts who cover the stock rate it a Buy. Cavendish comes in with a whopping 150p price target, which, if achieved, would see the share price more than treble from where the shares trade today. Canaccord raised its forecasts following the recent acquisition and set a 135p price target for the company, noting the consistent discount relative to UK SaaS peers and global marketing Technology companies.
Sales are expected to continue growing at double-digit rates, with a free cash flow yield in the high single digits.
The Bear Case
Despite quality metrics and analyst conviction, several risks remain:
- Profit Pressure: H1 FY2026 adjusted EBITDA down 7% to £12.8m, adjusted PBT down 12% to £8.7m despite 4% revenue growth. Administrative expenses grew 12% to £27.1m. Margin pressure is likely to continue.
- Questionable adjustments: In providing the numbers, the company hopes we would exclude ongoing share-based payments. Plus, their exceptional costs look anything but exceptional as they occur every year.
- Acquisition Execution Risk: Social Snowball requires integration with an additional $15m earnout over two years. Alia cost them an upfront payment of $30m, and they could be on the hook for a similar earnout cost. These acquisitions are not cheap unless they deliver the significant planned growth.
- Strong Comparatives: Management noted that H1 delivered against a strong comparator, indicating that the prior year benefited from exceptional performance. They note that customers remain cost-conscious, which may continue to put H2 margins under pressure.
- Marketing Weakness: While the company argues that it delivers clear ROI for customers, global marketing spend has been constrained. This may limit the ability to win new business or push through price rises to existing customers.
The Bottom Line
dotDigital is a high-quality SaaS business trading at a discount to market peers and broker price targets. 84% of its revenue comes from high-quality recurring sources. Contracted ARR was up 13% (6% organic) on an annualised basis in H1, demonstrating the continued ability to generate revenue growth.
However, there is no escaping their position in selling to the marketing industry. Industry weakness and cost pressures mean that significant new sales and price rises will be difficult to deliver, despite clear ROI from deploying their platform. H1 EBITDA declined 7% against a strong prior-year comparator, and PBt was down 12%. Admin expenses rising by 12% and margin compression mean some may be sceptical about their ability to deliver their full-year forecasts of around 5p EPS.
Recent acquisitions add both recurring revenue and significant cross-selling opportunities, but they were not cheap. These businesses will need to be integrated and deliver on planned growth to prove shrewd investments. Cash generation is strong, and with the cash balance expected to be rebuilt over the next few years, the ability to accelerate growth via further strategic bolt-ons remains.
The key question is whether recent weakness represents a temporary integration-related dip or a deterioration in fundamentals. If it is the former, this looks too cheap for the market to ignore for long.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
From Jan 2021 to Sept 2021 price ranged from 170 to 271 before heading south and it continued going south eever since ,probably worth a punt at the current level.
I can't see that they have much of a moat. Existing customers would have to get used to using a different way of sending out marketing emails and texts, but they would have an incentive to do so if it means paying a smaller fee to Anthropic instead of the subscription to DOTD. I'm sticking with companies that have proprietary databases for the time being.
I see today in a RNS they appointed a "Chief Revenue Officer role is a newly created Group position, established to bring all global go‑to‑market functions together under unified leadership as the Group continues to scale internationally." Maybe due to the go to market hitting the margins in h1 perhaps & needing more of a hands on approach? I haven't heard of any of the Companies he has worked for - maybe those close to the IT / Marketing industry may have?
Thanks good write Mark! Have you looked at Pinewood Technologies (LON:PINE) at all?
Thanks.
Not looked at Pinewood in detail, but on the surface it is not growing, or high-quality and certainly not cheap on a EV/EBITDA of around 27!
I know it has its fans, but it would have to fall a lot further for me to even consider looking at it when there are many cheap growing companies that meet these screen criteria, sorry!
A few thoughts, questions.
Are they vulnerable to the SasSmagedon by AI as they seemed to have sold off this year like others in this space? Seems to suggest the market thinks so.
Directors buying pretty small doesn't seem that significant.
Acquisitions seem to have diluted their returns (ROCE & ROA) - so they may be earning enhancing as they are paid for with cash flow, but are they just buying growth? Seem to have paid up for quite young US Companies.
Allied to that they mentioned that something called "Social Snowball go to market investment" was also behind some of the margin decline, although this is supposed to benefit h2. Not sure what that is even? So does the growth there come at greater cost than they figured?
Someone else mentioned institutional selling - I know Liontrust are big holders and they have been struggling with outflows so guess that could continue to be a drag on the share price.
Momentum awful as you noted - so definitely one for Contrarians as labelled by the Stocko algo.
After spending the last 20 years in the software business, I think Saasmagedon is overdone. Clients will continue to pay for software provided it delivers a clear RoI. I have taken a small position in dotDigital (LON:DOTD) hoping for one of two possible outcomes: (a) the management executes well and the market comes round to valuing that forward revenue sensibly or (b) DOTD becomes a target for a US predator or is taken private. Fingers crossed!
Widely used throughout Universities in the UK to assist with marketing campaigns to engage with and attract students
AI will kill most university degrees and debt will kill the rest. Sorry.
As Alan Partridge says, "Wikipedia makes a university education utterly pointless." ;-)
Don’t be, badly managed, poorly run, overstaffed, riddled with debt. It’s only in the aftermath of changes to Visa rules has the penny dropped and pointless degrees in tourism etc. are being canned as student numbers dwindle. Some companies will only appoint people with degrees, but not just any degree from any Uni.
Maybe this will impact the revenues of dot digital and another one widely used , Tribal
The Dead Kennedy's wrote a song in the mid 80's ("Soup is Good Food") that "machines will do a better job than you" they were either visionary of ahead of themselves on thinking about the risk of computers to Human Work. AI will help improve productivity and development, I'm sure but won't take over the world.
Might want to look at Platform SE & Co KgaA (ETR:TPG0) . Super cheap. Been hammered recently but results continue to be good.
looks interesting.
Hace held this for a year and now 60% down. I do understand the bear points but it doesn’t make any sense
Ditto. Smaller caps in Germany seem to be even more out of favour than in the UK. Real businesses with profits trading at very very low valuations. It would be very interesting to have the Stockopedia team look at the sector.
Can't believe the fall in SAP's price...
There’s been quite a bit of institutional selling which may have also weakened the share price recently