DUG: petaflops of power

A small company based in Perth, designs, builds, owns and operates some of the most powerful computers on the planet. DUG Technology (ASX:DUG) has facilities in Perth, London, Houston and Kuala Lumpur. Across these they have 30 petaflops of data processing power and over 43 petabytes of data storage capacity.
DUG’s supercomputers are used for high performance computing which involves using supercomputers and parallel processing techniques to solve very complex computational problems. For example, they worked with a satellite provider that provides agricultural analytics to enhance crop management. The data-processing tasks previously took weeks but using DUG’s services can be completed in hours.
DUG have also developed a patented cooling system that enables them to operate more energy efficiently. Therefore their supercomputers are not only some of the biggest, but also the greenest. This is demonstrated by the chart below.
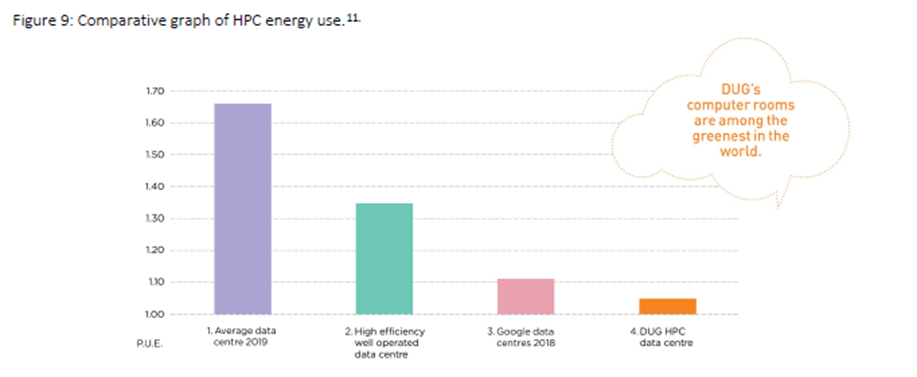
Source: DUG Technology Ltd, Prospectus, 10 July 2020
DUG have traditionally generated most of their revenue by servicing the oil and gas industry. This continues although they are also diversifying their revenue sources. They provide oil and gas companies with geoscience and seismic data processing. Seismic surveys enable geoscientists to visualise and interpret the subsurface of the earth. It requires the processing of large and complex datasets.
DUG’s revenue is broken down over three segments, services, software and high performance computing. Services accounts for about 80% of total revenue and is largely derived from geoscience and seismic data processing. US$25.2 million of the US$40.3 million revenue in this segment in FY23 was derived from the Houston office, servicing Middle East clients as well as US clients.
Revenue grew strongly in FY23 to US$50.9 million from US$33.8 million. This was driven by 70% growth in the services segment with modest growth in the other two segments. However it should be noted that in 2019, prior to listing, they generated US$52 million in revenue.
However importantly, FY23 also saw a record profit, and the first time they have made a profit since listing.
This strong performance is reflected in the StockRank score of 84.
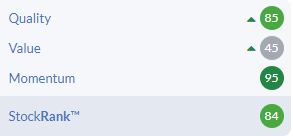
DUG’s Quality Rank has risen to 85. This is due to the high Health Trend and low Bankruptcy Risk as well as strong returns and margins. The net gearing ratio is 36%, inclusive of lease obligations.
The EBITDA margin went from 8% to 30% as revenue grew 51% while growth in expenses was contained under 12%. EPS went from negative to positive and Forecast 12 month rolling EPS growth is 86%. They are also generating strong cash flow with their operating cash flow to EPS ratio at 4.1.

The Momentum Rank is very high at 95. The share price has gone from 50c to $1.90 this year, with Relative Strength of 100% over the last six months.
The Value Rank is low at 45, but given the rapid growth in the share price that is still a reasonable level. A forecast PE ratio of 17.5 ranks ninth in the Software and IT services market.
The outlook is also bright. In July they took in record Services orders of US$18.6 million increasing the Services order book to US$42.2 million at the end of July. A lot of this growth is being driven by Multi Parameter Full Waveform Inversion imaging which can replace traditional processing and imaging of seismic data. This new technology is gaining traction with oil and gas companies as it reduces the processing time from about 12 months to five weeks.
They have also received grants from the Western Australian government including $5 million in funding to develop a new $10 million facility in Geraldton. This data hall will have 400 petaflops of capacity. They are also adding additional hardware in Houston to support projects there.
DUG is led by its founder Matthew Lamont who retains a shareholding of over 20%. Founder CEOs with a significant shareholding are usually well aligned with small shareholders who have a long-term, patient view.
DUG is competing with some of the world’s largest technology firms so they need to have an edge in terms of technology and efficiency. There is evidence to suggest that is the case, particularly in their niche of seismic data. Their ability to market their edge and expand into other areas will be critical to their future growth.
It would be easy to jump on board DUG as a play on the AI bandwagon. There is no doubt that AI will have a significant role to play in the future. However it is worth noting that an investment in DUG is not one based on hope of great things to come. They are a profitable business right now, and most of their revenue does not rely on AI applications. That said, AI is very computing resource intensive and they are well positioned to capitalise on that. DUG is worthy of consideration as an investment based on its business today, with one eye looking to the blue sky potential of tomorrow.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
I've noticed the the SP has been very resilient during the September downturn. Hopefully a sign that there is very little selling pressure and perhaps another upleg on the way.
Until today. Pennant broke to the downside, albeit on low volume.