ECO Animal Health: performance in H1 FY27 hurt by China challenges
Analyst’s view:
Today’s update from ECO Animal Health hasn’t been received well by investors and it’s easy to see why. As a result of challenges in China, the company now expects FY27 group revenue to be below market expectations.
Down 12% at 83.8p (£64m) - Trading Update and Notice of Interim Results
ECO Animal Health Group, a global animal health company developing and marketing branded veterinary products to improve livestock productivity and welfare, has posted a trading update for the six months ended 30 September 2026. It tells us:
Trading in the first half of the current financial year was in-line with the Board’s expectations and as outlined in the Company’s Annual Results for FY26 announced in July 2026.
Revenue growth of 6% has been achieved over the prior-year period excluding China, with revenue growth of greater than 50% in South and South East Asia.
In China, low pork prices resulting from an excess of supply have led to producer losses and a consequent reduction in expenditure on animal health products. As a result, ECO expects to report a significant reduction in revenues from its China and Japan geographical segment which will result in half-year Group revenues of £33 million (H1 FY26: £39 million).
Despite the reduction in revenues, the Company expects to report a further improvement in gross margins to c.52% for the period (H1 FY26: 49.6%) which, together with continued cost control, will result in adjusted EBITDA of c.£3.0 million, consistent with the first half of the prior year (H1 FY26: £3.0 million).
Earnings per share is expected to be strongly favourable compared with the prior year due to the exclusion of the minority interest in the China segment.
Cash as at 30 September 2026 was £24 million, in line with the Board’s expectations.
“As previously announced, trading in the first half of the year has been impacted by a pronounced trough in the pork cycle in China. However, a strong performance in other regions and our continued efforts improving gross margins are expected to deliver half year adjusted EBITDA in-line with the prior year, with market conditions expected to improve during H2. With the continued ramp-up of ECOVAXXIN® MS sales in the EU and further progress expected across our portfolio of innovative new products, ECO remains well positioned for our next phase of growth.”
In terms of the full-year outlook, it says:
The Board expects that adjusted EBITDA will be broadly in line with market consensus.
Earnings per share is also expected to be broadly in-line with market consensus.
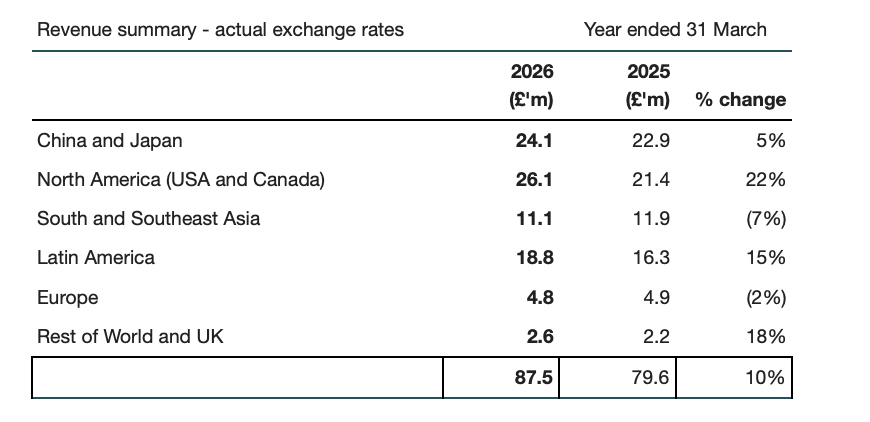
Whilst the Board expects an improvement in China in H2, full-year revenue for the China and Japan segment is likely to be less than half of FY26 (FY26 revenue here was £24.1 million).
Weaker trading in China is expected to result in a shortfall in group revenue compared to market consensus.
Note that it provides this market consensus: As at 5 November 2026, the market consensus for revenue and adjusted EBITDA for the year ending 31 March 2027 was £89.6m and £8.5m respectively. Market consensus for earnings per share was understood to be 3.30p.
Ed S’s view:
We previously had ECO Animal Health on an AMBER/GREEN rating. After this update, however, I think it’s appropriate to take it down a notch to AMBER.
The company is clearly experiencing some major challenges in China. This is an issue because the China and Japan segment is responsible for a large chunk of its revenue as the table below from FY26 results shows:
The company explains that national pork wholesale prices in China have taken a hit recently leading to lower levels of sow breeding. It adds that a reduction in supply will provide a foundation for an expected recovery in prices in 2027 and that its revenue prospects in China should improve.
“China’s national pork wholesale price declined steadily through the spring, reaching a low of approximately 14.3–14.5 CNY/kg in late June early July, before recovering to 16.40 CNY/kg by mid-September on festival pork meat stocking. This recovery has since partially unwound, reaching 15.49 CNY/kg in the week to 1 November (approximately 6% below the September peak and 13.8% lower year on year). The supply side is now adjusting quickly to these lower prices. The breeding sow herd fell 10.7% year-on-year to 36.0 million head at the end of September, indicating a material reduction in future supply and providing a foundation for an expected recovery in prices in 2027.”
In the near term though, the challenges in China are going to hurt its financial performance. It now expects group revenue of £33 million for the first half of FY27 versus £39 million in H1 FY26.
Meanwhile, it says that the weaker trading in China is expected to result in a shortfall in full-year FY27 group revenue compared to market consensus. The market was expecting £89.6 million here.
On the plus side, it says that gross margins are expected to continue to increase, which combined with continued cost discipline, is expected to mitigate the impact of lower revenues. It also says that it expects FY27 adjusted EBITDA and EPS to be ‘broadly in-line’ with market consensus, so the update is not a complete disaster.
One other positive from the update worth highlighting was growth in South and South East Asia. Here, it experienced year-on-year revenue growth of greater than 50%.
Overall, though, I see too many negatives to keep the stock on AMBER/GREEN:
FY27 revenue is going to miss expectations due to the China issues.
FY27 revenue is likely to be below the figure in FY24 so there’s little top-line growth here at the moment.
The stock looks quite expensive – the forward-looking P/E ratio is 24 using the current EPS estimate of 3.51p.
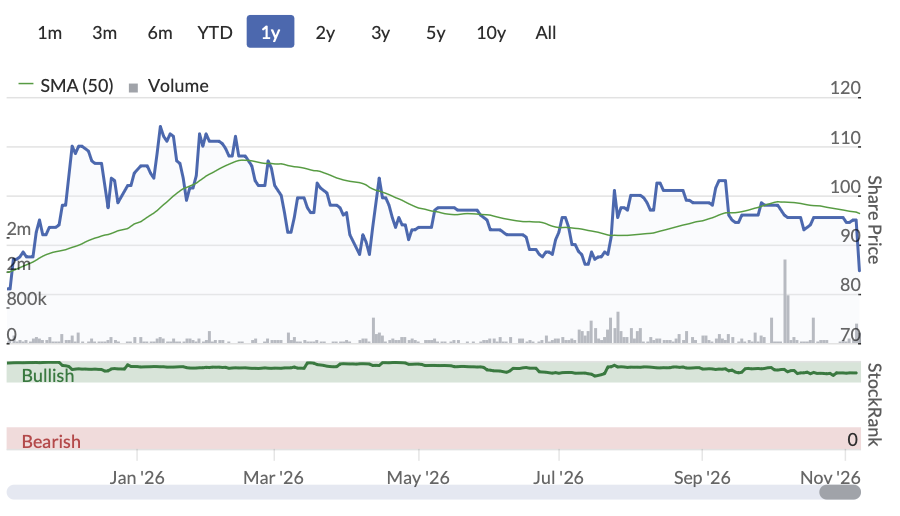
The technicals are becoming ugly – the stock is now below its 50-day and 200-day moving averages.
The StockRank is trending down – it was 98 in April but is now 86 (and will probably fall further).
So, I’m going to take EAH down to AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on ECO Animal Health (7)
Comments here are also visible in the Daily Stock Market Report
Might be the cynic in me and I am being unfair but I cant recall EAH ever having put out a trading update or results announcement on a friday. Which just so happened to be dominated by world news and stock market frenzy…….
ECO Animal Health (LON:EAH)
Doesn’t seem to be too much stuff that isn’t affected by these events nowadays , wouldn’t you say rm ?
You have to understand the eco business model to understand the specific risks they have - they are hugely elevated in comparison to normal stuff. they were a great buisness back in the day for whatever reason they have beena praetty terrible buisness since like 2021 - if you compare to the point they got to growing profits each year.
they have had sweet spot recently compared to their low point - so i kinda get that some wil be suckered into thinking this is sound low risk buisness that is growing nicely and trending to greater things - Meatloaf would say two out of 3 aint bad - but here the fact its high risk well that needs to be understood.
thats kinda key with every company how well will they manage when stuff goes against them - trust me when i say Eco wont always have plain sailing ref their fortunes as is evidenced by reaction today - note the actual issues today inthemsleves are huge and dont massively affect then investment proposition. they do evidence the kinda shit that can and will go wrong with this company.
Note overall i think if they keep plugging away theymay get some of the former glories back at some stage - whetehr than may be in 12 months time - 5 years time or 10 years time well thats the tricky one.
Note anyone who is surprised by the news today should be - this company has a long history of similar stuff like this .
ECO Animal Health (LON:EAH) (I hold)
Morning Graham,
Please can you review the trading update from ECO Animal Health?
I hold it as part of my NAPS portfolio.
Thanks, Richard
yes I expect us to cover that one today, Richard! Ed Sheldon is here too. G
ECO Animal Health (LON:EAH)
todays update kinda sums up the company in a nutshell - i take the viewpoint they are too much academics job for lifestyle brigade. I dont want to over knock them sometimes you gotta leave the nerds to work their magic and that pasy dividends long term. facts are though they are only half of 1/3 of the company they were pre covid times. ok the numbers have ben slowly trending upwards but its basically 5 years in the wilderness - how long do you give a company before you say well the default seems to be that the workers simply seem happy to have their job and do their nerdy stuff.
I wont knock then potential here - clearly if they they can find their mojo upside could be great - and they could kinda hit mini jackpot that there is nice potential to muti bag - so perhaps not the worst share to be bottom fishing with if you are happy.
Just seems to be much simpler stuff to invest in where you arent gonna get bad news simply due to random worldwide events - seems like all tehn revenue they have ever had in china simply exits the door to partners or whatever (that may be unfair perhaps) - would love to know if overall they have actually got net funds out of china or not.
“you arent gonna get bad news simply due to random worldwide events”
Doesn’t seem to be too much stuff that isn’t affected by these events nowadays , wouldn’t you say rm ?
All of my holdings ( many of which I appear to share with you ) have had a bizarre few days thanks , apparently, to the US mid term elections results.
All of them( whichever sector ) have been impacted to some extent by a series of unpredicted events happening, from Covid to Ukraine, from Iran v USA to Reeves/Starmer thinking it would be a good idea to wallop business continually .
It feels to me that most of my holdings (many of which are AIM listed) simply get dragged down by the noise even if the link to the ‘event’ is not that obvious.
On the positive side, at least many of them do subsequently bounce back which hopefully is a sign of a good and resilient business.
Maybe I just need to review my portfolio diversification which may not be a strong as I thought it was and add a couple of your “simpler stocks “
ECO Animal Health (LON:EAH)
Doesn’t seem to be too much stuff that isn’t affected by these events nowadays , wouldn’t you say rm ?
You have to understand the eco business model to understand the specific risks they have - they are hugely elevated in comparison to normal stuff. they were a great buisness back in the day for whatever reason they have beena praetty terrible buisness since like 2021 - if you compare to the point they got to growing profits each year.
they have had sweet spot recently compared to their low point - so i kinda get that some wil be suckered into thinking this is sound low risk buisness that is growing nicely and trending to greater things - Meatloaf would say two out of 3 aint bad - but here the fact its high risk well that needs to be understood.
thats kinda key with every company how well will they manage when stuff goes against them - trust me when i say Eco wont always have plain sailing ref their fortunes as is evidenced by reaction today - note the actual issues today inthemsleves are huge and dont massively affect then investment proposition. they do evidence the kinda shit that can and will go wrong with this company.
Note overall i think if they keep plugging away theymay get some of the former glories back at some stage - whetehr than may be in 12 months time - 5 years time or 10 years time well thats the tricky one.
Note anyone who is surprised by the news today should be - this company has a long history of similar stuff like this .
The investment thesis hasn't changed here IMO.
Long pipeline of "de-risked " / funded medicines.
It's a multibagger, but I'm prepared to hold until 2030 to see big returns.
Yes, a lot of cash is held in China.
I'm looking out for ROW segment to increasingly contribute to revenues.
I think the company have said that too.