ELTA - Share Idea - an off-the-radar (and cheap) way into TGI Fridays & Hotter Shoes

Share Idea
(by Paul Scott)
Electra Private Equity (ELTA)
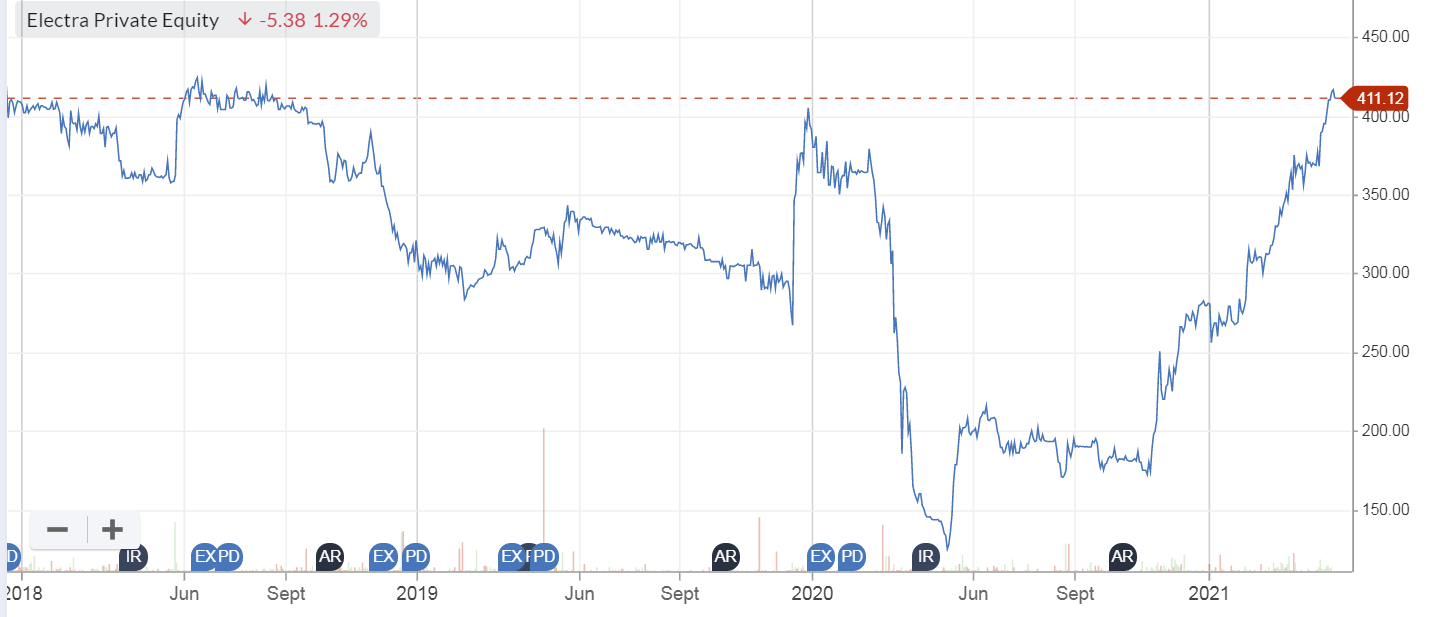
Share price: 410p
No. shares: 38.28m
Market cap: £157m
I’ve recently been looking for new ways of buying into the re-opening trade, of retailers, restaurants/bars, travel, etc, but most things look too expensive now, with upside already priced-in.
However, I’ve found something a bit obscure that looks cracking value, for 2 very nice businesses. The main one being the UK operation of TGI Fridays, the well-known casual dining chain. The other business is called Hotter Shoes - a now mainly online comfortable shoes company for the over-50’s. Both are owned by listed investment trust, Electra Private Equity (ELTA). Both businesses restructured during the pandemic, and seem to have promising futures.
ELTA was flagged to me by a friend who has demonstrated a long track record of being a highly successful investor in special situations, hence why I was keen to take a look.
After doing my own research, I found that ELTA is a simple share to understand, and I’ve bought an opening position myself, with the intention of holding until c.end 2021, when the winding up of this company is planned to complete. Add on mabe another 6 months to be safe, as many such things take longer than expected.
I think ELTA could deliver a potentially very good return, with little downside risk, in a reasonable timescale (circa end of 2021) through asset disposals & distribution of cash to shareholders. It’s an orderly winding up situation, of the remaining 2 investments in an investment trust ( a closed ended, listed investment fund) called Electra Private Equity.
Electra has already disposed of most of its assets, and distributed c.£2bn to shareholders via buybacks & dividends. What we have here are the last remaining 2 significant investments, TGI Fridays, and Hotter Shoes, both of which I think look really good businesses, that could attract sale prices well above the modest book values shown in ELTA’s accounts.
Electra would then be closed down, and cash distributed to shareholders - that is the stated strategy. Things look well-progressed, and the market for M&A (especially private equity deals) is very buoyant. So I think these asset sales have a good chance of succeeding in a timescale of c.1 year.
As always, please ensure you do your own research, this is not a recommendation, it’s just my personal opinions, backed up by facts & figures in the public domain. The future is inherently uncertain, so it may not pan out as we anticipate. Also I might have got something wrong, or overlooked something important, hence it's vital to check everything yourself.
Summary of the main investments -
TGI Fridays (“Fridays”) - the well-known casual dining chain.
Electra owns the UK (franchised) business, with 87 restaurant sites. 32 have re-opened recently (with outside space), the rest are due to re-open in May 2021. Hence this share is mainly about the upside value on Fridays.
In current buoyant conditions, I think Fridays could be sold for £290-400m - potentially more than double the market cap of Electra as a whole (which also has cash, and other investments on top).
That estimate is based on £30-40m EBITDA (management forecasts in Edison research note) rated at 11 times EBITDA - the typical private equity buyout ratio in this sector, less c.£40m debt.
The Edison notes give much more detail, and it’s noteworthy that Fridays has ambitious management that are looking at expanding into new sites. This is a wonderful time to be rolling out a restaurant format, because already fitted out sites are available in quantity due to CVAs & restructuring, and on cheap rent deals.
Management is also imminently launching a second format, a US-loft style cocktails-focused format. A second way to take advantage of (smaller) fitted out sites on cheap rents.
Hotter Shoes - this is a footwear manufacturer (in the UK) and retailer, specialising in comfort & specialist fit for the lucrative over 50’s market (think Saga, for feet).
A CVA was implemented during the pandemic, to ditch nearly all of its shops. What is left is a handful of stores, and a successful internet eCommerce business.
I reckon Hotter could be worth £50-100m on a disposal, because it is forecast to make £6-7m EBITDA this year, and private equity are typically paying about 11 times EBITDA for businesses in the consumer discretionary sector. That implies £66-77m proceeds from a disposal. There might be a bit of debt to come off that figure, I need to double-check that, but it's not material to the overall outcome. Stifel have already been appointed to find a buyer.
Other investments - have now mostly been sold, leaving £23.5m cash at the group level, plus a few other scraps of investments, so let’s say (at least) £25m cash in the bank, once everything has been sold off, plus the proceeds from selling TGI and Hotter.
Sum of the parts - this is the most appropriate way to value a winding up situation like this. I get to these numbers:
Fridays: £290-400m - my estimate of disposal proceeds
Hotter Shoes: £50-100m - my estimate
Cash + Other: £25m
Total: £365m - £525m
Total per share (38.28m in issue) = 953p - 1,371p per share (previous miscalculation here now corrected. My apologies)
The current share price is 410p. Therefore if my figures turn out to be correct, then the upside could be 132-234%, (previous error here now corrected) with a targeted return to shareholders of less than a year.
It sounds too good to be true, but I can’t see any problems with this, other than possible delays. If delays happen, so what? Electra has two great investments, both of which have a very strong outlook, having restructured during the pandemic.
A really cheap way into a good restaurant chain - this is how I see Electra shares. The gulf in valuation between ELTA, and Restaurant (LON:RTN) or Fulham Shore (LON:FUL) is really striking. Note also that the valuation comparison within the main Edison research note, showed comparator valuations on RTN and FUL some time ago, and their share prices have almost doubled since then. Although ELTA's share price has also risen a fair bit too.
Last week, I reviewed the positive trading update from Fulham Shore (FUL), and concluded that it looks rather expensive.
FUL is valued by the stock market on an EV/EBITDA of about 11 times pre-covid earnings. However, if we assume the restaurant sector bounces back strongly, with pent-up consumer demand, then post-covid EBITDA could be higher than that - plus FUL is planning on opening new sites, on attractive rents. So maybe this valuation does stack up?
This provides a benchmark for my valuation estimates above, and 11 times EV/EBITDA is also the valuation multiple suggested by Edison, in its 2 research notes on ELTA, which are essential reading for the detail here.
My opinion - this is one of the best special situations I’ve seen in a long time.
It provides an obscure, off the radar way of buying 2 smashing businesses (TGI Fridays & Hotter Shoes) at a very significant under-valuation compared with their likely disposal values, or what they would be valued at, if listed separately on the stock market.
I can’t see any obvious downside risks here, other than if covid takes off again and a 4th lockdown is needed. Fridays does have some debt, about £40m, but if it got into trouble, ELTA has £23.5m in cash doing nothing on its group balance sheet, so could support a refinancing if required. A refinancing isn’t likely, now Fridays is about to open the doors & probably be mobbed by customers wanting to eat out again (many sector peers are reporting they’re booked up for weeks to come).
If the disposals of Fridays and Hotter Shoes are delayed, so what? They’re only likely to go up in value, so I would be quite happy if there are delays. Actually, I would prefer it if ELTA listed them, and gave us shares in them, rather than selling them. I might write to ELTA to suggest this.
I’m making the assumption that ELTA owns 100% of its investments (implied in the Edison notes), and that no capital gains tax would be payable on disposals. You might want to make your own enquiries on that point, because I’m not 100% certain that is the case, but have asked other shareholders, who have confirmed they believe that is the case. Edison must have checked that too, so I’m fairly sure that’s OK. Shareholders might have to pay tax on dividends, so best to put this share in a tax-free wrapper like an ISA, SIPP, or even a Spread Bet, in my view, that’s what I’ve done.
The other point I haven't yet confirmed, is what the franchise contract is for Fridays. How much does it cost, and what duration? I need to look into that. If anyone knows, please leave a comment.
This share can be illiquid, although with a bit of patience I did manage to pick up some stock personally at 410p - a bit late to the party, but still good upside I reckon. As already disclosed, obviously I’m talking my own book here, as everyone does when telling people about their favourite shares. I confirm that I have no current plans to sell any of my shares - my intention is to hold until the winding up, planned for end 2021. Although I reserve the right to top-slice some of my position at any point, but that wouldn’t be under 600p. Unless of course some new information came out which changed the fundamentals.
I’d be interested in your views, so do please leave a comment below.
As always, please DYOR! (Do Your Own Research) - I'm not infallible, some of my investment do well, others do badly.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
43 comments
CGA Market Recovery Monitor is often cited as being as close to the horse’s mouth as you will get in terms of accuracy and timeliness for the state of the U.K. hospitality sector. You will need to register to get the full report, but the headline figures as of March 2021 can be found via this link:-
https://info.cga.co.uk/market-....
Gus.
Does anyone have a good source of ACTUAL closures within the retail and hospitality to date (not just a Daily mail list of major outlets closing, nor a 30% more closures due to lockdown extension. Any thoughts on how to research closures to come? In my view, long term supply is more important than any short term demand surge.
Historically, many/most fitted out restaurants that go bust return to being fitted out restaurants under new brands or owners. If this occurs again, we are back to discounting etc just with with a different group of players.
Finally, interesting Paul's throwaway comment that TGIF are now looking to push a "Friday's" vs TGIF branding - indication they don't think the M-F culture is coming back or meaningful for a clientele that they expect to use their casual restaurants?
The latest edition of the Market Recovery Monitor is here:
https://www.alixpartners.com/m...
It shows that by May 7.4% of hospitality sector venues had shut during the pandemic, rising to 9.7% for drink led venues.
The restaurant sector in particular has low barriers to entry - but you'd imagine that lenders won't be very keen to help new entrants and that the oversupply of mediocre chains that was prevalent before the pandemic struck will have been somewhat winnowed. And a lot of the survivors will be cash strapped.
It's not exactly a sector I favour but if there was ever a time to get in it's probably about now, if you can do so at the right price. But another CV-19 lockdown could still scupper all that.
timarr
More meaningful update from Electra Private Equity (LON:ELTA) this morning including plans/strategy for floating the TGI’s spin off.
https://www.investegate.co.uk/...
As a private equity firm, Electra will know how to play this game to maximise exit value so subject to market conditions execution should be well managed.
Gus.
More meaningful update from Electra Private Equity (LON:ELTA) this morning including plans/strategy for floating the TGI’s spin off.
It's a good update. In terms of overall valuation any delays to reopening do have some impact on Fridays (aka Hostmore):
In light of this and of the announcement of the delay to lock down easing to 19 July, Electra will continue to assess the optimal capital structure for both businesses and the potential sources of capital.
On the other hand there's no funding issue here and where other companies are on the verge of collapse or forced to raise funds at huge discounts - aka Revolution Bars (LON:RBG) - Hostmore should be a well capitalised company with refurbished outlets able to pick and choose new sites.
As long as lockdown doesn't turn out to be a permanent condition it would be an achievement from the management team to muck this up.
timarr
Any thoughts on the half year report released yesterday? Seems to have spooked some people
Any thoughts on the half year report released yesterday? Seems to have spooked some people
I don't think yesterday's RNS spooked anyone unless they have an irrational fear of databases:
A copy of the Half Year Report for the six months ended to 31 March 2021 has been submitted to the FCA's National Storage Mechanism and will shortly be available for inspection at: https://data.fca.org.uk/#/nsm/... and the Company's website, www.electraequity.com
Presumably the share price has fallen because of the delay to reopening which has a knock on effect on TGI Fridays. Whether that matters or not is part of the investing decision, as we could see a series of rolling restrictions for some time to come. Or not.
timarr
The report did state:
"Following today’s announcement of our intention to demerge
Fridays onto the FTSE Main Market and subsequently to bring
Hotter onto AIM through reclassification of the Electra entity in
the second half of 2021, the Board intends to ensure that both
companies are adequately capitalised to face the future with
confidence and to optimise shareholder value. The possibility
of further cash distributions will be assessed in conjunction
with the implementation of these transactions."
I'm wondering how much that changes the valuation if the cash from disposals isn't distributed
I'm wondering how much that changes the valuation if the cash from disposals isn't distributed
Not distributing the disposal cash makes no intrinsic difference to the valuation. Either way shareholders end up with the same assets - it's just a different combination of equity, debt and cash. It does, however, possibly make a difference to the viability of the companies after they're floated - personally I'd prefer they retain cash and ensure that they're well capitalised to take advantage of the opportunities ahead.
Note that the actual half-year report was released on 21st May after which the price rose from 510p to nearly 670p. It's given some of that back in the last few days, but if that's a response to the AR then it's a very delayed one. The price fall is probably a combination of general market jitters along with a bunch of quick-hit momentum investors getting out.
But share prices move all over the place for all kinds of reasons. Trying to figure out what they are is usually a fruitless task.
timarr
Thanks, I'm just weighing up increasing my holdings at the moment and trying to make sense of what the report released on the 14th June said:
https://www.electraequity.com/...
HSBC Research rate Electra Private Equity (LON:ELTA) a buy with a target price of 840p.
https://www.electraequity.com/...
Question for the accountants out there - wrt Fridays, given the adoption of IFRS 16 and with rent therefore being recognised through depreciation of the ROU asset is it accurate to value off the reported adjusted EBITDA? Surely rent charges need to be taken into consideration? Thanks in advance
Hi Claudia
There is no single way of doing this, the important thing is to be consistent between the definitions of EBITDA(R) and debt which I think is the point that you are seeking to emphasize. Many will apply a multiple to EBITDA less lease rentals and then deduct the debt excluding leases. Others will take a multiple of EBITDA and then deduct the debt including the capitalised value of leases..
Jim Armitage in the Evening Standard has TGI float at £275m and Hotter at £45m.
https://www.standard.co.uk/bus...
Reposting of comment on SCVR of May 21st.
——————————
Update from Electra Private Equity (LON:ELTA).
https://www.investegate.co.uk/...
Looks like they intend to IPO TGI Friday’s in Q3 and then list the final holding in Hotter using the existing Electra vehicle in Q4. Looks a good way to maximise sale value if markets are still benign and possibly give holders a chance to continue the ride in these two entities. NAV per share updated to March 31st of 514p, (so Ken Mitchell you can buy more at today’s 510p a share with an easy conscience if you want to!).
Gus.
Bear in mind that this stock distributes cash as special dividends - retail investors pay income tax on the whole amount unless you hold in an ISA or similar
Hi Paul, This is great content.
I recently came across similar opportunity in Uls Technology (LON:ULS) . £53M market cap having divested one of their businesses for £27m. Remaining business should be valued more than this based on EBITDA comparison. The significant upside that I see is the market is currently completely ignoring their rollout of their new DigitalMove platform that was built to disrupt and transform the home moving and home owning experience for consumers. It seems to be getting good traction with reported 40k transactions processed since relatively recent rollout.
This is really great Paul (and Ed for the encouragement/order). You already do a huge amount to help the PI community, you’ve no need to do more like this, but it is a wonderful help.
Have a good BH weekend.
Chris.
Thanks for the interesting article Paul, a great read and very thought provoking. Couple of questions for you or the wider forum.
Firstly, speaking to an friend in M&A, they suggested that the historical multiple would be c.8x for casual dining. Do you think 11x is justified with the intended expansion and new format?
And with regards to the Edison research note, am I right in saying that the company being reviewed pays for the article? Is it therefore independent research or marketing by the company? Or maybe somewhere in the middle, taking the research with a pinch of salt?
Hi JamesS,
I only used a takeover multiple of 11 times EBITDA, because Edison provides a table in its research note, which states that is the multiple that has been used in recent deals in that sector. So you may be right that 8x would have been used in the past, but private equity is awash with money at the moment, and prices being paid are higher. So it's logical to go with the current level of pricing.
There's no such thing as independent research in my view! Someone pays for all types of research in any field, directly or indirectly, and the output will usually provide the result that the person paying for it wants to see.
Edison research notes are commissioned by the company itself, so no it's not independent. That's no different to the house broker issuing a note on any of its clients. A lot of the stuff in the Edison note is straight out of ELTA's own Annual Report. I don't have a problem with any of that. The Edison note certainly doesn't use aggressive assumptions, it's quite cautious in my view, and it's good to have an experienced analyst spend a lot of time going through everything and putting it into a readily digestible format, so I think the Edison note is really helpful.
Here's the link again to the main Edison report, although note that a further disposal has been made since this was written, at about double book value, which helps validate that NAV seriously understates the real world value of its investments.
https://www.edisongroup.com/pu... (Dec 2020, detailed)
https://www.edisongroup.com/pu... (April 2021 update, brief)
Regards, Paul.
Hi Paul,
Thanks for the swift reply on both of those points.
Talking my own book further, Sherbounre are also involved with a 6% stake in Barc through their follow on vehicle £SIGC. The Electra stake is held in £SIGB. Sherborne Investors (guernsey) B (LON:SIGB) is too illiquid to trade. However Sherborne Investors (guernsey) C (LON:SIGC) is larger and trades at a 30% discount to the underlying investment in £BARC. Barclays (LON:BARC) numbers tomorrow.
The discount is interesting because at around 220 for Barc shares Sherboune will have recovered to approx breakeven after management fees and hedging costs. This effectively allows them to move on should they wish. Alternatively they step up pressure on Barclays (LON:BARC) but they have failed thus far to get on the board.
As a SIGC holder if they moved on at breakeven you would be back to 100. The current share price is 56. That is a 78% return. So if Barc +16% ... SIGC NAV =100. Last reported 79p on 1st April. Next will follow this Monday after the Barclays results. Seems bizarre doesn't it but its the unusual maths of a 50% fall is followed by a 100% recovery to get to breakeven.
This analysis involves the discount closing which would probably take a return or capital and realisation of the Barclays (LON:BARC) investment. So far they have NOT indicated they will do this. Their internal valuation of Barclays (LON:BARC) is between 400 and 500.
Thanks for the summary of the Sherborne Investors (guernsey) C (LON:SIGC) holding. This looks an equally interesting special situation as the Electra/TGI example. I've been meaning to look into it more closely but never got round to it. SIGC currently allows you to buy Barclays (LON:BARC) at 30% discount, while Barclays itself is on a 30% discount to its book value so tremendous value there. The only question is how long before they unwind the position and return money to shareholders - as you say presumably not before they are back in profit so would require a further rise in the Barclays share price.
I expect the discount to narrow a little once they are back to breakeven. Maybe 10=20% rather than 30%.
At the moment banks earnings are supported by the unwind of provisions taken around Covid this time last year. If central bank policy is to work then increased lending must follow. At Barclays (LON:BARC) this would be positive for Barclaycard and this is the main driver of the rating. Although Investment Bank earrings have been strong in the last 6 months this has done little to repair the Barclays discount to book value. However there would seem to be little appetite from within the bank to shrink investment banking. Whilst the market remains in an inflationary trend the backdrop is good for banks.
For Sherbourne they are much better executors of their own strategy and would be better focussing on a target where they have greater influence. They previously identified 3i as a target before Electra. When it became obvious they would not get the support they needed to gain a seat on the board they moved on. The first 2 quarters results from Barclays this year may yield the opportunity in August/September to place the stock. At this point they could either return the money or seek permission from shareholders to go for a new target.
Nice work Paul Ive been following Sherbourne and Electra for years.
I can also highlight in the finals earlier this year although NAV had fallen slightly to 353... the reference point for the company is the 2019 level of 548. The sentinel disposal has added 28p to NAV increasing the 2019 number to 576. The company stated they anticipated with business returning to 2019 levels they expected decent premiums to these levels to be achieved. So I certainly agree 600 is a good line in the sand.
Just want to say brilliant post Paul - you are going above and beyond.
Thank letap73!
Ed asked me to do some write-ups on individual companies, when I can find time after doing the SCVRs. I thought ELTA fit the bill very well, being low risk, hidden value type of situation.
Will keep my eyes peeled for other shares which offer good risk:reward, and hopefully more articles to follow, but only if I find something good enough.
Regards, Paul.
Hi Paul, thank you for flagging up this share. Looks a very interesting situation and worth further research.
What spread betting companies do you use?
Thanks, Tom
I use Spreadex, and have done for many years. They're excellent. To emphasise, I never recommend using spread bets, as the gearing can be a killer. But they can be useful, providing you are strict about not using too much (or indeed any) gearing, and also that you can resist the urge to punt on other things like indices, currencies, etc.
Thanks very much for highlighting this opportunity. I would perhaps value TGI Friday on a lower multiple of perhaps 7-8 x ebitda, reflecting that it is a somewhat tired brand (at least in my view, others may differ? ) whose earnings have been pretty stagnant over past few years. I think something like Fulham Shore (LON:FUL) does warrant a higher multiple than TGI. However, even applying a lower multiple this stills looks very cheap and offers a lot of upside.
Hi Bourden54,
I'd put a question mark over whether TGI Fridays is a "tired brand". The new management team installed by ELTA a couple of years ago have done a lot of work to revamp the offering. Also they're now looking at expansion into new, sometimes fully fitted out sites, so the capex on new sites from now on should be much lower than in the past. Lots of opportunities. Plus their new, second brand, which is being launched imminently.
I think we should all do some mystery shopping (dining) at our nearest TGIs and compare notes here!
Best wishes, Paul.
Thanks, not quite mystery shopping but I did try to book a table (in various locations) through the site and everything seemed to be booked up for next couple of weeks so that's surely a good sign.
I'm struggling with the final numbers that you calculate-maybe its me. £365m of value with 38.3m shares is nearer 950p? what am I missing.
the Edison note from 18/12/20 if you have access to it is a very good start (its on research tree).
Hi mepfish,
You're correct, sorry I made a miscalculation in the upside case for disposal value per share. I've now fixed it, sorry about that.
I agree the Edison notes are excellent, although note they have since sold a smaller investment, for about double book value, Sentinel I think it was called, from memory? I've included that within my £25m cash figure above.
Regards, Paul.
Seeing this quoted (14:30) at 436/455p at the moment (it was 420/422p) when I bought earlier, so either the MM’s have been caught short of stock or they’re just milking a PS inspired windfall!
Paul, very interesting special situation. Thanks for bringing it to our attention. I had one question:
Your sum of the parts valuation of £365-£525m is based on the proceeds. TGI & Hotter have a book cost of £112.4m (30/9/20). Does the book cost need to be removed from the sum of the parts valuation in order to get to the revised NAV?
That is, NAV would be £253m - £413m (660p - 1,079p). Therefore, the upside on the current share price (410p) is 60% - 163%.
Hi Reacher,
I'm ignoring book cost altogether, because it's irrelevant to the shareholder distributions that we should get. I'm doing my sum of the parts calculations purely on cash already held at the topco, and then the cash it will receive from selling Fridays & Hotter in due course. Book cost shouldn't really come into it.
Regards, Paul.
Makes sense now. Thanks for clarifying.
Thanks for this Paul - heading up quickly now
Seem quite difficult to buy and spread is fairly wide. Price is now 440p.
Now no live quotes.
Thanks Paul.
You make a convincing investment case and I’ve bought some back today after regretting selling too soon.
Current NAV is reported as 353p so with the share at 420p it’s trading at a 20% premium and I hardly ever buy Trusts trading at a premium.
BUT. That 353p NAV figure doesn’t seem to have been updated since September last year. No doubt Electra will update on NAV with their results next month and perhaps with a higher figure. Your mouth watering sum of the parts figures are way above that quoted NAV. I’ll be happy with less than your lower 758p figure.
Thanks for highlighting this interesting opportunity.
Bear in mind that this stock distributes cash by special dividends - retail investors pay tax on the whole amount distributed
Thanks Paul.
Very interesting situation. TGI’s appears to be where the vast majority of the value is to be had and the business appears to be in good post-COVID lockdown shape. As ever, the devil is probably in the detail. Here’s a couple of helpful documents for those DYOR-ing. The Sept 2020 Annual Report and the fund factsheet.
https://documentscdn.financial...
https://documentscdn.financial...
I have just taken a small opening position. Liquidity seems OK at the moment in retail size.
Gus.