Five Further Tremendous Turnarounds

Last week, I looked at some of the most interesting stocks from my Turnaround Screen. This week, I continue in the same vein with a first look at five more investment ideas for the turnaround investor.
Halfords (LON:HFD)
Many think of Halfords as a cycling retailer. However, their recent trading statement shows that they are increasingly a motor vehicle service centre operator:
The Group has two reporting segments: Autocentres (c.40% of Group revenue) and Retail (c.60%, across Motoring and Cycling). Motoring across both segments represents c.80% of total sales.
This is one of the highest VM-ranked stocks in the UK:
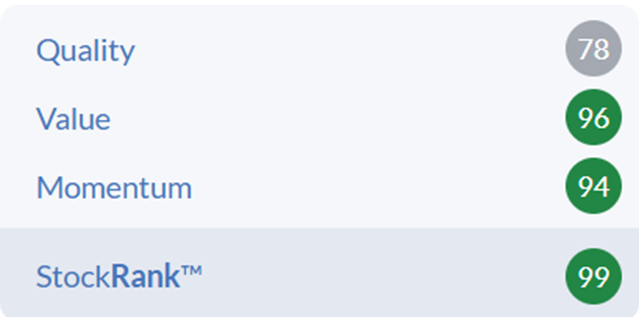
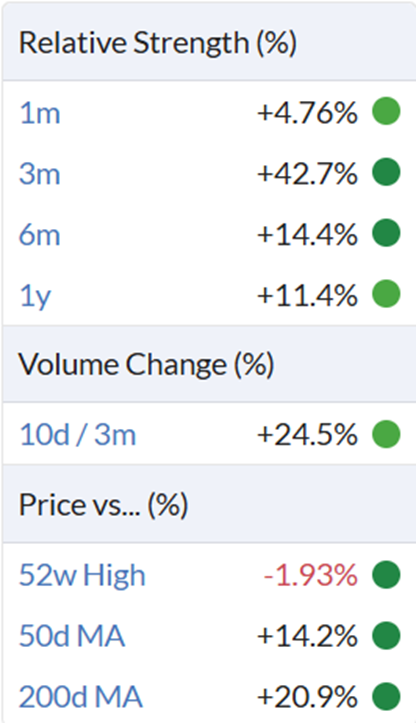
The Momentum Rank is driven by positive price moves across most timeframes:
There has been a strong recovery from April lows:
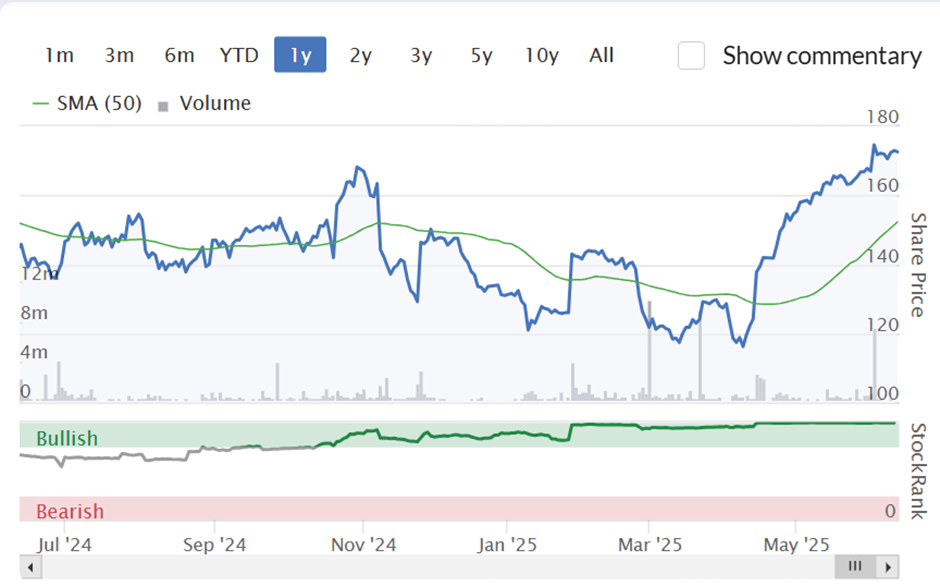
This is helped by an upbeat trading statement where they said:
Outperformed £30m cost saving target, mitigating more than £30m of inflation in the year.
Underlying Group profit before tax around the upper end of the £32m to £37m range previously guided.
However, the upgrades for future years have been very modest, and FY26 is now expected to be flat on FY25:

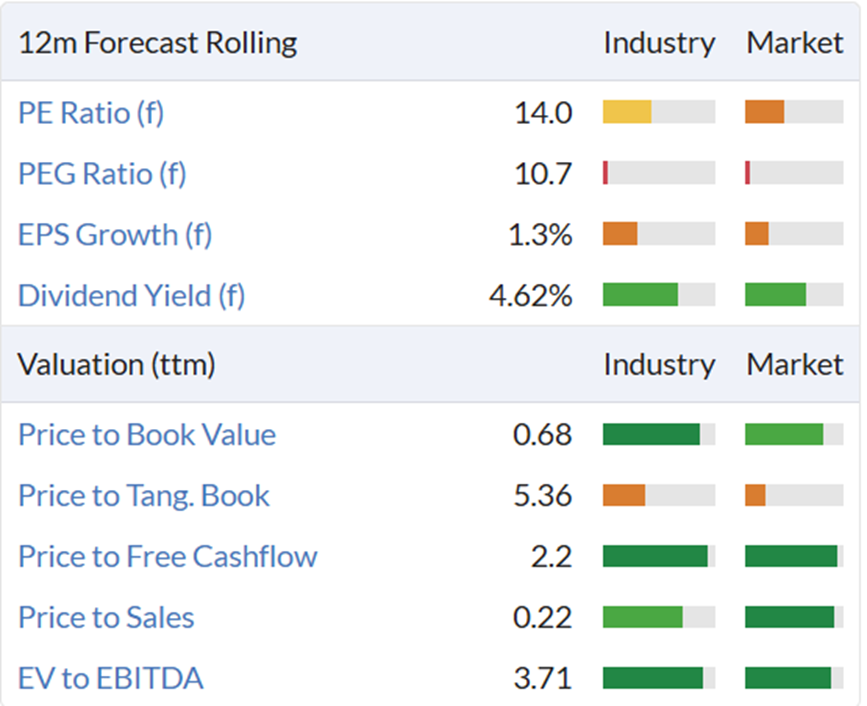
This makes it look expensive on forecast earnings. However, many of the other metrics are rated green, hence the high Value Rank:
The EPS trend over the years isn't particularly promising:
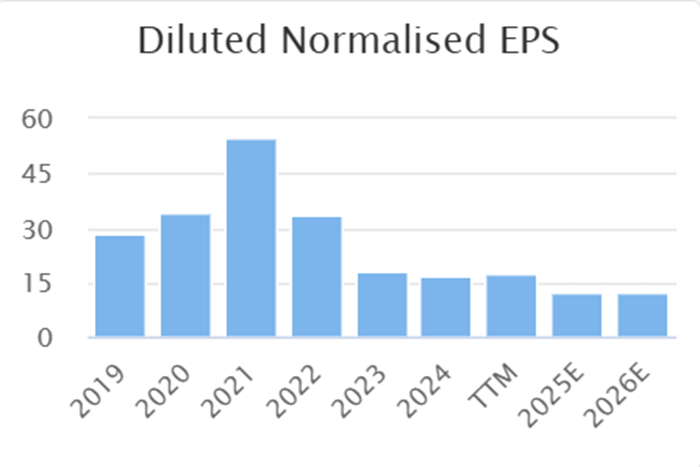
Of course, 2020 and 2021 represented a cycling boom. However, in 2019 they did much higher EPS and they were forecast to get close to these levels in 2026 before downgrades last year. Like many retailers, the main issue seems to be around higher costs. They have plans to mitigate these, as they said in their recent trading statement:
We have previously communicated that the changes to the Minimum Wage and National Insurance thresholds and rates introduced by the Autumn Budget will result in c.£23m of incremental direct labour cost in FY26. We also expect increased costs to be passed through in contracts for managed services.
We have undertaken a comprehensive review of the business to identify potential mitigations for the additional cost expected from FY26, which has generated opportunities in pricing strategy, further buying and cost efficiencies, proactive portfolio management and acceleration of strategic initiatives.
We expect to be able to mitigate the entirety of the direct inflationary impact of the Autumn Budget in FY26. However, retail sales remain volatile and the consumer outlook is uncertain.
If these cost issues are worked through and consumer confidence returns, I don't see why they wouldn't return to 2019 levels of EPS, making them look very cheap on earnings.
Bear Points
- As highlighted by their recent trading statement, the near term has considerable uncertainty to it. While the long-term turnaround story remains on track, any short-term warning would negatively impact both valuation and likely momentum.
- While they had net cash at the Half-Year, it was very small and won't represent the average position during the year, meaning this doesn't have the cash backing of something like Wickes. Their lease liabilities exceeded lease assets by £24.5m, suggesting that at least some of their leases are onerous or stores are loss-making. Any decline in trading would exacerbate this situation, and with negative working capital from the retail side, it could put them under financial pressure.
Summary
Halfords have been transitioning their business from in-store retail to a service centre operation backed up by a parts business. The returns from this have yet to hit the bottom line, hampered by increasing costs and weak consumer sentiment. However, recent trading suggests that the fruits of that labour may just be about to appear. The price has been strong on minimal movement in EPS forecasts, and with no growth in the short-term forecast, investors may want to wait and see the upcoming results before concluding that the turnaround is fully underway.
Staffline (LON:STAF)
Staffline has a chequered past. As a largely Blue-Collar temporary recruitment agency, their operating margin is tiny. This has made them vulnerable to being over-leveraged in the past, not helped by issues surrounding National Minimum Wage violations at customer sites. This means that they had to raise £37m of equity in 2019, followed by another £44m in 2021. This led to their share count soaring. (Although more recent buybacks have reversed that trend.)
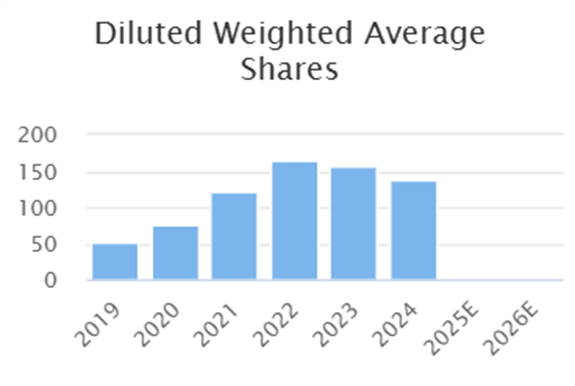
Today, they have the fifth-highest VM Rank amongst UK stocks:
This is due to a recent jump in the share price:
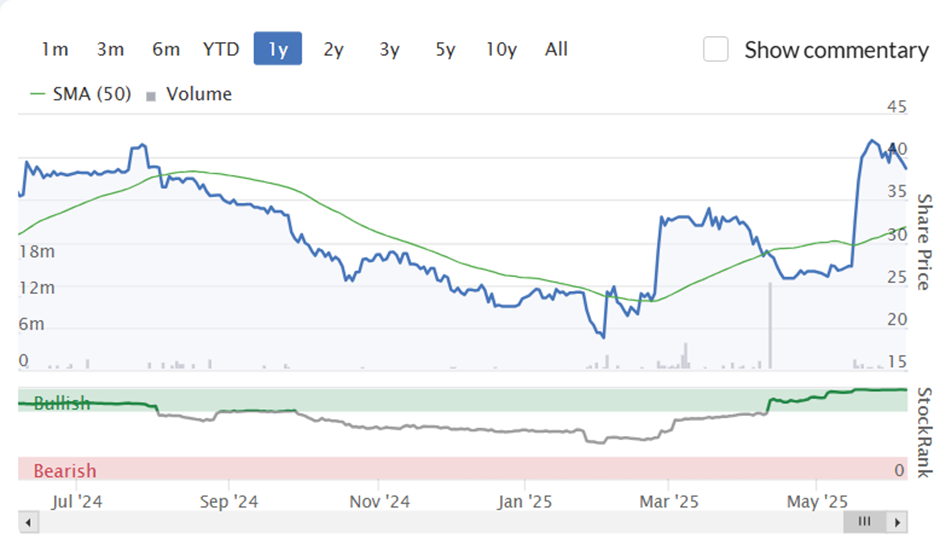
Similar to Mission Group below, much of that rise has occurred in the past month, leaving the stock at risk of short-term reversals:
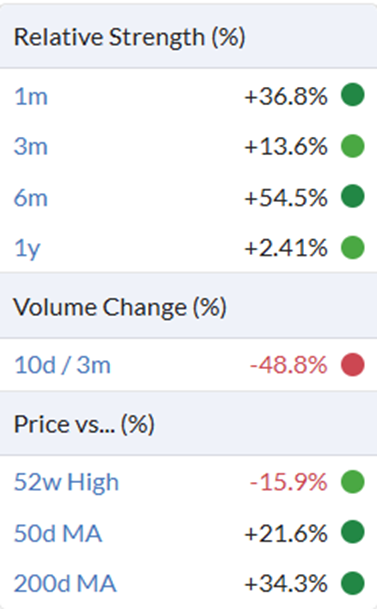
However, unlike Mission, this rise is backed by a big upgrade in forecasts:
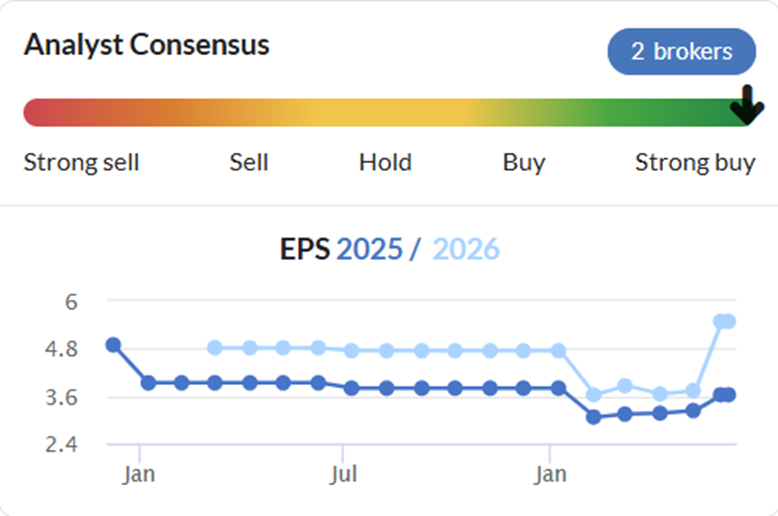
The following contract win caused the upgrades:
Staffline (AIM: STAF), the recruitment group, is pleased to announce it has secured a significant strategic partnership with one of the UK's leading food and drink supply chain management and logistics providers covering the whole of the UK and Ireland.
This new partnership comprises an initial two-year agreement with a one-year extension option to outsource to Staffline 100% of the agency labour services that are currently supplied by the wholly owned in-house labour supplier. This partnership will see the Group deliver flexible, temporary employment solutions in addition to managing second tier suppliers across the client's chilled and ambient business operations.
Investors had to read the brokers' notes to understand the impact of this. This is what Zeus said:
As a result of this win, we increase FY25 underlying PBT by 12% to £5.9m, FY26 by 47% to £8.3m and FY27 by 45% to £8.7m
The company doesn't mention the client, but a broker's report names them as Culina (Muller). The interesting part is that there is scope for the company to take on similar contracts for existing customers who are currently acquiring companies that don't currently use Staffline.
These upgrades mean that the shares still don't look expensive:
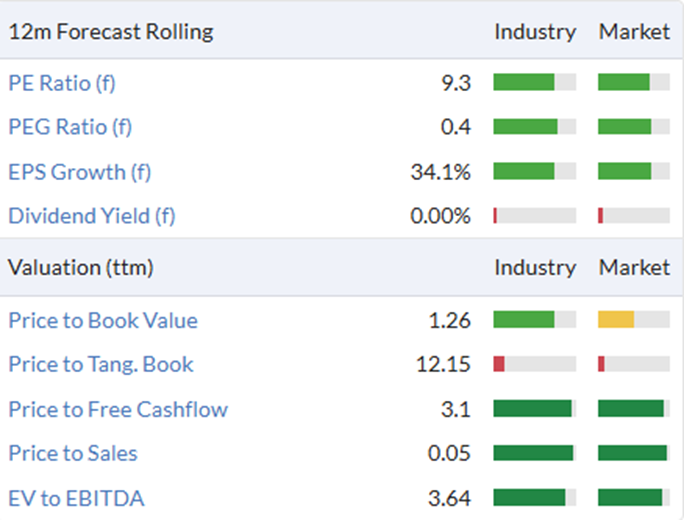
Although, again, there is a lack of tangible asset backing.
Bear Points
- This is another company that is flagged as potentially in distress:
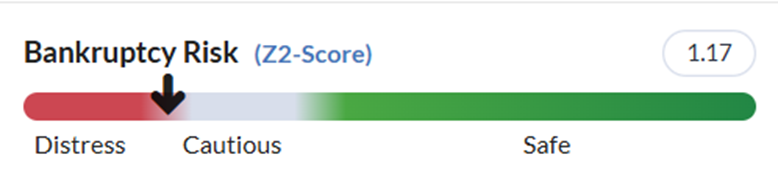
The reasons are: a lack of working capital, which can often be a sign that a company is struggling to pay its bills:
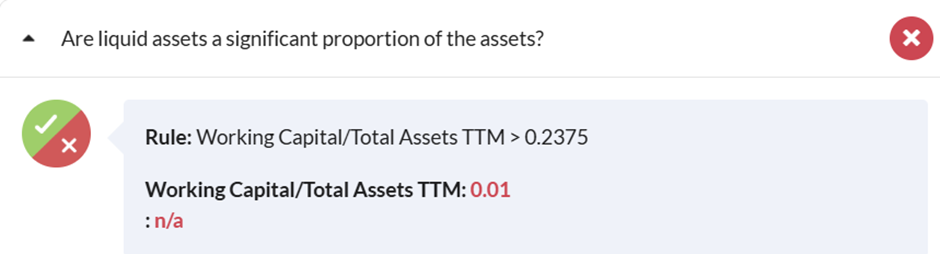
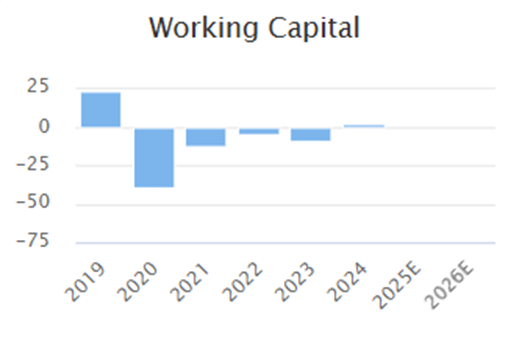
In this case, this figure doesn't look out of place and is actually a little better than in the past:
The other concern is that the liabilities are large compared to the equity:
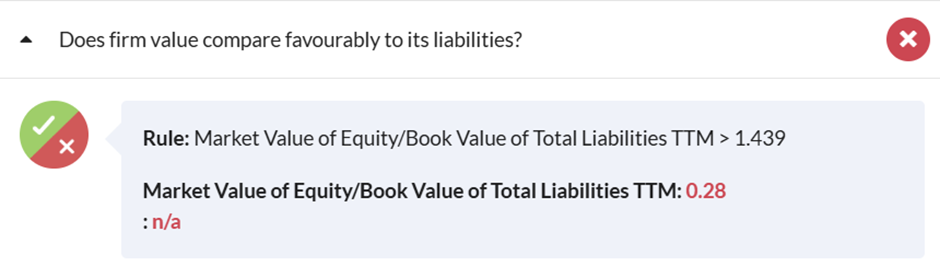
Again, this is a function of the business model, but a large turnover compared to profitability always adds to the risk to a business.
- The company recently sold their training business, PeoplePlus. This had been underperforming for a number of years. However, they didn't get much for it. The headline figure was £12.0m, but this included a £2.0m deferred element and a gross of a £5.1m deduction for advanced payments received in respect of future revenue. Therefore, they only received £4.9m up front for the business. While this was forecast to generate minimal profit in FY25, in 2021 and 2022, PeoplePlus generated around £4m of PBT. This perhaps reinforces their reputation as a business prone to mishaps.
- They also issued a trading statement in February this year, which was titled "Strong performance with underlying operating profit exceeding market expectations" with them referring to FY24. While they made no explicit mention of FY25 profits, their outlook caused their brokers to slash future year forecasts:
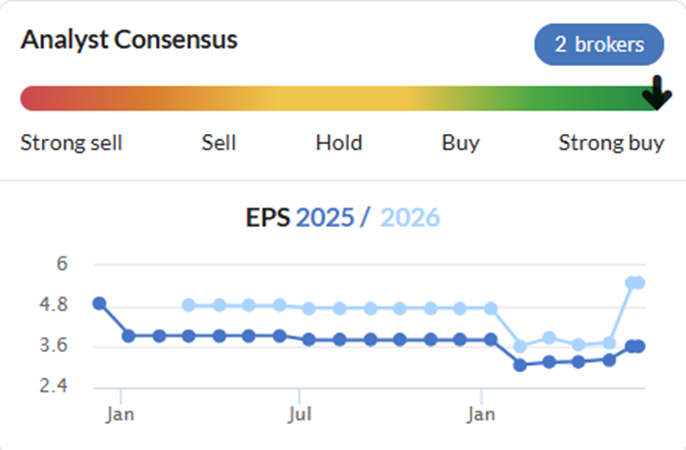
- Personally, I don't like the tendency here for management to be highly promotional about the good news and bury the bad news in broker forecasts.
Summary
Earlier this year, Ed wrote about how investing in companies that issue a materially ahead statement and the shares jump more than 15% on the day makes for great short-term investments. In this case, although the company did not explicitly state the words "ahead", a 45% upgrade in FY26 EPS forecasts suggests a similar outcome. The shares rose around 19% on the day, making this exactly the sort of stock Ed referred to. The shares have since experienced some of the positive drift, but there could be more to come. In Ed's study, the optimal holding period was around six months.
There is certainly a case to be made that this turnaround has legs over that sort of time frame. However, the business's tendency to be accident-prone, its lack of robustness to issues, and the sometimes overly promotional management mean that I would be more cautious about holding for the longer term unless there are further material upgrades in forecasts.
Mission (LON:TMG)
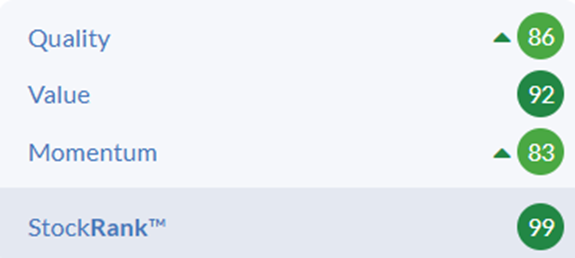
Mission Group is actually strong on all three Ranks:
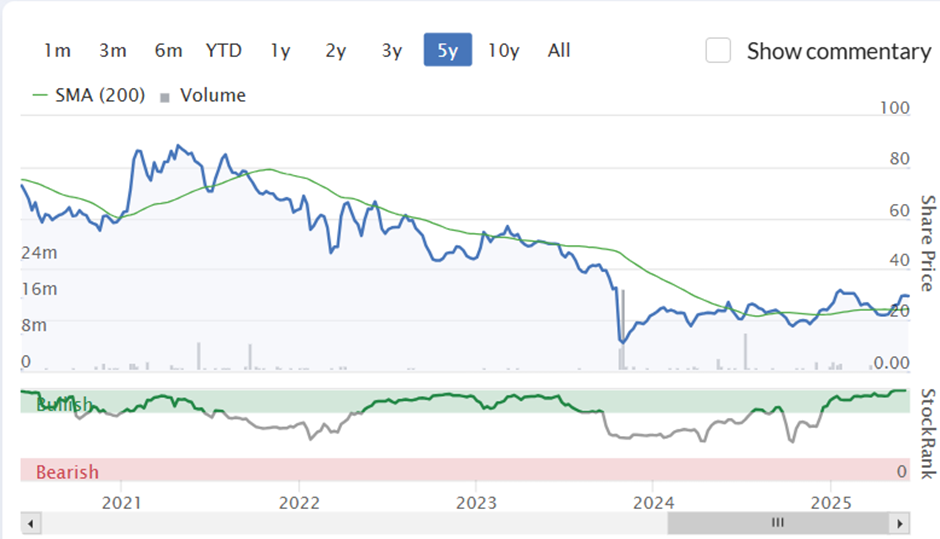
But I think it is the medium-term chart:
And the EPS trend that marks this out more as a turnaround story than anything else:
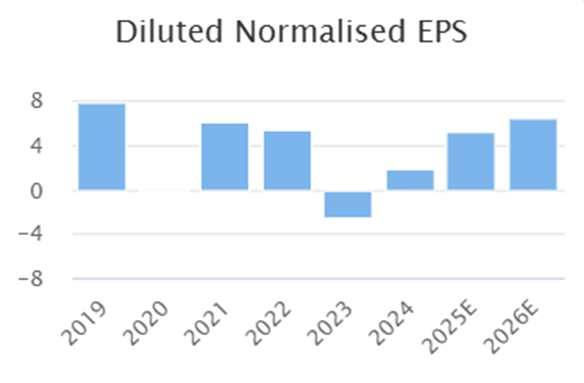
In their Final Results in March, they said, "Trading in the new financial year has started well and is in line with expectations." So, at this stage, these forecasts look realistic.
Marketing is a pretty cyclical business, and Mission Group has struggled in recent years. However, the issues have been particularly acute here, with the company having taken on debt to expand via acquisition, leaving it over-leveraged into the downturn:
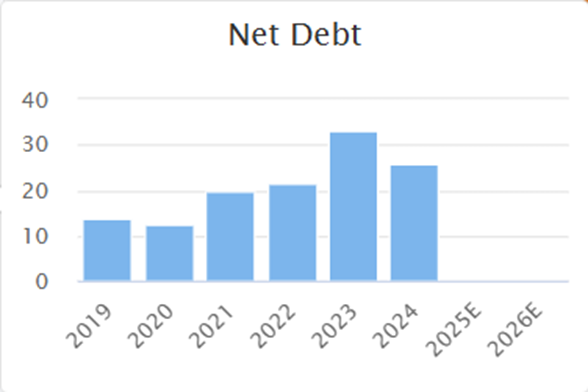
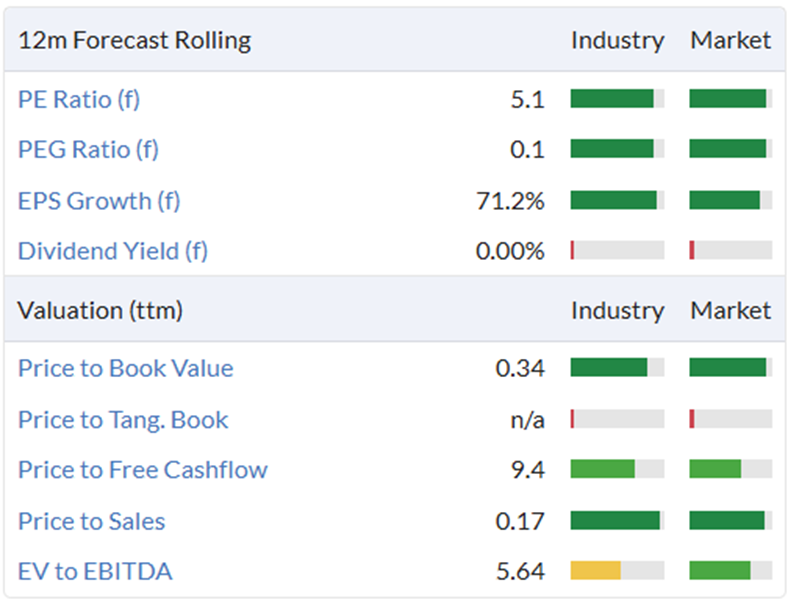
The net debt here includes lease liabilities and looks a bit better when only net bank debt is included. This was given as £9.5m on 31 December 2024, down from £15.6m a year earlier. To improve matters, Mission has sold off non-core agencies, cut costs and tried to focus on more resilient sectors such as technology and healthcare. It is the result of these actions that are starting to have a positive impact on EPS. This puts them on a very cheap rating on a number of forward measures:
Bear Points
- While the company appears relatively inexpensive on price multiples, it doesn't look as strong on EV measures that include debt, nor does it have any tangible assets backing it.
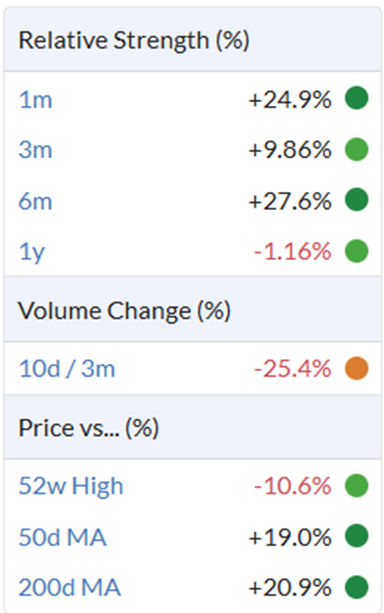
- The Momentum Rank has been rising recently, but mainly due to recent share price strength. While there is a good selection of green here, the bulk of the positive returns are in the last month, which may make it prone to short-term reversal:
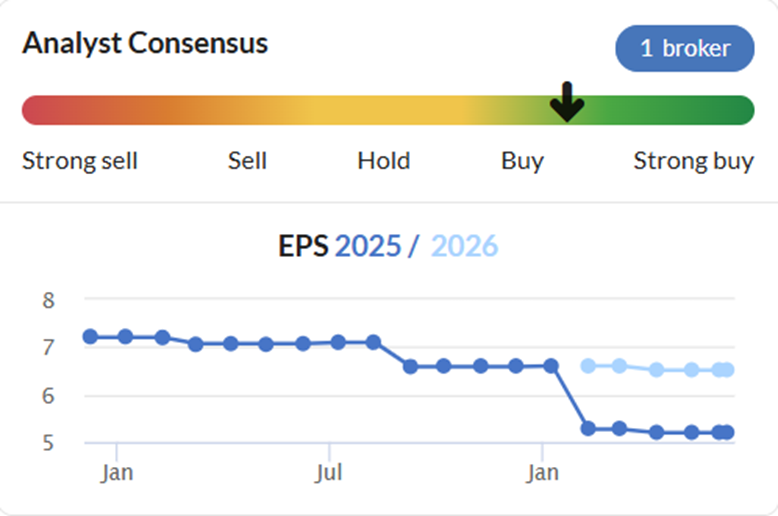
The share price strength isn't yet driven by broker upgrades, which may also mean some caution is warranted:
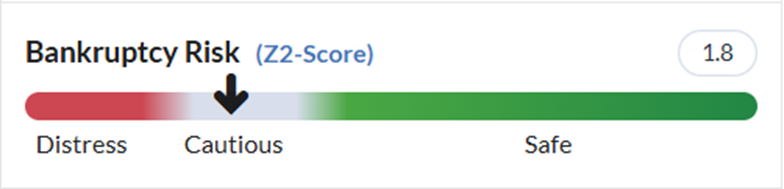
- Another reason to be cautious is highlighted by the Z-score: despite recent falls, the debt level still remains significant, leaving little room for manoeuvre if things take a turn for the worse.
Summary
Mission Group is very cheap if forward earnings forecasts are accurate, but perhaps not outstanding, as cyclical businesses in this sector never attract high multiples for good reasons. While the short-term share price strength is promising, it isn't yet backed up by earnings upgrades. This means such rises can be prone to reversals. The turnaround potential is strong here, but it may be wise to wait until earnings are upgraded or the 1-year Relative Strength is higher than the 1-month.
Vertu Motors (LON:VTU)
Motor dealer Vertu looks like a typical Turnaround stock. The VM Rank is strong, but the Quality Rank is only average:
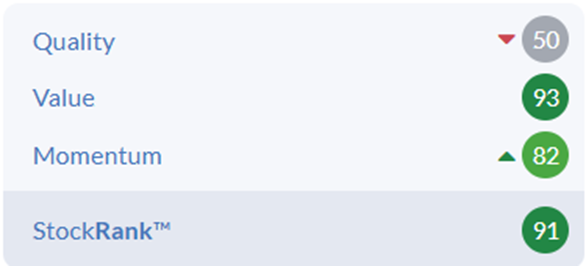
The issues are a relatively low long-term return on capital and a middling F-Score of 5. However, the value metrics here back up the 93 Value Rank:
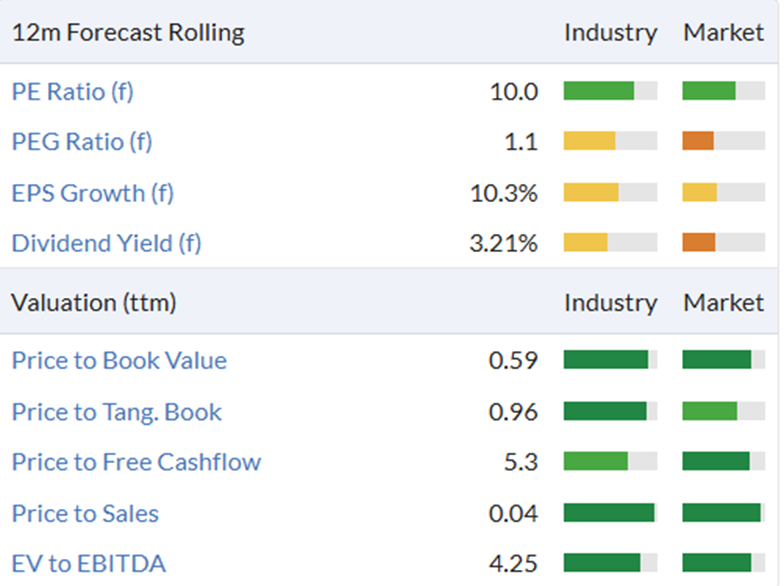
The standout value here is the price-to-book value, which largely represents the freehold property the company holds. Transactions in the sector typically go for a premium to book. Surplus property is often sold, meaning that there is often an alternative use value for these assets.
The Quality Rank is also let down by a Z-score that suggests the company is in financial distress:
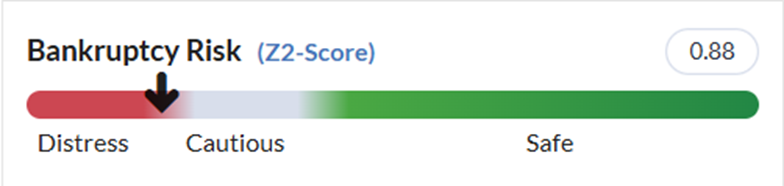
Similar to Staffline, the issues here are common to companies which earn small margins on large turnover:
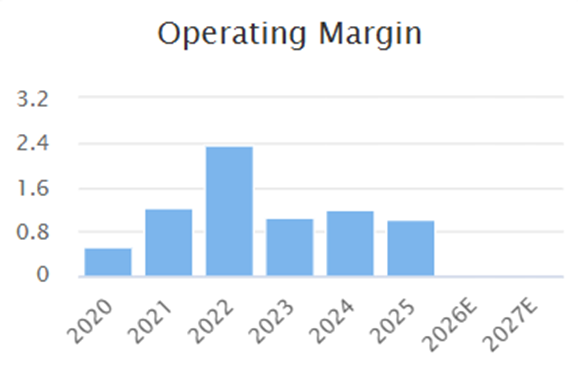
Plus, again, relatively low working capital:
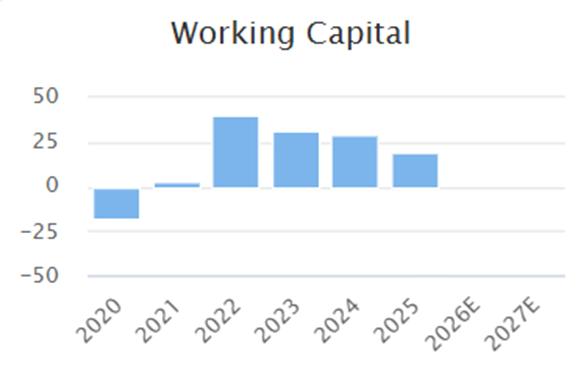
Although this trend has been declining recently, which may be a sign of financial distress, it can also represent improvements in operational efficiency. In this case, most of the working capital is provided by the OEMs in the form of vehicle stocking loans and is, therefore, low risk.
The company issued a nasty intraday profits warning in February, saying:
The Board anticipates that the Group's adjusted profit before tax for the year ending 28 February 2025 (FY25) will be significantly below current market expectations, primarily due to dislocation in the new car market.
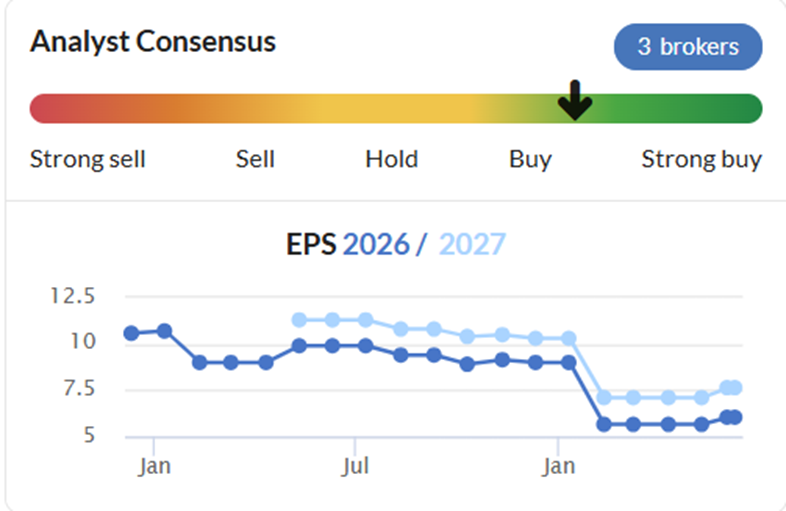
The issues listed included reduced consumer confidence in used cars, increased NI costs, and lower new car gross margins due to a higher fleet sales mix. In response, research provider Progressive took 4% out of FY25 EPS but made a 30% reduction in FY26 and FY27:
However, more recently, in the results statement itself, they said that:
Trading in March and April has been stronger than the prior year, as the UK retail new car market improved from its lows and the Group continued to focus on operational excellence. Our high margin Aftersales business has sustained its robust performance.
March and April saw a significant increase in the UK new retail car market as Manufacturers rebalanced fleet and retail mix. The Group performed well, generating significantly more new car profit in the period than the prior year.
This can be seen in the modest tick-up in the forecasts above. Assuming this momentum continues into 2027, the forward P/E may end up somewhat below the current 9x forecast multiple.
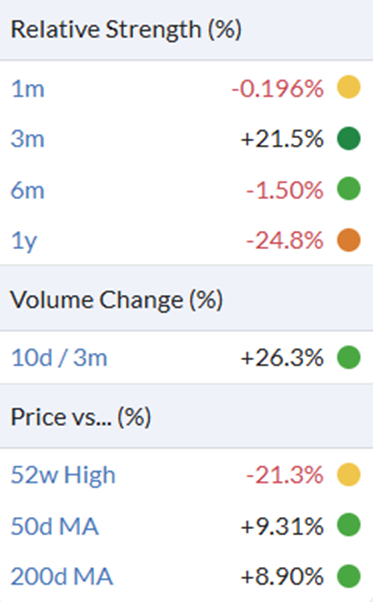
These more recent upgrades have seen the Momentum Rank rising recently, although the share price is still down over the past year:
One factor to consider is that several industry parties have been building a stake here:
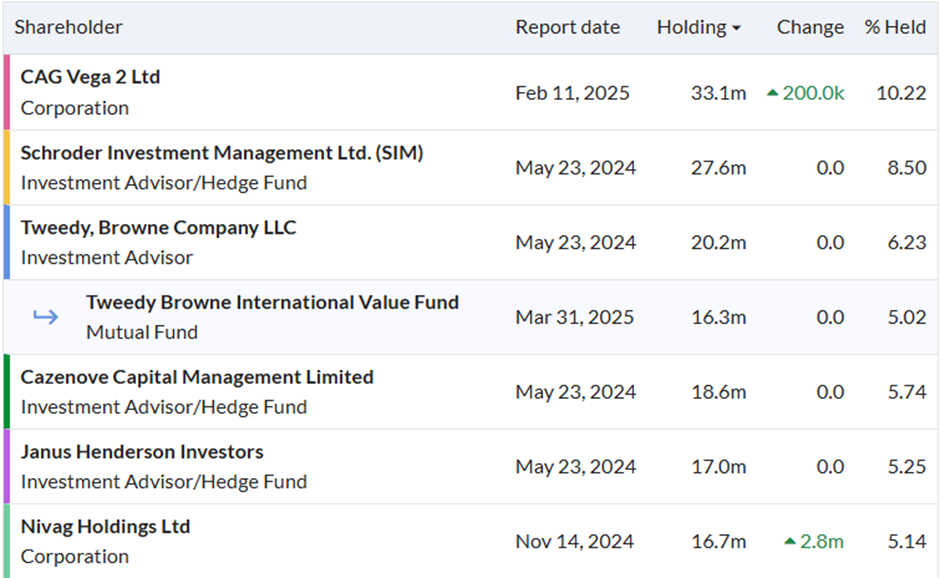
CAG Vega 2 is Constellation Automotive, which bought Marshall Motors. Nivag Holdings is owned by Gavin Hydes, CEO of Joe Duffy Motors in Ireland (Nivag being Gavin backwards). Vertu missed out on the takeover boom a couple of years ago that saw most competitors acquired. This may be due to chance or because acquirers prefer more asset-light businesses at the time. The scale of the acquisitions into weaker trading gave many of the acquirers indigestion, so it may be too much to expect any short-term action here, but it remains a possibility. Instead, Vertu have made acquisitions themselves, seeing the value of greater scale and diversity of OEMs.
Bear Points
- While trading may have improved over the past couple of months, the profits warning was relatively recent, and the Stockopedia research into warnings suggests that it typically takes much longer for a company to recover from such a warning. After all, the current minor upgrades are nowhere near the scale of the downgrade. The price has been strong and is now above the level prior to the profits warning, which may not be wholly logical.
- While the issues that came to light in the February profits warning may prove short-lived, the cut in dividend suggests that the company certainly expected them to have a short-term impact on cash flow. There is significant freehold property here, but these assets are not liquid, and that adds to the risk for a company that makes small margins on a large turnover.
- The industry is undergoing significant changes, including BEV mandates, Chinese competition, and moves by some OEMs, such as Mercedes, to transition from a traditional franchised dealership model to an agency model. In this model, OEMs sell directly to customers at a fixed price, with dealerships facilitating the handover for a commission. This means that the dealership landscape may look completely different in the UK in a few years' time. Even if Vertu successfully navigates these changes, they may be a less profitable group.
Summary
The discount to book value is attractive here, as the assets are largely freehold properties, and other dealer networks typically sell at a premium to book value. There have been recent small upgrades, but nowhere near the size of the downgrades earlier in the year. The share price is now back above the level before the earlier profits warning, driving the strong Momentum Rank. This means that investors are increasingly betting on a beat of expectations. The risk is that the share price and momentum go into reverse if this doesn't happen.
Wickes (LON:WIX)
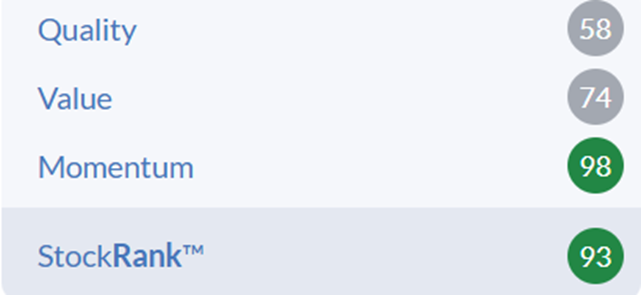
DIY retailer Wickes has a very strong Momentum Rank:
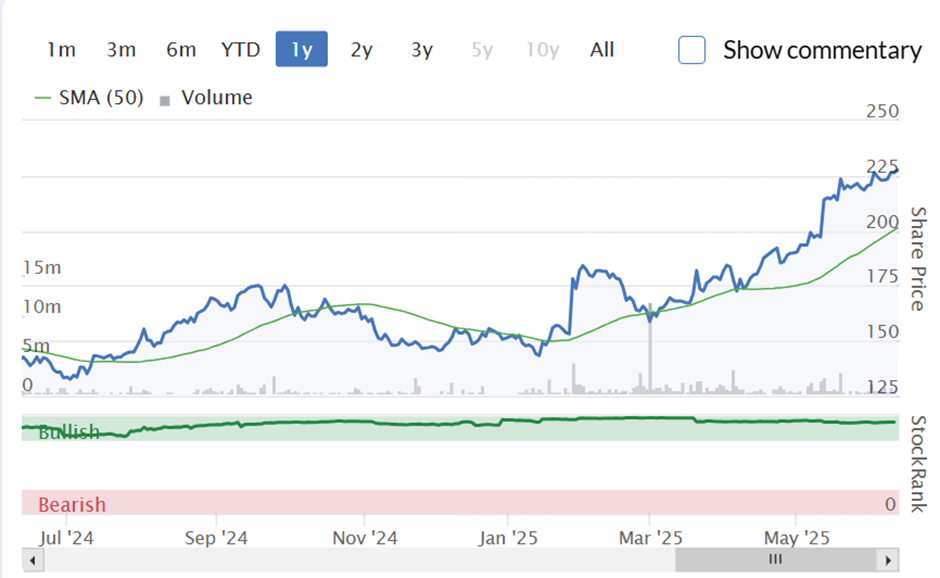
This is driven by a very nice recent share price trend:
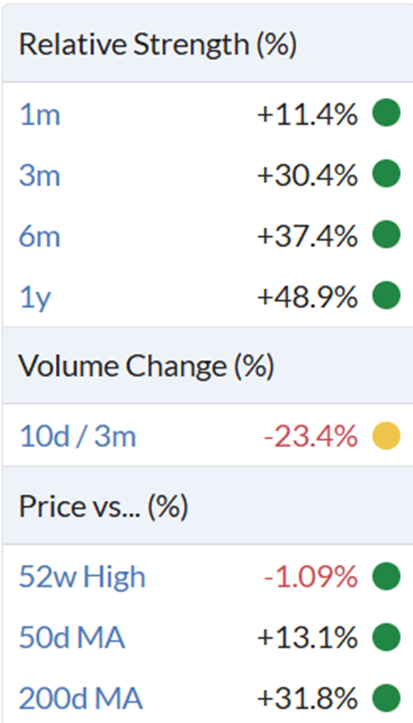
In this case, the relative strength measures look great, with the 1-year strongest:
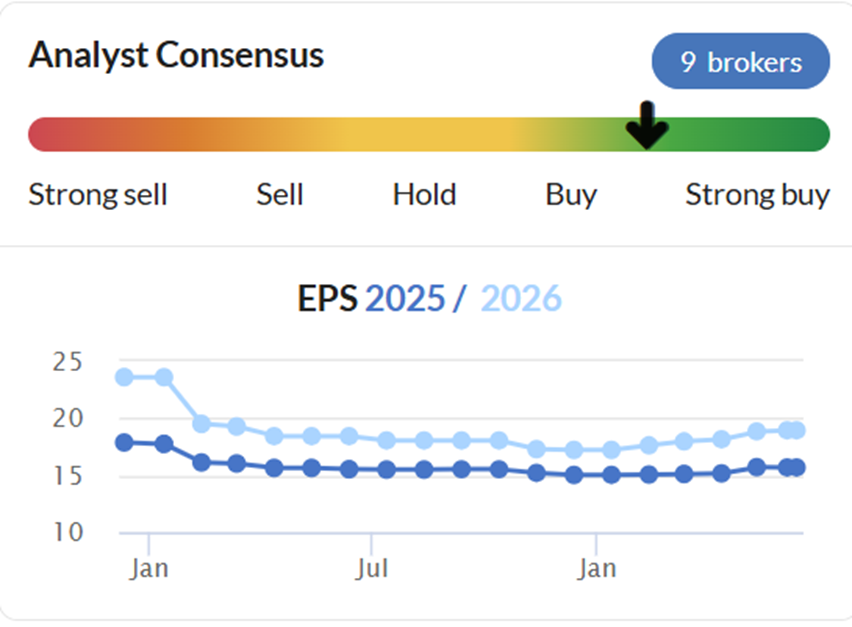
While the share price strength makes this an excellent Momentum play, the fundamental momentum is much more modest:
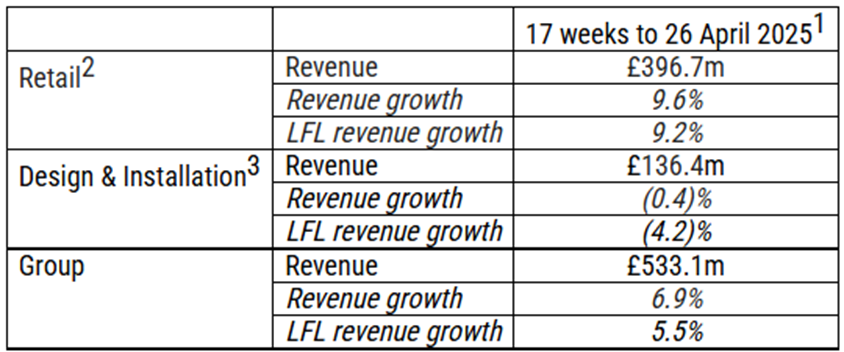
However, the recent business performance looks excellent for this market, with their retail sales up almost 10% in their latest trading statement:
There are long-term reasons to expect them to outperform their end-markets, as they say:
Investment in our strategic growth levers continues, with work underway to convert four former Homebase stores as part of our plan to open 5-7 new stores in 2025. We have refitted three further stores in the period and c.80% of the store estate is in the new format. In 2025 we will step up the level of investment in technology to enhance the customer experience further and to support productivity initiatives, positioning us for profitable growth in the next few years.
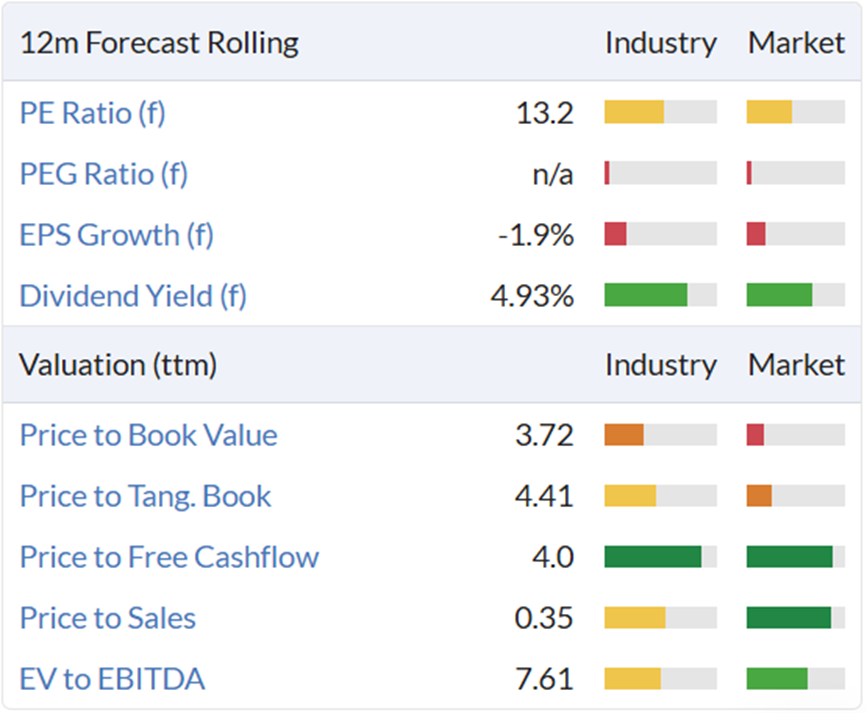
However, this doesn't look that cheap on forward earnings measures anymore:
They do pay a decent dividend, reflecting that cash-generative nature of the business. The StockReport suggests that this is highly leveraged:
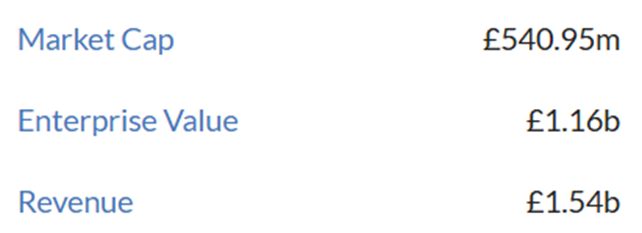
However, all of the debt here is IFRS16 lease liabilities. The last set of results said:
Net cash position of £86.3m (2023 £97.5m) and average cash across the year of £144.3m
Adjusting for this doesn't transform the valuation but makes it a bit more reasonable.
Bear Points
- While retail was strong, the do-it-for-me part of the business (largely kitchens, bathrooms and solar) has struggled. This suggests the consumer remains cost-conscious and reluctant to commit to big purchases. It seems it will take a while for this situation to change and the business to fire on all cylinders.
- Like Halfords, lease liabilities exceed lease assets. However, here, the figure is a whopping £142.8m. This suggests that there is a long tail of underperforming stores or onerous lease agreements, which will feed through to lower cash flows unless trading improves in these areas. If we treat the difference here as debt, then the valuation looks expensive compared to potential growth rates.
Summary
This is almost a perfect momentum stock. However, the value credentials are not as strong. While there is plenty of scope for the turnaround to gain traction and improve the value score, investors here need to be very wary of signs that the momentum is turning, as it may be some way down before the valuation starts to provide strong share price support.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Thanks Mark for a very interesting analysis. VM is an ideal combination to identify rising Values stocks but i consider an element of that rise is also due to investors looking for recoveries and joining the momentum rise. Currently with such low prices across the board any one of them MAY recover in the shorter term.
I attempt to find those of high Quality with a technical analysis setup suggesting an imminent move.
In a past Bull market there were more risers to balance the few fallers, where as in this market mildly poor Result's days can severely impact the portfolio. However i am confident those days will return, meanwhile i am being cautious; in this particular portfolio i do not have time on my side to see Value bloom.
Hi Funderstruck,
I agree. I think in the current UK markets things have been so cheap for so long, investors want some confirmation that things aren't going to get worse, as they are used to these types of stocks being severely punished. Which means that once a stock starts to move, investors are jumping on that and taking the stock much higher and more quickly than they normally would. The belief is that others have spotted a company that will beat, or is receiving takeover interest. Sometimes there may be truth in this but often the initial move is just noise. This makes which stocks soar and which remain unloved almost completely random (or at least subject to whims like newspaper tips). VM can be a good indicator of which cheaps stocks are starting to getting noticed.
The risk is that the stock goes down as quickly as it went up when that very short-term momentum fades. This is why my preference is for cheap stocks that are showing fundamental momentum as well as price momentum. This is more likely to be a new trend of beating expectaions than a one-off gain due to investor (over-)exhuberance. Nimble investors/traders may be better at taking advantage of short-term moves than me, though.
Mark
In the end Mark you write more caveats than positives in your personal style. I assume you own none of these, nor are considering doing so. May be , like graham your should reveal your own holdings? There is as much Mark as Analysis in this/
Take your point but I quite like the balanced commentary, there really isn't enough of it around these days
Stockopedia writers always declare when we own stocks we write about, so no declaration = no owership.
I like writing these types of articles becasue they help form my views on possible stocks for my watchlist. Although interstingly, I have owned all of these stocks in the past IIRC, and would consider owning them again so are already on my watchlist. Hence I know all of them reasonably well and feel a duty to readers to point out the most saleint points, bull and bear.
The bull case for a turnaround stock is often self-evident - the Momentum Rank is strong and it isn't expensive. The bear points are often more nuanced, and investors may miss them. There will be plenty of investors for whom the positives outweigh the negatives on these types of stocks. However, I am not a natural turnaround investor. I would probably own all of the above if they were cheaper but had weaker Momentum Ranks, or at least the Momentum was more broad-based and less focused on 1-month RSI where mean-reversion tends to be king, or the fundamental Momentum seemed stronger. But hey, we all have to find our own way in investing and there are plenty for whom going with the flow of strong Momentum is a better psychological fit.
Thank you Mark, an excellent informative response to a bit of a snotty comment!
I think its tricky one finding ones niche - i have generally a gone of fundamentals for my entire investing career - but must admit aided by the very useful trade/chart ideas thread. I now have a selection of stocks where others think "the chart look good" and there is some reasonable value and hope for upside - these are stocks i probably wouldnt touch on financials lack of managment trust alone - for example i have just picked up some vistry despite not trusting mangement one iota and have had a punt on Synthomer despite the woeful trend in future earnings expectations. Visrty is possible more safe as its got a nice discount to TNAV. with Synthomer the thinking is that the downgrades are over they have kitchen sinked the worst and they are trending back to higher profits. as i am going against my normal principles here i will get shot of these companies unless the news is good if the share price chart doesnt stay decent - i will see how flipping from often going agaisnt the tide to riding the wave (of a decent chart) gets on - i dont have high confidence as to me a chart is only good tillm its nlt good and the change can be next day before you have had a chance to sell - one cant doubt though that soem comapnies stay if the goove of ascending price for a decent length of time.