Gear4music and Focusrite - two online stocks beating the market

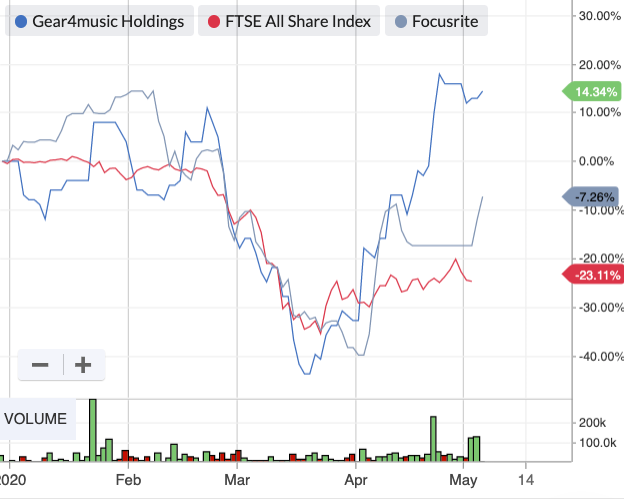
Gear4music Holdings (LON:G4M) and Focusrite (LON:TUNE) both provide music products and software online. Both also score well in terms of quality and momentum (G4M with a QM Rank of 87, TUNE with 98), and both also have their own founders still as top shareholders (see G4M here and TUNE here)
That is where a lot of the similarities end, however. Dig a little deeper and we have two quite different businesses in terms of established quality and profitability.
I last wrote about G4M on the 6th of April and noted that its prospects might be improving. Since then, shares are up by about 42.5% to 288p. In fact, its shares have nearly doubled since March 18th. The company has struggled to make profits in the past but some are clearly anticipating this will change. It is “cheap”, with a price to sales ratio of less than 0.5x.
Focusrite, on the other hand, has been very profitable for many years now. It has been a great success for shareholders. It has a superlative track record of high returns on capital and free cash flow. It is “expensive”, with a price to sales ratio of nearly 4x.
Both companies, I think, are quite well placed to navigate these conditions. Staying at home for so long may or may not permanently change habits, but I think it will almost certainly nudge established long term trends further along. One of the big trends of the past decade has been the shift to online retailing.
So will these two companies continue to be winners long after lockdown?
Edit: on an unrelated note, I see BOTB has once again surprised the market. It’s an interesting company. Paul is covering today’s news here and I covered it a couple of weeks ago here if you want to take a closer look.
Gear4Music
Market cap: £59.7m
QM Rank: 87
1y relative strength: +90.6%
What does it do?
Gear4music sells own-brand and third-party musical instruments products in the UK, Europe and the Rest of the World.
The group has struggled to prove the profitability of its business model though. This led management to introduce a raft of operational changes recently. The change in tack appears to be winning some people over.
A subsequent share price rally makes G4M a strong performer year-to-date:
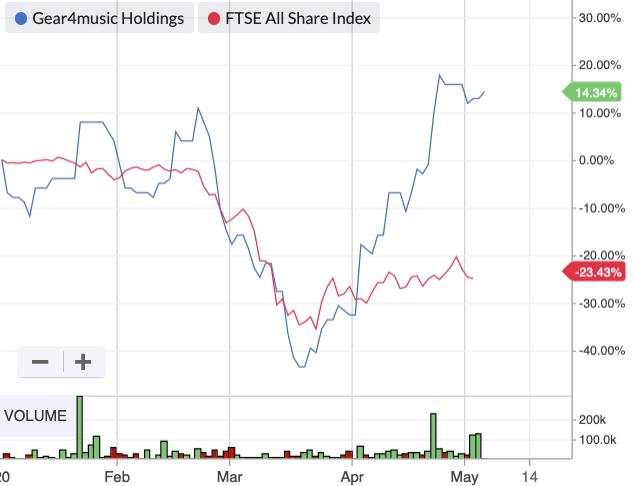
I wonder if G4M is now a fundamentally better company? If it is, then its growth prospects might not be adequately reflected in its share price.
If you judge recent gains in the context of the whole company, you can buy into G4M at not much more than its original IPO price after nearly five years of strong revenue growth and operational improvement. The all-important question is whether it is now a fundamentally more profitable operation.
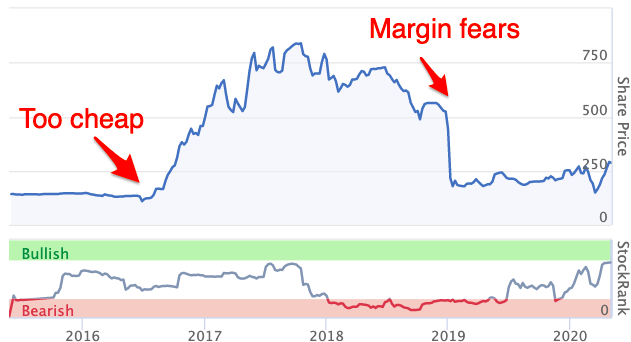
An interesting sidenote: this appears to be one company the StockRanks system has called quite well in the past... Looking at the bottom of the above image, in 2015 going into 2016, if you had acted on the improving Rank, you could have caught the dramatic upswing. And 2017 into 2018, paying attention to that deteriorating Rank could have saved you the equally dramatic drop.
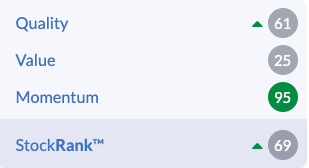
So it is with some interest I note the recent strengthening in Rank, driven not just by Momentum but by increasing Quality.
Catalyst - turning the corner on margins
To briefly recap events since G4M’s steep drop at the end of 2018, we have:
H1 19 results released in October 2018 showing revenue growth of 36% but gross margin compression of 230bps. The group goes from a small net profit to net loss. On gross margins, the group commented:
Gross margin reduced from 25.0% to 22.7% reflecting a highly competitive other-brand market and the Group focusing on rapidly gaining market share…
Efforts are on-going to improve gross margins including negotiations with certain suppliers, potentially removing very low margin products, and taking advantage of any tactical buying opportunities as and when they arise. Early indications in FY19 H2 are that gross margins are improving.
In January 2019 the group warns on profits after struggling to cope with rising demand. This news arguably overshadows the group’s “positive margin momentum”.
In April 2019 the company says “the Board is confident that having undertaken a thorough review of the business, including a strong emphasis on margin growth, the Group will return to a more profitable growth trajectory during the new financial year.”
In June 2019 it comments: Our FY20 H1 focus is on improving gross margins and ensuring a robust operational infrastructure is in place ahead of our peak H2 trading period, and I am pleased to report these actions are already yielding positive results.
August 2019: “The specific actions that we have undertaken to improve gross margins and ensure that the Group is operationally robust ahead of our peak trading period continue to yield positive results.”
October 2019: “We have restored our gross margins to FY18 levels whilst at the same time continuing to grow our revenues and taking market share… whilst the UK market remains highly competitive, we have returned to a more profitable margin structure.”
November 2019: “This has been an important period of balancing sales growth with our primary objective of improving gross margins and profitability, and I am pleased to report tangible evidence that we are making good progress in achieving that objective.”
By January 2020 there are signs that G4M is in a better position: “We are pleased to report that as a result of our focused strategic and operational initiatives, profits for the current financial year are expected to be at least in line with the Board's expectations. We remain confident in the medium to long term growth opportunity, whilst continuing our focus on improving gross margins and sustainable profitability.”
April 2020: “As a result of the commercial and operational progress we have made during the last 12 months, we now expect profits for the financial year ended 31 March 2020 to be ahead of previous expectations.”
The group gave its most recent market update nearly a month after that, on the 23rd of April, for the year to 31 March. Highlights of those results include:
- Group revenue up 9% to £120.3m
- UK sales up 5% to £61.8m
- Europe and RoW sales up 15% to £58.5m
- Gross margin improved by 310bps to 25.9%
So it does seem as though management has reconfigured the group into a more profitable operation (albeit at the expense of reduced revenue growth).
To this end, group CEO, founder, and c34% shareholder Andrew Wass commented:
I am very pleased to report that we have achieved our primary FY20 objectives of improving our operational strength and driving efficiencies in order to restore gross margins, resulting in record profits for the Group.
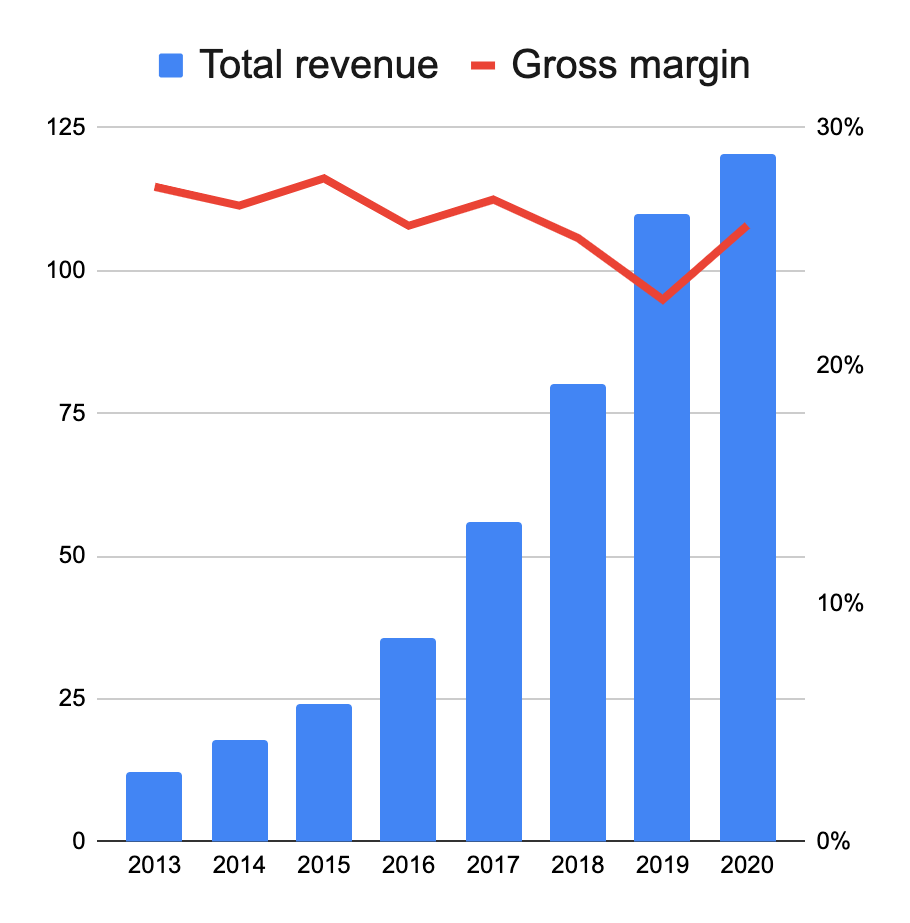
The 310bps improvement in gross margin is an important point and early evidence of improving profitability. Hopefully this improvement is sustainable. The group talks of EBITDA of “not less than £7m” - up from £2.4m in the previous year - pricing its shares at comfortably less than 10x EBITDA.
If margins and revenue can increase in tandem then there could be material upside. That is an “if”, though. In future, I hope to find more concrete examples of just how G4M intends to maintain or even increase margins.
In my previous article PhilH has compared G4M pricing to peers with mixed results here. G4M appears to be driving better margins by focusing more on higher margin products. Are rivals in a position to undercut it on price?
The boy who cried wolf
Now for the bad part - not only has G4M struggled to make a net profit ever since IPO, it has had to repeatedly source cash to fund its expansion.
You can see this in the “Cash flows from Investing” section of the company’s Cash Flow Statement (2014 on the right through to 2019 on the left):
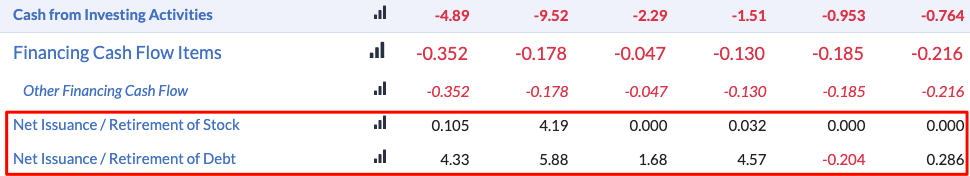
Usually seeing this in the cash flow statement puts me off a company. The question is whether you believe this is now changing.
Any prospects of margin and revenue growth must be balanced against the cold hard fact that, even after five years of operating as a public enterprise, G4M still struggles to turn a profit.
Valuation and conclusion
Having grown revenues by nearly four hundred percent over four years, I’m minded to believe that management has improved profitability by prioritising higher margin products and upgrading its infrastructure. The evidence of this is still in its early stages, though.
Managements says that it is now refocusing on growth orientated projects. Signs that the group is able to maintain higher margins despite a highly competitive UK market would be encouraging. The trick to long term success will be in balancing revenue growth with margin stability.
G4M says it is on course for £7m of adjusted EBITDA. I look forward to more detail on cold, hard operating profit and net income, though. These could still be negative - and if they are, how long will that continue to be the case?
The fact is, even after nearly doubling over the past month, G4M shares trade at well below one times sales - an attractive entry point if you believe this online retailer is proving its model and stands to gain from long term trends towards online retailing.
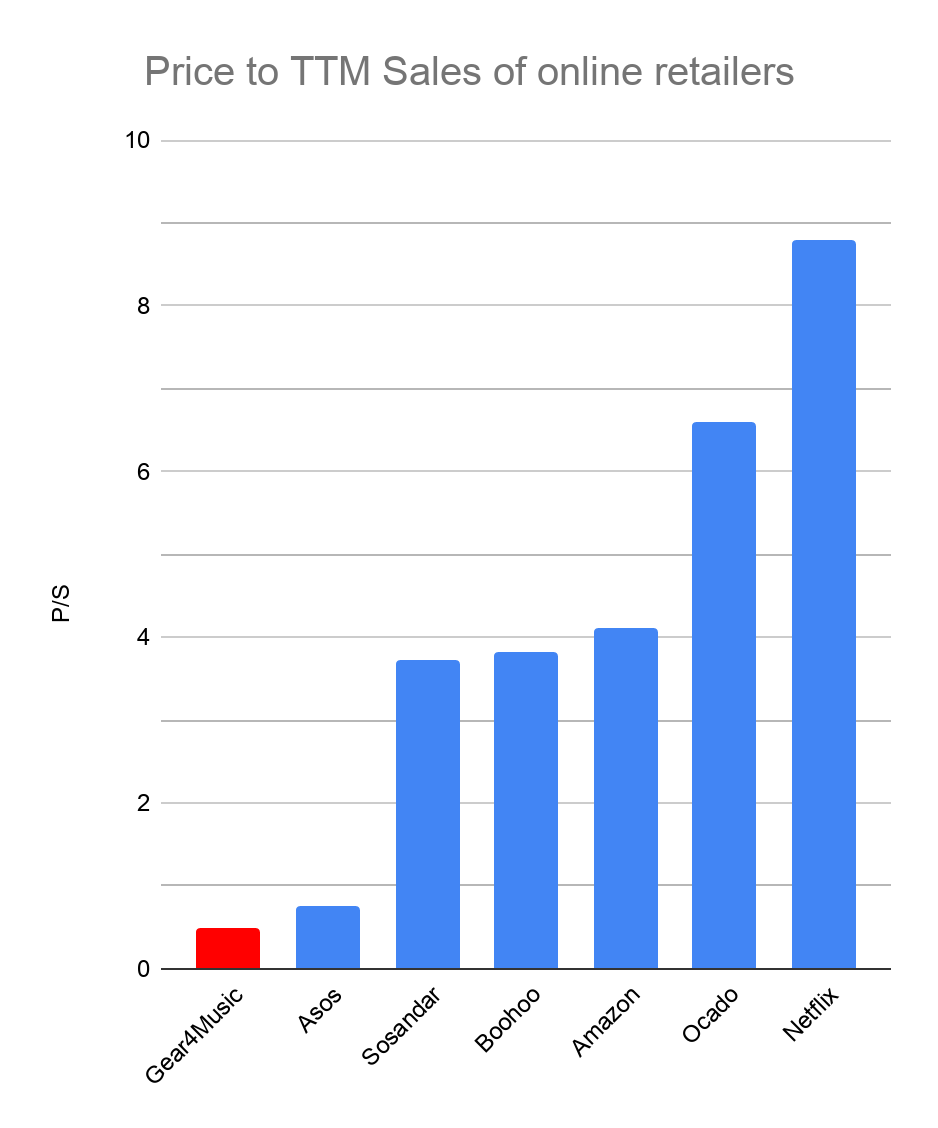
I think the lockdown is going to act as a nudge to entrenched trends - one of which is a shift away from the High Street to online retailing. Online models stand to benefit long after lockdowns lift.
Focusrite
- Market cap: £331.2m
- QM Rank: 98
- 1y relative strength: +40.1%
As if on cue, TUNE jumped c10% the day I decide to write on them. A good omen?
This company I know less well and I’ve spent too much time on G4M - I’ll have to revisit this one in more depth sometime. There are certainly promising signs that catch my eye.
The first point is that, while G4M has a market cap of £50m and annual sales of £120m, Focusrite has a market cap of more than £300m on annual sales of around £100m.
A market cap around six times as big as G4M despite generating less sales instantly suggests to me the market views this as a higher quality, safer operation. The Quality section of the two groups’ StockReports confirms this:
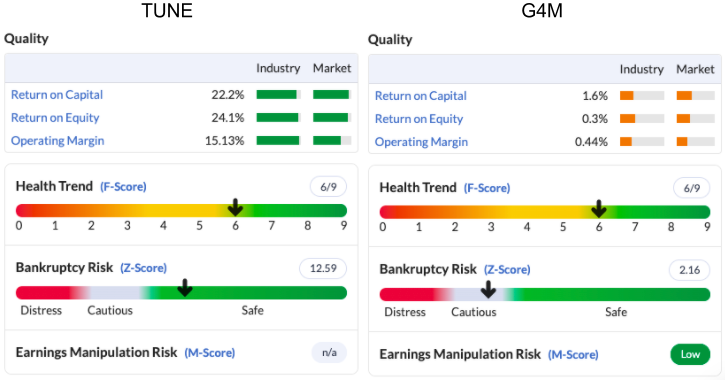
Comparing other quality indicators, we can see TUNE has:
- A higher Quality Rank (95 vs. 61)
- A higher Z-Score (12.59 vs. 2.16)
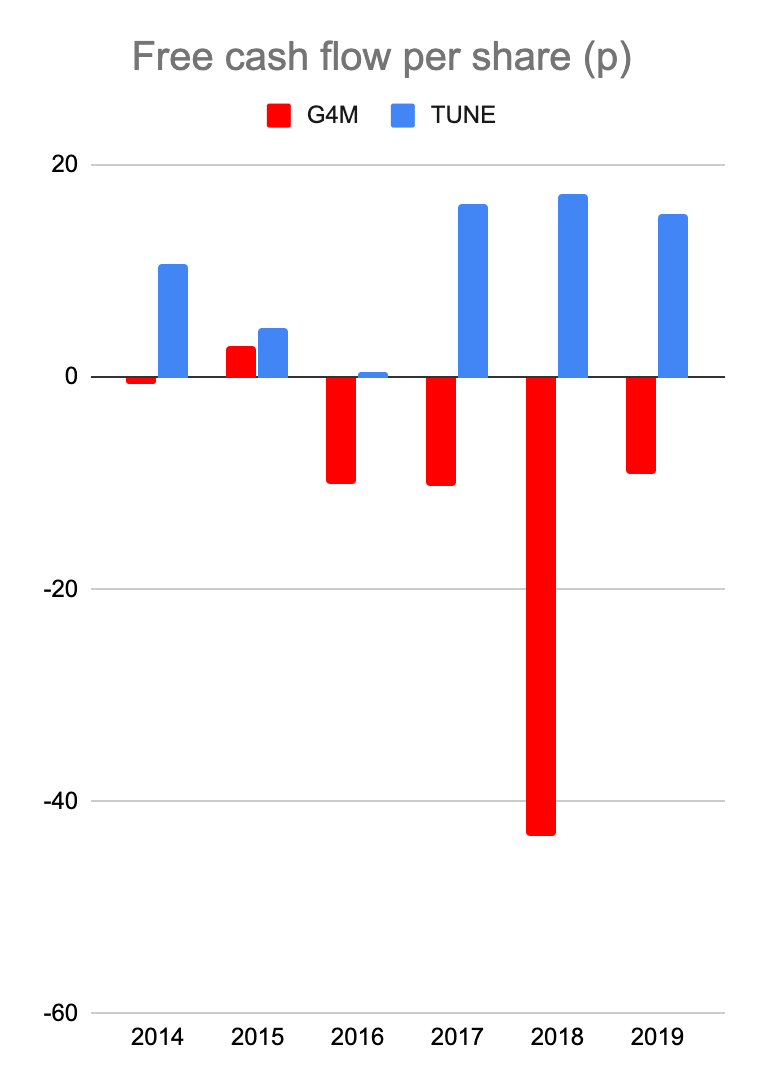
- It dependably generates more free cash flow and higher returns on capital, and
- It doesn’t need to raise funds via debt or equity to fund its operations
The last two points you can clearly see in the graph below: while G4M continues to soak up cash, TUNE is self funding. This dynamic makes TUNE higher quality, less risky, and justifies that higher price to sales rating.
What does it do?
Focusrite develops and markets proprietary hardware and software products that enable the high-quality production of recorded and live sound.
The fact that it develops proprietary products gives it more scope to capture value in my opinion. It makes sense that TUNE has been able to generate higher margins than G4M because of this.
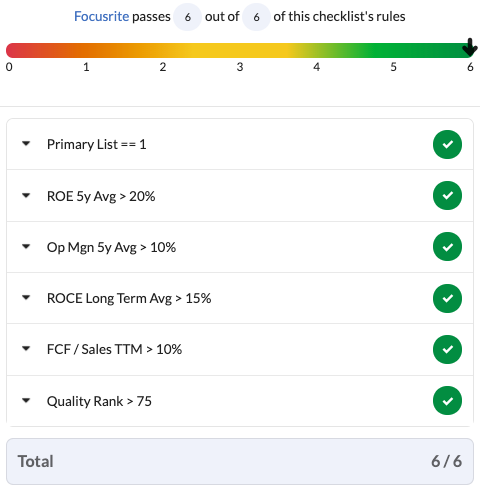
In fact, TUNE has displayed a knack for generating double digit returns on capital over a long period of time - something I look for in companies as signs of a potential competitive moat:
Catalyst - underpriced quality?
Focusrite looks like a great company and has already been a big success for many investors.
I can’t see an obvious share price catalyst here. What I do see is a quality operation backed up by a strong stable of brands and a great track record of growth. The fact that TUNE has generated persistently high returns on capital over quite a long time is an encouraging sign.
Sometimes with high quality shares they look expensive but in hindsight are proven to have been cheap because the market is underweighting future earnings growth. This is a company that IPOd in 2014 at 126p and now has a share price of 600p. Compare that to G4M, which has gone from 140p to 290p over a similar time frame.
Current trading
The group last updated on the 17th of March, so there has not been much comment on lockdown effects. It reported an encouraging c25% increase in H1 revenue, though, to £50m.
All of this increase in revenue came from two acquisitions made last year, though (ADAM Audio and Martin Audio). Excluding those, revenue for the half year was approximately £38m (HY19: £40.4m).
I do wonder why there was no organic revenue growth at all. TUNE strikes me as high quality, with well-regarded brands backed up by proprietary tech. Given the group’s pricey valuation though I would like to see acquisitive growth complimenting organic growth, not making up for a lack of it.
Valuation and conclusion
Do you want proven quality or growth potential?
While TUNE is the higher quality, more profitable, and proven company, G4M is more attractively valued and offers growth and rerating potential. The latter looks like a riskier proposition, though.
I have some reservations over TUNE’s valuation. Namely that the group’s H1 revenue growth came from acquisitions, and organic sales actually declined in the period. At 24.6x forecast earnings, I would like to see more organic growth. Swinging from net cash to net debt at this moment in time is also less than ideal.
That said, there are also strong signs of persistent quality. TUNE is clearly worth a closer look. Both of these companies are interesting for quite different reasons. Perhaps G4M presents a more immediate rerating opportunity, while TUNE represents more long term value?
I haven’t come to a solid conclusion yet on either of these shares but I see plenty of reasons to continue looking into both of them. It would be great to get input from anyone that has a view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Gear4music Holdings (LON:G4M) If my local were open I would go and ask the bar staff who are mostly recruited from a local music college. The phrase that sticks in my mind is "highly competitive market".
I find it strange nobody is talking about Naked Wines (LON:WINE)
That's a good point CamRaid, I'll add it to my list. Quite an obvious one now you've mentioned it! Do you hold?
Yes I do hold. One of the real interesting points prior to C19 was the position built by Punchcard Capital. C19 has merely acted as a catalyst to accelerate what they wanted to roll out in the US. There is huge opportunity for them in the US.
It may also be worth adding that Punchcard Capital have now taken a stake in Motorpoint (LON:MOTR)
Thanks for another great article Jack, I always look forward to reading them when I see you are the author.
I've followed the G4M story for a few years without dipping my toe. TUNE more recently came on my radar when I saw it was in Keith Ashworth-Lord's Buffetology fund. For me TUNE sounds like a better and more solid prospect on what I know so far (which is not much).
Please pardon my ignorance but it has baffled me for years. Why is there so much focus on price to sales? Isn't sales vanity and profit sanity? Lower your margin enough and you can increase your sales but what if you struggle to cover costs? I just don't get it. Give me a company making good margin every day of the week.
Hi wildshot,
Thanks, that's great to hear! Good question re. price to sales. I've wondered the same thing in the past.
P/S is handy in terms of making loss-making companies more comparable with others. Obviously, you would be hoping that company is only temporarily loss-making... Sales are also less easy to manipulate than earnings.
There is actually some pretty solid research that backs up price to sales as a good valuation metric to look at though - it's been a while since I read it, but James O'Shaughnessy finds it to be one of the best measures you can look at in What Works on Wall Street.
If you head over to the (O'Shaughnessy-inspired) Tiny Titans momentum screen, you'll see it has performed very well over the years despite mainly relying on just price to sales and relative strength.
Useful article, though I'd welcome more comments on future prospects post-CV19. To my mind the businesses operate in quite different market segments. I'm nervous about TUNE - live events are surely dead for some time at least in the UK (I accept their market is worldwide, so Europe and USA may pick up sooner) and it's hard to see recording studios being that active in a physical-distancing regime and being prepared to upgrade their hardware. I have a friend whose brother runs a respected recording studio in London so I may get some comments on general activity.
One attractive feature of TUNE is that the advfn board is quiet as a dormouse - almost 3 months since the last post!
Enjoyed this article Jack. G4M is on my radar and one I want to see start moving upwards before I start buying.
"The fact is, even after nearly doubling over the past month, G4M shares trade at well below one times sales - an attractive entry point if you believe this online retailer is proving its model and stands to gain from long term trends towards online retailing."
For me, it's about whether the market believes this online retailer is proving its model and stands to gain from long term trends towards online retailing!