GNC: Bumper harvest and bumper cash balances

Graincorp (ASX:GNC) is a diverse agribusiness. It is the largest grain storage and handling company on the East Coast of Australia. It is also a crusher and refiner of oilseed and a refiner of edible fats and oil.
Graincorp was one of the stocks selected for our inaugural NAPS Australia and New Zealand portfolio. With the year almost over they have deliver a total shareholder return of 8.4%, well above the ASX 300 benchmark at 5.1%. This performance was aided over the last week as they released their full year results (they have a 30 September year end) and surprised the market with a better than expected result.
Profits in FY23 were well below those in FY22, however this was expected as FY22 saw a bumper harvest, the second largest on record. The crop this year was still very strong, and revenue, EBITDA, EPS and dividends were all above expectations.
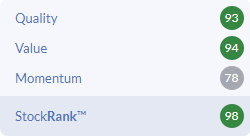
Graincorp was selected for the NAPS portfolio because its StockRank was 98. 11 months later and following the release of their FY23 results the StockRank is still 98. The two biggest factors contributing to this are the Quality score of 93 and the Value score of 94.
Despite the fall in some of the headline numbers in the most recent results, the Health Trend remains high at 7 out of 9. The return on assets and the gross margin fell, but all the other measures remained positive. Return on Capital and Return on Equity remain high despite contracting from last year’s levels.
Breaking the results down further, Graincorp’s business is divided into two main segments: Agribusiness and Processing.
The Agribusiness segment is dominated by grain storage and handling with the largest network on the East Coast of Australia. They have 160 regional receival sites and seven bulk ports, all connected by road and rail infrastructure.
The Processing segment is primarily involved in the refining of edible fats and oils. They are a leading oilseed crusher and refiner in Australia. The segment also includes Animal Nutrition. They are the largest canola meal producers and a supplier of vegetable oil and molasses-based feed supplements.
The results for the two segments moved in opposite directions in FY23. Agribusiness is the largest component with an EBITDA of $401m. This was down 36% on the prior year. Total grain handled fell to 37.4 million metric tonnes (mmt) from 41.1 mmt in FY22. The EBITDA for Processing of $153m, was up 20% on the prior year. This was on the back of improved performance of oilseed crushing, increasing throughput volume from 471 thousand metric tonnes (kmt) to 496 kmt, the fifth year in a row that throughput volume increased.

The high Quality score is supported by a strong balance sheet and strong cash flow. The cash balance lept to $735 million this year on the back of strong cash earnings and the divestment of United Malt Group. Graincorp received $127 million from the sale of their 8.5% stake in United Malt Group which completed its sale to Malteries Soufflet this month and has now been delisted.
This provides a sizable war chest for Graincorp’s management who are now in the enviable position of being able to both invest for growth as well as reward shareholders.
Dividends were retained at 54 cents for the financial year, the same as last year, despite the drop in net profit. The dividends are fully franked. This includes 26 cents of special dividends to take account of the cyclicality of earnings. Last year’s special dividend component was 28 cents. Structuring dividends this way helps to manage expectations. Market analysts are forecasting dividends per share for FY24 of 31 cents which would represent growth of 10% based on the ordinary component of the dividend.
In addition to dividends, management announced a $50 million on-market buy-back.
Graincorp are using some of this honey pot to invest for growth. They invested $35 million in the acquisition of an Animal Nutrition business. They are also making investments in digital and agtech, as well as assessing investments in additional crushing capacity. But the big ticket item that is currently being evaluated is an investment in a seed crushing plant to create biofuels. They are considering a new oilseed crushing plant in Western Australia to crush excess canola seeds from local farmers to create biofuels.
At present, excess canola seeds are exported and processed into biofuels overseas. Bringing some of this capacity onshore would have benefits in terms of domestic renewable energy security. The plant would have a crushing capacity of 750 kmt to 1 mmt and cost several hundred million dollars to build. They are already in discussions with airport operators IFM Investors about using the generated biofuel for aviation purposes. Further feasibility work is required before they make a final decision on the investment.
The other key component to their StockRank is the value score of 94. When compared with the FY23 results, all the value metrics appear cheap.

However the picture changes a little when looking at the forecast numbers. Given the cyclical nature of the business, there is an expectation that revenue and earnings will fall sharply in FY24 and even further in FY25. The PE ratio measured against FY25 forecast EPS is 18. That said, forecasts are inherently uncertain, especially when it comes to forecasting commodity prices and events of nature. Graincorp surprised on the upside this year, and may well do so again in future years. They are also working on strategies to try and smooth out some of the cyclicality in their earnings.
Graincorp has delivered very good results over the last few years. Whilst a lot of this has been due to bumper harvests, they have also been able to improve efficiency as well as diversify their earnings base. They are now in a strong position to use their balance sheet capacity to extend this further and keep the business on a solid footing.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?