Gold miners with clear catalysts: Shanta, AAZ, and Petropavlovsk

Gold is the gift that keeps on giving. This may change at some point but for now the signs continue to look promising.
A lot’s been happening here in recent days. Initially I wanted to cover three new miners as opportunities abound (Shanta Gold, Highland Gold, and Caledonia Mining, with Serabi and Pure Gold also waiting in the wings).
But there is new news this week for two previously mentioned stocks: AAZ and POG. Shanta Gold has also just announced its second quarter results, so I’ll focus on these three today. Users have just posted about Serabi (here) and Pure Gold (here) so those might be worth a look for anyone interested.
In the meantime, this Edison report is thought provoking. The key point is that the research house calculates a very strong correlation (0.909) between the price of gold and the US total monetary base since at least 1968. Basically, the more dollars in circulation, the higher the expected gold price.
Applying that correlation to the Fed’s huge asset-buying binge post-COVID implies a powerful tailwind.
After all the post-2008 concern around never before seen levels of QE, the Fed has gone and increased its monetary base by some 58% in just eight months to $5.2tn. Given that, and using its 0.9 correlation, Edison touts an implied gold price of $1,892/oz with an upper range figure of $3,000/oz.
At the current rate of monetary expansion, that $1,892 figure should continue to increase by $500 per ounce per year. Let’s see if the linear relationship holds in such an extreme environment...
Either way, it shows that if you’re concerned about the economic impact of lockdowns in 2020, gold is one of the primary ways to address that concern.
Shanta gold (LON:SHG)
- Share price: 15.25p
- Market cap: £129m
- Forecast revenue: £92.2m
- Production ounces: 80,000-85,000oz
- All-in sustaining cost: $771
Shanta Gold (LON:SHG) is an East Africa-focused mining operation with a ‘highly compelling’ growth pipeline. This profitable and (now) net cash miner has three projects across Kenya and Tanzania.
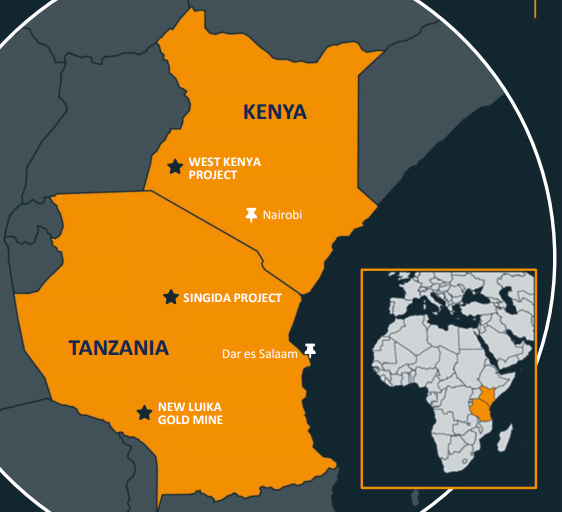
Source: company presentation
The management team has worked together for a decade or more and they, along with other insiders, own 9.3% of the £129m company.
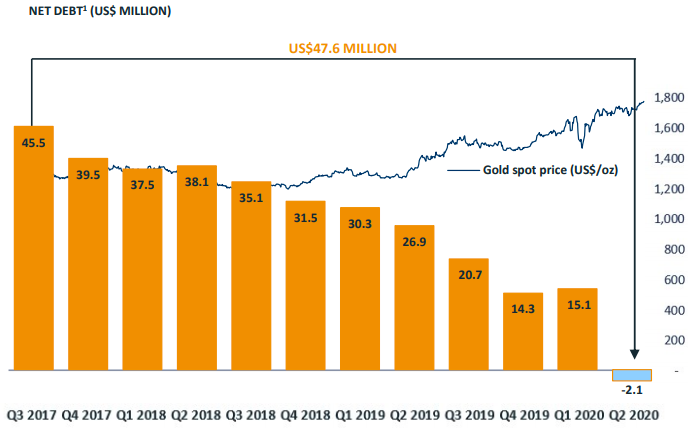
The key point to this one is that up until the most recent quarter, Shanta had been focused on reducing its net debt position. Now, after seven years, the group is net cash with producing assets and significant exploration potential.
Running through Shanta’s assets, we have:
New Luika Gold Mine
- High grade, low cost gold operation with Mine Life through to at least 2024 (based on reserves)
- Resources: 1.02 Moz at 2.77 g/t
- Cash costs 2019: US$564 /oz, AISC 2019: US$779 /oz
- 2019 Production: 85 koz
The Singida Project
- Open pit gold project in prospective greenstone belt in Central Tanzania
- Est. 7 Year Mine Life (based on reserves)
- Resources: 0.90 Moz at 2.38 g/t
The West Kenya Project
- Highly prospective project in Lake Victoria gold field
- $5m invested since 2010 by previous owners
- Resources: 1.18 Moz at 12.6 g/t
- Scoping study to be released in H2 2020
Shanta management seems to suggest that this upcoming West Kenya scoping study is not being properly priced in by the market.
Meanwhile the group’s Q2 operational update appears to show a low cost miner solidly executing, with current all in sustaining costs of $771 and annual production guidance of 80-85k/oz.
Highlights include:
- Quarterly gold production +10.2% to 22,216/oz;
- Adjusted EBITDA +29.3% to $19.4m based on an average realised gold price of US$1,663/oz;
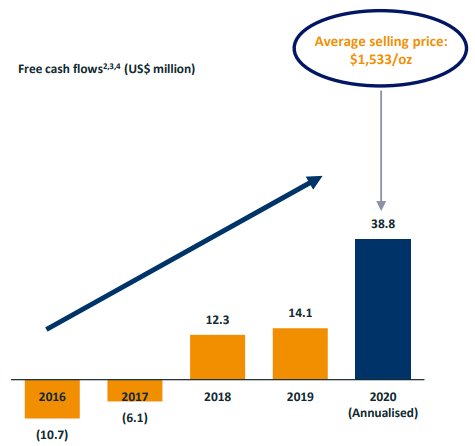
- Free cash flow up from $3.9m to $15.5m;
- Record quarterly deleveraging of US$17.2 m, taking Shanta into net cash for the first time in its producing history;
- Net cash of US$2.1 m (Q1: net debt of US$15.1 m);
- Gross debt down 34% to US$13.4 m (Q1: US$20.4 m);
- $40m Investec Senior Secured loan facilities fully repaid;
- Acquisition of the West Kenya Project on track for closure in Q3;
- Gold reserve of 243 koz announced at Singida grading 3.0 g/t, with potential for reserve expansion.
Eric Zurrin, Chief Executive Officer, commented:
Shanta enters a new chapter with a net cash position, completing a period of enormous deleveraging... Future production at Singida is expected to significantly increase the company's cashflow.
Shanta expects to shortly conclude the acquisition of Barrick's Kenya assets whereupon Shanta will own three projects with 3 million oz of high quality gold resources... We remain committed to rigorous capital allocation, growth of underlying shareholder value and to managing a sustainable and responsible mining company.
Conclusion
What is compelling here is the group looks to have two quite well defined company-specific share price catalysts: the swing from net debt to net cash, plus the exploration potential at its West Kenya site.
If gold prices remain strong, cash generation should be robust and Shanta will be able to add to its cash balances at a fair clip. Meanwhile we have that second half scoping study to watch out for. The two could be material share price drivers.
The current friendly environment is clear to see in the group’s free cash flow generation:
According to management, the West Kenya site is one of the highest grading 1m ounce deposits in Africa. Shanta has performed around 12 months of due diligence here, so I would hope their indication of ‘serious future value’ is built on solid foundations. Barrick has also spent c$50m developing it.
SHG looks like an increasingly profitable small cap miner with growing free cash flow, a new net cash balance sheet, and exploration upside potential. One to look at more closely, particularly with management flagging a possible H2 catalyst for the share price.
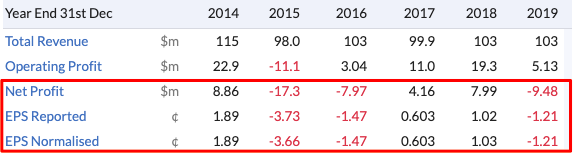
The group does have a patchy track record at the net profit level though, so I would want to spend more time reading previous annual reports to understand this before diving in.
Anglo Asian Mining (LON:AAZ)
- Share price: 143.5p
- Market cap: £161.9m
- Forecast revenue: £106m
- Production ounces: 75,000-80,000oz
- All-in sustaining cost: $591
(I hold)
Anglo Asian Mining (LON:AAZ) has announced a Joint Venture with Conroy Gold to acquire up to a 55% interest in the Longford Down Massif gold project in Ireland. Shares were up around 10% yesterday and are up again today at the time of writing.
It’s got the potential to be a material development, so worth unpacking. Here’s how the JV is structured:
- No initial payment required but an initial 17.5% interest will be earned by AAZ investing €2m in further exploration,
- This can ratchet up progressively to 55%, by developing the Clontibret gold deposit to mine construction-ready status,
- AAZ has warrants over 325,000 Ordinary Shares in Conroy Gold, with an additional 1,625,000 warrants in reserve,
- The additional warrants will become exercisable at certain milestones as AAZ invests funds into the JV,
- AAZ will retain an interest in each of the three joint venture companies even if it does not proceed to the Secondary Expenditure Programme.
It seems like a sensible way to structure the JV, with AAZ’s interest increasing as it ramps up investment, de-risks the project, and approaches production.
The licences cover over 800 square kilometres in a major gold district in the north-east of the island of Ireland, known as the Longford Down Massif.
Longford Down contains significant gold targets including:
- Clontibret - an existing JORC Resource of over 500,000 ounces of gold, situated in County Monaghan, in the Republic of Ireland
- Clay Lake in County Armagh, Northern Ireland - a gold target that lies at the north-eastern end of the 40 mile Longford Down gold trend, and
- An additional 8.8 million ounces of gold exploration targets in the Longford Down trend ‘providing significant upside potential’. These targets have been defined by soil geochemistry, are supported by geophysical data, and form an important part of the longer-term potential of this development.
Reza Vaziri, CEO, commented:
These are exciting times at Anglo Asian and I am delighted to announce this proposed joint venture with Conroy Gold which will be the Company's first enterprise outside of Azerbaijan.
The proposed joint venture is in keeping with the Company's stated strategy and ambitions and will complement the Company's existing pipeline of projects in Azerbaijan. It is of sufficient scale to considerably add to the Company's operations, but of a size which will not adversely impact the development of our assets in Azerbaijan.
Conclusion
I’ll be honest: I didn’t even know gold mining in Ireland was a thing. Perhaps we should all grab our shovels and start digging. It looks as though Clontibret is of a meaningful scale to AAZ with an estimated total resource of over 1m ounces.
Along with AAZ’s existing projects in Azerbaijan, the group now has a potentially substantial interest in three separate sites in Ireland. The group is profitable, cash generative, has a clean balance sheet, and is set to pay a handsome dividend.
DYOR, but I think AAZ should be over 200p. That view shouldn’t come as a surprise, as I do hold shares in this company.
That said, AAZ is not the only exciting opportunity in this space. Petropavlovsk is an altogether different proposition, one that comprehensively trumps AAZ in terms of relative share price strength...
Petropavlovsk (LON:POG)
- Share price: 36.45p
- Market cap: £1.04bn
- Forecast revenue: £1.124bn
- Production ounces: 430,000-460,000oz
- All-in sustaining cost: $1,020
POG shares jumped c17% earlier this week on the back of its half year results. The relative strength here is impressive:
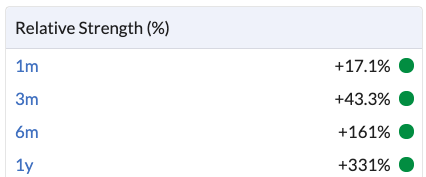
With forecasts rising all the time, there could still be an opportunity though, particularly given the low forecast earnings multiple of 7.8x. This is because a lot of the group’s growth is set to come from a transformational new asset: the POX hub. I went into it in a bit more detail recently here.
There’s not only scope for a rerating, but also further upside earnings surprises in future.
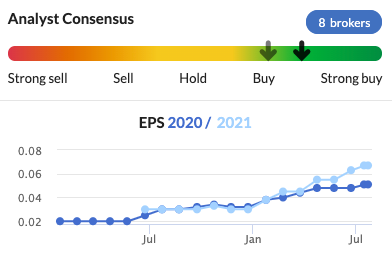
That said, I’m sure there is a bear case here as well - possibly revolving around historic corporate governance issues - so DYOR as always.
Highlights from the statement include:
- A 42% increase in total gold production to 320.6koz (H1 2019: 225.0koz), including 178.0koz from the processing of own and third-party refractory gold concentrates at the POX Hub
- A 39% increase in total gold sales to 312.4koz (H1 2019: 225.0koz) in H1 2020, including 170.9koz produced from the processing of own and third-party refractory gold concentrates at the POX Hub
- Average realised gold price of US$1,640/oz in H1 2020 (H1 2019: US$1,286/oz)
The important catalyst at POG is the POX hub - one of only two pressure oxidation plants in Russia, and something that could drive both company and third party revenue.
Regarding POX:
- All four autoclaves are now operating at their design parameters ‘and the POX Hub has demonstrated its unique flexibility in being able to treat multiple concentrates of different quality and composition’,
- The POX Hub is currently ready to treat the Company's own concentrate from the Pioneer flotation plant which is expected to be commissioned in Q4 2020
2020 outlook:
- Total gold production remains on track to meet the full year target of of 620koz to 720koz, including third-party concentrate processing
- Gold production from the Company's own ore remains on track to meet the full-year target of 430koz to 460koz
Conclusion
This share price is moving quickly as the market continues to adjust to POG’s evolving potential. It’s both a tech play and an angle on the rising gold price.
There’s a lot going on at this one though and I still haven’t wrapped my head around the various talking points. For example there is an ongoing court hearing covered in the statement that deserves more analysis.
For now, I’ve run out of time, and there are other companies to look at in this space (including Highland Mining, Caledonia Mining, Serabi Gold, and Pure Gold to name a few…)
With all these opportunities, perhaps the best way to play gold is to place smaller bets across a couple of operators? It would be great to get some views on this point.
AAZ, POG, and Shanta, for example, offer diversified operations across vastly different geographies (Azerbaijan, Ireland, Russia, and West Africa), and all have different mixes of potential share price catalysts and risk:reward profiles. Something to think about.
That's it for me - enjoy your weekend!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
I have been fearful of the current attempt to "grab" Shanta Gold! The share price has, in my opinion, been held down for some time. When you read the excellent reports from the company, the price doesn't tally!
This is an opportunistic attempt that has been planned for some time, in my opinion. They cannot be allowed to get away with it unless the "true"price is recognised and, that price, is a long way from the current "false" market!
The regulatory authorities, I trust, will examine what is going on here, with great interest.
Full year results for Anglo Asian Mining (LON:AAZ) were published this week and notably, the Stockopedia quality ranking has risen from mid 70s to 99. For once, the share price has reacted positively to these record results, even though they have been broadly known since the raw figures were announced in January. I believe the touch paper has been ignited by forward looking matters which are indicated by the company’s management in this Proactive interview https://www.proactiveinvestors.co.uk/companies/news/950115/anglo-asian-mining-present-record-revenues-and-outline-opportunities-ahead-950115.html
To summarise:
- Producing mines at Gedabek and Gosha generate excellent free cash flow with AISC of $700 /oz versus current gold price of $1880 /oz, some $200 higher than is being used by the company in their 2021 production targets.
- Awaiting access to 3 newly restored contract areas following the conflict with Armenia (the Chief Geologist has visited one of these already, as covered in the Proactive video).
- The other CA is Ordubad which going forward will have road/rail access to mainland Azerbaijan
- The company also hopes to acquire additional CAs in Azerbaijan and had hoped to announce these alongside FY results but negotiations are not yet finalised. One would imagine this announcement will be in the near term. Previously the company have said they hope to join up Gosha and Gedabek CAs but we will just have to wait and see what transpires.
- From the earlier airborne ZTEM survey of Gedabek/Gosha, 32 new mine targets were identified, 5 of which are being fast tracked. One of these is Zafer (production 2022) is described in the Proactive interview as game changing alongside an indication of the numbers that will support a maiden JORC report next month. Another of the 5 mines being fast tracked could come into production this year.
It is my largest holding, so obviously please take everything I say with a large pinch of salt and DYOR
Cheers
Simon
Well that was short-lived! Highland Gold Mining (LON:HGM) taken out just like that. While the 24% profit was great to have it is irksome to feel that others will benefit from the long term growth that seemed to be there. It happened recently to me with Rockrose Energy (LON:RRE) as well so reeling a little from the obvious fact that when it comes to the Stock Market it is often the hidden game that matters.
Aren't we lucky that Gordon Brown sold half the UK's gold reserves 20 years ago at what turned out to be the lowest point in its price since then?
https://www.bullionbypost.co.uk/gold-news/2019/may/07/worst-deal-uk-history-20-years-brown-sold-britains-gold/
Gold legend Alasdair Macleod is expecting the gold futures market to fail before the end of the year due to COMEX et al physical delivery issues (they don't have sufficient gold to settle contracts in physical metal). If he is right, the gold price would shoot up in USD terms much faster that the market is pricing in.
https://www.youtube.com/watch?v=XliHE6QgljY&t=1948s
Note: Gold remonitised would be worth about$32,885 /toz i.e. 17 times current spot price:
https://www.usdebtclock.org/gold-precious-metals.html
Well that is alarming, recorded 14 Jul. Crisis starting as close to two weeks. So that is tomorrow. I'm not sure my gold ETFs will be much use unless I can exchange them for a fully stocked bunker.
Hi HumourMe
Haha you're not wrong!
I expect the proverbial can to be kicked down the road a little bit further though but then again Alasdair Macleod certainly has a better handle on this than me so he is worth paying attention to.
We came off the Gold Standard in 1971, it wasn't that long ago really. These fiat currencies are all in a race to the bottom, when they start to collapse the odds are that the central banks will have to revert back to the previous system (Gold Standard), hence why central banks hold so much gold.
"the odds are that the central banks will have to revert back to the previous system (Gold Standard), hence why central banks hold so much gold."
Though large in absolute terms, US central bank holdings of gold are less than 5% of US money supply. So a return to a gold standard seems unlikely.
Fiat money allows a central bank to spend, spend, spend - effectively like a teenager with a credit card.
A gold standard only allows a central bank to spend within its means ie it is more like a debit card, than a credit card
In these terms, it's a surprise that the gold standard lasted as long as it did.
Howard Marx:
Very true, central banks love their fiat currencies. Meanwhile they accumulate gold.
The BIS (the bankers’ bank) up until recently only measured things in troy ounces, they didn’t even bother with the charade of fiat currencies.
I doubt the proletariat will trust fiat currencies again for at least few generations post a fiat collapse (which in my opinion is coming hence why accumulating gold and other gold related assets).
"We came off the Gold Standard in 1971."
According to Investopedia: "Britain stopped using the gold standard in 1931 and the U.S. followed suit in 1933 and abandoned the remnants of the system in 1973."
Pka:
As per Bretton Woods, the US government held the $35 per ounce price until August 15, 1971, when President Richard Nixon announced that the United States would no longer convert dollars to gold at a fixed value, thus completely abandoning the gold standard.
Just a little perspective. But when Anglo Asian Mining (LON:AAZ) announced its Irish Gold mining deal some eyebrows may have been raised. However, I suspect that most investors are probably unaware that Ireland hosts the largest Zinc mine in Europe - the Tara mine. In terms of Zinc, it’s highly prospective with more Zinc discovered per square kilometre than anywhere else on the planet. Basically, Ireland has a very established mining industry.
Incidentally, Shareprophets has just produced an online event “Mineprophets” that is probably worth a look. The link is here https://www.mineprophets.com/. It includes a long interview with Peter Hambro, co-founder of Petropavlovsk (LON:POG) as well as a variety of other speakers discussing the outlook for the Gold industry.
Perhaps the greatest underpriced optionality in Shanta Gold (LON:SHG) is the relative prospectivity of Tanzania, low number of other operators, Shanta's seeming closeness/favour with the government and the fact that this is a country that has recently lost interest from outside operators due to the furore around Acacia (I think the company appears to have deserved some grief).
If we move into a sustained gold bull market then Shanta's potential ability to acquire rights to prospective land and co-sponsor and 'oversee' exploration with partners (using their Tanzania badge of approval) gives them a potential route to a lot of low cost ounces.
As narratives and perceptions around gold and the value of operating in Tanzania shift positively then the optionality in Shanta could be massive. This is not a forecast, just a sight at how far the trash to glam move could go.
Zimbabwe is an even more troubled country...but in many respects that makes the potential upside to Caledonia Mining (LON:CMCL) even more marked.
A well worn fear is expropriation by govt in these countries. This is definitely a risk however I think it is more a rearview risk than an acute forward one. For sure rising gold price and activity will see governments seek ways to keep their take high....but countries like Tanzania and Zimbabwe have had some tough lessons on how bad for them it is to try and take over the laying of the golden goose's eggs all by themselves.
Not for the fainthearted...but one of the more extreme perception transformation out there beyond simple big discoveries. In Zim the stuff is known and in the ground so not so much discovering needed...its being able to operate in the country that is the skill. Tanzania requires more relative prospecting but general belief is that the gold is there and reasonably abundant and accessible.
I know very little about the gold industry in Tanzania, but I do hold a gas E&P whose operations are there, and they've been plagued with problems getting decisions made and agreements signed off. I think foreign owned mineral extraction has become such a hot potato, very much including the Acacia affair, that there's almost a paralysis of final decision making, and that's not good news for those operating there. There are signs that is finally being worked out, but those might yet prove to be false.
Is the risk priced? Shanta Gold (LON:SHG) appear to have created an ability to operate with a favourable light from govt. They'll probably never get their large VAT receivable back...but they might get some 'favours' for writing it off.
As owner of stock operating there I feel compelled to criticise govt for expropriation....however, trying to be objective I think that there has been a lot of abuse of mineral rights (from govt and cos) and that some of the recent heat is a rational attempt (maybe badly executed) to rectify this situation and ensure Tanzanian gets paid better for its bounty. I'm not saying that the current regime is good or not corrupt....
Nevertheless, Tanzania needs its mineral businesses to work as it needs the jobs and income they create. Shanta appear like they have got themselves on the inside track.
Highly risky obvs
Very interesting to see 3 Gold mining ETFS at the very top of the 200MA list of the ETF universe!
Hi HollandSmith,
That's a very interesting extract you put in your post of the top of the 200MA list of the ETF universe. Is there a free source of that information available on the web?
Sorry for a dumb question, but why do all these "Physical" metals all have different prices?
ETFS HEDGED METAL SECURITIES ETC (LON:GBSP)
Wisdomtree Commodity Securities ETC (LON:BULP)
WisdomTree Physical Gold Individual Securities ETC (LON:PHGP)
Gold Bullion Securities ETC (LON:GBSS)
Invesco Physical Gold ETC (LON:SGLP)
Ishares Physical Gold ETC (LON:SGLN)
Xtrackers Physical Gold Gbp Hedged Etc (LON:XGLS)
Cheers
Assume they hold differing quantities of Metals in trust, the price you pay would be for one share equivalent of the total Gold held in trust, ratio is defined by the Trust. Happy to be corrected if not the case though!
e.g. LON:SGLN -
Daily Metal Entitlement per Security
The amount of physical metal represented by one security.as of 24/Jul/2020 = 0.019545813
Total Metal (ounces)as of 24/Jul/2020 = 7,611,316.10
Another great write up, thanks Jack.
The key is a low cost god miner, these are going to see figures ahead of expectations die to the gold price. I would have to agree with Anglo Asian Mining (LON:AAZ) really low all in cost of $600, and compare to the gold price today of $1,900 is a fine margine there.
This is worth watching a new interview with Bill Morgan CFO and Stephen Westhead, Director of Geology and Mining talking about their Azerbaijani-Irish operations and what the future holds.
BW Business News Interview 24 July:
https://www.youtube.com/watch?v=mGJg7fsohSk&feature=emb_logo
Ive also got Golden Prospect Precious Metals (LON:GPM) and the managers have been plodding away for a long time at the more speculative end. Definitely a leveraged play and for me far better than trying to pick the winners from lower smaller end which is full of fraud & chancers, so you have to be very careful.
It looks like gold is heading for all time highs, so for me, the bull market for gold miners is just getting started. I have a position in all three of the miners mentioned in the headline - since last year, Shanta +92%, Anglo -5%, Pet +110%. Also have POLY, which has done well too.
I also like the others mentioned in the column by members and will look to add HUM if possible. Trans-Siberian also worth a closer look for me, prob add this too after a bit more research.
meant to add that I think the catalyst for trans Siberian is the untapped resource at rodnikova and the entire site‘s proximity to the POX plant owned by Petropavlosk, as always DYOR
Hi Jack
Thanks for the update on gold miners.
With the markets as they are I am currently 40% in cash and a further 12% in gold split about equally between physical gold (Invesco Physical Gold SGLP) and gold miners.
I have tried to look for gold miners with solid prospects of increasing production in the medium term. Generally, in my view, the market is relatively short-sighted so the real prospect of a step up in production may not be factored into the price if it is 8-12 months away.
Two miners in my view fit that bill.
Firstly Caledonia mining – they presented at the Mello event recently – this is their June presentation:
https://www.caledoniamining.com/wp-content/uploads/2020/06/Company-Presentation-NYC121-June-2020-Electronic.pdf
They are a profitable gold producer in Zimbabwe (Blanket Mine in the Gwanda Greenstone Belt).
They are producing around 50k oz gold. This was from old mine workings.
Over the last few years they have sunk a new central shaft which should be operational within 6 months. This is predicted to increase gold production by 60% (80k oz) by 2022.
Their share price is rising with current production and the rise in the gold price but I don’t believe the market has yet fully priced in the future increased production.
Secondly Hummingbird
This is a small gold miner (MC £140m) in Mali. Their Yanfolila mine has started to produce effectively after a couple of difficult years. Problems now sorted they are moving from a position of debt to net cash probably by the end of this year.
They have also had some decent exploration drills
https://www.investegate.co.uk/hummingbird-res---hum-/rns/2019-audited-final-results-and-exploration-update/202006030840278019O/
Following the production of 30,282 ozs in Q1 (at Yanfolia) we are pleased to maintain full year production guidance of 110,000-125,000 ozs and confirm that we remain on track to move from net debt to net cash position prior to the end of 2020.
Of particular note is the outstanding drill results coming in from our 2020 exploration drill programme.
These holes are intended to prove up underground resources at Komana East and also target new greenfield anomalies. No new targets have been drilled at Yanfolila since 2012 and so it is particularly gratifying to see the intersections at the Bolobi Coura target, prioritised due to their proximity to the plant, looking so strong.
Added to this is the valuable Dugbe asset which they have not had the funding to move into production. So a deal was done with ARX in June.
https://www.investegate.co.uk/hummingbird-res---hum-/rns/earn-in-agreement-with-arx-on-dugbe-gold-project/202006040700079000O/
The net present value (of Dugbe) was $337 million using $1,500 per ounce of gold and a 10% discount rate.
But Hummingbird will loose 49% of this to ARX and
Hummingbird’s stake in the project can be converted into a 51% stake in ARX.
Regarding their future ‘partners’:
ARX has an impressive team of mining veterans.
They will also carry the cost of a best practice feasibility study.
The market did not rate this as a good deal and combined with two difficult years at Yanfolila this has held back the share price.
In my view this was a pragmatic deal for shareholders as it turned 100% of a languishing asset into 51% of an asset with a much clearer pathway to production.
Finally on 8th June the acquisition of the Kouroussa gold project was announced:
https://www.investegate.co.uk/hummingbird-res---hum-/rns/acquisition-of-the-kouroussa-gold-project/202006080700072305P/
The acquisition of the Project turns Hummingbird into a near term multi-asset producer with jurisdictional diversification in line with the Company's strategy
Gold produced in 2 years, 100,000oz pa and a 5 year mine life. It has good synergy with Yanfolia andthe cost is $10m (a 9.1% share dilution)
Development cost estimated at $90 with Coris Bank International, to provide up to US$100m for the development of Kouroussa.
Their CEO (Daniel Betts) commented:
“It is of the scale, geology, process circuit design and grade that are all perfect for our team's experience to be put to immediate use, and it is in line with our strategy to focus on high margin projects.”
So this recently unloved company would seem to be on the cusp of a potentially significant step up in gold production over the next few years and the share price has moved up 50% in the last few weeks but I believe there is still significant potential here.
As always this is all just my personal opinion so DYOR :-)
Regards
Iron
I own a decent chunk of Royal Mint Physical Gold ETC Securities (LON:RMAP) (or Royal Mint Physical Gold ETC Securities (LON:RMAU) for the dollar version) and you are correct, it is a safe way to play gold, especially if focused on its safe haven characteristics. However, it won’t provide the same sort of upside (with the corresponding downside risk) as gold miners - these being a leveraged play on the price of gold.
Investing in individual (junior) miners is inherently risky and certainly volatile. A simpler and less risky way to gain exposure to major and/or junior miners is via ETFs or specialist gold funds. ISHRS GOLD PRODUCERS USD ETF (LON:SPGP) (which I hold) covers the majors but VANECK VECTORS UCITS ETF (LON:GDX) provides similar coverage and VANECK VECTORS UCITS ETF (LON:GDXJ) is a good way to play the juniors (there are plenty of other products available but I am less familiar with them). If gold keeps rising, these products are all likely to see significant upside but with a fair bit of volatility along the way.
A physical gold ETC on the other hand will simply move in line with the price of gold (plus forex movements) - less upside, less downside, lower volatility. But it’s horses for courses, if you want leveraged upside (with more volatility and more downside risk), miners are the way to go and the safest way to play those is via collective vehicles.
Cheers
Simon
Crazycoops wrote:
"I own a decent chunk of Royal Mint Physical Gold ETC Securities (LON:RMAP) (or Royal Mint Physical Gold ETC Securities (LON:RMAU) for the dollar version)"
Does anyone have any views on the pros and cons of owning the pound version of this physical gold ETC, RMAP, versus owning the dollar version, RMAU? I own some RMAP at present but I'm wondering whether I should sell that and buy RMAU instead.
I own the GBP version also. The way I see it is that the exchange rate will have a similar effect on value either way and ultimately, all my investment/expenditure needs are in GBP. I would also be interested in a good argument for the USD version if anyone has one.
Hi Crazycoops,
There's an article in today's Investors Chronicle entitled "How to hold gold" which says:
"Choosing between hedged and unhedged share classes [of physical gold ETFs] will also influence returns, because gold is a dollar asset. When the dollar is strong versus sterling, this will flatter unhedged returns. A hedged share class will suffer when the dollar is strong but pays off if it weakens against sterling. However, this is complicated by the fact that gold generally performs well when the dollar is weak."
This is what led to my query about what people think about whether it is better to hold the GBP or USD version of the Royal Mint Physical Gold ETC.
The ETC I mentioned in my previous post is called the Royal Mint Physical Gold ETC Securities, LON: RMAP.
A less risky way to invest in gold is via this Exchange Traded Commodity fund, which is physically backed by gold held by the UK government's Royal Mint:
https://www.moneyobserver.com/news/royal-mint-launches-physically-backed-gold-etc
After a 22% rise in Highland Gold Mining (LON:HGM) this week a little celebration seems to have been drummed up
https://www.youtube.com/watch?v=GEl2FpeJR3E
I own both this and Anglo Asian Mining (LON:AAZ) and find them to be a continual learning curve regarding their operations. Looking back they have been on my radar for some time but due to their locations have always ruled them out. Three months ago decided that the rewards for AAZ were to me more than offsetting the risks and the news out flow continues to make me sleep easy.
Highland Gold Mining (LON:HGM) is more recent and follows reading through Jack's comments, research notes and their accounts. That said video presentations seem readily available but as a non-Russian speaker are unhelpful, maybe other holders could point me in the right direction for in-depth company research.
Many thanks
Pan African Resources (LON:PAF) are worth a close look
I should add I hold.
Silver has been catching up with gold and my PAAS Pan American Silver has been doing well. I also hold AAZ and Kirkland Lake Gold in my ISA.
I take less specific share risk in my SIPP and there I hold funds - LF Ruffer Gold, Ninety One Global Gold and some physical gold £PHAU
Hi Jack
I agree that the Anglo Asian Mining (LON:AAZ) JV with Conroy is intriguing and value enhancing on a medium term view. The more significant news I believe was last week when the new portal to go underground at Gedabek was announced with production planned for Q4 2020. I believe the recent Hardman note had this pencilled in for 2023. That is some acceleration of the plan and should have a significant impact on 2021 production.
Disclosure - I hold
Cheers
Simon
Thanks Simon, I missed that one - I'll go back and read the RNS.
No problem Jack. We will probably get more detail in the coming week when the company update on H1 exploration. I think the problem with last week’s RNS was that investors initially saw a H1 production shortfall and the new portal to go u/g at Gedabek as a remedial measure to achieve 2020 guidance. While this may be the case, it is also likely to mean a significant ramp up in gold production for 2021+
Cheers
Simon
I have opened a long position in GPM as then it gives you a portfolio of miners and spreads the risk like you mentioned above.