GUD: Conglomerate to pure play

GUD Holdings (ASX:GUD) listed on the ASX in 1962. The business has never fit neatly into a classification as it has undergone multiple transformations throughout its life. In 2010, 44% of EBIT came from the consumer products division. This included the electrical appliances brand Sunbeam and Oates cleaning products. 28% of EBIT was from the automotive division and 25% from Davey Water Products. The remainder was from the security division. Prior to that they even owned Victa Mowers.
Today, GUD is a pure play automotive parts and accessories business having sold the Davey Water Products business last year to complete the transition from conglomerate to pure play. Initially, this has led to a substantial uptick in margins and returns.
Over the last 18 months, the Quality score has gone from 67 to 97. The underlying factors contributing to this include:
The Health score has gone from 3 to 8
Return on equity has doubled from 6% to 12%
Operating margin has gone from 10.6% to 16.4%
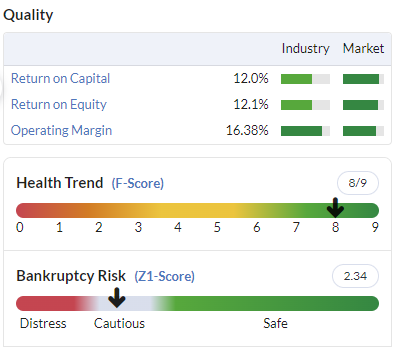
Turning to the Bankruptcy risk, the Z-score was previously in the distress zone, but has now moved into the cautious zone. It is held back by the low proportion of liquid assets and the low level of sales compared to assets. They have been paying down debt at a rapid rate, and in the first half of FY24 they reduced their borrowings by $70 million. The debt to equity ratio is now under 50% (including leases).
The total assets includes a high proportion, 64%, of intangible assets, both goodwill and identifiable intangible assets such as brands and customer relationships, reflecting the high level of acquisitions over recent years.
In January 2022 they acquired Melbourne based Auto Pacific Group (APG) which led to revenue almost doubling in size.
For reporting purposes they divide their operations into two segments, automotive and APG. Automotive includes spare parts, products and accessories for the automotive aftermarket. Some of the businesses in this segment include:
Auto Electrical, Lighting, and Power Management
Brown and Watson International (BWI) Australia
Projecta
GEL in NZ
Vision X
Rindab – European lighting specialist acquired in Nov. Will become part of BWI UK.
Powertrain
Ryco
Wesfil
IMG
EVs
Infinitev (brand within the IM group) – Repair and repurposing of hybrid and EV batteries
Undercar
DBA – brakes
Australian Clutch Services
X Clutch USA
APG is focused on towing and trailering and other functional accessories, eg. cargo management, for the aftermarket as well as supplying original equipment manufacturers.
Across these segments they have a host of different brands and products. Many are manufactured internally and others are sourced from external suppliers and distributed.
They remain focused on the two pronged approach to growth via organic growth as well as acquisitions. In November of 2023 they acquired Rindab AB, a European lighting specialist, providing a beachhead for greater penetration into Europe. Then in January of this year they acquired Caravan Electrical Solutions for $19 million.
Over the last month the Value Score and Momentum score have been moving in opposite directions as the share price has fallen by 15%. This reflects the weakness in retail spending with most discretionary segments experiencing declining sales over the last year, along with the realisation that interest rate relief is unlikely to come as soon as people were hoping.
In addition to the share price decline, the Momentum score has been impacted by a decline in analyst EPS forecasts as well, particularly following the release of the Interim results in mid February.

Revenue (excluding the discontinued Davey Water Products) grew by 8.6% in the first half and underlying profit was up 10.5%. But it was the negative sentiment in some of the outlook statements that led to the rerating. Management noted that the backlogs with original equipment manufacturers were still high with some of the supply chain disruptions encountered during the pandemic, still lingering. Toyota have deferred a replenishment order which will reduce EBITA for APG for the second half.
Management remains confident that the APG acquisition will deliver the business case targets when OEM supply constraints normalise, but in the short term it has underperformed expectations. People are still waiting eight months or more for the delivery of some popular SUV models. APG kit out a lot of these vehicles with accessories from the showroom floor, so that revenue is being deferred.
Looking at the numbers, APG earned a net profit margin of 10.4% for the half compared with 14% for the Automotive segment. The return on assets for APG was 1.8% compared to 5.8% for Automotive.
Despite these short term pressures, there are plenty of positive aspects to focus on. Whilst new car sales are one of the revenue drivers for GUD, they are only part of the story. The bigger drivers are the car parc, that is the total number of vehicles on the roads, along with the average age of vehicles. Both of these have been increasing and are forecasted to continue doing so as shown in the chart below. The average vehicle age has increased from 10.7 to 11.7 years over the last five years, as people hold onto their cars for longer. Older vehicles have a higher service requirement which is favourable for many of GUD’s Automotive brands.

Source: GUD, FY24 H1 Result presentation, 14/2/24
There is longevity in the management team and board of GUD and they now have a singular focus. They are facing some short term pressure, but if the long term story plays out as anticipated, the price weakness may represent an opportunity. The Value score has been rising. The forecast PE ratio is now 11.5 and the dividend yield 4.6% fully franked. Good opportunities rarely feel comfortable.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?